
Europe Auditing Services Market Size, Share, Trends and Forecast by Type, Service, and Country, 2026-2034
Europe Auditing Services Market Size, Share, Trends & Forecast (2026-2034)
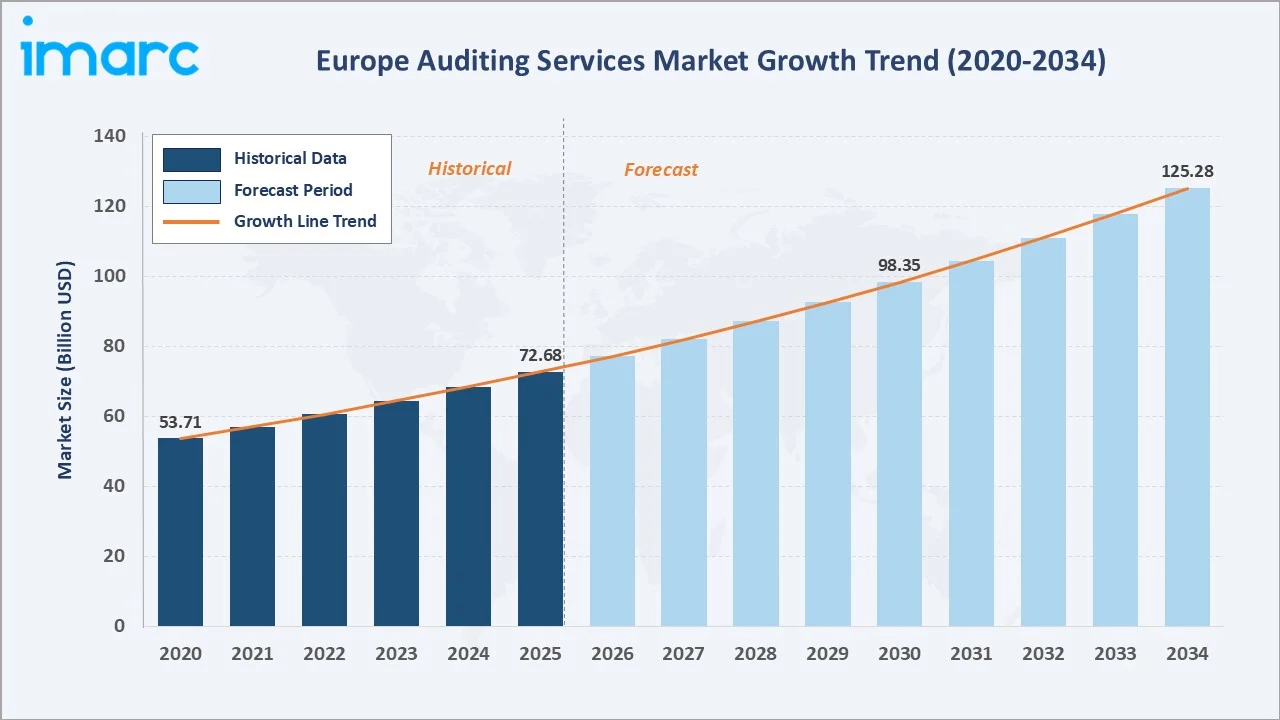
The Europe auditing services market grew from USD 72.68 Billion in 2025 to USD 77.21 Billion in 2026 and is projected to reach USD 125.28 Billion by 2034, growing at a CAGR of 6.24% during 2026-2034. The market is driven by rising regulatory compliance requirements across EU member states, digital transformation of audit processes, growing ESG and sustainability reporting mandates, and expanding cross-border business complexity. Financial Audits lead at 34.7%. Indoor Audit dominates at 52.6%. Germany commands 22.6% of the European market share.
Expanding audit scope under CSRD and DORA, rising demand for advisory and consulting services, and rapid adoption of AI-driven audit technologies are further supporting market growth.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 72.68 Billion |
|
Market Size (2026) |
USD 77.21 Billion |
|
Forecast Market Size (2034) |
USD 125.28 Billion |
|
CAGR (2026-2034) |
6.24% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Indoor Audit (52.6%, 2025) |
|
Dominant Service |
Financial Audits (34.7%, 2025) |
|
Leading Country |
Germany (22.6%, 2025) |
The Europe auditing services market size increased from USD 53.71 Billion in 2020 to USD 72.68 Billion in 2025 and is estimated to reach USD 77.21 Billion in 2026. The market is further expected to grow to USD 98.35 Billion by 2030 and USD 125.28 Billion by 2034. Europe auditing services market is anchored by robust regulatory ecosystems across EU member states and the UK, driven by financial compliance mandates, ESG reporting requirements, and digital audit adoption across all major European economies.
To get more information on this market, Request Sample
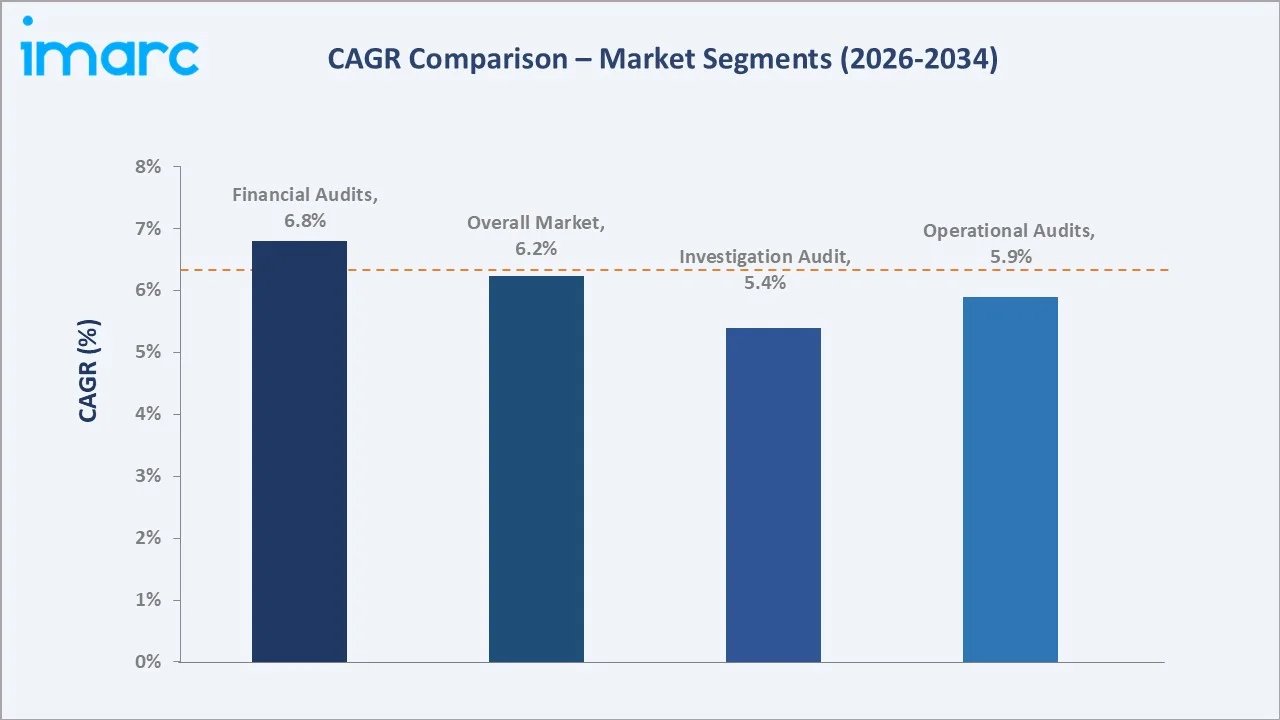
The Financial Audits segment leads at 34.7% through mandatory statutory audit requirements. Advisory and Consulting grows fastest through ESG compliance strategy and digital transformation guidance across European corporate markets. Indoor Audit at ~5.8% CAGR reflects mandatory internal audit dominance.
Executive Summary
The Europe auditing services market expanded from USD 72.68 Billion in 2025 to an estimated USD 77.21 Billion in 2026, positioning it as one of the world's largest regional professional services markets by value. The market's scale is underpinned by Europe's comprehensive regulatory landscape, the growing importance of sustainability reporting, and the increasing complexity of cross-border business operations requiring specialized audit expertise.
The market is projected to reach USD 125.28 Billion by 2034, registering a CAGR of 6.24% during 2026-2034. Indoor Audit at 52.6% leads through regulatory audit dominance. Financial Audits at 34.7% reflects corporate compliance requirements. Germany commands 22.6% regional market leadership.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Indoor Audit – 52.6% share (2025) |
|
Dominant Service |
Financial Audits – 34.7% market share (2025) |
|
Leading Country |
Germany – 22.6% share (2025) |
|
Market Opportunity |
ESG audit mandates under CSRD; digital audit technology adoption; cross-border regulatory compliance consulting; mid-market audit firm growth across Eastern Europe |
Key Analytical Observations Supporting the Above Data:
- Indoor Audit at 52.6%: The indoor audit segment dominates due to mandatory internal audit requirements at EU public interest entities and regulatory compliance review demand across European financial institutions and listed companies. Stringent EU Audit Regulation and national statutory frameworks ensure sustained non-discretionary demand.
- Financial Audits at 34.7%: Financial audits lead due to mandatory statutory audit requirements for publicly listed companies and financial institutions across Europe. Regulatory frameworks including IFRS, EU Audit Regulation, and national GAAP requirements ensure consistent baseline demand across all European markets.
- Germany at 22.6%: Germany dominates regionally due to its position as Europe's largest economy, high density of DAX-listed multinational corporations requiring complex audit services, and stringent national audit standards enforced by the Wirtschaftsprüferkammer (WPK).
Europe Auditing Services Market Overview
Europe auditing services market is positioned at the intersection of regulatory compliance, financial governance, and professional advisory services. The market is characterized by a tiered competitive structure dominated by the Big Four accounting firms, followed by second-tier international networks, and regional audit firms serving mid-market clients across EU member states.
Europe audit ecosystem integrates statutory audit mandates, voluntary assurance services, internal audit functions, ESG reporting assurance, and specialist advisory services. Macroeconomic factors including corporate growth, M&A activity, regulatory tightening under CSRD and DORA, and the EU's sustainability reporting agenda are driving market expansion across all service categories.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
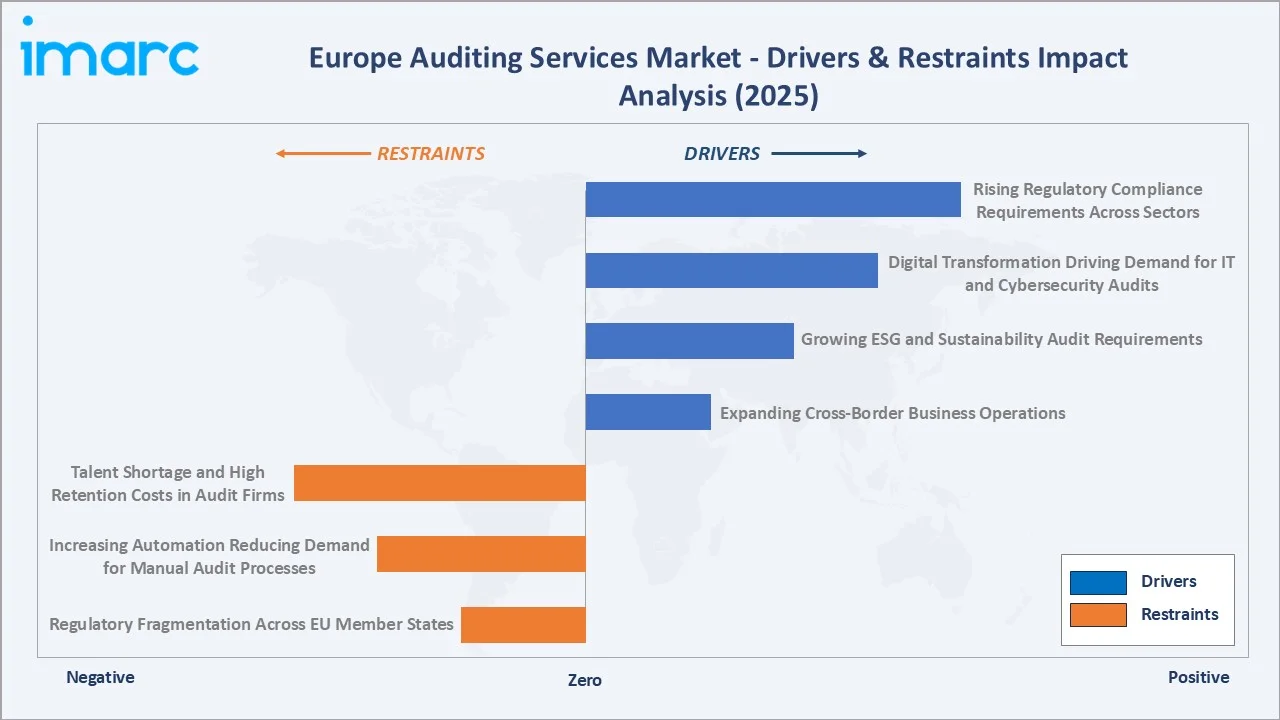
- Rising Regulatory Compliance Requirements Across Sectors: Increasingly stringent regulations across banking, insurance, healthcare, and public sectors are driving demand for audit and assurance services. The EU's Corporate Sustainability Reporting Directive (CSRD) is expected to significantly expand the audit market by requiring third-party assurance of non-financial reporting for thousands of additional companies across Europe.
- Digital Transformation Driving Demand for IT and Cybersecurity Audits: Rapid digitalization of business operations across European enterprises is creating sustained demand for IT audit, cybersecurity assurance, and digital risk management services. Regulatory requirements including DORA (Digital Operational Resilience Act) are mandating independent digital audit assessments for financial services firms across the EU.
- Growing ESG and Sustainability Audit Requirements: The European Green Deal and CSRD mandate verified ESG reporting for large companies, creating a growing new audit service category. Institutional investors and lenders are requiring ESG assurance from independent auditors as part of investment and credit risk frameworks, driving significant new revenue streams for audit firms.
- Expanding Cross-Border Business Operations: Growth in European M&A activity, foreign direct investment, and multinational business complexity is increasing demand for multi-jurisdiction audit services, transfer pricing reviews, and cross-border tax compliance audits. This trend benefits the largest international audit networks with integrated multi-country service capabilities.
Market Restraints
- Talent Shortage and High Retention Costs in Audit Firms: A persistent shortage of qualified auditors and audit specialists across Europe is constraining capacity expansion. Increasing competition for skilled professionals from advisory and financial services sectors, combined with rising salary expectations, is increasing operating costs and limiting growth potential for mid-tier audit firms.
- Increasing Automation Reducing Demand for Manual Audit Processes: Adoption of AI-powered audit tools, robotic process automation, and data analytics platforms is reducing the labor content of traditional audit engagements. This technological shift is compressing revenue per engagement for routine compliance audits, requiring audit firms to reposition toward higher-value advisory services.
- Regulatory Fragmentation Across EU Member States: Despite EU-level harmonization efforts, significant regulatory differences persist across member states in audit standards, independence requirements, and public oversight frameworks. This fragmentation increases compliance costs for firms operating across multiple EU jurisdictions and creates barriers to seamless pan-European service delivery.
Market Opportunities
- ESG Assurance as a New High-Growth Revenue Stream: The CSRD expansion is creating a large addressable market for sustainability assurance services, adding thousands of new mandatory audit clients across Europe. Audit firms with established ESG capabilities are positioned to capture this rapidly growing market opportunity through specialist service lines.
- Mid-Market Audit Demand in Eastern Europe: Rising corporate governance standards, EU funding requirements, and growing cross-border investment in Central and Eastern European markets are creating sustained demand for professional audit services in previously underserved geographies, offering above-average growth for regional audit network expansion.
Market Challenges
- Audit Quality Scrutiny and Regulatory Sanctions: Increased scrutiny of audit quality by European regulatory bodies following high-profile corporate failures is creating reputational and financial risks for audit firms. Regulatory sanctions and mandatory firm rotation requirements are increasing operational complexity and client transition costs across all service segments.
- Price Pressure from Client Cost-Optimization Initiatives: Corporate cost-reduction programs and procurement-driven audit fee negotiations are creating sustained downward pricing pressure, particularly in the statutory audit segment. This challenge is most acute for mid-tier audit firms competing against the Big Four on price rather than service quality differentiation.
Emerging Market Trends
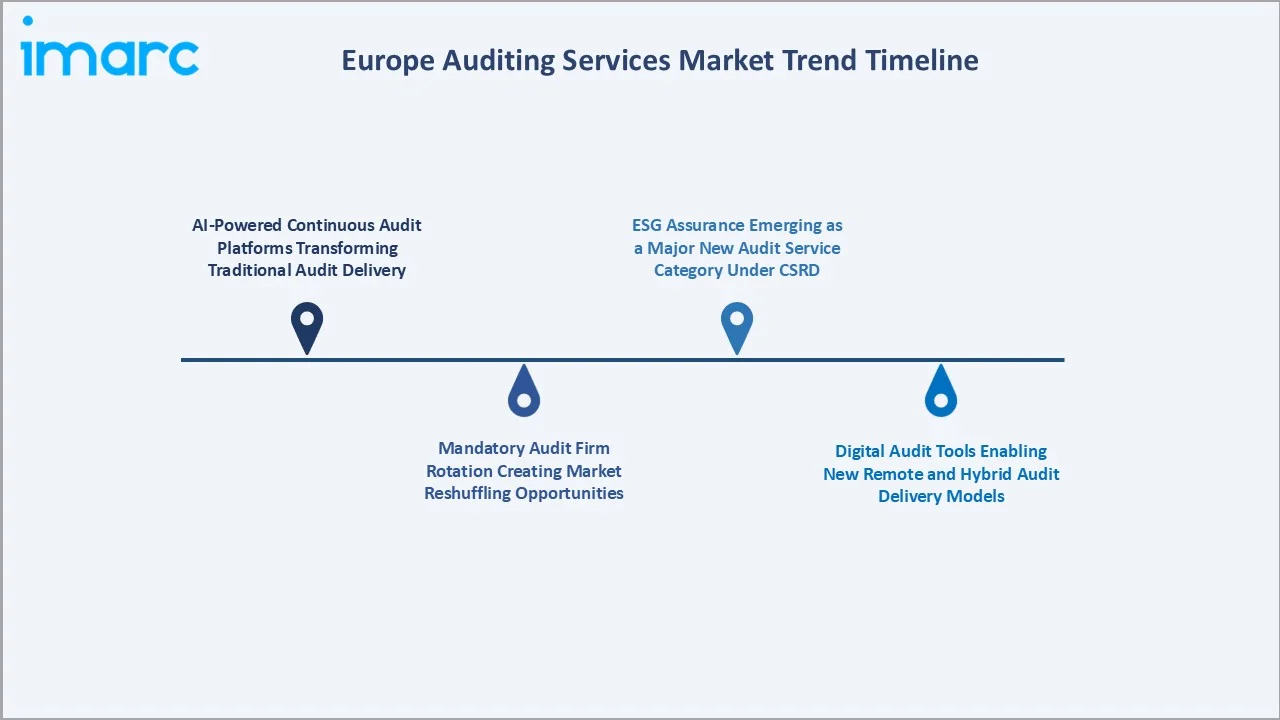
1. AI-Powered Continuous Audit Platforms Transforming Traditional Audit Delivery
AI-powered audit platforms are enabling continuous monitoring, predictive risk assessment, and real-time anomaly detection, transforming audit delivery from periodic reviews to ongoing assurance. Leading audit firms are investing in proprietary AI platforms to enhance efficiency, quality, and depth of audit coverage while differentiating their service propositions.
2. ESG Assurance Emerging as a Major New Audit Service Category
The CSRD mandate is driving rapid growth in ESG assurance services across Europe. Audit firms are building sustainability assurance capabilities through specialist hiring, acquisitions of ESG advisory firms, and development of proprietary ESG data verification methodologies. This trend creates a new competitive dynamic where accounting firms compete with specialist ESG consultancies for assurance mandates.
3. Mandatory Audit Firm Rotation Creating Market Reshuffling Opportunities
EU mandatory audit firm rotation requirements for public interest entities are creating regular market reshuffling across European listed companies. In 2025, rotation deadlines drove competitive tendering across hundreds of European listed companies simultaneously, enabling challenger firms to displace incumbents in established client relationships across Germany, France, and the Netherlands.
4. Digital Audit Tools Enabling New Remote and Hybrid Audit Delivery Models
Post-pandemic adoption of remote audit capabilities has been permanently integrated into European audit firm delivery models. Hybrid audit approaches combining remote data access, on-site sampling, and digital confirmation processes are reducing travel costs, enabling broader geographic coverage, and improving audit team efficiency across European engagement portfolios.
Industry Value Chain Analysis
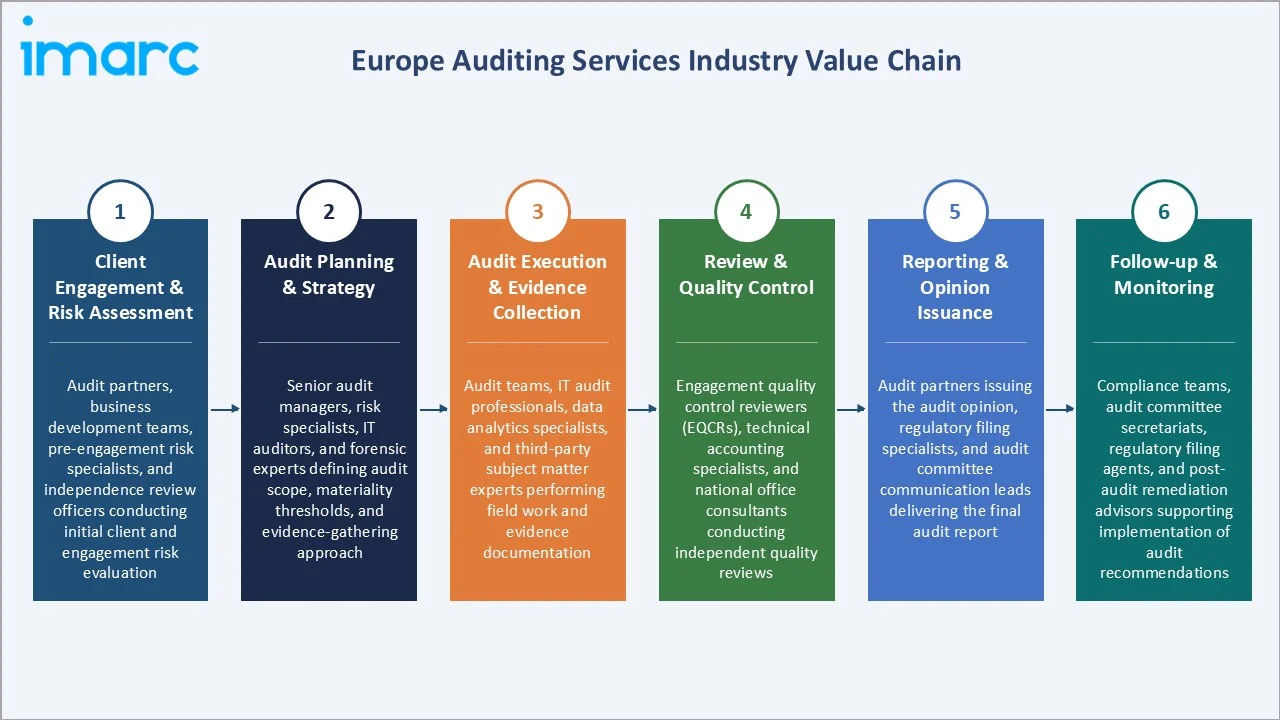
Europe auditing services value chain is structured across six key stages from client engagement through post-audit follow-up. The value chain's commercial structure reflects the professional service nature of audit delivery, where expertise, judgment, and independence add value at each stage beyond simple process execution.
|
Stage |
Key Participants |
|
Client Engagement & Risk Assessment |
Audit partners, business development teams, pre-engagement risk specialists, and independence review officers conducting initial client and engagement risk evaluation |
|
Audit Planning & Strategy |
Senior audit managers, risk specialists, IT auditors, and forensic experts defining audit scope, materiality thresholds, and evidence-gathering approach |
|
Audit Execution & Evidence Collection |
Audit teams, IT audit professionals, data analytics specialists, and third-party subject matter experts performing field work and evidence documentation |
|
Review & Quality Control |
Engagement quality control reviewers (EQCRs), technical accounting specialists, and national office consultants conducting independent quality reviews |
|
Reporting & Opinion Issuance |
Audit partners issuing the audit opinion, regulatory filing specialists, and audit committee communication leads delivering the final audit report |
|
Follow-up & Monitoring |
Compliance teams, audit committee secretariats, regulatory filing agents, and post-audit remediation advisors supporting implementation of audit recommendations |
The audit execution and quality control stages are the most commercially significant, collectively accounting for 60-70% of total engagement hours and the majority of professional fee revenue. Increasing regulatory scrutiny of audit quality is driving investment in EQC review processes, data analytics capabilities, and technical specialist networks across all major European audit firms.
Technology Landscape in the Europe Auditing Services Industry
AI and Data Analytics in Audit
AI and data analytics technologies are fundamentally transforming audit methodologies by enabling full-population testing, predictive risk modeling, and automated anomaly detection. These capabilities replace traditional sampling-based approaches, improving both audit quality and efficiency simultaneously. Leading audit firms have developed proprietary AI platforms that integrate client ERP data, enabling continuous monitoring between annual audit cycles across European engagement portfolios.
Cloud-Based Audit Management Platforms
Cloud-based audit management platforms are enabling distributed audit team collaboration, real-time work-paper review, and integrated client data portals supporting hybrid audit delivery. In 2025, Deloitte expanded its cloud-based audit platform across European markets, enabling audit teams in multiple countries to work simultaneously on cross-border engagement components, reducing travel costs and improving coordination across large international audit engagements.
Robotic Process Automation in Compliance Testing
Robotic process automation (RPA) is being deployed across routine audit compliance testing activities, including bank confirmations, accounts receivable verification, and payroll testing. RPA deployment reduces time required for high-volume, rule-based audit procedures, enabling audit professionals to allocate more time to judgment-intensive risk assessment and complex accounting evaluations that cannot be automated by technology platforms.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Indoor Audit |
52.6% |
2025 |
|
Service |
Financial Audits |
34.7% |
2025 |
|
Country |
Germany |
22.6% |
2025 |

By Type
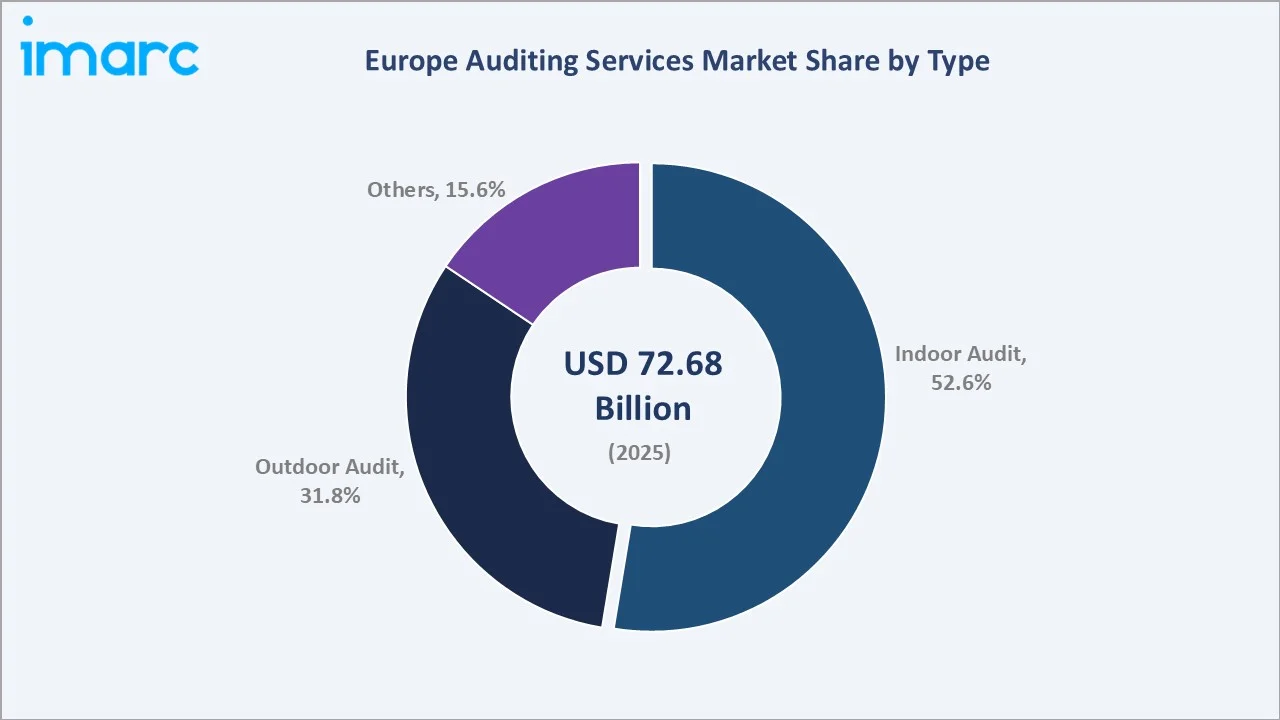
Indoor Audit leads at 52.6% (2025). The indoor audit segment encompasses mandatory internal audit functions, regulatory compliance reviews, and internal controls assessments across European corporations, financial institutions, and public sector entities. Indoor Audit grows at ~5.8% CAGR (2026-2034) driven by expanding regulatory mandates for independent internal audit at EU public interest entities.
To access detailed market analysis, Request Sample
Outdoor Audit at 31.8% represents external statutory audit mandates across listed companies, financial institutions, and regulated entities, growing at ~6.5% CAGR through expanding mandatory audit scope under EU Audit Regulation. Others at 15.6% encompasses specialist assurance services, forensic audit, and regulatory investigation mandates, growing at ~4.2% CAGR through 2034.
By Service
Financial Audits lead at 34.7% (2025). This segment encompasses statutory audit of financial statements, consolidated accounts, and regulatory capital adequacy assessments across European listed companies and financial institutions. Financial Audits grow at ~6.8% CAGR (2026-2034) driven by mandatory engagement requirements providing a stable, non-discretionary revenue base across all European markets.
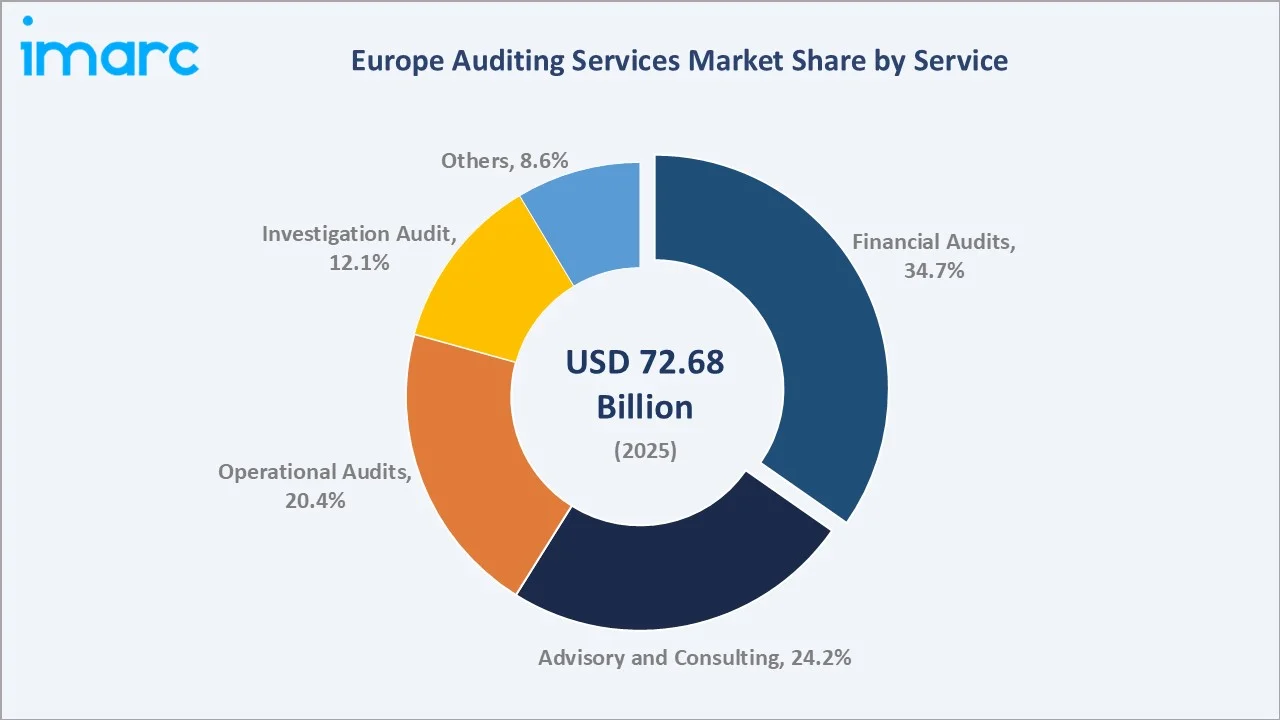
Advisory and Consulting at 24.2% grows fastest at ~6.2% CAGR through ESG compliance advisory and digital transformation guidance. Operational Audits at 20.4% serve process improvement mandates, growing at ~5.9% CAGR. Investigation Audit at 12.1% grows at ~5.4% CAGR through regulatory enforcement demand. Others at 8.6% grows at ~4.8% CAGR through niche assurance categories.
Regional Market Insights
|
Country |
Share (2025) |
Key Europe Auditing Services Market Drivers & Characteristics |
|
Germany |
22.6% |
Largest European economy with highest density of DAX-listed companies requiring complex multi-jurisdiction audit services and stringent WPK-regulated audit standards. |
|
United Kingdom |
19.8% |
Major financial services hub with FCA-regulated firms driving significant statutory and regulatory audit demand; FRC oversight ensures high audit quality standards. |
|
France |
13.5% |
Commissaires aux comptes statutory audit system and CAC 40 corporate audit market supporting sustained structured demand across large and mid-cap companies. |
|
Italy |
10.8% |
Large SME sector and growing regulatory audit requirements across banking and insurance sectors under Banca d'Italia oversight and EU harmonization mandates. |
|
Spain |
8.2% |
Expanding audit market driven by IBEX 35 corporate growth, regulatory harmonization with EU audit standards, and increasing ESG reporting requirements. |
|
Netherlands |
6.4% |
Major European HQ location for multinational corporations requiring consolidated group audit services; AFM oversight drives rigorous audit quality standards. |
|
Switzerland |
5.7% |
Global financial institutions and luxury goods multinationals creating premium audit service demand; RAB-regulated market with high quality standards. |
|
Poland |
4.9% |
Fastest-growing Eastern European audit market driven by FDI, EU compliance requirements, and mandatory audit scope expansion under EU Audit Regulation. |
|
Russia |
4.3% |
Large corporate sector with statutory audit requirements; geopolitical factors post-2022 are reshaping the service provider landscape and Big Four presence. |
|
Others |
3.8% |
Remaining European markets with growing audit demand driven by EU regulatory expansion, EU funding audit requirements, and economic development. |
Germany's 22.6% market leadership reflects its position as Europe's largest economy with the highest concentration of DAX-listed and mid-market companies requiring complex statutory and group audit services. The United Kingdom's 19.8% reflects London's role as Europe's leading financial services centre with FCA-regulated institutions driving significant regulatory audit mandates.
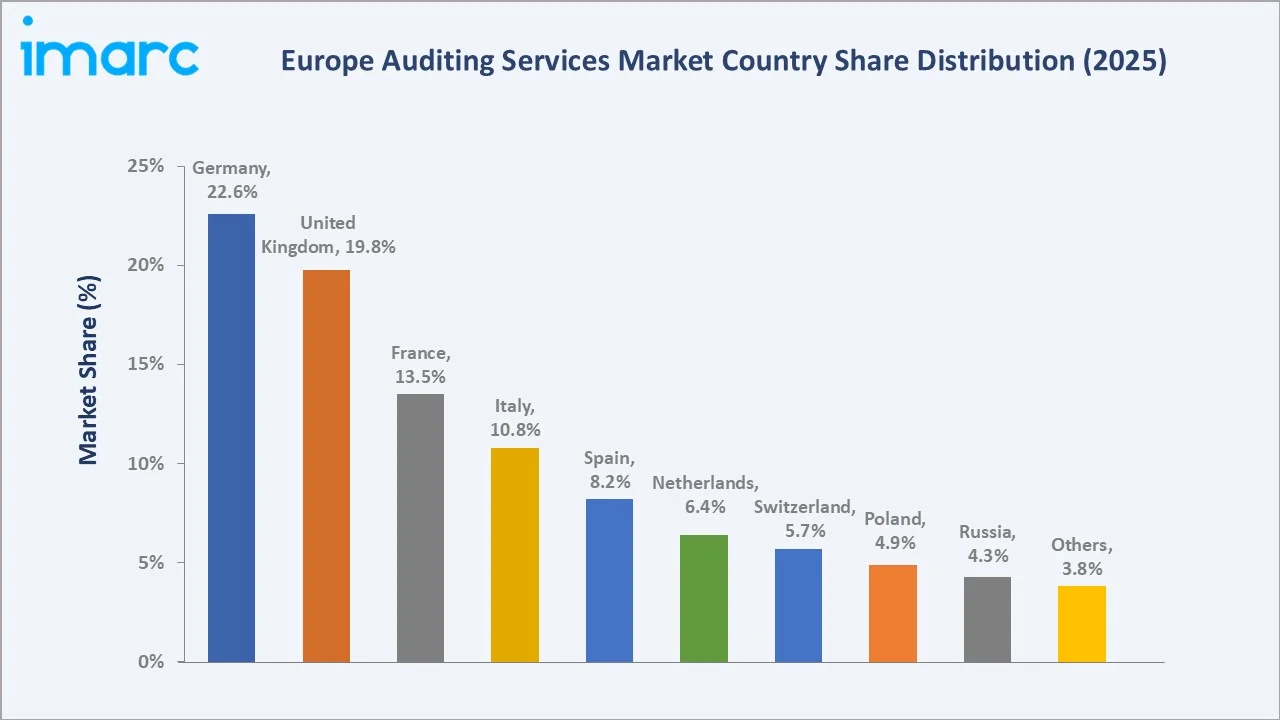
France's 13.5% reflects the established commissaires aux comptes system creating a structured domestic audit market. Poland's 4.9% represents the fastest-growing Eastern European audit market as EU regulatory requirements expand into previously less-audited segments of the Polish corporate and financial services sectors.
Competitive Landscape
Europe auditing services competitive landscape is dominated by the Big Four accounting firms – Deloitte, PricewaterhouseCoopers, Ernst & Young, and KPMG – which collectively account for approximately 60-65% of total European audit market revenue. The remaining market is served by second-tier international networks and regional boutique specialist practices.
|
Company |
Service Focus |
Market Position |
Core Strength |
|
Deloitte |
Audit, Advisory, Tax |
Market Leader |
World's largest professional services network with extensive EU regulatory audit capabilities and proprietary AI audit technology platform deployed across European markets. |
|
PricewaterhouseCoopers |
Assurance, Advisory, Tax |
Market Leader |
PricewaterhouseCoopers maintains the largest European assurance practice with dominant position in financial services, insurance, and cross-border group audit engagements. |
|
Ernst & Young |
Assurance, Consulting, Tax |
Market Leader |
Ernst & Young leads in ESG assurance and digital audit capabilities, with strong positions in German and UK statutory audit markets and CSRD assurance service development. |
|
KPMG |
Audit, Tax, Advisory |
Market Leader |
KPMG holds strong positions in financial services regulatory audit, public sector assurance, and banking supervision audit across European markets. |
|
BDO International |
Audit, Tax, Advisory |
Strong Challenger |
BDO International is the leading mid-market audit network, with strong presence in SME and owner-managed business audit and the fastest-growing European practice among second-tier networks. |
The competitive landscape's most significant dynamic is the growing competition between the Big Four and specialist consulting firms in the advisory and ESG assurance segments, where differentiation is based on technical capabilities rather than regulatory audit credentials, creating new entry opportunities for specialist providers.
Key Company Profiles
Deloitte
Deloitte is the world's largest professional services network by revenue, with a dominant position in the European auditing services market across all service categories and geographic markets. The firm's European audit practice serves the majority of DAX, FTSE 100, and CAC 40 listed companies across statutory and advisory audit services.
- Key Services: Statutory Audit, Internal Audit, ESG Assurance, Forensic Audit, Regulatory Advisory, IT Audit
- Recent Developments: In 2025, Deloitte launched an AI-powered audit analytics platform across its European practice, enabling real-time data analysis and continuous monitoring for major audit engagements across the EU and the United Kingdom.
- Strategic Focus: Expanding ESG assurance capabilities and digital audit technology investment to maintain market leadership as CSRD sustainability reporting mandates drive new mandatory assurance demand across European corporate clients.
PricewaterhouseCoopers
PricewaterhouseCoopers (PwC) maintains the largest European assurance practice by revenue, with particular strength in financial services, insurance, and cross-border group audit engagements. The firm's European network covers all major EU member states with fully integrated multi-jurisdiction audit service delivery capabilities across 26 European countries.
- Key Services: Financial Statement Audit, Regulatory Audit, Sustainability Assurance, Transaction Advisory, Risk Assurance
- Strategic Focus: Leading in sustainability assurance and building cross-border audit capabilities to serve multinational clients with complex EU regulatory compliance requirements across multiple jurisdictions simultaneously.
BDO International
BDO International is the world's fifth-largest accounting and advisory network and the leading mid-market audit firm in Europe, with a strong presence across SME, privately-owned, and mid-cap listed company audit markets. BDO positions as a quality-focused alternative to the Big Four for clients seeking more personalized partner-led engagement delivery.
- Key Services: External Audit, Internal Audit, Tax Compliance, Business Advisory, Corporate Finance, ESG Reporting Assurance
- Recent Developments: In 2025, BDO International expanded its Central and Eastern European practice through acquisitions in Poland, Czech Republic, and Romania, targeting the growing mid-market audit demand driven by EU regulatory expansion in these markets.
- Strategic Focus: Capturing mid-market audit opportunities created by mandatory firm rotation requirements and expanding into ESG assurance services for listed and pre-IPO companies across European markets.
Market Concentration Analysis
Europe auditing services market is highly concentrated in the statutory audit segment for listed companies and financial institutions, with the Big Four accounting for approximately 80-85% of public interest entity audit revenue. The mid-market segment is more fragmented, with BDO International, RSM International, Grant Thornton, and Mazars competing alongside regional and national audit firms.
Market concentration is evolving through two primary forces: mandatory audit firm rotation creating regular market entry opportunities for challenger firms in the listed company segment, and ESG assurance creating a new competitive arena where specialist ESG consultancies are competing with established audit firms for emerging sustainability assurance mandates across European markets.
Investment & Growth Opportunities
Highest Growth Segments
ESG assurance services (~15-20% CAGR from CSRD mandate expansion), IT and cybersecurity audit (~12-15% CAGR from DORA and NIS2 requirements), forensic and investigation audit (~8-10% CAGR from regulatory enforcement), advisory and consulting (~6.2% CAGR from digital transformation guidance), and Eastern European market expansion (~9-12% CAGR from EU regulatory harmonization) represent Europe's highest-growth audit investment vectors through 2034.
Emerging Investment Opportunities
Europe's ESG assurance market represents the highest-growth new audit service category, driven by CSRD mandatory assurance requirements expanding to cover an estimated 50,000+ companies by 2026. The ESG assurance market's growth is driven by new mandatory requirements, investor-led demand for verified sustainability data, and the complexity of climate and supply chain data verification requiring specialized expertise.
Investment Themes
- ESG assurance capability building through specialist hiring and methodology development to capture CSRD-driven mandatory assurance market: Audit firms investing in climate data verification, supply chain sustainability assessment, and biodiversity impact audit capabilities are well-positioned to lead this rapidly growing market segment through 2034.
- Technology investment in AI audit platforms to enhance quality and efficiency across traditional statutory audit engagement portfolios: Proprietary AI audit technology investment is becoming a strategic differentiator for audit firms competing on quality, efficiency, and risk coverage depth in the statutory audit market across all European geographies.
Future Market Outlook (2026-2034)
The Europe auditing services market is projected to grow from USD 72.68 Billion in 2025 to USD 77.21 Billion in 2026, reaching USD 125.28 Billion by 2034, registering a CAGR of 6.24% during 2026-2034. The market's anchor value of USD 98.35 Billion in 2030 represents a structural expansion driven by ESG mandates, digital audit technology adoption, and Eastern European market development from a comparatively lower penetration base.
Three structural forces define Europe auditing services market growth through 2034: the ESG reporting mandate expansion creating the largest new audit service category in European audit history through CSRD compliance; digital transformation of audit delivery enabling above-market efficiency gains and service quality improvements through AI and analytics technology adoption; and Eastern European market development creating sustainable above-average growth markets for mid-tier audit network expansion.
Research Methodology
Primary Research
Primary research comprised structured interviews with Europe auditing services industry stakeholders, including Managing Partners, Audit Committee Directors, CFOs and Finance Directors, regulatory affairs specialists, and audit technology providers across Germany, United Kingdom, France, and other key European markets.
Secondary Research
Secondary research encompassed European audit regulator publications, IAASB and FRC audit standards documentation, company annual reports, professional association data from EFAA and Accountancy Europe, investor relations materials, and European Commission regulatory impact assessments. Over 50 secondary sources reviewed.
Forecasting Models
Market revenue forecasts were developed using a regulatory-driven demand model: mandatory audit population by jurisdiction multiplied by average audit fee per engagement type, combined with advisory and consulting revenue estimates based on GDP growth, corporate complexity indices, and regulatory expansion trajectories across European markets.
Europe Auditing Services Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Indoor Audit, Outdoor Audit, Others |
| Services Covered | Operational Audits, Financial Audits, Advisory and Consulting, Investigation Audit, Others |
| Countries Covered | Germany, United Kingdom, France, Italy, Russia, Spain, Netherlands, Switzerland, Poland, Others |
| Companies Covered | Deloitte, PricewaterhouseCoopers, Ernst & Young, KPMG, BDO International, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe auditing services market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Europe auditing services market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe auditing services industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Auditing Services Market Report
The Europe auditing services market size is estimated at USD 77.21 Billion in 2026, driven by regulatory compliance requirements across EU member states, ESG reporting mandates under CSRD, and digital transformation driving demand for IT and cybersecurity audit services across European corporations and financial institutions.
The Europe auditing services market grows at 6.24% CAGR during 2026-2034, reaching USD 125.28 Billion by 2034. Growth is sustained by CSRD-driven ESG assurance expansion, DORA and NIS2 digital audit mandates, mandatory firm rotation creating market reshuffling opportunities, and Eastern European market development.
Indoor Audit leads at 52.6% through mandatory internal audit requirements at EU public interest entities and regulatory compliance review demand across European financial institutions and listed companies, growing at ~5.8% CAGR through 2034.
Financial Audits lead at 34.7% through mandatory statutory audit requirements under EU Audit Regulation and national audit legislation covering all European listed companies and financial institutions, growing at ~6.8% CAGR through 2034.
Germany leads at 22.6% through its position as Europe's largest economy with the highest density of DAX-listed and mid-market companies requiring complex multi-jurisdiction audit services and stringent WPK-regulated national audit standards.
Leading companies include Deloitte, PricewaterhouseCoopers, Ernst & Young, KPMG, BDO International, among others.
The Europe auditing services market is projected to reach approximately USD 98.35 Billion by 2030, with ESG assurance growing as CSRD mandatory requirements come into full effect, digital audit technology driving efficiency improvements, and Eastern European markets growing above the overall market CAGR of 6.24%.
Three priority investment opportunities: ESG assurance capability building to capture CSRD-driven mandatory sustainability reporting assurance mandates across 50,000+ new reporting companies; AI-powered audit platform investment to enhance quality and efficiency in statutory audit engagements; and Eastern European market expansion through mid-market audit network development.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade