
Europe Decorative Laminates Market Size, Share, Trends and Forecast by Product Type, Application, End Use, Texture, Pricing, Sector, and Country, 2026-2034
Europe Decorative Laminates Market Size, Share, Trends & Forecast (2026-2034)
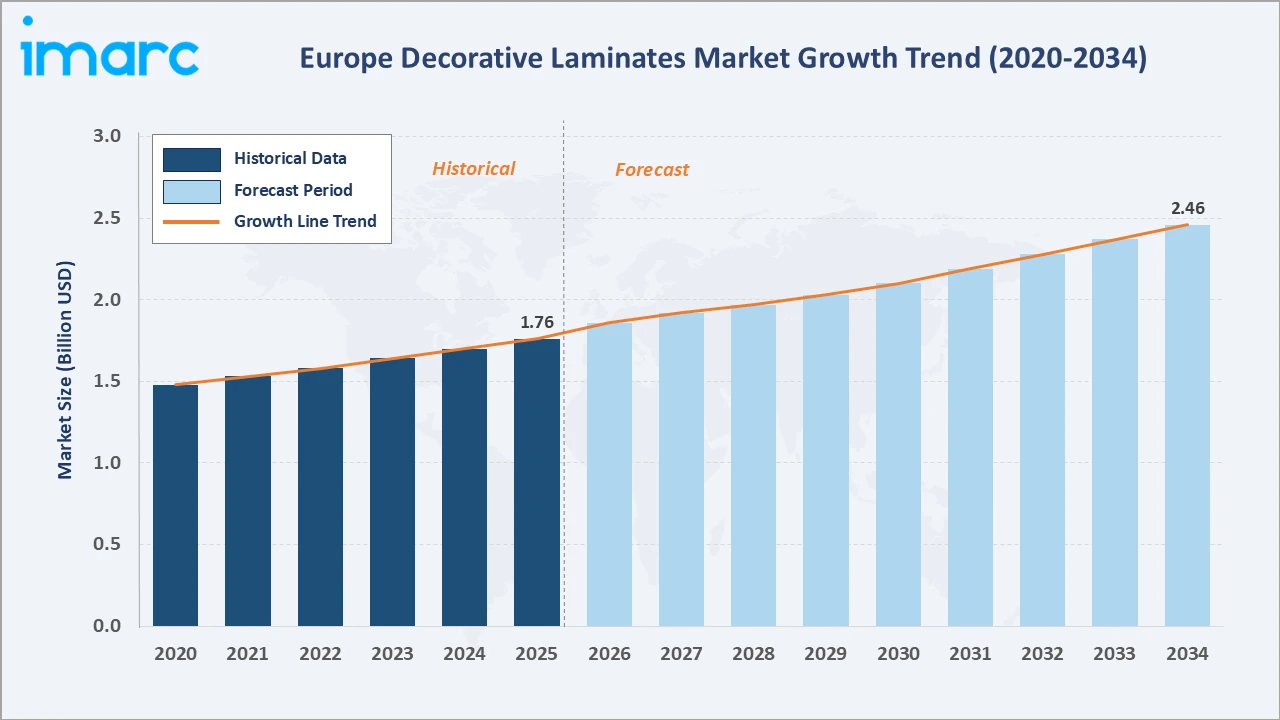
The Europe Decorative Laminates Market grew from USD 1.76 Billion in 2025 to USD 1.86 Billion in 2026 and is projected to reach USD 2.46 Billion by 2034, growing at a CAGR of 3.57% during 2026-2034. The market is driven by rising construction and renovation activity, growing demand for eco-certified surface materials, and expanding furniture manufacturing across Europe. Europe’s furniture industry consumes decorative laminates as the primary surface material for cabinets, wardrobes, and worktops, making it the single largest demand driver in the region. This robust industrial consumption base supports consistent laminate demand across both the residential and commercial segments.
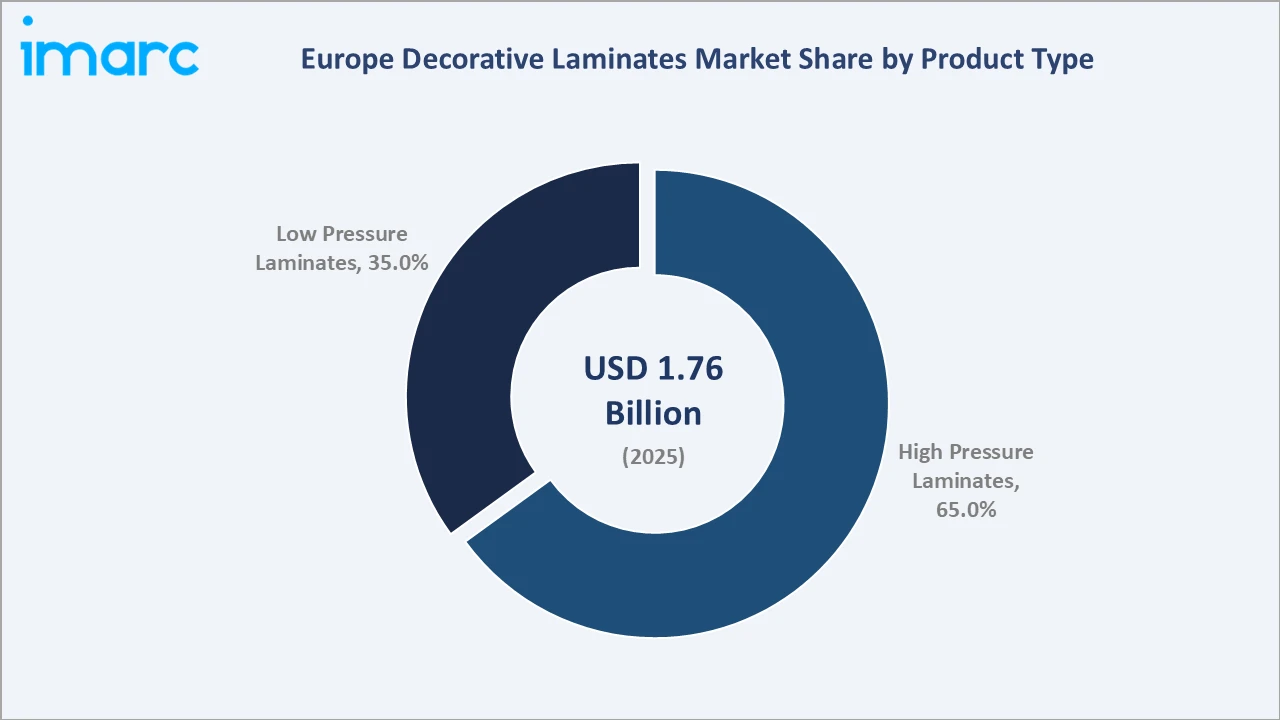
Expanding interior design aesthetics, digital printing innovation, and increasing preference for sustainable laminates with eco-certifications are further supporting market growth. Eastern Europe represents the next significant growth frontier for the industry. High Pressure Laminates dominate at 65.0%. Furniture and Cabinets lead application at 55.0%. Germany commands 30.0% of the regional market share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 1.76 Billion |
| Market Size (2026) | USD 1.86 Billion |
| Forecast Market Size (2034) | USD 2.46 Billion |
| CAGR (2026-2034) | 3.57% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Dominant Product Type | High Pressure Laminates (65.0%, 2025) |
| Dominant Application | Furniture and Cabinets (55.0%, 2025) |
| Leading Country | Germany (30.0%, 2025) |
The Europe Decorative Laminates Market size increased from USD 1.48 Billion in 2020 to USD 1.76 Billion in 2025 and is estimated to reach USD 1.86 Billion in 2026. The market is further expected to grow to USD 2.10 Billion by 2030 and USD 2.46 Billion by 2034. Europe's decorative laminates sector benefits from the convergence of sustainable construction mandates, urbanization-driven renovation demand, and premium interior design trends.
To get more information on this market, Request Sample
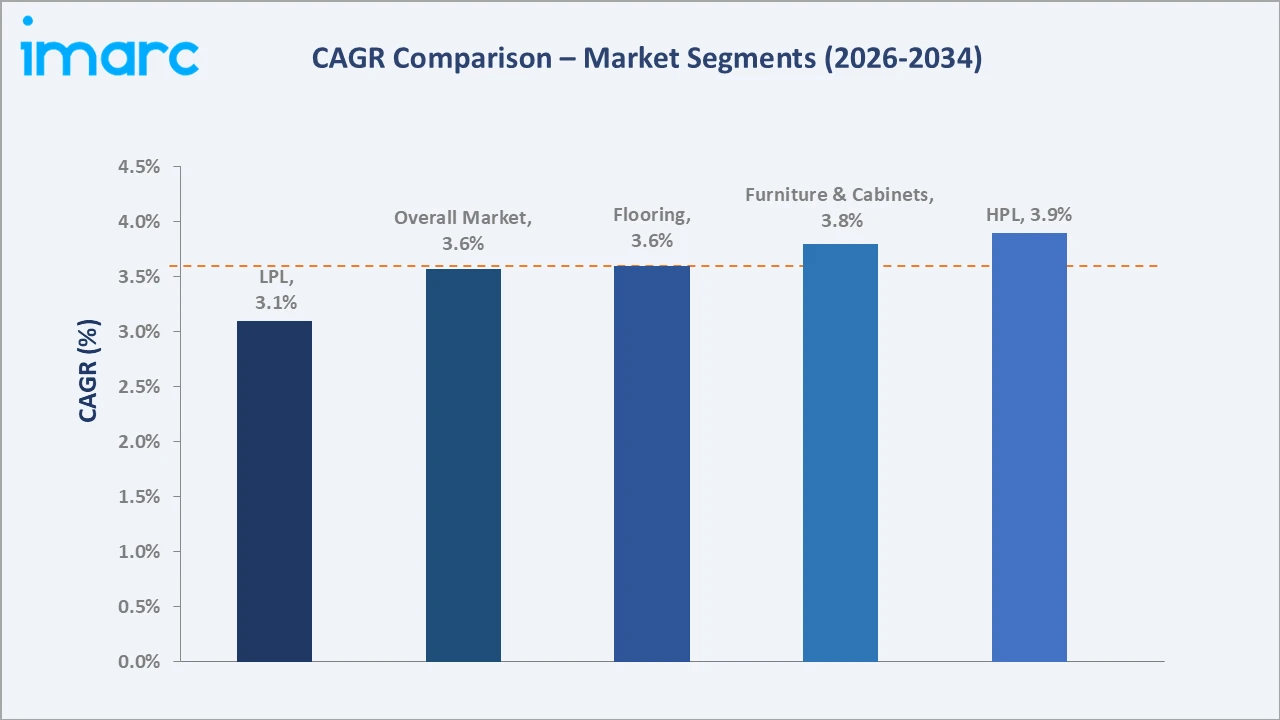
High Pressure Laminates segment leads at ~3.9% CAGR through construction-grade surface material demand and commercial interior specification requirements. Low Pressure Laminates expand at ~3.1% CAGR supported by the mass furniture segment and residential renovation markets. Furniture and Cabinets application segment grows at ~3.8% CAGR driven by Europe’s large furniture manufacturing base and rising demand for design-coordinated interior solutions. Flooring segment advances at ~3.6% CAGR supported by residential renovation activity and increasing preference for durable, low-maintenance laminate flooring across commercial spaces.
Executive Summary
The Europe Decorative Laminates Market expanded from USD 1.76 Billion in 2025 to an estimated USD 1.86 Billion in 2026, positioning Europe as one of the most commercially significant decorative surface material markets globally. The market’s scale is underpinned by Europe’s large furniture manufacturing base, the enduring specification of high-pressure laminates in commercial and institutional construction, and rising consumer demand for premium and eco-certified interior surfaces. These structural demand drivers are supporting the expansion of the High Pressure Laminates segment at a rate that outpaces Europe’s overall construction output growth. The Europe Decorative Laminates Market is commercially distinguished from other global decorative surface markets by its exceptionally high design standards and the influence of Europe’s export-oriented furniture industry on laminate specification. The market is projected to reach USD 2.46 Billion by 2034, registering a CAGR of 3.57% during 2026-2034. High Pressure Laminates at 65.0% leads through superior durability and broad commercial specification. Furniture and Cabinets at 55.0% reflects Europe’s design-forward furniture manufacturing base. Germany leads regionally at 30.0%.
Key Market Insights
| Insight | Data |
|---|---|
| Dominant Product Type | High Pressure Laminates – 65.0% share (2025) |
| Dominant Application | Furniture and Cabinets – 55.0% market share (2025) |
| Leading Country | Germany – 30.0% share (2025) |
| Market Opportunity | Premium and sustainable HPL products; Eastern European market expansion; digital printing and large-format laminate product lines |
Key Analytical Observations Supporting the Above Data:
- High Pressure Laminates at 65.0%: HPL dominates due to superior hardness, scratch resistance, and moisture performance, making it the preferred choice for commercial interiors, institutional environments, and premium residential applications. Its broad design versatility further supports specification by architects and interior designers across European markets.
- Furniture and Cabinets at 55.0%: The furniture application segment leads as Europe's large and export-oriented furniture manufacturing industry relies heavily on decorative laminates for kitchen cabinets, wardrobes, and work surfaces. Germany, Italy, and Poland are key production centers driving consistent laminate demand from furniture OEMs.
- Germany at 30.0%: Germany's market leadership reflects its position as Europe's largest furniture manufacturer and one of the most active construction and renovation markets in the region. Strong demand from both industrial furniture producers and commercial construction contractors sustains Germany's dominant share.
Europe Decorative Laminates Market Overview
The Europe decorative laminates market is positioned at the intersection of construction materials, furniture components, and interior design products. The market's commercial structure is characterized by significant demand from the furniture manufacturing sector, growing commercial construction activity, and increasing renovation spending across residential and institutional property segments. Europe's mature building stock, combined with regulatory incentives for energy-efficient renovation, creates sustained demand for surface upgrade materials including decorative laminates.
The market ecosystem integrates chemical and paper suppliers, specialized laminate manufacturers, distribution networks, and end-user segments including furniture OEMs, flooring contractors, and commercial interior fit-out companies. Germany, Italy, and Poland represent the primary manufacturing hubs, while Western European commercial construction and renovation projects drive the most significant demand volumes.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
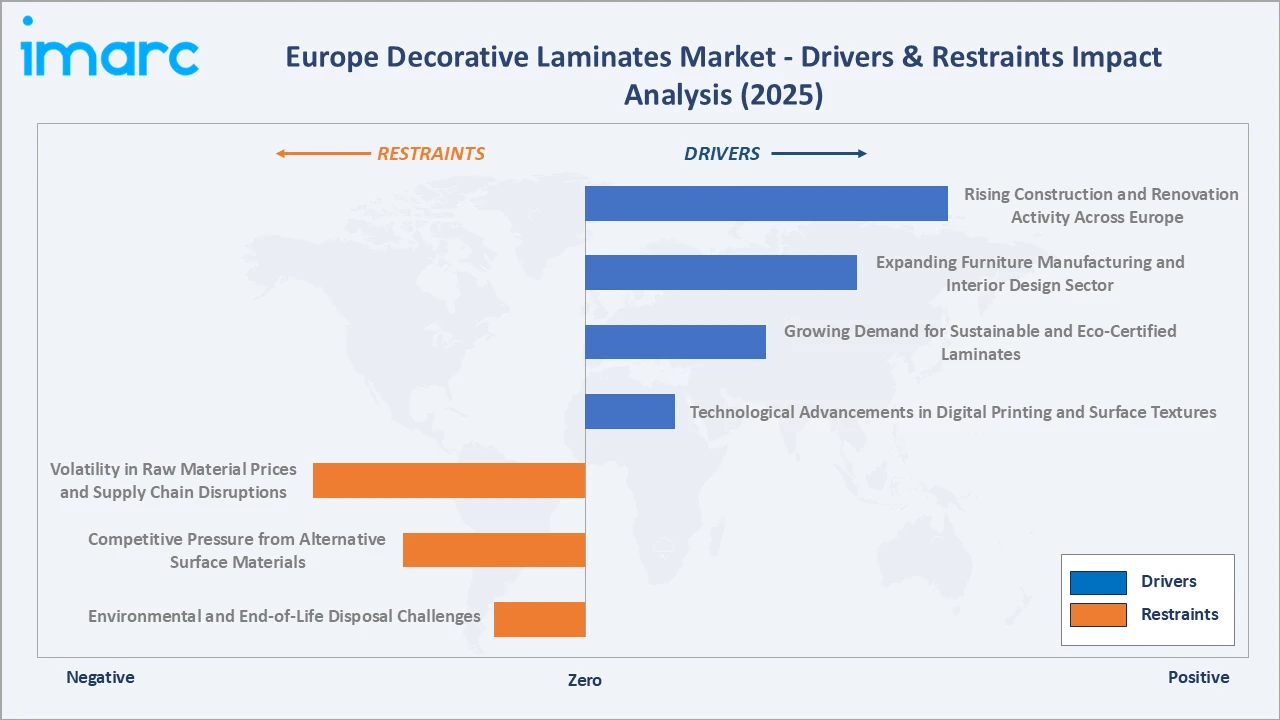
- Rising Construction and Renovation Activity Across Europe: Growing construction output and home renovation spending across Germany, France, and the UK are significantly expanding demand for decorative laminates in flooring, wall panels, and furniture applications. European residential renovation rates grew by over 4.0% annually in recent years, boosting surface material consumption. Decorative laminates benefit directly from the EU's push for sustainable building renovation under the Energy Efficiency Directive.
- Expanding Furniture Manufacturing and Interior Design Sector: Europe's furniture industry, valued at over EUR 95 Billion, is driving robust demand for high-quality decorative laminates used in cabinet, wardrobe, and worktop manufacturing. Growing urbanization and interior design consciousness among consumers are encouraging the adoption of premium surface materials. The trend toward modular furniture and custom interiors is further increasing laminate consumption per housing unit.
- Growing Demand for Sustainable and Eco-Certified Laminates: Increasing consumer preference for environmentally certified products is accelerating demand for laminates with low VOC emissions, recycled content, and FSC or PEFC certification. Regulatory standards such as EU REACH and the European Green Deal are prompting manufacturers to reformulate products for improved environmental performance. Green-certified laminates now command a premium of 8–12% over standard products, supporting revenue growth.
- Technological Advancements in Digital Printing and Surface Textures: Advances in digital printing technology are enabling manufacturers to produce laminates with photorealistic wood, stone, and abstract designs at competitive costs. High-definition surface textures, synchronized pore technology, and matte/gloss finish combinations are attracting premium-segment buyers in the hospitality and retail sectors. Such innovations reduce design lead times by up to 30%, enabling faster response to market trends.
Market Restraints
- Volatility in Raw Material Prices and Supply Chain Disruptions: Fluctuating prices of phenol, melamine, and paper substrates, key inputs for decorative laminates, introduce cost unpredictability for manufacturers. Supply chain disruptions from global logistics constraints have periodically increased input costs, squeezing operating margins for mid-size producers.
- Competitive Pressure from Alternative Surface Materials: Decorative laminates face growing competition from engineered stone, ceramic tiles, vinyl flooring, and solid surface materials. These alternatives offer comparable aesthetics with differing performance characteristics, limiting laminate penetration in certain premium applications.
- Environmental and End-of-Life Disposal Challenges: Thermosetting resins used in HPL production are difficult to recycle, creating end-of-life disposal challenges that are becoming a concern under evolving EU waste regulations. Increasing recycling mandates may raise compliance costs for laminate manufacturers operating in the European market.
Market Opportunities
- Growing Demand in Commercial and Hospitality Sectors: Rapid expansion of the European hospitality, retail, and healthcare construction sectors is creating sustained demand for durable and aesthetically versatile decorative laminates. High-traffic commercial interiors require surface materials that combine design flexibility with performance durability, where HPL has distinct advantages.
- Penetration into Eastern European Emerging Markets: Eastern European markets including Poland, Czech Republic, and Romania are undergoing rapid urbanization and housing development, creating new growth frontiers for decorative laminate manufacturers. Lower market saturation compared to Western Europe offers significant volume growth potential.
- Premium and Customized Product Lines for Design-Conscious Consumers: Growing consumer demand for personalized interior spaces is creating opportunities for manufacturers to develop premium, design-forward laminate collections. High-margin specialty products such as anti-fingerprint matte surfaces, large-format panels, and coordinated décor ranges offer strong revenue upside.
Market Challenges
- Maintaining Compliance with Evolving Environmental Regulations: Increasingly stringent EU environmental and chemical safety standards require continuous product reformulation and testing investment. Smaller manufacturers face disproportionate compliance burdens, while all players must invest in green chemistry expertise to maintain market access.
- Managing Production Cost Inflation and Energy Price Volatility: Laminate manufacturing is energy-intensive, and European energy price volatility has increased production costs significantly. Maintaining product competitiveness while absorbing higher energy costs remains a structural challenge across the industry.
Emerging Market Trends
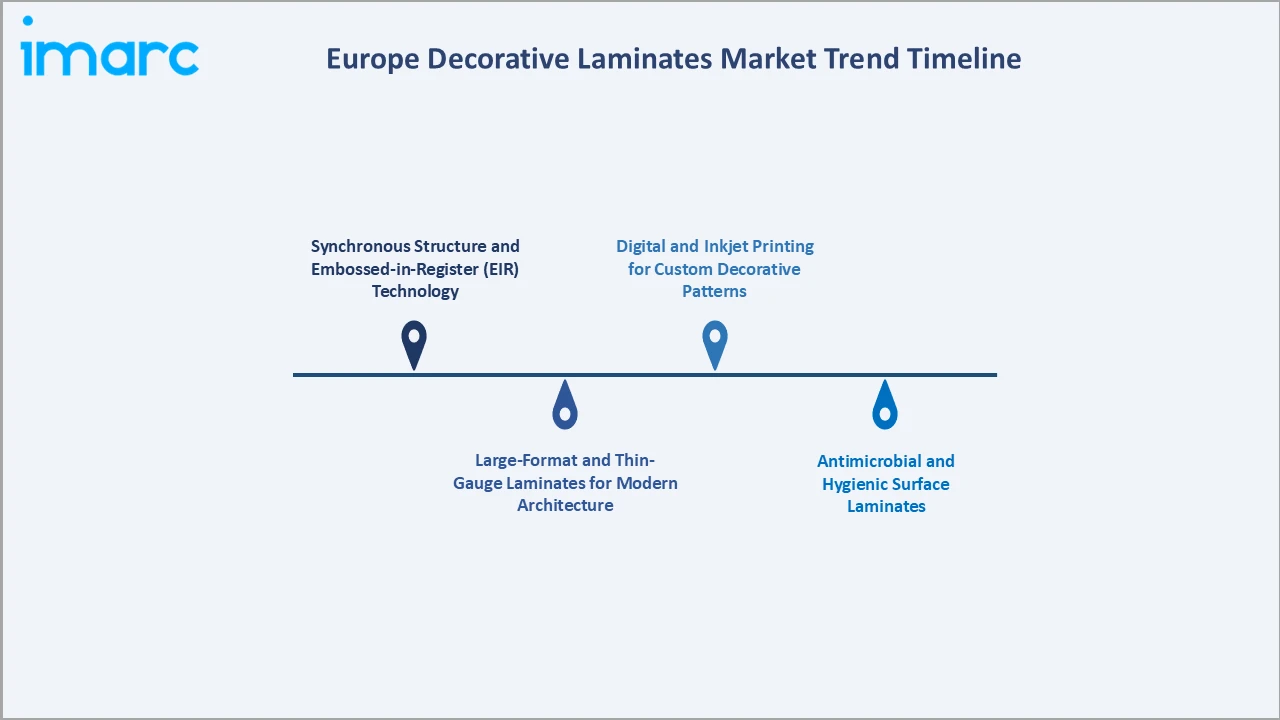
1. Synchronous Structure and Embossed-in-Register (EIR) Technology
Synchronous structure technology enables decorative laminates to replicate the tactile feel of real wood, stone, and fabric with near-perfect surface texture alignment. EIR laminates are gaining rapid adoption in premium furniture and flooring segments across Germany and Scandinavia, where authenticity of surface texture is a key purchase driver. This innovation supports a price premium of 15–25% over conventional laminates.
2. Large-Format and Thin-Gauge Laminates for Modern Architecture
Growing architectural preference for seamless, continuous surface coverage is driving demand for large-format decorative laminates. Thin-gauge HPL panels (0.5–1.2 mm) are gaining share in furniture overlay and wall cladding applications, offering design flexibility with reduced material weight. European furniture manufacturers are increasingly specifying large-format panels to create seamless cabinetry aesthetics.
3. Antimicrobial and Hygienic Surface Laminates
Post-pandemic emphasis on hygienic environments has accelerated adoption of antimicrobial decorative laminates in healthcare, education, and food service sectors. Silver-ion and copper-based antimicrobial treatments embedded in laminate surfaces provide continuous pathogen reduction without affecting aesthetics. Demand for hygienic surfaces in European healthcare infrastructure investments supports long-term growth for this product category.
4. Digital and Inkjet Printing for Custom Decorative Patterns
Digital inkjet printing technology is transforming decorative laminate production by enabling cost-effective short runs of customized designs. Manufacturers can now offer virtually unlimited design options including photographic imagery, brand-specific patterns, and customer-uploaded designs without tooling costs. This capability is particularly valued in retail fit-out and branded hospitality environments across Western Europe.
Industry Value Chain Analysis
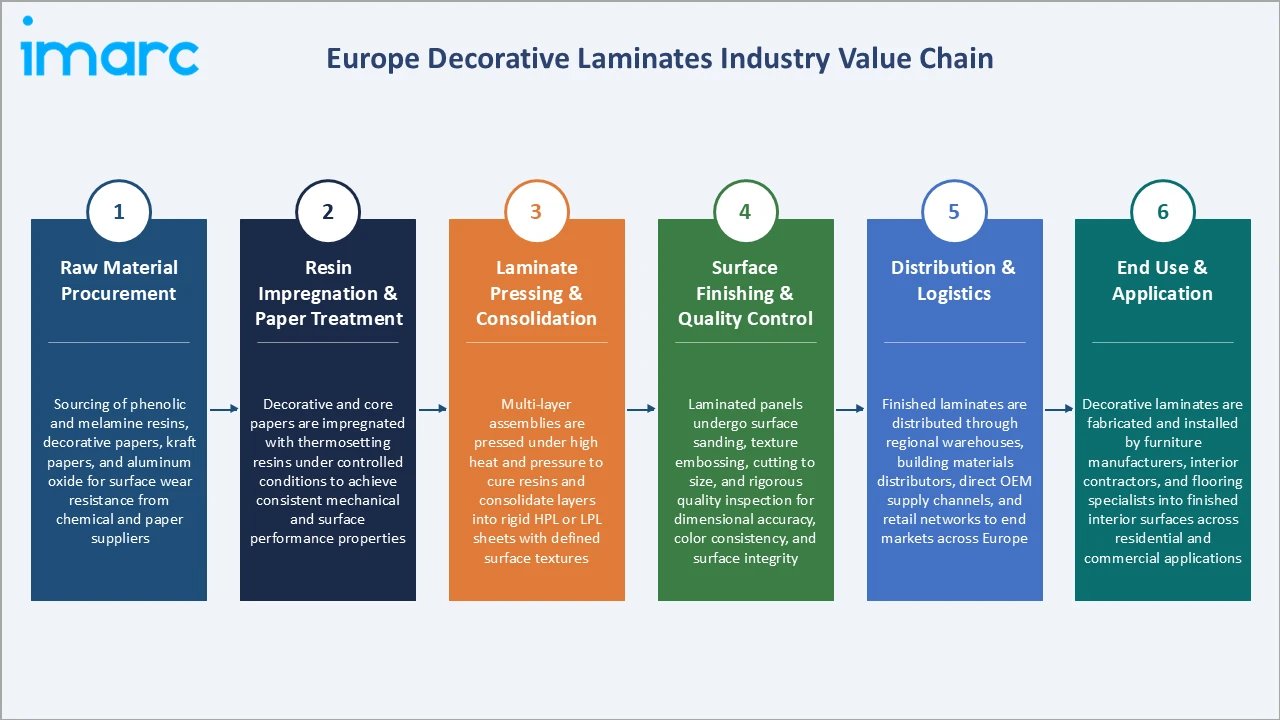
The decorative laminates industry value chain spans raw material extraction through consumer end use, with value addition concentrated in the resin impregnation and pressing stages where proprietary processes determine surface quality and performance characteristics. The chain's commercial structure creates differentiation opportunities through design capability, sustainability certification, and technical performance across each production stage.
| Stage | Key Participants / Activities |
|---|---|
| Raw Material Procurement | Sourcing of phenolic and melamine resins, decorative papers, kraft papers, and aluminum oxide for surface wear resistance from chemical and paper suppliers. |
| Resin Impregnation & Paper Treatment | Decorative and core papers are impregnated with thermosetting resins under controlled conditions to achieve consistent mechanical and surface performance properties. |
| Laminate Pressing & Consolidation | Multi-layer assemblies are pressed under high heat and pressure to cure resins and consolidate layers into rigid HPL or LPL sheets with defined surface textures. |
| Surface Finishing & Quality Control | Laminated panels undergo surface sanding, texture embossing, cutting to size, and rigorous quality inspection for dimensional accuracy, color consistency, and surface integrity. |
| Distribution & Logistics | Finished laminates are distributed through regional warehouses, building materials distributors, direct OEM supply channels, and retail networks to end markets across Europe. |
| End Use & Application | Decorative laminates are fabricated and installed by furniture manufacturers, interior contractors, and flooring specialists into finished interior surfaces across residential and commercial applications. |
Surface finishing and quality control represents the value chain's most commercially consequential stage, where manufacturers invest in advanced embossing technology, precision color management, and rigorous quality inspection systems. Leading manufacturers spend 10-18% of revenue on surface design development, enabling design-driven differentiation in a market where aesthetic performance increasingly determines product positioning and pricing power.
Technology Landscape in the Europe Decorative Laminates Industry
Thermosetting Resin Technology and HPL Engineering
High-pressure laminate technology remains the cornerstone of the decorative laminates industry, relying on thermosetting phenolic and melamine resin systems that deliver exceptional durability and surface hardness. Advanced resin formulations now enable improved moisture resistance, reduced formaldehyde emissions, and enhanced bond strength between laminate layers. European manufacturers are investing in bio-based resin alternatives to address sustainability requirements, with some producers achieving significant reductions in fossil-derived inputs across their HPL production lines.
Digital Printing and Surface Decoration Technology
Industrial digital inkjet printing is revolutionizing decorative surface production by enabling high-resolution imagery and unlimited design variety at commercial scale. Printing systems integrated with laminate press lines allow manufacturers to respond rapidly to design trends and offer customized decor collections with minimal tooling investment. European producers are deploying advanced color management systems to ensure design consistency across production batches, meeting the stringent requirements of furniture industry customers.
Nano-coating and Functional Surface Technologies
Nano-ceramic and nano-silica coating technologies are enabling next-generation decorative laminate surfaces with enhanced scratch resistance, anti-fingerprint properties, and self-cleaning capabilities. Functional laminates incorporating phase-change materials for thermal regulation and conductive layers for smart surface applications represent emerging technology frontiers. These innovations target high-value commercial and healthcare applications where surface performance requirements extend beyond aesthetics.
Sustainable Manufacturing and Circular Economy Technologies
European laminate manufacturers are adopting closed-loop water recycling systems, solvent recovery technologies, and biomass energy utilization to reduce environmental impact. Developments in thermoplastic laminate formulations aim to create recyclable surface materials that can re-enter material cycles at end of life. Certification systems including EPD (Environmental Product Declarations) are being adopted by leading manufacturers to communicate verified environmental performance data to specification-led commercial customers.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Product Type | High Pressure Laminates | 65.0% | 2025 |
| Application | Furniture and Cabinets | 55.0% | 2025 |
| End Use | Residential | 🔒 | 2025 |
| Texture | Matte/Suede | 🔒 | 2025 |
| Pricing | Premium | 🔒 | 2025 |
| Sector | Organized | 🔒 | 2025 |
| Country | Germany | 30.0% | 2025 |

By Product Type
High Pressure Laminates lead at 65.0% (2025). HPL's dominant position reflects its superior performance characteristics including high surface hardness (>130 Brinell), impact resistance, and broad design versatility that make it the specification material of choice for commercial interiors, healthcare facilities, and premium residential applications across Europe.
To access detailed market analysis, Request Sample
Low Pressure Laminates at 35.0% serve the mass furniture manufacturing segment with cost-effective decorative surfaces. LPL growth at ~3.1% CAGR is supported by the expanding flat-pack furniture industry and residential renovation activity across Europe's growing housing markets in Eastern and Central Europe.
By Application
Furniture and Cabinets dominate at 55.0% (2025). This segment reflects Europe's globally significant furniture industry, where decorative laminates are the primary surface material for kitchen cabinets, wardrobes, office furniture, and modular storage systems. Growing demand for design-coordinated interior packages is further expanding laminate consumption per residential and commercial project.
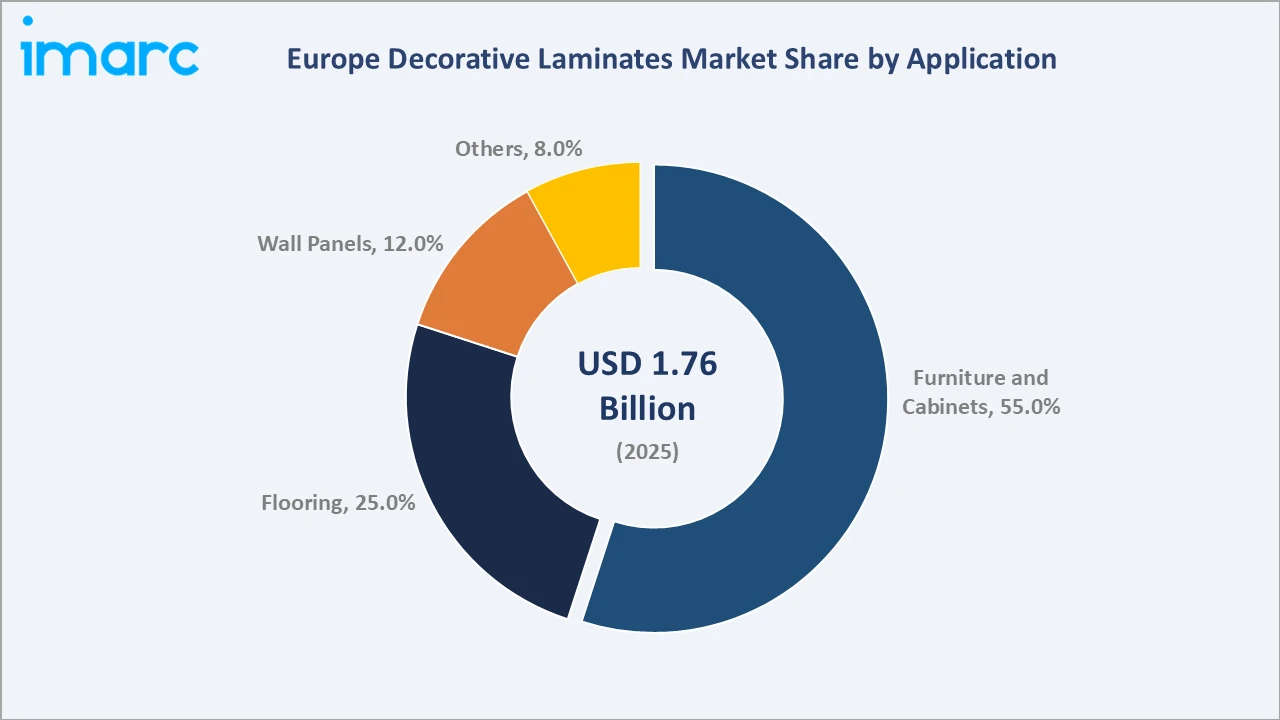
Flooring at 25.0% grows at ~3.6% CAGR through renovation activity and demand for durable, low-maintenance floor surfaces in commercial and residential applications. Wall Panels at 12.0% benefits from commercial construction and healthcare sector specification. Others at 8.0% encompasses retail fixtures, transportation interiors, and laboratory surfaces.
Regional Market Insights
| Country | Share (2025) | Key Market Drivers & Characteristics |
|---|---|---|
| Germany | 30.0% | Germany is the dominant market, driven by its large furniture manufacturing industry—one of Europe's most significant—and robust construction activity. High adoption of HPL surfaces in premium furniture, commercial interiors, and public infrastructure supports strong volume demand. |
| France | 17.0% | France's market is supported by active residential renovation activity and a sophisticated interior design culture. Growing demand for premium-finish laminates in kitchen furniture, retail interiors, and hospitality fit-outs underpins the country's substantial market share. |
| United Kingdom | 15.0% | The UK market benefits from sustained commercial construction activity and strong demand from the hospitality and healthcare sectors. Post-pandemic renovation spending and institutional infrastructure investment continue to support decorative laminate consumption. |
| Italy | 13.0% | Italy's design-focused furniture manufacturing industry drives significant demand for high-aesthetic decorative laminates. Italian furniture brands are major consumers of premium HPL and textured laminate surfaces for export-oriented production. |
| Spain | 10.0% | Spain's growing construction sector and recovering hospitality industry are supporting increasing laminate consumption. Rising investment in commercial and tourism infrastructure is expanding demand for durable decorative surface solutions. |
| Others | 15.0% | Other European markets including the Netherlands, Poland, Belgium, and Scandinavia collectively represent a significant share, supported by ongoing urbanization, infrastructure development, and expanding furniture manufacturing in Eastern Europe. |
Germany's 30.0% market leadership reflects its position as Europe's largest furniture manufacturing nation and a major construction market. France's 17.0% share is supported by active residential renovation and a sophisticated interior design culture. The UK's 15.0% reflects commercial construction demand and healthcare sector specification.
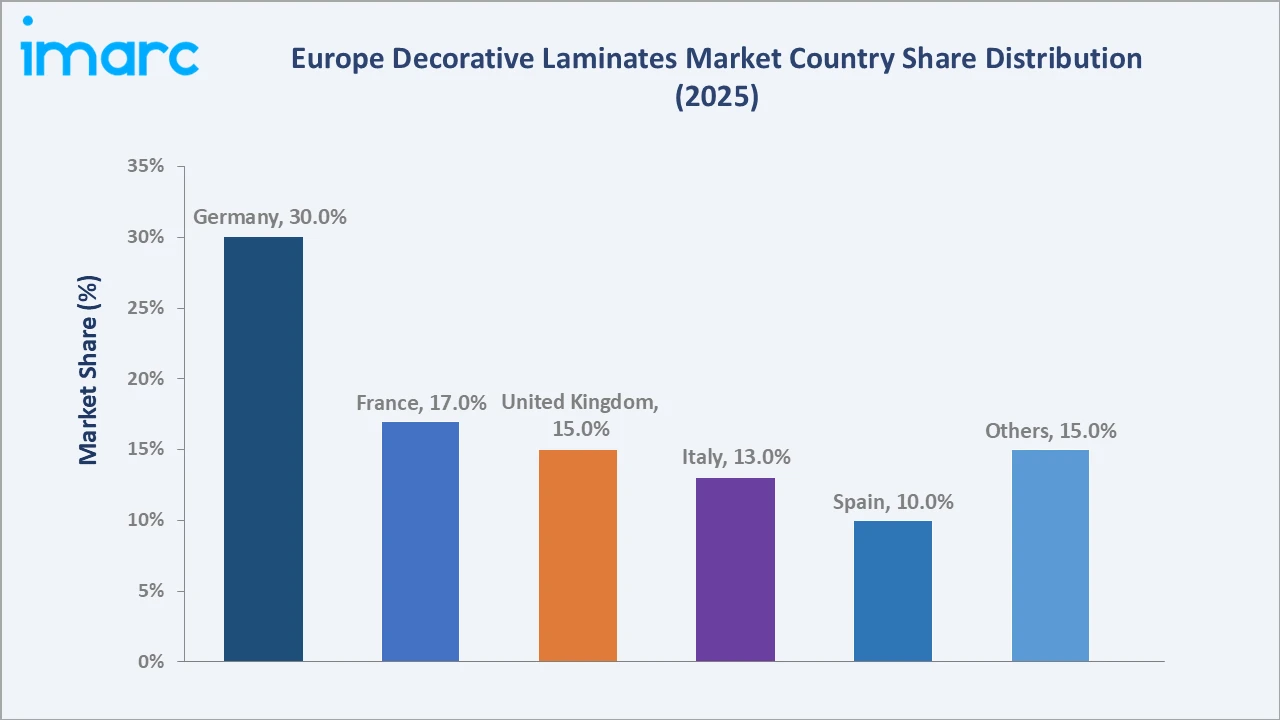
Italy's 13.0% reflects the country's globally recognized furniture manufacturing industry and strong export-oriented production that consumes premium decorative laminates. Spain at 10.0% benefits from recovering construction and hospitality sectors. Other European markets collectively hold 15.0%, with Poland and the Netherlands representing the fastest-growing individual markets within this group.
Competitive Landscape
The Europe decorative laminates competitive landscape is characterized by a combination of integrated wood-based panel manufacturers with laminate divisions and specialized laminate producers. Competition is intensifying through investment in digital design capabilities, sustainable product certification, and geographic expansion into Eastern European markets where construction and furniture manufacturing is growing rapidly.
| Company | Key Product Lines | Market Position | Core Strength |
|---|---|---|---|
| Abet Laminati S.p.A. | Compact HPL, Postforming Laminates, Digital Print Surfaces | Market Leader | Abet Laminati S.p.A. leads the European decorative laminates market with its premium HPL product portfolio and extensive design innovation across residential and commercial segments. |
| EGGER Group | MFC Boards, Laminates | Market Leader | EGGER Group leverages vertically integrated manufacturing and sustainable forestry practices to deliver high-quality wood-based laminates across Europe. |
| Formica Group | Formica HPL, Infiniti Surfaces, DecoMetal Laminates | Strong Challenger | Formica Group commands strong brand recognition in Europe through its diverse range of high-pressure laminates for interior design and furniture applications. |
| FunderMax GmbH | Interior HPL, Exterior Compact Panels, Fx Facade Systems | Innovator | FunderMax GmbH specializes in compact high-pressure laminates for exterior cladding and interior surfaces, known for durability and architectural innovation. |
| Pfleiderer GmbH | Melamine-Faced Boards, HPL Panels | Strong Challenger | Pfleiderer GmbH offers a comprehensive range of wood-based panel products with decorative laminate surfaces, serving the furniture and construction sectors across Germany and Europe. |
The competitive landscape is evolving as large integrated manufacturers leverage sustainability certification and scale advantages, while specialty HPL producers differentiate through design innovation and technical performance. Digital printing capabilities are becoming a key competitive differentiator, enabling manufacturers to offer broader design portfolios with shorter lead times, supporting premium pricing in design-sensitive market segments.
Key Company Profiles
Abet Laminati S.p.A.
Abet Laminati S.p.A. is an Italian decorative laminates manufacturer with deep expertise in high-pressure laminate production. The company serves residential, commercial, and institutional markets across Europe with a broad product portfolio spanning standard and specialty HPL surfaces.
- Key Product Lines: Compact HPL, Standard HPL, Postforming Laminates, Digital Print Surfaces, Exterior Laminates.
- Recent Developments: In 2025, Abet Laminati S.p.A. expanded its digital print collection with new photorealistic stone and concrete décors, targeting the premium hospitality and retail fit-out segments across Western Europe.
- Strategic Focus: Maintaining design leadership in HPL surfaces through continuous collection renewal and investment in digital printing technology, while expanding distribution reach across Southern and Eastern European markets.
EGGER Group
EGGER Group is a leading European manufacturer of wood-based panels and decorative surfaces, operating an integrated production model from timber sourcing to finished surface materials. The company serves furniture manufacturers, flooring producers, and construction markets across Europe and globally.
- Key Product Lines: MFC Boards, HPL Panels, LPL Surfaces, Edgebanding, Flooring Systems, Compact Laminates.
- Recent Developments: In 2026, EGGER Group introduced its Decorative Collection 26+, expanding its decorative surface portfolio with new designs, textures and laminate solutions for furniture manufacturing and interior design. The collection includes 12 new thermally fused laminate (TFL) decors, comprising eight woodgrain designs and four solid colours. A key innovation is the ST17 Omnipore Oiled texture, which replicates the natural appearance and feel of oiled wood veneer. The collection also expands design flexibility for residential and commercial interiors, supporting applications such as cabinetry, furniture and interior surfaces.
- Strategic Focus: Leveraging vertical integration and certified sustainable manufacturing to strengthen market position in specification-led commercial and institutional construction segments, while expanding laminate design collections for the residential furniture sector.
Formica Group
Formica Group is a globally recognized brand in high-pressure laminates, with a significant manufacturing and commercial presence across Europe. The company supplies HPL surfaces to furniture manufacturers, commercial interior contractors, and architectural specification markets through an established pan-European distribution network.
- Key Product Lines: Formica HPL, Infiniti Surfaces, DecoMetal Laminates, Formica Compact, Postforming HPL.
- Recent Developments: In 2026, Formica Group introduced FENIX® NTX, an innovative decorative surfacing material featuring up to 90% bio-based content, an ultra-matte finish and a soft-touch surface. Launched following its introduction at NeoCon 2026, the product expands the company's sustainable materials portfolio with its first woodgrain designs for the FENIX range, alongside established solid colours. Designed for residential and commercial interiors, the material can be used in furniture, cabinetry, architectural millwork, doors, drawer fronts and wall panels. The launch highlights Formica Group's focus on combining design versatility, durability and more sustainable material solutions in the decorative surfaces industry.
- Strategic Focus: Growing market share in the commercial and healthcare specification segments through technical performance marketing, sustainable product certification, and digital design tools that enable architects and interior designers to visualize laminate applications.
Market Concentration Analysis
The Europe decorative laminates market exhibits a moderately consolidated competitive structure, with a combination of large integrated panel manufacturers and specialized laminate producers competing across product quality, design breadth, and distribution reach. Market concentration is highest in the HPL segment, where capital-intensive production infrastructure and brand recognition create meaningful barriers to entry for new competitors.
Competitive dynamics are evolving as consolidation among major players continues and digital printing capabilities democratize design differentiation. Mid-size regional manufacturers compete effectively by focusing on rapid customization and local service capabilities, while large groups leverage scale and vertical integration to maintain cost competitiveness in standard product ranges. The market balance between HPL specialists and integrated wood-panel manufacturers is expected to evolve as sustainability requirements increasingly favor large, certified production operations.
Investment & Growth Opportunities
Highest Growth Segments
High Pressure Laminates (~3.9% CAGR through commercial construction and institutional specification demand), Furniture and Cabinets application (~3.8% CAGR through furniture manufacturing expansion and renovation activity), Flooring segment (~3.6% CAGR through residential and commercial renovation), and Eastern European market penetration (~5-7% CAGR through urbanization-driven construction growth) represent Europe's highest-growth decorative laminate investment vectors through 2034.
Emerging Investment Opportunities
Europe's premium sustainable laminate segment, growing at above-market rates as green building certifications become standard in commercial construction specifications, represents a compelling investment opportunity. Manufacturers with established eco-certification credentials and EPD-verified products are well-positioned to capture premium pricing in the growing sustainable interior materials specification market.
Investment Themes
- Premium and sustainable HPL product development targeting the commercial construction specification market: Growing adoption of BREEAM, DGNB, and other green building certification schemes across Europe is creating structural demand for laminates with verified environmental performance credentials, supporting premium pricing for certified products.
- Eastern European market expansion through local distribution and production investment: Rapid urbanization, housing development, and furniture manufacturing growth in Poland, Romania, Czech Republic, and the Balkans offer significant volume growth opportunities for manufacturers that establish local supply chain presence ahead of demand maturation.
Future Market Outlook (2026-2034)
The Europe Decorative Laminates Market is projected to grow from USD 1.76 Billion in 2025 to USD 1.86 Billion in 2026, reaching USD 2.46 Billion by 2034, registering a CAGR of 3.57% during 2026-2034. The market's anchor value of USD 2.10 Billion in 2030 reflects the decorative laminates industry at a structural inflection point, where sustainability-driven product innovation and Eastern European construction growth converge to accelerate demand expansion.
Three structural forces define Europe decorative laminates market growth through 2034 the EU's Renovation Wave initiative, creating sustained surface material demand through mandated building energy efficiency upgrades; the European furniture industry's continued design innovation, maintaining laminate specification as the standard surface solution; and Eastern Europe's rapid construction market development, creating new volume growth beyond the mature Western European markets.
Research Methodology
Primary Research
Primary research comprised structured interviews with Europe decorative laminates industry stakeholders including procurement managers at furniture OEMs, commercial interior contractors, laminate product managers, and distribution channel representatives across Germany, France, the UK, Italy, and Spain. Consumer research and specification data from major European construction and renovation projects were also incorporated to validate demand-side estimates.
Secondary Research
Secondary research encompassed European construction statistics, furniture industry trade association data, company annual reports, product certification databases, European laminate trade association publications, and customs import/export records for decorative surface materials. Over 45 secondary sources were reviewed to triangulate market size and segment share estimates.
Forecasting Models
Market revenue forecasts were developed using a bottom-up demand model incorporating construction output projections by country, renovation rate assumptions, furniture production volumes, and laminate consumption intensity per unit of end-use activity. The model was calibrated against historical production and trade data, with segment growth rates adjusted for application-specific demand drivers and validated through expert interviews with industry participants across the European market.
Europe Decorative Laminates Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
|
Scope of the Report
|
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | High Pressure Laminates, Low Pressure Laminates |
| Applications Covered | Furniture and Cabinets, Flooring, Wall Panels, Others |
| End Uses Covered | Non-Residential, Residential, Transportation |
| Textures Covered | Matte/Suede, Glossy |
| Pricings Covered | Premium, Mass |
| Sectors Covered | Organised, Unorganised |
| Countries Covered | Germany, France, United Kingdom, Italy, Spain,Others |
| Companies Covered | Abet Laminati S.p.A., EGGER Group, Formica Group, FunderMax GmbH, Pfleiderer GmbH, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Europe decorative laminates market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Europe decorative laminates market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Europe decorative laminates industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Europe Decorative Laminates Market Report
The Europe decorative laminates market reached USD 1.76 Billion in 2025, supported by robust furniture manufacturing, construction activity, and rising demand for premium surface aesthetics.
The Europe decorative laminates market is projected to grow at a CAGR of 3.57% during 2026-2034, reaching USD 2.46 Billion by 2034.
High Pressure Laminates lead with a 65.0% market share in 2025, driven by superior durability and broad application across furniture, flooring, and wall panel segments.
Furniture and Cabinets dominate with a 55.0% share in 2025, supported by Europe's large and design-conscious furniture manufacturing industry.
Germany leads with a 30.0% market share in 2025, driven by its large furniture manufacturing base and strong construction sector demand.
The Europe decorative laminates market is projected to reach approximately USD 2.10 Billion by 2030, supported by growing renovation spending and sustainable product demand.
Leading companies include Abet Laminati S.p.A., EGGER Group, Formica Group, FunderMax GmbH, and Pfleiderer GmbH.
Key drivers include rising construction and renovation activity, expanding furniture manufacturing, growing demand for sustainable laminates, and technological advances in surface decoration.
Primary restraints include raw material price volatility, competition from alternative surface materials, and end-of-life disposal challenges under evolving EU regulations.
Key opportunities include premium product development, expansion into Eastern European markets, and investment in sustainable and digitally printed laminate product lines.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade