
Japan 3D Scanning Market Size, Share, Trends and Forecast by Type, Range, Application, End Use Industry, and Region, 2026-2034
Japan 3D Scanning Market Size, Share, Trends & Forecast (2026-2034)
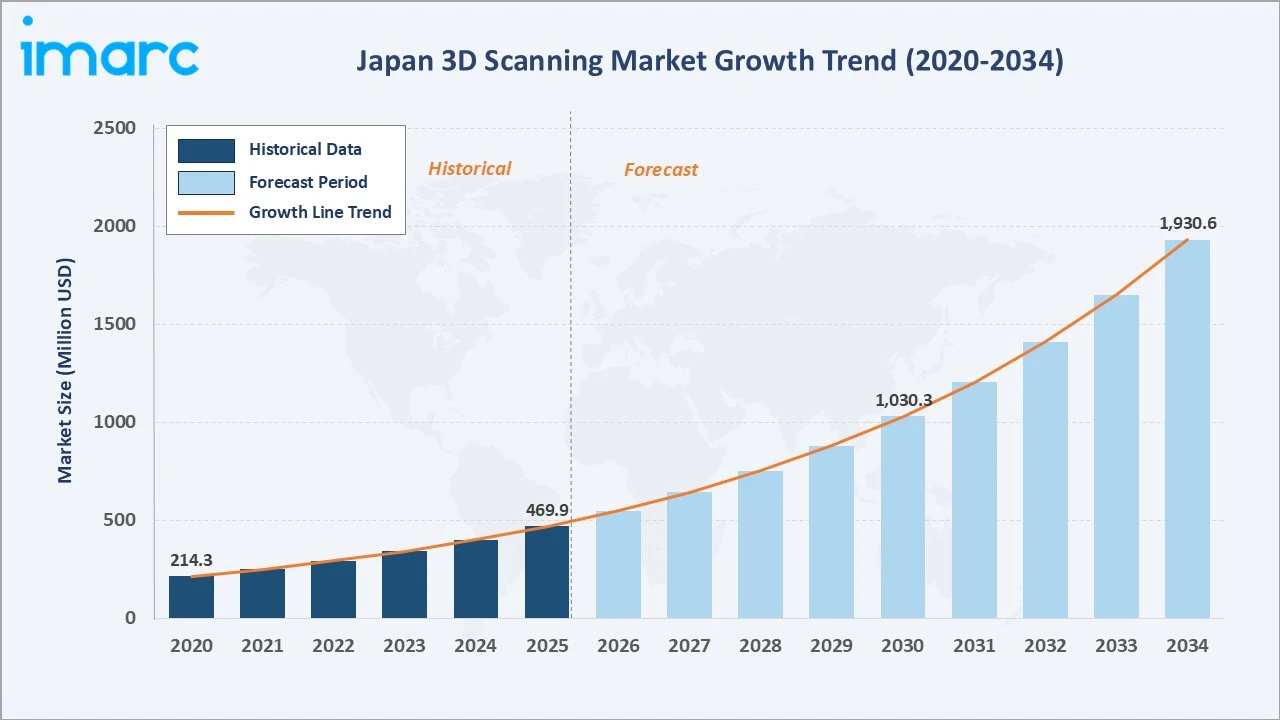
The Japan 3D scanning market grew from USD 469.9 Million in 2025 to USD 549.8 Million in 2026 and is projected to reach USD 1,930.6 Million by 2034, growing at a CAGR of 17.00% during 2026-2034. Demand is driven by accelerating industrial automation, expanding electric vehicle manufacturing, and broad adoption of digital twin technology across aerospace, automotive, and healthcare sectors. Hardware dominates at 68.4% in 2025. Short range scanning leads by range at 42.8%. The Kanto region accounts for 38.5% of the 2025 market, reflecting the dense manufacturing and technology base.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 469.9 Million |
|
Market Size (2026) |
USD 549.8 Million |
|
Forecast Market Size (2034) |
USD 1,930.6 Million |
|
CAGR (2026-2034) |
17.00% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Hardware (68.4%, 2025) |
|
Dominant Range |
Short Range (42.8%, 2025) |
|
Leading Region |
Kanto (38.5%, 2025) |
The Japan 3D scanning market grew from USD 214.3 Million in 2020 to USD 469.9 Million in 2025, and further to USD 549.8 Million in 2026, reflecting sustained investments in advanced manufacturing technologies. The market is projected to reach USD 1,030.3 Million by 2030 before achieving USD 1,930.6 Million by 2034.
To get more information on this market, Request Sample
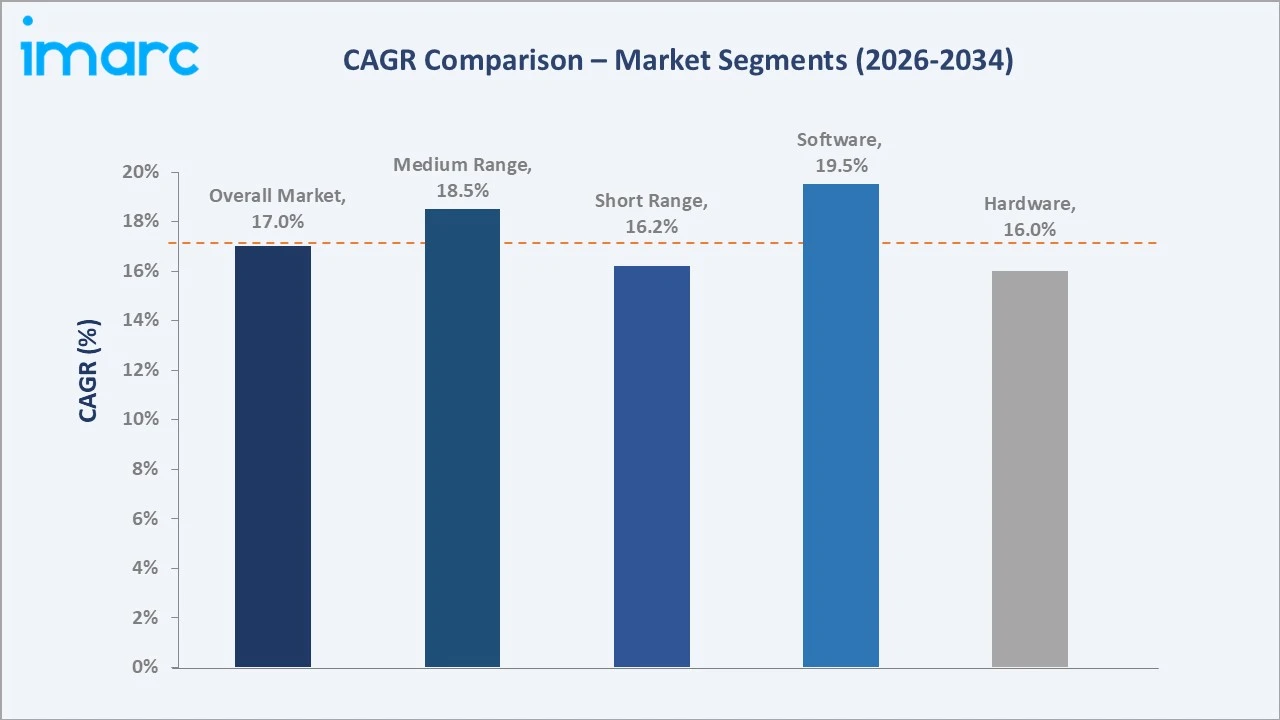
Software grows at approximately 19.5% CAGR, outpacing the overall market as 3D scanning software platforms gain adoption in cloud-based data processing, AI-driven defect detection, and digital twin workflows. Hardware maintains solid momentum at ~16.0% CAGR driven by new-generation LiDAR and structured light scanner deployments.
Executive Summary
The Japan 3D scanning market is on a high-growth trajectory, underpinned by the nation's world-class manufacturing industry, accelerating EV production cycles, and national digitalization mandates driving adoption across industrial, healthcare, and infrastructure verticals. The market expanded, reflecting strong investment in precision measurement technologies.
Hardware holds 68.4% of the market in 2025, driven by demand for laser scanners, structured light systems, and optical measurement tools deployed across automotive assembly, aerospace manufacturing, and quality control operations. Short range scanners lead at 42.8%, while medium range at 34.6% and long range at 22.6% serve infrastructure and civil engineering applications. The Kanto region at 38.5% commands the largest regional share, anchored by dense automotive, electronics, and aerospace manufacturing activity in Greater Tokyo.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Hardware – 68.4% share (2025) |
|
Dominant Range |
Short Range – 42.8% share (2025) |
|
Leading Region |
Kanto Region – 38.5% (2025) |
|
Key Market Opportunity |
Industrial automation, digital twin integration, and EV manufacturing are creating sustained demand for high-precision 3D scanning solutions across Japan. |
Key Analytical Observations Supporting the Above Data:
- Hardware at 68.4%: Hardware dominates because 3D scanners, LiDAR systems, structured light devices, and optical digitizers form the foundational measurement tools required in quality control, reverse engineering, and inspection workflows across Japan's precision manufacturing industries.
- Short Range at 42.8%: Short range scanners are preferred for detailed part inspection, component measurement, and surface analysis tasks in automotive and electronics manufacturing, where sub-millimeter accuracy and compact form factors are essential.
- Kanto Region at 38.5%: The Kanto region's leadership reflects its concentration of advanced automotive OEMs, electronics manufacturers, aerospace facilities, and technology companies that are the primary adopters of 3D scanning across Japan.
Japan 3D Scanning Market Overview
The Japan 3D scanning market encompasses hardware devices, including laser scanners, structured light systems, optical scanners, and LiDAR, as well as associated software platforms used for point cloud processing, 3D modeling, inspection, and digital twin development. Applications span reverse engineering, rapid prototyping, quality control, face and body scanning, and large-scale infrastructure digitalization across aerospace, automotive, healthcare, media, and construction industries.
Japan's advanced manufacturing base provides a strong structural demand foundation. National digitalization initiatives and Industry 4.0 adoption are accelerating 3D scanning integration into smart factory environments, driving consistent investment across both hardware refresh cycles and software platform upgrades.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
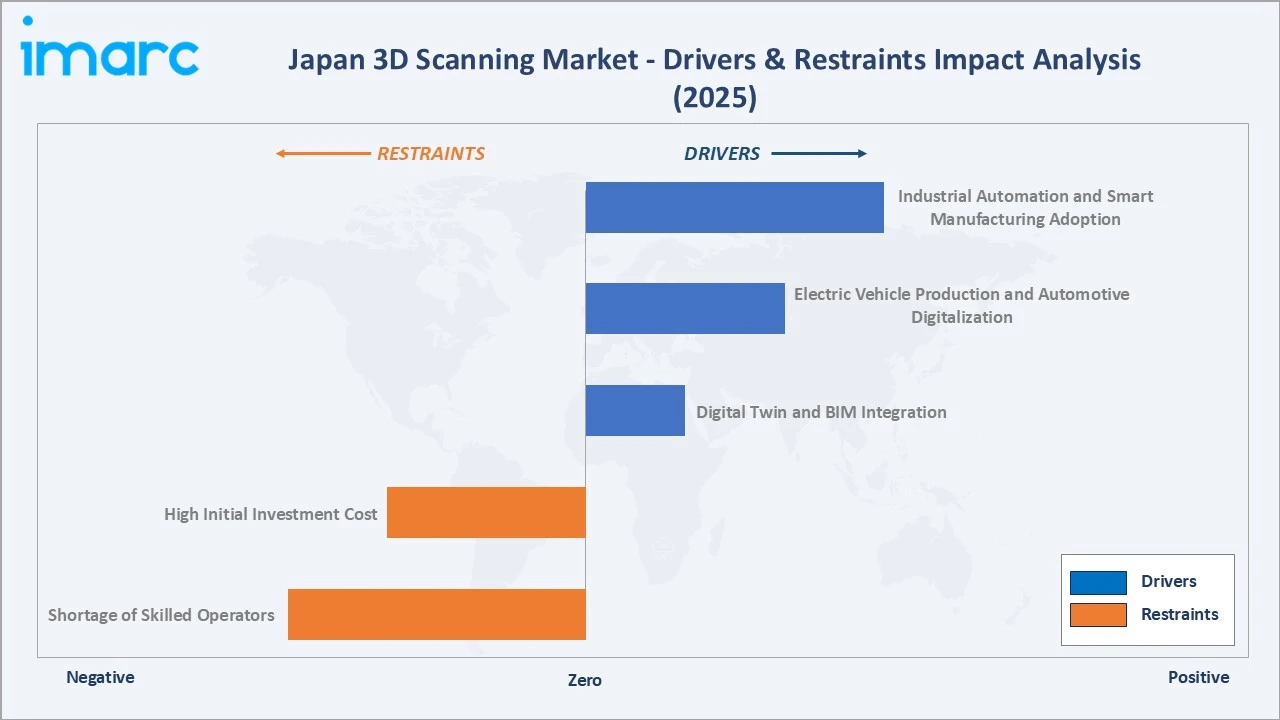
- Industrial Automation and Smart Manufacturing Adoption: Japan's manufacturing sector continues to invest heavily in automation and Industry 4.0 technologies, with 3D scanning integrated into automated quality control lines, robotic guidance systems, and digital factory environments. Precision measurement supports zero-defect manufacturing goals across automotive and electronics production.
- Electric Vehicle Production and Automotive Digitalization: Japan recorded over 100,000 EV sales in 2025, representing less than 3% of new-car sales, while hybrid vehicles continued to dominate, accounting for approximately one-third of the market. The rapid transition to EV production is generating demand for high-precision 3D scanning across battery cell inspection, motor component measurement, and body panel quality control. Major Japanese OEMs are integrating scanning technologies into new EV assembly lines requiring tighter dimensional tolerances.
- Digital Twin and BIM Integration: Government-backed digitalization programs and private sector investment in digital twin technology are creating broad demand for 3D scanning as the primary data capture method for creating accurate digital replicas of facilities, assets, and infrastructure.
Market Restraints
- High Initial Investment Cost: Advanced 3D scanning systems, particularly industrial-grade laser scanners and metrology-grade CMM-integrated systems, require substantial capital investment that can limit adoption among smaller manufacturers and SMEs with constrained technology budgets.
- Shortage of Skilled Operators: Effective deployment of 3D scanning systems requires trained operators capable of managing data acquisition, point cloud processing, and inspection software, creating a skills gap that constrains adoption velocity and increases total cost of ownership for new adopters.
Market Opportunities
- Portable and Handheld Scanner Innovation: Growing demand for flexible, field-deployable 3D scanning solutions is driving innovation in portable and handheld scanners that deliver professional accuracy with reduced setup time, opening new application areas in construction inspection, asset management, and cultural heritage documentation.
- Healthcare and Medical Imaging: 3D scanning applications in prosthetics fitting, dental modeling, surgical planning, and patient-specific implant design are expanding as Japan's healthcare sector embraces digital manufacturing and personalized medicine workflows.
Market Challenges
- Intense Global Competition: Competition from global technology leaders and emerging Chinese scanner manufacturers is intensifying pricing pressure across mid-range product categories, compressing margins and accelerating product lifecycle compression for scanner hardware.
- Rapid Technology Obsolescence: The fast pace of innovation in sensor technology, AI processing, and software analytics means that scanner hardware investments risk obsolescence within shorter cycles, requiring vendors to continuously invest in R&D to maintain competitive positioning.
Emerging Market Trends
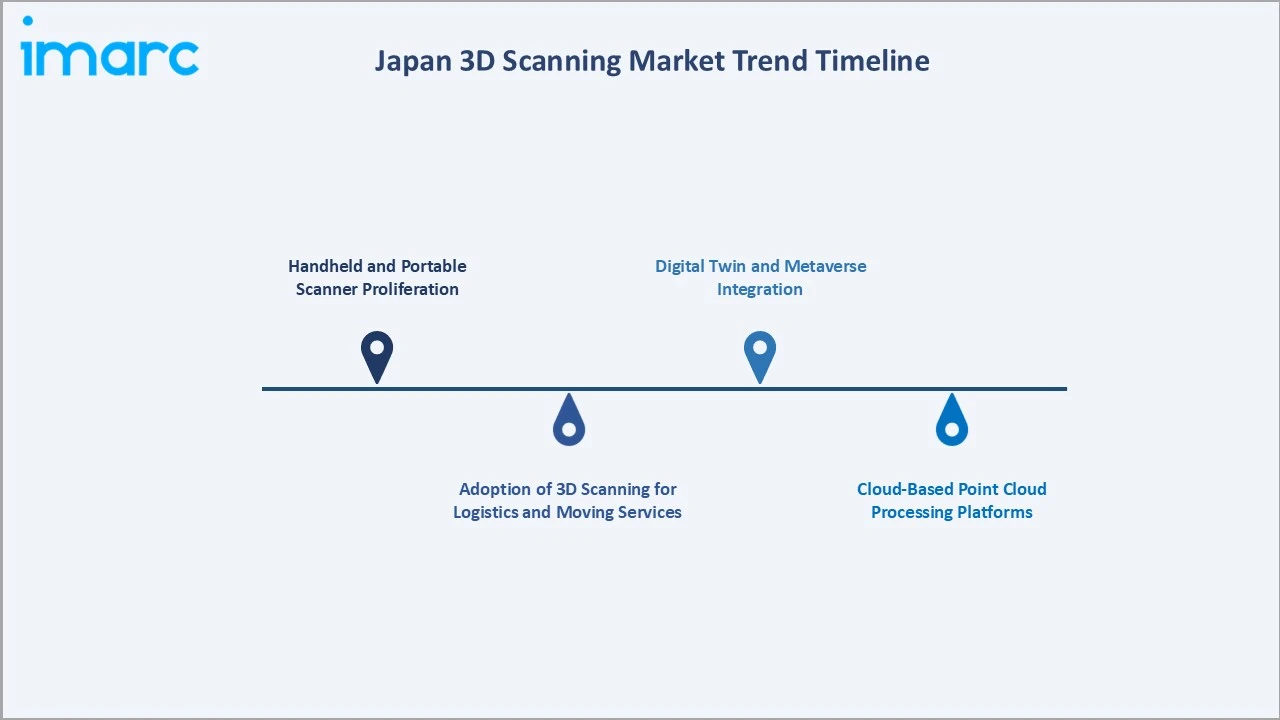
1. Handheld and Portable Scanner Proliferation
The market is witnessing rapid expansion in handheld 3D scanning solutions offering industrial-grade accuracy in lightweight, fieldwork-ready form factors. Portable scanners featuring photogrammetry and structured light technologies are enabling new use cases in field maintenance inspection, heritage documentation, and construction site monitoring, expanding the addressable market beyond traditional controlled-environment factory applications.
2. Adoption of 3D Scanning for Logistics and Moving Services
In April 2024, nat Co., Ltd. launched Japan’s first field trial using its 3D scanning app, Scanat, to support on-site surveys for Yamato Transport’s international moving services. The launch highlights the growing adoption of 3D scanning technology for on-site surveys and logistics operations. This trend can improve measurement accuracy, streamline moving assessments, and reduce the time required for physical site inspections.
3. Digital Twin and Metaverse Integration
3D scanning is becoming the foundational data acquisition layer for digital twin platforms, enabling manufacturers to maintain accurate virtual replicas of production lines, facilities, and products. In February 2024, Shimizu Corporation developed a metaverse-based inspection system that combines 3D building scans with BIM data to enable remote inspections of construction sites. The technology is expected to streamline building construction and production processes in Japan.
4. Cloud-Based Point Cloud Processing Platforms
Cloud-native software platforms for 3D point cloud storage, processing, and collaboration are gaining adoption as organizations seek to reduce local infrastructure requirements and enable remote team collaboration on large-scale scanning datasets. Cloud platforms also facilitate AI model training on aggregated scan data, accelerating the development of automated inspection algorithms.
Industry Value Chain Analysis
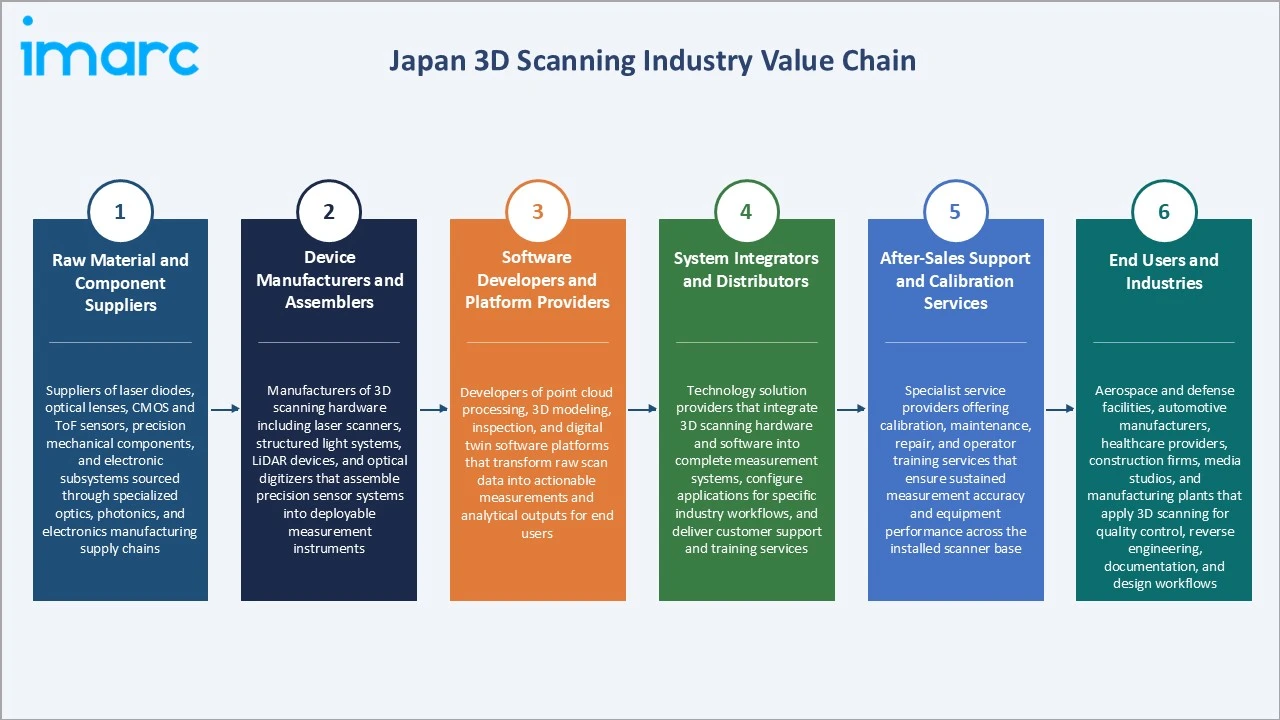
The Japan 3D scanning industry value chain spans six integrated stages, from raw material and component supply through end-user application. Value addition is highest at the device manufacturing and software development stages, where intellectual property, sensor precision, and algorithm sophistication define competitive differentiation and determine the performance specifications that drive purchasing decisions.
|
Stage |
Key Participants Activities |
|
Raw Material and Component Suppliers |
Suppliers of laser diodes, optical lenses, CMOS and ToF sensors, precision mechanical components, and electronic subsystems sourced through specialized optics, photonics, and electronics manufacturing supply chains. |
|
Device Manufacturers and Assemblers |
Manufacturers of 3D scanning hardware including laser scanners, structured light systems, LiDAR devices, and optical digitizers that assemble precision sensor systems into deployable measurement instruments. |
|
Software Developers and Platform Providers |
Developers of point cloud processing, 3D modeling, inspection, and digital twin software platforms that transform raw scan data into actionable measurements and analytical outputs for end users. |
|
System Integrators and Distributors |
Technology solution providers that integrate 3D scanning hardware and software into complete measurement systems, configure applications for specific industry workflows, and deliver customer support and training services. |
|
After-Sales Support and Calibration Services |
Specialist service providers offering calibration, maintenance, repair, and operator training services that ensure sustained measurement accuracy and equipment performance across the installed scanner base. |
|
End Users and Industries |
Aerospace and defense facilities, automotive manufacturers, healthcare providers, construction firms, media studios, and manufacturing plants that apply 3D scanning for quality control, reverse engineering, documentation, and design workflows. |
The device manufacturing and assembly stage represents the highest value-added segment of the 3D scanning value chain. At this stage, raw optical and electronic components are integrated into precision instruments through advanced assembly processes requiring cleanroom environments, optical alignment expertise, and rigorous calibration protocols.
Technology Landscape in the Japan 3D Scanning Industry
Laser Scanning and LiDAR Technology
Laser-based 3D scanning technology, including time-of-flight and phase-shift LiDAR, continues to advance with improvements in scan speed, range accuracy, and miniaturization. Modern industrial laser scanners achieve measurement accuracies at high scan speeds, enabling real-time quality control integration on high-volume production lines.
Structured Light and Photogrammetry
Structured light scanning systems using projected pattern illumination and dual-camera capture deliver high-resolution surface data ideal for part inspection and reverse engineering. Combined photogrammetry workflows, where reference photographs are aligned with laser scan data, are improving outdoor and large-scale scanning accuracy for construction and infrastructure applications.
AI and Machine Learning Integration
Embedded AI capabilities in scanning software platforms are automating point cloud segmentation, defect classification, and dimensional reporting workflows. Machine learning models trained on large scan datasets are enabling semi-autonomous inspection systems that operate with reduced operator oversight, improving throughput and consistency in high-volume quality control environments.
Cloud Processing and Edge Computing
Cloud-connected 3D scanning workflows are enabling real-time data upload and collaborative processing across distributed teams. Edge computing integration in portable scanning systems is simultaneously allowing on-device AI analysis for applications where network connectivity is limited, creating a hybrid processing architecture suited to both factory and field environments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Hardware |
68.4% |
2025 |
|
Range |
Short Range |
42.8% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End Use Industry |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
38.5% |
2025 |

By Type
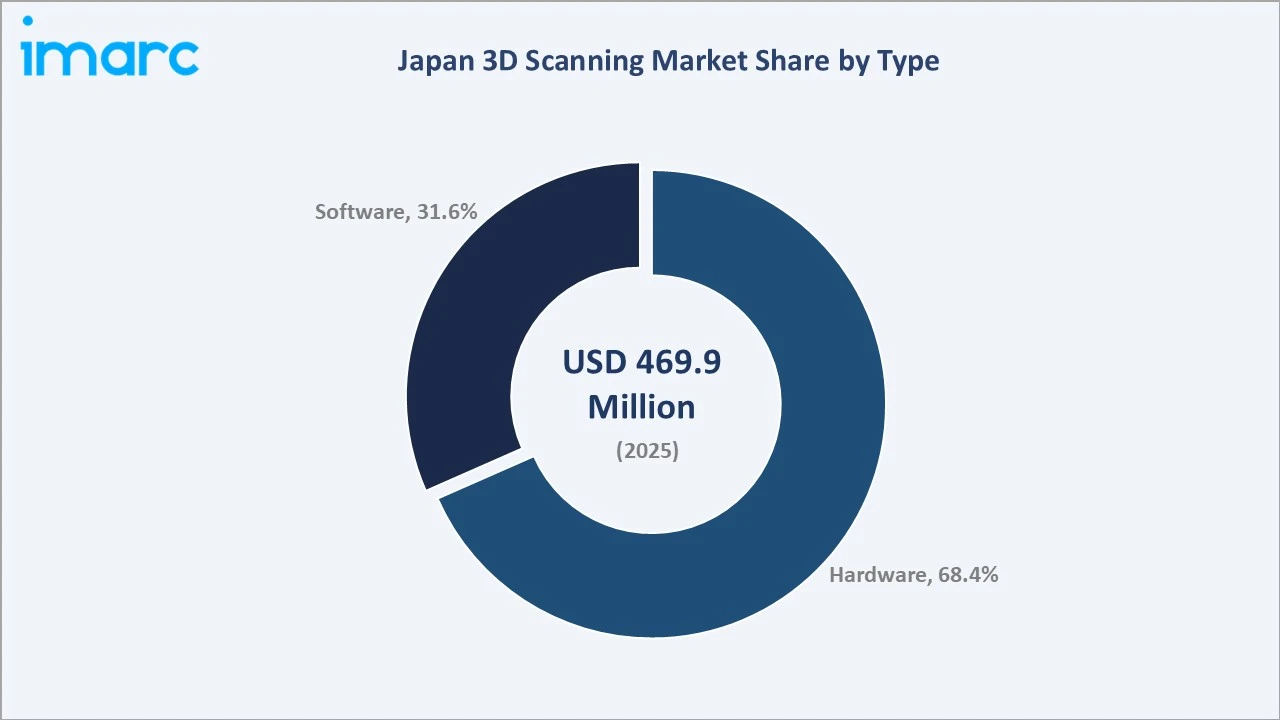
Hardware leads at 68.4% in 2025, driven by widespread deployment of laser scanners, structured light systems, and optical digitizers across automotive assembly, aerospace manufacturing, and precision engineering applications. The hardware segment encompasses a broad range of scanner form factors from bench-top metrology systems to portable handheld devices, supporting applications across factory floor and field environments.
To access detailed market analysis, Request Sample
Software at 31.6% is growing at a faster rate as organizations invest in cloud-based point cloud processing platforms, AI-assisted inspection analytics, and integrated BIM and CAD modeling tools that extend the analytical value of physical scanner investments. The software segment increasingly drives recurring revenue models and long-term customer relationships for technology providers.
By Range
Short range dominates at 42.8% in 2025, reflecting the market's strong concentration in factory-floor quality control, small part inspection, and reverse engineering applications where close-range, high-resolution measurement is the primary requirement. Japan's automotive and electronics manufacturing industries are the primary adopters of short range scanning systems for dimensional inspection and tolerance verification.
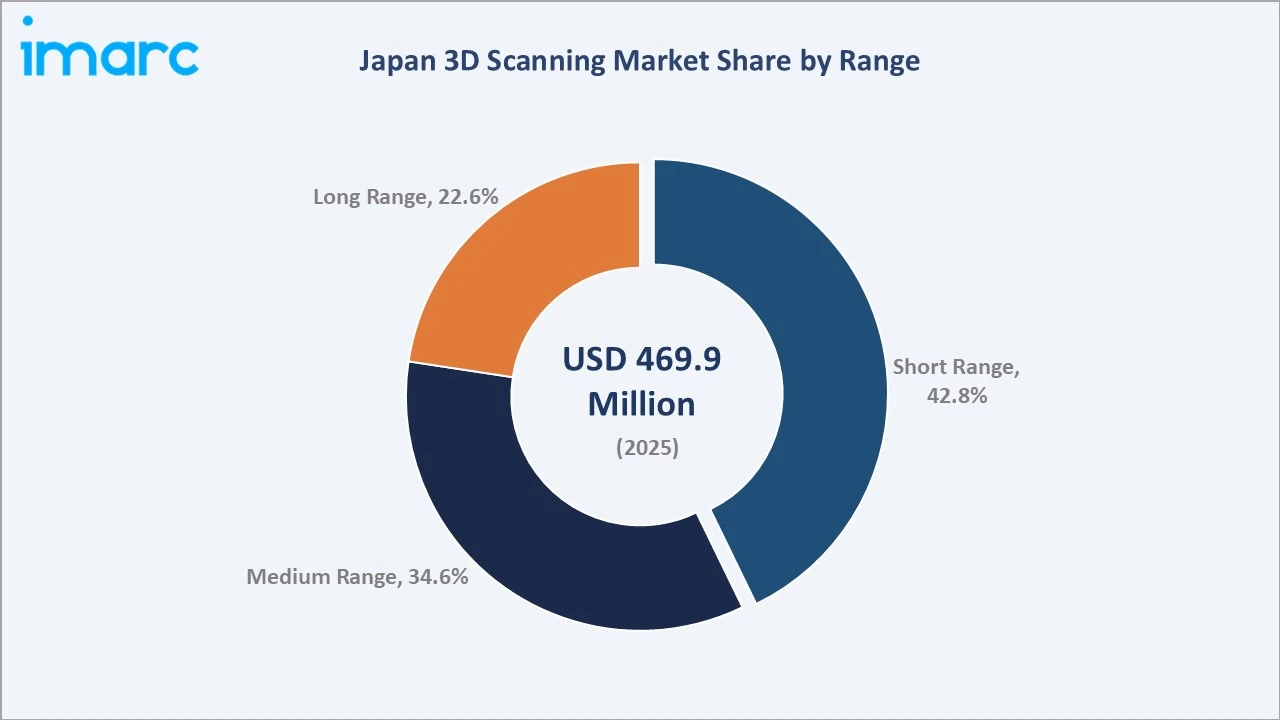
Medium range at 34.6% serves industrial facility inspection, large component measurement, and mid-scale infrastructure documentation, balancing accuracy with measurement volume capability. Long range at 22.6% is applied in outdoor infrastructure surveying, civil engineering, urban mapping, and large industrial plant digitalization, where extended measurement distances of tens to hundreds of meters are required.
Regional Market Insights
|
Region |
Share (2025) |
Key Japan 3D Scanning Market Drivers & Characteristics |
|
Kanto Region |
38.5% |
Reflecting the dense concentration of automotive OEMs, electronics manufacturers, and aerospace facilities in Greater Tokyo and surrounding prefectures, driving the greatest regional demand for precision 3D scanning. |
|
Kansai/Kinki Region |
18.7% |
Reflecting strong manufacturing activity in automotive components, machinery, and pharmaceutical production, supporting consistent demand for quality control and inspection scanning. |
|
Central/Chubu Region |
14.2% |
Reflecting the high concentration of automotive manufacturing activity in major OEM and tier-1 supplier facilities requiring high-volume quality inspection scanning. |
|
Kyushu-Okinawa Region |
9.6% |
Reflecting semiconductor manufacturing, automotive production, and growing aerospace activities that generate specialized scanning demand across the region. |
|
Tohoku Region |
6.8% |
Reflecting industrial manufacturing, food processing, and electronics production that utilize 3D scanning for quality inspection and process improvement. |
|
Chugoku Region |
5.1% |
Reflecting shipbuilding, steel production, and industrial manufacturing activities that apply 3D scanning for large component measurement and quality assurance. |
|
Hokkaido Region |
4.2% |
Reflecting agricultural technology, food processing, and infrastructure development, creating niche scanning demand across the northernmost prefecture. |
|
Shikoku Region |
2.9% |
Reflecting chemical manufacturing and electronics production that generate specialized measurement and inspection scanning requirements. |
The Kanto region holds the dominant share at 38.5% in 2025, hosting the highest concentration of automotive OEMs, aerospace manufacturers, electronics companies, and precision engineering firms in Japan. The Kansai/Kinki region accounts for 18.7% in 2025 and is home to significant automotive component manufacturing, precision machinery production, pharmaceutical manufacturing, and consumer electronics production. The Central/Chubu region contributes 14.2% in 2025, is home to major automotive OEMs and their supplier networks and is the primary driver of 3D scanning demand in this region.
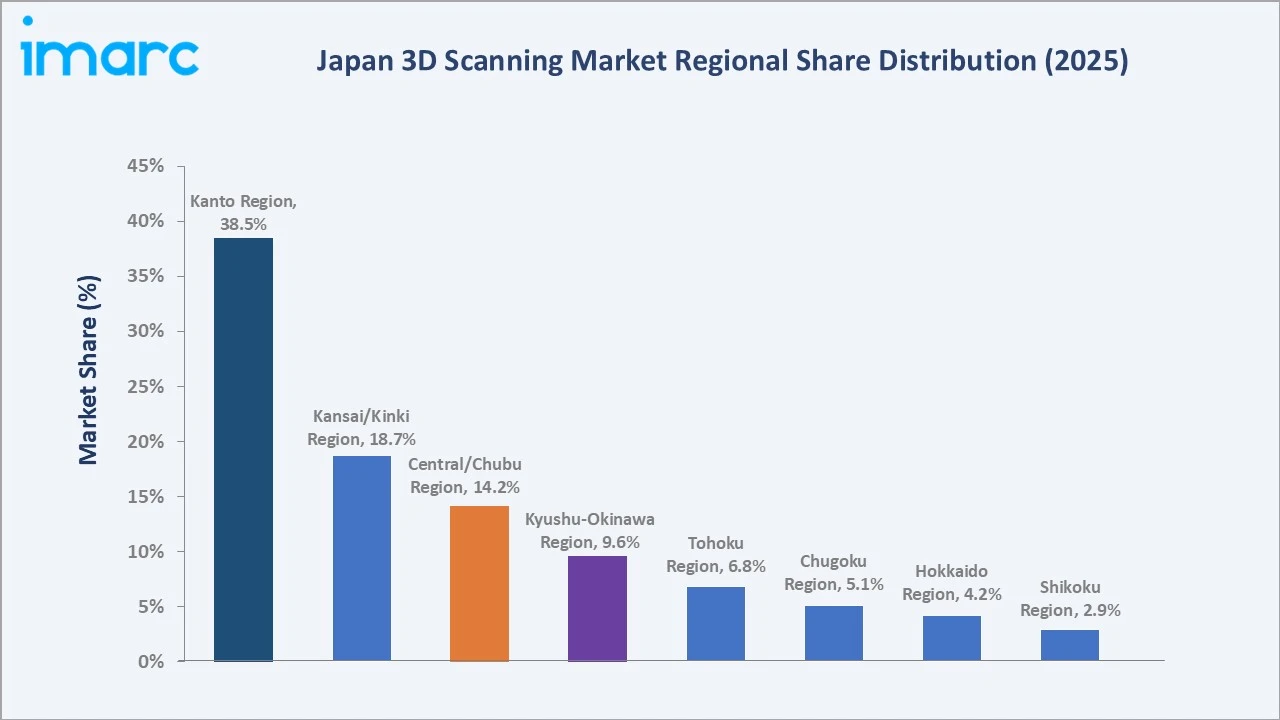
The Kyushu-Okinawa region holds 9.6% of the 2025 market, driven by semiconductor manufacturing, automotive production, and growing aerospace activity. The Tohoku region accounts for 6.8% of the 2025 market. The Chugoku region contributes 5.1% to the Japan 3D scanning market in 2025; shipbuilding, steel production, and precision industrial manufacturing activities drive demand for large-scale component measurement and structural quality assurance scanning. Hokkaido region accounts for 4.2% of the Japan 3D scanning market in 2025. Shikoku region accounts for 2.9% of the 2025 market, the smallest regional share reflecting its more limited heavy manufacturing and technology industrial base compared to other Japanese regions.
Competitive Landscape
The Japan 3D scanning market is moderately concentrated among global technology leaders, with established players holding significant market share through brand reputation, product breadth, and deep integration with Japan's industrial manufacturing customer base. The market also features specialist innovators and emerging regional players addressing specific application niches.
|
Company |
Key Products |
Market Position |
Core Strength |
| KEYENCE CORPORATION | VL-800 Series 3D Scanner CMM, VR-6000 series, KEYENCE’s 3D structured light scanner | Market Leader | KEYENCE CORPORATION plays a leading role in Japan's industrial automation, quality control, and metrology sectors by developing high-precision non-contact 3D scanners, optical profilers, and 3D machine vision systems. |
| Hexagon AB | Hexagon HYPERSCAN, Hexagon Absolute Scanner, Hexagon ATLASCAN, Hexagon MARVELSCAN | Market Leader | Hexagon AB acts as a major supplier of 3D scanning, portable metrology, and quality inspection solutions in Japan through its Manufacturing Intelligence and geospatial divisions. |
| Trimble Inc. | Trimble X9 3D scanner | Established Player | Trimble Inc. plays a foundational role in Japan’s 3D scanning, reality capture, and high-precision spatial positioning markets, supporting the country's national infrastructure and digital construction. |
| RIEGL | RIEGL VZ-600i, RIEGL VZ-400i, RIEGL VZ-2000i |
Innovator |
RIEGL Japan provides localized sales, training, and technical support for high-precision 3D LiDAR technology and smart-waveform laser scanning systems. |
| Revopoint 3D |
RANGE 3 RANGE 3 Pro, MetroY Ultra, MetroY MetroY Pro |
Challenger |
Revopoint 3D plays an expanding, accessible role in Japan’s 3D scanning, additive manufacturing, and digital design ecosystems, serving hobbyists, engineering firms, and educational institutions. |
Competition is intensifying as portable scanner innovation and software platform differentiation become the primary battlegrounds, with established hardware leaders investing in AI-enabled software to create sticky recurring revenue streams alongside one-time device sales.
Key Company Profiles
KEYENCE CORPORATION
KEYENCE CORPORATION is a leading Japanese manufacturer of sensors, measuring systems, laser markers, and machine vision systems, with a growing 3D scanning and metrology portfolio. The company serves a broad range of industrial applications through a direct sales model that provides deep customer integration and application-specific technical support across Japan's manufacturing sector.
- Key Products: VL-800 Series 3D Scanner CMM, VR-6000 series, KEYENCE’s 3D structured light scanner.
- Strategic Focus: Deepening integration of 3D measurement tools into automated production line quality control; expanding direct sales coverage across Japan's manufacturing SME base.
Hexagon AB
Hexagon AB is an information technology company providing smart digital reality solutions, with a comprehensive portfolio spanning precision metrology hardware, 3D scanning systems, and industrial software platforms. In Japan, Hexagon serves automotive, aerospace, and industrial manufacturing customers through integrated measurement and quality management ecosystems.
- Key Products: Leica RTC360 3D laser scanner, Romer absolute arm, PC-DMIS quality management software, SCENE point cloud processing software.
- Strategic Focus: Advancing the convergence of physical measurement and digital analytics through AI-driven inspection automation and smart factory integration platforms.
Market Concentration Analysis
The Japan 3D scanning market exhibits moderate concentration at the hardware level, with established global technology providers holding significant combined market share through recognized brand positioning, broad product portfolios, and deep customer relationships across Japan's precision manufacturing sectors. The hardware segment is anchored by a small number of leading vendors with established Japan-specific sales and service networks, while the software segment is more fragmented across a wider range of point cloud processing, inspection analytics, and digital twin platform providers addressing distinct workflow requirements across industries.
The market is expected to evolve toward a more consolidated structure over the 2026–2034 forecast period, as hardware providers invest in software and analytics capabilities to create integrated ecosystem offerings generating recurring subscription revenues. Portable and handheld scanner categories remain the most competitively open segments, with multiple emerging vendors entering the market on the basis of price-to-performance differentiation targeting SME and field inspection application customers that established industrial-grade scanner providers have historically underserved.
Investment & Growth Opportunities
Highest Growth Segments
Software at ~19.5% CAGR represents the highest-growth opportunity in the Japan 3D scanning market, driven by cloud platform adoption, AI-assisted inspection analytics, and digital twin integration. Portable and handheld scanner hardware is the fastest-growing hardware subcategory as field-deployable scanning expands into construction, infrastructure, and healthcare.
Investment Themes
- AI-Enabled Inspection Automation: Investment in AI-powered point cloud analysis platforms that automate defect detection, dimensional reporting, and pass/fail classification offers high-margin recurring revenue opportunities alongside hardware sales, with growing adoption across Japan's precision manufacturing sector.
- Healthcare and Dental 3D Scanning: Japan's aging population and advanced healthcare system are creating expanding demand for 3D scanning in prosthetics manufacturing, dental laboratory workflows, and surgical planning, representing an under-penetrated high-value application segment.
- Portable Scanner Innovation: Developing next-generation handheld and wearable scanning systems with improved accuracy, speed, and connectivity will open new SME and field application markets that current high-cost industrial scanner pricing cannot effectively address.
Future Market Outlook (2026-2034)
The Japan 3D scanning market grew from USD 469.9 Million in 2025 to USD 549.8 Million in 2026 and is projected to reach USD 1,930.6 Million by 2034, exhibiting a CAGR of 17.00% during 2026-2034. The market is expected to reach an intermediate milestone of approximately USD 1,030.3 Million by 2030, as EV manufacturing investments, digital twin adoption, and healthcare scanning applications reach broad commercial penetration across Japan's industrial landscape.
Three structural forces will define the Japan 3D scanning market through 2034. First, Japan's advanced manufacturing base will maintain consistent demand for precision scanning tools as quality requirements in EV, aerospace, and semiconductor production tighten. Second, the progressive digitalization of Japan's construction and infrastructure sectors through i-Construction and smart city programs will create a large, government-supported demand stream for terrestrial and mobile scanning. Third, the software platform transition will shift revenue composition toward recurring streams, improving market predictability and incentivizing technology providers to increase R&D investment in AI-driven analytics capabilities.
Research Methodology
Primary Research
Primary research comprised structured consultations with 3D scanning technology executives, industrial manufacturing quality engineers, procurement managers, system integrators, and end-user facility managers across Japan's automotive, aerospace, and manufacturing sectors. These consultations validated market sizing estimates, assessed technology adoption trajectories, and provided insights into competitive dynamics and application segment growth drivers.
Secondary Research
Secondary research drew on published industry association data, government digitalization program documentation, company annual reports and investor presentations, trade publication coverage of 3D scanning technology developments, and historical scanner shipment data. Market data spanning 2020 through 2025 was cross-validated across primary and secondary sources.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical segment growth rates, end-use industry investment trends, technology adoption lifecycle models, EV manufacturing transition timelines, government infrastructure digitalization spending projections, and macroeconomic indicators including Japan's industrial production index and capital expenditure data.
Japan 3D Scanning Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered |
|
| Ranges Covered | Short Range, Medium Range, Long Range |
| Applications Covered | Reverse Engineering, Rapid Prototyping, Quality Control/Inspection, Face and Body Scanning, Others |
| End Use Industries Covered | Aerospace and Defense, Automotive, Healthcare, Manufacturing, Media and Entertainment, Architecture and Construction, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | KEYENCE CORPORATION, Hexagon AB, Trimble Inc., RIEGL, Revopoint 3D, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, Japan 3D scanning market outlook, and dynamics of the market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Japan 3D scanning market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan 3D scanning industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan 3D Scanning Market Report
The Japan 3D scanning market reached USD 549.8 Million in 2026, driven by industrial automation, EV manufacturing investment, digital twin adoption, and expanding quality control applications.
The market is projected to grow at a CAGR of 17.00% during 2026-2034, supported by manufacturing digitalization, AI-integrated scanning, and healthcare and infrastructure application expansion.
The market is projected to reach approximately USD 1,030.3 Million by 2030, driven by EV production scaling, digital twin deployments, and government infrastructure digitalization.
Hardware leads with a 68.4% share in 2025, encompassing laser scanners, structured light systems, optical digitizers, and LiDAR devices deployed across industrial manufacturing.
Short range leads with 42.8% in 2025, driven by factory-floor quality control, small component inspection, and reverse engineering applications in automotive and electronics.
The Kanto region leads with 38.5% in 2025, reflecting the dense manufacturing and technology base across industrial prefectures.
Key players include KEYENCE CORPORATION, Hexagon AB, Trimble Inc., RIEGL, and Revopoint 3D, among others.
The market is projected to reach USD 1,930.6 Million by 2034, driven by manufacturing quality demands, infrastructure digitalization, healthcare adoption, and AI-integrated scanning expansion.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade