
Japan Athletic Footwear Market Size, Share, Trends and Forecast by Product Type, Sports Footwear Type, End User, Distribution Channel, and Region, 2026-2034
Japan Athletic Footwear Market Size, Share, Trends & Forecast (2026-2034)
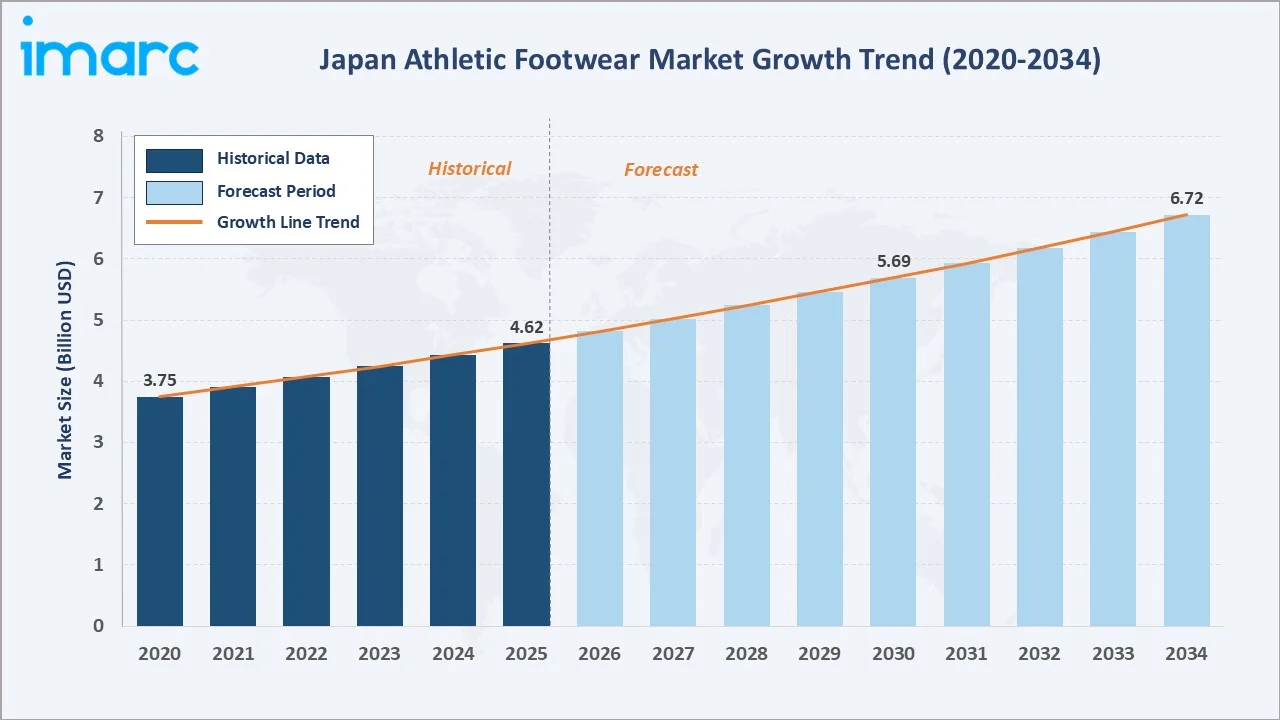
The Japan athletic footwear market grew from USD 4.62 Billion in 2025 to USD 4.82 Billion in 2026 and is projected to reach USD 6.72 Billion by 2034, exhibiting a CAGR of 4.26% during 2026-2034. Japan's athletic footwear industry continues to benefit from deep-rooted sports culture, rising consumer preference for performance-driven footwear, and strong growth in fitness and wellness activities.
Running shoes lead the product type segment at 30.1%, men command the largest end user share at 48.7%, and Kanto Region dominates with a 36.8% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 4.62 Billion |
|
Market Size (2026) |
USD 4.82 Billion |
|
Forecast Market Size (2034) |
USD 6.72 Billion |
|
CAGR (2026-2034) |
4.26% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Leading Product Type |
Running Shoes (30.1%, 2025) |
|
Leading End User |
Men (48.7%, 2025) |
|
Largest Region |
Kanto Region (36.8%, 2025) |
|
Second Largest Region |
Kansai/Kinki Region (22.4%, 2025) |
The Japan athletic footwear market expanded from USD 3.75 Billion in 2020 to USD 4.62 Billion in 2025 and is estimated to reach USD 4.82 Billion in 2026. The market is further expected to grow to USD 5.69 Billion by 2030 and USD 6.72 Billion by 2034, supported by expanding e-commerce distribution, innovation in sustainable and performance-oriented footwear, and a maturing wellness-conscious consumer base across Japan.
To get more information on this market, Request Sample
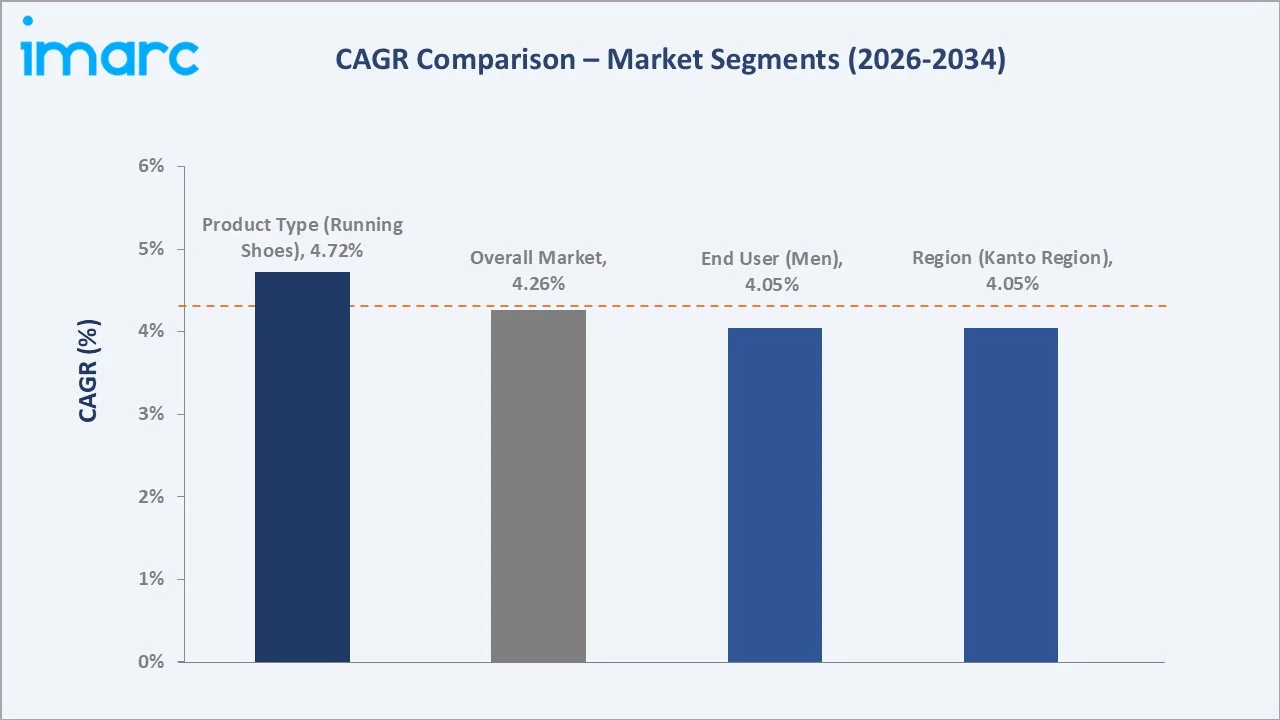
CAGR trajectories across product type and end user sub-segments, together with regional patterns, highlight Kyushu-Okinawa Region and aerobic and gym wear shoes expanding at a faster pace than the overall 4.26% market CAGR, driven by rising gym participation, outdoor recreation trends, and expanding retail presence in secondary urban areas.
Executive Summary
The Japan athletic footwear market expanded from USD 4.62 Billion in 2025 to an estimated USD 4.82 Billion in 2026. The market has evolved significantly, moving beyond performance-oriented demand toward a broader athleisure and lifestyle footwear culture encompassing running, training, sport, trekking, and gym categories. Rising health awareness, rapid urbanization, and sustained investment in product innovation by domestic and global brands are collectively driving this transition.
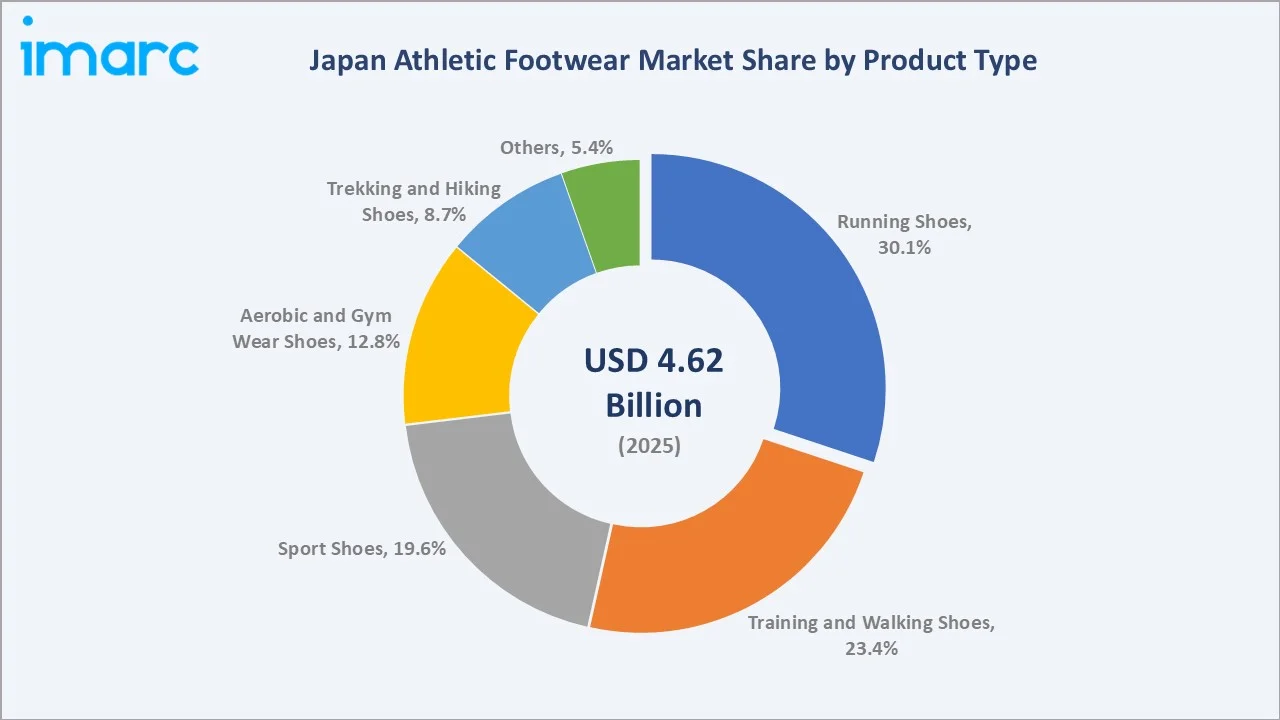
Running shoes dominate the product type segment at 30.1% in 2025, reflecting consistent demand across recreational and competitive runners. Men hold the largest end user share at 48.7%, indicating strong participation in sports, running, training, and other fitness activities. Kanto Region commands 36.8% of the regional share, anchored by Tokyo's position as the country's primary retail and sports hub.
Key Market Insights
|
Insight |
Data |
|
Leading Product Type |
Running Shoes – 30.1% share (2025) |
|
Second Largest Product Type |
Training and Walking Shoes – 23.4% share (2025) |
|
Leading End User |
Men – 48.7% share (2025) |
|
Second Largest End User |
Women – 32.6% share (2025) |
|
Leading Region |
Kanto Region – 36.8% share (2025) |
|
Second Largest Region |
Kansai/Kinki Region – 22.4% share (2025) |
|
Top Companies |
Nike, Inc., Adidas AG, Asics Corporation, Mizuno Corporation, New Balance, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Running shoes lead with a 30.1% product type share, reflecting strong demand from both competitive athletes and recreational runners participating in Japan's well-established road race and marathon culture.
- Training and walking shoes at 23.4% are supported by the growing popularity of gym workouts, cross-training, and functional fitness activities among urban Japanese consumers seeking multi-purpose performance footwear.
- Men at 48.7% account for the largest end user segment, with strong participation in sports, running, training, and other fitness activities.
- Women at 32.6% reflect rising female participation in running, gym workouts, yoga, walking, and other fitness activities, alongside growing interest in athletic footwear for everyday and athleisure use.
- Kanto Region at 36.8% leads all regions, anchored by Tokyo's dense concentration of specialty sports retailers, flagship brand stores, and a high concentration of urban fitness consumers in Japan.
Japan Athletic Footwear Market Overview
Athletic footwear refers to shoes designed for sports, fitness, and physical activity, including categories such as running shoes, training shoes, sport-specific footwear, gym and aerobic shoes, and trekking and hiking footwear. These products are designed with performance-enhancing features including cushioning systems, motion control technologies, breathable materials, and sport-specific outsole designs to support optimal physical performance.
The Japan market ecosystem integrates global athletic footwear brands, domestic manufacturers, sports specialty retailers, department stores, e-commerce platforms, and key raw material and component suppliers. Together, they serve a diverse consumer base spanning professional athletes, recreational participants, lifestyle consumers, and youth sports participants across all regions of Japan.
Market Dynamics
To evaluate market opportunities, Request Sample
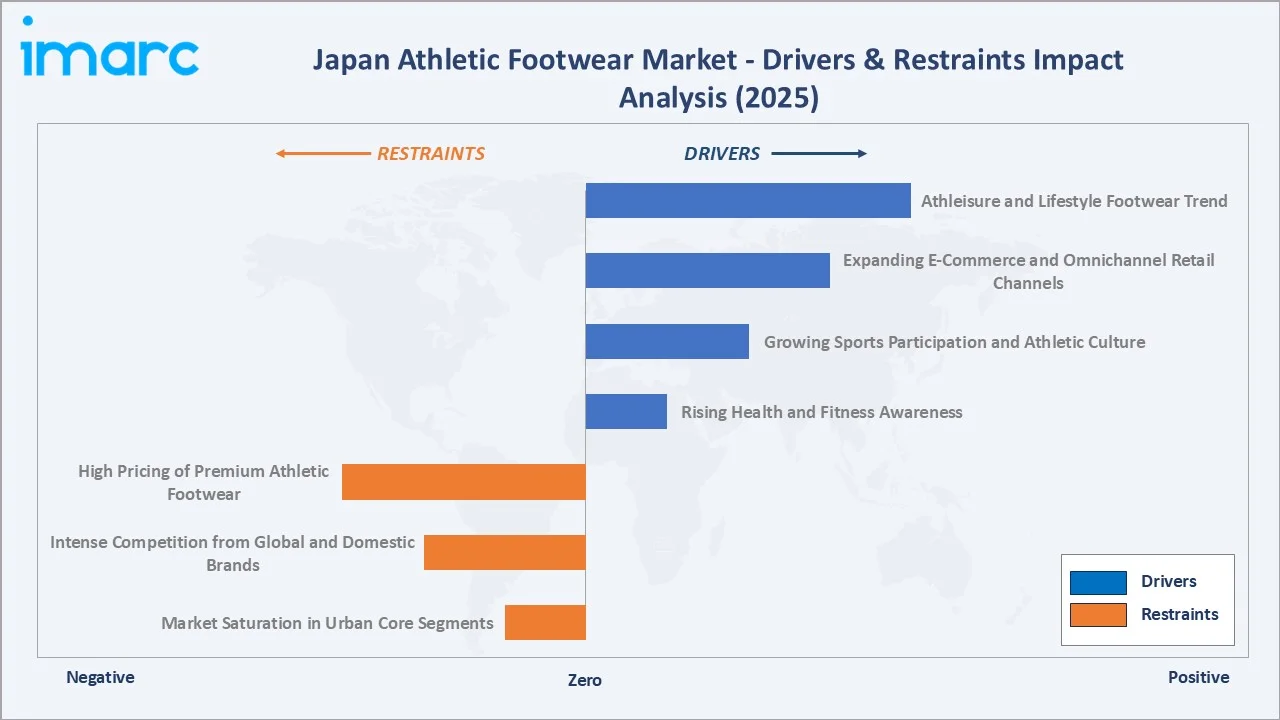
Market Drivers
- Rising Health and Fitness Awareness: Japan's aging population and government-led health promotion programs are driving sustained consumer interest in physical activity, increasing demand for performance athletic footwear across running, walking, and gym training categories. As of September 15, 2026, the population of seniors in Japan, those aged 65 and older, reached 36.2 Million, as reported by the Ministry of Internal Affairs and Communications, following an increase of 20,000 from 2025.
- Growing Sports Participation and Athletic Culture: Japan's long-standing tradition of school sports programs, corporate fitness initiatives, and major marathon events sustains year-round demand for athletic footwear across multiple consumer segments.
- Expanding E-Commerce and Omnichannel Retail Channels: Rapid growth in athletic footwear sales through e-commerce platforms, brand direct-to-consumer websites, and digital marketplaces is broadening market access, particularly for consumers in regional and non-metropolitan areas. As per IMARC Group, the Japan e-commerce market size, valued at USD 286.5 Billion in 2025.
- Athleisure and Lifestyle Footwear Trend: Growing adoption of athletic footwear for everyday casual use, supported by the global athleisure fashion movement, is expanding the addressable consumer market beyond sports participants to include lifestyle-oriented buyers across Japan.
Market Restraints
- High Pricing of Premium Athletic Footwear: Premium brand athletic footwear commands significantly elevated price points in Japan, which can limit purchase frequency and category penetration among price-sensitive consumer segments, particularly in regional markets.
- Intense Competition from Global and Domestic Brands: The coexistence of dominant global brands alongside established Japanese athletic footwear manufacturers creates a highly competitive pricing and marketing environment, compressing margins for mid-tier players.
- Market Saturation in Urban Core Segments: Retail and consumer penetration of athletic footwear in major metropolitan areas such as Tokyo and Osaka has reached high levels, making incremental volume growth increasingly dependent on product innovation, premiumization, and geographic expansion into secondary cities.
Market Opportunities
- Expanding Women's Athletic Footwear Segment: Rising female participation in running, fitness, yoga, and team sports presents a significant and underserved market opportunity for brands investing in women's performance footwear design, sizing, and marketing strategies.
- Growth in Trekking, Hiking, and Outdoor Footwear: Japan's rich network of hiking trails, national parks, and growing outdoor recreation tourism is creating expanding demand for high-performance trekking and hiking athletic footwear, particularly in regional prefectures.
Market Challenges
- Balancing Performance and Sustainability Demands: Consumers increasingly expect athletic footwear to deliver both high performance and demonstrable environmental sustainability, requiring brands to invest simultaneously in technical innovation and sustainable material development.
- Supply Chain Disruptions and Raw Material Cost Volatility: Athletic footwear manufacturers face ongoing exposure to supply chain disruptions and fluctuating costs for synthetic materials, rubber compounds, and specialized performance fabrics, which can impact product margins and retail pricing stability.
Emerging Market Trends
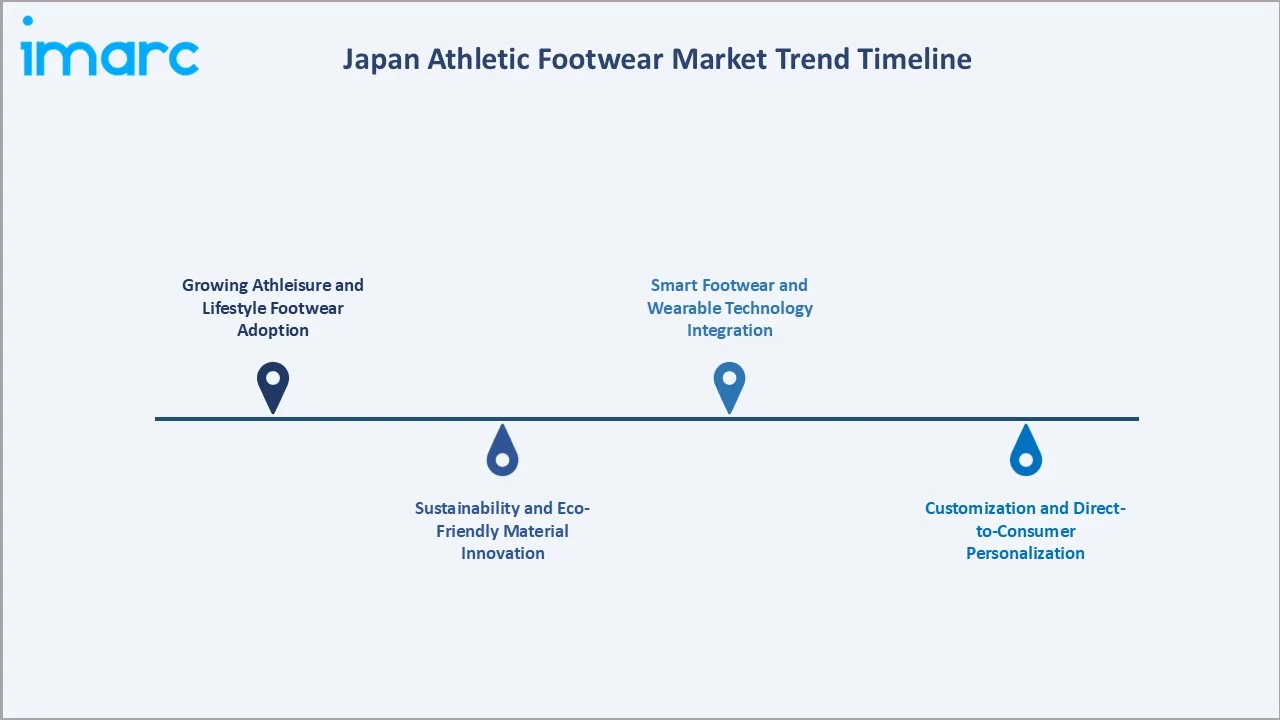
1. Growing Athleisure and Lifestyle Footwear Adoption
The boundary between athletic performance footwear and everyday lifestyle footwear is increasingly blurring in Japan, with consumers wearing running and training shoes in non-sport contexts. Brands are responding with dual-purpose designs that combine technical performance features with fashion-forward aesthetics, broadening market reach across age and lifestyle demographics.
2. Sustainability and Eco-Friendly Material Innovation
Consumer demand for environmentally responsible products is driving leading athletic footwear brands to invest in recycled materials, plant-based components, and reduced-carbon manufacturing processes. Global brands operating in Japan have launched dedicated sustainable product lines, and Japanese consumers' growing environmental consciousness is expected to make eco-certified footwear a meaningful market differentiator through 2034.
3. Smart Footwear and Wearable Technology Integration
Next-generation athletic footwear embedded with pressure sensors, gait analysis chips, and Bluetooth-enabled performance tracking capabilities is gaining early-adopter traction in Japan's technology-forward consumer market. These innovations align with Japan's broader acceptance of health-monitoring wearables and are expected to expand the premium smart footwear segment through 2030.
4. Customization and Direct-to-Consumer Personalization
Leading global brands operating in Japan are expanding personalized and customizable footwear offerings, allowing consumers to select colorways, materials, and fit specifications directly through digital platforms. This trend supports premium pricing, increases brand engagement, and reduces return rates, contributing to improving revenue quality for athletic footwear brands.
Industry Value Chain Analysis
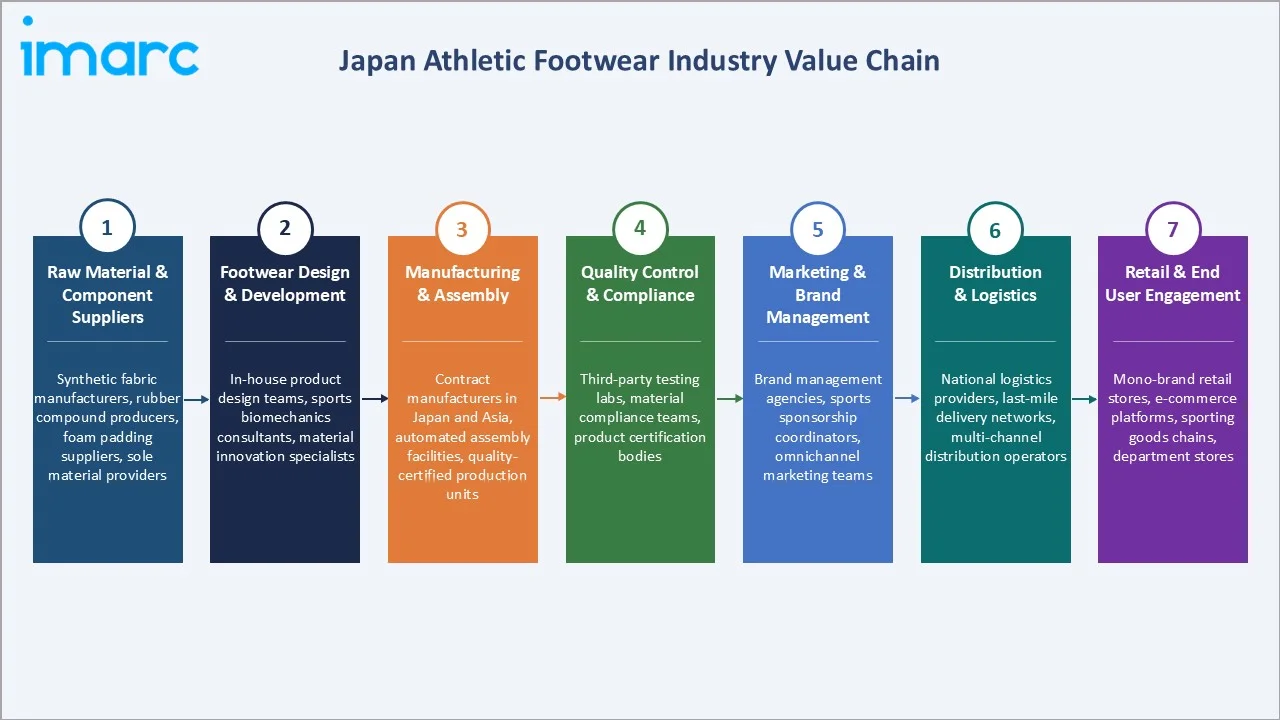
The Japan athletic footwear value chain spans seven stages, from raw material and component sourcing through retail engagement and end user lifecycle management. Design and development, brand marketing, and retail distribution capture the highest value-add, while sustainability compliance and performance innovation capabilities are increasingly determining competitive position within Japan's quality-focused consumer market.
|
Stage |
Key Players / Examples |
|
Raw Material & Component Suppliers |
Synthetic fabric manufacturers, rubber compound producers, foam padding suppliers, and sole material providers |
|
Footwear Design & Development |
In-house product design teams, sports biomechanics consultants, and material innovation specialists |
|
Manufacturing & Assembly |
Contract manufacturers in Japan and Asia, automated assembly facilities, and quality-certified production units |
|
Quality Control & Compliance |
Third-party testing laboratories, material compliance teams, and product certification bodies |
|
Marketing & Brand Management |
Brand management agencies, sports sponsorship coordinators, and omnichannel marketing teams |
|
Distribution & Logistics |
National logistics providers, last-mile delivery networks, and multi-channel distribution operators |
|
Retail & End User Engagement |
Mono-brand retail stores, e-commerce platforms, sporting goods chains, and department stores |
Vertically integrated brands that control proprietary design, manufacturing partnerships, and direct retail channels are positioned to capture greater value than distribution-dependent players. Japanese consumer preference for product authenticity and quality further reinforces the competitive advantage of brands with robust quality control and innovation capabilities.
Technology Landscape in the Japan Athletic Footwear Market
Advanced Midsole and Cushioning Technologies
Midsole innovation represents one of the most contested areas of development in the Japan athletic footwear market. Expanded polyurethane (EPU) and polyether block amide (PEBA) foam compounds have emerged as dominant cushioning materials, delivering superior energy return, lightweight construction, and durability compared to conventional EVA foams.
Knit and Engineered Upper Technologies
Seamless knit uppers constructed from mono-yarn and engineered mesh fabrics have replaced traditional cut-and-sew constructions across mid-to-premium athletic footwear segments. These materials offer targeted zone-specific support, superior breathability, reduced waste in manufacturing, and improved fit consistency. Brands are investing in precision knit engineering to achieve foot-mapping constructions that minimize friction and maximize adaptive fit across running, training, and lifestyle categories.
Sustainable and Bio-Based Material Technologies
The integration of bio-derived and recycled materials into athletic footwear construction is accelerating across brands serving the market. Recycled polyester yarns, plant-based rubber outsoles, and ocean-recovered plastic components are increasingly featured in mid-to-premium footwear lines. Leading brands have established material traceability and recycled content certification programs aligned with Japan's growing demand for environmentally responsible consumer products.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Running Shoes |
30.1% |
2025 |
|
Sports Footwear Type |
🔒 |
🔒 |
2025 |
|
End User |
Men |
48.7% |
2025 |
|
Distribution Channel |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
36.8% |
2025 |

By Product Type
Running shoes command a 30.1% majority share in 2025, driven by Japan's highly active marathon and road racing culture, strong participation in recreational running, and consistent demand from dedicated performance runners seeking premium cushioning and stability technologies.
To access detailed market analysis, Request Sample
Training and walking shoes follow at 23.4%, supported by the growing popularity of gym-based functional fitness, HIIT training, and urban walking activities.
By End User
Men account for 48.7% of the Japan athletic footwear market in 2025, reflecting historically higher rates of competitive and recreational sports participation, coupled with stronger spending on performance-oriented footwear.
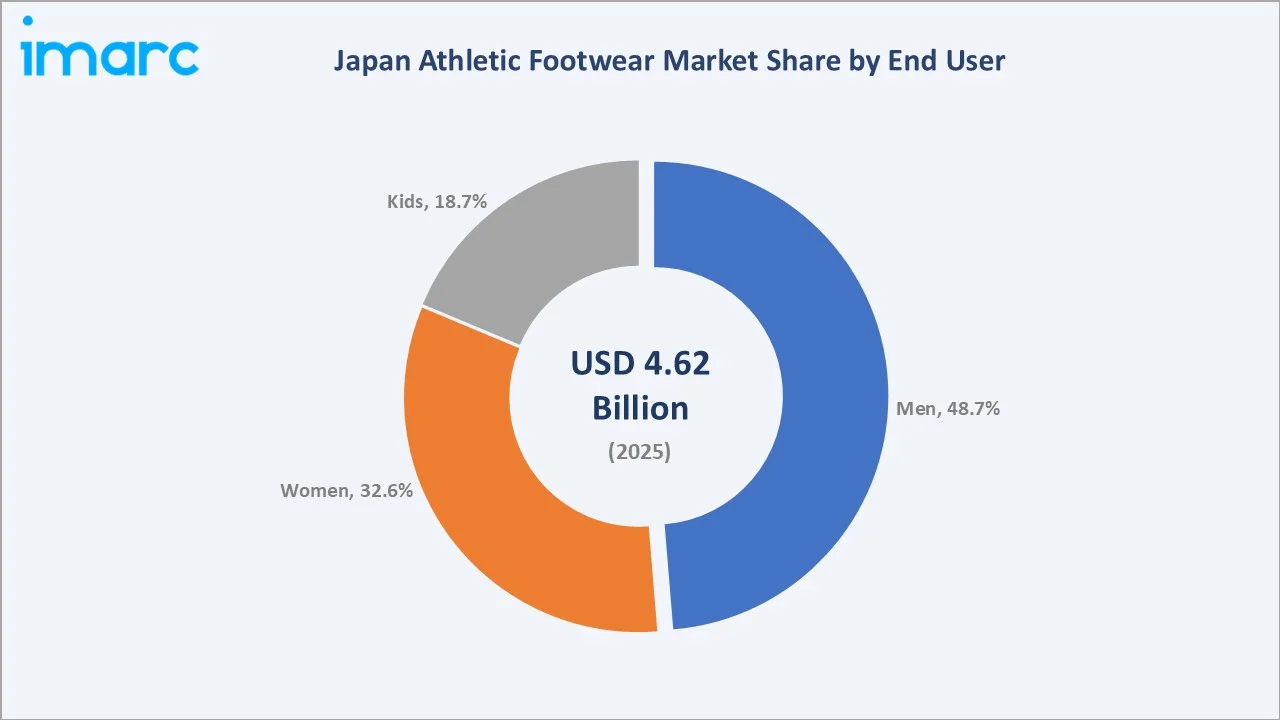
Women represent 32.6% of market share in 2025 and are the fastest-growing end user segment. Rising female participation in running events, group fitness, yoga, and outdoor activities is driving brand investments in women's-specific designs, colorways, and performance technologies.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Kanto Region |
36.8% |
Dense urban population, high sports participation, strong retail infrastructure, and leading concentration of brand headquarters and specialty stores |
|
Kansai/Kinki Region |
22.4% |
Growing lifestyle and athleisure adoption, established retail networks, and strong consumer spending on branded footwear |
|
Central/Chubu Region |
14.8% |
Rising health awareness, expanding suburban retail footprint, and growing participation in outdoor recreational activities |
|
Kyushu-Okinawa Region |
8.9% |
Warm climate supporting year-round outdoor activity, growing tourism-driven footwear demand, and rising regional sports events |
|
Tohoku Region |
6.7% |
Increasing government-supported sports development programs and growing demand for cold-weather athletic footwear |
|
Chugoku Region |
5.2% |
Expanding e-commerce access bridging geographic distance and growing interest in hiking and trekking footwear |
|
Hokkaido Region |
3.1% |
Cold climate driving demand for specialized athletic footwear suited to snow and winter outdoor sports |
|
Shikoku Region |
2.1% |
Emerging retail expansion, growing interest in trail running, and rising youth sports participation |
Kanto Region at 36.8% in 2025 leads the regional landscape, anchored by Greater Tokyo metropolitan area's position as Japan's leading consumer market and home to the high concentration of athletic specialty retailers, mono-brand flagship stores, and fitness-oriented urban consumers. Tokyo's marathon culture, running community infrastructure, and proximity to leading brand distribution hubs reinforce sustained regional dominance.
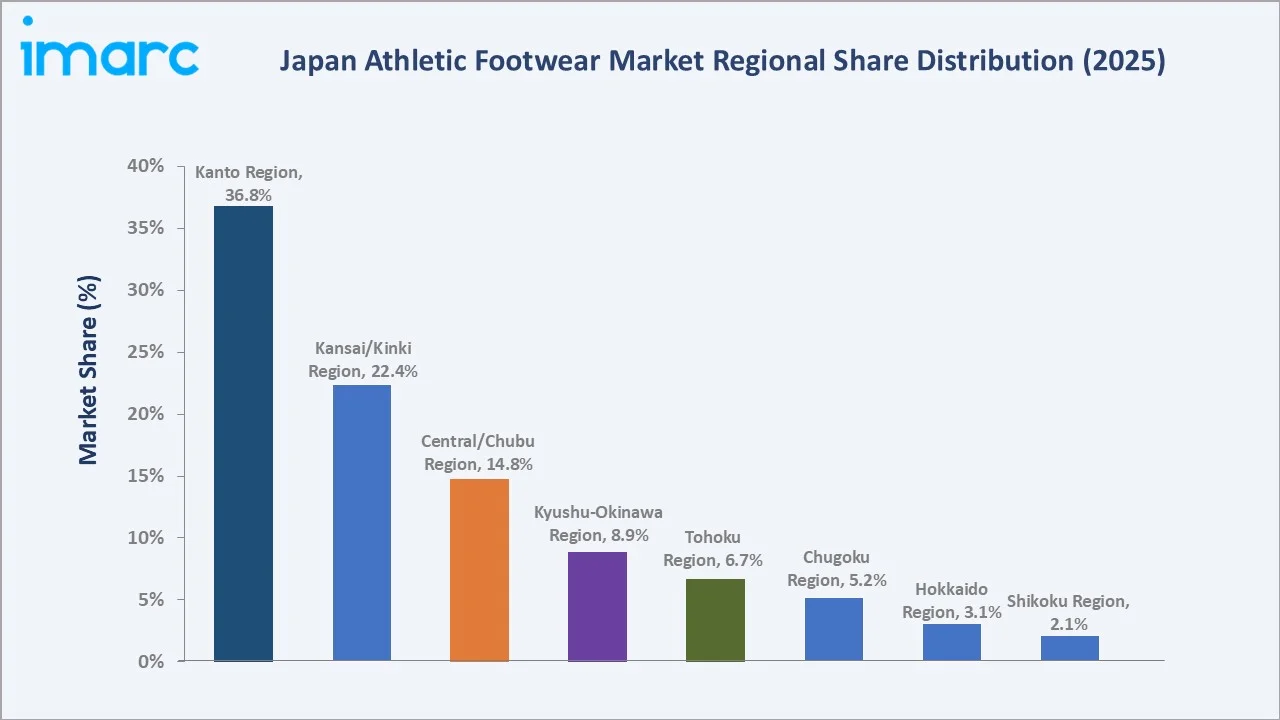
Kansai/Kinki Region at 22.4% is reflects strong demand from major urban centers such as Osaka, Kyoto, and Kobe, supported by a well-established retail network, active sports culture, and a large consumer base.
Competitive Landscape
The Japan athletic footwear market is moderately concentrated, with a small number of dominant global brands holding significant market share alongside established Japanese manufacturers with strong domestic brand loyalty. Product innovation, performance credibility, brand heritage, and multi-channel retail execution form the primary competitive differentiators across the industry.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Nike, Inc. | Nike | Leader | Strengthening digital commerce and product innovation to maintain category leadership across Japanese athletic footwear segments |
| Adidas AG | Adidas | Leader | Expanding performance and lifestyle footwear product lines while deepening retail and e-commerce presence in Japan |
| Asics Corporation | ASICS | Leader | Reinforcing running and performance footwear dominance through biomechanics-led innovation and domestic market expansion |
| Mizuno Corporation | Mizuno | Challenger | Growing presence in running and sport footwear through precision engineering and expanding global retail distribution |
| New Balance, Inc. | New Balance | Challenger | Strengthening lifestyle and performance athletic footwear positioning among urban Japanese consumers through design differentiation |
Key players include Nike, Inc., Adidas AG, Asics Corporation, Mizuno Corporation, and New Balance, Inc., among others.
Key Company Profiles
Nike, Inc.
Nike, Inc. is an American multinational corporation headquartered in Beaverton, Oregon, United States, and is the world's leading designer, manufacturer, and marketer of athletic footwear, apparel, and equipment.
- Product Portfolio: Athletic footwear spanning running, training, sport, and lifestyle categories, including the Air Max, React Infinity Run, Pegasus, Free RN, and Jordan series.
- Recent Developments: The company continues to invest in product development and retail capabilities in Japan, advancing its omnichannel presence and consumer engagement initiatives across key urban markets.
- Strategic Focus: Leveraging technology-driven product development and omnichannel retail expansion to deepen brand relevance and sustain category leadership across Japan's athletic footwear landscape.
Adidas AG
Adidas AG is a German multinational corporation headquartered in Herzogenaurach, Germany, and one of the world's largest producers of athletic footwear, apparel, and accessories, with a significant presence in the Japanese market.
- Product Portfolio: Athletic and lifestyle footwear lines including Ultraboost, Adizero, Stan Smith, and Samba, spanning running, training, court sport, and lifestyle categories.
- Recent Developments: Adidas AG continues to strengthen its brand presence in Japan through investments in retail expansion and consumer-facing initiatives across performance and lifestyle footwear segments.
- Strategic Focus: Broadening its performance and lifestyle product assortment while accelerating omnichannel retail integration and e-commerce penetration across Japanese consumer markets.
Asics Corporation
Asics Corporation is a Japanese multinational corporation headquartered in Kobe, Japan, specializing in athletic footwear, apparel, and accessories with a particular focus on running and performance sports equipment.
- Product Portfolio: High-performance running shoes, alongside court shoes for tennis and volleyball.
- Recent Developments: Asics Corporation continues to advance its footwear research capabilities and expand its product range across running, trail, and court sport categories within the domestic market.
- Strategic Focus: Advancing biomechanics-based footwear development and strengthening performance category leadership through sustained investment in sports science, product engineering, and domestic market reach.
Market Concentration Analysis
The Japan athletic footwear market is moderately concentrated, with leading global brands, notably Nike, Inc., Adidas AG, and Asics Corporation, accounting for a significant portion of total market volume, supported by strong brand recognition, extensive retail distribution, and continuous investment in product innovation.
Barriers to market entry include substantial requirements for brand-building investment, performance technology development costs, the need for established relationships with Japan's organized retail networks, and the high consumer expectations for product quality and innovation that define the Japanese footwear market.
Consolidation trends are gradual, with leading global brands selectively acquiring design studios and technology start-ups to strengthen innovation pipelines. Strategic partnerships between athletic footwear brands, domestic retail chains, and e-commerce platforms are further shaping competitive positioning, particularly as direct-to-consumer channels gain importance across the Japanese market.
Investment & Growth Opportunities
Fastest-Growing Segments
Women represent the fastest-growing end user category, expanding on rising female sports and fitness participation rates across Japan. Within product types, aerobic and gym wear shoes are registering above-average growth, driven by increasing participation in gym workouts, aerobics, fitness classes, and indoor training activities, along with growing demand for lightweight and comfortable footwear.
Emerging Markets
Kyushu-Okinawa Region is an emerging market, driven by increasing participation in recreational sports, fitness activities, and outdoor pursuits, along with expanding retail availability and growing consumer interest in athletic and lifestyle footwear.
Venture & Investment Trends
Investment activity is concentrated in sustainable footwear material innovation, smart shoe technology development, and direct-to-consumer e-commerce platform enhancement. Capital is also directed toward customization technologies, personalized fit solutions, and athletic footwear lines targeting the growing women's and senior active consumer segments in Japan.
Future Market Outlook (2026-2034)
The Japan athletic footwear market is projected to grow from USD 4.62 Billion in 2025 to USD 4.82 Billion in 2026, reaching USD 6.72 Billion by 2034, registering a CAGR of 4.26% during 2026-2034.
Four forces will shape the market through 2034: continued premiumization of performance footwear driven by innovation in cushioning and motion control technologies; expanding lifestyle and athleisure demand beyond traditional sports demographics; growth of e-commerce and direct-to-consumer channels accelerating access to underserved regional markets; and rising consumer expectations for sustainable, eco-certified footwear.
By 2034, the Japan athletic footwear market is expected to be defined by integrated performance and lifestyle positioning, with women's footwear and outdoor categories accounting for a growing share of incremental volume. Brands that successfully combine product innovation, digital retail investment, and credible sustainability commitments are well-positioned to capture disproportionate share of the market's long-term growth.
Research Methodology
Primary Research
Primary research included structured interviews with senior representatives from athletic footwear brands, specialty sports retailers, footwear industry associations, and consumer market researchers operating in Japan, validating market sizing, segment mix, and regional demand patterns across product categories.
Secondary Research
Secondary sources included Japan Sports Agency publications, Ministry of Economy, Trade and Industry (METI) reports, Japan Sporting Goods Industry Association data, brand annual reports and investor presentations, trade press covering the Japanese athletic footwear sector, and publicly available consumer survey data.
Forecasting Models
Market forecasts used top-down and bottom-up models combining retail sales volume data, consumer spending trends, athletic participation statistics, and macroeconomic variables. Scenario analysis addressed consumer demand trends, sustainability transitions, e-commerce adoption pace, and competitive dynamics through the forecast period.
Japan Athletic Footwear Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Product Types Covered | Running Shoes, Training and Walking Shoes, Sport Shoes, Aerobic and Gym Wear Shoes, Trekking and Hiking Shoes, Others |
| Sports Footwear Types Covered | Tennis Shoes, Soccer Shoes, Basketball Shoes, Cricket Shoes |
| End Users Covered | Men, Women, Kids |
| Distribution Channels Covered | Hypermarket and Supermarket, Specialty Store, Brand Outlets, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Nike, Inc., Adidas AG, Asics Corporation, Mizuno Corporation, New Balance, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan athletic footwear market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan athletic footwear market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan athletic footwear industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Athletic Footwear Market Report
The Japan athletic footwear market size is estimated at USD 4.82 Billion in 2026, driven by rising health consciousness, strong sports participation culture, and growing demand for performance and lifestyle athletic footwear.
The market is projected to grow at a CAGR of 4.26% from 2026-2034, reaching USD 6.72 Billion, supported by expanding e-commerce retail channels, growing athleisure demand, and product innovation in sustainable footwear.
Running shoes lead the product type segment at 30.1% in 2025, reflecting Japan's established marathon and road racing culture and broad recreational running participation across age groups.
Men represent the largest end user segment at 48.7% of market share in 2025, reflecting historically higher rates of competitive and recreational sports participation and consistent demand for performance athletic footwear across running, training, and sport categories.
Kanto Region commands 36.8% of the market share in 2025, anchored by Greater Tokyo area's dense concentration of athletic retailers, fitness consumers, and brand headquarters.
Leading players include Nike, Inc., Adidas AG, Asics Corporation, Mizuno Corporation, and New Balance, Inc., among others.
Key trends include growing athleisure adoption, demand for sustainable eco-friendly footwear, emergence of smart footwear with wearable technology, and expansion of direct-to-consumer personalization platforms.
Key opportunities include expanding women's athletic footwear, growing outdoor and trekking footwear demand, penetration of secondary regional markets through e-commerce, and premium segment growth in smart and sustainable footwear.
E-commerce platforms are broadening market access beyond metropolitan retail centers, enabling brands to serve consumers in secondary cities and rural prefectures while supporting direct-to-consumer customization and digital engagement strategies.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade