
Japan Cloud Storage Market Size, Share, Trends and Forecast by Component, Deployment Type, Industry Vertical, and Region, 2026-2034
Japan Cloud Storage Market Size, Share, Trends & Forecast (2026-2034)
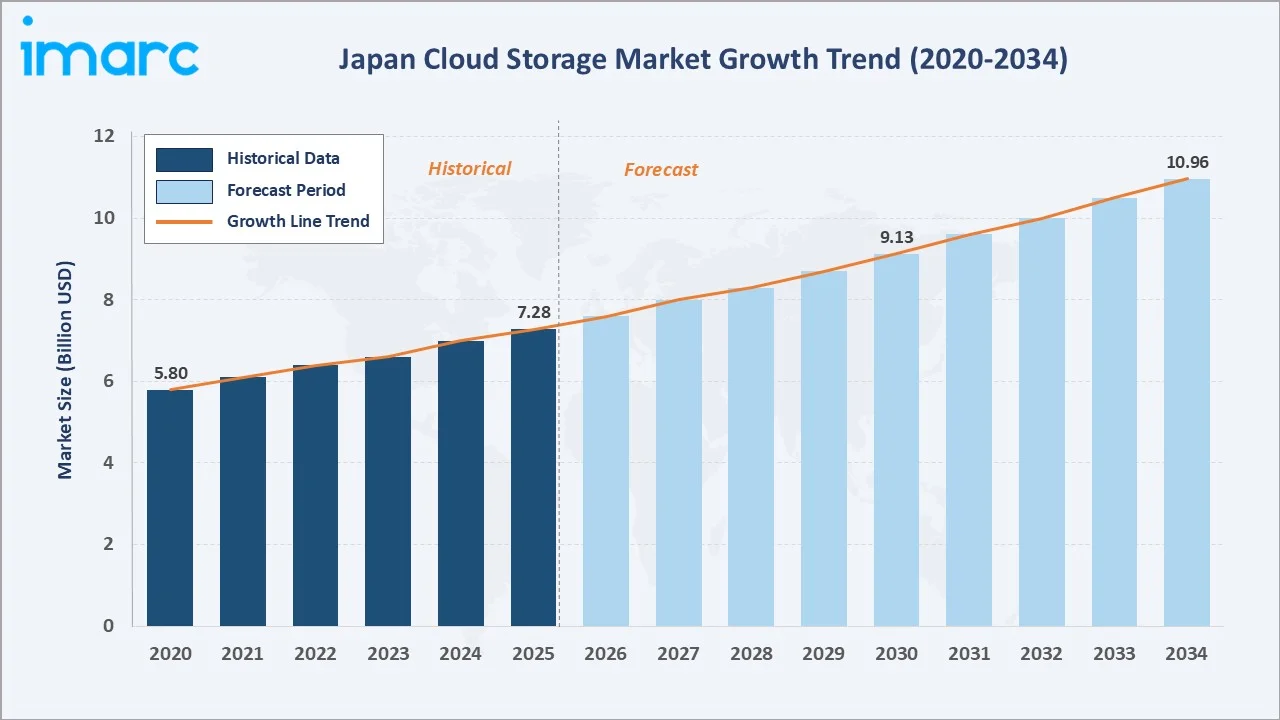
The Japan cloud storage market reached USD 7.28 Billion in 2025 and is projected to reach USD 10.96 Billion by 2034, expanding at a CAGR of 4.65% during 2026-2034. Rising data creation and consumption across enterprises, coupled with growing BFSI and healthcare sector adoption of cloud storage, and post-pandemic remote work and digital collaboration demand are the primary growth catalysts.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 7.28 Billion |
|
Forecast Market Size (2034) |
USD 10.96 Billion |
|
CAGR (2026-2034) |
4.65% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
The Kanto region leads the Japan cloud storage landscape, holding a 41.5% share in 2025, anchored by the region's concentration of enterprise headquarters and data center infrastructure. Solution offerings command the largest share of the component segment at 62.4%, reflecting sustained demand for scalable storage platforms and software across enterprise applications.
To get more information on this market, Request Sample
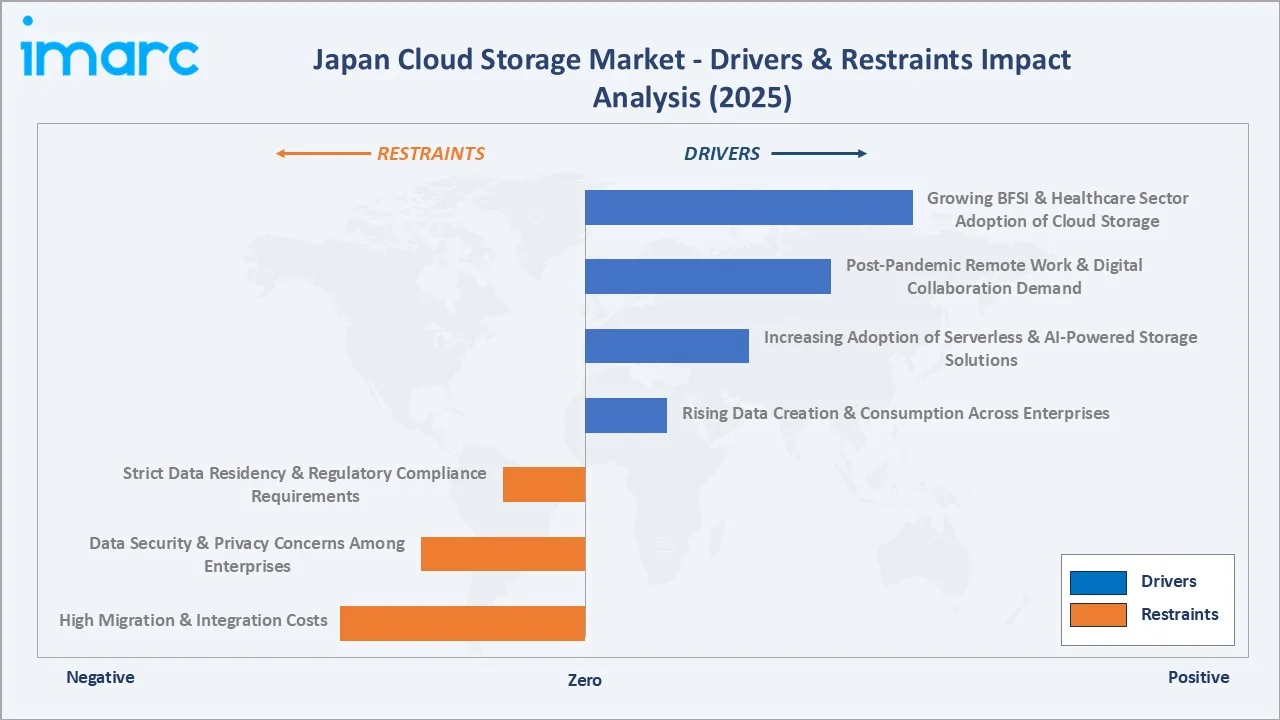
The Japan cloud storage market is underpinned by three structural forces: rising data creation and consumption across enterprises, growing BFSI and healthcare sector adoption of cloud storage, and post-pandemic remote work and digital collaboration demand. Each force independently reinforces category growth, sustaining steady CAGR expansion through 2034 despite strict data residency and regulatory compliance requirements.
Executive Summary
The Japan cloud storage market is experiencing steady expansion, driven by rising enterprise data creation, growing sector-specific cloud adoption, and supportive digital transformation trends. The market was valued at USD 7.28 Billion in 2025 and is forecast to reach USD 10.96 Billion by 2034, growing at a CAGR of 4.65%.
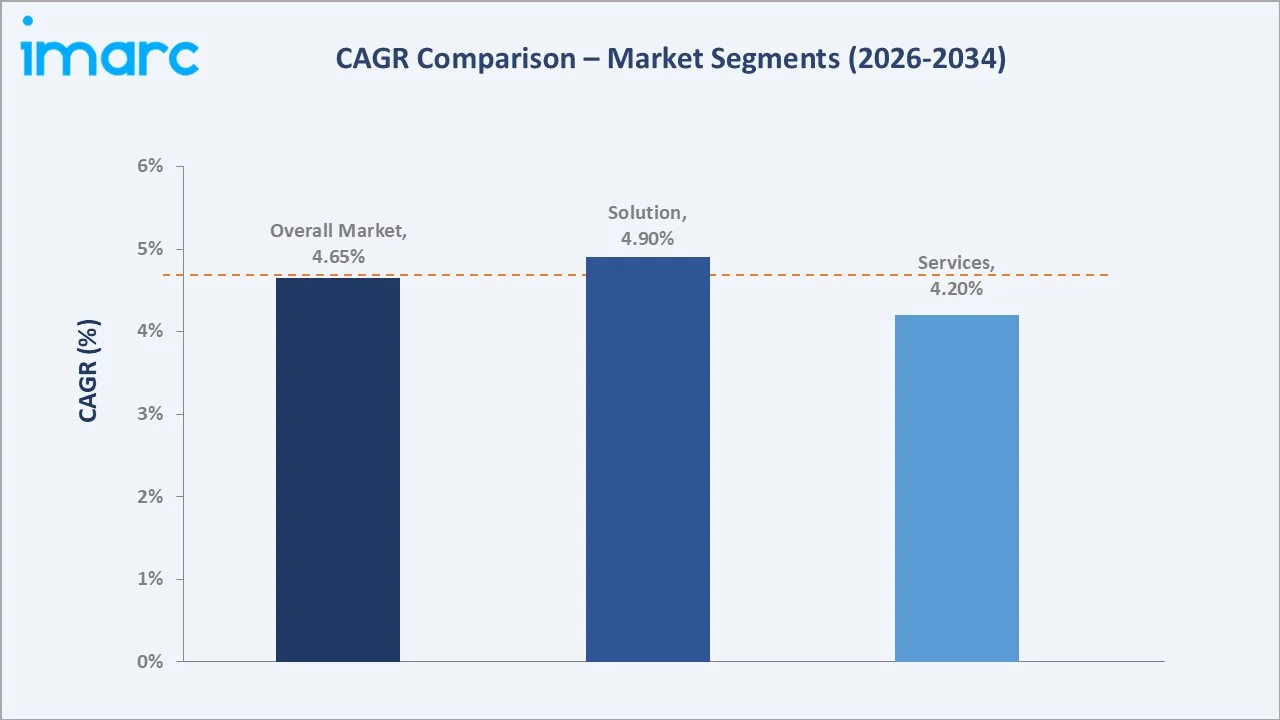
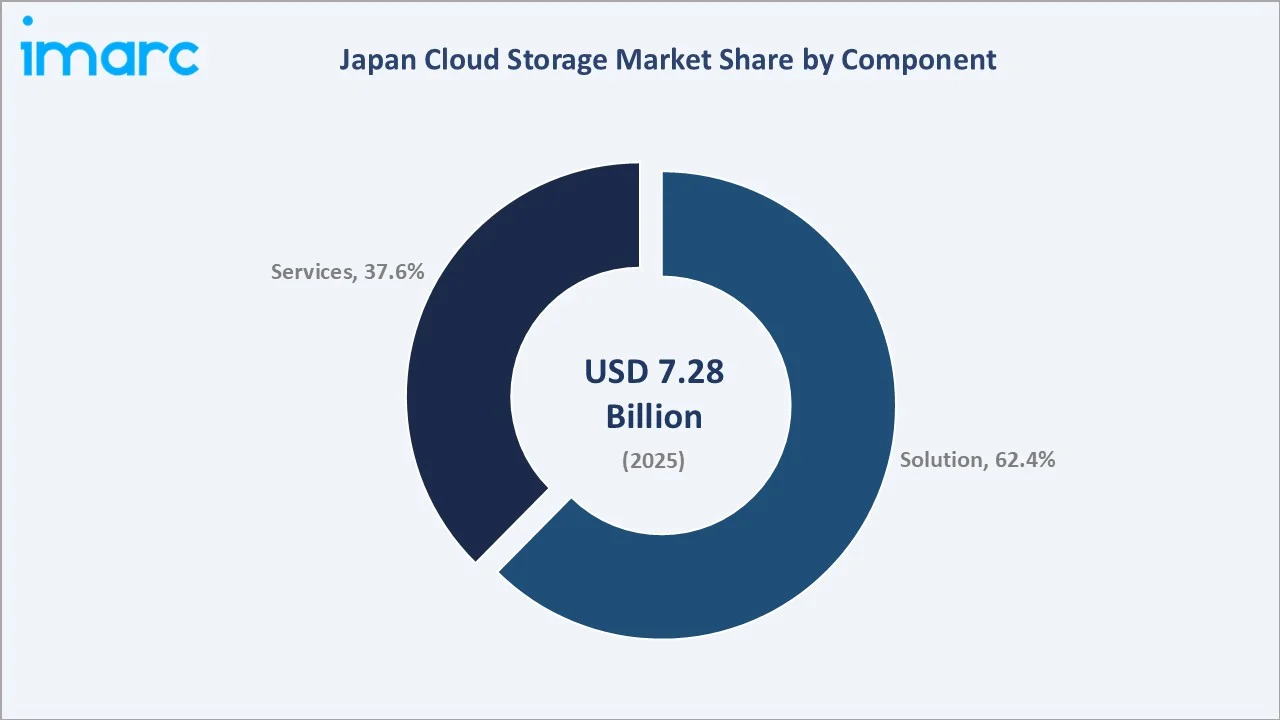
Solution offerings dominate the component segment with a 62.4% share in 2025, encompassing scalable storage platforms and software, while services account for 37.6%, reflecting continued demand for managed support, integration, and consulting services across enterprise deployments.
Public leads the deployment type segment at 46.8% share, supported by its cost efficiency and scalability, while hybrid (31.2%) and private (22.0%) continue to serve enterprises with stricter security and compliance requirements. The Kanto region leads regionally at 41.5%, anchored by the region's concentration of enterprise headquarters and data center infrastructure.
Key Market Insights
|
Insight |
Data |
|
Largest Component Segment |
Solution – 62.4% share (2025) |
|
Fastest Growing Component Segment |
Solution – ~4.9% CAGR (2026-2034) |
|
Largest Deployment Type Segment |
Public – 46.8% share (2025) |
|
Leading Region |
Kanto Region – 41.5% share (2025) |
|
Top Companies |
NTT Group, Fujitsu Limited, Hitachi, Ltd., KDDI CORPORATION, Internet Initiative Japan Inc. |
Key Analytical Observations Supporting The Above Data:
- Solution offerings account for 62.4% of the Japan cloud storage market in 2025. This dominance reflects sustained demand for scalable storage platforms and software across enterprise applications.
- Public remains the leading deployment type at a 46.8% share (2025), supported by its cost efficiency, scalability, and ease of adoption across enterprises of varying sizes.
- Hybrid deployment is expanding steadily at a 31.2% share (2025), as enterprises increasingly balance scalability with data security and compliance requirements.
- The Kanto region's 41.5% share (2025) reflects its concentration of enterprise headquarters, data center infrastructure, and business activity.
- Rising convergence of cloud storage with AI-powered management and serverless architectures is broadening the addressable market across BFSI, healthcare, government, and enterprise applications.
Japan Cloud Storage Market Overview
The Japan cloud storage market encompasses solution and services components delivered through public, private, and hybrid deployment models, offering scalable data storage, management, and security solutions for enterprises, government bodies, and other organizations. The cloud storage ecosystem spans infrastructure providers, platform and software developers, and an expanding network of data center operators and managed service partners.
Macroeconomic drivers include rising data creation and consumption across enterprises, growing BFSI and healthcare sector adoption of cloud storage, and post-pandemic remote work and digital collaboration demand. Providers are simultaneously investing in AI-powered management, serverless architectures, and hybrid deployment capabilities to improve service delivery, positioning the Japan cloud storage sector for continued innovation-led growth through 2034 despite strict data residency and regulatory compliance requirements.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
- Growing BFSI & Healthcare Sector Adoption of Cloud Storage: Rising adoption of cloud storage for electronic medical records, transaction data, and compliance archiving is accelerating category growth. Initiatives led by Fujitsu, IBM Japan, Sumitomo Mitsui Financial Group (SMBC), and SoftBank Corp. aim to strengthen data sovereignty, improve interoperability, and integrate financial infrastructure into healthcare delivery using cloud and AI technologies.
- Post-Pandemic Remote Work & Digital Collaboration Demand: A Japan survey reported that remote work adoption among Japanese companies increased from approximately 40% before February 2020 to more than 75% by April 2025. Continued hybrid and remote work arrangements are sustaining demand for accessible, secure cloud storage infrastructure.
- Increasing Adoption of Serverless & AI-Powered Storage Solutions: Growing integration of AI-powered management and serverless architectures is broadening cloud storage capability and adoption. For instance, in April 2026, Microsoft announced a USD 10 billion investment in Japan from 2026 to 2029 to expand domestic AI infrastructure, cybersecurity partnerships, and cloud capacity.
- Rising Data Creation & Consumption Across Enterprises: Growing enterprise data volumes are driving sustained cloud storage demand across Japanese businesses of all sizes.
Market Restraints
- Strict Data Residency & Regulatory Compliance Requirements: Japan's data protection and residency regulations can add complexity and cost to cloud storage deployment for enterprises. In July 2026, Japan’s parliament enacted a revised personal data protection law allowing companies to use sensitive information without individual consent for AI development and statistical analysis.
- Data Security & Privacy Concerns Among Enterprises: The 2026 Wasabi Cloud Storage Index found that 42% of Japanese respondents experienced a cyberattack that caused loss of access to public cloud data. Moreover, 46% said their cloud providers lacked adequate tools to mitigate cyberattacks, highlighting a major security gap in Japan’s expanding cloud ecosystem.
- High Migration & Integration Costs: Significant costs associated with migrating legacy on-premises systems to cloud storage can limit adoption among cost-sensitive enterprises.
Market Opportunities
- AI-Powered Storage Management Expansion: Rising demand for intelligent, automated storage management presents opportunities for providers offering AI-integrated solutions.
- Hybrid & Multi-Cloud Architecture Growth: Growing enterprise preference for hybrid and multi-cloud deployment creates opportunities for providers serving flexible, distributed storage needs.
- Serverless & Edge Computing Integration: Rising demand for serverless and edge-integrated storage solutions offers providers new technology integration opportunities.
Market Challenges
- Balancing Cost and Compliance: Providers must balance storage infrastructure costs with the need to meet strict regulatory and data residency requirements.
- Addressing Legacy System Migration: Ensuring consistent, secure migration of legacy on-premises data to cloud storage requires ongoing investment and coordination.
Emerging Market Trends
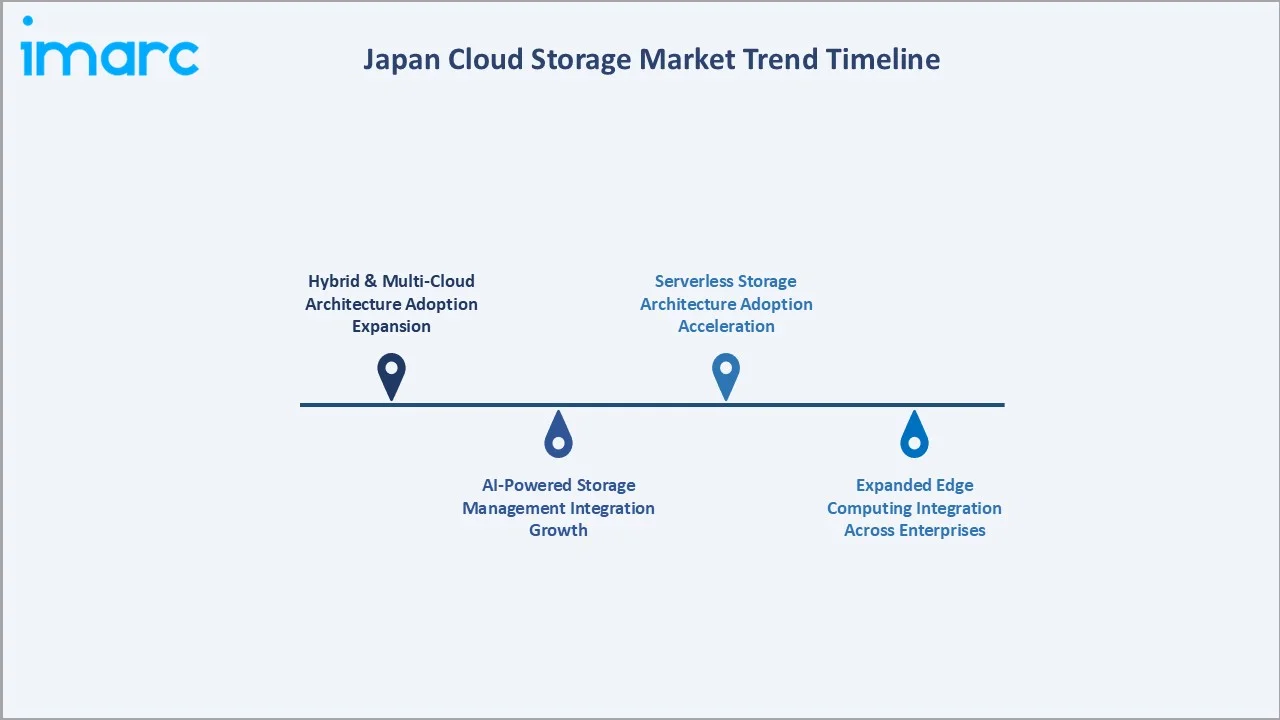
1. Hybrid & Multi-Cloud Architecture Adoption Expansion
Enterprises are increasingly adopting hybrid and multi-cloud storage architectures, enabling improved flexibility, redundancy, and cost optimization across workloads. In Japan, 83% of enterprise cloud decision-makers use at least two deployment models, while 76% of public-cloud users rely on multiple providers, highlighting strong demand for flexible multi-cloud architectures.
2. AI-Powered Storage Management Integration Growth
Growing integration of AI-powered management tools is improving storage efficiency, predictive capacity planning, and automated data tiering across enterprise deployments. For instance, Alibaba Cloud announced the launch of its fifth data center in Tokyo in June 2026, expanding secure cloud and AI capacity for Japanese enterprises across retail, gaming, entertainment, and manufacturing.
3. Serverless Storage Architecture Adoption Acceleration
Rising adoption of serverless storage architectures is eliminating fixed infrastructure costs and improving scalability for enterprises with variable storage demands.
4. Expanded Edge Computing Integration Across Enterprises
Growing enterprise adoption of edge computing integration is broadening cloud storage capability for real-time data processing and reduced-latency applications. In June 2026, At Tokyo and Zadara announced the launch of ATBeX Edge Compute Powered by Zadara, integrating compute, storage, and networking to support low-latency AI workloads across Japan.
Industry Value Chain Analysis
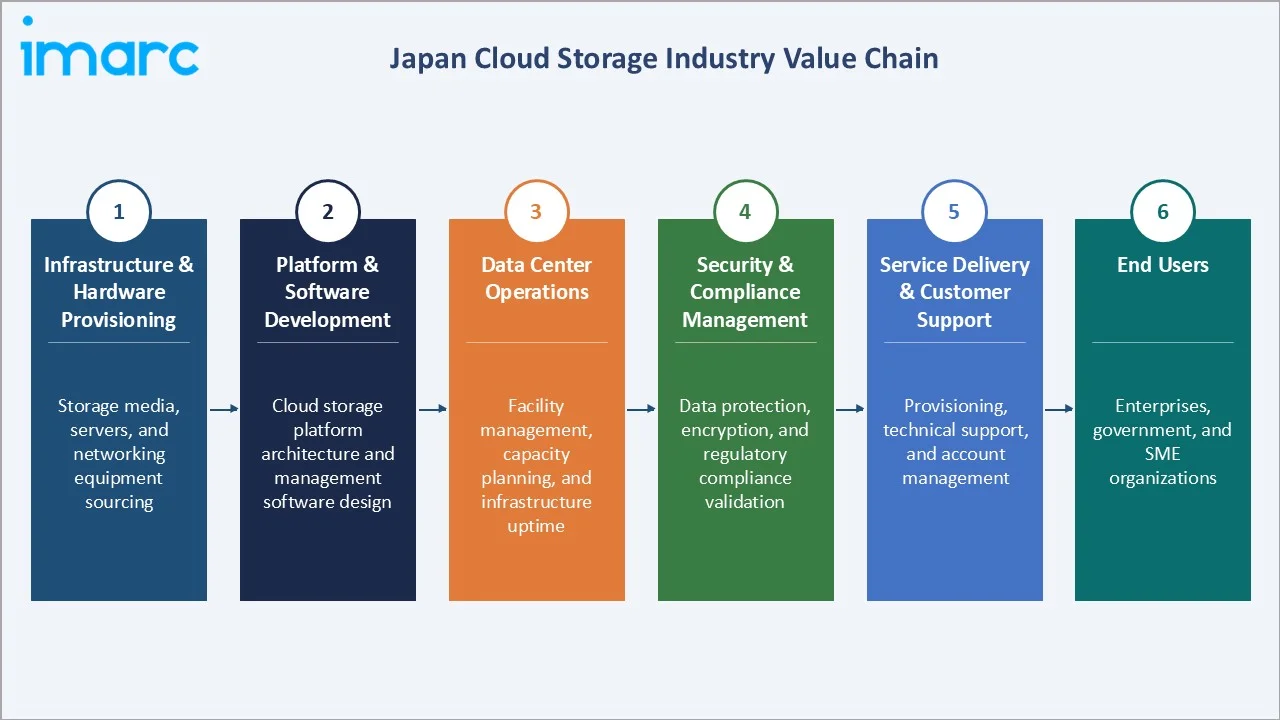
The Japan cloud storage value chain spans infrastructure provisioning through end-user delivery, with each stage occupied by specialized hardware providers, platform developers, and data center operators whose performance directly influences service reliability, security, and cost-effectiveness.
|
Stage |
Key Activities |
|
Infrastructure & Hardware Provisioning |
Storage media, servers, and networking equipment sourcing |
|
Platform & Software Development |
Cloud storage platform architecture and management software design |
|
Data Center Operations |
Facility management, capacity planning, and infrastructure uptime |
|
Security & Compliance Management |
Data protection, encryption, and regulatory compliance validation |
|
Service Delivery & Customer Support |
Provisioning, technical support, and account management |
|
End Users |
Enterprises, government, and SME organizations |
Technology Landscape in the Japan Cloud Storage Industry
Advanced Object & Block Storage Technology
Providers are advancing object and block storage technology to improve data accessibility and reliability, supporting broader adoption among enterprise and government applications. Enhanced erasure coding and replication techniques are further improving fault tolerance across distributed data centers.
AI-Integrated Storage Management Development
Growing investment in AI-powered storage management technology is expanding automated capacity planning and data tiering capabilities, addressing rising demand for operational efficiency. Predictive analytics tools are also enabling proactive identification of storage anomalies and performance bottlenecks.
Hybrid & Multi-Cloud Integration Systems
Providers are engineering advanced hybrid and multi-cloud integration systems to extend adoption across demanding enterprise and regulatory-sensitive application segments. Improved data sovereignty controls are further supporting compliance with Japan's stringent data residency requirements.
Serverless & Edge-Enabled Storage Innovation
Expanding research into serverless architecture and edge-enabled storage technology is strengthening system responsiveness, supporting premium positioning across latency-sensitive use cases. Growing deployment of edge caching nodes is further reducing data retrieval latency for geographically dispersed users.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Component |
Solution |
62.4% |
2025 |
|
Deployment Type |
Public |
46.8% |
2025 |
|
User Type |
🔒 |
🔒 |
2025 |
|
Industry Vertical |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
41.5% |
2025 |

By Component
Solution offerings dominate with a 62.4% share in 2025. This segment encompasses scalable storage platforms and software, supported by sustained demand for their reliability across enterprise applications.
To access detailed market analysis, Request Sample
Services represent 37.6% (2025) of the market, reflecting continued demand for managed support, integration, and consulting services across enterprise cloud storage deployments.
By Deployment Type
Public deployment leads the deployment type segment at a 46.8% share (2025), supported by its cost efficiency, scalability, and ease of adoption across enterprises of varying sizes.
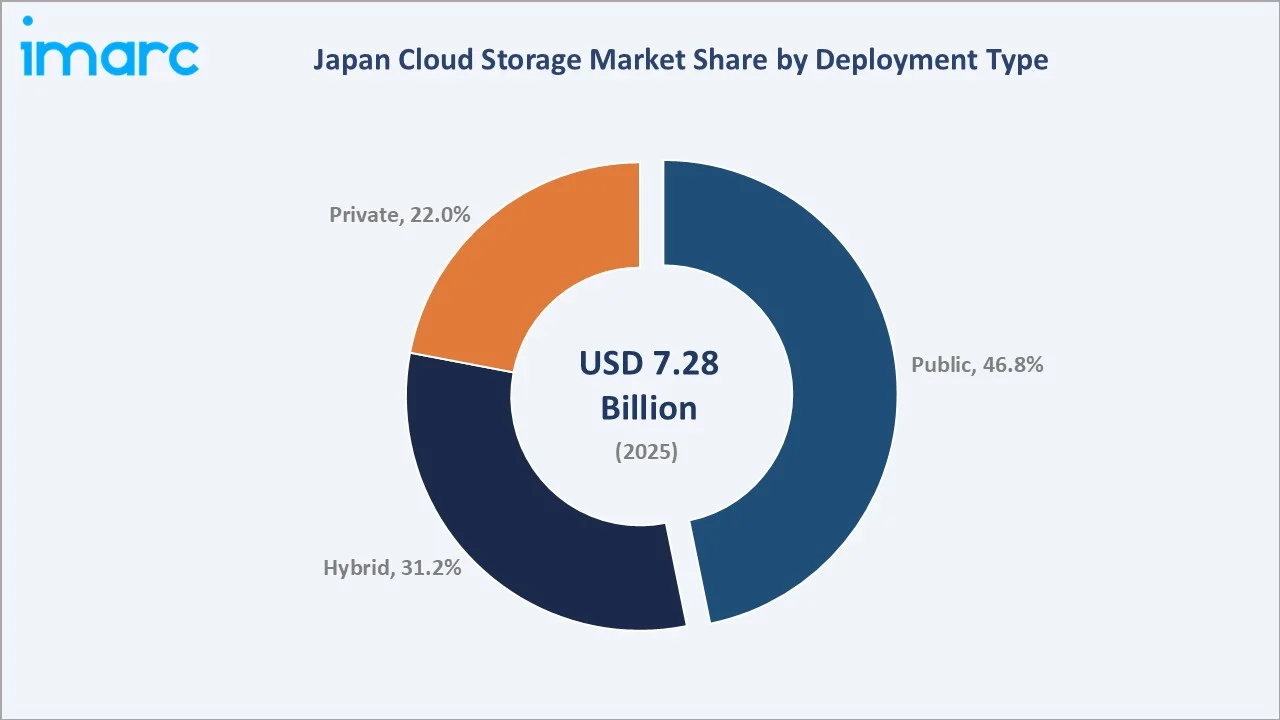
Hybrid (31.2%) and private (22.0%) continue to serve enterprises with stricter security and compliance requirements, with Hybrid expanding steadily as organizations balance scalability with data governance needs.
Regional Market Insights
The Kanto region's market leadership (41.5%, 2025) reflects its concentration of enterprise headquarters, data center infrastructure, and business activity. Growing enterprise digitalization and expanding hybrid cloud adoption combine to sustain its dominant position through 2034.
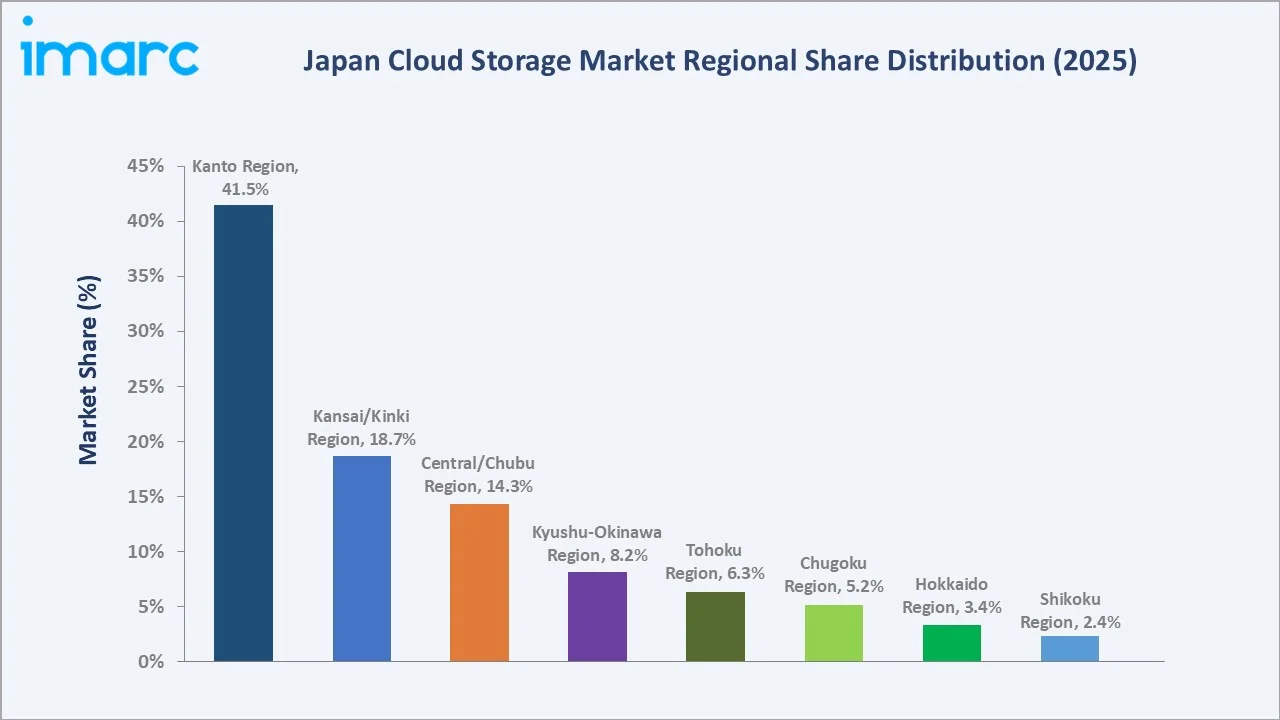
The Kansai/Kinki region at 18.7% (2025) represents the second-largest cloud storage market regionally. Strong industrial activity and expanding enterprise cloud adoption are sustaining steady growth, positioning the region as a key contributor alongside Kanto through the forecast period.
|
Region |
Share (2025) |
Key Growth Drivers |
|
Kanto Region |
41.5% |
Concentration of enterprise headquarters and data center infrastructure |
|
Kansai/Kinki Region |
18.7% |
Strong industrial base and expanding enterprise cloud adoption |
|
Central/Chubu Region |
14.3% |
Growing manufacturing sector and digitalization demand |
|
Kyushu-Okinawa Region |
8.2% |
Rising regional business development and cloud infrastructure investment |
|
Tohoku Region |
6.3% |
Growing industrial recovery and regional digital transformation |
|
Chugoku Region |
5.2% |
Rising manufacturing and logistics-linked cloud adoption |
|
Hokkaido Region |
3.4% |
Expanding regional data center investment and enterprise demand |
|
Shikoku Region |
2.4% |
Emerging regional digitalization initiatives |
Competitive Landscape
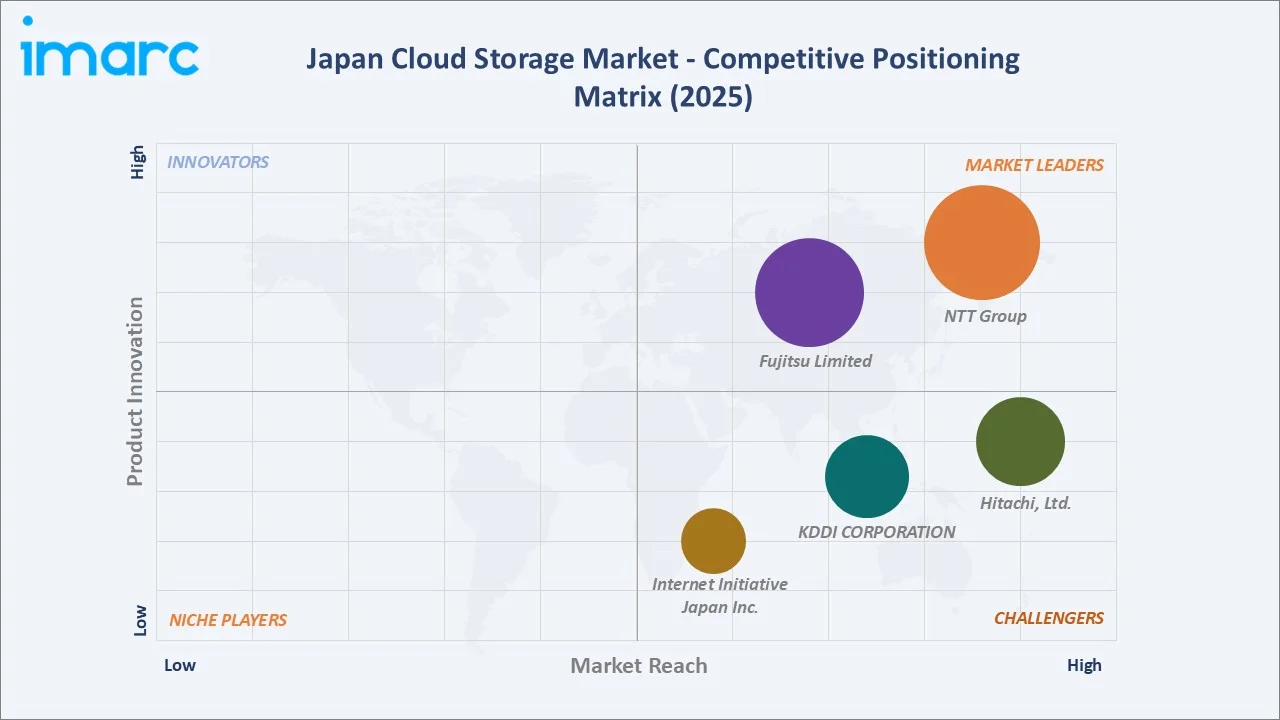
The Japan cloud storage market exhibits moderate concentration, with leading providers collectively holding a significant share of market revenue in 2025, reflecting sustained investment in infrastructure and service reach.
|
Company Name |
Brand Name |
Market Position |
Core Strength |
|
NTT Group |
NTT DATA |
Market Leader |
Nationwide telecom-backed data center infrastructure and enterprise cloud storage leadership |
|
Fujitsu Limited |
Fujitsu |
Market Leader |
Hybrid and private cloud storage expertise across manufacturing and public-sector accounts |
|
Hitachi, Ltd. |
Hitachi Vantara |
Strong Challenger |
Enterprise data infrastructure and object storage capabilities |
|
KDDI CORPORATION |
KDDI |
Strong Challenger |
Telecom-integrated cloud and data center service offerings |
|
Internet Initiative Japan Inc. |
IIJ |
Challenger |
Domestic cloud and IT services expertise with strong enterprise and government relationships |
NTT Group and Fujitsu Limited dominate through comprehensive nationwide infrastructure and extensive enterprise account servicing, supported by continuous digital investment. Hitachi, Ltd., KDDI CORPORATION, and Internet Initiative Japan Inc. compete through targeted premium positioning, telecom integration, and niche SME service differentiation, respectively.
Key Company Profiles
NTT Group
NTT Group’s subsidiary NTT DATA Group Corporation is one of Japan's dominant telecom-backed cloud and data center operators, leveraging nationwide infrastructure to serve enterprise cloud storage needs across BFSI, government, and other verticals.
- Product Portfolio: Cloud storage, data center colocation, and integrated enterprise infrastructure solutions under the NTT DATA brand.
- Recent Developments: In April 2026, NTT DATA Group Corporation opened the AI-ready Keihanna OSK11 Data Center in Kyoto, expanding its digital infrastructure footprint in Japan’s Kansai region. The facility provides 30 MW of IT capacity, resilient carrier-neutral connectivity, and efficient cooling to support growing cloud, AI, and enterprise workloads.
- Strategic Focus: Strengthening nationwide data center capacity; expanding cloud storage service reach across emerging application segments.
Fujitsu Limited
Fujitsu Limited is one of the major Japanese IT conglomerates offering hybrid and private cloud storage solutions with a strong presence across manufacturing and public-sector accounts.
- Product Portfolio: Hybrid and private cloud storage, enterprise IT infrastructure, and integrated digital solutions under the Fujitsu brand.
- Recent Developments: In December 2025, Fujitsu Limited and the University of Tokyo launched Japan’s first cloud-connected trial to shift computing workloads between regional data centers based on power-grid conditions and electricity prices.
- Strategic Focus: Scaling hybrid cloud storage capabilities; deepening manufacturing and public-sector distribution partnerships.
Market Concentration Analysis
The Japan cloud storage market exhibits moderate concentration, with NTT Group, Fujitsu Limited, and Hitachi, Ltd. collectively accounting for a significant share of total category revenue in 2025, reflecting sustained infrastructure investment, brand loyalty, and extensive distribution capacity across the region.
Consolidation pressure remains limited as leading providers maintain distinct strategic positioning: NTT Group and Fujitsu Limited through comprehensive multi-segment infrastructure portfolios, Hitachi, Ltd. and KDDI CORPORATION through object storage and telecom-integration positioning, and Internet Initiative Japan Inc. through diversified niche and hardware-focused differentiation, rather than pursuing direct M&A consolidation.
Investment & Growth Opportunities
Fastest Growing Segments
Solution offerings (~4.9% CAGR) represent the highest-growth investment vector through 2034, driven by expanding enterprise digitalization demand and continuous innovation across storage platform technologies. This subcategory addresses a rapidly expanding addressable market within the Japan cloud storage ecosystem.
Emerging Market Expansion
Hokkaido and Shikoku regional markets collectively represent an incremental growth opportunity beyond the Kanto region, Kansai/Kinki region, and Central/Chubu region by 2034, as rising regional data center investment and expanding digitalization accelerate category penetration in these emerging markets.
Venture and Institutional Investment Trends
- Provider investment toward AI-powered storage management technology is creating opportunities for technology vendors serving the cloud storage sector.
- Growing hybrid and multi-cloud adoption demand is sustaining institutional interest in specialty infrastructure and integration platforms.
- Serverless and edge computing innovation, led by major providers, is opening opportunities for technology vendors serving the Japan cloud storage industry.
Future Market Outlook (2026-2034)
The Japan cloud storage market is positioned for steady, technology-driven expansion through 2034. From a base of USD 7.28 Billion in 2025, the market is projected to reach USD 10.96 Billion by 2034, representing incremental value creation at a CAGR of 4.65%. This growth is underpinned by rising enterprise data creation, growing sector-specific cloud adoption, and supportive digital transformation trends.
The component segment will continue evolving through 2034, with Solution offerings gaining further share as enterprise digitalization and AI-powered storage demand accelerate. This shift creates opportunities for providers investing in hybrid architecture, serverless technology, and edge-integrated storage capacity to capture the next phase of the Japan cloud storage market growth.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry participants across 2024-2025, including cloud storage provider executives, enterprise IT procurement managers, government technology administrators, and data infrastructure specialists across major Japanese regions. Expert input validated market sizing, segmentation trends, and regional consumption patterns.
Secondary Research
Secondary research encompassed provider annual reports, cloud industry association publications, and trade press covering technology innovation, regulatory trends, and regional market dynamics across major markets.
Forecasting Models
Market size estimations were derived using top-down and bottom-up forecasting, incorporating component and deployment segment transitions and provider capacity disclosures. A base-case CAGR of 4.65% reflects consensus estimates validated against announced infrastructure investment timelines and provider strategic development plans.
Japan Cloud Storage Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Components Covered | Solution, Services |
| Deployment Types Covered | Private, Public, Hybrid |
| User Types Covered | Large Enterprises, Small and Medium-sized Enterprises |
| Industry Verticals Covered | BFSI, Government and Public Sector, Healthcare, IT and Telecom, Retail, Manufacturing, Media and Entertainment, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | NTT Group, Fujitsu Limited, Hitachi, Ltd., KDDI CORPORATION, Internet Initiative Japan Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan cloud storage market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan cloud storage market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan cloud storage industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Cloud Storage Market Report
The Japan cloud storage market reached USD 7.28 Billion in 2025 and is projected to reach USD 10.96 Billion by 2034.
The market is expected to grow at a CAGR of 4.65% during 2026-2034, driven by rising enterprise data creation and growing sector-specific cloud adoption.
Kanto region leads with a 41.5% share in 2025, anchored by the region's concentration of enterprise headquarters and data center infrastructure.
Solution dominates with a 62.4% share in 2025, driven by sustained demand for scalable storage platforms and software.
Public deployment leads with a 46.8% share in 2025, supported by its cost efficiency and scalability.
Some of the key players include NTT Group, Fujitsu Limited, Hitachi, Ltd., KDDI CORPORATION, and Internet Initiative Japan Inc.
Solution offerings are growing fastest at an estimated 4.9% CAGR as enterprise digitalization demand accelerates.
Key challenges include strict data residency and regulatory compliance requirements, data security and privacy concerns, and high migration costs for legacy systems.
AI-powered storage management expansion, hybrid and multi-cloud architecture growth, and serverless and edge computing integration represent leading investment opportunities.
Hybrid deployment, at 31.2% share, is expanding steadily as enterprises balance scalability with data security and compliance requirements.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade