
Japan Cybersecurity Market Size, Share, Trends and Forecast by Component, Deployment Type, User Type, Industry Vertical, and Region, 2026-2034
Japan Cybersecurity Market Size, Share, Trends & Forecast (2026-2034)
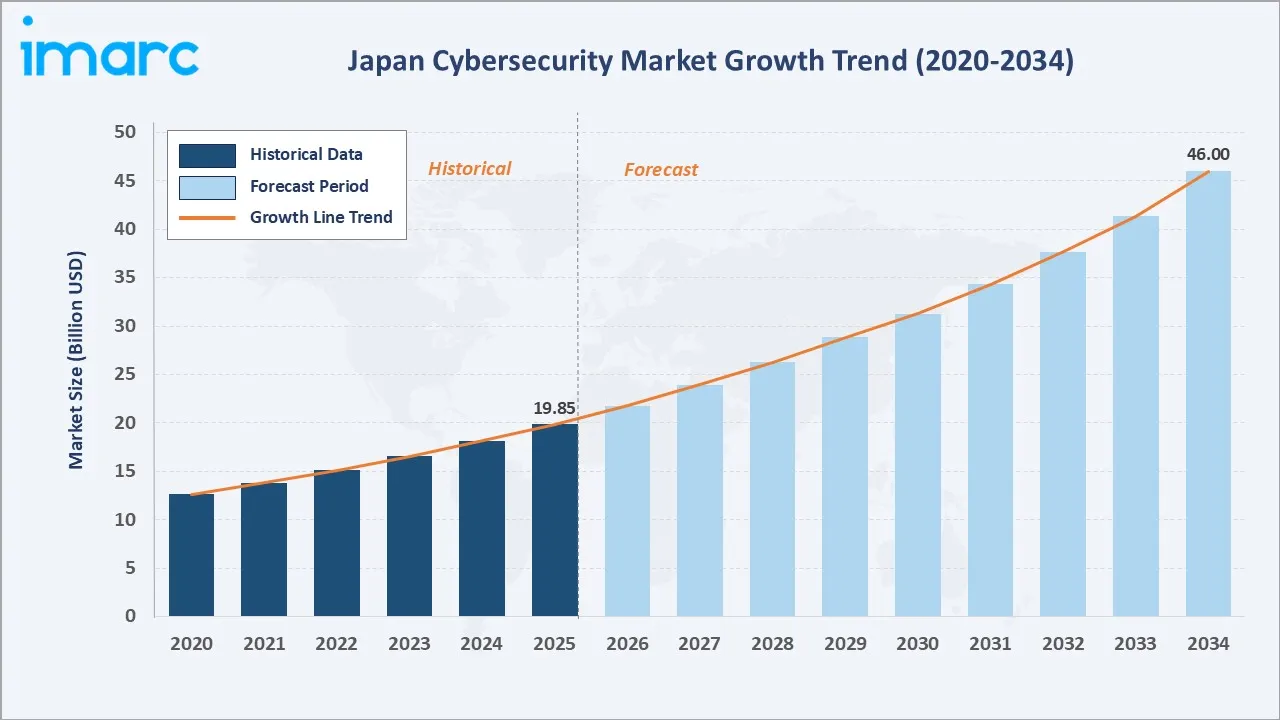
The Japan cybersecurity market grew from USD 19.85 Billion in 2025 to USD 22.27 Billion in 2026 and is projected to reach USD 46.00 Billion by 2034, growing at a CAGR of 9.5% during 2026-2034. Growth is underpinned by an escalating frequency of sophisticated cyberattacks, with over 200 incidents attributed to foreign state actors between 2019 and 2024, alongside rapid cloud adoption, AI integration, and government-mandated data protection reforms. Cloud-based solutions dominate with a 58.7% deployment share in 2025, while large enterprises represent 63.5% of end-user demand. The Kanto region leads regionally, contributing 36.7% of total revenue in 2025.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 19.85 Billion |
|
Market Size (2026) |
USD 22.27 Billion |
|
Forecast Market Size (2034) |
USD 46.00 Billion |
|
CAGR (2026-2034) |
9.5% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Deployment Type |
Cloud-based (58.7%, 2025) |
|
Dominant User Type |
Large Enterprises (63.5%, 2025) |
|
Leading Region |
Kanto Region (36.7%, 2025) |
The Japan cybersecurity market grew from USD 12.62 Billion in 2020 to USD 19.85 Billion in 2025, and further to USD 22.27 Billion in 2026, reaching USD 31.24 Billion by 2030 and USD 46.00 Billion by 2034.
To get more information on this market, Request Sample
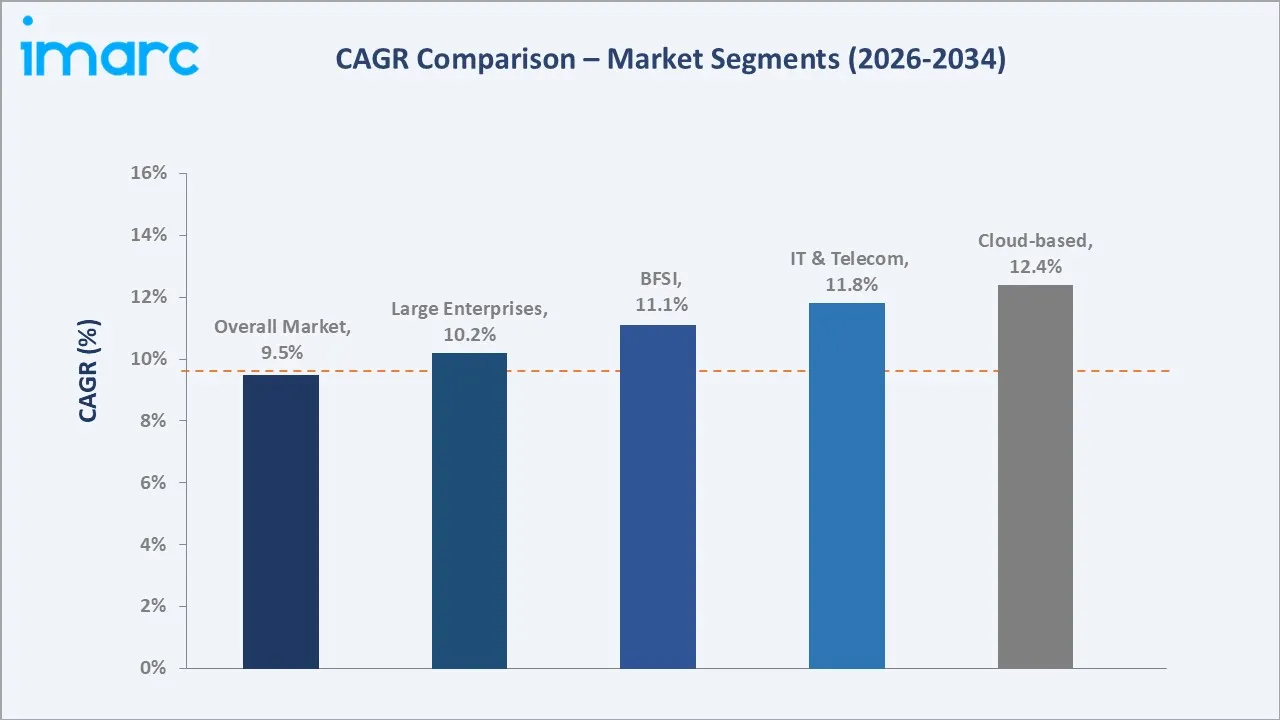
Cloud-based solutions lead at 12.4% CAGR, reflecting accelerating shift to subscription-based security architectures. The IT and telecom vertical follows at 11.8%, driven by infrastructure modernization. BFSI records 11.1% CAGR amid intensifying regulatory scrutiny, while the large enterprise user segment grows at 10.2%, supported by advanced SOC and XDR investments.
Executive Summary
The Japan cybersecurity market is on a consistent growth trajectory, underpinned by rising state-sponsored cyber threats, accelerating cloud transformation, and stringent regulatory compliance. Digital transformation across BFSI, healthcare, and manufacturing continues to amplify enterprise security spending. AI-integrated threat detection, zero-trust architecture, and managed security services are transformative forces shaping the competitive landscape.
Cloud-based at 58.7%, reflecting enterprise preference for scalable subscription security architectures and reduced on-site infrastructure burden. Large enterprises at 63.5%, driven by complex, multi-layered IT environments requiring dedicated threat management and advanced compliance capabilities. Kanto region at 36.7%, anchoring market leadership through Tokyo's concentration of financial institutions, government agencies, and technology headquarters.
Key Market Insights
|
Insight |
Data |
|
Dominant Deployment |
Cloud-based – 58.7% revenue share (2025) |
|
Dominant User Type |
Large Enterprises – 63.5% market share (2025) |
|
Leading Region |
Kanto Region – 36.7% of total market revenue (2025) |
|
Market Opportunity |
AI-driven security tools, SME managed services, and government-mandated compliance programs. |
Key Analytical Observations Supporting the Above Data:
- Cloud-based at 58.7%: Cloud-based solutions' dominance reflects enterprise preference for scalable subscription security and hybrid cloud expansion across Japan's enterprise landscape.
- Large Enterprises at 63.5%: Large enterprises commanded 63.5% of user-type revenue, driven by complex IT environments and stringent regulatory compliance obligations across BFSI, healthcare, and critical infrastructure.
- Kanto Region at 36.7%: The Kanto region generated 36.7% of total market revenue in 2025, underpinned by Tokyo's dense cluster of financial institutions, tech headquarters, and government ministries requiring advanced security.
Japan Cybersecurity Market Overview
The Japan cybersecurity market encompasses the technologies, processes, and services designed to protect digital infrastructure, data, and networks from unauthorized access, disruption, and attacks. The ecosystem spans solution providers, covering identity management, infrastructure security, and data privacy, as well as professional and managed service providers serving enterprise and government clients. Japan's market is significantly influenced by accelerated digital transformation, increasing cross-border data flows, and geopolitical tensions driving state-sponsored cyber threats.
Applications span financial services, healthcare, manufacturing, telecommunications, and government, making cybersecurity a foundational pillar of Japan's digital economy strategy. The market serves a broad ecosystem spanning individual enterprises, large conglomerates, government ministries, and critical infrastructure operators.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
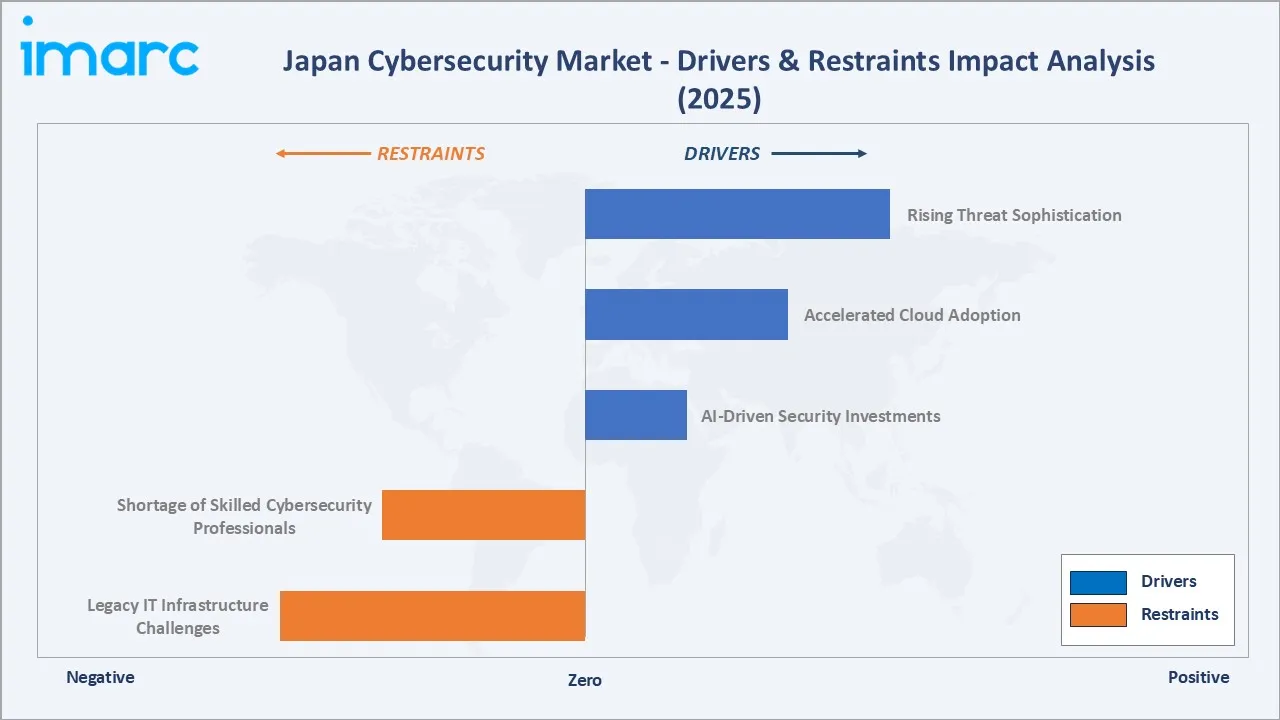
- Rising Threat Sophistication: Japan recorded over 200 state-attributed cyberattacks between 2019 and 2024, compelling enterprises to significantly increase security budgets and adopt advanced threat detection and response platforms.
- Accelerated Cloud Adoption: Cloud workloads in Japan are growing, expanding the attack surface and creating heightened demand for cloud-native security solutions and identity management services.
- AI-Driven Security Investments: Generative AI adoption across enterprises is driving investments in AI-powered security operations centers to counter AI-enabled attack vectors and automate threat response workflows at scale.
Market Restraints
- Shortage of Skilled Cybersecurity Professionals: A persistent shortage of qualified cybersecurity professionals constrains deployment timelines and increases operational costs for security teams across both public and private sectors in Japan.
- Legacy IT Infrastructure Challenges: Integration complexity between legacy IT systems and modern cybersecurity platforms prolongs deployment cycles and reduces solution effectiveness in older enterprise environments.
Market Opportunities
- SME Market Penetration: Over 60% of Japanese SMEs lack formalized cybersecurity protocols as of 2025, representing a substantial untapped market for affordable subscription-based managed security services.
- Public Sector Expansion: Government investments in active cyber defense and national security infrastructure are expected to generate significant public-sector procurement opportunities through the forecast period.
Market Challenges
- Rising Costs of Continuous Cybersecurity Updates and Threat Mitigation: The rapidly evolving threat landscape requires continuous product updates and security patch cycles, placing ongoing financial and operational burdens on both vendors and enterprise clients.
- Increasing Sophistication of Social Engineering Attacks: The growing sophistication of social engineering attacks, including phishing and business email compromise, remains difficult to address through technology alone, requiring sustained workforce training.
Emerging Market Trends
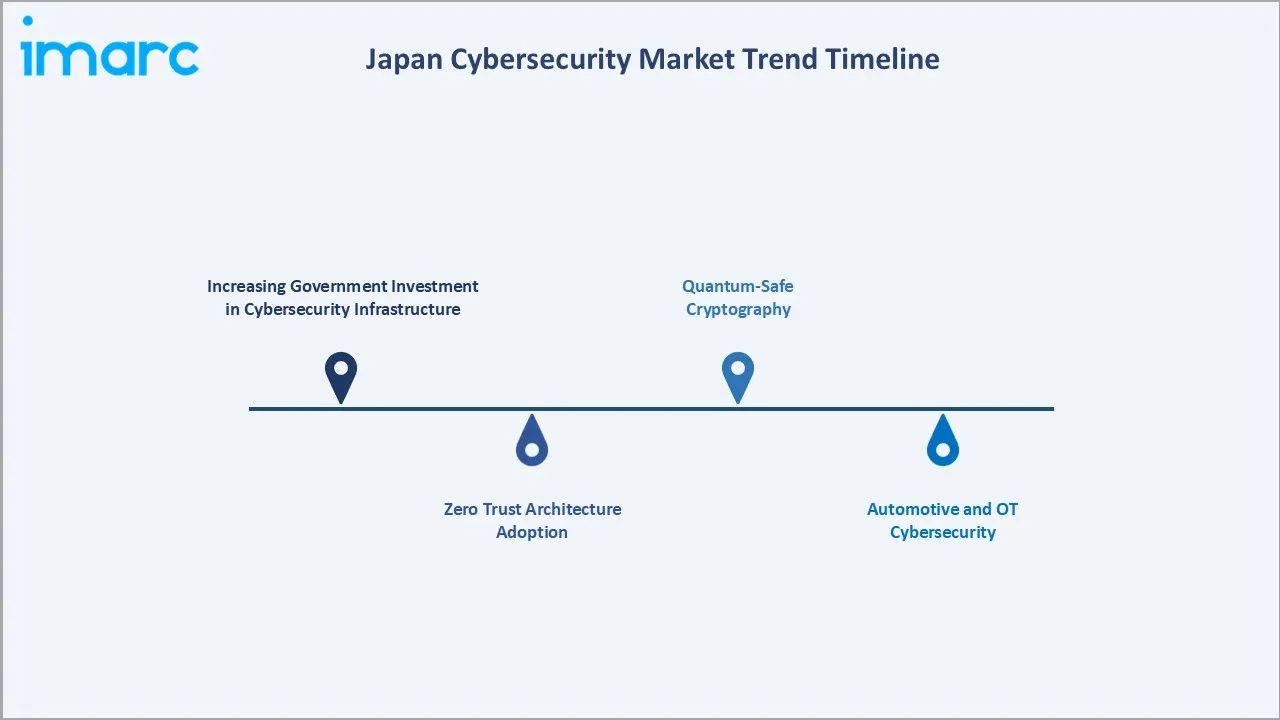
1. Increasing Government Investment in Cybersecurity Infrastructure
Increased government funding and security initiatives are expected to accelerate demand for advanced threat detection, incident response, data protection, and enterprise cybersecurity solutions. In November 2026, Japan introduced a multimillion-dollar emergency policy package in response to a surge in cyberattacks targeting businesses. Prime Minister Sanae Takaichi pledged stronger action following reports of unauthorized system access and potential customer data breaches across several companies.
2. Zero Trust Architecture Adoption
Zero trust principles, requiring verification of every user and device regardless of network location, are gaining rapid traction. Adoption is growing rapidly, driven by remote work policies and hybrid cloud environments across Japan's large enterprises.
3. Quantum-Safe Cryptography
With quantum computing advancing rapidly, Japan's financial and defense sectors are beginning to invest in quantum-resistant encryption standards. Pilot programs for post-quantum cryptography are underway, with commercial deployment expected between 2027 and 2030 across regulated industries.
4. Automotive and OT Cybersecurity
According to the Japan Automobile Manufacturers Association (JAMA), Japan's vehicle production rose by 1.9% year over year to 691,156 units in December 2025, while annual production increased by 2.1% to 8.41 million units. Japan's automotive manufacturing dominance is driving demand for operational technology cybersecurity.
Industry Value Chain Analysis
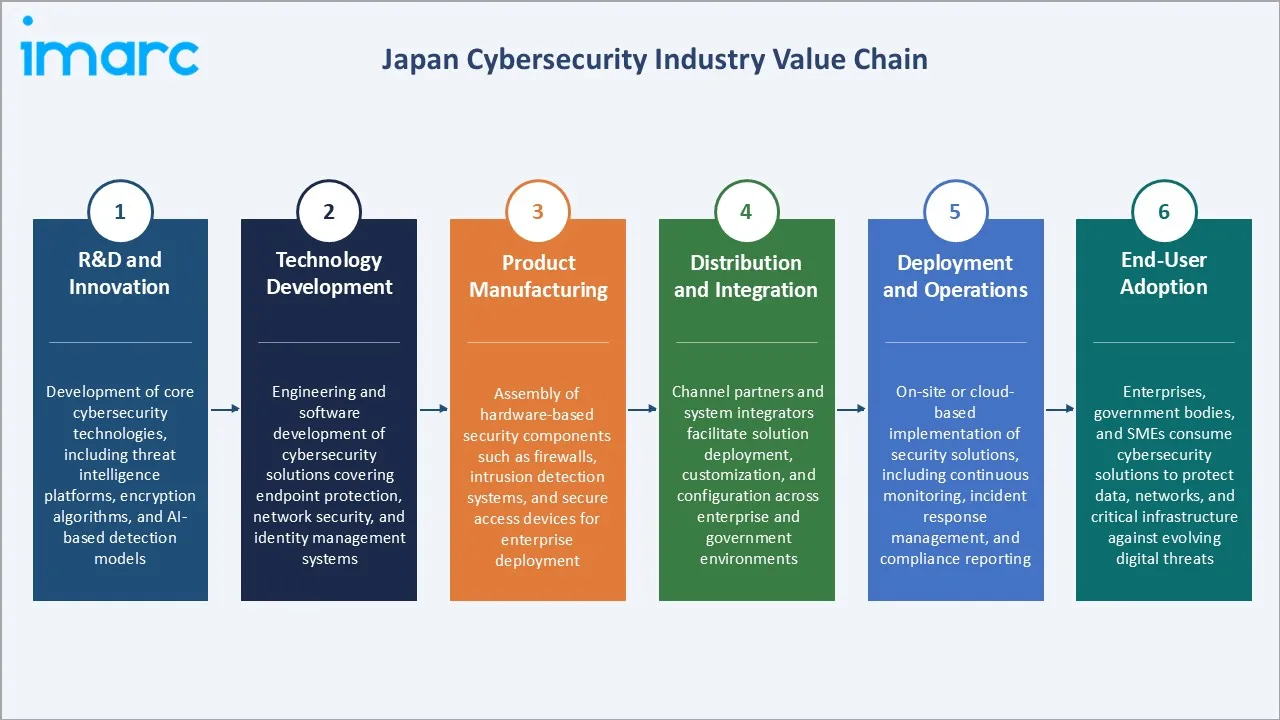
The Japan cybersecurity market value chain is structured across six integrated stages from research and innovation through end-user adoption. Each stage adds distinct value and involves specialized participants contributing to the overall security ecosystem.
|
Stage |
Key Participants |
| R&D and Innovation | Development of core cybersecurity technologies, including threat intelligence platforms, encryption algorithms, and AI-based detection models. |
| Technology Development | Engineering and software development of cybersecurity solutions covering endpoint protection, network security, and identity management systems. |
| Product Manufacturing | Assembly of hardware-based security components such as firewalls, intrusion detection systems, and secure access devices for enterprise deployment. |
| Distribution and Integration | Channel partners and system integrators facilitate solution deployment, customization, and configuration across enterprise and government environments. |
| Deployment and Operations | On-site or cloud-based implementation of security solutions, including continuous monitoring, incident response management, and compliance reporting. |
| End-User Adoption | Enterprises, government bodies, and SMEs consume cybersecurity solutions to protect data, networks, and critical infrastructure against evolving digital threats. |
The deployment and operations stage holds the greatest strategic significance in the cybersecurity value chain, as managed security service providers deliver continuous monitoring and incident response. This stage drives the greatest recurring revenue potential, with managed security services growth as enterprises shift to operational-expenditure security models.
Technology Landscape in the Japan Cybersecurity Industry
Cloud-Native Security Platforms
Japanese enterprises are increasingly adopting cloud-native security solutions to protect cloud-based applications, workloads, and digital infrastructure. These platforms offer scalable threat detection, continuous monitoring, automated security updates, and centralized protection across hybrid and multi-cloud environments. Additionally, growing cloud adoption is encouraging organizations to shift toward flexible, integrated cybersecurity frameworks.
Extended Detection and Response (XDR)
Japanese organizations are increasingly adopting Extended Detection and Response (XDR) solutions to strengthen cybersecurity across endpoints, networks, cloud environments, and email systems. These platforms integrate security data from multiple sources to identify threats, detect suspicious activities, and automate incident responses. Additionally, XDR helps reduce response times, improve threat visibility, and enhance overall security operations.
Security Orchestration and Automation (SOAR)
Japanese organizations are increasingly leveraging SOAR solutions to automate repetitive cybersecurity tasks and streamline incident response processes. These platforms integrate multiple security tools to centralize threat monitoring, investigation, and remediation activities. Additionally, SOAR improves operational efficiency, reduces manual workloads, and enables security teams to respond more quickly to cyber threats.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Component |
🔒 |
🔒 |
2025 |
|
Deployment Type |
Cloud-based |
58.7% |
2025 |
|
User Type |
Large Enterprises |
63.5% |
2025 |
|
Industry Vertical |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
36.7% |
2025 |

By Deployment Type
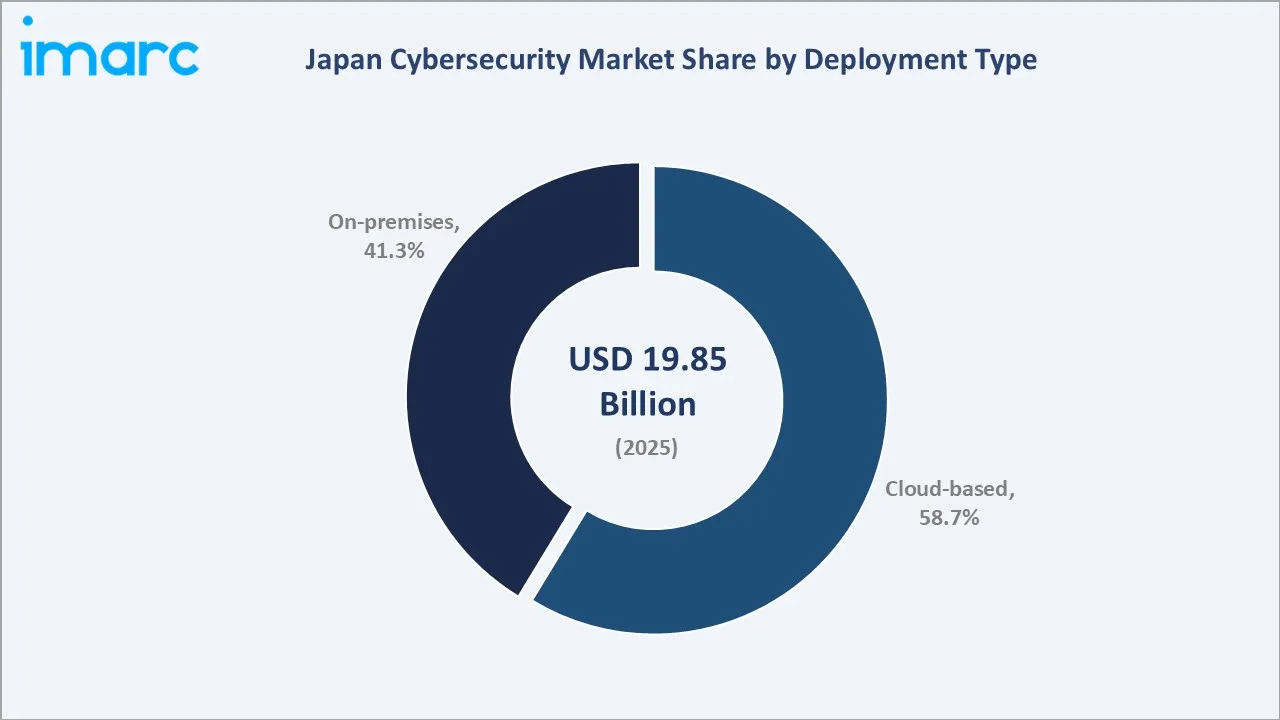
Cloud-based leads at 58.7% in 2025, reflecting enterprise preference for scalable, subscription-based security infrastructure and the rapid adoption of hybrid and multi-cloud environments across Japan. The cloud-based sub-segment is expected to grow at a CAGR of approximately 12.4% through 2034, driven by ongoing digital transformation and demand for real-time, remotely managed security services.
To access detailed market analysis, Request Sample
On-premises solutions at 41.3% retain significance in sectors with stringent data sovereignty requirements, such as defense, government, and core financial services. This segment is forecast to maintain a stable share of approximately 38-42% through 2034, supported by legacy infrastructure upgrades and security modernization programs in regulated industry verticals.
By User Type
Large enterprises lead at 63.5% in 2025, underpinned by complex multi-layered IT environments, dedicated security operations teams, and high regulatory compliance burdens across BFSI, healthcare, and manufacturing. Their preference for end-to-end managed security services and bespoke deployments drives premium pricing and higher average contract values across the market.
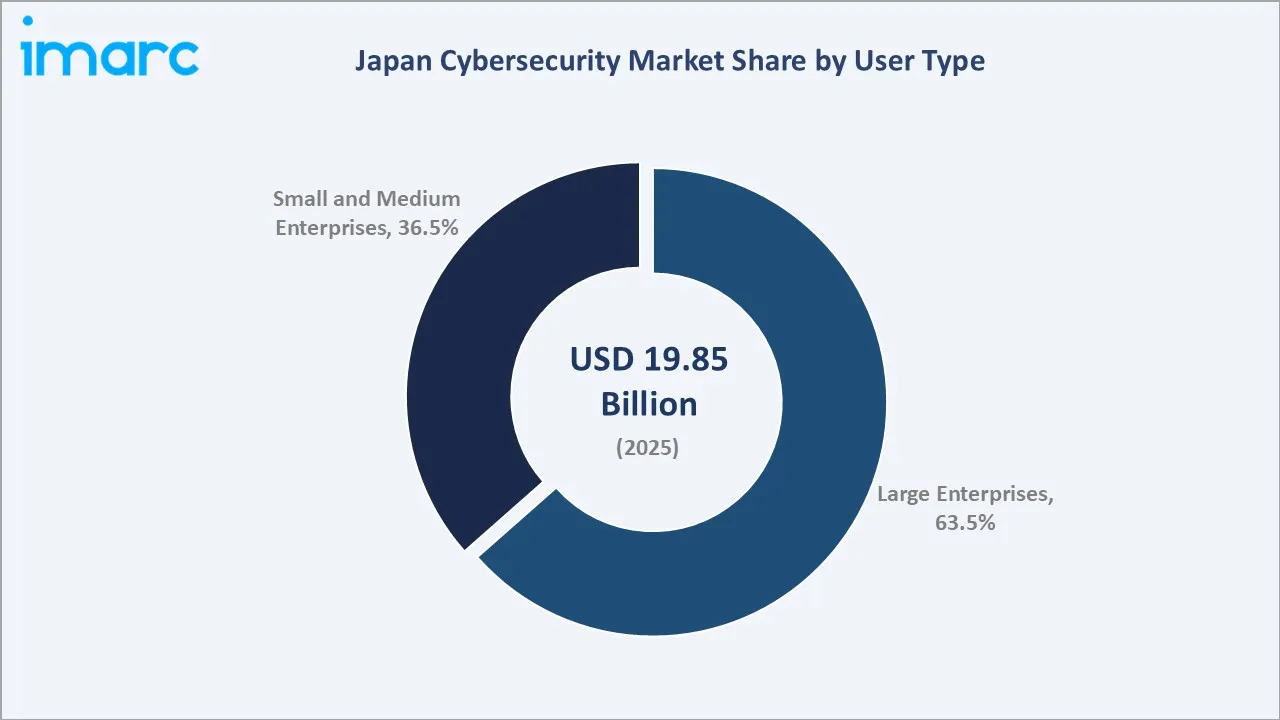
Small and medium enterprises at 36.5% represent the fastest-growing user category. As affordable cloud-based security subscriptions emerge and government support programs expand, SME adoption is forecast to grow at approximately 11.5% CAGR through 2034, progressively closing the spending gap with large enterprise security investment levels across all major verticals.
Regional Market Insights
|
Region |
Share (2025) |
Key Drivers & Characteristics |
| Kanto Region | 36.7% | Dense concentration of financial institutions, tech firms, and government agencies. |
| Kinki Region | 19.8% | Diverse industrial bases include manufacturing, retail, and pharmaceuticals. |
| Central/Chubu Region | 16.4% | Automotive and heavy machinery sector drives OT and industrial cybersecurity demand. |
| Kyushu-Okinawa Region | 9.6% | Emerging technology and logistics hub with growing SME digitization activity. |
| Tohoku Region | 6.9% | Recovery-driven digital infrastructure expansion and government framework adoption. |
| Chugoku Region | 5.8% | Industrial and maritime sector activity drives supply chain security demand. |
| Hokkaido Region | 3.0% | Agriculture, tourism, and public services digitization driving cloud adoption. |
| Shikoku Region | 1.8% | Emerging market for foundational cybersecurity services targeting SMEs. |
The Kanto region contributed 36.7% of Japan's total cybersecurity revenue in 2025, making it the dominant regional market. The concentration of financial institutions, technology headquarters, and government ministries sustains consistently high security spending per enterprise. Kinki (19.8%) follows, supported by Osaka's diverse industrial and retail sectors with rising demand for OT and supply chain security.
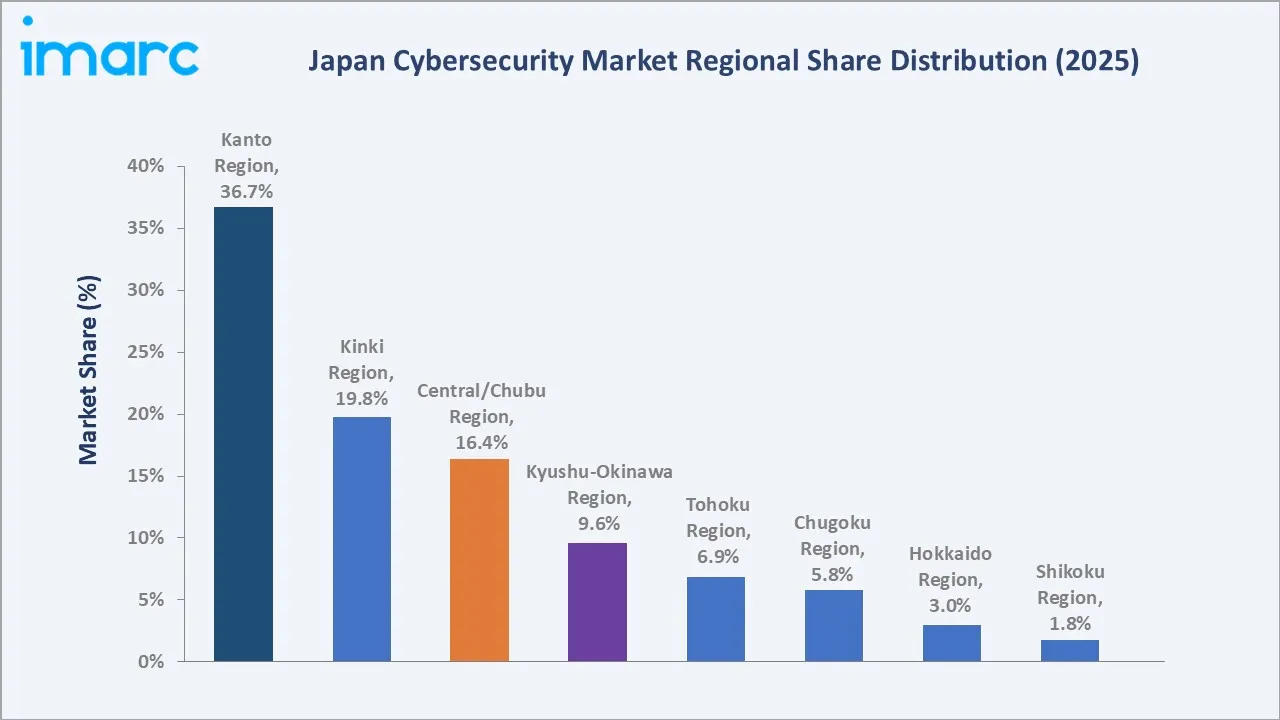
Central/Chubu (16.4%) reflects strong automotive OT security demand, anchored by the region's manufacturing concentration. Kyushu-Okinawa (9.6%) emerges as the fastest-growing region, benefiting from expanding defense-related infrastructure and SME digitization programs. Tohoku (6.9%), Chugoku (5.8%), Hokkaido (3.0%), and Shikoku (1.8%) collectively represent early-stage but expanding cybersecurity markets with long-term growth potential through 2034.
Competitive Landscape
The Japan cybersecurity market is moderately concentrated at the enterprise solutions and managed services level. The broader market, including cloud security, endpoint protection, and niche OT security providers, is more fragmented, with hundreds of domestic and international players competing across specific verticals and deployment segments.
|
Company |
Key Offerings |
Market Position |
Core Strength |
| Fujitsu | Fujitsu Managed Security Services, Network Security, Identity and Access Management, Endpoint Security | Market Leader | Fujitsu plays a leading role in Japan’s cybersecurity landscape as a top digital services provider, supporting both corporate defense and government-led active cyber defense initiatives. |
| NTT DATA Group Corporation | Risk Management and Compliance, Secure Business Enablement, Enterprise Cyber Resilience | Market Leader | NTT DATA Group Corporation provides enterprise-grade managed security services, governance consulting, and 24/7 threat monitoring for both private corporations and public institutions. |
| Trend Micro Incorporated | TrendAI, TXOne Networks, Magna, VicOne | Established Player | Trend Micro Incorporated serves as a major anchor and private-sector pillar in Japan’s cybersecurity landscape. |
| NEC Corporation | CyIOC | Innovator | NEC Corporation plays a leading role in Japan’s national cybersecurity, economic security, and critical infrastructure defense. |
| Cisco Systems, Inc. | Cisco SecureX | Challenger | Cisco Systems, Inc. plays a major role through national resilience partnerships, threat intelligence deployment, talent training, and secure networking infrastructure. |
Competition is intensifying as global cybersecurity vendors expand their Japan operations through direct investments, local partnerships, and channel programs. AI-driven product differentiation and managed service capabilities are becoming critical competitive differentiators across all market tiers through the forecast period.
Key Company Profiles
Fujitsu
Fujitsu is a leading Japanese information technology company offering a comprehensive range of cybersecurity services and solutions across enterprise and public-sector clients. The company operates a global security operations center network, leveraging AI-driven analytics to deliver proactive threat management at enterprise and national scale.
- Key Offerings: Fujitsu Managed Security Services, Network Security, Identity and Access Management, Endpoint Security.
- Strategic Focus: Strategic focus centers on AI and automation integration in security operations, expanding managed service capabilities, and deepening partnerships with government agencies and critical infrastructure operators across Japan and globally.
NTT DATA Group Corporation
NTT DATA Group Corporation is one of Japan's largest IT services providers, delivering end-to-end cybersecurity solutions through proprietary platforms and global threat intelligence networks. The company serves clients across BFSI, healthcare, manufacturing, and government verticals with a comprehensive portfolio of security operations and advisory services.
- Key Offerings: Risk Management and Compliance, Secure Business Enablement, Enterprise Cyber Resilience.
- Strategic Focus: Strategic priorities include AI-led security automation, international threat intelligence collaboration, and expanding the managed security service portfolio for mid-market and large enterprise clients across Japan.
Market Concentration Analysis
The Japan cybersecurity market exhibits moderate concentration at the enterprise solutions and managed services level, where the top domestic players collectively command a substantial portion of total market revenue. Domestic incumbents retain a competitive advantage through established enterprise relationships, government sector expertise, and deep integration with Japan's IT services ecosystem, creating meaningful entry barriers in core security segments.
The broader cybersecurity market, including cloud security, endpoint protection, and niche OT security providers, is significantly more fragmented, with hundreds of operators serving specific verticals and deployment segments. Consolidation activity, including partnerships, acquisitions, and joint ventures, is expected to intensify through the forecast period, gradually shifting market share toward players with comprehensive AI-integrated and cloud-native security portfolios.
Investment Growth Opportunities
Highest Growth Segments
Cloud-based security at 58.7% represents the largest and fastest-growing deployment segment, sustained by accelerating enterprise cloud migration and demand for scalable subscription security architectures that provide policy-backed demand continuity through the forecast period. The cloud security sub-segment is projected to grow at a CAGR of approximately 12.4% through 2034, significantly outpacing the overall market average of 9.5%.
Investment Themes
- Government-Backed Security Infrastructure: Japan's planned active cyber defense framework and national security infrastructure investments are expected to drive public-sector procurement, creating significant opportunities for vendors with established government relationships and cleared personnel across defense and critical infrastructure verticals.
- AI-Driven and OT Cybersecurity Ventures: AI and ML security tools, automotive cybersecurity, and OT protection are primary investment themes in Japan's first cybersecurity-focused investments. Cross-border AI collaboration programs further amplify the investment thesis for AI-native security platforms targeting Japan's enterprise market.
Future Market Outlook (2026-2034)
The Japan cybersecurity market grew from USD 19.85 Billion in 2025 to USD 22.27 Billion in 2026, reaching USD 46.00 Billion by 2034, exhibiting a CAGR of 9.5% during 2026-2034. The market reflects a fundamental shift from reactive to proactive security postures, with AI-powered threat detection, zero-trust implementation, and quantum-safe cryptography defining the technology agenda. Managed security services are forecast to emerge as the market's largest revenue contributor by 2034 as enterprises increasingly outsource security operations.
Three structural forces will define Japan's cybersecurity market through 2034. First, sustained government cybersecurity investment will provide a policy-backed demand floor that insulates the market from cyclical spending pressures. Second, accelerating enterprise digital transformation across manufacturing, healthcare, and financial services will sustain strong demand for specialized OT, cloud, and application security solutions, creating durable multi-year revenue streams for vendors with cross-sector capabilities. Third, geopolitical tensions and the rise of state-sponsored cyber warfare will compel both public and private sector organizations to continuously upgrade security capabilities, driving above-average growth in threat intelligence and incident response services.
Research Methodology
Primary Research
Primary research comprised structured consultations with cybersecurity executives, IT directors, government officials, and industry experts across Japan. Engagements provided first-hand insights into market dynamics, technology adoption trends, procurement cycles, and competitive positioning across enterprise, government, and SME security segments.
Secondary Research
Secondary research drew on published government data, including Japan's METI and NISC publications, Union Budget allocations, regulatory filings, company annual reports, and third-party market databases. Global cybersecurity benchmarks and cross-border threat intelligence reports supplemented Japan-specific primary findings.
Forecasting Models
Market forecasts were developed using bottom-up and top-down modeling approaches incorporating historical sector growth rates, regulatory adoption curves, and enterprise security budget allocation trends. CAGR projections are benchmarked against macroeconomic indicators and technology adoption curve analysis validated through triangulation with primary research findings.
Japan Cybersecurity Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered |
|
| Deployment Types Covered | Cloud-based, On-premises |
| User Types Covered | Large Enterprises, Small and Medium Enterprises |
| Industry Verticals Covered | IT and Telecom, Retail, BFSI, Healthcare, Defense/Government, Manufacturing, Energy, Others |
| Regions Covered | Kanto Region, Kinki Region, Central/Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Fujitsu, NTT DATA Group Corporation, Trend Micro Incorporated, NEC Corporation, Cisco Systems, Inc.,etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan cybersecurity market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the Japan cybersecurity market.
- Porter's Five Forces analysis assists stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan cybersecurity industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Cybersecurity Market Report
The Japan cybersecurity market reached USD 22.27 Billion in 2026, driven by state-sponsored threat escalation, cloud adoption, and regulatory compliance requirements across enterprises.
The market is projected to grow at a CAGR of 9.5% during 2026-2034, supported by sustained AI-driven security investments, cloud migration, and government cybersecurity mandates.
The market is projected to reach approximately USD 31.24 Billion by 2030, driven by peak AI security deployments, zero-trust architecture adoption, and expanding SME managed service adoption.
Cloud-based deployment leads with a 58.7% revenue share in 2025, reflecting enterprise preference for scalable subscription security architectures and hybrid cloud environment expansion.
Large enterprises accounted for 63.5% of Japan's cybersecurity market by user type in 2025, driven by complex IT environments and regulatory compliance mandates across BFSI and healthcare.
The Kanto region holds the largest share at 36.7% in 2025, anchored by Tokyo's concentration of financial institutions, government agencies, and technology enterprise headquarters.
Key players include Fujitsu, NTT DATA Group Corporation, Trend Micro Incorporated, NEC Corporation, and Cisco Systems, Inc., among others.
The Japan cybersecurity market is projected to reach USD 46.00 Billion by 2034, driven by sustained infrastructure investment, residential AI security, and government active cyber defense programs.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade