
Japan Flame Retardants Market Size, Share, Trends and Forecast by Type, Application, End Use Industry, and Region, 2026-2034
Japan Flame Retardants Market Size, Share, Trends & Forecast (2026-2034)
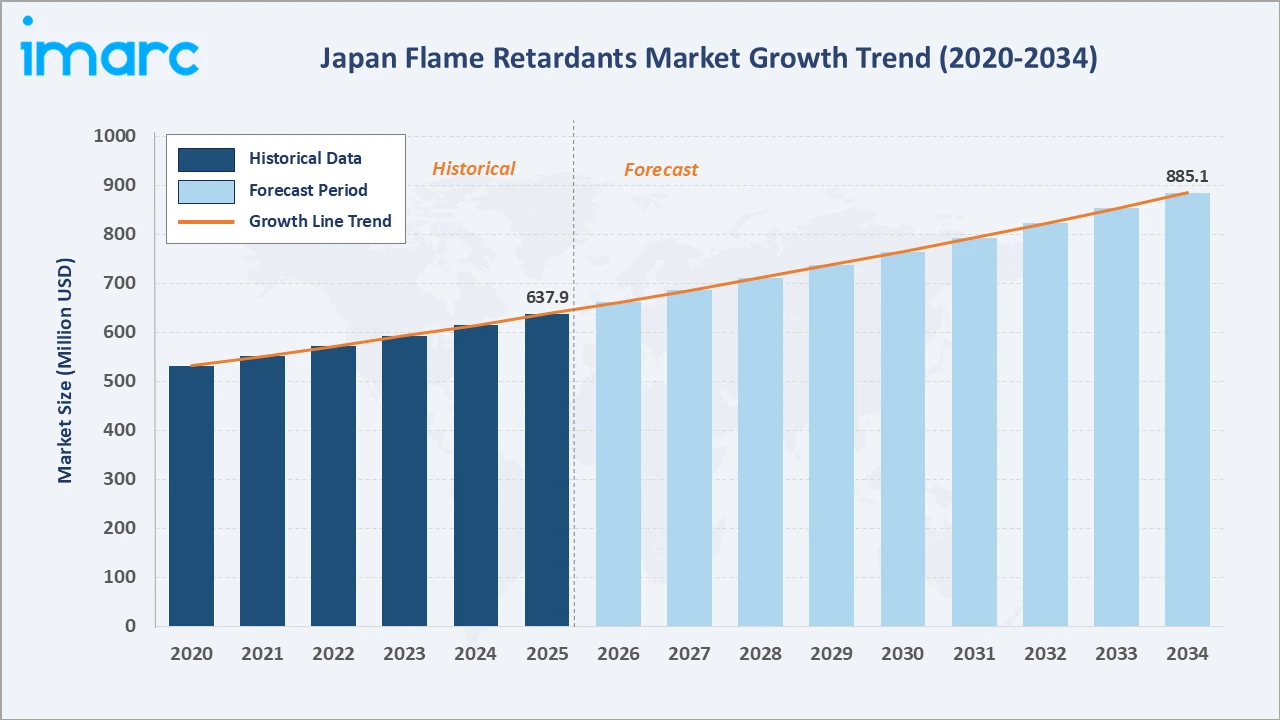
The Japan flame retardants market grew from USD 637.9 Million in 2025 to USD 661.6 Million in 2026 and is projected to reach USD 885.1 Million by 2034, exhibiting a CAGR of 3.71% during 2026-2034. Stringent fire safety regulations, rising demand from automotive and electronics sectors, and the ongoing shift toward halogen-free formulations are the primary forces shaping market growth.
Alumina trihydrate leads the type segment at 30.0%, polyolefins dominate the application segment at 25.0%, and Kanto Region commands 32.0% of regional share.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 637.9 Million |
| Market Size (2026) | USD 661.6 Million |
| Forecast Market Size (2034) | USD 885.1 Million |
| CAGR (2026-2034) | 3.71% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | Kanto Region (32.0%, 2025) |
| Second Largest Region | Kansai/Kinki Region (20.0%, 2025) |
| Leading Type | Alumina Trihydrate (30.0%, 2025) |
| Leading Application | Polyolefins (25.0%, 2025) |
The Japan flame retardants market size increased from USD 531.8 Million in 2020 to USD 637.9 Million in 2025 and is estimated to reach USD 661.6 Million in 2026. The market is further expected to grow to USD 765.2 Million by 2030 and USD 885.1 Million by 2034. The industry is commercially mature yet evolving, underpinned by one of Asia's most rigorous building and fire safety codes, a technology-intensive manufacturing base, and an accelerating transition toward environmentally compliant, halogen-free formulations.
To get more information on this market, Request Sample
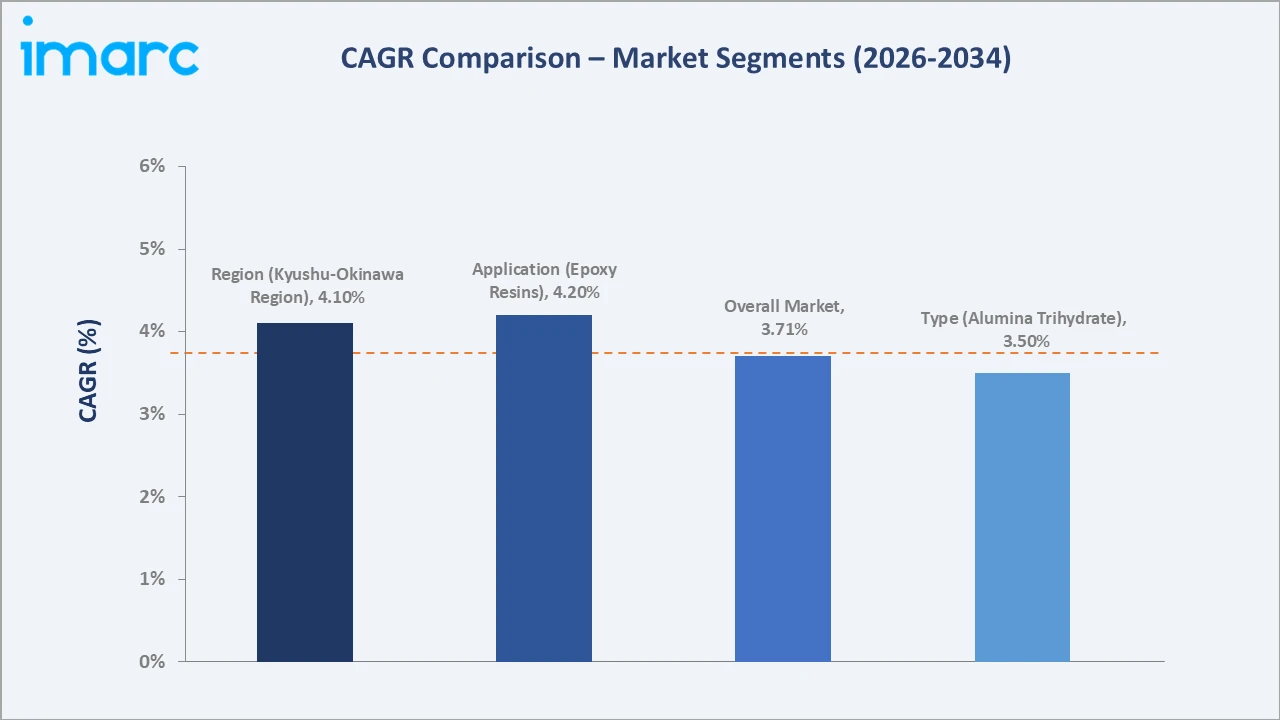
CAGR trajectories across type, application, and regional sub-segments show phosphorus flame retardants and Kyushu-Okinawa Region expanding faster than the overall 3.71% market CAGR, driven by regulatory transition toward halogen-free formulations, growing electronics and automotive activity, and expanding industrial manufacturing activities.
Executive Summary
The Japan flame retardants market expanded from USD 637.9 Million in 2025 to an estimated USD 661.6 Million in 2026, positioning it among Asia's most established flame retardants markets. The market is supported by rising electronics and automotive production and increasing replacement of halogenated compounds with phosphorus-based alternatives.
Alumina trihydrate commands 30.0% type share, reflecting its cost-efficiency, non-halogenated profile, and compatibility with polyolefins and rubber. Polyolefins prevail over the application segment with 25.0% share, fueled by their widespread use in electrical insulation, automotive components, and consumer goods. Kanto Region leads regional share at 32.0%, anchored by its dense industrial and electronics manufacturing cluster.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Type | Alumina Trihydrate – 30.0% share (2025) |
| Second Largest Type | Brominated Flame Retardants – 25.0% share (2025) |
| Leading Application | Polyolefins – 25.0% share (2025) |
| Second Largest Application | PVC – 22.0% share (2025) |
| Leading Region | Kanto Region – 32.0% share (2025) |
| Second Largest Region | Kansai/Kinki Region – 20.0% share (2025) |
| Top Companies | Tosoh Corporation, Nihon Seiko Co., Ltd., Albemarle Corporation, Lanxess AG |
Key Analytical Observations Expanding On the Data Above:
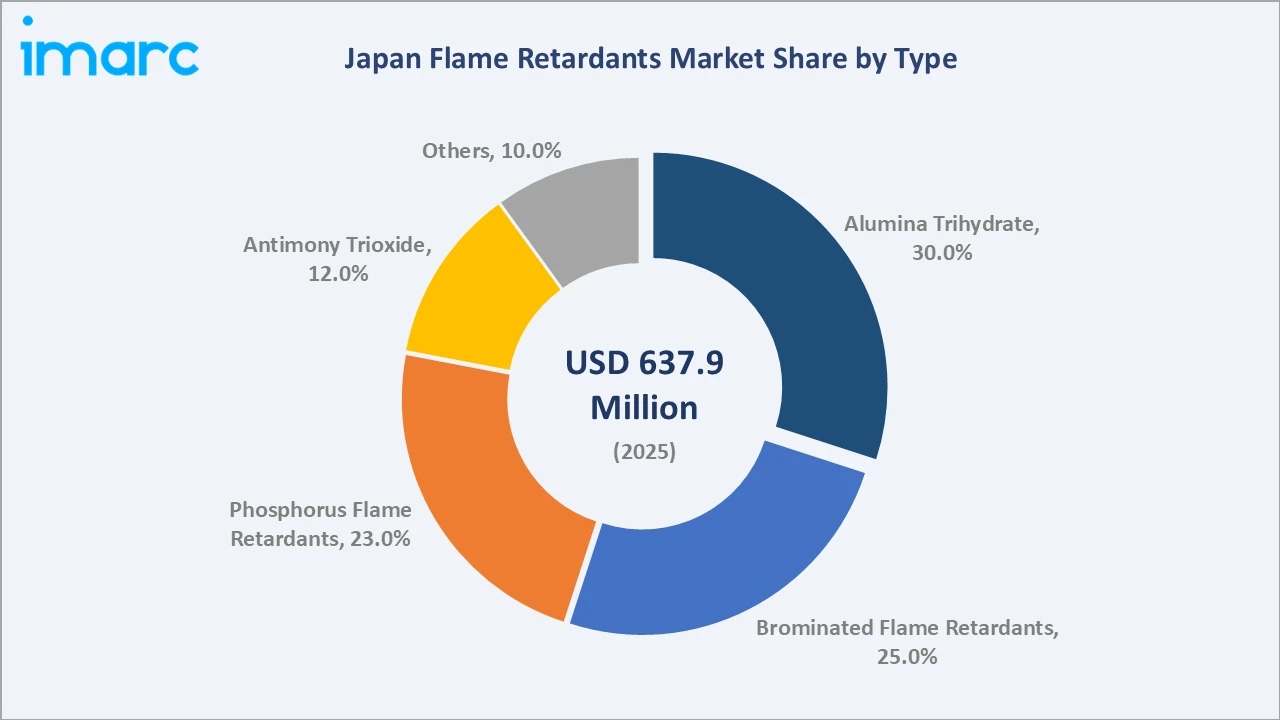
- Alumina trihydrate leadership at 30.0% reflects its wide polymer compatibility, non-toxicity, and competitive cost, making it the preferred flame retardant across construction, cable, and industrial rubber applications in Japan.
- Brominated flame retardants at 25.0% remain significant due to their high efficacy at low loading levels, particularly in electronics and automotive components, despite ongoing regulatory scrutiny in some end-use segments.
- Polyolefins leadership at 25.0% is driven by Japan's large polyethylene and polypropylene processing industry, where flame retardants are mandatory for electrical, automotive, and construction material applications.
- PVC at 22.0% benefits from Japan's robust cable, flooring, and construction product sector, where PVC compounds require flame retardant additives to meet building and electrical safety standards.
- Kanto Region leadership at 32.0% is anchored by the region's concentration of electronics manufacturers, automotive suppliers, and chemical processors that collectively drive Japan's highest per-region demand for flame retardants.
Japan Flame Retardants Market Overview
Flame retardants are chemical compounds incorporated into polymers, textiles, and coatings to inhibit or delay ignition and slow the spread of fire. Key chemistries include alumina trihydrate, brominated and phosphorus compounds, antimony trioxide, and halogen-free alternatives.
The Japan flame retardants ecosystem integrates raw material suppliers, specialty chemical manufacturers, compounders, distributors, and end-use processors across construction, electronics, automotive, and cable industries. Government regulatory bodies, testing laboratories, and industry associations form the supporting framework, reinforcing the high compliance standards that define the market's competitive and commercial structure.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
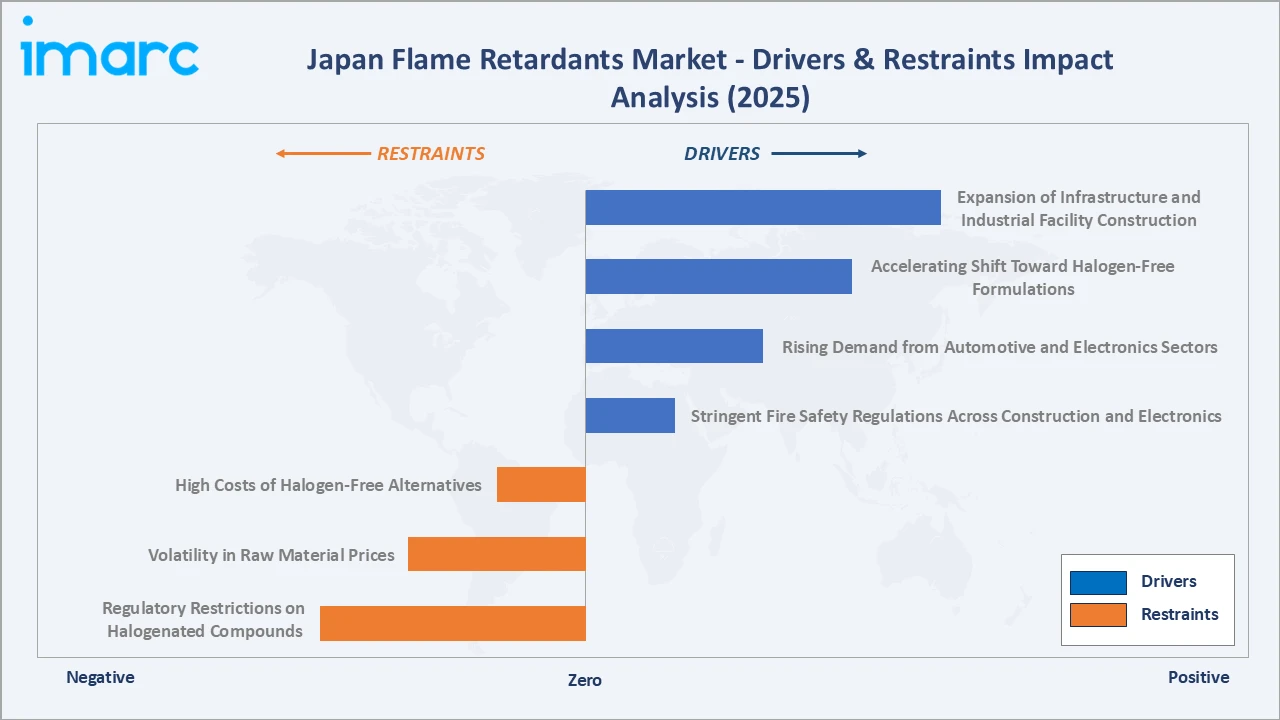
- Stringent Fire Safety Regulations Across Construction and Electronics: Japan's strict fire safety requirements for buildings, electrical equipment, and electronic components are encouraging manufacturers to incorporate flame retardants into materials to improve fire resistance and comply with applicable safety standards.
- Rising Demand from Automotive and Electronics Sectors: Japan's automotive and electronics sectors are among the world's largest, generating sustained demand for flame retardant polymers in under-hood components, cable harnesses, and consumer electronics enclosures, where fire safety standards are strictly enforced.
- Accelerating Shift Toward Halogen-Free Formulations: Growing environmental and regulatory pressure to phase out brominated flame retardants is driving adoption of phosphorus-based and inorganic alternatives, particularly in electronics and construction applications, supporting premium-priced halogen-free product growth.
- Expansion of Infrastructure and Industrial Facility Construction: Japan's ongoing investment in transportation infrastructure, data centers, and industrial facilities is driving incremental demand for flame retardant coatings, cables, and structural materials, broadening the end-use base beyond traditional consumer electronics and automotive. As per IMARC Group, the Japan data center market is projected to reach 2.18 GW by 2034, growing at a CAGR of 4.74% during 2026-2034.
Market Restraints
- Regulatory Restrictions on Halogenated Compounds: Increasing regulatory scrutiny and voluntary phase-out commitments for certain brominated flame retardants are constraining demand for established halogenated product lines, requiring manufacturers to invest in reformulation and compliance documentation.
- Volatility in Raw Material Prices: Fluctuations in prices for bromine, phosphorus intermediates, and aluminum hydroxide introduce margin pressure for flame retardant producers, complicating pricing strategy and long-term supply contracts with downstream polymer processors.
- High Costs of Halogen-Free Alternatives: Halogen-free flame retardants often involve higher formulation and processing costs than conventional alternatives, creating price pressures for manufacturers and limiting adoption among cost-sensitive end-use industries.
Market Opportunities
- Development of Next-Generation Halogen-Free Flame Retardants: The transition away from halogenated compounds presents significant commercial opportunity for producers able to deliver high-performance phosphorus and inorganic flame retardants that meet the efficacy standards of incumbent brominated systems at competitive cost.
- Growth in EV and Advanced Automotive Applications: Japan's accelerating EV production is generating new demand for flame retardant battery components, charging infrastructure, and lightweight polymer systems, creating application-specific product development opportunities for specialty flame retardant suppliers.
Market Challenges
- Cost of Reformulation and Regulatory Compliance: Transitioning product lines to halogen-free formulations requires significant R&D investment, testing, and certification, creating a cost and time burden that may slow adoption among smaller compounders and downstream processors.
- Performance Trade-Offs in Halogen-Free Alternatives: Achieving equivalent fire performance to brominated systems with halogen-free alternatives at comparable polymer loadings remains a technical challenge, limiting substitution rates in high-specification applications such as aerospace and advanced electronics.
Emerging Market Trends
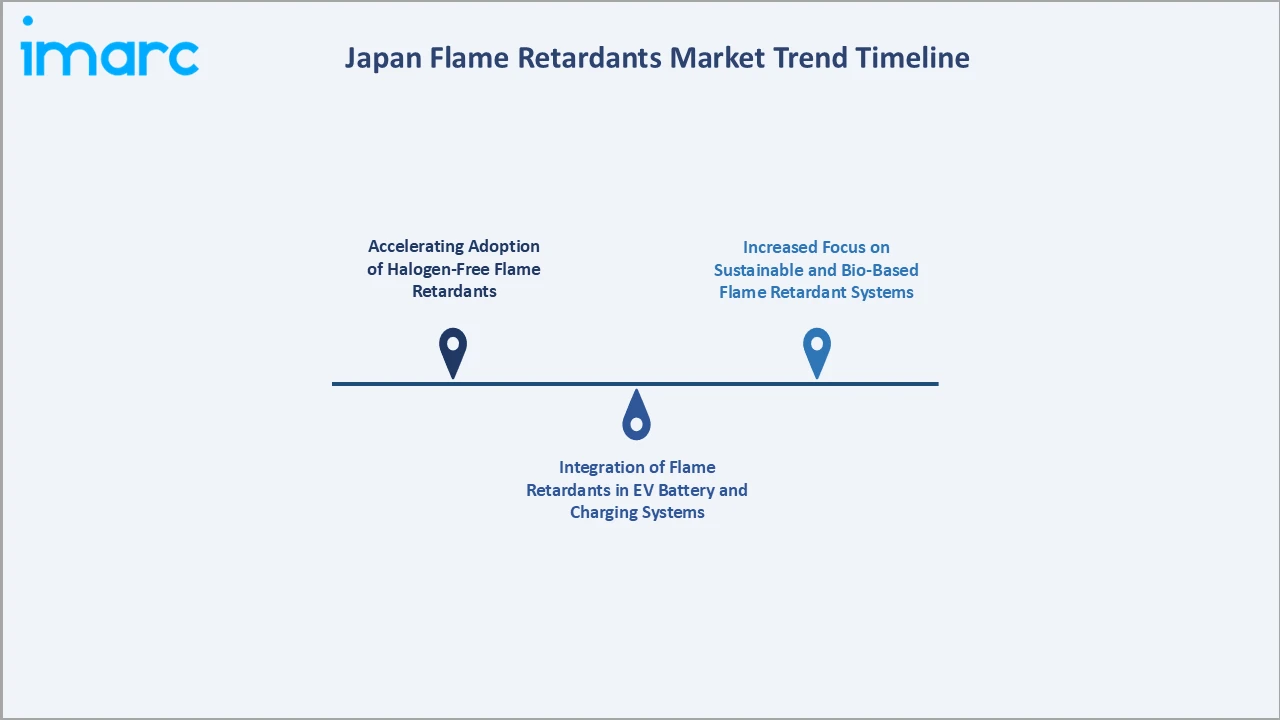
1. Accelerating Adoption of Halogen-Free Flame Retardants
Regulatory momentum and OEM procurement standards are driving rapid substitution of brominated flame retardants with phosphorus-based and inorganic alternatives. Japan's leading electronics manufacturers and automotive OEMs have set internal targets for eliminating halogenated flame retardants from new product platforms, catalyzing formulation changes across their polymer supply chains.
2. Integration of Flame Retardants in EV Battery and Charging Systems
EV adoption in Japan is creating new flame retardant application segments, including battery cell separators, module housings, and charging infrastructure components. These applications require high-performance, non-halogenated flame retardant systems that meet both fire safety and lightweight requirements.
3. Increased Focus on Sustainable and Bio-Based Flame Retardant Systems
Research into bio-based and recyclable flame retardant systems is gaining commercial relevance in Japan, driven by corporate sustainability goals and circular economy commitments among major chemical and polymer processors. Bio-derived phosphorus compounds and natural mineral fillers are being evaluated as lower-impact alternatives in select polymer processing applications.
Industry Value Chain Analysis
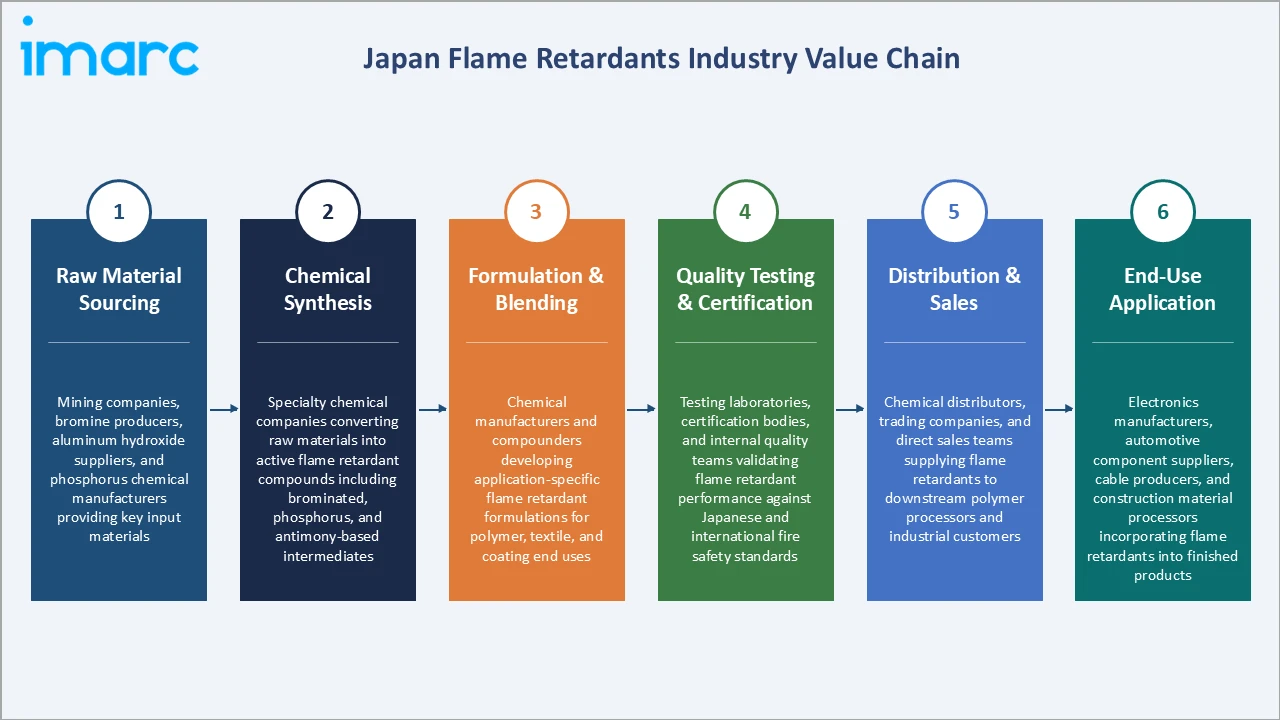
The Japan flame retardants value chain spans six stages, from raw material sourcing through end-use application. Chemical synthesis and formulation stages capture the highest value-add, while quality certification and distribution are increasingly competitive differentiators in a market characterized by stringent compliance requirements.
| Stage | Key Players / Examples |
|---|---|
| Raw Material Sourcing | Mining companies, bromine producers, aluminum hydroxide suppliers, and phosphorus chemical manufacturers providing key input materials |
| Chemical Synthesis | Specialty chemical companies converting raw materials into active flame retardant compounds including brominated, phosphorus, and antimony-based intermediates |
| Formulation & Blending | Chemical manufacturers and compounders developing application-specific flame retardant formulations for polymer, textile, and coating end uses |
| Quality Testing & Certification | Testing laboratories, certification bodies, and internal quality teams validating flame retardant performance against Japanese and international fire safety standards |
| Distribution & Sales | Chemical distributors, trading companies, and direct sales teams supplying flame retardants to downstream polymer processors and industrial customers |
| End-Use Application | Electronics manufacturers, automotive component suppliers, cable producers, and construction material processors incorporating flame retardants into finished products |
Vertically integrated producers controlling chemical synthesis and formulation stages capture the greatest margin across the value chain. Distributors and traders play an important role in serving Japan's fragmented downstream compounding sector, ensuring product availability and technical support across diverse application segments.
Technology Landscape in the Japan Flame Retardants Industry
Inorganic Flame Retardant Technologies
Alumina trihydrate and magnesium hydroxide dominate the inorganic segment, valued for their non-toxicity, smoke suppression, and regulatory acceptance. Processing advances are improving surface treatment and particle size control, enhancing polymer compatibility at high loading levels.
Brominated Compound Technology
Brominated flame retardants deliver high efficacy at low loadings, preserving polymer mechanical properties. Encapsulation technology and reactive brominated monomers are reducing leaching risk and extending product life in electronics and automotive applications.
Automation and Smart Formulation Systems
Japan's leading flame retardant manufacturers are investing in automated dosing, inline quality monitoring, and AI-assisted formulation systems. These capabilities reduce development cycles, improve batch consistency, and enable rapid customization for application-specific polymer processing requirements across the electronics and automotive supply chain.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Type | Alumina Trihydrate | 30.0% | 2025 |
| Application | Polyolefins | 25.0% | 2025 |
| End-Use Industry | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 32.0% | 2025 |

By Type
Alumina trihydrate commands a 30.0% majority share in 2025, driven by its cost-effectiveness, broad polymer compatibility, and non-halogenated profile that aligns with regulatory trends favoring environmentally compliant flame retardants. It is widely used in polyolefins, PVC cables, and rubber compounds across construction and industrial applications.
To access detailed market analysis, Request Sample
Brominated flame retardants at 25.0% remain essential for high-performance electronics and automotive applications, where their efficacy at low loadings preserves critical polymer properties.
By Application
Polyolefins represent 25.0% of the application segment in 2025, reflecting Japan's large polyethylene and polypropylene processing industry. Flame retardants are mandatory in cable and wire jacketing, automotive interior components, and construction film applications, sustaining strong baseline demand across Japan's polyolefins processing sector.
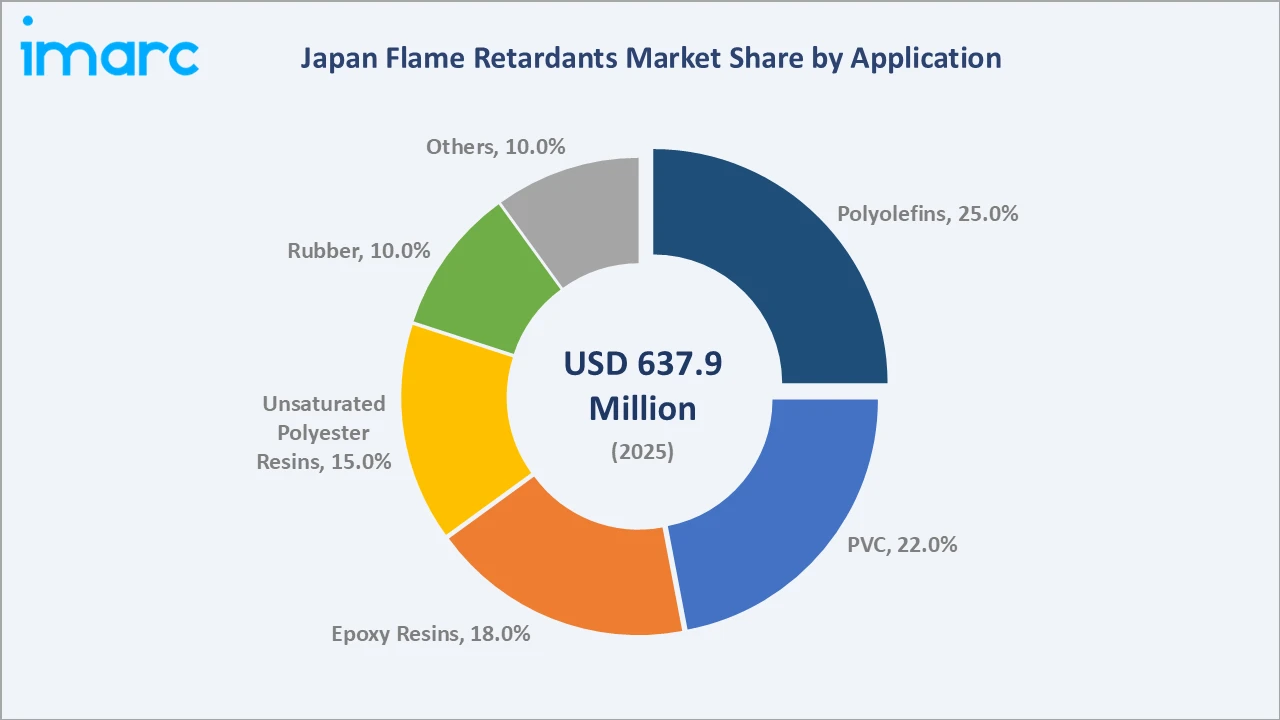
PVC at 22.0% is the second-largest application, sustained by Japan's cable, flooring, and construction product industries.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| Kanto Region | 32.0% | Large electronics and automotive manufacturing base, high industrial concentration, robust construction activity, and strong demand from cable and wire processing industries |
| Kansai/Kinki Region | 20.0% | Established chemical manufacturing corridor, strong industrial processing sector, growing electronics component production, and well-developed distribution infrastructure |
| Central/Chubu Region | 17.0% | Dense automotive manufacturing cluster, growing electronics and machinery production, expanding industrial facilities investment, and strong polymer processing activity |
| Kyushu-Okinawa Region | 10.0% | Expanding semiconductor and electronics manufacturing presence, growing automotive assembly activity, industrial park development, and increasing construction sector demand |
| Tohoku Region | 7.0% | Post-earthquake reconstruction projects, growing industrial facility investment, expanding food processing and electronics manufacturing, and increasing infrastructure development |
| Chugoku Region | 6.0% | Industrial manufacturing base in Hiroshima and Yamaguchi, petrochemical processing activity, automotive component production, and steady construction sector demand |
| Hokkaido Region | 5.0% | Construction activity driven by infrastructure projects, growing food processing industry, renewable energy facility development, and steady industrial polymer processing demand |
| Shikoku Region | 3.0% | Chemical production in Tokushima and Ehime, industrial processing activity, construction material manufacturing, and moderate electronics assembly operations |
Kanto Region at 32.0% in 2025 leads the regional landscape, anchored by Tokyo's extensive electronics and manufacturing cluster and the surrounding prefectures' automotive and cable processing industries. The region hosts high concentration of flame retardant consumers across all major end-use sectors.
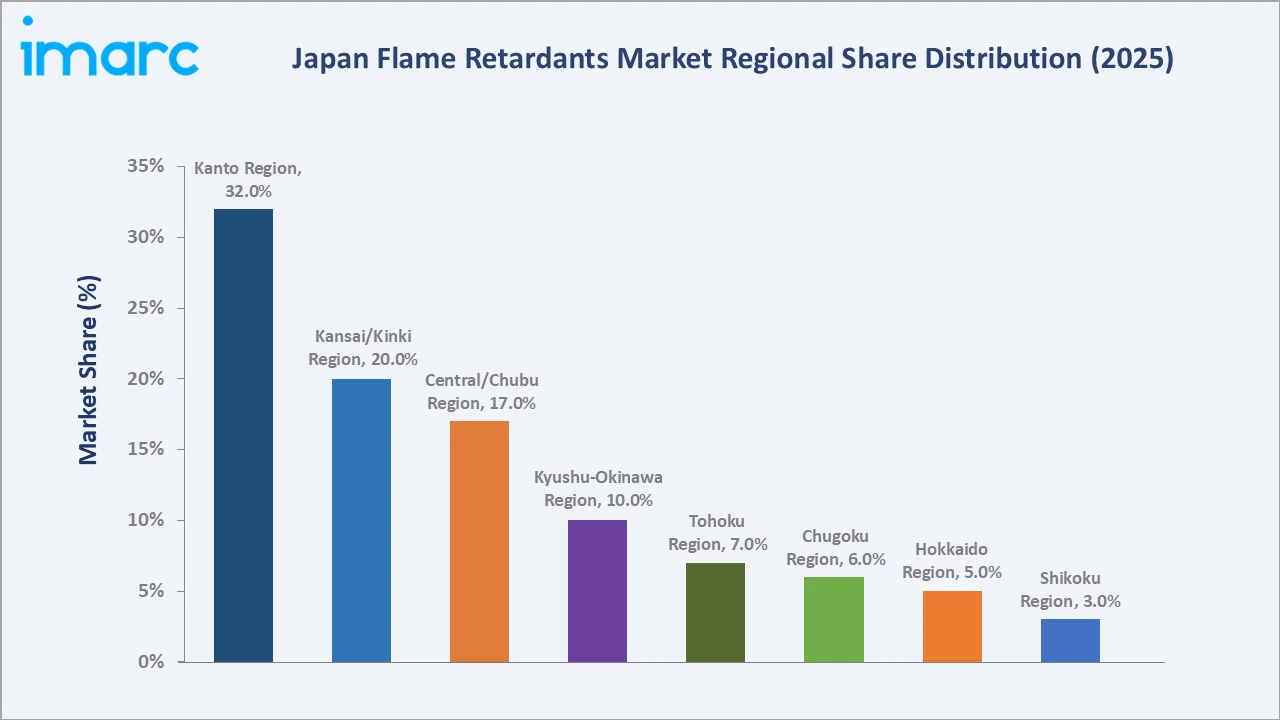
Kyushu-Okinawa Region, while currently at 10.0%, is the fastest-growing regional market, supported by expanding semiconductor fabrication, automotive assembly operations, and continued government-backed industrial park development in Fukuoka and Kumamoto.
Competitive Landscape
The Japan flame retardants market is moderately consolidated, with a mix of large domestic chemical companies and global specialty chemical groups competing on product performance, regulatory compliance credentials, technical service, and supply reliability. Scale, formulation expertise, and proximity to key end-use customers form the primary competitive differentiators in this technically demanding market.
| Company Name | Brand / Key Product | Position | Strategic Focus |
|---|---|---|---|
| Tosoh Corporation | FLAMECUT® | Leader | Expanding production capacity for brominated and halogen-based flame retardant lines through continuous R&D investment and strategic customer partnerships in Japan |
| Nihon Seiko Co., Ltd. | Antimony Trioxide / Sodium Antimonate | Leader | Strengthening domestic antimony trioxide and sodium antimonate production to serve Japan's flame retardant industry as a core inorganic synergist supplier |
| Albemarle Corporation | Saytex | Challenger | Advancing brominated flame retardant portfolio diversification and growing Japan market penetration through application-specific formulation development |
| Lanxess AG | Levagard | Challenger | Developing high-performance phosphorus-based flame retardant solutions for engineering plastics and electronics while expanding Asia-Pacific distribution |
Key players include Tosoh Corporation, Nihon Seiko Co., Ltd., Albemarle Corporation, and Lanxess AG, among others.
Key Company Profiles
Tosoh Corporation
Tosoh Corporation is a Japanese integrated chemical company headquartered in Tokyo, Japan. It is one of Japan's largest producers of chlorine-alkali chemicals, specialty chemicals, and polymer materials, with brominated flame retardant products marketed under the FLAMECUT® brand forming part of its specialty chemicals portfolio.
- Product Portfolio: FLAMECUT® brominated flame retardants for engineering plastics, electronics, and industrial polymer applications.
- Recent Developments: The company continues to invest in expanding its specialty chemicals product range and strengthening its production infrastructure to support growing domestic and regional demand for performance chemical solutions, including brominated and halogen-based flame retardant formulations.
- Strategic Focus: Strengthening production capacity for FLAMECUT® brominated flame retardants and broadening the specialty chemicals portfolio through R&D investment in high-performance polymer additive formulations.
Nihon Seiko Co., Ltd.
Nihon Seiko Co., Ltd. is a Japanese specialty chemicals manufacturer listed on the Tokyo Stock Exchange, headquartered in Japan. The company is one of Japan's primary domestic producers of antimony trioxide and related antimony compounds, which are widely used as inorganic synergists in halogenated flame retardant systems across electronics, cable, and engineering plastic applications.
- Product Portfolio: Antimony trioxide (flame retardant synergist for halogen-based systems) and sodium antimonate (flame retardant for engineering plastic resins), along with metal powder products through its subsidiary.
- Recent Developments: The company continues to advance product quality and capacity optimization across its antimony trioxide and sodium antimonate lines to meet evolving technical requirements from the electronics and polymer processing sectors.
- Strategic Focus: Maintaining domestic leadership in antimony trioxide and sodium antimonate supply for the Japan flame retardants industry while expanding into electronic materials and battery-related specialty chemical applications.
Albemarle Corporation
Albemarle Corporation is a United States-based specialty chemicals company headquartered in Charlotte, North Carolina. It is a global leader in brominated flame retardants and maintains a significant commercial presence in Japan's electronics and polymer markets.
- Product Portfolio: Saytex brand brominated flame retardants including specialty brominated compounds for electronics, textiles, and polymer applications.
- Recent Developments: The company continues to develop next-generation brominated and halogen-free flame retardant solutions in response to regulatory trends and OEM demand for sustainable fire protection options.
- Strategic Focus: Growing application-specific flame retardant solutions for Japan's electronics and automotive sectors while developing halogen-free alternatives for regulatory-sensitive end markets.
Market Concentration Analysis
The Japan flame retardants market exhibits moderate concentration, with the top tier of operators comprising domestic chemical majors and global specialty chemical groups holding a combined significant share of addressable volume.
Barriers to entry include capital requirements for certified chemical production, the technical complexity of flame retardant formulation, proximity to key end-use customers, and compliance with Japan's rigorous chemical safety regulatory framework. These factors favor established producers over greenfield entrants and sustain moderate pricing discipline in the market.
Consolidation activity has been limited, but cross-border strategic partnerships and licensing agreements are emerging as a route for smaller domestic formulators to gain access to next-generation halogen-free technologies developed by global specialty chemical groups.
Investment & Growth Opportunities
Fastest-Growing Segments
Phosphorus flame retardants are expanding fastest among type sub-segments, driven by regulatory transition and OEM demand for halogen-free formulations. Phosphorus-based formulations are gaining traction as manufacturers seek effective flame resistance with reduced reliance on halogenated compounds.
Emerging Markets
Kyushu-Okinawa Region is the fastest-growing regional market, supported by major semiconductor fabrication investments and expanding automotive assembly, both generating new demand for high-performance flame retardant polymer systems. The region represents a significant opportunity for flame retardant suppliers with application expertise in advanced electronics and automotive components.
Venture & Investment Trends
Investment is flowing into halogen-free flame retardant R&D, particularly reactive phosphorus systems and intumescent formulations for construction applications. EV battery fire protection and advanced cable systems are attracting focused product development investment from both domestic and international specialty chemical companies serving Japan's market.
Future Market Outlook (2026-2034)
The Japan flame retardants market is projected to grow from USD 661.6 Million in 2026 to USD 885.1 Million by 2034, registering a CAGR of 3.71% during 2026-2034.
Four forces will shape the market through 2034 the ongoing regulatory transition to halogen-free formulations; growing EV and advanced electronics demand for high-performance fire protection; continued infrastructure and construction investment sustaining inorganic flame retardant demand; and innovation in reactive phosphorus and intumescent systems driving premium-segment growth.
By 2034, the Japan flame retardants market is expected to be characterized by a mix of established inorganic and brominated compound demand in traditional applications and rapidly growing phosphorus-based and halogen-free systems in electronics, EV, and next-generation construction materials, with technology differentiation playing an increasing role in supplier competitive positioning.
Research Methodology
Primary Research
Primary research included structured interviews with flame retardant producers, polymer compounders, end-use industry procurement teams, and regulatory affairs specialists, validating market sizing, segment mix, and regional demand patterns across Japan's flame retardants value chain.
Secondary Research
Secondary sources included Ministry of Economy, Trade and Industry (METI) chemical industry statistics, Fire and Disaster Management Agency regulatory publications, Japan Chemical Industry Association data, and public disclosures from listed chemical manufacturers and polymer processors operating in Japan.
Forecasting Models
Market forecasts were developed using top-down and bottom-up modeling combining Japan chemical industry production and trade data, end-use sector growth projections, flame retardant adoption rate assumptions, and regulatory transition scenario analysis across type and application segments.
Japan Flame Retardants Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Alumina Trihydrate, Brominated Flame Retardants, Antimony Trioxide, Phosphorus Flame Retardants, Others |
| Applications Covered | Unsaturated Polyester Resins, Epoxy Resins, PVC, Rubber, Polyolefins, Others |
| End Use Industries Covered | Construction, Wires and Cables, Automotive and Transportation, Electrical and Electronics, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Tosoh Corporation, Nihon Seiko Co., Ltd., Albemarle Corporation, Lanxess AG, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan flame retardants Market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan flame retardants Market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan flame retardants Market industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Flame Retardants Market Report
The Japan flame retardants market size is estimated at USD 661.6 Million in 2026, driven by fire safety regulations, electronics and automotive demand, and growing adoption of halogen-free flame retardant formulations.
The market is projected to grow at a CAGR of 3.71% from 2026-2034, reaching USD 885.1 Million by 2034, supported by regulatory compliance demand and expansion of end-use industries.
Alumina trihydrate dominates the market with 30.0% type share in 2025, driven by its non-halogenated profile, cost-effectiveness, and broad compatibility with polyolefins, PVC, and rubber compounds.
Polyolefins represent 25.0% of the application segment in 2025, driven by Japan's large polyethylene and polypropylene processing industry and mandatory flame retardant requirements in cable, automotive, and construction applications.
Kanto Region commands 32.0% share in 2025, anchored by the large concentration of electronics, automotive, and cable manufacturing industries.
Kyushu-Okinawa Region is the fastest-growing region, supported by expanding semiconductor fabrication investments, automotive assembly growth, and increasing industrial park development in Kumamoto and Fukuoka prefectures.
Key players include Tosoh Corporation, Nihon Seiko Co., Ltd., Albemarle Corporation, and Lanxess AG, among others.
Key drivers include stringent fire safety regulations, rising electronics and automotive production, the regulatory transition to halogen-free formulations, and expanding infrastructure construction activity across Japan.
Key trends include the shift to halogen-free formulations, growing EV battery fire protection demand, intumescent coating adoption in construction, and increasing sustainability focus in chemical procurement across Japan.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade