
Japan Smart Meters Market Size, Share, Trends and Forecast by Product, Technology, AMR, End Use, and Region, 2026-2034
Japan Smart Meters Market Size, Share, Trends & Forecast (2026-2034)
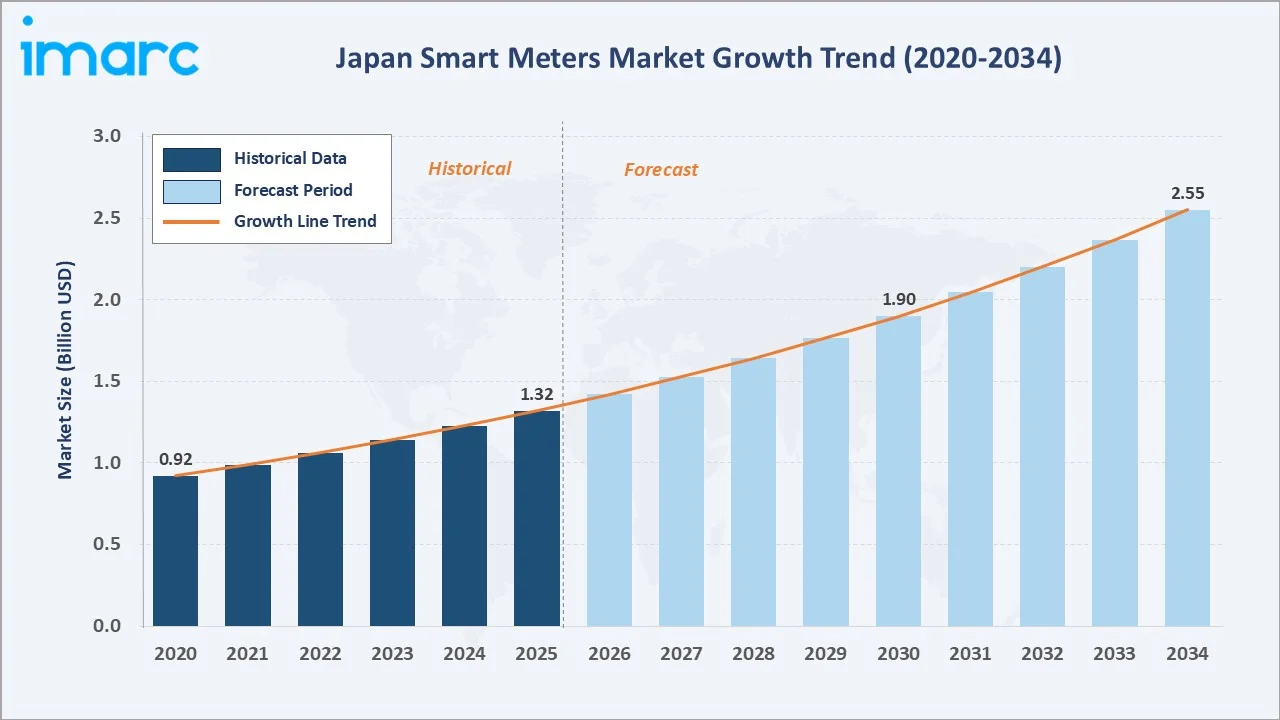
The Japan smart meters market reached USD 1.32 Billion in 2025 and is projected to reach USD 2.55 Billion by 2034, growing at a CAGR of 7.57% during 2026-2034. The market is driven by the METI-mandated nationwide rollout, the next-generation meter replacement cycle, renewable energy integration, and utility migration to advanced metering platforms. Smart electricity meters dominate at 64.3%, AMI leads technology at 81.6%, and the Kanto Region commands 34.8%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 1.32 Billion |
|
Forecast Market Size (2034) |
USD 2.55 Billion |
|
CAGR (2026-2034) |
7.57% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Smart Electricity Meter (64.3%, 2025) |
|
Dominant Technology |
AMI (Advanced Metering Infrastructure) (81.6%, 2025) |
|
Leading Region |
Kanto Region (34.8%, 2025) |
The market expanded from USD 0.92 Billion in 2020 to USD 1.32 Billion in 2025, anchored at USD 1.90 Billion in 2030 and forecast to reach USD 2.55 Billion by 2034.
To get more information on this market, Request Sample
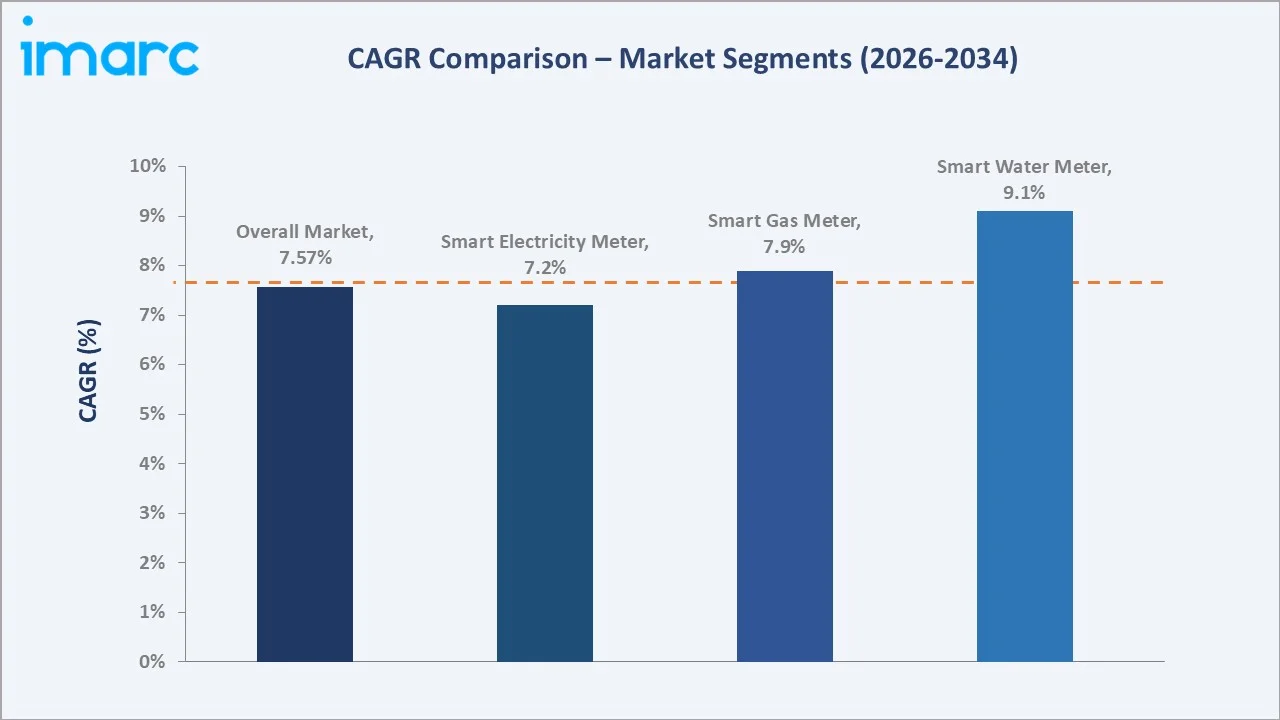
Smart water meters grow fastest at ~9.1% CAGR as municipal waterworks replace manual reading amid severe workforce shortages. AMI expands at ~8.1% CAGR as utilities upgrade to next-generation specifications supporting one-minute data granularity and multi-protocol communication.
Executive Summary
The Japan smart meters market reached USD 1.32 Billion in 2025, representing Asia-Pacific's most mature national metering ecosystem following near-complete low-voltage electricity meter penetration. The market is projected to reach USD 2.55 Billion by 2034.
Smart electricity meters at 64.3% dominate through an installed base of roughly 78 million low-voltage units. AMI at 81.6% leads as utilities standardise on Wi-SUN mesh networks. The Kanto Region at 34.8% leads through Tokyo metropolitan household density.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Smart Electricity Meter - 64.3% share (2025) |
|
Dominant Technology |
AMI (Advanced Metering Infrastructure) - 81.6% market share (2025) |
|
Leading Region |
Kanto Region - 34.8% market share (2025) |
|
Market Opportunity |
Next-generation AMI 2.0 platforms; municipal smart water meter rollout; Grid Data Bank analytics; VPP and demand response services; multi-utility metering |
Key Analytical Observations Supporting the Above Data:
- Smart Electricity Meter at 64.3%: The segment dominates because Japan's ten regional transmission and distribution utilities completed a mandated nationwide replacement of legacy electromechanical meters. The scale of this installed base, combined with a certification-driven ten-year renewal cycle, sustains the largest recurring procurement volume.
- AMI at 81.6%: Advanced metering infrastructure leads because Japanese electricity utilities selected two-way Wi-SUN mesh communication as the national standard. AMI supports remote connection, outage detection, and thirty-minute settlement data, making it indispensable for retail competition and renewable integration.
- Kanto Region at 34.8%: Kanto leads through the Tokyo metropolitan area's household and commercial premises density, served by the country's largest distribution utility. Concentrated demand response programmes, dense rooftop solar penetration, and early AMI upgrades reinforce regional revenue dominance.
Japan Smart Meters Market Overview
The Japan smart meters market encompasses the design, manufacture, deployment, and data management of digital metering devices measuring electricity, gas, and water consumption across residential, commercial, and industrial premises nationwide.
The ecosystem integrates metering semiconductor and communication module suppliers, meter manufacturers, AMI head-end and meter data management platform vendors, system integrators, regional utilities, municipal waterworks, and regulatory bodies setting specifications and certification standards.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
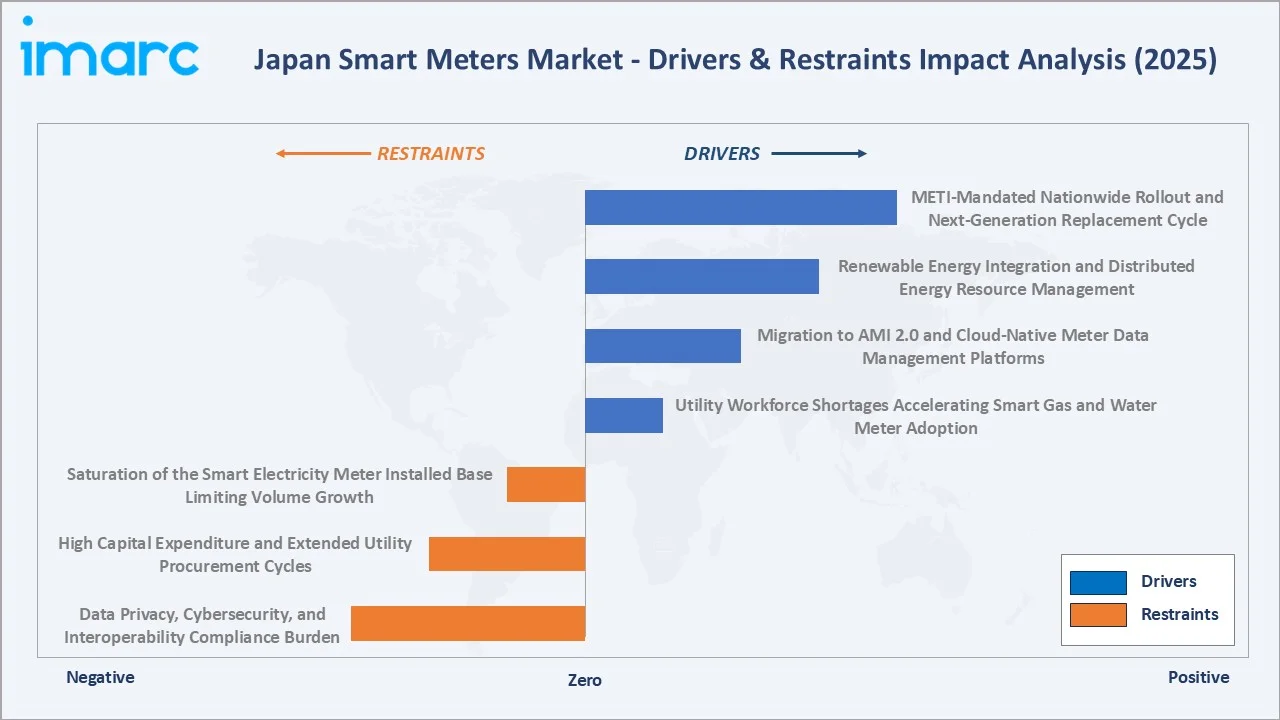
- METI-Mandated Nationwide Rollout and Next-Generation Replacement Cycle: Government-led policy required regional utilities to replace legacy meters with smart meters nationwide. With initial penetration effectively complete, a structural replacement cycle now begins, as certified meters reach end-of-life and are substituted with next-generation devices offering enhanced data granularity. Utilities are budgeting multi-year procurement programmes to sequence these replacements without disrupting billing continuity. This creates a predictable, policy-backed demand floor that insulates suppliers from consumer discretionary spending cycles.
- Renewable Energy Integration and Distributed Energy Resource Management: Japan's Strategic Energy Plan targets a substantially higher renewable share of national generation. Rooftop solar, battery storage, and electric vehicle charging create bidirectional power flows that require granular metering data for accurate settlement, voltage management, and distribution network planning. Operators increasingly rely on interval consumption records to forecast local load and manage reverse power flow on distribution feeders. This elevates metering from a billing function into a core grid operations asset.
- Migration to AMI 2.0 and Cloud-Native Meter Data Management Platforms: Utilities are relocating meter data management systems onto scalable cloud infrastructure to handle higher-resolution consumption records. This transition raises platform, integration, and analytics spending per meter, expanding market value beyond hardware and supporting new grid intelligence services. Cloud architectures also shorten deployment timelines for new tariff structures and consumer-facing applications. Vendors offering managed platform services capture recurring revenue that scales with connected meter volumes rather than one-time hardware sales.
- Utility Workforce Shortages Accelerating Smart Gas and Water Meter Adoption: Japan's shrinking working-age population makes manual meter reading increasingly costly for gas retailers and municipal waterworks. Automated remote reading reduces field visits, improves billing accuracy, and enables leak detection, driving adoption across previously underpenetrated utility categories. Operators are consolidating reading contracts and prioritising remote-capable devices within replacement tenders. Extended battery life and low-power communication reduce lifecycle cost, improving the investment case for smaller operators working within constrained capital budgets.
Market Restraints
- Saturation of the Smart Electricity Meter Installed Base Limiting Volume Growth: With nationwide electricity meter penetration effectively achieved, incremental unit demand now depends largely on replacement rather than new installation. This structurally caps volume growth and shifts competition toward price, software content, and service differentiation among established suppliers. Suppliers consequently face intensified price competition within long-term framework tenders. Revenue growth increasingly depends on raising software and service content per meter rather than expanding installed unit volumes.
- High Capital Expenditure and Extended Utility Procurement Cycles: Metering programmes require substantial upfront investment in devices, communication networks, and back-end systems recovered over long regulatory periods. Multi-year tender cycles and rigorous certification requirements slow technology refresh and delay revenue recognition for suppliers. Regulated cost recovery mechanisms further constrain how quickly operators can accelerate investment. Suppliers must sustain production capacity and engineering teams across uneven order flows, which pressures working capital and margins.
- Data Privacy, Cybersecurity, and Interoperability Compliance Burden: Granular consumption data raises privacy obligations, while critical infrastructure status demands rigorous cybersecurity controls. Meeting evolving certification, encryption, and interoperability requirements increases development cost and lengthens product qualification timelines for meter and platform vendors. Certification testing must be repeated whenever firmware or communication stacks are materially updated. These obligations raise the effective barrier to entry and slow the introduction of new metering features into operating networks.
Market Opportunities
- Municipal Smart Water Meter Deployment: Japanese waterworks remain substantially less digitised than electricity networks. Ageing pipelines, non-revenue water losses, and reading workforce shortages create a sizeable addressable opportunity for ultrasonic smart water meters combined with low-power wide-area communication and leak analytics. Combining consumption data with pressure and acoustic sensing enables early identification of losses across ageing distribution networks. Vendors packaging hardware, connectivity, and analytics into a single procurement offer are best positioned to capture this demand.
- Smart Meter Data Monetisation and Virtual Power Plant Services: The national grid data platform enables consented sharing of consumption records with third parties. This supports demand response aggregation, energy management applications, and insurance or property services, creating recurring software revenue layered above metering hardware. Aggregated consumption profiles support flexibility services that help balance an increasingly variable generation mix. Revenue from these services accrues continuously, improving supplier earnings quality relative to cyclical hardware tender awards.
Market Challenges
- Component and Semiconductor Supply Constraints for Certified Metering Hardware: Metering integrated circuits and communication modules require long qualification cycles, limiting substitution when supply tightens. Any disruption can delay utility deployment schedules, raise procurement costs, and compress supplier margins on fixed-price framework contracts. Dual sourcing is constrained because each alternative component must be re-certified before field deployment. Suppliers therefore carry larger inventory buffers, tying up working capital and reducing flexibility during periods of volatile demand.
- Fragmented Municipal Procurement in Gas and Water Metering: Unlike electricity, gas retail and water supply involve numerous municipal and private operators with differing specifications and budgets. This fragmentation raises sales costs, limits standardisation, and slows the pace of nationwide smart metering adoption. Differing technical specifications also restrict manufacturing scale economies across individual contracts. Broader adoption will require greater harmonisation of device requirements and shared communication infrastructure between utility categories.
Emerging Market Trends
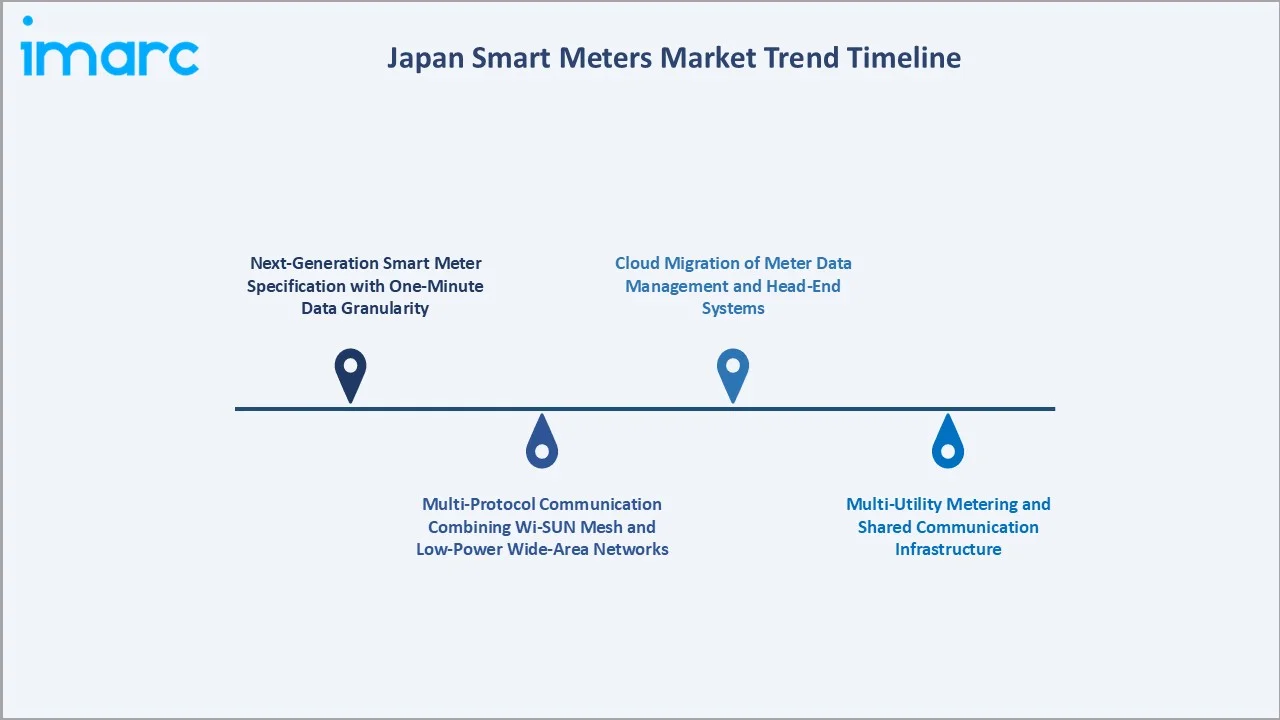
1. Next-Generation Smart Meter Specification with One-Minute Data Granularity
Utilities are adopting a revised national specification that records and stores higher-resolution consumption data locally. Finer granularity supports accurate settlement of distributed generation, faster outage detection, and richer consumer applications, raising demand for meters with expanded memory and processing capability.
2. Multi-Protocol Communication Combining Wi-SUN Mesh and Low-Power Wide-Area Networks
Meter designs increasingly support several communication options within one platform. Combining mesh networking for dense urban areas with cellular and low-power wide-area technologies for remote premises improves coverage economics and enables shared infrastructure across electricity, gas, and water metering.
3. Cloud Migration of Meter Data Management and Head-End Systems
Regional utilities are shifting large-scale metering platforms from on-premises hardware onto public cloud infrastructure. This improves elasticity for higher data volumes, reduces operating cost, and creates an integration opportunity for information technology vendors alongside traditional meter manufacturers.
4. Multi-Utility Metering and Shared Communication Infrastructure
Operators are exploring combined electricity, gas, and water data collection over common networks. Shared infrastructure lowers per-meter communication cost, simplifies field operations, and accelerates smart gas and water adoption in regions where standalone deployment economics remain challenging.
Industry Value Chain Analysis
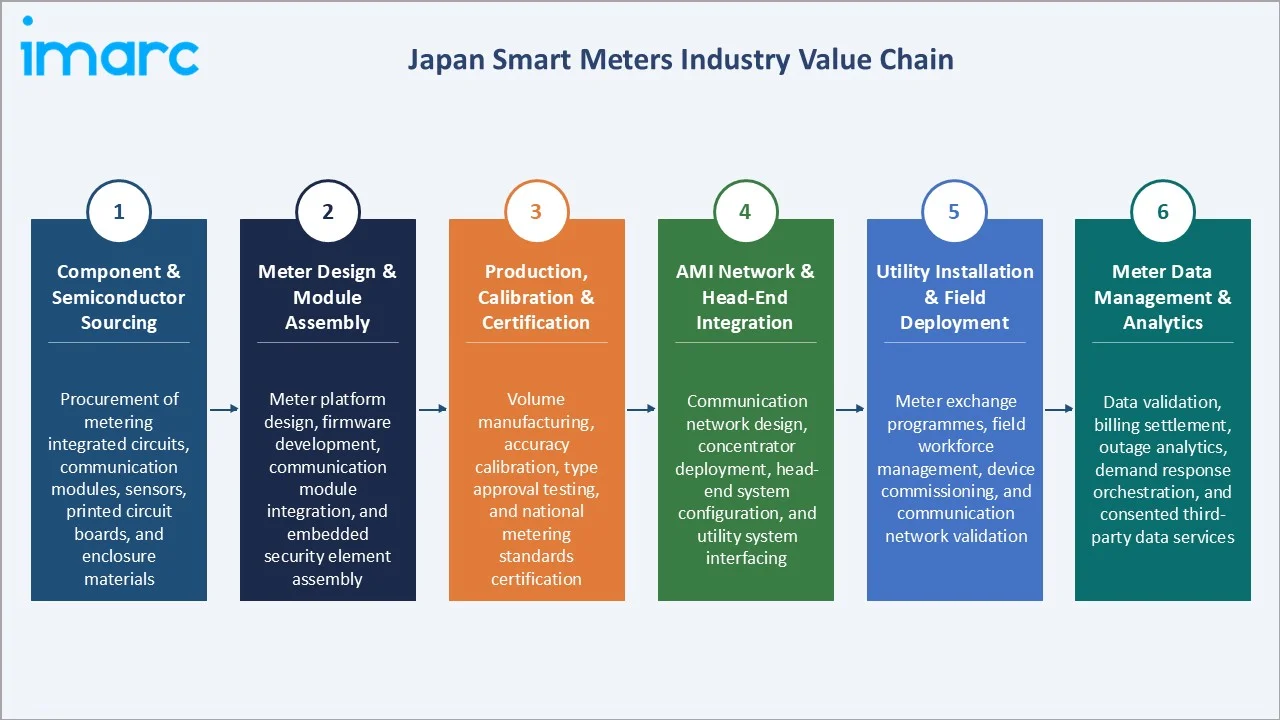
The value chain integrates component and semiconductor sourcing, meter design and communication module assembly, production and certification, AMI network and head-end integration, utility field deployment, and meter data management with analytics services.
|
Stage |
Key Participants |
|
Component & Semiconductor Sourcing |
Procurement of metering integrated circuits, communication modules, sensors, printed circuit boards, and enclosure materials |
|
Meter Design & Module Assembly |
Meter platform design, firmware development, communication module integration, and embedded security element assembly |
|
Production, Calibration & Certification |
Volume manufacturing, accuracy calibration, type approval testing, and national metering standards certification |
|
AMI Network & Head-End Integration |
Communication network design, concentrator deployment, head-end system configuration, and utility system interfacing |
|
Utility Installation & Field Deployment |
Meter exchange programmes, field workforce management, device commissioning, and communication network validation |
|
Meter Data Management & Analytics |
Data validation, billing settlement, outage analytics, demand response orchestration, and consented third-party data services |
Certification and calibration remain the value chain's most restrictive stage, creating durable incumbency advantages. Meter data management and analytics is the fastest-evolving tier as cloud platforms and third-party services displace legacy on-premises architectures.
Technology Landscape in the Japan Smart Meters Industry
Advanced Metering Infrastructure (AMI) Technology
AMI provides two-way communication between meters and utility systems, enabling remote reading, remote connection and disconnection, outage notification, and settlement-grade interval data. Its bidirectional capability underpins retail electricity competition and distributed energy integration across Japan's regional networks.
Automatic Meter Reading (AMR) Technology
AMR supports one-way automated collection of consumption data without remote control capability. It remains relevant for gas and water applications where lower cost, extended battery life, and simpler installation outweigh the benefits of full two-way network functionality.
Wi-SUN Mesh and Low-Power Wide-Area Communication
Wi-SUN mesh networking is the established communication backbone for Japanese electricity metering, providing resilient self-healing coverage in dense areas. Low-power wide-area technologies increasingly complement it for battery-powered gas and water meters requiring multi-year operation without maintenance.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Smart Electricity Meter |
64.3% |
2025 |
|
Technology |
AMI (Advanced Metering Infrastructure) |
81.6% |
2025 |
|
End Use |
🔒 |
🔒 |
2025 |
|
Region |
Kanto Region |
34.8% |
2025 |

By Product
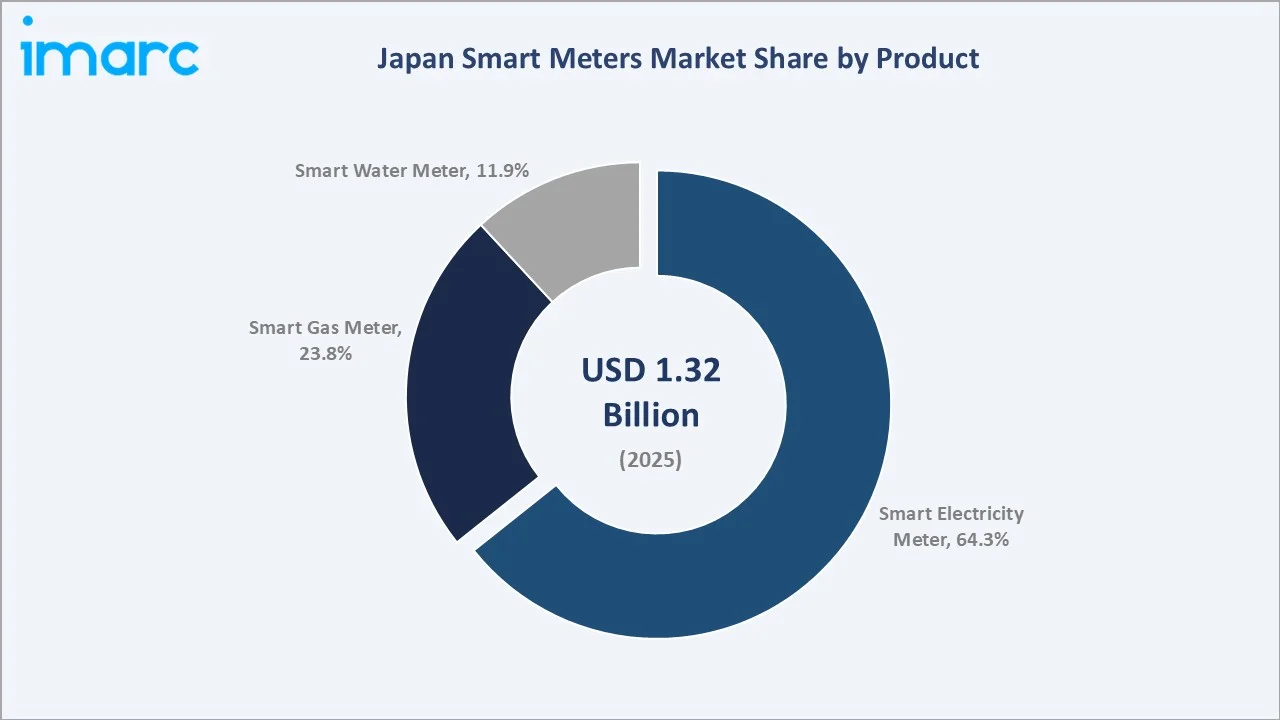
Smart electricity meters lead at 64.3% in 2025, reflecting the nationwide low-voltage installed base and the mandated replacement programme that established electricity as the country's most digitised metering category.
To access detailed market analysis, Request Sample
Smart gas meters at 23.8% benefit from established security metering requirements and remote shut-off capability for earthquake safety. Smart water meters at 11.9% represent the smallest but fastest-growing category at approximately 9.1% CAGR, driven by municipal digitisation.
By Technology
AMI leads at 81.6% through nationwide electricity utility standardisation on two-way communication. The segment grows at approximately 8.1% CAGR as next-generation specifications and cloud-based meter data platforms increase software and service content per installed meter.
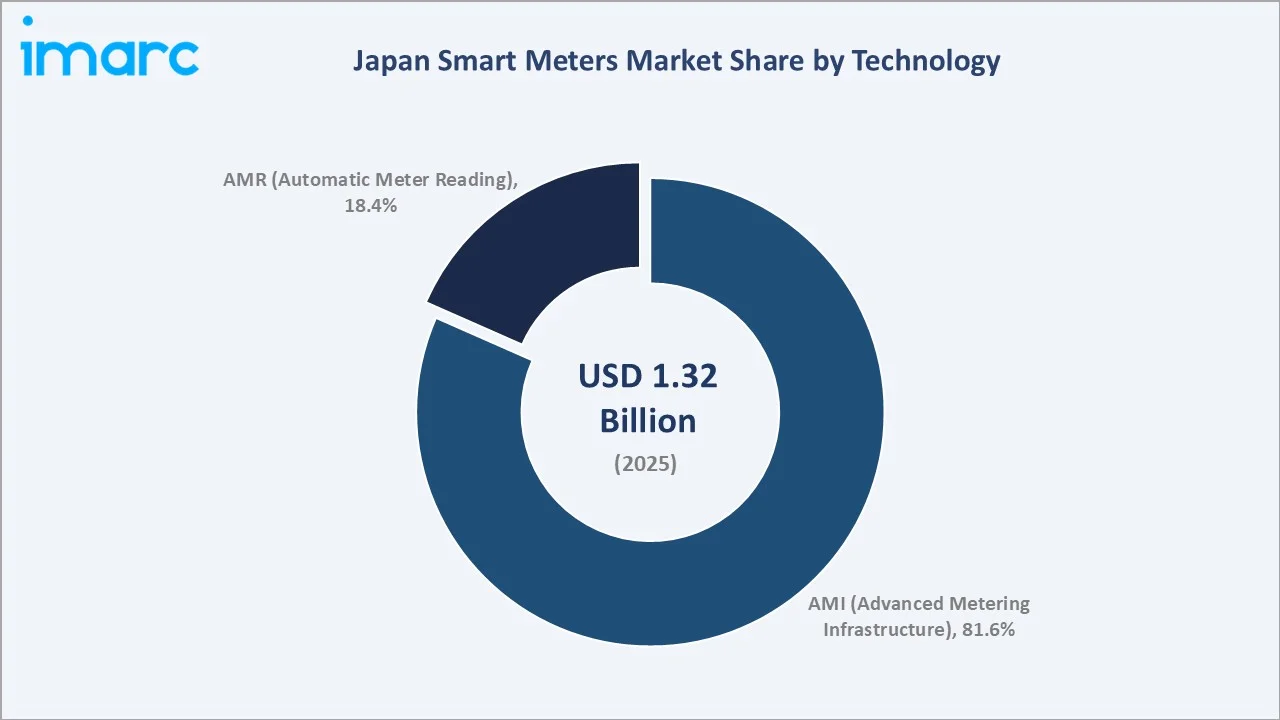
AMR at 18.4% retains a meaningful position in gas and water metering where one-way collection satisfies operational requirements at lower cost. The segment grows more slowly at approximately 5.2% CAGR as utilities progressively migrate toward two-way architectures.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
Kanto Region |
34.8% |
Leading share supported by the highest concentration of metered premises, dense urban demand, and early adoption of advanced metering infrastructure |
|
Kansai/Kinki Region |
17.6% |
Supported by a large urban and commercial consumption base, mature metering infrastructure, and progressive adoption of meter data platforms |
|
Central/Chubu Region |
15.1% |
Driven by manufacturing-intensive industrial demand, high distributed generation penetration, and continued distribution network modernisation |
|
Kyushu-Okinawa Region |
9.3% |
Supported by a high renewable generation share, output management requirements, and active demand-side flexibility programmes |
|
Tohoku Region |
8.1% |
Driven by grid resilience investment, renewable energy integration, and dispersed premises that favour remote reading economics |
|
Chugoku Region |
6.3% |
Supported by coastal industrial demand, metering technology pilots, and growing interest in higher-resolution consumption data |
|
Hokkaido Region |
5.1% |
Driven by cold-climate heating loads, winter supply resilience requirements, and renewable integration across a dispersed network |
|
Shikoku Region |
3.7% |
Emerging with a smaller premises base, ongoing meter replacement activity, and gradual municipal water metering digitisation |
Kanto at 34.8% leads through metropolitan premises density and the largest regional metered base. Kansai/Kinki at 17.6% reflects concentrated commercial demand and early adoption of cloud-based meter data platforms.
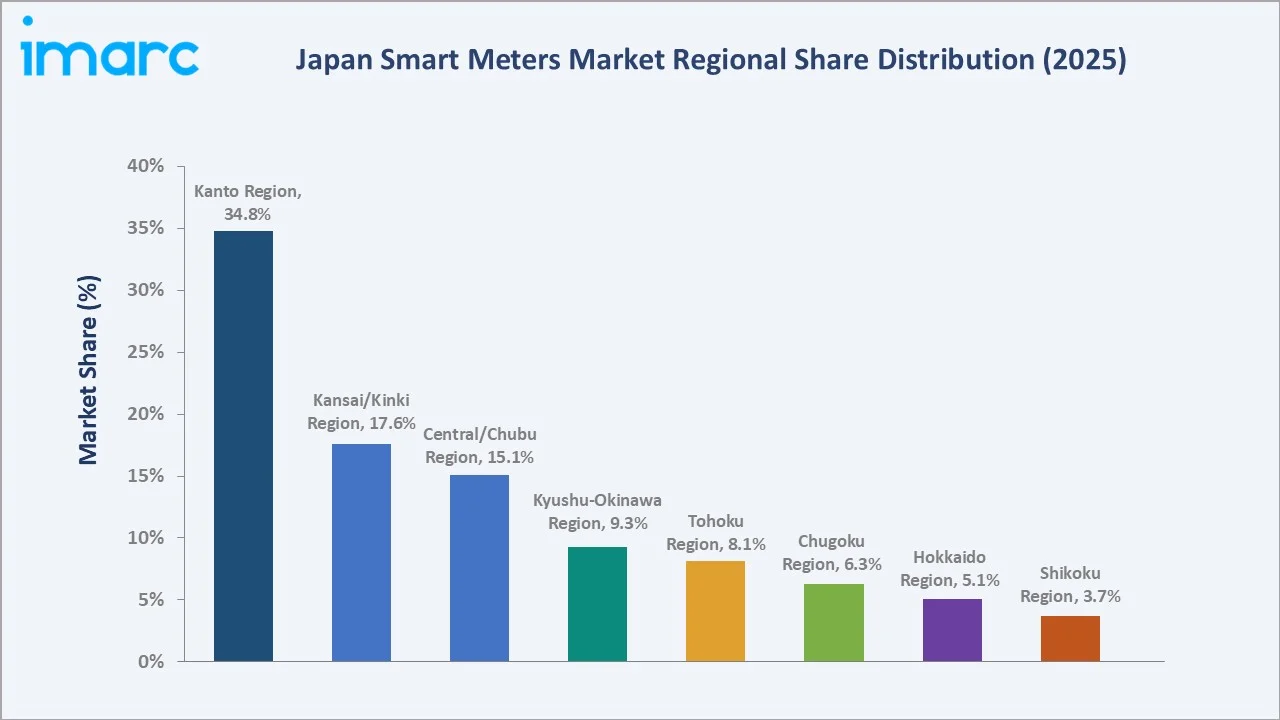
Central/Chubu at 15.1% reflects industrial consumption intensity and distributed generation penetration. Kyushu-Okinawa at 9.3% and Tohoku at 8.1% are shaped by renewable integration requirements, while Chugoku, Hokkaido, and Shikoku represent smaller but steadily digitising regional markets.
Competitive Landscape
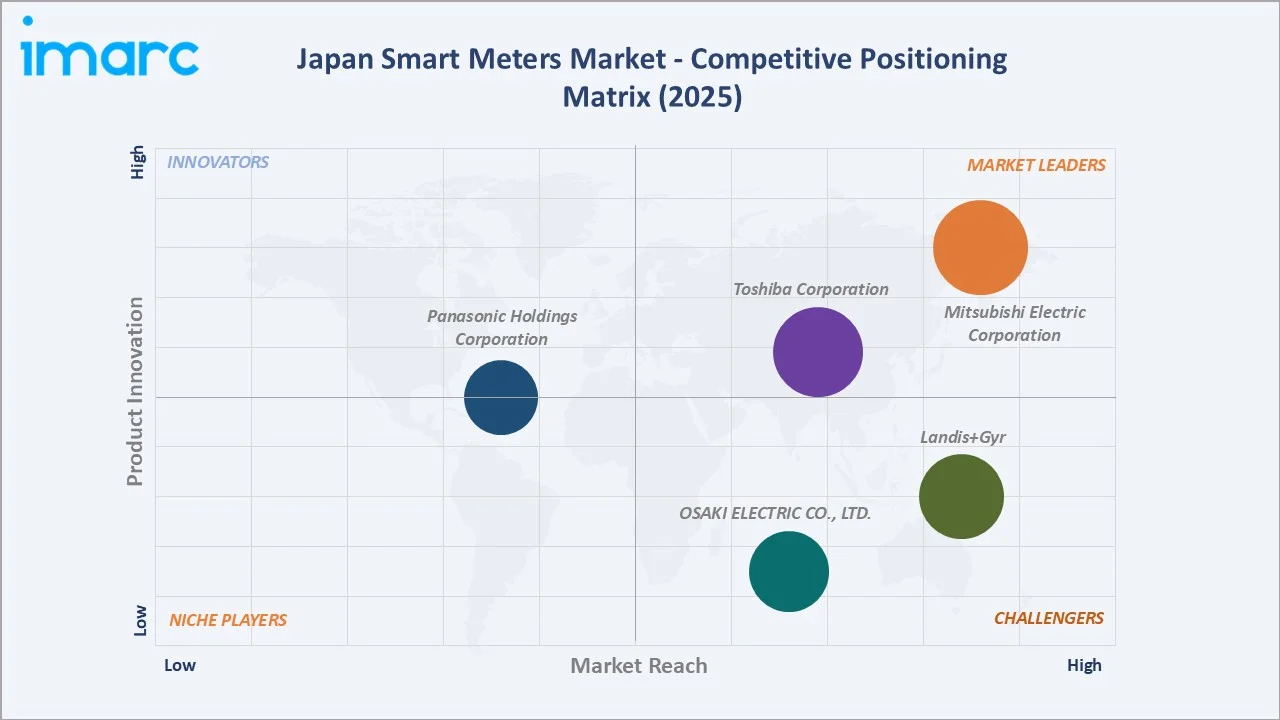
The Japan smart meters market is moderately consolidated across three competitive tiers: domestic electrical equipment conglomerates, specialist metering manufacturers, and information technology vendors supplying head-end and meter data management platforms.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Mitsubishi Electric Corporation |
Smart electricity meters, BLEnDer AMI head-end system, communication modules |
Market Leader |
Integrated meter and head-end system supply with proven overseas AMI deployment capability |
|
Toshiba Corporation |
Smart electricity meters, AMI communication systems, energy management platforms |
Market Leader |
Large-scale utility meter supply combined with grid infrastructure and systems integration depth |
|
OSAKI ELECTRIC CO., LTD. |
Smart electricity meters |
Strong Challenger |
Metering specialisation with global delivery scale through its EDMI subsidiary |
|
Landis+Gyr |
Smart electricity meters, Smart gas meters |
Strong Challenger |
International metering pure-play with substantial Japanese smart meter supply history |
|
Panasonic Holdings Corporation |
Smart electricity meters |
Established Player |
Consumer and building energy management integration alongside metering hardware |
Key players include Mitsubishi Electric Corporation, Toshiba Corporation, OSAKI ELECTRIC CO., LTD., Landis+Gyr, Panasonic Holdings Corporation, and others.
Key Company Profiles
Mitsubishi Electric Corporation
Mitsubishi Electric Corporation is a Japan-based electrical equipment manufacturer with a leading position in the smart meters market through its metering hardware, communication modules, and advanced metering infrastructure head-end systems.
- Key Products: Smart electricity meters, BLEnDer AMI head-end system, metering communication modules.
- Strategic Focus: Expanding integrated metering and grid management offerings that combine meters, communication infrastructure, and data platforms for utilities managing rising distributed energy penetration. The company is aligning its metering roadmap with next-generation national specifications requiring finer data granularity. Its combined hardware and software capability supports operators seeking single-vendor accountability across large-scale deployment programmes.
Toshiba Corporation
Toshiba Corporation is a Japanese infrastructure and energy systems group with a substantial presence in the smart meters market through utility-scale meter supply and advanced metering infrastructure system integration.
- Key Products: Smart electricity meters, AMI communication and head-end systems, energy management platforms.
- Strategic Focus: Strengthening grid infrastructure and metering system integration capability, linking meter data with distribution automation and renewable energy management solutions for regional utilities. Metering is positioned as an entry point into broader grid modernisation contracts. Its infrastructure engineering base supports integration between consumption data, network automation, and long-term resilience planning.
Market Concentration Analysis
The market is moderately consolidated at the meter manufacturing level, with the key players collectively accounting for a substantial share of domestic smart electricity meter supply.
Long-term framework tenders and stringent certification requirements reinforce incumbency in hardware. The software and head-end layer is more fragmented, attracting information technology vendors and cloud providers, and concentration is expected to ease modestly as data platforms gain revenue weight.
Investment & Growth Opportunities
Highest Growth Segments
Smart water meters (~9.1% CAGR), AMI technology (~8.1% CAGR), smart gas meters (~7.9% CAGR), meter data management software and analytics services, and multi-utility communication infrastructure represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Municipal water metering digitisation offers the market's largest untapped unit opportunity, given low current penetration, ageing pipeline networks, non-revenue water losses, and acute reading workforce shortages across hundreds of local waterworks operators nationwide.
Investment Themes
- Meter data platform and analytics capability as the primary source of margin expansion through 2034: As hardware pricing compresses under replacement-driven tenders, recurring software and analytics revenue becomes the principal differentiator. Vendors combining certified metering hardware with cloud-native data platforms can defend margins that pure hardware suppliers cannot.
- Multi-utility communication infrastructure enabling shared deployment economics across electricity, gas, and water: Investment in common network architecture lowers the per-meter cost of connecting battery-powered gas and water devices. This unlocks addressable volume in categories where standalone deployment economics have historically remained unattractive.
Future Market Outlook (2026-2034)
The Japan smart meters market is projected to grow from USD 1.32 Billion in 2025 to USD 2.55 Billion by 2034, delivering a 7.57% CAGR. The anchor value of USD 1.90 Billion in 2030 marks the sector's transition from hardware rollout to data-led growth.
By 2030, next-generation meters offering finer data granularity are expected to constitute the mainstream electricity procurement specification, cloud-based meter data management should be widely adopted, and municipal smart water metering is anticipated to scale materially.
Research Methodology
Primary Research
Primary research comprised structured interviews with 50+ industry stakeholders (2025), including utility metering programme managers, meter manufacturing executives, AMI communication engineers, meter data platform architects, and municipal waterworks digitisation leads.
Secondary Research
Secondary research encompassed company annual reports and disclosures; Ministry of Economy, Trade and Industry policy documentation; Strategic Energy Plan targets; regional utility deployment statistics; metering standards and certification publications; and international smart metering market studies. Over 60 secondary sources reviewed.
Forecasting Models
Forecasts were developed using an installed-base bottom-up model: (i) metered premises by utility category and region; (ii) meter replacement cycle timing and certification expiry; (iii) average realised device price by product and technology; (iv) software, communication, and services revenue layered per connected meter.
Japan Smart Meters Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Products Covered | Smart Electricity Meter, Smart Water Meter, Smart Gas Meter |
| Technologies Covered | AMI (Advanced Metering Infrastructure), AMR (Automatic Meter Reading) |
| End Uses Covered | Residential, Commercial, Industrial |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | Mitsubishi Electric Corporation, Toshiba Corporation, OSAKI ELECTRIC CO., LTD., Landis+Gyr , Panasonic Holdings Corporation, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan smart meters market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan smart meters market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan smart meters industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Smart Meters Market Report
The Japan smart meters market reached USD 1.32 Billion in 2025, supported by smart electricity meters dominating at 64.3%, AMI technology leading at 81.6%, the Kanto Region commanding 34.8% share, and a nationwide installed base sustaining recurring replacement demand.
The market grows at 7.57% CAGR during 2026-2034, reaching USD 2.55 Billion by 2034. Growth reflects the certified meter replacement cycle, renewable energy integration requirements, cloud meter data platform migration, and expanding smart gas and water meter adoption.
Smart electricity meters lead at 64.3%, reflecting the nationwide low-voltage installed base created by the mandated rollout. Smart water meters grow fastest at approximately 9.1% CAGR as municipal waterworks digitise reading operations amid workforce shortages.
AMI leads at 81.6% through nationwide electricity utility standardisation on two-way communication supporting remote control and settlement data. AMI also grows fastest at approximately 8.1% CAGR as next-generation specifications increase software content per meter.
The Kanto Region leads at 34.8% through Tokyo metropolitan premises density, the largest regional distribution utility base, early advanced metering infrastructure upgrades, and concentrated demand response programme activity.
Leading companies include Mitsubishi Electric Corporation, Toshiba Corporation, OSAKI ELECTRIC CO., LTD., Landis+Gyr, Panasonic Holdings Corporation, and others.
The market is projected to reach approximately USD 1.90 Billion by 2030, with next-generation meter specifications becoming mainstream, cloud-based meter data management widely adopted, and municipal smart water metering scaling materially across regional waterworks operators.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade