
Saudi Arabia Automotive Wiring Harness Market Size, Share, Trends and Forecast by Application, Material Type, Transmission Type, Vehicle Type, Category, Component, and Region, 2026-2034
Saudi Arabia Automotive Wiring Harness Market Size, Share, Trends & Forecast (2026-2034)
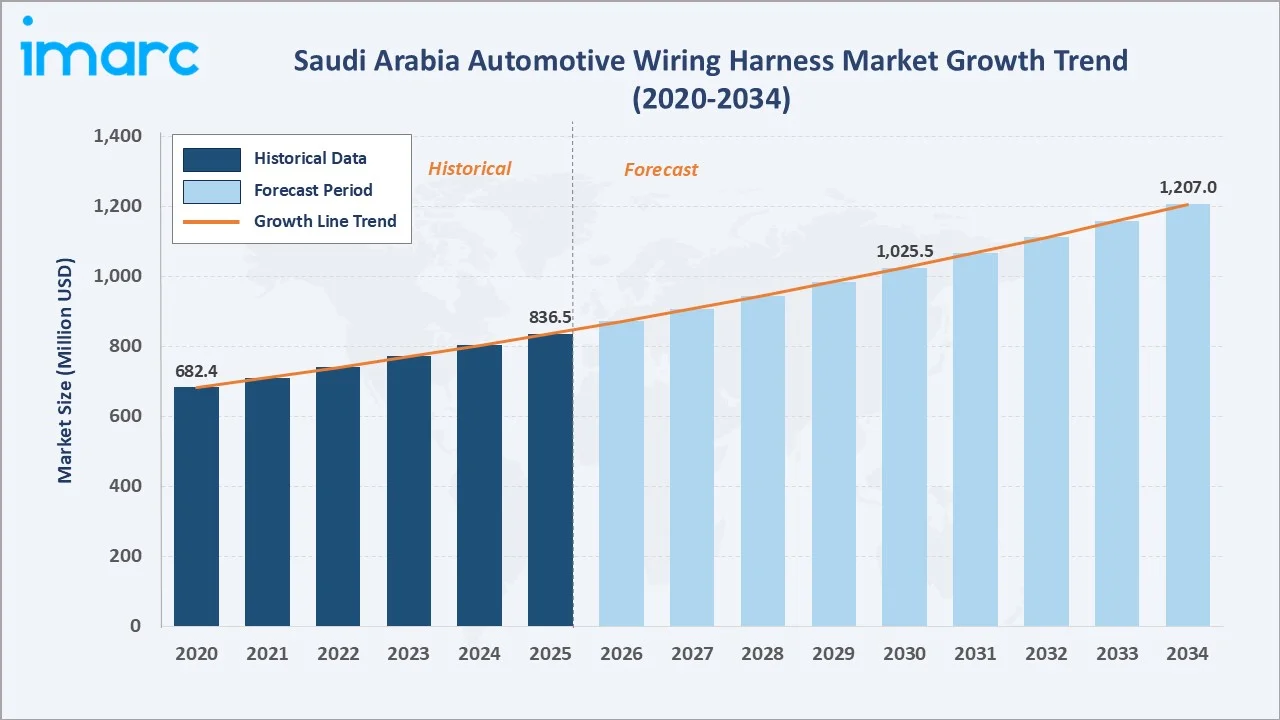
The Saudi Arabia automotive wiring harness market grew from USD 836.5 Million in 2025 to USD 871.3 Million in 2026 and is projected to reach USD 1,207.0 Million by 2034, growing at a CAGR of 4.16% during 2026-2034. The market is driven by rising vehicle sales under Vision 2030, EV and connected vehicle adoption, expanding NEOM and giga-project demand, and increasing integration of advanced driver assistance systems (ADAS) across passenger and commercial vehicles.
Passenger Cars dominate at 61.4%. General Wires lead category at 38.6%. Northern and Central Region commands 42.7% of the national market share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 836.5 Million |
|
Market Size (2026) |
USD 871.3 Million |
|
Forecast Market Size (2034) |
USD 1,207.0 Million |
|
CAGR (2026-2034) |
4.16% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Vehicle Type |
Passenger Cars (61.4%, 2025) |
|
Dominant Category |
General Wires (38.6%, 2025) |
|
Leading Region |
Northern & Central Region (42.7%, 2025) |
The Saudi Arabia automotive wiring harness market size increased from USD 682.4 Million in 2020 to USD 836.5 Million in 2025 and is estimated to reach USD 871.3 Million in 2026. The market is further expected to grow to USD 1,025.5 Million by 2030 and USD 1,207.0 Million by 2034. Saudi Arabia's automotive wiring harness market is commercially anchored by the Kingdom's large and growing vehicle parc, Vision 2030's industrial localisation agenda, and increasing demand for high-complexity harness solutions across electrified and connected vehicle platforms.
To get more information on this market, Request Sample
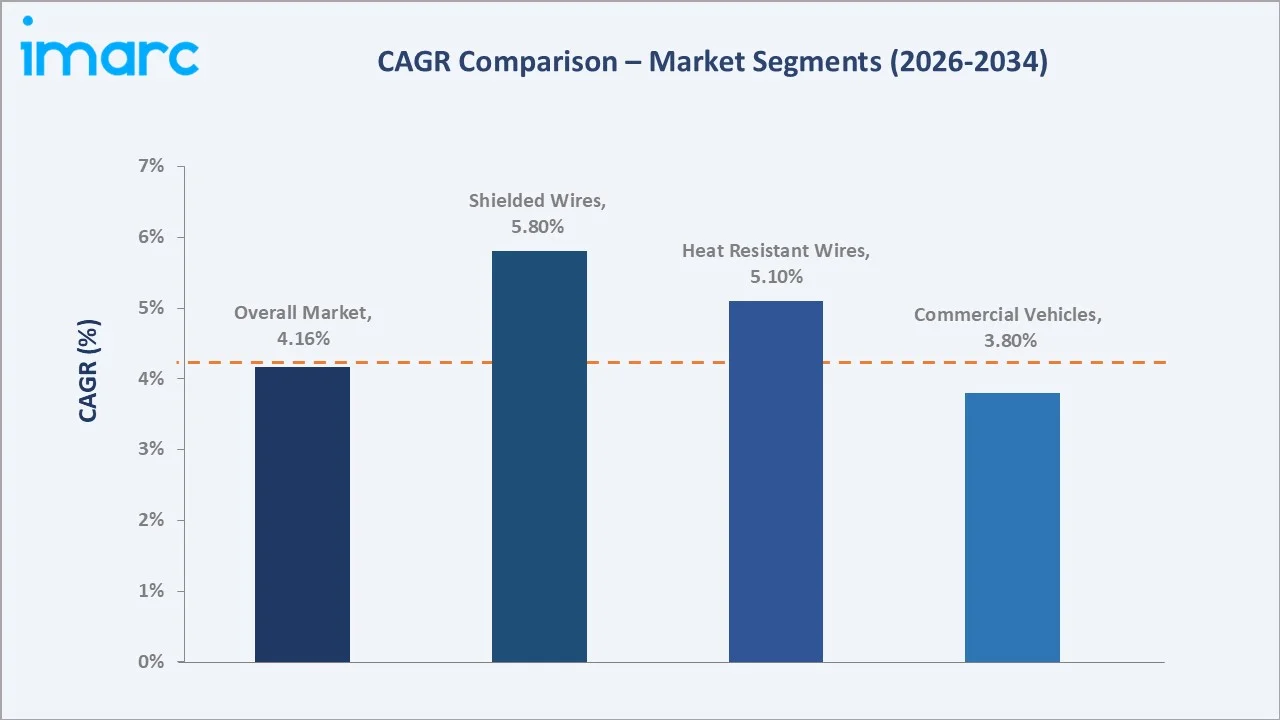
The heat resistant wires segment grows fastest at ~5.1% CAGR through rising underhood temperature requirements in turbocharged engines and EV battery systems. Shielded wires grow at ~5.8% CAGR driven by ADAS, infotainment, and high-speed data transmission proliferation.
Executive Summary
The Saudi Arabia automotive wiring harness market expanded from USD 836.5 Million in 2025 to an estimated USD 871.3 Million in 2026, positioning it as the largest automotive wiring harness market in the GCC by value. The market is underpinned by Saudi Arabia's rapidly expanding vehicle parc, Vision 2030's manufacturing and infrastructure ambitions, and growing adoption of electrical and electronic architectures in modern vehicles. The market is projected to reach USD 1,207.0 Million by 2034. Passenger Cars at 61.4% lead through consumer demand for premium connected vehicles. General Wires at 38.6% reflect foundational harness infrastructure requirements. Northern and Central Region leads regionally at 42.7%.
Key Market Insights
|
Insight |
Data |
|
Dominant Vehicle Type |
Passenger Cars – 61.4% share (2025) |
|
Dominant Category |
General Wires – 38.6% market share (2025) |
|
Leading Region |
Northern & Central Region – 42.7% share (2025) |
|
Market Opportunity |
EV and HEV harness localisation; NEOM smart mobility infrastructure; ADAS and connected vehicle proliferation; IKTVA-aligned local wiring harness manufacturing |
Key Analytical Observations Supporting the Above Data:
- Passenger Cars at 61.4%: Passenger cars dominate as Saudi Arabia's consumer vehicle market expands with rising income, youthful demographics, and Vision 2030 tourism and entertainment driving personal mobility demand. Premium and mid-range cars with higher harness complexity per unit amplify revenue contribution above unit volume share, supporting the segment's commercial leadership in wiring harness procurement.
- General Wires at 38.6%: General wires lead as the foundational wiring category across all vehicle types and all harness applications, providing the bulk of power and signal distribution in standard automotive architectures. Their widespread compatibility across OEM platforms and high usage density per vehicle reinforces their dominant share over specialty categories.
- Northern & Central Region at 42.7%: Northern and Central Region dominates due to Riyadh's status as the Kingdom's automotive retail, logistics, and government procurement hub. High urbanisation, major infrastructure projects, and the highest concentration of commercial fleet operators generate disproportionate harness demand across both passenger and commercial vehicle segments.
Saudi Arabia Automotive Wiring Harness Market Overview
Saudi Arabia automotive wiring harness market is commercially positioned at the intersection of the Kingdom's largest vehicle market, Vision 2030's industrial localisation programme, and the global automotive industry's transition toward electrification and connectivity. These structural forces are creating multi-layered harness demand across standard, heat-resistant, shielded, and tubed wire categories.
Saudi Arabia's wiring harness ecosystem integrates global tier-1 suppliers with domestic distributors, IKTVA-compliant assembly operations, and OEM service networks. Macroeconomic factors include rising disposable incomes, government fleet modernisation, and accelerating infrastructure buildout under Vision 2030's giga-projects including NEOM, Diriyah, and Red Sea developments.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
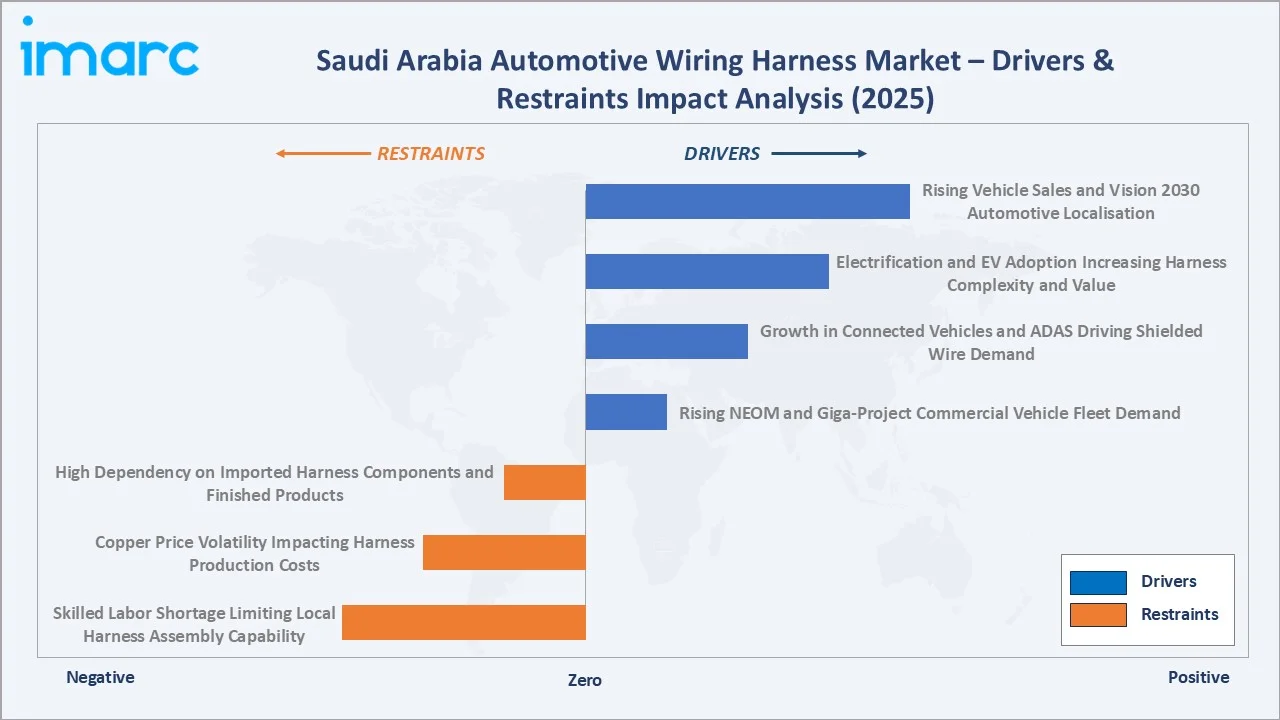
- Rising Vehicle Sales and Vision 2030 Automotive Localisation: Saudi Arabia's Vision 2030 targets domestic vehicle production and manufacturing ecosystem development, creating structural demand for locally sourced automotive components including wiring harnesses. Rising new vehicle registrations driven by income growth, population expansion, and tourism infrastructure development are expanding the national vehicle parc, generating sustained harness replacement and OEM fitment demand. Government incentives for domestic automotive assembly further accelerate localisation.
- Electrification and EV Adoption Increasing Harness Complexity and Value: The transition toward electric and hybrid vehicles is significantly increasing average wiring harness content per vehicle, as EV platforms require high-voltage battery management harnesses, charging system wiring, and expanded power distribution networks alongside conventional low-voltage signal harnesses.
- Growth in Connected Vehicles and ADAS Driving Shielded Wire Demand: Increasing penetration of ADAS features, infotainment systems, and vehicle-to-everything (V2X) connectivity in new vehicle models entering the Saudi market is driving disproportionate growth in high-performance shielded and data transmission wiring harness categories.
- Rising NEOM and Giga-Project Commercial Vehicle Fleet Demand: Saudi Arabia's unprecedented scale of infrastructure development under NEOM, Red Sea Project, Diriyah, and associated giga-projects is generating large commercial vehicle fleet procurement for construction, logistics, and transportation, each requiring robust commercial-grade wiring harnesses. Fleet operators purchasing heavy trucks, buses, and specialised vehicles at scale create concentrated, predictable procurement demand that supports harness supplier capacity investment and long-term supply contracts.
Market Restraints
- High Dependency on Imported Harness Components and Finished Products: Saudi Arabia currently imports the substantial majority of its automotive wiring harness requirements from global manufacturing hubs in Mexico, Morocco, China, and Eastern Europe, creating vulnerability to global supply chain disruptions, logistics cost inflation, and foreign exchange exposure. Limited domestic harness manufacturing capacity constrains IKTVA compliance and restricts the Kingdom's ability to build competitive local automotive supply chain depth.
- Copper Price Volatility Impacting Harness Production Costs: Copper is the primary conductor material in automotive wiring harnesses, typically accounting for 60-70% of harness material cost. Global copper price volatility driven by energy transition demand, mining supply constraints, and speculative market dynamics creates persistent cost uncertainty for harness manufacturers and their automotive OEM customers. Sustained copper price elevation compresses harness supplier margins and can trigger pricing renegotiations that create commercial friction in established supply relationships.
- Skilled Labor Shortage Limiting Local Harness Assembly Capability: Automotive wiring harness assembly is a labour-intensive manufacturing process requiring skilled technicians for manual wire routing, connector crimping, and harness testing. Saudi Arabia's current workforce demographics and technical skills base present challenges for establishing competitive in-Kingdom harness assembly operations that meet global OEM quality standards, constraining the pace of IKTVA-compliant local manufacturing development.
Market Opportunities
- EV and HEV Wiring Harness Localisation Investment Under IKTVA: Saudi Arabia's commitment to EV manufacturing through Lucid Motors and potential additional OEM entrants creates an opportunity for early-mover harness suppliers to establish in-Kingdom EV harness manufacturing capability qualifying for premium IKTVA procurement scoring. EV harnesses command 2-3x conventional vehicle harness value, making localisation investment economics significantly more attractive per unit of manufacturing capacity.
- NEOM Smart Mobility and Connected Infrastructure Harness Demand: NEOM's THE LINE and connected mobility infrastructure create novel harness specifications for autonomous vehicles, smart transportation systems, and integrated mobility platforms that represent new product categories without established incumbent suppliers. Early qualification in NEOM's automotive and mobility supply chain creates long-term demand visibility aligned with Vision 2030's most ambitious project timelines.
Market Challenges
- Rapid Technology Evolution Requiring Continuous Product Qualification: The automotive industry's accelerating technology evolution across EV platforms, ADAS systems, and software-defined vehicle architectures is shortening harness product lifecycles and requiring continuous engineering updates, new material qualifications, and OEM approval cycles. Harness suppliers serving Saudi Arabia must maintain both global technology development capability and local application engineering resources to remain qualified on next-generation vehicle platforms.
- Competitive Pressure from Low-Cost Global Manufacturing Hubs: Established harness manufacturing hubs in Morocco, Romania, and Southeast Asia offer cost structures that are difficult for Saudi Arabia-based assembly operations to match at current scale, creating persistent price competition pressure in standard harness categories. Building Saudi manufacturing cost competitiveness requires sustained IKTVA procurement preference, scale investment, and workforce productivity development over multiple years.
Emerging Market Trends
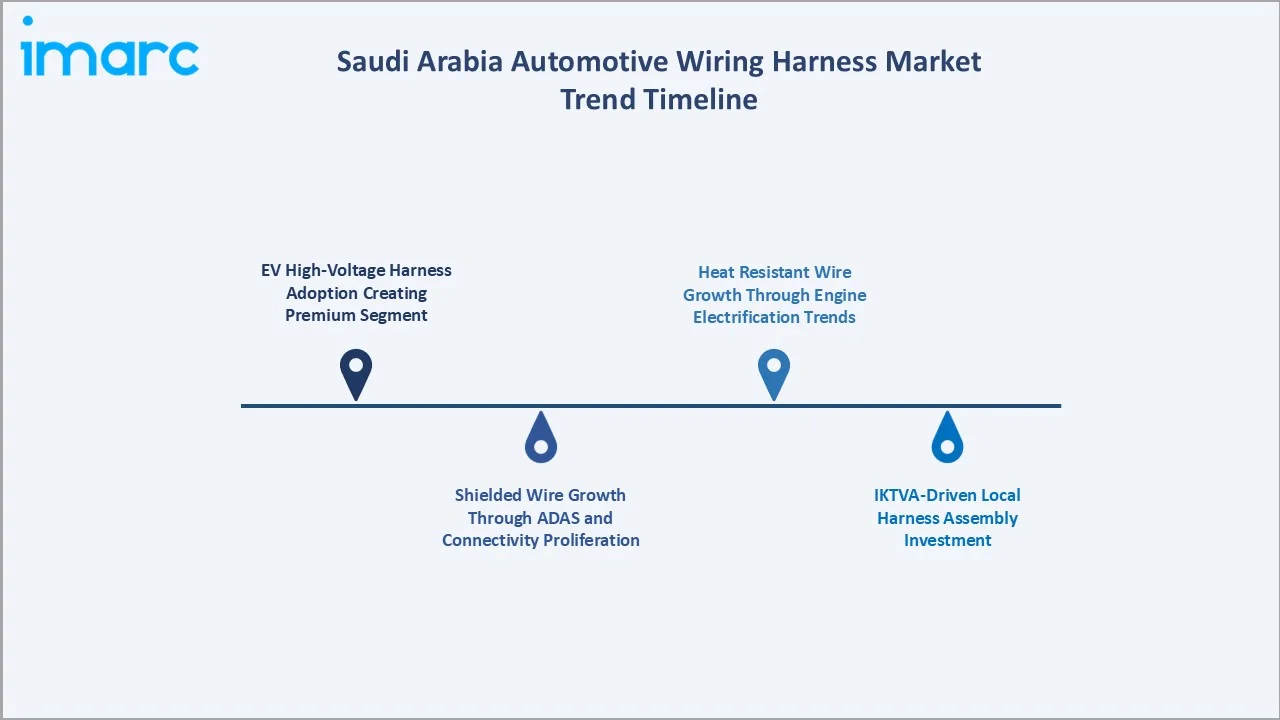
1. EV High-Voltage Harness Adoption Creating Premium Segment
Electric vehicle platforms require high-voltage wiring harnesses rated at 400V-800V for battery-to-motor power delivery, charging systems, and thermal management. Lucid Motors' Jeddah manufacturing presence and Saudi Arabia's EV adoption targets under Vision 2030 are creating the first sustained domestic demand for HV harness systems, attracting global tier-1 suppliers to establish local qualification and logistics capabilities.
2. Shielded Wire Growth Through ADAS and Connectivity Proliferation
Every new ADAS sensor, radar module, camera system, and V2X communication unit added to modern vehicles requires shielded wire harness connections to prevent electromagnetic interference. The rapid adoption of Level 2 and Level 3 ADAS features in new passenger vehicles entering Saudi Arabia is driving above-market growth in shielded wire demand, creating a premium category with specialised supply chain requirements.
3. IKTVA-Driven Local Harness Assembly Investment
Saudi Aramco's IKTVA programme and the broader National Industrial Clusters Development Programme (NICDP) are incentivising global harness suppliers to establish in-Kingdom assembly operations. Several tier-1 suppliers are evaluating Saudi Arabia manufacturing bases to qualify for Vision 2030-aligned procurement preferences, with the Eastern Region's industrial zones representing the primary investment destination.
4. Heat Resistant Wire Growth Through Engine Electrification Trends
Turbocharged engines, hybrid powertrains, and exhaust heat recovery systems are increasing underhood temperature environments beyond the ratings of standard general wires. Heat resistant wires with fluoropolymer or cross-linked polyethylene insulation are gaining adoption across Saudi Arabia's vehicle parc as import vehicles carry increasing electrification content, supporting the segment's above-average CAGR through 2034.
Industry Value Chain Analysis
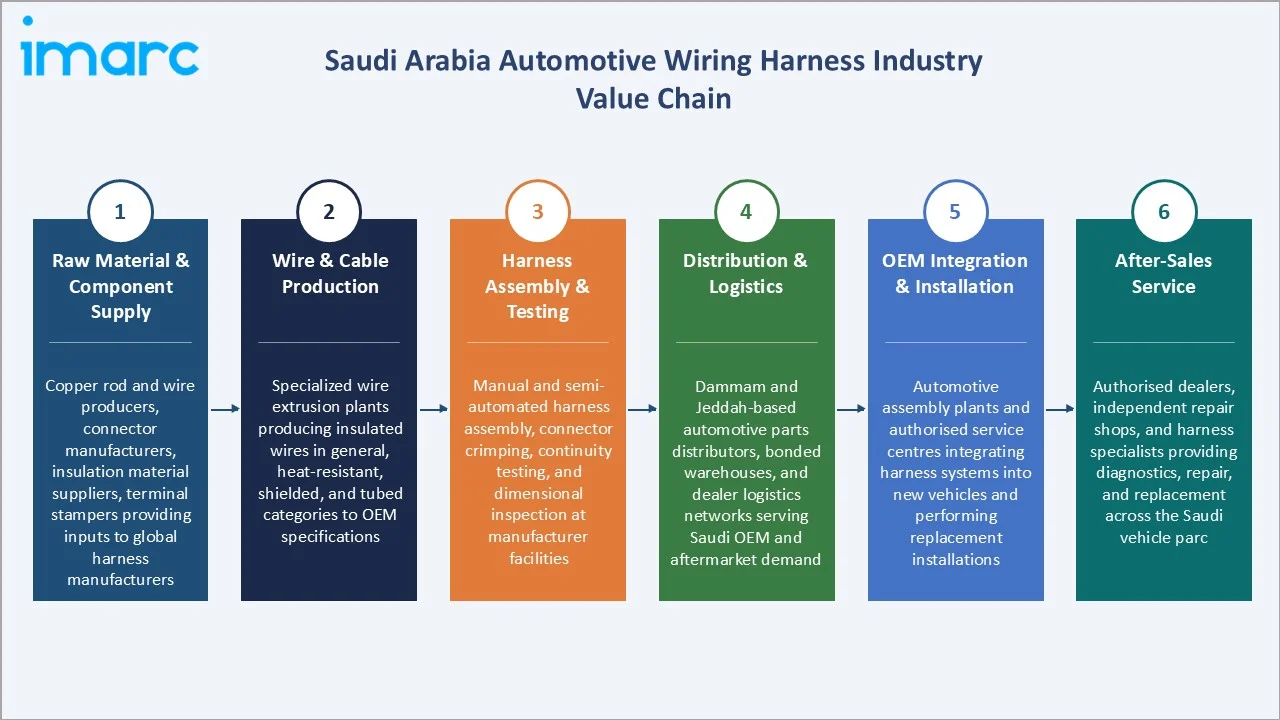
Saudi Arabia automotive wiring harness value chain is characterised by high import dependency at the finished product level, with global tier-1 suppliers and distributors forming the core commercial structure. Increasing IKTVA local content requirements are driving progressive in-Kingdom value-addition across assembly, testing, and technical support stages.
|
Stage |
Key Participants |
|
Raw Material & Component Supply |
Copper rod and wire producers, connector manufacturers, insulation material suppliers, terminal stampers providing inputs to global harness manufacturers |
|
Wire & Cable Production |
Specialized wire extrusion plants producing insulated wires in general, heat-resistant, shielded, and tubed categories to OEM specifications |
|
Harness Assembly & Testing |
Manual and semi-automated harness assembly, connector crimping, continuity testing, and dimensional inspection at manufacturer facilities |
|
Distribution & Logistics |
Dammam and Jeddah-based automotive parts distributors, bonded warehouses, and dealer logistics networks serving Saudi OEM and aftermarket demand |
|
OEM Integration & Installation |
Automotive assembly plants and authorised service centres integrating harness systems into new vehicles and performing replacement installations |
|
After-Sales Service |
Authorised dealers, independent repair shops, and harness specialists providing diagnostics, repair, and replacement across the Saudi vehicle parc |
The harness assembly and OEM integration stage is commercially most critical, as Saudi Arabia's IKTVA programme targets increasing in-Kingdom content at these value-adding stages. Companies establishing Saudi assembly operations before IKTVA thresholds escalate create structural competitive advantages in government and fleet procurement tenders.
Technology Landscape in the Saudi Arabia Automotive Wiring Harness Industry
Conventional Copper Wire Harness Technology
Conventional copper wire harnesses remain the dominant technology, providing reliable, cost-effective power and signal distribution across all vehicle types. Technology innovation focuses on reduced conductor cross-sections using higher-conductivity copper alloys, improved insulation materials for space efficiency, and modular connector designs that reduce assembly time and field serviceability complexity.
High-Voltage EV Harness Technology
High-voltage harness systems for EV and HEV applications require orange-sheathed cables rated at 600V or 1000V, high-current terminal designs, and enhanced shielding for battery management and motor drive circuits. Lucid Motors' Saudi manufacturing facility represents the Kingdom's first large-scale HV harness procurement demand, attracting global specialists and creating technology qualification requirements for in-Kingdom suppliers.
Data Transmission and Shielded Wire Technologies
Shielded wire harnesses for CAN bus, LIN, Ethernet, and coaxial applications are growing driven by ADAS sensor proliferation and infotainment system complexity. Automotive Ethernet harnesses supporting 100Mbps to 1Gbps data rates are emerging in premium vehicle segments entering Saudi Arabia, requiring new connector technologies and shielding specifications beyond conventional harness manufacturing capability.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Application |
🔒 |
🔒 |
2025 |
|
Material Type |
🔒 |
🔒 |
2025 |
|
Transmission Type |
🔒 |
🔒 |
2025 |
|
Vehicle Type |
Passenger Cars |
61.4% |
2025 |
|
Category |
General Wires |
38.6% |
2025 |
|
Component |
🔒 |
🔒 |
2025 |
|
Region |
Northern & Central Region |
42.7% |
2025 |

By Vehicle Type
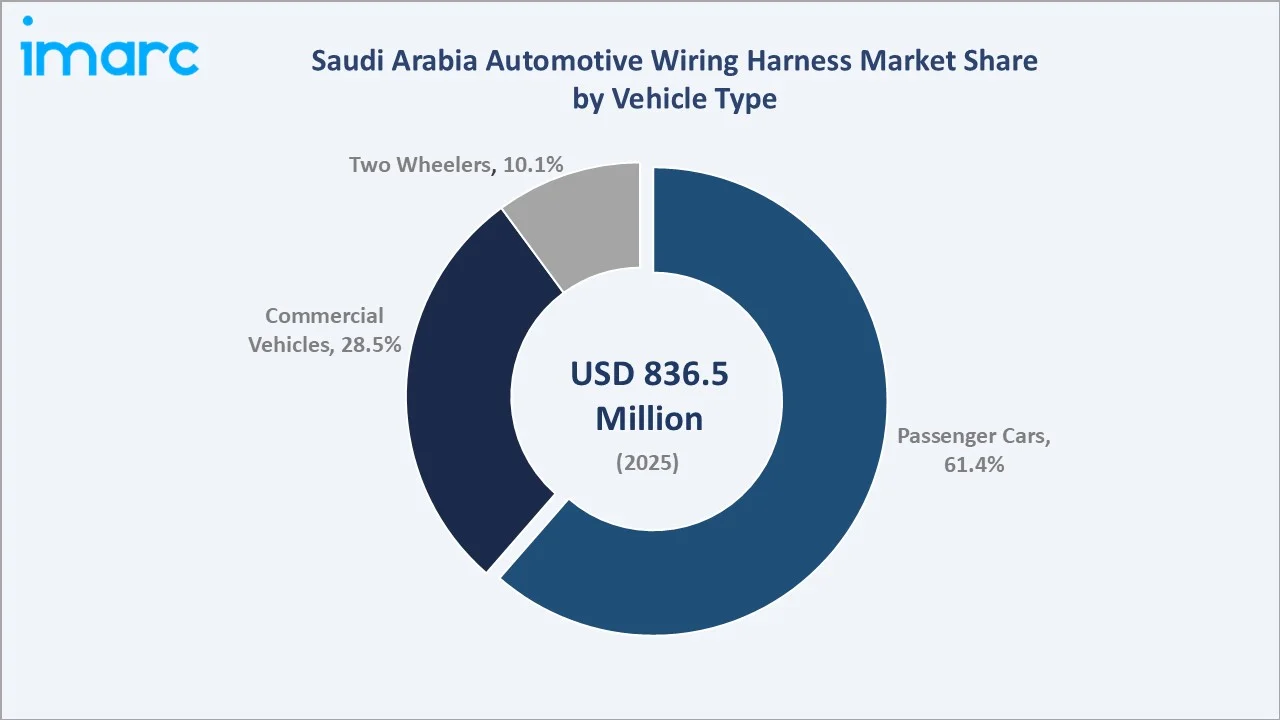
Passenger Cars lead at 61.4% (2025). This segment encompasses Saudi Arabia's largest and fastest-growing vehicle category, from affordable sedans to premium SUVs, each containing between 1,500 and 5,000 metres of wiring depending on specifications. Rising consumer preference for feature-rich vehicles with ADAS, infotainment, and comfort electronics amplifies average harness content and value per passenger car sold in the Kingdom.
To access detailed market analysis, Request Sample
Commercial Vehicles at 28.5% grow through Saudi Arabia's large logistics, construction, and fleet transportation sector, including heavy trucks, buses, and specialised vehicles serving NEOM and giga-project operations. Two Wheelers at 10.1% represent the smallest but consistently stable segment, serving delivery logistics and recreational segments across the Kingdom.
By Category
General Wires lead at 38.6% (2025). This category forms the foundational wiring infrastructure across all vehicle types and harness applications, providing cost-effective power and signal distribution in standard operating temperature environments. General wire's universal compatibility and established supply chains reinforce its dominant share across the breadth of Saudi Arabia's diverse vehicle parc.
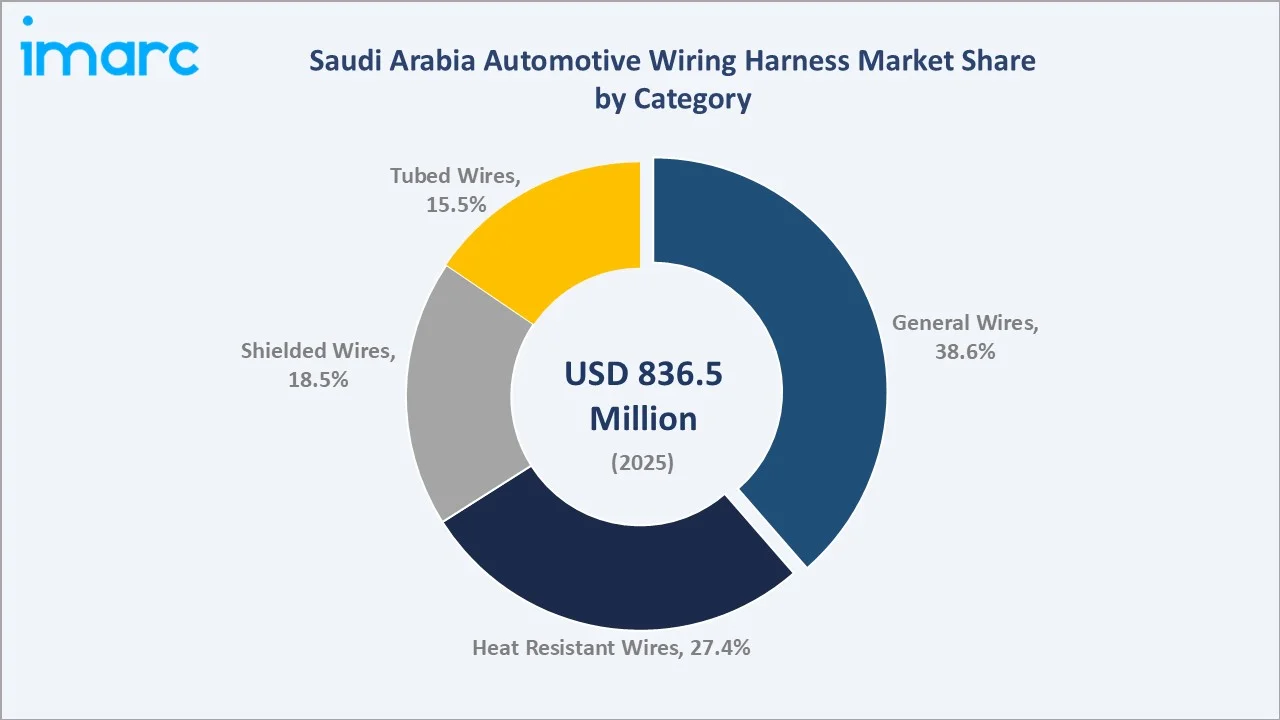
Heat Resistant Wires at 27.4% grow at ~5.1% CAGR through underhood environment intensification. Shielded Wires at 18.5% grow fastest at ~5.8% CAGR through ADAS and connectivity proliferation. Tubed Wires at 15.5% provide protected routing in exposed chassis and underbody applications across commercial vehicle applications.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Automotive Wiring Harness Market Drivers & Characteristics |
|
Northern & Central Region |
42.7% |
Home to Riyadh, the Kingdom's automotive retail, government fleet, and infrastructure hub. Drives the highest concentration of passenger and commercial vehicle harness demand across all categories. |
|
Western Region |
27.5% |
Jeddah and Mecca anchor harness demand through high vehicle density, port-based imports, and growing commercial logistics activity tied to Vision 2030 tourism and Red Sea development. |
|
Eastern Region |
19.6% |
Supported by Dammam's industrial base, oil sector fleet vehicles, and Saudi Aramco-related commercial transportation demand creating consistent harness procurement volumes. |
|
Southern Region |
10.2% |
Smallest share reflecting lower vehicle density; growing gradually through infrastructure investment and cross-border trade route development connecting to GCC and Yemen markets. |
Northern and Central Region's 42.7% dominance reflects Riyadh's position as the Kingdom's largest consumer market, primary government procurement centre, and highest concentration of commercial fleet operators. Western Region's 27.5% reflects Jeddah's status as Saudi Arabia's primary automotive import gateway and second-largest consumer market.
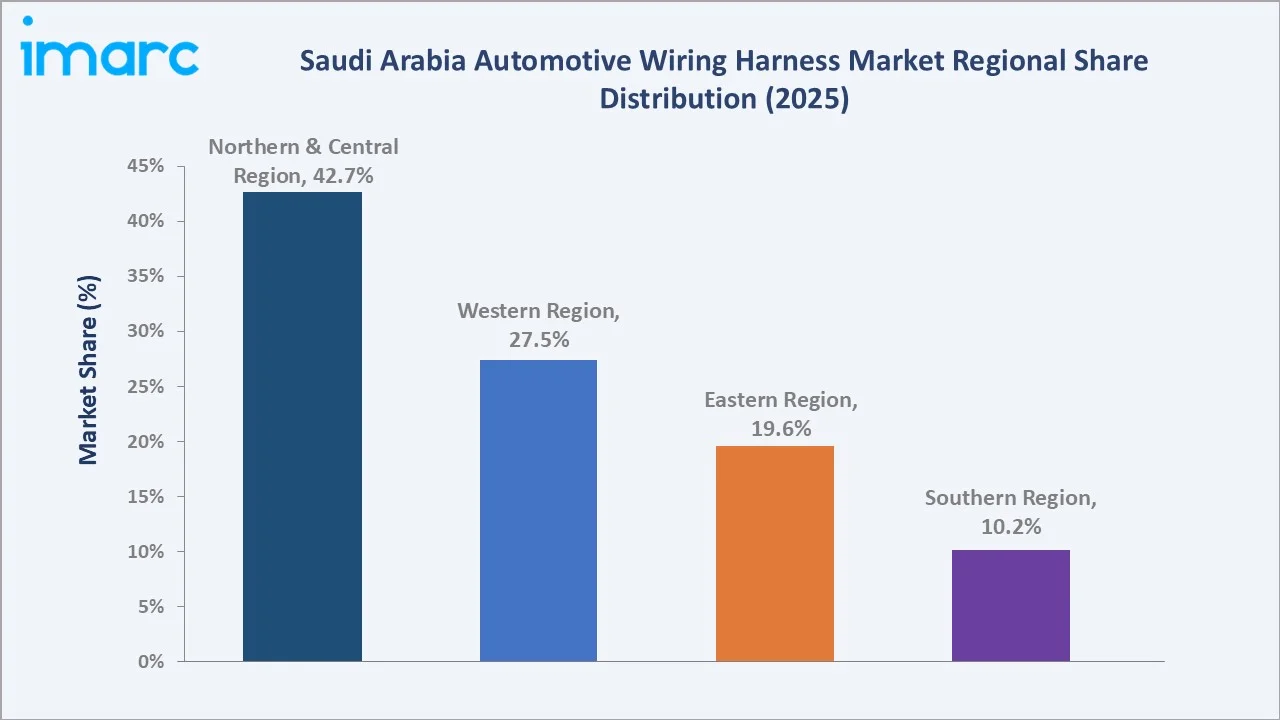
Eastern Region's 19.6% is anchored by the oil and gas sector's extensive vehicle fleet and Dammam's industrial manufacturing zone attracting automotive component distributors. Southern Region's 10.2% is the least commercially developed but growing above regional average as Vision 2030 infrastructure investment reaches Abha and Jizan, stimulating vehicle and fleet procurement growth.
Competitive Landscape
Saudi Arabia automotive wiring harness competitive landscape is dominated by global tier-1 suppliers importing finished harnesses through authorised distributors and local agents, with increasing competitive pressure from IKTVA local content requirements incentivising in-Kingdom assembly investment. Competition is intensifying through EV harness technology differentiation, harness lightweighting capability, and integrated supply chain management.
| Company | Key Offerings | Market Position | Core Strength |
|---|---|---|---|
| Yazaki Corporation | Automotive wiring harnesses, connectors, instruments | Market Leader | World's largest wiring harness manufacturer, supplying major Japanese and global OEMs with broad product portfolio spanning all vehicle types. |
| Aptiv | Smart vehicle architecture, high-voltage harnesses, data connectivity | Market Leader | Leading high-voltage EV harness capability and advanced vehicle architecture solutions, aligned with Saudi Arabia's EV transition demand. |
| Sumitomo Electric Industries, Ltd. | Automotive wiring harnesses, optical fibre cables, copper wire | Strong Challenger | Extensive wiring harness portfolio with proven GCC market presence and strong OEM relationships across Japanese vehicle brands dominant in Saudi Arabia. |
| Motherson | Integrated wiring harness, rear-view mirrors, polymer products | Strong Challenger | Diversified automotive supplier with large-scale wiring harness manufacturing capacity and active Gulf region expansion strategy. |
| Furukawa Electric Co., Ltd. | Automotive wiring harnesses, copper products, optical cables | Innovator | Leading Japanese wiring harness specialist supplying Toyota-group OEMs and key supplier across light vehicle platforms popular in Saudi Arabia. |
| Lear | E-Systems, wiring harnesses, seating systems | Niche Player | Integrated electrical systems and wiring harness manufacturer with growing EV and advanced connectivity harness portfolio for premium vehicle segments. |
Key players include Yazaki Corporation, Aptiv, Sumitomo Electric Industries, Ltd., Motherson, Furukawa Electric Co., Ltd., Lear, and others.
Key Company Profiles
Yazaki Corporation
Yazaki Corporation is the world's largest automotive wiring harness manufacturer, supplying major global OEMs with a comprehensive portfolio of wiring harnesses, connectors, instruments, and charging systems for conventional, hybrid, and electric vehicles.
- Key Products: Automotive wiring harnesses across body, engine, chassis, HVAC, and sensor applications; EV charging systems; automotive connectors and terminals; instrument clusters.
- Strategic Focus: Expanding EV and HEV high-voltage harness capability across global manufacturing locations while targeting localisation partnerships in Vision 2030-priority markets. Yazaki is investing in lightweight harness design using aluminium conductors and optimised routing to reduce vehicle weight and material costs, supporting OEM electrification targets. The company aims to leverage its dominant market position in Japanese-brand vehicle harness supply to consolidate leadership as these OEMs introduce EV models into Saudi Arabia.
Aptiv
Aptiv is a global technology company focused on developing safer, greener, and more connected vehicles, with a specialised portfolio spanning smart vehicle architecture, high-voltage EV harnesses, and advanced data connectivity systems for automotive OEMs worldwide.
- Key Products: High-voltage wiring harnesses for EV and HEV platforms; CentriQ smart vehicle architecture; ADAS sensor wiring and data transmission systems; next-generation vehicle connectivity solutions.
- Strategic Focus: Focusing on smart vehicle architecture and high-voltage harness leadership as the automotive industry's electrification transition accelerates, creating the highest-value harness product segments in the Saudi Arabia market. Aptiv is investing in software-defined vehicle harness architectures that consolidate ECU complexity into zonal configurations, reducing harness weight and cost while increasing functional capability. The company targets partnership with Saudi Arabia's Vision 2030 automotive manufacturing ambitions as a premium technology supplier.
Market Concentration Analysis
Saudi Arabia automotive wiring harness market is moderately concentrated, with the key players collectively commanding an estimated 55-60% of the market by value through their dominant positions in Japanese and premium OEM harness supply. The remaining share is distributed among regional specialists and local distributors.
Market concentration is evolving as IKTVA requirements drive differentiation between companies with Saudi Arabia in-Kingdom manufacturing and those relying on pure import supply. Early IKTVA investors are building structural competitive advantages in government fleet and Vision 2030 project procurement that compound over successive tender cycles, gradually reshaping the competitive balance toward locally established players.
Investment & Growth Opportunities
Highest Growth Segments
Shielded wires (~5.8% CAGR through ADAS and connectivity proliferation), heat resistant wires (~5.1% CAGR through engine electrification), and commercial vehicle (~3.8% CAGR through NEOM fleet demand) represent Saudi Arabia's highest-growth wiring harness investment vectors through 2034.
Emerging Investment Opportunities
Saudi Arabia's IKTVA-compliant in-Kingdom harness assembly is an emerging investment opportunity, with the National Industrial Clusters Development Programme actively seeking harness manufacturing partners for its Eastern Region industrial zones. EV harness assembly offers the highest per-unit investment return given HV harness average selling prices 2-3x conventional vehicle equivalents.
Investment Themes
- In-Kingdom harness assembly establishment under IKTVA framework for Vision 2030 procurement preference: IKTVA-qualifying manufacturing creates systematic bid advantages in government fleet procurement and giga-project vehicle supply contracts. Early entrants establishing Saudi assembly before IKTVA thresholds intensify build long-term competitive moats that pure-import competitors cannot overcome without significant capital investment.
- EV and HEV high-voltage harness capability development aligned with Lucid Motors and future OEM entrants: Saudi Arabia's EV manufacturing ambition creates first-mover harness supply opportunities for companies establishing HV-rated harness capability and OEM qualification in the Kingdom.
Future Market Outlook (2026-2034)
The Saudi Arabia automotive wiring harness market is projected to grow from USD 836.5 Million in 2025 to USD 871.3 Million in 2026, reaching USD 1,207.0 Million by 2034, registering a CAGR of 4.16% during 2026–2034. The market's anchor value of approximately USD 1,025.5 Million in 2030 represents Saudi Arabia's wiring harness industry at a structural inflection, where EV harness localisation begins generating meaningful domestic production value and ADAS-related shielded wire demand reaches commercially material scale.
Three structural forces define Saudi Arabia automotive wiring harness market growth through 2034: Saudi Arabia's vehicle parc expansion sustaining baseline harness replacement and OEM fitment demand; Vision 2030's EV and manufacturing localisation agenda creating premium harness segments with above-market growth rates; and the global automotive industry's electrification and connectivity transition delivering increasing harness value per vehicle across all categories entering the Kingdom.
Research Methodology
Primary Research
Primary research comprised structured interviews with Saudi Arabia automotive industry stakeholders, including Automotive Parts Directors, Fleet Procurement Managers, OEM Service Heads, Supply Chain Executives, and wiring harness distributor representatives operating across Riyadh, Jeddah, and Dammam.
Secondary Research
Secondary research encompassed Saudi General Authority for Statistics vehicle registration data, Saudi Ministry of Industry manufacturing reports, company annual reports, IKTVA programme guidelines, and GCC automotive industry publications. Over 40 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using a vehicle parc-based demand model: Saudi Arabia new vehicle registration volumes by category multiplied by average harness value per vehicle by segment, calibrated against Vision 2030 manufacturing targets and EV adoption programme timelines.
Saudi Arabia Automotive Wiring Harness Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Applications Covered | Body Wiring Harness, Engine Wiring Harness, Chassis Wiring Harness, HVAC Wiring Harness, Sensors Wiring Harness, Others |
| Material Types Covered | Copper, Aluminum, Others |
| Transmission Types Covered | Data Transmission, Electrical Wiring |
| Vehicle Types Covered | Two Wheelers, Passenger Cars, Commercial Vehicles |
| Categories Covered | General Wires, Heat Resistant Wires, Shielded Wires, Tubed Wires |
| Components Covered | Connectors, Wires, Terminals, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Yazaki Corporation, Aptiv, Sumitomo Electric Industries, Ltd., Motherson, Furukawa Electric Co., Ltd., Lear, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia automotive wiring harness market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia automotive wiring harness market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia automotive wiring harness industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Automotive Wiring Harness Market Report
Saudi Arabia automotive wiring harness market size is estimated at USD 871.3 Million in 2026, driven by rising vehicle sales, Vision 2030 industrial development, and growing demand for advanced electrical and connectivity harness systems across passenger and commercial vehicle categories.
Saudi Arabia automotive wiring harness market grows at 4.16% CAGR during 2026-2034, reaching USD 1,207.0 Million by 2034, sustained by EV adoption, ADAS proliferation, NEOM fleet demand, and increasing harness content per vehicle across all segments.
Passenger Cars lead at 61.4% through Saudi Arabia's dominant consumer vehicle market, driven by rising income, youthful demographics, and increasing demand for feature-rich vehicles with higher average harness content per unit than commercial or two-wheeler categories.
General Wires lead at 38.6% as the foundational wiring category providing standard power and signal distribution across all vehicle types and harness applications, with universal OEM compatibility reinforcing their commercial dominance in the Saudi market.
Northern and Central Region leads at 42.7% through Riyadh's position as the Kingdom's largest automotive retail market, government fleet procurement hub, and highest concentration of commercial vehicle operators generating disproportionate harness demand.
Leading companies include Yazaki Corporation, Aptiv, Sumitomo Electric Industries, Ltd., Motherson, Furukawa Electric Co., Ltd., Lear, and others.
Saudi Arabia automotive wiring harness market is projected to reach approximately USD 1,025.5 Million by 2030, with EV harness adoption scaling through Lucid Motors and new OEM entrants, shielded wire growth accelerating through ADAS proliferation, and IKTVA-driven local assembly investment beginning to generate commercial-scale domestic production value.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade