
Saudi Arabia Entertainment and Amusement Market Size, Share, Trends and Forecast by Type of Entertainment Destination, Source of Revenue, and Region, 2026-2034
Saudi Arabia Entertainment and Amusement Market Size, Share, Trends & Forecast (2026-2034)
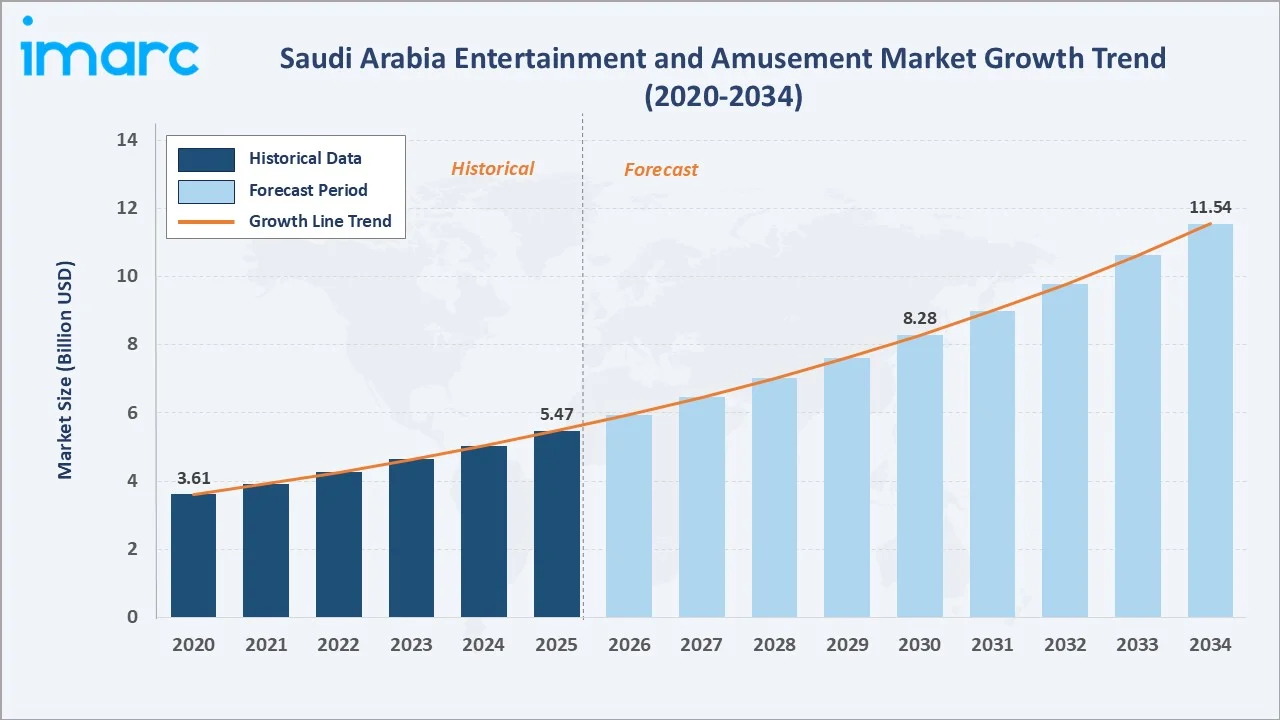
The Saudi Arabia entertainment and amusement market reached USD 5.47 Billion in 2025 and is projected to reach USD 11.54 Billion by 2034, growing at a CAGR of 8.65% during 2026-2034. The market is driven by Vision 2030's Quality of Life Program targeting USD 64 billion in entertainment investment, the lifting of decades-long social restrictions enabling cinemas, concerts, and mixed-gender entertainment, a large and growing youth population seeking leisure experiences, and rising tourist arrivals. Malls lead at 28.6% by entertainment destination type, tickets dominate at 48.7% by source of revenue, and the Northern and Central region commands the largest share at 43.5%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 5.47 Billion |
|
Forecast Market Size (2034) |
USD 11.54 Billion |
|
CAGR (2026-2034) |
8.65% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type of Entertainment Destination |
Malls (28.6%, 2025) |
|
Dominant Source of Revenue |
Tickets (48.7%, 2025) |
|
Leading Region |
Northern and Central Region (43.5%, 2025) |
The Saudi Arabia entertainment and amusement market has grown from USD 3.61 Billion in 2020 to USD 5.47 Billion in 2025, representing one of the most dramatic entertainment sector transformations globally. The market is projected to reach USD 8.28 Billion by 2030 and USD 11.54 Billion by 2034.
To get more information on this market, Request Sample
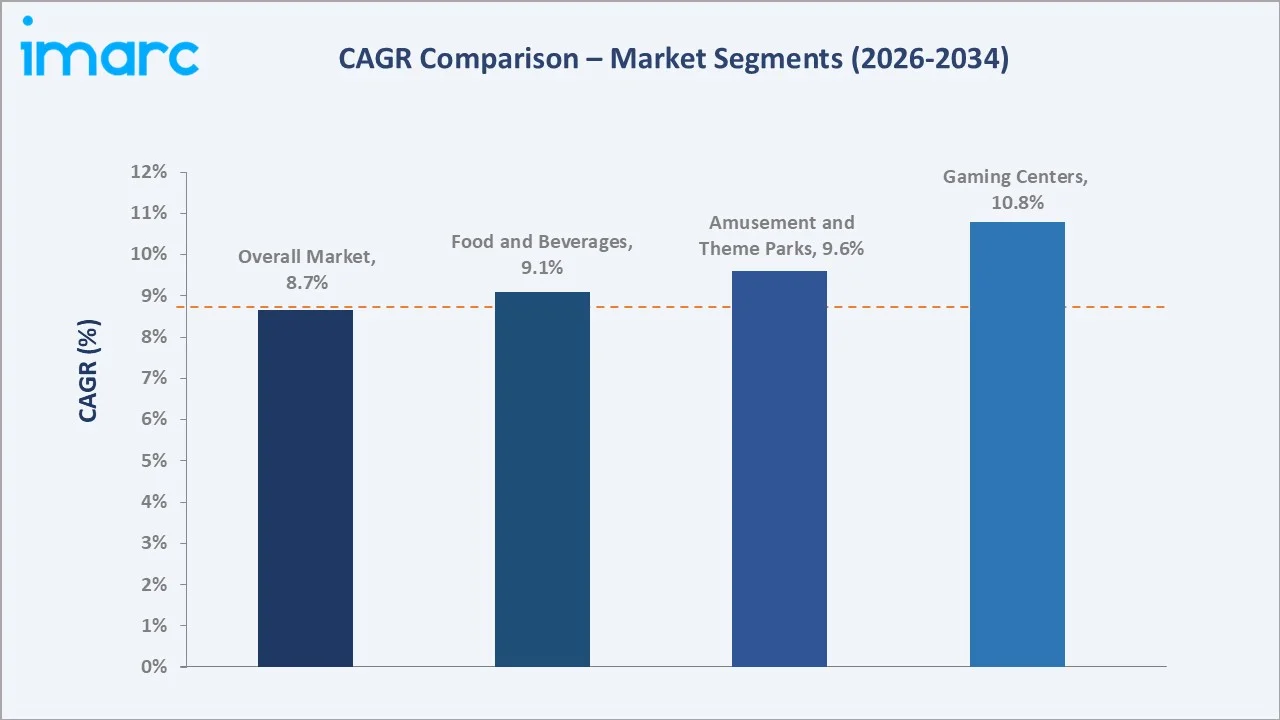
Gaming centers grow at ~10.8% CAGR through esports and youth gaming culture adoption. Amusement and theme parks grow at ~9.6% CAGR through Qiddiya mega-project delivery. Food and beverages grow at ~9.1% CAGR through premium dining and F&B integration in entertainment destinations.
Executive Summary
The Saudi Arabia entertainment and amusement market is undergoing one of the most remarkable transformations of any consumer sector globally, driven by Vision 2030's Quality of Life Program, which has fundamentally redefined what is permissible, possible, and profitable in Saudi leisure and entertainment. Malls lead at 28.6% as integrated entertainment destinations serving diverse demographics. Tickets lead at 48.7% as the primary revenue source across all venue categories. Northern & Central region leads regionally at 43.5%.
Key Market Insights
|
Insight |
Data |
|
Dominant Type of Entertainment Destination |
Malls - 28.6% share (2025) |
|
Dominant Source of Revenue |
Tickets - 48.7% share (2025) |
|
Leading Region |
Northern & Central Region - 43.5% (2025) |
|
Key Market Opportunities |
Theme and amusement park development, family entertainment centers (FECs), gaming and esports, immersive AR/VR attractions, live events, and tourism-integrated leisure destinations. |
Key Analytical Observations Supporting the Above Data:
- Malls at 28.6%: Malls lead entertainment destination share because Saudi Arabia's modern retail malls have evolved into comprehensive entertainment destinations anchored by indoor theme parks, cinema multiplexes, gaming centers, dining precincts, and family entertainment zones.
- Tickets at 48.7%: Ticket revenue dominates because Saudi Arabia's entertainment market has transitioned from zero to a diverse paid admission ecosystem within a decade. Cinema admissions generate consistent ticket revenue from various screens, while the Saudi Season entertainment programs sell tickets across concerts, sporting events, theatrical performances, and experiential attractions.
- Northern & Central Region at 43.5%: The Northern and Central region dominates through Riyadh's status as Saudi Arabia's largest population center and the primary concentration of entertainment infrastructure investments.
Saudi Arabia Entertainment and Amusement Market Overview
The Saudi Arabia entertainment and amusement market encompasses all organized leisure, recreation, and entertainment activities, including indoor and outdoor amusement and theme parks, cinema and theatre venues, mall-based entertainment zones, gaming centers and esports venues, gardens, zoos and nature-based attractions, live events and concerts, sporting events, and immersive and experiential entertainment facilities. Saudi Arabia's National Tourism Strategy targeting 150 million annual visits by 2030 creates additional entertainment demand from international visitors, supplementing the large domestic consumer base of Saudi nationals and residents.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
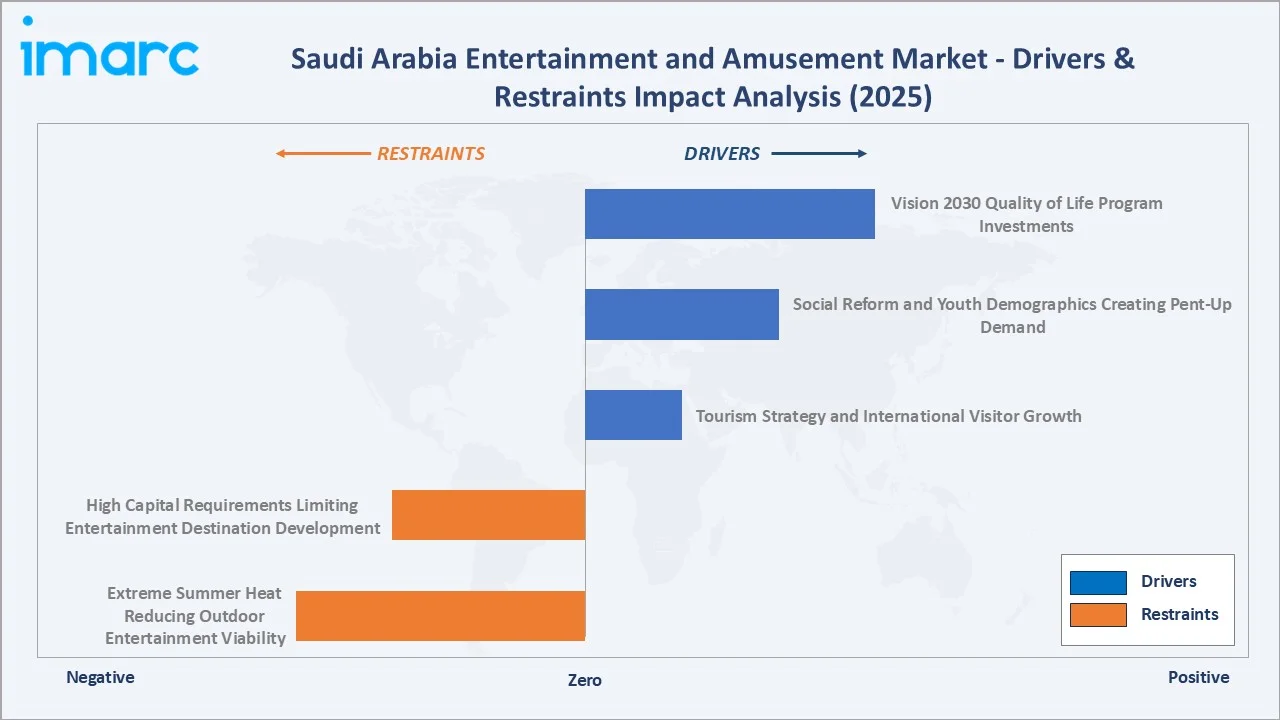
- Vision 2030 Quality of Life Program Investments: Saudi Arabia’s entertainment sector transformation, driven by a USD 64 billion investment pipeline, through a combination of direct PIF investment, foreign company licensing, and private sector development incentives. GEA's entertainment licensing framework has enabled thousands of entertainment businesses to establish operations, while GEA-produced Saudi Season entertainment programs in Riyadh, Jeddah, Al-Ula, and other cities annually attract millions of visitors and generate billions in economic activity.
- Social Reform and Youth Demographics Creating Pent-Up Demand: Saudi Arabia's social reforms have enabled mixed-gender entertainment, concerts, cinemas, sporting events, and diverse leisure activities that were previously unavailable. The release of decades of pent-up entertainment demand from a young population, with 71% under 35, into a rapidly developing entertainment infrastructure has created exceptional market growth velocity. Saudi youth demonstrate high entertainment spending propensity, with leisure and entertainment commanding growing shares of household discretionary budgets.
- Tourism Strategy and International Visitor Growth: Saudi Arabia's National Tourism Strategy targets 150 million annual visits by 2030. International tourist arrivals contribute higher per-visitor entertainment spending than domestic visitors, with tourists seeking distinctive Saudi experiences across historical, cultural, and entertainment venues.
Market Restraints
- High Capital Requirements Limiting Entertainment Destination Development: World-class theme parks and entertainment destinations require high capital investments of several billion dollars, limiting market entry to well-capitalized sovereign wealth fund-backed entities and major international operators. The capital intensity of entertainment infrastructure development constrains the pace of supply addition and creates concentration among a small number of large-scale developers, limiting competitive diversity in the market.
- Extreme Summer Heat Reducing Outdoor Entertainment Viability: Saudi Arabia's summer temperatures regularly exceeding 45°C for several months render outdoor entertainment virtually non-viable from June through September. This seasonal constraint concentrates entertainment demand into indoor air-conditioned venues and limits the operational seasons for outdoor attractions, reducing overall market utilization and affecting the revenue-per-venue economics for outdoor entertainment operators.
Market Opportunities
- Esports and Gaming Center Expansion: Saudi Arabia is aggressively positioning itself as a global esports hub, with SAR 142 billion (USD 38 billion) committed by PIF to advance the gaming sector. Gaming centers targeting Saudi youth, who rank among the world's highest per-capita gaming consumers, represent the fastest-growing entertainment sub-sector. Qiddiya City's gaming district will include the first purpose-built esports arena of its scale, creating international gaming events revenue alongside domestic gaming center expansion.
- International IP Partnerships and Licensed Entertainment Experiences: Saudi Arabia's entertainment market is increasingly attractive to international entertainment IP holders, including major sports organizations for licensing arrangements. The combination of a large, young, high-spending consumer base and government partnership capability through PIF creates uniquely compelling market entry propositions for international entertainment brands seeking Middle East expansion.
Market Challenges
- Talent and Expertise Shortage for Entertainment Operations: Saudi Arabia's rapidly developing entertainment sector faces a structural shortage of experienced entertainment operations professionals including theme park managers, cinema operators, event production specialists, and guest experience designers. Building domestic entertainment operations expertise requires sustained investment in education programs, international mentorship partnerships, and competitive compensation to attract expatriate entertainment professionals.
- Cultural Sensitivity Requirements in Content and Programming: Entertainment operators in Saudi Arabia must navigate content guidelines and cultural sensitivities that require ongoing content screening, programming modifications, and regulatory coordination. While Saudi Arabia's entertainment environment has liberalized significantly, operators still require cultural competency in content curation that adds operational complexity compared to entertainment markets with fewer content guidelines.
Emerging Market Trends
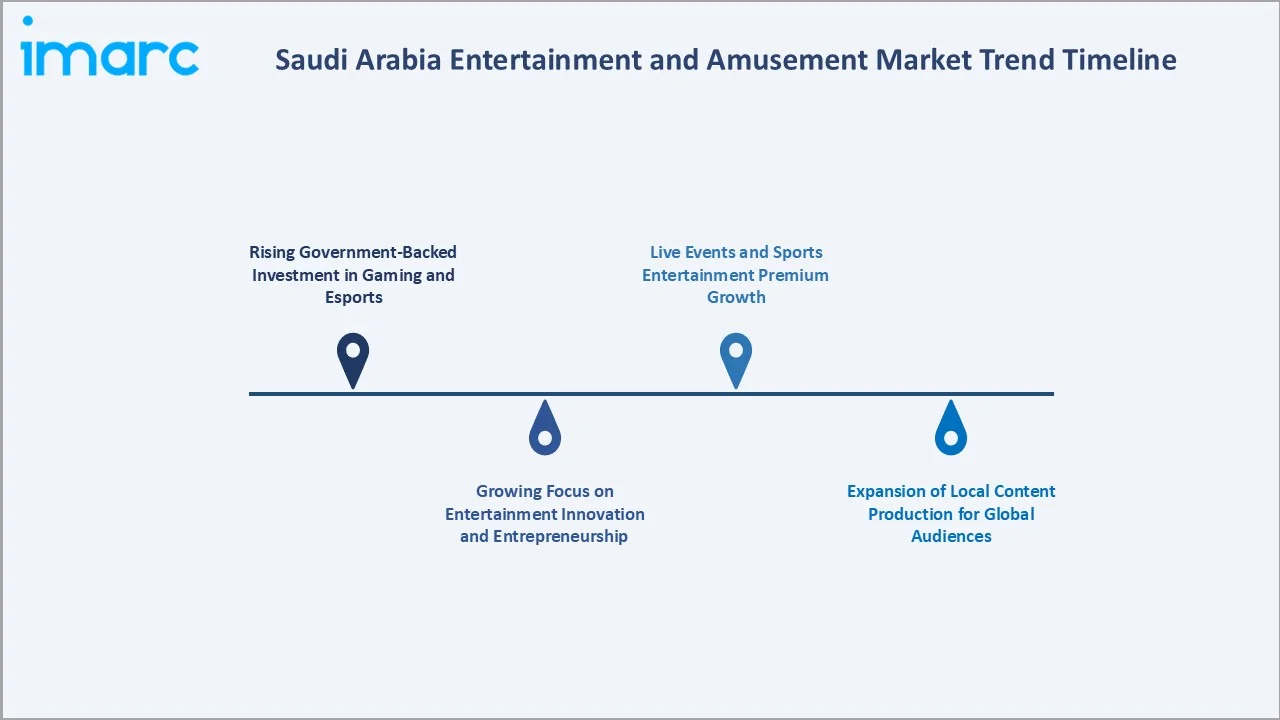
1. Rising Government-Backed Investment in Gaming and Esports
Saudi Arabia is increasingly using dedicated financing programs to accelerate local game development and esports expansion. In August 2026, Saudi Arabia’s National Development Fund approved over USD 112 million in financing under its Esports and Gaming Financing Program by the end of 2025, benefiting 82 entities across the industry. The funding supported the development of more than 127 games while enhancing the capabilities and competitiveness of Saudi companies in the gaming and esports sector. This trend is strengthening domestic capabilities, encouraging new market entrants, and supporting the Kingdom’s ambition to build a globally competitive gaming ecosystem.
2. Growing Focus on Entertainment Innovation and Entrepreneurship
Saudi Arabia is increasingly promoting technology-driven innovation and entrepreneurship within its entertainment ecosystem through dedicated programs, mentorship, and project incubation. In November 2025, Saudi Arabia’s GEA launched the “Entertainment Innovations” program to promote creativity, entrepreneurship, and technology in the entertainment sector. The initiative supports over 100 participants through mentoring, bootcamps, and project challenges aimed at developing practical, market-ready entertainment solutions. This trend is encouraging the development of locally created entertainment concepts and strengthening the sector’s competitiveness and diversification.
3. Live Events and Sports Entertainment Premium Growth
Saudi Arabia's aggressive sports entertainment has positioned the Kingdom as a premier destination for premium live sports entertainment. In July 2026, SURJ Sports Investment, Live Nation, and Oak View Group launched radia, a joint venture focused on supporting Saudi Arabia’s expanding sports infrastructure. The platform will combine local market knowledge with global expertise in venue management, operations, activations, and commercialization across stadiums, arenas, and major sports precincts. These events generate substantial ticket revenue, hospitality spend, and tourism multiplier effects that add to measured entertainment market revenues.
4. Expansion of Local Content Production for Global Audiences
Partnerships between major Saudi brands and domestic production companies are accelerating the creation of locally developed films, series, and entertainment content. In September 2026, Saudi football club Al-Ittihad is expanding into film and television through a long-term partnership with Telfaz 11. The collaboration will develop films, series, and other entertainment content targeting audiences in Saudi Arabia, regional markets, and globally. This trend supports Saudi Arabia’s emergence as a regional content-production hub while increasing the international reach of Saudi-origin intellectual property.
Industry Value Chain Analysis
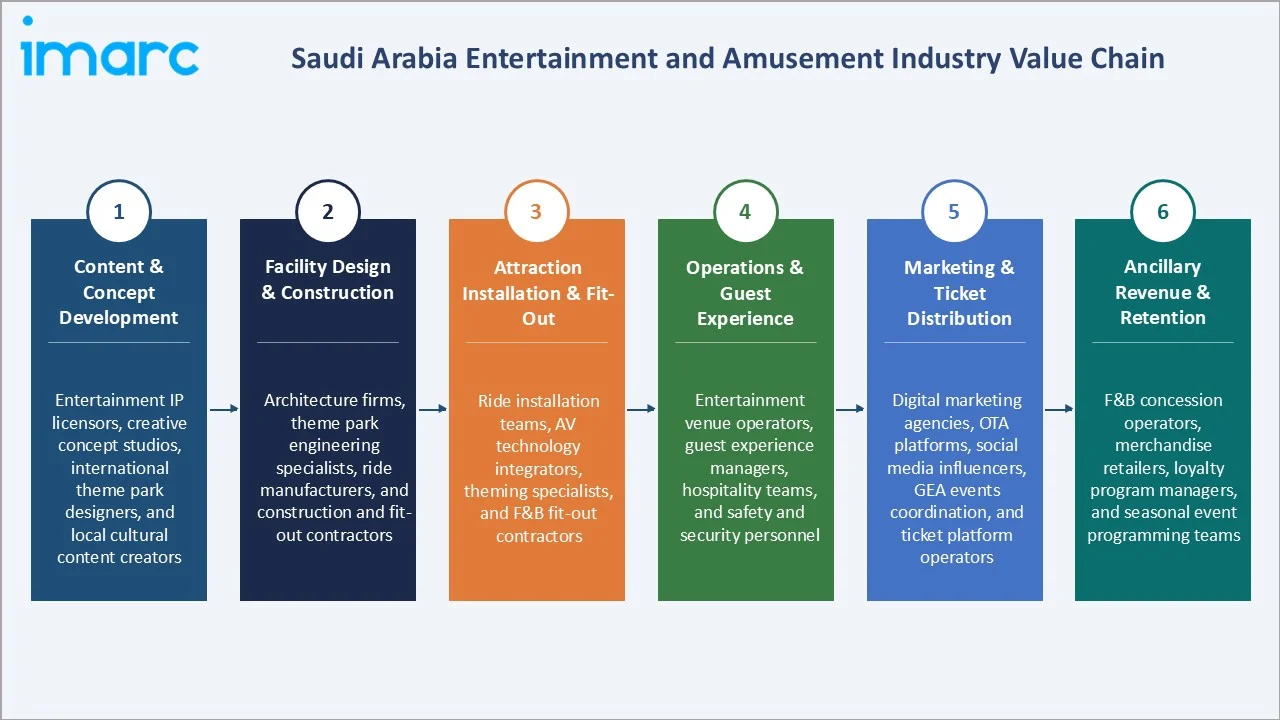
The Saudi Arabia entertainment and amusement value chain integrates content and concept development, facility design and construction, attraction installation and fit-out, operations and guest experience delivery, marketing and ticket distribution, and ancillary revenue generation and guest retention across all entertainment destination categories.
|
Stage |
Key Participants |
|
Content & Concept Development |
Entertainment IP licensors, creative concept studios, international theme park designers, and local cultural content creators. |
|
Facility Design & Construction |
Architecture firms, theme park engineering specialists, ride manufacturers, and construction and fit-out contractors. |
|
Attraction Installation & Fit-Out |
Ride installation teams, AV technology integrators, theming specialists, and F&B fit-out contractors. |
|
Operations & Guest Experience |
Entertainment venue operators, guest experience managers, hospitality teams, and safety and security personnel. |
|
Marketing & Ticket Distribution |
Digital marketing agencies, OTA platforms, social media influencers, GEA events coordination, and ticket platform operators. |
|
Ancillary Revenue & Retention |
F&B concession operators, merchandise retailers, loyalty program managers, and seasonal event programming teams. |
Operations and guest experience represent the most critical ongoing value stage in the Saudi Arabia entertainment value chain, as operational excellence directly determines repeat visitation rates, per-capita spending, and brand advocacy in a social media-active Saudi consumer market. Entertainment operators that deliver consistently outstanding guest experiences, leveraging well-trained local Saudi hospitality staff, innovative seasonal programming, and personalised digital engagement, achieve significantly higher annual visitation frequency and ancillary spend per visitor than those competing solely on attractions and infrastructure.
Technology Landscape in the Saudi Arabia Entertainment Industry
Digital Ticketing and Experience Personalization
Saudi Arabia's entertainment sector is rapidly adopting digital ticketing platforms, mobile admission systems, and AI-powered experience personalization that enhance guest convenience and operator revenue management. Ticketing platforms integrated with Saudi nationals' digital identity system enable seamless pre-booked admission, dynamic pricing, and post-visit loyalty engagement. Major operators utilize sophisticated digital ticketing infrastructure that collects rich visitor data, enabling personalized marketing and upsell optimization across food and beverage, merchandise, and premium experiences.
Immersive Technology and Theme Park Innovation
State-of-the-art ride technology, including multi-dimensional dark rides, ultra-high-speed rollercoasters, water coasters, and AR/VR hybrid attractions, is being specified for Saudi Arabia's new theme park developments. Projection mapping, holographic entertainment, and AI-powered interactive storytelling are being integrated into Saudi entertainment destinations to create differentiated experiences beyond what visiting international theme parks can offer.
Esports and Gaming Technology Infrastructure
Saudi Arabia's gaming and esports sector is investing in world-class tournament infrastructure including LED-arena broadcasting technology, ultra-low latency network infrastructure for competitive gaming, and streaming platforms that distribute Saudi esports content to global audiences. The Qiddiya gaming district's planned esports arena will incorporate broadcast-grade production facilities, player training centers, and spectator experience technology that positions Saudi Arabia to host global esports championships alongside domestic gaming center expansion.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type of Entertainment Destination |
Malls |
28.6% |
2025 |
|
Source of Revenue |
Tickets |
48.7% |
2025 |
|
Region |
Northern and Central Region |
43.5% |
2025 |

By Type of Entertainment Destination
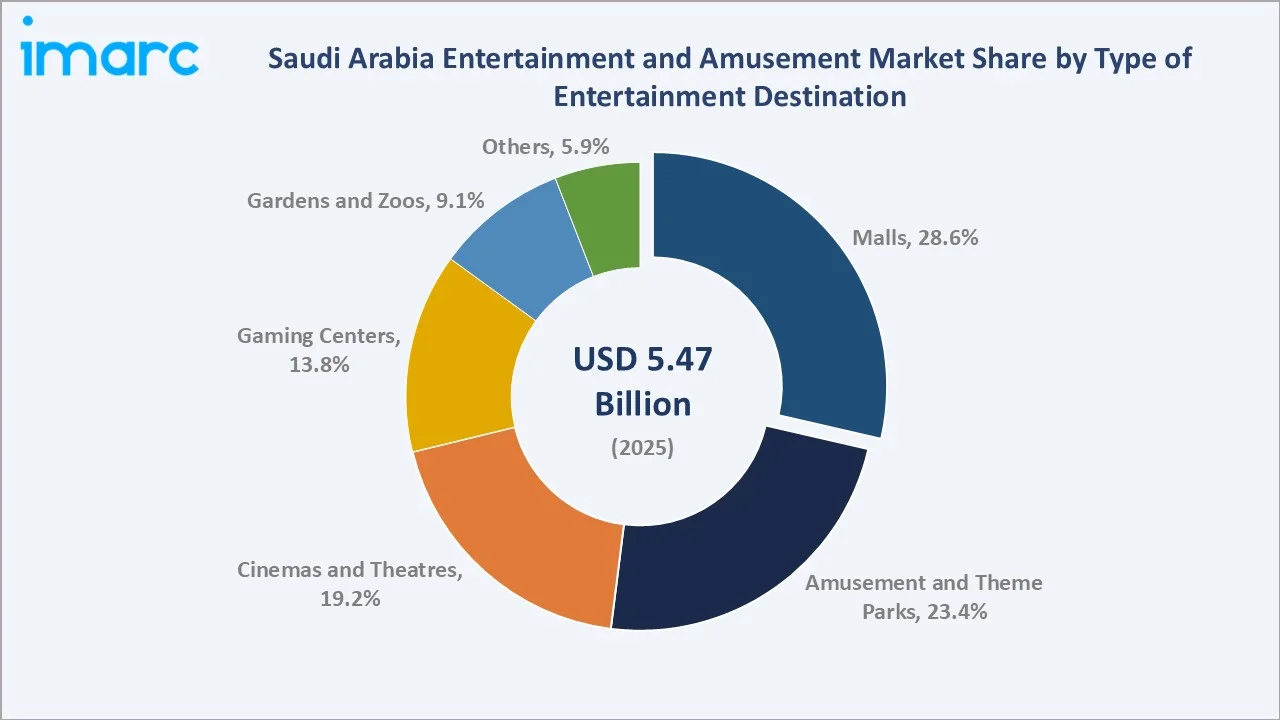
Malls lead at 28.6% (2025), serving as Saudi Arabia's primary integrated family entertainment destinations combining retail, cinema, gaming, F&B, and indoor attractions within air-conditioned environments that address extreme summer heat constraints.
To access detailed market analysis, Request Sample
Amusement and theme parks at 23.4% reflect rapid growth with initial Qiddiya attractions and existing theme parks; this segment will grow fastest through 2034 as Qiddiya's major attractions open. Cinemas and theatres at 19.2% have scaled to various screens across various locations. Gaming centers at 13.8% represent the fastest-growing type at ~10.8% CAGR. Gardens and zoos at 9.1% serve nature-based leisure demand. Others at 5.9% include live events and experiential attractions.
By Source of Revenue
Tickets lead at 48.7% (2025), as paid admission from cinema multiplexes, theme parks, gaming centers, and live events forms the foundation of Saudi Arabia's newly monetized entertainment ecosystem, with Saudi consumers demonstrating strong willingness to pay for previously unavailable experiences.
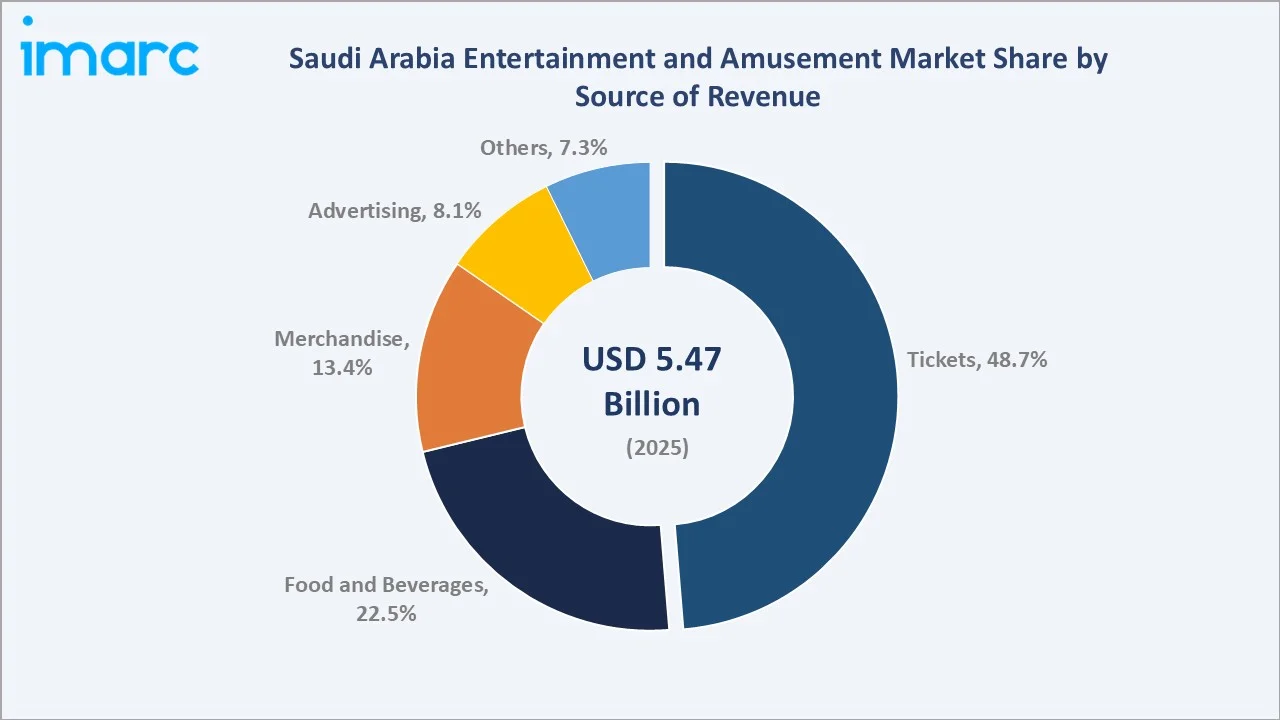
Food and beverages at 22.5% reflect premium dining integration within entertainment venues as F&B becomes an experience extension rather than purely functional. Merchandise at 13.4% grows through IP-licensed theme park retail and event merchandise. Advertising at 8.1% includes in-venue digital advertising and sponsorship. Others at 7.3% includes parking, premium seating, and ancillary services.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Entertainment & Amusement Market Drivers & Characteristics |
|
Northern & Central Region |
43.5% |
Reflecting Riyadh's concentration of entertainment infrastructure and Saudi Season programming that collectively deliver the Kingdom's largest entertainment market by revenue. |
|
Western Region |
24.6% |
Reflecting Jeddah's vibrant entertainment culture, the Red Sea Project's luxury tourism entertainment infrastructure, and Makkah and Madinah's pilgrimage-associated entertainment economy. |
|
Eastern Region |
20.8% |
Reflecting a large expatriate population driving strong cinema and gaming center demand, and mall entertainment zones serving the Eastern Province's high-income oil sector workforce. |
|
Southern Region |
11.1% |
Reflecting the ecotourism entertainment economy, growing tourism infrastructure, and government investment in entertainment facilities serving historically underserved southern provinces. |
The Northern and Central region's 43.5% dominance reflects Riyadh's extraordinary entertainment infrastructure concentration, hosting Saudi Arabia's largest malls, highest cinema screen count, most gaming centers, and the majority of GEA Saudi Season programming, alongside proximity to the Qiddiya entertainment mega-project that will anchor the region's entertainment position through 2034 and beyond. The Western region's 24.6% reflects Jeddah's historically more liberal social environment that has made it a preferred entertainment investment destination alongside the transformative Red Sea Project luxury tourism development.
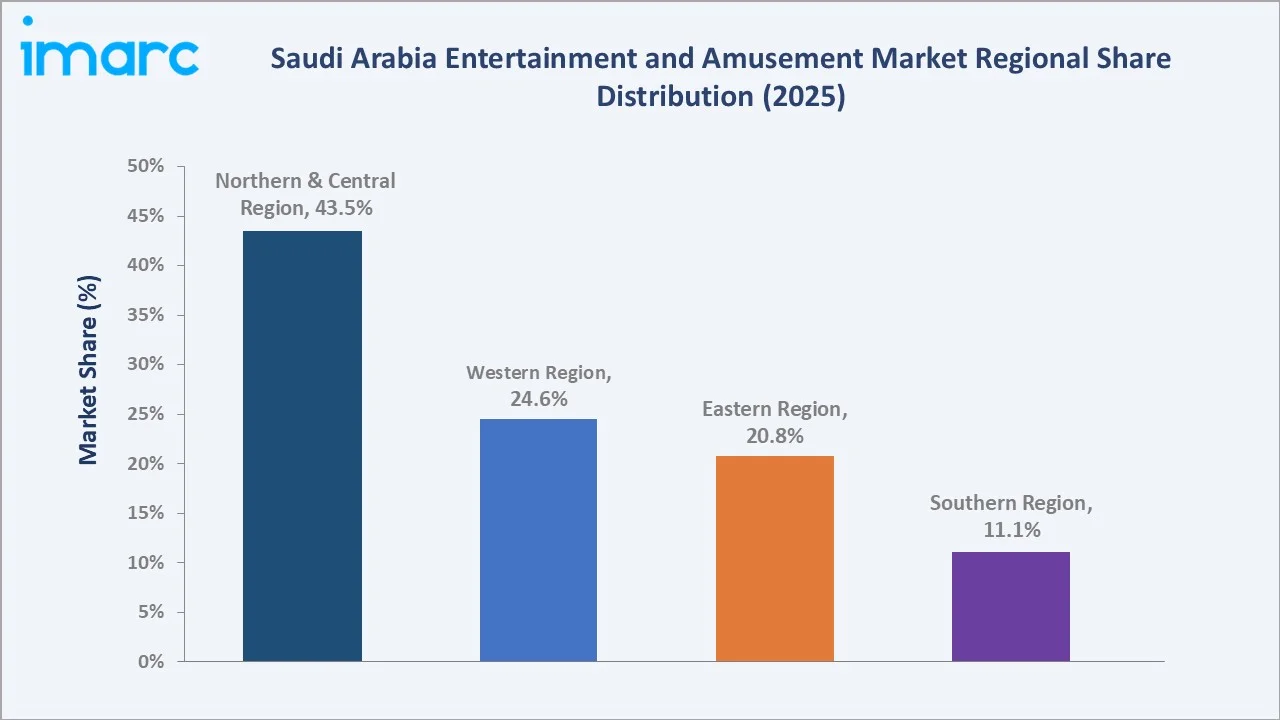
The Eastern region's 20.8% reflects the diverse entertainment demand of large expatriate communities that drives premium cinema, F&B entertainment, and family leisure spending. The Southern region at 11.1% is growing as the mountain tourism economy develops distinctive nature-based entertainment and government investment in southern provincial entertainment infrastructure expands access.
Competitive Landscape
The Saudi Arabia entertainment and amusement market features a unique competitive landscape combining sovereign wealth fund-backed mega-developers, major international entertainment operators, and regional entertainment groups. Competition is shaped by licensing, access to capital for large-scale development, IP partnerships, and operational excellence. The market is characterized by high entry barriers due to capital requirements, enabling a small number of large operators to dominate specific entertainment categories.
|
Company |
Key Offerings |
Market Position |
Core Strength |
|
Qiddiya Investment Company |
QIDDIYA CITY, SEVEN |
Market Leader |
The Qiddiya Investment Company acts as the master developer for Qiddiya City, serving as Saudi Arabia’s primary driver for transforming the domestic entertainment, sports, and arts sectors under Vision 2030. |
|
Majid Al Futtaim |
Magic Planet, Little Explorers, VOX Cinemas |
Market Leader |
Majid Al Futtaim plays a major role in Saudi Arabia's entertainment sector by delivering high-profile cinemas, family entertainment centers, and immersive virtual reality destinations. |
|
Mdlbeast |
MDLBEAST Radio, MixTape |
Established Player |
Mdlbeast serves as the creative heartbeat and primary catalyst in transforming Saudi Arabia’s modern entertainment and music landscape. |
|
BAAN |
Mechanical and Electronic Games |
Innovator |
BAAN (formerly known as the Abdulmohsen Al-Hokair Group) is a major pioneer and national leader in Saudi Arabia's entertainment, amusement, and hospitality sectors. |
|
SELA |
blvdcity, blvdworld, Jeddah Superdome |
Established Player |
Sela is a premier, PIF-owned entertainment, sports, and hospitality company that acts as a primary driving force behind Saudi Arabia's Vision 2030 cultural and leisure transformation. |
Companies across the competitive landscape are investing in premium guest experience differentiation, IP licensing, digital engagement platforms, and talent development programs. The market is expected to see further international operator entries as Saudi Arabia's scale and growth trajectory attract entertainment companies seeking Middle East market positions.
Key Company Profiles
Qiddiya Investment Company
Qiddiya Investment Company is a Saudi Arabian developer focused on creating large-scale entertainment, sports, cultural, and leisure destinations. Within the Saudi Arabia entertainment and amusement market, the company plays a major role in developing integrated attractions, theme parks, recreational facilities, and visitor experiences. Its projects are designed to expand domestic entertainment options, attract international visitors, and support the Kingdom’s broader tourism and quality-of-life objectives.
- Key Offerings: QIDDIYA CITY, SEVEN.
- Strategic Focus: Focuses on developing large-scale, integrated entertainment and amusement destinations that combine theme parks, sports, leisure, and cultural experiences. Its strategy emphasizes destination diversification, global partnerships, and attracting both domestic and international visitors.
Majid Al Futtaim
Majid Al Futtaim is one of the Middle East's most successful retail, entertainment, and hospitality conglomerates, operating in Saudi Arabia through its premium mall portfolio, VOX Cinemas Saudi Arabia and entertainment attractions. MAF's Saudi Arabia strategy centers on delivering comprehensive mall-based family entertainment ecosystems where cinema, dining, retail, and activities combine to maximize dwell time and per-visit spending. The company's Mall of Arabia in Jeddah and City Centre developments anchor its Saudi portfolio, with ongoing expansion into Riyadh and other cities aligned with Saudi Arabia's urbanization and entertainment spending growth.
- Key Offerings: Magic Planet, Little Explorers, VOX Cinemas.
- Strategic Focus: Expanding VOX Cinemas Saudi Arabia screen count through new mall developments, integrating immersive and technology-driven entertainment experiences into mall environments, and developing premium dining and F&B programs that increase per-visitor entertainment spending beyond cinema ticket revenue.
Market Concentration Analysis
The Saudi Arabia entertainment market exhibits moderate concentration at the mega-project development level, with PIF-backed entities commanding the largest development footprints, while cinema and gaming markets show greater competitive diversity among international and regional operators. The unique government-private partnership model, where PIF anchors large-scale entertainment investment while international operators provide IP and operational expertise, creates a market structure unlike typical consumer entertainment markets. Concentration is expected to increase as popular destinations collectively dominate entertainment destination capacity through 2034.
Investment & Growth Opportunities
Highest Growth Segments
Gaming centers and esports venues (~10.8% CAGR), amusement and theme parks (~9.6% CAGR), food and beverages within entertainment (~9.1% CAGR), live events and concerts, and immersive technology entertainment experiences represent the highest-growth investment vectors in the Saudi Arabia entertainment market through 2034.
Investment Themes
- Esports and gaming center development: Building premium gaming and esports facilities that serve Saudi Arabia's leading per-capita gaming consumption creates high-growth revenue opportunities. The convergence of PIF's esports investment, Saudi youth gaming culture, and Qiddiya's planned global esports arena creates a favorable ecosystem for gaming center investment and esports event programming that can generate both domestic revenue and international media revenue.
- Entertainment technology and immersive experience investment: Deploying immersive VR, AR, and projection mapping entertainment within Saudi entertainment destinations addresses Saudi youth demand for cutting-edge experiences while differentiating venues in an increasingly competitive market. Technology-driven experiences have lower physical footprint requirements than traditional attractions, enabling faster rollout and more flexible operational economics.
Future Market Outlook (2026-2034)
The Saudi Arabia entertainment and amusement market is projected to grow from USD 5.47 Billion in 2025 to USD 11.54 Billion by 2034, exhibiting a CAGR of 8.65% during 2026-2034. The market is projected to reach an anchor value of USD 8.28 Billion by 2030, representing the mid-period milestone at which Qiddiya's first major attractions open, popular destinations reach operational scale, and Saudi Arabia hosts Riyadh Expo.
Three structural forces will define the Saudi Arabia entertainment and amusement market through 2034. First, supply delivery of transformational entertainment infrastructure will progressively unlock consumer spending that currently leaks to international entertainment destinations. Second, international tourism growth under the National Tourism Strategy will progressively shift Saudi Arabia's entertainment market from almost entirely domestic to a mixed domestic-international consumer base. Third, demographic forces will sustain Saudi Arabia's exceptional entertainment market growth through the forecast period.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with entertainment venue operators, regulatory officials, entertainment investment developers, experience designers, and consumer behavior analysts. These discussions validated market size estimates, assessed venue type and revenue source dynamics, evaluated competitive positioning, and provided insights into regulatory developments and future market evolution.
Secondary Research
Secondary research encompassed company annual reports and entertainment sector publications, Saudi Tourism Authority visitor statistics, PIF portfolio disclosures and project documentation, major entertainment company investor presentations, Saudi Arabia Vision 2030 Quality of Life Program reports, and industry publications covering Middle East and Saudi Arabia entertainment market developments.
Forecasting Models
Forecasting models incorporated historical entertainment market revenue trends, Vision 2030 entertainment infrastructure delivery schedules, demographic consumer spending projections, tourist arrival growth forecasts, and competitive market share analysis across venue types and revenue sources. Both top-down macro-economic and bottom-up venue-level revenue modeling approaches were cross-validated.
Saudi Arabia Entertainment and Amusement Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types of Entertainment Destination Covered | Cinemas and Theatres, Amusement and Theme Parks, Gardens and Zoos, Malls, Gaming Centers, Others |
| Sources of Revenue Covered | Tickets, Food and Beverages, Merchandise, Advertising, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Qiddiya Investment Company, Majid Al Futtaim, Mdlbeast, BAAN, SELA, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia entertainment and amusement market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia entertainment and amusement market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia entertainment and amusement industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Entertainment and Amusement Market Report
The Saudi Arabia entertainment and amusement market reached USD 5.47 Billion in 2025, driven by Vision 2030's Quality of Life Program, social reform lifting entertainment restrictions, mega-project development, rising youth entertainment spending, and growing international tourism.
The Saudi Arabia entertainment and amusement market is projected to grow at a CAGR of 8.65% during 2026-2034, sustained by tourism growth, gaming and esports expansion, and progressive entertainment spending normalization among Saudi consumers.
The market is projected to reach approximately USD 8.28 Billion by 2030, representing the mid-period milestone at which Qiddiya's first major attractions achieve full operation, the major destination network reaches scale, and Riyadh Expo generates peak international entertainment demand.
Malls lead with a 28.6% share in 2025, serving as Saudi Arabia's primary integrated family entertainment destinations combining cinema, gaming, F&B, and indoor attractions within air-conditioned environments that address the extreme summer heat constraint and serve diverse family demographics.
Tickets dominate with a 48.7% share in 2025, reflecting the rapid monetization of Saudi Arabia's new entertainment ecosystem across cinema admissions, theme park gate admissions, gaming center session fees, and live event tickets for the previously entertainment-restricted consumer market.
The Northern and Central region leads with a 43.5% share in 2025, driven by Riyadh's concentration of entertainment infrastructure, including Saudi Season programming, major cinema multiplexes, and gaming centers serving Saudi Arabia's largest population center.
Key players include Qiddiya Investment Company, Majid Al Futtaim, Mdlbeast, BAAN, and SELA, among others.
The Saudi Arabia entertainment and amusement market is projected to reach USD 11.54 Billion by 2034, driven by infrastructure and event revenue, gaming and esports market maturation, and Saudi Arabia's establishment as a top-tier global entertainment destination.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: sales@imarcgroup.com
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade