
Saudi Arabia Kitchen Hoods Market Size, Share, Trends and Forecast by Product, End User, Distribution Channel, and Region, 2026-2034
Saudi Arabia Kitchen Hoods Market Size, Share, Trends & Forecast (2026-2034)
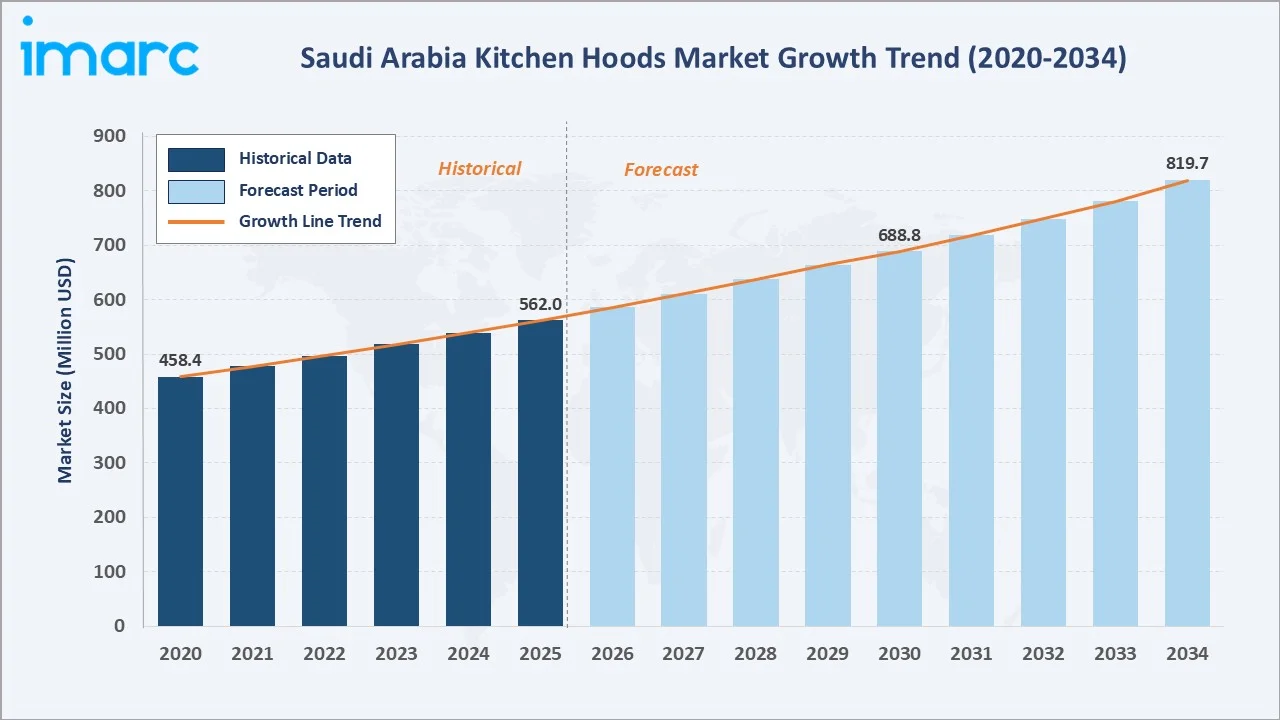
The Saudi Arabia kitchen hoods market reached USD 562.0 Million in 2025 and is projected to reach USD 819.7 Million by 2034, growing at a CAGR of 4.16% during 2026-2034. The market is driven by rapid urbanisation, Vision 2030 residential and hospitality expansion, and rising consumer demand for smart ventilation. Wall Mount leads at 43.8%; Residential dominates at 81.6%; the Northern and Central Region commands 39.4% share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 562.0 Million |
|
Forecast Market Size (2034) |
USD 819.7 Million |
|
CAGR (2026-2034) |
4.16% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product |
Wall Mount (43.8%, 2025) |
|
Dominant End User |
Residential (81.6%, 2025) |
|
Leading Region |
Northern and Central Region (39.4%, 2025) |
The market expanded from USD 458.4 Million in 2020 to USD 562.0 Million in 2025, anchored at USD 688.8 Million in 2030 and forecast to reach USD 819.7 Million by 2034. Vision 2030 mega-project construction, rising middle-class kitchen upgrades, and smart appliance adoption drove consistent market expansion.
To get more information on this market, Request Sample
Wall Mount kitchen hoods grow fastest at ~4.4% CAGR, reflecting consumer preference for aesthetically prominent ventilation solutions in open-plan kitchen designs increasingly prevalent across Saudi Arabia's premium residential construction sector.
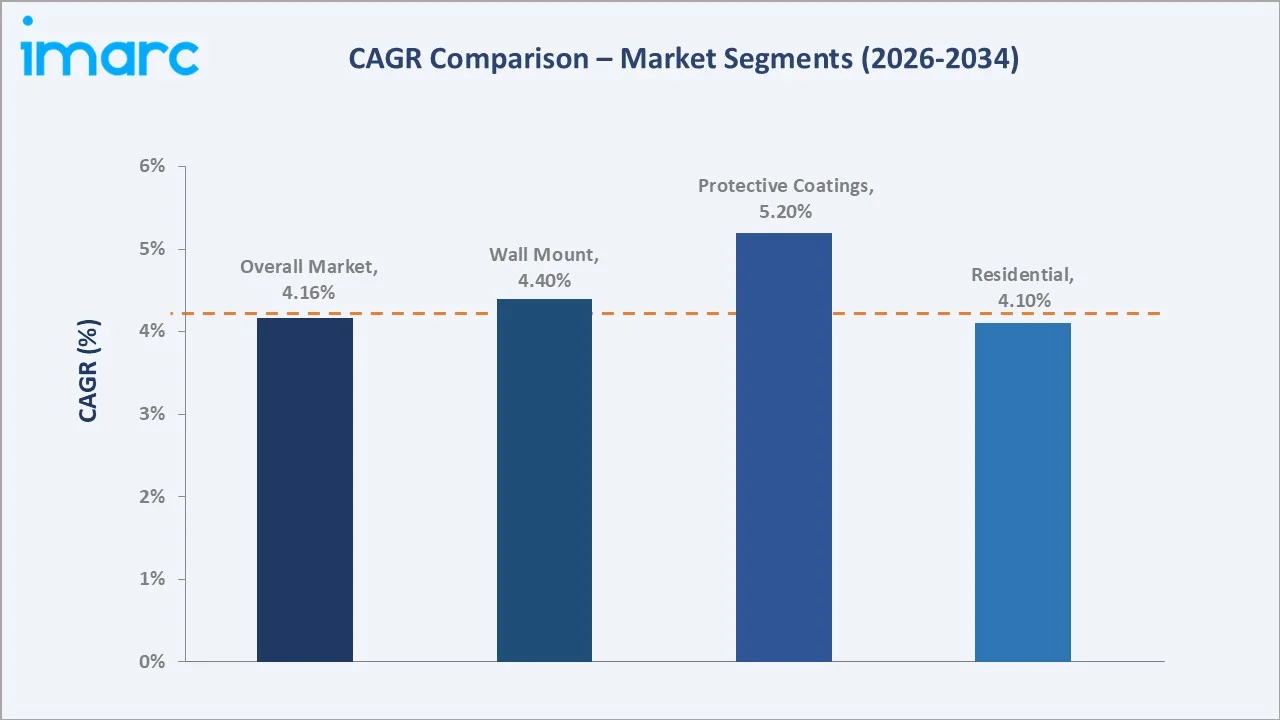
Residential end use grows at ~4.1% CAGR as Vision 2030 housing programmes and rising home ownership aspirations expand the addressable market for kitchen appliances across the Kingdom's rapidly urbanising population base.
Executive Summary
The Saudi Arabia kitchen hoods market reached USD 562.0 Million in 2025, positioning it as a structurally growing consumer appliance market driven by Vision 2030's residential construction momentum and the Kingdom's accelerating hospitality infrastructure expansion. The market is projected to reach USD 819.7 Million by 2034.
Wall Mount technology at 43.8% dominates through its aesthetic appeal and suitability for open-plan kitchen designs proliferating across Saudi Arabia's premium residential sector. The Residential segment at 81.6% leads through sustained government housing programmes and rising household kitchen upgrade expenditure.
Key Market Insights
|
Insight |
Data |
|
Dominant Product |
Wall Mount – 43.8% share (2025) |
|
Dominant End User |
Residential – 81.6% market share (2025) |
|
Leading Region |
Northern and Central Region – 39.4% market share (2025) |
|
Market Opportunity |
Smart hood integration, Vision 2030 residential growth, commercial kitchen expansion, premium product adoption |
Key Analytical Observations Supporting the Above Data:
- Wall Mount at 43.8%: Consumer preference for visually prominent and aesthetically integrated kitchen ventilation in Saudi Arabia's growing premium housing segment is driving wall mount adoption, supported by expanding product design options from global manufacturers and local interior design trends. Each new Vision 2030 residential development contributes incremental wall mount kitchen hood volume.
- Residential at 81.6%: Government-subsidised housing programmes, the Sakani initiative, and Vision 2030's 70% homeownership target are expanding the residential kitchen appliance addressable market significantly. Rising disposable income and increased cooking culture awareness are further accelerating residential kitchen hood adoption across urban Saudi Arabia.
- Northern and Central Region at 39.4%: Riyadh's position as the Kingdom's economic and demographic centre, combined with Vision 2030 giga-project construction and the highest per-capita appliance spending, drives disproportionate kitchen hood demand. The region's concentration of premium residential and commercial developments creates structural volume advantages for kitchen ventilation products.
Saudi Arabia Kitchen Hoods Market Overview
The Saudi Arabia kitchen hoods market encompasses the design, import, distribution, and application of kitchen ventilation appliances across residential, commercial, hospitality, and institutional end-use segments throughout the Kingdom.
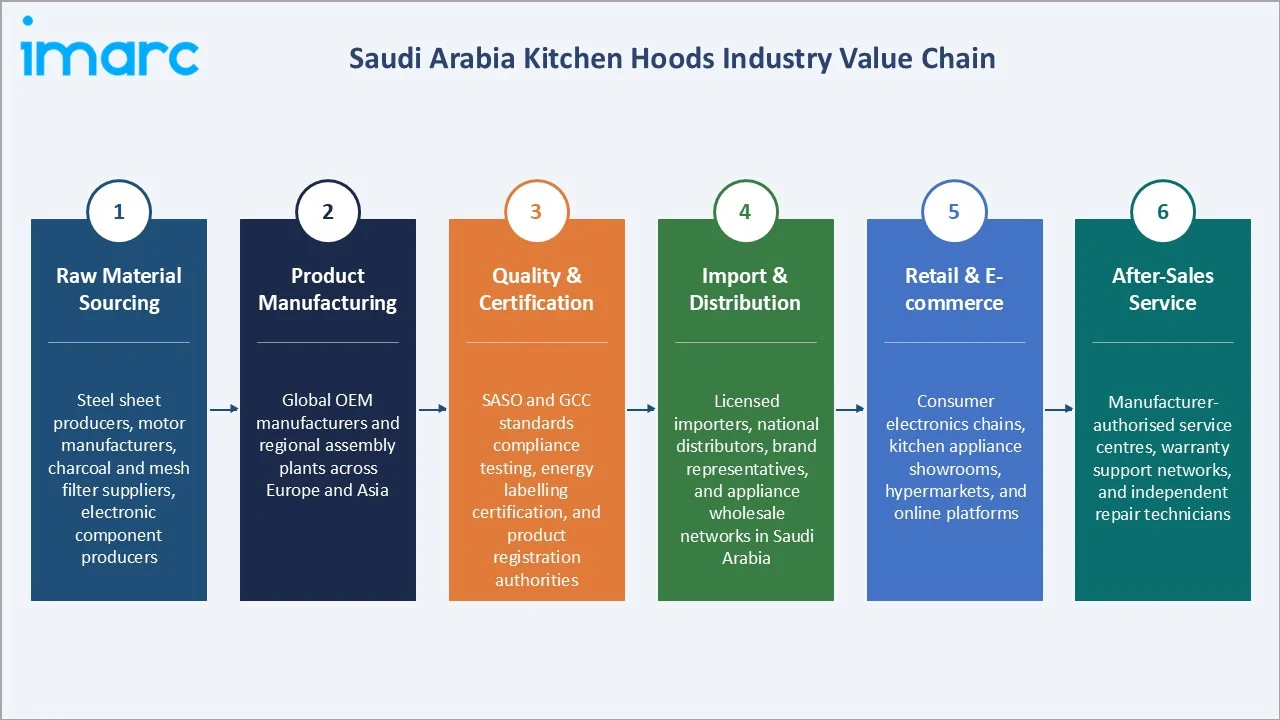
The ecosystem integrates global appliance manufacturers, licensed importers, national distributors, retail electronics chains, and e-commerce platforms. Key macroeconomic drivers include Vision 2030's residential and hospitality construction pipeline, rising household incomes, growing food service sector activity, and increasing consumer awareness of indoor air quality and kitchen hygiene standards.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
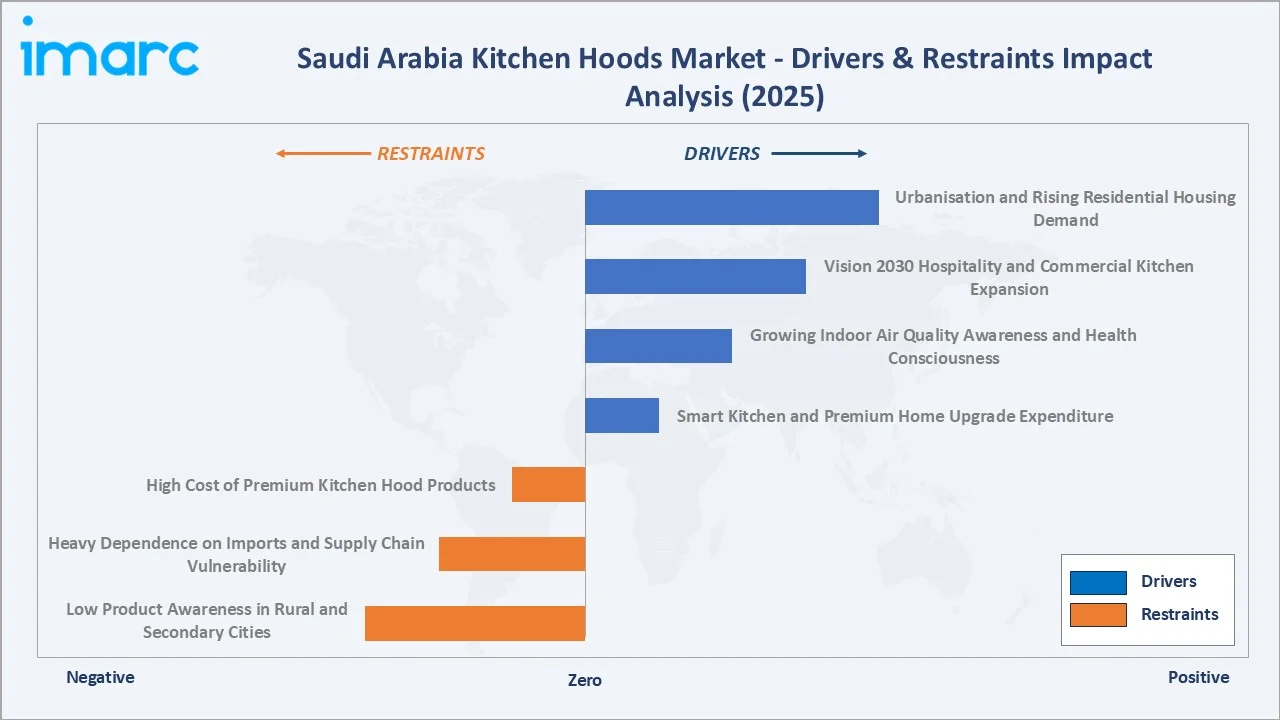
- Urbanisation and Rising Residential Housing Demand: Saudi Arabia's rapid urbanisation and the government's National Housing Programme create a continuously expanding pipeline of newly constructed residential units requiring kitchen appliance fit out. Each new housing unit completion translates to direct kitchen hood demand, with premiumisation trends in Riyadh, Jeddah, and Dammam driving higher per-unit values. Vision 2030's 70% homeownership target generates sustained structural demand through the forecast period, particularly as first-time homeowners invest in quality kitchen appliances across all price segments.
- Vision 2030 Hospitality and Commercial Kitchen Expansion: The Kingdom's ambitious Vision 2030 tourism targets — including 150 million tourists by 2030 — are driving unprecedented hotel, resort, and food service facility construction across Saudi Arabia. Each commercial kitchen installation in the hospitality sector requires high-performance industrial kitchen ventilation systems, creating a structurally growing high-value demand segment. NEOM, the Red Sea Project, Qiddiya, and Diriyah Gate are generating large-scale commercial kitchen ventilation requirements that extend well into the forecast period.
- Growing Indoor Air Quality Awareness and Health Consciousness: Rising consumer awareness of indoor air pollution generated by cooking activities, including oil vapour, combustion gases, and particulate matter, is accelerating kitchen hood adoption beyond its traditional aesthetic role. Saudi consumers are increasingly treating kitchen ventilation as a health necessity rather than a luxury, particularly in enclosed apartment kitchens. The Saudi Energy Efficiency Center's mandatory energy labelling programme is further raising product awareness and directing consumers toward more capable ventilation solutions that provide measurable air quality improvements.
- Smart Kitchen and Premium Home Upgrade Expenditure: Saudi Arabia's rapidly growing upper-middle and affluent consumer class is driving sustained demand for smart kitchen hoods featuring Wi-Fi connectivity, voice control integration, auto-sensing fan speed, and touchscreen interfaces. The Kingdom's high smartphone penetration and technology-forward consumer culture create strong receptivity to connected kitchen appliances, with premium smart hood models commanding higher per-unit values and driving market revenue growth above underlying volume expansion.
Market Restraints
- High Cost of Premium Kitchen Hood Products: International premium kitchen hood brands from Germany, Italy, and Switzerland command price premiums that restrict addressable consumer reach in Saudi Arabia's mid-market and lower-income residential segments. Import duties, local agent margins, and logistics costs further amplify end-consumer prices relative to production cost, creating affordability barriers that limit penetration outside major urban centres and premium housing developments. Price sensitivity in the secondary housing market remains a persistent constraint on premium product adoption.
- Heavy Dependence on Imports and Supply Chain Vulnerability: Saudi Arabia has no significant domestic kitchen hood manufacturing capability, making the market entirely dependent on imported products from Europe, Asia, and North America. Supply chain disruptions, shipping cost volatility, and currency exchange rate fluctuations directly impact product availability and pricing stability. Port delays and logistics bottlenecks periodically constrain product availability in secondary cities, limiting sales velocity and customer satisfaction in regions outside major distribution hubs.
- Low Product Awareness in Rural and Secondary Cities: Kitchen hood adoption rates remain significantly lower in Saudi Arabia's secondary urban centres and rural populations, where traditional open kitchen designs, cooking habits, and limited retail distribution constrain market penetration. The absence of specialist kitchen appliance retailers in smaller cities and insufficient after-sales service networks create both awareness deficits and purchase confidence barriers that slow market development outside the Kingdom's major metropolitan areas.
Market Opportunities
- Smart Home Integration and IoT-Enabled Kitchen Ventilation: Growing consumer demand for integrated smart home ecosystems creates significant product development and premium pricing opportunities for kitchen hood manufacturers incorporating advanced sensor technology, air quality monitoring, automated operation, and seamless integration with popular smart home platforms including Google Home and Amazon Alexa. First movers in smart kitchen ventilation stand to capture disproportionate premium segment share.
- Commercial Kitchen Expansion in Hotels and Restaurants: The Kingdom's expanding food service and hospitality sector, accelerated by Vision 2030's tourism targets and the proliferation of international restaurant chains entering the Saudi market, creates a structurally growing high-volume commercial kitchen ventilation demand pool that complements the established residential segment and provides diversification against cyclical housing construction activity.
Market Challenges
- After-Sales Service Network Coverage: Building reliable after-sales service infrastructure capable of servicing complex kitchen ventilation systems across Saudi Arabia's geographically dispersed population remains a persistent challenge for international brands. Insufficient authorised service centres in secondary cities creates consumer concerns about product support that inhibit premium purchase decisions, particularly for technologically sophisticated smart hood models requiring specialised maintenance.
- Competition from Low-Cost Asian Imports: The proliferation of low-cost kitchen hood products from Chinese and South East Asian manufacturers entering the Saudi market through online platforms and grey market channels creates intense price pressure that compresses margins for established premium brands and local distributors. These products often do not meet SASO performance standards but gain market share among price-sensitive consumers through aggressive online pricing.
Emerging Market Trends
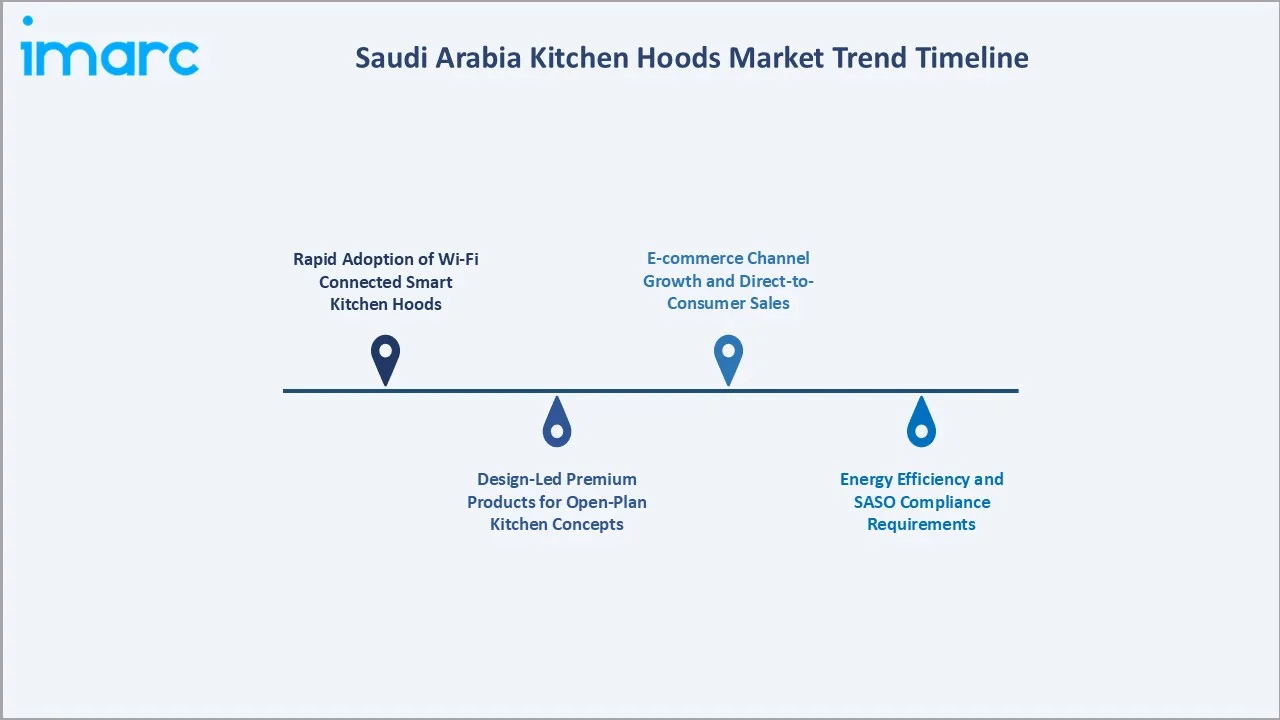
1. Rapid Adoption of Wi-Fi Connected Smart Kitchen Hoods
Saudi Arabia's high smartphone adoption rate and technology-forward consumer culture are accelerating smart kitchen hood uptake. Models offering app-controlled fan speed, real-time air quality monitoring, and voice assistant integration are gaining strong traction in premium residential projects, particularly in Riyadh's gated communities and high-rise developments.
2. Design-Led Premium Products for Open-Plan Kitchen Concepts
The architectural shift toward open-plan kitchen-living spaces in Saudi Arabia's premium residential market is driving demand for decorative island hoods and design-statement wall hoods that function as aesthetic focal points. Italian and German designer kitchen hood brands are gaining market share in this premium design-conscious segment.
3. Energy Efficiency and SASO Compliance Requirements
The Saudi Energy Efficiency Center's appliance labelling framework and evolving SASO standards are directing consumer purchasing toward energy-efficient kitchen hoods with higher airflow efficiency ratings. Manufacturers are investing in low-noise, high-efficiency motor technology to meet regulatory requirements and justify premium pricing.
4. E-commerce Channel Growth and Direct-to-Consumer Sales
Online kitchen appliance purchasing is growing rapidly in Saudi Arabia through platforms including Amazon.sa, Noon, and brand direct e-commerce sites. Consumers increasingly research and purchase kitchen hoods online, enabling international brands to access Saudi consumers without establishing physical retail networks and reducing distributor dependency.
Industry Value Chain Analysis
The Saudi Arabia kitchen hoods value chain integrates global component manufacturing, OEM product assembly, international shipping and customs clearance, licensed distributor networks, retail and e-commerce channels, and post-sale service infrastructure. The commercial structure is evolving toward direct brand e-commerce and project specification channels.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Steel sheet producers, motor manufacturers, charcoal and mesh filter suppliers, electronic component producers |
|
Product Manufacturing |
Global OEM manufacturers and regional assembly plants across Europe and Asia |
|
Quality & Certification |
SASO and GCC standards compliance testing, energy labelling certification, product registration authorities |
|
Import & Distribution |
Licensed importers, national distributors, brand representatives, and appliance wholesale networks in Saudi Arabia |
|
Retail & E-commerce |
Consumer electronics chains, kitchen appliance showrooms, hypermarkets, and online platforms |
|
After-Sales Service |
Manufacturer-authorised service centres, warranty support networks, and independent repair technicians |
The import and distribution tier carries the highest commercial risk given Saudi Arabia's dependence on international supply chains. The retail and e-commerce tier is experiencing the fastest structural transformation as established appliance retailers expand digital capabilities and international brands develop direct consumer engagement.
Technology Landscape in the Saudi Arabia Kitchen Hoods Industry
Ducted Kitchen Hood Technology
Ducted kitchen hoods represent the performance-leading technology segment, directing extracted air, grease, and cooking vapour through dedicated ductwork to the exterior. This technology dominates in Saudi Arabia's newly constructed residential and commercial kitchens where ductwork installation is planned into the building design from the outset.
Ductless Kitchen Hood Technology
Ductless recirculating hoods filter extracted air through charcoal and grease filters before returning it to the kitchen, enabling installation in apartments and retrofitted kitchens where exterior ductwork is impractical. This technology is gaining traction in Saudi Arabia's growing high-rise apartment segment where duct installation is structurally constrained.
Smart and Auto-Sensing Kitchen Hood Technology
Smart kitchen hoods incorporating auto-sensing fan speed control, integrated cooking sensors, and IoT connectivity are the fastest-growing technology sub-segment. These products command premium pricing and are driving revenue growth faster than volume growth as Saudi consumers in higher-income brackets invest in connected kitchen solutions.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product |
Wall Mount |
43.8% |
2025 |
|
End User |
Residential |
81.6% |
2025 |
|
Distribution Channel |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
39.4% |
2025 |

By Product
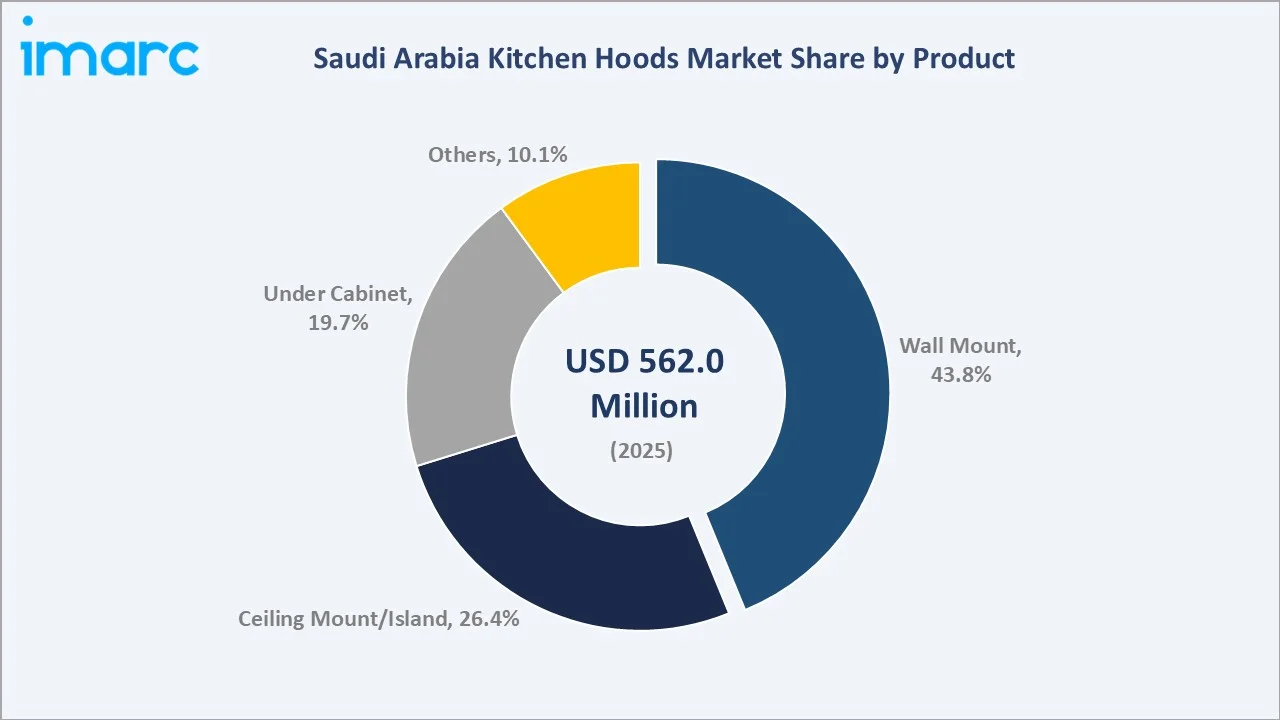
Wall Mount kitchen hoods lead at 43.8% in 2025, capturing the dominant share of Saudi Arabia's residential and commercial kitchen installations where wall-mounted configurations align with standard kitchen design layouts and offer the widest product selection across all price points.
To access detailed market analysis, Request Sample
Ceiling Mount/Island hoods at 26.4% capture premium open-plan kitchen installations growing in Saudi Arabia's luxury residential sector. Under Cabinet hoods at 19.7% serve the apartment and retrofitted kitchen segment. Others at 10.1% encompass downdraft and integrated cooktop ventilation systems gaining traction in premium kitchen designs.
By End User
Residential end use leads at 81.6% through the largest installed base of kitchen appliance demand, driven by Saudi Arabia's expanding housing stock, rising homeownership rates under Vision 2030, and growing consumer investment in kitchen quality across all residential segments from entry-level to ultra-premium.
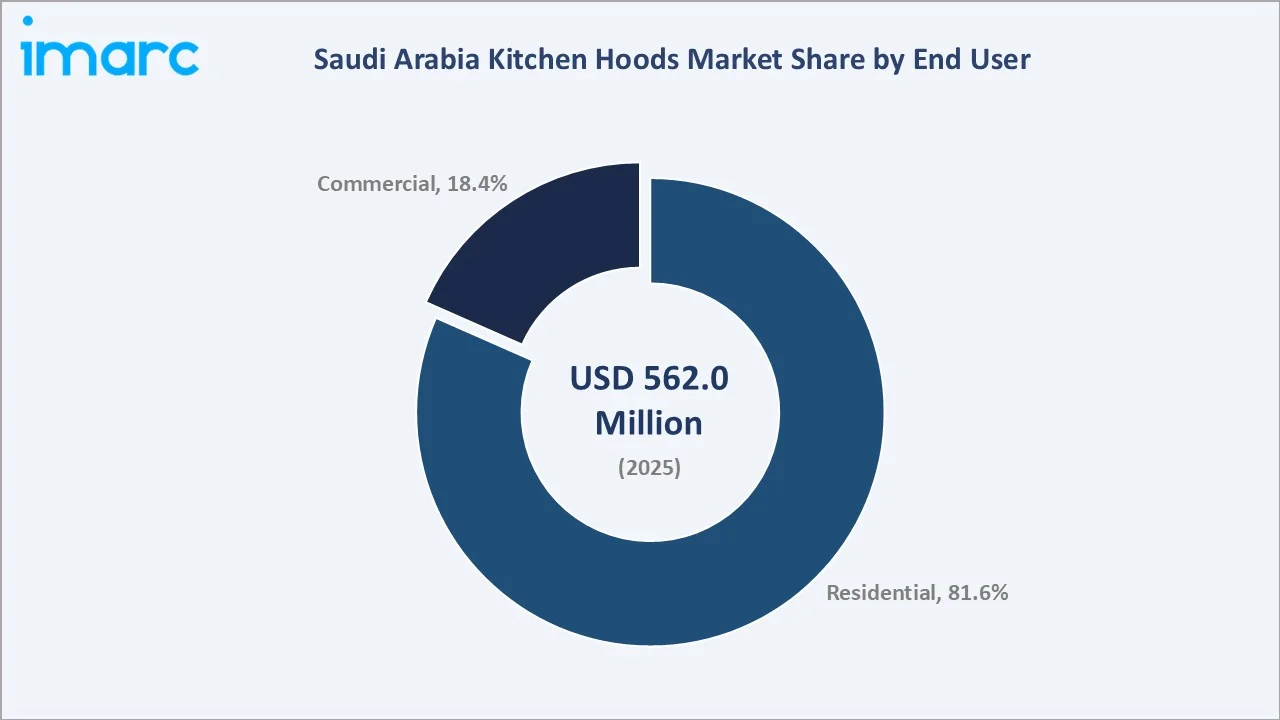
Commercial end use at 18.4% captures hotel, restaurant, institutional kitchen, and food service facility demand, growing at an above-market rate driven by Saudi Arabia's expanding hospitality and food service sector under Vision 2030's ambitious tourism and entertainment targets. Commercial kitchens require higher-specification industrial ventilation systems.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
Northern and Central Region |
39.4% |
Driven by Riyadh's urban expansion, Vision 2030 mega-projects, high disposable income, and concentrated residential and commercial construction activity creating strong kitchen appliance demand |
|
Western Region |
30.6% |
Driven by Jeddah's large residential population, Makkah and Madinah hospitality infrastructure growth, and expanding commercial kitchen requirements across hotel and restaurant sectors |
|
Eastern Region |
18.5% |
Driven by Dammam and Al Khobar's high-income expatriate and professional population, industrial housing demand, and commercial catering operations in the oil and gas sector |
|
Southern Region |
11.5% |
Emerging market with growing residential construction under government housing programmes and increasing awareness of kitchen ventilation among a rising urban population base |
The Northern and Central Region at 39.4% leads through Riyadh's urban expansion, Vision 2030 mega-project construction, and the highest per-capita appliance expenditure in the Kingdom. The Western Region at 30.6% benefits from Jeddah's large residential population and Makkah and Madinah's hospitality infrastructure growth.
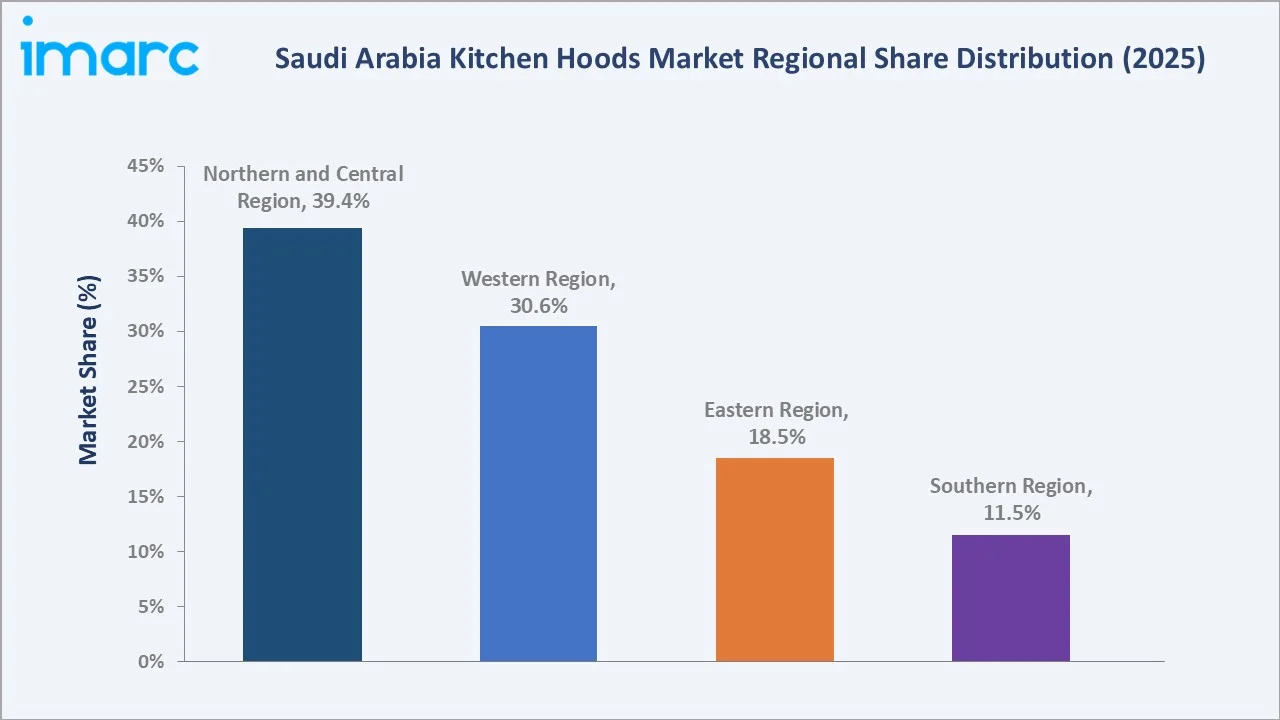
The Eastern Region at 18.5% is driven by Dammam and Al Khobar's high-income professional and expatriate population base and robust commercial kitchen demand from the oil and gas sector. The Southern Region at 11.5% represents a developing market with growing residential construction activity supported by government regional development investment.
Competitive Landscape
The Saudi Arabia kitchen hoods competitive landscape is moderately concentrated at the premium tier, with European manufacturers holding strong positions in the premium and mid-market segments. At the same time, some key players dominate ultra-premium project specification channels.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Electrolux |
Cooker Hoods |
Market Leader |
Broad multi-brand portfolio spanning premium and mass-market kitchen ventilation with strong Saudi retail channel distribution |
| Franke Electrolux Technology and Trademark Ltd. |
Kitchen Hoods, Cooker Hoods |
Niche Player |
Swiss premium kitchen solutions provider leveraging high-end residential project specification in luxury developments |
|
Miele & Cie. KG |
Cooker Hoods |
Niche Player |
German ultra-premium appliance brand with strong positioning in Saudi Arabia's luxury residential and hospitality kitchen segments |
Key players include Electrolux, Franke Technology and Trademark Ltd., Miele & Cie. KG, and others.
Key Company Profiles
Electrolux
Electrolux is a Sweden-based global appliance manufacturer with a comprehensive multi-brand kitchen ventilation portfolio available in Saudi Arabia through its Electrolux and AEG brands, serving both residential and commercial kitchen hood segments through retail and project channels.
- Key Products: Cooker Hoods
- Strategic Focus: Deploying a differentiated dual-brand approach — Electrolux for broad residential coverage and AEG for premium and design-led positioning — to capture kitchen hood demand across multiple Saudi consumer segments simultaneously. Electrolux aims to accelerate commercial kitchen ventilation growth by targeting Saudi Arabia's rapidly expanding hospitality sector through dedicated commercial product ranges and foodservice industry distribution partnerships.
Miele & Cie. KG
Miele & Cie. KG is a Germany-based global leader in premium domestic appliances, headquartered in Gütersloh, serving Saudi Arabia's ultra-premium residential and hospitality kitchen ventilation segment.
- Key Products: Cooker Hoods
- Strategic Focus: Miele targets specification in landmark Vision 2030 luxury developments, high-end villa and penthouse projects, and five-star hospitality kitchens through its Riyadh Experience Center retail platform, Awad Badi Nahas distribution partnership, and growing culinary events programme designed to deepen brand affinity among Saudi Arabia's affluent household decision-makers.
Market Concentration Analysis
The Saudi Arabia kitchen hoods market is moderately concentrated at the premium segment, with the key players collectively accounting for an estimated 40–50% of premium kitchen hood revenue. The mass-market segment is more fragmented, with multiple Asian and European brands competing through retail and e-commerce channels.
Investment & Growth Opportunities
Highest Growth Segments
Smart kitchen hoods (~5–6% CAGR), Ceiling Mount/Island premium products (~4.8% CAGR), commercial kitchen ventilation (~5.2% CAGR from Vision 2030 hospitality expansion), and e-commerce distribution channels represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Vision 2030 mega-project hotel and resort kitchen specification presents the market's highest-value emerging opportunity, with luxury hospitality projects requiring premium commercial ventilation systems at high per-unit values. Early supplier qualification for NEOM, Red Sea Project, and Qiddiya hospitality developments creates durable competitive barriers for established premium kitchen hood brands.
Investment Themes
- E-commerce and direct-to-consumer digital channel investment to capture Saudi Arabia's growing online appliance purchasing behaviour and reach consumers in secondary cities beyond existing physical retail distribution networks.
- Smart kitchen hood product development and IoT integration investment to capture the growing premium segment demand for connected appliances and to position ahead of anticipated SASO energy and smart appliance standards evolution.
Future Market Outlook (2026-2034)
The Saudi Arabia kitchen hoods market is projected to grow from USD 562.0 Million in 2025 to USD 819.7 Million by 2034, delivering a 4.16% CAGR. Vision 2030's residential and hospitality construction pipeline, smart appliance adoption, and the Kingdom's growing commercial food service sector will anchor market growth throughout the forecast horizon.
Three structural forces define market growth through 2034. Vision 2030's residential construction pipeline creates a structurally elevated kitchen appliance demand pool extending well beyond any single project cycle. Smart technology integration drives sustained premiumisation of the product mix toward higher-value connected kitchen hoods commanding above-market per-unit revenue. The Kingdom's expanding hospitality and food service sector creates a growing commercial ventilation demand pool that diversifies market growth drivers beyond residential construction activity.
Research Methodology
Primary Research
Primary research comprised structured interviews with 35+ industry stakeholders (2025), including kitchen appliance importers, retail buyers, kitchen designers, commercial kitchen contractors, and hospitality procurement managers across Saudi Arabia's major demand regions.
Secondary Research
Secondary research encompassed company annual reports, SASO regulatory publications, Saudi Ministry of Housing data, Vision 2030 programme documentation, GCC appliance market databases, and over 45 secondary sources systematically reviewed and cross-referenced.
Forecasting Models
Market revenue forecasts developed using a housing completions-based bottom-up model: (i) Saudi Arabia residential and commercial kitchen construction output; (ii) kitchen hood penetration rate by housing segment; (iii) average selling price by product type; (iv) smart product premiumisation adjustment and commercial segment contribution.
Saudi Arabia Kitchen Hoods Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Products Covered | Wall Mount, Ceiling Mount/Island, Under Cabinet, Others |
| End Users Covered | Residential, Commercial |
| Distribution Channels Covered | Offline, Online |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Electrolux, Franke Electrolux Technology and Trademark Ltd., Miele & Cie. KG, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia kitchen hoods market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia kitchen hoods market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia kitchen hoods industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Kitchen Hoods Market Report
The Saudi Arabia kitchen hoods market reached USD 562.0 Million in 2025, driven by Wall Mount products leading at 43.8%, Residential end use dominating at 81.6%, the Northern and Central Region commanding 39.4% through Vision 2030 residential construction, and expanding commercial kitchen demand from the hospitality and food service sectors.
The market grows at a CAGR of 4.16% during 2026-2034, reaching USD 819.7 Million by 2034. This growth reflects Vision 2030 residential construction, smart kitchen hood adoption, hospitality sector expansion, and progressive premiumisation of the product mix toward higher-value connected ventilation appliances.
Wall Mount kitchen hoods lead at 43.8% in 2025, driven by their suitability for Saudi Arabia's standard kitchen layouts, the widest product range and price point selection, and strong aesthetic appeal in the growing open-plan kitchen design segment across both residential and commercial installations.
Residential end use leads at 81.6% in 2025, driven by Vision 2030's residential construction pipeline, the Sakani housing programme expanding homeownership, and rising consumer investment in kitchen quality and indoor air quality across Saudi Arabia's growing urban middle and upper-middle class household base.
The Northern and Central Region leads at 39.4% in 2025, anchored by Riyadh's status as Saudi Arabia's largest residential market, highest per-capita household spending on appliances, and concentrated Vision 2030 residential and commercial construction activity across the greater Riyadh metropolitan area.
Leading companies include Electrolux, Franke Technology and Trademark Ltd., Miele & Cie. KG, and others.
The market is projected to reach approximately USD 688.8 Million by 2030, with smart kitchen hood adoption achieving broader residential penetration, commercial kitchen ventilation expanding through Vision 2030 hospitality projects, and Ceiling Mount/Island hoods capturing growing share in Saudi Arabia's premium residential segment.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade