
Saudi Arabia Liner Hanger System Market Size, Share, Trends and Forecast by Type, Location of Deployment, and Region, 2026-2034
Saudi Arabia Liner Hanger System Market Size, Share, Trends & Forecast (2026-2034)
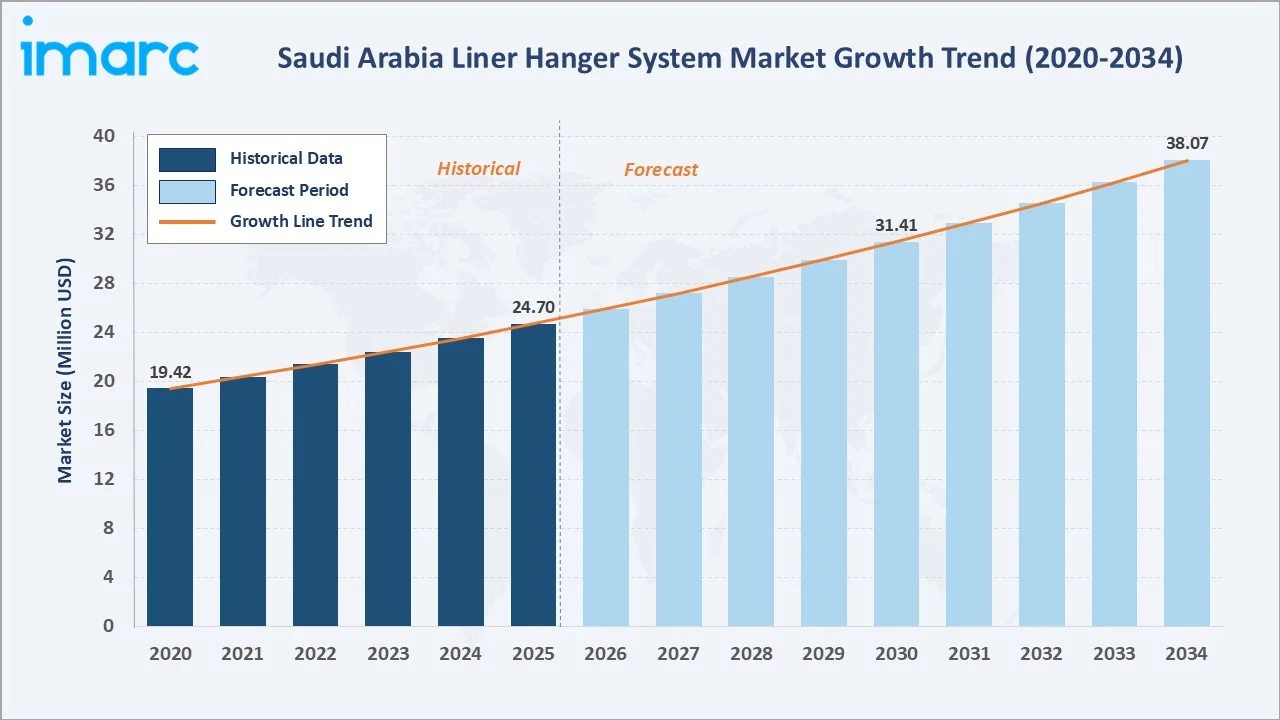
The Saudi Arabia liner hanger system market grew from USD 24.70 Million in 2025 to USD 25.91 Million in 2026 and is projected to reach USD 38.07 Million by 2034, growing at a CAGR of 4.92% during 2026-2034. The market is driven by intensive drilling programmes under Saudi Vision 2030, rising unconventional resource development in the Jafurah basin, and growing demand for advanced wellbore completion technologies across Saudi Aramco's expanding onshore and offshore portfolio.
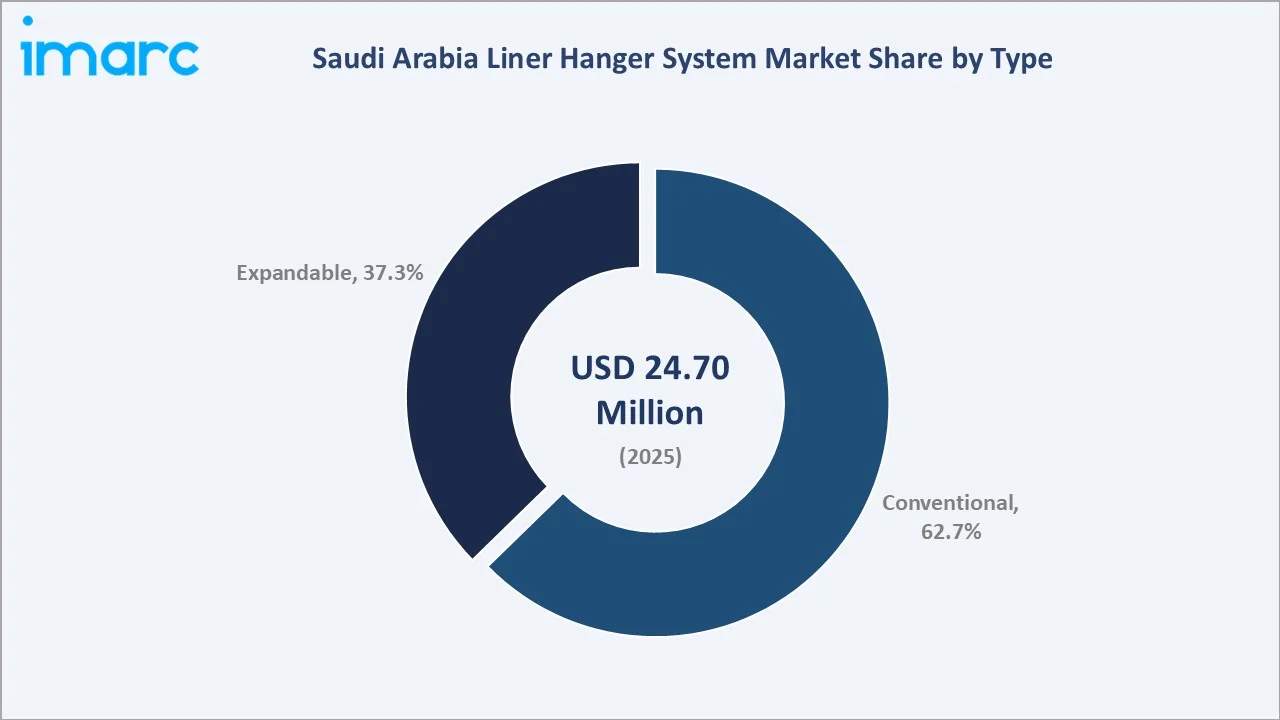
Conventional liner hangers dominate at 62.7%, reflecting widespread use across mature onshore fields. Onshore deployment leads at 78.5%. The Eastern Region commands 45.6% of the national market share, anchored by Saudi Aramco's operational headquarters in Dhahran.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 24.70 Million |
|
Market Size (2026) |
USD 25.91 Million |
|
Forecast Market Size (2034) |
USD 38.07 Million |
|
CAGR (2026-2034) |
4.92% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Conventional (62.7%, 2025) |
|
Dominant Deployment |
Onshore (78.5%, 2025) |
|
Leading Region |
Eastern Region (45.6%, 2025) |
The Saudi Arabia liner hanger system market size increased from USD 19.42 Million in 2020 to USD 24.70 Million in 2025 and is estimated to reach USD 25.91 Million in 2026. The market is further expected to grow to USD 31.41 Million by 2030 and USD 38.07 Million by 2034. Saudi Arabia's liner hanger market is commercially unique among GCC nations, combining the world's most active national oil company drilling programme, a large-scale unconventional gas development creating new completions demand, and a growing private-sector drilling services market under Vision 2030's IKTVA local content initiative.
To get more information on this market, Request Sample
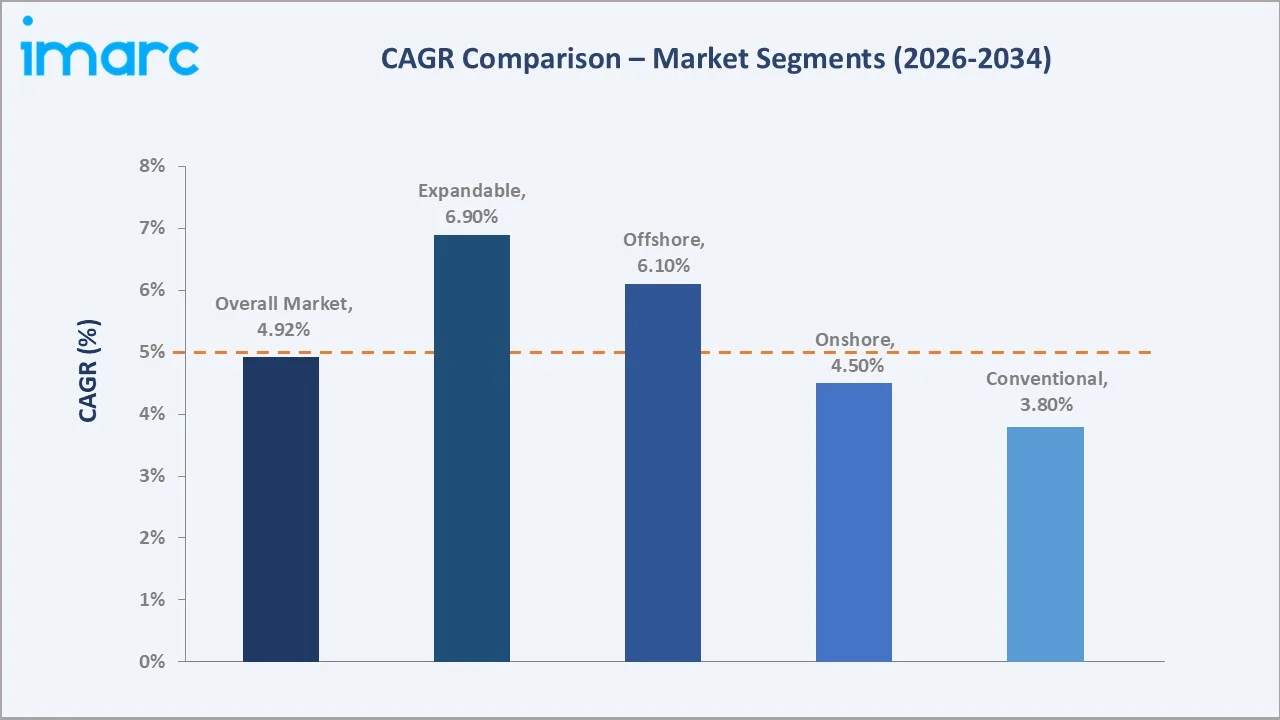
The expandable liner hanger segment grows fastest at ~6.9% CAGR through HPHT well development, extended-reach drilling in Jafurah unconventional gas fields, and offshore Marjan and Zuluf capacity expansion programmes. Offshore applications grow at ~6.1% CAGR.
Executive Summary
The Saudi Arabia liner hanger system market expanded from USD 24.70 Million in 2025 to an estimated USD 25.91 Million in 2026, positioning it as the largest national liner hanger market in the GCC by value. The market's scale is underpinned by Saudi Aramco's multi-year capital expenditure commitments, the Kingdom's unconventional gas development ambitions, and rising demand for precision wellbore completion technologies in increasingly complex well environments. The market is projected to reach USD 38.07 Million by 2034 at a CAGR of 4.92%. Conventional at 62.7% leads through proven field performance and cost efficiency. Onshore at 78.5% reflects Saudi Arabia's dominant land-based drilling activity. Eastern Region leads regionally at 45.6%.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Conventional – 62.7% share (2025) |
|
Dominant Deployment |
Onshore – 78.5% market share (2025) |
|
Leading Region |
Eastern Region – 45.6% share (2025) |
|
Market Opportunity |
Expandable liner hanger adoption in HPHT and extended-reach wells; Jafurah unconventional gas development; offshore Marjan and Zuluf expansion |
Key Analytical Observations Supporting the Above Data:
- Conventional at 62.7%: The conventional liner hanger segment dominates due to proven reliability, lower cost, and compatibility with Saudi Arabia's existing well architectures. Their mechanical simplicity and API-certified interoperability with established casing programmes make them the preferred choice across Saudi Aramco's standard well completions.
- Onshore at 78.5%: Onshore deployment leads as Saudi Arabia's prolific land-based producing fields including Ghawar, Khurais, and Shaybah continue to require active well completions and workovers. The Kingdom's sustained land rig count consistently supports high onshore demand for liner hanger systems.
- Eastern Region at 45.6%: The Eastern Region dominates due to the highest concentration of oil and gas producing assets in Saudi Arabia, including Ghawar, Abqaiq, and the offshore Eastern fields, with Saudi Aramco's primary headquarters in Dhahran driving centralised procurement.
Saudi Arabia Liner Hanger System Market Overview
Saudi Arabia liner hanger system market is commercially positioned at a unique intersection: the world's largest oil-producing nation with the most active national oil company drilling programme globally, an accelerating unconventional gas development creating new demand for advanced completion systems, and a growing private-sector well services market under Vision 2030's IKTVA programme creating domestic manufacturing opportunities.
Saudi Arabia liner hanger ecosystem integrates international oilfield service company technology with Saudi Aramco's centralised procurement framework, IKTVA local content compliance requirements, in-Kingdom logistics and warehousing networks, and field-level installation and technical support services.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
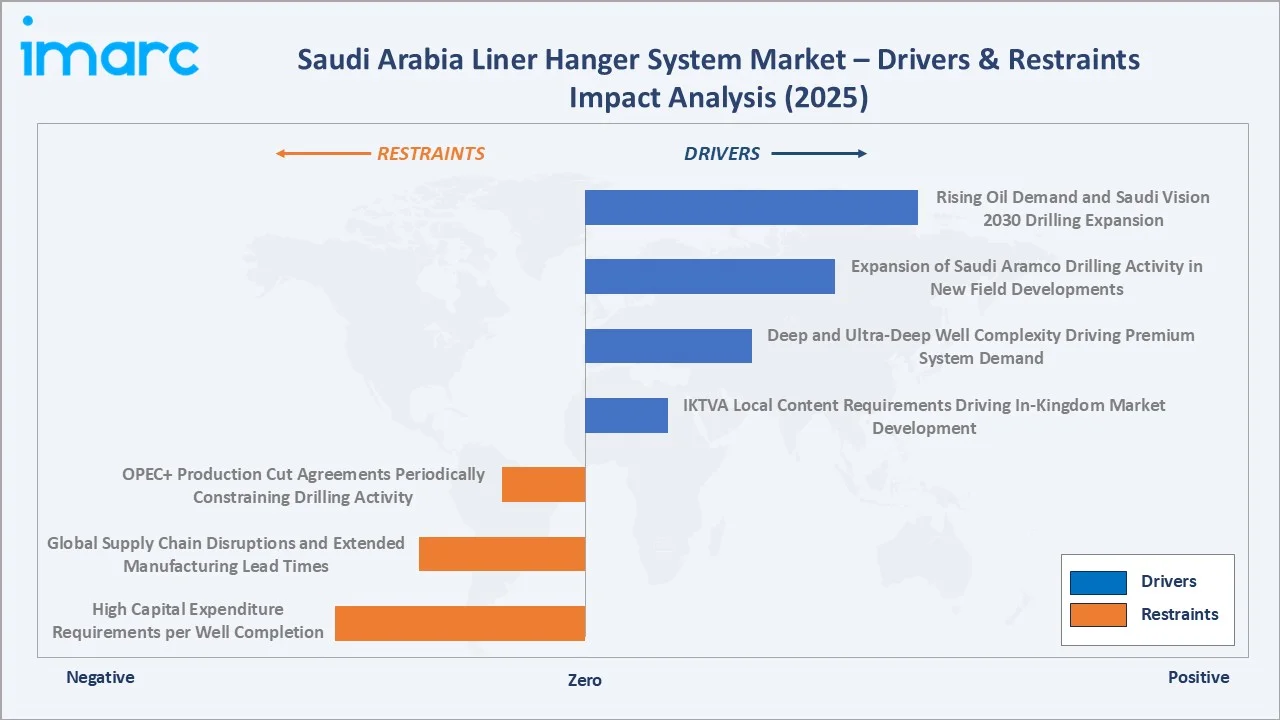
- Rising Oil Demand and Saudi Vision 2030 Drilling Expansion: Saudi Aramco's sustained commitment to maintaining over 12 million bpd production capacity drives continuous well drilling, workover, and completion activities across the Kingdom. The Vision 2030 programme's energy sector investment targets create multi-year capital expenditure visibility for liner hanger system suppliers. Saudi Arabia's Jafurah unconventional gas basin development is projected to require hundreds of new well completions over the coming decade, creating substantial structural demand for advanced wellbore completion equipment including liner hanger systems across both conventional and expandable product categories.
- Expansion of Saudi Aramco Drilling Activity in New Field Developments: Saudi Aramco's ongoing development of the Jafurah tight gas basin, the Marjan and Zuluf offshore field expansions, and infill drilling across mature onshore fields collectively sustain one of the world's highest annual well completions volumes. The company's multi-year integrated drilling contracts with leading oilfield service companies establish forward demand visibility supporting supplier investment in Saudi Arabia-specific product qualification and in-Kingdom service infrastructure.
- Deep and Ultra-Deep Well Complexity Driving Premium System Demand: As Saudi Arabia's conventional reservoirs mature, operators are targeting deeper, more technically challenging formations requiring advanced completion technologies. Extended-reach drilling, HPHT well conditions, and deviated wellbore geometries create demand for premium liner hanger systems with enhanced sealing, anchoring, and temperature resistance capabilities.
- IKTVA Local Content Requirements Driving In-Kingdom Market Development: Saudi Aramco's In-Kingdom Total Value-Added programme mandates increasing local content in procurement, creating regulatory pressure for international oilfield service companies to establish Saudi Arabia-based manufacturing or assembly operations. Companies achieving higher IKTVA scores receive systematic competitive advantages in Aramco bid evaluations. This regulatory framework is driving joint venture formation, local manufacturing investment, and technology transfer agreements that expand the domestic liner hanger market beyond pure import supply, supporting new domestic market participants and supply chain development.
Market Restraints
- High Capital Expenditure Requirements per Well Completion: Liner hanger systems, particularly expandable and HPHT-rated premium variants, represent significant per-well capital expenditure that can be deferred during oil price downturns or Aramco budget re-prioritisation periods. The cyclical nature of oilfield capital expenditure creates revenue volatility for liner hanger system suppliers that limits long-term investment certainty in Saudi Arabia-specific product development. Budget constraints can shift procurement toward lower-cost conventional alternatives, suppressing overall market value growth below volume trends during periods of spending restraint.
- Global Supply Chain Disruptions and Extended Manufacturing Lead Times: Complex liner hanger systems require specialised metallurgy, precision machining, and proprietary sealing elements sourced from a limited number of qualified global suppliers. Supply chain disruptions, raw material cost inflation, and extended manufacturing lead times can constrain market supply and create delivery risk, particularly for emergency well completion and workover requirements where schedule is critical. Limited alternative suppliers for HPHT-rated components create single-source dependencies that amplify price and schedule risk during periods of high global demand.
- OPEC+ Production Cut Agreements Periodically Constraining Drilling Activity: Saudi Arabia's participation in OPEC+ production restraint agreements periodically limits active drilling programme volumes when production targets are reduced below technical capacity. Reduced active rig counts during production restraint periods directly lower near-term liner hanger system demand, creating market cyclicality that complicates supplier revenue planning and investment timing.
Market Opportunities
- Jafurah Unconventional Gas Basin Development Creating Structural New Demand: Saudi Arabia's Jafurah basin, estimated to hold over 200 trillion cubic feet of tight gas, requires specialised liner hanger systems optimised for horizontal well completions, multi-stage fracturing compatibility, and corrosive gas environment resistance. This development programme creates a structurally new demand segment distinct from conventional oil well completions, with differentiated technical requirements that favour suppliers with proven unconventional completion expertise.
- Smart Liner Hanger Technology Integration with Digital Oilfield Programmes: The integration of pressure, temperature, and strain sensors into liner hanger systems enables real-time wellbore monitoring aligned with Saudi Aramco's Upstream Digital transformation programme. Smart liner hanger systems command significant price premiums over conventional equivalents, creating high-margin product segments and sticky long-term service relationships that extend beyond initial equipment supply.
Market Challenges
- Saudi Aramco's Concentrated Buyer Power and Procurement Pricing Pressure: Saudi Aramco's position as the dominant buyer of liner hanger systems in Saudi Arabia creates significant negotiating leverage that persistently pressures supplier pricing and margin structures. Extended procurement cycles, multi-year framework agreements with pre-negotiated pricing, and competitive tender processes involving multiple qualified suppliers limit the ability of liner hanger system suppliers to achieve pricing commensurate with their technology investment.
- Technology Qualification Costs and Timeline Requirements for Aramco Approval: Gaining and maintaining qualification on Saudi Aramco's approved vendor list for liner hanger systems requires substantial investment in API certification, Aramco-specific testing, in-Kingdom technical support infrastructure, and ongoing performance documentation. These qualification barriers create high market entry costs that limit competition but also constrain the speed at which new technology innovations can achieve commercial deployment at scale.
Emerging Market Trends
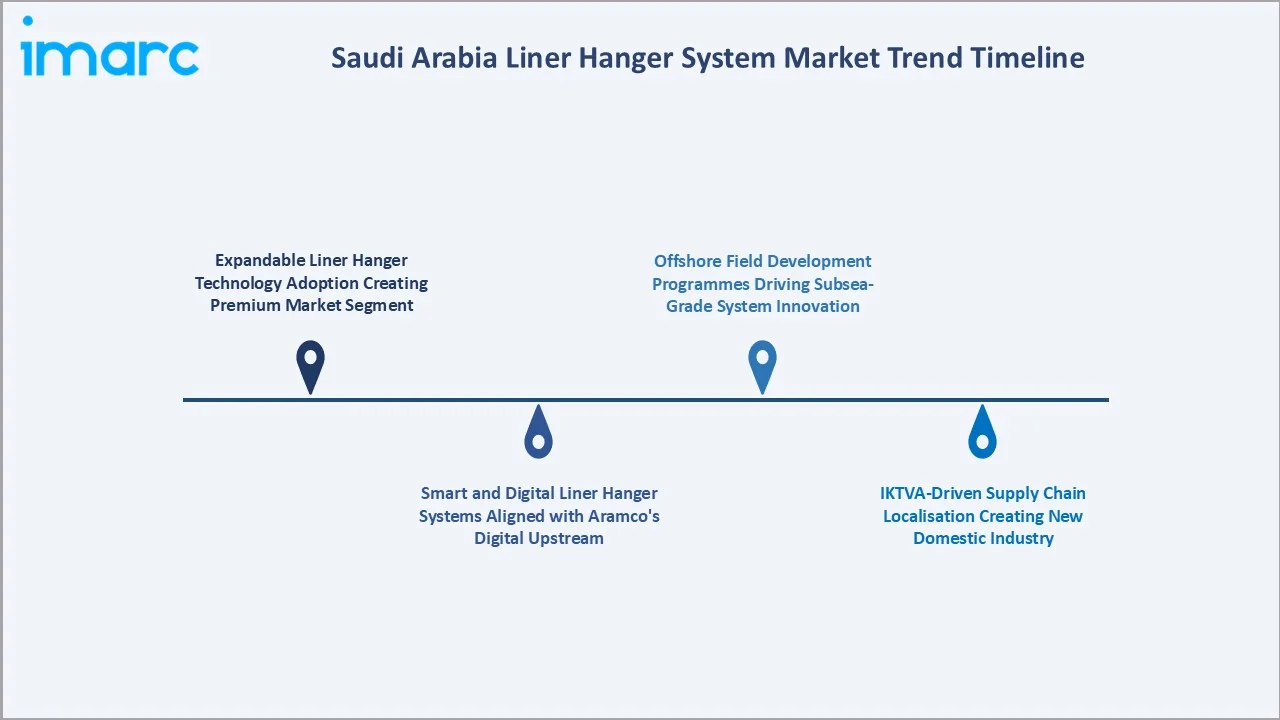
1. Expandable Liner Hanger Technology Adoption Creating Premium Market Segment
Expandable liner hangers are gaining sustained commercial traction in Saudi Arabia's HPHT and extended-reach well environments. Their superior zonal isolation in high-pressure, high-temperature, and deviated well conditions supports production zone integrity and long-term well productivity. The Jafurah unconventional gas programme's horizontal well completions represent the highest-volume expandable liner hanger adoption opportunity in the Kingdom, with system requirements combining corrosion resistance, high differential pressure ratings, and multi-stage completion compatibility.
2. Smart and Digital Liner Hanger Systems Aligned with Aramco's Digital Upstream
The integration of downhole sensors, wireless telemetry, and data analytics platforms with liner hanger systems is progressing from pilot deployment to broader commercial adoption within Saudi Aramco's digital oilfield programme. These smart systems deliver real-time wellbore pressure and integrity data enabling predictive maintenance and production optimisation decisions, creating recurring data service revenue streams alongside initial equipment supply.
3. IKTVA-Driven Supply Chain Localisation Creating New Domestic Industry
International liner hanger system manufacturers are progressively establishing Saudi Arabia-based manufacturing, assembly, and technical support operations to meet escalating IKTVA local content requirements in Saudi Aramco procurement evaluations. Companies with established in-Kingdom manufacturing receive systematic procurement preference advantages that create structural competitive moats unavailable to pure-import competitors. This trend is building a domestic oilfield equipment manufacturing ecosystem that positions Saudi Arabia as a regional liner hanger system supply hub.
4. Offshore Field Development Programmes Driving Subsea-Grade System Innovation
Saudi Aramco's multi-billion-dollar offshore capacity expansion at Marjan and Zuluf fields is creating sustained demand for offshore-rated liner hanger systems with subsea-qualified materials, enhanced corrosion resistance, and specialised installation tooling. Offshore liner hanger systems command premium pricing above onshore equivalents, and the scale of Marjan and Zuluf programmes extending through 2030 creates a significant offshore product revenue growth driver that supports both system technology development and in-Kingdom service capability investment.
Industry Value Chain Analysis
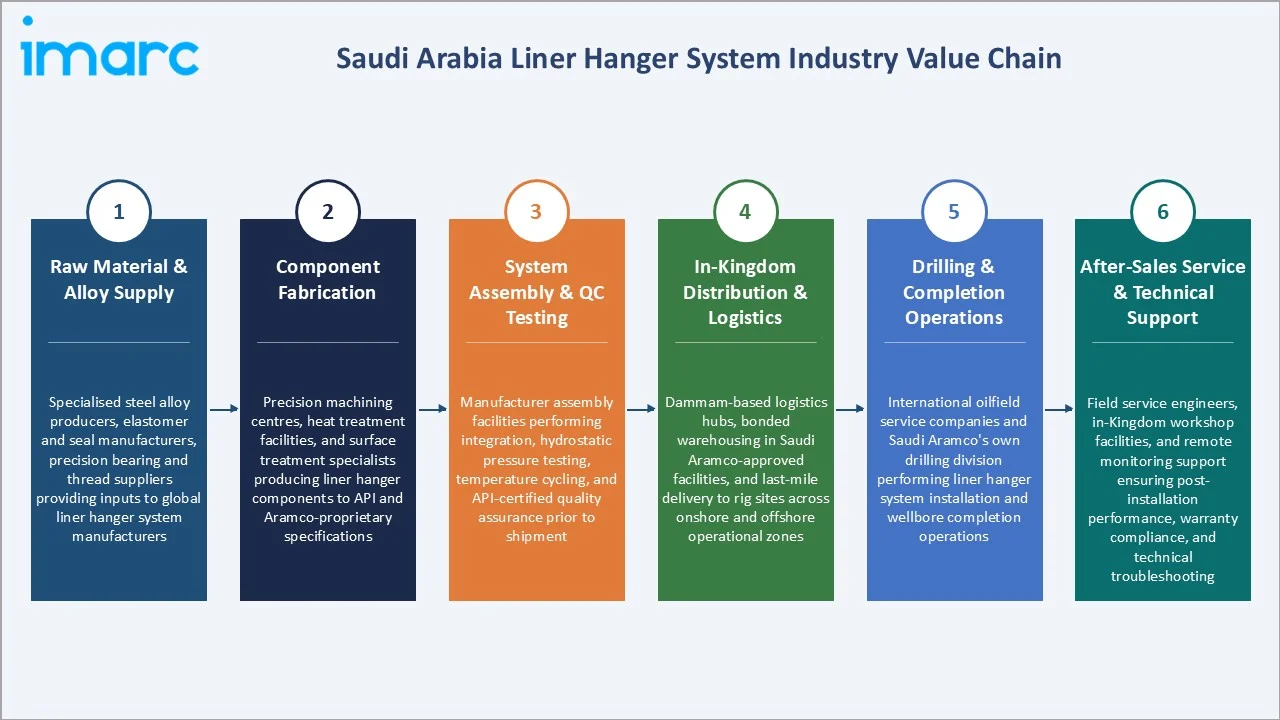
Saudi Arabia liner hanger system value chain is one of the most procurement-concentrated of any oilfield equipment category in the GCC. Saudi Aramco's centralised procurement authority through its Supply Chain Management division creates a highly structured commercial environment where approved vendor lists, long-term service agreements, and IKTVA-weighted performance-based contracting define market access for all suppliers.
|
Stage |
Key Participants |
|
Raw Material & Alloy Supply |
Specialised steel alloy producers, elastomer and seal manufacturers, precision bearing and thread suppliers providing inputs to global liner hanger system manufacturers |
|
Component Fabrication |
Precision machining centres, heat treatment facilities, and surface treatment specialists producing liner hanger components to API and Aramco-proprietary specifications |
|
System Assembly & QC Testing |
Manufacturer assembly facilities performing integration, hydrostatic pressure testing, temperature cycling, and API-certified quality assurance prior to shipment |
|
In-Kingdom Distribution & Logistics |
Dammam-based logistics hubs, bonded warehousing in Saudi Aramco-approved facilities, and last-mile delivery to rig sites across onshore and offshore operational zones |
|
Drilling & Completion Operations |
International oilfield service companies and Saudi Aramco's own drilling division performing liner hanger system installation and wellbore completion operations |
|
After-Sales Service & Technical Support |
Field service engineers, in-Kingdom workshop facilities, and remote monitoring support ensuring post-installation performance, warranty compliance, and technical troubleshooting |
The in-Kingdom distribution and logistics stage is increasingly commercially significant as IKTVA requirements drive bonded warehousing, technical support localisation, and inventory stocking at Saudi Aramco-approved facilities.
Technology Landscape in the Saudi Arabia Liner Hanger System Industry
Conventional Mechanical Liner Hanger Technology
Conventional mechanical liner hangers utilise slips and cone mechanisms to anchor the liner within the casing string, providing reliable wellbore isolation at proven cost efficiency. Their commercial dominance reflects API-certified interoperability with Saudi Arabia's existing well designs, lower total cost of ownership versus expandable alternatives, and decades of field-qualified performance across Saudi Aramco's onshore producing portfolio. Technology innovation focuses on slip material hardening, torque-resistant body designs, improved packer element materials for extended service life, and enhanced sealing performance for higher-temperature reservoir applications.
Expandable Liner Hanger Technology
Expandable liner hanger technology employs hydraulic or mechanical radial expansion to create metal-to-metal seals against casing walls, delivering superior zonal isolation in HPHT, sour gas, and geometrically challenging wellbore environments. This technology is gaining accelerating adoption in Saudi Arabia's unconventional gas completions, deep offshore applications, and extended-reach wells where conventional elastomer seal performance is insufficient.
Digital Monitoring and Smart Completion Technologies
The integration of downhole pressure, temperature, and strain sensors with liner hanger systems enables real-time wellbore integrity monitoring aligned with Saudi Aramco's Upstream Digital programme objectives. Smart liner hanger systems with embedded sensors deliver continuous wellbore data supporting predictive maintenance, production zone optimisation, and early warning of integrity concerns.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Conventional |
62.7% |
2025 |
|
Location of Deployment |
Onshore |
78.5% |
2025 |
|
Region |
Eastern Region |
45.6% |
2025 |

By Type
Conventional leads at 62.7% (2025). The conventional segment encompasses Saudi Arabia's broadest commercial application base, from standard casing programmes in mature onshore fields to straightforward offshore well completions across the Kingdom's producing portfolio.
To access detailed market analysis, Request Sample
Expandable at 37.3% grows fastest at ~6.9% CAGR through Saudi Arabia's deepening well inventory, increasing HPHT reservoir targets, and Jafurah unconventional gas programme completion requirements.
By Location of Deployment
Onshore leads at 78.5% (2025). This segment serves Saudi Arabia's extensive land-based drilling activity across the Ghawar, Khurais, Shaybah, and Jafurah fields, forming the commercial foundation of the Kingdom's liner hanger system demand.
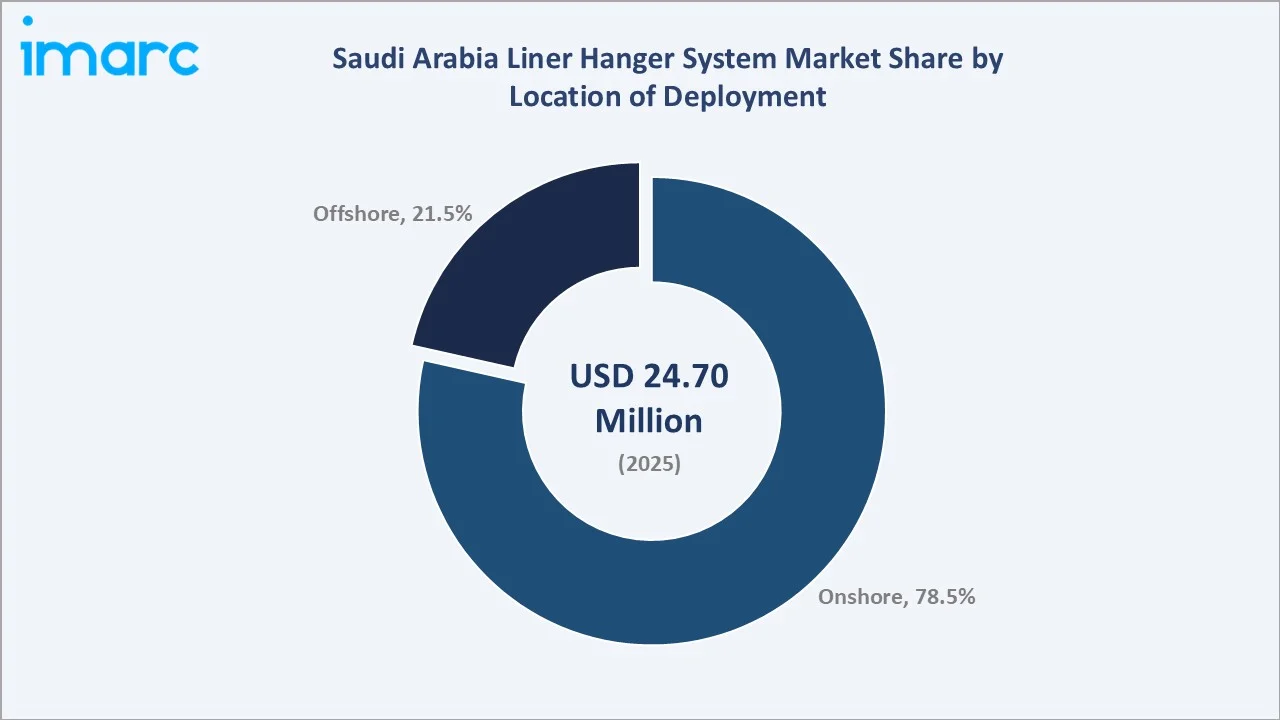
Offshore at 21.5% grows at ~6.1% CAGR through Saudi Aramco's Marjan and Zuluf offshore capacity expansion programmes adding significant incremental daily production through 2030.
Regional Market Insights
|
Region |
Share (2025) |
Key Saudi Arabia Liner Hanger System Market Drivers & Characteristics |
|
Eastern Region |
45.6% |
Home to Saudi Aramco's primary production assets including Ghawar, Abqaiq, and the Eastern offshore fields. Dominant in both onshore and offshore liner hanger demand, with Dhahran serving as the procurement and logistics hub. |
|
Northern and Central Region |
28.7% |
Driven by active exploration and development drilling in the Widyan basin and growing unconventional resource development including Jafurah tight gas field operations. |
|
Western Region |
17.4% |
Supported by Red Sea coastal exploration programmes and growing industrial well services demand tied to Vision 2030 industrial corridor development projects. |
|
Southern Region |
8.3% |
Smallest market share reflecting lower concentration of major producing fields. Rising development drilling in the Rub' al Khali basin supports gradual demand growth. |
Eastern Region's 45.6% market leadership reflects Saudi Aramco's operational headquarters concentration in Dhahran, the Kingdom's highest-density oil and gas production zone. Northern and Central Region's 28.7% reflects the Jafurah unconventional gas development programme's growing drilling activity and ongoing exploration success in the Widyan basin.
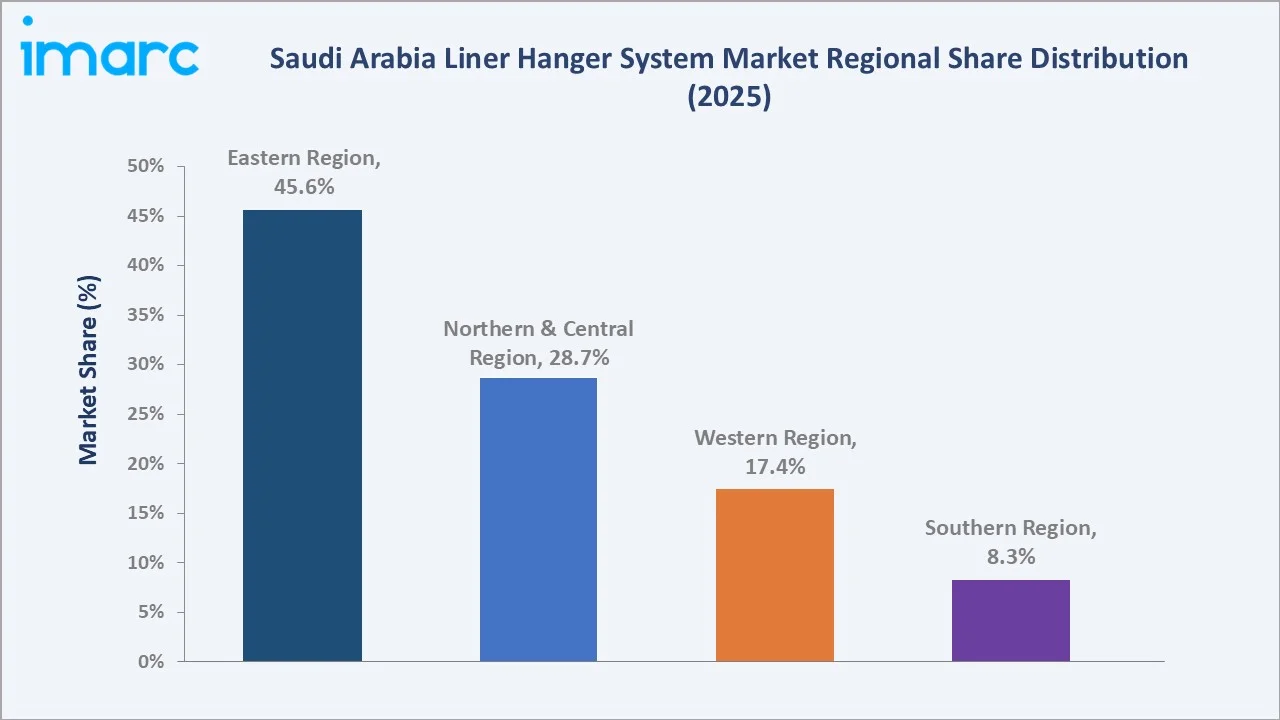
Western Region's 17.4% is growing through Red Sea exploration programmes and Vision 2030's industrial development corridor, where new gas supply infrastructure requires well completion services. Southern Region's 8.3% is the commercially least developed region but growing above the overall market CAGR as Rub' al Khali exploration programmes create first-cycle liner hanger system demand from a comparatively lower activity base.
Competitive Landscape
Saudi Arabia liner hanger system competitive landscape is characterised by strong concentration among global oilfield service leaders, with the top three players commanding an estimated combined market share above 65%.
|
Company |
Key Products |
Market Position |
Core Strength |
|
SLB |
Xcelis, Liner Tieback, COLOSSUS |
Market Leader |
Broadest portfolio across conventional and expandable types, strong HPHT capability, and Vision 2030-aligned in-Kingdom manufacturing partnership programme. |
|
Baker Hughes Company |
BAKERLINE hanger packer, FLEX-LOCK liner hanger system, Hyflo II liner hanger, Hyflo III liner hanger, UniFlex Pro liner hanger and packer system |
Strong Challenger |
HPHT metal-seal expandable technology leadership and next-generation liner hanger systems rated to 30,000 psi for Saudi Arabia's deepest well applications. |
|
Weatherford |
IntegraLine |
Strong Challenger |
Competitive conventional liner hanger portfolio and established Saudi Arabia service network supporting Saudi Aramco onshore drilling programmes at scale. |
|
NOV |
GSP II Liner Hanger, SURESET Liner Hanger Packer |
Innovator |
Integrated drilling equipment manufacturer with liner hanger systems qualified within Saudi Aramco's broader drillstring and completion procurement framework. |
Key players include SLB, Baker Hughes Company, Weatherfor, NOV, and others.
Key Company Profiles
SLB
SLB is a leading technology company in Saudi Arabia's liner hanger system market, offering the broadest portfolio of conventional, expandable, and intelligent liner hanger solutions across onshore and offshore applications, with a comprehensive Vision 2030 IKTVA alignment programme supporting its market leadership alongside Halliburton.
- Key Products: Xcelis, Liner Tieback, COLOSSUS
- Strategic Focus: Digital integration of liner hanger systems within the DELFI cognitive computing environment, enabling predictive completion optimisation and real-time wellbore monitoring aligned with Saudi Aramco's Upstream Digital initiative. SLB is prioritising HPHT expandable liner hanger qualification for Jafurah unconventional gas applications, investing in specialised product development addressing the unique completion environment of Saudi Arabia's tight gas reservoirs.
Baker Hughes Company
Baker Hughes is a premier completion technology provider in the Saudi Arabia liner hanger system market, distinguished by its HPHT metal-seal expandable liner hanger leadership, strong technical qualification with Saudi Aramco for deep and ultra-deep well applications, and growing Saudi Arabia operational footprint supporting IKTVA compliance requirements across the Kingdom.
- Key Products: BAKERLINE hanger packer, FLEX-LOCK liner hanger system, Hyflo II liner hanger, Hyflo III liner hanger, UniFlex Pro liner hanger and packer system
- Strategic Focus: Leveraging HPHT technical differentiation and metal-seal expandable liner hanger leadership to capture premium market opportunities in Saudi Aramco's most technically demanding well programmes, including Jafurah unconventional gas completions and deep offshore HPHT development wells. Baker Hughes is investing in Saudi Arabia-specific product engineering to optimise liner hanger system performance for Jafurah reservoir conditions, including corrosive gas resistance and multi-stage completion compatibility.
Market Concentration Analysis
Saudi Arabia liner hanger system market is highly concentrated at the premium and HPHT segments, with the key players commanding an estimated combined 65–70% of the Kingdom's organised market by value. The IKTVA procurement framework creates persistent barriers that reinforce established players' dominant positions against international challengers seeking Saudi Aramco market access without in-Kingdom operational investment.
Market concentration is evolving through two opposing forces: established players' deepening IKTVA local manufacturing investments maintaining procurement preference advantages with Saudi Aramco, while technology disruption in expandable and smart liner hanger systems creates entry opportunities for technology-focused challengers. Niche players are carving specialised positions in subsea and innovative design segments where scale advantages of the majors are less decisive.
Investment & Growth Opportunities
Highest Growth Segments
Expandable liner hanger systems (~6.9% CAGR through HPHT well expansion) and offshore liner hanger systems (~6.1% CAGR through Marjan and Zuluf development) represent Saudi Arabia's highest-growth liner hanger investment vectors through 2034.
Emerging Investment Opportunities
Saudi Arabia's IKTVA-compliant in-Kingdom liner hanger manufacturing is growing at an accelerating pace, driven by Saudi Aramco's increasing IKTVA score requirements in bid evaluations. Manufacturing partnerships combining international technology with Saudi industrial investors create structurally advantaged market positions unavailable to pure-import competitors and generate long-term supply agreement opportunities providing revenue visibility beyond individual well completion contracts.
Investment Themes
- In-Kingdom liner hanger manufacturing investment under IKTVA framework creating Saudi Aramco procurement preference: The IKTVA programme's escalating local content requirements create structural first-mover advantages for companies establishing Saudi Arabia-based manufacturing before IKTVA thresholds become mandatory exclusion criteria.
- Smart liner hanger technology platform investment for Saudi Aramco's Digital Upstream programme: Integration of liner hanger systems with Saudi Aramco's real-time wellbore monitoring platforms creates recurring data service revenue streams alongside equipment supply, building high-value customer relationships that extend beyond transactional procurement.
Future Market Outlook (2026-2034)
The Saudi Arabia liner hanger system market is projected to grow from USD 24.70 Million in 2025 to USD 25.91 Million in 2026, reaching USD 38.07 Million by 2034, registering a CAGR of 4.92% during 2026–2034. The market's anchor value of USD 31.41 Million in 2030 represents a structural inflection where Jafurah unconventional gas completions begin generating sustained above-market-average demand growth and offshore Marjan and Zuluf programmes reach peak development drilling intensity.
Three structural forces define Saudi Arabia liner hanger market growth through 2034: Saudi Aramco's capital expenditure commitment sustaining above-global-average drilling activity; Vision 2030's upstream technology localisation creating domestic industry development alongside international supply; and the Kingdom's unconventional gas development creating a structurally new completion technology requirement that elevates average system complexity, premium product mix, and pricing power across the entire market.
Research Methodology
Primary Research
Primary research comprised structured interviews with Saudi Arabia oilfield services industry stakeholders, including Drilling and Completion Directors, Supply Chain Managers, Business Development Executives, Saudi Aramco procurement specialists, and liner hanger system field engineers operating across the Eastern, Northern, and Western regions of the Kingdom.
Secondary Research
Secondary research encompassed Saudi Aramco annual reports and capital expenditure disclosures, Saudi Ministry of Energy drilling statistics, company investor presentations, API standards documentation, IKTVA programme guidelines, GCC oilfield equipment trade statistics, and industry journals covering completion technology advances. Over 45 secondary sources were reviewed and cross-referenced.
Forecasting Models
Market revenue forecasts were developed using a rig-activity-based demand model: Saudi Arabia active rig count by deployment location multiplied by average liner hanger system procurement per well by product type, calibrated against Saudi Aramco capital expenditure guidance, OPEC+ production agreement timelines, and Vision 2030 drilling programme schedules.
Saudi Arabia Liner Hanger System Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Conventional, Expandable |
| Location of Deployments Covered | Offshore, Onshore |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | SLB, Baker Hughes Company, Weatherford, NOV, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia liner hanger system market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia liner hanger system market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia liner hanger system industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Liner Hanger System Market Report
Saudi Arabia liner hanger system market size is estimated at USD 25.91 Million in 2026, driven by Saudi Aramco's sustained drilling programmes, Vision 2030 upstream investments, and growing demand for advanced wellbore completion technologies across HPHT and unconventional gas well applications.
Saudi Arabia liner hanger system market grows at 4.92% CAGR during 2026-2034, reaching USD 38.07 Million by 2034. Overall growth is sustained by Jafurah unconventional gas development, offshore capacity expansion programmes, expandable technology adoption, and IKTVA-driven domestic industry development.
Conventional leads at 62.7% through Saudi Arabia's dominant demand for proven, cost-effective liner hanger systems across its extensive onshore and standard offshore well portfolio, with established API certification compatibility across Saudi Aramco's well design standards.
Onshore leads at 78.5% through Saudi Arabia's prolific land-based producing fields including Ghawar, Khurais, and Shaybah, with Saudi Aramco's sustained onshore well completion and workover activity creating consistent annual demand for liner hanger systems across conventional and unconventional onshore applications.
Eastern Region leads at 45.6% through Saudi Aramco's operational headquarters concentration in Dhahran, the Kingdom's highest-density oil and gas production zone, and the Eastern offshore field development programmes creating both onshore and offshore liner hanger system demand from a single geographically concentrated procurement hub.
Leading companies include include SLB, Baker Hughes Company, Weatherfor, NOV, and others.
Saudi Arabia liner hanger system market is projected to reach approximately USD 31.41 Million by 2030, with expandable technology adoption growing as Jafurah unconventional gas completions scale, offshore Marjan and Zuluf development reaching peak drilling intensity, and smart liner hanger systems beginning commercial deployment across Saudi Aramco's digital oilfield programme.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade