
Saudi Arabia Solar Energy Storage Market Size, Share, Trends and Forecast by Type, Installation, and Region, 2026-2034
Saudi Arabia Solar Energy Storage Market Size, Share, Trends & Forecast (2026-2034)
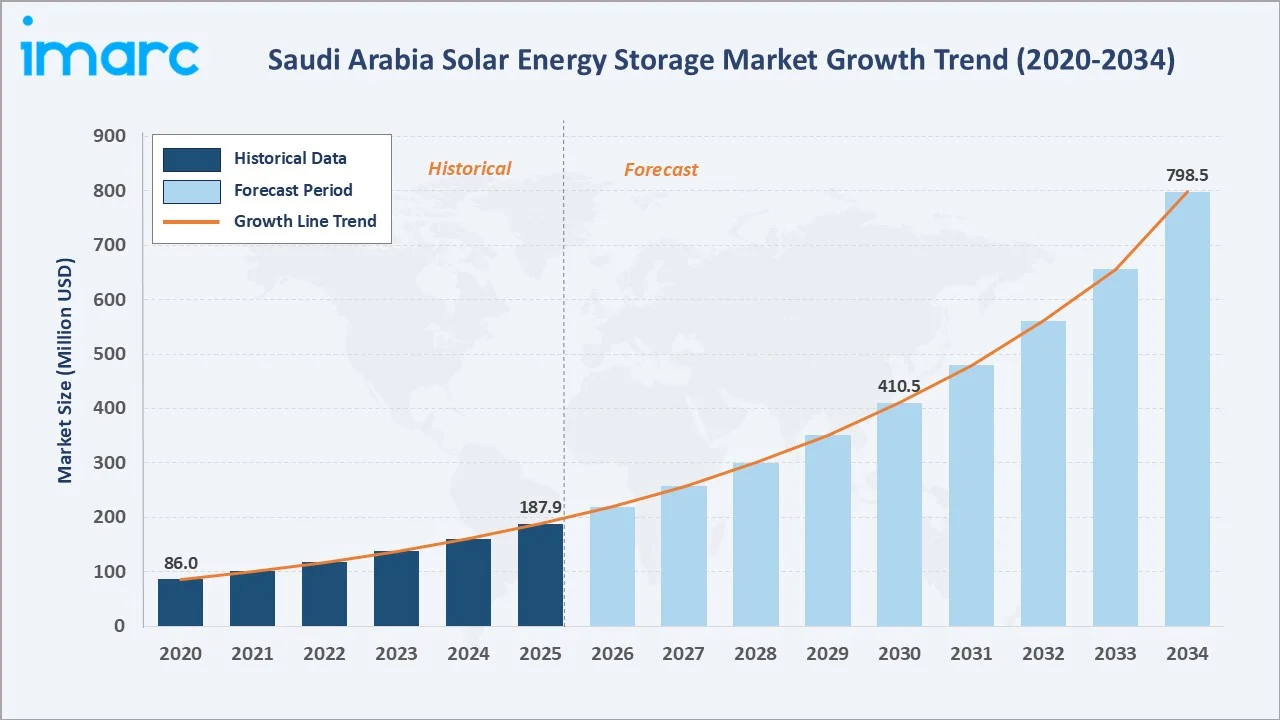
The Saudi Arabia solar energy storage market size increased from USD 187.9 Million in 2025 to USD 228.7 Million in 2026 and is projected to reach USD 798.5 Million by 2034, expanding at a CAGR of 16.92% during 2026-2034. The market is driven by accelerating renewable energy targets under Vision 2030 and falling lithium-ion battery costs.
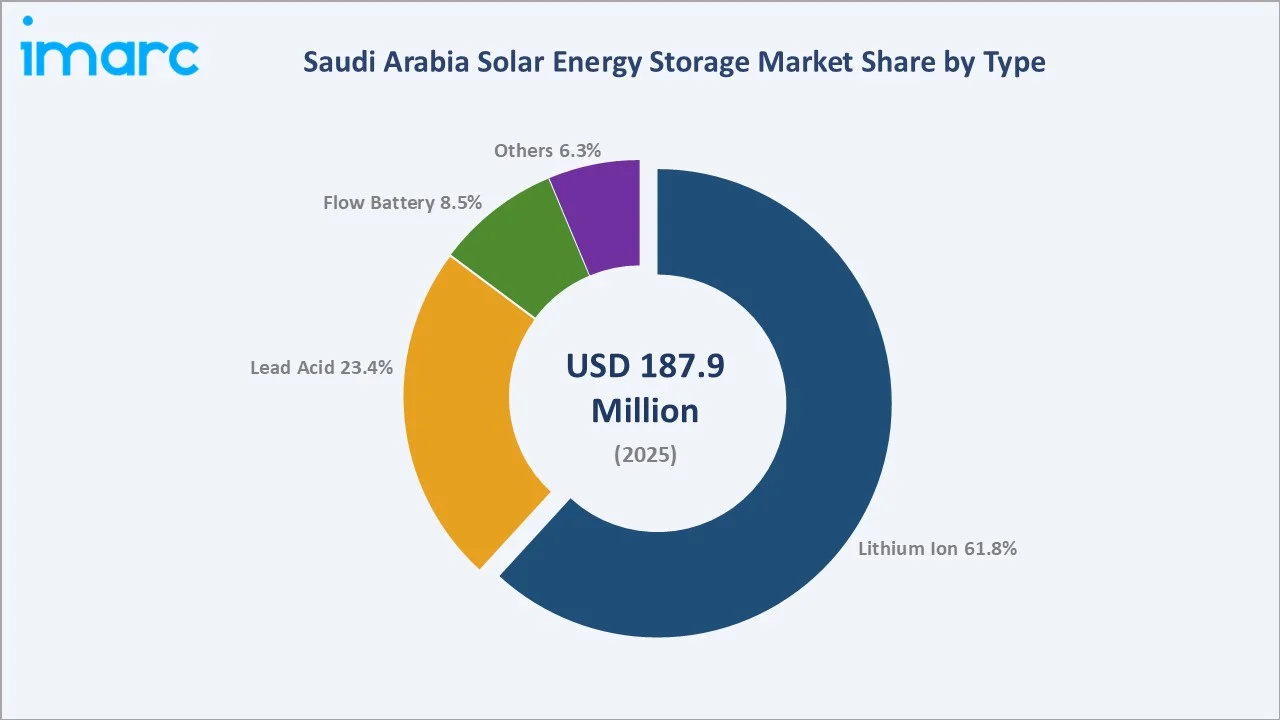
Lithium ion leads the type segment at 61.8%, on grid dominates the installation segment at 74.2%, and Northern and Central Region accounts for the largest regional share at 39.1%.
Market Snapshot
|
Metric |
Value |
| Base Year Market Size (2025) |
USD 187.9 Million |
| Market Size (2026) | USD 228.7 Million |
|
Forecast Market Size (2034) |
USD 798.5 Million |
|
CAGR (2026-2034) |
16.92% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Northern and Central Region (39.1%, 2025) |
|
Second Largest Region |
Western Region (28.4%, 2025) |
|
Leading Type |
Lithium Ion (61.8%, 2025) |
|
Leading Installation |
On Grid (74.2%, 2025) |
The Saudi Arabia solar energy storage market expanded from USD 86.0 Million in 2020 to USD 187.9 Million in 2025 and an estimated USD 228.7 Million in 2026, underpinned by accelerating renewable energy deployment under Vision 2030, declining lithium-ion battery system costs, and a rapidly expanding pipeline of utility-scale solar-plus-storage projects across the Kingdom. Anchored at USD 410.5 Million in 2030, the forecast to USD 798.5 Million by 2034 reflects sustained momentum from grid modernization imperatives and giga-project energy storage requirements.
To get more information on this market, Request Sample
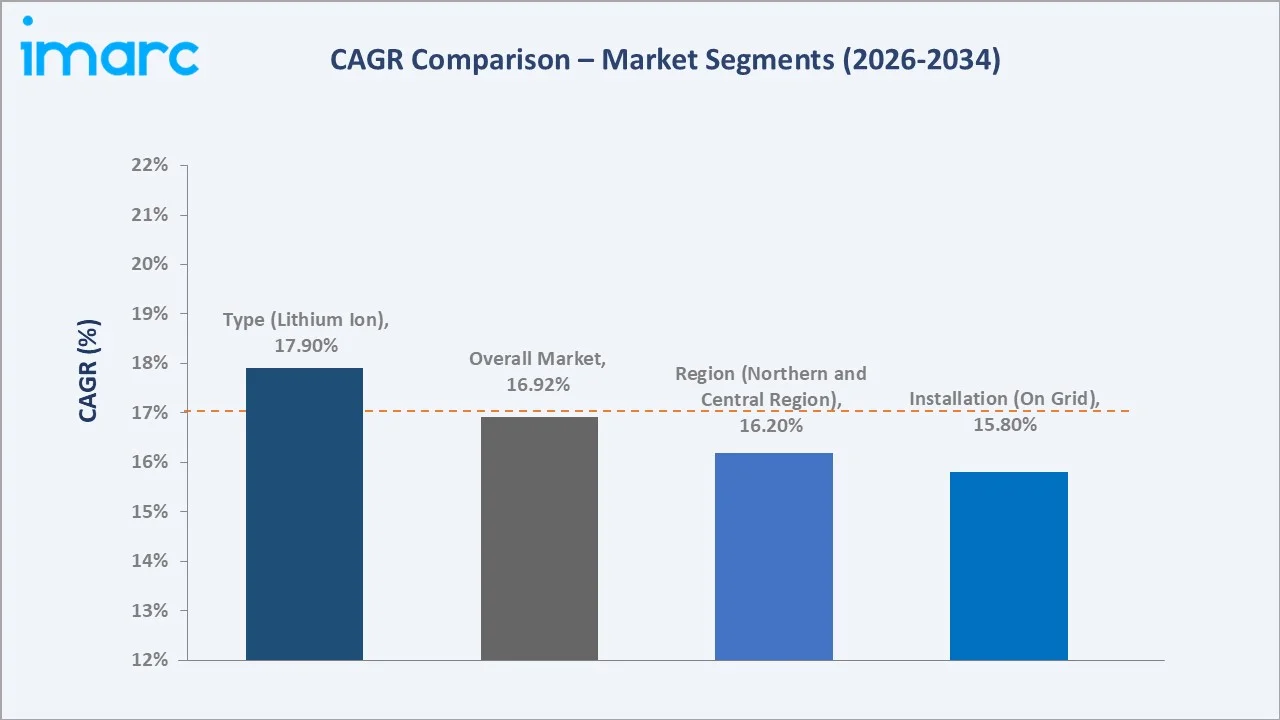
CAGR trajectories across type and installation sub-segments, together with regional patterns, show lithium ion and off grid expanding faster than the overall 16.92% market CAGR, driven by increasing demand for high-efficiency energy storage and decentralized power solutions.
Executive Summary
The Saudi Arabia solar energy storage market is on a strong growth trajectory, rising from USD 86.0 Million in 2020 to an estimated USD 228.7 Million in 2026 and is projected to reach USD 798.5 Million by 2034 at a CAGR of 16.92%. The market is underpinned by supportive government initiatives, expanding renewable energy investments, rising solar power deployment, technological advancements in energy storage systems, and growing demand for reliable and efficient energy solutions across the Kingdom.
Lithium ion dominates the type segment at 61.8% in 2025, driven by superior energy density, declining cell costs, and broad compatibility with utility-scale solar installations. Based on installation, on grid accounts for 74.2% of the market in 2025, reflecting the rapid expansion of grid-connected utility-scale solar projects across the Kingdom. Northern and Central Region leads with a 39.1% market share, anchored by Riyadh's administrative concentration and proximity to large-scale solar irradiation zones.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Lithium Ion – 61.8% share (2025) |
|
Second Largest Type |
Lead Acid – 23.4% share (2025) |
|
Leading Installation |
On Grid – 74.2% share (2025) |
|
Second Largest Installation |
Off Grid – 25.8% share (2025) |
|
Leading Region |
Northern and Central Region – 39.1% share (2025) |
|
Second Largest Region |
Western Region – 28.4% share (2025) |
|
Top Companies |
Contemporary Amperex Technology Co., Limited, BYD Co., Ltd., Tesla, Inc., LG Energy Solution, ABB Ltd. |
Key Analytical Observations Expanding On the Data Above:
- Lithium ion dominance at 61.8% is driven by economies of scale in global battery manufacturing, compatibility with utility-scale solar inverters, and an expanding track record of lithium-ion deployments across Saudi Arabia's flagship giga-projects.
- Lead acid at 23.4% remains relevant for cost-sensitive commercial and backup power applications, where lower upfront capital requirements offset energy density limitations.
- On grid leadership at 74.2% reflects the scale of government-backed utility solar projects requiring grid-connected battery storage for frequency regulation, peak shaving, and renewable integration.
- Off grid growth at 25.8% is underpinned by Saudi Arabia's remote industrial infrastructure, NEOM's off-grid energy master plan, and expanding telecom tower electrification requirements.
- Northern and Central Region at 39.1% is anchored by Riyadh's large administrative and commercial electricity demand, proximity to high-irradiation desert solar zones, and concentration of transmission infrastructure.
Saudi Arabia Solar Energy Storage Market Overview
Solar energy storage refers to the capture and retention of electricity generated by solar photovoltaic systems for later use, enabling grid operators, commercial entities, and residential users to decouple energy generation from consumption. Storage systems are deployed across utility-scale grid-connected configurations, distributed commercial and industrial installations, and remote off-grid applications.
The Saudi ecosystem integrates global technology providers, domestic energy companies, engineering procurement and construction (EPC) contractors, grid operators led by the Saudi Electricity Company (SEC), and government authorities.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
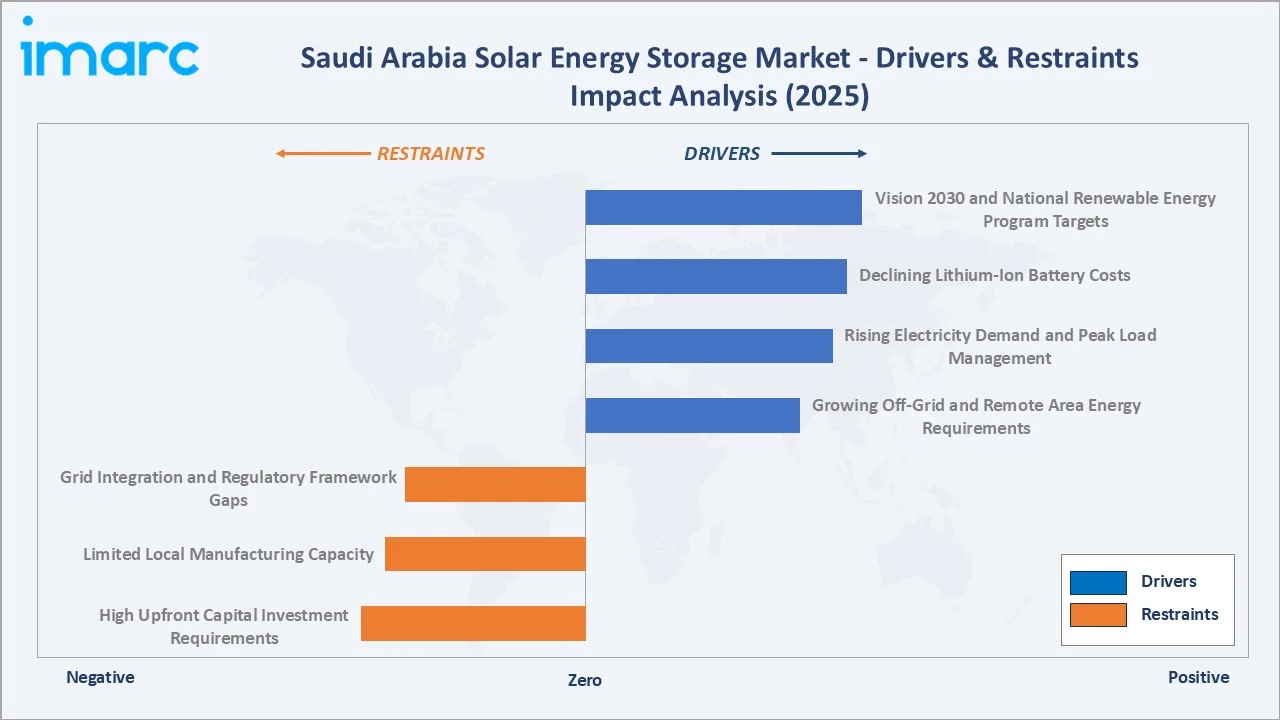
- Vision 2030 and National Renewable Energy Program Targets: Saudi Arabia's Vision 2030 mandates that 50% of the Kingdom's electricity be sourced from renewables by 2030, requiring substantial energy storage deployment to manage the intermittency of solar generation.
- Declining Lithium-Ion Battery Costs: The average cost of utility-scale lithium-ion battery storage systems is falling, making solar-plus-storage economically competitive with conventional peaker plants in Saudi Arabia's high-irradiation environment. This structural cost deflation continues to unlock demand across utility, commercial, and industrial segments.
- Rising Electricity Demand and Peak Load Management: Saudi Arabia's residential and commercial cooling demand creates sharp summer electricity peaks. Utilities and large consumers are deploying storage systems to reduce peak tariff exposure and defer costly transmission infrastructure investments, driving demand for on-grid storage across the Kingdom.
- Growing Off-Grid and Remote Area Energy Requirements: Industrial sites, telecommunications infrastructure, desalination plants, and agricultural facilities in remote areas are adopting solar-plus-storage systems to reduce dependence on expensive and logistically complex diesel supply chains, supporting sustained growth in off-grid installation configurations.
Market Restraints
- High Upfront Capital Investment Requirements: Despite falling technology costs, utility-scale battery storage projects require significant upfront capital expenditure on system components, civil works, grid interconnection, and commissioning. Access to project finance at competitive rates remains a challenge for smaller developers and adds to project risk in a market still building its storage track record.
- Limited Local Manufacturing Capacity: Saudi Arabia currently lacks a domestic battery cell manufacturing base, making the market dependent on imported systems primarily from China, South Korea, and the United States. Supply chain concentration and import logistics introduce cost variability and project schedule risks for storage deployment at scale.
- Grid Integration and Regulatory Framework Gaps: Clear technical standards and commercial frameworks for grid-connected battery storage, including ancillary services market design, storage dispatch rules, and capacity remuneration mechanisms, are still being developed. This regulatory uncertainty slows investment decisions and project structuring for independent power producers.
Market Opportunities
- Localization and In-Kingdom Manufacturing: Saudi Arabia's Vision 2030 local content requirements and the Public Investment Fund's interest in establishing battery manufacturing capacity present opportunities for global storage companies to partner with local industrial groups. In-Kingdom assembly and eventually cell production would reduce import dependency, lower project costs, and create qualifying local content for government-backed procurement.
- Long-Duration Energy Storage for Grid Reliability: As solar penetration deepens, demand for four-hour-plus storage capable of bridging evening demand peaks will expand significantly. Flow batteries, compressed air storage, and emerging gravity-based systems are positioned to capture this segment, with the Kingdom's geography and infrastructure offering suitable sites for large-scale long-duration installations.
Market Challenges
- Skilled Workforce and Technical Expertise Gap: The design, installation, operation, and maintenance of advanced battery storage systems require specialized engineering expertise that is currently in short supply within Saudi Arabia. Workforce development through training programs and international knowledge transfer is a critical enabler of the market's long-term growth.
- End-of-Life Battery Management and Recycling Infrastructure: As early storage deployments reach end of operational life through the forecast period, the absence of a developed battery recycling and second-life ecosystem in Saudi Arabia poses environmental compliance and cost challenges. Developing circular economy infrastructure for spent storage assets is an emerging priority for regulators and project developers.
Emerging Market Trends
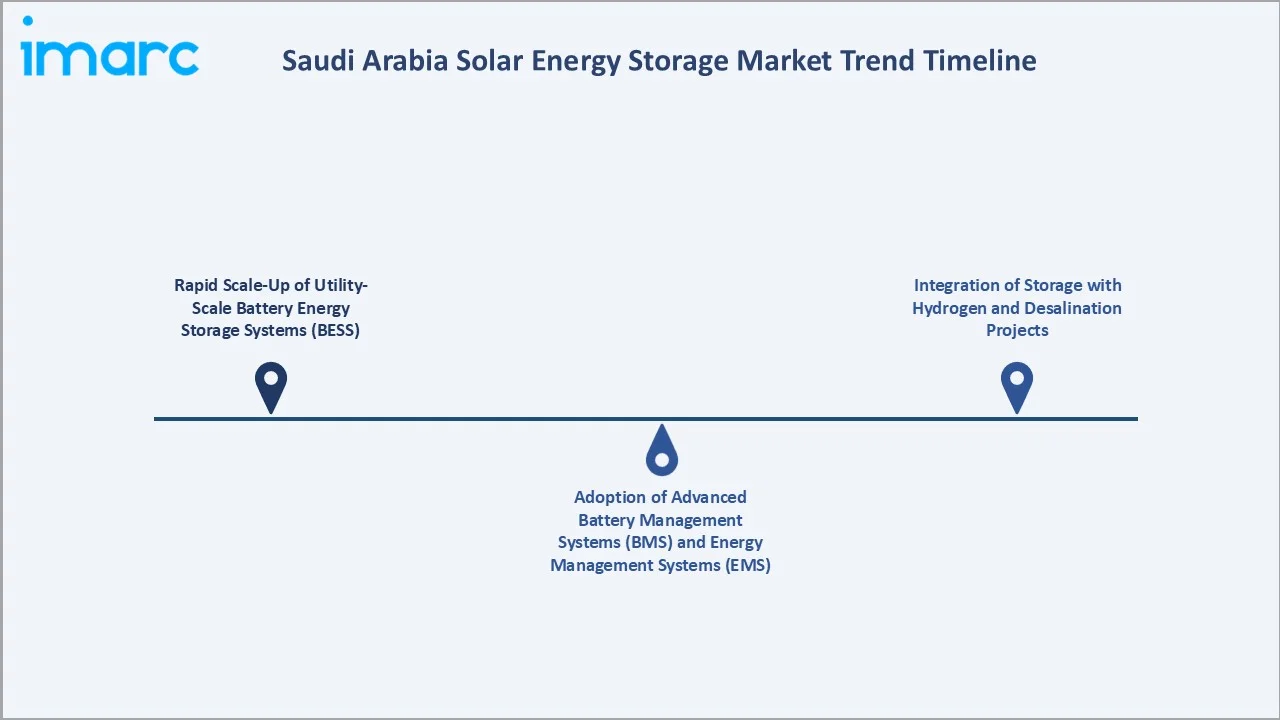
1. Rapid Scale-Up of Utility-Scale Battery Energy Storage Systems (BESS)
Saudi utility-scale solar projects are increasingly incorporating co-located battery storage as a standard component of project design. Government procurement for renewable energy under the NREP requires storage integration in a growing share of new contracts. The trend reflects a global shift toward hybrid solar-plus-storage project structures that can deliver firm, dispatchable renewable power, reducing the need for gas peakers.
2. Adoption of Advanced Battery Management Systems (BMS) and Energy Management Systems (EMS)
Project developers and system operators are deploying sophisticated BMS and EMS platforms to optimize storage dispatch, extend battery life, and maximize economic value from grid services. AI and machine learning (ML) are being integrated into EMS platforms to predict solar generation, anticipate load patterns, and schedule storage operation accordingly, enhancing asset returns.
3. Integration of Storage with Hydrogen and Desalination Projects
Saudi Arabia's emerging green hydrogen ambitions and its large-scale desalination requirements are creating new integration pathways for solar energy storage. Storage systems are being designed to buffer solar power supply for electrolyzers and reverse osmosis plants, enabling continuous operation independent of cloud cover or nighttime conditions.
Industry Value Chain Analysis
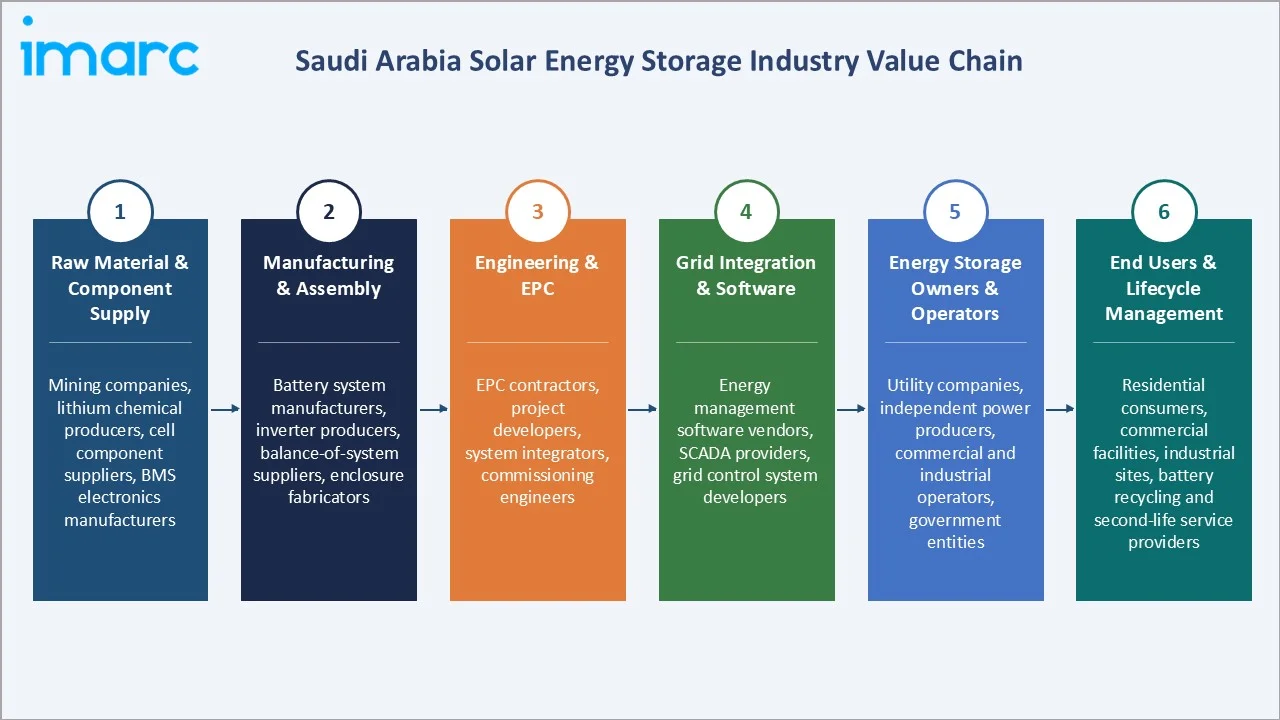
The Saudi Arabia solar energy storage value chain spans six stages, from raw material and component supply through to end-user lifecycle management. Vertically integrated global battery manufacturers that control cell production, pack assembly, and system integration hold a structural cost and quality advantage, enabling them to capture higher margins and offer more competitive pricing to Saudi project developers.
|
Stage |
Key Players / Examples |
|
Raw Material & Component Supply |
Mining companies, lithium chemical producers, cell component suppliers, BMS electronics manufacturers |
|
Manufacturing & Assembly |
Battery system manufacturers, inverter producers, balance-of-system suppliers, enclosure fabricators |
|
Engineering & EPC |
EPC contractors, project developers, system integrators, commissioning engineers |
|
Grid Integration & Software |
Energy management software vendors, SCADA providers, grid control system developers |
|
Energy Storage Owners & Operators |
Utility companies, independent power producers, commercial and industrial operators, government entities |
|
End Users & Lifecycle Management |
Residential consumers, commercial facilities, industrial sites, battery recycling and second-life service providers |
Local EPC contractors and engineering firms occupy a strategically important position as the primary interface between international technology suppliers and Saudi project owners. Strengthening local EPC capabilities in storage system commissioning and integration represents a key bottleneck and opportunity within the Kingdom's value chain.
Technology Landscape in the Saudi Arabia Solar Energy Storage Industry
Lithium-Ion Battery Technology
Lithium-ion remains the dominant storage technology, underpinned by continuous cell chemistry improvements, including lithium iron phosphate (LFP) and nickel manganese cobalt (NMC) variants, that balance energy density, cycle life, and safety. Manufacturers are extending calendar life and achieving high round-trip efficiencies, improving the economics of utility-scale deployments in Saudi Arabia's high-cycling environment.
Thermal Management Systems
Given Saudi Arabia's extreme ambient temperatures, advanced thermal management is a critical technology differentiation. Active liquid cooling and phase-change material systems are increasingly specified in utility-scale BESS contracts to maintain battery cell temperatures within optimal ranges, preserving system efficiency and extending asset life in conditions that would otherwise accelerate degradation.
Advanced BMS Platforms
Next-generation BMS platforms incorporate cell-level monitoring, predictive state-of-health algorithms, and real-time communication with EMS platforms. These systems improve safety, optimize charge/discharge cycles to maximize battery longevity, and provide operators with actionable data to schedule maintenance and forecast replacement timelines.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Lithium Ion | 61.8% |
2025 |
| Installation | On Grid | 74.2% |
2025 |
|
Region |
Northern and Central Region | 39.1% |
2025 |

By Type
Lithium ion commands a 61.8% majority share in 2025, driven by superior energy density, declining cell costs, high round-trip efficiency, and its proven performance in utility-scale solar-plus-storage projects globally. The segment benefits from a deep global supply chain and a large installed base that provides Saudi project developers with bankable technology references.
To access detailed market analysis, Request Sample
Lead acid at 23.4% in 2025 retains relevance in commercial and backup power applications where capital cost constraints outweigh the performance advantages of lithium-ion chemistry.
By Installation
On grid leads with 74.2% share in 2025, reflecting Saudi Arabia's primary focus on utility-scale solar-plus-storage projects that feed into the national transmission grid. Grid-connected systems are prioritized in NREP procurement rounds, driven by the need for frequency regulation, peak load management, and renewable energy curtailment reduction across the Kingdom's interconnected power network.
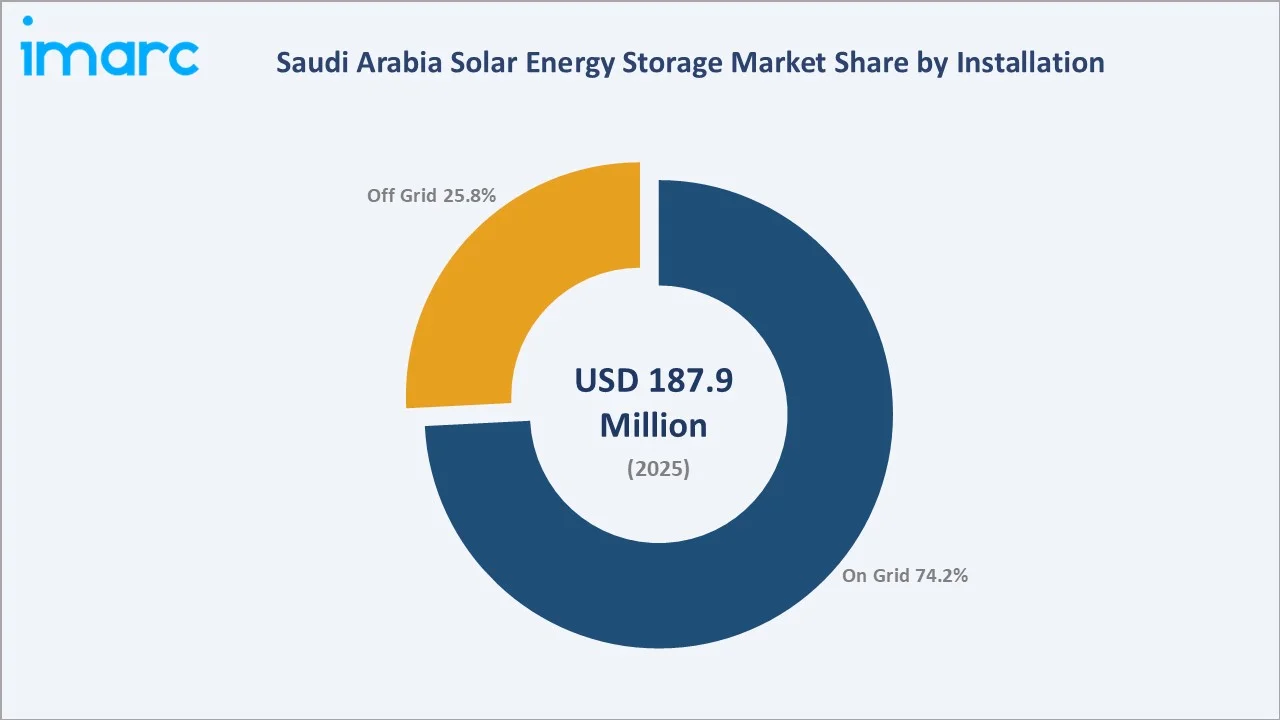
Off grid at 25.8% in 2025 is expanding across remote industrial facilities, oil and gas field electrification programs, NEOM's designated off-grid zones, and rural community electrification initiatives. Off-grid configurations are increasingly cost-competitive with diesel generation across the Kingdom's remote areas, supporting sustained segment growth through the forecast period.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Northern and Central Region |
39.1% |
High electricity demand in Riyadh, large-scale solar project pipeline, strong grid infrastructure |
|
Western Region |
28.4% |
Jeddah industrial base, Red Sea Project storage demand, port and industrial energy needs |
|
Eastern Region |
20.3% |
Oil and gas sector electrification, petrochemical industrial parks, expanding renewable capacity |
|
Southern Region |
12.2% |
Rural electrification programs, emerging solar zones, government infrastructure investment |
Northern and Central Region at 39.1% in 2025 leads the regional landscape, anchored by Riyadh's position as Saudi Arabia's administrative and commercial capital, high electricity demand concentration, and the region's proximity to major solar irradiation zones and existing high-voltage transmission infrastructure.
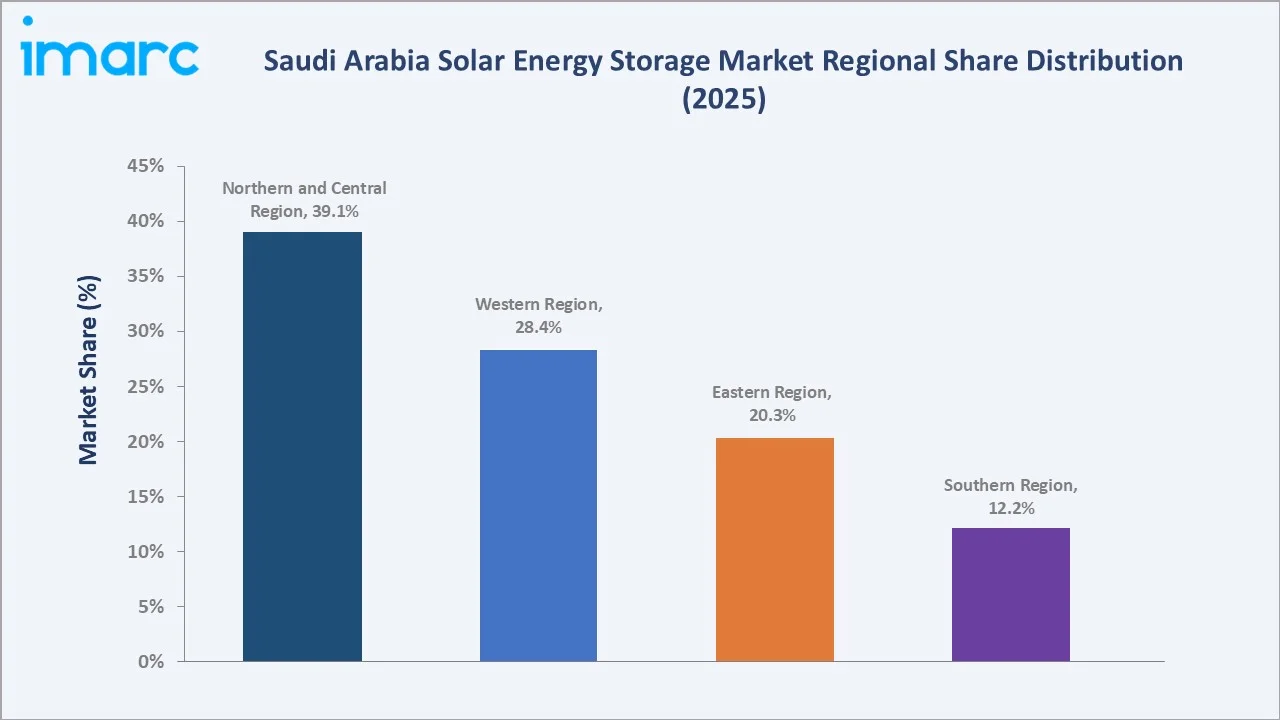
Southern Region, while currently the smallest regional contributor at 12.2%, is expanding as rural electrification programs and solar energy projects in Asir and Jizan governorates gain momentum, supported by government investment in underserved communities and industrial zones.
Competitive Landscape
The Saudi Arabia solar energy storage market is moderately concentrated, with global battery manufacturers and integrated energy technology companies competing for utility-scale project contracts, EPC partnerships, and direct supply agreements.
|
Company Name |
Key Products / Brands |
Position |
Strategic Focus |
| Contemporary Amperex Technology Co., Limited | TENER / EnerC | Leader | Expanding global utility-scale BESS deployments and strengthening supply chain localization |
| BYD Co., Ltd. | MC Cube-T / Battery-Box |
Leader |
Growing presence in utility and commercial storage through integrated battery and system solutions |
| Tesla, Inc. | Megapack / Powerwall |
Leader |
Scaling utility-scale Megapack deployments and expanding direct sales in high-growth markets |
| LG Energy Solution | LG ESS | Challenger | Expanding modular storage system portfolio and deepening EPC partnerships in the Middle East |
| ABB Ltd. | Proteus / ABB Ability |
Challenger |
Growing grid integration and energy management platform capabilities for utility storage |
Key players include Contemporary Amperex Technology Co., Limited, BYD Co., Ltd., Tesla, Inc., LG Energy Solution, and ABB Ltd., among others.
Key Company Profiles
Contemporary Amperex Technology Co., Limited
Contemporary Amperex Technology Co., Limited is a Chinese multinational corporation headquartered in Ningde, Fujian. The company supplies battery cells and integrated energy storage systems to utility-scale solar projects, grid operators, and electric vehicle manufacturers globally.
- Product Portfolio: TENER, EnerC, and other energy storage solutions designed for utility-scale, grid-connected, industrial, commercial, and renewable energy applications.
- Recent Developments: The company has continued to expand its global energy storage deployment pipeline, advancing product development and strengthening its international project delivery capabilities across key renewable energy markets.
- Strategic Focus: Growing global utility-scale BESS deployments and increasing supply chain localization across key renewable energy markets.
BYD Co., Ltd.
BYD Co., Ltd. is a Chinese conglomerate headquartered in Shenzhen, specializing in rechargeable batteries, electric vehicles, and energy storage systems. Its energy storage division supplies battery modules, pack assemblies, and complete BESS solutions for utility, commercial, and residential applications across several countries.
- Product Portfolio: MC Cube-T, Battery-Box series (residential and commercial).
- Recent Developments: The company has been actively expanding its utility-scale storage order book, deepening partnerships with energy utilities and grid operators, and growing its international delivery capabilities across high-growth storage markets.
- Strategic Focus: Expanding its presence in utility-scale and commercial energy storage through integrated battery and system solutions across international markets.
Tesla, Inc.
Tesla, Inc. is an American technology and clean energy company headquartered in Austin, Texas, designing and manufacturing electric vehicles, solar energy systems, and utility-scale battery storage solutions. Its energy division serves utility operators, independent power producers, and commercial customers with integrated storage and software platforms.
- Product Portfolio: Megapack (utility-scale BESS), Powerwall (residential).
- Recent Developments: The company has continued to scale its energy storage manufacturing and deployment operations, expanding production capacity and broadening its project delivery footprint across utility and commercial storage segments internationally.
- Strategic Focus: Increasing utility-scale Megapack deployments while strengthening its presence in rapidly expanding energy storage markets worldwide.
Market Concentration Analysis
The Saudi Arabia solar energy storage market is moderately concentrated, with a small number of global battery manufacturers and integrated energy technology companies holding the majority of project supply contracts and framework agreements with leading EPCs and utility operators.
Barriers to market entry include the capital-intensive nature of battery system manufacturing, the technical complexity of utility-scale storage integration, the requirement for bankable project references in large-scale procurement processes, and growing local content requirements under Saudi Vision 2030 industrial policy. These factors are moderating new entrant activity while incumbents consolidate their positions through scale, cost competitiveness, and deepening local partnerships.
Market consolidation is expected to increase over the forecast period as global battery manufacturers acquire niche storage technology developers, expand into software-defined energy management platforms, and pursue vertical integration strategies that improve margin and supply chain control. The competitive intensity in Saudi Arabia will remain high, driven by the scale of the project pipeline and the participation of well-capitalized global competitors.
Investment & Growth Opportunities
Fastest-Growing Segments
Flow battery is expanding fastest among type categories, driven by rising demand for long-duration energy storage as solar penetration deepens and multi-hour dispatch requirements grow across Saudi Arabia's grid. Off-grid is the fastest-growing installation segment, supported by remote industrial electrification, NEOM project demands, and declining system costs that are making solar-plus-storage competitive with diesel across a widening range of off-grid applications.
Emerging Markets
Eastern Region is the fastest-growing region, supported by expanding oil and gas sector electrification programs, development of petrochemical industrial parks with captive renewable power requirements, and a growing pipeline of independent power projects that incorporate storage as a core component of dispatchable clean energy supply.
Venture & Investment Trends
Investment activity is concentrated in utility-scale lithium-ion BESS project development, long-duration storage technology pilots, battery management software, and localization of storage system assembly in the Kingdom. International development finance institutions and green bond markets are providing additional capital for bankable Saudi storage projects aligned with sustainability criteria.
Future Market Outlook (2026-2034)
The Saudi Arabia solar energy storage market is projected to grow from USD 187.9 Million in 2025 to USD 228.7 Million in 2026, reaching USD 798.5 Million by 2034 at a CAGR of 16.92%, adding approximately USD 610.6 Million in absolute market value over the forecast period.
Four forces will shape the market through 2034: continued scale-up of utility-scale solar-plus-storage projects under the NREP; deeper integration of storage into NEOM and other giga-project energy infrastructure; growing commercial and industrial adoption driven by tariff optimization and reliability requirements; and expanding off-grid deployment serving remote industrial and rural electrification needs.
By 2034, the Saudi solar energy storage market is expected to be defined by increasingly cost-competitive, long-duration storage systems with advanced grid-forming capabilities, local content requirements driving in-Kingdom assembly and manufacturing, and digital energy management platforms optimizing multi-asset storage portfolios across the Kingdom's diversifying power system.
Research Methodology
Primary Research
Primary research included structured interviews with energy storage project developers, EPC contractors, utility company representatives, battery system manufacturers, and government energy agency officials active in the Saudi Arabian market. Insights from primary sources were used to validate market size estimates, growth drivers, and competitive dynamics identified through secondary research.
Secondary Research
Secondary sources included SEC publications, Ministry of Energy announcements, Vision 2030 delivery office reports, IRENA global renewable energy statistics, BNEF energy storage market assessments, SEC annual reports, company annual reports and investor presentations, and publicly available project databases for Saudi solar and storage project deployments.
Forecasting Models
Market forecasts used top-down and bottom-up models combining installed solar capacity projections, storage attachment rate assumptions, average system cost trajectories, and project pipeline data. Macroeconomic inputs including oil price assumptions, Saudi government capital expenditure budgets, and electricity demand growth models were incorporated to stress-test base-case forecasts.
Saudi Arabia Solar Energy Storage Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Lead Acid, Lithium Ion, Flow Battery, Others |
| Installations Covered | On grid, Off grid |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Contemporary Amperex Technology Co., Limited, BYD Co., Ltd., Tesla, Inc., LG Energy Solution, ABB Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia solar energy storage market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia solar energy storage market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia solar energy storage industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Solar Energy Storage Market Report
The Saudi Arabia solar energy storage market size is estimated at USD 228.7 Million in 2026, driven by accelerating solar project deployment, falling lithium-ion battery costs, and strong policy support under Vision 2030 renewable energy targets.
The market is projected to grow at a CAGR of 16.92% from 2026-2034, reaching USD 798.5 Million, supported by large-scale NREP project execution, giga-project energy storage requirements, and expanding commercial and industrial storage adoption.
Lithium ion leads the type segment at 61.8% in 2025, driven by superior energy density, declining cell costs, and its proven track record in utility-scale solar-plus-storage projects globally and within the Kingdom.
On grid dominates the installation segment at 74.2% in 2025, reflecting the prevalence of government-backed utility-scale solar projects requiring grid-connected battery storage for frequency regulation and peak load management.
Northern and Central Region commands 39.1% share in 2025, led by Riyadh's high electricity demand concentration, strong transmission infrastructure, and proximity to large solar irradiation zones suitable for utility-scale solar-plus-storage development.
Leading players include Contemporary Amperex Technology Co., Limited, BYD Co., Ltd., Tesla, Inc., LG Energy Solution, and ABB Ltd., among others.
Vision 2030 is supporting the growth of the market by promoting renewable energy development, strengthening energy infrastructure, and encouraging investment in clean energy technologies. These initiatives are creating a favorable environment for the adoption of energy storage solutions across the Kingdom.
Key investment opportunities include solar-plus-storage projects, battery energy storage systems, grid-connected storage solutions, off-grid applications, and related energy management technologies. Growing renewable energy deployment and increasing demand for reliable power are expected to create further opportunities across the market.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade