
Tobacco Packaging Market Size, Share, Trends and Forecast by Material Type, Packaging Type, End Use, and Region, 2026-2034
Tobacco Packaging Market Size, Share, Trends & Forecast (2026-2034)
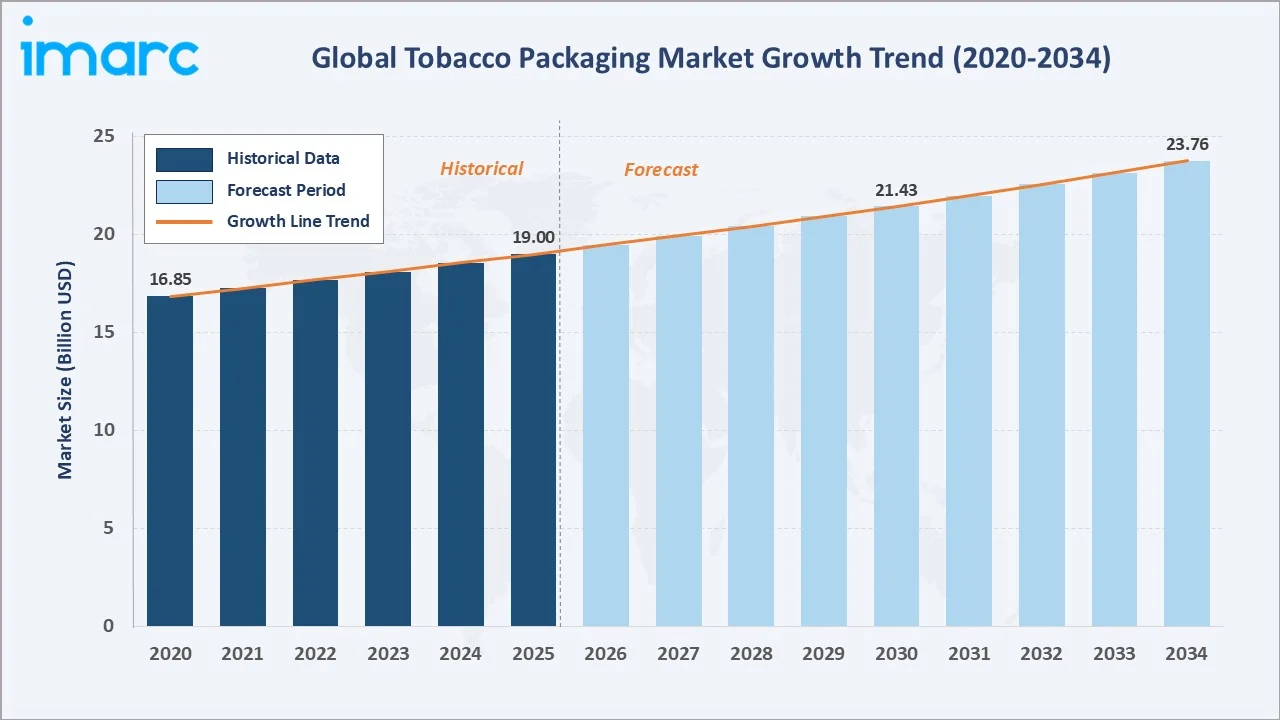
The tobacco packaging market grew from USD 19.00 Billion in 2025 to USD 19.47 Billion in 2026 and is projected to reach USD 23.76 Billion by 2034, exhibiting a CAGR of 2.44% during 2026-2034. Rising demand for tamper-evident and regulatory-compliant packaging solutions is a primary driver shaping market growth.
Paper boxes dominate material type at 38.5%, secondary packaging commands the largest share at 52.4% within the packaging type segment, and Asia-Pacific leads the regional landscape with 48.2% share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 19.00 Billion |
|
Market Size (2026) |
USD 19.47 Billion |
|
Forecast Market Size (2034) |
USD 23.76 Billion |
|
CAGR (2026-2034) |
2.44% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Asia-Pacific (48.2%, 2025) |
|
Second Largest Region |
Europe (18.7%, 2025) |
|
Leading Material Type |
Paper Boxes (38.5%, 2025) |
|
Leading Packaging Type |
Secondary Packaging (52.4%, 2025) |
The tobacco packaging market size increased from USD 16.85 Billion in 2020 to USD 19.00 Billion in 2025 and is estimated to reach USD 19.47 Billion in 2026. The market is further expected to grow to USD 21.43 Billion by 2030 and USD 23.76 Billion by 2034. Stringent plain packaging mandates across several countries are driving standardization toward paper-based formats, while expanding tobacco consumption in Asia-Pacific, Latin America, and Middle East and Africa sustains packaging demand across cigarettes, cigars, and smokeless tobacco formats.
To get more information on this market, Request Sample
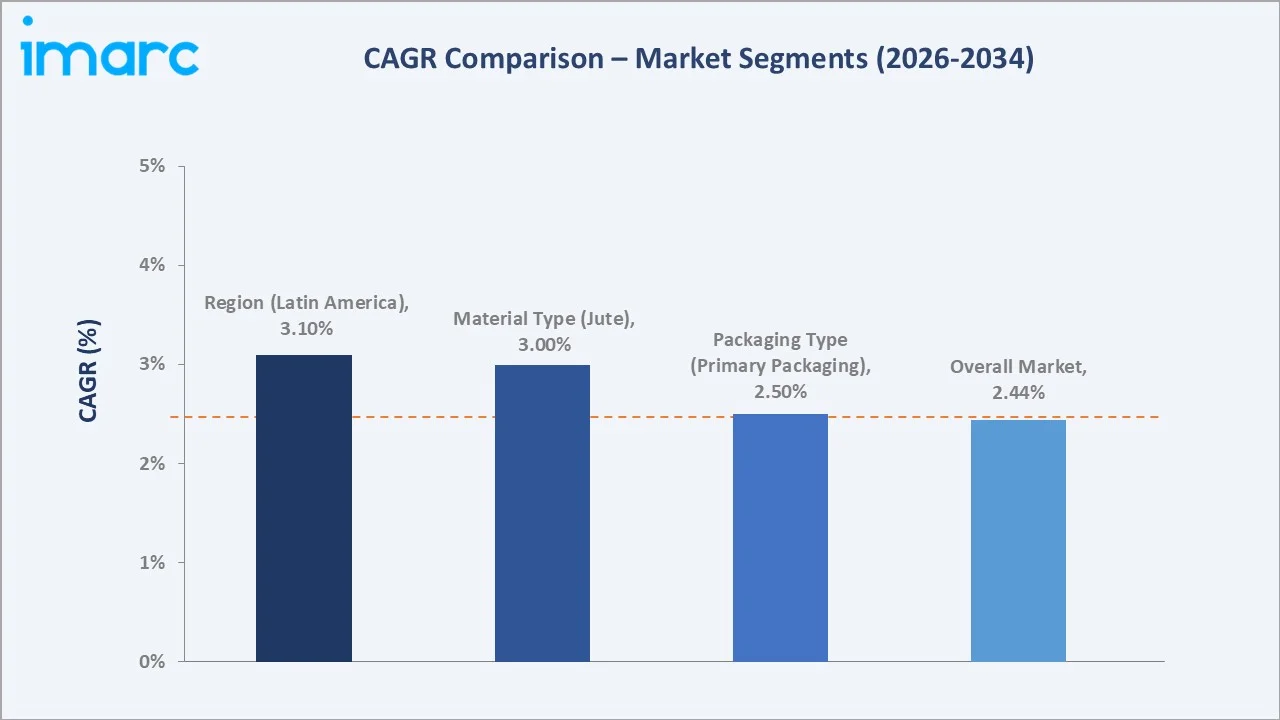
CAGR trajectories across material type, packaging type, and regional sub-segments indicate that bulk packaging and Latin America are expanding faster than the overall 2.44% market CAGR, driven by increasing demand for cost-efficient packaging solutions, expanding industrial and commercial applications, and rising trade and distribution activities across the region.
Executive Summary
The tobacco packaging market expanded from USD 19.00 Billion in 2025 to an estimated USD 19.47 Billion in 2026. The industry has evolved from commodity-driven production to a compliance-intensive, design-forward sector responding to stringent regulatory frameworks, rising consumer expectations for premium formats, and a broad shift toward sustainable and recyclable materials across key markets.
Paper boxes command a 38.5% material type share in 2025, underpinned by regulatory compliance requirements and consumer familiarity with rigid box formats for premium cigarette brands. Secondary packaging leads with 52.4% share, serving wholesale logistics and retail display functions critical to the tobacco supply chain. Asia-Pacific commands 48.2% of the global market, underpinned by large tobacco production bases in China, Indonesia, and India.
Key Market Insights
|
Insight |
Data |
|
Leading Material Type |
Paper Boxes – 38.5% share (2025) |
|
Second Largest Material Type |
Paperboards – 21.7% share (2025) |
|
Leading Packaging Type |
Secondary Packaging – 52.4% share (2025) |
|
Second Largest Packaging Type |
Primary Packaging – 28.6% share (2025) |
|
Leading Region |
Asia-Pacific – 48.2% share (2025) |
|
Second Largest Region |
Europe – 18.7% share (2025) |
|
Top Companies |
Amcor plc, Mondi plc, CCL Industries Inc. |
Key Analytical Observations Expanding On the Data Above:
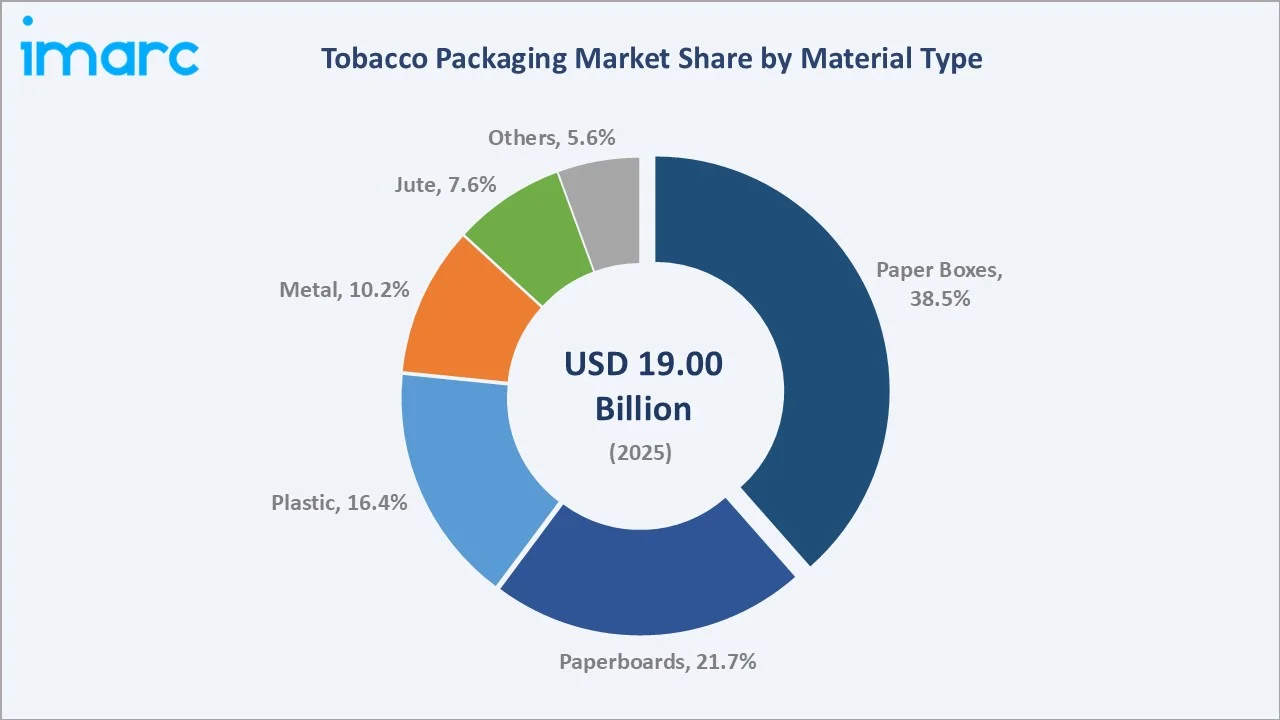
- Paper boxes dominance at 38.5% is driven by stringent regulatory requirements mandating standardized packaging dimensions, graphic health warnings, and tamper-evident features on primary cigarette boxes across regulated markets.
- Paperboards at 21.7% reflect growing use in carton-level secondary packaging and premium cigar boxes, supported by their versatility in printing, structural rigidity, and compatibility with specialty coatings for brand differentiation.
- Secondary packaging leadership at 52.4% is underpinned by the critical role of outer cartons, master cases, and shipper boxes in protecting products through the tobacco supply chain from factory floor to retail shelf.
- Primary packaging at 28.6% maintains a significant role due to its direct function in containing and protecting tobacco products, while providing essential branding, product identification, and regulatory information at the point of sale.
- Asia-Pacific at 48.2% leads the market, anchored by strong tobacco production and consumption, extensive cigarette manufacturing capacity, and established packaging supply chains across major regional markets.
Tobacco Packaging Market Overview
Tobacco packaging encompasses all packaging materials and solutions used to contain, protect, display, and distribute tobacco products including cigarettes, cigars, smokeless tobacco, and pipe tobacco. It spans primary, secondary, and bulk packaging formats, integrating regulatory compliance design, brand communication, and supply chain protection functions within a single packaging system.
The ecosystem integrates raw material suppliers, specialty paper and paperboard producers, printing and converting firms, packaging manufacturers, tobacco companies, distributors, and regulatory bodies. Together, these stakeholders navigate a complex regulatory environment shaped by the WHO Framework Convention on Tobacco Control, national plain packaging laws, and graphic health warning mandates that increasingly define allowable packaging formats across markets.
Market Dynamics
To evaluate market opportunities, Request Sample
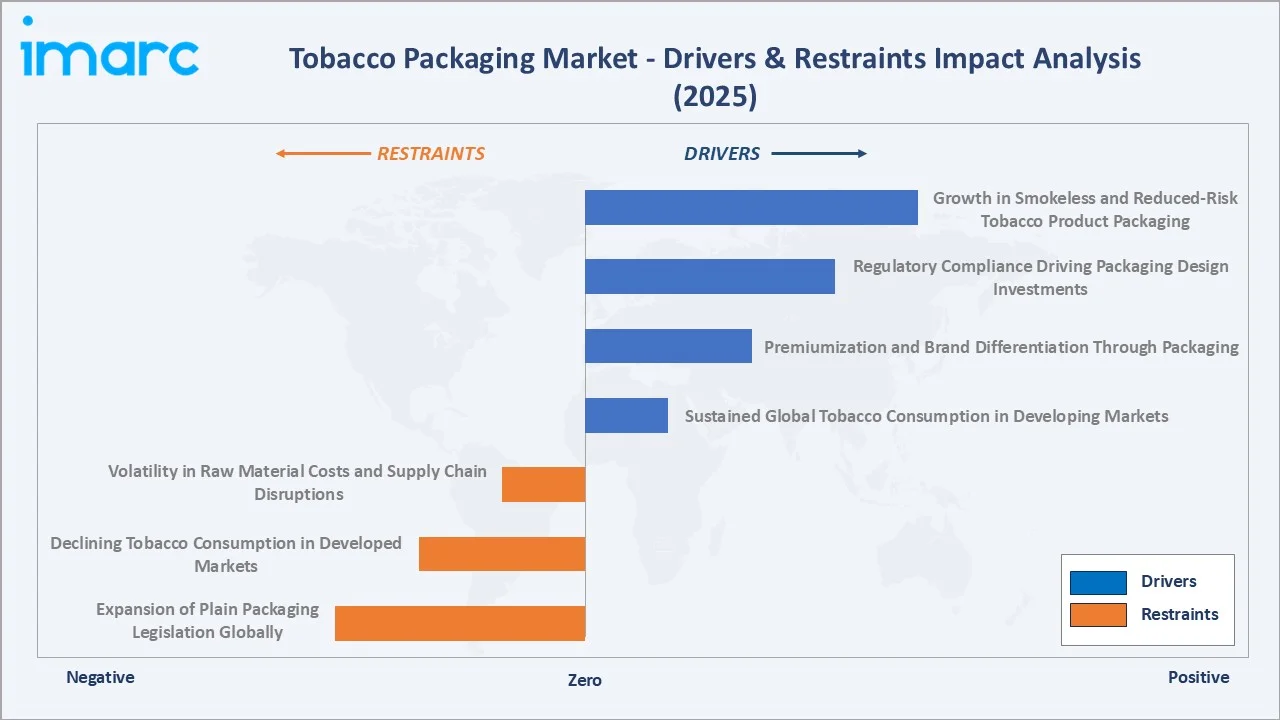
Market Drivers
- Sustained Global Tobacco Consumption in Developing Markets: High and relatively stable tobacco consumption rates across Asia, Africa, and parts of Latin America continue to generate consistent demand across the global tobacco packaging market for all product categories.
- Premiumization and Brand Differentiation Through Packaging: Tobacco companies are increasingly investing in premium packaging formats, specialty printing techniques, embossing, and unique structural designs to differentiate brands in a tightly regulated market where traditional advertising channels are restricted or banned in many jurisdictions.
- Regulatory Compliance Driving Packaging Design Investments: Evolving packaging regulations are increasing the need for compliant designs that incorporate health warnings, product information, traceability elements, and tamper-evident features, encouraging tobacco manufacturers to invest in packaging formats that meet changing regulatory requirements.
- Growth in Smokeless and Reduced-Risk Tobacco Product Packaging: The expansion of smokeless tobacco, heated tobacco products, and oral nicotine pouches is generating demand for specialized, small-format packaging solutions with precision-engineered closures, moisture barriers, and child-resistant features.
Market Restraints
- Expansion of Plain Packaging Legislation Globally: Increasing adoption of standardized or plain packaging laws, which restrict brand logos, colors, and design elements on tobacco packaging, is constraining premium packaging demand and limiting innovation opportunities for packaging manufacturers in regulated markets.
- Declining Tobacco Consumption in Developed Markets: Long-term structural decline in tobacco consumption across Western Europe, North America, and Australia, driven by increasing health awareness and stricter regulation, is creating volume headwinds for packaging demand in these traditionally high-value regional markets.
- Volatility in Raw Material Costs and Supply Chain Disruptions: Fluctuations in paper pulp, aluminum, and plastic resin prices, compounded by periodic logistics disruptions, create cost uncertainty for packaging manufacturers operating on thin margins in a commoditized segment of the tobacco supply chain.
Market Opportunities
- Transition to Sustainable and Recyclable Packaging Materials: Growing regulatory and consumer pressure for eco-friendly packaging is creating significant opportunity for manufacturers offering recyclable paperboard, biodegradable films, and FSC-certified paper solutions as alternatives to conventional plastic and composite packaging materials.
- Smart and Digital Packaging Integration: The integration of QR codes, NFC tags, and digital authentication features into tobacco packaging is creating new opportunities for brand engagement, supply chain traceability, and anti-counterfeiting, particularly in markets with high illicit tobacco trade volumes.
- Expanding Tobacco Markets in Africa and Southeast Asia: Rising disposable incomes, urbanization, and tobacco market formalization across Sub-Saharan Africa and Southeast Asian markets are expanding the addressable base for branded, compliant tobacco packaging solutions.
Market Challenges
- Increasing Complexity of Multi-Country Regulatory Compliance: Managing packaging designs that simultaneously comply with differing health warning sizes, languages, colors, and placement requirements across multiple jurisdictions creates significant operational and cost complexity for tobacco companies and their packaging suppliers.
- Counterfeit and Illicit Trade Impact on Premium Packaging Demand: The large-scale illicit tobacco trade in several markets, particularly in Asia and Africa, undermines demand for compliant branded packaging by creating volume channels that bypass regulated packaging requirements entirely.
Emerging Market Trends
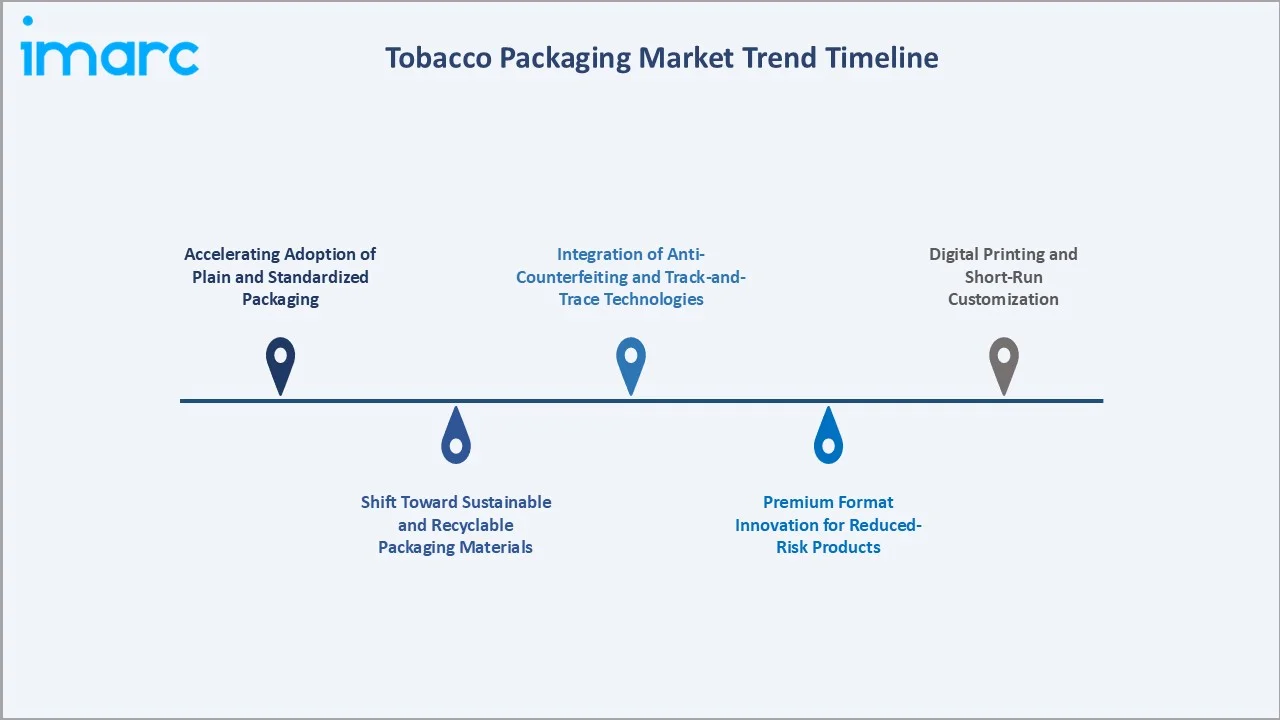
1. Accelerating Adoption of Plain and Standardized Packaging
Plain packaging legislation has expanded rapidly across global markets. By November 2025, 27 countries had adopted standardized or plain tobacco packaging laws, fundamentally reshaping packaging design requirements and shifting competitive differentiation from visual branding to product format and positioning.
2. Shift Toward Sustainable and Recyclable Packaging Materials
Growing regulatory pressure on single-use plastics and increasing corporate sustainability commitments are driving tobacco companies and packaging suppliers to transition toward FSC-certified paperboard, recyclable films, and biodegradable closures. This shift is reshaping material sourcing and production workflows, with the tobacco packaging market size expected to reflect this material transition through 2034.
3. Integration of Anti-Counterfeiting and Track-and-Trace Technologies
The integration of tax stamps, digital authentication codes, serialization, and track-and-trace systems into tobacco packaging is expanding as governments and industry stakeholders strengthen efforts to combat illicit trade. These technologies add value-added complexity to packaging specifications and create ongoing demand for specialist printing and coding capabilities.
4. Premium Format Innovation for Reduced-Risk Products
The rapid growth of heated tobacco products, oral nicotine pouches, and e-cigarette categories is generating demand for innovative, small-format packaging with precision-engineered closures, moisture management features, and premium structural designs. These categories are driving packaging complexity and value-add above traditional cigarette packaging benchmarks.
5. Digital Printing and Short-Run Customization
Advances in digital printing technologies are enabling tobacco companies to produce shorter production runs with country-specific health warnings, limited-edition designs, and region-specific regulatory variants without incurring traditional plate change costs. This flexibility is particularly valuable in markets requiring rapid compliance updates.
Industry Value Chain Analysis
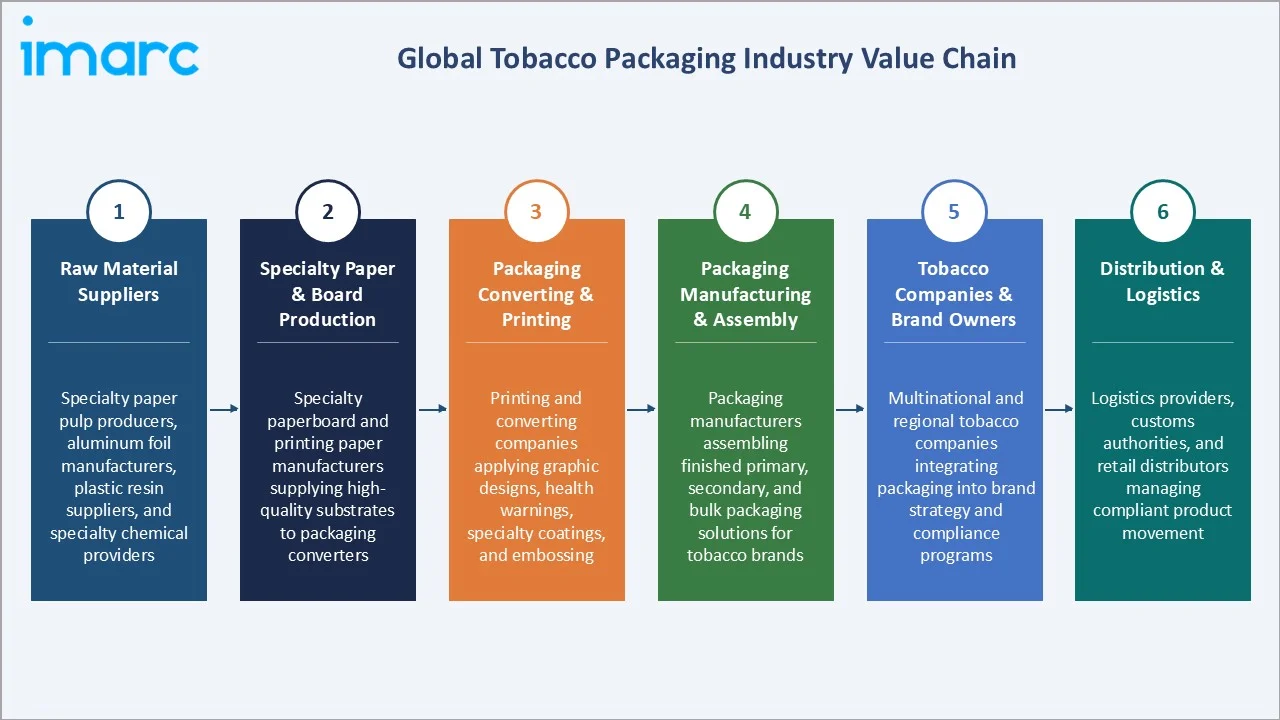
The tobacco packaging value chain spans six stages, from raw material extraction and paper pulp production through end-user consumption and packaging disposal. Converting and printing stages capture the highest share of value-add, while regulatory compliance integration and anti-counterfeiting capabilities increasingly determine competitive differentiation.
|
Stage |
Key Players / Examples |
|
Raw Material Suppliers |
Specialty paper pulp producers, aluminum foil manufacturers, plastic resin suppliers, and specialty chemical providers enabling ink, coating, and adhesive production |
|
Specialty Paper & Board Production |
Specialty paperboard and printing paper manufacturers supplying high-quality substrates to packaging converters and printing firms |
|
Packaging Converting & Printing |
Printing and converting companies applying graphic designs, health warnings, specialty coatings, embossing, and structural forming to raw materials |
|
Packaging Manufacturing & Assembly |
Packaging manufacturers assembling finished primary, secondary, and bulk packaging solutions for tobacco brands across global markets |
|
Tobacco Companies & Brand Owners |
Multinational and regional tobacco companies integrating packaging into brand strategy, compliance programs, and supply chain operations |
|
Distribution & Logistics |
Logistics providers, customs authorities, and retail distributors managing compliant product movement from manufacturing to retail channels |
Packaging manufacturers with integrated printing capabilities and compliance design expertise are positioned to capture greater value than commodity converters, as the regulatory complexity of tobacco packaging continues to increase globally.
Technology Landscape in the Tobacco Packaging Industry
Advanced Printing and Finishing Technologies
High-definition offset, gravure, and flexographic printing combined with specialty finishing processes including hot foil stamping, UV varnishing, and embossing enable tobacco packaging manufacturers to deliver premium aesthetics and tactile differentiation within increasingly constrained regulatory design parameters.
Sustainable Material Innovation
Development of FSC-certified paperboard grades, biodegradable film laminates, and water-based inks and coatings is enabling packaging manufacturers to reduce environmental impact while maintaining the barrier properties and print quality required by tobacco brands and regulatory specifications.
Smart Packaging and Digital Authentication
Serialization platforms, QR codes, NFC tags, and digital authentication features are increasingly being integrated into tobacco packaging to support product traceability, anti-counterfeiting efforts, and regulatory compliance, strengthening the role of authenticated and connected packaging formats in the tobacco packaging market share.
Automated Manufacturing and Quality Control
Inline vision inspection systems, automated defect detection, and high-speed robotic case-packing solutions are improving manufacturing efficiency and compliance verification in tobacco packaging production, reducing waste and ensuring consistent health warning placement in line with regulatory requirements.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Material Type |
Paper boxes |
38.5% |
2025 |
|
Packaging Type |
Secondary packaging |
52.4% |
2025 |
|
End Use |
Smoking Tobacco |
🔒 |
2025 |
|
Region |
Asia-Pacific |
48.2% |
2025 |

By Material Type
Paper boxes command a 38.5% majority share in 2025, driven by their dominant use in cigarette packaging across both premium and mainstream brands. The segment benefits from the global regulatory shift toward standardized packaging formats, which have reinforced the paper box as the default primary packaging format across most regulated markets.
To access detailed market analysis, Request Sample
Paperboards at 21.7% in 2025 serve secondary and display packaging applications, including outer cartons and point-of-sale display units.
By Packaging Type
Secondary packaging leads with 52.4% share in 2025, encompassing the outer cartons, multi-pack formats, and shipper cases that protect and transport tobacco products through the distribution chain. This segment's dominance reflects the logistical importance of outer packaging in ensuring product integrity and regulatory compliance from manufacturing to retail.
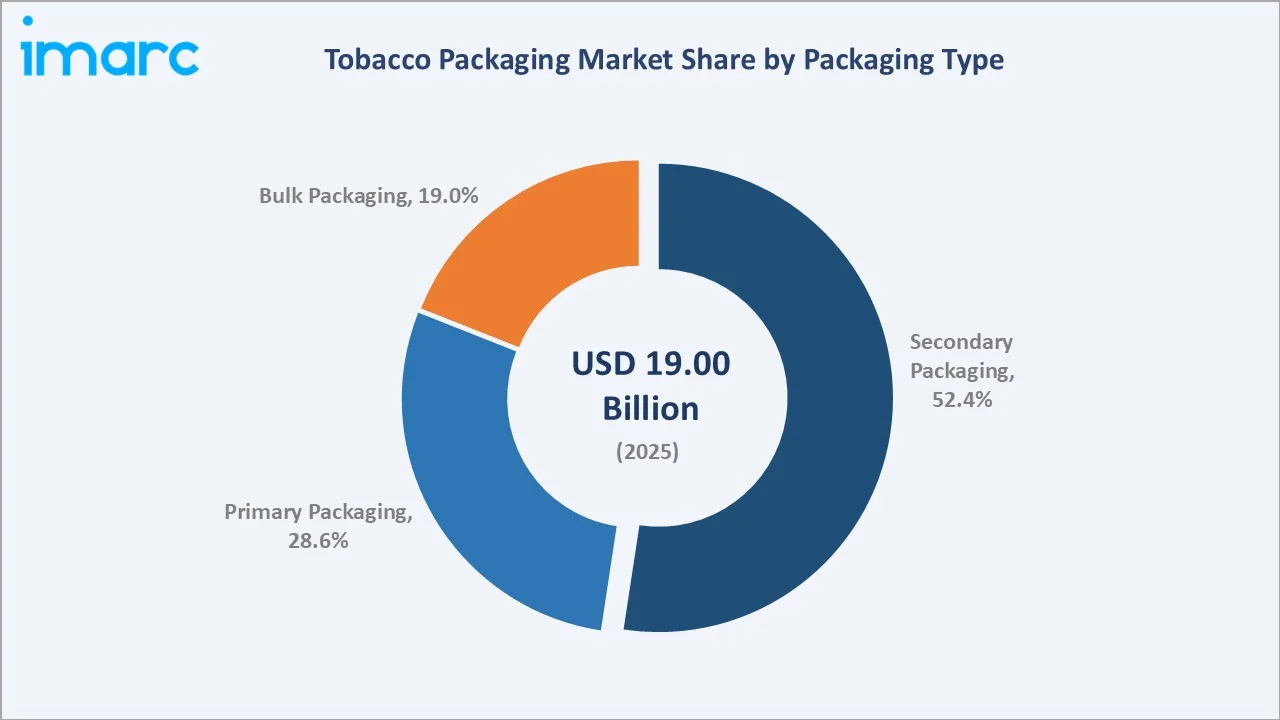
Primary packaging at 28.6% in 2025 covers the direct consumer-facing packaging that contains the individual tobacco product, including cigarette packs, cigar tubes, and pouch formats.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Asia-Pacific |
48.2% |
Large tobacco production base, growing domestic consumption, and strong demand from China, Indonesia, India, and Vietnam
|
|
Europe |
18.7% |
Premium packaging demand, high regulatory compliance investment, and sustained demand from established tobacco markets |
|
North America |
14.3% |
Mature market with steady replacement demand and growing smokeless and alternative product packaging segments |
|
Middle East and Africa |
10.6% |
Growing tobacco markets, expanding retail formalization, and rising brand adoption in urban centers |
|
Latin America |
8.2% |
Urbanization, rising disposable income, growing branded tobacco demand, and expanding formal retail channels |
Asia-Pacific at 48.2% in 2025 leads the tobacco packaging landscape, anchored by high tobacco production and consumption, extensive cigarette manufacturing capacity, and well-established packaging supply chains across major regional markets.
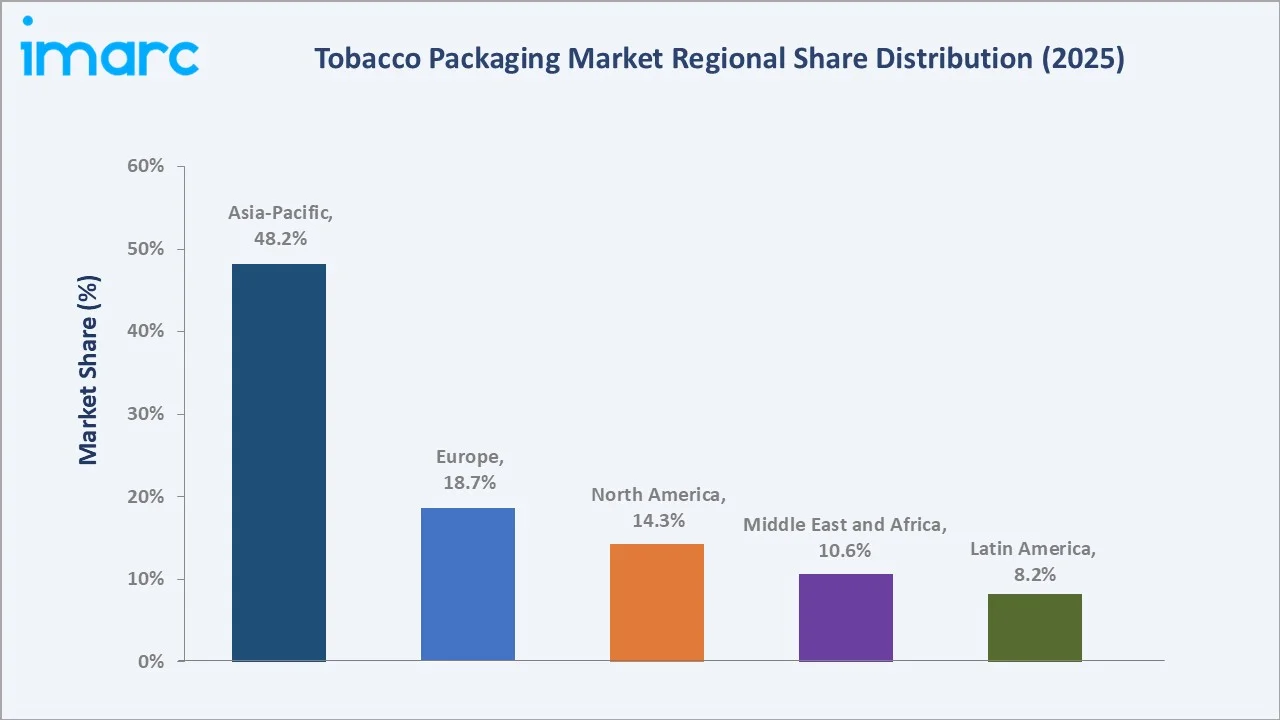
Europe at 18.7% is supported by established tobacco manufacturing industries, mature packaging infrastructure, and stringent regulatory requirements that encourage demand for compliant and specialized packaging solutions.
Competitive Landscape
The tobacco packaging market is moderately consolidated, with global packaging majors competing on scale, material innovation, geographic reach, and regulatory compliance expertise. The ability to deliver multi-format, multi-country compliant packaging solutions at volume scale while integrating sustainability and anti-counterfeiting capabilities defines the competitive frontier.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
Amcor plc |
Amcor Flexible Packaging Solutions |
Leader |
Expanding sustainable tobacco packaging solutions and growing lightweight material portfolios across regulated markets globally |
|
Mondi plc |
Barrier Papers |
Leader |
Strengthening paper-based and flexible packaging capabilities and expanding sustainable offerings for tobacco applications |
|
CCL Industries Inc. |
Innovia Films |
Challenger |
Advancing specialty BOPP film solutions for tobacco overwrap and flexible packaging through sustainable material innovation |
Key players include Amcor plc, Mondi plc, and CCL Industries Inc., among others.
Key Company Profiles
Amcor plc
Amcor plc is a global packaging company headquartered in Zurich, Switzerland, and one of the world's leading suppliers of flexible packaging for the tobacco industry, serving major tobacco manufacturers across several countries with a broad portfolio of film-based, paper-based, and foil packaging solutions.
- Product Portfolio: Flexible packaging films, lightweight cigarette wrapping films, aluminum foil laminates, barrier packaging formats, and specialty folding cartons for tobacco applications, including sustainable and recyclable alternatives.
- Recent Developments: Amcor plc continues to advance its packaging innovation capabilities through investments in materials science and sustainable packaging development, maintaining its position as a preferred supplier to leading global tobacco brands.
- Strategic Focus: Delivering sustainable flexible packaging solutions by integrating recyclable material innovations into tobacco packaging formats and expanding supply capabilities across high-growth regulatory markets globally.
Mondi plc
Mondi plc is an international packaging and paper company, recognized for its barrier papers, flexible packaging, and specialty kraft paper solutions serving the tobacco packaging supply chain across European and global markets.
- Product Portfolio: Specialty kraft papers, folding boxboards, barrier-coated papers, flexible packaging formats, and inner liner solutions for tobacco wrapping and secondary packaging applications under its Barrier Papers brand.
- Recent Developments: Mondi plc continues to strengthen its packaging portfolio through ongoing investment in fiber-based and sustainable packaging solutions, with a focus on recyclable barrier papers for tobacco and consumer goods markets.
- Strategic Focus: Strengthening fiber-based barrier packaging capabilities and expanding paper-based tobacco packaging offerings across European and emerging market distribution channels through scalable sustainable production technologies.
CCL Industries Inc.
CCL Industries Inc. is a global specialty packaging company headquartered in Toronto, Canada, and the parent company of Innovia Films, a leading manufacturer of BOPP films used in tobacco overwrap, cigarette packaging, and specialty flexible packaging formats worldwide.
- Product Portfolio: Specialty BOPP films for tobacco unit overwrap and packaging, specialty label films, sustainable and recyclable BOPP film formats, and barrier film solutions under the Innovia Films brand for global tobacco packaging markets.
- Recent Developments: CCL Industries Inc. continues to advance its Innovia Films division's sustainable packaging capabilities, with ongoing development of bio-based and recycled content film options for tobacco and consumer packaging applications.
- Strategic Focus: Advancing specialty BOPP overwrap film technologies and expanding sustainable film portfolios to address growing compliance and recyclability requirements in regulated tobacco packaging markets globally.
Market Concentration Analysis
The tobacco packaging market is moderately consolidated at the global level, with leading packaging majors capturing a significant share of total market revenue through their scale advantages, integrated manufacturing capabilities, and established relationships with multinational tobacco companies.
Barriers to entry include capital-intensive specialized printing and converting equipment, the need for extensive compliance expertise across multiple regulatory jurisdictions, long-term supply contracts with tobacco majors, and the scale required to serve global tobacco brands with consistent quality across geographies.
Consolidation is accelerating as major packaging groups expand through strategic acquisitions to broaden their product portfolios, strengthen regional manufacturing capabilities, enhance production efficiency, and deepen relationships with tobacco manufacturers.
Investment & Growth Opportunities
Fastest-Growing Segments
Bulk packaging represents the fastest growing packaging type segment, driven by rising demand for efficient transportation and storage solutions, greater emphasis on supply chain protection, and the need for durable packaging formats across tobacco distribution networks.
Emerging Markets
Latin America presents an emerging growth opportunity, supported by established tobacco consumption, expanding packaged tobacco product distribution, and increasing demand for compliant packaging formats. Growing regulatory requirements and efforts to curb illicit trade are also encouraging manufacturers to adopt more secure, traceable, and specialized packaging solutions.
Venture & Investment Trends
Capital is flowing into sustainable and recyclable packaging material development, particularly FSC-certified paperboard, biodegradable films, and water-based coating technologies. Investment is also directed toward track-and-trace and digital authentication integration capabilities as governments tighten anti-illicit trade packaging requirements globally.
Future Market Outlook (2026-2034)
The tobacco packaging market is projected to grow from USD 19.00 Billion in 2025 to USD 19.47 Billion in 2026, reaching USD 23.76 Billion by 2034, registering a CAGR of 2.44% during 2026-2034, adding roughly USD 4.76 Billion in incremental market value over the forecast period.
Four forces will shape the market through 2034: continued regulatory expansion of plain and standardized packaging mandates; accelerating industry transition to sustainable and recyclable packaging materials; growing demand for track-and-trace and digital authentication capabilities; and expanding tobacco packaging demand from developing markets in Asia-Pacific and Latin America.
By 2034, the tobacco packaging market is expected to be defined by a strong paper-and-board material predominance, a growing share of sustainable material formats, and increasing technological complexity in packaging design and authentication. Continued regulatory pressure in developed markets will be offset by volume growth from developing markets, sustaining the overall positive trajectory.
Research Methodology
Primary Research
Primary research included structured interviews with tobacco packaging manufacturers, tobacco company procurement and packaging executives, material suppliers, and industry compliance specialists, validating market sizing, segment mix, and regional demand patterns across key markets.
Secondary Research
Secondary sources included WHO tobacco reports and FCTC documentation, national regulatory authority publications on tobacco packaging requirements, industry association data, company annual reports, press releases, and investor presentations from listed packaging companies and tobacco majors.
Forecasting Models
Market forecasts used top-down and bottom-up models combining tobacco production and consumption volume trends, packaging material adoption rates, regulatory transition timelines, and macroeconomic variables. Scenario analysis addressed regulatory developments, sustainability transitions, and tobacco consumption trajectory assumptions.
Tobacco Packaging Market Report Scope:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Material Types Covered | Paperboards, Paper Boxes, Plastic, Jute, Metal, Others |
| Packaging Types Covered | Primary Packaging, Secondary Packaging, Bulk Packaging |
| End Uses Covered |
|
| Regions Covered | Asia Pacific, Europe, North America, Latin America, Middle East and Africa |
| Companies Covered | Amcor plc, Mondi plc, CCL Industries Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the tobacco packaging market from 2020-2034.
- The research study provides the latest information on the market drivers, challenges, and opportunities in the global tobacco packaging market.
- The study maps the leading, as well as the fastest-growing, regional markets.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the tobacco packaging industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Tobacco Packaging Market Report
The tobacco packaging market size is estimated at USD 19.47 Billion in 2026, driven by sustained tobacco consumption in developing markets, evolving regulatory compliance requirements, and growing demand for premium and sustainable packaging formats.
The market is projected to grow at a CAGR of 2.44% from 2026-2034, reaching USD 23.76 Billion, supported by expanding tobacco markets in developing regions and industry transition toward sustainable packaging materials.
Paper boxes lead the material type segment with a 38.5% share in 2025, driven by their dominant role in cigarette packaging globally and alignment with regulatory requirements for standardized packaging formats.
Secondary packaging commands the largest share at 52.4% in 2025, reflecting the critical role of outer cartons and multi-pack formats in protecting and transporting tobacco products through the distribution supply chain.
Asia-Pacific commands 48.2% share in 2025, led by high tobacco production and consumption, extensive cigarette manufacturing capacity, and established packaging supply chains across major regional markets.
Leading players include Amcor plc, Mondi plc, and CCL Industries Inc., among others.
Growing regulatory and corporate pressure for eco-friendly packaging is driving the transition toward FSC-certified paperboard, recyclable films, and biodegradable materials, reshaping material sourcing and production across the tobacco packaging supply chain.
Key challenges include managing multi-country regulatory compliance complexity, addressing rising raw material cost volatility, navigating declining tobacco volumes in developed markets, and managing the competitive impact of illicit trade on compliant packaging demand.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade