
UK Cybersecurity Market Size, Share, Trends and Forecast by Component, Deployment Type, User Type, Industry Vertical, and Region, 2026-2034
UK Cybersecurity Market Size, Share, Trends & Forecast (2026-2034)
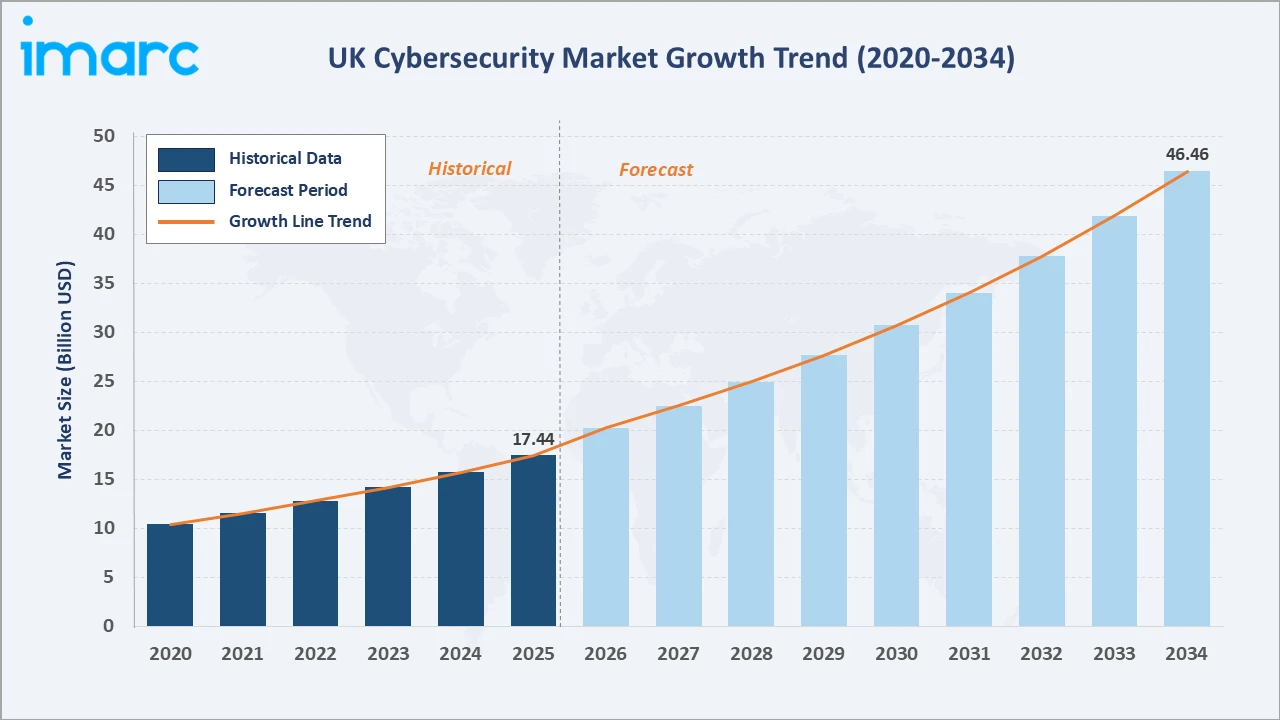
The UK cybersecurity market grew from USD 17.44 Billion in 2025 to USD 20.27 Billion in 2026 and is projected to reach USD 46.46 Billion by 2034, exhibiting a CAGR of 10.93% during 2026-2034. Surging adoption of cloud-based security solutions, rising frequency of sophisticated cyberattacks targeting critical infrastructure, and expanding digital transformation initiatives across enterprises and government agencies are the primary forces shaping market growth.
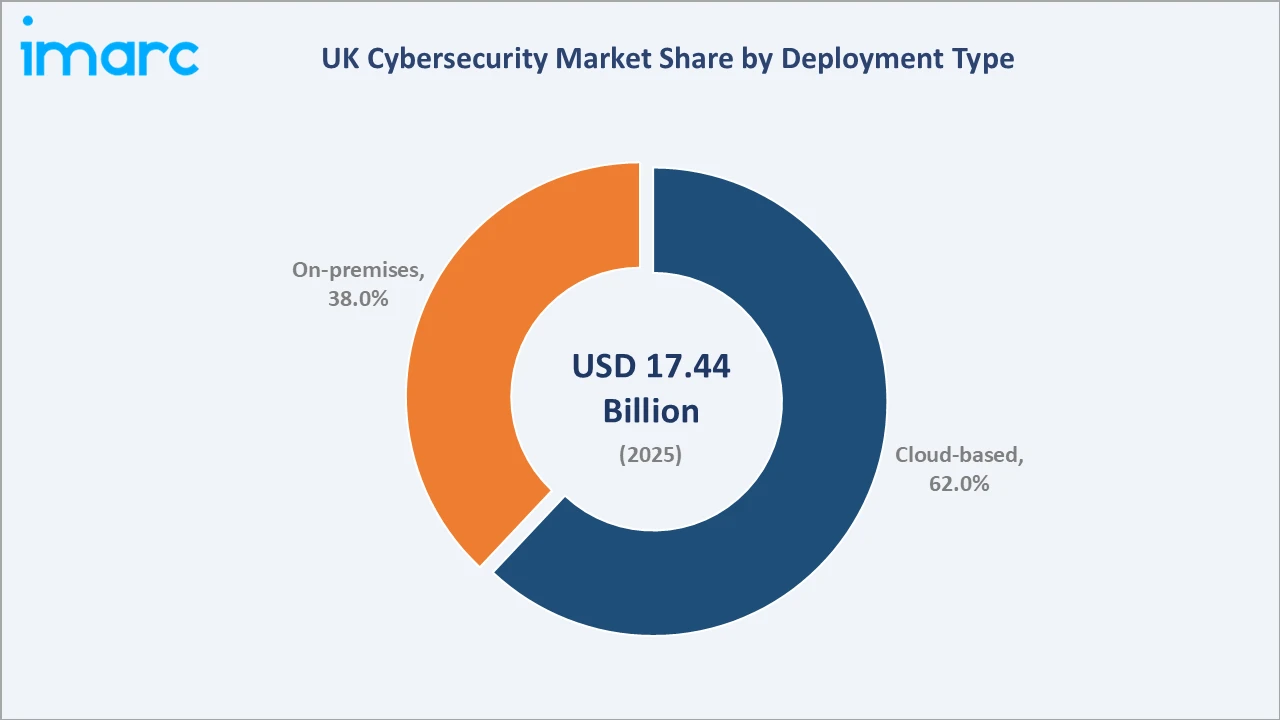
Cloud-based leads the deployment type segment at 62.0%, large enterprises dominate the user type segment at 58.0%, and London commands 22.0% of regional share within the market.
Market Snapshot
| Metric | Value |
|---|---|
| Base Year Market Size (2025) | USD 17.44 Billion |
| Market Size (2026) | USD 20.27 Billion |
| Forecast Market Size (2034) | USD 46.46 Billion |
| CAGR (2026-2034) | 10.93% |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Largest Region | London (22.0%, 2025) |
| Second Largest Region | South East (16.0%, 2025) |
| Leading Deployment Type | Cloud-based (62.0%, 2025) |
| Leading User Type | Large Enterprises (58.0%, 2025) |
The UK cybersecurity market size increased from USD 10.39 Billion in 2020 to USD 17.44 Billion in 2025 and is estimated to reach USD 20.27 Billion in 2026. The market is further expected to grow to USD 29.29 Billion by 2030 and USD 46.46 Billion by 2034. The market is commercially significant among global cybersecurity markets, underpinned by the UK's advanced digital economy, a large financial services sector, stringent regulatory frameworks, and growing government investment in national cyber resilience.
To get more information on this market, Request Sample
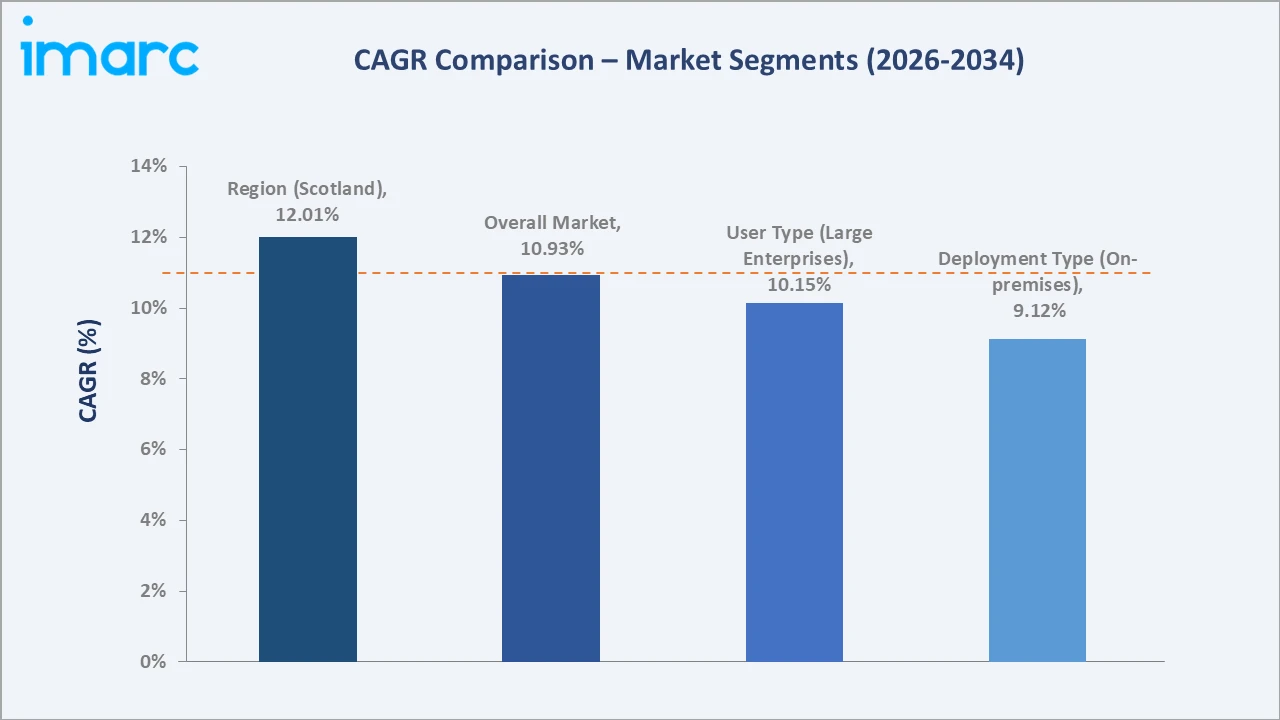
CAGR trajectories across deployment type, user type, and regional sub-segments show cloud-based and Scotland expanding faster than the overall 10.93% market CAGR, driven by accelerating cloud migration, growing enterprise security investment, and expanding government-backed cyber resilience initiatives across the UK.
Executive Summary
The UK cybersecurity market stood at USD 17.44 Billion in 2025, driven by increasing cyber threats, rapid cloud adoption, and expanding enterprise digital transformation. Growing investment in advanced threat detection and managed security services is reinforcing market expansion across public and private sectors.
Cloud-based commands 62.0% of the deployment type segment in 2025, reflecting accelerating migration of enterprise security infrastructure to cloud-native platforms that enable scalable, consumption-based threat management. Large enterprises account for 58.0% of the user type segment, supported by their capacity to sustain dedicated cybersecurity budgets and implement enterprise-wide security programs spanning network, endpoint, cloud, and identity domains. London leads regional share at 22.0%, anchored by its concentration of global financial institutions and government headquarters.
Key Market Insights
| Insight | Data |
|---|---|
| Leading Deployment Type | Cloud-based – 62.0% share (2025) |
| Second Largest Deployment Type | On-premises – 38.0% share (2025) |
| Leading User Type | Large Enterprises – 58.0% share (2025) |
| Second Largest User Type | Small and Medium Enterprises – 42.0% share (2025) |
| Leading Region | London – 22.0% share (2025) |
| Second Largest Region | South East – 16.0% share (2025) |
| Top Companies | BT Group plc, BAE Systems plc, Darktrace, Palo Alto Networks, Inc. |
Key Analytical Observations Expanding On the Data Above:
- Cloud-based dominance at 62.0% reflects accelerating enterprise migration to cloud infrastructure and growing demand for scalable managed security services that reduce reliance on capital-intensive on-premises hardware.
- On-premises share at 38.0% is sustained by regulated industries, including financial services, healthcare, and government, which maintain strict data sovereignty requirements limiting full cloud migration.
- Large enterprises leadership at 58.0% reflects their advanced security posture, dedicated IT security teams, and budgetary capacity to deploy multi-layered cybersecurity solutions across network, endpoint, cloud, identity, and operational technology domains.
- Small and medium enterprises at 42.0% represent a growing segment, driven by rising cyber risk awareness and expanding availability of cost-effective managed security services tailored to smaller organizations.
- London regional dominance at 22.0% is driven by its role as the UK's financial capital and primary hub for multinational corporations and government agencies, creating concentrated demand for advanced cybersecurity solutions.
UK Cybersecurity Market Overview
The UK cybersecurity market encompasses the provision of technology solutions, software, services, and infrastructure protection tools designed to secure digital assets, networks, endpoints, data, and cloud environments from unauthorized access, cyberattacks, data breaches, and service disruptions. The market spans identity and access management, threat intelligence, managed security services, network security, endpoint protection, and application security across enterprise and public sector clients.
The UK cybersecurity ecosystem integrates hardware manufacturers, software vendors, managed security service providers, government agencies, regulatory bodies, professional services firms, and enterprise end users across financial services, healthcare, government, retail, and manufacturing. Macroeconomic influences include the accelerating pace of digital transformation, growing dependence on cloud infrastructure, increasing state-sponsored cyber threat activity, and evolving regulatory frameworks governing data protection and critical infrastructure security.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
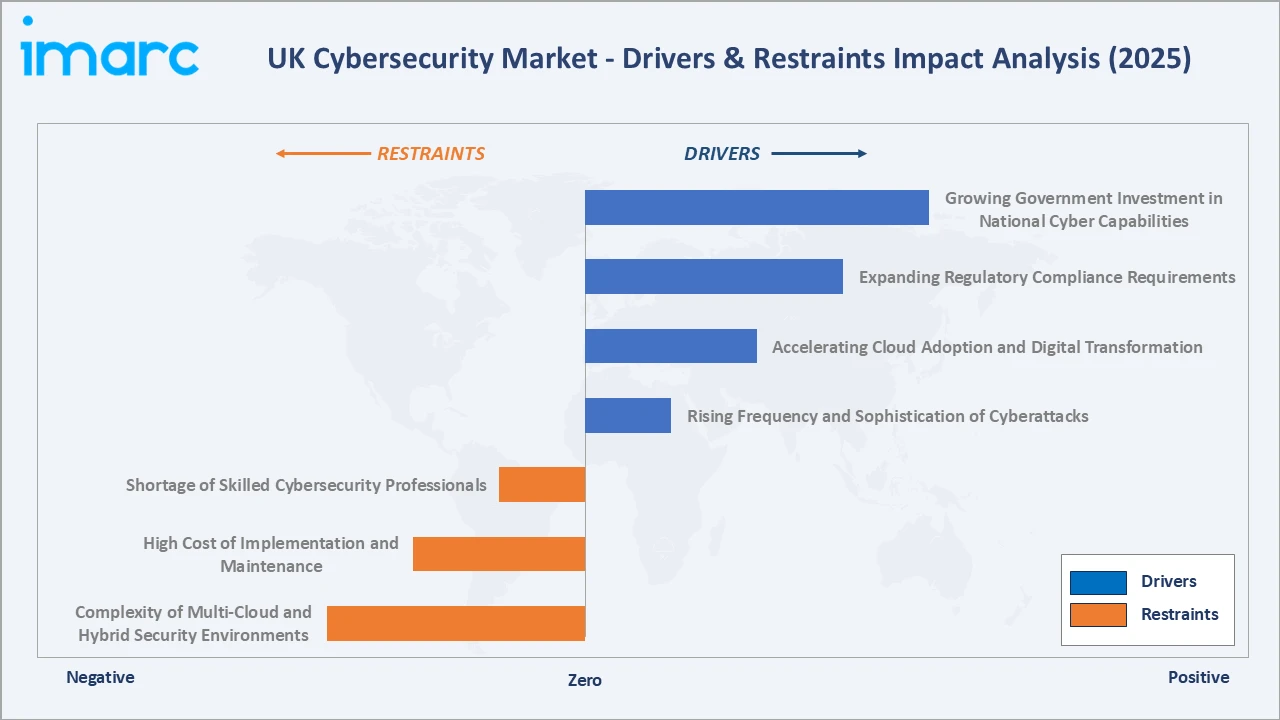
- Rising Frequency and Sophistication of Cyberattacks: According to the Cyber Security Breaches Survey 2025/2026, in the UK, more than four in ten businesses (43%) and about three in ten charities (28%) indicated that they faced some form of cyber security breach or attack, reflecting an environment of persistent and growing threat activity. Rising adoption of ransomware-as-a-service models, AI-assisted attack tools, and supply chain compromise techniques is compelling organizations across all sectors of the UK cyber security market to invest in advanced detection and response capabilities.
- Accelerating Cloud Adoption and Digital Transformation: Migration of enterprise workloads to public, private, and hybrid cloud environments is expanding the attack surface, driving demand for cloud-native security solutions, zero-trust architectures, and identity management platforms to protect distributed digital assets and remote workforces.
- Expanding Regulatory Compliance Requirements: Increasing regulatory scrutiny and stricter data protection requirements are compelling organizations to strengthen cybersecurity frameworks, improve risk management, and enhance incident response capabilities. Growing compliance obligations, potential financial penalties, and the need to safeguard sensitive customer information are encouraging businesses to increase cybersecurity investments and adopt comprehensive security solutions.
- Growing Government Investment in National Cyber Capabilities: Rising government expenditure on cybersecurity infrastructure, threat intelligence, and national cyber resilience initiatives is supporting market growth. Increased funding for critical infrastructure protection, public-sector digital security, and cyber threat preparedness is encouraging wider adoption of advanced cybersecurity technologies across government agencies and private enterprises.
Market Restraints
- Shortage of Skilled Cybersecurity Professionals: The persistent scarcity of qualified cybersecurity personnel is limiting organizations’ ability to fully deploy and manage advanced security solutions, increasing reliance on managed service providers and creating operational gaps in threat monitoring and incident response functions.
- High Cost of Implementation and Maintenance: Advanced cybersecurity infrastructure, including security information and event management platforms, extended detection and response tools, and cloud security posture management systems, requires substantial capital investment and ongoing operational expenditure, restricting comprehensive adoption among smaller organizations.
- Complexity of Multi-Cloud and Hybrid Security Environments: Managing consistent security postures across heterogeneous multi-cloud and hybrid infrastructure environments introduces significant operational complexity, increasing integration costs and the risk of misconfiguration-driven security vulnerabilities.
Market Opportunities
- Expansion of Managed Security Services for Small and Medium Enterprises: Growing cyber risk awareness among smaller organizations, combined with limited in-house security capabilities and rising UK GDPR compliance obligations, is creating strong demand for managed detection and response, managed firewall, and security operations center-as-a-service offerings tailored to the small and medium enterprise segment.
- Adoption of AI and Machine Learning (ML) in Threat Detection: Integration of AI and ML into security operations platforms is enabling faster threat detection, automated response, and predictive risk assessment, opening new revenue streams for cybersecurity vendors and service providers aligned with UK cybersecurity market trends toward AI-driven threat detection and automated response.
Market Challenges
- Evolving and Increasingly Sophisticated Threat Landscape: Cybercriminals and state-sponsored actors are continuously developing new attack techniques, including deepfake-enabled social engineering, AI-powered malware, and supply chain compromises, requiring ongoing investment in research, detection capabilities, and workforce training to maintain effective security postures.
- Balancing Cybersecurity with Business Agility and User Experience: Implementing stringent security controls, multi-factor authentication, and access restrictions can introduce operational friction, complicate digital workflows, and affect employee productivity. Organizations face the challenge of maintaining robust security standards while ensuring seamless user experiences, efficient business operations, and uninterrupted digital service delivery.
Emerging Market Trends
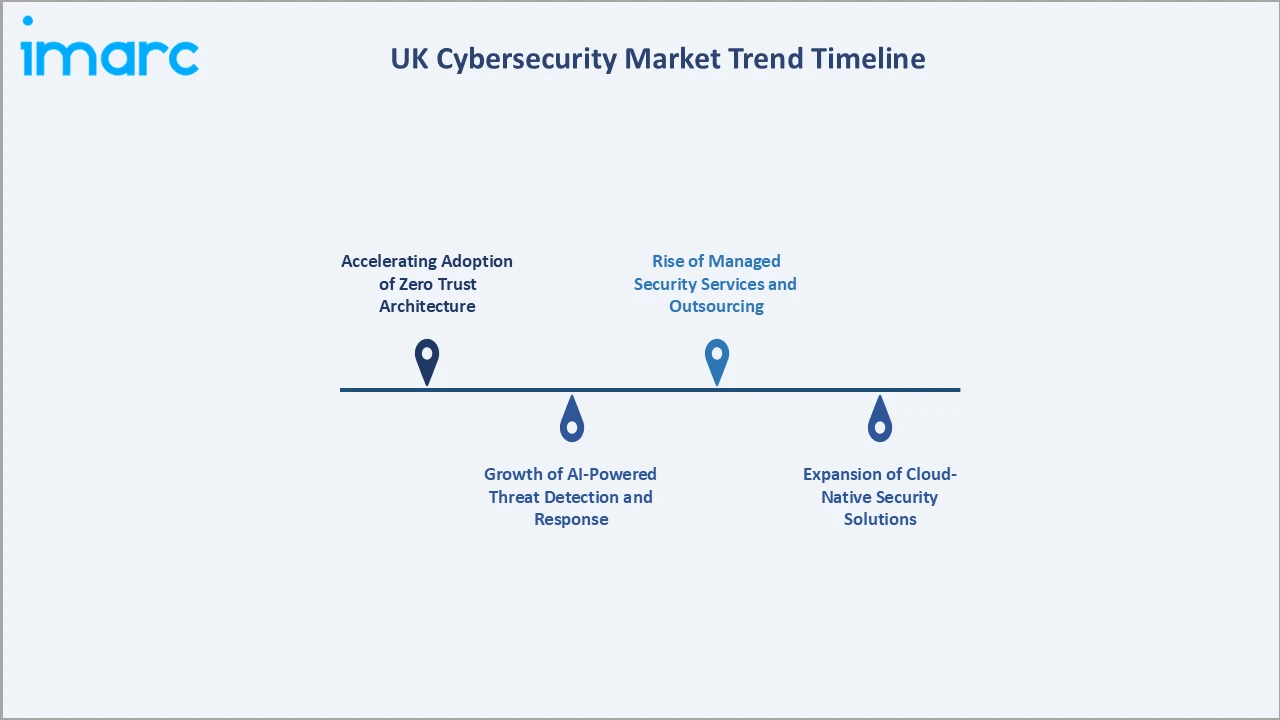
1. Accelerating Adoption of Zero Trust Architecture
Zero trust architecture, based on the principle of never trusting and always verifying all users, devices, and applications, is gaining rapid traction across UK enterprises and government agencies. Its adoption is driven by the dissolution of traditional network perimeters through remote work and cloud infrastructure expansion. Organizations are deploying identity-centric, micro segmented security environments that enforce continuous authentication and least-privilege access controls.
2. Growth of AI-Powered Threat Detection and Response
AI and ML technologies are being integrated into security operations platforms, endpoint protection tools, and network monitoring systems to enable real-time anomaly detection and automated response. UK vendors are pioneering AI-native security models that detect novel threats without signature-based methods.
3. Expansion of Cloud-Native Security Solutions
The migration of enterprise workloads to cloud environments is driving demand for cloud-native security products, including cloud access security brokers, cloud security posture management tools, and cloud workload protection platforms. As cloud-based deployment dominates the market, the demand for integrated cloud security capabilities is reshaping vendor product portfolios and partner ecosystems across the UK.
4. Rise of Managed Security Services and Outsourcing
Resource constraints and skills shortages are driving increasing outsourcing of security operations to managed security service providers. Security operations center services, managed detection and response, and threat intelligence subscriptions are among the fastest-growing service categories as organizations seek 24/7 coverage without the overhead of building in-house capabilities.
Industry Value Chain Analysis
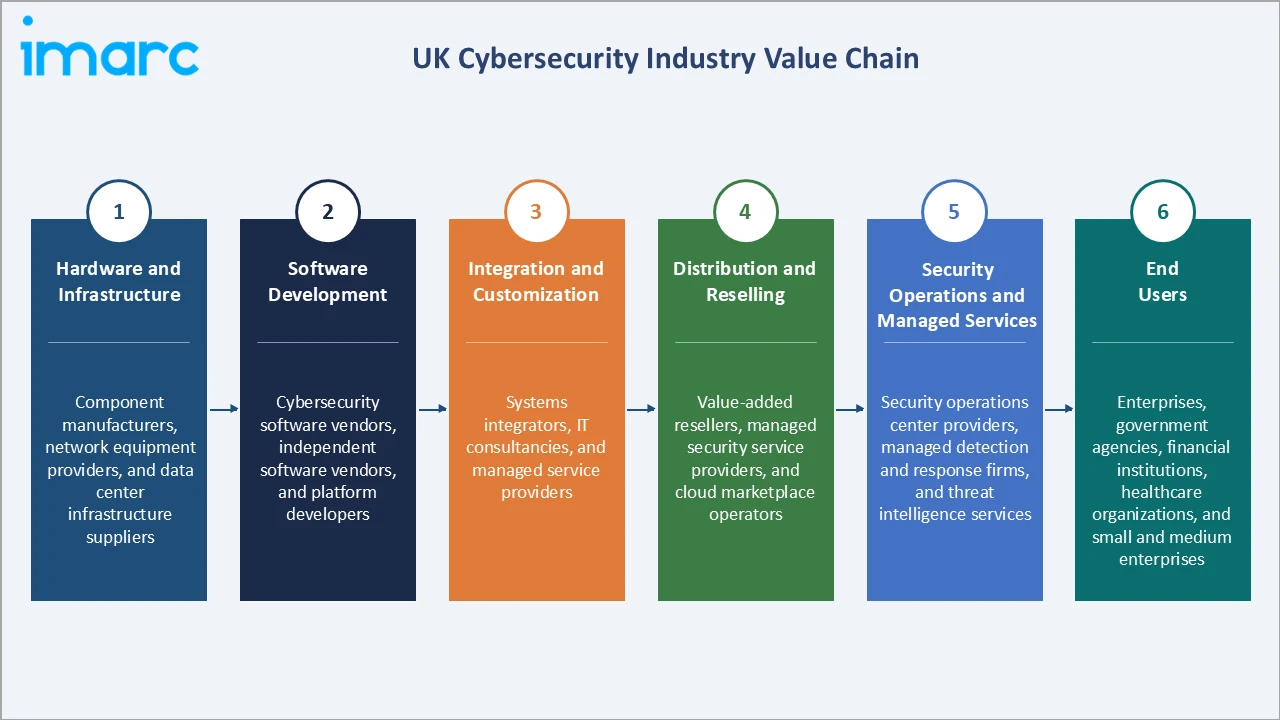
The UK cybersecurity value chain spans six stages, from hardware and infrastructure provision through software development, integration, distribution, security operations, and end-user deployment. The managed services and security operations layer is capturing growing value as organizations increasingly outsource security monitoring, incident response, and advisory functions to specialist providers.
| Stage | Key Players / Examples |
|---|---|
| Hardware and Infrastructure | Component manufacturers, network equipment providers, and data center infrastructure suppliers providing physical security hardware, server infrastructure, and networking equipment for cybersecurity deployments across UK enterprise and government environments |
| Software Development | Cybersecurity software vendors, independent software vendors, and platform developers creating threat detection engines, identity management systems, endpoint protection platforms, and security analytics tools for enterprise and public sector clients |
| Integration and Customization | Systems integrators, IT consultancies, and managed service providers configuring, deploying, and customizing security solutions to meet enterprise and government client requirements across on-premises, cloud, and hybrid environments |
| Distribution and Reselling | Value-added resellers, managed security service providers, and cloud marketplace operators distributing cybersecurity products and services to end users across enterprise, public sector, and small and medium enterprise segments |
| Security Operations and Managed Services | Security operations center providers, managed detection and response firms, and threat intelligence services delivering ongoing monitoring, incident response, and advisory services to enterprise and government clients across the UK |
| End Users | Enterprises, government agencies, financial institutions, healthcare organizations, and small and medium enterprises consuming cybersecurity solutions across network, cloud, endpoint, identity, and application security domains |
Vertically integrated operators controlling software development, integration, and security operations are positioned to capture greater margin than single-layer vendors dependent on distribution channels and commodity resale. UK-headquartered managed security service providers with broad sector coverage and proven compliance credentials are increasingly differentiated from point-solution vendors across the value chain.
Technology Landscape in the UK Cybersecurity Industry
Cloud Security Technologies
Cloud security encompasses cloud access security brokers, cloud security posture management, and cloud workload protection platforms designed to secure enterprise workloads and data across public, private, and hybrid environments. Increasing enterprise migration to digital infrastructure, growing data protection requirements, and rising adoption of cloud-native security solutions are driving the UK cloud security market.
AI and ML in Security
AI and ML are being embedded into threat detection, behavioral analytics, and automated response systems. AI-powered tools enable faster identification of novel threats, reduce false positive rates in security alerts, and support autonomous threat containment in enterprise security operations environments across the UK.
Zero Trust and Identity Security
Zero trust architecture and identity access management solutions are among the fastest-growing technology categories in UK cybersecurity. These technologies enforce continuous authentication, microsegmentation, and least-privilege access across distributed enterprise environments, addressing security risks created by remote work and cloud adoption, including in the UK healthcare cyber security market where electronic health records and connected clinical systems represent high-value targets.
Automation and Security Orchestration
Security orchestration, automation, and response platforms are enabling security operations teams to automate repetitive investigation and remediation tasks. Automation reduces incident response time and improves analyst productivity in environments managing high volumes of security alerts across complex multi-cloud and hybrid IT estates, improving the economics of security operations for enterprise clients across the UK.
Market Segmentation Analysis
The report covers the following segments:
| Segment Category | Leading Segment | Market Share | Year |
|---|---|---|---|
| Component | 🔒 | 🔒 | 2025 |
| Deployment Type | Cloud-based | 62.0% | 2025 |
| User Type | Large Enterprises | 58.0% | 2025 |
| Industry Vertical | 🔒 | 🔒 | 2025 |
| Region | London | 22.0% | 2025 |

By Deployment Type
Cloud-based commands a 62.0% majority share of the market, driven by enterprise-wide migration to cloud infrastructure, growing availability of cloud-native security platforms, and the scalability advantages of consumption-based security services over capital-intensive on-premises deployments.
To access detailed market analysis, Request Sample
On-premises retains a 38.0% share, anchored by regulated industries, including banking, insurance, government, and critical national infrastructure operators, that maintain strict data sovereignty, compliance, and operational control requirements necessitating physically secured, locally managed security environments.
By User Type
Large enterprises represent 58.0% share of the market, reflecting their extensive digital estates, high-value data assets, complex regulatory obligations, and dedicated cybersecurity budgets enabling comprehensive multi-layered security investment spanning endpoint, network, cloud, identity, and operational technology domains.
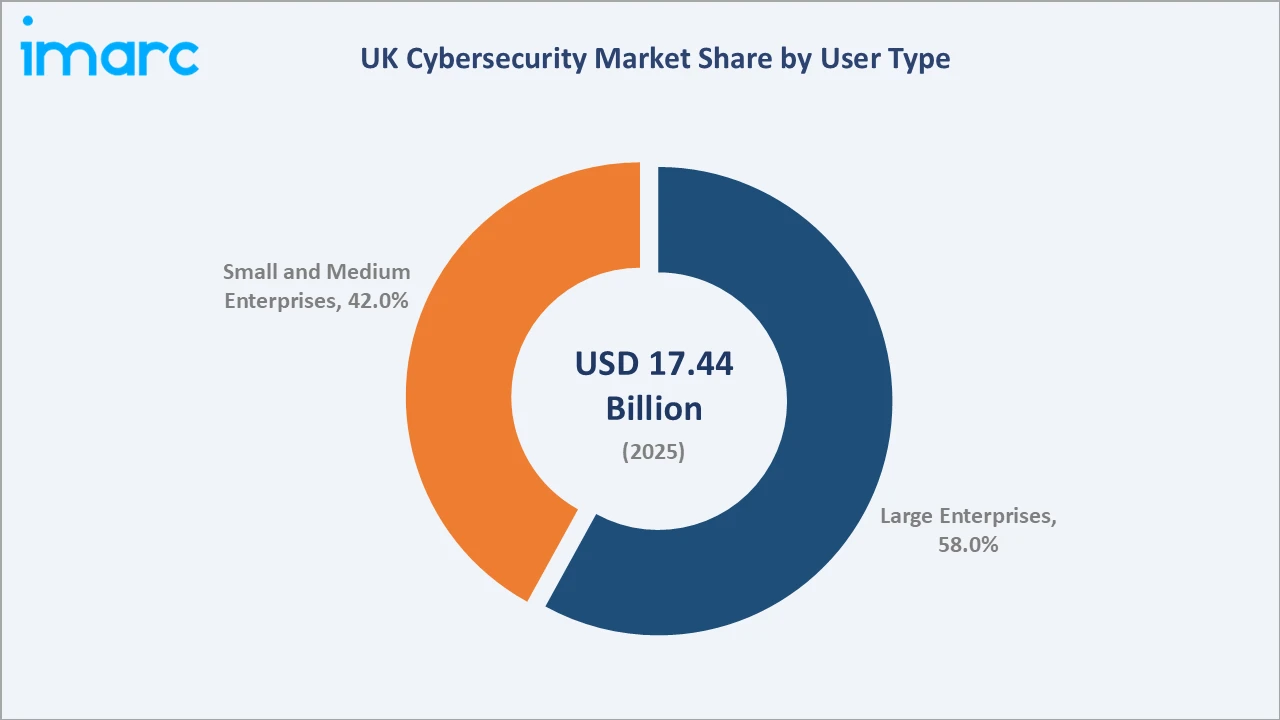
Small and medium enterprises account for 42.0%, a growing share supported by rising cyber risk awareness, expanding UK GDPR compliance obligations, and increasing availability of scalable managed security services tailored to the resource and budget constraints of smaller organizations.
Regional Market Insights
| Region | Share (2025) | Key Growth Drivers |
|---|---|---|
| London | 22.0% | Concentration of global financial institutions, multinational corporations, and government departments, high-value data assets, regulatory compliance demand, and the largest density of enterprise cybersecurity procurement in the UK |
| South East | 16.0% | Technology corridors, regional headquarters of financial and professional services firms, expanding digital economy, and proximity to London driving cross-regional cybersecurity investment |
| North West | 12.0% | Strong digital sector presence in Manchester and Salford, growing fintech and media industries, expanding public sector investment in cybersecurity, and increasing mid-market enterprise security adoption |
| East of England | 10.0% | High-technology cluster around Cambridge, science and research sector, life sciences and advanced manufacturing industries with rising intellectual property protection requirements |
| Scotland | 9.0% | Financial services sector in Edinburgh, energy industry cybersecurity requirements, growing digital economy in Glasgow, and Scottish Government investment in national cyber resilience initiatives |
| West Midlands | 8.5% | Manufacturing sector digitization, automotive industry operational technology security requirements, expanding technology sector, and growing public sector cybersecurity investment in Birmingham and surrounding areas |
| Yorkshire and the Humber | 8.0% | Financial services in Leeds, manufacturing sector security requirements, expanding digital economy, and growing enterprise adoption of managed security services across the region |
| South West | 7.5% | Defense and aerospace sector in Bristol and Exeter, growing technology industry, expanding professional services firms, and increasing public sector cybersecurity procurement across the region |
| East Midlands | 4.5% | Manufacturing and logistics sector digitization, expanding retail and distribution industry cybersecurity requirements, and growing enterprise investment in cloud security solutions |
| Others | 2.5% | Emerging regional markets including Wales, Northern Ireland, and North East England with expanding public sector investment, growing digital economy initiatives, and increasing enterprise cybersecurity awareness |
London at 22.0% in 2025 leads the regional landscape, anchored by its concentration of global financial institutions, multinational corporations, and government departments generating high per-organization cybersecurity expenditure in the UK.
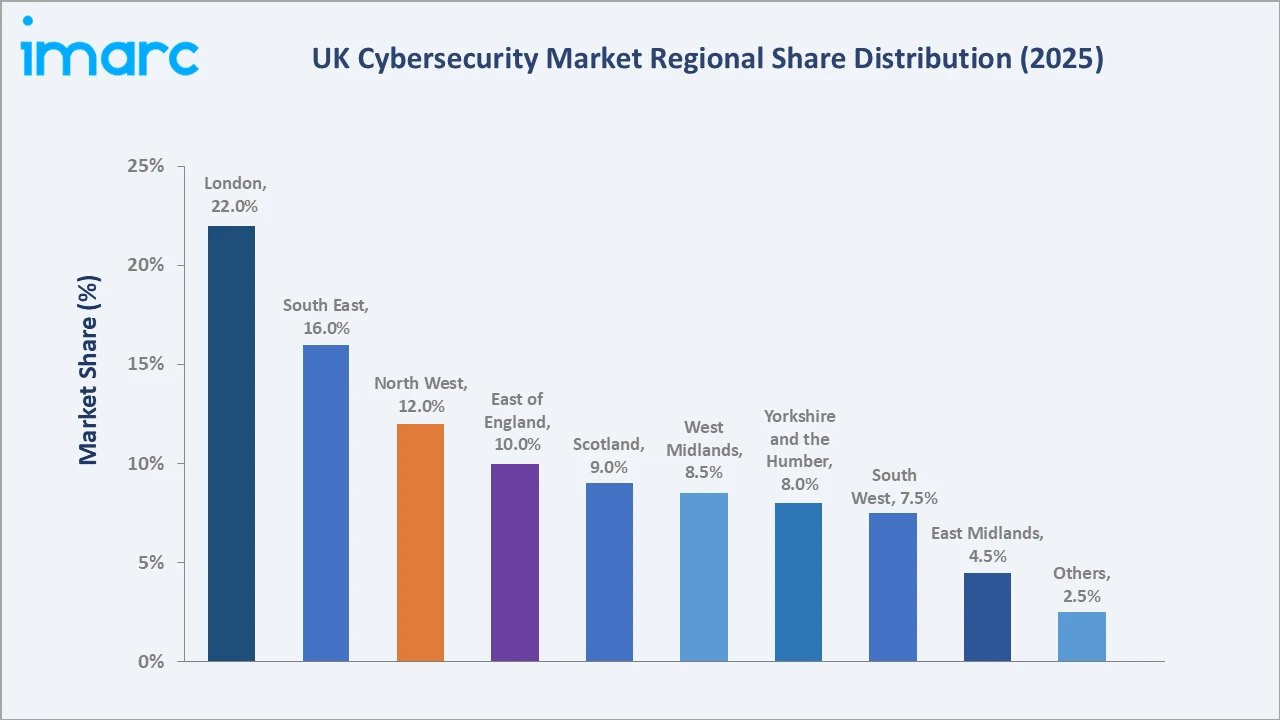
Scotland, while currently ranked fifth at 9.0%, is expanding at an above-average rate as financial services in Edinburgh, energy sector cybersecurity requirements, and the Scottish Government's national cyber resilience strategy drive growing investment in managed security services and enterprise security solutions across the region.
Competitive Landscape
The UK cybersecurity market is competitive, featuring a mix of large domestic integrated security providers, specialist UK-based vendors, and international technology companies competing on product breadth, service quality, compliance credentials, and sector expertise. Scale, certified managed service capability, AI-driven threat detection, and proximity to regulated UK sectors form the key competitive differentiators across the industry.
| Company Name | Brand / Key Product | Market Position | Strategic Focus |
|---|---|---|---|
| BT Group plc | BT Security | Leader | Expanding managed security service capabilities and cloud security solutions for enterprise and government clients |
| BAE Systems plc | BAE Systems Digital Intelligence & Land | Leader | Strengthening cybersecurity intelligence and threat detection capabilities for government and defense clients |
| Darktrace | ActiveAI Security | Leader | Developing AI-native cybersecurity technology for detecting novel threats across enterprise, cloud, and email environments |
| Palo Alto Networks, Inc. | Cortex XDR | Challenger | Expanding AI-driven security operations and cloud security capabilities for enterprise clients globally |
Key players include BT Group plc, BAE Systems plc, Darktrace, and Palo Alto Networks, Inc., among others.
Key Company Profiles
BT Group plc
BT Group plc is a British multinational telecommunications holding company headquartered in London, UK. BT Security, its cybersecurity division, provides managed security services, threat intelligence, and cloud security solutions to enterprise, government, and public sector clients across the UK and internationally.
- Product Portfolio: Managed security services, security operations center services, threat intelligence, endpoint protection, network security, cloud security, and identity and access management solutions for enterprise and government clients.
- Recent Developments: The firm has continued to expand its managed detection and response capabilities and strengthen its security operations center infrastructure, supporting enterprise clients navigating increasingly complex multi-cloud security environments across the UK.
- Strategic Focus: Strengthening managed security service capabilities and expanding cloud security solutions to address growing enterprise demand for outsourced 24/7 security operations across UK and international markets.
BAE Systems plc
BAE Systems plc is a British multinational defense, security, and aerospace company. BAE Systems Digital Intelligence & Land delivers cybersecurity, intelligence, and digital transformation solutions to government agencies, defense organizations, and financial institutions globally.
- Product Portfolio: Cybersecurity solutions, threat intelligence platforms, digital forensics, identity and access management, and managed security services supporting government, defense, and financial sector clients across the UK and internationally.
- Recent Developments: The firm has continued to develop its threat intelligence and cyber analytics capabilities, supporting UK government agencies and international defense clients in addressing advanced persistent threat activity and nation-state cyber operations.
- Strategic Focus: Expanding cybersecurity intelligence and threat detection capabilities for government and defense clients, with growing investment in AI-driven security analytics and digital transformation advisory services.
Darktrace
Darktrace is a British cybersecurity company headquartered in Cambridge, UK. The company develops AI-powered cybersecurity products capable of detecting novel and sophisticated cyber threats in real time across enterprise, cloud, email, and operational technology environments globally.
- Product Portfolio: ActiveAI Security Platform combining detect, respond, prevent, and heal capabilities, designed for enterprise clients across multiple industries.
- Recent Developments: The firm has continued to enhance its AI-powered cybersecurity portfolio, focusing on improving threat detection, automated incident response, and real-time security monitoring capabilities to address evolving cyber risks and strengthen its competitive position in the global cybersecurity market.
- Strategic Focus: Developing AI-native cybersecurity technology capable of detecting zero-day threats and novel attack techniques without signature-based methods, with expanding international market coverage and growing enterprise customer base.
Market Concentration Analysis
The UK cybersecurity market is moderately fragmented, with a mix of large domestic integrated providers, specialist UK-based vendors, and international technology companies sharing revenue across solution and service categories.
Barriers to entry include the need for sector-specific compliance certifications, established government procurement frameworks, technical expertise in complex security architectures, and the relationship capital required to win and retain large enterprise and public sector contracts. These factors favor established players with proven UK credentials over smaller or international entrants without domestic track records.
Consolidation is progressing through strategic acquisitions, partnership agreements, and the expansion of platform-based security models that bundle multiple capabilities under single vendor relationships. Larger players are acquiring specialist boutique providers in AI security, identity management, and operational technology security to expand their solution portfolios and accelerate growth in high-margin service segments.
Investment & Growth Opportunities
Fastest-Growing Segments
Cloud-based is expanding fastest among deployment type sub-segments, driven by accelerating enterprise cloud migration and growing adoption of cloud-delivered security platforms. Small and medium enterprises represent the fastest-growing user type segment, as rising awareness of cyber risk, expanding regulatory obligations, and increasing availability of affordable managed security services drive adoption among organizations historically underserved by the enterprise-focused market.
Emerging Markets
Scotland is the fastest-growing regional market, supported by expanding financial services and government investment in cybersecurity. Increasing digital transformation across public and private sector organizations, alongside rising demand for advanced threat detection and data protection solutions, is further strengthening regional market growth.
Venture & Investment Trends
Investment activity is concentrated in AI-powered threat detection, cloud-native security platforms, zero trust identity solutions, and managed security services for the small and medium enterprise segment. Capital is flowing into UK cybersecurity start-ups and scale-ups with differentiated AI security technology, as well as into managed detection and response platforms that address the growing outsourcing of security operations by mid-market and enterprise clients.
Future Market Outlook (2026-2034)
The UK cybersecurity market is projected to grow from USD 17.44 Billion in 2025 to USD 20.27 Billion in 2026, reaching USD 46.46 Billion by 2034, registering a CAGR of 10.93% during 2026-2034.
Four forces will shape the market through 2034 deepening integration of AI into security operations across detection, response, and predictive risk management; expansion of cloud-native and managed security service models as organizations prioritize outcomes over infrastructure ownership; continued evolution of the regulatory environment with increasing obligations for both public and private sector operators; and growing threat activity from state-sponsored actors and organized criminal groups targeting UK critical infrastructure, financial institutions, and public sector organizations.
By 2034, the UK cybersecurity market is expected to be characterized by a mix of platform-based security vendors offering integrated multi-capability solutions, specialist managed service providers delivering sector-specific security operations, and AI-native security companies providing next-generation threat detection across cloud, endpoint, identity, and operational technology domains.
Research Methodology
Primary Research
Primary research included structured discussions with cybersecurity solution providers, enterprise security buyers, managed service providers, and industry analysts, validating market sizing, segment mix, and regional demand patterns across the UK cybersecurity ecosystem.
Secondary Research
Secondary sources included UK government publications, National Cyber Security Centre reports, Office for National Statistics data, the Department for Science, Innovation and Technology's Cyber Security Sectoral Analysis, and public disclosures from listed cybersecurity vendors and managed service providers operating in the UK.
Forecasting Models
Market forecasts used top-down and bottom-up models combining enterprise cybersecurity spending data, managed service adoption trends, segment-level growth driver analysis, and regulatory impact assessments. Scenario analysis addressed regulatory implementation pace, AI adoption rates in security operations, and enterprise cloud migration trajectories across the forecast period.
UK Cybersecurity Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered |
|
| Deployment Types Covered | Cloud-based, On-premises |
| User Types Covered | Large Enterprises, Small and Medium-sized Enterprises |
| Industry Verticals Covered | IT and Telecom, Retail, BFSI, Healthcare, Defense/Government, Manufacturing, Energy, Others |
| Regions Covered | London, South East, North West, East of England, South West, Scotland, West Midlands, Yorkshire and The Humber, East Midlands, Others |
| Companies Covered | BT Group plc, BAE Systems plc, Darktrace, Palo Alto Networks, Inc., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the UK cybersecurity market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the UK cybersecurity market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the UK cybersecurity industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the UK Cybersecurity Market Report
The UK cybersecurity market size is estimated at USD 20.27 Billion in 2026, driven by expanding enterprise digital transformation, rising cyberattack frequency, and growing cloud adoption across financial services, government, and technology sectors.
The market is projected to grow at a CAGR of 10.93% from 2026-2034, reaching USD 46.46 Billion, supported by AI-driven security adoption and expanding managed security service demand.
Cloud-based dominates at 62.0% share in 2025, driven by accelerating enterprise cloud migration and growing demand for scalable, cloud-native security platforms.
Large enterprises dominate at 58.0% share in 2025, supported by dedicated cybersecurity budgets, complex regulatory obligations, and extensive digital estates requiring comprehensive multi-layered security investment.
London dominates at 22.0% share in 2025, driven by its concentration of global financial institutions, government headquarters, and multinational corporations generating high cybersecurity demand in the UK.
Scotland is among the fastest-growing regions, supported by financial services in Edinburgh, energy sector requirements, and the Scottish Government's national cyber resilience strategy driving increased investment.
Key players include BT Group plc, BAE Systems plc, Darktrace, and Palo Alto Networks, Inc., among others.
Key drivers include rising cyberattack frequency, accelerating cloud adoption, expanding UK GDPR compliance requirements, and growing government investment in national cyber resilience capabilities.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade