Brazil Lactose Intolerance Market Size, Share, Trends and Forecast by Product Type, End User, Distribution Channel, and Region, 2026-2034
Brazil Lactose Intolerance Market Size, Share, Trends & Forecast (2026-2034)
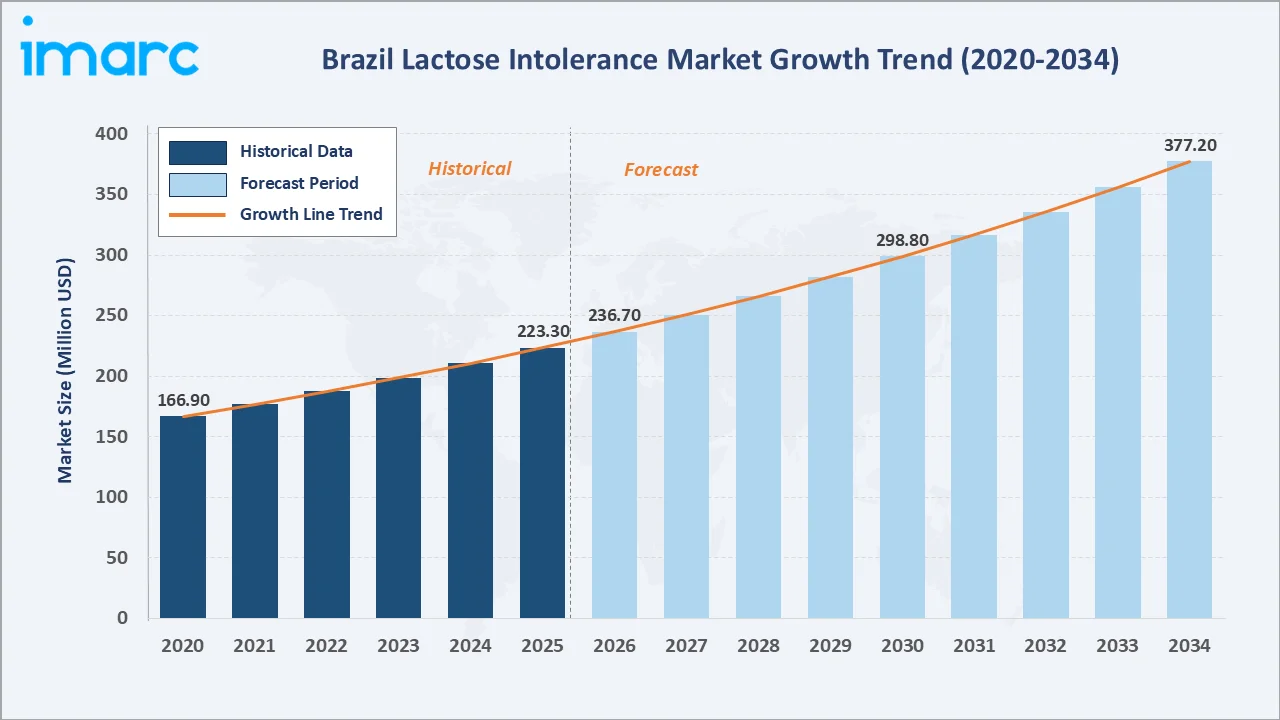
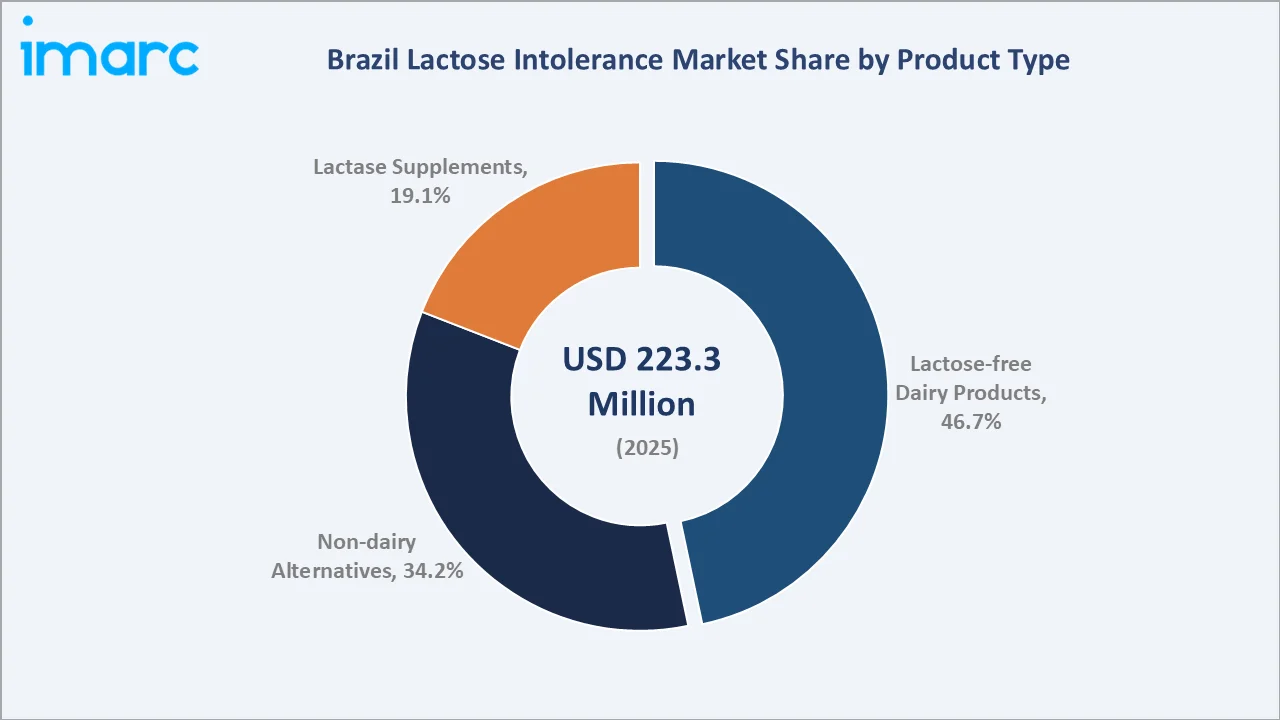
The Brazil lactose intolerance market grew from USD 223.3 Million in 2025 to USD 236.7 Million in 2026 and is projected to reach USD 377.2 Million by 2034, growing at a CAGR of 6.00% during 2026-2034. The market is driven by growing awareness of digestive health and increasing diagnosis and recognition of lactose intolerance among consumers. Rising demand for lactose-free dairy products, plant-based alternatives, and digestive enzyme supplements is further supporting market growth. Lactose-free dairy products lead at 46.7% by product type, adults command the largest end-user segment at 72.4%, and the Southeast region holds the primary market position at 44.5%.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 223.3 Million |
|
Market Size (2026) |
USD 236.7 Million |
|
Forecast Market Size (2034) |
USD 377.2 Million |
|
CAGR (2026-2034) |
6.00% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Product Type |
Lactose-free Dairy Products (46.7%, 2025) |
|
Dominant End User |
Adults (72.4%, 2025) |
|
Leading Region |
Southeast (44.5%, 2025) |
The Brazil lactose intolerance market grew from USD 166.9 Million in 2020 to USD 223.3 Million by 2025 and is estimated to reach USD 236.7 Million in 2026. The market is projected to reach USD 298.8 Million by 2030 and USD 377.2 Million by 2034.
To get more information on this market, Request Sample
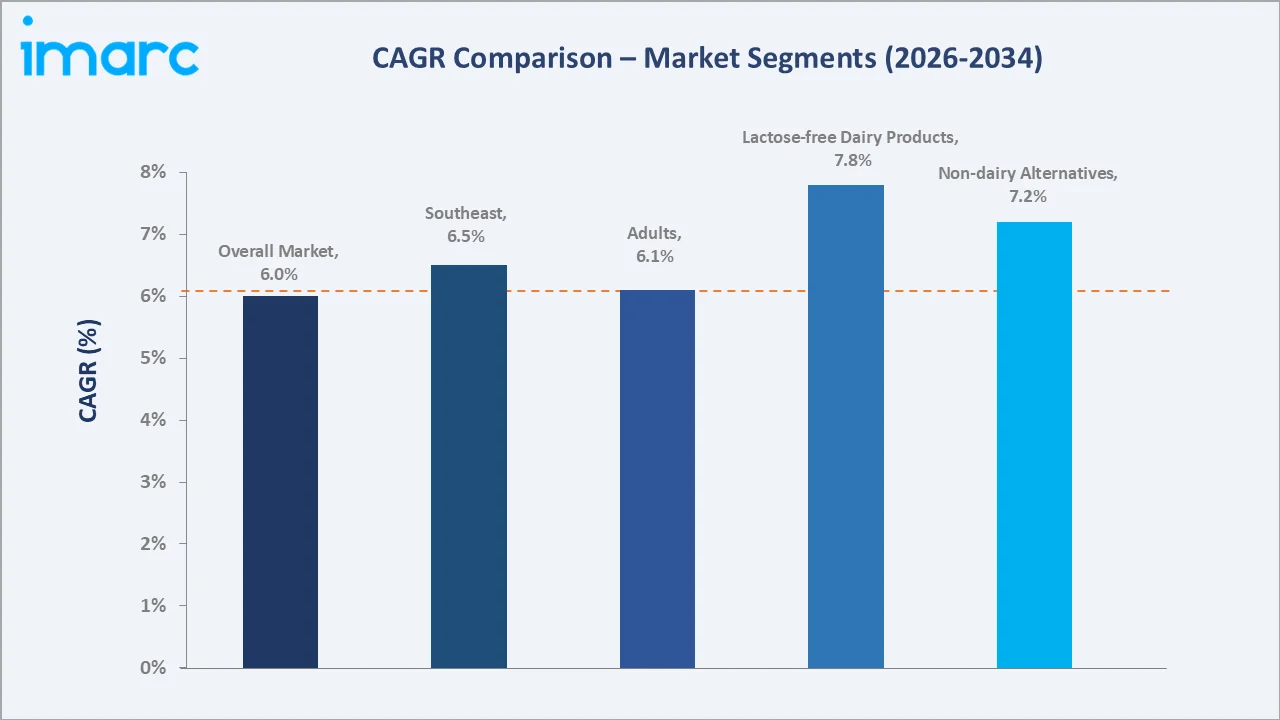
Non-dairy alternatives grow fastest at ~7.2% CAGR through oat, almond, and coconut milk expansion. Lactase supplements expand at ~6.8% CAGR through pharmacy channel and e-commerce growth. Southeast region leads at ~6.5% CAGR through organized retail penetration and healthcare diagnosis expansion.
Executive Summary
The Brazil lactose intolerance market is experiencing robust growth driven by high population prevalence, rising health awareness, rapid product innovation from dairy and food companies, and the mainstreaming of lactose-free and plant-based alternatives in organized retail. The market is driven by the expansion of lactose-free dairy lines from all major Brazilian dairy brands, the surge in plant-based milk alternatives following global consumption trends, and growing lactase supplement adoption through pharmacy and e-commerce channels.
Lactose-free dairy products dominate at 46.7% through the widespread launch of Sem Lactose dairy ranges. Non-dairy alternatives at 34.2% are the fastest-growing category. Adults at 72.4% are the primary end-user segment. The Southeast region commands 44.5% market share through São Paulo's concentrated consumer market and highest per-capita health food spending.
Key Market Insights
|
Insight |
Data |
|
Dominant Product Type |
Lactose-free Dairy Products - 46.7% share (2025) |
|
Dominant End User |
Adults - 72.4% share (2025) |
|
Leading Region |
Southeast - 44.5% (2025) |
|
Key Market Opportunity |
Brazil's lactose-intolerant population represents an incremental addressable market opportunity by 2030 through improved consumer diagnostics, awareness programs, and affordable product access expansion. |
Key analytical observations supporting the above data:
- Lactose-free Dairy Products at 46.7%: The lactose-free dairy segment has experienced transformative growth when Brazilian dairy companies began systematically launching Sem Lactose (without lactose) versions of their core products. Lactose-free dairy's growth is sustained by consumers preferring the familiar taste, nutritional profile, and cooking applications of dairy products over plant-based alternatives.
- Adults at 72.4%: The adult segment dominates through the largest consumer base, highest product awareness, and widest product availability. Brazilian adults with lactose intolerance are the primary purchasers of lactose-free dairy products at supermarkets and plant-based beverages from health food stores and online channels. The adult segment encompasses self-diagnosed consumers managing symptoms through dietary modification as well as formally diagnosed patients following gastroenterologist recommendations.
- Southeast at 44.5%: The Southeast region leads due to its large urban population, higher consumer purchasing power, and greater awareness of digestive health. The region also benefits from extensive retail and healthcare networks, supporting wider availability and adoption of lactose-free products and related solutions.
Brazil Lactose Intolerance Market Overview
The Brazil lactose intolerance market encompasses food, beverage, and supplement products specifically formulated for individuals with lactose malabsorption, a condition resulting from insufficient production of lactase enzyme in the small intestine, leading to gastrointestinal symptoms (bloating, cramping, diarrhea) upon consumption of conventional lactose-containing dairy products. The market is structured across three product categories: lactose-free dairy products (conventional dairy reformulated through lactase enzyme addition or ultrafiltration), non-dairy alternatives (plant-based beverages and foods derived from oats, almonds, soy, coconuts, or other plant sources replacing conventional dairy), and lactase enzyme supplements (pharmaceutical or nutraceutical products enabling conventional dairy consumption).
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
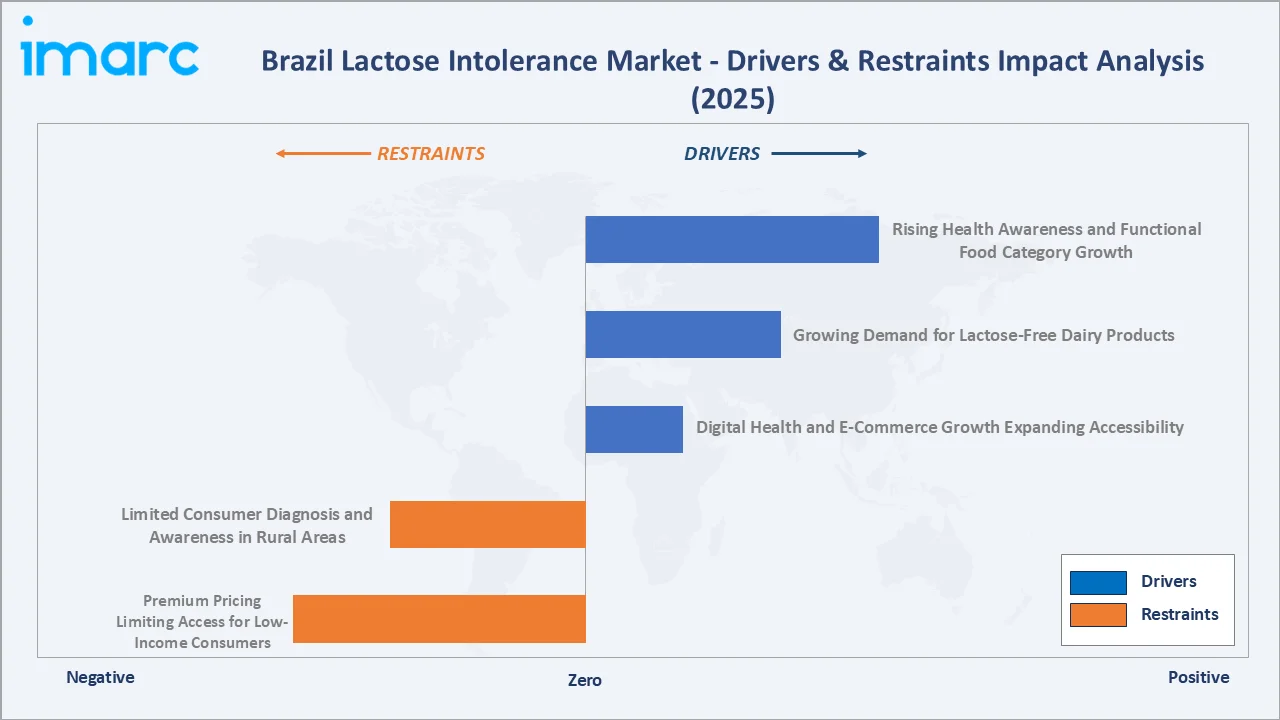
- Rising Health Awareness and Functional Food Category Growth: Post-COVID health consciousness has accelerated Brazilian consumer interest in functional and specialized food products, with lactose-free products benefiting from both genuine medical need and the broader "free-from" food trend among health-conscious consumers. Social media health influencers, nutrition podcasts, and growing gastroenterology digital content are raising awareness of lactose intolerance as a diagnosable and manageable condition, converting symptom-tolerating consumers into active product purchasers.
- Growing Demand for Lactose-Free Dairy Products: The expanding availability of lactose-free alternatives that retain traditional taste and texture is widening consumer choice and encouraging greater adoption, thereby supporting market growth. In September 2026, Brazilian dairy company Tirol has launched a 250g dulce de leche containing no added sugar or lactose. The product maintains the creamy texture and distinctive taste of traditional dulce de leche while catering to consumers seeking lactose-free and reduced-sugar alternatives.
- Digital Health and E-Commerce Growth Expanding Accessibility: Brazil's rapid e-commerce growth is dramatically improving product accessibility for consumers in regions where supermarket lactose-free shelf space is limited. Telemedicine platforms connecting patients with gastroenterologists and dietitians are accelerating formal diagnosis, while subscription e-commerce platforms specializing in health foods are building loyal consumer bases for lactase supplements and plant-based alternative brands.
Market Restraints
- Premium Pricing Limiting Access for Low-Income Consumers: Lactose-free dairy products command price premiums versus conventional dairy equivalents in Brazilian supermarkets, reflecting lactase enzyme processing costs and smaller production runs. Plant-based milk alternatives are frequently priced at 2-3x conventional cow milk. These premiums create access barriers for Brazil's Classe C, D, and E consumers who cannot consistently afford specialized products, limiting market penetration to higher socioeconomic segments.
- Limited Consumer Diagnosis and Awareness in Rural Areas: Brazil's lactose-intolerant population has not been formally diagnosed or is not actively managing their condition through specialized products, instead adapting dietary habits or tolerating symptoms. Insufficient gastroenterologist density in rural areas, low healthcare access among lower-income segments, and cultural normalization of digestive discomfort as a dietary consequence rather than a manageable condition create awareness gaps that limit market conversion from potential to actual consumers.
Market Opportunities
- Affordable Lactose-Free Private Label Product Development: Supermarket private label lactose-free dairy products, priced below national branded equivalents while maintaining regulatory-compliant Sem Lactose specifications, can expand market penetration into the Classe C consumer segment.
- Pediatric and Infant Lactose-Free Formula Market Development: With Brazil's lactose intolerance market attributed to the infant segment and primary lactase deficiency affecting Brazilian newborns, the clinical infant formula segment represents a high-value opportunity for specialized pediatric nutrition companies. Brazilian pediatric formula brands are growing this premium clinical segment through pediatrician and neonatologist prescriptions and hospital supply programs.
Market Challenges
- Regulatory Complexity for Health Claims on Lactose-Free Products: Strict regulatory framework for health claim authorization on food and supplement products requires clinical substantiation at specific regulatory standards before consumer-facing health claims can be made. Lactase supplement companies seeking to make therapeutic efficacy claims, and dairy companies seeking to market products as medically appropriate for lactose intolerance management, navigate complex submission and approval processes that increase time-to-market and compliance costs for new entrant products.
- Consumer Education Gaps on Product Differentiation: Brazilian consumers frequently conflate lactose-free dairy products (still contain milk protein, casein, and whey - inappropriate for milk-allergic individuals) with non-dairy plant-based alternatives (appropriate for both lactose intolerance and cow's milk allergy). This product confusion creates inappropriate purchasing decisions, occasional adverse reactions from milk-allergic consumers using lactose-free dairy products, and difficulty communicating product value propositions across diverse consumer need profiles.
Emerging Market Trends
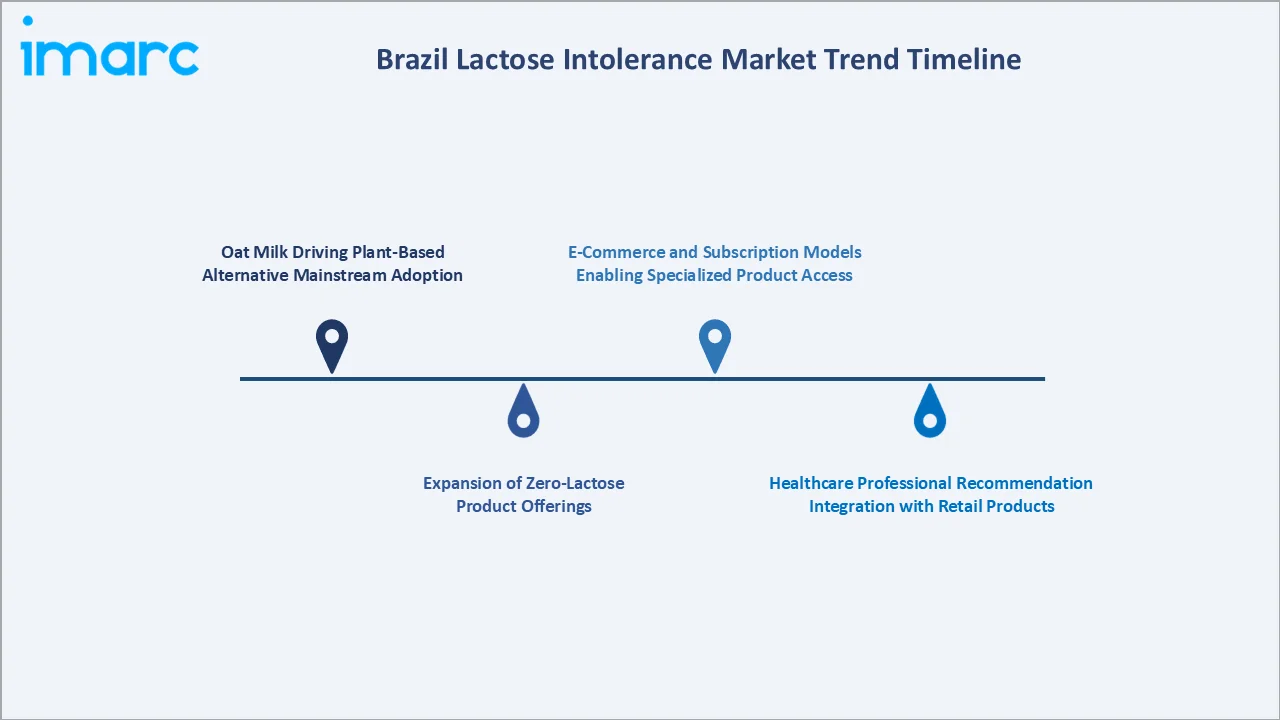
1. Oat Milk Driving Plant-Based Alternative Mainstream Adoption
Oat milk has emerged as the dominant plant-based milk alternative in Brazil, replacing soy milk as the leading non-dairy choice among health-conscious consumers. Global brands and local Brazilian brands are expanding oat milk distribution from specialty health food stores into mainstream supermarkets and coffee shop channels, with artisan coffee shops adopting oat milk as a standard non-dairy offering. The oat milk category's creamy texture, neutral flavor, and strong sustainability narrative are driving trial rates significantly above almond and soy alternatives.
2. Expansion of Zero-Lactose Product Offerings
In September 2026, in Brazil, Anvisa permits products containing up to 100 milligrams of lactose per 100 grams or 100 milliliters to carry a “zero lactose” label. In cheese production, this threshold can be achieved through processes such as whey removal and bacterial fermentation, although trace amounts of lactose may still remain. Clear regulatory standards for “zero lactose” labeling are encouraging dairy manufacturers in Brazil to develop and commercialize products tailored to lactose-sensitive consumers. This is supporting greater product diversification and increasing the availability of specialized lactose-free dairy options across retail channels.
3. E-Commerce and Subscription Models Enabling Specialized Product Access
E-commerce is fundamentally reshaping the distribution economics of lactose intolerance products, enabling niche plant-based brands and specialty lactase supplement companies to reach nationwide consumer bases without the shelf space economics of physical retail. Specialized health food e-commerce platforms are building lactose intolerance product categories with SKUs that far exceed the 15-30 lactose-free SKUs typically stocked in physical supermarkets. Monthly subscription models for plant-based milks and lactase supplements are generating recurring revenue and high consumer retention for digital-first brands.
4. Healthcare Professional Recommendation Integration with Retail Products
Healthcare professional recommendation integration involves aligning lactose-free foods, lactase supplements, and related retail products with guidance provided by doctors, dietitians, and nutritionists. Such recommendations can improve consumer awareness and confidence when selecting products for lactose management. Partnerships between healthcare and retail channels can also enhance product visibility and encourage informed purchasing decisions, supporting market adoption.
Industry Value Chain Analysis
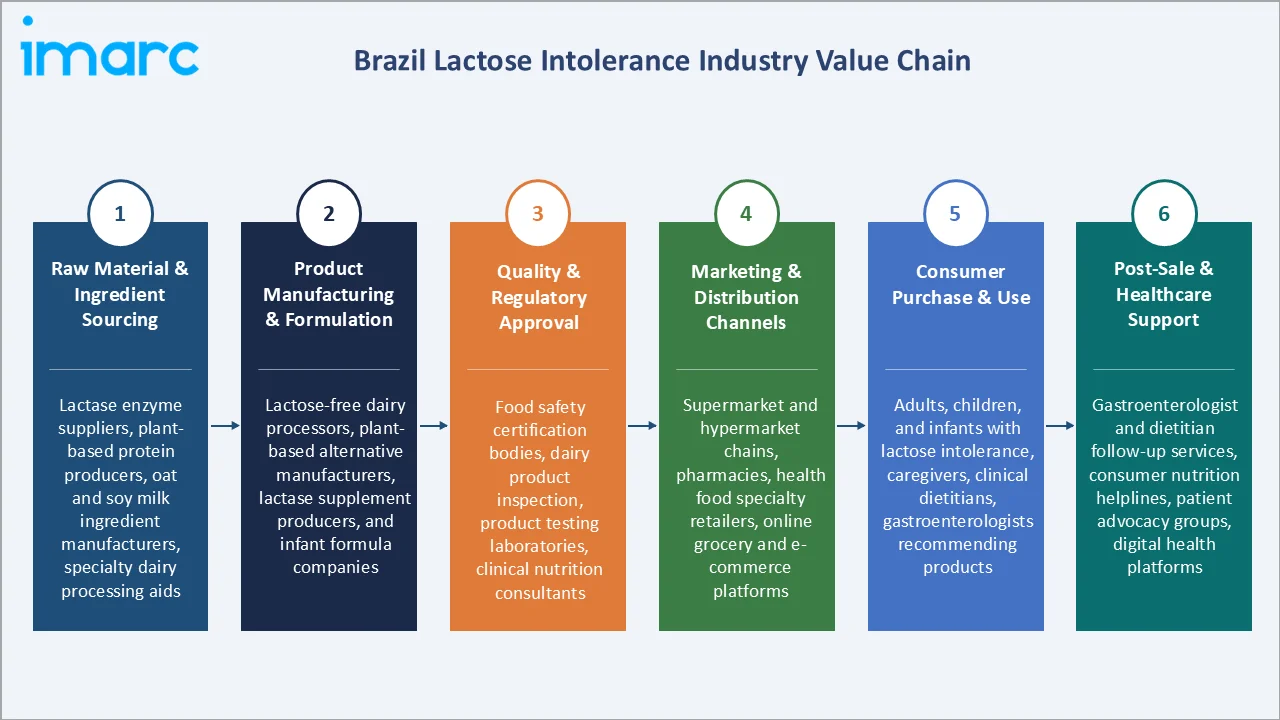
The Brazil lactose intolerance market value chain encompasses raw material and ingredient sourcing, product manufacturing and formulation, quality testing and regulatory approval, distribution channel marketing, end consumer purchase and use, and healthcare and post-sale support services.
|
Stage |
Key Players |
|
Raw Material & Ingredient Sourcing |
Lactase enzyme suppliers, plant-based protein producers, oat and soy milk ingredient manufacturers, specialty dairy processing aids. |
|
Product Manufacturing & Formulation |
Lactose-free dairy processors, plant-based alternative manufacturers, lactase supplement producers, and infant formula companies. |
|
Quality & Regulatory Approval |
Food safety certification bodies, dairy product inspection, product testing laboratories, clinical nutrition consultants. |
|
Marketing & Distribution Channels |
Supermarket and hypermarket chains, pharmacies, health food specialty retailers, online grocery and e-commerce platforms. |
|
Consumer Purchase & Use |
Adults, children, and infants with lactose intolerance, caregivers, clinical dietitians, gastroenterologists recommending products. |
|
Post-Sale & Healthcare Support |
Gastroenterologist and dietitian follow-up services, consumer nutrition helplines, patient advocacy groups, digital health platforms. |
Product manufacturing and formulation represent the highest value-creation stage, where technical differentiation in lactase enzyme activity, taste profile optimization, and nutritional fortification creates consumer preference and brand premium pricing power. Companies achieving consistent lactose reduction while maintaining the organoleptic properties of conventional dairy capture the highest consumer value in the category.
Technology Landscape in the Brazil Lactose Intolerance Industry
Lactase Enzyme Processing Technology in Dairy Manufacturing
Commercial lactose-free dairy production relies on two primary enzymatic processing approaches: batch neutralization (adding fungal or yeast-derived lactase enzyme to processed milk and allowing lactose hydrolysis under controlled temperature) and continuous column systems (passing milk through immobilized lactase enzyme reactors for rapid hydrolysis at production scale). Brazilian dairy manufacturers use batch enzymatic processing to achieve < 0.1 g lactose per 100mL in their Sem Lactose lines, while larger producers are investing in continuous column systems for improved processing efficiency and consistency at scale.
Plant-Based Milk Processing and Formulation Technology
Brazilian plant-based milk manufacturers are deploying oat milling and enzymatic beta-glucan processing technology to produce oat milk with improved texture, mouthfeel, and stability versus early-generation plant-based beverages. Homogenization technology enables fat emulsification from whole nuts and seeds without stabilizer additives, supporting clean-label positioning preferred by premium Brazilian plant-based consumers. Micronutrient fortification technology is enabling plant-based brands to make nutritional equivalence claims that reassure health-conscious consumers making dietary transitions.
Rapid Lactose Diagnostic and Consumer Testing Technology
Point-of-care hydrogen breath test devices and home-use genetic lactase gene testing kits are emerging as enabling technologies for the Brazilian lactose intolerance market, potentially dramatically reducing the time from symptom onset to formal diagnosis. Brazilian health tech companies are developing digital hydrogen breath test monitoring systems connected to mobile health apps that enable home-based lactose tolerance assessment, creating a gateway to product recommendation and consumer market conversion that bypasses the traditional 3-6 month specialist appointment waiting time.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Product Type |
Lactose-free Dairy Products |
46.7% |
2025 |
|
End User |
Adults |
72.4% |
2025 |
|
Distribution Channel |
🔒 |
🔒 |
2025 |
|
Region |
Southeast |
44.5% |
2025 |
By Product Type
Lactose-free dairy products command 46.7% in 2025, reflecting the preference of Brazilian consumers for dairy-derived nutrition when available in tolerable form. Lactose-free UHT milk serves as the category entry point for the majority of Brazilian lactose-intolerant consumers, with major companies competing across all supermarket price tiers.
To access detailed market analysis, Request Sample
Non-dairy alternatives at 34.2%, growing at the fastest rate of ~7.2% CAGR, encompass oat milk, almond milk, coconut milk, soy milk, Brazil nut milk, and plant-based yogurt, cheese, and ice cream. Lactase supplements at 19.1% serve the pharmaceutical management approach, enabling conventional dairy consumption through enzymatic intervention, with strong growth through pharmacy chains and e-commerce health platforms.
By End User
Adults dominate at 72.4% end-user share in 2025, representing the largest purchasing demographic who are self-managing or medically managing lactose intolerance through diet modification and specialized product consumption. Brazilian adults with lactose intolerance show high awareness of condition management options relative to global averages, particularly in urban Southeast and South markets where health food retail penetration and nutritionist recommendation rates are highest.
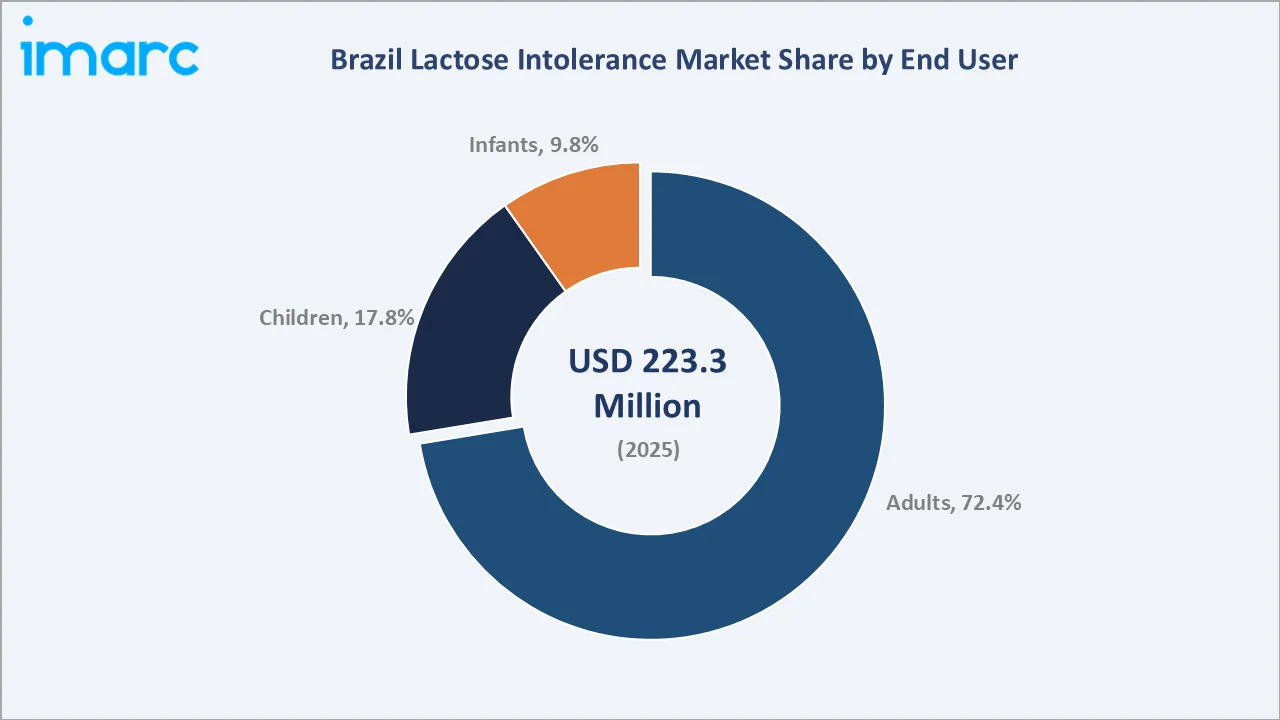
Children at 17.8% represent a high-value segment where parents seek specialized nutritional alternatives to conventional dairy, particularly lactose-free milk, yogurt, and cheese for school lunches, with strong parental willingness to pay premiums for child-appropriate formulations. Infants at 9.8% represent the clinical segment where pediatric gastroenterologists prescribe specialized lactose-free infant formulas for primary lactase deficiency or secondary lactase deficiency following gastrointestinal illness.
Regional Market Insights
|
Region |
Share (2025) |
Key Brazil Lactose Intolerance Market Drivers & Characteristics |
|
Southeast |
44.5% |
Reflecting the largest consumer market, highest healthcare diagnosis rates for lactose intolerance, concentration of organized retail distribution for lactose-free and plant-based products, and the highest per-capita spending on premium health and functional food products. |
|
South |
22.9% |
Reflecting high income levels and strong dairy consumption culture, creating elevated lactose intolerance awareness and demand for lactose-free dairy alternatives, combined with well-developed supermarket distribution of branded lactose-free products. |
|
Northeast |
15.8% |
Reflecting a high regional prevalence of lactose intolerance linked to mixed ethnic heritage populations, growing health awareness in urban centers, and increasing modern retail distribution enabling access to previously unavailable lactose-free product formats. |
|
Central-West |
9.3% |
Reflecting high per-capita income and healthcare access supporting formal lactose intolerance diagnosis and product adoption, growing urban professional populations, and expanding organized retail lactose-free shelf space in regional capitals. |
|
North |
7.5% |
Reflecting the high indigenous and mixed-heritage population with elevated genetic lactose intolerance rates, limited healthcare access for formal diagnosis, and underdeveloped cold chain infrastructure restricting lactose-free dairy product penetration in smaller cities and rural communities. |
Southeast's 44.5% share reflects Sao Paulo state's combination of Brazil's largest consumer market, highest organized retail supermarket density with dedicated lactose-free shelf sections, highest per-capita spending on health and functional foods, and the greatest concentration of gastroenterologists and registered dietitians generating formal diagnosis and product recommendation rates well above the national average. South Brazil's 22.9% reflects the paradox of the region with the highest traditional dairy consumption culture also having the highest organized lactose-free product adoption, as high dairy consumption frequency increases symptom frequency and diagnosis motivation among the region's lactose-intolerant population.
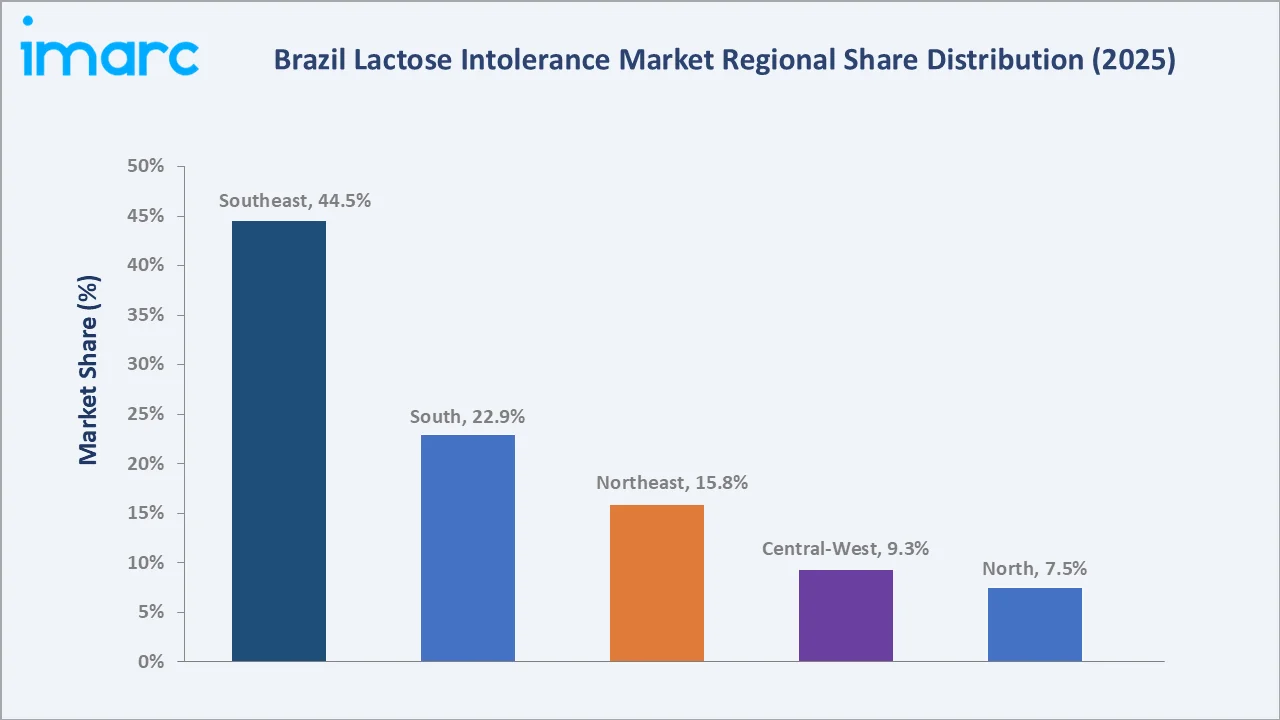
Northeast at 15.8% is the market's highest growth potential region due to high genetic prevalence and growing urban middle-class health food retail access. Central-West at 9.3% is growing through a high-income consumer base. The North at 7.5% represents the market's highest prevalence but lowest managed-consumer penetration, limited by cold chain infrastructure and healthcare access constraints.
Competitive Landscape
The Brazil lactose intolerance market features a competitive landscape spanning dairy majors with lactose-free extensions, pharmaceutical lactase supplement providers, clinical nutrition multinationals, and Brazilian plant-based innovators. Market leadership is contested through product range breadth, distribution channel reach, healthcare professional engagement, and brand trust among lactose-intolerant consumers.
|
Company |
Key Products |
Market Position |
Core Strength |
|
Tirolez Dairy Products Ltd. |
Spreadable Cheese Lactose Free, Mozzarella Lactose Free Cheese, Minas Fresh Lactose Free Cheese |
Market Leader |
Tirolez provides the largest portfolio of lactose-free cheeses and dairy spreads in Brazil, helping consumers with lactose intolerance enjoy traditional dairy products without digestive discomfort |
|
Laticinios Bela Vista SA |
Dairy Drink with Chocolate Flavor Zero Lactose, UHT Table Cream Zero Lactose |
Market Leader |
Laticínios Bela Vista SA played a revolutionary and market-defining role in addressing lactose intolerance in Brazil through their brand Piracanjuba. |
|
Abbott |
Similac Isomil, PediaSure |
Established Player |
Abbott plays a leading role in managing lactose intolerance and pediatric nutrition in Brazil by providing specialty formulas and clinical nutrition solutions designed for sensitive digestive systems. |
|
Nestlé |
NINHO Zero Lactose |
Established Player |
Nestlé provides specialized low-lactose dairy and plant-based beverage options in Brazil to support consumers who experience lactose intolerance. |
|
Verde Campo |
Natural Whey Milk Dessert, Natural Whey Protein Dessert, Natural Whey Yogurt, Natural Skimmed Yogurt LACFREE, LACFREE Butter, LACFREE Cheese |
Innovator |
Verde Campo plays a pioneering role in Brazil's functional and lactose-free dairy market by providing natural, high-protein, and zero-lactose alternatives for consumers with digestive sensitivities. |
Competitive dynamics are evolving as traditional dairy companies defend market share against plant-based alternatives through lactose-free dairy innovation, while Brazilian plant-based startups challenge global brands with locally relevant formulations. Healthcare channel engagement, through gastroenterologist and dietitian product sampling, prescription support, and digital health integration, is becoming an increasingly important competitive differentiator separating premium clinical brands from commodity retail alternatives.
Key Company Profiles
Tirolez Dairy Products Ltd.
Tirolez Dairy Products Ltd. is a Brazilian dairy company with a diversified portfolio of cheese and value-added dairy products, including options designed for lactose-sensitive consumers. The company serves retail and food service channels through established production and distribution capabilities. Within the Brazil lactose intolerance market, its lactose-free offerings support growing consumer demand for dairy products that combine convenience, quality, and dietary suitability.
- Key Products: Spreadable Cheese Lactose Free, Mozzarella Lactose Free Cheese, Minas Fresh Lactose Free Cheese.
- Strategic Focus: Expanding its lactose-free and value-added dairy portfolio to address the evolving dietary needs of lactose-sensitive consumers. Its strategy emphasizes product innovation, quality enhancement, and broader distribution to strengthen accessibility across the Brazilian market.
Laticinios Bela Vista SA
Laticinios Bela Vista SA is a prominent Brazilian dairy company offering a diversified portfolio of milk and value-added dairy products, including lactose-free alternatives. The company serves consumers through established brands and an extensive production and distribution network. Within Brazil’s lactose intolerance market, its specialized dairy offerings address growing demand for products that accommodate digestive and dietary preferences.
- Key Products: Dairy Drink with Chocolate Flavor Zero Lactose, UHT Table Cream Zero Lactose.
- Strategic Focus: Expanding its lactose-free and value-added dairy portfolio to meet rising demand from lactose-sensitive consumers. Its strategy emphasizes product innovation, broader distribution, quality enhancement, and portfolio diversification to strengthen its presence across Brazil.
Market Concentration Analysis
The Brazil lactose intolerance market is moderately concentrated, with Tirolez Dairy Products Ltd., Nestlé, and Verde Campo collectively accounting for an estimated 35-45% of lactose-free dairy product revenues through their nationally distributed Sem Lactose product ranges. The plant-based alternatives segment is the most fragmented, with global brands, regional importers, and Brazilian startups sharing revenue across a rapidly growing but still relatively small category.
Market consolidation is expected through the forecast period as investment capital flows into successful plant-based startups enabling scale-up, and as large dairy companies respond to plant-based competition by acquiring or partnering with local plant-based brands. The supplement segment may experience consolidation as pharmaceutical distribution advantages favor larger players, while the clinical infant formula segment remains dominated by the established global clinical nutrition multinationals Abbott and Nestlé.
Investment & Growth Opportunities
Highest Growth Segments
Non-dairy plant-based alternatives (~7.2% CAGR) through oat and nut milk expansion, lactase supplements (~6.8% CAGR) through e-commerce and pharmacy growth, Southeast urban premium lactose-free specialty products (~6.5% CAGR); pediatric lactose-free clinical nutrition, D2C subscription health food models, and affordable private label lactose-free dairy for mass market penetration represent the highest-return investment vectors through 2034.
Investment Themes
- Plant-Based Beverage Brand Building with Local Brazilian Ingredients: Developing plant-based milk products from distinctively Brazilian ingredients creates unique product differentiation versus generic global oat and almond milk brands while supporting sustainability narratives around biodiversity and smallholder farmer income. Products with genuine Brazilian ingredient provenance can command international export premiums alongside domestic premium retail positioning.
- Pediatric and Clinical Nutrition Market Penetration: The infant and child lactose intolerance segment commands premium pricing and strong healthcare professional recommendation loyalty, creating high revenue per unit and low price sensitivity. Investment in pediatrician relationship management, clinical research supporting product health claims, and regulatory-compliant infant formula manufacturing represents a capital-intensive but high-barrier, high-margin market development opportunity.
Future Market Outlook (2026-2034)
The Brazil lactose intolerance market is projected to grow from USD 223.3 Million in 2025 to USD 236.7 Million in 2026, reaching USD 377.2 Million by 2034, exhibiting a CAGR of 6.00% during 2026-2034. The market is projected to reach an anchor value of USD 298.8 Million by 2030, representing the mid-period milestone at which oat milk achieves mainstream supermarket parity with conventional UHT milk, lactose-free dairy Sem Lactose ranges extend to core dairy category SKUs, and lactase enzyme supplements achieve 30%+ penetration among formally diagnosed Brazilian adults.
Three structural forces will define the Brazil lactose intolerance market through 2034. First, the diagnosis gap closure represents the single largest market expansion lever available, with each percentage point of diagnosis penetration improvement potentially adding high annual market revenue. Second, the plant-based alternatives category's maturation will make plant-based substitution an economically rational choice for the full demographic range of lactose-intolerant consumers, not only the premium health-conscious minority. Third, ingredient and formulation innovation will create new product categories that expand the market's total addressable revenue per consumer beyond the current product types.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with Brazilian gastroenterologists, registered dietitians specializing in digestive health, dairy company product managers, plant-based startup founders, pharmaceutical lactase supplement executives, pharmacy chain category managers, and consumer health organizations. These discussions validated market size estimates, product type demand dynamics, end-user segment adoption patterns, and technology trajectory for the 2026-2034 forecast period.
Secondary Research
Secondary research encompassed regulatory publications on lactose-free food labeling, Brazilian lactose intolerance prevalence studies, food consumption surveys, Brazilian dairy and plant-based industry association data, IMARC Group proprietary functional food and clinical nutrition databases, company annual reports, and academic publications covering lactose malabsorption epidemiology and management in Brazilian populations through 2025.
Forecasting Models
Forecasting models incorporated historical market revenue correlations with Brazilian GDP, middle-class expansion, and functional food category growth rates; lactose intolerance diagnosis rate improvement trajectories from healthcare access expansion, plant-based beverage adoption S-curves calibrated against comparable emerging market case studies, lactase supplement penetration projections based on pharmacy channel expansion and e-commerce growth, and macroeconomic indicators. Both bottom-up product category and distribution channel revenue modeling and top-down total addressable population approaches were cross-validated for forecast consistency.
Brazil Lactose Intolerance Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Product Types Covered | Lactose-free Dairy Products, Lactase Supplements, Non-dairy Alternatives |
| End Users Covered | Adults, Children, Infants |
| Distribution Channels Covered | Supermarkets/Hypermarkets, Online Retail, Health Food Stores, Pharmacies |
| Regions Covered | Southeast, South, Northeast, North, Central-West |
| Companies Covered | Tirolez Dairy Products Ltd., Laticinios Bela Vista SA, Abbott, Nestlé, Verde Campo, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Brazil lactose intolerance market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Brazil lactose intolerance market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Brazil lactose intolerance industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Brazil Lactose Intolerance Market Report
The Brazil lactose intolerance market reached USD 236.7 Million in 2026, driven by the expansion of Sem Lactose dairy product ranges from major Brazilian dairy brands, rapid plant-based alternative adoption, growing lactase supplement pharmacy and e-commerce distribution, and rising health awareness among Brazil's large lactose-intolerant population.
The Brazil lactose intolerance market is projected to grow at a CAGR of 6.00% during 2026-2034, driven by plant-based alternative mainstream adoption, lactose-free dairy product range expansion, e-commerce health product distribution growth, pediatric clinical nutrition development, and consumer health awareness improvement.
The market is projected to reach USD 298.8 Million by 2030, representing the mid-period milestone when oat milk achieves supermarket pricing parity with conventional milk, lactose-free Sem Lactose dairy covers all core product categories, and lactase supplements reach high penetration among formally diagnosed Brazilian adults.
Lactose-free dairy products lead with a 46.7% share in 2025, driven by the launch of comprehensive Sem Lactose product ranges covering UHT milk, mozzarella, prato, requeijao, and yogurt at major supermarkets nationwide.
Adults lead with a 72.4% share in 2025, representing the largest consumer base that is self-managing or medically managing lactose intolerance through specialized product consumption, with the highest awareness of lactose-free dairy, plant-based alternatives, and lactase supplement management options.
The Southeast leads with a 44.5% share in 2025, anchored by São Paulo's largest consumer market, highest organized retail lactose-free shelf penetration, highest per-capita health food spending, and the greatest concentration of healthcare professionals generating formal diagnosis and product recommendation rates.
Key players include Tirolez Dairy Products Ltd., Laticinios Bela Vista SA, Abbott, Nestlé, and Verde Campo, among others.
The market is projected to reach USD 377.2 Million by 2034, driven by diagnosis gap closure converting unmanaged consumers to active product users, plant-based alternative price parity enabling broader demographic adoption, next-generation lactase formulations, and pediatric clinical nutrition market growth.
Key opportunities include plant-based beverages from distinctly Brazilian ingredients, affordable private-label lactose-free dairy for mass market penetration, pediatric clinical nutrition market development, digital health diagnostic-to-product conversion platforms, oat milk foodservice channel expansion, and D2C subscription health food models.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade