Comparing North America, Europe, and Asia-Pacific: Where General Aviation Demand Is Strongest Globally
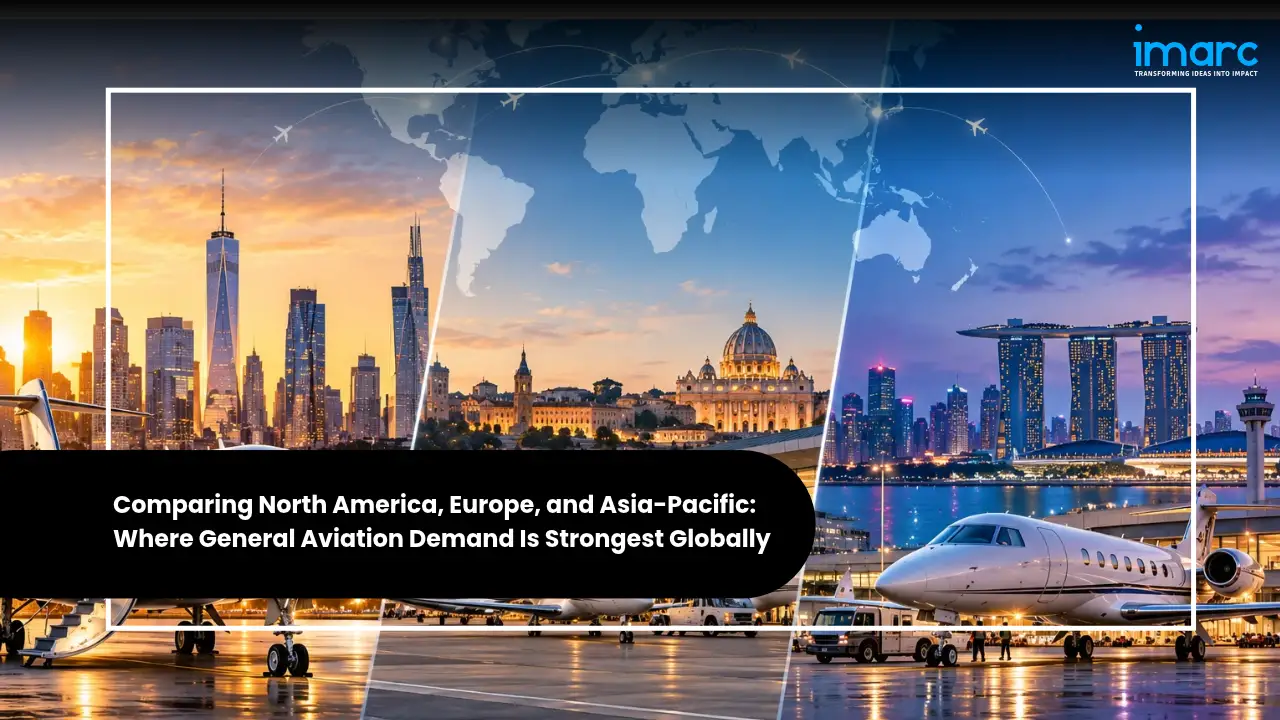
Introduction: The General Aviation Market Compared
The general aviation market is no longer a single, uniformly growing market. It behaves as a set of regional demand systems with very different fleet age profiles, airport densities, financing conditions and regulatory costs. IMARC Group estimates that the global market stood at USD 27.6 Billion in 2025, is estimated at USD 28.4 Billion in 2026, and will reach USD 35.5 Billion by 2034, expanding at a CAGR of 2.83% between 2026 and 2034. That moderate headline rate hides a much sharper regional split, which is exactly what this comparison sets out to explain.
Three forces carry most of the growth. Demand for business and private air travel keeps rising because it converts travel time into productive time for companies and entrepreneurs. Continuous advances in avionics, propulsion systems and safety equipment keep improving aircraft reliability and utilisation. Public and private spending on runways, hangars, terminals, navigation aids and air traffic management determines how much of that demand can actually fly. Specialised missions such as air ambulance, search and rescue, aerial surveillance and pipeline inspection add a demand floor that is largely independent of discretionary flying.
The defining theme is the convergence of electrification, autonomy and digital operations. The strategic agreement signed between Honeywell and Bombardier in December 2024, valued at USD 17 Billion and covering next generation avionics such as Honeywell Anthem, enhanced engines and satellite communications, shows how avionics and software content per aircraft keeps rising even where unit volumes are flat. Investment is shifting from airframe metal toward electronics, data and energy systems.
This blog compares North America, Europe and Asia-Pacific on infrastructure depth, fleet demand, regulation and investment, identifies where demand is strongest today and where it is compounding fastest, and translates that into practical implications for operators, manufacturers and investors.
Key Takeaways
- Scale and trajectory: The global general aviation market stood at USD 27.6 Billion in 2025, is estimated at USD 28.4 Billion in 2026, and is projected to reach USD 35.5 Billion by 2034, a CAGR of 2.83% from 2026 to 2034.
- Leading product segment: Helicopters held around a 53.2% share in 2025, the largest product category, sustained by offshore transport, emergency medical services, search and rescue and tourism missions.
- Leading region: North America remains the largest regional market, anchored by the United States, where a network of more than 5,000 regional airports delivers access that scheduled airlines cannot replicate.
- Notable recent development: In January 2025 the Biden-Harris Administration announced over USD 332 Million in Bipartisan Infrastructure Law grants to modernise airports across 32 states, directly expanding general aviation capacity.
- Key trend: Electrification and sustainable fuel adoption, illustrated by Honda Aircraft Company flying the HondaJet on 100% sustainable aviation fuel in October 2025, the first twin-turbine very light jet to do so.
Market Size, Share & Growth Outlook
According to IMARC Group, the global general aviation market grew from USD 27.6 Billion in 2025 to an estimated USD 28.4 Billion in 2026 and is forecast to reach USD 35.5 Billion by 2034, exhibiting a CAGR of 2.83% during 2026-2034. The leading segments are:
- Product: Helicopters are the largest product category, holding around a 53.2% share in 2025. Their lead reflects versatility rather than price alone: they reach remote sites without runways, serve offshore oil and gas platforms, support medical evacuation and search and rescue, and are cheaper to acquire and operate than comparable fixed-wing aircraft. Piston fixed-wing aircraft, turboprops and business jets make up the remainder, with business jets carrying the highest value per unit.
- Application: Demand divides into commercial and non-commercial use. Commercial flying covers air charter, cargo transport, aerial surveying, crop dusting and pipeline inspection, where the value proposition is schedule independence and access to locations that scheduled carriers do not serve. Non-commercial flying covers personal transport, recreational flying, flight training and government or military use, and it is the segment most sensitive to pilot licensing activity and aircraft ownership costs.
- Region: North America dominates the market, supported by extensive infrastructure, a strong economic base and high demand for private and business aviation. Within the region, the United States accounts for a significant majority of activity, helped by a dense airport network and a long established culture of private flying. Europe and Asia-Pacific follow, with Asia-Pacific positioned as the fastest developing region.
The segmentation shows a market whose current centre of gravity is a mature helicopter and business aircraft fleet in North America, while incremental growth is weighted toward Asia-Pacific and toward new aircraft categories.
Recent News & Mega Announcements
Developments between July 2024 and October 2025 show how public funding, sustainability commitments and ownership changes are reshaping capacity across the three regions:
- US airport modernisation funding (January 2025): More than USD 332 Million was announced through the Bipartisan Infrastructure Law to modernise airports in 32 states, improving safety, lighting, runways and navigation aids at facilities that general aviation depends on.
- Honeywell and Bombardier technology agreement (December 2024): The strategic agreement, valued at USD 17 Billion, covers next generation avionics including Honeywell Anthem, enhanced engines and satellite communications, and signals that avionics content per airframe is becoming a larger share of aircraft value.
- GMR Airports stake in Bird Delhi General Aviation Services (January 2025): GMR Airports Ltd entered a share purchase agreement to acquire up to 500,000 equity shares and 19,000,000 non-cumulative compulsorily convertible preference shares, representing 50% of paid-up share capital, pointing to consolidation in Indian business aviation ground handling.
- Gulfstream sustainable fuel milestone (October 2025): Gulfstream Aerospace Corp. reported that its corporate, demonstration and support fleet had surpassed 3 million nautical miles flown on sustainable aviation fuel blends, and displayed the G800, G700, G600 and G400 at NBAA-BACE 2025.
- HondaJet 100% SAF flight (October 2025): Honda Aircraft Company became the first twin-turbine very light business jet manufacturer to fly the HondaJet on 100% sustainable aviation fuel, a test of fuel compatibility in the light jet category rather than a laboratory demonstration.
- HIF Global and Airbus e-SAF memorandum (July 2024): Two companies agreed to advance electro-sustainable aviation fuel production, with commercial-scale e-Fuel facilities under development in Texas, Uruguay, Australia and Chile, which matters because fuel availability, not airframe capability, currently constrains SAF uptake at regional airfields.
Industry Trends Shaping 2026
Three technology and infrastructure shifts will decide which region converts interest into deliveries over the next two years.
1. Electric and Hybrid Propulsion Moving From Prototype to Certification
Battery energy density and motor efficiency have reached the point where short-haul electric flight is treated as an engineering programme rather than a research question. The commercial argument rests on operating economics: electricity is cheaper per flight hour than avgas or jet fuel, electric motors have far fewer moving parts, and low noise profiles can reopen airfields that neighbour complaints had effectively closed. Range remains the binding constraint, which limits early deployments to training circuits, sightseeing, short charter legs and cargo runs of under roughly an hour. That is why flight schools, flying clubs and recreational operators are the natural first buyers rather than long-haul charter companies, and why the aerobatic aircraft market is being watched as an early test bed for high-torque electric powertrains, where instant torque and quiet operation matter more to operators than range. Certification is the gating factor: every new powertrain needs its own compliance path with the FAA or EASA, and programme timelines have slipped repeatedly. Electrification is therefore a 2026 to 2030 volume story in training and light sport categories, not an overnight fleet replacement.
2. Urban Air Mobility and Vertiport Infrastructure
Urban air mobility has moved from concept studies to planning applications in several metropolitan areas, and the constraint is now physical rather than technical. Vertiports need land, grid capacity and noise approval, and each of those sits with municipal authorities rather than aviation regulators. The near-term relevance for general aviation is less about passenger air taxis and more about the airspace management, charging infrastructure and ground systems being built to support them, which regional operators and air charter businesses can share. Certification of passenger carrying eVTOL aircraft has taken longer than promoters expected, so revenue in 2026 is likely to come mainly from cargo, survey and pilot training variants. Regions that pair clear vertiport rules with grid investment, particularly parts of Europe and the Gulf, will capture early operations, while regions without them will see programmes stall at the demonstration stage.
3. Digital Operations, Cloud Platforms and Data-Driven Infrastructure
Cloud-based flight planning, predictive maintenance and digital airworthiness records are changing the cost base of small operators. The aviation cloud market is expanding because a five-aircraft charter operator can now buy scheduling, crew duty tracking and maintenance forecasting as a subscription instead of building internal systems. The aircraft computers market follows the same logic on the airframe side, where integrated modular avionics replace discrete boxes, cutting weight and wiring while raising software content per aircraft. These systems only pay off where ground infrastructure can use the data, which is why the aviation infrastructure market and the software layer are increasingly assessed together. Remote and digital tower deployments keep low-traffic aerodromes open with fewer controllers, and performance-based navigation lets turboprops and business jets fly approaches once restricted to larger aircraft. For operators, the practical result is higher aircraft availability and lower unplanned maintenance, which improves the utilisation economics that regional demand depends on.

Geographic Hotspots in the General Aviation Market
Demand is strongest in absolute terms in North America, and the reason is structural rather than cyclical. The United States operates a network of more than five thousand regional airports, which means a business jet or turboprop can land within a short drive of almost any mid-sized city. That density supports a large community of private pilots, aircraft owners, flying clubs and flight schools, and it sustains a secondary market in used aircraft that keeps entry costs lower than anywhere else. Business aviation demand continues to accelerate as corporations prioritise flexible scheduling over airline connections, and emergency medical services, search and rescue and disaster response rely on general aviation assets that have no practical substitute. Canada contributes a smaller but stable share, dominated by resource, medical and utility flying over long distances.
Europe shows steady expansion rather than rapid growth. Demand is pulled by a growing high-net-worth population seeking time-efficient travel and by congestion in metropolitan areas where ground transport is at capacity. Business aviation remains robust for executive transport and client travel, but the market operates under tighter noise restrictions, stricter slot rules and higher fuel taxation than North America, which raises operating costs and slows fleet renewal. Regulatory harmonisation across member states is gradually reducing administrative burden for operators flying between countries, and sustainability rules are pushing faster adoption of sustainable aviation fuel and electric training aircraft than the region's growth rate alone would suggest.
Asia-Pacific is where the growth rate is highest, even though absolute volumes remain below North America. Rapid economic development, expanding corporate sectors and rising high-net-worth populations across China, India, Japan, South Korea, Australia and Indonesia are creating first-time demand rather than replacement demand. Infrastructure is being built to meet it: new regional airports, dedicated general aviation facilities and modernised air traffic management. Island nations and remote regions rely on general aviation for cargo and essential services where scheduled flights are uneconomic. India's regional connectivity framework has expanded short-haul connectivity to smaller cities, and operator interest is visible in transactions such as GMR Airports' stake in Bird Delhi General Aviation Services. The binding constraints are pilot supply, maintenance capacity and customs and landing procedures rather than customer demand.
Latin America and the Middle East and Africa complete the picture. In Latin America, general aviation fills gaps where geography and low population density make scheduled service unviable, with agricultural aviation, medical evacuation and tourism flights carrying much of the activity, although airport and navigation coverage remains uneven. In the Gulf, concentrated wealth and new aviation hubs support strong business aviation and helicopter demand, including offshore oil and gas transport, while parts of Africa face insurance and security costs that limit route viability even where demand exists.
Competitive Landscape & Key Players Strategies
The competitive landscape combines established manufacturers with scale in conventional fixed-wing, turboprop and helicopter production, and a younger group of electric vertical take-off and landing developers targeting urban air mobility. Competition is intensifying in avionics, flight training and ground infrastructure as well, and companies are using collaborations, acquisitions and supply agreements to extend reach into air taxi, cargo and recreational segments. Sustainability credentials have become a differentiator in tender processes and corporate procurement, which is why airframers now publish sustainable fuel milestones alongside delivery numbers.
- Gulfstream Aerospace Corporation: The US business jet manufacturer competes at the large cabin end and uses sustainability performance as a brand asset, with its fleet surpassing 3 million nautical miles flown on sustainable aviation fuel blends by October 2025.
- Bombardier: Focused on business jets, and its December 2024 technology agreement with Honeywell, valued at USD 17 Billion, positions next generation avionics and connectivity as core to its product roadmap.
- Textron Aviation Inc.: Holds the broadest portfolio across piston, turboprop and jet aircraft through the Cessna, Beechcraft and Hawker brands, which gives it exposure to flight training demand and to corporate replacement cycles simultaneously.
- Cirrus Design Corporation: Has built its position on piston and single-engine jet aircraft with integrated avionics and a strong training and owner-flown following.
- Embraer: Combines business jets with regional and defence programmes, giving it scale advantages in engineering and aftermarket support.
- Dassault Aviation: Competes in long-range business jets with a focus on range, efficiency and military-derived engineering discipline.
- Pilatus Aircraft Ltd: The PC-12 turboprop remains a reference point for utility and regional transport missions where runway quality and operating cost matter.
- Honda Aircraft Company: Positioned in the very light jet category and used the HondaJet's October 2025 flight on 100% sustainable aviation fuel to demonstrate fuel compatibility ahead of competitors in its class.
- Diamond Aircraft Industries: Emphasises composite airframes and efficient piston and training aircraft, a portfolio that aligns with the electrification of flight training.
- Piper Aircraft, Inc: Serves training and personal transport demand with a piston-heavy line-up, making it sensitive to flight school economics.
- Robinson Helicopter Company: Leads light helicopter volume with simple, low-cost designs that suit training, tourism and utility work.
- Eclipse Aerospace, Inc.: Operates in the very light jet segment, where aftermarket support and upgrade programmes matter as much as new sales.
Policy & Regulatory Landscape, Challenges & Risks
Government policy has become a primary market force, shaping where capacity is built and what aircraft can fly. Key frameworks include:
- Bipartisan Infrastructure Law airport grants (United States): Over USD 332 Million was announced in January 2025 for airport modernisation across 32 states, funding runway, lighting and safety upgrades at general aviation facilities and effectively underwriting regional capacity that private operators cannot finance alone.
- FAA Reauthorization Act of 2024: The multi-year reauthorisation signed in May 2024 sets funding levels and programme direction for airport improvement, safety oversight and pilot training pathways, giving manufacturers and operators a stable planning horizon for fleet and infrastructure decisions.
- ReFuelEU Aviation (European Union): The mandate requires a minimum share of sustainable aviation fuel at EU airports, starting at 2% from 2025 and rising in stages to 2050, which raises fuel costs for operators but creates a guaranteed demand pool for producers and accelerates fleet compatibility work.
- ICAO CORSIA: The global carbon offsetting scheme for international aviation creates reporting obligations that flow down to business aviation operators, pushing adoption of emissions monitoring software and favouring operators with modern, fuel-efficient fleets.
On the constraining side, several structural risks persist:
- Pilot and technician shortage: Training capacity has not kept pace with retirements and airline hiring, which caps utilisation growth and raises crew costs, particularly in Asia-Pacific where instructor supply is thin.
- Infrastructure and airspace integration gaps: vertiports, charging facilities and digital tower coverage are approved by municipal and national bodies on different timelines, so aircraft certification can run ahead of the ground systems needed to operate them.
- Certification and technology risk: Electric and autonomous systems require new compliance paths with the FAA and EASA, and schedule slippage raises development costs and delays the revenue that underwrites those programmes.
- Capital intensity and cost volatility: Aircraft acquisition, insurance and fuel costs are sensitive to interest rates and energy prices, and in regions with weaker currencies, financing conditions can defer fleet replacement even where demand is present.
Forecast 2026-2034: General Aviation Market Trajectory
IMARC Group projects the market to move from USD 28.4 Billion in 2026 to USD 35.5 Billion by 2034, a CAGR of 2.83% across the period. In absolute terms that is roughly USD 7.1 Billion of additional annual value over eight years, a measured expansion consistent with a mature installed base rather than a demand shock. The rate reflects two offsetting forces: replacement demand in North America and Europe, where fleets are old enough to need renewal but where aircraft are expensive and utilisation is already high, and volume growth in Asia-Pacific, where new operators are entering rather than replacing.
The segment mix is likely to shift slowly. Helicopters should retain the largest product share because offshore, medical and utility missions are not easily substituted, but business jets and turboprops are expected to capture a rising share of value as corporate demand grows in Asia-Pacific and the Gulf. Electric and hybrid aircraft will add volume in training and short-haul categories, though the base case treats them as incremental rather than transformative before 2030, since certification timelines remain the principal uncertainty.
Regionally, North America is expected to remain the largest market throughout the period, with growth driven by fleet replacement, avionics upgrades and airport modernisation rather than fleet expansion. Europe should grow in line with the global average, constrained by regulation and lifted by sustainable fuel and electric training adoption. Asia-Pacific is expected to grow faster than the global rate, with China, India, Indonesia and Australia contributing most of the increment. Risks to this path are concentrated in fuel and financing costs, pilot availability and the pace of certification for new aircraft types.
Opportunities for Stakeholders
- Original equipment manufacturers: The clearest volume opportunity sits in Asia-Pacific first-time buyers and in North American replacement demand, where a 2.83% CAGR still implies steady order books for turboprops, light jets and helicopters.
- Avionics and electronics suppliers: Rising content per aircraft, visible in the Honeywell and Bombardier agreement, means retrofit and upgrade programmes can generate revenue without new airframe sales.
- Flight training organisations: Pilot shortages across all three regions create durable demand for training aircraft, simulators and instructor capacity, and the segment is the natural entry point for electric aircraft.
- Airport and vertiport developers: Public funding programmes and urban air mobility planning create bankable projects in runway rehabilitation, hangar construction, charging infrastructure and ground access.
- Maintenance, repair and overhaul providers: An ageing fleet in North America and Europe supports component overhaul, predictive maintenance and digital records services, with capacity gaps in Asia-Pacific offering expansion room.
- Fuel and energy suppliers: Sustainable aviation fuel mandates in Europe and voluntary corporate targets in North America create a supply opportunity, particularly for producers able to serve regional airfields rather than only major hubs.
- Financiers and lessors: Leasing and fractional ownership structures lower entry barriers in price-sensitive markets, and pre-owned aircraft financing remains underserved in Latin America and parts of Asia-Pacific.
- Software and data providers: Cloud platforms for scheduling, compliance and maintenance tracking suit the small operator base that dominates general aviation and can be sold across regions without physical infrastructure.
Where Demand Holds and Where It Grows
The answer to the comparison is not a single winner. North America holds the deepest and most durable demand, built on more than five thousand regional airports, a large owner-flown fleet and a regulatory environment that treats private flying as normal economic activity. Europe holds steady demand with higher operating costs and a stronger sustainability mandate, which makes it the most likely early market for electric training aircraft and sustainable fuel uptake. Asia-Pacific holds the growth, with first-time buyers, new airports and expanding corporate sectors producing rates above the global average even if absolute volumes remain smaller.
The practical implication is that strategy should follow the map. Manufacturers need North America for volume stability, Europe for regulatory credibility and technology validation, and Asia-Pacific for growth and for establishing support networks before demand peaks. Investors should treat infrastructure, training and aftermarket services as the lower-risk exposure, since they benefit from fleet growth regardless of which airframe wins. With the market moving from USD 28.4 Billion in 2026 to USD 35.5 Billion by 2034, the returns will come from positioning in the right region and the right layer of the value chain rather than from waiting for a step change in global demand.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Recent border tensions, an escalating regional security environment, and a decisive set of policy reforms have converged to put the India defense sector squarely in front of global investors and OEMs.
The general aviation sector is undergoing a transformative phase shaped by technological advancements, evolving travel preferences, and new mobility solutions that bridge gaps in regional connectivity. Across business travel, emergency services, leisure flying, cargo movement, and emerging electrified aircraft applications, the industry is expanding its influence and redefining how people and goods move across short and mid-range distances.
The global anti-drone market has emerged as one of the fastest-growing segments within the defense and security industry, driven by escalating concerns over unauthorized drone activities threatening critical infrastructure, military installations, and civilian safety. As unmanned aerial systems (UAS) proliferate across commercial and recreational sectors, the parallel demand for sophisticated Counter-UAS (C-UAS) solutions has intensified dramatically.
A drone, otherwise known as an Unmanned Aerial Vehicle, is a type of aircraft that is flown without the presence of a human pilot on board and can either be remotely controlled or autonomously flown based on predetermined flight paths and onboard sensors. Drones are crafted from lightweight materials such as carbon fiber composites and aluminum to ensure flying efficiency and better battery life. The individual components comprising a drone include a propulsion system, power source, flight control system, sensors, and communication module.
The global drones market is going through a profound change, fueled mainly by the incorporation of artificial intelligence (AI). Drones are no longer confined to remotely controlled operations, they are becoming autonomous platforms that can learn, improve, and make decisions based on data in real time.
In the dynamic landscape of technological innovation, Japan is rapidly emerging as a global frontrunner in drone technology, primarily due to the transformative integration of artificial intelligence (AI).
The Indian space sector, led by the Indian Space Research Organisation (ISRO), plays a pivotal role in various aspects of the country's economy and technological advancement. According to ISRO’s report, India's space industry is experiencing significant growth and development, with its share in the global space economy standing at 2-3% and expected to increase to 8-10% in the coming years.
A remote sensing satellite is an artificial satellite designed to observe Earth from orbit and collect information about its surface, atmosphere, and oceans. Equipped with various sensors and devices, these satellites capture images and data from space in different parts of the electromagnetic spectrum, including visible light, infrared, and microwave wavelengths. They find applications in a wide range of fields, such as earth observation, environmental monitoring, mapping and navigation, meteorology, cartography, mineral resource exploration, insurance, defence, and security, along with flood and drought monitoring, soil moisture assessment, vegetation analysis, deforestation tracking, forest fire detection, and carbon storage.