
Saudi Arabia Dairy Enzymes Market Size, Share, Trends and Forecast by Type, Source, Application, and Region, 2026-2034
Saudi Arabia Dairy Enzymes Market Size, Share, Trends & Forecast (2026-2034)
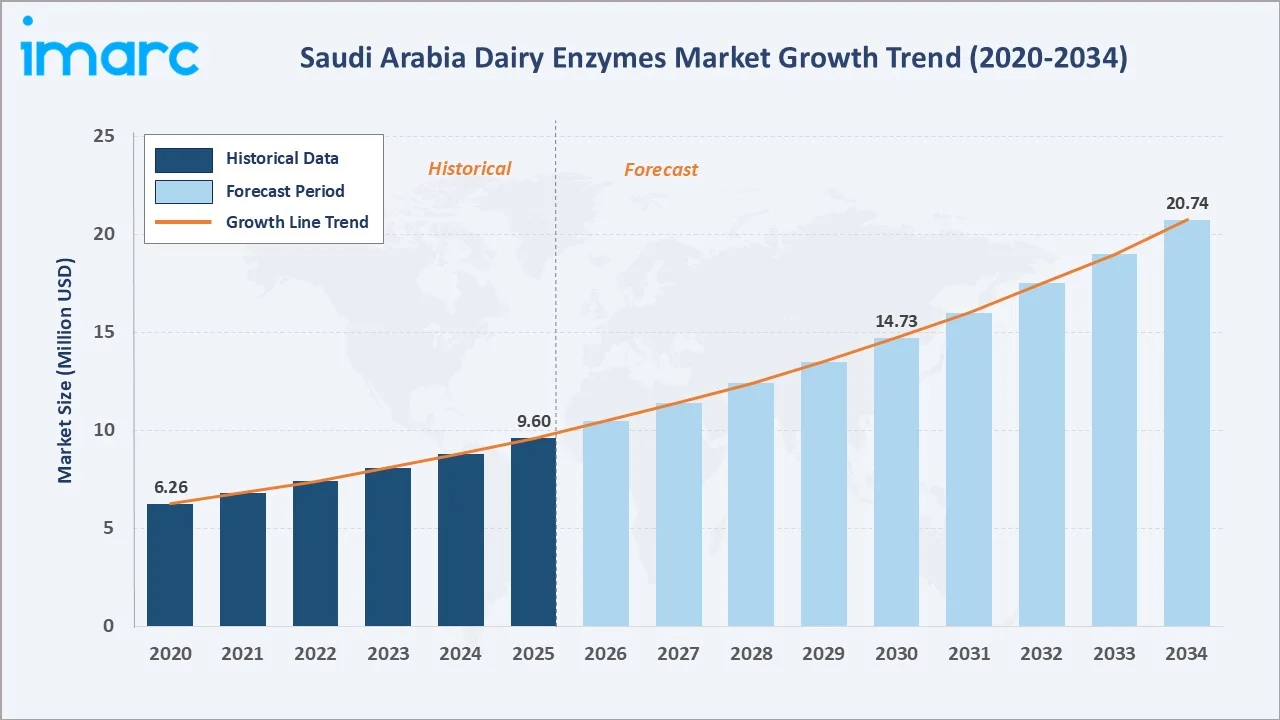
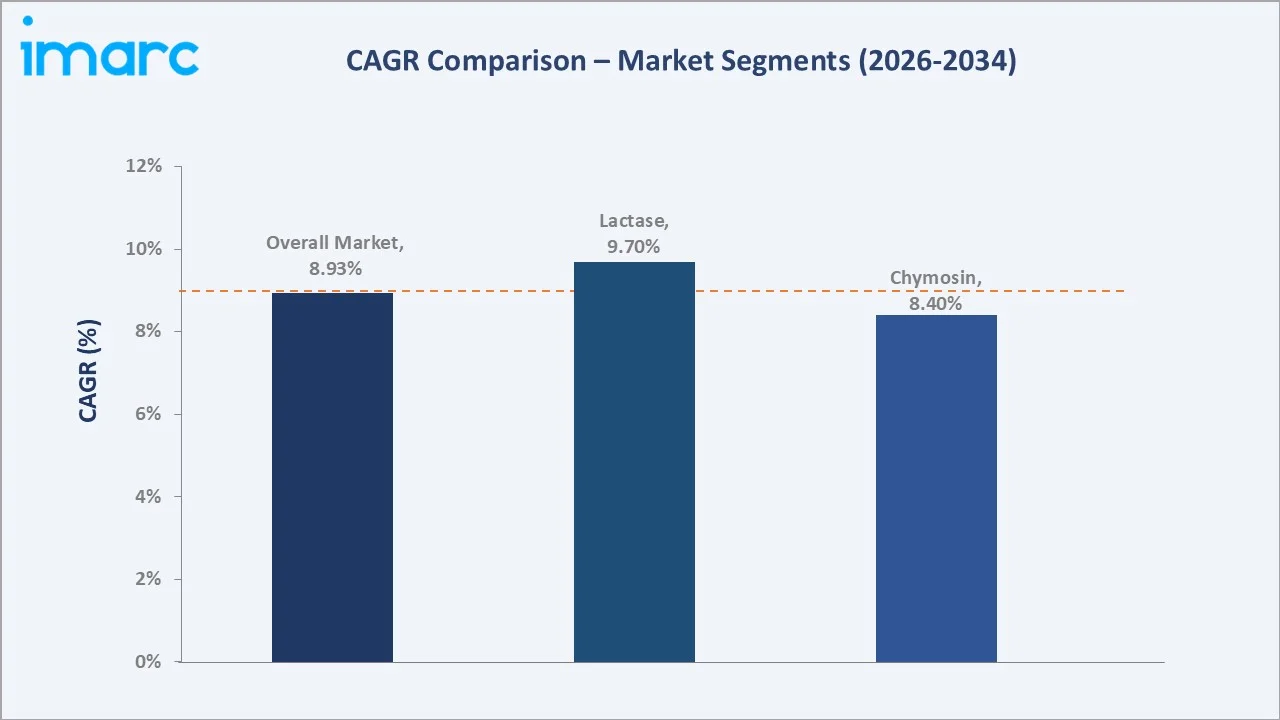
The Saudi Arabia dairy enzymes market reached USD 9.60 Million in 2025 and is projected to reach USD 20.74 Million by 2034, expanding at a CAGR of 8.93% during 2026-2034. Advancements in enzyme production technologies, including genetic engineering and fermentation processes, coupled with rising lactose intolerance awareness and growing consumer demand for enzyme-enhanced dairy products, are the primary growth catalysts.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 9.60 Million |
|
Forecast Market Size (2034) |
USD 20.74 Million |
|
CAGR (2026-2034) |
8.93% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
Northern and Central Region leads the national dairy enzymes landscape, holding a 40.9% share in 2025, anchored by the region's concentration of dairy processing facilities and urban consumption centers. Chymosin commands the largest share of the type segment at 36.7%, reflecting sustained demand for cheese and milk coagulation applications across the domestic dairy processing ecosystem.
To get more information on this market, Request Sample
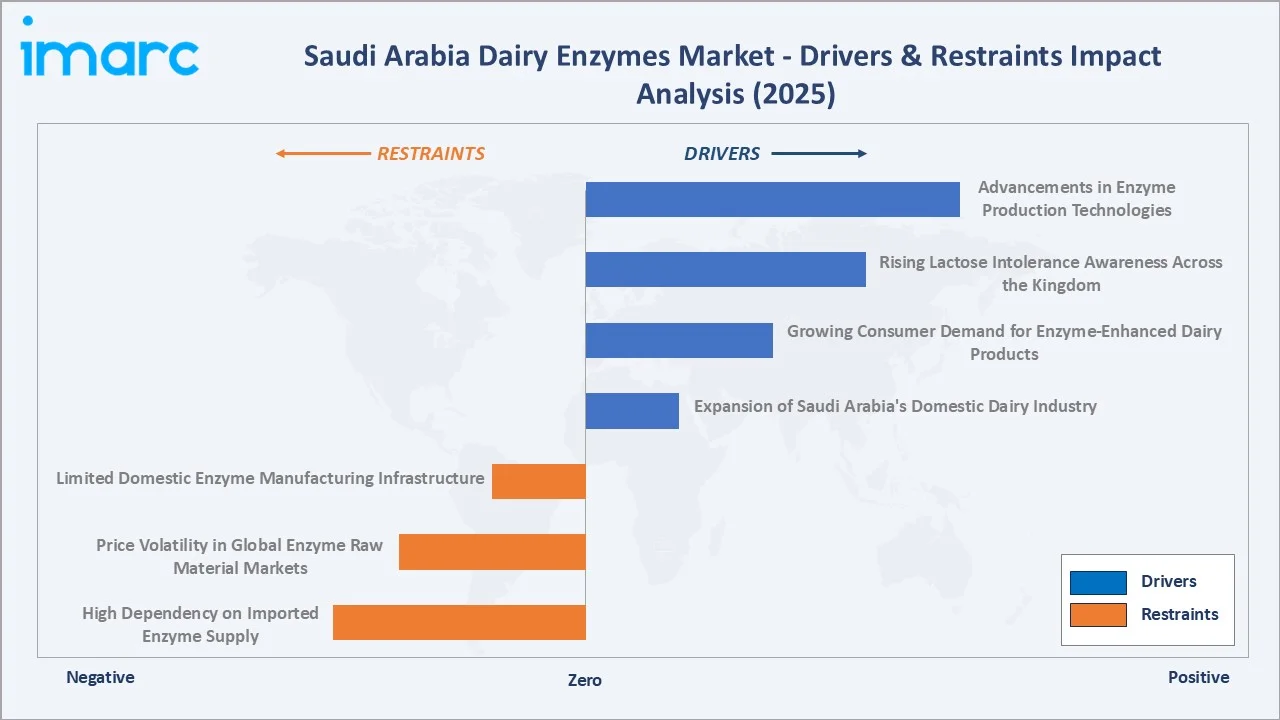
The Saudi Arabia dairy enzymes market is underpinned by three structural forces: advancements in enzyme production technologies including genetic engineering and fermentation processes, rising lactose intolerance awareness, and growing consumer demand for enzyme-enhanced dairy products. Each force independently reinforces category growth, sustaining steady CAGR expansion through 2034 despite high dependency on imported enzyme supply.
Executive Summary
The Saudi Arabia dairy enzymes market is experiencing steady expansion, driven by rising enzyme production technology advancements, growing lactose intolerance awareness, and increasing consumer demand for enzyme-enhanced dairy products. The market was valued at USD 9.60 Million in 2025 and is forecast to reach USD 20.74 Million by 2034, growing at a CAGR of 8.93%.
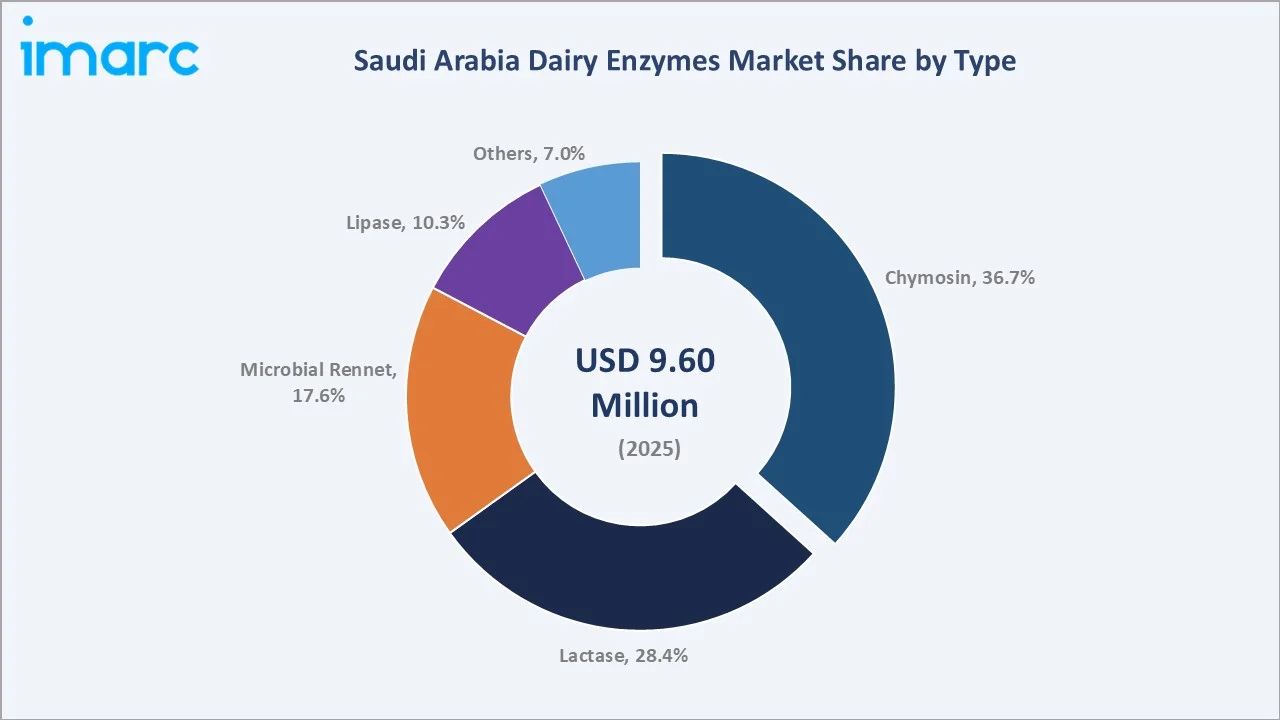
Chymosin dominates the type segment with a 36.7% share in 2025, encompassing milk coagulation applications for cheese production, while lactase accounts for 28.4%, microbial rennet for 17.6%, lipase for 10.3%, and others for 7.0%, reflecting the market's broad application diversity across dairy processing streams.
Microorganisms lead the source segment at 67.8% share, supported by fermentation-based production scalability, followed by plant and animal-derived enzymes at 32.2%. Northern and Central Region leads regionally at 40.9%, anchored by the region's concentration of dairy processing facilities and urban consumption centers.
Key Market Insights
|
Insight |
Data |
|
Largest Type Segment |
Chymosin – 36.7% share (2025) |
|
Fastest Growing Type Segment |
Lactase – ~9.7% CAGR (2026-2034) |
|
Largest Source Segment |
Microorganisms – 67.8% share (2025) |
|
Leading Region |
Northern and Central Region – 40.9% share (2025) |
|
Top Companies |
DSM-Firmenich AG, Novonesis Group, Kerry Group P.L.C., Amano Enzyme Inc., Advanced Enzyme Technologies Limited |
Key Analytical Observations Supporting The Above Data:
- Chymosin accounts for 36.7% of the Saudi Arabia dairy enzymes market in 2025. This dominance reflects sustained demand for cheese and milk coagulation applications across the domestic dairy processing ecosystem.
- Microorganisms remain the leading source category at 67.8% share (2025), supported by fermentation-based production scalability and consistent enzyme quality.
- Lactase is expanding steadily at 28.4% share (2025), as growing lactose intolerance awareness continues to drive category growth.
- Northern and Central Region's 40.9% share (2025) reflects its concentration of dairy processing facilities and urban consumption centers.
- Rising convergence of dairy enzymes with clean-label formulation and genetic engineering-based production is broadening the addressable market across cheese, yogurt, and infant formula applications.
Saudi Arabia Dairy Enzymes Market Overview
The Saudi Arabia dairy enzymes market encompasses chymosin, lactase, microbial rennet, lipase, and other enzyme categories delivered through microorganism and plant/animal-derived sources, offering functional enzyme solutions for a wide range of dairy processing applications. The dairy enzymes ecosystem spans raw material sourcing providers, fermentation and extraction facilities, and an expanding network of distribution and import partnership providers.
Macroeconomic drivers include advancements in enzyme production technologies, including genetic engineering and fermentation processes, rising lactose intolerance awareness, and growing consumer demand for enzyme-enhanced dairy products. Suppliers are simultaneously investing in clean-label product formulation, domestic dairy industry expansion partnerships, and advanced genetic engineering-based production technology to improve enzyme quality and consistency, positioning the Saudi Arabia dairy enzymes sector for continued steady growth through 2034 despite high dependency on imported enzyme supply.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
- Advancements in Enzyme Production Technologies: Growing adoption of genetic engineering and fermentation-based production processes is driving improved enzyme purity, consistency, and cost efficiency.
- Rising Lactose Intolerance Awareness Across the Kingdom: Growing consumer awareness of lactose intolerance is accelerating demand for lactase-treated and enzyme-processed dairy products. A study involving 2,150 adult participants found that the average score for correctly answering questions related to lactose intolerance awareness was 28.9% (±21.9), indicating growing knowledge among respondents.
- Growing Consumer Demand for Enzyme-Enhanced Dairy Products: Rising preference for functional dairy products with improved digestibility and flavor is broadening the addressable market for dairy enzyme applications.
- Expansion of Saudi Arabia's Domestic Dairy Industry: Growing domestic dairy processing capacity is increasing demand for chymosin, rennet, and lipase enzymes across cheese and dairy product manufacturing. For instance, in April 2026, Saudi Arabia launched a 1 million sq. m dairy industrial cluster in Al-Kharj to strengthen dairy manufacturing capabilities, attract investment, and support food security goals under the National Industrial Strategy.
Market Restraints
- High Dependency on Imported Enzyme Supply: Persistent reliance on imported enzyme products can constrain supply consistency and increase exposure to international price fluctuations.
- Price Volatility in Global Enzyme Raw Material Markets: Fluctuating global raw material prices can complicate cost forecasting and margin management for dairy processors.
- Limited Domestic Enzyme Manufacturing Infrastructure: Insufficient domestic enzyme production capacity can constrain local supply chain resilience and increase import dependency.
Market Opportunities
- Clean-Label Product Formulation Expansion: Consumer research indicates that Saudi consumers are increasingly preferring natural, minimally processed, and clean-label products. Growing consumer demand for natural and clean-label dairy products presents opportunities for suppliers offering enzyme-based natural processing solutions.
- Genetic Engineering-Based Production Technology Adoption: Rising demand for improved enzyme purity and cost efficiency offers opportunities for suppliers investing in advanced genetic engineering production technology.
- Domestic Enzyme Manufacturing Investment: Growing interest in reducing import dependency creates opportunities for suppliers investing in domestic enzyme production and processing capabilities.
Market Challenges
- Balancing Import Reliance and Supply Consistency: Suppliers must balance import dependency with the need to maintain consistent, cost-competitive enzyme supply for dairy processors.
- Addressing Domestic Production Scale-Up: Ensuring consistent, high-quality domestic enzyme production capacity requires ongoing infrastructure investment and technology transfer.
Emerging Market Trends
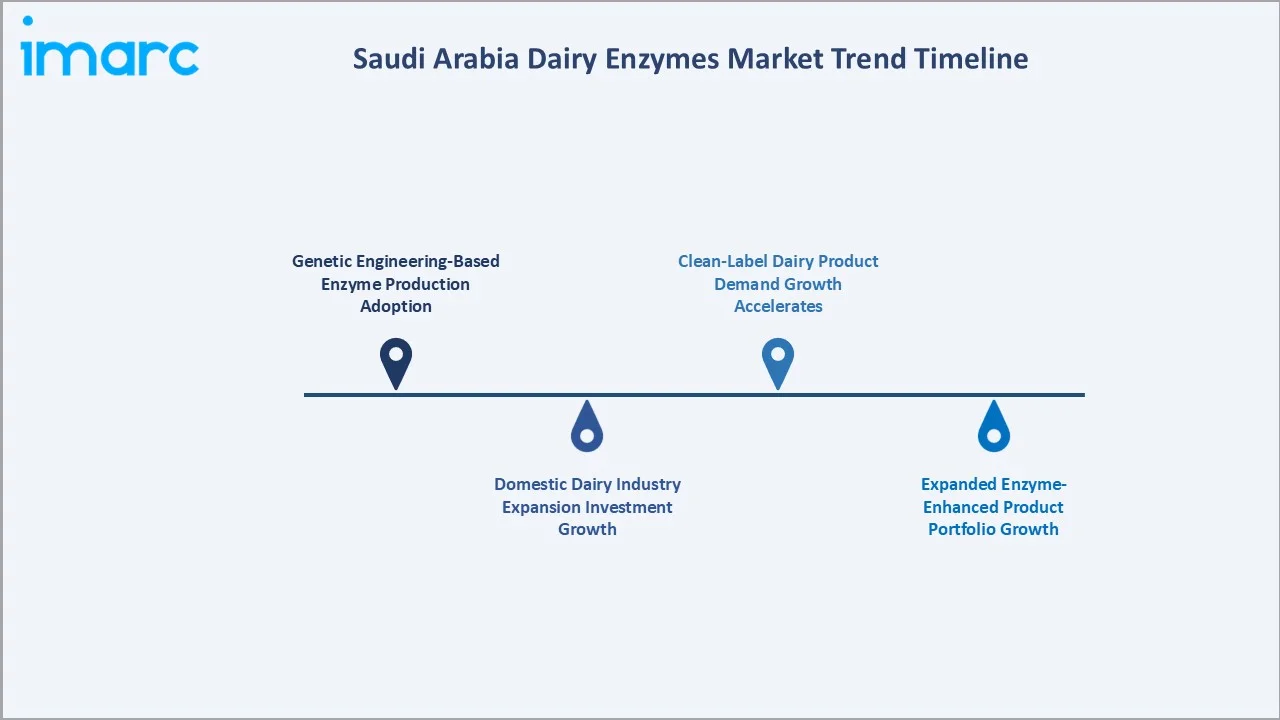
1. Genetic Engineering-Based Enzyme Production Adoption
In July 2025, Saudi Arabia’s National Livestock and Fisheries Development Program (NLFDP) announced plans to enhance cow milk production through genetic improvement and biotechnology initiatives aimed at increasing productivity and strengthening dairy self-sufficiency. The program’s genetic testing can reduce genetically linked and production-related diseases by up to 60%, while improving milk quality, safety, and overall dairy sector competitiveness.
2. Domestic Dairy Industry Expansion Investment Growth
Growing investment in Saudi Arabia's domestic dairy industry is expanding processing capacity and driving increased demand for chymosin, lactase, and lipase enzyme applications. In March 2024, Saudi Arabia’s Almarai announced a SAR 18 billion (USD 4.8 billion) investment plan through 2028 to expand operations, strengthen supply chain capabilities, and support growth across dairy, poultry, and food product categories.
3. Clean-Label Dairy Product Demand Growth Accelerates
Rising consumer preference for natural and clean-label dairy products is accelerating adoption of enzyme-based natural processing solutions across cheese, yogurt, and milk applications. Growing consumer scrutiny of ingredient lists is further encouraging domestic dairy processors to replace synthetic additives with enzyme-based alternatives.
4. Expanded Enzyme-Enhanced Product Portfolio Growth
Growing consumer demand for functional dairy products is driving expansion of enzyme-enhanced product portfolios across the domestic dairy manufacturing ecosystem. Rising interest in lactose-free and digestion-friendly dairy options is further encouraging manufacturers to broaden their enzyme-processed product ranges.
Industry Value Chain Analysis
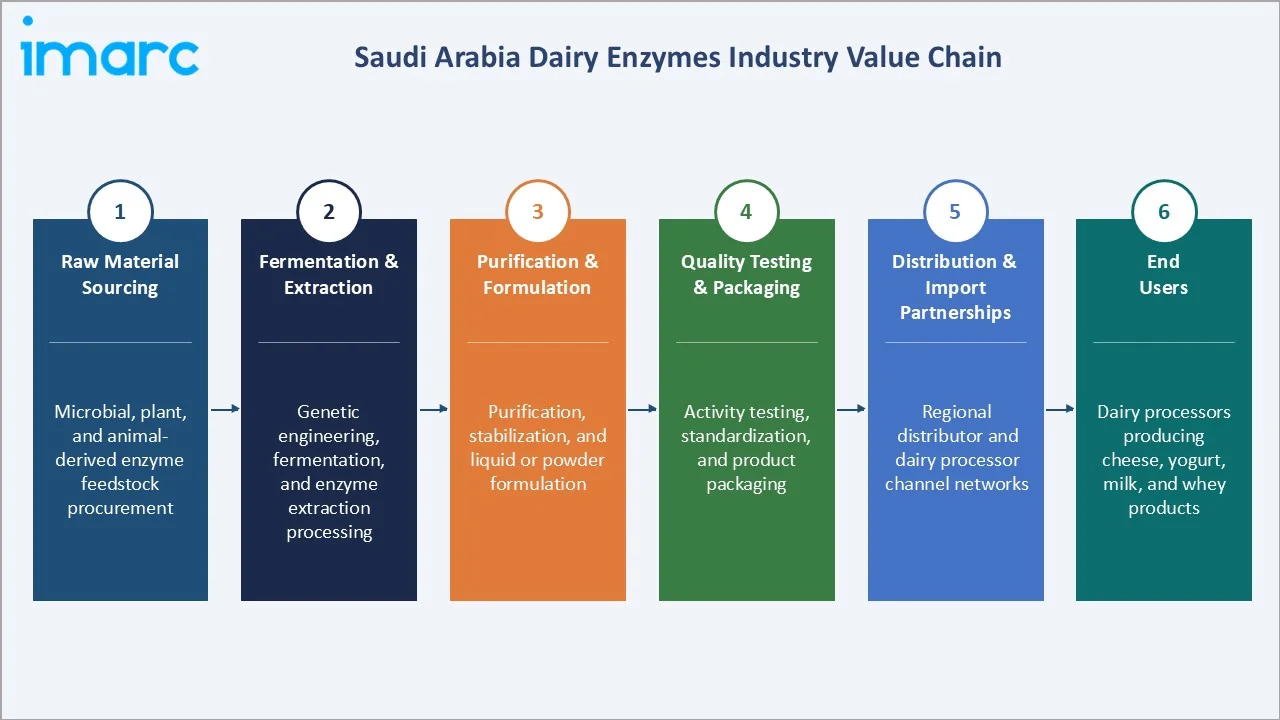
The Saudi Arabia dairy enzymes value chain spans raw material sourcing through end-user delivery, with each stage occupied by specialized fermentation providers, purification and formulation facilities, and distribution and import partnership providers whose performance directly influences enzyme purity, activity consistency, and cost-effectiveness.
|
Stage |
Key Activities |
|
Raw Material Sourcing |
Microbial, plant, and animal-derived enzyme feedstock procurement |
|
Fermentation & Extraction |
Genetic engineering, fermentation, and enzyme extraction processing |
|
Purification & Formulation |
Purification, stabilization, and liquid or powder formulation |
|
Quality Testing & Packaging |
Activity testing, standardization, and product packaging |
|
Distribution & Import Partnerships |
Regional distributor and dairy processor channel networks |
|
End Users |
Dairy processors producing cheese, yogurt, milk, and whey products |
Technology Landscape in the Saudi Arabia Dairy Enzymes Industry
Advanced Fermentation Technology
Suppliers are advancing fermentation technology to improve enzyme purity and production scalability, supporting broader adoption among cheese and dairy processing applications. Enhanced microbial strain optimization is further improving yield efficiency and reducing production batch variability.
Genetic Engineering Production Development
Growing investment in genetic engineering-based production technology is expanding enzyme consistency and cost efficiency, addressing rising demand for reliable, high-purity dairy enzymes. Increasing use of recombinant DNA techniques is further enabling precise control over enzyme activity and thermal stability profiles.
Clean-Label Formulation Innovation
Suppliers are engineering advanced clean-label enzyme formulations to extend product suitability across demanding natural and organic dairy processing applications. Growing emphasis on non-GMO and additive-free enzyme sourcing is further aligning products with evolving Halal and clean-label certification standards.
Import & Distribution Ecosystem Integration
Expanding investment in import and distribution ecosystem integration is strengthening dairy enzyme value chain reliability, supporting premium positioning across leading national dairy processing programs. Improved cold-chain logistics and local warehousing partnerships are further ensuring enzyme stability and timely supply to domestic processors.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Chymosin |
36.7% |
2025 |
|
Source |
Microorganisms |
67.8% |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
Region |
Northern and Central Region |
40.9% |
2025 |

By Type
Chymosin dominates with a 36.7% share in 2025. This segment encompasses milk coagulation applications for cheese production, supported by sustained demand across the national dairy processing ecosystem.
To access detailed market analysis, Request Sample
Lactase represents 28.4% of the market (2025), followed by microbial rennet at 17.6%, lipase at 10.3%, and others at 7.0%, reflecting the market's broad application diversity across dairy processing streams.
By Source
Microorganisms lead the source segment at a 67.8% share (2025), supported by fermentation-based production scalability and consistent enzyme quality across the domestic dairy processing ecosystem.
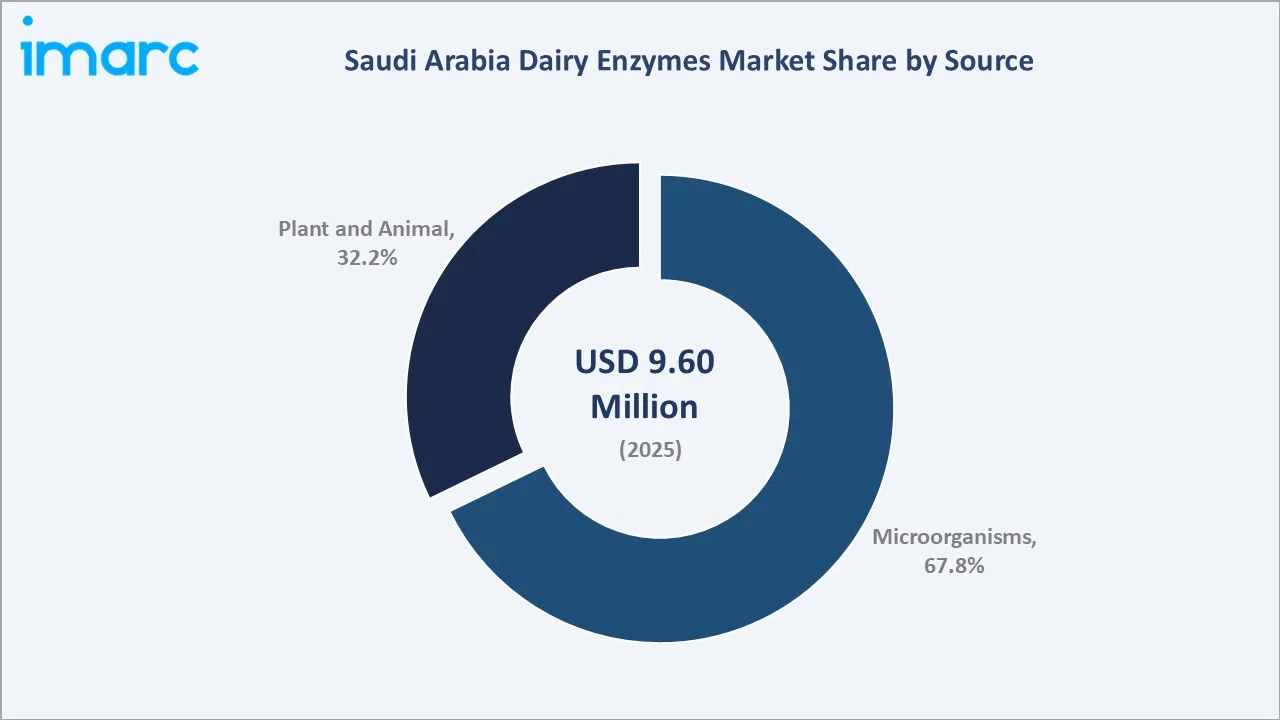
Plant and animal-derived enzymes account for 32.2% of the market (2025), continuing to broaden the market's source diversity as demand for traditional and specialty enzyme processing methods persists.
Regional Market Insights
Northern and Central Region's market leadership (40.9%, 2025) reflects the region's concentration of dairy processing facilities and urban consumption centers. Growing domestic dairy industry expansion and expanding clean-label product formulation investment combine to sustain its dominant position through 2034.
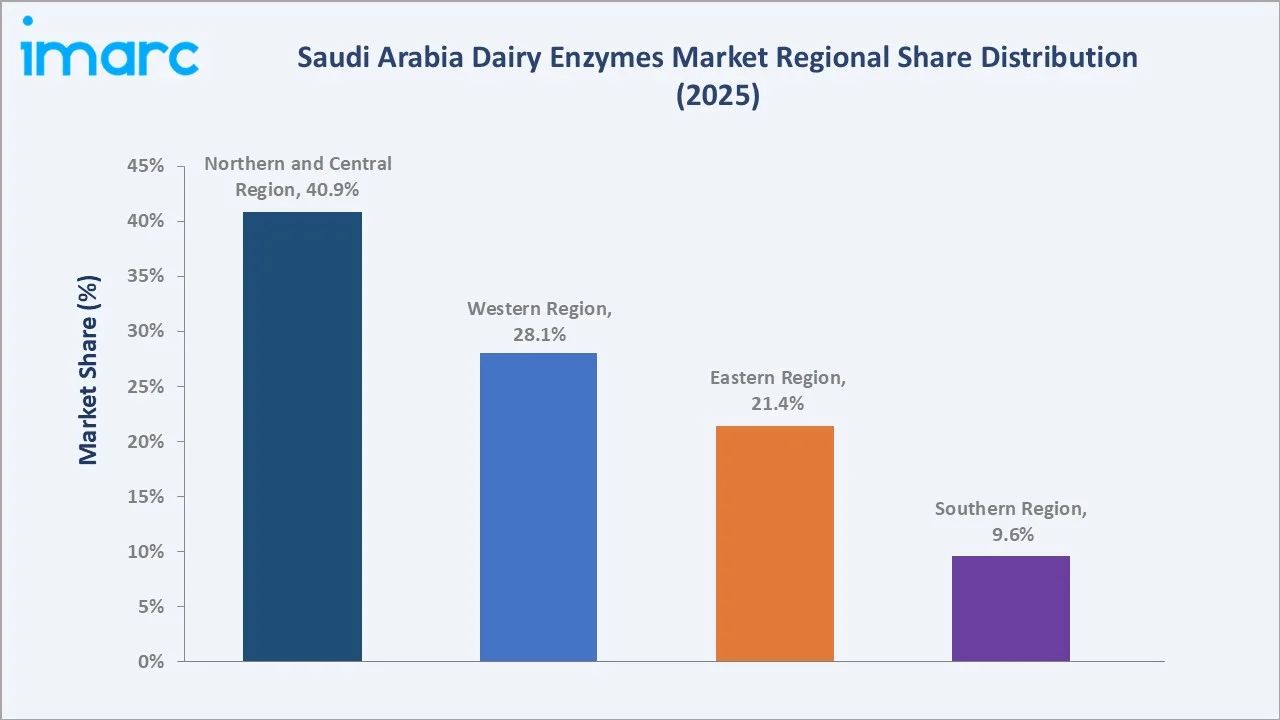
Western Region at 28.1% represents the second-largest Saudi Arabia dairy enzymes market regionally. Growing port-based import infrastructure and expanding retail dairy distribution are sustaining steady growth, positioning the region as a key contributor alongside Northern and Central Region through the forecast period.
|
Region |
Share (2025) |
Key Growth Drivers |
|
Northern and Central Region |
40.9% |
Concentration of dairy processing facilities and urban consumption centers |
|
Western Region |
28.1% |
Growing port-based import infrastructure and expanding retail dairy distribution |
|
Eastern Region |
21.4% |
Established industrial base and rising dairy processing capacity investment |
|
Southern Region |
9.6% |
Emerging dairy consumption growth and gradual distribution network expansion |
Competitive Landscape
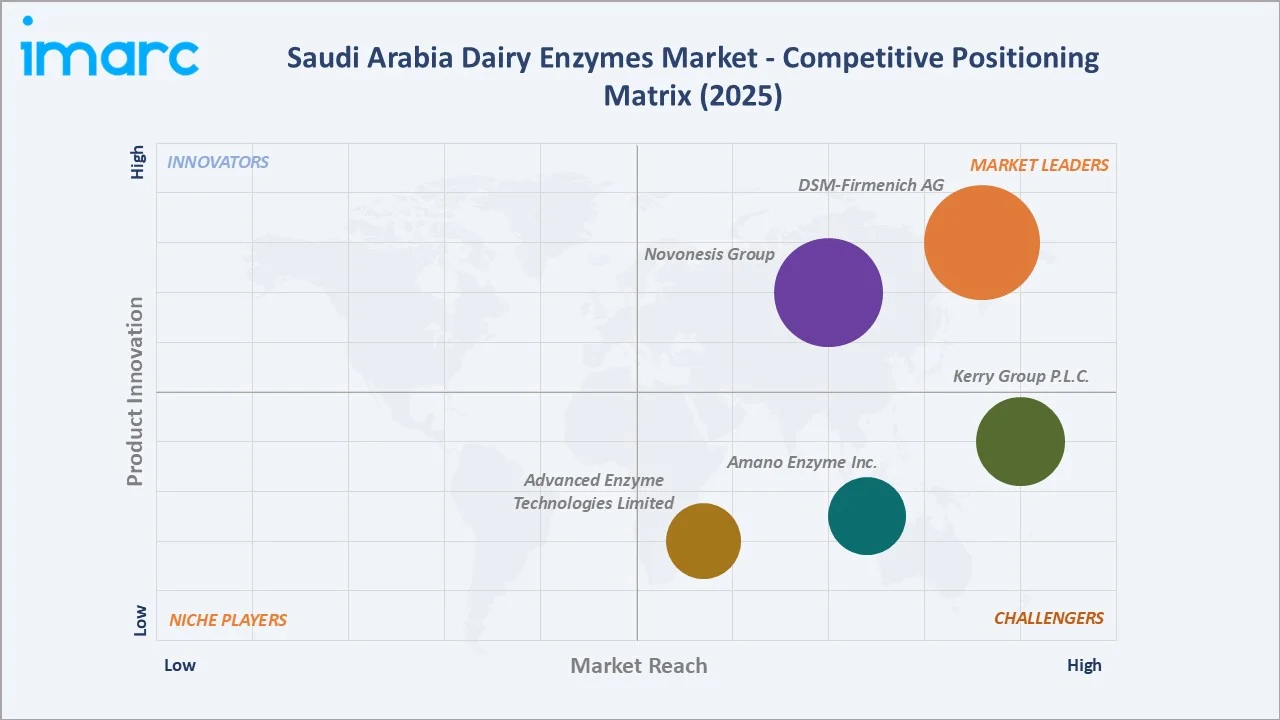
The Saudi Arabia dairy enzymes market exhibits moderate concentration, with leading suppliers collectively holding a significant share of market revenue in 2025, reflecting sustained investment in production innovation and supply chain reach.
|
Company Name |
Brand/Sub-Brand Name |
Market Position |
Core Strength |
|
DSM-Firmenich AG |
Delvo, Tolerase, Maxiren, Purifine, among others |
Market Leader |
One of the leading global enzyme manufacturers with extensive dairy processing solution integration |
|
Novonesis Group |
Galaya, YieldMax, Chy-Max, Saphera |
Market Leader |
Global biotechnology enzyme manufacturer with broad international distribution reach |
|
Kerry Group P.L.C. |
NOLA, Ha-Lactase |
Strong Challenger |
Diversified food ingredients manufacturer with global dairy enzyme distribution capabilities |
|
Amano Enzyme Inc. |
Amano Enzyme, CheeseMax |
Challenger |
Asia-based enzyme specialist with advanced fermentation and formulation portfolio |
|
Advanced Enzyme Technologies Limited |
SEBCheese Pro, Hydrolact W, FlavourSEB NP, FirmSEB PME 1000L |
Challenger |
International enzyme manufacturer with expanding global export capabilities |
DSM-Firmenich AG and Novonesis Group dominate through comprehensive product portfolios and extensive global distribution reach, supported by continuous investment. Kerry Group P.L.C., Amano Enzyme Inc., and Advanced Enzyme Technologies Limited compete through targeted dairy culture heritage, diversified ingredient integration, and specialized fermentation differentiation, respectively.
Key Company Profiles
DSM-Firmenich AG
DSM-Firmenich AG is one of the leading global enzyme manufacturers with extensive dairy processing solution integration serving processors across international markets.
- Product Portfolio: Chymosin, lactase, and specialty dairy enzyme solutions under Delvo, Tolerase, Maxiren, Purifine, among other brands.
- Recent Developments: In July 2026, DSM-Firmenich AG reported first-half 2026 sales of EUR 4.66 billion (USD 5.33 billion), up 5% like-for-like (LFL). The Taste, Texture & Health division recorded EUR 1.63 billion (USD 1.87 billion) in H1 sales, up 4% LFL, while Q2 sales grew 6% LFL to EUR 843 million, driven by demand for innovative food, nutrition, and health ingredient solutions.
- Strategic Focus: Strengthening global distribution reach; expanding clean-label enzyme technology across emerging application segments.
Novonesis Group
Novonesis Group is one of the leading global biotechnology enzyme manufacturers with broad international distribution reach across diverse dairy processing markets.
- Product Portfolio: Microbial rennet, lipase, and fermentation-based dairy enzyme products under the Galaya, YieldMax, Saphera and Chy-Max brands.
- Recent Developments: In February 2024, Novozymes and Chr. Hansen completed their merger to form Novonesis Group, a global biosolutions company with estimated annual revenue of EUR 3.7 billion (~USD 4 billion) and operations spanning more than 30 industries, including dairy enzymes.
- Strategic Focus: Scaling global distribution reach; deepening dairy processor partnership development.
Market Concentration Analysis
The Saudi Arabia dairy enzymes market exhibits moderate concentration, with DSM-Firmenich AG and Novonesis Group collectively accounting for a significant share of total category revenue in 2025, reflecting sustained production investment, supply chain loyalty, and extensive application reach across the industry.
Consolidation pressure remains limited as leading suppliers maintain distinct strategic positioning: DSM-Firmenich AG and Novonesis Group through comprehensive product and distribution portfolios, Kerry Group P.L.C. through ingredient integration scale positioning, and Amano Enzyme Inc. and Advanced Enzyme Technologies Limited through diversified specialized fermentation and export differentiation, rather than pursuing direct M&A consolidation.
Investment & Growth Opportunities
Fastest Growing Segments
Lactase (~9.7% CAGR) represents the highest-growth investment vector through 2034, driven by expanding lactose intolerance awareness and continuous innovation across enzyme processing technologies. This subcategory addresses a rapidly expanding addressable market within the Saudi Arabia dairy enzymes ecosystem.
Emerging Market Expansion
The Eastern Region and Southern Region regional markets collectively represent an incremental growth opportunity beyond Northern and Central Regions and the Western Region by 2034, as rising dairy processing investment and expanding distribution network development accelerate category penetration in these emerging markets.
Venture and Institutional Investment Trends
- Supplier investment toward genetic engineering-based production infrastructure and clean-label technology is creating opportunities for technology vendors serving the dairy enzymes sector.
- Growing domestic dairy industry demand is sustaining institutional interest in specialty fermentation and processing facility providers.
- Clean-label-led dairy innovation, led by major suppliers, is opening opportunities for technology and formulation vendors serving the Saudi Arabia dairy enzymes industry.
Future Market Outlook (2026-2034)
The Saudi Arabia dairy enzymes market is positioned for steady, technology-driven expansion through 2034. From a base of USD 9.60 Million in 2025, the market is projected to reach USD 20.74 Million by 2034, representing substantial incremental value creation at a CAGR of 8.93%. This growth is structurally supported by advancements in enzyme production technologies, including genetic engineering, rising lactose intolerance awareness, and growing consumer demand for enzyme-enhanced dairy products.
The type and source segment will continue evolving through 2034, with lactase gaining further share as lactose intolerance awareness and advanced enzyme processing technology innovation accelerate. This shift creates opportunities for suppliers investing in genetic engineering-based production, clean-label formulation ecosystem expansion, and advanced fermentation capabilities to capture the next phase of the Saudi Arabia dairy enzymes market growth.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry participants across 2024-2025, including dairy enzyme supplier executives, dairy processor procurement specialists, food technology experts, and regulatory compliance advisors across major Saudi Arabian regions. Expert input validated market sizing, segmentation trends, and regional consumption patterns.
Secondary Research
Secondary research encompassed supplier annual reports, dairy industry association publications, and trade press covering production innovation, regulatory trends, and regional market dynamics across the Kingdom.
Forecasting Models
Market size estimations were derived using top-down and bottom-up forecasting, incorporating type and source segment transitions and supplier production capacity disclosures. A base-case CAGR of 8.93% reflects consensus estimates validated against announced production investment timelines and supplier strategic development plans.
Saudi Arabia Dairy Enzymes Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Lactase, Chymosin, Microbial Rennet, Lipase, Others |
| Sources Covered | Plant and Animal, Microorganisms |
| Applications Covered | Milk, Cheese, Ice Cream and Desserts, Yogurt, Whey, Infant Formula, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | DSM-Firmenich AG, Novonesis Group, Kerry Group P.L.C., Amano Enzyme Inc., Advanced Enzyme Technologies Limited, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia dairy enzymes market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia dairy enzymes market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia dairy enzymes industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Dairy Enzymes Market Report
The Saudi Arabia dairy enzymes market reached USD 9.60 Million in 2025 and is projected to reach USD 20.74 Million by 2034.
The market is expected to grow at a CAGR of 8.93% during 2026-2034, driven by advancements in enzyme production technologies and rising lactose intolerance awareness.
Northern and Central Region leads with a 40.9% share in 2025, anchored by the region's concentration of dairy processing facilities and urban consumption centers.
Chymosin dominates with a 36.7% share in 2025, driven by sustained demand for milk coagulation applications in cheese production.
Microorganisms lead with a 67.8% share in 2025, supported by fermentation-based production scalability and consistent enzyme quality.
Some of the key players include DSM-Firmenich AG, Novonesis Group, Kerry Group P.L.C., Amano Enzyme Inc., and Advanced Enzyme Technologies Limited.
Lactase is growing fastest at an estimated 9.7% CAGR as lactose intolerance awareness accelerates.
Key challenges include high dependency on imported enzyme supply, price volatility in global enzyme raw material markets, and limited domestic enzyme manufacturing infrastructure.
Clean-label product formulation expansion, genetic engineering-based production technology adoption, and domestic enzyme manufacturing investment represent leading investment opportunities.
Plant and animal-derived enzymes, at 32.2% share, continue to reflect demand for traditional and specialty enzyme processing methods, complementing microorganism-derived enzyme demand.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade