
Saudi Arabia Paper and Paperboard Packaging Market Size, Share, Trends and Forecast by Type, End User, and Region, 2026-2034
Saudi Arabia Paper and Paperboard Packaging Market Size, Share, Trends & Forecast (2026-2034)
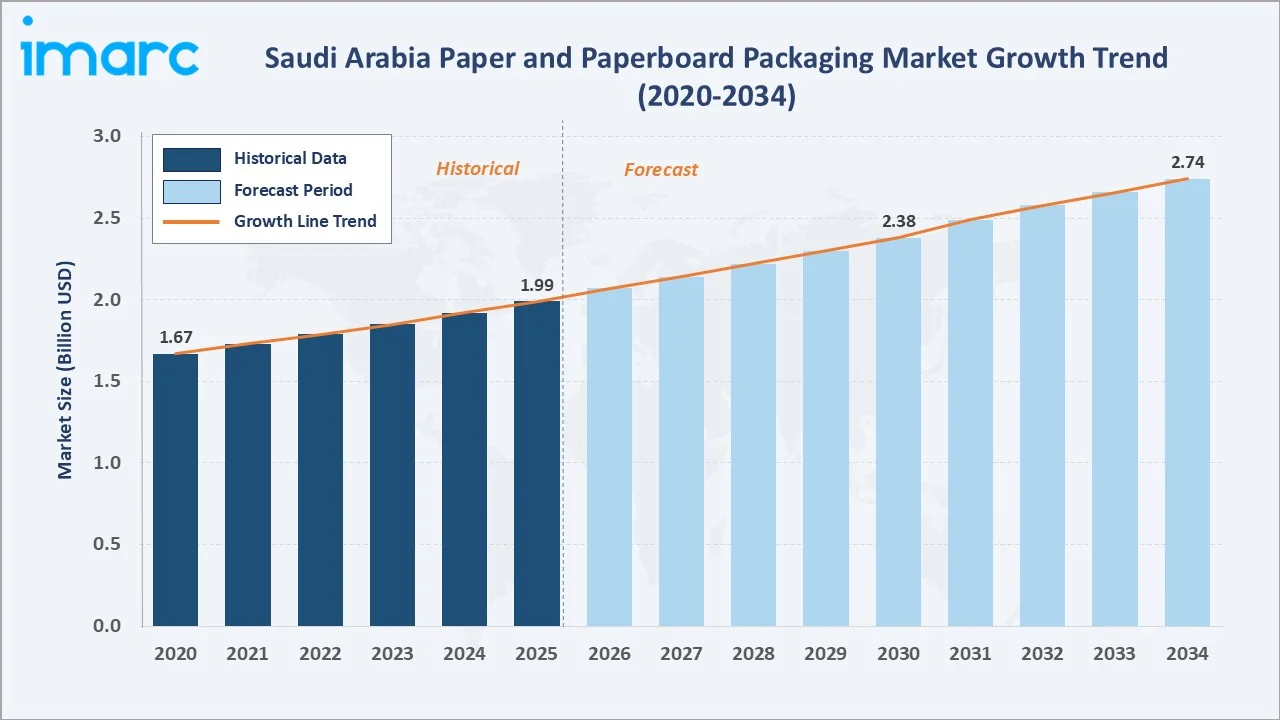
The Saudi Arabia paper and paperboard packaging market reached USD 1.99 Billion in 2025 and is projected to reach USD 2.74 Billion by 2034, growing at a CAGR of 3.61% during 2026-2034. The market is driven by the expanding e-commerce sector and rising demand for economical, recyclable packaging solutions. Corrugated boxes dominate at 58.4%. Food and beverage leads as the largest end-user segment at 42.8%. The Northern and Central Region commands 39.2% of total market share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 1.99 Billion |
|
Forecast Market Size (2034) |
USD 2.74 Billion |
|
CAGR (2026-2034) |
3.61% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Corrugated Boxes (58.4%, 2025) |
|
Dominant End User |
Food and Beverage (42.8%, 2025) |
|
Leading Region |
Northern and Central Region (39.2%, 2025) |
The Saudi Arabia paper and paperboard packaging market expanded from USD 1.67 Billion in 2020 to USD 1.99 Billion in 2025, anchored at USD 2.38 Billion in 2030, and forecast to reach USD 2.74 Billion by 2034. Vision 2030 sustainability mandates and accelerating e-commerce logistics have sustained above-trend packaging demand growth through 2022-2025.
To get more information on this market, Request Sample
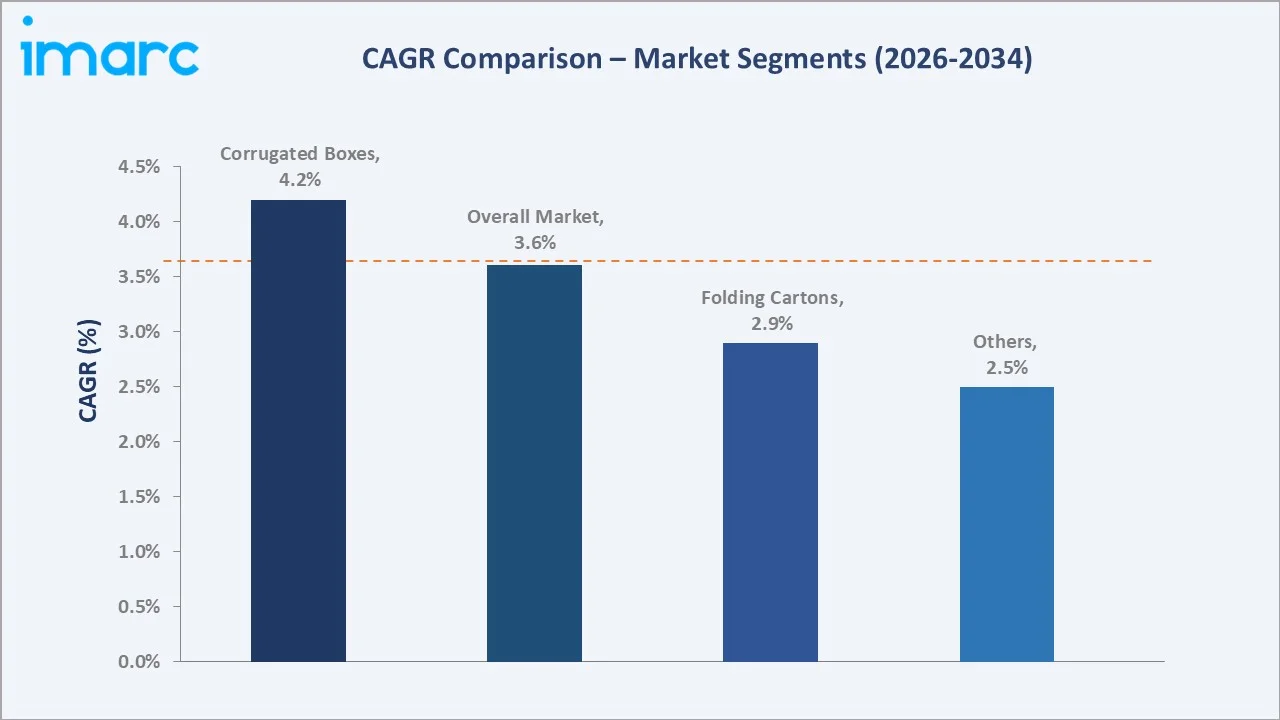
Corrugated boxes grow at ~4.2% CAGR as e-commerce packaging demand surges. Folding cartons grow at ~2.9% CAGR driven by food retail and pharmaceutical packaging. The Northern and Central Region leads regional growth at ~4.0% CAGR, underpinned by Riyadh's expanding commercial and logistics infrastructure.
Executive Summary
The Saudi Arabia paper and paperboard packaging market reached USD 1.99 Billion in 2025. The market encompasses corrugated box manufacturing, folding carton production, and specialty paper packaging, serving food and beverage, healthcare, personal care, and industrial sectors. The market is projected to reach USD 2.74 Billion by 2034 at a 3.61% CAGR during 2026-2034.
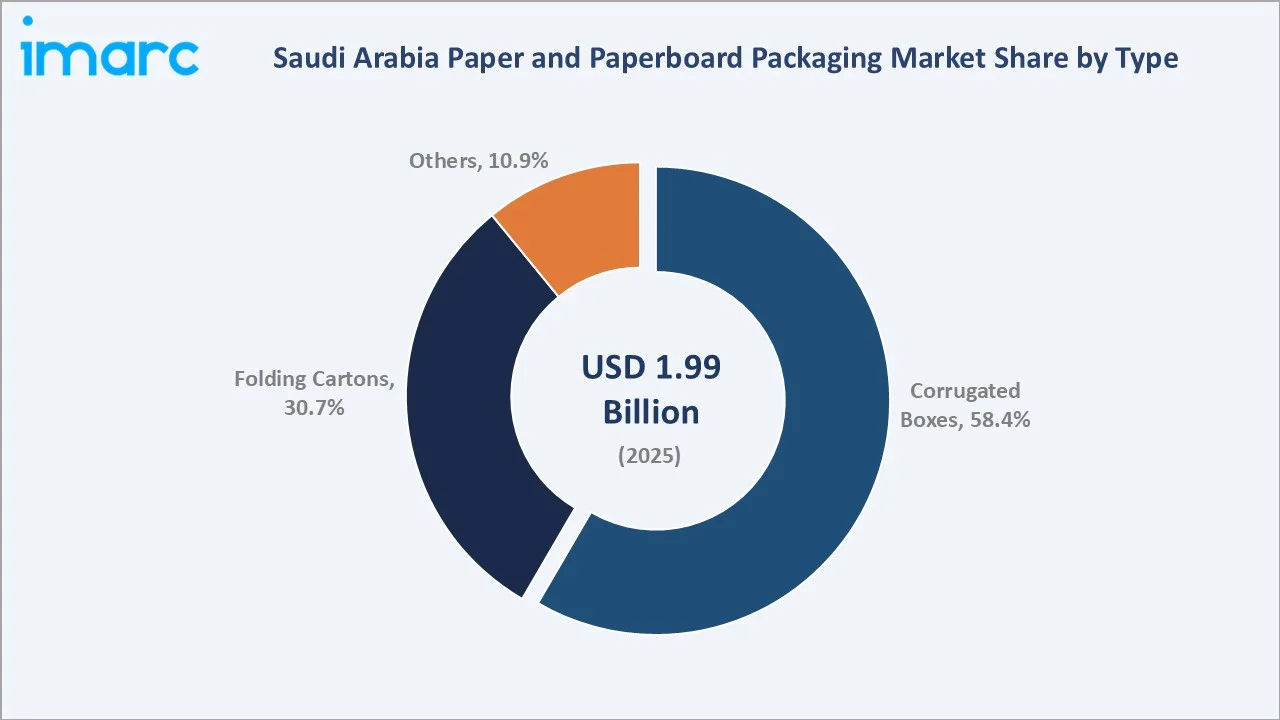
Corrugated boxes at 58.4% dominate through logistics efficiency for e-commerce and food distribution, growing at ~4.2% CAGR. Folding cartons at 30.7% lead through food retail, personal care, and pharmaceutical packaging, growing at ~2.9% CAGR. The Northern and Central Region at 39.2% leads the market.
Food and beverage at 42.8% leads end-user segments through Saudi Arabia's expanding quick-service restaurant network and modern trade channel growth. Industrial at 21.3% reflects ongoing Vision 2030 manufacturing and construction activity.
Key Market Insights
|
Insight |
Data |
|
Dominant Type (2025) |
Corrugated Boxes – 58.4% share |
|
Dominant End User (2025) |
Food and Beverage – 42.8% market share |
|
Leading Region (2025) |
Northern and Central Region – 39.2% market share |
|
Market Opportunity |
E-commerce growth; plastic-to-paper substitution; Vision 2030 packaging demand; healthcare sector expansion |
Key Analytical Observations Supporting the Above Data:
- Corrugated Boxes at 58.4% (CAGR ~4.2%): Corrugated boxes dominate due to structural durability, superior load-bearing capacity, and compatibility with high-speed automated packing lines serving Saudi Arabia's growing e-commerce and food distribution sectors.
- Food and Beverage at 42.8%: Food and beverage leads because Saudi Arabia's thriving quick-service restaurant, hypermarket, and food export sectors demand high volumes of hygienic, tamper-evident, and branded packaging solutions.
- Northern and Central Region at 39.2%: Riyadh's dense concentration of FMCG manufacturers, distribution centres, and modern retail formats drives sustained packaging consumption.
Saudi Arabia Paper and Paperboard Packaging Market Overview
The Saudi Arabia paper and paperboard packaging market encompasses the design, manufacture, conversion, and supply of fiber-based packaging materials for commercial and industrial use. The market covers corrugated boxes, folding cartons, rigid boxes, paper bags, and specialty wrapping materials used across food and beverage, healthcare, personal care, and industrial applications.
Macroeconomic factors include Vision 2030 sustainability mandates, rapid e-commerce growth, rising consumer spending on packaged goods, and Saudi Arabia's expanding pharmaceutical and healthcare manufacturing base. Government-led plastic restriction regulations are accelerating the structural shift from plastic to paper-based packaging.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
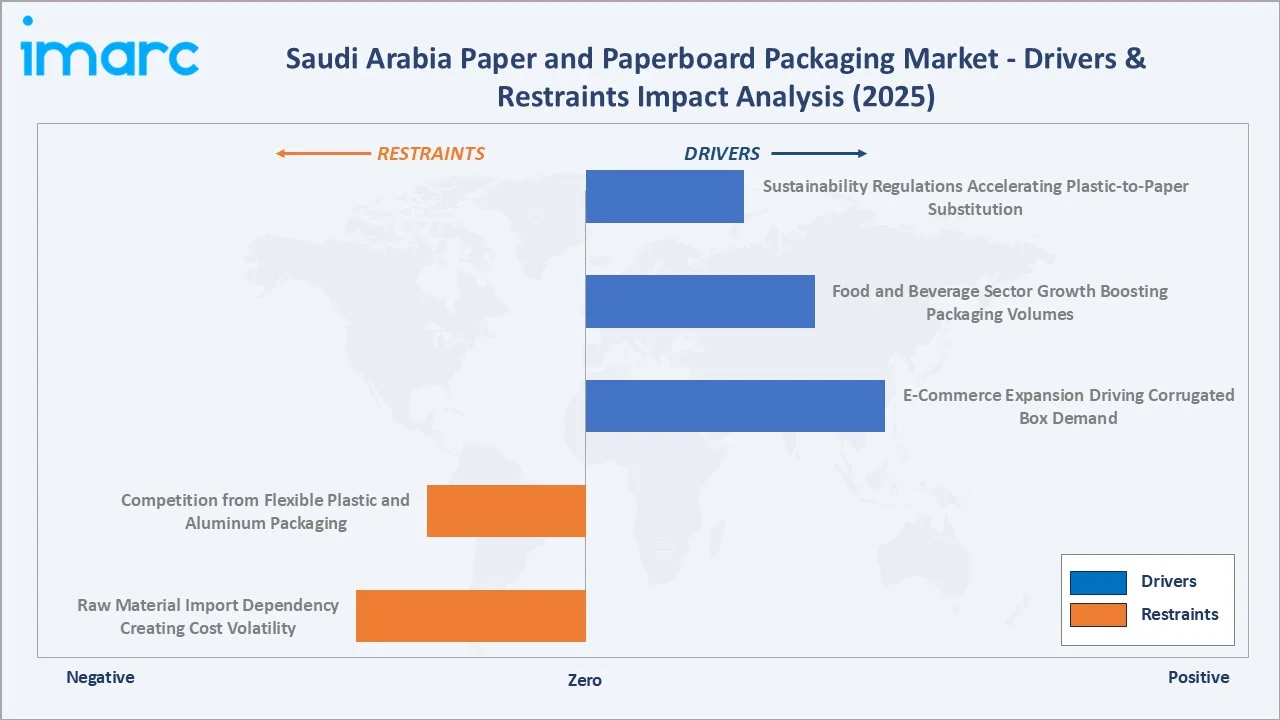
- E-Commerce Expansion Driving Corrugated Box Demand: Rapid growth of online retail in Saudi Arabia is generating sustained demand for corrugated boxes and protective packaging for last-mile delivery. Major e-commerce platforms operating in the Kingdom are scaling packaging procurement significantly, with corrugated board consumption rising across fulfilment centres in Riyadh, Jeddah, and Dammam.
- Sustainability Regulations Accelerating Plastic-to-Paper Substitution: Government mandates to restrict single-use plastics under Vision 2030 are directly driving the transition toward paper-based packaging. Saudi Arabia's National Environment Strategy and circular economy alignment are compelling brand owners and retailers to shift packaging portfolios toward recyclable paper alternatives.
- Food and Beverage Sector Growth Boosting Packaging Volumes: Rising consumer spending on packaged food and beverages, the proliferation of quick-service restaurants, and expanding modern trade formats are increasing consumption of folding cartons, corrugated distribution packaging, and specialty food-grade paperboard.
- Urbanization and Infrastructure Expansion Creating Industrial Packaging Demand: Saudi Arabia's ongoing megaproject development under Vision 2030, including NEOM, the Red Sea Project, and Diriyah Gate, is expanding the industrial and construction sectors, driving significant demand for corrugated industrial packaging for machinery, components, and building materials.
Market Restraints
- Raw Material Import Dependency Creating Cost Volatility: Saudi Arabia's limited domestic pulp and paper production capacity forces heavy reliance on imported wood pulp, virgin paperboard, and recycled fiber, exposing packaging manufacturers to global commodity price fluctuations, currency risks, and supply chain disruptions that can compress margins.
- Competition from Flexible Plastic and Aluminum Packaging: Flexible plastic and aluminum packaging continue to compete on cost-per-unit, barrier performance, and weight in food, beverage, and personal care applications, constraining paper packaging's penetration in moisture-sensitive and extended-shelf-life product categories.
- High Capital Investment Requirements Limiting Domestic Manufacturing Scale-Up: Establishing integrated paper mills and packaging converting facilities requires substantial capital expenditure in machinery, energy infrastructure, and wastewater management systems, creating barriers for new domestic entrants and limiting in-Kingdom capacity development.
Market Opportunities
- Healthcare Packaging Expansion: Saudi Arabia's pharmaceutical manufacturing scale-up under Vision 2030 health sector development programs is creating growing demand for specialist folding cartons, blister packaging support, and secondary packaging for domestic and export pharmaceutical products.
- Premiumization in Personal Care and Luxury Packaging: Rising expatriate consumer spending and growing domestic demand for premium cosmetics, skincare, and gifting products is driving demand for high-quality folding cartons with specialty printing, embossing, and sustainable board substrates.
Market Challenges
- Supply Chain Disruptions and Raw Material Availability: Global supply chain disruptions in wood pulp and recycled fiber markets create periodic raw material availability challenges for Saudi packaging converters, increasing production lead times and procurement costs.
- Skilled Workforce Constraints in Packaging Converting: Saudi Arabia's packaging converting sector faces challenges in recruiting and retaining technically skilled workers for advanced corrugated and folding carton manufacturing operations, impacting production efficiency and quality consistency.
Emerging Market Trends
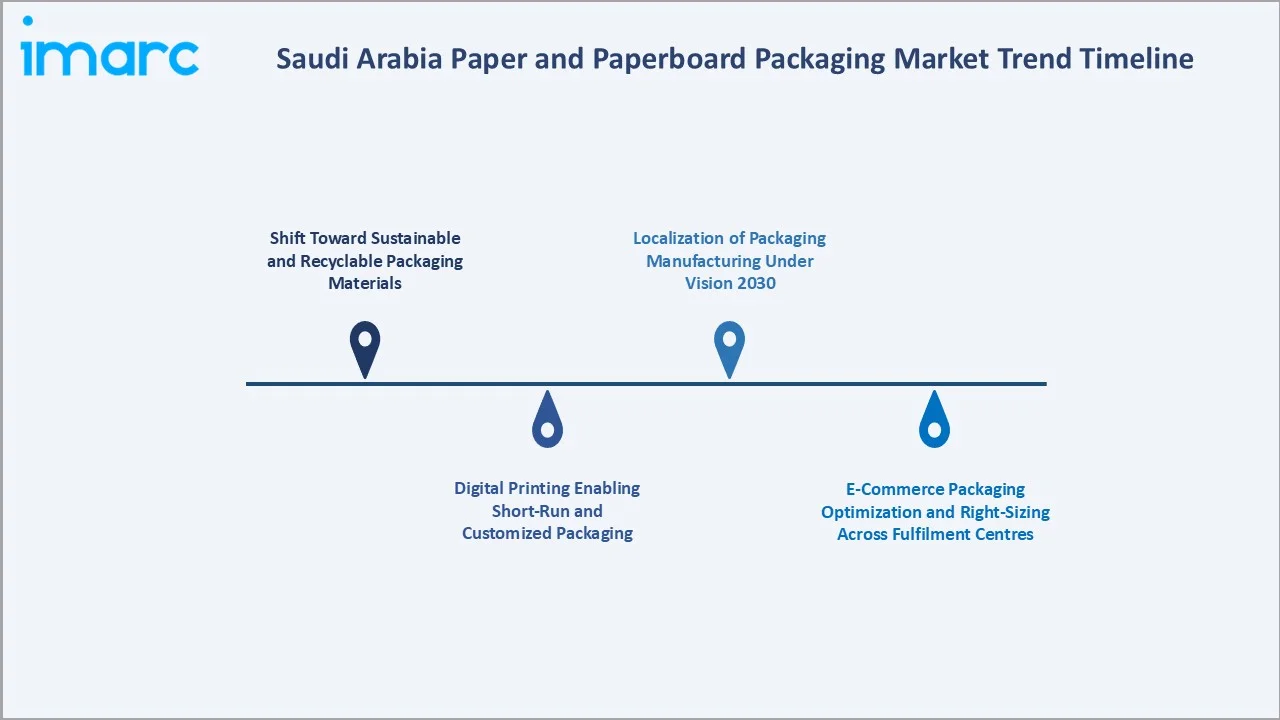
1. Shift Toward Sustainable and Recyclable Packaging Materials
Saudi Arabia's alignment with global environmental sustainability goals is accelerating adoption of FSC-certified paperboard, recycled-content corrugated board, and water-based coating systems. Multinational FMCG brands operating in the Kingdom are mandating supplier sustainability standards, driving converters to invest in certified and traceable fiber sourcing.
2. Digital Printing Enabling Short-Run and Customized Packaging
Digital inkjet and toner-based printing technologies are enabling Saudi packaging converters to offer short-run, personalized, and variable-data packaging at competitive economics. This trend is particularly relevant for the food service, pharmaceutical, and e-commerce sectors where SKU proliferation and seasonal packaging campaigns require rapid design-to-production turnaround.
3. E-Commerce Packaging Optimization and Right-Sizing
Saudi Arabia's leading e-commerce logistics operators are implementing packaging right-sizing programs and automated void-fill systems to reduce corrugated material consumption per shipment while improving packaging integrity. Corrugated box manufacturers are developing standardized, optimized packaging formats and investing in automated packaging line equipment.
4. Localization of Packaging Manufacturing Under Vision 2030
Saudi Arabia's National Industrial Development and Logistics Program (NIDLP) is incentivizing the localization of packaging manufacturing to reduce import dependency. Several international packaging groups have established or are expanding Saudi manufacturing operations to meet growing domestic demand and qualify for in-Kingdom procurement preferences.
Industry Value Chain Analysis
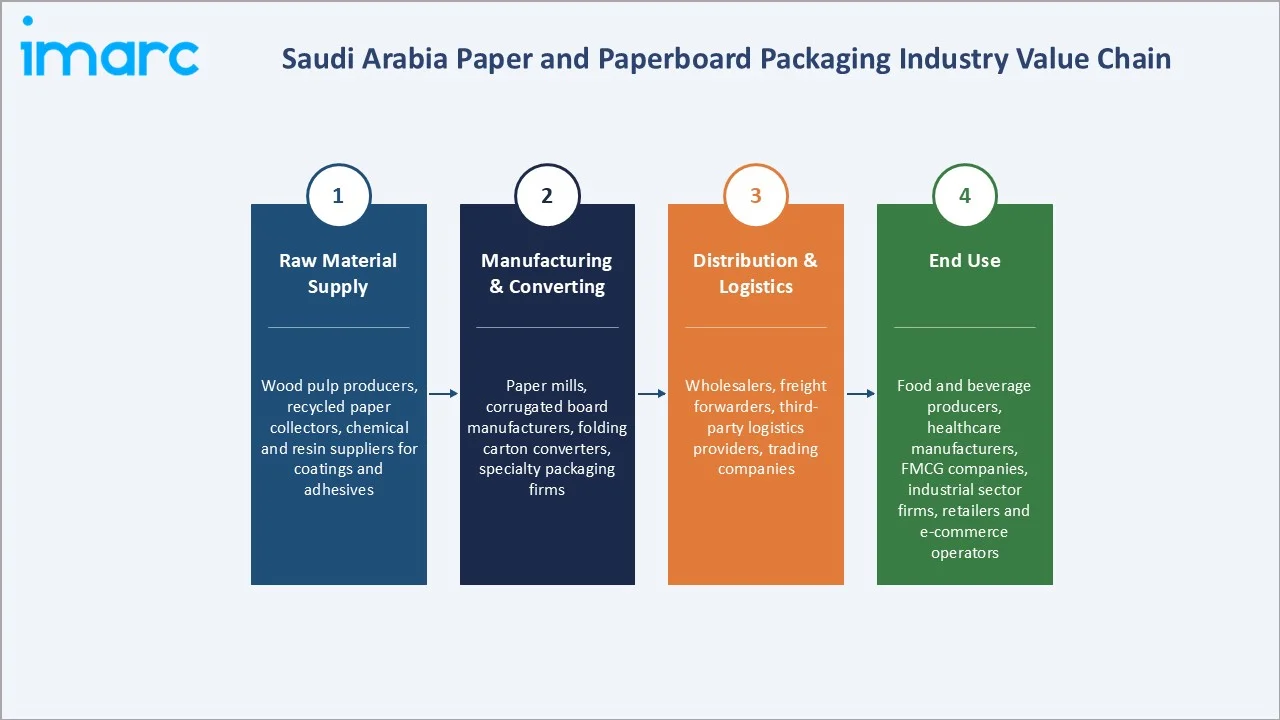
The Saudi Arabia paper and paperboard packaging value chain integrates raw material sourcing and processing, paper and board manufacturing, packaging conversion, distribution and logistics, and final end-use application across commercial and industrial sectors.
|
Stage |
Key Participants |
|
Raw Material Supply |
Wood pulp producers, recycled paper collectors, chemical and resin suppliers for coatings and adhesives |
|
Manufacturing & Converting |
Paper mills, corrugated board manufacturers, folding carton converters, specialty packaging firms |
|
Distribution & Logistics |
Wholesalers, freight forwarders, third-party logistics providers, trading companies |
|
End Use |
Food and beverage producers, healthcare manufacturers, FMCG companies, industrial sector firms, retailers |
The manufacturing and converting stage is the value chain's most commercially differentiated phase. Packaging converters add value through structural design, printing, coating, and finishing, creating brand-differentiated packaging products from commodity paperboard inputs. Logistics integration is becoming increasingly critical as e-commerce fulfilment centres demand just-in-time packaging supply.
Technology Landscape in the Saudi Arabia Paper and Paperboard Packaging Industry
Corrugated Board Manufacturing Technology
Modern corrugated board manufacturing utilizes high-speed single-facer and double-facer equipment capable of producing 200-350 meters per minute. Advanced flute profiles (B, C, E, and micro-flute) enable lightweight, high-performance corrugated packaging for both heavy industrial applications and premium e-commerce packaging.
Digital and Flexographic Printing Technology
Flexographic and digital printing technologies enable high-resolution graphics, variable data printing, and short-run customization on corrugated and folding carton substrates. UV-curable and water-based ink systems are increasingly adopted to meet food-contact safety regulations and sustainability requirements in Saudi Arabia.
Sustainable Coating and Barrier Technology
Water-based barrier coatings, clay coatings, and biopolymer-based barrier systems are replacing traditional plastic lamination in food-grade packaging applications. These technologies enable paper and paperboard packaging to meet moisture, grease, and oxygen barrier requirements while remaining fully recyclable.
Automation and Smart Packaging Technology
Automated case erecting, filling, and sealing systems integrated with Industry 4.0 data management platforms are enabling Saudi packaging converters to improve throughput, reduce waste, and meet e-commerce packaging volume requirements. Smart packaging elements including QR codes and NFC tags are gaining adoption in pharmaceutical and premium consumer goods packaging.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Corrugated Boxes |
58.4% |
2025 |
|
End User |
Food and Beverage |
42.8% |
2025 |
|
Region |
Northern and Central Region |
39.2% |
2025 |

By Type
Corrugated boxes lead at 58.4% (2025), growing at a CAGR of ~4.2% during 2026-2034. The corrugated box encompasses single-wall, double-wall, and triple-wall corrugated containers serving e-commerce logistics, food distribution, and industrial applications. Folding cartons at 30.7% grow at ~2.9% CAGR, serving food retail, pharmaceutical, and personal care packaging markets. Others at 10.9% include rigid boxes, paper bags, and specialty wrap, growing at ~2.5% CAGR.
To get more information on this market, Request Sample
Corrugated boxes grow fastest at ~4.2% CAGR through e-commerce packaging demand surge, food distribution volume growth, and industrial packaging expansion under Vision 2030. Folding cartons grow at ~2.9% CAGR through premium food, pharmaceutical, and personal care packaging growth. The others segment at 10.9% grows at ~2.5% CAGR as paper bag substitution for plastic carrier bags accelerates.
By End User
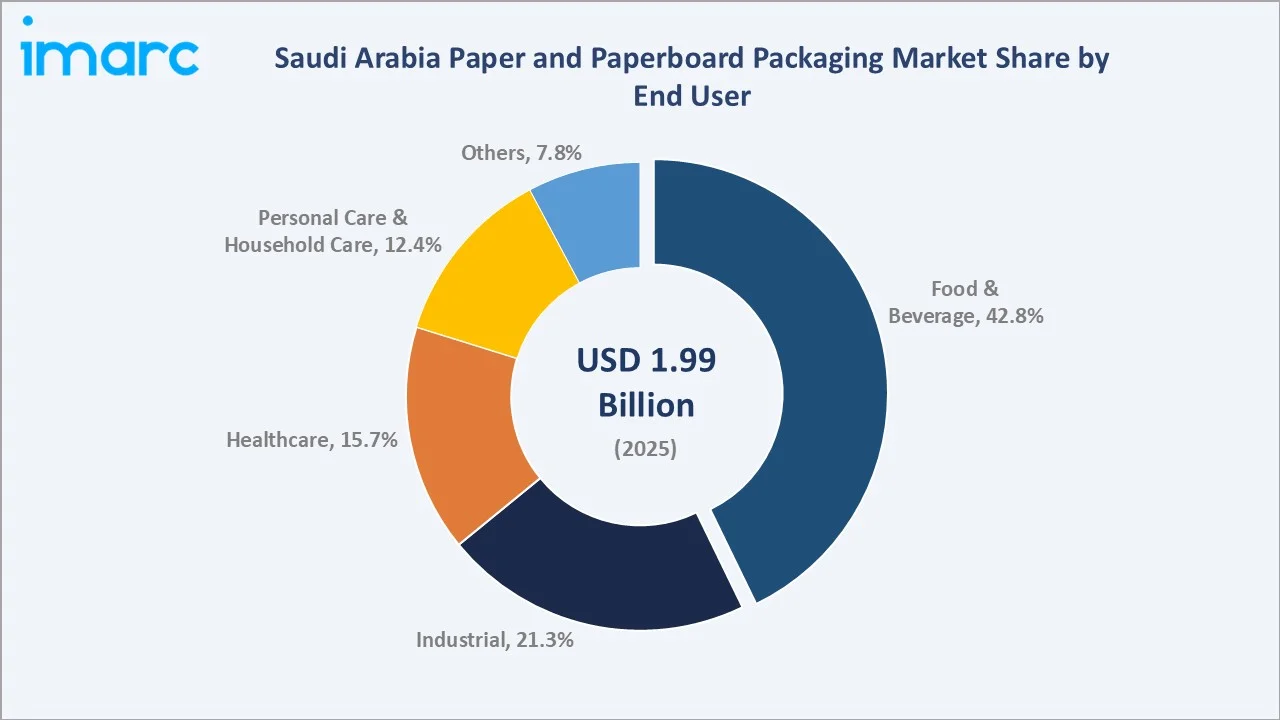
Food and beverage leads at 42.8% (2025), growing at ~4.1% CAGR during 2026-2034. Saudi Arabia's food and beverage packaging market is driven by the Kingdom's thriving quick-service restaurant sector, rapid modern trade expansion, and growing food processing and export activity. Industrial at 21.3% grows at ~3.5% CAGR, reflecting expanding manufacturing and construction activity. Healthcare at 15.7% grows at ~5.0% CAGR, the fastest-growing segment, driven by pharmaceutical manufacturing scale-up under Vision 2030. Personal care and household care at 12.4% grows at ~3.8% CAGR through premium packaging demand. Others at 7.8% grows at ~2.5% CAGR.
Regional Market Insights
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
Northern and Central Region |
39.2% |
Anchored by Riyadh; dense FMCG manufacturing base; major logistics hubs; mega-project infrastructure investment driving industrial packaging demand. |
|
Western Region |
29.1% |
Jeddah as primary commercial port; elevated Hajj/Umrah seasonal packaging demand; dense Red Sea coastal retail corridor. |
|
Eastern Region |
20.0% |
Petrochemical and industrial activity in Jubail and Dammam; export-oriented manufacturing requiring high-volume corrugated packaging. |
|
Southern Region |
11.7% |
Agricultural processing and Vision 2030 infrastructure projects in Jizan, Najran, and Asir stimulating local packaging demand. |
The Northern and Central Region's 39.2% leadership is anchored by Riyadh's position as Saudi Arabia's commercial and governmental capital, hosting the highest concentration of FMCG manufacturers, retail chains, logistics hubs, and construction activity. The Western Region's 29.1% reflects Jeddah's role as the Kingdom's primary commercial seaport.
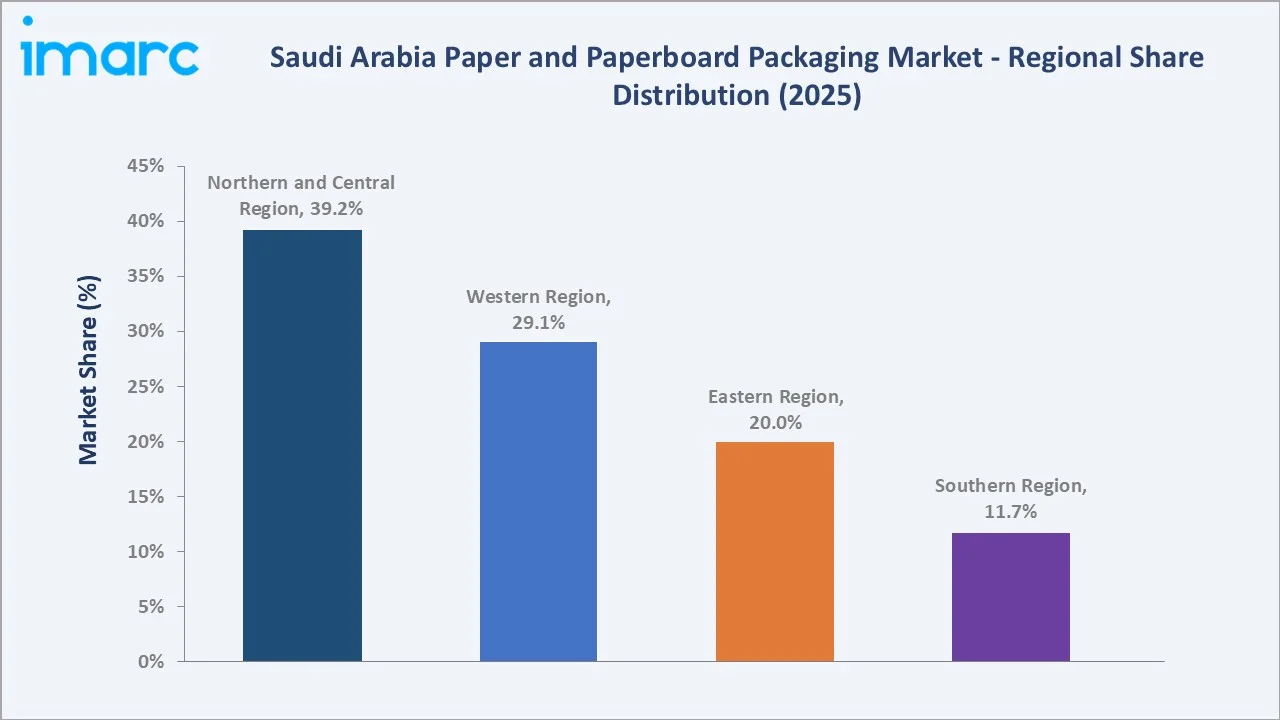
The Eastern Region's 20.0% is driven by petrochemical and industrial manufacturing activity centred in Jubail and Dammam, generating high-volume corrugated packaging demand. The Southern Region at 11.7% is the smallest but experiencing steady growth, supported by Vision 2030 agricultural processing and infrastructure development in Jizan, Najran, and Asir.
Competitive Landscape
The Saudi Arabia paper and paperboard packaging market competitive landscape encompasses global packaging conglomerates, regional converters, and specialist packaging firms. International players leverage advanced manufacturing technology, global procurement scale, and established brand relationships. Domestic converters compete through proximity, faster turnaround, and competitive pricing.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
Smurfit Westrock |
Corrugated containers, consumer packaging, paperboard |
Market Leader |
A global leader in paper-based packaging formed through the merger of Smurfit Kappa and WestRock, with operations across 40+ countries and a strong focus on sustainable, recycled-content corrugated and consumer packaging solutions. |
|
International Paper |
Corrugated packaging, containerboard |
Market Leader |
One of the world's largest producers of fiber-based packaging and pulp, with an integrated corrugated packaging platform serving e-commerce, food and beverage, and industrial customers across North America, Europe, and Asia. |
|
Mondi |
Kraft paper, corrugated board, flexible packaging |
Established Player |
A global packaging and paper company with a strong emphasis on sustainable, eco-designed packaging solutions, investing in circular economy initiatives and barrier paper technologies for consumer and industrial markets worldwide. |
The Saudi Arabia packaging market is moderately concentrated at the large-format corrugated segment, with international groups and well-capitalized Saudi converters commanding significant volumes. The folding carton and specialty packaging segments are more fragmented, with numerous mid-sized domestic converters serving food and beverage and personal care brand owners.
Key Company Profiles
Smurfit Westrock
Smurfit Westrock is a global leader in paper-based packaging, formed through the merger of Smurfit Kappa Group and WestRock Company. The company is one of the world's largest producers of corrugated packaging, consumer packaging, and recycled paperboard, serving customers across consumer goods, e-commerce, healthcare, and industrial markets globally.
- Key Products: Corrugated containers, consumer packaging, paperboard, industrial packaging, and point-of-purchase displays.
- Recent Developments: In July 2026, Smurfit Westrock partnered with Coca-Cola China to develop a series of innovative paper-based packaging solutions for Coca-Cola’s 2026 World Cup campaign. The solutions were designed for both retail and e-commerce channels, including an eight-can 330 ml gift pack with space for a World Cup souvenir. Smurfit Westrock engineered the gift pack with an octagonal structure to combine visual appeal, strength, and material efficiency. The company also developed seven mini-can, basket-style, and e-commerce packaging formats, optimizing materials and structures across multiple production sites.
- Strategic Focus: Focuses on sustainability-driven innovation, expanding recycled-content and certified fiber product lines, and growing its footprint in high-growth emerging markets including the Middle East.
International Paper
International Paper is one of the world's largest producers of fiber-based packaging, pulp, and paper products, with manufacturing operations spanning North America, Europe, Latin America, and Asia. The company serves a broad customer base across industrial, food and beverage, retail, and e-commerce sectors.
- Key Products: Corrugated packaging, containerboard, kraft pulp, and industrial packaging solutions.
- Recent Developments: In May 2026, International Paper broke ground on a new sustainable packaging facility in Rankin County, Mississippi, marking an expansion of its paper-based packaging manufacturing capabilities. The investment is focused on supporting the company's sustainable packaging portfolio and strengthening its ability to serve customers with fiber-based packaging solutions. The development reflects International Paper's continued shift toward sustainable packaging following its combination with DS Smith and supports the company's strategy of expanding its packaging-focused operations in North America.
- Strategic Focus: Pursues capacity optimization, portfolio rationalization toward sustainable corrugated packaging, and strategic investments in supply chain integration to serve global e-commerce customers.
Mondi
Mondi is a global packaging and paper company headquartered in London, with a strong emphasis on sustainable, eco-designed packaging solutions for consumer and industrial customers worldwide. The company operates integrated pulp, paper, and packaging manufacturing across Europe, North America, and emerging markets.
- Key Products: Kraft paper, corrugated board, flexible packaging, and specialty papers for functional and sustainable end-uses.
- Recent Developments: In August 2026, Mondi unveiled an award-winning packaging concept designed to simplify eCommerce packaging through laser marking. The solution uses laser technology to create easy-open and return features directly on the packaging, helping eliminate the need for additional packaging components while improving the consumer experience. The development reflects Mondi’s continued focus on innovative, efficient and sustainable packaging solutions for the growing eCommerce sector.
- Strategic Focus: Invests in circular economy initiatives, increases use of recycled fibers and certified sustainable inputs, and expands its product portfolio through innovation in barrier and sustainable packaging technologies.
Market Concentration Analysis
The Saudi Arabia paper and paperboard packaging market is moderately fragmented at the converting tier, with international packaging conglomerates and a small number of large Saudi packaging converters holding significant volume positions in corrugated and folding carton segments. The specialty and premium packaging segments are more fragmented, with numerous domestic converters competing for food, personal care, and pharmaceutical packaging contracts.
Market consolidation is occurring at the technology and materials supply level, with global paperboard suppliers and corrugated medium producers increasingly establishing regional distribution agreements and supply partnerships with Saudi converters to secure preferred supplier positioning.
Investment & Growth Opportunities
Highest Growth Segments
Healthcare pharmaceutical packaging (~5.0% CAGR), corrugated packaging for e-commerce (~4.2% CAGR), premium folding cartons for personal care (~3.8% CAGR), and sustainable certified paper packaging across all segments represent the highest-growth Saudi paper and paperboard packaging investment vectors through 2034.
Emerging Investment Opportunities
Saudi Arabia's National Industrial Development and Logistics Program is creating significant near-term investment opportunities for integrated paper and packaging manufacturing localization. Packaging technology companies and converting equipment suppliers that establish early preferred supplier relationships with Vision 2030 industrial development programs are positioned for above-market revenue growth.
Investment Themes
- In-Kingdom corrugated box manufacturing capacity investment capturing growing e-commerce and food distribution packaging demand, with Vision 2030 industrial localization incentives reducing effective capital cost of new converting capacity.
- Sustainable packaging innovation investment developing certified recycled-content corrugated board and FSC-certified folding carton products for multinational FMCG customers mandating supplier sustainability compliance in Saudi Arabia.
Future Market Outlook (2026-2034)
The Saudi Arabia paper and paperboard packaging market is projected to grow from USD 1.99 Billion in 2025 to USD 2.74 Billion by 2034, delivering a 3.61% CAGR over the forecast period. The market anchor value of USD 2.38 Billion in 2030 represents a packaging industry at its most transformative commercial inflection, with e-commerce packaging achieving mainstream adoption, sustainable packaging mandates driving material substitution, and healthcare packaging expanding through domestic pharmaceutical manufacturing scale-up.
Three structural forces define market growth through 2034: Vision 2030 sustainability mandates creating policy-driven demand for eco-friendly packaging; e-commerce logistics expansion generating sustained corrugated box demand as online retail penetration increases across the Kingdom; and healthcare and pharmaceutical development driving specialized packaging demand for domestically manufactured medical products.
Research Methodology
Primary Research
Primary research comprised structured interviews with 40+ industry stakeholders including packaging manufacturing executives, FMCG procurement directors, logistics and distribution managers, regulatory specialists, and regional packaging market analysts across Saudi Arabia and the GCC.
Secondary Research
Secondary research encompassed Saudi packaging industry publications; SFDA regulatory data; Vision 2030 program documentation; company annual reports; GCC trade and customs data; international packaging association reports; and regional market intelligence databases. Over 50 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts developed using a segment bottom-up model: (i) corrugated packaging component by end-use sector; (ii) folding carton component by end-use sector; (iii) specialty packaging and other paper packaging component, aggregated to total market with macro-economic calibration and cross-validation.
Saudi Arabia Paper and Paperboard Packaging Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Types Covered | Folding Cartons, Corrugated Boxes, Others |
| End Users Covered | Food and Beverage, Healthcare, Personal Care and Household Care, Industrial, Others |
| Regions Covered | Northern and Central Region, Western Region, Eastern Region, Southern Region |
| Companies Covered | Smurfit Westrock, International Paper, Mondi, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 9-11 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Saudi Arabia paper and paperboard packaging market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Saudi Arabia paper and paperboard packaging market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Saudi Arabia paper and paperboard packaging industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Saudi Arabia Paper and Paperboard Packaging Market Report
The Saudi Arabia paper and paperboard packaging market reached USD 1.99 Billion in 2025. The market is driven by expanding e-commerce, Vision 2030 sustainability initiatives, and growth in food and beverage, healthcare, and personal care packaging demand.
The market grows at 3.61% CAGR during 2026-2034, reaching USD 2.74 Billion by 2034. Healthcare packaging grows fastest at ~5.0% CAGR and corrugated boxes grow at ~4.2% CAGR, driven by e-commerce packaging demand.
Corrugated boxes lead at 58.4% through logistical efficiency advantages for e-commerce and food distribution, structural versatility for industrial applications, and compatibility with automated packaging systems, growing at ~4.2% CAGR.
Food and beverage leads at 42.8% through Saudi Arabia's expanding quick-service restaurant sector, modern trade growth, and rising demand for hygienic and branded food packaging compliant with Saudi Food and Drug Authority standards.
The Northern and Central Region leads at 39.2% through Riyadh's concentration of FMCG manufacturing, logistics infrastructure, and modern retail formats driving sustained packaging consumption.
Leading companies include Smurfit Westrock, International Paper, and Mondi, among others.
The market is projected to reach approximately USD 2.38 Billion by 2030, with e-commerce corrugated packaging achieving mainstream adoption, sustainable packaging mandates accelerating material substitution, and healthcare packaging expanding through Vision 2030 pharmaceutical sector development.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade