
South East Asia Metal Recycling Market Size, Share, Trends and Forecast by Type, End Use Industry, and Country, 2026-2034
South East Asia Metal Recycling Market Size, Share, Trends & Forecast (2026-2034)
The South East Asia metal recycling market reached USD 10.20 Billion in 2025 and is projected to reach USD 19.07 Billion by 2034, growing at a CAGR of 6.98% during 2026-2034. The market is driven by rising scrap generation from construction and automotive sectors, expanding electric arc furnace steelmaking capacity, and tightening regional environmental regulations governing metal waste disposal and circular material recovery across ASEAN economies. Ferrous metal dominates at 68.4%. Building and construction leads end use industry at 27.8%. Indonesia commands 28.7% of the regional market share.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 10.20 Billion |
|
Forecast Market Size (2034) |
USD 19.07 Billion |
|
CAGR (2026-2034) |
6.98% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Type |
Ferrous Metal (68.4%, 2025) |
|
Dominant End Use Industry |
Building and Construction (27.8%, 2025) |
|
Leading Country |
Indonesia (28.7%, 2025) |
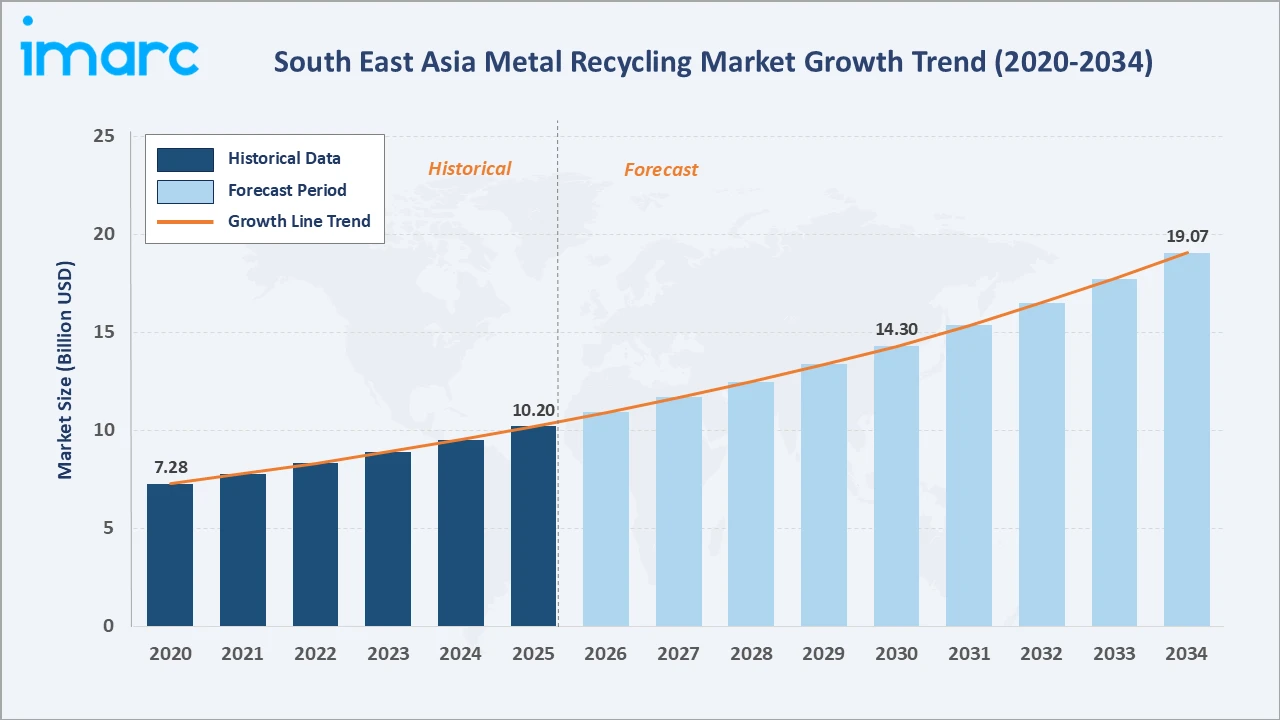
The South East Asia metal recycling market expanded from an estimated USD 7.28 Billion in 2020 to USD 10.20 Billion in 2025, anchored at USD 14.30 Billion in 2030, and forecast to reach USD 19.07 Billion by 2034. Pandemic-era disruption to scrap collection networks in 2020-2021 gave way to a strong rebound as construction activity, automotive production, and industrial output resumed across Indonesia, Thailand, and Vietnam, sustaining above-trend regional recycling volumes through 2022-2025.
To get more information on this market, Request Sample
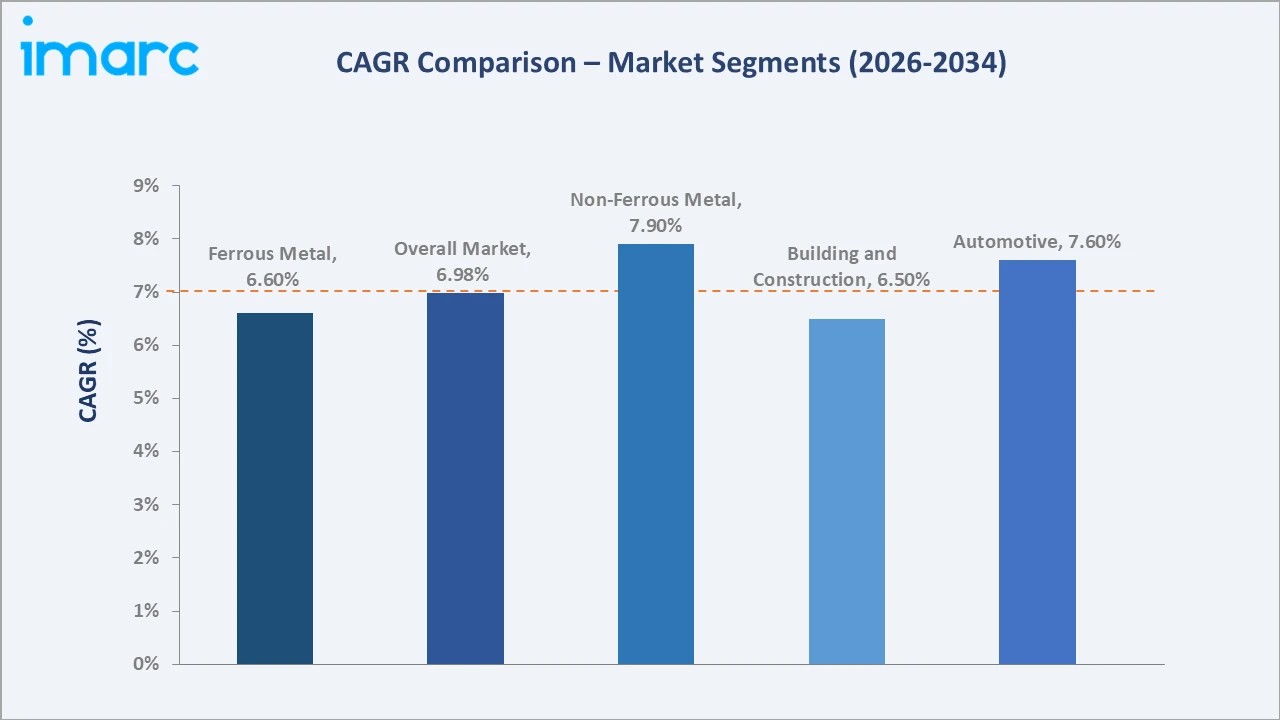
Non-Ferrous Metal grows fastest at ~7.9% CAGR as electronics and electrical equipment manufacturing expands regional demand for recovered copper, aluminium, and other non-ferrous alloys. Automotive at ~7.6% CAGR leads end use industry growth through rising end-of-life vehicle volumes and regional electric vehicle component sourcing.
Executive Summary
The South East Asia metal recycling market reached USD 10.20 Billion in 2025, representing an increasingly formalized intersection of industrial scrap generation, environmental regulation, and secondary raw material supply for the region's steelmaking and manufacturing base. The market encompasses ferrous and non-ferrous scrap collection, sorting and grading, shredding and processing, smelting and refining, and distribution of recycled metal to construction, automotive, industrial machinery, packaging, electronics, and shipbuilding end users.
Ferrous Metal at 68.4% dominates through the region's large electric arc furnace steelmaking base and high-volume construction rebar demand. Building and Construction at 27.8% leads end use industry through sustained regional infrastructure investment and urban housing development. Indonesia, at 28.7%, leads through its large domestic steel industry and expanding EAF capacity absorbing regional ferrous scrap supply.
Key Market Insights
|
Insight |
Data |
|
Dominant Type |
Ferrous Metal - 68.4% share (2025) |
|
Dominant End Use Industry |
Building and Construction - 27.8% market share (2025) |
|
Leading Country |
Indonesia - 28.7% market share |
|
Market Opportunity |
EAF steel capacity expansion; EV end-of-life battery and component recovery; AI-based scrap sorting; regional green steel certification; formalization of informal scrap networks |
Key Analytical Observations Supporting the Above Data:
- Ferrous Metal at 68.4%: The ferrous metal segment dominates due to strong regional electric arc furnace steel production, high construction rebar demand, and well-established ferrous scrap collection infrastructure across Indonesia, Thailand, and Vietnam. These structural factors sustain ferrous metal's leading position in feedstock volume and processing capacity.
- Building and Construction at 27.8%: The building and construction segment dominates because reinforcing steel bar and structural steel demand is directly tied to the region's sustained infrastructure and housing investment cycle. Government-backed infrastructure programs across Indonesia, Vietnam, and the Philippines continue to anchor recycled steel offtake.
- Indonesia at 28.7%: Indonesia dominates the market due to its large domestic steel industry, expanding electric arc furnace capacity, and government policy support for scrap-based steelmaking to reduce dependence on imported iron ore and pig iron. The country's scale of construction and automotive activity further reinforces its leading position.
South East Asia Metal Recycling Market Overview
The South East Asia metal recycling market encompasses the collection, sorting, shredding, smelting, and distribution of ferrous and non-ferrous scrap metal recovered from end-of-life vehicles, demolished structures, industrial offcuts, and discarded appliances and electronics across Indonesia, Thailand, Vietnam, Malaysia, Singapore, and the Philippines.
Macroeconomic factors include rising regional steel demand, expanding electric arc furnace capacity, and growing automotive and electronics manufacturing output. In addition, tightening environmental regulations, rising raw material import costs, and government-backed circular economy programs are accelerating formal scrap recycling adoption across ASEAN member states.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
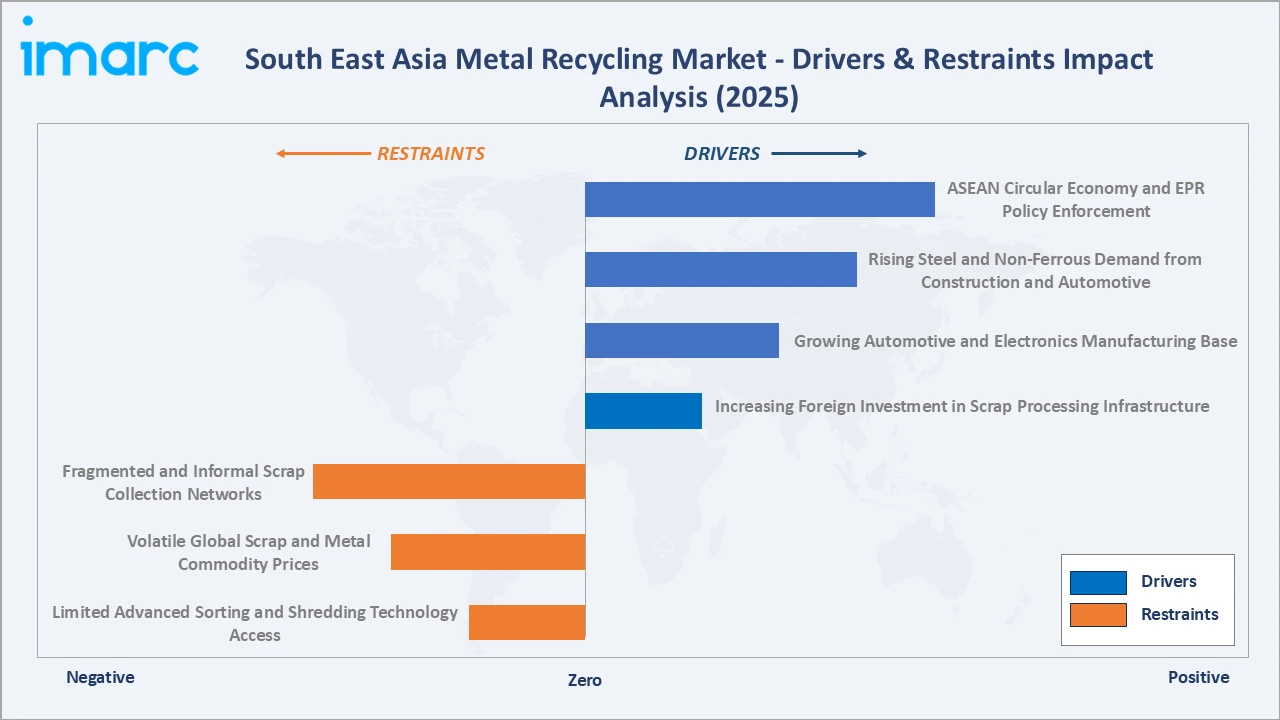
- ASEAN Circular Economy and EPR Policy Enforcement: ASEAN circular economy frameworks and extended producer responsibility regulations are compelling manufacturers and processors to formalize scrap collection and increase recycled material intake. Indonesia and Vietnam have both strengthened scrap import and domestic collection standards in 2025, pushing informal collectors toward registered recycling facilities and improving feedstock traceability across the region.
- Rising Steel and Non-Ferrous Demand from Construction and Automotive: Regional construction and automotive output continue to expand steel and non-ferrous metal consumption, directly increasing demand for recycled feedstock as an alternative to higher-cost virgin ore and imported billet. Indonesia's continued electric arc furnace capacity additions are increasing domestic ferrous scrap absorption.
- Growing Automotive and Electronics Manufacturing Base: Southeast Asia's growing role as an automotive and electronics manufacturing hub is increasing the volume of industrial offcuts and end-of-life components available for recovery. Vietnam and Malaysia's expanding electronics assembly base is generating rising volumes of recoverable copper, aluminium, and precious metal-bearing scrap.
- Increasing Foreign Investment in Scrap Processing Infrastructure: International and regional recyclers are investing in shredding, sorting, and smelting capacity across Thailand, Malaysia, and Vietnam to capture growing regional scrap volumes and reduce reliance on scrap exports to China and other Northeast Asian buyers.
Market Restraints
- Fragmented and Informal Scrap Collection Networks: A significant share of regional scrap collection remains informal and unregistered, particularly in Indonesia, the Philippines, and Vietnam, limiting quality consistency, traceability, and the ability of formal recyclers to secure stable feedstock volumes.
- Volatile Global Scrap and Metal Commodity Prices: Regional recyclers remain exposed to volatile global ferrous and non-ferrous commodity prices set by international benchmarks, creating margin uncertainty and complicating long-term investment planning for processing capacity.
- Limited Advanced Sorting and Shredding Technology Access: Many regional processors continue to rely on manual sorting and basic shredding equipment, limiting recovery purity and processing throughput relative to more automated facilities in Japan, South Korea, and China.
Market Opportunities
- Electric Vehicle End-of-Life Component Recovery: Rising regional electric vehicle adoption is creating a growing future stream of end-of-life battery packs and EV components requiring specialized recovery of lithium, cobalt, nickel, and copper, representing a high-value emerging recycling category for regional processors.
- AI-Based Scrap Sorting Technology Adoption: Rising investment in AI-enabled optical and sensor-based sorting technology is enabling higher-purity non-ferrous metal separation, allowing regional processors to capture premium pricing for high-grade recovered aluminium and copper fractions.
Market Challenges
- Cross-Border Regulatory Inconsistency: Inconsistent enforcement of scrap import and export regulations across ASEAN member states creates compliance complexity for recyclers operating multi-country collection and processing networks.
- Regional Scrap Export Competition from China: Competition for high-quality ferrous and non-ferrous scrap from Chinese buyers continues to draw regional export volumes away from domestic processors, constraining local feedstock availability for the region's own steel and alloy producers.
Emerging Market Trends
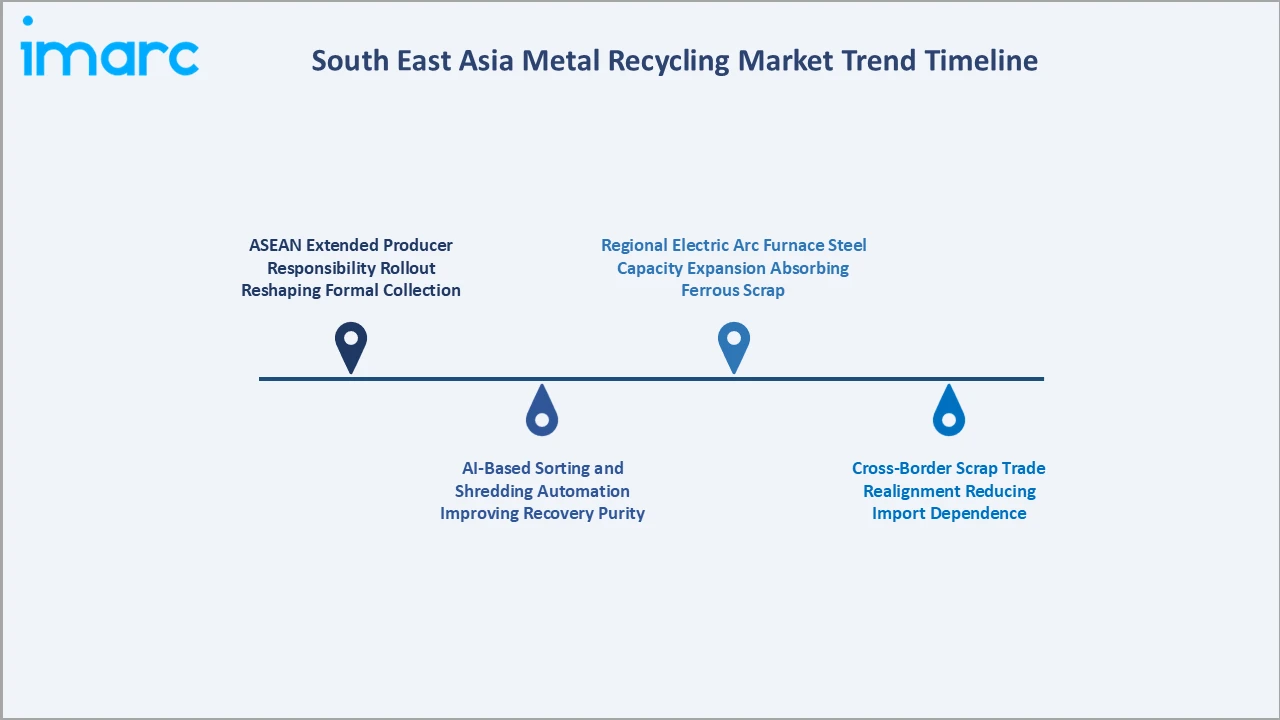
1. ASEAN Extended Producer Responsibility Rollout Reshaping Formal Collection
ASEAN member states are progressively adopting extended producer responsibility frameworks that require manufacturers to fund and support end-of-life material recovery, pushing informal scrap collection toward registered and auditable recycling channels. Indonesia's 2025 updates to its national waste management regulations extended coverage to metal packaging and industrial scrap, requiring registered processors to report recovery volumes. This regulatory formalization is improving feedstock traceability and encouraging investment in certified processing capacity across the region.
2. AI-Based Sorting and Shredding Automation Improving Recovery Purity
Regional processors are adopting AI-enabled optical sorting, sensor-based alloy identification, and automated shredding lines to improve recovery purity and reduce labor dependence. These technologies allow facilities to separate high-value non-ferrous fractions such as copper and aluminium from mixed scrap streams with greater precision, supporting premium pricing and reducing contamination-related rejections at downstream smelters.
3. Regional Electric Arc Furnace Steel Capacity Expansion Absorbing Ferrous Scrap
Steelmakers across Indonesia, Vietnam, and Malaysia continue to add electric arc furnace capacity, directly increasing domestic demand for ferrous scrap as an alternative to imported iron ore and pig iron. This capacity expansion is reducing the region's historical reliance on scrap exports and encouraging longer-term offtake agreements between recyclers and steel producers.
4. Cross-Border Scrap Trade Realignment Reducing Import Dependence
Southeast Asian steelmakers are increasingly sourcing scrap from within the region rather than relying solely on imports from Japan, the United States, and Europe, as domestic collection infrastructure matures. This realignment is strengthening intra-ASEAN scrap trade corridors and supporting investment in regional processing and logistics hubs, particularly in Thailand and Malaysia.
Industry Value Chain Analysis
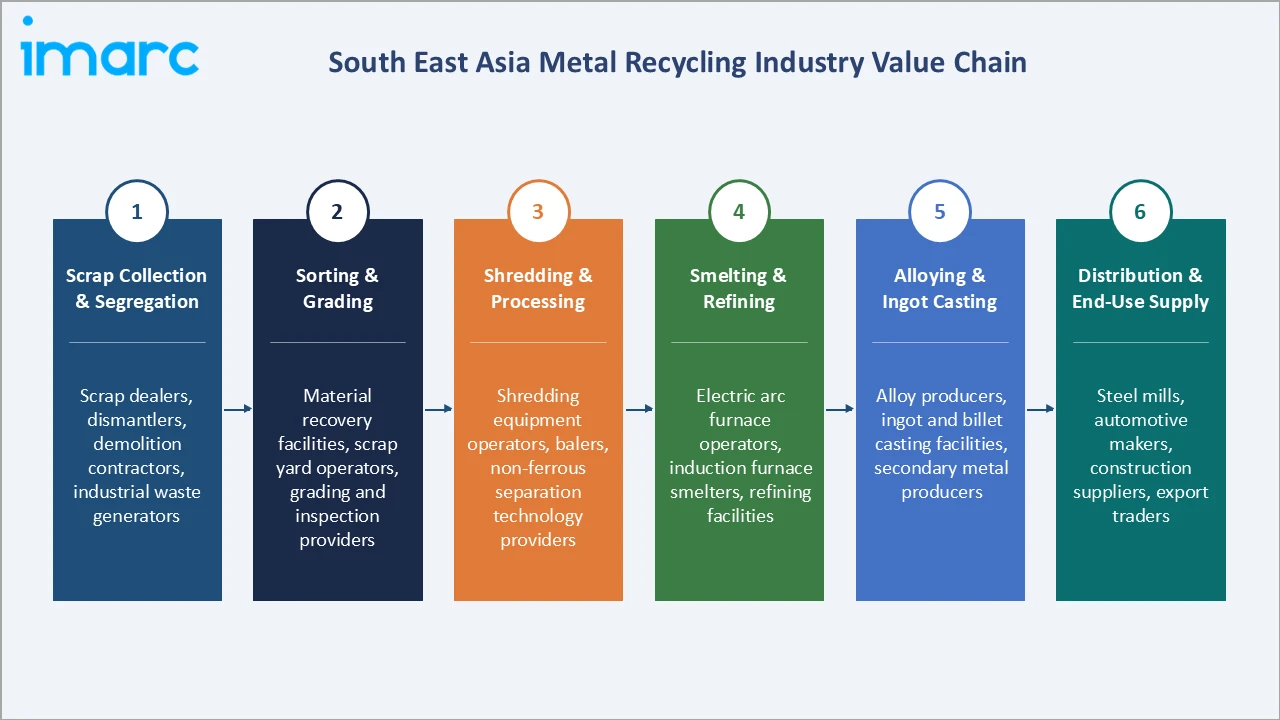
The South East Asia metal recycling value chain integrates scrap collection and segregation, sorting and grading, shredding and processing, smelting and refining, alloying and ingot casting, and distribution to end-use manufacturers across construction, automotive, and industrial sectors.
|
Stage |
Key Participants |
|
Scrap Collection & Segregation |
Scrap dealers, dismantlers, demolition contractors, industrial waste generators |
|
Sorting & Grading |
Material recovery facilities, scrap yard operators, grading and inspection service providers |
|
Shredding & Processing |
Shredding equipment operators, balers, non-ferrous separation technology providers |
|
Smelting & Refining |
Electric arc furnace operators, induction furnace smelters, refining and purification facilities |
|
Alloying & Ingot Casting |
Alloy producers, ingot and billet casting facilities, secondary metal producers |
|
Distribution & End-Use Supply |
Steel mills, automotive component makers, construction material suppliers, export traders |
The shredding and processing stage is the value chain's most technically differentiated phase, where investment in automated sorting determines recovery purity and downstream pricing. The smelting and refining layer anchors the region's growing electric arc furnace steelmaking capacity, converting recovered ferrous scrap directly into construction-grade steel billet.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Ferrous Metal |
68.4% |
2025 |
|
End Use Industry |
Building and Construction |
27.8% |
2025 |
|
Country |
Indonesia |
28.7% |
2025 |
By Type
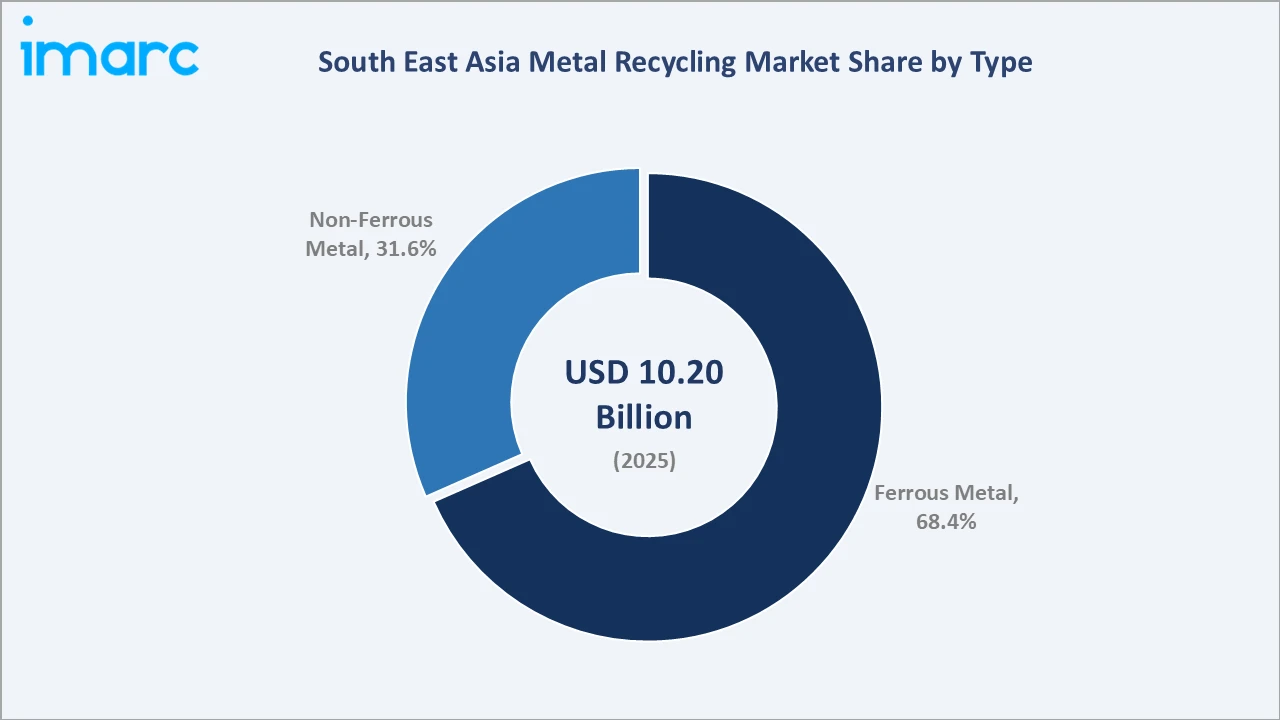
Ferrous metal leads at 68.4% (2025), growing at a ~6.6% CAGR through 2034. The ferrous metal segment encompasses recycled iron and steel scrap recovered from construction demolition, automotive end-of-life vehicles, and industrial manufacturing offcuts, supplying electric arc furnace and induction furnace steelmaking across the region.
To access detailed market analysis, Request Sample
Non-ferrous metal at 31.6% encompasses recycled aluminium, copper, zinc, lead, and other base metals recovered from electronics, packaging, and automotive components. Non-ferrous metal's ~7.9% CAGR is above the overall market rate, driven by rising electronics manufacturing and copper-intensive electric vehicle component demand across Vietnam and Malaysia.
By End Use Industry
Building and construction leads at 27.8% (2025), growing at a ~6.5% CAGR, driven by sustained regional infrastructure and housing investment requiring high volumes of recycled reinforcing steel and structural sections.
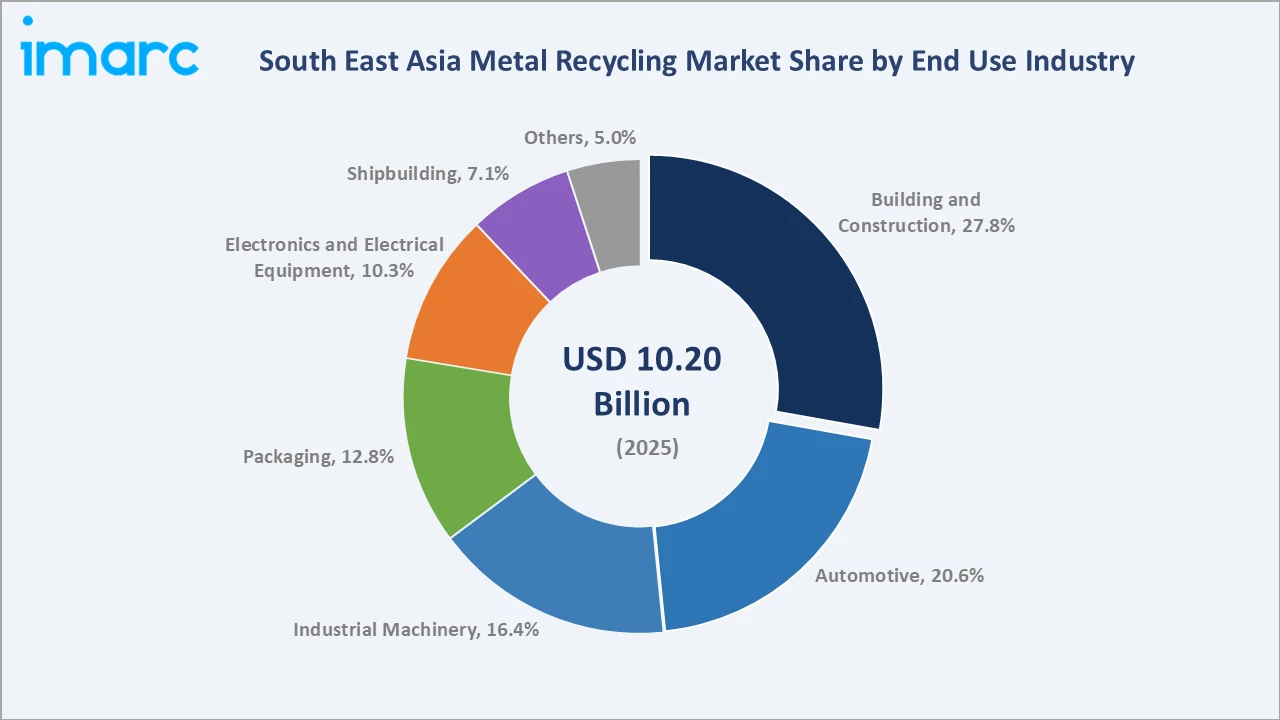
Automotive at 20.6% grows fastest among major end use segments at a ~7.6% CAGR, reflecting the region's expanding vehicle production base and rising end-of-life vehicle recycling volumes. Industrial machinery at 16.4% (~6.9% CAGR), packaging at 12.8% (~6.2% CAGR), and electronics and electrical equipment at 10.3% (~8.3% CAGR) collectively represent the region's manufacturing-linked recycled metal demand, while shipbuilding at 7.1% (~5.8% CAGR) and others at 5.0% (~6.0% CAGR) complete the end use industry breakup.
Regional Market Insights
|
Country |
Share (2025) |
Key Market Drivers & Characteristics |
|
Indonesia |
28.7% |
Driven by a large domestic steel industry, expanding electric arc furnace capacity, and government support for scrap-based steel production. |
|
Thailand |
18.9% |
Supported by an established electric-furnace steel industry and strong construction and automotive manufacturing demand. |
|
Vietnam |
16.8% |
Driven by rapid industrialization, expanding steel billet production capacity, and growing electronics assembly output. |
|
Malaysia |
13.7% |
Anchored by growing EAF steel capacity and expanding regional scrap processing and trading infrastructure. |
|
Singapore |
9.8% |
Supported by its role as a regional scrap trading and logistics hub with advanced non-ferrous processing capability. |
|
Philippines |
7.4% |
Driven by rising construction activity and gradual formalization of domestic scrap collection networks. |
|
Others |
4.7% |
Includes Myanmar, Cambodia, and Laos, supported by early-stage industrialization and infrastructure investment. |
Indonesia's 28.7% market leadership is anchored by the country's position as Southeast Asia's largest steel producer and its continued electric arc furnace capacity additions absorbing domestic ferrous scrap. Thailand's 18.9% reflects its established electric-furnace steel base and constant net-import scrap demand.
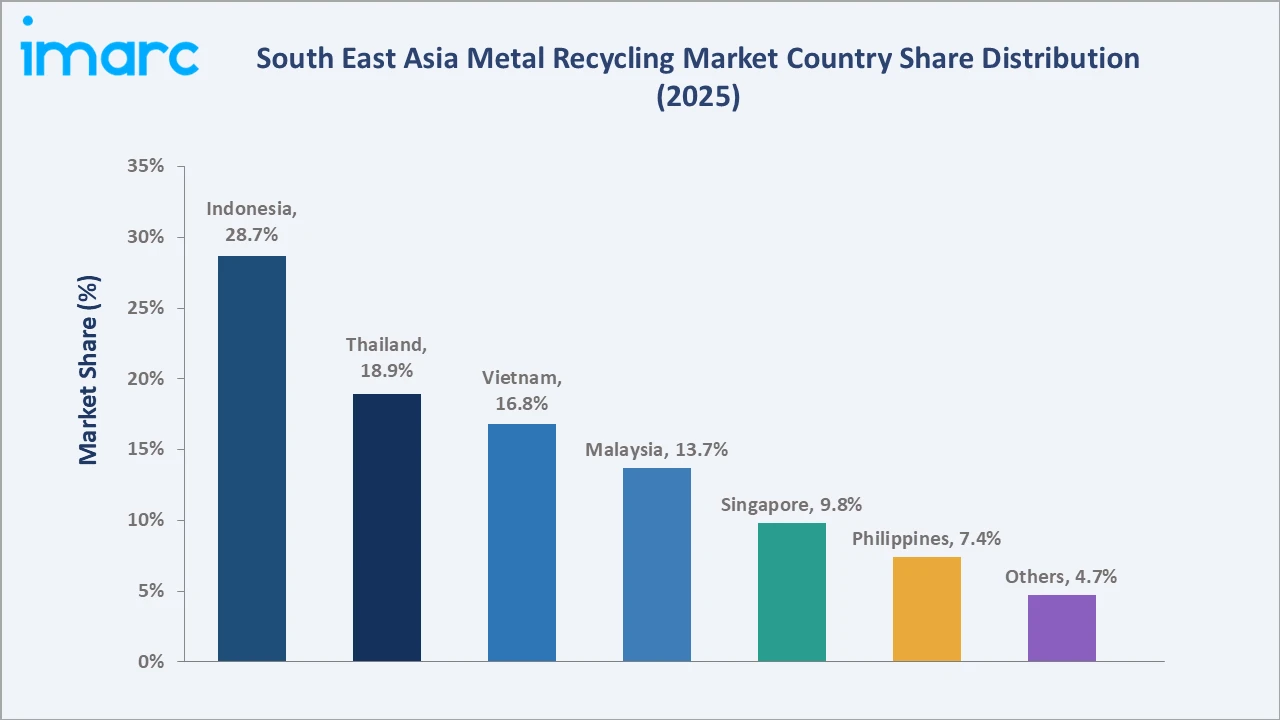
Vietnam's 16.8% encompasses rapidly expanding steel billet production alongside growing electronics assembly-driven non-ferrous scrap generation. Malaysia and Singapore together anchor the region's scrap trading and processing infrastructure, while the Philippines represents the most commercially dynamic growth market by CAGR as domestic collection formalizes.
Competitive Landscape
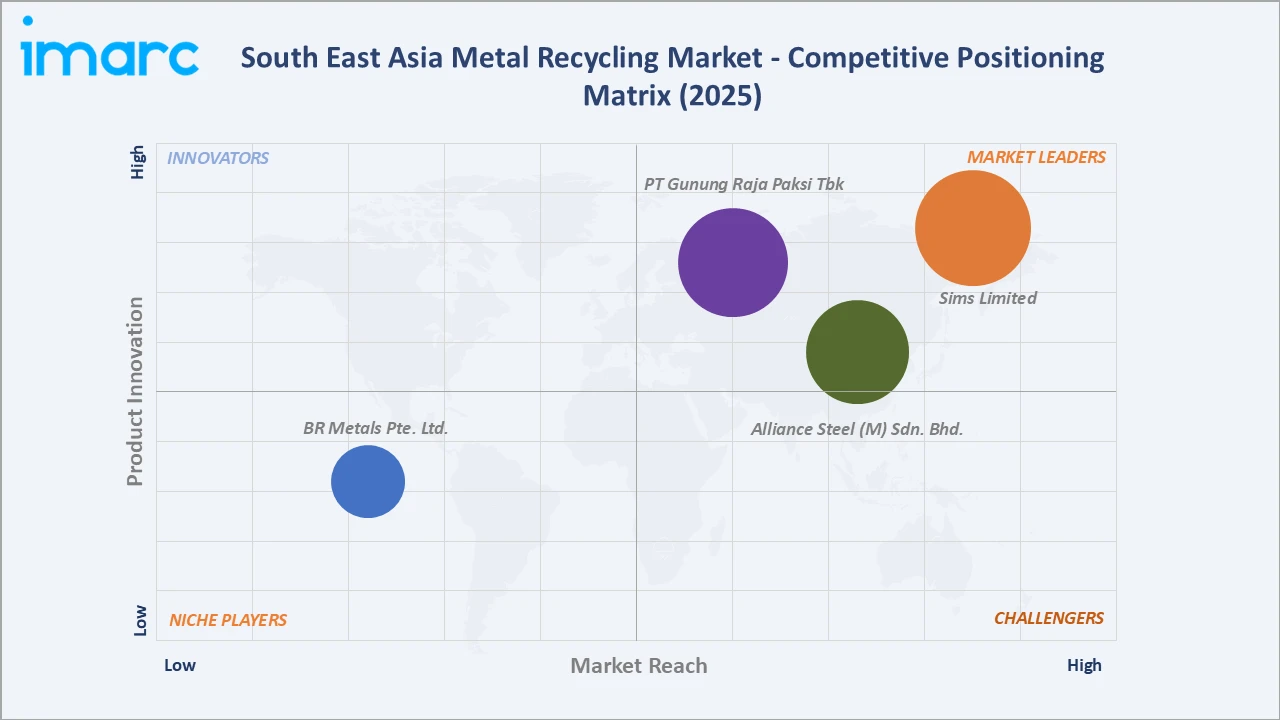
The South East Asia metal recycling market competitive landscape encompasses distinct tiers: integrated regional steel producers with in-house scrap processing, dedicated ferrous and non-ferrous scrap recyclers, and international recycling groups with regional processing footprints.
|
Company Name |
Market Positioning |
Key Products |
Core Strength |
|
Sims Limited |
Market Leader |
Recycled ferrous scrap, recycled aluminium and copper |
Global metal recycling operator with regional non-ferrous and ferrous scrap processing capability across Southeast Asia. |
|
PT Gunung Raja Paksi Tbk |
Market Leader |
Steel billet |
Large-scale integrated electric arc furnace steel producer with substantial domestic ferrous scrap absorption capacity. |
|
Alliance Steel (M) Sdn. Bhd. |
Market Leader |
Hot-rolled coil, steel billet, |
Large basic oxygen and electric arc furnace steel complex supporting regional scrap-based and ore-based production. |
|
BR Metals Pte. Ltd. |
Niche Player |
Recovered precious metals, catalytic converter scrap |
Leading precious and non-ferrous metal recycler specializing in catalytic converter and industrial catalyst recovery. |
Regional consolidation reflects steelmakers' preference for securing captive scrap supply through vertical integration, while dedicated recyclers such as BR Metals and Sims Limited compete on processing specialization and export market relationships. Competitive intensity is increasing at the technology investment tier as processors upgrade sorting and shredding capability.
Key Company Profiles
Sims Limited
Sims Limited is a leading global metal recycling operator with processing operations spanning ferrous and non-ferrous scrap recovery across multiple Southeast Asian markets. The company specializes in large-scale shredding, sorting, and metal recovery technology serving regional steelmakers and export markets.
- Key Operations: Ferrous and non-ferrous scrap shredding, sorting, and export processing facilities.
- Recent Developments: In July 2025, Sims Limited announced a non-binding Memorandum of Understanding with Alter Steel to establish a scrap supply and services agreement for Alter Steel’s proposed electric arc furnace in Pinkenba, Queensland. Under the proposed agreement, Sims would supply up to 550,000 tonnes of ferrous scrap annually, manage scrap inventory, and provide access to port and rail infrastructure. The collaboration is expected to support the conversion of locally recovered scrap into up to 500,000 tonnes of lower-carbon reinforcing steel annually, strengthening metal recycling and circular steel production in Australia.
- Strategic Focus: Focuses on automated sorting technology investment, export market diversification, and sustainability-linked recycling certification.
PT Gunung Raja Paksi Tbk
PT Gunung Raja Paksi Tbk is one of Indonesia's largest integrated steel producers, operating electric arc furnace and basic oxygen furnace capacity that absorbs substantial volumes of domestic and imported ferrous scrap. The company supplies construction and industrial steel products across the Indonesian market.
- Key Operations: Integrated steelmaking with electric arc furnace and basic oxygen furnace ferrous scrap processing.
- Strategic Focus: Centered on capacity expansion, domestic scrap supply chain formalization, and construction-grade steel product diversification.
Market Concentration Analysis
The South East Asia metal recycling market is moderately fragmented at the scrap collection tier, with numerous small and informal collectors operating alongside registered material recovery facilities across Indonesia, the Philippines, and Vietnam. Processing and steelmaking capacity is more concentrated, with a handful of large integrated producers such as PT Gunung Steel Group, Tata Steel (Thailand), and Alliance Steel accounting for a substantial share of regional ferrous scrap absorption. Market concentration is increasing at the processing technology tier through capacity expansion and selective consolidation.
Investment & Growth Opportunities
Highest Growth Segments
Non-ferrous metal recycling (~7.9% CAGR), automotive end-use scrap recovery (~7.6% CAGR), electric vehicle battery and component recycling (~15% CAGR from a small base), AI-based sorting technology deployment (~12% CAGR), and Vietnam and Malaysia's expanding EAF-linked ferrous scrap demand (~8-9% CAGR) represent the highest-growth investment vectors through 2034.
Emerging Investment Opportunities
Regional electric arc furnace capacity expansion represents the largest near-term structural opportunity for ferrous scrap processors. Recyclers and technology providers that establish long-term offtake relationships with steelmakers in Indonesia, Vietnam, and Malaysia are positioned for above-market volume growth as regional EAF capacity additions continue through 2030.
Investment Themes
- AI-Enabled Sorting Infrastructure Investment: Automated non-ferrous sorting investment capturing premium-grade copper and aluminium recovery from mixed electronics and automotive scrap streams, supporting higher realized pricing versus unsorted mixed metal exports.
- Electric Vehicle Component Recovery Platform Development: Regional recyclers establishing dedicated electric vehicle battery and component recovery lines are positioned to capture an emerging high-value revenue stream as the region's EV parc reaches end-of-life scale from the early 2030s onward.
Future Market Outlook (2026-2034)
The South East Asia metal recycling market is projected to grow from USD 10.20 Billion in 2025 to USD 19.07 Billion by 2034, delivering a 6.98% CAGR over the forecast period. The market's anchor value of USD 14.30 Billion in 2030 represents a regional recycling industry at its most transformative point since the initial wave of electric arc furnace capacity additions, with AI-based sorting achieving mainstream adoption among leading regional processors, electric vehicle component recovery moving from pilot to commercial scale, and cross-border ASEAN scrap trade corridors displacing a growing share of extra-regional scrap imports.
Three structural forces define regional metal recycling market growth through 2034 with strong confidence. Regional steel self-sufficiency policy across Indonesia, Vietnam, and Malaysia creates government-backed electric arc furnace capacity growth that sustains scrap demand regardless of short-term commodity price cycles. ASEAN circular economy and extended producer responsibility regulation formalizes scrap collection, progressively displacing informal channels. Technology cost reduction is making automated sorting and shredding capability commercially accessible to mid-sized regional processors.
Research Methodology
Primary Research
Primary research comprised structured interviews with 40+ industry stakeholders (2025) including plant operations directors, business development heads, regional scrap trading executives, steel mill procurement managers, and country-level recycling association representatives.
Secondary Research
Secondary research encompassed regional steel and scrap trade publications, ASEAN environmental regulation databases, company annual reports, customs and trade statistics, and industry association data. Over 45 secondary sources were reviewed.
Forecasting Models
Market revenue forecasts were developed using a segment bottom-up model: (i) ferrous metal recycling component; (ii) non-ferrous metal recycling component; (iii) country-level scrap collection and processing capacity component.
South East Asia Metal Recycling Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report | Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Ferrous Metal, Non-Ferrous Metal |
| End Use Industries Covered | Building and Construction, Packaging, Automotive, Industrial Machinery, Electronics and Electrical Equipment, Shipbuilding, Others |
| Countries Covered | Indonesia, Thailand, Singapore, Philippines, Vietnam, Malaysia, Others |
| Companies Covered | Sims Limited, PT Gunung Raja Paksi Tbk, Alliance Steel (M) Sdn. Bhd.and BR Metals Pte. Ltd., etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the South East Asia metal recycling market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the South East Asia metal recycling market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the South East Asia metal recycling industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the South East Asia Metal Recycling Market Report
The South East Asia metal recycling market reached USD 10.20 Billion in 2025. The market is driven by rising scrap generation from construction and automotive sectors, expanding electric arc furnace steelmaking capacity, and tightening regional environmental regulations governing metal waste recovery.
The market grows at a 6.98% CAGR during 2026-2034, reaching USD 19.07 Billion by 2034. Non-ferrous metal grows fastest at ~7.9% CAGR through rising electronics and automotive-linked copper and aluminium recovery demand.
Ferrous metal leads at 68.4% through the region's large electric arc furnace steelmaking base, high construction rebar demand, and well-established ferrous scrap collection infrastructure.
Building and construction leads at 27.8% through sustained regional infrastructure and housing investment requiring high volumes of recycled reinforcing steel and structural sections.
Indonesia leads at 28.7% through its large domestic steel industry and continued electric arc furnace capacity expansion absorbing regional ferrous scrap supply.
Leading companies include Sims Limited, PT Gunung Raja Paksi Tbk, Alliance Steel (M) Sdn. Bhd.and BR Metals Pte. Ltd., among others.
The market is projected to reach approximately USD 14.30 Billion by 2030, with AI-based sorting technology achieving broader adoption among leading regional processors and electric arc furnace capacity expansion continuing across Indonesia, Vietnam, and Malaysia.
ASEAN circular economy frameworks and extended producer responsibility regulations are formalizing scrap collection across the region, pushing informal collectors toward registered recycling channels and improving feedstock traceability for processors and steelmakers.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade