
United States Data Governance Market Size, Share, Trends and Forecast by Component, Deployment Mode, Organization Size, Business Function, Application, End Use Industry, and Region, 2026-2034
United States Data Governance Market Size, Share, Trends & Forecast (2026-2034)
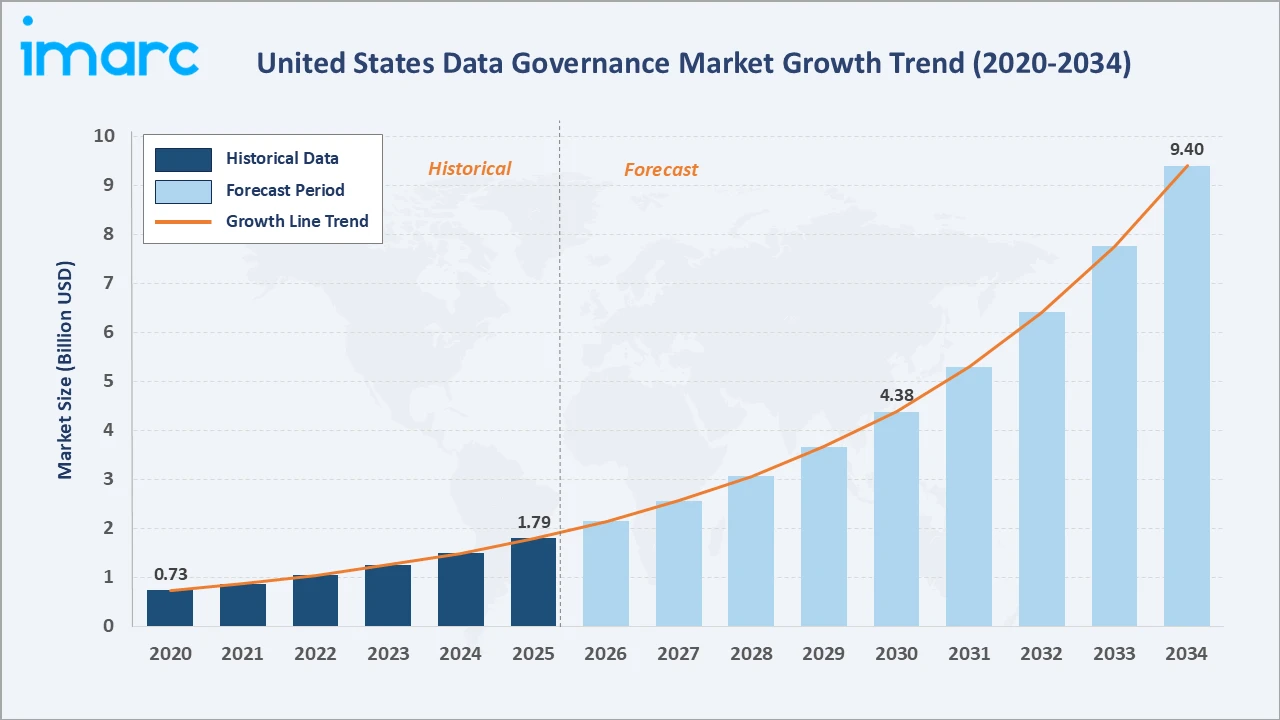
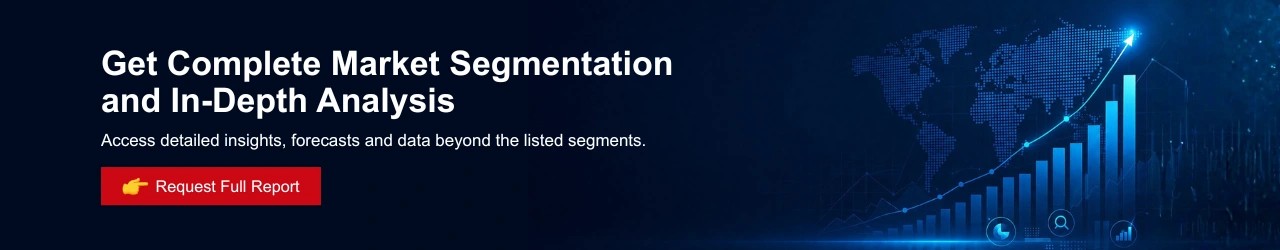
The United States data governance market reached USD 1.79 Billion in 2025 and is projected to reach USD 9.40 Billion by 2034, exhibiting an exceptional CAGR of 19.63% during 2026-2034. The US data governance market is propelled by the proliferation of state-level data privacy legislation, the generative AI revolution’s demand for high-quality and well-governed training data, and growing recognition. According to the Identity Theft Resource Center’s 2025 Annual Data Breach Report, the United States recorded 3,322 data compromises in 2025, setting a new all-time high and exceeding the previous record of 3,202 incidents in 2023. This sharp rise in data breaches is driving the market by increasing enterprise demand for stronger data classification, access controls, lineage, policy enforcement, privacy management, and regulatory compliance frameworks. Software leads the component at 62.8%, cloud-based deployment dominates at 68.5%, and the West region commands the largest share at 28.6%.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 1.79 Billion |
|
Forecast Market Size (2034) |
USD 9.40 Billion |
|
CAGR (2026-2034) |
19.63% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Component |
Software – 62.8% (2025) |
|
Dominant Deployment Mode |
Cloud-based – 68.5% (2025) |
|
Leading Region |
West – 28.6% (2025) |
The US data governance market grew from USD 0.73 Billion in 2020 to USD 1.79 Billion in 2025, driven by the COVID-19 pandemic’s data sprawl acceleration as remote work multiplied uncontrolled data generation across cloud platforms and the enterprise recognition that data governance is a prerequisite for AI and analytics trustworthiness. The market is projected to reach USD 4.38 Billion by 2030 and USD 9.40 Billion by 2034.
To get more information on this market, Request Sample
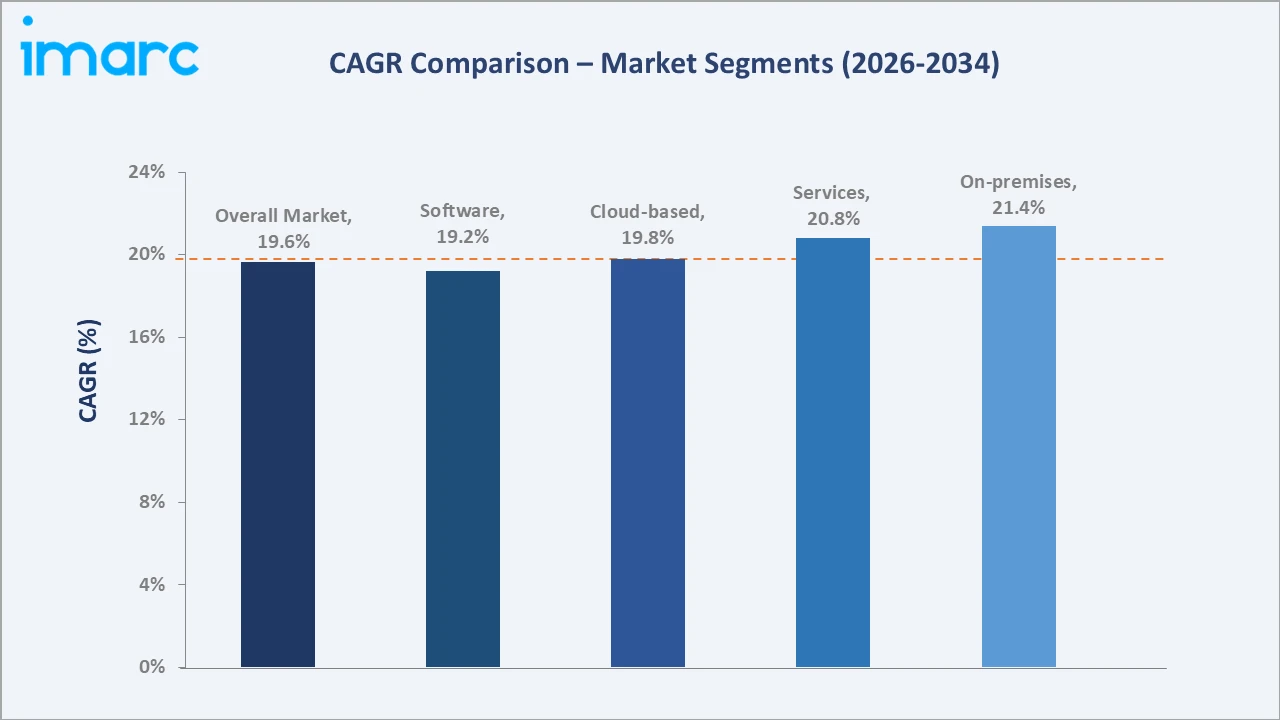
On-premises deployment grows fastest at ~21.40% CAGR through regulated industry demand for sovereign data control. Services component grows at ~20.80% CAGR through implementation consulting, managed governance, and integration services. Cloud-based deployment grows at ~19.80% CAGR through enterprise SaaS data governance platform adoption. The software component grows at ~19.20% CAGR through data catalog, lineage, and quality management platform expansion.
Executive Summary
The United States data governance market represents the enterprise technology sector’s most strategically critical investment category for the 2026-2034 period, where the convergence of three simultaneous structural forces is creating a compliance, competitive, and risk imperative for data governance investment that no enterprise with significant data assets can responsibly defer. The US market’s 19.63% CAGR reflects the transition from data governance as a specialized compliance tool to a foundational enterprise data infrastructure investment as essential as cybersecurity.
Software’s 62.8% component dominance reflects US enterprises’ preference for productized, scalable data governance platforms over purely service-delivered governance programs. Cloud-based deployment’s 68.5% market majority reflects the alignment between cloud data governance platforms and the cloud-native data environments where the majority of US enterprise data now resides, making cloud-native governance tools the default specification for greenfield data governance deployments. West’s 28.6% regional leadership reflects the geographic concentration of both data governance technology vendors and the technology-intensive enterprises that are among the earliest and largest data governance adopters.
Key Market Insights
|
Insight |
Data |
|
Dominant Component |
Software – 62.8% share (2025) |
|
Dominant Deployment Mode |
Cloud-based – 68.5% share (2025) |
|
Leading Region |
West – 28.6% share (2025) |
|
Market Opportunity |
Generative AI data trust and governance platform for LLM training data quality; healthcare PHI governance under HIPAA for cloud data lakes; financial services data lineage for SEC and OCC model risk reporting; SMB cloud-native data governance SaaS at accessible price points |
Key Analytical Observations:
- Software at 62.8% (2025): US enterprise data governance has progressively transitioned from policy documentation and manual stewardship processes to software-automated governance platforms that embed governance controls directly into data pipelines, analytics environments, and cloud data platforms. Data governance software encompasses four primary functional categories: data catalog and discovery, data lineage, data quality management, and policy and compliance management.
- Cloud-based Deployment at 68.5% (2025): Cloud-native data governance deployment encompasses SaaS data governance platforms accessed over the internet without on-premises infrastructure investment, cloud-deployed data governance software running in enterprise-managed environments, and hybrid architectures connecting cloud-based governance tools to on-premises data sources through API connectivity.
- West Region at 28.6% (2025): The West region leads the market, supported by a high concentration of technology companies, cloud service providers, and data-intensive enterprises. Strong adoption of AI, analytics, cybersecurity, and privacy management solutions further strengthens regional demand for data governance platforms.
United States Data Governance Market Overview
The United States data governance market encompasses software, platforms, and services used to manage the availability, quality, security, privacy, lineage, and compliance of enterprise data. It includes data cataloging, metadata management, master data management, policy enforcement, access governance, and regulatory compliance solutions. The market serves industries such as BFSI, healthcare, government, retail, telecommunications, and technology, where organizations manage large volumes of sensitive and business-critical data. Macroeconomic factors include strong enterprise digitalization, rising cloud and AI adoption, increasing cybersecurity spending, and stricter regulatory requirements around privacy and data management. Expanding public-sector digitization and modernization of the US e governance market are also increasing demand for secure, standardized, and compliant data governance frameworks.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
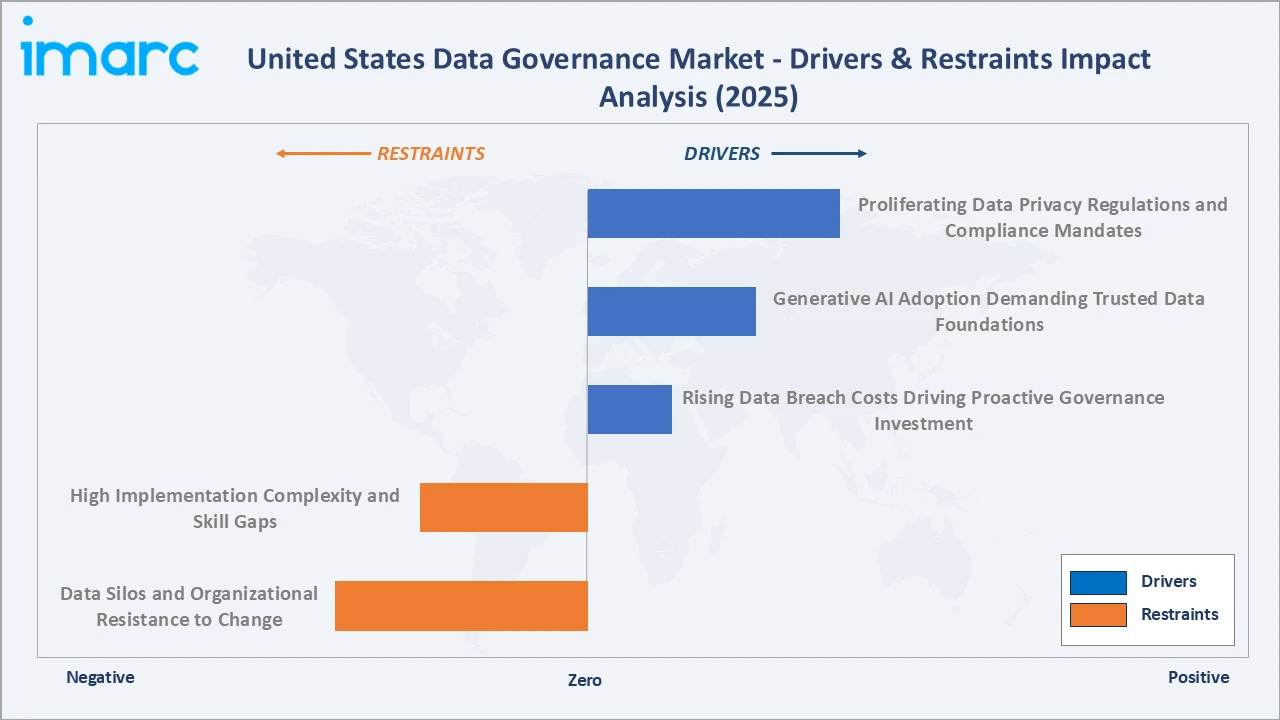
- Proliferating Data Privacy Regulations and Compliance Mandates: The US data governance market’s primary structural demand driver is the progressive legislative creation of enforceable data privacy rights across US states that require enterprises to maintain comprehensive data inventories, consent management records, and data subject access request fulfillment capabilities. In June 2026, Amazon agreed to pay USD 2.25 million in civil penalties to resolve Federal Trade Commission (FTC) allegations that it knowingly violated the Fair Credit Reporting Act (FCRA). The allegations centered on Amazon’s failure to provide transaction records to consumers whose personal information had been fraudulently used by identity thieves. Such enforcement encourages US enterprises to strengthen data governance, access controls, auditability, retention policies, and regulatory compliance systems, thereby driving demand for comprehensive data governance solutions.
- Generative AI Adoption Demanding Trusted Data Foundations: Rapid adoption of generative AI is driving the market as enterprises require accurate, consistent, secure, and well-governed data to produce reliable AI outputs. Generative AI applications increasingly access both structured and unstructured enterprise information, increasing requirements for data quality, lineage, metadata management, access controls, and privacy protection. Organizations are therefore strengthening governance frameworks to reduce data leakage, inaccurate outputs, and compliance risks. This growing need for AI-ready and trusted data foundations is accelerating investment in enterprise data governance platforms.
- Rising Data Breach Costs Driving Proactive Governance Investment: The average cost of a data breach in the United States reached a record high of USD 10.22 million in 2026. Enterprises are therefore investing more heavily in data classification, access governance, lineage, quality management, and policy enforcement. Proactive governance helps identify sensitive data, strengthen accountability, and reduce breach exposure. This is accelerating demand for comprehensive data governance platforms across the United States.
Market Restraints
- High Implementation Complexity and Skill Gaps: Implementing enterprise-wide data governance can be complex due to fragmented data environments, legacy systems, multiple cloud platforms, and inconsistent data ownership practices. Organizations also face shortages of professionals skilled in data stewardship, metadata management, compliance, and governance technologies. These challenges increase deployment costs, extend implementation timelines, and can slow adoption of advanced data governance solutions.
- Data Silos and Organizational Resistance to Change: Fragmented data across departments, legacy systems, and multiple cloud environments makes it difficult for organizations to establish consistent data definitions, ownership, quality, and governance policies. Resistance from employees and business units to new governance processes can further slow implementation. These challenges increase integration costs, delay enterprise-wide governance initiatives, and hamper growth of the United States data governance market.
Market Opportunities
- AI Governance Platform Integration: Integrating AI governance capabilities with existing data governance platforms creates an opportunity to manage data quality, lineage, access controls, AI models, agents, and compliance within unified frameworks. Such integration enables enterprises to apply consistent policies and oversight throughout the AI lifecycle while improving auditability and risk management. This creates opportunities for data governance vendors to expand into rapidly growing enterprise AI governance requirements.
- SMB Cloud-Native Governance SaaS: Cloud-native data governance SaaS creates an opportunity to serve small and medium-sized businesses (SMBs) that often lack the budgets and specialized teams required for complex enterprise governance programs. Scalable subscription-based solutions can provide automated data discovery, access controls, quality management, security, and compliance with lower infrastructure and implementation requirements. This can expand the addressable market for governance vendors as SMBs increasingly adopt cloud applications, analytics, and AI.
Market Challenges
- Balancing Data Accessibility with Security: Organizations must make enterprise data readily available for analytics, AI, and business decision-making while protecting sensitive information. Excessively restrictive governance can reduce productivity, whereas insufficient controls increase privacy and cybersecurity risks. Achieving the appropriate balance between data democratization and security remains a major challenge.
- Maintaining Data Quality for AI Applications: The expansion of generative AI increases the importance of accurate, complete, consistent, and traceable enterprise data. Poor-quality or outdated datasets can contribute to unreliable AI outputs and weak business decisions. Organizations therefore face growing challenges in continuously monitoring, cleansing, validating, and governing AI-ready data.
Emerging Market Trends
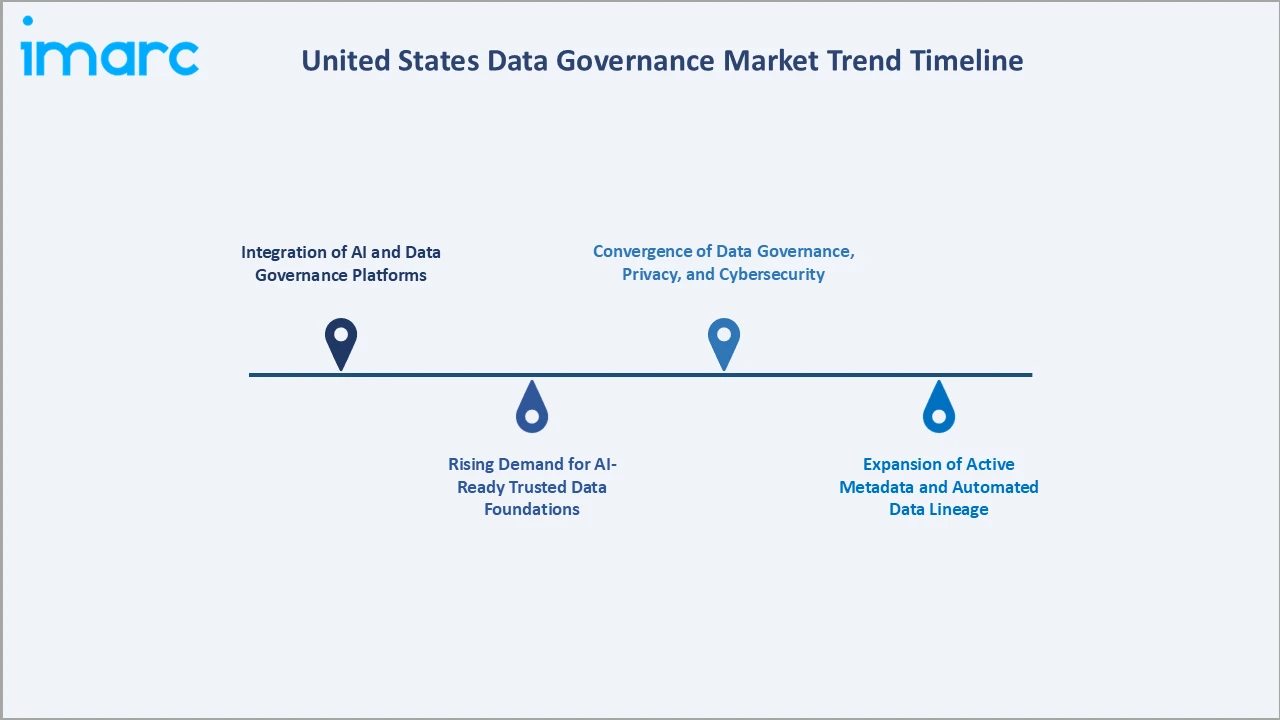
1. Integration of AI and Data Governance Platforms
Enterprises are increasingly integrating AI governance with traditional data governance frameworks to manage data, models, agents, and automated decisions through unified environments. In August 2026, AI/R launched AI/Cockpit One, a centralized platform designed to manage enterprise-wide AI access, security, observability, and governance. The platform acts as a unified hub connecting AI/R’s AI/Cockpit development modules with internally developed tools and third-party platforms such as Langflow, Flowise, and n8n, helping organizations coordinate and govern increasingly complex AI ecosystems. Continuous monitoring is also replacing periodic governance reviews. This convergence is expanding the scope of enterprise governance platforms.
2. Rising Demand for AI-Ready Trusted Data Foundations
Organizations are shifting their focus toward making enterprise data accurate, accessible, contextualized, and trustworthy for generative AI and analytics. Data fragmentation and inadequate metadata can prevent AI projects from progressing beyond pilot stages. Consequently, enterprises are strengthening data quality, semantic layers, metadata management, and governance controls. Unified access to structured and unstructured data is also gaining importance. Trusted data foundations are becoming essential infrastructure for enterprise AI deployment.
3. Expansion of Active Metadata and Automated Data Lineage
Data governance is moving beyond static catalogs toward platforms that continuously capture metadata and track how information moves across enterprise systems. Automated lineage provides visibility into data origins, transformations, dependencies, ownership, and downstream usage. This improves impact analysis, troubleshooting, compliance, and data quality management. Lineage is also expanding to connect AI models with the datasets used for training and evaluation. This is strengthening end-to-end governance across data and AI lifecycles.
4. Convergence of Data Governance, Privacy, and Cybersecurity
Enterprises are increasingly treating governance, privacy, and cybersecurity as interconnected functions rather than separate initiatives. AI adoption creates additional risks involving sensitive-data exposure, excessive access, oversharing, and inappropriate AI usage. Organizations are therefore combining classification, access controls, privacy policies, security monitoring, and governance processes. Greater collaboration among data, security, and compliance teams is becoming essential. This convergence supports demand for integrated governance and security platforms.
Industry Value Chain Analysis
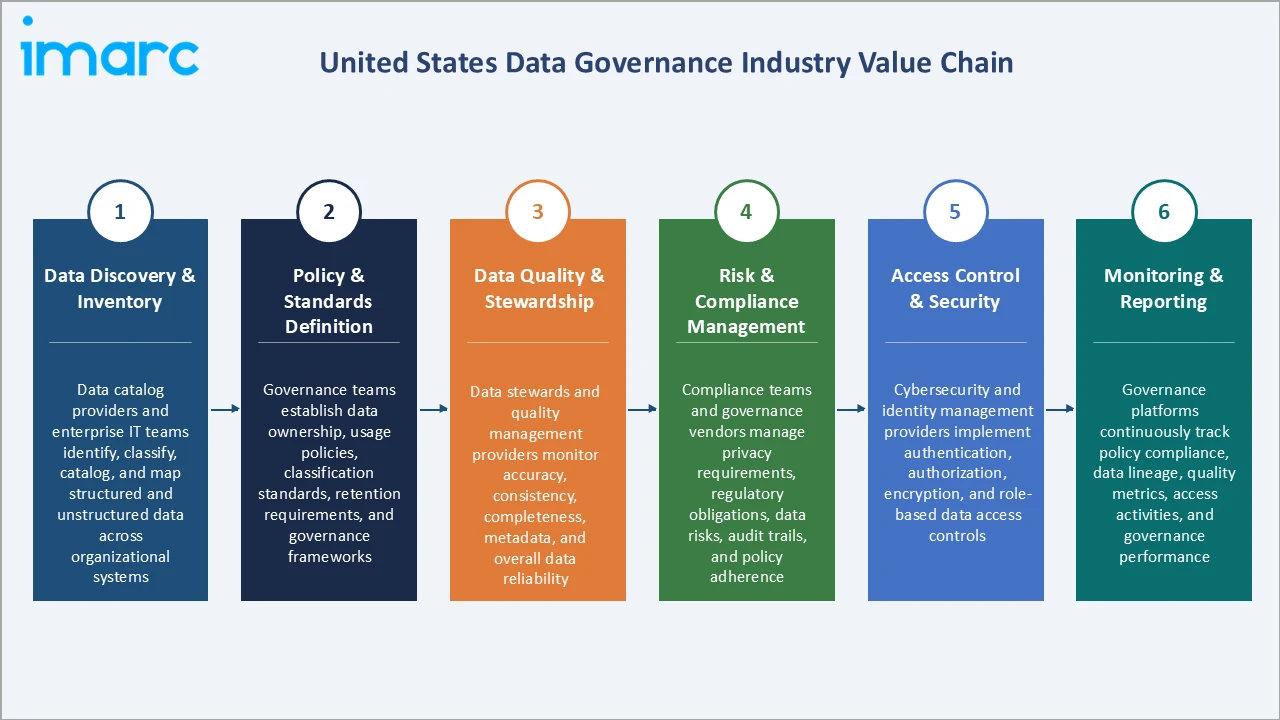
The US data governance value chain integrates data discovery and inventory, policy and standards governance, data quality and stewardship, risk and compliance management, access control and security, and monitoring and reporting into a continuous governance lifecycle that requires coordinated technology, process, and organizational capability investment.
|
Stage |
Key Participants |
|
Data Discovery & Inventory |
Data catalog providers and enterprise IT teams identify, classify, catalog, and map structured and unstructured data across organizational systems. |
|
Policy & Standards Definition |
Governance teams establish data ownership, usage policies, classification standards, retention requirements, and governance frameworks. |
|
Data Quality & Stewardship |
Data stewards and quality management providers monitor accuracy, consistency, completeness, metadata, and overall data reliability. |
|
Risk & Compliance Management |
Compliance teams and governance vendors manage privacy requirements, regulatory obligations, data risks, audit trails, and policy adherence. |
|
Access Control & Security |
Cybersecurity and identity management providers implement authentication, authorization, encryption, and role-based data access controls. |
|
Monitoring & Reporting |
Governance platforms continuously track policy compliance, data lineage, quality metrics, access activities, and governance performance. |
Risk & compliance management represents the most value-added stage in the United States data governance value chain, as it converts governance policies into actionable controls for managing regulatory, privacy, and operational risks. This stage combines compliance automation, data lineage, policy enforcement, auditability, and risk assessment. Its ability to reduce regulatory exposure and strengthen enterprise accountability generates significant strategic value for organizations.
Technology Landscape in the United States Data Governance Industry
Automated Data Lineage Technology
Data lineage technology automatically tracks how information originates, moves, transforms, and is consumed across enterprise systems. It provides visibility into upstream sources and downstream dependencies, helping organizations assess the impact of data changes. Column-level lineage can strengthen regulatory compliance and sensitive-data governance. Automated lineage also improves troubleshooting and auditability. Growing AI adoption is increasing the importance of traceable data provenance.
Data Quality and Observability Technology
Data quality technologies continuously assess information for accuracy, completeness, consistency, validity, and freshness. Data observability extends these capabilities by monitoring data pipelines and identifying anomalies or unexpected changes. Automated alerts enable organizations to address quality issues before they affect analytics or AI applications. Quality metrics can also be integrated into enterprise data catalogs. These technologies are becoming critical for establishing trusted, AI-ready data foundations.
Master Data Management (MDM) Technology
Master data management technology creates consistent and trusted records for critical business entities such as customers, products, suppliers, and locations. MDM platforms integrate, standardize, match, and reconcile information originating from multiple systems. This reduces duplication and inconsistent definitions across organizations. Modern governance suites increasingly combine MDM with data quality, catalogs, and reference data management. The technology strengthens enterprise-wide data consistency and decision-making.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Component |
Software |
62.8% |
2025 |
|
Deployment Mode |
Cloud-based |
68.5% |
2025 |
|
Organization Size |
🔒 |
🔒 |
2025 |
|
Business Function |
🔒 |
🔒 |
2025 |
|
Application |
🔒 |
🔒 |
2025 |
|
End Use Industry |
🔒 |
🔒 |
2025 |
|
Region |
West |
28.6% |
2025 |
By Component
Software leads at 62.8% (2025) through enterprise data catalog, lineage, quality management, and policy enforcement platform adoption at scale.
To access detailed market analysis, Request Sample
Services at 37.2%, growing fastest at ~20.80% CAGR, through implementation consulting, managed governance, and organizational change management services demand that software procurement consistently generates.
By Deployment Mode
Cloud-based leads at 68.5% (2025) through SaaS data governance platform adoption aligned to US enterprise cloud-first data architecture.
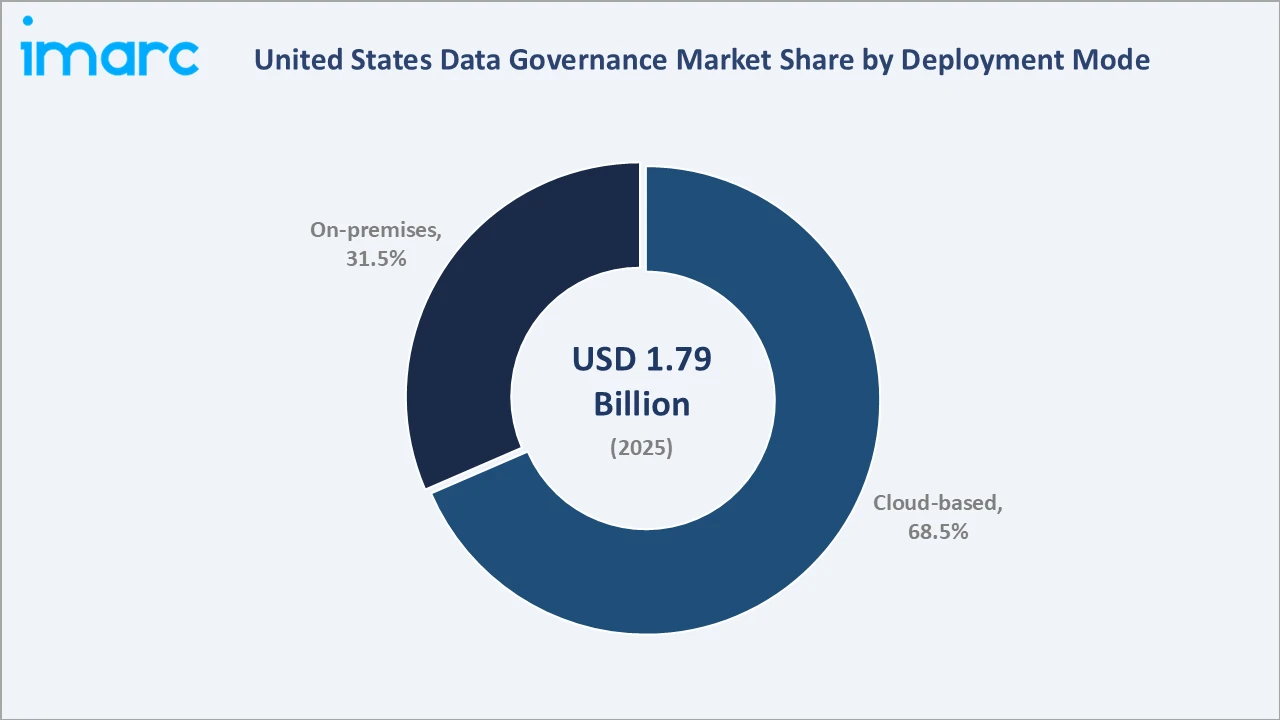
On-premises at 31.5%, growing fastest at ~21.40% CAGR, through regulated industry sovereign data governance requirements and US federal agency-compliant deployment mandates.
Regional Market Insights
|
Region |
Share (2025) |
Key US Data Governance Market Drivers & Characteristics |
|
West |
28.6% |
Leads due to a strong technology ecosystem, high cloud and AI adoption, and stringent privacy requirements supporting advanced data governance deployment. |
|
South |
27.4% |
Supported by expanding data center infrastructure, enterprise digitalization, and growing adoption of cloud-based data management and compliance solutions. |
|
Northeast |
23.8% |
Strong BFSI, healthcare, and enterprise activity supports demand for data quality, privacy, security, and regulatory compliance solutions. |
|
Midwest |
20.2% |
Growing data center investment, cloud adoption, and digital transformation across manufacturing and other industries support governance requirements. |
West region leads with a 28.6% share in 2025, supported by strong technology adoption, cloud migration, AI deployment, and stringent data privacy requirements. The South accounts for 27.4%, driven by expanding digital infrastructure, enterprise modernization, and growing data center activity.
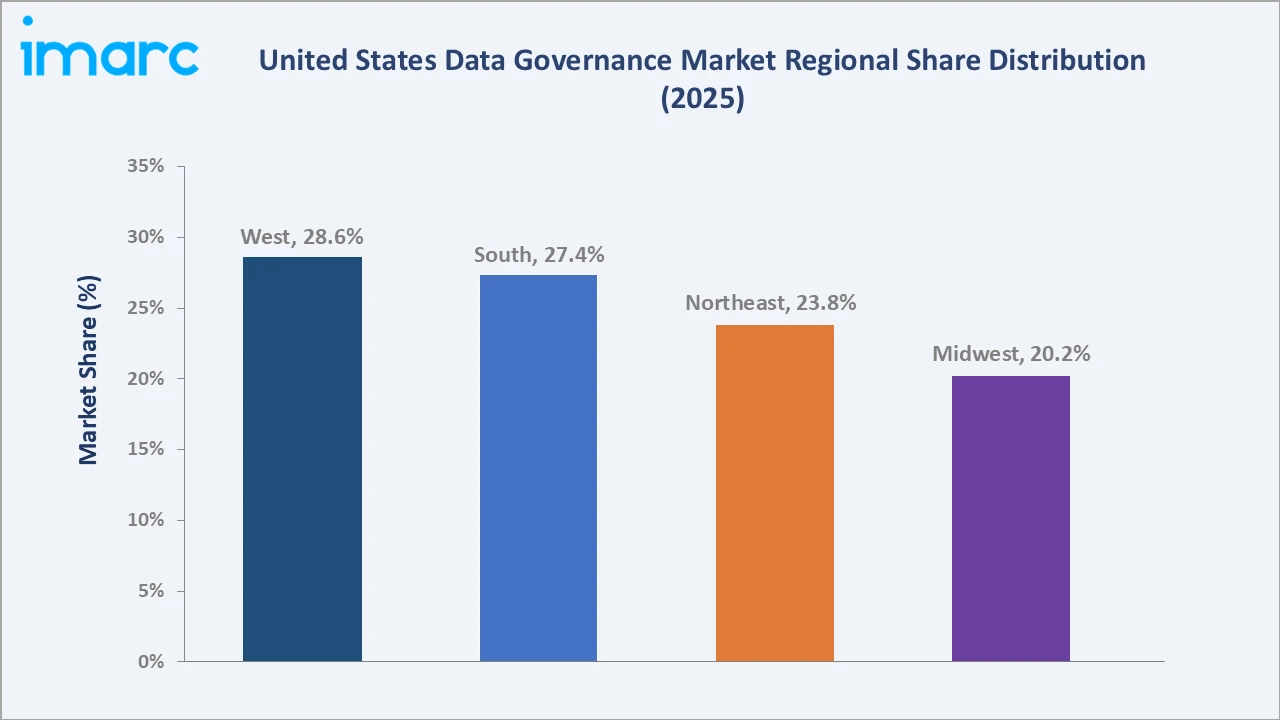
The Northeast holds 23.8%, benefiting from significant demand across BFSI, healthcare, professional services, and other highly regulated industries. The Midwest represents 20.2%, supported by digital transformation across manufacturing, healthcare, and financial services.
Competitive Landscape
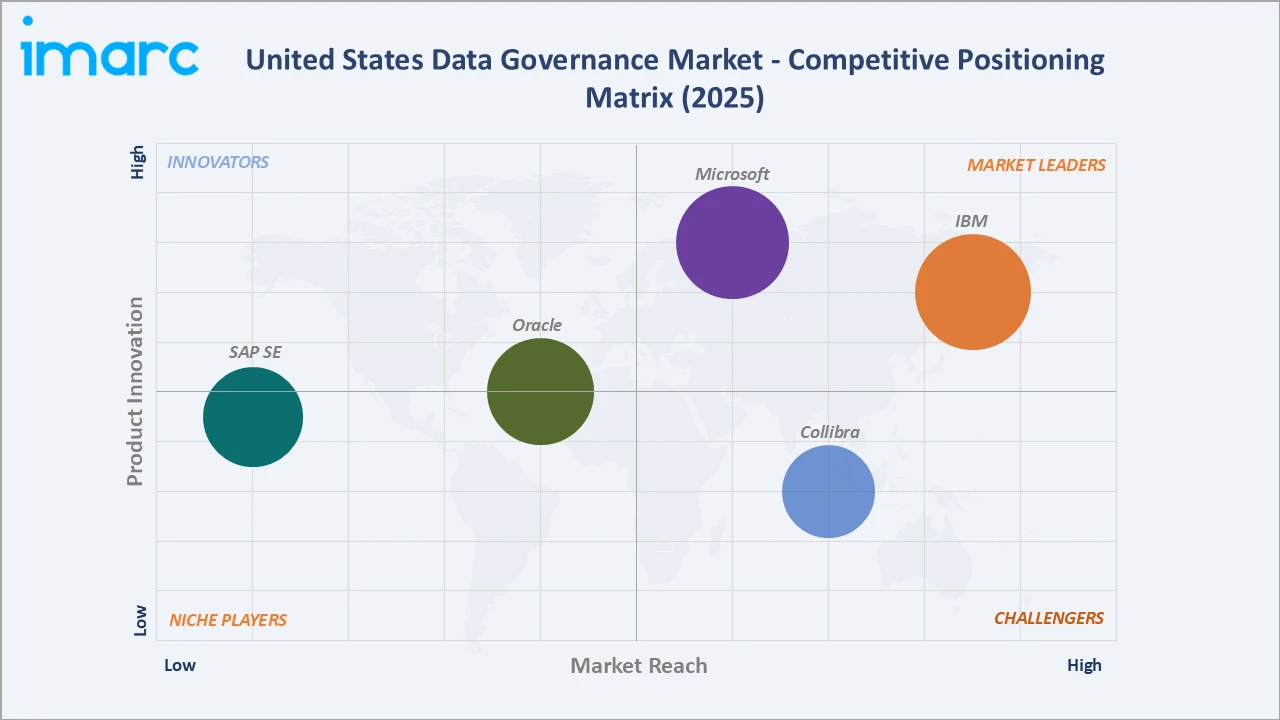
The United States data governance market is moderately concentrated, comprising large enterprise technology vendors and specialized governance platform providers. Competition centers on AI-enabled governance, automated data lineage, metadata management, data quality, regulatory compliance, and multi-cloud integration, with vendors increasingly enhancing platforms to support trusted enterprise AI and agentic applications.
|
Company |
Key Products |
Market Position |
Core Strength |
|
IBM |
IBM watsonx.governance, IBM Guardium Data Protection, IBM watsonx.data intelligence |
Market Leader |
IBM shapes United States data governance by providing the enterprise software and policy frameworks necessary to maintain data integrity, security, and privacy. |
|
Microsoft |
Microsoft Purview Data Governance |
Market Leader |
Microsoft drives US data governance by providing the enterprise technology stack that enforces compliance, privacy, and security. |
|
Oracle |
Oracle Enterprise Metadata Management |
Established Player |
Oracle serves as a critical technological backbone for United States data governance by providing the software, cloud infrastructure, and regulatory compliance tools. |
|
SAP SE |
SAP Master Data Governance |
Established Player |
SAP SE facilitates United States data governance by providing enterprise software that automates compliance, unifies data sources, and enforces data quality standards. |
|
Collibra |
Collibra Platform |
Challenger |
It enables organizations to discover, catalog, and govern data assets while integrating with AI to automate metadata generation and enforce cross-enterprise policies. |
The US data governance competitive landscape is undergoing a structural consolidation from vendors toward platform ecosystem competition for the business-user-centric and modern data stack governance segments where the hyperscaler platforms are less optimized.
Key Company Profiles
IBM
IBM is a technology and consulting company with core capabilities spanning hybrid cloud, artificial intelligence, data management, automation, cybersecurity, and enterprise infrastructure. Within the United States data governance market, IBM provides an integrated portfolio led by watsonx.data intelligence, watsonx.governance, and IBM Guardium. Its solutions support data cataloging, metadata management, data quality, lineage, privacy, policy enforcement, access controls, and regulatory compliance across hybrid and multi-cloud environments. IBM increasingly combines data and AI governance, enabling enterprises to establish trusted, governed data foundations for analytics and generative AI applications.
- Key Products: IBM watsonx.governance, IBM Guardium Data Protection, IBM watsonx.data intelligence.
- Strategic Focus: Creating an AI-native, unified governance environment through its watsonx portfolio. The company is strengthening watsonx.data intelligence to integrate data cataloging, quality, lineage, metadata management, and policy controls while connecting these capabilities with watsonx.governance for AI oversight.
Microsoft
Microsoft is a technology company with operations spanning cloud computing, artificial intelligence, enterprise software, cybersecurity, data management, and productivity solutions. Within the United States data governance market, the company provides Microsoft Purview, a unified portfolio covering data governance, data security, and compliance. Purview’s key governance capabilities include Unified Catalog and Data Map, which support metadata management, data discovery, data quality, lineage, classification, and governed access across enterprise data environments.
- Key Products: Microsoft Purview Data Governance.
- Strategic Focus: Expanding Microsoft Purview as a unified, AI-powered platform for data governance, security, risk, and compliance. The company is strengthening Unified Catalog and Data Map to improve metadata management, data discovery, quality, lineage, and governed access across hybrid and multi-cloud environments.
Market Concentration Analysis
The United States data governance market is moderately concentrated, with established enterprise technology vendors and specialized governance providers competing for market share. Competition centers on AI-enabled governance, metadata management, data lineage, quality, privacy, compliance, and multi-cloud integration. High integration complexity, regulatory expertise requirements, and enterprise switching costs create meaningful barriers to entry. However, specialized vendors continue to compete through AI governance, automated data discovery, and cloud-native offerings. Growing generative AI adoption is likely to intensify competition as enterprises seek unified platforms capable of governing both traditional data and AI workloads.
Investment & Growth Opportunities
Highest Growth Segments
On-premises deployment (~21.40% CAGR) and services component (~20.80% CAGR) represent the US data governance market’s highest-growth investment vectors through 2034, driven by defense and regulated industry sovereign governance deployment and the professional services demand generated by enterprise software governance platform procurement.
Investment Themes
- AI Governance Data Platform: Investment in AI governance data platforms offers opportunities as enterprises seek unified solutions for governing data, AI models, and increasingly agentic AI systems. Platforms combining data lineage, model monitoring, policy enforcement, risk management, and compliance automation can become critical infrastructure for responsible enterprise AI deployment.
- Mid-Market Cloud-Native Governance SaaS: Investment in cloud-native governance SaaS for mid-market companies offers strong potential as subscription-based platforms reduce upfront infrastructure costs and simplify deployment. Scalable solutions providing automated cataloging, data quality, compliance, and policy management can enable mid-sized businesses to implement enterprise-grade governance without large, specialized teams.
Future Market Outlook (2026-2034)
The United States data governance market is projected to grow from USD 1.79 Billion in 2025 to USD 9.40 Billion by 2034, delivering an exceptional 19.63% CAGR that positions US data governance as one of the enterprise technology sector’s highest-conviction growth investment categories for the next decade, driven by the irreversible convergence of regulatory mandate expansion, generative AI data quality imperative, and enterprise data breach cost escalation that collectively create multi-path demand for governance investment that no single regulatory or competitive event can reverse. The midpoint anchor of USD 4.38 Billion in 2030 confirms the structural consistency of US data governance market growth across economic cycles and technology generations.
First, the US data privacy regulatory landscape’s progressive expansion to a comprehensive national patchwork of state-level privacy laws is creating governance compliance obligations that will reach virtually every US enterprise with national consumer or employee data. Second, the generative AI enterprise adoption wave is creating an unprecedented data quality and data governance demand driver that is specifically motivating executive-level governance investment outside the traditional compliance budget cycle. Third, US enterprise cybersecurity investment’s progressive convergence with data governance is creating a new data governance investment motivation that is funded from cybersecurity budget rather than data management budget, effectively doubling the enterprise buyer universe for data security governance platforms.
Research Methodology
Primary Research
Primary research comprised in-depth interviews with data governance platform product leadership, chief data officers and chief data and analytics officers across BFSI, healthcare, retail, and technology sectors, data governance program managers implementing compliance automation, governance programs, and data controls, data governance consultants, and enterprise data governance technology buyers across the West, South, Northeast, and Midwest regions.
Secondary Research
Secondary research encompassed a review of government publications, regulatory documents, company reports, industry associations, technology white papers, academic studies, and market databases. The analysis also covered data privacy regulations, cybersecurity trends, cloud adoption, AI governance developments, enterprise data management practices, and competitive activity across the United States data governance market.
Forecasting Models
Forecasting models were developed using historical US data governance market data (2020-2025), state privacy law adoption rate trajectory, government and commercial adoption rate modeling, US enterprise AI investment correlation with data governance platform procurement, SEC cybersecurity disclosure rule data governance investment trigger modeling, cloud data platform adoption growth, and US data breach cost trajectory impact on proactive governance investment ROI calculation.
United States Data Governance Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report | Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Components Covered | Software, Services |
| Deployment Modes Covered | Cloud-based, On-premises |
| Organization Sizes Covered | Small and Medium-sized Enterprises (SMEs), Large Enterprises |
| Business Functions Covered | Operation and IT, Legal, Finance, Sales and Marketing, Others |
| Applications Covered | Incident Management, Process Management, Risk and Compliance Management, Audit Management, Data Quality and Security Management, Others |
| End Use Industries Covered | IT and Telecom, Healthcare, Retail, Defense, BFSI, Others |
| Regions Covered | Northeast, Midwest, South, West |
| Conmpanies Covered | IBM, Microsoft, Oracle, SAP SE, Collibra, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the United States data governance market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the United States data governance market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the United States data governance industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the United States Data Governance Market Report
The United States data governance market reached USD 1.79 Billion in 2025, driven by rising data privacy regulations, increasing cybersecurity risks, and growing enterprise adoption of cloud, analytics, and AI technologies. Expanding demand for data quality, lineage, access governance, compliance automation, and trusted AI-ready data foundations further supported market growth.
The market grows at 19.63% CAGR, reaching USD 9.40 Billion by 2034, supported by expanding AI adoption, stricter data privacy requirements, and rising cybersecurity risks. Increasing enterprise investment in automated governance, data quality, lineage, compliance, and AI-ready data foundations will further accelerate market growth
Software leads at 62.8% (2025) through enterprise data catalog, lineage, quality management, and policy enforcement platform adoption.
Cloud-based leads at 68.5% (2025) through SaaS governance platform alignment with cloud-native enterprise data environments where the majority of new US enterprise analytics investment is concentrated.
West leads at 28.6% through California’s enforcement creating the US market’s most active state privacy compliance investment mandate, Silicon Valley data governance vendor concentration, and technology company data governance demand.
Leading companies include IBM, Microsoft, Oracle, SAP SE, and Collibra, among others.
The market is projected to reach USD 4.38 Billion by 2030, driven by accelerating enterprise AI adoption, expanding cloud and multi-cloud environments, and stricter privacy and compliance requirements. Rising demand for automated data discovery, lineage, quality management, access governance, and AI governance platforms will further support market expansion.
Top US data governance investment opportunities include AI governance data platforms, SMB cloud-native governance SaaS, privacy compliance automation for state law patchwork, healthcare AI governance for AI training data, and federal government data governance SaaS.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade