India Dry Type Transformer Market Size, Share, Trends and Forecast by Voltage, Application, and Region, 2026-2034
India Dry Type Transformer Market Size, Share, Trends & Forecast (2026-2034)
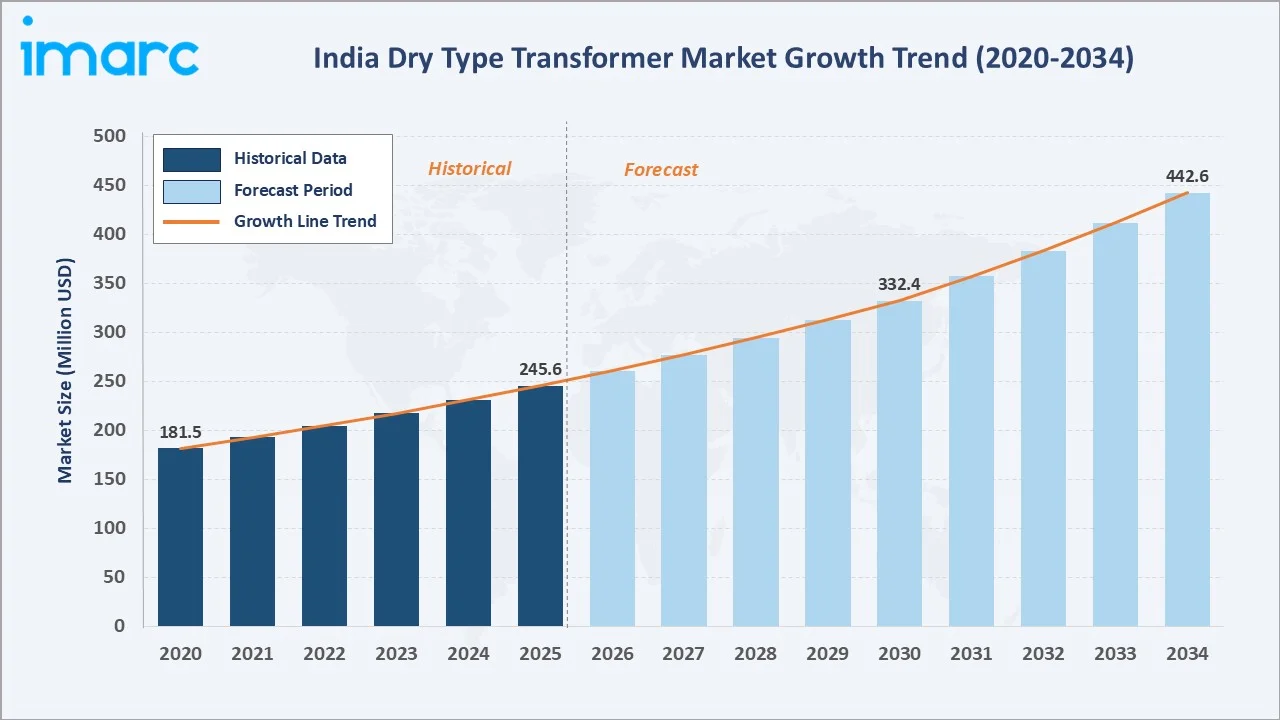
The India dry type transformer market reached USD 245.6 Million in 2025 and is projected to reach USD 442.6 Million by 2034, growing at a CAGR of 6.24% during 2026-2034. Growth is driven by rising investments in renewable energy projects, expanding data center infrastructure, and stricter fire-safety regulations favoring oil-free power distribution equipment. Utilities and industrial facilities are increasingly replacing conventional oil-immersed units with dry type transformers to minimize fire risk and reduce maintenance needs. Medium Voltage leads the voltage segment at 47.0% share, reflecting widespread deployment across industrial plants and utility substations. Industrial application dominates at 42.0%, while West India commands the largest regional share at 34.0%, supported by concentrated manufacturing and infrastructure activity.
Market Snapshot
|
Metric |
Value |
|
Market Size (2025) |
USD 245.6 Million |
|
Forecast Market Size (2034) |
USD 442.6 Million |
|
CAGR (2026-2034) |
6.24% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Dominant Voltage |
Medium Voltage (47.0%, 2025) |
|
Dominant Application |
Industrial (42.0%, 2025) |
|
Leading Region |
West India (34.0%, 2025) |
The market expanded from an estimated USD 181.5 Million in 2020 to USD 245.6 Million in 2025, supported by steady grid expansion and industrial power demand. Growth is anchored at USD 332.4 Million by 2030 and is forecast to reach USD 442.6 Million by 2034. Sustained investment in renewable energy integration and data center construction is expected to keep demand on a consistent upward trajectory through the forecast period.
To get more information on this market, Request Sample
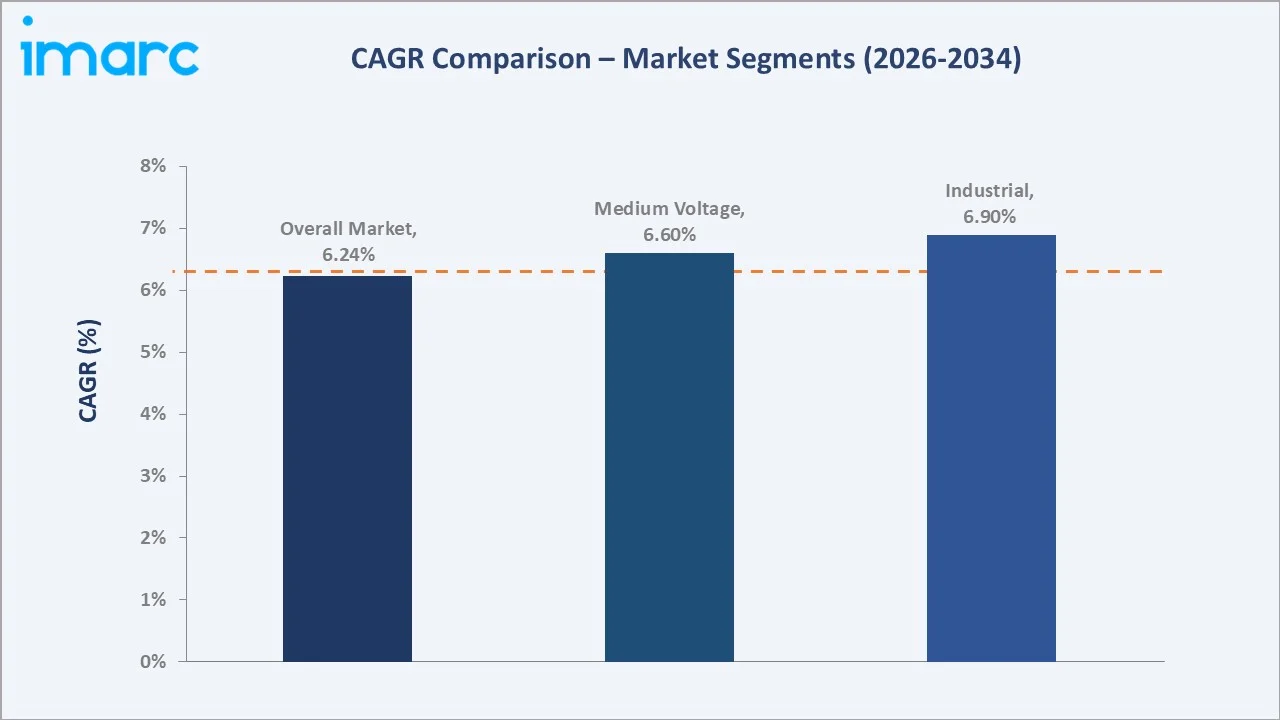
Medium Voltage transformers are estimated to grow at approximately 6.6% CAGR through 2034, ahead of the overall market, as utilities and industrial units scale up distribution capacity. The Industrial application segment is projected to expand at approximately 6.9% CAGR, outpacing the market average, driven by manufacturing expansion, data center construction, and rising factory electrification across India.
Executive Summary
The India dry type transformer market reached USD 245.6 Million in 2025, reflecting the country's shift toward safer, oil-free power distribution equipment amid rapid industrialization and renewable energy expansion. Dry type transformers are increasingly preferred in server rooms, hospitals, metro systems, and solar and wind installations for their fire resistance, low maintenance, and compact indoor-suitable design. The market is projected to reach USD 442.6 Million by 2034.
Medium Voltage at 47.0% dominates by serving industrial plants, commercial buildings, and utility substations requiring reliable mid-range power distribution. Industrial application at 42.0% leads through expanding manufacturing capacity, data center construction, and factory electrification. West India at 34.0% leads regionally through its concentrated industrial base, infrastructure development, and renewable energy project pipeline.
Key Market Insights
|
Insight |
Data |
|
Dominant Voltage |
Medium Voltage - 47.0% share (2025) |
|
Dominant Application |
Industrial - 42.0% market share (2025) |
|
Leading Region |
West India - 34.0% market share (2025) |
|
Market Opportunity |
Data center power infrastructure; renewable energy microgrids; smart-grid monitoring-enabled transformers; oil-free retrofits in urban buildings |
Key Analytical Observations Supporting the Above Data:
- Medium Voltage at 47.0%: Medium Voltage transformers dominate by offering the optimal balance of capacity and safety for industrial plants, commercial complexes, and utility substations. Their widespread deployment in factories and mid-sized infrastructure projects, combined with growing preference for oil-free equipment, continues to strengthen segment demand across India.
- Industrial at 42.0%: The industrial segment leads due to expanding manufacturing capacity, factory electrification, and rising data center construction across India. Industrial facilities increasingly adopt dry type transformers for their fire safety, low maintenance, and reliable power distribution, supporting continuous demand from process industries and manufacturing hubs.
- West India at 34.0%: West India dominates through its concentrated industrial base, well-developed infrastructure, and a strong pipeline of renewable energy and data center projects. The region's advanced power distribution network further reinforces its lead in dry type transformer demand.
India Dry Type Transformer Market Overview
The India dry type transformer market encompasses the design, manufacture, and supply of oil-free power distribution transformers used across industrial, commercial, utility, and infrastructure applications nationwide. The ecosystem integrates raw material suppliers of electrical steel and insulation resins, transformer core and winding manufacturers, testing and certification bodies, utility and industrial end users, and regulatory authorities setting fire-safety and energy-efficiency standards. Macroeconomic factors including rising electricity demand, urbanization, renewable energy targets, and government-led infrastructure programs continue to shape ecosystem-wide investment and capacity expansion decisions.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
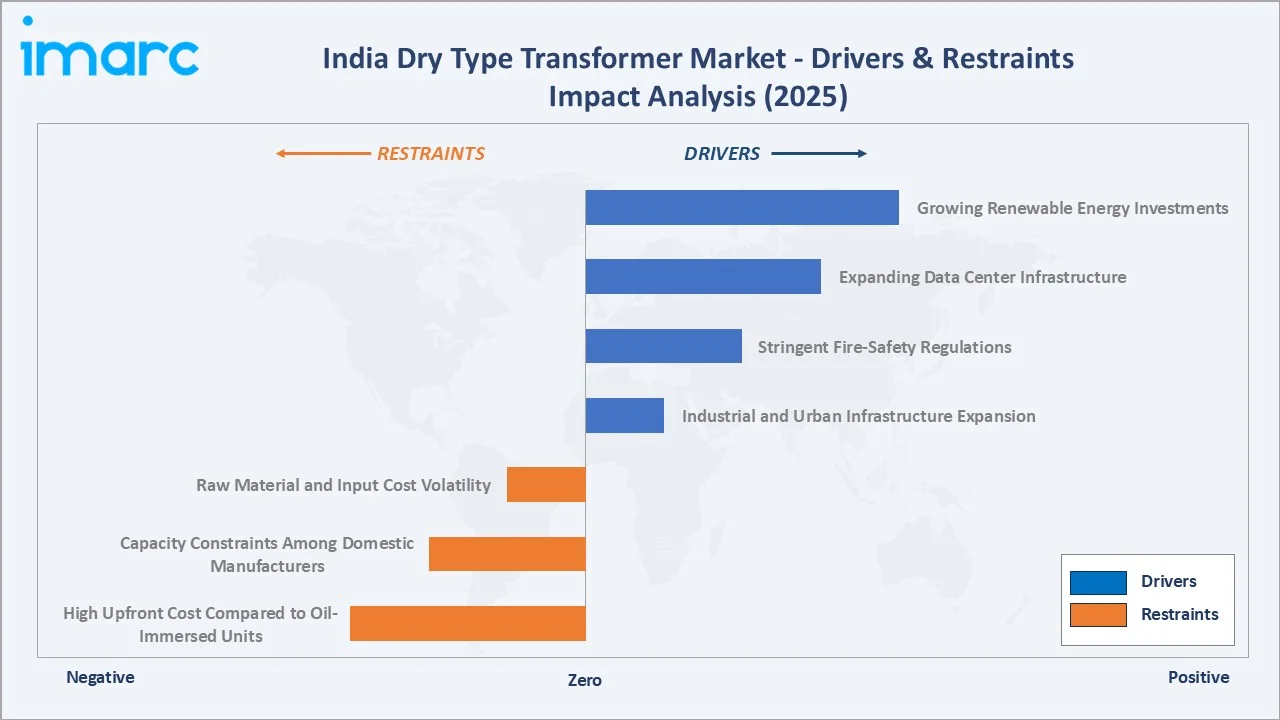
- Growing Renewable Energy Investments: Rising investments in solar, wind, and hybrid renewable energy projects are driving demand for fire-safe, oil-free transformers suited for inverter stations and substations. As India expands solar parks, wind farms, and battery storage capacity, developers increasingly specify dry type transformers to minimize fire risk at renewable generation sites. Government-backed renewable capacity targets and rising private investment in clean energy infrastructure are expected to sustain steady transformer procurement through the forecast period.
- Expanding Data Center Infrastructure: India's growing data center footprint, driven by cloud adoption, digitalization, and data localization mandates, is boosting demand for dependable, low-maintenance power distribution equipment. Hyperscale and edge data center operators are prioritizing dry type transformers within server rooms and power distribution units to safeguard sensitive IT equipment and maintain uninterrupted operations. Continued expansion of cloud services and enterprise data storage facilities across major Indian cities is expected to keep data center-linked transformer demand on a consistent growth path.
- Stringent Fire-Safety Regulations: Government and utility mandates promoting oil-free equipment in high-occupancy, fire-sensitive facilities are accelerating adoption of dry type transformers over conventional oil-immersed units. Updated safety codes for hospitals, metro systems, and commercial complexes increasingly favor equipment that eliminates the fire and environmental risks associated with insulating oil. As enforcement of fire-safety norms strengthens across urban and industrial zones, facility owners are proactively replacing aging oil-immersed units with dry type alternatives.
- Industrial and Urban Infrastructure Expansion: Rapid industrialization, urban infrastructure development, and expansion of manufacturing capacity across India are increasing demand for reliable indoor power distribution equipment. Dry type transformers' compact, space-efficient design makes them well-suited for factories, commercial buildings, and space-constrained urban installations where oil-immersed units are impractical. Continued investment in industrial corridors, smart city projects, and metro rail expansion is expected to generate sustained demand for indoor-rated transformer capacity.
Market Restraints
- High Upfront Cost Compared to Oil-Immersed Units: Dry type transformers typically carry a higher initial purchase cost than conventional oil-immersed alternatives, which can deter price-sensitive buyers in cost-constrained segments. This cost differential can slow adoption among smaller industrial and commercial users despite the long-term safety and maintenance benefits offered by dry type units. Budget-constrained public sector and small-scale infrastructure projects may continue to favor lower-cost oil-immersed transformers where fire-safety regulations permit their use.
- Capacity Constraints Among Domestic Manufacturers: Limited local production capacity for large-rating dry type transformers can create supply bottlenecks amid rising demand from utilities and data centers. Extended lead times and dependence on imported components for select ratings can delay project execution and raise procurement costs for large infrastructure developers. Manufacturers are gradually investing in capacity expansion, but near-term supply constraints may continue to affect large-scale utility and data center project timelines.
- Raw Material and Input Cost Volatility: Fluctuating prices of electrical steel, copper, and insulation resins used in transformer manufacturing can compress manufacturer margins and affect pricing stability. This volatility can also disrupt production planning and delay capacity expansion among small and mid-sized transformer manufacturers operating on thinner margins. Manufacturers reliant on imported raw materials face additional exposure to currency fluctuations and global commodity price swings that can affect cost competitiveness.
Market Opportunities
- Retrofit and Replacement Demand in Urban Buildings: Aging oil-immersed transformer installations in urban commercial and residential-adjacent buildings present a significant retrofit opportunity for dry type equipment upgrades. Facility owners seeking to comply with updated fire-safety codes are increasingly evaluating phased replacement programs for legacy oil-immersed transformers. This retrofit opportunity is particularly strong in densely built urban centers where fire-safety compliance and space constraints favor oil-free equipment.
- Smart Monitoring-Enabled Transformer Adoption: Growing utility and industrial interest in digital grid infrastructure is creating opportunities for dry type transformers equipped with sensor-based monitoring capabilities. Manufacturers offering integrated thermal and load monitoring solutions can differentiate their offerings for utilities pursuing predictive maintenance and grid reliability programs. As smart grid initiatives expand across Indian states, demand for monitoring-enabled transformer solutions is expected to grow steadily through the forecast period.
Market Challenges
- Price Competition from Unorganized Domestic Manufacturers: Competition from smaller, unorganized domestic transformer manufacturers offering lower-cost products can pressure pricing and margins for established players. These smaller manufacturers often compete aggressively on price in tenders for smaller-capacity industrial and commercial projects, limiting margin expansion for larger suppliers. Established manufacturers must balance competitive pricing with quality and safety standards to retain market share against low-cost domestic competition.
- Extended Project Approval and Procurement Timelines: Lengthy tendering, approval, and procurement cycles for utility and government infrastructure projects can delay transformer order conversion and revenue realization. Manufacturers must navigate multi-stage approval processes and evolving technical specifications, which can extend project timelines beyond initial estimates. These extended cycles can also complicate capacity planning for manufacturers balancing multiple large-scale utility and industrial orders simultaneously.
Emerging Market Trends
1. Smart Grid-Ready Monitoring Integration
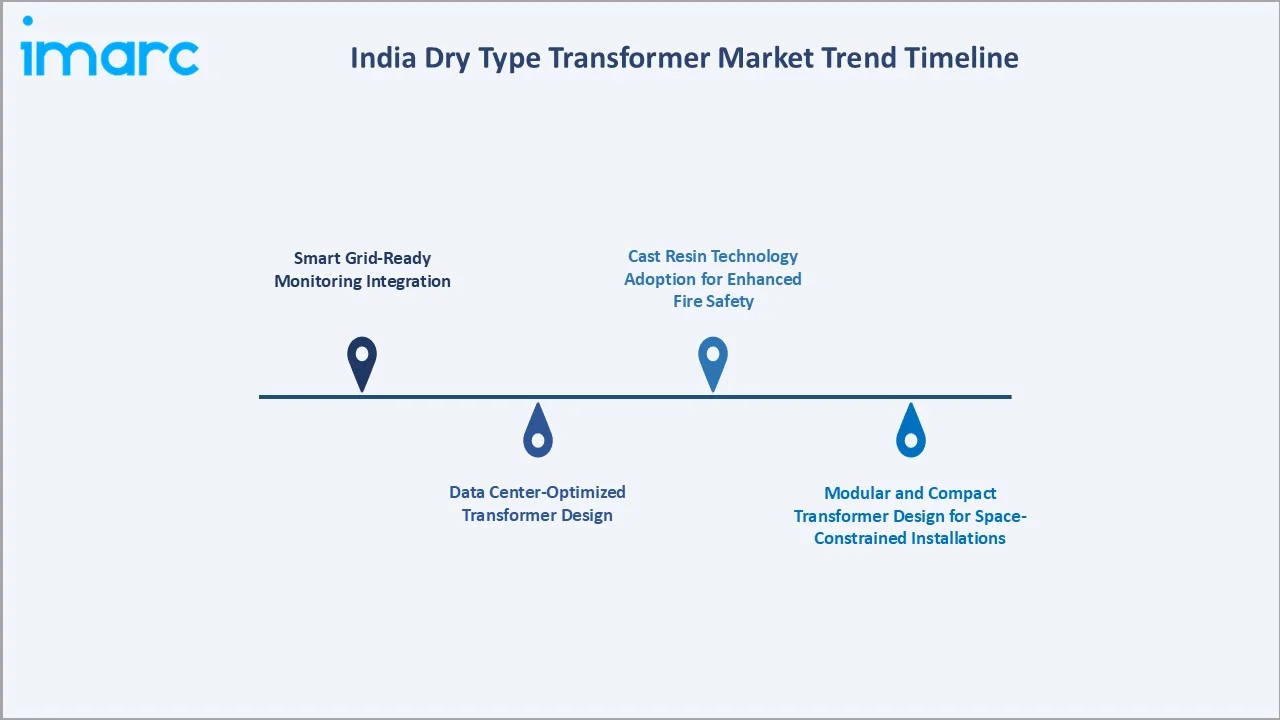
Transformer manufacturers are integrating digital sensors and IoT-enabled monitoring into dry type transformers, enabling real-time load tracking, thermal monitoring, and predictive maintenance. This trend is gaining traction among utilities and data center operators seeking improved grid reliability and reduced downtime.
2. Data Center-Optimized Transformer Design
As hyperscale and edge data centers expand across India, manufacturers are developing compact, high-efficiency dry type transformers tailored for space-constrained server environments, supporting stable voltage regulation and enhanced fire safety for critical IT infrastructure.
3. Cast Resin Technology Adoption for Enhanced Fire Safety
Cast resin dry type transformers are gaining preference across industrial and commercial installations for their superior fire resistance, moisture tolerance, and low maintenance requirements. Manufacturers are expanding cast resin production lines to meet rising demand from data centers, hospitals, and metro infrastructure projects.
4. Modular and Compact Transformer Design for Space-Constrained Installations
Rising urban density and space-constrained project sites are driving demand for modular, compact dry type transformer designs that simplify installation and reduce footprint. This trend is particularly relevant for retrofit projects in existing commercial and industrial buildings.
Industry Value Chain Analysis
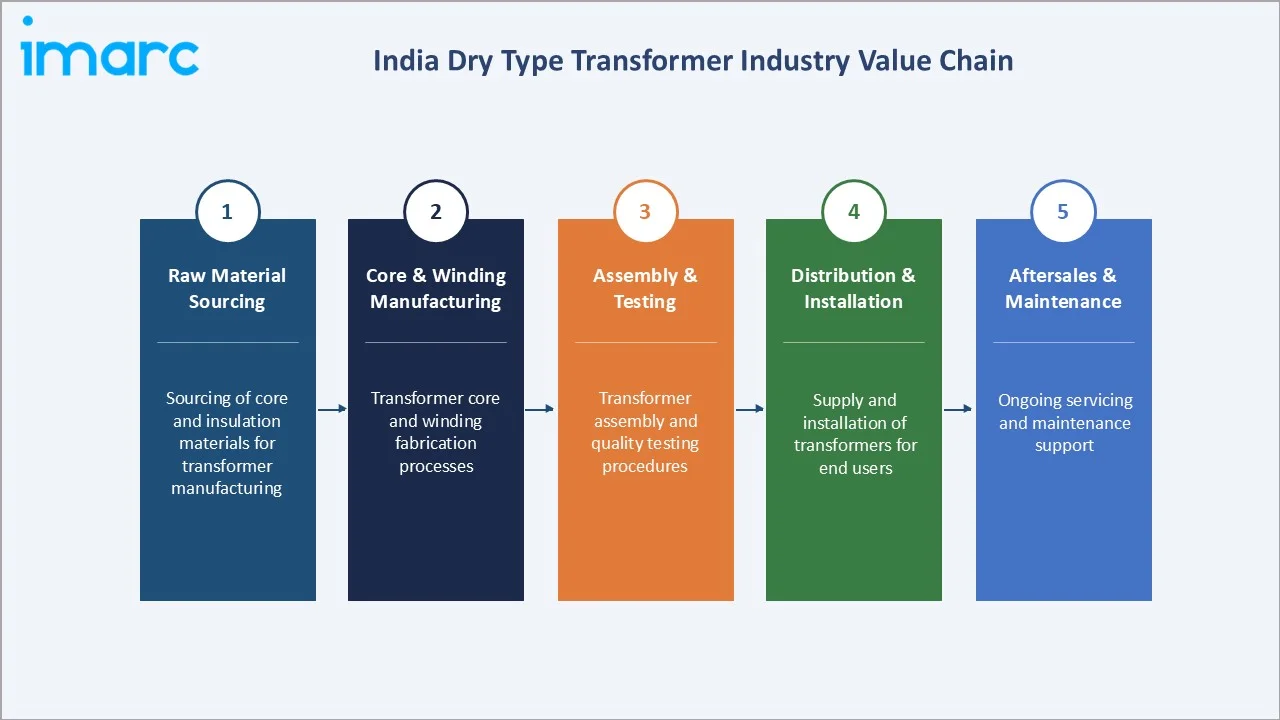
The dry type transformer value chain integrates raw material procurement, core and winding manufacturing, assembly and testing, and distribution to end users across utility, industrial, and commercial segments. Manufacturing is increasingly consolidating around integrated production facilities that combine core fabrication, winding, and testing to reduce lead times and ensure consistent quality for large-scale infrastructure and data center projects.
|
Stage |
Key Participants |
|
Raw Material Sourcing |
Sourcing of core and insulation materials for transformer manufacturing |
|
Core & Winding Manufacturing |
Transformer core and winding fabrication processes |
|
Assembly & Testing |
Transformer assembly and quality testing procedures |
|
Distribution & Installation |
Supply and installation of transformers for end users |
|
Aftersales & Maintenance |
Ongoing servicing and maintenance support |
Technology Landscape in the India Dry Type Transformer Industry
Cast Resin Transformer Technology
Cast resin transformer technology offers high fire resistance, low maintenance, and suitability for indoor and environmentally sensitive installations. Its adoption is expanding across data centers, hospitals, and metro infrastructure projects where safety and reliability are critical priorities.
Vacuum Pressure Impregnated (VPI) Transformer Technology
Vacuum pressure impregnated transformer technology provides enhanced moisture resistance and mechanical strength, making it suitable for industrial environments with variable humidity and load conditions. VPI transformers are widely used in manufacturing facilities and process industries across India.
Smart Monitoring and Digital Transformer Technology
Integration of digital sensors and monitoring systems into dry type transformers is enabling real-time thermal and load tracking for utilities and industrial operators. This technology supports predictive maintenance and improved grid reliability as India's power distribution network modernizes.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Voltage |
Medium Voltage |
47.0% |
2025 |
|
Application |
Industrial |
42.0% |
2025 |
|
Region |
West India |
34.0% |
2025 |

By Voltage
To access detailed market analysis, Request Sample
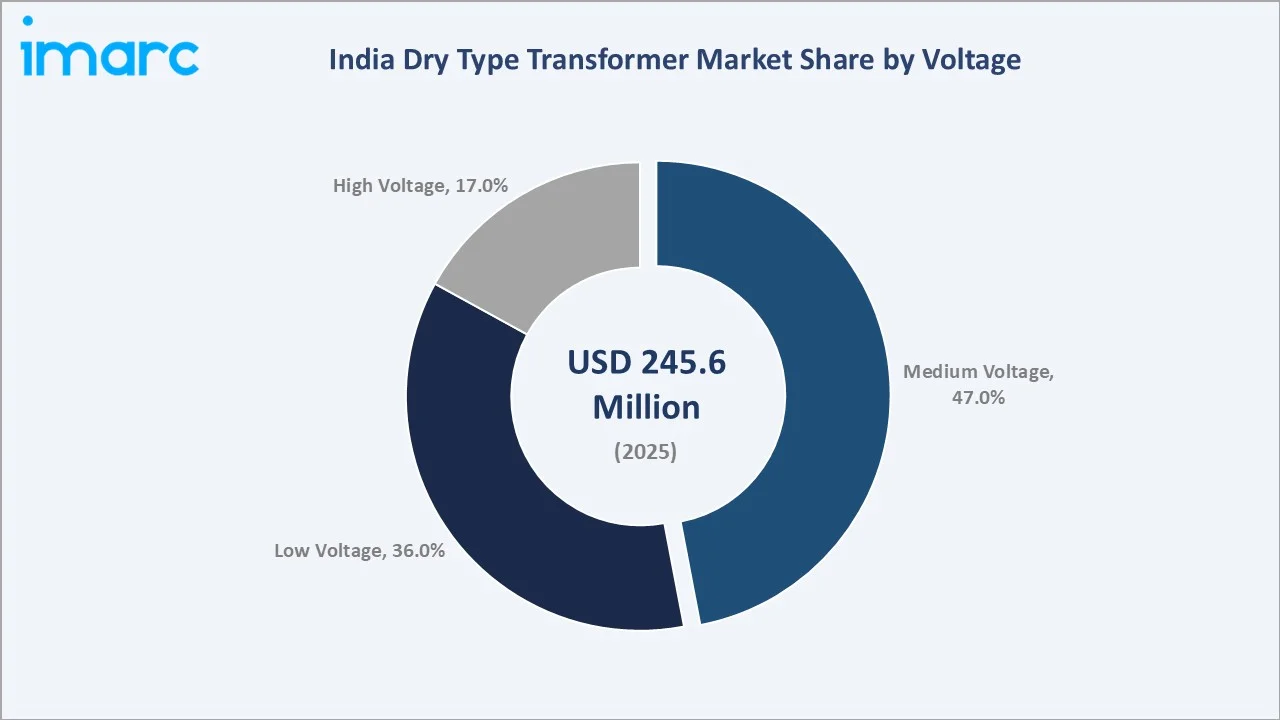
Medium Voltage transformers lead the market at 47.0% share in 2025, widely deployed across industrial plants, commercial buildings, and utility substations requiring balanced capacity and reliability. Low Voltage transformers follow at 36.0%, serving small commercial and residential-adjacent installations, while High Voltage transformers account for 17.0%, supporting large industrial facilities and utility-scale substations requiring higher power transfer capacity.
By Application
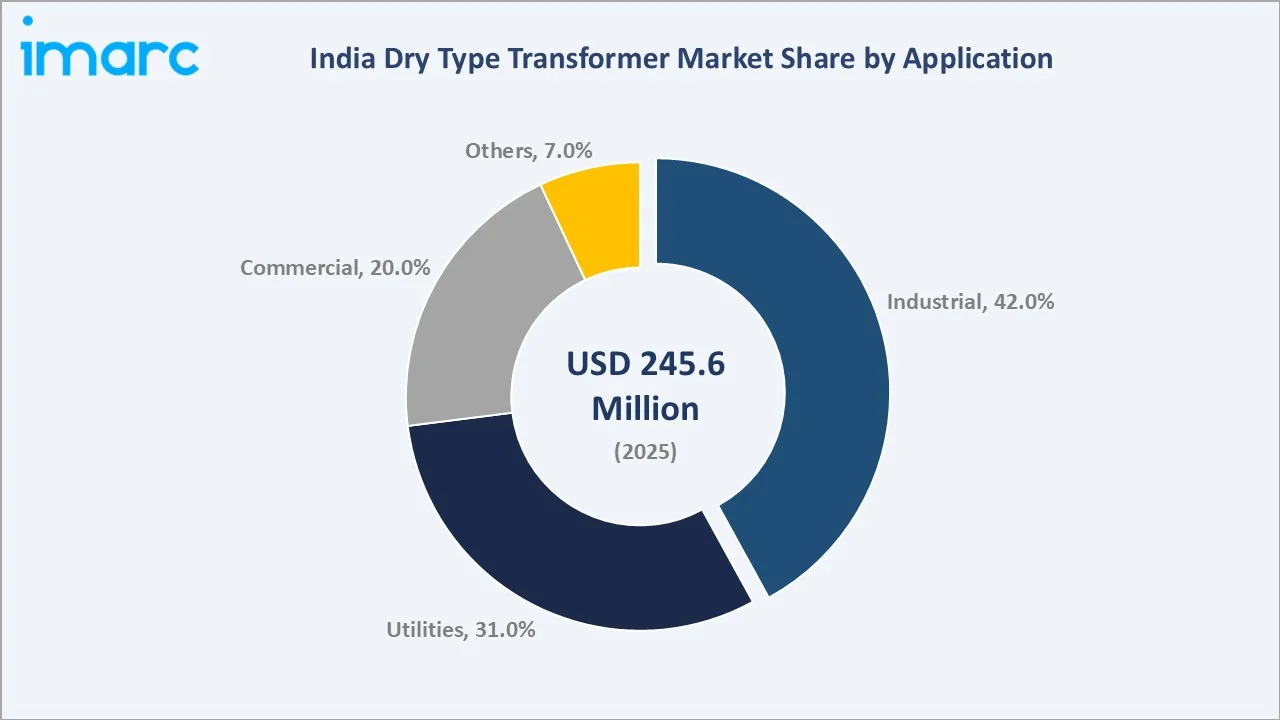
Industrial application leads at 42.0% share, driven by expanding manufacturing capacity and factory electrification requiring reliable, fire-safe power distribution. Utilities follow at 31.0%, reflecting grid modernization and substation upgrades, while Commercial applications hold 20.0% through office complexes, hospitals, and data centers. The Others category, at 7.0%, includes residential-adjacent and specialized installations.
Regional Market Insights
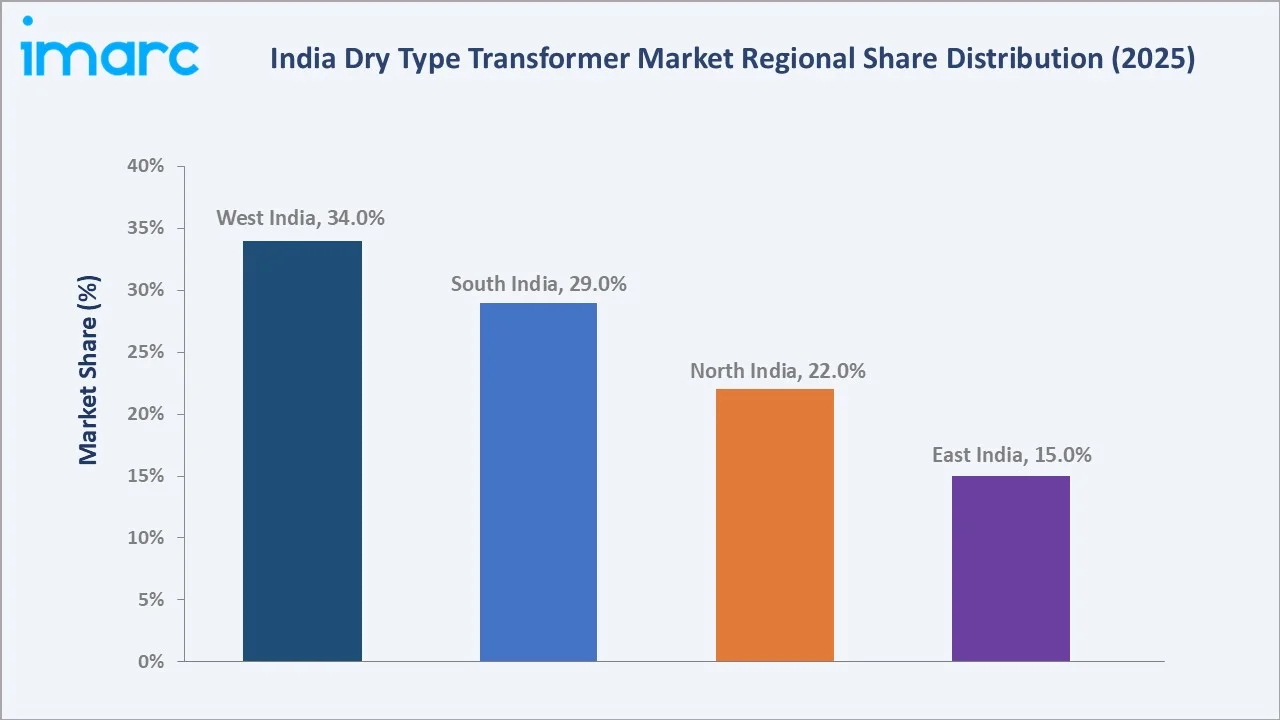
|
Region |
Share (2025) |
Key Market Drivers & Characteristics |
|
West India |
34.0% |
Driven by a strong industrial and manufacturing base, well-developed infrastructure, and an expanding renewable energy and data center project pipeline |
|
South India |
29.0% |
Supported by robust industrial and IT infrastructure growth, expanding data center investment, and steady renewable energy capacity additions |
|
North India |
22.0% |
Driven by urban infrastructure development, grid modernization initiatives, and growing commercial and utility power distribution needs |
|
East India |
15.0% |
Reflects emerging industrial development, expanding power infrastructure investment, and rising electrification initiatives |
West India, at 34.0%, leads through its concentrated manufacturing base, well-developed infrastructure, and renewable energy project pipeline. South India, at 29.0%, benefits from expanding industrial and data center investment. North India, at 22.0%, and East India, at 15.0%, reflect steadily growing but comparatively earlier-stage regional markets driven by infrastructure modernization and rising electrification.
Competitive Landscape
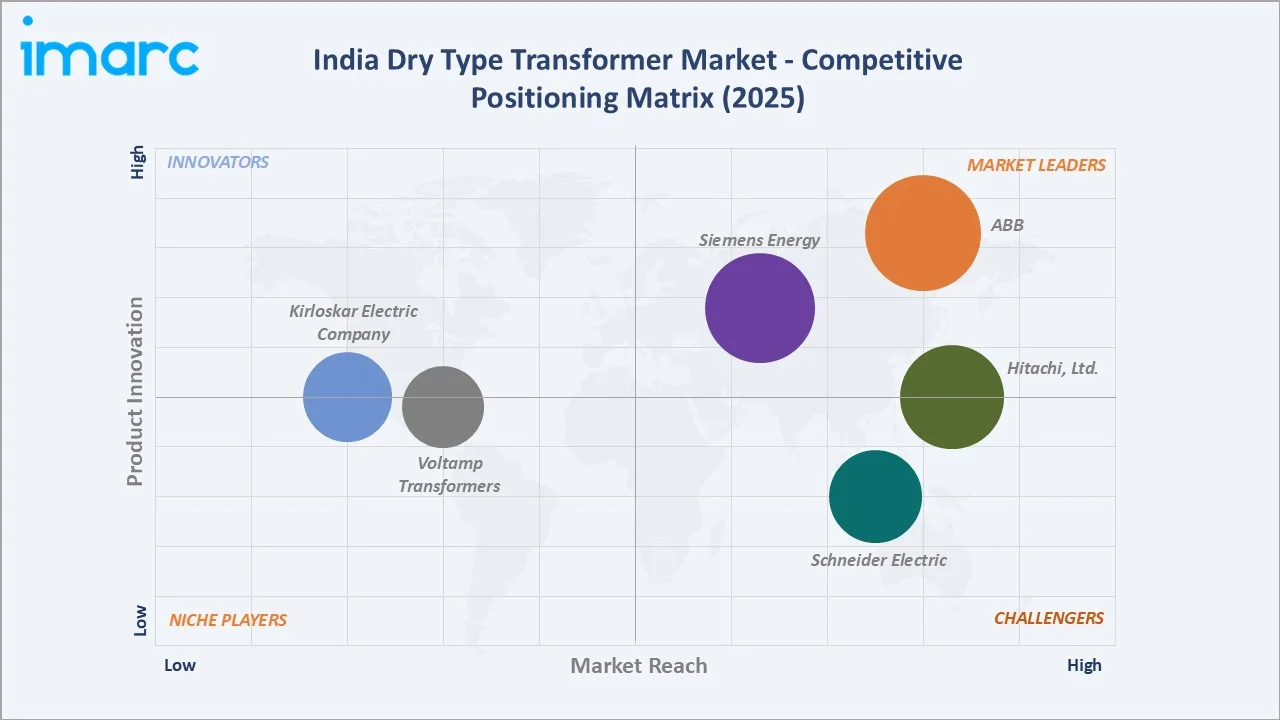
The India dry type transformer market is moderately consolidated, led by established multinational electrical equipment manufacturers alongside strong domestic Tier-1 players. Global majors maintain leading positions through extensive manufacturing footprints and technology portfolios, while domestic players compete through cost-competitive offerings and localized manufacturing. Ongoing capacity expansions across the industry reflect rising demand from utilities, data centers, and renewable energy projects.
|
Company Name |
Key Products |
Market Position |
Core Strength |
|
ABB |
Low Voltage Dry Type Vented Transformers, Low Voltage Dry Type Non-Ventilated Transformers |
Market Leader |
Extensive domestic manufacturing footprint and design expertise across dry type and oil-immersed distribution transformers. |
|
Siemens Energy |
CAREPOLE |
Market Leader |
Expanding large power transformer manufacturing capacity backed by strong order backlog and technology depth. |
|
Hitachi, Ltd. |
Vacuum Cast Coil (VCC), RESIBLOC transformers |
Market Leader |
Growing production capacity across key Indian states supported by global grid technology expertise. |
|
Schneider Electric |
Trihal |
Strong Challenger |
Broad energy management portfolio with dry type transformers for commercial and industrial use. |
|
Kirloskar Electric Company |
Dry Type & Distribution Transformers |
Established Player |
Long-standing domestic manufacturer with a diversified transformer product portfolio. |
|
Voltamp Transformer |
Cast Resin Dry Type Transformers |
Established Player |
Focused specialization in cast resin dry type transformers for industrial and commercial clients. |
Key players include ABB, Siemens Energy, Hitachi, Ltd., Schneider Electric, Kirloskar Electric Company, Voltamp Transformer, and others.
Key Company Profiles
ABB
ABB is a leading manufacturer of electrical equipment and automation technologies with a significant presence in the Indian dry type of transformer market through its distribution transformer manufacturing facilities.
- Key Products: Low Voltage Dry Type Vented Transformers, Low Voltage Dry Type Non-Ventilated Transformers
- Strategic Focus: Expanding domestic manufacturing capacity and localization to serve growing demand from renewable energy, data center, and industrial infrastructure projects across India. The company continues to invest in engineering and R&D capabilities to support next-generation transformer and switchgear technologies for the Indian market. ABB India Ltd. is also strengthening its service and testing infrastructure to support faster project delivery for utility and industrial customers.
Siemens Energy
Siemens Energy is a leading energy technology company with a growing transformer manufacturing presence, operating as an independently listed entity following its 2025 demerger from Siemens Limited.
- Key Products: Large Power Transformers, Distribution Transformers.
- Strategic Focus: Scaling domestic transformer manufacturing capacity to support India's grid modernization and renewable energy integration under the Make in India initiative. The company is prioritizing large power transformer capacity additions to address rising domestic and export demand for transmission infrastructure. Siemens Energy India Limited continues to strengthen its engineering and project execution capabilities to support large-scale utility and industrial transformer orders.
Market Concentration Analysis
The India dry type transformer market is moderately concentrated, with the key players collectively holding a significant share of large-scale utility and industrial contracts. Domestic manufacturers are gradually expanding their presence through cost-competitive offerings and capacity investments. Market concentration is expected to gradually ease over the forecast period as domestic players scale production and secure larger utility and data center contracts.
Investment & Growth Opportunities
Highest Growth Segments
High Voltage transformers, Utilities application, and South India's expanding industrial and data center base represent above-average growth vectors through 2034, supported by grid modernization and infrastructure investment across these categories.
Emerging Investment Opportunities
Data center power infrastructure represents the India dry type transformer market's highest-growth emerging opportunity, as hyperscale and edge data center developers increasingly specify compact, fire-safe transformer solutions to support expanding digital infrastructure investment across major Indian cities.
Investment Themes
- Capacity expansion for large-rating dry type transformers to address utility and data center demand: Manufacturers investing in expanded production capacity for higher-rating dry type transformers can capture a growing share of utility and data center contracts that currently rely on imported or limited domestic supply.
- Smart monitoring-enabled transformer development for grid modernization programs: Investment in sensor-based monitoring and digital integration capabilities positions manufacturers to serve utilities and industrial customers pursuing predictive maintenance and enhanced grid reliability.
Future Market Outlook (2026-2034)
The India dry type transformer market is projected to grow from USD 245.6 Million in 2025 to USD 442.6 Million by 2034, delivering a 6.24% CAGR over the forecast period. Growth will be anchored by continued renewable energy capacity additions, expanding data center infrastructure, and stricter fire-safety regulations favoring oil-free equipment. Medium Voltage transformers are expected to maintain their leading position as industrial and utility infrastructure expands, while Industrial application demand is set to strengthen further through manufacturing growth. West India is likely to retain its regional lead, supported by sustained industrial and infrastructure investment.
Continued investment in renewable energy capacity, data center infrastructure, and industrial electrification is expected to sustain steady demand for dry type transformers through 2034. Medium Voltage transformers and Industrial application are likely to retain their leading positions, while High Voltage and Utilities segments are expected to post above-average growth as grid modernization programs expand. West India is expected to maintain its regional lead, though South India's expanding industrial and data center base is likely to narrow the gap over the forecast period.
Research Methodology
Primary Research
Primary research comprised structured interviews with industry stakeholders, including transformer manufacturers, utility procurement teams, and infrastructure project developers across India.
Secondary Research
Secondary research encompassed company annual reports, government infrastructure and energy policy publications, industry association data, and trade and regulatory filings related to the Indian power distribution sector.
Forecasting Models
Market revenue forecasts were developed using a bottom-up approach incorporating historical market trends, segment-wise demand patterns by voltage and application, and regional infrastructure investment trajectories across India.
India Dry Type Transformer Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Million USD |
| Scope of the Report |
Exploration of Historical Trends and Market Outlook, Industry Catalysts and Challenges, Segment-Wise Historical and Future Market Assessment:
|
| Voltages Covered | Low Voltage, Medium Voltage, High Voltage |
| Applications Covered | Industrial, Commercial, Utilities, Others |
| Regions Covered | North India, South India, East India, West India |
| Companies Covered | ABB, Siemens Energy, Hitachi, Ltd., Schneider Electric, Kirloskar Electric Company, Voltamp Transformer, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the India dry type transformer market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the India dry type transformer market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the India dry type transformer industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the India Dry Type Transformer Market Report
The India dry type transformer market reached USD 245.6 Million in 2025, driven by Medium Voltage transformers dominant at 47.0%, Industrial application leading at 42.0%, and West India commanding the largest regional share at 34.0% through its concentrated industrial base and infrastructure investment.
The India dry type transformer market grows at a CAGR of 6.24% during 2026-2034, reaching USD 442.6 Million by 2034. This growth reflects sustained renewable energy investment, expanding data center infrastructure, and increasing adoption of fire-safe, oil-free power distribution equipment.
Medium Voltage leads at 47.0% share, capturing the mainstream industrial and utility transformer specification. This segment grows at approximately 6.6% CAGR through 2034, supported by continued industrial and utility infrastructure expansion.
Industrial application leads at 42.0% through expanding manufacturing capacity and factory electrification, growing at approximately 6.9% CAGR through 2034 as data center construction and industrial infrastructure investment continue to strengthen demand.
West India leads at 34.0% through its concentrated industrial base, infrastructure development, and expanding renewable energy and data center project pipeline.
Leading companies include ABB, Siemens Energy, Hitachi, Ltd., Schneider Electric, Kirloskar Electric Company, Voltamp Transformer, and others.
The India dry type transformer market is projected to reach approximately USD 332.4 Million by 2030, supported by continued renewable energy investment, data center expansion, and industrial infrastructure development across India.
Three priority investment opportunities include capacity expansion for large-rating dry type transformers, smart monitoring-enabled transformer development for grid modernization programs and retrofit replacement of aging oil-immersed transformers in urban commercial buildings.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade