
Japan Oleochemicals Market Size, Share, Trends and Forecast by Type, Form, Application, Feedstock, and Region, 2026-2034
Japan Oleochemicals Market Size, Share, Trends & Forecast (2026-2034)
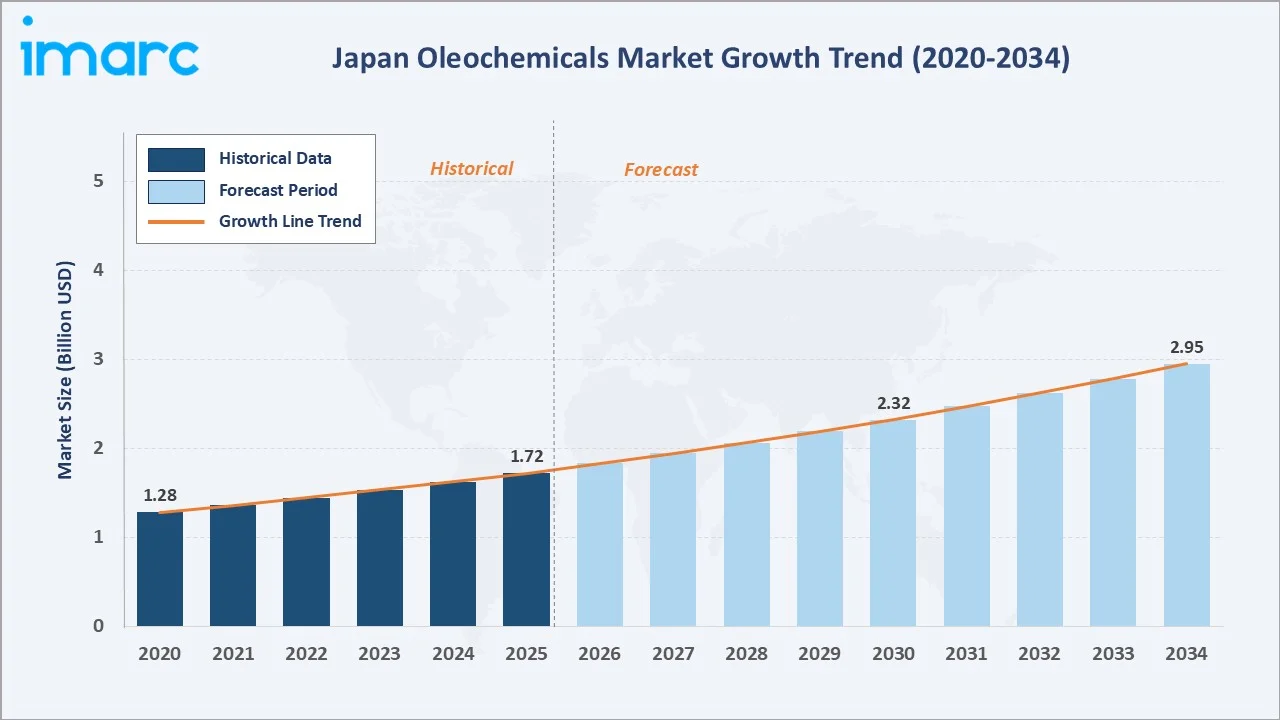
The Japan oleochemicals market grew from USD 1.72 Billion in 2025 to USD 1.83 Billion in 2026 and is projected to reach USD 2.95 Billion by 2034, exhibiting a CAGR of 6.18% during 2026-2034. Expanding domestic demand from personal care, food, and industrial sectors, combined with Japan's strong push toward bio-based and sustainable chemical alternatives, is fueling consistent market growth.
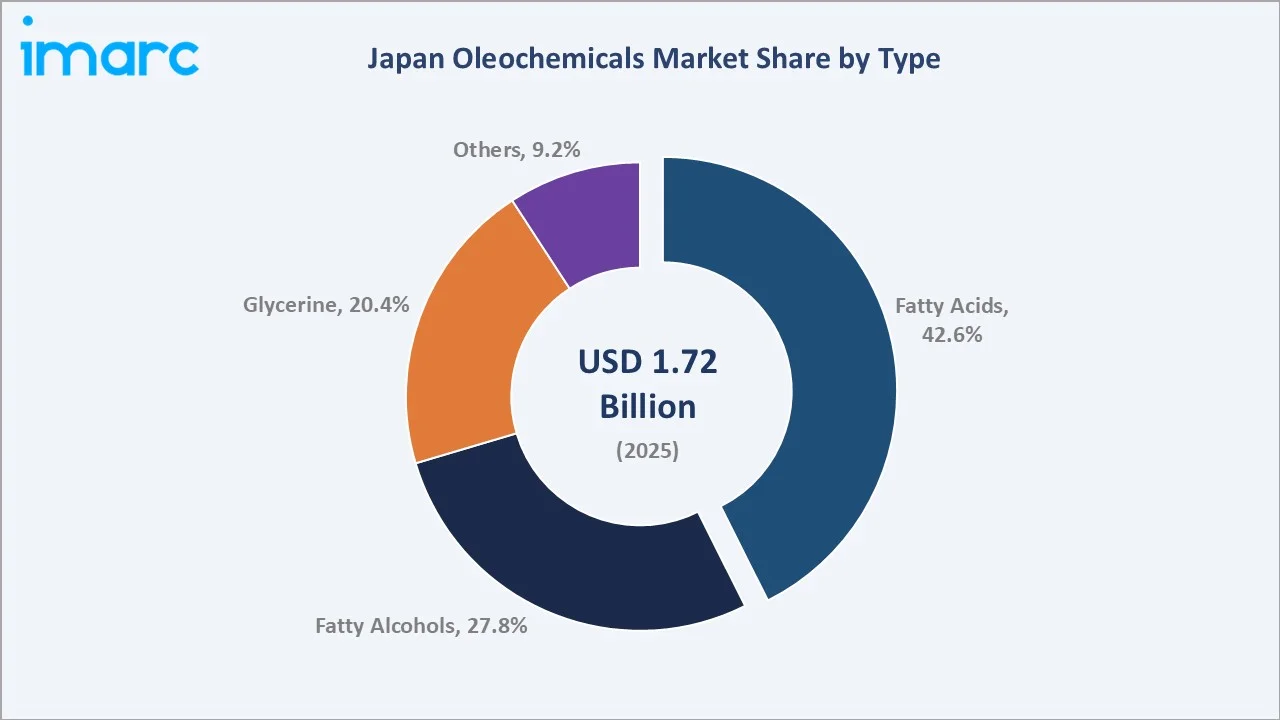
Fatty acids lead the type segment at 42.6%, liquid dominates the form segment at 64.7%, and Kanto Region commands 36.7% regional share.
Market Snapshot
|
Metric |
Value |
|
Base Year Market Size (2025) |
USD 1.72 Billion |
|
Market Size (2026) |
USD 1.83 Billion |
|
Forecast Market Size (2034) |
USD 2.95 Billion |
|
CAGR (2026-2034) |
6.18% |
|
Base Year |
2025 |
|
Historical Period |
2020-2025 |
|
Forecast Period |
2026-2034 |
|
Largest Region |
Kanto Region (36.7%, 2025) |
|
Second Largest Region |
Kansai/Kinki Region (22.5%, 2025) |
|
Leading Type |
Fatty Acids (42.6%, 2025) |
|
Leading Form |
Liquid (64.7%, 2025) |
The Japan oleochemicals market size increased from USD 1.28 Billion in 2020 to USD 1.72 Billion in 2025 and is estimated to reach USD 1.83 Billion in 2026. The market is further expected to grow to USD 2.32 Billion by 2030 and USD 2.95 Billion by 2034. The market is supported by widening bio-based product adoption, rising demand from personal care manufacturers, and growing use of oleochemical derivatives in food processing and pharmaceutical applications.
To get more information on this market, Request Sample
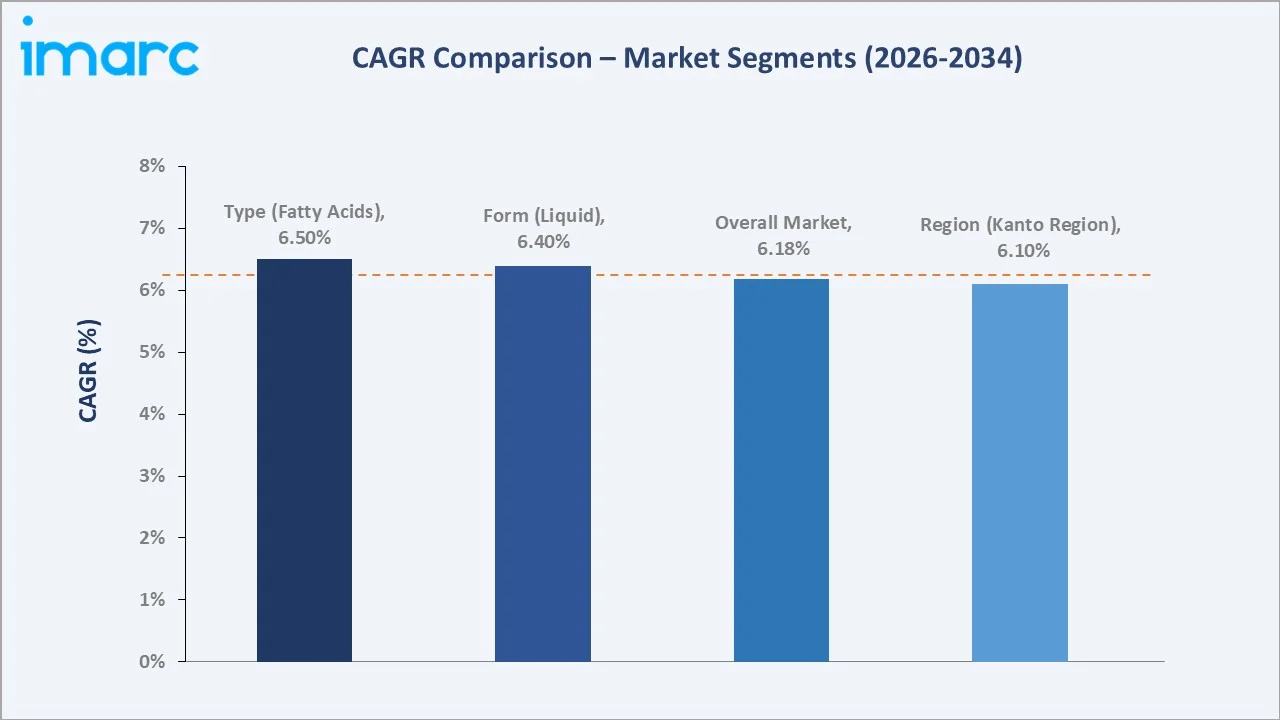
CAGR trajectories across type and form sub-segments, together with regional patterns, show fatty alcohols and Kyushu-Okinawa Region expanding faster than the overall 6.18% market CAGR, driven by rising demand for specialty personal care ingredients, expanding industrial applications, and increasing manufacturing activity.
Executive Summary
The Japan oleochemicals market expanded from USD 1.72 Billion in 2025 to an estimated USD 1.83 Billion in 2026, maintaining its position as a key oleochemical hub in the Asia-Pacific region. Japan's advanced manufacturing capabilities, stringent quality standards, and established chemical industry infrastructure position it as a key oleochemical hub in the Asia-Pacific region.
Fatty acids command a 42.6% type segment share in 2025, supported by high-volume demand from detergent and personal care formulators. Based on form, liquid leads at 64.7%, reflecting formulation preferences across personal care and food applications. Kanto Region commands 36.7% of regional share, anchored by the concentration of chemical manufacturers, research institutions, and logistics infrastructure in Tokyo and surrounding prefectures.
Key Market Insights
|
Insight |
Data |
|
Leading Type |
Fatty Acids – 42.6% share (2025) |
|
Second Largest Type |
Fatty Alcohols – 27.8% share (2025) |
|
Leading Form |
Liquid – 64.7% share (2025) |
|
Second Largest Form |
Solid – 35.3% share (2025) |
|
Leading Region |
Kanto Region – 36.7% share (2025) |
|
Second Largest Region |
Kansai/Kinki Region – 22.5% share (2025) |
|
Top Companies |
KAO Corporation, NOF Corporation, New Japan Chemical Co., Ltd., BASF SE |
Key Analytical Observations Expanding On the Data Above:
- Fatty acids dominance at 42.6% reflects strong and consistent demand from detergent manufacturers, personal care formulators, and food processors seeking high-purity fatty acid inputs for product development and production.
- Fatty alcohols share at 27.8% is supported by rising consumption of emollients, emulsifiers, and conditioning agents in premium personal care and cosmetic formulations across Japan's well-established beauty and skincare market.
- Liquid dominance at 64.7% reflects formulation flexibility, ease of blending, and broad compatibility with personal care, food, and industrial manufacturing processes.
- Solid share at 35.3% is supported by demand for stable, easy-to-handle fatty acid and fatty alcohol products used in detergents, cosmetics, lubricants, and other industrial applications.
- Kanto Region at 36.7% leads regional share, anchored by Tokyo's role as Japan's financial and industrial capital and the dense concentration of chemical manufacturers, research centers, and distribution networks in the Greater Tokyo area.
Japan Oleochemicals Market Overview
Oleochemicals are chemicals derived from animal or vegetable fats and oils through processes including hydrolysis, hydrogenation, and transesterification. The Japan oleochemicals ecosystem is characterized by advanced manufacturing processes, stringent quality standards, and strong integration between raw material sourcing, chemical processing, and end-use industry demand.
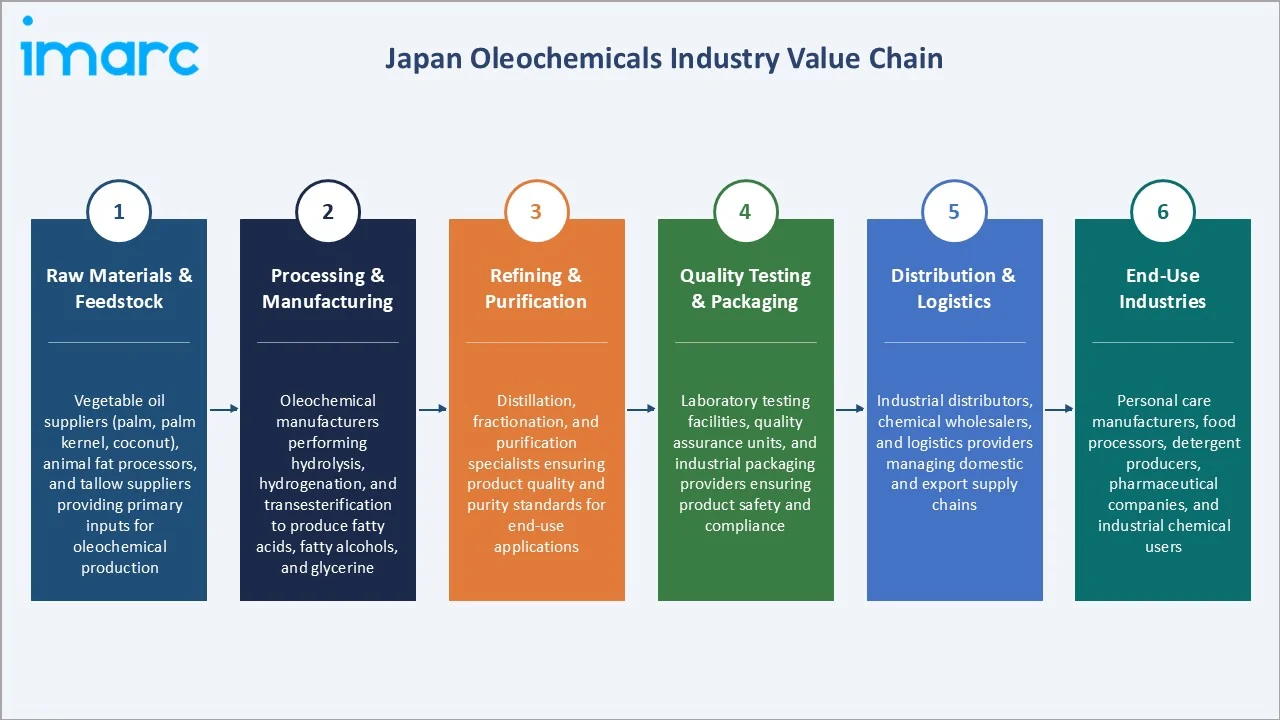
The market integrates raw material importers, domestic oleochemical manufacturers, specialty chemical refiners, quality testing laboratories, distribution networks, and a diverse set of end-use industries spanning personal care, detergents, food processing, pharmaceuticals, and industrial chemicals. Together, they enable a mature and increasingly sustainability-driven oleochemical supply chain that supports both domestic consumption and export-oriented production.
Market Dynamics
To evaluate market opportunities, Request Sample
Market Drivers
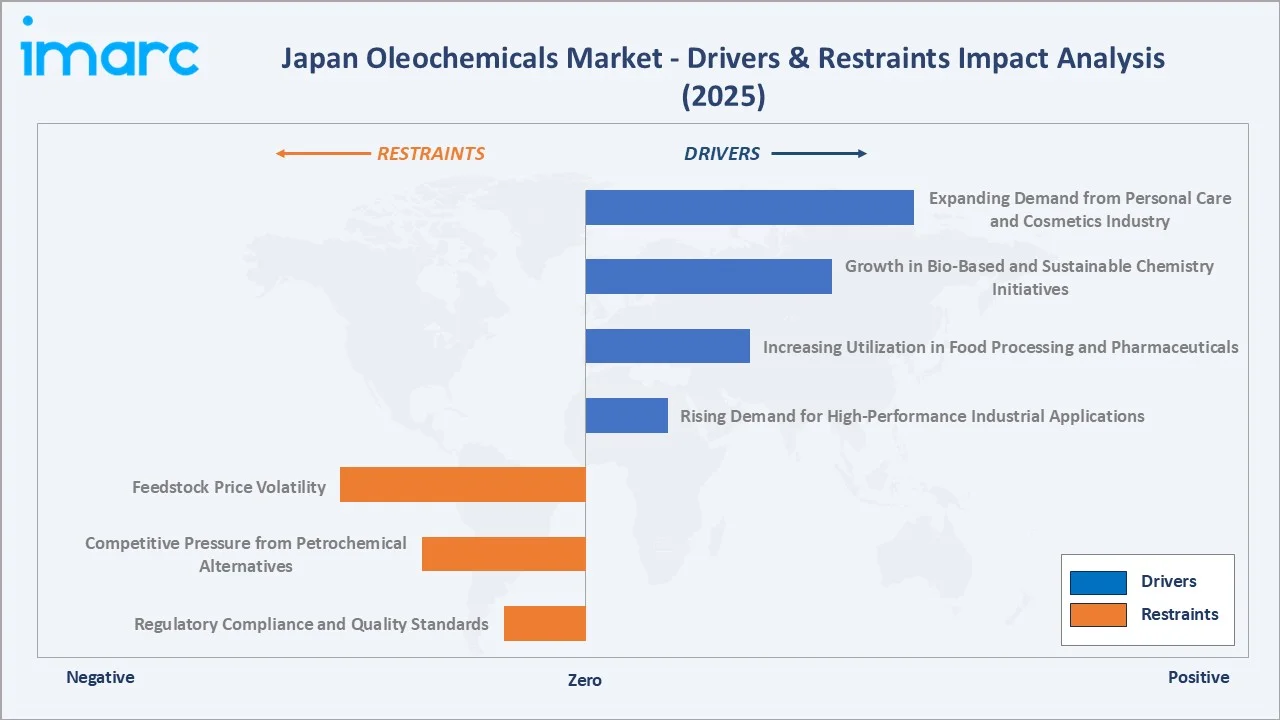
- Expanding Demand from Personal Care and Cosmetics Industry: As per IMARC Group, the Japan cosmetics market grew from USD 28.66 Billion in 2025. Japan's highly developed personal care market drives consistent demand for fatty alcohols, emulsifiers, and specialty fatty acid derivatives used in premium skin care, hair care, and cosmetic formulations.
- Growth in Bio-Based and Sustainable Chemistry Initiatives: Rising regulatory emphasis on green chemistry and sustainability across Japanese manufacturing sectors is accelerating the transition from petroleum-based to bio-derived oleochemical inputs in detergents, surfactants, and industrial lubricants.
- Increasing Utilization in Food Processing and Pharmaceuticals: Oleochemical derivatives serve as functional food additives, emulsifiers, and pharmaceutical excipients. Japan's mature food processing and pharmaceutical industries represent stable, high-value demand channels for glycerine, fatty acids, and specialty esters.
- Rising Demand for High-Performance Industrial Applications: Increasing use of oleochemical derivatives in lubricants, plastics, coatings, and specialty chemicals is supporting demand for high-purity fatty acids, esters, and other performance-oriented products across Japan's industrial manufacturing base.
Market Restraints
- Feedstock Price Volatility: Oleochemical production in Japan relies predominantly on imported palm and coconut oil, which are subject to significant price fluctuations driven by weather events, palm oil producing country policies, and global commodity market dynamics. This exposes Japanese manufacturers to margin pressure and production cost uncertainty.
- Competitive Pressure from Petrochemical Alternatives: In certain industrial applications, petrochemical-derived surfactants and lubricants continue to compete on cost, limiting oleochemical market penetration in price-sensitive industrial segments.
- Regulatory Compliance and Quality Standards: Japan's stringent chemical safety, labeling, and environmental compliance requirements impose an operational burden on smaller oleochemical producers and increase barriers to entry for new players.
Market Opportunities
- Development of High-Value Specialty Oleochemical Derivatives: Growing demand for functional esters, biosurfactants, and specialty fatty acid derivatives in pharmaceutical, cosmetic, and high-performance industrial applications presents significant value-addition opportunities for advanced Japanese manufacturers.
- Circular Economy and Waste Fat Valorization: Expanding programs to valorize waste cooking oils and animal fats as oleochemical feedstocks align with Japan's circular economy goals and offer cost-competitive raw material alternatives for domestic producers.
Market Challenges
- Raw Material Supply Chain Concentration: Dependence on a limited number of palm oil producing countries for primary feedstock creates supply chain vulnerability, which can be exacerbated by geopolitical events, export restrictions, or climate-related supply disruptions.
- Ageing Manufacturing Infrastructure: A portion of Japan's oleochemical production capacity was established several decades ago, and modernization requirements represent a significant capital investment challenge for mid-sized domestic producers competing against larger global players.
Emerging Market Trends
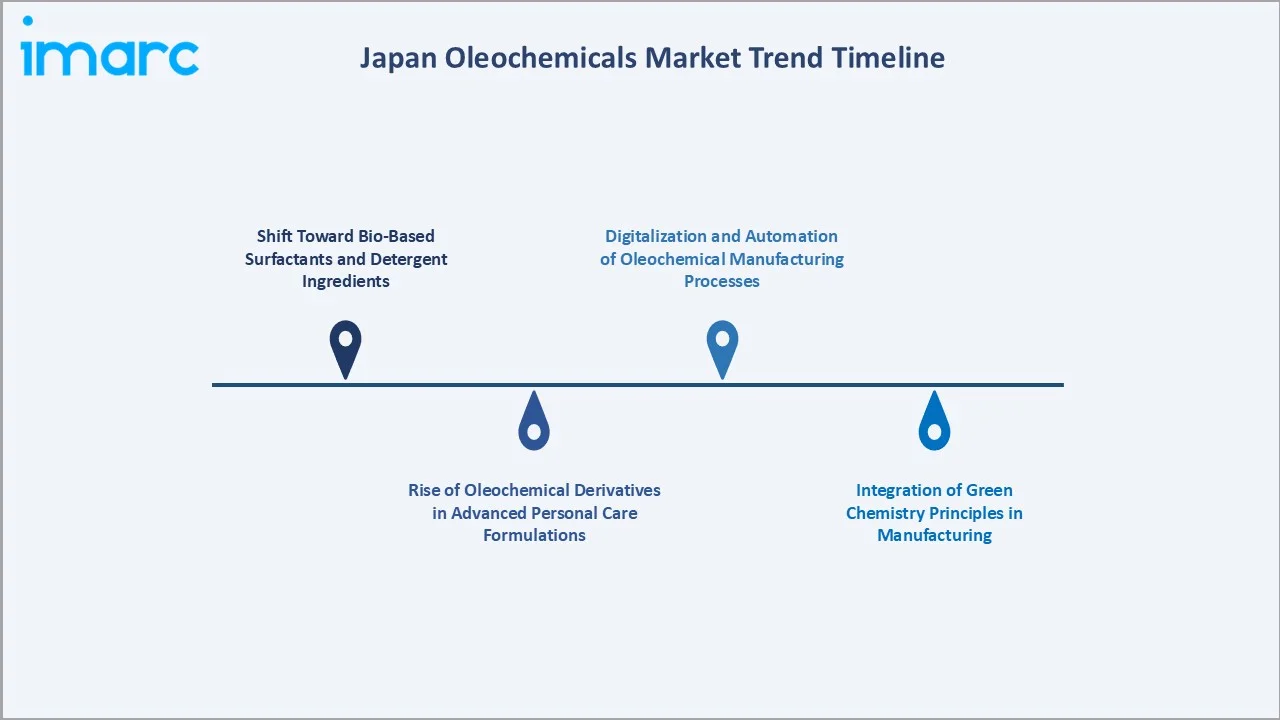
1. Shift Toward Bio-Based Surfactants and Detergent Ingredients
Japanese detergent and household cleaning product manufacturers are progressively reformulating products to replace synthetic surfactants with plant-derived oleochemical alternatives, driven by consumer preference for environmentally friendly formulations and corporate sustainability targets.
2. Integration of Green Chemistry Principles in Manufacturing
Japanese oleochemical producers are investing in cleaner production technologies, including enzymatic transesterification and continuous flow processing, to reduce waste, lower energy consumption, and improve product purity. This trend aligns with Japan's Society 5.0 and Carbon Neutrality 2050 goals.
3. Rise of Oleochemical Derivatives in Advanced Personal Care Formulations
Premium cosmetic and skin care brands are increasingly incorporating specialty esters, ceramide precursors, and bio-derived emollients derived from oleochemical processing into product formulations. This trend is further supported by growing consumer preference for mild, skin-compatible, and sustainably sourced ingredients in premium personal care products.
4. Digitalization and Automation of Oleochemical Manufacturing Processes
Japanese manufacturers are deploying advanced process control, IoT-enabled monitoring systems, and AI-driven quality management tools to optimize oleochemical production efficiency, reduce batch variability, and improve supply chain responsiveness.
Industry Value Chain Analysis
The Japan oleochemicals value chain spans six stages, from raw material sourcing and import through end-use industry application and product lifecycle management. Processing and refining stages capture the highest value-add, while quality assurance and distribution capabilities are increasingly important competitive differentiators in Japan's demanding industrial and consumer markets.
|
Stage |
Key Players / Examples |
|
Raw Materials & Feedstock |
Vegetable oil suppliers (palm, palm kernel, coconut), animal fat processors, and tallow suppliers providing primary inputs for oleochemical production |
|
Processing & Manufacturing |
Oleochemical manufacturers performing hydrolysis, hydrogenation, and transesterification to produce fatty acids, fatty alcohols, and glycerine |
|
Refining & Purification |
Distillation, fractionation, and purification specialists ensuring product quality and purity standards for end-use applications |
|
Quality Testing & Packaging |
Laboratory testing facilities, quality assurance units, and industrial packaging providers ensuring product safety and compliance |
|
Distribution & Logistics |
Industrial distributors, chemical wholesalers, and logistics providers managing domestic and export supply chains |
|
End-Use Industries |
Personal care manufacturers, food processors, detergent producers, pharmaceutical companies, and industrial chemical users |
Vertically integrated manufacturers with direct raw material sourcing relationships, proprietary processing technology, and established end-user partnerships are best positioned to capture premium margins across the value chain. Specialty chemical producers focusing on high-purity derivatives and custom oleochemical solutions hold a strategic advantage over commodity-focused players.
Technology Landscape in the Japan Oleochemicals Industry
Hydrolysis and Fractionation Technology
High-pressure continuous hydrolysis and advanced fractionation techniques are enabling Japanese producers to achieve higher purity fatty acids and improved separation efficiency. These processes underpin the production of pharmaceutical-grade and food-grade oleochemical products that command premium pricing in domestic and export markets.
Hydrogenation and Catalytic Processing
Catalytic hydrogenation technology is central to fatty alcohol and hardened fat production in Japan. Advances in catalyst efficiency, selectivity, and lifetime are reducing production costs and energy consumption, supporting the competitiveness of Japanese oleochemical manufacturers against lower-cost regional competitors.
Enzymatic Processing and Biotechnology
Enzymatic transesterification and biocatalytic processes are gaining adoption in Japan for the production of specialty esters, wax esters, and structured lipids. These processes offer improved selectivity, reduced energy requirements, and enhanced sustainability credentials compared to conventional chemical synthesis routes.
Process Automation and Digital Manufacturing
Japanese oleochemical manufacturers are investing in advanced process control systems, real-time quality monitoring platforms, and data-driven production optimization tools. These investments are reducing batch variability, improving yield consistency, and enabling faster response to customer quality specifications in high-value specialty product segments.
Market Segmentation Analysis
The report covers the following segments:
|
Segment Category |
Leading Segment |
Market Share |
Year |
|
Type |
Fatty Acids | 42.6% | 2025 |
| Form | Liquid | 64.7% | 2025 |
| Application | 🔒 | 🔒 | 2025 |
| Feedstock | 🔒 | 🔒 | 2025 |
| Region | Kanto Region | 36.7% | 2025 |

By Type
Fatty acids command a 42.6% majority share in 2025, driven by high-volume demand from detergent, personal care, food processing, and industrial chemical sectors. The segment benefits from established supply chains, mature processing infrastructure, and broad end-use applicability across multiple industries.
To access detailed market analysis, Request Sample
Fatty alcohols at 27.8% represent the fastest-growing type segment, driven by rising demand from premium personal care and cosmetics manufacturers for emollient, conditioning, and emulsifying agents.
By Form
Liquid leads with 64.7% share in 2025, reflecting the formulation preferences of personal care, food, and industrial chemical manufacturers who require pumpable, blendable inputs compatible with continuous manufacturing processes.
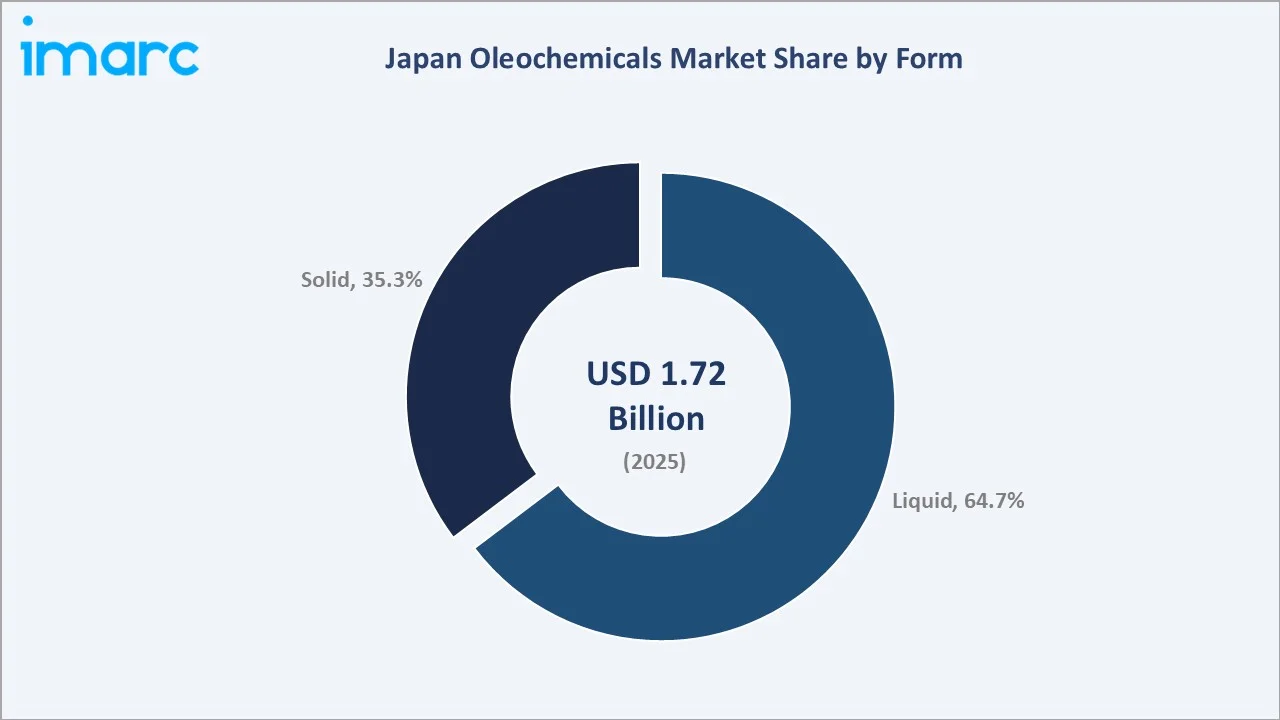
Solid at 35.3% remains significant for applications in wax formulations, cosmetic bars, and industrial specialty chemical products where physical form is a functional requirement. Technological advances in solid oleochemical processing are supporting incremental product innovation in this segment.
Regional Market Insights
|
Region |
Share (2025) |
Key Growth Drivers |
|
Kanto Region |
36.7% |
High concentration of industrial and chemical manufacturers, well-developed logistics infrastructure, and strong domestic demand from personal care and industrial sectors |
|
Kansai/Kinki Region |
22.5% |
Dense manufacturing base, presence of major chemical companies, and proximity to key port facilities supporting export-oriented oleochemical production |
|
Central/Chubu Region |
15.8% |
Growing industrial activity, expanding automotive and specialty chemical sectors, and rising demand for functional oleochemical derivatives |
|
Kyushu-Okinawa Region |
8.9% |
Expanding chemical and agricultural industries, growing regional demand for bio-based inputs, and improving logistics connectivity |
|
Tohoku Region |
6.2% |
Rising industrial development, growing food processing sector, and increasing adoption of oleochemical-based ingredients in regional manufacturing |
|
Chugoku Region |
4.7% |
Established chemical manufacturing base, proximity to major industrial ports, and growing specialty chemical demand |
|
Hokkaido Region |
3.7% |
Expanding agricultural and food processing industries driving incremental demand for oleochemical ingredients and specialty derivatives |
|
Shikoku Region |
1.5% |
Niche industrial and agricultural demand, growing interest in bio-based specialty chemicals, and improving regional connectivity |
Kanto Region at 36.7% in 2025 leads the regional landscape, anchored by Tokyo's role as Japan's industrial and commercial capital and the dense concentration of oleochemical manufacturers, specialty chemical companies, and distribution infrastructure in the Greater Kanto area. Strong industrial demand from personal care, food processing, and detergent manufacturers, combined with well-developed port facilities for raw material imports, supports sustained regional leadership.
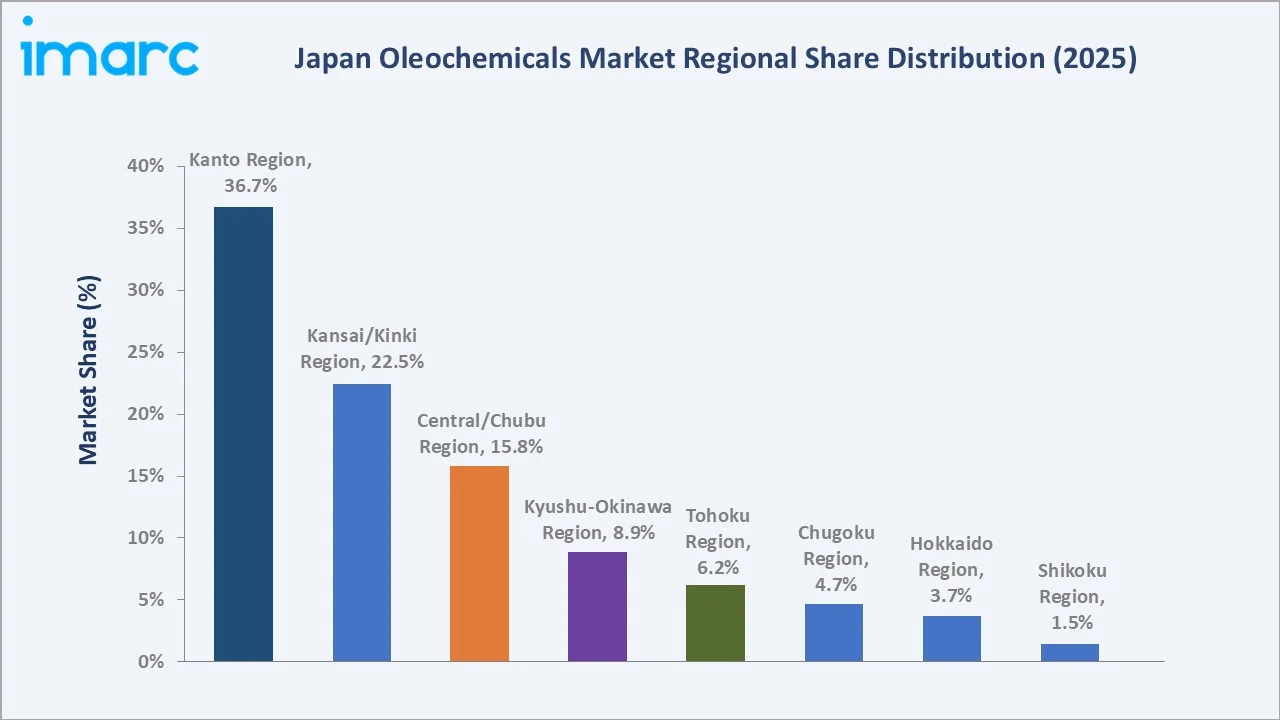
Kansai/Kinki Region at 22.5% is supported by its strong concentration of chemical, pharmaceutical, manufacturing, and consumer goods industries, which generate consistent demand for oleochemical-based ingredients and specialty derivatives.
Competitive Landscape
The Japan oleochemicals market is moderately concentrated, with established domestic chemical manufacturers and global specialty chemical companies leading production and product development while regional players compete on niche derivative products and application-specific solutions. Manufacturing scale, product purity standards, process technology capability, and end-user relationship depth form the key competitive differentiators across the industry.
|
Company Name |
Brand / Key Product |
Position |
Strategic Focus |
|
KAO Corporation |
Fatty acids, fatty alcohols, surfactants |
Leader |
Expanding bio-based oleochemical product lines and strengthening supply chain sustainability across domestic and export markets |
|
NOF Corporation |
Fatty acids, glycerine, surfactants |
Leader |
Deepening specialty oleochemical capabilities and advancing research into functional fatty acid derivatives for industrial applications |
|
New Japan Chemical Co., Ltd. |
RiKACRYSTA, RiKANATURA |
Leader |
Growing specialty oleochemical portfolio and expanding customer partnerships in personal care and food additive segments |
|
BASF SE |
Lutensol, Cremophor, Kolliphor series |
Challenger |
Advancing sustainable oleochemical solutions and deepening customer relationships in personal care, food, and industrial end markets |
Key players include KAO Corporation, NOF Corporation, New Japan Chemical Co., Ltd., and BASF SE, among others.
Key Company Profiles
KAO Corporation
KAO Corporation is a Japanese multinational chemical and consumer goods company headquartered in Tokyo, Japan, operating across oleochemicals, personal care, cosmetics, and industrial chemicals.
- Product Portfolio: Fatty acids, fatty alcohols, fatty amines, glycerine, and surfactants derived from natural fats and oils for industrial, personal care, and pharmaceutical applications.
- Recent Developments: The company continues to invest in product and process innovation across its chemical business, with ongoing initiatives aimed at improving manufacturing efficiency, broadening the application range of its oleochemical portfolio, and reinforcing its sustainability commitments across domestic and international operations.
- Strategic Focus: Strengthening its position as a globally integrated oleochemical producer by broadening its bio-based product offerings and deepening supply chain partnerships across key end-use industries.
NOF Corporation
NOF Corporation is a Japanese specialty chemical company headquartered in Tokyo, producing oleochemicals, functional lipids, and specialty chemical products for pharmaceutical, personal care, and industrial applications.
- Product Portfolio: Fatty acids, glycerine, fatty acid derivatives, surfactants, functional lipids, oleochemical-based pharmaceutical excipients, and industrial chemical solutions.
- Recent Developments: The company continues to pursue strategic development across its functional chemicals and life science businesses, directing resources toward enhancing product performance, expanding application coverage, and meeting evolving customer requirements in pharmaceutical and personal care segments.
- Strategic Focus: Cultivating high-value specialty oleochemical capabilities while broadening its reach in pharmaceutical excipient and personal care ingredient markets through continued product differentiation.
New Japan Chemical Co., Ltd.
New Japan Chemical Co., Ltd. is a Japanese chemical manufacturer producing oleochemical derivatives, specialty esters, and functional ingredients for personal care, food, and industrial sectors, listed on the Tokyo Stock Exchange.
- Product Portfolio: Oleochemicals including hydrogenated oils, fatty acids and esters, glycerine, fatty alcohols, surfactants, specialty esters, and plasticizers for personal care, food, and industrial applications.
- Recent Developments: The company continues to develop and commercialize differentiated chemical products across its oleochemical and functional materials businesses, with sustained investment in research and development supporting the advancement of its proprietary product lines and their adoption across multiple industry segments.
- Strategic Focus: Scaling up proprietary biomass-derived and specialty oleochemical product lines while reinforcing customer relationships across personal care, food ingredient, and industrial application markets.
Market Concentration Analysis
The Japan oleochemicals market is moderately concentrated, with the top oleochemical producers and specialty chemical companies accounting for a meaningful share of domestic production and product distribution, reflecting the capital intensity, regulatory complexity, and quality standards that characterize Japan's advanced chemical industry.
Barriers to entry include significant capital investment requirements for processing infrastructure, the need for established raw material sourcing relationships, stringent Japanese quality and safety certification requirements, and the scale required to compete effectively in both commodity and specialty oleochemical segments. These factors favor established players with proven manufacturing reliability and existing end-user relationships.
Consolidation activity is gradually increasing as domestic and global chemical companies seek to expand product portfolios and capture growing demand in high-value specialty oleochemical segments. Strategic partnerships between oleochemical producers, personal care formulators, and food processing companies are further shaping competitive positioning and market structure.
Investment & Growth Opportunities
Fastest-Growing Segments
Fatty alcohols are expanding fastest among type categories, driven by rising demand for premium personal care and cosmetic ingredients in Japan's well-developed beauty market. Liquid is growing faster than solid, reflecting formulation flexibility requirements across personal care and industrial manufacturing.
Emerging Markets
Kyushu-Okinawa Region represents the fastest-growing region, supported by expanding manufacturing activity, food processing, and chemical production, which are increasing demand for oleochemical-based ingredients and industrial derivatives.
Venture & Investment Trends
Investment activity in Japan's oleochemicals sector is concentrated in bio-based surfactant technology, high-purity specialty ester production, glycerine valorization, and green oleochemical derivative development. Capital is also flowing into process automation, digital manufacturing, and sustainable feedstock sourcing solutions that align with corporate ESG commitments and Japan's Carbon Neutrality 2050 roadmap.
Future Market Outlook (2026-2034)
The Japan oleochemicals market is projected to grow from USD 1.72 Billion in 2025 to USD 1.83 Billion in 2026, reaching USD 2.95 Billion by 2034, registering a CAGR of 6.18% during 2026-2034.
Four forces will shape the market through 2034: continued expansion of bio-based personal care and cosmetic formulations; deepening industrial adoption of green oleochemical surfactants and lubricants; growing pharmaceutical and food processing demand for high-purity oleochemical derivatives; and Japan's strategic push toward circular economy integration and sustainable chemistry across its manufacturing base.
By 2034, the Japan oleochemicals market is expected to be defined by specialty and high-value derivative products, with fatty alcohols and glycerine-based derivatives growing faster than the commodity fatty acid segment. Continued regulatory support for bio-based alternatives, combined with Japan's strong innovation capability, is expected to sustain above-average growth in premium oleochemical categories through the forecast horizon.
Research Methodology
Primary Research
Primary research included structured interviews with oleochemical manufacturers, specialty chemical distributors, personal care formulators, food industry procurement executives, and regulatory specialists in Japan, validating market sizing, segment mix, regional demand patterns, and key competitive dynamics.
Secondary Research
Secondary sources included Japan's Ministry of Economy, Trade and Industry (METI) publications, Japan Chemical Industry Association (JCIA) data, trade association reports, customs and trade statistics, company annual reports, press releases, and investor presentations from listed chemical manufacturers and oleochemical producers.
Forecasting Models
Market forecasts used top-down and bottom-up models combining oleochemical production data, end-use industry demand trends, trade flows, and macroeconomic variables. Scenario analysis addressed feedstock price movements, regulatory developments, technology adoption pace, and bio-based material investment trends in Japan and key export markets.
Japan Oleochemicals Market Report Coverage:
| Report Features | Details |
|---|---|
| Base Year of the Analysis | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Units | Billion USD |
| Scope of the Report |
Exploration of Historical and Forecast Trends, Industry Catalysts and Challenges, Segment-Wise Historical and Predictive Market Assessment:
|
| Types Covered | Fatty Acids, Fatty Alcohols, Glycerine, Others |
| Forms Covered |
|
| Applications Covered | Soaps and Detergents, Plastics, Paper, Lubricants, Rubber, Coatings and Resins, Personal Care Products, Others |
| Feedstocks Covered | Palm, Soy, Rapeseed, Sunflower, Tallow, Palm Kernel, Coconut, Others |
| Regions Covered | Kanto Region, Kansai/Kinki Region, Central/ Chubu Region, Kyushu-Okinawa Region, Tohoku Region, Chugoku Region, Hokkaido Region, Shikoku Region |
| Companies Covered | KAO Corporation, NOF Corporation, New Japan Chemical Co., Ltd., BASF SE, etc. |
| Customization Scope | 10% Free Customization |
| Post-Sale Analyst Support | 10-12 Weeks |
| Delivery Format | PDF and Excel through Email (We can also provide the editable version of the report in PPT/Word format on special request) |
Key Benefits for Stakeholders:
- IMARC’s industry report offers a comprehensive quantitative analysis of various market segments, historical and current market trends, market forecasts, and dynamics of the Japan oleochemicals market from 2020-2034.
- The research report provides the latest information on the market drivers, challenges, and opportunities in the Japan oleochemicals market.
- Porter's five forces analysis assist stakeholders in assessing the impact of new entrants, competitive rivalry, supplier power, buyer power, and the threat of substitution. It helps stakeholders to analyze the level of competition within the Japan oleochemicals industry and its attractiveness.
- Competitive landscape allows stakeholders to understand their competitive environment and provides an insight into the current positions of key players in the market.
Frequently Asked Questions About the Japan Oleochemicals Market Report
The Japan oleochemicals market size is estimated at USD 1.83 Billion in 2026, driven by rising demand from personal care, food processing, and industrial sectors alongside Japan's growing shift toward bio-based chemical inputs.
The market is projected to grow at a CAGR of 6.18% during 2026-2034, reaching USD 2.95 Billion, supported by expanding specialty oleochemical demand and Japan's bio-based chemistry initiatives.
Fatty acids dominate the type segment with a 42.6% share in 2025, the largest among all type categories, driven by high-volume demand from detergent manufacturers, personal care formulators, food processors, and industrial chemical producers.
Liquid is the largest form segment, commanding a 64.7% share in 2025, the dominant form category, driven by formulation preferences and process compatibility requirements across personal care, food, and industrial manufacturing.
Kanto Region commands 36.7% share in 2025, anchored by the concentration of oleochemical manufacturers, research institutions, and logistics infrastructure in the Greater Tokyo area.
Leading players include KAO Corporation, NOF Corporation, New Japan Chemical Co., Ltd., and BASF SE, among others.
Fatty alcohols growth is driven by rising demand for emollient, conditioning, and emulsifying agents in premium personal care and cosmetic formulations across Japan's advanced beauty market.
Key challenges include feedstock price volatility from palm oil dependence, competitive pressure from petrochemical alternatives in cost-sensitive segments, and capital requirements for manufacturing modernization.
Need more help?
- Speak to our experienced analysts for insights on the current market scenarios.
- Include additional segments and countries to customize the report as per your requirement.
- Gain an unparalleled competitive advantage in your domain by understanding how to utilize the report and positively impacting your operations and revenue.
- For further assistance, please connect with our analysts.
 Request Customization
 Speak to an Analyst
 Request Brochure
 Inquire Before Buying
Benefits of Customization
- Personalize this research
- Triangulate with your data
- Get data as per your format and definition
- Gain a deeper dive into a specific application, geography, customer, or competitor
- Any level of personalization
Get in Touch With Us
UNITED STATES
Phone: +1-201-971-6302
INDIA
Phone: +91-120-433-0800
UNITED KINGDOM
Phone: +44-753-714-6104
Email: [email protected]
Client Testimonials























Related Reports

Choose your plan
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Single User License
- 1 User License, Access on 2 Devices
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- No Printing Rights
- 10% Free Report Customization
- 10–12 Weeks of Analyst Support
Five User License
- Access for 5 Users, 2 Devices per User
- PDF Report + Excel Dataset (Password Protected)
- Lifetime Access
- Dedicated Account Manager
- 12–14 Weeks of Analyst Support
- No Printing Rights
- 15% Free Report Customization
- 25% Discount on Your Next Purchase
Corporate User License
- Unlimited User Access (Within Your Organization)
- PDF Report + Excel Dataset
- Lifetime Access
- Dedicated Account Manager
- 14–20 Weeks of Analyst Support
- No Printing Rights
- 20% Free Report Customization
- 30% Discount on Your Next Purchase
Essential Insights
What's included:
3 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 2 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Professional Access
What's included:
5 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 8 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Business Advantage
What's included:
8 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 14 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade
Enterprise Intelligence
What's included:
10 reports
- Lifetime Access
- PDF Reports
- Excel Datasets
- 20 Weeks of Free Analyst Support
- 2 User Licenses
- Access on 2 Devices
- Printing Rights
- Complimentary PowerPoint (PPT) Version
- Complimentary License Upgrade