What's Fueling Foreign Direct Investment in Saudi Arabia's Utility-Scale Renewable Energy Projects?
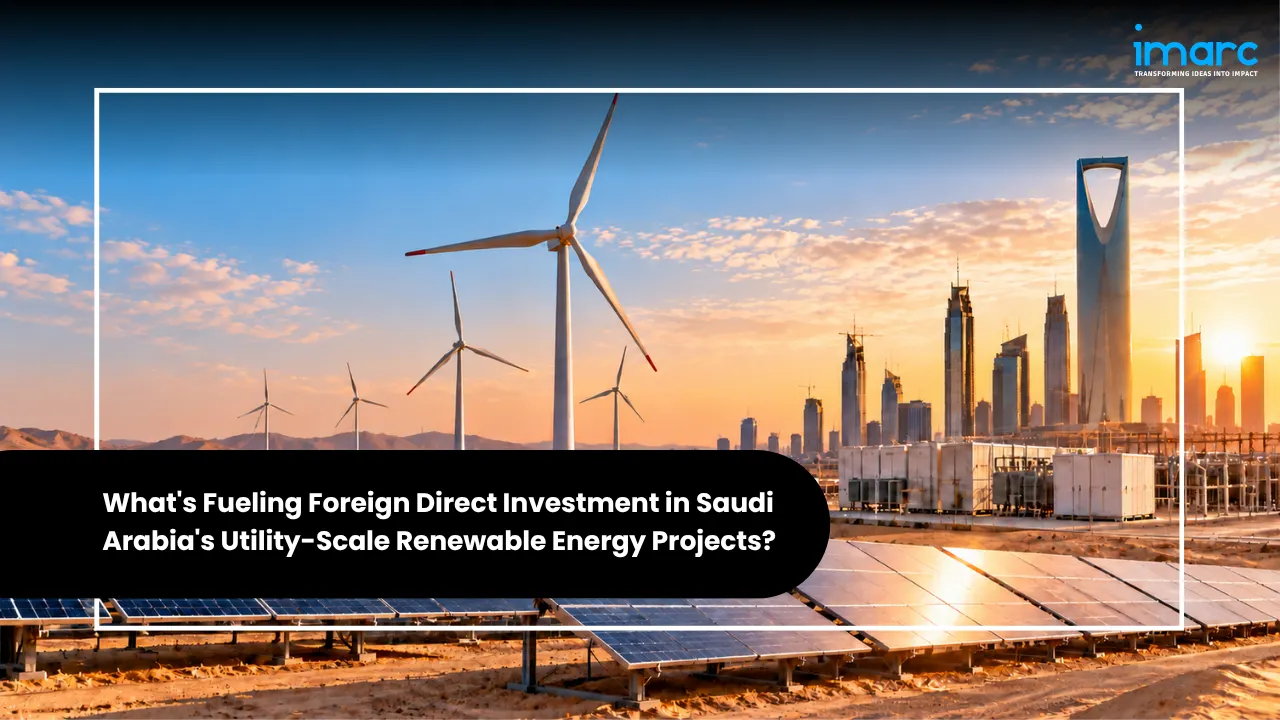
Introduction: Foreign Capital Moves into the Kingdom's Utility-Scale Pipeline
Saudi Arabia has turned its power transition into one of the world's largest procurement programmes, and international developers, lenders, and equipment makers are following the tenders. According to IMARC Group, the Saudi Arabia renewable energy market stood at 2.8 Gigawatt in 2025 and is projected to reach 40.8 Gigawatt by 2034, expanding at a CAGR of 34.46% (2026–2034). Few energy markets anywhere offer that combination of scale and speed.
What attracts foreign money is not the resource alone but the contracting structure. Projects are tendered as independent power producers with long-term power purchase agreements signed by the Saudi Power Procurement Company, a single sovereign-backed offtaker. Under the National Renewable Energy Program, that agency had already awarded over 19 GW of renewable capacity by 2024, with a mandate to supply 50% of the Kingdom's electricity from renewables by 2030.
The results are visible in deal size. In one transaction, ACWA Power, PIF subsidiary Badeel, and Aramco subsidiary SAPCO closed USD 8.2 billion of financing for 15 GW across seven solar and wind projects, with USD 5.9 billion of senior debt from 20 lenders including HSBC, Standard Chartered, Bank of China, and KfW IPEX-Bank. That syndicate is itself a measure of how deeply global capital is now committed.
This blog examines the Saudi Arabia renewable energy market's size and segments, recent announcements, the trends shaping investment, regional hotspots, competitive strategies, policy risks, and the long-range forecast, helping developers, financiers, and suppliers evaluate entry into the Kingdom.
Key Takeaways
- The Saudi Arabia renewable energy market stood at 2.8 Gigawatt in 2025 and is forecast to reach 40.8 Gigawatt by 2034, at a CAGR of 34.46% (2026–2034).
- Solar dominates the technology mix with a 93% share in 2025, while the Western Region leads geographically with a 35% share.
- A single consortium of ACWA Power, Badeel, and SAPCO reached financial close on USD 8.2 billion for 15 GW of solar and wind in November 2025.
- Round 7 of the National Renewable Energy Program covers 5.3 GW, with Masdar, EDF, ENGIE, TotalEnergies Renewables, and KEPCO among the qualified bidders.
- The NEOM green hydrogen complex, powered by 4 GW of solar and wind, is targeting production from mid-2027 under a 30-year Air Products offtake.
Market Size, Share & Growth Outlook
According to IMARC Group, capacity growth is concentrated in solar photovoltaics and in the provinces that combine strong irradiance with transmission access. Procurement volumes explain the trajectory: Round 6 alone brought 4,500 MW to tender across Dawadmi wind (1,500 MW), Najran (1,400 MW), Samtah (600 MW), Darb (600 MW), and Sufun (400 MW). The leading segments are:
- Type: Solar accounts for a 93% share in 2025, reflecting the Kingdom's irradiance levels and the speed at which photovoltaic plants can be built relative to wind.
- Wind: Wind is scaling from a smaller base, with 3 GW under construction at Starah (2 GW) and Shaqra (1 GW) in Riyadh Province, and a further 2.2 GW tendered in Round 7 at Bilghah and Shagran.
- Region: The Western Region leads with a 35% share in 2025, supported by projects around Makkah and Madinah provinces and proximity to major load centres.
- Storage: Grid integration is advancing alongside generation, with the Saudi Electricity Company deploying a 7.8 gigawatt-hour battery energy storage system in December 2025.
Saudi Arabia renewable energy investment is therefore moving in blocks of gigawatts rather than incremental additions, which is what makes the forecast growth rate achievable from a small 2025 base.
Recent News & Mega Announcements
Deal flow over the past two years has been dominated by large consortium transactions and new foreign entrants:
- In November 2025, ACWA Power, Badeel, and SAPCO announced financial close on 15,000 MW of renewable projects, comprising 12 GW of solar at Bisha, Humaij, Khulis, Afif1, and Afif2 and 3 GW of wind at Starah and Shaqra, with commercial operation expected between the second half of 2027 and the first half of 2028.
- In October 2025, TotalEnergies and Aljomaih Energy were awarded a 400 MW solar project at As Sufun, with operations beginning in 2027.
- In January 2026, Nextpower and Abunayyan Holding launched the Nextpower Arabia joint venture, with a Jeddah manufacturing facility starting up in the second quarter of 2026.
- In January 2026, the Saudi Power Procurement Company named qualified bidders for the 5.3 GW Round 7, including Masdar, EDF, ENGIE, TotalEnergies Renewables, KEPCO, and Alfanar.
The pattern is consistent: sovereign-linked sponsors anchor the equity, international utilities compete for the balance, and global banks fund the debt.
Industry Trends Shaping the Saudi Arabia Renewable Energy Market
Three trends explain why foreign direct investment keeps rising in the Kingdom's utility-scale pipeline:
1. Rising Foreign Investment in Utility-Scale Solar and Wind Projects
Foreign participation now spans equity, debt, and manufacturing. Round 7's qualified bidder list features Masdar, EDF, ENGIE, TotalEnergies Renewables, and KEPCO competing for six projects totalling 5.3 GW, while the 15 GW financing drew 20 lenders from Europe, Asia, and the Gulf, including Bank of China, China Construction Bank, Emirates NBD, and KfW IPEX-Bank. Supply-chain investment is following, with the Nextpower Arabia joint venture building in Jeddah, giving overseas suppliers a local production base rather than an export relationship.
2. Vision 2030-Driven Diversification into Green Hydrogen and Renewables
The Saudi Arabia renewable energy target 2030 is the anchor for every procurement decision. The National Renewable Energy Program aims to supply 50% of national electricity from renewables by 2030, and surplus clean power is being channelled into export molecules. The NEOM green hydrogen complex, backed by about USD 8 billion and 4 GW of wind and solar, is designed for 600 tonnes of hydrogen a day and up to 1.2 million tonnes of ammonia a year, with production targeted from mid-2027 under a 30-year Air Products offtake. Localization is part of the same agenda, with Public Investment Fund ventures in wind turbine components and photovoltaic cells.
3. Growth of Public-Private Partnerships and Independent Power Producer (IPP) Models
The independent power producer structure is what converts policy targets into bankable assets. Projects are contracted with the Saudi Power Procurement Company as sole offtaker under long-term agreements, with sponsors splitting equity between a developer, a PIF subsidiary, and an Aramco subsidiary. The procurement agency manages predevelopment, tendering, and offtake across the programme, which shortens development timelines and reduces the permitting and counterparty risk that foreign investors price most heavily.

Geographic Hotspots
The Western Region leads the Saudi Arabia renewable energy market with a 35% share in 2025, anchored by Makkah and Madinah provinces, where demand from cities, industry, and the Red Sea developments sits close to new generation. Khulis (2 GW) in Makkah Province and Humaij (3 GW) in Madinah Province are among the largest plants now financed.
Central Saudi Arabia is the second engine. Riyadh Province hosts Afif1 and Afif2 at 2 GW each along with the Starah and Shaqra wind projects, benefiting from strong wind resource and proximity to the largest load centre. In the south, Bisha in Asir Province adds 3 GW of solar, while Round 6 tendered 1,400 MW in Najran and 1,200 MW across Samtah and Darb in Jazan. In the northwest, the NEOM complex pairs 4 GW of wind and solar with hydrogen production, creating a cluster where generation is consumed on site rather than exported to the grid.
Competitive Landscape & Key Players' Strategies
Competitive activity is intensifying as leading developers expand their presence across the Kingdom, with sovereign-linked sponsors partnering international operators rather than competing against them. Key players include:
- ACWA Power: Anchors the largest portfolio, leading the 15 GW consortium with Badeel and SAPCO and securing USD 8.2 billion in financing.
- Alfanar Group: Competes as a local champion in the Round 7 tender for 5.3 GW of solar and wind, combining EPC capability with project development.
- Badeel and SAPCO: As subsidiaries of the Public Investment Fund and Aramco, they co-invest alongside developers to underwrite gigawatt-scale projects.
- EDF Renewables: Qualified for Round 7, and already among the established international developers active in the Kingdom.
- ENGIE Middle East: Builds on its regional water and power platform to bid utility-scale renewables.
- Masdar: Qualified for Round 7, extending its Gulf portfolio into Saudi solar and wind.
- TotalEnergies: Won the 400 MW As Sufun solar project with Aljomaih Energy in October 2025, pairing generation with its industrial footprint.
Winning bids increasingly depend on cost of capital and local content rather than technology, which favours consortia that pair a global balance sheet with a Saudi partner.
Policy & Regulatory Landscape, Challenges & Risks
The policy framework is built for investor certainty:
- National Renewable Energy Program: Runs the competitive rounds and targets 50% of electricity from renewables by 2030, having awarded over 19 GW to date.
- Single-Offtaker Model: Long-term power purchase agreements with the Saudi Power Procurement Company underpin project revenues.
- Localization Requirements: Public Investment Fund ventures in photovoltaic cells and wind turbine components support domestic content targets.
Key challenges and risks include:
- Execution gap between award and operation: Even fully financed projects are scheduled for commercial operation only in 2027 and 2028, so capacity targets depend on construction and grid connection running to plan.
- Technology concentration: With solar at 93% of the mix, output is heavily exposed to a single generation profile, raising the value of storage and dispatchable capacity.
- Grid and integration constraints: Large storage deployments such as the 7.8 gigawatt-hour system installed in 2024 indicate the scale of investment needed before high renewable shares can be absorbed reliably.
- Hydrogen offtake risk: The NEOM complex is not due to produce until mid-2027, and export economics for green ammonia remain unproven at scale.
Forecast 2026–2034
IMARC Group projects the Saudi Arabia renewable energy market to expand from 2.8 Gigawatt in 2025 to 40.8 Gigawatt by 2034, a CAGR of 34.46% (2026–2034). The near-term additions are already contracted: 15 GW reaching commercial operation between the second half of 2027 and the first half of 2028, plus 5.3 GW moving through Round 7.
Beyond 2028, growth depends on sustained tendering, grid build-out, and storage. Solar should remain dominant, with wind gaining share as Riyadh Province and Madinah projects commission, and hydrogen-linked demand creating a second market for captive generation. For international investors, the pipeline visibility is the differentiator, and demand for Saudi renewable energy strategy consulting is rising as new entrants assess bid economics, local content, and partner selection.
Opportunities for Stakeholders
- International Developers: Pre-qualify for upcoming rounds and partner with sovereign-linked sponsors to share development risk and meet local content expectations.
- Lenders & Institutional Investors: Participate in syndicated project finance backed by long-term agreements with a single sovereign-linked offtaker.
- Equipment Manufacturers: Establish local production, as photovoltaic and wind component ventures gain from localization policy.
- Storage & Grid Specialists: Supply batteries, transmission equipment, and flexibility services that a solar-heavy system needs to stay reliable.
- Hydrogen & Industrial Offtakers: Secure early positions in green ammonia supply from projects designed around dedicated renewable capacity.
Conclusion: Building the Kingdom's Next Renewable Decade
Foreign direct investment is flowing into Saudi Arabia's utility-scale pipeline because the Kingdom has removed the risks investors dislike most: uncertain offtake, fragmented permitting, and unclear volumes. With a projected CAGR of 34.46% (2026–2034) and gigawatt-scale rounds arriving on a regular cadence, the question for most players is timing rather than whether to enter.
For developers, the priority is to qualify early and build a credible local partnership. For financiers, the opening lies in long-dated, contracted infrastructure debt. For policymakers, keeping tender schedules and grid investment aligned will determine whether the 2030 targets are met, and whether the Kingdom converts contracted gigawatts into delivered power.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Setting up a Battery Manufacturing Plant in India is a high-demand, energy-driven venture, powered by the country's booming automotive sector, huge power-backup market, and the fast-growing shift to electric vehicles and renewable storage.
Setting up a Liquefied Natural Gas (LNG) Manufacturing Plant in India is a capital-intensive, strategically important venture, powered by the country's push toward a gas-based economy, the shift to cleaner fuels in transport and industry, and rising demand for LNG as a truck, bus, and industrial fuel.
The India carbon credit market is moving from a voluntary, project-by-project trade into a regulated national system with binding targets, a central registry, and exchange-based price discovery. According to IMARC Group, the market was valued at USD 33.69 Billion in 2025, grew to USD 44.42 Billion in 2026, and is projected to reach USD 405.47 Billion by 2034, expanding at a CAGR of 31.84% (2026–2034).
Setting up a Syngas Production Plant in India is a capital-intensive but strategically valuable venture, driven by the country's push for cleaner industrial fuels, coal and biomass utilization, and chemical self-reliance. Syngas, or synthesis gas, is a mixture of hydrogen and carbon monoxide produced by gasifying carbon-rich feedstocks, and it serves as a versatile building block for power, chemicals, hydrogen, and synthetic fuels. With abundant biomass, coal, and waste feedstock and growing policy support for gasification, India offers a favourable environment for new plants.
Setting up a Battery Energy Storage System Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's renewable energy expansion, grid modernization, and supportive storage policies. As solar and wind capacity scales up and the grid needs to balance variable generation, battery energy storage systems have become essential infrastructure.
Setting up a Lithium-ion Battery Recycling Plant in India is a capital-intensive but high-potential venture. India's rapid rise as a major electric-vehicle market, its large consumer-electronics base, and its fast-growing energy-storage sector are together creating one of the deepest and fastest-expanding pools of end-of-life lithium-ion batteries in the world.
Solar glass is a type of specialty glass that has high transmittance and is designed exclusively for use in solar energy systems. Unlike regular flat glass, solar glass is designed to have maximum light transmission with minimal losses due to reflection and absorption.
A solar inverter is a vital component in solar photovoltaic (PV) systems, responsible for transforming the direct current (DC) electricity produced by solar panels into alternating current (AC) electricity. This AC power is then suitable for use by the electrical grid, various appliances, and industrial equipment.
Australia has firmly established itself as a dominant force in the global liquefied natural gas (LNG) market, maintaining its position as one of the world's leading exporters. The country's strategic geographical location in the Asia-Pacific region, combined with substantial natural gas reserves, has enabled it to become a critical energy supplier to rapidly growing Asian economies, particularly China, Japan, and South Korea.
Japan's lead acid battery market stands as a cornerstone of the nation's energy storage infrastructure, demonstrating remarkable resilience and adaptability in an era dominated by rapid technological evolution. Despite the global shift toward lithium-ion technologies, the Japanese lead acid battery sector continues to thrive, driven by its unmatched cost-effectiveness, proven reliability, and exceptional recyclability.
Green hydrogen is the cleanest form of hydrogen available, as it is produced through water electrolysis using the electricity generated from renewable energy sources such as solar, wind, or hydropower. Carbon dioxide emissions are zero since no fossil fuels are used. Essentially, an electrolyzer is used in the electrolysis process to split water molecules into hydrogen and oxygen. The resulting hydrogen is refined by purification, compression, or liquefaction and then fed into various applications. Green hydrogen is considered a cornerstone of the global energy transition because it can store renewable energy, decarbonize hard-to-abate sectors, and serve as a sustainable alternative to fossil-fuel-based hydrogen.
Japan’s thermal power plant industry remains a crucial pillar of the nation’s energy infrastructure, providing a stable and reliable source of electricity for both industrial and residential consumption. Thermal power generation, which primarily involves the combustion of fossil fuels such as coal, natural gas, and oil, continues to play a key role despite increasing investments in renewable energy.
An electrical panel, also called a distribution board or switchboard, is an important installation in electrical infrastructure that acts as the main center for the distribution, control, and protection of electrical power within residential, commercial, and industrial systems. It acts as the point at which electrical energy is received from the utility or a source of power generation and is distributed to various circuits and equipment in an organized manner.
The global oil and gas EPC market is currently experiencing a remarkable transformation as it positions itself at the intersection of traditional energy demands and technological innovation. As of 2024, the market is demonstrating robust growth, reaching USD 52.9 Billion in 2024, depending on regional scope and market segmentation approaches. This substantial market base is supporting a major number of capital projects worldwide, including offshore platform projects and onshore installations that are collectively shaping the energy landscape.
Bamboo pellets are a biomass fuel type created through the compression of bamboo residues like shavings, sawdust, and chips into thick cylindrical pellets. They are an environmentally friendly substitute for conventional fossil fuels like natural gas and coal. Due to the fast growth rate and high biomass yield of bamboo, it has become one of the most renewable raw materials for the production of bioenergy.
Biomass briquettes are dense, solid fuel blocks made of compressed organic waste materials like sawdust, agricultural wastes, wood shavings, coconut shells, rice husk, or herbaceous biomass. The briquetting process usually involves drying the biomass to lower the moisture content (usually down to 10-15%), grinding or milling for a fine particle size uniformity, and then compressing under high pressure with or without a binding agent.
Biogas is a renewable energy form generated by the anaerobic fermentation of organic matter including agricultural residues, animal waste, municipal solid waste, sewage sludge, and food waste. Microorganisms in the absence of oxygen break down organic substances in the process and produce a gaseous mixture of mainly methane (CH4) and carbon dioxide (CO2), with traces of hydrogen sulfide (H2S) and water vapor.
A battery is an electrochemical energy storage system that transforms chemical energy into electrical energy by way of redox reactions between its electrodes and electrolyte. It consists of a single or multiple electrochemical cells, each having a positive electrode (cathode), a negative electrode (anode), and an electrolyte for ion transfer. Batteries are categorically divided into primary (non-rechargeable) and secondary (rechargeable) types.
The global energy landscape is undergoing a seismic transformation, with green hydrogen emerging as one of the most promising solutions to achieve deep decarbonization across sectors. Far from a niche technology, green hydrogen is emerging as a critical pillar of the future energy system, offering a pathway to a sustainable and resilient economy.
Transmission line towers are essential support components of transmission lines installed on overhead to distribute high-voltage electricity over long distances. Towers are made of galvanized steel, primarily, and are designed to tolerate mechanical stress, environmental loads, and electrical safety. Some of the important characteristics of transmission line towers are high structural strength, corrosion resistance, adaptability for modular design, and high service life. They are normally produced in lattice form (tubular or free-standing towers) or tubular form, with types including suspension towers, tension towers, angle towers, and terminal towers based on use.
The energy storage revolution is here, and it's powered by graphene. While the world struggles with the limitations of conventional lithium-ion batteries, a new technology is emerging that promises to shatter every performance barrier we've accepted as unchangeable.
Australia is undergoing a significant energy transformation, underscoring the growing role of renewable energy sources. These sources are key to combating climate change by reducing greenhouse gas emissions, the primary cause of global warming and air pollution. Beyond environmental benefits, renewable energy strengthens energy security by diversifying power sources and reducing dependence on volatile fossil fuel imports, contributing to greater energy independence.
Learn how to plan capital investment, manage raw material costs, post manufacturing cost and optimize operations for setting up solar panel plant.
Battery Energy Storage System (BESS) represents a power grid technology that stores electricity to enhance electric power grid reliability while increasing operational efficiency. BESS permits battery recharging during periods of low demand or extra grid supply capacity. BESS provides three principal operational functionalities which include power grid stabilization during supply disruptions, control of energy supply variations, and integration of intermittent renewable generation from wind and solar resources.
China's economic presence is expanding globally, and Latin America and the Caribbean (LAC) have become a focal point for its investments, especially within the energy sector. The region, rich in natural resources and experiencing rising energy demands, offers strategic opportunities for Chinese energy giants looking to invest and expand. LAC is currently leading a transformative movement towards sustainable energy. From 2015 to 2022, the region increased its renewable energy capacity by an impressive 51%, now generating 64% of its electricity from renewables such as hydropower, wind, and solar. This shift addresses the global demand for cleaner energy while supporting local economic growth and enhancing energy security.
Hydrogen is a clean, renewable, and widely available energy source that can be produced through various methods. Production techniques such as coal gasification, steam methane reforming, electrolysis, and thermochemical processes highlight its versatility. Hydrogen is essential in several critical sectors, including methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant. The increasing concern over carbon emissions and greenhouse gases has led to a shift towards cleaner fuel options. Hydrogen is recognized for its cleanliness and versatility as an energy carrier. Additionally, supportive government initiatives and favorable policies are driving the growth of hydrogen production globally.
Hydrogen is a clean, renewable, and abundant energy source derived from various methods. Its applications span across transportation, heating, and power generation. Diverse production methods, including coal gasification, steam methane reforming, electrolysis, and thermochemical processes, contribute to its versatility. Hydrogen plays a pivotal role in crucial sectors like methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant.
A floating solar farm is a renewable energy installation in which solar panels are mounted on floating structures in water bodies such as lakes, reservoirs, ponds, or even the sea. This technology, also known as a floating photovoltaic (PV) system, or “floatovoltaics,” enables solar power generation in areas with limited available land or where land use is restricted for other purposes. Floating solar farms offer various benefits, including improved solar panel efficiency through cooling, land conservation, reduction of evaporation and algae growth, and integration with hydropower facilities to generate both solar and hydroelectric power in the same location.
Nuclear power utilizes nuclear reactions to generate heat, which is then converted into electricity. This energy is released from the nucleus—the core of atoms composed of protons and neutrons. Nuclear power can be derived from nuclear fission, nuclear decay, and nuclear fusion reactions. Across the globe, nuclear power plants predominantly use the fission of uranium and plutonium to produce electricity. The heat generated from fission is used to create steam, which drives turbines connected to generators. Nuclear power offers several advantages over fossil fuels, such as minimal greenhouse gas emissions and a higher energy density, meaning a small amount of nuclear fuel produces a large amount of energy.