Why Demand for Cyber Insurance Could Rise Across Japan's Banking, Manufacturing, and IT Industries
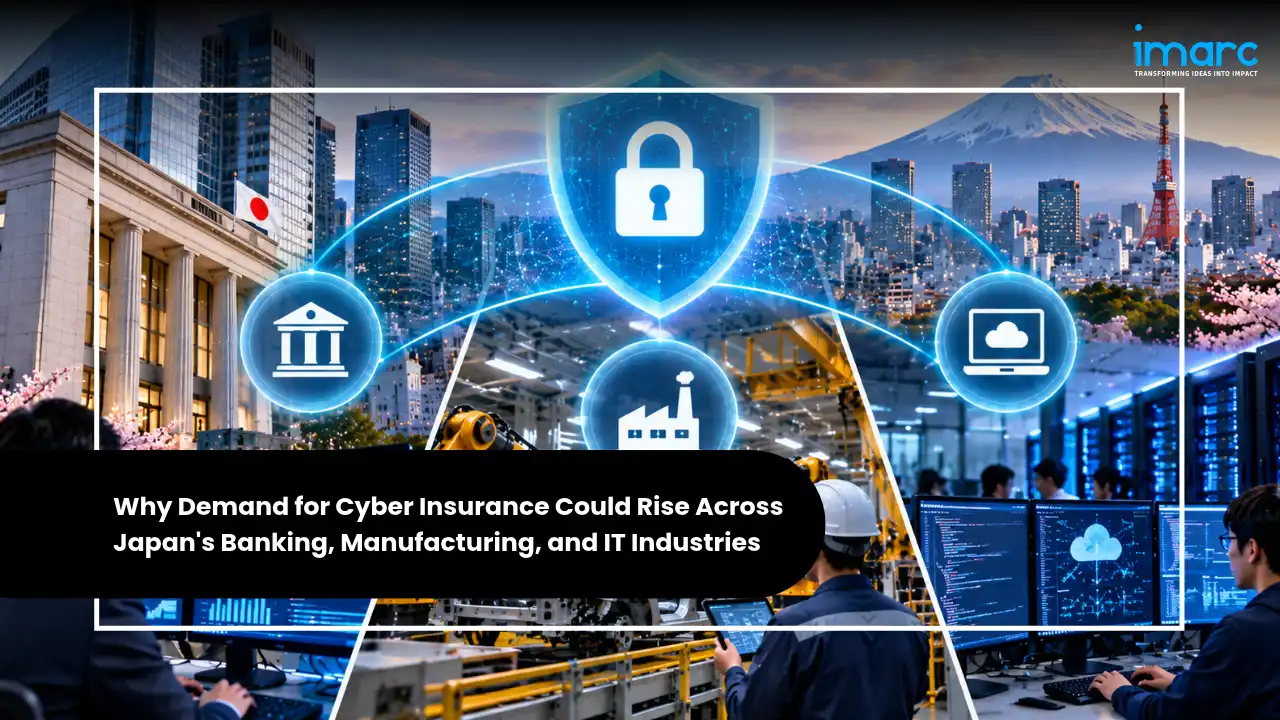
Introduction: Japan's Cyber Insurance Market Accelerates
The Japan cyber insurance market is entering a period of sustained expansion, driven by a convergence of rising cyberattack frequency, sweeping regulatory reform, and deepening enterprise digitalization. According to IMARC Group, the market was valued at USD 1,005.66 Million in 2025 and is projected to reach USD 4,798.00 Million by 2034, advancing at a compound annual growth rate (CAGR) of 18.96% from 2026 to 2034. This trajectory places Japan among the fastest-growing cyber insurance markets in the Asia-Pacific region, reflecting the scale of the opportunity as organizations across the country recognize cyber risk as a core financial exposure.
Several structural forces are propelling this growth. Japan's economy is undergoing rapid digital transformation, with widespread adoption of cloud infrastructure, Internet of Things devices, and remote work environments across banking, manufacturing, and technology sectors. Each layer of new connectivity adds measurable exposure. At the same time, ransomware campaigns targeting Japanese enterprises have become more sophisticated and costly, compelling boards and risk committees to formalize their cyber risk transfer strategies. Regulatory pressure from bodies such as the Financial Services Agency (FSA) is reinforcing this shift, making cyber insurance a logical complement to internal security investments.
A defining theme in Japan's cyber insurance industry is the integration of technology directly into the insurance value chain. Insurers are deploying artificial intelligence and machine learning to automate underwriting, price risk more precisely, and deliver real-time vulnerability monitoring to policyholders. In September 2025, Tokio Marine Kiln launched its enhanced Cyber Ctrl product suite, combining proactive risk management, physical damage protection, and sector-specific endorsements for construction, manufacturing, and utilities, illustrating how carriers are tailoring products to match the specific threat profiles of industrial sectors.
This blog examines the key market dynamics, segment performance, competitive strategies, regulatory developments, and investment opportunities shaping the japan cyber insurance market through 2034.
Key Takeaways
- The Japan cyber insurance market was valued at USD 1,005.66 Million in 2025 and is forecast to reach USD 4,798.00 Million by 2034, growing at a CAGR of 18.96%, reflecting the rapid institutionalization of cyber risk transfer across Japanese enterprises.
- The Solution segment leads with a 62% market share in 2025, driven by enterprise demand for AI-powered underwriting engines, real-time threat monitoring platforms, and integrated cyber risk assessment tools that enable insurers to identify and price digital vulnerabilities accurately.
- The BFSI sector holds the largest end-use share at 33% in 2025, underpinned by Financial Services Agency data protection mandates, high-value digital asset exposure, and the critical need to secure client financial data against escalating cyberthreats.
- In September 2025, Tokio Marine Kiln launched its enhanced Cyber Ctrl product suite with integrated proactive risk management, physical damage protection, and sector-specific endorsements for manufacturing, construction, and utilities, marking a significant product evolution in Japan's cyber insurance industry.
- The most prominent market trend is the growing adoption of AI-driven cyber risk analytics in underwriting workflows, which is enabling more accurate premium pricing, faster policy issuance, and scalable risk assessment across small and medium enterprises that account for a 48% share of the market by organization size.
Market Size, Share & Growth Outlook
According to IMARC Group, the Japan cyber insurance market was valued at USD 1,005.66 Million in 2025 and is projected to reach USD 4,798.00 Million by 2034, expanding at a CAGR of 18.96% during 2026-2034. This growth reflects the compounding effect of regulatory modernization, enterprise digitalization, and an increasingly active threat landscape that is forcing organizations of all sizes to formally quantify and transfer cyber risk. The leading segments are:
- Component: Solution accounts for a 62% share in 2025, reflecting strong enterprise demand for technology-driven platforms that combine threat intelligence, automated underwriting, and dynamic vulnerability monitoring into unified digital ecosystems.
- Insurance Type: Packaged coverage leads with a 55% share in 2025, as Japanese businesses increasingly prefer bundled policies that consolidate first-party loss protection, third-party liability, and incident response services within a single, simplified framework.
- Organization Size: Small and Medium Enterprises represent the largest segment at 48% in 2025, driven by heightened susceptibility to phishing and ransomware campaigns, combined with growing legal requirements that encourage smaller organizations to adopt formal cyber risk transfer mechanisms.
- End Use Industry: BFSI holds the dominant position at 33% in 2025, prompted by FSA-mandated data protection obligations, the concentration of high-value digital assets in financial institutions, and urgent demands to protect client information from increasingly targeted cyber campaigns.
Taken together, these segment dynamics indicate a market that is broad-based rather than concentrated in one niche, with meaningful demand emerging simultaneously from enterprise technology buyers, compliance-driven financial institutions, and cost-conscious small businesses seeking accessible coverage.
Recent News & Mega Announcements
The Japan cyber insurance market has seen a series of notable developments in 2025 that signal accelerating maturity across product innovation, regulatory reform, and enterprise risk awareness.
- Tokio Marine Kiln Cyber Ctrl Launch (September 2025): Tokio Marine Kiln introduced an enhanced version of its Cyber Ctrl product suite, featuring integrated proactive risk management capabilities, physical damage coverage extensions, and tailored endorsements for manufacturing, construction, and utilities sectors. The launch reflects growing insurer recognition that industrial organizations require coverage frameworks that address both digital and physical consequences of cyber incidents.
- Japan's Active Cyber Defense Act (2025): The Japanese government enacted the Active Cyber Defense Act, a landmark piece of legislation that authorizes government entities to take proactive defensive measures against cyber threats, including penetration of adversary systems under defined legal conditions. The law represents a fundamental shift in Japan's national cybersecurity posture from passive defense to active deterrence, and is expected to accelerate enterprise investment in complementary risk transfer solutions as organizations align with the broader national framework.
- Financial Services Agency Cybersecurity Guidelines Update: Japan's Financial Services Agency published comprehensive updated cybersecurity guidelines establishing detailed requirements for financial institutions regarding risk identification, attack defense, incident response protocols, and third-party vendor risk management. These requirements are creating structured compliance obligations that directly support cyber insurance adoption as a risk mitigation tool within the BFSI sector.
- Rising Ransomware Targeting of SMEs: Industry reporting through 2025 has documented a sustained increase in ransomware incidents targeting Japanese small and medium enterprises, which represent the largest organizational segment in the cyber insurance market at 48% share. The practical and financial disruption caused by these attacks is demonstrating to SME leadership, in concrete terms, the value of insurance coverage as a recovery mechanism, contributing to accelerating adoption rates across the segment.
Industry Trends Shaping 2026
Three interconnected trends are defining the trajectory of Japan's cyber insurance industry in 2026 and setting the foundation for growth through the forecast period.
1. Rising Adoption of AI-Driven Cyber Risk Analytics
Artificial intelligence and machine learning are becoming central to how insurers in Japan assess, price, and manage cyber risk. Traditional underwriting approaches relying on questionnaire-based evaluations are being replaced by automated platforms capable of scanning enterprise IT environments in real time, identifying vulnerabilities, and generating dynamic risk scores that inform premium pricing with far greater precision. Leading domestic carriers are partnering with international insurtech firms to access proprietary threat intelligence datasets and automated policy management tools, particularly to serve the small and medium enterprise segment, where manual assessment workflows are neither commercially viable nor operationally scalable. The practical benefit is twofold: insurers gain higher confidence in risk selection and pricing accuracy, while policyholders gain actionable visibility into their own security posture as a byproduct of the coverage procurement process. This feedback loop is reinforcing the value proposition of solution-based cyber insurance products and explaining, in part, why the Solution component commands a 62% market share.
2. Expansion of Packaged Cyber Coverage Solutions
Japanese insurers are investing significantly in the development of bundled cyber insurance products that integrate first-party loss indemnification, third-party liability protection, regulatory fine coverage, and incident response services into single unified policies. The appeal for enterprise buyers is clear: a single policy with coordinated terms eliminates the coverage gaps that arise when multiple standalone policies attempt to address different aspects of the same cyber incident. The September 2025 launch of Tokio Marine Kiln's enhanced Cyber Ctrl suite, which introduced sector-specific endorsements for manufacturing, construction, and utilities alongside broader proactive risk management and physical damage provisions, illustrates how insurers are moving beyond generic bundles toward industry-calibrated packaged products. For organizations operating across interconnected supply chains, where a single intrusion can cascade into operational shutdowns affecting multiple partners, comprehensive packaged coverage is the most practical and cost-effective risk transfer instrument available. This is driving the Packaged segment to its 55% share of Japan's cyber insurance market.
3. Strengthening Regulatory Mandates for Cybersecurity Compliance
Japan's regulatory environment has undergone meaningful transformation in 2025, and the direction of travel is toward greater mandatory accountability for cybersecurity risk across both public and private sector organizations. The enactment of the Active Cyber Defense Act represents the most significant legislative development, signaling that the government views cyber resilience as a national security imperative rather than a purely commercial concern. For the financial sector, the FSA's updated cybersecurity guidelines establish a detailed governance framework requiring institutions to demonstrate robust controls across risk identification, incident response, and third-party risk management, with cyber insurance increasingly referenced as a recommended component of a comprehensive risk management program. Taken together, these regulatory developments are converting what was previously a discretionary risk management decision into a compliance-linked procurement priority, broadening the addressable market and shortening enterprise sales cycles for insurers serving the BFSI, manufacturing, and IT sectors.

Geographic Hotspots
Japan's cyber insurance demand is concentrated in its three principal economic centers, each presenting a distinct driver profile that insurers are actively addressing through product specialization and distribution investment.
Tokyo, as Japan's financial and corporate headquarters hub, represents the single largest demand center in the market. The concentration of banking institutions, insurance companies, securities firms, and major technology corporations in the capital creates a dense cluster of organizations with both high cyber exposure and the financial sophistication to procure complex risk transfer products. The FSA's updated guidelines for financial institutions are particularly influential here, as Tokyo-based BFSI organizations are among the first to align their risk management frameworks with the new compliance requirements. The BFSI sector's 33% share of the national market is substantially driven by the density of regulated entities in the greater Tokyo region.
Nagoya and the broader Chubu industrial belt represent a growing hotspot driven by manufacturing sector demand. Japan's manufacturing sector, which includes automotive, electronics, and precision engineering industries, has faced increasing cyber pressure as adversaries target industrial control systems, proprietary production data, and complex supplier networks. The Tokio Marine Kiln Cyber Ctrl product suite's specific inclusion of manufacturing endorsements reflects insurer recognition of this demand cluster. As factories integrate smart manufacturing technologies and industrial IoT infrastructure, the attack surface expands and the financial consequences of operational disruption grow proportionally, making cyber insurance an increasingly rational procurement decision for plant operators and tier-one suppliers.
Osaka and the Kansai region contribute demand through its mix of pharmaceutical, healthcare, retail, and technology companies. Healthcare providers in particular are facing growing ransomware exposure, and the combination of sensitive patient data obligations and operational continuity requirements makes cyber insurance a logical component of institutional risk management. The government's broader push through the Active Cyber Defense Act framework is creating awareness across regional enterprises that have historically been slower to adopt formal cyber risk transfer products than their Tokyo-based counterparts, suggesting that geographic demand is broadening beyond the capital as regulatory and threat dynamics intensify nationally.
Competitive Landscape
The competitive landscape is shaped by a combination of established industry participants, emerging businesses, and specialized providers, with competition influenced by product quality, innovation, pricing strategies, distribution capabilities, and customer service. Market participants focus on strengthening their market presence by enhancing product offerings, improving operational efficiency, expanding distribution networks, and adapting to evolving consumer preferences. Technological advancements, changing purchasing behaviour, regulatory developments, and shifting industry requirements also influence competitive strategies. As market conditions evolve, businesses increasingly emphasize differentiation, value creation, and customer-centric approaches to sustain competitiveness and capitalize on emerging growth opportunities.
Policy & Regulatory Landscape, Challenges & Risks
Japan's policy environment is increasingly supportive of cyber insurance adoption, but the regulatory landscape also introduces compliance complexity and evolving underwriting challenges that participants must navigate carefully.
- Active Cyber Defense Act (2025): The legislation authorizes proactive government cyber defense measures and establishes a legal framework for public-private information sharing on threat intelligence. For insurers, the Act is significant because it signals a national commitment to reducing the baseline cyber risk environment over time, though it also raises questions about how government-initiated defensive actions may interact with insurance policy exclusions and claims processes.
- FSA Cybersecurity Guidelines: The Financial Services Agency's comprehensive updated guidelines create detailed compliance obligations for financial institutions, directly expanding the addressable market for cyber insurance products targeted at the BFSI sector. However, they also require insurers offering coverage to financial institutions to demonstrate that their own underwriting and claims capabilities meet rigorous operational standards.
- Personal Information Protection Commission (PPC) Enforcement: Japan's PPC has increased its scrutiny of data breach incidents under the Act on Protection of Personal Information, with mandatory breach notification requirements now in place. This regulatory pressure is creating direct financial liability exposure for organizations that suffer data incidents, reinforcing the value of cyber insurance as a mechanism for covering regulatory fines and notification costs.
Challenges & Risks
- Challenges in SME Risk Assessment: The small and medium enterprise segment, which accounts for 48% of the market by organization size, presents a consistent underwriting challenge. Many SMEs lack the security documentation and IT governance maturity needed for traditional risk assessment approaches, requiring insurers to invest in simplified onboarding tools and AI-assisted vulnerability scanning to evaluate these organizations accurately and efficiently.
- Systemic and Catastrophe Risk Accumulation: As the cyber insurance market grows in volume, insurers face increasing accumulation risk from large-scale incidents that affect multiple policyholders simultaneously, such as supply chain attacks targeting shared software dependencies or cloud infrastructure providers. Managing this exposure requires careful policy wording on exclusions, reinsurance program design, and scenario modeling, all of which add complexity to market development.
- Talent Shortages in Cyber Underwriting: Japan faces a well-documented shortage of cybersecurity professionals, and this constraint extends to the insurance sector, where experienced cyber underwriters and incident response specialists are in limited supply relative to the volume of new business entering the market.
Forecast 2026-2034
The Japan cyber insurance market is positioned for a sustained and substantial expansion through 2034, with the IMARC Group projecting growth from USD 1,005.66 Million in 2025 to USD 4,798.00 Million by 2034, at a CAGR of 18.96%. This nearly fivefold increase over the forecast period reflects a market transitioning from early adoption among large enterprises to broad institutional uptake across SMEs, mid-market companies, and regulated industries.
The first phase of the forecast period, from 2026 through approximately 2028, is likely to be characterized by accelerating penetration in the BFSI and large enterprise segments as FSA compliance requirements and Active Cyber Defense Act implementation create structured demand. Insurers will be investing heavily in technology infrastructure during this period, deploying AI-driven underwriting platforms and expanding their incident response capabilities to support growing policy volumes. Strategic partnerships between domestic carriers and global insurtech companies will be a defining feature of this phase, as Japanese insurers seek to accelerate capability development without building all technology infrastructure organically.
The middle forecast years, from 2029 through 2031, are expected to see the center of gravity shift toward the SME segment, which already accounts for the largest share of the market at 48% by organization size. As ransomware and phishing attacks continue to demonstrate their financial impact on smaller organizations, and as regulatory requirements cascade down supply chains to smaller suppliers and contractors, SME awareness and procurement rates will increase materially. Simplified digital distribution channels and standardized policy products designed for this segment will be essential to serving this demand at scale.
By the later forecast years, approaching 2034, the market is expected to reach a level of maturity where cyber insurance is treated as a standard component of corporate risk management across most industry sectors in Japan, comparable to the status of property and casualty coverage. Manufacturing sector penetration is a particularly significant growth vector, given the sector's scale in Japan's economy and its escalating vulnerability as industrial digitalization deepens. The Packaged insurance type, which currently holds a 55% share, is expected to retain its dominant position as insurers continue refining bundled offerings to deliver comprehensive, administratively convenient coverage frameworks that address the full spectrum of cyber risk dimensions.
Opportunities for Stakeholders
- Insurers and Underwriters: The most immediate opportunity lies in the SME segment, which holds a 48% share by organization size and remains underpenetrated relative to its cyber exposure. Carriers that invest in simplified digital onboarding workflows, AI-assisted risk scoring for organizations without extensive security documentation, and competitively priced entry-level packaged products will be best positioned to capture this volume at acceptable margins.
- Insurtech Companies and Technology Partners: There is significant demand for AI-powered cyber risk analytics platforms, automated vulnerability assessment tools, and real-time threat monitoring services that insurers can integrate into their underwriting and policy management workflows. Insurtech firms offering these capabilities through software partnerships or white-label arrangements have a clear pathway into the Japan market given the documented appetite among domestic carriers for technology collaboration.
- Manufacturing Sector Organizations: Japan's manufacturing companies face a growing cyber risk exposure as industrial IoT adoption deepens and supply chains become more digitally interconnected. Procurement teams and risk managers in this sector have an opportunity to leverage the increasingly specialized packaged products, including Tokio Marine Kiln's sector-specific manufacturing endorsements, to close coverage gaps that generic commercial policies do not address.
- BFSI Institutions: Financial institutions facing FSA compliance requirements have an opportunity to structure cyber insurance procurement as a core component of their regulatory risk management frameworks, rather than treating it as a supplementary purchase. This positions cyber coverage as a governance investment with a clear compliance rationale, simplifying internal budget approval processes.
- Brokers and Risk Consultants: The complexity of the Japan cyber insurance market, spanning multiple product types, evolving regulatory requirements, and rapidly changing threat profiles, creates strong demand for specialist advisory services. Brokers with expertise in cyber risk quantification and policy placement can differentiate meaningfully in a market where buyers, particularly SMEs, lack the internal expertise to evaluate coverage options independently.
- Reinsurers: The rapid growth of primary cyber insurance portfolios in Japan creates parallel demand for reinsurance capacity, particularly for catastrophic accumulation scenarios. Reinsurers with sophisticated cyber modeling capabilities and experience in structured treaty arrangements are well positioned to support Japanese market growth while managing their own exposure concentration.
Japan's Cyber Insurance Growth Is Just Beginning
The Japan cyber insurance market stands at an inflection point, where the combination of regulatory reform, enterprise digital transformation, and escalating threat activity is converting latent demand into active procurement across banking, manufacturing, IT, and a broad range of additional industries. The market's projected growth from USD 1,005.66 Million in 2025 to USD 4,798.00 Million by 2034, at a CAGR of 18.96% is not an abstract statistical projection; it reflects the concrete financial logic of organizations that have observed ransomware attacks shut down production lines, data breaches trigger regulatory investigations, and business interruption losses exceed what balance sheets can absorb without insurance support.
What makes Japan's trajectory distinctive within Asia-Pacific is the alignment of multiple reinforcing forces: a government that is moving from passive cybersecurity posture to active defense legislation, a financial regulator issuing detailed compliance frameworks that embed insurance considerations, a sophisticated domestic insurance industry investing in AI-integrated underwriting, and an SME sector that is beginning to recognize, through costly experience, that cyber risk is not a concern exclusive to large enterprises.
For insurers, technology partners, brokers, and risk management professionals, the next decade in Japan's cyber insurance industry represents one of the clearest and most broadly supported growth opportunities in the regional market. The organizations that build the analytical capabilities, distribution relationships, and product architectures now will define who captures the value of this expansion.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Japan spent decades as a market where conglomerates held non-core units indefinitely and founders passed businesses to family. Both assumptions have broken down, and private capital is absorbing the change.
Investor capital is rotating away from traditional Metro Manila residential product for a simple, measurable reason: the condominium market is oversupplied. Metro Manila closed 2025 with a residential vacancy rate of 24.7%, projected to peak at a record 25.6% by end-2026 as roughly 13,000 new units complete, nearly double 2025 deliveries, with Bay Area vacancy potentially approaching 60%.
Australia's property sector is drawing renewed investor attention because population-driven demand, a persistent housing shortage, and a tightening foreign investment regime are reshaping who can enter and how.
The Commercial Insurance Market reached USD 979.7 Billion in 2025 and is projected to reach USD 1,701.8 Billion by 2034, growing at a CAGR of 6.01% (2026–2034).
The Australia private equity industry is experiencing transformative growth as institutional investors increasingly allocate capital to high-potential sectors, including technology, healthcare, and renewable energy. The Australia private equity market size reached USD 23.9 Billion in 2025 and is projected to surge to USD 48.5 Billion by 2034, exhibiting a robust compound annual growth rate (CAGR) of 8.21% during 2026-2034.
The global maritime sector operates as the backbone of international trade, facilitating the movement of the world’s goods by volume. Within this vast and complex ecosystem, the marine insurance market plays an indispensable role by providing financial protection against risks inherent to maritime operations. From hull and machinery coverage to cargo, liability, and protection and indemnity (P&I) insurance, marine insurance safeguards the assets, revenues, and reputation of shipowners, cargo operators, and logistics companies.
The Australian travel insurance market has grown from a value-added travel product to a necessary protection for travelers. As confidence in domestic and foreign travel increases, Australian travelers increasing value full coverage against unexpected events like medical issues, flight cancellations, and trip interruptions.
Australia’s wealth management industry is undergoing a profound transformation, driven by rapid technological advancements, evolving investor behavior, and the increasing integration of artificial intelligence (AI) in financial services. The nation’s strong economic fundamentals, coupled with its expanding base of high-net-worth individuals (HNWIs) and robust superannuation system, have established a solid foundation for sustained market growth.
The Australia investment banking industry is experiencing transformative growth driven by technological innovation, sustainable finance initiatives, and robust mergers and acquisitions activity. With market valuations reaching USD 7.9 Billion in 2024, the sector demonstrates remarkable resilience despite global economic uncertainties.
The Australian fintech industry stands as one of the most dynamic and rapidly expanding financial technology ecosystems in the Asia-Pacific region. The market reached USD 4.10 Billion in 2024 and is projected to surge to USD 9.50 Billion by 2033, representing a compound annual growth rate (CAGR) of 8.90%. This remarkable trajectory positions Australia as a global fintech powerhouse, with around 767 companies operating across major capital cities including Sydney, Melbourne, and Brisbane.
Australia’s equity market is leaning into artificial intelligence as a practical lever for returns, liquidity, and product innovation. By size, the Australia stock market reached USD 72.9 Million in 2024 and is projected to hit USD 114.4 Million by 2033 at a 5.13% CAGR (2025–2033). Those headline figures sit on top of an economy where listed companies already deploy AI in operations, compliance, and customer-facing tools, while market plumbing: data centers, cloud, and connectivity, ramps for GPU-heavy workloads.
The Australian cryptocurrency market is experiencing significant growth, with the rise of digital assets capturing both public and institutional interest. Driven by technological innovation, evolving regulations, and increasing institutional adoption, the Australia cryptocurrency exchange market was valued at USD 975.76 Million in 2024, stated by the IMARC Group.
India’s real estate market is entering a new phase of structured growth, driven by a powerful confluence of factors. The real estate market size in India was valued at approximately USD 482 Billion in 2024, is being reshaped by robust residential demand, the expansion of commercial spaces, and increasing institutional investment.
In a progressively interconnected world, where digital operations form the backbone of commerce and daily life, the specter of cyber threats is no longer rare – it is becoming a daily headline. From phishing scams to full-blown ransomware assaults, cyber threats are evolving faster than most businesses can react.
India’s foreign exchange market has emerged as a crucial component of the nation's financial system. Over the past decade, its scale, depth, and liquidity have expanded significantly, fueled by increasing international trade volume, attracting foreign investments (FDI and FII), and facilitating outbound remittances.
India's real estate market is rapidly transforming, driven by urbanization, economic growth, and evolving consumer preferences. Real estate is no longer limited to residential and commercial properties; it is shaping infrastructure, technology-driven housing, and sustainable developments. With increasing investments, policy reforms, and rising demand for smart and affordable housing, the sector is witnessing significant expansion.
Real estate represents tangible property encompassing land and any enhancements, whether natural or artificial, affixed to it. It can serve various purposes, including residential, commercial, agricultural, and industrial. Ownership of real estate can belong to a government, a corporate entity, or a private party. The value of real estate is often influenced by factors such as location, demand, economic conditions, and market trends. Real estate markets can vary significantly from one region to another, with factors like population growth, urbanization, and infrastructure development playing crucial roles in shaping these markets.
The combustion of fossil fuels results in the release of a substantial amount of greenhouse gases, mainly carbon dioxide. Carbon dioxide emissions occur directly or indirectly from individuals, organizations, events, or products. A carbon footprint measures the environmental impact in terms of carbon emissions. Governments and organizations worldwide are engaged in various initiatives to reduce carbon emissions. In 1992, the United Nations Framework Convention on Climate Change (UNFCCC) introduced the "Kyoto Protocol," an international agreement aimed at significantly reducing greenhouse gas emissions. Adopted in Kyoto, Japan, on December 11, 1997, it became international law on February 16, 2005. Under the Kyoto Protocol, countries were allocated a maximum number of carbon credits. If a country exceeded its assigned limit, penalties in the form of a reduced emissions cap for the subsequent period were imposed.