Solar Panel Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
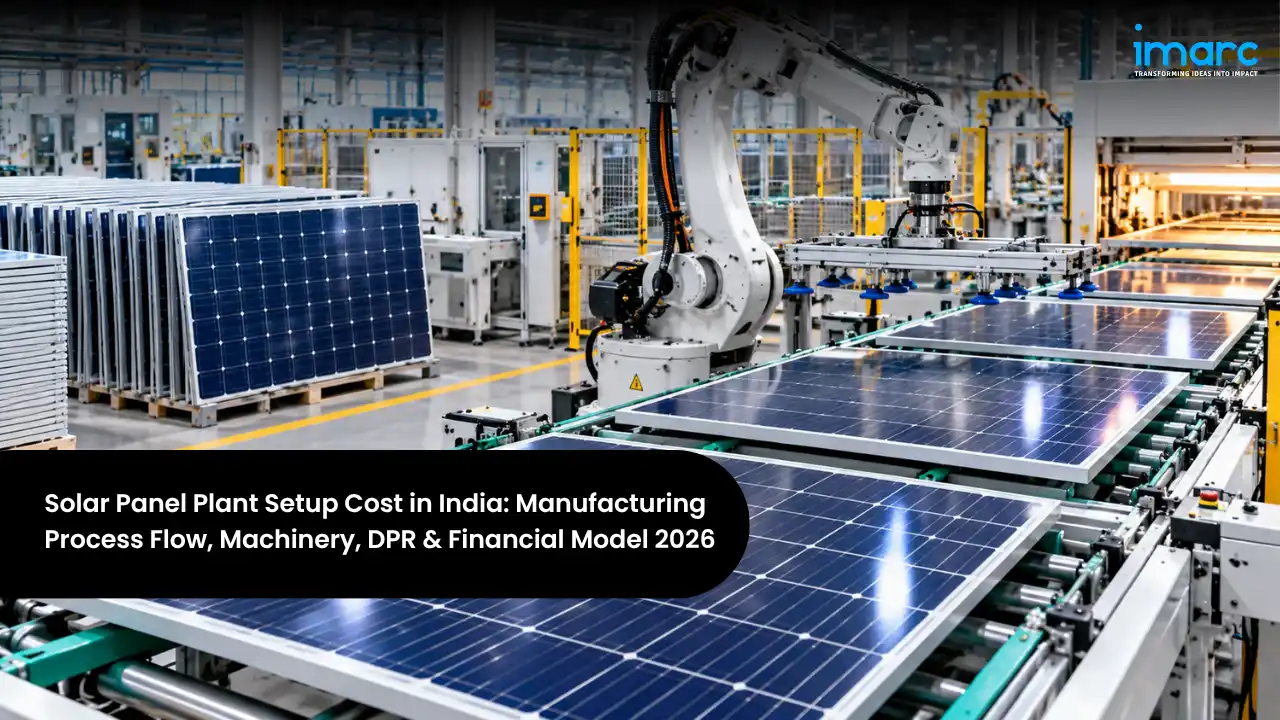
Few industries in India have scaled as quickly as solar manufacturing. Backed by ambitious renewable energy targets, a rooftop programme for households, import duties on foreign modules, and the Approved List of Models and Manufacturers (ALMM), domestic module capacity has multiplied in just a few years. For investors, a Solar Panel Manufacturing Plant Setup in India offers entry into a strategic, policy-backed sector, though one that now rewards technology choice, cost discipline, and cell integration far more than it did when capacity was scarce.
Capital needs depend on line capacity, cell technology, and the degree of automation. For a module assembly plant of roughly 100 MW to 2 GW, the Solar Panel Manufacturing Plant Cost typically falls between INR 25 crore and INR 400 crore, while backward integration into cells raises the figure several times over. Solar cells alone make up most of the operating cost of a module-only plant, so cell sourcing is the decision that shapes margins more than any other. At healthy utilisation, a competitive plant can deliver a net profit margin of 5 to 12% and an IRR of 14 to 22%, with payback usually reached within 3.5 to 5.5 years.
This guide is written for investors weighing how to start a Solar Panel manufacturing plant in India. It explains the product and technologies, the demand picture, production flow, machinery and raw materials, site and infrastructure planning, a detailed cost and financial breakdown, the certifications and approvals involved, and how a DPR brings everything together into a plan that lenders can evaluate.
India Market Snapshot
| Key Facts | Details |
|---|---|
| ALMM List-I Module Capacity | Over 217 GW enlisted (August 2026) |
| ALMM List-II Cell Capacity | Roughly 28–30 GW enlisted (April 2026) |
| Leading Technologies | TOPCon, Mono PERC, HJT, bifacial glass-glass |
| Key Demand Segments | Utility-scale, rooftop, C&I, exports |
| Indicative Total Investment | INR 25–400 Crore (module assembly) |
| Typical Payback Period | 3.5–5.5 Years |
The snapshot tells two stories. Demand is large and policy-supported, but enlisted module capacity has grown far faster than domestic cell capacity, and faster than annual installations. That gap is the key to planning: plants that secure competitively priced cells, move to newer technologies, and serve domestic-content (DCR) demand are well placed, while generic module-only capacity faces tighter margins. The rest of this guide works through those choices.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Product Range | TOPCon, PERC, HJT, and bifacial modules |
| Total Project Investment | INR 25 – 400 Crore (module assembly) |
| Payback Period | 3.5 – 5.5 Years |
| Net Profit Margin | 5 – 12% |
| IRR | 14 – 22% |
| Preferred States | Gujarat, Maharashtra, Rajasthan, Karnataka, Tamil Nadu, Telangana |
| Key Approvals | BIS registration, ALMM enlistment, Factory License, Fire NOC, E-waste EPR |
| Key Requirement | Reliable cell supply and ALMM-ready quality systems |
These ranges are a starting point for early planning. Actual returns depend on cell prices and availability, the technology the line is built for, how quickly the plant achieves BIS and ALMM listing, and whether offtake is secured with developers, EPC companies, or rooftop channels. A site-specific Solar Panel Feasibility Report narrows each of these assumptions to your chosen capacity, technology, and location.
Table of Contents
- What is Solar Panel Manufacturing?
- Why is Solar Panel Manufacturing Growing in India?
- Solar Panel Manufacturing Process Flow
- Raw Materials Required for Solar Panel
- Location, Land & Infrastructure
- Machinery and Equipment Required
- Solar Panel Manufacturing Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for Solar Panel Manufacturing in India
- Recent Developments in the India Solar Panel Manufacturing Industry
- How a Solar Panel Manufacturing Project Report and DPR Helps Investors
- Frequently Asked Questions
What is Solar Panel Manufacturing?
Solar panel manufacturing, more precisely called PV module manufacturing, is the assembly of solar cells into a sealed, framed, weatherproof unit that generates electricity for 25 years or more. Cells are interconnected into strings, laid up between glass and encapsulant layers, laminated under heat and vacuum, framed, fitted with a junction box, and tested for power output and safety. The quality of materials and process control directly determines a module's efficiency, reliability, and warranty performance.
The value chain runs from polysilicon to ingots, wafers, cells, and finally modules. Most new entrants start at the module stage, which needs the least capital and the shortest build time, and consider cell integration later. A well-run Solar Panel Manufacturing Plant can sell into several channels at once: utility-scale developers, EPC contractors, commercial and industrial rooftops, residential installers, and, for qualified producers, export markets.
- Utility-Scale Projects: Large solar parks and tenders that buy high-wattage modules in bulk, often with ALMM requirements.
- Rooftop and Residential: Household and small commercial systems, including schemes that require domestically made cells and modules.
- Commercial & Industrial: Factories and businesses installing captive and open-access plants to cut power costs.
- Exports: Markets that seek supply outside China, open to producers with strong quality systems and traceable supply chains.
The Main Module Technologies in Indian Manufacturing
Technology choice is the most consequential early decision, because it defines the equipment, the cell supply you need, and how long the line stays competitive:
| Technology | Description | Key Property | Primary Demand |
|---|---|---|---|
| Mono PERC | Established mono-crystalline cell design | Mature, lower cost | Price-sensitive rooftop and C&I |
| TOPCon | Tunnel oxide passivated contact cells | Higher efficiency, now mainstream | Utility-scale and C&I |
| HJT | Heterojunction cells | High efficiency, low degradation | Premium and utility projects |
| Bifacial Glass-Glass | Power from both faces, dual glass | Higher yield, long life | Utility-scale and trackers |
PERC is rapidly giving way to TOPCon as the industry standard, while HJT and back-contact designs occupy the premium end. Because cell technology moves quickly, a new line should be specified for current large-format wafers and TOPCon or HJT cells, with multi-busbar or zero-busbar stringing and glass-glass bifacial capability. A line built for yesterday's formats risks becoming uncompetitive well before its equipment is depreciated.
Why is Solar Panel Manufacturing Growing in India?
Key Growth Drivers in the Indian Market
Demand rests on a combination of national targets, supportive policy, and improving economics for buyers:
- Renewable energy targets: India's long-term clean energy goals require sustained additions of solar capacity every year, anchoring demand for modules.
- Rooftop programmes: Subsidised household rooftop schemes that require domestically made modules and cells are creating a large, distributed market.
- Trade protection: Basic customs duty on imported cells and modules, plus ALMM requirements, favour domestic supply for most projects.
- Commercial and industrial adoption: Businesses are installing solar to lower electricity bills and meet sustainability commitments.
- Manufacturing incentives: The PLI scheme for high-efficiency modules has accelerated investment in integrated capacity.
India-Specific Market Opportunity
| Segment | India Market Context | Manufacturing Role |
|---|---|---|
| Utility-Scale | Largest share of annual additions | High-wattage bifacial modules |
| Residential Rooftop | Subsidy-driven, DCR required | Domestic-cell modules |
| C&I and Open Access | Cost-saving captive demand | Efficient mid and large modules |
| Government Projects | ALMM and DCR mandated | Listed, certified supply |
| Exports | Buyers diversifying supply | Traceable, high-quality modules |
The strongest opportunity lies in modules made with domestic cells, which qualify for DCR-linked schemes and command a clear price premium over modules using imported cells. Producers who pair module lines with cell supply, whether their own or through long-term contracts with Indian cell makers, and who invest in current technologies are best placed as enlisted module capacity continues to outpace demand.
Solar Panel Manufacturing Process Flow
Understanding the flow helps you plan equipment, cleanroom-grade floor areas, and where yield losses arise. Module assembly is a highly automated sequence in which cells are tested, interconnected, encapsulated, and framed, with inspection built into several stages. Dust control, humidity management, and careful handling of fragile cells all affect yield.
The Solar Panel Manufacturing Process Flow
The sequence below describes a typical automated module line. Integrated plants add a cell line upstream, which involves a far more complex chemical and thermal process and a much larger investment.
| Unit Operation | Key Activity |
|---|---|
| Cell Inspection & Sorting | Cells tested and binned by power and appearance |
| Laser Cutting | Cells cut into half-cut or multi-cut pieces |
| Stringing | Cells soldered into strings with ribbon or wire |
| Layup & Bussing | Glass, encapsulant, strings, and back layer assembled |
| Pre-Lamination EL Test | Electroluminescence check for cracks and defects |
| Lamination | Stack sealed under heat and vacuum |
| Trimming & Framing | Excess material trimmed and aluminium frame fitted |
| Junction Box & Curing | Junction box attached, potted, and cured |
| Performance Testing | Sun simulator, final EL, and insulation tests |
| Labelling & Packing | Rated, labelled, palletised, and dispatched |
Two factors decide profitability across this flow. The first is yield: cells are the most expensive input, and every cracked cell or rejected module is a direct loss, so automated handling and inline EL inspection pay for themselves quickly. The second is power binning, because modules are sold by the watt, and a line that delivers consistently high output per module earns more from the same materials. Lamination is typically the throughput bottleneck, so laminator capacity usually sets the line's rated output.
Raw Materials Required for Solar Panel
The main inputs are solar cells, glass, encapsulant, backsheet or rear glass, aluminium frames, and junction boxes. Cells dominate cost and determine both the module's efficiency and its eligibility for domestic-content schemes, so cell sourcing is the heart of the supply plan.
| Raw Material | Role in Module | India Sourcing | % of OpEx |
|---|---|---|---|
| Solar Cells | Convert sunlight to electricity | Domestic cell makers and imports | 55–60% |
| Solar Glass | Front (and rear) protection | Domestic and imported | 5–8% |
| Aluminium Frames | Structural support | Domestic extruders | 4–7% |
| EVA / POE Encapsulant | Bonds and protects cells | Domestic and imported | 3–6% |
| Backsheet | Rear insulation (glass-foil modules) | Domestic and imported | 1–3% |
| Junction Box, Cables & Connectors | Electrical output | Domestic suppliers | 2–3% |
| Ribbon, Flux & Sealants | Interconnection and sealing | Domestic and imported | 1–2% |
Because cells account for well over half of operating cost, the gap between imported and domestic cell prices, and the premium that DCR modules command, largely decides a plant's margin. Imported cells attract customs duty, while domestic cells remain in short supply relative to module capacity. Long-term supply contracts, qualified alternative suppliers for glass and encapsulant, and a clear strategy on DCR versus non-DCR output are therefore central to the business plan.
Location, Land & Infrastructure
Site selection for a module plant is shaped by access to ports for imported inputs, proximity to major solar markets, reliable power, and state incentives. Because modules are heavy and fragile, freight to project sites is a meaningful cost, and several states now offer dedicated incentives and ready land in manufacturing parks.
Choosing the Best Location for Solar Panel Manufacturing Plant Setup
| State | Why It Works | Key Advantage |
|---|---|---|
| Gujarat | Around 40% of enlisted module capacity | Ports, supplier cluster, policy support |
| Maharashtra | Large industrial base and demand | Market access and skilled labour |
| Rajasthan | Largest solar installation base | Proximity to utility-scale projects |
| Karnataka | Strong electronics and solar ecosystem | Talent and supplier access |
| Tamil Nadu | Manufacturing incentives and ports | Export logistics and skilled workforce |
| Telangana | Growing solar manufacturing cluster | Land, power, and incentives |
Gujarat leads by a wide margin, with established clusters around Mundra, Dholera, and Surat, port access for imported cells and glass, and a deep supplier base. Rajasthan offers proximity to the country's largest solar parks, while Tamil Nadu, Karnataka, and Telangana combine incentives, skilled manpower, and export-friendly logistics. The final choice should weigh inbound input logistics, outbound freight to target customers, and the value of state capital subsidies and power tariff concessions.
Quality, Certification and ALMM Readiness
Market access for a module maker depends on certification as much as on price. Modules must be registered with BIS against the relevant Indian standards, and most projects require the manufacturer and its models to be enlisted on ALMM, which involves a factory inspection and verification of manufacturing capability. That means a controlled production environment, calibrated test equipment, documented quality procedures, traceability from cell to finished module, and reliability testing. An experienced Solar Panel Manufacturing Consultant in India can help plan the line, quality system, and certification sequence so the plant is ready for enlistment soon after commissioning.
Infrastructure Requirements (Mid-Sized Plant)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Total Land Area | 20,000 – 60,000 sq. metres | Industrial or solar park plot |
| Production Hall | Dust- and humidity-controlled | Protects cells and encapsulant |
| Power Requirement | 2 – 8 MW | Stable supply; rooftop solar common |
| Warehousing | Covered storage for inputs and pallets | Glass and modules need space |
| Testing Laboratory | Reliability and performance testing | Supports BIS and ALMM |
| Compressed Air & HVAC | Clean, dry air supply | For automation and environment control |
| Logistics Access | Highway and port connectivity | Heavy inbound and outbound freight |
Controlled production halls, reliable power, and ample warehousing form the backbone of a module plant. Planning floor space and power capacity for a second line, or for future cell integration, from the outset avoids costly rework, since most successful Indian manufacturers have expanded in phases.
Machinery and Equipment Required
Module assembly is highly automated, and the equipment set covers cell handling, stringing, layup, lamination, framing, and testing. Line capacity is usually quoted in MW or GW per year and is set largely by the stringers and laminators. The main machinery is summarised below.
| Equipment | Function | Key Specification |
|---|---|---|
| Cell Tester & Sorter | Grade incoming cells | Power and visual binning |
| Laser Cutting Machine | Produce half-cut or multi-cut cells | Low-damage, non-destructive cutting |
| Automatic Stringer | Solder cells into strings | Multi-busbar or zero-busbar capable |
| Automatic Layup & Bussing | Assemble module stack | Precise string placement |
| EL Tester (Inline) | Detect cracks and defects | Pre- and post-lamination |
| Laminator | Seal the module | Multi-stage, large-format capable |
| Trimming & Framing Machine | Finish edges and fit frames | Automatic, glass-glass capable |
| Junction Box Fixing & Potting | Attach and seal junction box | Automated dispensing |
| Sun Simulator (IV Tester) | Measure power output | Class AAA accuracy |
| Hi-Pot & Insulation Tester | Check electrical safety | Inline testing |
| Automated Conveyors & Packing | Move and palletise modules | Minimise handling damage |
Equipment should be chosen for the technology you intend to run for the next several years, not the one that is cheapest today. Stringers and laminators compatible with large-format TOPCon and HJT cells and glass-glass modules protect the line against rapid obsolescence, while inline EL testing and accurate sun simulators protect yield and customer trust.
Solar Panel Manufacturing Plant Setup Cost in India (CapEx & OpEx)
The tables below break down capital and operating costs for a mid-sized module assembly facility in India. The final Solar Panel Investment Cost for your project will depend on line capacity, technology, automation level, location, and whether cell manufacturing is included.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Plant & Machinery | 40–50% | Automated module line and testing |
| Land & Buildings | 18–25% | Controlled production hall and warehouse |
| Utilities & Electricals | 6–10% | Power, HVAC, compressed air |
| Testing Laboratory | 2–4% | Reliability and certification testing |
| Fire & Safety Systems | 2–3% | Detection, hydrants, safety systems |
| Pre-operative & Contingency | 5–8% | Engineering, DPR, certification, buffer |
| Working Capital | 10–15% | Cell and material stocks, receivables |
Machinery dominates the capital budget, and its specification, particularly technology compatibility and automation, has the biggest long-term effect on competitiveness. Working capital is also significant, since cells and glass must be bought ahead of sales and project customers often pay on milestones. A detailed Solar Panel Business Plan should model these items separately, along with the option of phasing in cell production, so that capacity and technology decisions rest on realistic numbers.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Raw Materials (cells, glass, frames) | 75–85% | Cells dominate; DCR cells cost more |
| Labour & Skilled Manpower | 3–5% | Highly automated lines |
| Power & Utilities | 2–4% | Lamination and HVAC loads |
| Quality, Testing & Certification | 1–3% | BIS, ALMM, reliability tests |
| Packaging & Logistics | 3–5% | Heavy, fragile product |
| Maintenance & Overheads | 2–4% | Equipment upkeep and admin |
With materials making up the large majority of operating cost, this is essentially a procurement-and-yield business. Margins move with cell and glass prices, so the operating model should track these closely and test profitability under different cell price scenarios, DCR premiums, and utilisation levels. Small improvements in yield and power binning have an outsized effect on the bottom line.
Financial Analysis and Profitability
Based on analysis of a mid-sized module assembly facility, the financial profile is sound but increasingly competitive. The profitability of Solar Panel manufacturing business in India depends heavily on securing cells at good prices, producing DCR modules, running current technology, and keeping utilisation high in a market where enlisted capacity exceeds annual demand.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 12–20% | Driven by cell cost and DCR premium |
| Net Profit Margin | 5–12% | After depreciation and Indian corporate taxes |
| Payback Period | 3.5–5.5 Years | Faster with DCR and long-term contracts |
| IRR (Internal Rate of Return) | 14–22% | Higher with cell integration |
| Capacity Utilization (stable ops) | 60–85% | Offtake contracts protect volumes |
| Break-even Capacity Utilization | 55–65% | Thin per-watt margins |
Technology, cell sourcing, and offtake determine where a plant lands within these ranges. A line assembling older-technology modules from imported cells competes largely on price and sits at the lower end, while a plant producing high-efficiency DCR modules with secured offtake can move toward the upper end. Because per-watt margins are thin, utilisation and yield carry unusual weight.
Returns can be strengthened by signing offtake agreements with developers and EPC firms before commissioning, building DCR capability through domestic cell contracts or integration, specifying lines for TOPCon and HJT, targeting rooftop channels where DCR modules command a premium, and pursuing export customers seeking non-Chinese supply. Strong quality systems that minimise warranty claims protect both margins and bankability.
Key Risks and Mitigation
The main risks are overcapacity and price pressure, cell supply and price volatility, rapid technology change, and policy shifts. Price risk is reduced by long-term offtake and a focus on DCR and premium segments; supply risk by multi-source cell contracts or integration; technology risk by specifying flexible, current-generation equipment; and policy risk by tracking ALMM, duty, and scheme changes closely. Promoters frequently work with a Solar Panel Business Plan Consultant in India to test these scenarios before committing capital.
Licenses and Approvals for Solar Panel Manufacturing in India
Solar module manufacturing is a certification-driven business, and approvals determine which projects a plant can supply. Promoters setting up a Solar Panel Manufacturing Plant in India generally need the following:
- BIS Registration: Registration under the compulsory registration scheme for solar PV modules against the applicable Indian standards, such as IS 14286 and IS/IEC 61730.
- ALMM Enlistment: Listing of the manufacturer and module models on MNRE’s ALMM List-I after factory inspection, required for most government-linked, net-metering, and open-access projects.
- Factory License: Registration and plan approval under the Occupational Safety, Health and Working Conditions Code, 2020.
- Pollution Control Consents: Consent to Establish and Consent to Operate from the State Pollution Control Board, as applicable to the unit category.
- E-Waste EPR Registration: Registration as a manufacturer under the E-Waste (Management) Rules, which cover solar PV modules, panels, and cells.
- Business & Tax Registration: Company incorporation, GST, Udyam, and an IEC for importing cells and exporting modules.
- Fire Safety & Labour Registrations: Fire NOC and employee welfare registrations such as EPF and ESI.
BIS registration and ALMM enlistment are the critical items, because without them a plant cannot supply most of the Indian market. Planning the testing laboratory, quality documentation, and inspection readiness alongside construction helps shorten the gap between commissioning and first commercial sales. State incentive applications should also be filed early, as they often require approvals before investment is made.
Note: The exact approvals, registrations, licenses, and certification requirements may vary depending on factors such as plant location, technology, target projects, export markets, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India Solar Panel Manufacturing Industry
Several recent developments shape the outlook for new entrants:
- ALMM List-II for cells: From June 1, 2026, covered projects must use cells from ALMM-listed manufacturers, raising demand for domestic cells and for modules built with them.
- Rapid module capacity growth: Enlisted module capacity passed 217 GW in August 2026, far ahead of domestic cell capacity, which is intensifying competition among module-only producers.
- Technology transition: The industry is moving from PERC to TOPCon, with HJT capacity also being added, shortening the competitive life of older lines.
- Backward integration: Leading manufacturers are investing in cells and, in some cases, wafers and ingots to secure supply and qualify for domestic-content demand.
The direction is clear: the market increasingly rewards integration, current technology, and domestic-content capability rather than raw assembly capacity. New entrants who plan for these realities, whether through cell partnerships, phased integration, or a focus on premium and DCR segments, will be best positioned through the rest of the decade.
How a Solar Panel Manufacturing Project Report and DPR Helps Investors
A detailed DPR provides a structured roadmap for the venture, from market demand and technology selection to machinery, layout, certification, and economics. It helps investors decide the right capacity and product mix, estimate capital and operating expenditure, assess profitability, and identify risks before any funds are committed.
At its core is a detailed Solar Panel Financial Model covering revenue by product and channel, per-watt cost build-ups, cell price scenarios, cash flows, break-even, return on investment, and payback. Banks and investors rely on this model to judge long-term viability, which is why many promoters appoint a Solar Panel Plant Project Report Consultant in India to prepare the report and test its assumptions against current market data.
For a solar project, a strong DPR also sets out the cell sourcing strategy, the technology roadmap, the certification timeline, and the offtake plan, which together are the factors most likely to decide success. By modelling utilisation against realistic demand and stress-testing margins against cell price movements, the report turns a competitive, fast-moving opportunity into a plan that lenders and partners can trust.
Frequently Asked Questions
What are the first steps to set up a solar panel manufacturing plant in India?
Start by deciding capacity, cell technology, and target segments, then commission a feasibility study and DPR. Next, secure land in a supportive state, order a line compatible with current cell formats, arrange cell and material supply, build the testing laboratory, and obtain BIS registration and ALMM enlistment along with the factory license, pollution consents, and Fire NOC.
How much does it cost to set up a solar panel manufacturing plant in India?
A module assembly plant of roughly 100 MW to 2 GW typically needs INR 25 crore to INR 400 crore, depending on capacity, technology, and automation. Adding cell manufacturing increases the investment several times over. Machinery, buildings, and working capital are the largest components.
What are the main steps in solar panel manufacturing?
The flow runs from cell inspection and sorting through laser cutting, stringing, layup and bussing, pre-lamination EL testing, lamination, trimming and framing, junction box fixing and curing, performance and safety testing, and labelling and packing.
Which machinery does a solar panel manufacturing plant need?
Key equipment includes a cell tester and sorter, laser cutting machine, automatic stringer, layup and bussing machine, inline EL testers, laminator, trimming and framing machine, junction box fixing and potting system, sun simulator, hi-pot tester, and automated conveyors and packing.
What raw materials are used to make solar panels?
The main inputs are solar cells, solar glass, aluminium frames, EVA or POE encapsulant, backsheet or rear glass, junction boxes with cables and connectors, and ribbon, flux, and sealants. Cells account for well over half of operating cost.
How profitable is solar panel manufacturing in India?
A competitive plant typically earns a 5 to 12% net margin and a 14 to 22% IRR, with payback in 3.5 to 5.5 years at healthy utilisation. Profitability improves with DCR modules, current technology, secured offtake, and cell integration, while module-only plants using older technology face tighter margins.
Which licenses does a solar panel plant need in India?
Typical approvals include BIS registration for solar PV modules, ALMM enlistment with MNRE, a factory license, State Pollution Control Board consents, E-waste EPR registration, a Fire NOC, and GST, Udyam, IEC, and labour registrations.
How do I get a feasibility study or DPR for a solar panel project?
A detailed feasibility study and DPR covers market demand, technology and cell strategy, plant design, certification, and full financials. Investors usually engage a Solar Panel Manufacturing Feasibility Study Consultant with experience in renewable energy manufacturing to prepare the report and validate it for lenders.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Setting up an Electrical Panel Manufacturing Plant in India is a fabrication-and-assembly venture powered by heavy grid modernisation, a fast-growing renewable-energy build-out, rising industrial and commercial construction, and the spread of automation across factories and buildings.
Saudi Arabia has turned its power transition into one of the world's largest procurement programmes, and international developers, lenders, and equipment makers are following the tenders.
Setting up a Battery Manufacturing Plant in India is a high-demand, energy-driven venture, powered by the country's booming automotive sector, huge power-backup market, and the fast-growing shift to electric vehicles and renewable storage.
Setting up a Liquefied Natural Gas (LNG) Manufacturing Plant in India is a capital-intensive, strategically important venture, powered by the country's push toward a gas-based economy, the shift to cleaner fuels in transport and industry, and rising demand for LNG as a truck, bus, and industrial fuel.
The India carbon credit market is moving from a voluntary, project-by-project trade into a regulated national system with binding targets, a central registry, and exchange-based price discovery. According to IMARC Group, the market was valued at USD 33.69 Billion in 2025, grew to USD 44.42 Billion in 2026, and is projected to reach USD 405.47 Billion by 2034, expanding at a CAGR of 31.84% (2026–2034).
Setting up a Syngas Production Plant in India is a capital-intensive but strategically valuable venture, driven by the country's push for cleaner industrial fuels, coal and biomass utilization, and chemical self-reliance. Syngas, or synthesis gas, is a mixture of hydrogen and carbon monoxide produced by gasifying carbon-rich feedstocks, and it serves as a versatile building block for power, chemicals, hydrogen, and synthetic fuels. With abundant biomass, coal, and waste feedstock and growing policy support for gasification, India offers a favourable environment for new plants.
Setting up a Battery Energy Storage System Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's renewable energy expansion, grid modernization, and supportive storage policies. As solar and wind capacity scales up and the grid needs to balance variable generation, battery energy storage systems have become essential infrastructure.
Setting up a Lithium-ion Battery Recycling Plant in India is a capital-intensive but high-potential venture. India's rapid rise as a major electric-vehicle market, its large consumer-electronics base, and its fast-growing energy-storage sector are together creating one of the deepest and fastest-expanding pools of end-of-life lithium-ion batteries in the world.
Solar glass is a type of specialty glass that has high transmittance and is designed exclusively for use in solar energy systems. Unlike regular flat glass, solar glass is designed to have maximum light transmission with minimal losses due to reflection and absorption.
A solar inverter is a vital component in solar photovoltaic (PV) systems, responsible for transforming the direct current (DC) electricity produced by solar panels into alternating current (AC) electricity. This AC power is then suitable for use by the electrical grid, various appliances, and industrial equipment.
Australia has firmly established itself as a dominant force in the global liquefied natural gas (LNG) market, maintaining its position as one of the world's leading exporters. The country's strategic geographical location in the Asia-Pacific region, combined with substantial natural gas reserves, has enabled it to become a critical energy supplier to rapidly growing Asian economies, particularly China, Japan, and South Korea.
Japan's lead acid battery market stands as a cornerstone of the nation's energy storage infrastructure, demonstrating remarkable resilience and adaptability in an era dominated by rapid technological evolution. Despite the global shift toward lithium-ion technologies, the Japanese lead acid battery sector continues to thrive, driven by its unmatched cost-effectiveness, proven reliability, and exceptional recyclability.
Green hydrogen is the cleanest form of hydrogen available, as it is produced through water electrolysis using the electricity generated from renewable energy sources such as solar, wind, or hydropower. Carbon dioxide emissions are zero since no fossil fuels are used. Essentially, an electrolyzer is used in the electrolysis process to split water molecules into hydrogen and oxygen. The resulting hydrogen is refined by purification, compression, or liquefaction and then fed into various applications. Green hydrogen is considered a cornerstone of the global energy transition because it can store renewable energy, decarbonize hard-to-abate sectors, and serve as a sustainable alternative to fossil-fuel-based hydrogen.
Japan’s thermal power plant industry remains a crucial pillar of the nation’s energy infrastructure, providing a stable and reliable source of electricity for both industrial and residential consumption. Thermal power generation, which primarily involves the combustion of fossil fuels such as coal, natural gas, and oil, continues to play a key role despite increasing investments in renewable energy.
An electrical panel, also called a distribution board or switchboard, is an important installation in electrical infrastructure that acts as the main center for the distribution, control, and protection of electrical power within residential, commercial, and industrial systems. It acts as the point at which electrical energy is received from the utility or a source of power generation and is distributed to various circuits and equipment in an organized manner.
The global oil and gas EPC market is currently experiencing a remarkable transformation as it positions itself at the intersection of traditional energy demands and technological innovation. As of 2024, the market is demonstrating robust growth, reaching USD 52.9 Billion in 2024, depending on regional scope and market segmentation approaches. This substantial market base is supporting a major number of capital projects worldwide, including offshore platform projects and onshore installations that are collectively shaping the energy landscape.
Bamboo pellets are a biomass fuel type created through the compression of bamboo residues like shavings, sawdust, and chips into thick cylindrical pellets. They are an environmentally friendly substitute for conventional fossil fuels like natural gas and coal. Due to the fast growth rate and high biomass yield of bamboo, it has become one of the most renewable raw materials for the production of bioenergy.
Biomass briquettes are dense, solid fuel blocks made of compressed organic waste materials like sawdust, agricultural wastes, wood shavings, coconut shells, rice husk, or herbaceous biomass. The briquetting process usually involves drying the biomass to lower the moisture content (usually down to 10-15%), grinding or milling for a fine particle size uniformity, and then compressing under high pressure with or without a binding agent.
Biogas is a renewable energy form generated by the anaerobic fermentation of organic matter including agricultural residues, animal waste, municipal solid waste, sewage sludge, and food waste. Microorganisms in the absence of oxygen break down organic substances in the process and produce a gaseous mixture of mainly methane (CH4) and carbon dioxide (CO2), with traces of hydrogen sulfide (H2S) and water vapor.
A battery is an electrochemical energy storage system that transforms chemical energy into electrical energy by way of redox reactions between its electrodes and electrolyte. It consists of a single or multiple electrochemical cells, each having a positive electrode (cathode), a negative electrode (anode), and an electrolyte for ion transfer. Batteries are categorically divided into primary (non-rechargeable) and secondary (rechargeable) types.
The global energy landscape is undergoing a seismic transformation, with green hydrogen emerging as one of the most promising solutions to achieve deep decarbonization across sectors. Far from a niche technology, green hydrogen is emerging as a critical pillar of the future energy system, offering a pathway to a sustainable and resilient economy.
Transmission line towers are essential support components of transmission lines installed on overhead to distribute high-voltage electricity over long distances. Towers are made of galvanized steel, primarily, and are designed to tolerate mechanical stress, environmental loads, and electrical safety. Some of the important characteristics of transmission line towers are high structural strength, corrosion resistance, adaptability for modular design, and high service life. They are normally produced in lattice form (tubular or free-standing towers) or tubular form, with types including suspension towers, tension towers, angle towers, and terminal towers based on use.
The energy storage revolution is here, and it's powered by graphene. While the world struggles with the limitations of conventional lithium-ion batteries, a new technology is emerging that promises to shatter every performance barrier we've accepted as unchangeable.
Australia is undergoing a significant energy transformation, underscoring the growing role of renewable energy sources. These sources are key to combating climate change by reducing greenhouse gas emissions, the primary cause of global warming and air pollution. Beyond environmental benefits, renewable energy strengthens energy security by diversifying power sources and reducing dependence on volatile fossil fuel imports, contributing to greater energy independence.
Learn how to plan capital investment, manage raw material costs, post manufacturing cost and optimize operations for setting up solar panel plant.
Battery Energy Storage System (BESS) represents a power grid technology that stores electricity to enhance electric power grid reliability while increasing operational efficiency. BESS permits battery recharging during periods of low demand or extra grid supply capacity. BESS provides three principal operational functionalities which include power grid stabilization during supply disruptions, control of energy supply variations, and integration of intermittent renewable generation from wind and solar resources.
China's economic presence is expanding globally, and Latin America and the Caribbean (LAC) have become a focal point for its investments, especially within the energy sector. The region, rich in natural resources and experiencing rising energy demands, offers strategic opportunities for Chinese energy giants looking to invest and expand. LAC is currently leading a transformative movement towards sustainable energy. From 2015 to 2022, the region increased its renewable energy capacity by an impressive 51%, now generating 64% of its electricity from renewables such as hydropower, wind, and solar. This shift addresses the global demand for cleaner energy while supporting local economic growth and enhancing energy security.
Hydrogen is a clean, renewable, and widely available energy source that can be produced through various methods. Production techniques such as coal gasification, steam methane reforming, electrolysis, and thermochemical processes highlight its versatility. Hydrogen is essential in several critical sectors, including methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant. The increasing concern over carbon emissions and greenhouse gases has led to a shift towards cleaner fuel options. Hydrogen is recognized for its cleanliness and versatility as an energy carrier. Additionally, supportive government initiatives and favorable policies are driving the growth of hydrogen production globally.
Hydrogen is a clean, renewable, and abundant energy source derived from various methods. Its applications span across transportation, heating, and power generation. Diverse production methods, including coal gasification, steam methane reforming, electrolysis, and thermochemical processes, contribute to its versatility. Hydrogen plays a pivotal role in crucial sectors like methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant.
A floating solar farm is a renewable energy installation in which solar panels are mounted on floating structures in water bodies such as lakes, reservoirs, ponds, or even the sea. This technology, also known as a floating photovoltaic (PV) system, or “floatovoltaics,” enables solar power generation in areas with limited available land or where land use is restricted for other purposes. Floating solar farms offer various benefits, including improved solar panel efficiency through cooling, land conservation, reduction of evaporation and algae growth, and integration with hydropower facilities to generate both solar and hydroelectric power in the same location.
Nuclear power utilizes nuclear reactions to generate heat, which is then converted into electricity. This energy is released from the nucleus—the core of atoms composed of protons and neutrons. Nuclear power can be derived from nuclear fission, nuclear decay, and nuclear fusion reactions. Across the globe, nuclear power plants predominantly use the fission of uranium and plutonium to produce electricity. The heat generated from fission is used to create steam, which drives turbines connected to generators. Nuclear power offers several advantages over fossil fuels, such as minimal greenhouse gas emissions and a higher energy density, meaning a small amount of nuclear fuel produces a large amount of energy.