Australia's Power Industry: How Coal Retirement and Data Centre Demand Are Reshaping Power Investment
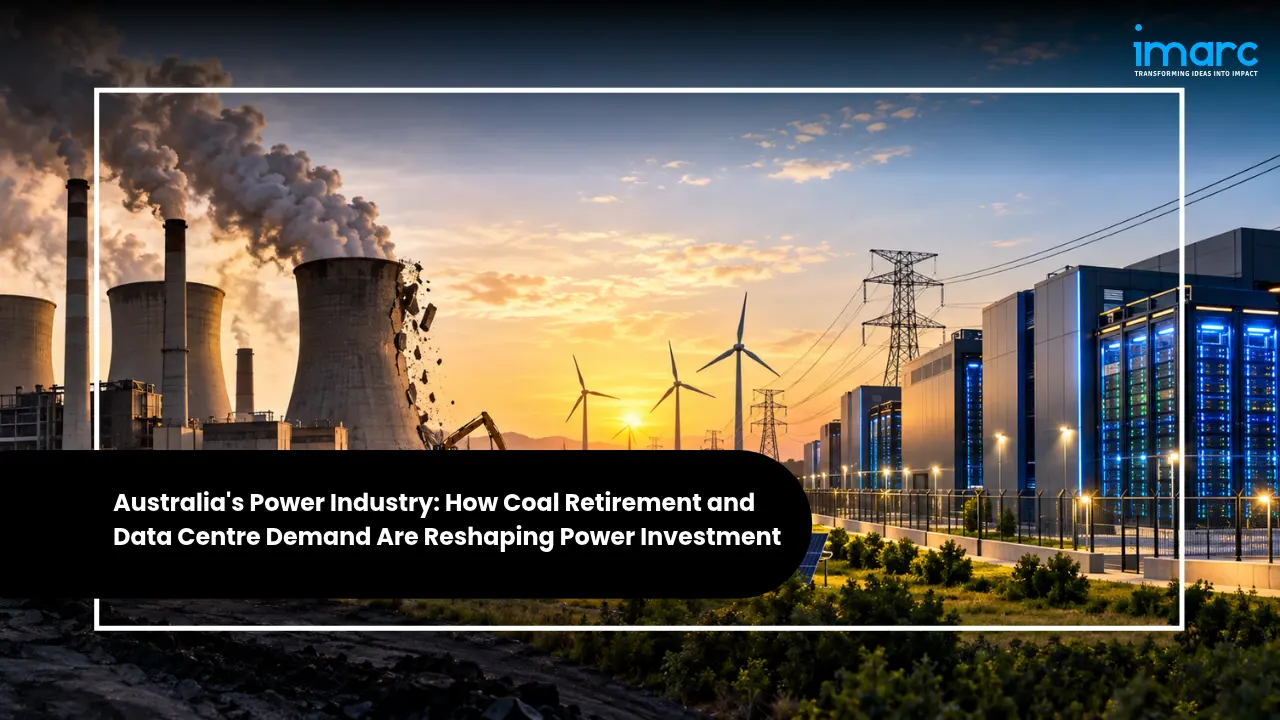
Introduction: Australia's Power Industry Enters a Coal-to-Clean Transition Era
The Australia Power Industry is the physical foundation of one of the developed world's most coal-reliant electricity systems, which is precisely why its transition now ranks among the largest infrastructure investment programmes in the country's history. According to IMARC Group, the market reached 285.7 TWh in 2025 and is projected to reach 385.5 TWh by 2034, expanding at a CAGR of 2.98% during 2026–2034. The policy architecture behind that trajectory is unusually explicit: the Australian Government's Climate Change Act 2022 legislated a 43% reduction in national greenhouse gas emissions below 2005 levels by 2030 and net zero by 2050, while the Department of Climate Change, Energy, the Environment and Water (DCCEEW) administers a complementary national target of 82% renewable electricity by 2030.
Demand-side and supply-side drivers are now pulling in the same direction. On the supply side, the Australian Energy Market Operator's Integrated System Plan assumes that roughly 90% of the National Electricity Market's coal-fired generation withdraws by 2035, and the federal Capacity Investment Scheme (CIS) has been expanded to 32 GW of new renewable generation and clean dispatchable capacity, underwritten through long-dated revenue contracts advised by AEMO Services. Rewiring the Nation, backed by AUD 20 billion in concessional finance, is rebuilding the transmission backbone on which renewable energy zones and new loads both depend. On the demand side, data centres, the electrification of transport and industry, and the displacement of gas in buildings and process heat are resetting load growth after more than a decade of flat consumption.
At the segmentation level, power generation source activity leads the Australia Power Industry with a 67.8% share, spanning coal, natural gas, oil, renewables and other technologies, with renewables taking almost all new capacity additions while coal and gas still carry the bulk of the energy balance. Storage is the fastest-moving layer of the market: IMARC Group values the Australia energy storage market at 4.72 GW in 2025, projected to reach 19.81 GW by 2034 at a 17.28% CAGR during 2026–2034. Regionally, the National Electricity Market spans Queensland, New South Wales, the Australian Capital Territory, Victoria, South Australia and Tasmania, with New South Wales the largest demand centre and Victoria and Queensland close behind, while Western Australia's South West Interconnected System operates a separate Wholesale Electricity Market. The defining theme is that investment has shifted from building megawatt-hours to building firmness, flexibility and grid access.
This blog examines the Australia Power Industry's size and segments, recent announcements, trends shaping 2026, geographic hotspots, competitive landscape, policy environment, forecast through 2034, and the opportunities available to generators, networks, investors, technology providers and large energy users.
Key Takeaways
- The Australia Power Industry reached 285.7 TWh in 2025 and is projected to reach 385.5 TWh by 2034, growing at a CAGR of 2.98% during 2026–2034.
- Power generation source leads the market with a 67.8% share, covering coal, natural gas, oil, renewables and other technologies, while storage is the fastest-growing layer, rising from 4.72 GW in 2025 to 19.81 GW by 2034 at a 17.28% CAGR (2026–2034).
- New South Wales is the largest demand centre in the National Electricity Market, followed by Victoria and Queensland, with South Australia, Tasmania and the Australian Capital Territory completing the NEM and Western Australia operating a separate Wholesale Electricity Market.
- Coal retirement sets the investment clock: AEMO's planning assumes about 90% of NEM coal-fired generation withdraws by 2035, and the Capacity Investment Scheme has been expanded to 32 GW of new renewable and clean dispatchable capacity backed by long-dated underwriting.
- AGL Energy's 500 MW Liddell Battery and Origin Energy's 700 MW Eraring battery show the scale of the firming build-out now taking shape at retiring coal sites, supported by an AUD 1.2 billion commitment to battery storage at Loy Yang.
Australia Power Market Size, Share & Growth Outlook
According to IMARC Group, the Australia Power Market reached 285.7 TWh in 2025 and is projected to reach 385.5 TWh by 2034, at a CAGR of 2.98% during 2026–2034, with the market standing at 277.10 TWh in 2024 and on track for 374.38 TWh in 2033. Growth is modest in volume terms but radical in composition, because every terawatt-hour that coal leaves behind must be replaced by a combination of variable renewables, firming storage, gas peaking and transmission capacity. The leading segments are:
- By Power Generation Source: Generation-source activity is the largest segment of the market with a 67.8% share, spanning coal, natural gas, oil, renewables (hydro, solar and wind) and other technologies. Coal still provides the largest single block of energy, but renewables now account for the overwhelming majority of new capacity entering the system.
- By Region: Australia Capital Territory & New South Wales is the largest regional market by demand, followed by Victoria & Tasmania, with Queensland, Western Australia, and Northern Territory & Southern Australia completing the national picture. Western Australia's South West Interconnected System sits outside the NEM and is served by its own Wholesale Electricity Market and state-owned generation fleet.
Recent News & Mega Announcements
Recent developments in the Australia Power Industry include significant announcements, investments and partnerships:
- In March 2026, AGL Energy moved its 500 MW Liddell Battery into commissioning at the site of the retired Liddell power station, the largest grid-scale battery in its portfolio, supported by a further AUD 1.2 billion commitment to battery storage at Loy Yang as part of its coal-to-firming replacement programme.
- In May 2026, Origin Energy continued construction of the 700 MW Eraring battery alongside the continued operation of the 2,880 MW Eraring coal station, positioning Australia's largest energy retailer as the country's biggest supplier of dispatchable generation capacity in the National Electricity Market.
- In May 2024, the Australian Government expanded the Capacity Investment Scheme to 32 GW of new renewable generation and clean dispatchable capacity, split between roughly 23 GW of variable renewable capacity and 9 GW of dispatchable capacity, with AEMO Services appointed as the independent adviser administering the tenders.
- In June 2024, the Australian Energy Market Operator released the 2024 Integrated System Plan, which found that about 90% of the National Electricity Market's coal-fired generation is expected to withdraw by 2035 and set out the transmission projects and firming capacity required to keep the system reliable through the transition.
- In August 2024, AEMO's annual Electricity Statement of Opportunities flagged reliability risks in the National Electricity Market as coal plants retire faster than replacement firming capacity and transmission are delivered, reinforcing the case for underwriting new dispatchable assets.
Industry Trends Shaping 2026
Three trends are shaping the Australia Power Industry in 2026:
1. Coal Retirement Sets the Investment Clock
AEMO's Integrated System Plan assumes roughly 90% of National Electricity Market coal-fired generation withdraws by 2035, and the closure calendar now runs from Eraring in August 2027 through Yallourn in mid-2028, Bayswater in 2033 and Loy Yang A in 2035. Because those plants supply the bulk of firm capacity today, every closure date triggers a corresponding firming investment decision, and the Capacity Investment Scheme's 32 GW underwriting programme exists precisely to pull that replacement capacity forward.
2. Data Centres and Electrification Reset Demand Growth
Demand growth has returned after a decade of flat consumption. IMARC Group values the Australia data centre power market at USD 427.99 Million in 2026, projected to reach USD 665.04 Million by 2034 at a 5.66% CAGR (2026–2034), as hyperscale campuses cluster around Sydney, Melbourne and Brisbane where fibre, land and grid capacity intersect. Electrification of transport, buildings and industrial process heat adds a second load block, and AEMO's planning scenarios now treat data centres and electrification as structural, not marginal, sources of new demand.
3. Storage Becomes the Firming Backbone
Storage has moved from pilot to procurement. IMARC Group puts the Australia energy storage market at 4.72 GW in 2025, rising to 19.81 GW by 2034 at a 17.28% CAGR (2026–2034). The build-out is anchored by marquee assets: Snowy Hydro's 2,200 MW Snowy 2.0 pumped hydro scheme, Origin's 700 MW Eraring battery, AGL's 500 MW Liddell battery and EnergyAustralia's 350 MW Wooreen battery in Victoria, all replacing coal-origin firmness with dispatchable, fast-ramping capacity.

Geographic Hotspots
New South Wales is the largest power market in the National Electricity Market and the centre of the transition's hardest trade-offs. The state's Electricity Infrastructure Roadmap, legislated through the Electricity Infrastructure Investment Act 2020, established five declared renewable energy zones and a Consumer Trustee to underwrite new generation, storage and transmission, while the retirement of Eraring, Bayswater and Mount Piper forces the state to replace thousands of megawatts of firm capacity within a single decade. Sydney's data centre corridor, the Hunter Valley's industrial load and the state's reliance on interstate imports during peak periods make New South Wales the decisive market for firming investment and for the HumeLink and EnergyConnect transmission projects.
Victoria combines the country's most aggressive renewable energy targets with the deepest industrial demand, and its offshore wind programme is designed to add large-scale capacity close to the Melbourne load centre. The state's grid is being reshaped by the Western Renewables Link and VNI West, which connect the western renewable energy zones to the load centre and strengthen the Victoria–New South Wales transfer path. Queensland follows closely, with its publicly owned generation fleet, Renewable Energy Zones and state plan to reach 70% renewable electricity by 2032 and 80% by 2035, complemented by large-scale solar, wind and pumped hydro projects in the state's north and central regions.
South Australia remains the world's most instructive high-renewables laboratory, with rooftop solar penetration so high that wholesale prices regularly turn negative in the middle of the day and grid-scale batteries are now the primary source of evening firming. The state's position is reinforced by Project EnergyConnect, the interconnector to New South Wales that adds around 800 MW of transfer capability and allows South Australian wind and solar to reach eastern demand centres, while Tasmania supplies hydro firmness through Basslink and the planned 1,500 MW Marinus Link.
Western Australia sits outside the National Electricity Market and operates on its own terms. The South West Interconnected System runs a separate Wholesale Electricity Market, and the state's government-owned coal-fired stations in Collie are scheduled to close by 2029, leaving a gap that is being filled by rooftop solar, utility-scale wind and solar, big batteries and gas-backed firming. The state's distance from the eastern grid, combined with mining and industrial load from iron ore, lithium and alumina operations, makes it one of the least substitutable power markets in the country.
Competitive Landscape & Key Players' Strategies
Competitive activity is intensifying as leading players expand across the Australia Power Industry:
- AGL Energy Ltd.: Australia's largest listed electricity generator and retailer, operating the Loy Yang A, Bayswater, Torrens Island and other assets, with a strategy built on replacing coal with renewable and firming capacity and a battery portfolio that includes the 500 MW Liddell Battery and an AUD 1.2 billion storage commitment at Loy Yang alongside wind and solar offtake agreements.
- Origin Energy Ltd.: Australia's largest energy retailer and the operator of the 2,880 MW Eraring power station, whose closure was extended to August 2027, while the company builds the 700 MW Eraring battery and expands through its stake in Octopus Energy and its integrated generation, retail and energy markets businesses.
- Snowy Hydro Ltd.: The federal government-owned generator behind Snowy 2.0, a 2,200 MW pumped hydro expansion with 350,000 MWh of storage, whose portfolio of hydro, gas-fired peaking and retail brands makes it the largest single provider of flexible capacity on the east coast and a decisive counterparty for grid stability services.
What wins in this market is a combination of firming optionality, a contracted revenue base, network connection rights secured ahead of the queue and the balance sheet to carry multi-decade assets through a decade of policy and price volatility.
Policy & Regulatory Landscape
The Australia Power Industry operates within a supportive and unusually explicit policy and regulatory framework:
- Climate Change Act 2022: Legislated a 43% reduction in greenhouse gas emissions below 2005 levels by 2030 and net zero by 2050, providing the statutory anchor that underpins the electricity sector's decarbonisation timetable.
- 82% Renewable Electricity Target: Administered by DCCEEW, it sets the national ambition for renewable generation share by 2030 and shapes federal underwriting, transmission planning and state-level targets.
- Capacity Investment Scheme (CIS): A federal underwriting programme expanded to 32 GW of new renewable and clean dispatchable capacity, delivering long-dated revenue contracts through tenders advised by AEMO Services, which de-risks investment and pulls firming capacity forward.
- Renewable Energy Target (RET): Requires 33,000 GWh of additional large-scale renewable generation by 2030 and operates the Small-scale Renewable Energy Scheme that has driven Australia's world-leading rooftop solar penetration.
- Rewiring the Nation: A AUD 20 billion concessional financing programme, supported by the Rewiring the Nation Corporation, dedicated to building and upgrading the transmission projects identified in AEMO's Integrated System Plan, including HumeLink, VNI West, EnergyConnect and Marinus Link.
- Integrated System Plan (ISP): AEMO's statutory biennial roadmap sets out the least-cost development path for generation, storage and transmission, and has become the reference document used by investors, network businesses and governments to sequence the transition.
- National Electricity Rules and Market Bodies: The Australian Energy Market Operator, Australian Energy Regulator and Australian Energy Market Commission govern dispatch, reliability obligations, network regulation and market design across the National Electricity Market, while Western Australia's Wholesale Electricity Market operates under a separate framework.
- Default Market Offer and Victorian Default Offer: Retail price caps set by the Australian Energy Regulator and the Essential Services Commission protect household and small business customers, shaping retailer conduct and the economics of retail competition.
- State Roadmaps and Plans: New South Wales's Electricity Infrastructure Roadmap legislated five renewable energy zones and an underwriting Consumer Trustee; Queensland's Energy and Jobs Plan targets 70% renewable electricity by 2032 and 80% by 2035; Victoria combines a 95% renewable target for 2035 with offshore wind capacity targets; and Western Australia has committed to closing its state-owned Collie coal stations by 2029.
- Future Gas Strategy: Confirms the continued role of gas as a firming and peaking fuel while the renewable build-out proceeds, supporting new investment in fast-start gas capacity alongside storage.
Challenges & Risks
Key challenges and risks include:
- Reliability gaps during the coal exit: AEMO's Electricity Statement of Opportunities has repeatedly flagged reliability risks as coal plants retire faster than replacement firming capacity and transmission are delivered, and a single delayed project can widen the gap in a supply-constrained region.
- Transmission delays and approval risk: HumeLink, VNI West and other critical projects face long approval timelines, landholder negotiations and cost escalation, which slows the connection of renewable energy zones and directly constrains how quickly new generation can reach demand.
- Social licence and community opposition: Rural and regional opposition to new transmission lines and large-scale renewable developments can delay or reshape projects, adding cost and uncertainty to development pipelines.
- Wholesale price volatility and negative pricing: Very high daytime solar penetration pushes prices negative in several regions and compresses the revenue available to merchant generators, making unhedged projects harder to finance and raising the cost of capital for new entrants.
- Skills and workforce shortages: Electricians, transmission engineers, grid connection specialists and construction labour are all in short supply, and the same workforce is required simultaneously for generation, storage, networks and data centre projects.
- Extreme weather and climate-driven demand peaks: Heatwaves, bushfires and storms drive record peak demand and network outages, forcing investment in resilience that does not generate energy revenue.
Forecast 2026–2034
IMARC Group projects the Australia Power Market to expand from 285.7 TWh in 2025 to 385.5 TWh by 2034, at a CAGR of 2.98% during 2026–2034, with the market passing 374.38 TWh in 2033.
That trajectory reflects a market in which the disruption of rapid coal withdrawal is gradually giving way to a more mature phase in which firming capacity, grid access and flexible demand decide competitive position rather than the simple volume of generation. Demand growth will be driven less by population than by structural electrification: data centres clustering around major fibre and grid nodes, industrial process heat displacing gas, electric vehicle charging, and the continued replacement of gas appliances in buildings. Supply will be dominated by utility-scale solar and wind, supported by a storage fleet expanding at a 17.28% CAGR from 4.72 GW in 2025 to 19.81 GW by 2034, by pumped hydro in the Snowy and Tasmanian schemes, and by a shrinking but still essential gas peaking fleet. Transmission completion is the swing factor: where interconnectors and renewable energy zones arrive on schedule, renewable penetration accelerates and reliability margins hold; where they slip, gas generation and higher wholesale prices persist for longer. Volume growth of 2.98% a year understates the value of the market, because the composition shift toward storage, networks and firming services is where the capital is actually being deployed.
Opportunities for Stakeholders
- Renewable Developers and EPC Contractors: The Capacity Investment Scheme's 32 GW underwriting programme, combined with state renewable energy zone frameworks, creates a contracted route to market for utility-scale solar, wind and hybrid projects. Developers that secure grid connection rights early and build inside declared renewable energy zones capture the lowest connection and curtailment risk.
- Storage and Firming Providers: The storage market's expansion from 4.72 GW in 2025 to 19.81 GW by 2034 at a 17.28% CAGR is the single clearest growth signal in the industry. Grid-scale battery developers, pumped hydro proponents and flexible gas peaking operators all have a defined role in replacing retiring coal capacity, particularly where they can position assets at existing generator connection points.
- Transmission and Grid Technology Providers: With Rewiring the Nation deploying AUD 20 billion and projects such as HumeLink, VNI West, EnergyConnect and Marinus Link under delivery, demand is strong for high-voltage equipment, grid-forming inverters, dynamic line rating systems, advanced metering and grid stability software that allows more renewables to be carried on existing infrastructure.
- Investors and Lenders: The Australian power sector offers long-dated, policy-underwritten cash flows through CIS agreements alongside merchant exposure in a deeply traded wholesale market. Highest-conviction assets include contracted firming capacity, regulated network businesses, and storage projects co-located with retiring coal sites where land, water and connection infrastructure already exist.
- Large Energy Users and Data Centre Operators: Data centre power demand valued at USD 427.99 Million in 2026 and projected to reach USD 665.04 Million by 2034 at a 5.66% CAGR means hyperscale operators and industrial energy users must lock in generation, storage and transmission access years ahead of commissioning. Direct power purchase agreements, co-located generation and demand flexibility contracts are becoming the standard route to controlling both cost and carbon.
- Retailers and Technology Suppliers: As coal closes and renewables dominate, retailers increasingly compete on demand flexibility, home electrification services, solar and battery financing, and electric vehicle charging rather than on tariffs alone. Suppliers of home energy management, virtual power plant platforms and demand response technologies have a direct route into millions of Australian households and businesses.
Conclusion: Investment Shifts From Megawatt-Hours to Firmness
The Australia Power Industry, valued at 285.7 TWh in 2025 and projected to reach 385.5 TWh by 2034 at a CAGR of 2.98% during 2026–2034, is being reshaped by three forces at once: the retirement of roughly 90% of National Electricity Market coal generation by 2035; a demand resurgence driven by data centres, valued by IMARC Group at USD 427.99 Million in 2026, and by electrification of transport, buildings and industry; and a storage build-out expanding from 4.72 GW in 2025 to 19.81 GW by 2034 at a 17.28% CAGR.
The obstacles are real, from reliability risks and transmission delays to community opposition, negative pricing, skills shortages and extreme weather exposure. Each is navigable by participants that secure firming optionality, contracted revenue and grid access ahead of the queue. For generators, networks, investors, technology providers and large energy users alike, the coming decade offers a policy-backed, investment-intensive growth platform in which Australia's electricity system is rebuilt around firmness, flexibility and renewable supply rather than coal-fired volume.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Every solar panel is connected by cables built to survive 25 years or more of sun, heat, rain, and high DC voltage. India added a record 44.6 GW of solar capacity in 2025-26, taking cumulative solar capacity past 150 GW, and rooftop programmes such as PM Surya Ghar are adding millions of smaller systems.
Biomass briquettes, often called white coal, are dense blocks of compressed agricultural and forestry residues that burn cleanly in industrial boilers, furnaces, and power plants.
Lead-acid batteries start every car, truck, and two-wheeler, back up telecom towers, data centres, and homes through inverters and UPS systems, and store energy for solar installations. Almost all of the lead, plastic, and acid in a used battery can be recovered, and India already meets more than 80% of its lead demand from recycling.
Fuel cells turn hydrogen into electricity with water as the only exhaust, which makes them one of the most important technologies in India's clean energy transition. They power hydrogen buses, trucks, and trains, provide backup power for telecom towers and data centres, and supply off-grid and distributed electricity where diesel generators are used today.
India's cities generate well over a lakh tonnes of municipal solid waste every day, and much of it still ends up in overflowing dumpsites that release methane, catch fire, and pollute land and water.
Every solar power system needs an inverter to convert the direct current produced by solar panels into alternating current that homes, businesses, and the grid can use.
Sodium-ion batteries are emerging as a practical complement to lithium-ion technology. They work on the same principle, shuttling ions between a cathode and an anode, but use sodium, which is abundant, inexpensive, and available within India, in place of lithium.
Few industries in India have scaled as quickly as solar manufacturing. Backed by ambitious renewable energy targets, a rooftop programme for households, import duties on foreign modules, and the Approved List of Models and Manufacturers (ALMM), domestic module capacity has multiplied in just a few years.
Setting up an Electrical Panel Manufacturing Plant in India is a fabrication-and-assembly venture powered by heavy grid modernisation, a fast-growing renewable-energy build-out, rising industrial and commercial construction, and the spread of automation across factories and buildings.
Saudi Arabia has turned its power transition into one of the world's largest procurement programmes, and international developers, lenders, and equipment makers are following the tenders.
Setting up a Battery Manufacturing Plant in India is a high-demand, energy-driven venture, powered by the country's booming automotive sector, huge power-backup market, and the fast-growing shift to electric vehicles and renewable storage.
Setting up a Liquefied Natural Gas (LNG) Manufacturing Plant in India is a capital-intensive, strategically important venture, powered by the country's push toward a gas-based economy, the shift to cleaner fuels in transport and industry, and rising demand for LNG as a truck, bus, and industrial fuel.
The India carbon credit market is moving from a voluntary, project-by-project trade into a regulated national system with binding targets, a central registry, and exchange-based price discovery. According to IMARC Group, the market was valued at USD 33.69 Billion in 2025, grew to USD 44.42 Billion in 2026, and is projected to reach USD 405.47 Billion by 2034, expanding at a CAGR of 31.84% (2026–2034).
Setting up a Syngas Production Plant in India is a capital-intensive but strategically valuable venture, driven by the country's push for cleaner industrial fuels, coal and biomass utilization, and chemical self-reliance. Syngas, or synthesis gas, is a mixture of hydrogen and carbon monoxide produced by gasifying carbon-rich feedstocks, and it serves as a versatile building block for power, chemicals, hydrogen, and synthetic fuels. With abundant biomass, coal, and waste feedstock and growing policy support for gasification, India offers a favourable environment for new plants.
Setting up a Battery Energy Storage System Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's renewable energy expansion, grid modernization, and supportive storage policies. As solar and wind capacity scales up and the grid needs to balance variable generation, battery energy storage systems have become essential infrastructure.
Setting up a Lithium-ion Battery Recycling Plant in India is a capital-intensive but high-potential venture. India's rapid rise as a major electric-vehicle market, its large consumer-electronics base, and its fast-growing energy-storage sector are together creating one of the deepest and fastest-expanding pools of end-of-life lithium-ion batteries in the world.
Solar glass is a type of specialty glass that has high transmittance and is designed exclusively for use in solar energy systems. Unlike regular flat glass, solar glass is designed to have maximum light transmission with minimal losses due to reflection and absorption.
A solar inverter is a vital component in solar photovoltaic (PV) systems, responsible for transforming the direct current (DC) electricity produced by solar panels into alternating current (AC) electricity. This AC power is then suitable for use by the electrical grid, various appliances, and industrial equipment.
Australia has firmly established itself as a dominant force in the global liquefied natural gas (LNG) market, maintaining its position as one of the world's leading exporters. The country's strategic geographical location in the Asia-Pacific region, combined with substantial natural gas reserves, has enabled it to become a critical energy supplier to rapidly growing Asian economies, particularly China, Japan, and South Korea.
Japan's lead acid battery market stands as a cornerstone of the nation's energy storage infrastructure, demonstrating remarkable resilience and adaptability in an era dominated by rapid technological evolution. Despite the global shift toward lithium-ion technologies, the Japanese lead acid battery sector continues to thrive, driven by its unmatched cost-effectiveness, proven reliability, and exceptional recyclability.
Green hydrogen is the cleanest form of hydrogen available, as it is produced through water electrolysis using the electricity generated from renewable energy sources such as solar, wind, or hydropower. Carbon dioxide emissions are zero since no fossil fuels are used. Essentially, an electrolyzer is used in the electrolysis process to split water molecules into hydrogen and oxygen. The resulting hydrogen is refined by purification, compression, or liquefaction and then fed into various applications. Green hydrogen is considered a cornerstone of the global energy transition because it can store renewable energy, decarbonize hard-to-abate sectors, and serve as a sustainable alternative to fossil-fuel-based hydrogen.
Japan’s thermal power plant industry remains a crucial pillar of the nation’s energy infrastructure, providing a stable and reliable source of electricity for both industrial and residential consumption. Thermal power generation, which primarily involves the combustion of fossil fuels such as coal, natural gas, and oil, continues to play a key role despite increasing investments in renewable energy.
An electrical panel, also called a distribution board or switchboard, is an important installation in electrical infrastructure that acts as the main center for the distribution, control, and protection of electrical power within residential, commercial, and industrial systems. It acts as the point at which electrical energy is received from the utility or a source of power generation and is distributed to various circuits and equipment in an organized manner.
The global oil and gas EPC market is currently experiencing a remarkable transformation as it positions itself at the intersection of traditional energy demands and technological innovation. As of 2024, the market is demonstrating robust growth, reaching USD 52.9 Billion in 2024, depending on regional scope and market segmentation approaches. This substantial market base is supporting a major number of capital projects worldwide, including offshore platform projects and onshore installations that are collectively shaping the energy landscape.
Bamboo pellets are a biomass fuel type created through the compression of bamboo residues like shavings, sawdust, and chips into thick cylindrical pellets. They are an environmentally friendly substitute for conventional fossil fuels like natural gas and coal. Due to the fast growth rate and high biomass yield of bamboo, it has become one of the most renewable raw materials for the production of bioenergy.
Biomass briquettes are dense, solid fuel blocks made of compressed organic waste materials like sawdust, agricultural wastes, wood shavings, coconut shells, rice husk, or herbaceous biomass. The briquetting process usually involves drying the biomass to lower the moisture content (usually down to 10-15%), grinding or milling for a fine particle size uniformity, and then compressing under high pressure with or without a binding agent.
Biogas is a renewable energy form generated by the anaerobic fermentation of organic matter including agricultural residues, animal waste, municipal solid waste, sewage sludge, and food waste. Microorganisms in the absence of oxygen break down organic substances in the process and produce a gaseous mixture of mainly methane (CH4) and carbon dioxide (CO2), with traces of hydrogen sulfide (H2S) and water vapor.
A battery is an electrochemical energy storage system that transforms chemical energy into electrical energy by way of redox reactions between its electrodes and electrolyte. It consists of a single or multiple electrochemical cells, each having a positive electrode (cathode), a negative electrode (anode), and an electrolyte for ion transfer. Batteries are categorically divided into primary (non-rechargeable) and secondary (rechargeable) types.
The global energy landscape is undergoing a seismic transformation, with green hydrogen emerging as one of the most promising solutions to achieve deep decarbonization across sectors. Far from a niche technology, green hydrogen is emerging as a critical pillar of the future energy system, offering a pathway to a sustainable and resilient economy.
Transmission line towers are essential support components of transmission lines installed on overhead to distribute high-voltage electricity over long distances. Towers are made of galvanized steel, primarily, and are designed to tolerate mechanical stress, environmental loads, and electrical safety. Some of the important characteristics of transmission line towers are high structural strength, corrosion resistance, adaptability for modular design, and high service life. They are normally produced in lattice form (tubular or free-standing towers) or tubular form, with types including suspension towers, tension towers, angle towers, and terminal towers based on use.
The energy storage revolution is here, and it's powered by graphene. While the world struggles with the limitations of conventional lithium-ion batteries, a new technology is emerging that promises to shatter every performance barrier we've accepted as unchangeable.
Australia is undergoing a significant energy transformation, underscoring the growing role of renewable energy sources. These sources are key to combating climate change by reducing greenhouse gas emissions, the primary cause of global warming and air pollution. Beyond environmental benefits, renewable energy strengthens energy security by diversifying power sources and reducing dependence on volatile fossil fuel imports, contributing to greater energy independence.
Learn how to plan capital investment, manage raw material costs, post manufacturing cost and optimize operations for setting up solar panel plant.
Battery Energy Storage System (BESS) represents a power grid technology that stores electricity to enhance electric power grid reliability while increasing operational efficiency. BESS permits battery recharging during periods of low demand or extra grid supply capacity. BESS provides three principal operational functionalities which include power grid stabilization during supply disruptions, control of energy supply variations, and integration of intermittent renewable generation from wind and solar resources.
China's economic presence is expanding globally, and Latin America and the Caribbean (LAC) have become a focal point for its investments, especially within the energy sector. The region, rich in natural resources and experiencing rising energy demands, offers strategic opportunities for Chinese energy giants looking to invest and expand. LAC is currently leading a transformative movement towards sustainable energy. From 2015 to 2022, the region increased its renewable energy capacity by an impressive 51%, now generating 64% of its electricity from renewables such as hydropower, wind, and solar. This shift addresses the global demand for cleaner energy while supporting local economic growth and enhancing energy security.
Hydrogen is a clean, renewable, and widely available energy source that can be produced through various methods. Production techniques such as coal gasification, steam methane reforming, electrolysis, and thermochemical processes highlight its versatility. Hydrogen is essential in several critical sectors, including methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant. The increasing concern over carbon emissions and greenhouse gases has led to a shift towards cleaner fuel options. Hydrogen is recognized for its cleanliness and versatility as an energy carrier. Additionally, supportive government initiatives and favorable policies are driving the growth of hydrogen production globally.
Hydrogen is a clean, renewable, and abundant energy source derived from various methods. Its applications span across transportation, heating, and power generation. Diverse production methods, including coal gasification, steam methane reforming, electrolysis, and thermochemical processes, contribute to its versatility. Hydrogen plays a pivotal role in crucial sectors like methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant.
A floating solar farm is a renewable energy installation in which solar panels are mounted on floating structures in water bodies such as lakes, reservoirs, ponds, or even the sea. This technology, also known as a floating photovoltaic (PV) system, or “floatovoltaics,” enables solar power generation in areas with limited available land or where land use is restricted for other purposes. Floating solar farms offer various benefits, including improved solar panel efficiency through cooling, land conservation, reduction of evaporation and algae growth, and integration with hydropower facilities to generate both solar and hydroelectric power in the same location.
Nuclear power utilizes nuclear reactions to generate heat, which is then converted into electricity. This energy is released from the nucleus—the core of atoms composed of protons and neutrons. Nuclear power can be derived from nuclear fission, nuclear decay, and nuclear fusion reactions. Across the globe, nuclear power plants predominantly use the fission of uranium and plutonium to produce electricity. The heat generated from fission is used to create steam, which drives turbines connected to generators. Nuclear power offers several advantages over fossil fuels, such as minimal greenhouse gas emissions and a higher energy density, meaning a small amount of nuclear fuel produces a large amount of energy.