Low Voltage Cable Market Insights: How Electrification Is Driving Demand and Growth
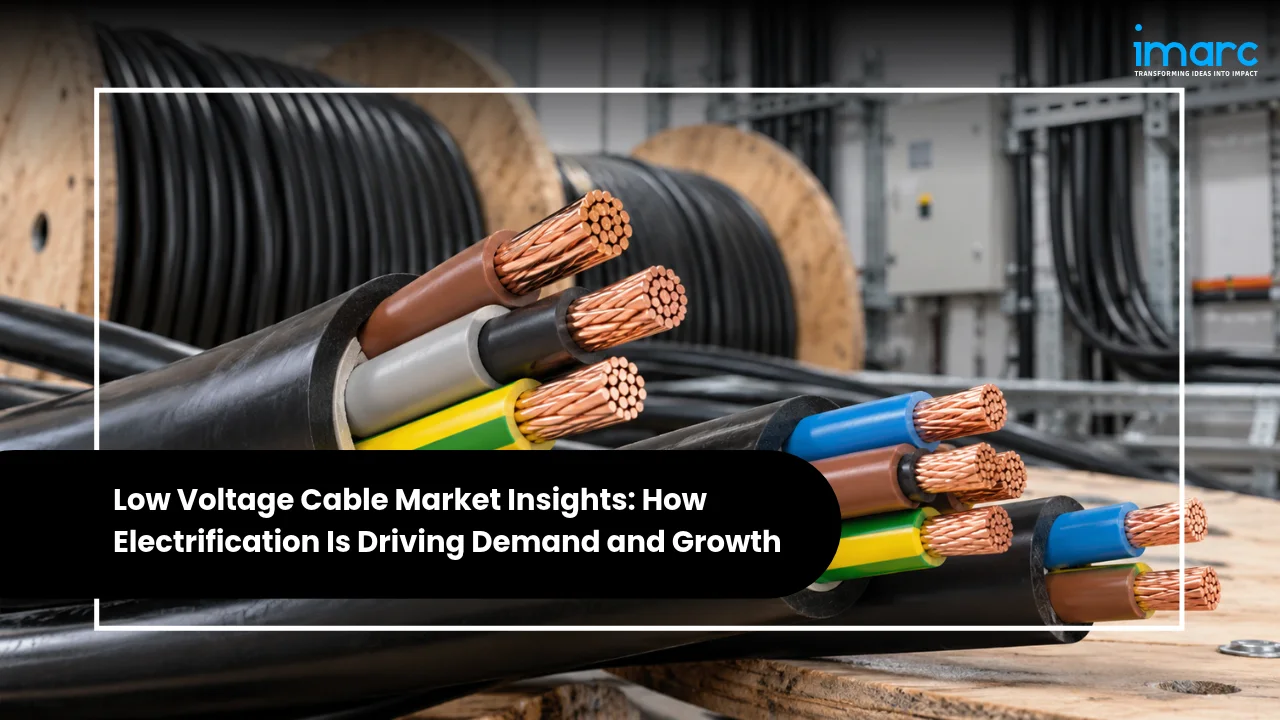
Introduction: Electrification Rewires Cable Demand
The low voltage cable market sits exactly where electrification stops being a policy target and becomes physical infrastructure. Every new solar rooftop, data centre hall, charging depot, factory line and connected building relies on low voltage cable to move power from a transformer to the load, which is why demand keeps compounding even when headline generation projects pause. According to IMARC Group, the global market grew from USD 129.7 Billion in 2025 to USD 138.0 Billion in 2026, and is projected to reach USD 204.2 Billion by 2034, registering a CAGR of 5.02% across the 2026-2034 forecast period.
The engines behind that trajectory are broad rather than concentrated. Rising electricity demand across residential, commercial and industrial sectors, urbanisation and infrastructure expansion, renewable energy integration in solar and wind assets, grid modernisation, electric vehicle charging rollouts and the spread of smart building technology all converge on the same component. Because these drivers operate on different investment cycles, no single sector slowdown removes the market floor.
The clearest emerging theme is the fusion of power distribution with digital control. On 29 February 2024, Siemens and Enlighted partnered with Zumtobel Group to integrate Enlighted IoT sensors into Zumtobel lighting systems, targeting energy efficiency in commercial buildings, higher education and smart hospitals, with the collaboration showcased at Light + Building 2024. Every node in such a system depends on low voltage wiring that carries power and data together, which links cable demand to building technology budgets rather than to construction volumes alone.
This blog covers the low voltage cable market size, share and growth outlook, the trends shaping 2026, regional hotspots, competitive strategies, the regulatory backdrop and the opportunities that follow through the forecast period.
Key Takeaways
- Market Trajectory: The low voltage cable market expanded from USD 129.7 Billion in 2025 to USD 138.0 Billion in 2026 and is forecast to reach USD 204.2 Billion by 2034, a CAGR of 5.02% over 2026-2034.
- Leading Installation Segment: Overhead installation holds the largest share in 2025, favoured for cost effectiveness, ease of installation, terrain adaptability and resilience in flood prone environments.
- Leading Region: Asia Pacific dominates the low voltage cable market in 2025, supported by distribution network expansion, industrial construction and government electrification programmes.
- Notable Recent Development: Siemens and Enlighted partnered with Zumtobel Group on 29 February 2024 to embed IoT sensors in lighting systems, tying low voltage wiring directly to smart building efficiency.
- Key Trend: Aluminium conductors, XLPE insulated underground cables and smart grid deployments are reshaping the product mix as grid modernisation and EV charging infrastructure scale.
Market Size, Share & Growth Outlook
According to IMARC Group, the global low voltage cable market size grew from USD 129.7 Billion in 2025 to USD 138.0 Billion in 2026 and is forecast to reach USD 204.2 Billion by 2034, expanding at a CAGR of 5.02% between 2026 and 2034. Expressed over a nine year window, that rate adds roughly USD 66.2 Billion of new annual revenue between 2026 and 2034, which points to a market driven more by steady volume growth and specification upgrades than by short cyclical spikes. The leading segments are:.
- Installation Type: Overhead installation leads the low voltage cable market share in 2025, selected for cost effectiveness, ease of installation and adaptability across rural electrification, urban distribution and utility applications, with maintenance simplicity and flood resilience reinforcing its position in challenging environments.
- Material: Aluminium dominates the material segment because its lightweight profile and cost efficiency matter most where structural loading and project economics are decisive, particularly in long distance transmission and renewable energy installations, helped by an attractive conductivity to weight ratio.
- Overhead Product: Conductors represent the largest overhead product category since they carry the electrical load itself, with ongoing innovation in conductor materials supporting higher current carrying capacity, lower resistive losses and adoption of aluminium alloys and composite cores.
- Underground Product: XLPE cables hold the leading position within underground products, valued for high temperature resistance, moisture and chemical resistance and stable electrical performance in utility and industrial applications where unplanned downtime is costly.
- Region: Asia Pacific currently dominates the market in 2025, driven by transmission and distribution spending, industrial expansion, urban construction and publicly funded electrification programmes across South and Southeast Asia.
Read together, these segments describe a market where volume growth comes from the expanding reach of distribution networks and value growth comes from higher specification products such as XLPE insulated cables, alloy conductors and certified joints and terminations. For buyers, the global low voltage cable industry report data implies that procurement strategies anchored only on unit price will underperform against those that weigh lifecycle performance, since a rising share of demand now sits in applications that penalise failure.
Recent News & Mega Announcements
Policy funding, corporate consolidations and technology partnerships over 2024 and 2025 have materially shaped the demand environment for low voltage cable.
- EU Grid Investment Framework (November 2023, Guiding Budgets Through 2025 and 2030): The European Commission's EU Action Plan for Grids places electricity grid investment needs at approximately EUR 584 Billion by 2030, with the majority tied to distribution networks, the segment where low voltage cable carries power the final distance to consumers.
- US Federal Energy Funding (2021 Legislation, With Awards and Construction Running Through 2024 and 2025): The Infrastructure Investment and Jobs Act directed roughly USD 65 Billion to energy programmes, including electric grid resilience and modernisation work that converts directly into procurement of conductors, cable terminations and joints.
- India Rooftop Solar And Distribution Reform (February 2024 Onwards): PM Surya Ghar Muft Bijli Yojana, launched in February 2024 with a target of rooftop solar for 10 million households, is expanding service connections, metering and low voltage distribution, while the Revamped Distribution Sector Scheme modernises feeders and reduces technical losses.
- Smart Building Integration (February 2024): Siemens and Enlighted partnered with Zumtobel Group on 29 February 2024 to embed IoT sensors within lighting systems for commercial buildings, higher education and smart hospitals, an arrangement that increases structured low voltage wiring content per building.
- Manufacturing Consolidation (2024): Prysmian's acquisition of Encore Wire moved a significant volume of North American low voltage and building wire capacity into a larger global group, signalling that scale and regional manufacturing footprints are becoming competitive requirements.
- Electric Vehicle Momentum (2023 Baseline, Accelerating Into 2025 and 2026): The International Energy Agency reported around 14 million electric vehicles sold worldwide in 2023, an increase of roughly 35% year on year, each vehicle requiring low voltage harnesses, control wiring and charging connections.
Industry Trends Shaping 2026
Three forces will define product mix, specification levels and regional demand balance over the next two years.
1. Automotive Electrification and EV Charging Build Out
The automotive industry has become one of the most consistent demand engines for low voltage cable. Every electric vehicle uses low voltage wiring for harnesses, control circuits, sensors, lighting and onboard connectivity, while charging infrastructure adds cable runs from the grid connection point through switchgear to dispensers and depot bays. The IMARC analysis cites International Energy Agency data showing about 14 million electric vehicles sold globally in 2023, roughly 35% higher than the prior year, a scale that translates into predictable annual cable volumes rather than one-off project demand.
What matters more for the market than raw unit growth is the change in specification. Vehicle platforms demand cable that tolerates higher temperatures, vibration and tight routing envelopes, and charging installations require cables suited to outdoor exposure, mechanical protection and load management equipment. This shifts the mix from generic building wire toward engineered products, which supports value per kilometre even when total conductor tonnage grows more slowly. Fleet depot charging, workplace chargers and destination parking installations add distributed, smaller ticket demand that is harder for a single supplier to serve, creating room for regional manufacturers.
2. Modernisation of Ageing Grid Infrastructure
An increasing share of capital expenditure is directed at repairing and extending networks rather than building new generation. The Infrastructure Investment and Jobs Act allocated approximately USD 65 Billion for energy related programmes, including electric grid resilience and modernisation, and similar commitments appear in European and Asian distribution reform plans. Outdated low voltage networks suffer higher losses, more frequent faults and greater safety exposure, so utilities replace conductors, reconfigure feeders and upgrade substations with modern cable and jointing systems.
Modernisation typically lifts specification alongside volume. Replacement programmes favour XLPE insulated underground cable for its thermal and moisture performance, aluminium alloy conductors for weight and cost benefits, and factory tested joints and terminations that reduce field failure risk. Storm exposed regions add undergrounding programmes that remove overhead exposure in exchange for higher cable intensity per kilometre of network. For cable suppliers, this trend converts a maintenance budget into a recurring, standards driven revenue stream with longer qualification cycles and stronger customer stickiness.
3. Smart Grids, Automation and Connected Buildings
Smart grid deployment depends on low voltage cable at the last mile. As cited in the IMARC analysis, residential smart meter penetration in the United States exceeded 100 million units as of 2022, up from fewer than 40 million in 2012, and each connected meter requires sound low voltage distribution, communications wiring and metering infrastructure. The same pattern repeats in Europe and Asia Pacific, where distribution utilities are installing sensors and remote switching to monitor loading and isolate faults faster.
Industrial automation reinforces the trend, since programmable controllers, drives and sensors rely on low voltage power and signal cabling that must perform in electrically noisy environments. Smart buildings add another layer: the Siemens, Enlighted and Zumtobel collaboration announced on 29 February 2024 shows how lighting fixtures become sensor platforms feeding occupancy and energy data into building management systems, with low voltage wiring carrying both power and data. Across data centres, hospitals and logistics facilities, this convergence means cable selection now influences operational visibility, not only electrical safety.
Geographic Hotspots: Where the Low Voltage Cable Market is Growing Fastest
Asia Pacific currently dominates the low voltage cable market in 2025. China's urban distribution build out, India's distribution reform and rooftop solar programmes, and industrial relocation across Southeast Asia combine to create the largest concentration of demand. In India, the Revamped Distribution Sector Scheme targets feeder separation, loss reduction and metering upgrades, all of which are low voltage intensive. Rooftop solar expansion under PM Surya Ghar Muft Bijli Yojana adds inverter to panel and inverter to distribution board cabling at household scale, and this demand is highly distributed, which favours domestic manufacturers with regional depots.
North America remains a high value market with a replacement bias. Federal energy funding under the Infrastructure Investment and Jobs Act supports grid resilience projects, while electric vehicle charging corridors, data centre construction and utility undergrounding programmes drive specification upgrades. The United States is also notable for the breadth of public programmes that stimulate demand, including Environmental Protection Agency initiatives such as the RE-Powering America's Land programme together with biogas recovery, combined heat and power and landfill gas recovery efforts. Each of these installations requires interconnection and distribution cabling.
Europe's demand profile is shaped by the EU Action Plan for Grids and the roughly EUR 584 Billion of grid investment needs identified for the period to 2030, most of it at distribution level. Electrification of heating, expansion of rooftop and utility scale solar, offshore wind connections and building renovation all raise low voltage cable content per site. Certification requirements for fire performance in construction works add a compliance dimension that favours established suppliers.
The Middle East, Africa and Latin America present smaller but faster evolving opportunities. Gulf giga projects, mining electrification, urban network extensions and off-grid or mini-grid electrification all require low voltage distribution cable, and financing availability rather than technical demand is usually the binding constraint. Across all regions, the common thread is that distribution networks, not generation assets, determine low voltage cable volumes.
Competitive Landscape & Key Players' Strategies
The competitive field is moderately concentrated at the top and fragmented below it. Global manufacturers compete on conductor efficiency, insulation technology, fire performance certification, delivery reliability and local manufacturing presence, while regional producers compete on cost, service proximity and utility relationships. Consolidation has accelerated as scale becomes necessary for raw material purchasing, testing infrastructure and multi-country qualification.
- Prysmian Group: Pursues scale and geographic balance, with the 2024 acquisition of Encore Wire strengthening North American low voltage and building wire capacity alongside a broad transmission and distribution portfolio.
- Nexans: Positions around electrification and grid services, targeting distribution utility customers and building segments where certification and lifecycle performance drive purchase decisions.
- Sumitomo Electric Industries: Leverages conductor technology and infrastructure project experience, particularly in Asian transmission and distribution programmes.
- Southwire Company: Focuses on North American utility, industrial and construction channels, where distribution reach and contractor relationships determine share.
- Polycab and Finolex Cables: Indian manufacturers that benefit from distribution heavy demand, government electrification programmes and cost competitive manufacturing for domestic and export markets and.
Strategies converge on three themes: adding capacity close to demand to reduce lead times and tariff exposure, moving the product mix toward higher specification insulations and alloy conductors, and offering jointing, termination and testing services so that the cable sale becomes a system sale.
Policy & Regulatory Landscape, Challenges & Risks
Government spending and technical regulation set both the scale and the pace of low voltage cable demand, while raw material and logistics variables create the main downside risks.
- United States Energy And Grid Funding: The Infrastructure Investment and Jobs Act directed roughly USD 65 Billion to energy programmes, including grid resilience and modernisation, which sustains utility procurement of conductors, joints and terminations.
- European Grid And Efficiency Policy: The EU Action Plan for Grids identifies approximately EUR 584 Billion of grid investment needs by 2030, and construction products rules on cable fire performance influence which products qualify for building installation.
- Indian Distribution And Solar Programmes: The Revamped Distribution Sector Scheme links utility financing to loss reduction and metering improvement, and PM Surya Ghar Muft Bijli Yojana targets rooftop solar for 10 million households, both of which raise low voltage cable content in the network.
- Environmental and Reuse Programmes in the United States: Environmental Protection Agency initiatives covering renewable energy on previously used land, biogas recovery, combined heat and power and landfill gas recovery create generation and interconnection projects that require distribution cabling.
On the constraining side, several structural risks persist:
- Raw Material Price Volatility: Fluctuations in copper, aluminum, and polymer prices increase manufacturing costs, squeeze profit margins, and create uncertainty in long-term supply contracts.
- Intense Market Competition: Price pressure from regional manufacturers and low-cost imports limits profitability, particularly in standardized cable segments where product differentiation remains limited.
- Stringent Regulatory Compliance: Evolving electrical safety standards, fire-resistance requirements, and environmental regulations increase testing, certification, and production costs for cable manufacturers.
- Supply Chain Disruptions: Dependence on global raw material suppliers, transportation bottlenecks, and geopolitical tensions can delay production schedules, increase procurement costs, and disrupt project deliveries.
Forecast 2026-2034
The low voltage cable market forecast 2026-2034 points to steady rather than spectacular expansion. From USD 138.0 Billion in 2026, the market is expected to reach USD 204.2 Billion by 2034, a low voltage cable market CAGR of 5.02% that implies roughly USD 66.2 Billion in additional annual revenue over the period. That profile is characteristic of a mature, infrastructure linked industry: growth tracks electricity consumption, construction activity and network replacement cycles rather than discretionary spending.
Upside potential sits in three areas. Faster electric vehicle adoption widens charging and vehicle wiring demand beyond current projections. Accelerated grid spending in Europe and Asia Pacific, where distribution networks absorb the majority of identified investment needs, adds volume at the segment where low voltage cable is indispensable. Growing electrical load from data centres, heat pump conversion and industrial automation raises cable content per site even where project counts are flat.
Downside risks are equally identifiable. Higher copper and aluminium prices can defer utility purchasing, permitting and right of way delays can push installations beyond forecast windows, and trade measures can redirect trade flows and raise landed costs. On balance, the segment mix is likely to shift toward aluminium conductors, XLPE insulated underground products and certified jointing systems, so value growth should modestly outpace tonnage growth through 2034.
Opportunities for Stakeholders in the Low Voltage Cable Market
- Cable Manufacturers: Invest in XLPE and aluminium alloy production close to demand centres, since local capacity shortens lead times and reduces exposure to tariffs and freight volatility.
- Utilities and Distribution Companies: Treat reconductoring and loss reduction as specification upgrade programmes, adopting factory tested joints and terminations to lower failure and maintenance costs over the asset life.
- EPC Contractors and Installers: Build certified jointing and testing capacity, because installation skill, not cable supply, increasingly determines project schedules in underground heavy markets.
- Component and Accessory Suppliers: Joints, terminations, glands and metering accessories represent high margin attach revenue that tracks cable volumes and benefits from stricter utility standards.
- Investors and Lenders: Distribution network upgrades in Asia Pacific and Europe, supported by identified public investment needs, offer predictable, regulated returns tied to network expansion.
- EV Charging and Renewable Developers: Plan low voltage cable procurement early in project design, since charging depots, rooftop solar balance of system and storage interconnections all depend on the same constrained supply base.
Electrification as the Structural Demand Engine
The low voltage cable market is best understood as the physical expression of electrification. Growth of 5.02% CAGR from USD 138.0 Billion in 2026 to USD 204.2 Billion by 2034 reflects an installed base that must be extended, replaced and upgraded at the same time, across buildings, networks, vehicles and industrial plants. No single end market carries the forecast, which is precisely why the outlook remains resilient against sector specific slowdowns.
The competitive and policy signals reinforce that conclusion. Consolidation such as Prysmian's expansion in North America, product shifts toward XLPE and aluminium conductors, and public programmes from the EU Action Plan for Grids to India's distribution and rooftop solar initiatives all point in the same direction: more low voltage cable kilometres per unit of electricity delivered. Suppliers that combine capacity, certification and installation support will capture the value, while buyers that plan procurement around project timelines rather than spot prices will protect their schedules. Electrification is not a temporary investment theme for this market; it is the structural demand engine that will define it through 2034.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Recycled, or secondary, aluminium is made by melting aluminium scrap and refining it into alloy ingots, billets, and liquid metal, using about 95% less energy than making primary aluminium from bauxite.
The Australia Power Industry is the physical foundation of one of the developed world's most coal-reliant electricity systems, which is precisely why its transition now ranks among the largest infrastructure investment programmes in the country's history.
Every solar panel is connected by cables built to survive 25 years or more of sun, heat, rain, and high DC voltage. India added a record 44.6 GW of solar capacity in 2025-26, taking cumulative solar capacity past 150 GW, and rooftop programmes such as PM Surya Ghar are adding millions of smaller systems.
Biomass briquettes, often called white coal, are dense blocks of compressed agricultural and forestry residues that burn cleanly in industrial boilers, furnaces, and power plants.
Lead-acid batteries start every car, truck, and two-wheeler, back up telecom towers, data centres, and homes through inverters and UPS systems, and store energy for solar installations. Almost all of the lead, plastic, and acid in a used battery can be recovered, and India already meets more than 80% of its lead demand from recycling.
Fuel cells turn hydrogen into electricity with water as the only exhaust, which makes them one of the most important technologies in India's clean energy transition. They power hydrogen buses, trucks, and trains, provide backup power for telecom towers and data centres, and supply off-grid and distributed electricity where diesel generators are used today.
India's cities generate well over a lakh tonnes of municipal solid waste every day, and much of it still ends up in overflowing dumpsites that release methane, catch fire, and pollute land and water.
Every solar power system needs an inverter to convert the direct current produced by solar panels into alternating current that homes, businesses, and the grid can use.
Sodium-ion batteries are emerging as a practical complement to lithium-ion technology. They work on the same principle, shuttling ions between a cathode and an anode, but use sodium, which is abundant, inexpensive, and available within India, in place of lithium.
Few industries in India have scaled as quickly as solar manufacturing. Backed by ambitious renewable energy targets, a rooftop programme for households, import duties on foreign modules, and the Approved List of Models and Manufacturers (ALMM), domestic module capacity has multiplied in just a few years.
Setting up an Electrical Panel Manufacturing Plant in India is a fabrication-and-assembly venture powered by heavy grid modernisation, a fast-growing renewable-energy build-out, rising industrial and commercial construction, and the spread of automation across factories and buildings.
Saudi Arabia has turned its power transition into one of the world's largest procurement programmes, and international developers, lenders, and equipment makers are following the tenders.
Setting up a Battery Manufacturing Plant in India is a high-demand, energy-driven venture, powered by the country's booming automotive sector, huge power-backup market, and the fast-growing shift to electric vehicles and renewable storage.
Setting up a Liquefied Natural Gas (LNG) Manufacturing Plant in India is a capital-intensive, strategically important venture, powered by the country's push toward a gas-based economy, the shift to cleaner fuels in transport and industry, and rising demand for LNG as a truck, bus, and industrial fuel.
The India carbon credit market is moving from a voluntary, project-by-project trade into a regulated national system with binding targets, a central registry, and exchange-based price discovery. According to IMARC Group, the market was valued at USD 33.69 Billion in 2025, grew to USD 44.42 Billion in 2026, and is projected to reach USD 405.47 Billion by 2034, expanding at a CAGR of 31.84% (2026–2034).
Setting up a Syngas Production Plant in India is a capital-intensive but strategically valuable venture, driven by the country's push for cleaner industrial fuels, coal and biomass utilization, and chemical self-reliance. Syngas, or synthesis gas, is a mixture of hydrogen and carbon monoxide produced by gasifying carbon-rich feedstocks, and it serves as a versatile building block for power, chemicals, hydrogen, and synthetic fuels. With abundant biomass, coal, and waste feedstock and growing policy support for gasification, India offers a favourable environment for new plants.
Setting up a Battery Energy Storage System Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's renewable energy expansion, grid modernization, and supportive storage policies. As solar and wind capacity scales up and the grid needs to balance variable generation, battery energy storage systems have become essential infrastructure.
Setting up a Lithium-ion Battery Recycling Plant in India is a capital-intensive but high-potential venture. India's rapid rise as a major electric-vehicle market, its large consumer-electronics base, and its fast-growing energy-storage sector are together creating one of the deepest and fastest-expanding pools of end-of-life lithium-ion batteries in the world.
Solar glass is a type of specialty glass that has high transmittance and is designed exclusively for use in solar energy systems. Unlike regular flat glass, solar glass is designed to have maximum light transmission with minimal losses due to reflection and absorption.
A solar inverter is a vital component in solar photovoltaic (PV) systems, responsible for transforming the direct current (DC) electricity produced by solar panels into alternating current (AC) electricity. This AC power is then suitable for use by the electrical grid, various appliances, and industrial equipment.
Australia has firmly established itself as a dominant force in the global liquefied natural gas (LNG) market, maintaining its position as one of the world's leading exporters. The country's strategic geographical location in the Asia-Pacific region, combined with substantial natural gas reserves, has enabled it to become a critical energy supplier to rapidly growing Asian economies, particularly China, Japan, and South Korea.
Japan's lead acid battery market stands as a cornerstone of the nation's energy storage infrastructure, demonstrating remarkable resilience and adaptability in an era dominated by rapid technological evolution. Despite the global shift toward lithium-ion technologies, the Japanese lead acid battery sector continues to thrive, driven by its unmatched cost-effectiveness, proven reliability, and exceptional recyclability.
Green hydrogen is the cleanest form of hydrogen available, as it is produced through water electrolysis using the electricity generated from renewable energy sources such as solar, wind, or hydropower. Carbon dioxide emissions are zero since no fossil fuels are used. Essentially, an electrolyzer is used in the electrolysis process to split water molecules into hydrogen and oxygen. The resulting hydrogen is refined by purification, compression, or liquefaction and then fed into various applications. Green hydrogen is considered a cornerstone of the global energy transition because it can store renewable energy, decarbonize hard-to-abate sectors, and serve as a sustainable alternative to fossil-fuel-based hydrogen.
Japan’s thermal power plant industry remains a crucial pillar of the nation’s energy infrastructure, providing a stable and reliable source of electricity for both industrial and residential consumption. Thermal power generation, which primarily involves the combustion of fossil fuels such as coal, natural gas, and oil, continues to play a key role despite increasing investments in renewable energy.
An electrical panel, also called a distribution board or switchboard, is an important installation in electrical infrastructure that acts as the main center for the distribution, control, and protection of electrical power within residential, commercial, and industrial systems. It acts as the point at which electrical energy is received from the utility or a source of power generation and is distributed to various circuits and equipment in an organized manner.
The global oil and gas EPC market is currently experiencing a remarkable transformation as it positions itself at the intersection of traditional energy demands and technological innovation. As of 2024, the market is demonstrating robust growth, reaching USD 52.9 Billion in 2024, depending on regional scope and market segmentation approaches. This substantial market base is supporting a major number of capital projects worldwide, including offshore platform projects and onshore installations that are collectively shaping the energy landscape.
Bamboo pellets are a biomass fuel type created through the compression of bamboo residues like shavings, sawdust, and chips into thick cylindrical pellets. They are an environmentally friendly substitute for conventional fossil fuels like natural gas and coal. Due to the fast growth rate and high biomass yield of bamboo, it has become one of the most renewable raw materials for the production of bioenergy.
Biomass briquettes are dense, solid fuel blocks made of compressed organic waste materials like sawdust, agricultural wastes, wood shavings, coconut shells, rice husk, or herbaceous biomass. The briquetting process usually involves drying the biomass to lower the moisture content (usually down to 10-15%), grinding or milling for a fine particle size uniformity, and then compressing under high pressure with or without a binding agent.
Biogas is a renewable energy form generated by the anaerobic fermentation of organic matter including agricultural residues, animal waste, municipal solid waste, sewage sludge, and food waste. Microorganisms in the absence of oxygen break down organic substances in the process and produce a gaseous mixture of mainly methane (CH4) and carbon dioxide (CO2), with traces of hydrogen sulfide (H2S) and water vapor.
A battery is an electrochemical energy storage system that transforms chemical energy into electrical energy by way of redox reactions between its electrodes and electrolyte. It consists of a single or multiple electrochemical cells, each having a positive electrode (cathode), a negative electrode (anode), and an electrolyte for ion transfer. Batteries are categorically divided into primary (non-rechargeable) and secondary (rechargeable) types.
The global energy landscape is undergoing a seismic transformation, with green hydrogen emerging as one of the most promising solutions to achieve deep decarbonization across sectors. Far from a niche technology, green hydrogen is emerging as a critical pillar of the future energy system, offering a pathway to a sustainable and resilient economy.
Transmission line towers are essential support components of transmission lines installed on overhead to distribute high-voltage electricity over long distances. Towers are made of galvanized steel, primarily, and are designed to tolerate mechanical stress, environmental loads, and electrical safety. Some of the important characteristics of transmission line towers are high structural strength, corrosion resistance, adaptability for modular design, and high service life. They are normally produced in lattice form (tubular or free-standing towers) or tubular form, with types including suspension towers, tension towers, angle towers, and terminal towers based on use.
The energy storage revolution is here, and it's powered by graphene. While the world struggles with the limitations of conventional lithium-ion batteries, a new technology is emerging that promises to shatter every performance barrier we've accepted as unchangeable.
Australia is undergoing a significant energy transformation, underscoring the growing role of renewable energy sources. These sources are key to combating climate change by reducing greenhouse gas emissions, the primary cause of global warming and air pollution. Beyond environmental benefits, renewable energy strengthens energy security by diversifying power sources and reducing dependence on volatile fossil fuel imports, contributing to greater energy independence.
Learn how to plan capital investment, manage raw material costs, post manufacturing cost and optimize operations for setting up solar panel plant.
Battery Energy Storage System (BESS) represents a power grid technology that stores electricity to enhance electric power grid reliability while increasing operational efficiency. BESS permits battery recharging during periods of low demand or extra grid supply capacity. BESS provides three principal operational functionalities which include power grid stabilization during supply disruptions, control of energy supply variations, and integration of intermittent renewable generation from wind and solar resources.
China's economic presence is expanding globally, and Latin America and the Caribbean (LAC) have become a focal point for its investments, especially within the energy sector. The region, rich in natural resources and experiencing rising energy demands, offers strategic opportunities for Chinese energy giants looking to invest and expand. LAC is currently leading a transformative movement towards sustainable energy. From 2015 to 2022, the region increased its renewable energy capacity by an impressive 51%, now generating 64% of its electricity from renewables such as hydropower, wind, and solar. This shift addresses the global demand for cleaner energy while supporting local economic growth and enhancing energy security.
Hydrogen is a clean, renewable, and widely available energy source that can be produced through various methods. Production techniques such as coal gasification, steam methane reforming, electrolysis, and thermochemical processes highlight its versatility. Hydrogen is essential in several critical sectors, including methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant. The increasing concern over carbon emissions and greenhouse gases has led to a shift towards cleaner fuel options. Hydrogen is recognized for its cleanliness and versatility as an energy carrier. Additionally, supportive government initiatives and favorable policies are driving the growth of hydrogen production globally.
Hydrogen is a clean, renewable, and abundant energy source derived from various methods. Its applications span across transportation, heating, and power generation. Diverse production methods, including coal gasification, steam methane reforming, electrolysis, and thermochemical processes, contribute to its versatility. Hydrogen plays a pivotal role in crucial sectors like methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant.
A floating solar farm is a renewable energy installation in which solar panels are mounted on floating structures in water bodies such as lakes, reservoirs, ponds, or even the sea. This technology, also known as a floating photovoltaic (PV) system, or “floatovoltaics,” enables solar power generation in areas with limited available land or where land use is restricted for other purposes. Floating solar farms offer various benefits, including improved solar panel efficiency through cooling, land conservation, reduction of evaporation and algae growth, and integration with hydropower facilities to generate both solar and hydroelectric power in the same location.
Nuclear power utilizes nuclear reactions to generate heat, which is then converted into electricity. This energy is released from the nucleus—the core of atoms composed of protons and neutrons. Nuclear power can be derived from nuclear fission, nuclear decay, and nuclear fusion reactions. Across the globe, nuclear power plants predominantly use the fission of uranium and plutonium to produce electricity. The heat generated from fission is used to create steam, which drives turbines connected to generators. Nuclear power offers several advantages over fossil fuels, such as minimal greenhouse gas emissions and a higher energy density, meaning a small amount of nuclear fuel produces a large amount of energy.