Cement Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
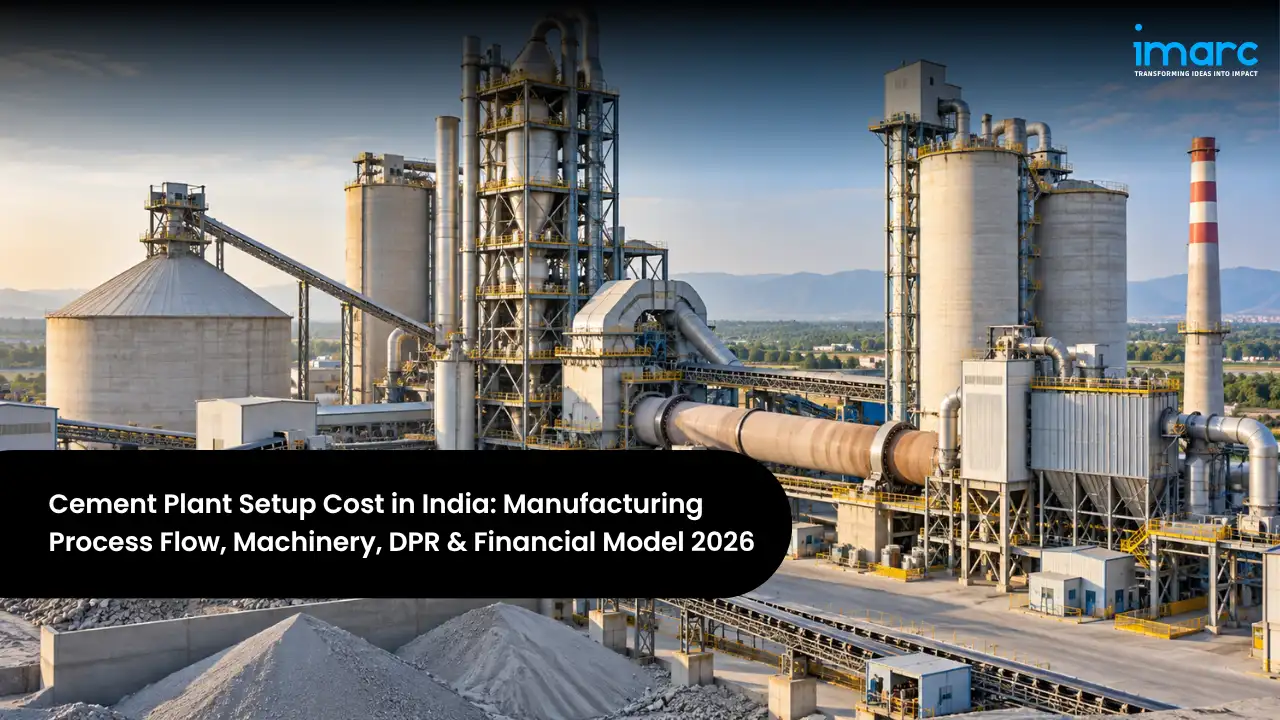
Setting up a Cement Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's massive infrastructure programme, housing boom, and status as the world's second-largest cement producer. Cement is the essential binder in concrete and the backbone of all construction, and demand rises with every road, building, dam, and industrial project. With abundant limestone reserves, strong and durable demand, and proven pyroprocessing technology, a Cement Manufacturing Plant is one of the more strategic large-scale opportunities in the building-materials economy.
The Cement Manufacturing Plant Cost depends heavily on capacity and technology, and because cement making is limestone-, energy-, and equipment-intensive, total project investment typically ranges from INR 300 crore to INR 3,000 crore. Limestone, coal or fuel for the kiln, and power are the largest operating inputs, so raw-material reserves and energy efficiency are the most important financial decisions in the project, and together they shape the overall Cement Investment Cost. At healthy capacity utilisation, a well-run plant in India delivers a net profit margin of 10 to 18% and an IRR of 13 to 20%, with payback typically achieved within 5 to 8 years.
This guide is written for investors and entrepreneurs asking how to start a Cement manufacturing plant in India. It covers what the business involves, why demand is rising, the process flow, the machinery and raw materials required, location and infrastructure planning, a detailed cost and financial breakdown, the licenses you must secure, and how a project report and DPR turns all of this into a bankable plan.
India Market Snapshot
| Key Facts | Details |
|---|---|
| India Cement Market | Large, multi-billion dollar (indicative) |
| Primary Products | OPC, PPC, and blended cement |
| Projected Market CAGR (2026–2034) | 7–10% (indicative) |
| Typical Plant Capacity | 1 – 5+ MTPA |
| Indicative Total Investment | INR 300–3,000 Crore |
| Typical Payback Period | 5–8 Years |
The snapshot captures why a Cement Manufacturing Plant in India attracts strong investor interest: an essential construction material, broad and durable demand, and abundant limestone. The wide investment range reflects a genuine choice of capacity and configuration, from an integrated plant with a captive limestone mine to a standalone grinding unit near markets. Because cement underpins all construction and India's infrastructure and housing pipeline is deep, the demand base is structurally strong, even though it moves with the construction cycle, which is part of why lenders view well-located projects favourably. The rest of this guide unpacks that decision in detail.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Plant Capacity (Typical) | 1 – 5+ MTPA |
| Total Project Investment | INR 300 – 3,000 Crore |
| Payback Period | 5 – 8 Years |
| Net Profit Margin | 10 – 18% |
| IRR | 13 – 20% |
| Best Locations | Rajasthan, Madhya Pradesh, Chhattisgarh, Andhra Pradesh, Karnataka |
| Mandatory Approvals | Environmental Clearance, Mining Lease, CPCB/SPCB, Factory License |
| Primary Revenue | OPC, PPC, and blended cement |
These indicative parameters give a realistic frame for early feasibility work. The returns can be strong, but they depend on securing limestone reserves, managing fuel and power costs, controlling freight, and building steady demand among builders, infrastructure contractors, and dealers. A well-prepared Cement Feasibility Report tightens each of these numbers to your specific location, capacity, and limestone source.
Table of Contents
- What is Cement Manufacturing?
- Why is Cement Manufacturing Growing in India?
- Cement Manufacturing Process
- Raw Materials and India Sourcing
- Location, Land & Infrastructure
- Machinery and Equipment Required
- Cement Manufacturing Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for Cement Manufacturing Plant in India
- Recent Developments in the India Cement Manufacturing Industry
- How a Cement Manufacturing Project Report and DPR Helps Investors
- Frequently Asked Questions
What is Cement Manufacturing?
Cement manufacturing is the production of the powder binder that, when mixed with water and aggregates, forms concrete, made by burning limestone and clay into clinker and grinding it with gypsum and additives. The heart of the process is the kiln, where the raw mix is heated to around 1,450 degrees Celsius to form clinker, which is then ground into finished cement. The output is supplied mainly as Ordinary Portland Cement (OPC), Portland Pozzolana Cement (PPC), and other blended cements for construction.
From a business perspective, what makes this sector attractive in India is the combination of essential, durable demand and abundant raw material. Every builder, infrastructure contractor, real-estate developer, and dealer is a potential buyer, and India's large limestone reserves supply the main input. A manufacturer that runs an efficient kiln, controls fuel and freight, and maintains quality is positioned to serve a large, essential, and structurally growing market driven by the country's construction and infrastructure ambitions.
- Ordinary Portland Cement: OPC in various grades, the standard cement for structural concrete.
- Portland Pozzolana Cement: PPC blended with fly ash, widely used, durable, and more sustainable.
- Blended & Slag Cement: PSC and composite cements using slag and additives for specific uses.
- Specialty Cement: Rapid-hardening, sulphate-resistant, and other specialty cements that command better prices.
The Main Segments in Cement Manufacturing
Understanding which products and plant configuration you will run is the foundational decision, because it drives raw materials, machinery, and value:
| Segment | Typical Products | Key Property | Primary Demand |
|---|---|---|---|
| Integrated Plant | Clinker and cement | Full production | Large-scale supply |
| Grinding Unit | Cement from clinker | Lower CapEx | Market-proximate supply |
| Blended Cement | PPC, PSC | Sustainable, cost-efficient | Housing and general |
| Specialty Cement | Rapid, sulphate-resistant | Higher margin | Infrastructure and niche |
This choice shapes the entire plant, because an integrated plant with a captive limestone mine and kiln differs greatly from a grinding unit that buys clinker and grinds it near markets. Many Indian groups run integrated plants near limestone and add grinding units near demand centres to cut freight, and blend fly ash or slag to lower cost and improve sustainability. The configuration and product decision drives everything from raw-material strategy to the level of investment required.
Why is Cement Manufacturing Growing in India?
Key Growth Drivers in the Indian Market
India's cement sector is being propelled by several structural factors that combine an infrastructure boom with housing and urbanisation. Few products ride as many favourable trends at once:
- Infrastructure programme: Massive investment in roads, railways, ports, and public works drives strong, sustained cement demand.
- Housing and real estate: Rapid urban and rural housing construction underpins large, durable demand.
- Urbanisation: Growing cities and towns continually expand construction and cement consumption.
- Abundant limestone: Large domestic limestone reserves provide a reliable, low-cost raw-material base.
- Blended cement and sustainability: Use of fly ash and slag lowers cost and emissions while expanding blended-cement demand.
India-Specific Market Opportunity
| Segment | India Market Context | Cement Role |
|---|---|---|
| Infrastructure | Large public pipeline | Core construction material |
| Housing | Booming construction | Structural concrete |
| Real Estate | Urban development | Building material |
| Rural Demand | Growing rural build-out | Individual housing |
| Ready-Mix Concrete | Expanding RMC market | Bulk cement supply |
The strongest opportunity lies in supplying builders, infrastructure contractors, and dealers with consistent, competitively priced cement, ideally from a plant well placed on limestone and close to demand to control freight. A manufacturer that runs efficiently and maintains quality and brand can lock in steady demand across the cycle. Blended cements and, where feasible, grinding units near markets further strengthen a plant's cost position in a large, growing market.
Cement Manufacturing Process
Understanding how cement is actually made helps you plan mining, the kiln, and the main cost drivers. Production is a continuous pyroprocessing operation that turns limestone into clinker and then cement, with quality control throughout, and it is both energy-intensive and capital-intensive. The typical flow moves limestone through crushing and the kiln to clinker, grinding, and dispatch:
The Cement Manufacturing Process
In this flow, limestone is mined and crushed, blended with additives and ground into raw meal, preheated and burned in a rotary kiln to form clinker, then cooled and ground with gypsum and additives into finished cement before packing and dispatch. Consistent raw-mix chemistry and efficient burning are essential to clinker and cement that meet strength standards at a competitive cost.
| Unit Operation | Key Activity |
|---|---|
| Limestone Mining | Limestone extracted and hauled |
| Crushing | Limestone crushed to size |
| Raw Grinding | Raw meal ground and blended |
| Preheating | Raw meal preheated in the tower |
| Kiln Burning | Clinker formed at high temperature |
| Clinker Cooling | Clinker rapidly cooled |
| Cement Grinding | Clinker ground with gypsum |
| Blending | Fly ash or slag added |
| Packing | Cement bagged or bulk-loaded |
| Dispatch | Delivered to markets |
Two points determine profitability across this flow. First, limestone quality and raw-mix control drive both clinker quality and cost, so mining and blending directly govern outcomes. Second, the kiln consumes large amounts of fuel and power, so thermal and electrical efficiency are decisive margin levers, and freight to market is a further major cost. Rigorous quality control, for strength and setting, is what allows a manufacturer to certify cement to standards and build a trusted brand. Because builders and contractors rely on consistent strength and reliable supply, quality and availability matter as much to them as headline price.
Raw Materials and India Sourcing
The main input is limestone, supported by additives, fuel, and power, and securing large, good-grade limestone reserves is the single biggest determinant of a plant's viability. Because limestone, fuel, and power dominate cost, reserve security and energy strategy materially affect margin, alongside the gypsum, fly ash or slag, and additives the process needs.
| Raw Material | Role in Process | India Sourcing | % of OpEx |
|---|---|---|---|
| Limestone | Primary raw material | Captive mines and leases | 10–18% |
| Fuel (Coal/Pet Coke) | Kiln energy | Domestic and imported fuel | 25–35% |
| Power | Grinding and operations | Grid, captive, or renewable | 12–20% |
| Gypsum & Additives | Setting and blending | Domestic and imports | 3–6% |
| Fly Ash / Slag | Blending for PPC/PSC | Power plants and steel mills | 3–6% |
Because limestone and energy together dominate cost, reserve and energy strategy are the biggest levers on profitability. A captive limestone mine with decades of good-grade reserves is the foundation of an integrated cement plant, since limestone is bulky and costly to transport. Fuel, whether coal or pet coke, is the largest single operating cost, so efficient burning, alternative fuels, and waste-heat recovery protect margins. Fly ash and slag are low-cost blending materials that both cut cost and improve sustainability, while gypsum and additives are smaller but essential to quality.
Location, Land & Infrastructure
Choosing the best location for Cement manufacturing plant setup significantly affects limestone access, fuel and power costs, and freight to markets. Being on or near a large limestone deposit, with fuel access and reasonable distance to demand, shapes site selection, alongside large land, water, and the mining and environmental infrastructure a cement plant demands.
Best States for Cement Manufacturing Plant Setup in India
| State | Why It Works | Key Advantage |
|---|---|---|
| Rajasthan | Large limestone reserves | Raw material and demand |
| Madhya Pradesh | Limestone and central location | Reserves and logistics |
| Chhattisgarh | Limestone and coal | Raw material and fuel |
| Andhra Pradesh | Limestone belt | Reserves and southern demand |
| Karnataka | Limestone and industry | Reserves and demand |
| Tamil Nadu | Limestone and market | Reserves and offtake |
The strongest locations combine large, good-grade limestone reserves with access to fuel and reasonable freight to demand centres. Rajasthan, Madhya Pradesh, Chhattisgarh, Andhra Pradesh, and Karnataka offer strong limestone belts, while proximity to coal and to growing markets adds advantage. Because cement is bulky and freight-sensitive, and mining is central, limestone reserves, fuel access, power cost, and distance to market should weigh heavily in the final choice, alongside land, water, and environmental capacity for a plant of this scale.
Infrastructure Requirements (Mid-Sized Plant)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Limestone Mine & Land | Captive reserves | Decades of supply |
| Crushing & Raw Grinding | Crushers and mills | Raw material prep |
| Preheater & Kiln | Rotary kiln with preheater | Core process unit |
| Clinker Cooler & Storage | Cooler and silos | Clinker handling |
| Cement Grinding & Packing | Mills and packers | Finishing and dispatch |
| Power & Fuel Systems | Captive power and fuel yard | For kiln and grinding |
| Environmental & Logistics | Dedusting and dispatch | ESP, WHRB, and siding |
Infrastructure for a cement plant centres on the limestone mine, crushing and raw grinding, the preheater and kiln, clinker cooling, and cement grinding and packing, backed by power, fuel, and environmental systems, because output, cost, and compliance depend on all of them. Environmental control, including dedusting and often waste-heat recovery, is especially important given how closely cement plants are regulated and how energy-intensive they are. Building adequate reserves, power, and environmental capacity from the start supports both economics and compliance, so a well-planned layout with room to expand pays off strongly.
Machinery and Equipment Required
The equipment set spans mining and crushing, raw and cement grinding, and the kiln, and the line-up scales with capacity and technology. Because product quality and efficiency depend on continuous, well-controlled processing, machinery must be heavy-duty and energy-efficient. The core machinery, from limestone crushing through cement packing, is summarized below.
| Equipment | Function | Key Specification |
|---|---|---|
| Crushers | Crush limestone | Primary and secondary |
| Raw Mill | Grind raw meal | Vertical or ball mill |
| Preheater / Precalciner | Preheat raw meal | Multi-stage cyclones |
| Rotary Kiln | Form clinker | High-temperature kiln |
| Clinker Cooler | Cool clinker | Grate cooler |
| Cement Mill | Grind cement | Ball or roller mill |
| Blending & Silos | Blend and store | Homogenising silos |
| Packing Plant | Bag and load | Rotary packers |
| ESP / Baghouse | Control emissions | Dedusting systems |
| WHRB & Utilities | Recover heat and supply power | Waste-heat recovery |
Equipment selection should follow your capacity, limestone, and integration rather than the other way around. An integrated plant needs crushing, raw and cement grinding, a preheater kiln, and a cooler, while a grinding unit needs mainly grinding, blending, and packing. The kiln, grinding mills, and their energy systems are the heart of the plant and easy to under-budget, because their efficiency and reliability determine fuel and power consumption, clinker quality, and the ability to operate within environmental norms, on which the economics depend.
Cement Manufacturing Plant Setup Cost in India (CapEx & OpEx)
The tables below give you a breakdown of both the upfront capital investment and the ongoing operating costs, based on industry analysis of a mid-sized facility in India. The actual Cement Manufacturing Plant Cost for your specific project will depend on your chosen location, capacity, technology, and whether it is integrated or a grinding unit.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Kiln & Pyroprocessing | 25–35% | Kiln, preheater, and cooler |
| Grinding & Mills | 18–25% | Raw and cement mills |
| Power & WHRB | 12–18% | Captive power and heat recovery |
| Building & Civil Works | 10–15% | Structures and foundations |
| Mine Development | 5–8% | Limestone mine and handling |
| Environmental Systems | 5–8% | Dedusting and controls |
| Pre-operative & Contingency | 6–10% | Engineering, DPR, and buffer |
The CapEx profile is dominated by the kiln, grinding mills, and power systems, with mine development and environmental systems significant because cement is a mining-and-energy business. A grinding unit is far less capital-intensive than an integrated plant, since it skips the kiln and mine. Under-provisioning the kiln, power, or environmental systems is a common and costly mistake, so all are modelled carefully in the Cement Business Plan and Financial Model.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Fuel & Energy | 25–35% | Largest cost; kiln is fuel-intensive |
| Power | 12–20% | Grinding is power-intensive |
| Freight & Logistics | 15–25% | Cement is bulky and freight-heavy |
| Limestone & Additives | 10–18% | Captive limestone and gypsum |
| Labour & Maintenance | 5–8% | Operators and heavy-plant upkeep |
| Packing & Compliance | 3–6% | Bags and environmental norms |
With fuel, power, and freight together dominating operating cost, cement is fundamentally an energy-and-logistics business, and margin depends on efficient burning, low power use, and tight freight control alongside cheap limestone. Fuel prices move with coal and pet-coke markets, so a financial model should track them closely and stress-test margins against fuel, power, and freight swings, which are the biggest variables, while accounting for the durable demand that construction provides. Blended cements and waste-heat power are what lift a plant's margin above the industry average.
Financial Analysis and Profitability
Based on analysis of a mid-sized cement facility in India, the financial profile is strong but cyclical, supported by essential, growing construction demand and abundant limestone. Because energy, freight, and limestone drive economics, the profitability of Cement manufacturing business in India improves markedly with secure low-cost limestone, efficient energy use, controlled freight, and high utilisation.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 22–35% | Driven by energy, freight, and prices |
| Net Profit Margin | 10–18% | After depreciation and Indian corporate taxes |
| Payback Period | 5–8 Years | Faster with secure limestone and power |
| IRR (Internal Rate of Return) | 13–20% | Higher with blended cement and WHRB |
| Capacity Utilization (stable ops) | 75–90% | Rises with demand and brand |
| Break-even Capacity Utilization | 55–70% | High fixed costs need steady output |
Energy cost, freight, and utilisation are the factors that most determine outcomes, because a cement plant carries very high fixed costs and must run at high output while keeping fuel and freight in check to be economical. An operator with secure limestone, efficient energy use, and markets within a reasonable freight radius can achieve healthy margins, while one exposed to fuel swings or long hauls will see margins move with the cycle. This is why limestone reserves, energy, and logistics are as central to the financial model as the plant itself.
There are several ways to strengthen returns in the Indian context: securing long-life limestone reserves, improving thermal and electrical efficiency and adding waste-heat power, using alternative fuels and higher blending with fly ash and slag, keeping the plant well utilised, and placing grinding units near markets to cut freight. A trusted brand and dealer network further stabilise demand and pricing. Because freight is such a large cost, optimising the plant-to-market footprint is often the single biggest lever on delivered-cost competitiveness across the cycle.
Key Risks and Mitigation
The principal risks are fuel and power price volatility, construction-cycle demand swings, and environmental compliance. Energy risk is mitigated by efficient kilns, alternative fuels, and waste-heat power; demand risk is mitigated by diverse markets and a strong brand; freight risk is mitigated by market-proximate grinding units; and compliance risk is mitigated by robust dedusting and environmental systems. A manufacturer that treats limestone security, energy, logistics, and compliance as core priorities is far better placed to sustain returns through the cycle.
Licenses and Approvals for Cement Manufacturing Plant in India
The approvals for this business are extensive, because a cement plant involves mining, is energy-intensive, and generates dust and emissions subject to strict regulation. Manufacturers planning to establish a Cement Manufacturing Plant generally need to obtain the following, and environmental and mining approvals are especially central:
- Environmental Clearance (EC): Prior EC from the environment ministry for the plant and mine, often the longest-lead approval.
- Mining Lease & Approvals: Limestone mining lease and mine-plan approvals from the state and mining authorities.
- Pollution Control Consents: Consent to Establish and Consent to Operate from the State Pollution Control Board (CTE and CTO).
- Forest & Land Approvals: Forest clearance where applicable, and land acquisition and use approvals.
- Factory License: Factory establishment and operation approval under the Occupational Safety, Health and Working Conditions Code, 2020.
- Power, Water & Fire: Power and water allocations and fire safety compliance.
- Business, Tax & BIS: Incorporation, GST, and BIS certification for cement products.
For a cement plant, environmental clearance, the limestone mining lease, and pollution-control consents are the critical, long-lead items and should be pursued very early, well before construction, because an integrated plant cannot be built or operated without secure limestone and clearances. Engaging consultants experienced in environmental and mining regulations is essential given the complexity, since a delayed clearance or lease can hold up a large investment for years. Sequencing approvals well, alongside reserve and market development, is one of the most important things that keeps a heavy project on schedule.
Note: The exact approvals, registrations, licenses, and compliance requirements may vary depending on factors such as plant location, capacity, mining, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India Cement Manufacturing Industry
A few structural trends give useful context for investors considering entry into this industry:
- Infrastructure-led demand: Sustained public infrastructure and housing investment continues to underpin strong cement demand.
- Blended cement and decarbonisation: Higher fly-ash and slag blending, alternative fuels, and waste-heat recovery are cutting cost and emissions.
- Consolidation and capacity addition: Ongoing capacity expansion and consolidation are reshaping the industry toward larger, efficient players.
The common thread is a market growing with infrastructure and housing, with energy efficiency, blending, and logistics increasingly decisive. For a new entrant, the implication is clear: the window to establish a well-located plant with secure limestone and efficient energy is open, and those who build reserve security, energy efficiency, and a strong market footprint into their model from the start will be best placed as construction demand grows through the decade.
How a Cement Manufacturing Project Report and DPR Helps Investors
A comprehensive Cement Project Report, prepared as a Detailed Project Report (DPR), provides a structured roadmap for establishing the facility by evaluating every aspect of the venture, from market demand and limestone reserves to technology, energy, logistics, and economics. It helps investors determine the optimal capacity and configuration, estimate capital expenditure (CapEx) and operating expenditure (OpEx), assess profitability, and identify potential risks before implementation.
The report also brings together a Cement Business Plan with revenue forecasts, production costs, cash flow analysis, break-even assessment, return on investment (ROI), and payback period calculations, supported by a detailed Cement Financial Model. These insights enable investors, lenders, and stakeholders to make informed decisions and evaluate the long-term viability of the project. Many investors engage a Cement Business Plan Consultant in India or a Cement Manufacturing Consultant in India to prepare and validate these documents.
For a cement project specifically, a strong DPR also clarifies the limestone and energy strategy, the plant configuration and logistics plan, and the environmental and mining approval pathway, which are the factors most likely to determine success in this heavy, capital-intensive business. By modelling utilisation and delivered cost against realistic demand and testing margins against fuel, power, and freight swings, the report turns a strategic but cyclical opportunity into an executable plan that lenders and partners can trust. It also maps the phased implementation and funding schedule, so investors can see how a large project is built and financed in stages.
Frequently Asked Questions
How to start a cement manufacturing plant in India?
Begin by choosing your capacity and configuration, then prepare a feasibility report and DPR, secure limestone reserves and a mining lease, tie up fuel and power, arrange the kiln, grinding, and packing equipment, and obtain environmental clearance, pollution-control, and factory approvals. Because this is a heavy, mining-linked project, reserves and clearances should be secured very early. A detailed project report maps each step.
What is the cement manufacturing plant cost in India?
It typically ranges from INR 300 crore to INR 3,000 crore depending on capacity and whether the plant is integrated or a grinding unit, and the wider Cement Investment Cost is dominated by the kiln, grinding mills, and power systems. Process equipment and civil works are the largest components.
What is the cement manufacturing process?
The process runs from limestone mining and crushing, through raw grinding and blending, preheating, and kiln burning to form clinker, to clinker cooling, cement grinding with gypsum, blending with fly ash or slag, packing, and dispatch, with quality control on strength and setting throughout.
What machinery is required for a cement plant?
Key equipment includes crushers, a raw mill, a preheater and precalciner, a rotary kiln, a clinker cooler, a cement mill, blending silos, a packing plant, dedusting systems such as ESP or baghouse, and often a waste-heat recovery boiler and captive power.
What is the best location for cement manufacturing plant setup?
The ideal site combines large, good-grade limestone reserves with fuel access and reasonable freight to demand. Rajasthan, Madhya Pradesh, Chhattisgarh, Andhra Pradesh, and Karnataka are leading choices, given their limestone belts and demand.
What is the profitability of cement manufacturing business in India?
It is strong but cyclical, with a typical 10 to 18% net profit margin and a 13 to 20% IRR, and a 5 to 8 year payback at healthy utilization. Returns improve with secure low-cost limestone, efficient energy, blended cement, waste-heat power, and controlled freight, though margins move with fuel, power, and construction cycles.
How do I get a project report or feasibility report for a cement plant?
A Cement Project Report and Cement Feasibility Report cover the full plant setup and financials. Many investors engage a Cement Plant Project Report Consultant in India or a Cement Manufacturing Feasibility Study Consultant to prepare and validate them.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Setting up a PVC Panel Manufacturing Plant in India is a high-demand, construction-driven venture, powered by the country's building boom, fast-growing interior and renovation market, and the shift away from plywood and plaster toward affordable, waterproof panels.
Setting up an Electric Motor Manufacturing Plant in India is a high-value, engineering-driven venture, powered by the country's industrial expansion, energy-efficiency push, and the rise of electric vehicles and automation.
Setting up an Iron Ore Pellets Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's ambitious steel-capacity expansion, the shift toward value-added iron ore, and rising demand from blast furnaces and sponge iron units.
The Saudi Arabia construction market has emerged as one of the most closely watched construction economies in the world. The market reached USD 101.4 Billion in 2025 and is projected to reach USD 140.4 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 3.6% between 2026 and 2034.
A WPC (Wood Plastic Composite) door is a type of composite door made from a combination of wood fibers or wood flour and thermoplastic resins like PVC, polyethylene, or polypropylene, with additives to improve durability and processability. The resulting composite material is then extruded or molded into door panels and frames, providing the attractive look of wood and the strength and water-resistance of plastic.
UPVC windows refer to window frames and window assemblies manufactured from ‘unplasticized polyvinyl chloride,’ which is a relatively rigid and strong thermoplastic substance. While PVC is a flexible material that requires the addition of a softening substance called a plasticizer to be formed into a durable performance material, PVC window frames and UPVC window assemblies, for instance, do not display such requirements due to the presence of unplasticizers, a component of the material that provides enhanced strength, stability, and resistance to the elements such as UV radiation, moisture, and temperature changes.
The Saudi Arabia factoring market represents a critical component of the Kingdom's evolving financial services landscape, offering businesses an increasingly popular alternative to traditional bank lending. Factoring, which involves the sale of accounts receivable to a third-party financial institution at a discount, has emerged as a vital mechanism for improving liquidity, managing cash flow, and mitigating credit risk across diverse industry sectors.
The GCC bridge construction market represents a vital component of the region's ambitious infrastructure transformation agenda, serving as a cornerstone for enhanced mobility, economic integration, and sustainable urban development across the Gulf states.
The Australia industrial couplings industry stands at a transformative juncture in 2025, propelled by technological advancement and surging demand across critical sectors. As mechanical devices connecting two shafts to transmit power and torque, industrial couplings form the backbone of machinery operations in manufacturing, mining, automotive, and energy sectors.
The Saudi Arabia real estate market stands at a pivotal juncture in its evolution, representing one of the most dynamic and transformative sectors within the Kingdom's economy. With this country having a very ambitious agenda of economic diversification and modernization, the real estate business has come out as one of the pillars of this transformation.
Steel is an alloy that consists of iron and carbon in addition to trace amounts of other elements like manganese, silicon, chromium, and nickel. The amount of carbon in steel is usually less than two percent and is an important factor in determining the strength, hardness, and ductility of steel.
Saudi Arabia’s precast concrete market reached USD 1.2 Billion in 2024 as per the IMARC Group, clear proof that off-site construction is rapidly becoming the Kingdom’s go-to building solution. With residential, commercial, and major infrastructure projects multiplying, developers are increasingly turning to precast building solutions to keep pace.
The GCC cold storage construction market represents critical infrastructure underpinning regional food security, pharmaceutical distribution, and temperature-sensitive logistics across the Arabian Peninsula. As Gulf Cooperation Council nations diversify their economies and reduce hydrocarbon dependence, robust cold chain infrastructure has emerged as a cornerstone of sustainable development planning.
PVC panels are lightweight, durable building materials made from polyvinyl chloride using extrusion or molding processes. They are available as rigid or semi-rigid sheets designed primarily for wall and ceiling cladding, partitions, and decorative finishes. Known for their excellent resistance to moisture, chemicals, termites, and corrosion, PVC panels offer a smooth surface and a clean, polished look that’s easy to maintain. Available in an extensive range of colors, textures, and patterns, these panels serve as a practical alternative to traditional materials like wood, plaster, or tiles.
Ready mix concrete (RMC) is a precisely engineered construction material produced in a controlled environment within a batching plant and delivered to construction sites in a freshly mixed, plastic state. It is formulated by combining cement, aggregates, water, and chemical or mineral admixtures in carefully proportioned quantities to achieve specific performance characteristics. Unlike site-mixed concrete, RMC ensures consistent quality, uniformity, and superior workability through automated production and quality control processes.
The construction industry across the Gulf Cooperation Council (GCC) member states is at the core of a monumental economic transformation. Far exceeding traditional building activities, the sector now serves as the principal vehicle for national economic diversification strategies, moving these nations beyond reliance on oil revenues.
Paver blocks are precast construction material made basically from cement, aggregates, sand, and pigments for constructing surfacing. They are produced in standardized shape and thickness, allowing each unit to interlock to form a strong, load-bearing surface with no need for continuous concrete pouring. Paver blocks possess high compressive strength, abrasion resistance, and are easy to lay and maintain.
The Brazil ceramic tiles market has witnessed stable growth, reflecting broader trends in the construction and building materials industries of the country. The Brazil ceramic tiles market size was valued at USD 1.6 Billion in 2025. The market is expected to reach USD 2.2 Billion by 2034, exhibiting a CAGR of 3.91% during 2026-2034.
MDF is an engineered wood product produced by breaking down hardwood or softwood residuals into wood fibers, which are then combined with resin binders under heat and pressure. MDF exhibits a homogeneous density, a smooth surface, and fine texture, ensuring a much more workable material compared to natural wood.
Float glass is a type of flat glass that is manufactured by floating molten glass on a bed of molten tin. This produces a smooth, uniform surface and consistent thickness. The float process was developed by Pilkington in the 1950s and revolutionized glassmaking because it enabled the production of large, flawless sheets of glass without needing polishing or grinding. The basic raw materials used-silica sand, soda ash, limestone, and dolomite-are heated in the furnace to a very high temperature, then continuously poured onto the tin bath, where the molten glass spreads out into an even layer. It cools and solidifies into a perfectly flat and perfectly transparent sheet. As it provides optical clarity and strength and is easily processed into coated, laminated, or toughened forms, float glass is used as a basic product for various applications, ranging from architectural and automotive to industrial applications.
ERW steel pipes can be identified as one of the most important categories of welded pipes and find wide applications in infrastructure, construction, and other industries because of their precision, cost-effectiveness, and reliability. The raw material to produce these pipes is either hot-rolled or cold-rolled steel coils that are longitudinally formed and welded by the application of high-frequency electric resistance welding.
Drill bits are specifically designed cutting instruments intended to produce cylindrical holes in various materials, ranging from soft woods and plastics to hardened steels, stone, and rock. Although they seem straightforward, drill bits consist of various specialized shapes, coatings, and materials that are designed to suit the cutting characteristics of the intended material and the requirements of the drilling task.
Concrete is among the most widely used construction materials in the world due to its strength, versatility, and durability. It is a composite material largely made of cement, water, aggregates-sand, gravel, or crushed stone-and in some cases, admixtures which give special properties to the concrete.
Clay bricks are one of the oldest and most extensively used construction materials in the globe, appreciated for their strength, durability, insulation against heat, and beauty. They are produced mainly from natural clay and shale, which are fashioned, dried, and subjected to high-temperature firing to produce a hard, dense material that can resist multiple environmental and structural stresses. The mix generally consists of alumina, silica, lime, iron oxide, and magnesia that collectively decide the color, texture, and performance properties of the brick.
Metal beam crash barriers and high mast light poles are essential infrastructural features providing security and visibility on highways, city roads, and industrial sites. Metal beam crash barriers or guardrails are made of galvanized steel beams, typically W-beam or Thrie-beam, that are designed to dissipate the impact energy on impact with a vehicle and minimize death and damage to vehicles.
Laminated plywood is an engineered wood material that is produced by laminating several layers of thin veneers of wood together with powerful adhesives and covering them with a protective or decorative laminate sheet. This amalgamation not only increases the strength of the plywood but also its beauty, which is why it is extremely versatile for use in furniture, cabinetry, floors, paneling, and interior design.
Ductile iron pipes (DIP) are a key part of new water and wastewater infrastructure, providing enhanced performance capabilities over older piping materials. Cast from ductile cast iron, a material that has the strength of steel combined with the resistance to corrosion of cast iron, these pipes are designed to endure high-pressure use while still being flexible enough to absorb stress without cracking.
The real estate sector plays a critical role in driving economic growth and shaping communities. It significantly contributes to national economies by generating jobs, influencing investment flows, and boosting government revenues through taxes. Beyond these economic benefits, real estate development directly affects the quality of life by creating homes, enhancing infrastructure, and revitalizing urban areas.
Gypsum boards, also referred to as drywall or plasterboard, are lightweight, strong and fireproof building materials that are frequently used for partitions, walls and ceilings. Constructed from a gypsum core encased in paper liners, they provide improved acoustics, cost effectiveness, and speedy installation. Gypsum boards are favoured in industrial, commercial, and residential construction because of its environmentally beneficial qualities, ability to withstand moisture, and ability to insulate against heat. They are an essential part of efficient and sustainable construction methods because of their adaptability to contemporary building processes.
A frameless shower door is a modern and aesthetically appealing bathroom fixture that has gained popularity for its sleek and minimalist design. They are constructed without the bulky metal framing that surrounds the glass panels and are typically made from thick, tempered glass that is securely attached to the wall and floor using hinges or brackets.