Solar Cell Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
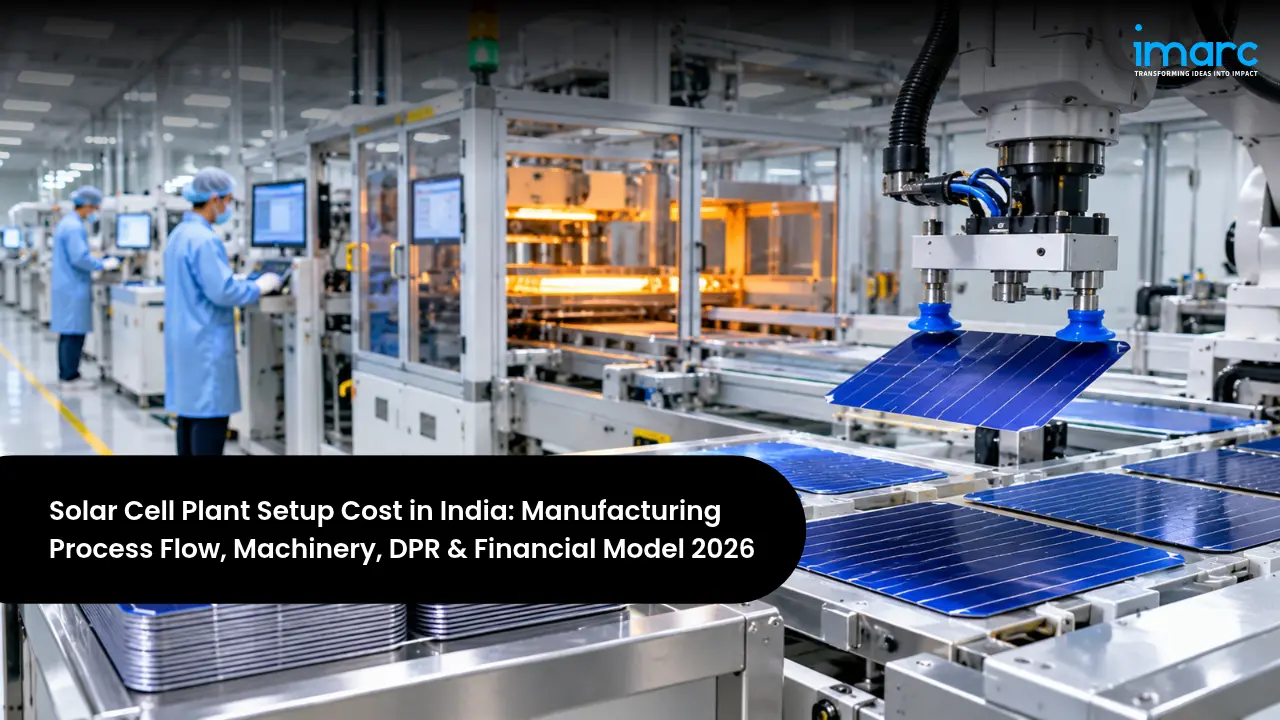
A Solar Cell Manufacturing Plant Setup in India sits at the centre of the country's push to build a complete domestic solar supply chain. Solar cells are the semiconductor devices that convert sunlight into electricity, and they are the core component of every crystalline silicon solar module. India has built very large module assembly capacity, but cell production has lagged far behind, leaving the industry dependent on imports. With the Approved List of Models and Manufacturers (ALMM) List-II for solar cells in force from 1 June 2026, most new solar projects must now use domestically made cells, creating strong demand for new cell capacity.
The overall Solar Cell Manufacturing Plant Cost depends mainly on capacity, cell technology, and the degree of automation, with industry estimates placing a 1 GW cell line at roughly INR 250 crore to INR 400 crore, about five to eight times the cost of an equivalent module line, and typically taking 18 to 24 months to build. A 1 to 2 GW TOPCon cell plant therefore usually needs INR 300 crore to INR 800 crore. Silicon wafers and silver paste account for most of operating cost. Industry benchmarks point to gross margins of 15 to 25% and net margins of 5 to 12%, although current domestic shortages under ALMM List-II have supported higher realisations in the near term.
This guide is written for module manufacturers planning backward integration, renewable energy developers, semiconductor and electronics investors, and entrepreneurs exploring how to start a Solar Cell manufacturing plant in India. It covers cell technologies and markets, policy and demand drivers, the cell fabrication process, machinery and raw materials, site and infrastructure planning, a detailed cost and returns breakdown, the approvals involved, and how a DPR brings these elements into a bankable plan.
India Market Snapshot
| Key Facts | Details |
|---|---|
| Global Solar Cell Market | USD 154.00 Billion (2025) |
| Global Market Outlook | USD 468.10 Billion by 2034, 13.2% CAGR |
| ALMM-Listed Cell Capacity | About 31 GW (June 2026) |
| ALMM-Listed Module Capacity | About 193 GW (June 2026) |
| Typical Cost of a 1 GW Cell Line | INR 250–400 Crore |
| Indicative Total Investment | INR 300–800 Crore (1–2 GW) |
The snapshot shows a fast-growing global market and a striking imbalance in India, where enlisted cell capacity is only about one-sixth of module capacity. Because ALMM List-II now requires domestic cells for most projects, the gap translates into strong demand for new cell plants, particularly from standalone module makers that lack their own cell lines. At the same time, cell manufacturing is far more capital- and technology-intensive than module assembly, so execution capability is critical.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Product Range | TOPCon, Mono PERC, and HJT monocrystalline solar cells |
| Total Project Investment | INR 300 – 800 Crore (1–2 GW) |
| Payback Period | 4 – 7 Years |
| Net Profit Margin | 5 – 12% (benchmark) |
| IRR | 14 – 20% |
| Best Locations | Gujarat, Tamil Nadu, Telangana, Andhra Pradesh, Himachal Pradesh, West Bengal |
| Mandatory Approvals | ALMM List-II Enlistment, BIS Certification, SPCB Consents, PESO, Factory License |
| Key Requirement | Proven technology partner, reliable wafer supply, and stable power |
These figures provide a practical frame for early evaluation. Returns depend on choosing a competitive cell technology, achieving high conversion efficiency and yield, securing wafers and silver paste at competitive prices, running the line at high utilisation, and selling to module makers under long-term agreements. A technology- and capacity-specific Solar Cell Feasibility Report is essential before capital is committed.
Table of Contents
- What is Solar Cell Manufacturing?
- Why is Solar Cell Manufacturing Growing in India?
- Solar Cell Manufacturing Process Flow
- Raw Materials Required for Solar Cell Manufacturing
- Location, Land & Infrastructure
- Solar Cell Manufacturing Machinery and Equipment
- Solar Cell Manufacturing Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for Solar Cell Manufacturing in India
- Recent Developments in the India Solar Cell Manufacturing Industry
- How Solar Cell Manufacturing Project Report and DPR Helps Investors
- Frequently Asked Questions
What is Solar Cell Manufacturing?
A crystalline silicon solar cell is made from a thin silicon wafer that is chemically textured, doped to form a p-n junction, coated with passivation and anti-reflection layers, and printed with metal contacts. When light strikes the cell, it generates electrical current. Modern Indian lines are shifting from Mono PERC to higher-efficiency TOPCon, which adds an ultra-thin tunnel oxide and doped polysilicon layer, while heterojunction (HJT) cells combine crystalline silicon with thin amorphous silicon layers. A Solar Cell Manufacturing Plant therefore resembles a semiconductor fab, combining wet chemistry, high-temperature furnaces, vacuum deposition, lasers, screen printing, and automated testing in a clean, controlled environment.
Commercially, solar cells are sold mainly to module manufacturers, who assemble them into panels for utility-scale solar parks, rooftop systems, commercial and industrial projects, and government programmes. Integrated players use their own cells, while standalone module makers buy cells from third-party producers. Export markets, especially the United States and Europe, offer further opportunities for compliant suppliers.
- Mono PERC Cells: Mature technology with lower capital cost, still widely enlisted in India.
- TOPCon Cells: N-type cells with higher efficiency and bifaciality, now the leading choice for new lines.
- HJT Cells: Heterojunction cells with high efficiency and low-temperature processing.
- Advanced and Back-Contact Cells: Emerging high-efficiency designs for premium applications.
Main Cell Technologies in Solar Cell Production
Technology choice shapes equipment, efficiency, cost, and competitiveness:
| Technology | Description | Key Feature | Market Position |
|---|---|---|---|
| Mono PERC | P-type, passivated rear contact | Lower capex, mature | Large installed base, declining |
| TOPCon | N-type, tunnel oxide passivated contact | High efficiency, bifacial | Leading for new capacity |
| HJT | Heterojunction with amorphous silicon | Very high efficiency | Growing, higher capex |
| Back-Contact | Contacts on rear side | Premium efficiency | Emerging |
| Bifacial Variants | Light capture on both sides | Higher energy yield | Utility-scale demand |
Because cell technology evolves quickly, the technology selected today must remain competitive for most of the plant's life. Most new Indian investments are adopting TOPCon, with some players investing in HJT, while older PERC lines face pressure. Choosing upgradeable equipment and a strong technology partner helps reduce the risk of obsolescence.
Why is Solar Cell Manufacturing Growing in India?
Key Growth Drivers in the Indian Market
Demand for domestic solar cells is driven by policy, strong solar installation growth, and supply-chain security. IMARC Group values the global solar cell market at USD 154.00 billion in 2025 and expects it to reach USD 468.10 billion by 2034:
- ALMM List-II mandate: From 1 June 2026, most solar projects must use modules made with cells from ALMM-listed domestic manufacturers.
- Massive cell-module gap: Enlisted cell capacity of about 31 GW compares with about 193 GW of module capacity, leaving standalone module makers short of domestic cells.
- Solar installation growth: India added a record 55 GW of non-fossil capacity in the last financial year, and solar now supplies nearly a fifth of electricity.
- Production-linked incentives: Government incentives for high-efficiency solar manufacturing support integrated and cell capacity investments.
- Export opportunities: Trade measures on Chinese supply in major markets create opportunities for compliant Indian cell producers.
India-Specific Market Opportunity
| Segment | India Market Context | Plant Role |
|---|---|---|
| Standalone Module Makers | Large capacity, few domestic cells | Third-party cell supply |
| Integrated Manufacturers | Backward integration into cells | Captive cell lines |
| Government Programmes | Domestic content requirements | DCR-compliant cells |
| Utility & C&I Projects | Strong installation pipeline | High-efficiency bifacial cells |
The strongest position for a Solar Cell Manufacturing Plant in India combines modern high-efficiency technology with long-term offtake from module makers that need ALMM-compliant cells. Integration with module assembly, or firm supply agreements with standalone module manufacturers, reduces market risk, while export certification can open additional markets.
Solar Cell Manufacturing Process Flow
Understanding the Solar Cell Manufacturing Process helps promoters plan equipment, clean rooms, utilities, and quality control. Cell fabrication is a sequence of precise chemical, thermal, vacuum, laser, and printing steps, and small deviations can reduce efficiency or yield. The flow below reflects a typical TOPCon cell line.
Step-by-Step Solar Cell Manufacturing Process Flow
Wafers are inspected, then textured to reduce reflection. Doping forms the junction, followed by edge isolation and cleaning. Tunnel oxide and doped polysilicon layers are deposited, passivation and anti-reflection coatings are applied, laser processes open contacts, and metal pastes are screen printed and fired. Finished cells are tested, sorted by efficiency, and packed.
| Unit Operation | Key Activity |
|---|---|
| Wafer Inspection | Incoming wafer quality checks |
| Texturing & Cleaning | Surface texturing to trap light |
| Diffusion / Doping | Junction formation in furnaces |
| Etching & Edge Isolation | Remove unwanted layers, isolate edges |
| Tunnel Oxide & Poly-Si Deposition | Passivated contact layers (TOPCon) |
| Passivation & Anti-Reflection Coating | Aluminium oxide and silicon nitride layers |
| Laser Processing | Contact opening and selective emitters |
| Screen Printing | Silver and aluminium contact printing |
| Firing & Contact Optimisation | High-temperature firing and laser treatment |
| Testing, Sorting & Packing | Efficiency testing, EL inspection, binning |
Two factors decide profitability. The first is conversion efficiency: each tenth of a percentage point of efficiency increases the value of every cell, so process control, equipment quality, and continuous optimisation matter enormously. The second is yield and throughput: wafer breakage, printing defects, and low-efficiency bins erode margins, while high-speed automated lines with in-line inspection keep costs down. Electroluminescence imaging and IV testing on every cell support consistent quality and customer acceptance.
Raw Materials Required for Solar Cell Manufacturing
The main inputs are silicon wafers, silver and aluminium pastes, process chemicals, specialty gases, and ultra-pure water. Wafers and silver paste dominate material cost, and India currently imports most of its wafers.
| Raw Material | Role in Process | India Sourcing | % of OpEx |
|---|---|---|---|
| Monocrystalline Silicon Wafers | Base material | Largely imported; domestic capacity emerging | 55–65% |
| Silver Paste | Front and rear contacts | Imported and domestic suppliers | 10–15% |
| Aluminium Paste | Rear contact (PERC) | Domestic and imported | 1–2% |
| Process Chemicals | Texturing, etching, cleaning | Domestic and imported chemicals | 2–4% |
| Specialty Gases | Deposition and doping | Industrial gas suppliers, on-site plants | 2–4% |
Wafer supply is the industry's biggest vulnerability, because most wafers come from a concentrated global supply base, and wafer prices can swing sharply. Domestic ingot and wafer projects are under development and are expected to improve supply security over time. Silver paste costs have risen with silver prices, prompting efforts to reduce silver consumption through finer printing and alternative metallisation. Reliable supply of ultra-pure water, nitrogen, and specialty gases is also essential.
Location, Land & Infrastructure
A cell plant needs large volumes of stable, high-quality power and water, access to specialty gases and chemicals, and proximity to module makers and ports. The best location for Solar Cell manufacturing plant setup combines a dedicated industrial park or electronics cluster with reliable grid supply, water availability, good port access for wafers and exports, and supportive state incentives.
Best Location for Solar Cell Manufacturing Plant Setup in India
| State | Why It Works | Key Advantage |
|---|---|---|
| Gujarat | Largest solar manufacturing hub | Ports, power, integrated players |
| Tamil Nadu | Large cell and module investments | Industrial infrastructure, ports |
| Telangana | Established cell manufacturers | Hyderabad electronics ecosystem |
| Andhra Pradesh | New greenfield cell projects | Land, incentives, ports |
| Himachal Pradesh | Existing cell capacity at Baddi | Industrial incentives |
| West Bengal | Long-running cell manufacturing | Eastern market and port access |
Gujarat hosts India's largest concentration of integrated solar manufacturing around Mundra, Jamnagar, Dholera, and Surat, while Tamil Nadu and Telangana have attracted major cell investments and established players. Andhra Pradesh is drawing new greenfield projects with land and incentives, and Himachal Pradesh and West Bengal host existing cell facilities. Power quality, water supply, and state electricity tariffs strongly influence operating cost and should be compared carefully.
Quality, Safety and Environmental Requirements
Solar cells must meet efficiency and reliability specifications and relevant standards, and manufacturers must be enlisted under ALMM List-II, which involves inspection of manufacturing facilities. Cell fabs use hazardous chemicals and gases, including acids, alkalis, silane, ammonia, and dopant gases, so gas cabinets, detection systems, scrubbers, emergency response, and trained staff are essential. Wastewater containing fluorides and other contaminants must be treated, and clean room conditions, air handling, and contamination control are critical for yield.
Infrastructure Requirements (1–2 GW Plant)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Total Land Area | 20 – 50 acres | Fab, utilities, storage, expansion |
| Production Building | Clean room fab halls | Controlled temperature and humidity |
| Power Requirement | 20 – 50 MW | Stable, high-quality supply with backup |
| Ultra-Pure Water Plant | High-volume UPW system | Water recycling recommended |
| Gas Supply | Nitrogen plant, specialty gas yards | Silane and dopant gas safety |
| Wastewater Treatment | Fluoride and chemical treatment | SPCB consent conditions |
| Testing & Warehousing | Cell testing, storage, dispatch | Humidity-controlled storage |
Infrastructure for a cell plant centres on clean room fab halls, a large and stable power supply, an ultra-pure water plant, gas supply systems including on-site nitrogen generation, chemical delivery and storage, wastewater treatment, and exhaust scrubbing. Planning for future lines and technology upgrades from the outset is important, because cell plants typically expand in phases.
Solar Cell Manufacturing Machinery and Equipment
Solar cell equipment is highly specialised and largely imported from established global equipment makers, with turnkey line suppliers often providing process technology, installation, and training. The main equipment is summarised below.
| Equipment | Function | Key Specification |
|---|---|---|
| Wafer Handling & Inspection | Load and inspect wafers | Automated, high throughput |
| Wet Benches | Texturing, etching, cleaning | Single- and double-sided processing |
| Diffusion Furnaces | Boron and phosphorus doping | Tube or batch furnaces |
| LPCVD / PECVD Tools | Tunnel oxide, poly-Si, nitride layers | Uniform deposition |
| ALD System | Aluminium oxide passivation | Atomic layer precision |
| Laser Systems | Contact opening, selective emitter | High precision |
| Screen Printers | Metallisation | Fine-line printing |
| Firing Furnace & Contact Optimisation | Fire contacts, laser treatment | Controlled temperature profile |
| IV Testers, EL Inspection & Sorters | Test and bin cells | Efficiency classification |
| Utilities: UPW, Gas, Scrubbers, HVAC | Support systems | Clean room and safety |
Equipment selection should follow the chosen technology and capacity, with attention to upgrade paths, throughput, efficiency roadmaps, and supplier support in India. Turnkey lines from experienced suppliers shorten ramp-up, while strong in-house process engineering is needed to reach and sustain high efficiency and yield.
Solar Cell Manufacturing Plant Setup Cost in India (CapEx & OpEx)
The tables below summarise the capital and operating cost structure of a TOPCon cell facility in India. The final Solar Cell Investment Cost for a specific project depends on capacity, technology, automation, utilities, clean room specification, land, and state incentives.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Production Equipment | 55–65% | Wet benches, furnaces, deposition, printers, testers |
| Clean Room & Buildings | 10–15% | Fab halls, HVAC, building works |
| Utilities | 10–14% | UPW, gases, power systems, scrubbers, WWT |
| Land & Site Development | 3–6% | Land and infrastructure |
| Pre-operative & Contingency | 4–7% | Engineering, technology fees, ramp-up |
| Working Capital | 6–10% | Wafers, paste, inventory, receivables |
Production equipment dominates the capital budget, followed by clean room buildings and utilities, which are far more demanding than in module assembly. Ramp-up costs and technology fees can also be significant. A Solar Cell Business Plan models these components carefully so that technology, capacity, and phasing decisions rest on realistic numbers.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Raw Materials | 70–75% | Wafers and silver paste dominate |
| Power & Utilities | 15–20% | High electricity and UPW use |
| Labour & Manpower | 3–5% | Skilled engineers and technicians |
| Maintenance & Spares | 2–4% | Equipment upkeep |
| Consumables | 1–2% | Screens, parts, filters |
| Overheads & Compliance | 1–2% | Testing, certification, administration |
With wafers and silver making up most of operating cost, profitability depends on the spread between cell prices and wafer and paste costs, along with efficiency, yield, and power tariffs. A sound financial model should test margins against wafer and silver price swings, cell prices, technology shifts, and utilisation.
Financial Analysis and Profitability
Solar cell manufacturing offers strong demand visibility under ALMM List-II but requires high capital, advanced technology, and careful execution. The profitability of Solar Cell manufacturing business in India improves with high-efficiency technology, high yields, low power costs, secure wafer supply, and long-term offtake agreements.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 15–25% | Benchmark; higher during shortages |
| Net Profit Margin | 5–12% | After depreciation and Indian corporate taxes |
| Payback Period | 4–7 Years | Depends on prices and ramp-up |
| IRR (Internal Rate of Return) | 14–20% | Sensitive to cell price spreads |
| Capacity Utilization (stable ops) | 70–90% | Strong domestic demand |
| Break-even Capacity Utilization | 50–65% | High depreciation |
Current domestic shortages have supported cell prices, but margins are likely to normalise as new capacity comes online and the market matures. Technology obsolescence is a key risk, because newer cell designs can quickly reduce the competitiveness of older lines. Plants that start with competitive technology, ramp up quickly, and lock in long-term customers are best placed to earn sustainable returns.
Returns can be strengthened by integrating with module assembly or signing long-term supply agreements, choosing upgradeable high-efficiency technology, securing wafer supply through long-term contracts or domestic partners, reducing silver consumption, negotiating competitive power tariffs, and using available government incentives.
Key Risks and Mitigation
The main risks are technology obsolescence, wafer supply concentration, price competition as capacity grows, slow ramp-up, high power costs, and changes in trade or domestic content policy. Technology risk is reduced through careful technology selection and upgradeable equipment; supply risk through diversified wafer sourcing; price risk through cost leadership and offtake agreements; ramp-up risk through experienced partners and skilled teams; and policy risk through a balanced domestic and export strategy.
Licenses and Approvals for Solar Cell Manufacturing in India
A solar cell plant requires product enlistment, environmental, chemical safety, and industrial approvals. Promoters typically need the following before commencing operations:
- ALMM List-II Enlistment: Enlistment of cell models and manufacturing capacity with MNRE under ALMM List-II, including facility inspection.
- BIS and Quality Certification: Certification to applicable standards and quality systems required by customers and programmes.
- Pollution Control Consents: Consent to Establish and Consent to Operate from the State Pollution Control Board, covering chemical effluent and emissions.
- Hazardous Chemicals and Waste Compliance: Compliance with hazardous chemical rules and authorisation for hazardous waste generated in processing.
- PESO Approvals: Approvals for storage and handling of compressed and flammable gases where applicable.
- Factory License and Fire NOC: Factory registration, building approval, and fire safety certification.
- Business, Trade and Labour Registrations: Company incorporation, GST, Udyam, an Import Export Code for equipment and wafers, and EPF and ESI registrations.
Pollution consents, chemical safety approvals, and ALMM enlistment sit on the critical path, as enlistment determines when cells can be sold into most domestic projects. Engaging a Solar Cell Manufacturing Consultant in India can help promoters select technology, plan utilities and approvals, and coordinate equipment suppliers and ALMM enlistment.
Note: The exact approvals, registrations, licenses, and certification requirements may vary depending on factors such as plant location, product range, capacity, target customers, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India Solar Cell Manufacturing Industry
Several recent developments are reshaping India's solar cell industry:
- ALMM List-II takes effect: The ALMM List-II requirement for solar cells came into force on 1 June 2026. Enlisted cell capacity stood at about 31 GW against about 193 GW of module capacity, leaving only around 2.6 GW available to standalone module makers after integrated players' captive use.
- Rapid enlistment growth: Enlisted cell capacity crossed 30 GW by April 2026, with additions including Reliance Industries' 1,238 MW of HJT cells at Jamnagar and expansions by Jupiter Solartech and Websol Energy Systems.
- New greenfield investments: In November 2025, Voltsun Labs announced a 2 GW TOPCon cell and module plant at Naidupeta, Andhra Pradesh, with an investment of INR 1,743 crore, and in December 2025 INOX Air Products agreed to supply ultra-high purity nitrogen to ReNew's TOPCon cell facility at Dholera, Gujarat.
Together these point to a market with strong policy-driven demand and rapid capacity additions, alongside real concerns about near-term cell shortages for standalone module makers. For new entrants, success depends on competitive technology, fast and reliable ramp-up, secure wafer supply, and long-term customer relationships.
How Solar Cell Manufacturing Project Report and DPR Helps Investors
A detailed Solar Cell Project Report gives investors a structured roadmap covering market and policy assessment, technology selection, process design, machinery, clean room and utility planning, raw material sourcing, regulatory pathway, and economics. It helps promoters choose the right technology and capacity, estimate capital expenditure (CapEx) and operating expenditure (OpEx), assess profitability, and identify risks before implementation.
At the core of the DPR is a Solar Cell Financial Model covering ramp-up, efficiency and yield, cell prices, wafer and silver costs, power tariffs, incentives, cash flow projections, break-even, return on investment (ROI), and payback. Because returns are sensitive to technology and price trends, lenders expect detailed sensitivity analysis, which is why many promoters engage a Solar Cell Plant Project Report Consultant in India to prepare bank-ready documents.
For a cell project specifically, a strong DPR also answers the questions that matter most: which technology will stay competitive, how wafers will be secured, who will buy the cells, how fast the line can ramp up, and how returns hold up when cell prices fall as new capacity arrives. An experienced Solar Cell Manufacturing Feasibility Study Consultant tests these scenarios so that the final plan is one lenders and partners can back with confidence.
Frequently Asked Questions
How do I set up a solar cell manufacturing factory in India?
Start by choosing a cell technology and capacity and securing a technology partner, then commission a feasibility study and DPR. Select a site with stable power, water, and gas supply, order equipment and build clean room facilities, obtain pollution, chemical safety, PESO, and factory approvals, secure wafer supply and offtake agreements, and complete ALMM List-II enlistment.
What is the solar cell manufacturing plant setup cost in India?
Industry estimates place a 1 GW cell line at about INR 250 crore to INR 400 crore, so a 1 to 2 GW plant typically needs INR 300 crore to INR 800 crore, depending on technology, automation, and utilities.
How are solar cells made?
Silicon wafers are textured, doped to form a junction, cleaned, and coated with passivation and anti-reflection layers. Laser processes open contacts, metal pastes are screen printed and fired, and finished cells are tested and sorted by efficiency.
What machinery is needed for a solar cell manufacturing plant?
Key equipment includes wafer handling systems, wet benches, diffusion furnaces, LPCVD and PECVD tools, ALD systems, lasers, screen printers, firing furnaces, IV testers and sorters, and utilities such as ultra-pure water, gas, scrubber, and clean room HVAC systems.
What raw materials are used in solar cells?
The main raw materials are monocrystalline silicon wafers, silver and aluminium pastes, process chemicals such as acids and alkalis, specialty gases, and ultra-pure water.
Is solar cell manufacturing profitable in India?
Industry benchmarks point to net margins of 5 to 12%, with current shortages under ALMM List-II supporting prices in the near term. Long-term profitability depends on technology, efficiency, wafer costs, power tariffs, and offtake.
What licenses are needed for a solar cell manufacturing unit in India?
A plant typically needs ALMM List-II enlistment, BIS and quality certifications, State Pollution Control Board consents, hazardous chemical and waste compliance, PESO approvals, a Factory License, a Fire NOC, and GST, Udyam, IEC, and labour registrations.
Which state is best for a solar cell manufacturing plant?
Gujarat, Tamil Nadu, Telangana, Andhra Pradesh, Himachal Pradesh, and West Bengal are strong options. The best site offers stable power, water, gas supply, port access, and state incentives.
How do I get a feasibility study or DPR for a solar cell manufacturing plant?
A professionally prepared DPR covers market and policy assessment, technology selection, technical design, approvals, costs, and financial projections for bank appraisal. Many promoters work with a Solar Cell Business Plan Consultant in India to prepare it and align it with lender requirements.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

India's energy storage market has moved from pilot projects to procured infrastructure, and the numbers now reflect that shift. The India energy storage market reached a volume of 331.3 MWh in 2025 and is projected to reach 9,294.4 MWh by 2034, expanding at a CAGR of 40.03% during 2026-2034.
A Biodiesel Manufacturing Plant Setup in India connects two national priorities: cutting diesel imports and turning waste oils into clean fuel. Biodiesel is a renewable fuel made of fatty acid methyl esters (FAME), produced by reacting oils and fats with methanol.
The India solar energy market is no longer a niche policy play; it sits at the centre of the country's power investment case. According to IMARC Group, the market grew from USD 30.03 Billion in 2025 to USD 41.39 Billion in 2026 and is projected to reach USD 538.91 Billion by 2034, expanding at a CAGR of 37.82% during 2026-2034.
Setting up a Bio-LNG Manufacturing Plant in India is an opportunity to turn agricultural residue, press mud, cattle dung, and municipal organic waste into a premium, low-carbon transport and industrial fuel.
Lithium-ion cells store energy by moving lithium ions between a cathode and an anode through an electrolyte, and can be charged and discharged thousands of times.
LPG is a mixture of propane and butane that is recovered from natural gas streams and produced in crude oil refineries, then stored as a liquid under moderate pressure and supplied in cylinders, bulk tankers, and pipelines.
Graphene-enhanced batteries use graphene, a single-atom-thick sheet of carbon with outstanding electrical and thermal conductivity, to improve conventional battery chemistries.
A utility-scale photovoltaic project turns sunlight into electricity through fields of PV modules, converts it from DC to AC in inverters, steps up the voltage, and feeds it into the grid for sale under long-term power purchase agreements.
Distribution transformers step down medium-voltage power, typically 11, 22, or 33 kV, to the 415 or 230 volts used by homes, shops, farms, and factories. They are the last link in the power supply chain and are installed in very large numbers on poles, plinths, and in substations across every town and village.
Flexible solar panels are lightweight, frameless modules that can bend to fit curved or weak surfaces where standard glass-and-aluminium panels are too heavy or rigid.
The low voltage cable market sits exactly where electrification stops being a policy target and becomes physical infrastructure. Every new solar rooftop, data centre hall, charging depot, factory line and connected building relies on low voltage cable to move power from a transformer to the load, which is why demand keeps compounding even when headline generation projects pause.
Recycled, or secondary, aluminium is made by melting aluminium scrap and refining it into alloy ingots, billets, and liquid metal, using about 95% less energy than making primary aluminium from bauxite.
The Australia Power Industry is the physical foundation of one of the developed world's most coal-reliant electricity systems, which is precisely why its transition now ranks among the largest infrastructure investment programmes in the country's history.
Every solar panel is connected by cables built to survive 25 years or more of sun, heat, rain, and high DC voltage. India added a record 44.6 GW of solar capacity in 2025-26, taking cumulative solar capacity past 150 GW, and rooftop programmes such as PM Surya Ghar are adding millions of smaller systems.
Biomass briquettes, often called white coal, are dense blocks of compressed agricultural and forestry residues that burn cleanly in industrial boilers, furnaces, and power plants.
Lead-acid batteries start every car, truck, and two-wheeler, back up telecom towers, data centres, and homes through inverters and UPS systems, and store energy for solar installations. Almost all of the lead, plastic, and acid in a used battery can be recovered, and India already meets more than 80% of its lead demand from recycling.
Fuel cells turn hydrogen into electricity with water as the only exhaust, which makes them one of the most important technologies in India's clean energy transition. They power hydrogen buses, trucks, and trains, provide backup power for telecom towers and data centres, and supply off-grid and distributed electricity where diesel generators are used today.
India's cities generate well over a lakh tonnes of municipal solid waste every day, and much of it still ends up in overflowing dumpsites that release methane, catch fire, and pollute land and water.
Every solar power system needs an inverter to convert the direct current produced by solar panels into alternating current that homes, businesses, and the grid can use.
Sodium-ion batteries are emerging as a practical complement to lithium-ion technology. They work on the same principle, shuttling ions between a cathode and an anode, but use sodium, which is abundant, inexpensive, and available within India, in place of lithium.
Few industries in India have scaled as quickly as solar manufacturing. Backed by ambitious renewable energy targets, a rooftop programme for households, import duties on foreign modules, and the Approved List of Models and Manufacturers (ALMM), domestic module capacity has multiplied in just a few years.
Setting up an Electrical Panel Manufacturing Plant in India is a fabrication-and-assembly venture powered by heavy grid modernisation, a fast-growing renewable-energy build-out, rising industrial and commercial construction, and the spread of automation across factories and buildings.
Saudi Arabia has turned its power transition into one of the world's largest procurement programmes, and international developers, lenders, and equipment makers are following the tenders.
Setting up a Battery Manufacturing Plant in India is a high-demand, energy-driven venture, powered by the country's booming automotive sector, huge power-backup market, and the fast-growing shift to electric vehicles and renewable storage.
Setting up a Liquefied Natural Gas (LNG) Manufacturing Plant in India is a capital-intensive, strategically important venture, powered by the country's push toward a gas-based economy, the shift to cleaner fuels in transport and industry, and rising demand for LNG as a truck, bus, and industrial fuel.
The India carbon credit market is moving from a voluntary, project-by-project trade into a regulated national system with binding targets, a central registry, and exchange-based price discovery. According to IMARC Group, the market was valued at USD 33.69 Billion in 2025, grew to USD 44.42 Billion in 2026, and is projected to reach USD 405.47 Billion by 2034, expanding at a CAGR of 31.84% (2026–2034).
Setting up a Syngas Production Plant in India is a capital-intensive but strategically valuable venture, driven by the country's push for cleaner industrial fuels, coal and biomass utilization, and chemical self-reliance. Syngas, or synthesis gas, is a mixture of hydrogen and carbon monoxide produced by gasifying carbon-rich feedstocks, and it serves as a versatile building block for power, chemicals, hydrogen, and synthetic fuels. With abundant biomass, coal, and waste feedstock and growing policy support for gasification, India offers a favourable environment for new plants.
Setting up a Battery Energy Storage System Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's renewable energy expansion, grid modernization, and supportive storage policies. As solar and wind capacity scales up and the grid needs to balance variable generation, battery energy storage systems have become essential infrastructure.
Setting up a Lithium-ion Battery Recycling Plant in India is a capital-intensive but high-potential venture. India's rapid rise as a major electric-vehicle market, its large consumer-electronics base, and its fast-growing energy-storage sector are together creating one of the deepest and fastest-expanding pools of end-of-life lithium-ion batteries in the world.
Solar glass is a type of specialty glass that has high transmittance and is designed exclusively for use in solar energy systems. Unlike regular flat glass, solar glass is designed to have maximum light transmission with minimal losses due to reflection and absorption.
A solar inverter is a vital component in solar photovoltaic (PV) systems, responsible for transforming the direct current (DC) electricity produced by solar panels into alternating current (AC) electricity. This AC power is then suitable for use by the electrical grid, various appliances, and industrial equipment.
Australia has firmly established itself as a dominant force in the global liquefied natural gas (LNG) market, maintaining its position as one of the world's leading exporters. The country's strategic geographical location in the Asia-Pacific region, combined with substantial natural gas reserves, has enabled it to become a critical energy supplier to rapidly growing Asian economies, particularly China, Japan, and South Korea.
Japan's lead acid battery market stands as a cornerstone of the nation's energy storage infrastructure, demonstrating remarkable resilience and adaptability in an era dominated by rapid technological evolution. Despite the global shift toward lithium-ion technologies, the Japanese lead acid battery sector continues to thrive, driven by its unmatched cost-effectiveness, proven reliability, and exceptional recyclability.
Green hydrogen is the cleanest form of hydrogen available, as it is produced through water electrolysis using the electricity generated from renewable energy sources such as solar, wind, or hydropower. Carbon dioxide emissions are zero since no fossil fuels are used. Essentially, an electrolyzer is used in the electrolysis process to split water molecules into hydrogen and oxygen. The resulting hydrogen is refined by purification, compression, or liquefaction and then fed into various applications. Green hydrogen is considered a cornerstone of the global energy transition because it can store renewable energy, decarbonize hard-to-abate sectors, and serve as a sustainable alternative to fossil-fuel-based hydrogen.
Japan’s thermal power plant industry remains a crucial pillar of the nation’s energy infrastructure, providing a stable and reliable source of electricity for both industrial and residential consumption. Thermal power generation, which primarily involves the combustion of fossil fuels such as coal, natural gas, and oil, continues to play a key role despite increasing investments in renewable energy.
An electrical panel, also called a distribution board or switchboard, is an important installation in electrical infrastructure that acts as the main center for the distribution, control, and protection of electrical power within residential, commercial, and industrial systems. It acts as the point at which electrical energy is received from the utility or a source of power generation and is distributed to various circuits and equipment in an organized manner.
The global oil and gas EPC market is currently experiencing a remarkable transformation as it positions itself at the intersection of traditional energy demands and technological innovation. As of 2024, the market is demonstrating robust growth, reaching USD 52.9 Billion in 2024, depending on regional scope and market segmentation approaches. This substantial market base is supporting a major number of capital projects worldwide, including offshore platform projects and onshore installations that are collectively shaping the energy landscape.
Bamboo pellets are a biomass fuel type created through the compression of bamboo residues like shavings, sawdust, and chips into thick cylindrical pellets. They are an environmentally friendly substitute for conventional fossil fuels like natural gas and coal. Due to the fast growth rate and high biomass yield of bamboo, it has become one of the most renewable raw materials for the production of bioenergy.
Biomass briquettes are dense, solid fuel blocks made of compressed organic waste materials like sawdust, agricultural wastes, wood shavings, coconut shells, rice husk, or herbaceous biomass. The briquetting process usually involves drying the biomass to lower the moisture content (usually down to 10-15%), grinding or milling for a fine particle size uniformity, and then compressing under high pressure with or without a binding agent.
Biogas is a renewable energy form generated by the anaerobic fermentation of organic matter including agricultural residues, animal waste, municipal solid waste, sewage sludge, and food waste. Microorganisms in the absence of oxygen break down organic substances in the process and produce a gaseous mixture of mainly methane (CH4) and carbon dioxide (CO2), with traces of hydrogen sulfide (H2S) and water vapor.
A battery is an electrochemical energy storage system that transforms chemical energy into electrical energy by way of redox reactions between its electrodes and electrolyte. It consists of a single or multiple electrochemical cells, each having a positive electrode (cathode), a negative electrode (anode), and an electrolyte for ion transfer. Batteries are categorically divided into primary (non-rechargeable) and secondary (rechargeable) types.
The global energy landscape is undergoing a seismic transformation, with green hydrogen emerging as one of the most promising solutions to achieve deep decarbonization across sectors. Far from a niche technology, green hydrogen is emerging as a critical pillar of the future energy system, offering a pathway to a sustainable and resilient economy.
Transmission line towers are essential support components of transmission lines installed on overhead to distribute high-voltage electricity over long distances. Towers are made of galvanized steel, primarily, and are designed to tolerate mechanical stress, environmental loads, and electrical safety. Some of the important characteristics of transmission line towers are high structural strength, corrosion resistance, adaptability for modular design, and high service life. They are normally produced in lattice form (tubular or free-standing towers) or tubular form, with types including suspension towers, tension towers, angle towers, and terminal towers based on use.
The energy storage revolution is here, and it's powered by graphene. While the world struggles with the limitations of conventional lithium-ion batteries, a new technology is emerging that promises to shatter every performance barrier we've accepted as unchangeable.
Australia is undergoing a significant energy transformation, underscoring the growing role of renewable energy sources. These sources are key to combating climate change by reducing greenhouse gas emissions, the primary cause of global warming and air pollution. Beyond environmental benefits, renewable energy strengthens energy security by diversifying power sources and reducing dependence on volatile fossil fuel imports, contributing to greater energy independence.
Learn how to plan capital investment, manage raw material costs, post manufacturing cost and optimize operations for setting up solar panel plant.
Battery Energy Storage System (BESS) represents a power grid technology that stores electricity to enhance electric power grid reliability while increasing operational efficiency. BESS permits battery recharging during periods of low demand or extra grid supply capacity. BESS provides three principal operational functionalities which include power grid stabilization during supply disruptions, control of energy supply variations, and integration of intermittent renewable generation from wind and solar resources.
China's economic presence is expanding globally, and Latin America and the Caribbean (LAC) have become a focal point for its investments, especially within the energy sector. The region, rich in natural resources and experiencing rising energy demands, offers strategic opportunities for Chinese energy giants looking to invest and expand. LAC is currently leading a transformative movement towards sustainable energy. From 2015 to 2022, the region increased its renewable energy capacity by an impressive 51%, now generating 64% of its electricity from renewables such as hydropower, wind, and solar. This shift addresses the global demand for cleaner energy while supporting local economic growth and enhancing energy security.
Hydrogen is a clean, renewable, and widely available energy source that can be produced through various methods. Production techniques such as coal gasification, steam methane reforming, electrolysis, and thermochemical processes highlight its versatility. Hydrogen is essential in several critical sectors, including methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant. The increasing concern over carbon emissions and greenhouse gases has led to a shift towards cleaner fuel options. Hydrogen is recognized for its cleanliness and versatility as an energy carrier. Additionally, supportive government initiatives and favorable policies are driving the growth of hydrogen production globally.
Hydrogen is a clean, renewable, and abundant energy source derived from various methods. Its applications span across transportation, heating, and power generation. Diverse production methods, including coal gasification, steam methane reforming, electrolysis, and thermochemical processes, contribute to its versatility. Hydrogen plays a pivotal role in crucial sectors like methanol and ammonia production, petroleum refining, transportation, power generation, as well as in electronics, metal industries, and as a rocket propellant.
A floating solar farm is a renewable energy installation in which solar panels are mounted on floating structures in water bodies such as lakes, reservoirs, ponds, or even the sea. This technology, also known as a floating photovoltaic (PV) system, or “floatovoltaics,” enables solar power generation in areas with limited available land or where land use is restricted for other purposes. Floating solar farms offer various benefits, including improved solar panel efficiency through cooling, land conservation, reduction of evaporation and algae growth, and integration with hydropower facilities to generate both solar and hydroelectric power in the same location.
Nuclear power utilizes nuclear reactions to generate heat, which is then converted into electricity. This energy is released from the nucleus—the core of atoms composed of protons and neutrons. Nuclear power can be derived from nuclear fission, nuclear decay, and nuclear fusion reactions. Across the globe, nuclear power plants predominantly use the fission of uranium and plutonium to produce electricity. The heat generated from fission is used to create steam, which drives turbines connected to generators. Nuclear power offers several advantages over fossil fuels, such as minimal greenhouse gas emissions and a higher energy density, meaning a small amount of nuclear fuel produces a large amount of energy.