SiC Power Devices Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
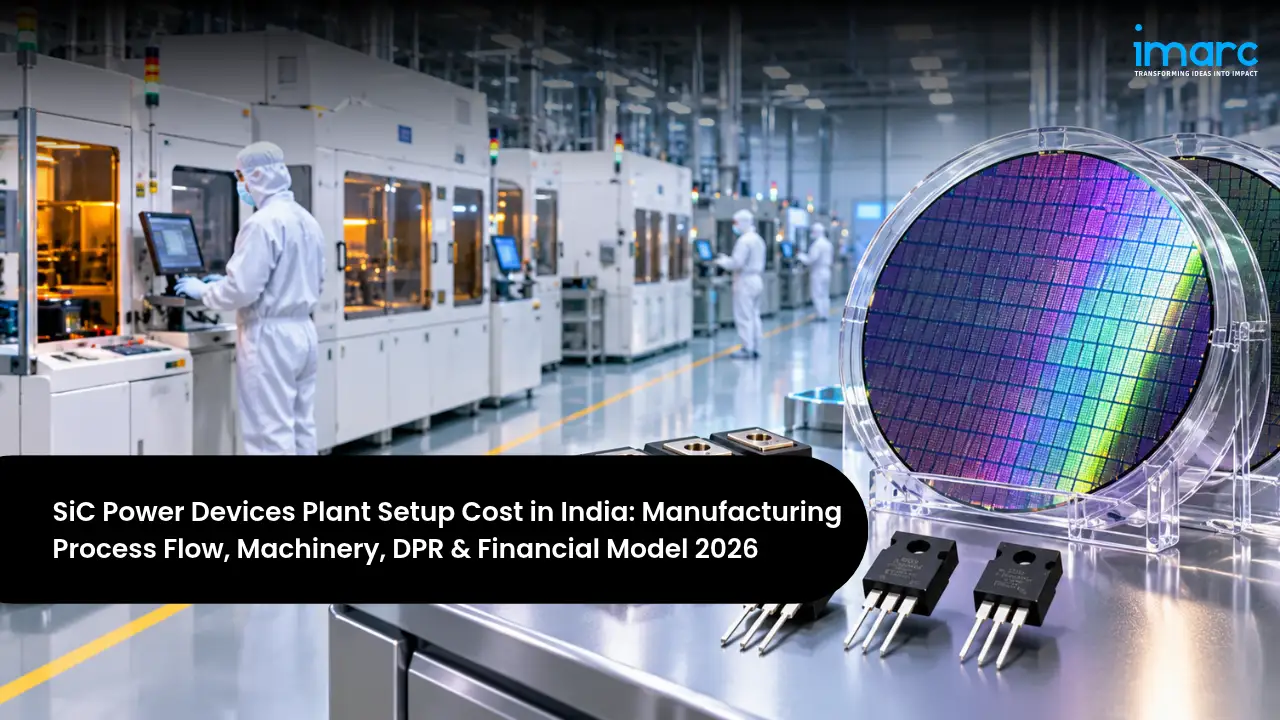
A SiC Power Devices Manufacturing Plant Setup in India places investors at the centre of the country's semiconductor and energy transition plans. Silicon carbide (SiC) is a wide-bandgap semiconductor that can switch higher voltages, at higher frequencies and temperatures, with far lower losses than conventional silicon. SiC MOSFETs, Schottky diodes, and power modules are now the preferred switches in electric vehicle traction inverters and on-board chargers, fast chargers, solar and storage inverters, railway traction, industrial drives, and data centre power supplies. India currently imports almost all of these devices, and the Union Cabinet's approval of the country's first commercial SiC fab in Odisha in 2025 has opened the door to a domestic SiC supply chain.
The overall SiC Power Devices Manufacturing Plant Cost depends mainly on whether the project covers front-end wafer fabrication, back-end assembly and test, or both, along with wafer size and capacity, epitaxy, high-temperature implantation and annealing tools, cleanroom area, ultra-pure water and gas systems, packaging lines, and the cost of qualifying products with automotive and industrial customers. An integrated 150 mm plant processing about 30,000 wafers a year with packaging typically needs INR 1,200 crore to INR 2,000 crore, while an assembly, test, and packaging unit for SiC discretes and modules using purchased die can start at around INR 150 crore to INR 400 crore. IMARC Group puts typical capacities at 10,000 to 50,000 wafers a year, with gross margins of 30 to 42% and net margins of 10 to 20%.
This guide is written for semiconductor companies, power electronics and EV component makers, global SiC players evaluating India, and investors exploring how to start a SiC Power Devices manufacturing plant in India. It explains device types and applications, demand drivers, the fabrication and packaging flow, machinery and materials, site selection in semiconductor clusters, a detailed cost and returns breakdown, India Semiconductor Mission support and other approvals, and how a DPR pulls these elements into a bankable plan.
India Market Snapshot
| Key Facts | Details |
|---|---|
| India Semiconductor Mission 2.0 Outlay | INR 1.275 Lakh Crore (approved July 2026) |
| Central Support for Compound Semiconductor Fabs | Up to 50% of project cost, pari-passu (ISM scheme) |
| India's First Commercial SiC Fab (SiCSem, Odisha) | 60,000 Wafers and 96 Million packaged units a year |
| Asia-Pacific Share of SiC Power Device Market | About 43.4% |
| Typical SiC Device Plant Capacity | 10,000–50,000 Wafers a year |
| Indicative Total Investment | INR 1,200–2,000 Crore (30,000 Wafers a year, integrated) |
The snapshot shows strong policy backing and a market in which Asia-Pacific already leads, according to IMARC Group. The second phase of the India Semiconductor Mission, approved in July 2026, explicitly targets compound semiconductors alongside silicon fabs and display units, and central and state incentives together can cover a large share of project cost, which materially improves the economics of a domestic SiC plant.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Product Range | SiC Schottky diodes, SiC MOSFETs (650 V–3.3 kV), power modules, bare die and foundry services |
| Total Project Investment | INR 1,200 – 2,000 Crore (integrated 30,000 Wafers a year); INR 150 – 400 Crore (assembly, test and packaging only) |
| Payback Period | 6 – 8 Years |
| Net Profit Margin | 10 – 20% (IMARC benchmark) |
| IRR | 14 – 20% (with ISM and state incentives) |
| Best Locations | Odisha, Gujarat, Uttar Pradesh, Karnataka, Tamil Nadu, Andhra Pradesh |
| Mandatory Approvals | ISM Approval for Fiscal Support, SPCB Consents, PESO Gas Licenses, Factory License (MAH), Environmental Clearance where applicable |
| Key Requirement | Technology partner, secure SiC substrate supply, skilled engineers, and customer qualification |
These figures offer a practical frame for early evaluation. Returns depend on access to proven device technology, secure supply of SiC substrates, manufacturing yield, the speed of automotive and industrial qualification, utilisation of an expensive tool set, and the level of central and state fiscal support. A capacity- and technology-specific SiC Power Devices Feasibility Report refines these numbers before capital is committed.
Table of Contents
- What is SiC Power Devices Manufacturing?
- Why is SiC Power Devices Manufacturing Growing in India?
- SiC Power Devices Manufacturing Process Flow
- Raw Materials Required for SiC Power Devices Manufacturing
- Location, Land & Infrastructure
- SiC Power Devices Manufacturing Machinery and Equipment
- SiC Power Devices Manufacturing Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for SiC Power Devices Manufacturing in India
- Recent Developments in the India SiC Power Devices Manufacturing Industry
- How SiC Power Devices Manufacturing Project Report and DPR Helps Investors
- Frequently Asked Questions
What is SiC Power Devices Manufacturing?
SiC power device manufacturing has two main stages. In front-end fabrication, polished SiC substrates are cleaned and a precisely doped epitaxial layer is grown on them by chemical vapour deposition. Device structures are then built through repeated cycles of photolithography, high-temperature ion implantation, activation annealing at very high temperatures, gate oxidation, etching, thin-film deposition, and metallisation, followed by wafer thinning and backside contacts. Finished wafers are tested electrically on probers. In back-end assembly, the wafers are diced, and the chips are attached to lead frames or ceramic substrates, often by silver sintering, connected with wire bonds or clips, moulded or enclosed in modules, burned in, and tested before shipment. A SiC Power Devices Manufacturing Plant can cover either or both stages, supported by cleanrooms, ultra-pure water, specialty gas systems, and metrology.
Devices are sold to EV and component makers, charger and inverter manufacturers, industrial drive and UPS companies, railway and defence suppliers, data centre power supply makers, and power module assemblers. Buyers expect low on-resistance and switching losses, high reliability under heat and voltage stress, consistent parametric performance, automotive qualification such as AEC-Q101 for discretes and AQG 324 for modules, IATF 16949 quality systems, and secure long-term supply.
- SiC Schottky Diodes: For power factor correction, solar inverters, and chargers.
- SiC MOSFETs: For EV traction inverters, on-board chargers, and fast chargers.
- SiC Power Modules: For traction, rail, industrial drives, and renewable energy.
- Bare Die and Foundry Services: For module makers and fabless device companies.
Main Product Types in SiC Power Device Production
The product mix shapes process complexity, qualification, and margins:
| Product Type | Description | Key Feature | Primary Market |
|---|---|---|---|
| SiC Schottky Diodes (650–1,700 V) | Simple unipolar devices | Fast entry product | PFC, solar, chargers |
| SiC MOSFETs (650–1,700 V) | Planar or trench transistors | Core high-value device | EVs, chargers, inverters |
| High-Voltage Devices (3.3 kV+) | Thick epitaxial layers | Niche, high value | Rail, grid, defence |
| Power Modules | Multiple dies in one package | Highest value per unit | Traction, industrial, renewables |
| Foundry & Bare Die | Wafers or dies for others | Asset-light customers | Module makers, fabless firms |
Many new entrants start with Schottky diodes and 1,200 V planar MOSFETs under licensed or partner technology, alongside discrete packaging, and then add power modules, higher-voltage devices, and trench MOSFETs as yields, qualification, and customer relationships mature. Starting with assembly and test of partner die is a common way to build customers before the front-end fab ramps up.
Why is SiC Power Devices Manufacturing Growing in India?
Key Growth Drivers in the Global and Indian Market
Demand for SiC devices is driven by electrification, renewable energy, and India's push for semiconductor self-reliance. IMARC Group expects strong double-digit growth in the coming years:
- Electric vehicles: SiC inverters and chargers extend EV range and cut charging time, and Indian two-, three-, and four-wheeler makers are adopting them.
- Renewable energy and storage: India's large solar, wind, and battery storage build-out needs efficient inverters and converters.
- Fast charging and data centres: High-power chargers and AI data centre power supplies require compact, efficient switches.
- Railways, industry and defence: Traction converters, industrial drives, and strategic systems benefit from rugged, high-voltage SiC devices.
- Semiconductor policy: India Semiconductor Mission support and state policies reduce capital cost and encourage domestic supply.
Application Market Opportunity
| Application | Demand Driver | Product Role |
|---|---|---|
| EV Traction & On-Board Charging | EV adoption and efficiency | MOSFETs, modules |
| EV Fast Chargers | Charging infrastructure growth | MOSFETs, diodes, modules |
| Solar, Wind & Storage Inverters | Renewable capacity targets | MOSFETs, diodes |
| Rail Traction & Industrial Drives | Railway modernisation, automation | High-voltage modules |
| Data Centres & Defence | AI computing, strategic autonomy | Discretes and modules |
The strongest position for a SiC Power Devices Manufacturing Plant in India combines a proven technology partner, secure substrate supply, high manufacturing yields, early engagement with Indian EV, charger, and inverter makers, automotive-grade quality systems, and full use of central and state incentives. Projects that pair front-end fabrication with domestic packaging and anchor customers are best placed to capture value.
SiC Power Devices Manufacturing Process Flow
Understanding the SiC Power Devices Manufacturing Process helps promoters plan tool selection, cleanroom layout, utilities, staffing, and quality control. SiC differs from silicon processing in several ways: substrates are expensive and hard, epitaxial layers must be grown with very low defect densities, dopants must be implanted at high temperature and activated at very high temperatures, and the gate oxide interface needs special treatment for reliable MOSFETs. The flow below reflects a typical integrated plant.
Step-by-Step SiC Power Device Manufacturing Flow
Substrates are inspected and cleaned before an epitaxial drift layer is grown. Device regions are patterned by lithography and formed by ion implantation, followed by activation annealing, gate oxidation, etching, deposition, and metallisation. Wafers are thinned, backside contacts are formed, and every die is tested on probers before dicing, die attach, interconnection, moulding or module assembly, burn-in, and final testing.
| Unit Operation | Key Activity |
|---|---|
| Substrate Inspection & Cleaning | Check defects, prepare wafers |
| Epitaxial Growth | Grow doped drift layer by CVD |
| Photolithography | Pattern device regions |
| Ion Implantation | High-temperature doping |
| Activation Annealing | Activate dopants |
| Gate Oxidation & Passivation | Form MOSFET gate stack |
| Etching & Thin-Film Deposition | Build device structures |
| Metallisation & Backside Processing | Contacts, thinning |
| Wafer Probe & Dicing | Test and separate dies |
| Assembly, Burn-in & Final Test | Package, stress test, ship |
Two factors decide profitability. The first is yield and substrate cost: SiC substrates are a major cost, and defects in substrates and epitaxy reduce the number of good dies per wafer, so improving yield is the most powerful lever on unit cost. The second is qualification and utilisation: an expensive tool set only pays back when the plant runs near capacity, which requires winning automotive and industrial qualifications and long-term supply agreements as early as possible.
Raw Materials Required for SiC Power Devices Manufacturing
The main inputs are SiC substrates, epitaxial precursor and dopant gases, photoresists and wet chemicals, etch and deposition gases, metals and sputtering targets, and packaging materials. IMARC Group estimates raw materials at 40 to 50% of operating cost and utilities at 20 to 28%.
| Raw Material | Role in Process | India Sourcing | % of OpEx |
|---|---|---|---|
| SiC Substrates (150 mm / 200 mm) | Base wafers for devices | Imported from global substrate makers | 25–32% |
| Epitaxy & Dopant Gases (Silane, Propane, Nitrogen, Aluminium Precursors) | Grow and dope epitaxial layers | Specialty gas suppliers | 3–5% |
| Photoresists, Wet Chemicals & Etch Gases | Patterning, cleaning, etching | Imported and domestic suppliers | 3–5% |
| Metals & Sputtering Targets | Contacts and metallisation | Imported suppliers | 2–3% |
| Packaging Materials (Lead Frames, Ceramic Substrates, Sinter Paste, Mould Compound) | Assembly of devices and modules | Imported and domestic suppliers | 4–6% |
SiC substrates are produced by a small number of companies in the United States, Europe, Japan, and China, so long-term supply agreements, dual sourcing, and close quality monitoring are essential. Specialty gases and high-purity chemicals also come largely from global suppliers, though suppliers are beginning to localise in Indian semiconductor clusters. Domestic substrate and epitaxy capacity, a stated focus of the second phase of the Semiconductor Mission, would reduce this dependence over time.
Location, Land & Infrastructure
Location shapes access to incentives, utilities, skills, and customers. The best location for SiC Power Devices manufacturing plant setup lies in a designated semiconductor or electronics cluster with a supportive state semiconductor policy, highly reliable power, large volumes of high-quality water, specialty gas and chemical logistics, an airport for time-critical imports and exports, and access to engineering talent.
Preferred States for SiC Power Device Plants in India
| State | Why It Works | Key Advantage |
|---|---|---|
| Odisha | India's first SiC fab and SiC projects in Bhubaneswar | Emerging SiC cluster, state incentives |
| Gujarat | Dholera and Sanand semiconductor hubs | Fab and OSAT ecosystem |
| Uttar Pradesh | Semiconductor parks near Jewar and Noida | Electronics base, policy support |
| Karnataka | Bengaluru chip design ecosystem | Talent and design partners |
| Tamil Nadu | EV and electronics manufacturing base | Customers and skilled workforce |
| Andhra Pradesh | Approved semiconductor ATMP projects | Policy support, ports |
Odisha has emerged as India's SiC hub, with SiCSem's approved compound semiconductor fab and RIR Power Electronics' SiC facility at Info Valley, Bhubaneswar. Gujarat offers the most developed semiconductor ecosystem around Dholera and Sanand, while Uttar Pradesh, Karnataka, Tamil Nadu, and Andhra Pradesh provide electronics clusters, design talent, EV and electronics customers, and state semiconductor incentives. Sites inside designated semiconductor parks benefit from shared utilities and faster approvals.
Cleanroom, Quality and Safety Requirements
SiC device plants require classified cleanrooms, tight control of particles, temperature, humidity, and vibration, and contamination control across every process step. Automotive customers require IATF 16949 quality systems, statistical process control, full traceability, and qualification to AEC-Q101 or AQG 324. Safety controls are equally important, as plants handle pyrophoric and toxic gases such as silane, corrosive acids, and high-temperature equipment, requiring gas cabinets, detection and abatement systems, scrubbers, emergency response plans, and trained staff.
Infrastructure Requirements (30,000 Wafers a Year Plant)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Total Land Area | 20 – 40 acres | Fab, packaging, utilities, expansion |
| Front-End Cleanroom | 3,000 – 6,000 m², ISO 5–7 | Vibration-controlled structure |
| Back-End Assembly Area | 2,000 – 4,000 m² | Cleanroom and controlled zones |
| Power | 15 – 30 MW, dual feed | Very high reliability, backup |
| Ultra-Pure Water | 500 – 1,500 KLD | UPW plant with recycling |
| Specialty Gases & Chemicals | Bulk and cylinder gas systems | Storage under PESO rules |
| Waste Treatment | Acid, fluoride and gas abatement | Zero liquid discharge often required |
Infrastructure for a SiC plant centres on vibration-isolated cleanroom buildings, an ultra-pure water plant, bulk and specialty gas systems, chemical distribution, exhaust and abatement systems, reliable high-capacity power with backup, waste treatment, metrology laboratories, and secure warehousing. Planning cleanroom shell space for 200 mm conversion and additional tools from the outset supports future growth.
SiC Power Devices Manufacturing Machinery and Equipment
Front-end and back-end equipment for SiC devices is supplied mainly by global semiconductor tool makers in the United States, Europe, Japan, and Asia, with some SiC-specific tools such as high-temperature implanters and activation furnaces from specialist vendors. The main equipment is summarised below.
| Equipment | Function | Key Specification |
|---|---|---|
| Epitaxial CVD Reactors | Grow SiC epitaxial layers | Low defect density, uniform doping |
| Photolithography Steppers & Track | Pattern device layers | Sized for 150/200 mm wafers |
| High-Temperature Ion Implanters | Dope SiC regions | Heated wafer chucks |
| Activation Anneal Furnaces | Activate implanted dopants | Very high temperature |
| Oxidation & Diffusion Furnaces | Grow gate oxide | Interface treatment capability |
| Plasma Etch & PVD/CVD Deposition Tools | Etch and deposit films | SiC-compatible processes |
| Wafer Grinding & Backside Laser Anneal | Thin wafers, form contacts | Low-resistance backside |
| Metrology, Inspection & CMP Tools | Control quality | Defect and parametric inspection |
| Wafer Probers & Dicing Saws | Test and separate dies | High-voltage probing, laser or blade dicing |
| Die Attach (Sintering), Bonders, Moulding, Burn-in & Test | Assemble and qualify devices | Automotive-grade lines |
Equipment selection should follow wafer size, product mix, and capacity. Epitaxy and implantation tools largely determine device performance and yield, while back-end sintering and testing determine reliability. Many promoters begin with 150 mm wafers and a balanced tool set for diodes and planar MOSFETs, adding tools for trench devices, higher volumes, and 200 mm wafers as demand grows.
SiC Power Devices Manufacturing Plant Setup Cost in India (CapEx & OpEx)
The tables below summarise the capital and operating cost structure of an integrated SiC power device plant processing about 30,000 wafers a year with in-house packaging in India. The final SiC Power Devices Investment Cost for a specific project depends on wafer size, front-end and back-end scope, tool set and redundancy, cleanroom area, utilities, technology license fees, land, and the level of central and state fiscal support.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Front-End Process Tools | 45–55% | Epitaxy, lithography, implant, anneal, etch, deposition |
| Back-End Assembly & Test Equipment | 10–14% | Dicing, sintering, bonding, moulding, test |
| Cleanroom & Building | 12–16% | Cleanroom shell, fit-out, HVAC |
| Utilities (UPW, Gases, Power, Abatement) | 8–12% | UPW plant, gas systems, substations |
| Technology License & Pre-operative | 4–7% | License fees, training, qualification |
| Land & Site Development | 2–4% | Land in semiconductor park |
| Working Capital & Contingency | 4–6% | Substrates, materials, start-up |
Process tools account for most of the fixed investment, which is why utilisation and fiscal support have such a strong effect on returns. A SiC Power Devices Business Plan models these components so that capacity, product mix, ramp-up, and financing rest on realistic yield, pricing, and incentive assumptions.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Raw Materials | 40–50% | SiC substrates dominate |
| Utilities | 20–28% | Cleanroom HVAC, UPW, power |
| Labour | 8–12% | Engineers, technicians, operators |
| Maintenance & Spares | 6–9% | Tool service contracts |
| Technology Royalties | 2–4% | Where licensed |
| Quality, Logistics & Overheads | 3–5% | Qualification, air freight, admin |
With substrates and utilities making up most of operating cost, profitability depends on yield, tool utilisation, substrate prices, and device selling prices, which have been falling as global capacity expands. A sound financial model should test margins against slower qualification, lower utilisation, faster price declines, substrate price swings, and delays in incentive disbursement.
Financial Analysis and Profitability
SiC power devices offer attractive long-term returns for well-executed projects, though capital needs and ramp-up times are significant. The profitability of SiC Power Devices manufacturing business in India improves with strong fiscal support, a proven technology partner, secure substrates, fast yield learning, early automotive and industrial qualification, anchor customer agreements, integrated packaging, and a product mix that moves towards MOSFETs and modules.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 30–42% | IMARC benchmark |
| Net Profit Margin | 10–20% | After depreciation and Indian corporate taxes |
| Payback Period | 6–8 Years | Includes ramp-up and qualification |
| IRR (Internal Rate of Return) | 14–20% | With ISM and state incentives |
| Capacity Utilization (stable ops) | 70–85% | After qualification |
| Break-even Capacity Utilization | 50–60% | High fixed costs |
Incentives, yield, and customer qualification are the decisive factors. Central support of up to 50% of project cost, combined with state incentives, can transform project economics, but returns ultimately depend on producing competitive devices at good yields and winning long-term business from EV, charger, and inverter makers as global prices fall. Projects with established technology partners and committed customers are best placed to succeed.
Returns can be strengthened by securing maximum central and state support, licensing proven device designs, signing long-term substrate agreements, locating in semiconductor parks with shared utilities, ramping with simpler diodes before MOSFETs, offering packaging and module services, building partnerships with Indian EV and renewable energy companies, and planning an early path to 200 mm wafers.
Key Risks and Mitigation
The main risks are technology access and yield learning, dependence on imported substrates and tools, long qualification cycles, rapid global price declines as SiC capacity expands, shortages of experienced engineers, and delays in incentives or approvals. Technology risk is reduced through partnerships and licenses; supply risk through long-term contracts and dual sourcing; qualification risk through early customer engagement; price risk through cost reduction and value-added modules; talent risk through training programmes and international hiring; and policy risk through close coordination with the Semiconductor Mission and state agencies.
Licenses and Approvals for SiC Power Devices Manufacturing in India
A SiC power device unit requires semiconductor incentive, environmental, hazardous materials, industrial, and quality approvals. Promoters typically need the following before starting commercial production:
- India Semiconductor Mission Approval: Application to the India Semiconductor Mission under MeitY for fiscal support under the compound semiconductor and ATMP schemes, followed by agreements with the state government for additional incentives.
- Environmental Clearance and Pollution Consents: Environmental clearance where applicable, plus Consent to Establish and Consent to Operate from the State Pollution Control Board, covering acid, fluoride, and gas emissions.
- PESO Licenses: Licenses for storage and handling of compressed and specialty gases, including hydrogen and silane.
- Factory License and Hazardous Chemical Compliance: Factory registration, safety reports, and on-site emergency plans for major accident hazard installations.
- Customs and Import Facilitation: SEZ, EOU, or bonded warehouse status and customs registrations for duty-free import of tools and materials.
- Quality and Product Qualifications: ISO 9001, ISO 14001, IATF 16949 certification, and product qualification to AEC-Q101, AQG 324, or customer standards.
- Business Registrations: Company incorporation, GST, an Import Export Code, and compliance with export control requirements for strategic customers.
ISM approval, environmental consents, and gas licenses usually sit on the critical path, while customer qualification determines when commercial sales can begin. Engaging a SiC Power Devices Manufacturing Consultant in India can help promoters select technology partners and sites, structure incentive applications, plan tool procurement, and organise approvals and qualification.
Note: The exact approvals, registrations, licenses, and certification requirements may vary depending on factors such as plant location, product range, capacity, target customers, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India SiC Power Devices Manufacturing Industry
Several recent developments are shaping the SiC power device industry in India and globally:
- India's first commercial SiC fab approved: On 12 August 2025, the Union Cabinet approved SiCSem's compound semiconductor fab at Info Valley, Bhubaneswar, Odisha, in collaboration with Clas-SiC Wafer Fab of the UK, with annual capacity of 60,000 wafers and 96 million packaged units.
- New foundry capacity for SiC MOSFETs: In March 2026, SK keyfoundry completed development of its SiC planar MOSFET process platform and won an order for a 1,200 V SiC MOSFET, entering the SiC compound semiconductor foundry business.
- India Semiconductor Mission 2.0: In July 2026, the Government of India approved the second phase of the Semiconductor Mission with an outlay of INR 1.275 lakh crore, with compound semiconductors among its target areas.
Together these point to strong policy momentum in India and expanding global SiC manufacturing and foundry options. For new entrants, success depends on technology partnerships, substrate security, yield, qualification with Indian and global customers, and full use of available incentives.
How SiC Power Devices Manufacturing Project Report and DPR Helps Investors
A detailed SiC Power Devices Project Report gives investors a structured roadmap covering demand by application, customer requirements, product roadmap, technology options and partners, process design, tool set, cleanroom and utilities, substrate and materials supply, workforce, incentives, approvals, and economics. It helps promoters choose the right scope, wafer size, and capacity, estimate capital expenditure (CapEx) and operating expenditure (OpEx), assess profitability, and identify risks before implementation.
At the core of the DPR is a SiC Power Devices Financial Model covering wafer starts and ramp-up, yields by product, die per wafer, average selling prices and price erosion, substrate and materials costs, utilities, labour, maintenance, royalties, central and state incentives, working capital, cash flow projections, break-even, return on investment (ROI), and payback. Because yields, prices, and incentives drive returns, lenders and the Semiconductor Mission expect detailed sensitivity analysis, which is why many promoters engage a SiC Power Devices Plant Project Report Consultant in India to prepare investment-ready documents.
For a SiC project specifically, a strong DPR also answers the questions that matter most: which technology partner and device roadmap to adopt, where substrates will come from, how fast yields and qualification can be achieved, which customers will commit to volumes, and how returns hold up if prices fall faster or ramp-up is slower than planned. An experienced SiC Power Devices Manufacturing Feasibility Study Consultant tests these scenarios so that the final plan is one lenders, partners, and government agencies can back with confidence.
Frequently Asked Questions
How do I set up a SiC power devices manufacturing plant in India?
Start by securing a technology partner, substrate supply, and anchor customers, then commission a feasibility study and DPR. Choose a site in a semiconductor cluster, apply for India Semiconductor Mission and state incentives, build cleanrooms and utilities, install front-end and back-end tools, obtain environmental, gas, and factory approvals, and complete customer qualification before volume production.
What is the cost of setting up a SiC power devices manufacturing plant in India?
An integrated 150 mm plant processing about 30,000 wafers a year with packaging typically needs INR 1,200 crore to INR 2,000 crore. An assembly, test, and packaging unit for SiC discretes and modules using purchased die can start at around INR 150 crore to INR 400 crore.
How are SiC power devices made?
SiC substrates receive an epitaxial layer, then device structures are formed through lithography, high-temperature ion implantation, activation annealing, gate oxidation, etching, deposition, and metallisation. Wafers are thinned, tested, and diced, and the chips are assembled, burned in, and tested as discretes or modules.
What machinery is needed for a SiC power devices manufacturing plant?
Key equipment includes epitaxial CVD reactors, lithography tools, high-temperature ion implanters, activation anneal furnaces, oxidation furnaces, plasma etch and deposition tools, wafer grinding and backside anneal systems, metrology tools, wafer probers, dicing saws, die attach and sintering systems, wire bonders, moulding, burn-in, and test equipment.
What raw materials are used in SiC power devices manufacturing?
The main inputs are SiC substrates, epitaxial precursor and dopant gases, photoresists, wet chemicals, etch gases, metals and sputtering targets, and packaging materials such as lead frames, ceramic substrates, sinter paste, and mould compounds.
Is SiC power devices manufacturing profitable in India?
Benchmark figures point to a 10 to 20% net margin and an IRR of around 14 to 20% with incentives, with payback in 6 to 8 years. Profitability depends mainly on yield, utilisation, substrate costs, price trends, qualification speed, and the level of government support.
What licenses are needed for a SiC power devices manufacturing unit in India?
A unit typically needs India Semiconductor Mission approval for incentives, environmental clearance where applicable, State Pollution Control Board consents, PESO gas licenses, a Factory License with hazardous chemical compliance, customs facilitation, quality certifications, GST, and an IEC.
Which state is best for a SiC power devices manufacturing plant?
Odisha, Gujarat, Uttar Pradesh, Karnataka, Tamil Nadu, and Andhra Pradesh are strong options. The best site is in a semiconductor park with strong state incentives, reliable power and water, and access to talent and customers.
How do I get a feasibility study or DPR for a SiC power devices manufacturing plant?
A professionally prepared DPR covers market and customer analysis, technology selection, tool and facility design, incentives, approvals, costs, and financial projections for appraisal by lenders and the Semiconductor Mission. Many promoters work with a SiC Power Devices Business Plan Consultant in India to prepare it and align it with lender and government requirements.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

A P.C.C. Electric Poles Manufacturing Plant Setup in India supplies the backbone of the country's power distribution network. Prestressed cement concrete (P.C.C.) poles are made by casting high-strength concrete around high-tensile steel wires that are stretched before casting and released once the concrete has hardened, which puts the concrete into compression and gives a slender, strong, and durable pole.
Yes, India's intensifying heat is one of the clearest demand signals behind the India air conditioning market, which IMARC Group values at USD 6.15 Billion in 2025 and USD 7.07 Billion in 2026. The market is projected to reach USD 21.59 Billion by 2034, growing at a CAGR of 14.98% during 2026-2034.
An Alkaline Battery Manufacturing Plant Setup in India addresses a product used in almost every home, office, and clinic, yet until recently made almost entirely abroad.
An LED Light Manufacturing Plant Setup in India taps into one of the largest and most mature consumer electrical markets in the country.
An LED Chip Manufacturing Plant Setup in India addresses one of the biggest gaps in the country's lighting and display supply chain. India assembles hundreds of millions of LED bulbs, battens, panels, and displays every year, yet almost all LED chips, the tiny semiconductor dies that actually emit light, are imported, mainly from China, Taiwan, and South Korea.
A Smartphone Manufacturing Plant Setup in India places an investor inside one of the country's biggest industrial success stories of the past decade.
A Smart Watch Manufacturing Plant Setup in India serves one of the world's largest wearables markets. Indian consumers buy tens of millions of smartwatches every year, and domestic brands have shifted much of their production from imports to local contract manufacturers.
The India Semiconductor Market has moved past the stage of ambition documents and into the stage of concrete assets, approved sites and dated delivery milestones. The India Semiconductor Market size reached USD 59.78 Billion in 2025, expanded to USD 73.00 Billion in 2026, and is projected to reach USD 180.20 Billion by 2034, growing at a CAGR of 11.95% over the 2026-2034 forecast period.
A genset combines an engine, usually diesel or gas, with an alternator that converts its motion into electricity, mounted on a steel base frame with a fuel tank, exhaust and emission after-treatment, a control panel, and in most cases a soundproof acoustic enclosure.
Setting up a Power Cable Manufacturing Plant in India puts an investor directly in the path of one of the country's largest infrastructure build-outs.
Servos are precision electric motors fitted with a position sensor, called an encoder, and paired with an electronic drive that controls speed, torque, and position very accurately.
PVC-insulated wires and cables are made by drawing copper or aluminium rod into fine conductors, annealing and stranding them, and covering them with coloured PVC insulation and, for multi-core cables, an outer PVC sheath and sometimes steel armour.
Portable chargers are compact battery packs made from lithium-ion or lithium-polymer cells, a charging and protection circuit board, ports or wireless coils, and a plastic or metal casing.
Small electric cooking and food preparation products, such as mixer grinders, induction cooktops, electric kettles, air fryers, hand blenders, and sandwich makers, are made by moulding plastic bodies, forming steel and aluminium parts, winding motors or fitting heating elements, assembling control boards, and wiring and testing each unit for safety.
Aluminum-air batteries generate electricity by reacting aluminum plates with oxygen from the air in a water-based electrolyte. Aluminum has a very high theoretical energy density, and instead of being recharged from a socket, spent plates are swapped for fresh ones while the aluminum hydroxide produced is recycled into new aluminum.
LED bulbs use light-emitting diodes mounted on a metal-core circuit board, powered by a small electronic driver and housed in a plastic and aluminium body with a diffuser and a standard B22 or E27 cap.
Inverters convert direct current from batteries or solar panels into the alternating current used by homes, shops, and factories.
Electrical control panels are steel enclosures that house circuit breakers, contactors, relays, busbars, meters, drives, and controllers to distribute power and control motors, machines, and processes safely.
Microchips, or integrated circuits and semiconductor devices, are the building blocks of phones, computers, vehicles, appliances, power systems, telecom networks, and defence equipment.
Resistors are the most widely used electronic components, found by the dozens or hundreds in almost every circuit board, from phones, laptops, and televisions to vehicles, appliances, telecom equipment, power electronics, medical devices, and defence systems.
Rare earth magnets, mainly neodymium-iron-boron (NdFeB) and samarium-cobalt, are the strongest permanent magnets made, and they sit at the heart of electric vehicle motors, wind turbine generators, electronics, industrial automation, medical devices, and defence systems. India imported over 53,000 tonnes of rare earth permanent magnets in 2024-25 and has almost no domestic production, while demand is expected to double by 2030.
Wires and cables carry power and signals through every home, office, factory, railway, data centre, and solar park, and India's market has grown to about USD 10 billion as construction, power transmission, renewable energy, and industrial investment have expanded.
Heat exchangers are among the most widely used pieces of engineering equipment in the world. Refineries, petrochemical and fertiliser plants, power stations, pharmaceutical and food factories, HVAC systems, and data centers all depend on them to heat, cool, condense, and recover energy from process streams.
India's trucks and buses rarely rest. They carry freight across highway corridors, move goods from ports and factories, and ferry millions of passengers every day, often under heavy loads and tough road conditions.
Silicon wafers are the thin, precisely sliced discs and squares on which solar cells and computer chips are built. India has rapidly become a major assembler of solar modules and is now building cell capacity, but almost all of the wafers those cells need are still imported.
Every video call, UPI payment, and 5G connection in India ultimately travels over glass. Fiber optic cables carry the country's data between cities, into mobile towers and data centres, and increasingly right into homes through fiber-to-the-home connections.
Setting up an Air Conditioner Manufacturing Plant in India is an assembly-driven, high-volume consumer durable venture, powered by rising household incomes, extreme summers, rapid urbanisation, and one of the lowest room air-conditioning penetration rates among large economies.
Setting up a High Voltage Cable Manufacturing Plant in India is a capital-intensive, high-value venture, powered by the country's massive power-transmission expansion, renewable-energy build-out, and the shift toward underground cabling in cities.
Setting up a Copper Cable Manufacturing Plant in India is a high-demand, infrastructure-driven venture, powered by the country's construction boom, rapid electrification, and steady industrial and appliance demand.
Setting up a Junction Box Manufacturing Plant in India is a high-demand, infrastructure-driven venture, powered by the country's construction boom, rapid electrification, and expanding solar and industrial sectors.
Setting up an Electric Cable Manufacturing Plant in India is a high-demand, infrastructure-linked venture, powered by the country's rapid growth in power, construction, renewable energy, and electrification. Cables and wires are essential to every building, factory, grid, and vehicle, giving an Electric Cable Manufacturing Plant a large and steadily growing market.
Setting up a Semiconductor Fabrication Manufacturing Plant in India is a highly capital-intensive but strategically transformative venture, driven by the country's semiconductor mission, deep policy incentives, and a vast import-substitution opportunity. Semiconductors are the foundation of every modern electronic and digital product, yet India currently imports almost all of its chip requirement.
Setting up a PCB Manufacturing Plant in India is a capital-intensive but strategically timed venture, driven by the country's electronics manufacturing push, strong policy incentives, and a large import-substitution opportunity. Printed circuit boards are the backbone of every electronic product, yet India still imports the overwhelming majority of its PCB requirement.
The Indian PCB (Printed Circuit Board) Market is emerging as the physical backbone of the country's electronics manufacturing ambitions. The market reached USD 7.27 Billion in 2025 and is projected to reach USD 25.48 Billion by 2034, growing at a CAGR of 14.96% (2026–2034), a total addressable market expansion driven by the Production Linked Incentive (PLI) scheme, 5G infrastructure rollout, and rising domestic consumer electronics demand.
Setting up an E-waste Recycling Plant in India is a capital-intensive but high-potential venture, driven by the country's soaring volume of discarded electronics, tightening Extended Producer Responsibility regulations, and the rising value of recovered metals. India is now among the world's largest generators of electronic waste, yet only a small share is processed through formal, compliant channels, leaving a large, policy-backed opportunity for organized recyclers who can capture volumes shifting from the informal sector.
Global semiconductor demand across automotive, data centers, and defense, highlighting market segmentation, key applications, regional dynamics, and industry shifts.
The hearables market represents one of the most dynamic segments within consumer electronics and wearable technology. These intelligent audio devices have evolved beyond simple wireless earbuds into multifunctional platforms combining premium audio with health monitoring, artificial intelligence, and seamless digital connectivity.
A smart washing machine is a sophisticated home appliance that incorporates advanced digital features such as connectivity, sensor technology, and automated controls for improved efficiency, convenience, and user control. In contrast to traditional washing machines, smart washing machines come pre-installed with advanced features such as Wi-Fi connectivity, smart load detection, smart detergent dispensing, and voice-control capability.
A smartphone is a portable electronic device that combines sophisticated capabilities in computer processing, wireless communication, multimedia entertainment, and internet access. Smartphones are distinct from other mobile phones in that their operation involves highly sophisticated platforms of operation that are capable of supporting multiple applications, multitasking, and connectivity with internet platforms.
Semiconductor manufacturing is a highly specialized industrial process that involves the design, fabrication, and assembly of semiconductor devices including integrated circuits (ICs), memory chips, sensors, and discrete components. The process transforms raw semiconductor materials, primarily silicon, into sophisticated electronic components through a combination of physical and chemical processing steps, such as wafer fabrication, photolithography, doping, etching, thin-film deposition, and packaging.
The retail landscape is experiencing a profound transformation as self-checkout systems emerge as critical infrastructure components reshaping consumer experiences and operational efficiency globally. These automated solutions enable customers to independently scan, bag, and pay for purchases without cashier assistance, representing a fundamental shift in modern commerce.
The webcams market is experiencing unprecedented transformation as digital communication becomes the cornerstone of modern business, education, and healthcare. Global webcam industry dynamics are being reshaped by technological innovation and evolving workplace models.
As smartphones become a way of life for most Filipinos, the market has changed dramatically and expectations from consumers are higher than ever before. With the demand for smartphones growing, there is a significant change in consumer shopping habits with more emphasis on using online platforms for shopping. This change is closely interlinked with the fast growth of the Philippines e-commerce market, both bringing opportunities and challenges to the stakeholders of the smartphone industry.
As technology continues to advance, lighting has transformed from a basic necessity into a strategic enabler of innovation, efficiency, and sustainability. The evolution from incandescent bulbs to LEDs, smart systems, and intelligent lighting networks represents not just technological change but a redefinition of how energy, design, and functionality intersect in the built environment.
An LED light is an illuminating device that utilizes Light Emitting Diodes as its source of light, generating light through a semiconductor-based process called electroluminescence. When electrical current flows across the semiconductor material of the diode, electrons emit energy as photons and thus produce highly efficient and concentrated illumination.
An LED bulb is a solid-state lighting device that uses Light Emitting Diodes (LEDs) as its illumination source. Different from incandescent or fluorescent lamps, light in LED bulbs is produced by electroluminescence, a process where the passing of an electric current through a semiconductor material emits photons directly. This process is highly energy-efficient, with a far larger percentage of the electricity being converted to usable light and very little heat generated in the process.
The junction box, generally made from plastic, metal, or composite materials, houses wire connections, terminations, and protective components to allow the safe distribution and routing of electrical circuits. The junction box will provide insulation, mechanical protection, and a secure environment to avoid accidental contact with live electrical parts, moisture intrusion, or dust accumulation.
The Japan power electronics market is poised to grow substantially, driven by rising demand in automotive, energy, industrial automation, and infrastructure sectors. According to IMARC Group, the Japan power electronics market is studied from 2019 to 2024 with projections extending to 2033.
Japan's printed circuit board (PCB) industry is the world leader in technology innovation, enabling consumer electronics, automotive, and next-generation communication system development. As a key enabler of modern electronic products, PCBs provide the essential building blocks for embedding semiconductors, sensors, and microchips into miniaturized, high-performance devices. Japan, through its world-class manufacturing base and engineering expertise, remains the hub of the global PCB supply chain.
Aluminum-Air (Al-Air) battery is a new energy storage technology that has attracted interest as a future alternative to conventional lithium-ion batteries, specifically for electric vehicle (EV) use. As opposed to normal rechargeable batteries, the Al-Air battery is a metal-air electrochemical cell with aluminum as the anode, oxygen from the ambient air as the cathode reactant, and a liquid electrolyte (commonly sodium hydroxide or potassium hydroxide) as the medium through which the reaction occurs.
Aluminium wire is an essential industrial commodity commonly employed in power transmission, electrical distribution, building construction, and manufacturing processes owing to its high conductivity-to-weight ratio, resistance to corrosion, and cost advantage over copper. Produced by methods including continuous casting, rolling, and drawing, aluminum wire is available in various grades and alloys to serve the wide demands, from overhead transmission conductors and building wiring to automotive harnesses and electronic applications.
Air conditioners are electromechanical devices used to control indoor climate by extracting heat and humidity and ensuring optimum air circulation. Generally consisting of a compressor, condenser, evaporator, refrigerant fluid, filters, fans, and electronic controls, air conditioners work based on the principle of heat exchange, moving heat from indoor areas to the external environment. Contemporary units come in diverse configurations, such as split systems, window units, central air systems, and portable models, supporting respective residential, commercial, and industrial applications. Some of the major characteristics are efficiency in cooling, energy use, noise rating, and environmental footprint in relation to refrigerant type.
E-waste, or electronic waste, is electrical and electronic equipment that has been discarded, such as computers, cell phones, television sets, servers, and household appliances. It is among the world's fastest-growing streams of waste, consisting of a heterogeneous combination of metals, plastics, glass, and toxic substances. E-waste contains valuable metals like copper, aluminum, gold, silver, palladium, and rare earth elements, in addition to toxic materials like lead, mercury, cadmium, and brominated flame retardants.
Polished silicon wafers are very pure, ultra-flat semiconductor substrates that are produced from high-quality single-crystal silicon. The wafers act as the material base for making integrated circuits, power devices, and MEMS (Microelectromechanical Systems). The wafers are made of monocrystalline silicon ingots using the Czochralski or Float-Zone process, from which the wafers are cut, lapped, etched, and polished to atomic-scale flatness and defect-free surfaces.
AI is revolutionizing Japan’s semiconductor industry by boosting innovation and efficiency across the entire value chain. Advanced artificial intelligence (AI)-powered Electronic Design Automation (EDA) tools significantly shorten chip design cycles, improving performance and energy efficiency.
Recent projections indicate that Australia semiconductor market, including services, is growing at a steady compound annual growth rate as the nation deepens its tech infrastructure. The importance of semiconductors spans electronics, defense systems, telecommunications, and emerging AI applications, which position the local ecosystem as strategically vital for growth.
Fiber optic cables are high-tech communications cables that carry information like bursts of light along extremely thin glass or plastic strands, providing high-speed, high-bandwidth connectivity with little loss of signal. Fiber optic cables make up the foundation of contemporary telecommunications, carrying internet, cloud computing, 5G networks, and smart infrastructure.
CAT (Category) cables are twisted-pair Ethernet cables utilized for copper-based wired network communications, varying from CAT5e to CAT8 standards. The cables carry data through copper conductors, but with different speeds (up to 40 Gbps for CAT8) and bandwidths, supporting networks such as LANs, data centers, and smart buildings.
India's semiconductor industry is undergoing a revolutionary phase driven by rising demand from industries like consumer electronics, automotive technologies, industrial automation, and telecom infrastructure.
USB data cables are critical elements of contemporary digital connectivity, enabling high-speed and consistent data transfer and power supply for a broad scope of electronic products. They provide the foundation for charging and synchronizing smartphones, tablets, laptops, and other peripherals, with significant applications in consumer electronics, industrial automation, and new technologies. With technologies like USB-C, the cables today carry faster data speeds, more power output, and universal compatibility, making them essential in a world that is connected.
Thin-film-transistor (TFT) liquid-crystal display (LCD) is a type of display technology used in many electronic devices, such as smartphones, tablets, laptops, and televisions (TVs). A backlight, colour filters, a thin-film transistor array, and a liquid crystal layer are among the layers that make up this flat-panel display. TFT LCDs are made to produce sharp images with superb viewing angles, strong contrast, and accurate colour reproduction. They are made up of thousands of tiny transistors that regulate how much light enters each pixel. This makes it possible for the display to generate crisp, detailed images at rapid refresh rates. TFT LCD technology's low power consumption is one of its main benefits, which makes it perfect for battery-operated gadgets.
Polycrystalline solar photovoltaic (PV) modules are a key component of solar energy systems, harnessing sunlight and converting it into electricity through the photovoltaic effect. These modules are composed of multiple interconnected solar cells, each made from polycrystalline silicon. Polycrystalline solar panels are renowned for their efficiency, affordability, and versatility, making them a popular choice for various applications such as solar installations, commercial and industrial projects, off-grid systems and solar farms.
The LED chip is the core component of an LED bulb, comprising semiconductor layers that enable the free flow of protons and electrons. Employed in all LED lighting fixtures—from bulbs to tubes—the LED chip fundamentally determines light quality, with variations in brightness, voltage, and wavelength. These chips are manufactured through a process called MOCVD (metal-organic chemical vapor deposition), which creates the semiconductor layers that facilitate electric flow. Major applications of these chips include backlighting, illumination, automotive lighting, signs, and signals.
Semiconductors are crucial components in the modern electronics industry, used in electronic equipment and devices to manage and control the flow of electricity. They are found in consumer items like smartphones, wearables, smart TVs, and advanced equipment used in industrial applications, defense, and aerospace. Semiconductors are further divided into four broad categories: optoelectronics, discrete components, integrated circuits, and sensors. Memory devices, logic devices, analog ICs, MPUs, discrete power devices, MCUs, and sensors are some of the major components of semiconductors.