How Is Automotive Lead-acid Battery Manufacturing Transforming the Global Automotive Battery Market?
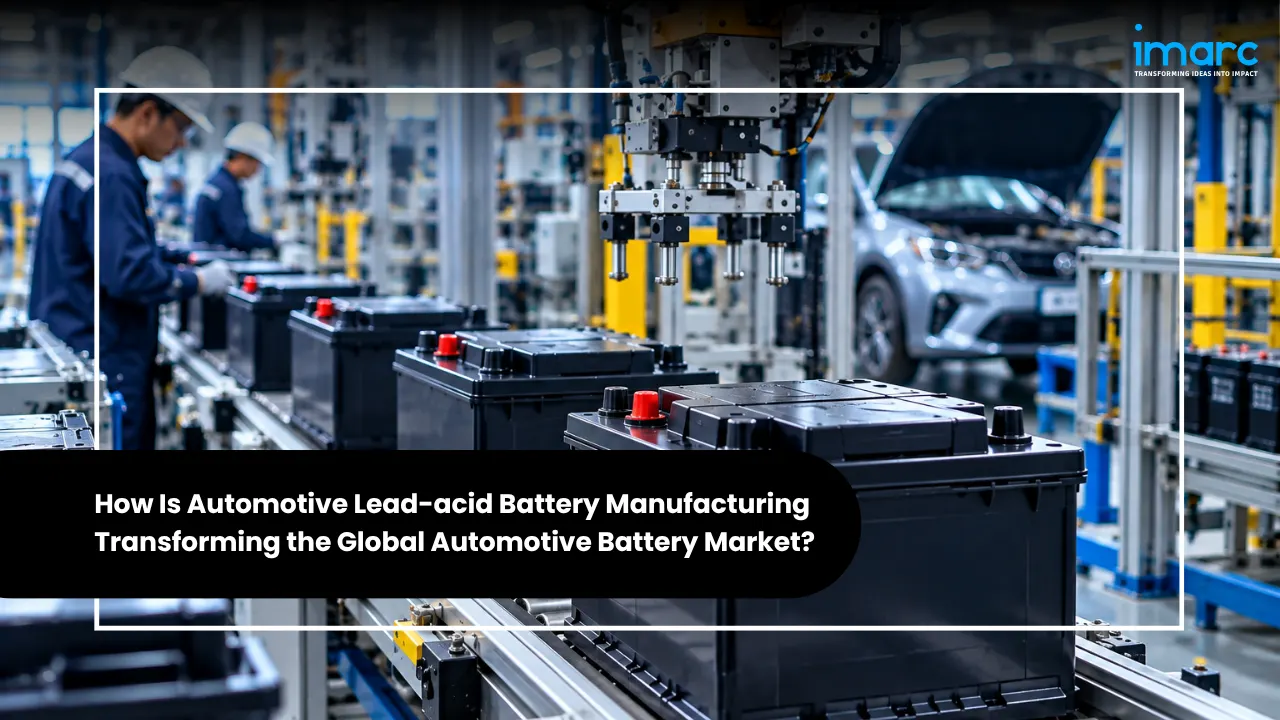
Introduction: The Current State of the Automotive Lead-acid Battery Market
The global automotive lead-acid battery market reached USD 13.89 Billion in 2025 and is projected to reach USD 16.60 Billion by 2034, growing at a CAGR of 1.94% (2026–2034). Having expanded from USD 12.61 Billion in 2020, this remains a foundational component market despite the rise of electrification, with lead-acid batteries continuing to power ignition, lighting, and auxiliary systems across conventional and hybrid vehicles.
What is driving demand? Four forces stand out. Rising global vehicle production and ownership sustains both OEM fitment and a growing vehicle parc. Growing demand for start-stop battery systems is lifting the Micro Hybrid Battery segment, which is expanding fastest at roughly 3.2% CAGR (2026–2034). Demand for reliable and cost-effective automotive power solutions keeps lead-acid competitive, given its affordability, high cranking current, and mature manufacturing base. And the expansion of electric and hybrid vehicle auxiliary applications is creating an entirely new demand pool, as HEV Cars grow fastest among vehicle types at roughly 3.0% CAGR (2026–2034), reshaping how the wider automotive battery market allocates its chemistries.
Key Takeaways
- The Automotive Lead-acid Battery Market was valued at USD 13.89 Billion in 2025 and is forecast to reach USD 16.60 Billion by 2034, at a CAGR of 1.94% (2026–2034).
- Commercial Vehicles lead by vehicle type at 36.8% share, SLI Batteries dominate by product at 72.6% share, and Asia Pacific commands 43.8% of global market share, all in 2025.
- Micro Hybrid Batteries (~3.2% CAGR, 2026–2034) and HEV Cars (~3.0% CAGR, 2026–2034) are the fastest-growing product and vehicle segments, both driven by start-stop system adoption.
- AGM and EFB technology upgrades, EV auxiliary battery demand, and recycling and circular-economy investment are the market's three clearest opportunity vectors.
- Lead-acid batteries remain effectively 100% recyclable, with lead recovery forming a critical feedback loop that supplies a significant share of raw material back into manufacturing.
Market Size, Share & Growth Outlook
IMARC Group segments the automotive lead-acid battery market size by vehicle type, product, type, customer segment, and region, showing exactly where demand is concentrated.
- By Vehicle Type: Commercial Vehicles lead at 36.8% share in 2025, as trucks, buses, and delivery vans require robust batteries for ignition, lighting, and air conditioning under demanding conditions; Passenger Cars follow at 33.5%, Two-Wheelers at 21.4%, and HEV Cars at 8.3%, the last growing fastest at roughly 3.0% CAGR (2026–2034).
- By Product: SLI Batteries dominate at 72.6% share, remaining the primary power source for starting internal combustion engines thanks to affordability and high cranking current delivery; Micro Hybrid Batteries hold 27.4% and grow fastest at roughly 3.2% CAGR (2026–2034) as automakers adopt start-stop technology to meet fuel efficiency targets.
Recent News & Mega Announcements
Recent corporate activity shows manufacturers concentrating capital on AGM capacity and portfolio positioning:
- In February 2026, East Penn Manufacturing was reported to be pursuing a USD 110 million-plus expansion of its Temple, Texas, facility, including manufacturing, distribution and auxiliary-support infrastructure.
- In December 2025, Exide Technologies strengthened its AGM battery portfolio with improved deep-cycle capabilities for renewable energy storage systems.
- In January 2025, Clarios International Inc. launched a loan deal to fund a USD 4.5 billion dividend to its private equity owners, underscoring the cash-generative nature of scaled lead-acid manufacturing.
Collectively, these moves show established manufacturers prioritizing AGM capability and balance-sheet optimization over volume expansion in a low-growth, high-cash-flow market.
Industry Trends Shaping 2026
Three technology trends are reshaping the lead-acid battery market for automotive applications.
1. Expansion of AGM and Enhanced Flooded Battery Technology
Growing adoption of absorbent glass mat and enhanced flooded battery technologies supports start-stop systems and higher electrical loads, improving vibration resistance, charging efficiency, and lifespan, and making these formats increasingly standard in new passenger and light commercial vehicle platforms globally. AGM immobilizes electrolyte within a glass fiber mat for deep-cycle durability, while EFB enhances conventional flooded designs with improved plate structure and additives, delivering better cycling at lower cost, an attractive mid-tier option for entry-level start-stop platforms in price-sensitive markets.
2. Increasing Focus on Battery Recycling and the Circular Economy
Lead-acid batteries' well-established recycling ecosystem supports sustainable raw material sourcing, with lead recovery forming a critical feedback loop that supplies a significant share of raw material requirements back into the manufacturing process. Manufacturers investing in advanced recycling facilities can reduce material costs, strengthen sustainability credentials, and secure supply chain resilience amid lead price volatility, while closed-loop models help meet tightening environmental regulations proactively. Expanding recycling capacity in emerging markets presents a further long-term cost and supply advantage.
3. Integration of Smart Battery Management and Monitoring
Advanced battery management systems now monitor lead-acid battery health, charge cycles, and performance in real time, improving reliability and lifespan and helping lead-acid batteries remain competitive against alternative chemistries in modern vehicles with sophisticated electrical architectures. Digital battery monitoring and predictive maintenance services also represent incremental value-added revenue opportunities for manufacturers and aftermarket service providers alike, extending the technology's relevance beyond the battery itself.

Geographic Hotspots
Asia Pacific leads with 43.8% share in 2025, driven by China, Japan, India, and South Korea's dominant vehicle manufacturing base, rapid urbanization, rising disposable incomes, and expanding commercial fleets generating substantial demand across both OEM-fitted and aftermarket channels.
Europe follows at 22.1% share, supported by stringent emission regulations, established automotive manufacturing, and strong aftermarket replacement networks across mature vehicle fleets. North America holds 19.7% share, reflecting a large vehicle parc, strong aftermarket service infrastructure, and steady commercial vehicle demand. Latin America (8.0%) and the Middle East and Africa (6.4%) represent developing but growing markets driven by rising vehicle ownership and expanding aftermarket infrastructure.
Competitive Landscape & Key Players' Strategies
The competitive landscape is moderately fragmented, with the top five to six players collectively holding a significant share of global OEM and aftermarket revenue. Companies increasingly compete on AGM and EFB technology upgrades, recycling capacity, and aftermarket distribution reach. The top automotive lead-acid battery manufacturers include:
- Clarios: The largest global lead-acid battery manufacturer by revenue, supplying both OEM and aftermarket channels worldwide under brands including VARTA and ACDelco; in January 2025 it launched a loan deal funding a USD 4.5 billion dividend to its private equity owners.
- East Penn Manufacturing Company: Family-owned operator of the world's largest single-site lead-acid battery manufacturing facility and the second-largest SLI battery provider in North America; pioneered AGM form, fit, and function standards for the automotive industry and expanded AGM capacity in February 2026.
- EnerSys: US-based stored energy solutions company with a broad SLI, motive power, and reserve power portfolio serving OEM and aftermarket customers globally, expanding recycling and reserve power capacity to diversify revenue.
- Exide Industries Ltd.: India-based manufacturer of SLI and micro hybrid batteries with strong OEM and aftermarket presence across Asia, investing in recycling infrastructure to improve raw material self-sufficiency.
- Exide Technologies: Separately owned US and Europe-focused manufacturer, distinct from India's Exide Industries; strengthened its AGM portfolio with improved deep-cycle capabilities in December 2025.
- GS Yuasa International Ltd.: Japan-based manufacturer of SLI and EFB automotive batteries with strong OEM partnerships across Japan and Asia, positioned in premium AGM and hybrid battery solutions for start-stop platforms.
Regional Asian manufacturers continue gaining share through cost-competitive production and expanding aftermarket distribution, while market concentration is expected to remain broadly stable as established players reinforce brand trust and distribution scale.
Policy & Regulatory Landscape, Challenges & Risks
Environmental regulation is the dominant policy force shaping manufacturing economics:
- Lead Toxicity and Emissions Regulation: Stringent rules governing lead toxicity, manufacturing emissions, and battery disposal increase compliance costs, with occupational health requirements at production facilities adding further obligations and manufacturers operating across regions navigating varying frameworks.
- Recycling and Waste Management Mandates: Growing environmental awareness is pushing regulators toward stricter recycling mandates, raising operational complexity while simultaneously rewarding manufacturers with established closed-loop recovery infrastructure.
Key challenges and roadblocks facing the market include the following.
- Volatility in lead and raw material prices directly affects production costs and margins, complicating long-term planning and pressuring smaller producers who lack the scale to hedge; manufacturers with limited vertical integration into recycling face the greatest exposure.
- Increasing competition from lithium-ion batteries is narrowing lead-acid's addressable applications in higher-value automotive electrical systems, with declining lithium-ion costs further closing the price gap and automakers evaluating alternatives for weight-sensitive systems.
- Changing automotive technologies and electrification trends require manufacturers to upgrade battery technology to meet rising electrical demands while preserving lead-acid's core cost advantage, a balance that smaller regional producers may struggle to fund.
- Intense aftermarket price competition among regional and global suppliers pressures margins, compounded by counterfeit and low-quality products in some regions that complicate brand differentiation.
Forecast 2026–2034
The IMARC Group Automotive Lead-acid Battery Market Report projects to grow from USD 13.89 Billion (2025) to USD 16.60 Billion (2034), at a CAGR of 1.94% (2026–2034), anchored at USD 15.29 Billion in 2030.
Three structural forces sustain this steady growth: rising global vehicle production and ownership, continuous aftermarket replacement cycles, and increasing adoption of advanced lead-acid technologies supporting start-stop systems and hybrid auxiliary power. By 2034, AGM and EFB formats are expected to command a substantially larger share of new vehicle fitments as start-stop technology becomes standard across mainstream segments, underpinning a resilient, moderate-growth trajectory even as broader vehicle electrification accelerates.
Opportunities for Stakeholders
Lead-acid batteries sit at the core of vehicle electrification in a way that is often overlooked: even fully electric vehicles rely on them for auxiliary functions, creating distinct opportunities across the ecosystem:
- EV and Hybrid Auxiliary Battery Suppliers: Electric vehicles increasingly use lead-acid batteries for lighting, infotainment, and safety systems, and HEV platforms deploy dual-battery architectures pairing lead-acid with primary systems, creating a complementary demand pool that insulates suppliers from direct competition with primary EV chemistries.
- AGM and EFB Manufacturing Investors: Investing in advanced AGM and EFB production capacity captures rising start-stop vehicle demand and secures OEM partnerships and premium aftermarket positioning.
- Recycling and Circular Economy Operators: Advanced recycling facilities reduce material costs and strengthen supply chain resilience amid lead price volatility, with emerging-market recycling capacity offering a further long-term advantage.
- Asia Pacific Aftermarket Networks: Expanding distribution and service networks across Asia Pacific captures the region's large and growing vehicle parc, particularly in two-wheeler and commercial vehicle replacement demand.
- Digital Monitoring Service Providers: Battery management integration and predictive maintenance services present incremental, higher-margin revenue streams layered on top of commodity battery sales.
Lead-acid's Enduring Role in an Electrifying Automotive Market
The automotive lead-acid battery market is a study in resilience: a mature, low-growth technology that electrification was widely expected to displace, yet which continues to expand, set to reach USD 16.60 Billion by 2034. Its survival rests not on competing with lithium-ion for primary propulsion, but on occupying roles, ignition, auxiliary power, start-stop cycling, where cost, reliability, and recyclability matter more than energy density.
For manufacturers, the imperative is to migrate capacity toward AGM and EFB formats where start-stop adoption is creating genuine premium demand, rather than defending share in commoditized flooded batteries. For investors, the combination of stable cash generation, a proven recycling loop, and complementary EV auxiliary demand offers a defensive thesis in an otherwise volatile automotive supply chain. For policymakers and industry bodies, sustaining the closed-loop recycling infrastructure that already makes lead-acid among the most recycled consumer products will determine how cleanly the technology ages into its next decade.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Setting up an Electric Scooter Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's rapid shift to electric mobility, supportive EV policies, and surging demand for affordable, clean urban transport. As two-wheelers dominate Indian roads and buyers move from petrol to battery-powered scooter manufacturing, an EV Scooter Manufacturing Plant is one of the most accessible and strategically timed entry points into the electric vehicle economy.
Capital is flowing into the united states used car market because structural affordability pressure, digital retail maturity, and a record-old national vehicle fleet have converged into a genuinely investable thesis.
The Europe Tire Market reached a volume of 458.89 Million Units in 2025 and is projected to reach 565.69 Million Units by 2034, growing at a CAGR of 2.35% (2026–2034).
A strategic analysis of how PLI policies and localization drive global OEM investments. India’s EV battery market hits USD 15,898.31 Million by 2034 (21.7% CAGR).
A tyre is circular in shape and made of a combination of rubber materials that fit perfectly over a circular rim on a wheel, providing traction, load-carrying capabilities, shock absorption, and directional stability. As such, tyres are engineered materials composed of a combination of natural or synthetic materials. They are composed of a combination of materials such as rubber, a combination of materials such as steel or textile, and various chemical materials, among others.
A tractor is a self-propelled, torque-requiring vehicle intended primarily for pulling power at low speeds for agricultural, industrial, and utility purposes. It functions as a mobile power source that can be used for towing, pushing, lifting, or driving a variety of agricultural implements through mechanical, hydraulic, or power take-off systems. Tractors are designed with powerful propulsion systems, sturdy frames, and versatile coupling systems for use on different terrains and under heavy loads.
The electric boat and ship market size is experiencing unparalleled growth as the marine industry embraces electrification on a large scale across different geographies. As sustainability is becoming a strategic priority, with each passing day, more and more marine operators look to electric propulsion technologies as alternatives aimed at cutting down emissions, improving operational efficiencies, and enabling greener ports.
The GCC car rental market has emerged as a critical component of the region's transportation ecosystem, driven by robust tourism activity, expanding business travel, and a substantial expatriate population. Countries across the Gulf Cooperation Council are witnessing unprecedented demand for flexible mobility solutions that cater to diverse customer segments. The GCC car rental market size was valued at USD 1.65 Billion in 2024 as governments prioritize infrastructure development and sustainable tourism initiatives.
The Indian automotive sector has formed a vital part of the country's industrial and economic development for a long period. Over the years, the industry has transformed significantly, influenced by changes in technology, global trends, and consumer preference. Among the various factors shaping its trajectory, government policies have emerged as a decisive force driving growth, innovation, and competitiveness in the India auto parts manufacturing industry.
The India motorcycle tires market continues to evolve in response to changing mobility preferences, rising urbanization, and the growing significance of two-wheelers as essential transportation assets for millions of riders. As per sources, the India motorcycle tires market size reached USD 933.66 Million in 2024. The market is projected to reach USD 2,419.36 Million by 2033, exhibiting a growth rate (CAGR) of 10.3% during 2025-2033.
The Saudi Arabia tire market is undergoing a significant transformation driven by the nation’s economic diversification, rapid urbanization, and growing vehicle ownership. As one of the largest automotive hubs in the Middle East, Saudi Arabia is witnessing increasing demand for both passenger and commercial vehicle tires across urban and industrial regions.
One of the world's most dynamic and quickly changing markets, India's automotive industry is undergoing revolutionary changes in both the new and used car markets. Despite general economic uncertainty, the used car industry has shown remarkable resilience and growth potential, making it a particularly vibrant part of this ecosystem.
One of the world's most vibrant and quickly growing automobile markets is India's passenger car sector. From technological innovation to economic development, a number of interrelated factors have contributed to the sector's remarkable transformation. For stakeholders looking to take advantage of the enormous opportunities in this dynamic market, it is imperative that they comprehend these growth drivers.
India's truck industry is at a turning point in its development, driven by extensive government policies that are changing the commercial vehicle market. The industry, which is the foundation of the country's logistics ecosystem, is gaining previously unheard-of momentum thanks to smart regulatory frameworks and forward-thinking legislative initiatives. A fundamental change in truck operations on Indian highways is being sparked by government initiatives ranging from infrastructure development to emission standards, digitalization, and financial incentives.
The electric rickshaw sector in India has experienced a significant upheaval in recent years and is now a vital part of the country's sustainable transportation network. Strategic government policies aimed at hastening the adoption of clean mobility solutions have played a major role in orchestrating this evolution. India's larger vision of sustainable urbanization is in line with the electric rickshaw industry, which combines social development objectives, economic opportunities, and environmental imperatives.
Transportation in India is undergoing a spectacular change with the advent of electric two-wheelers that are quite an enticing alternative to traditional fuel-powered ones. This change is not merely an act of technological transformation, but an indication of how millions of Indians will think about city mobility, eco-awareness, and economic effectiveness.
As one of the world's leading industrial powerhouses, Japan has long been recognized for its commitment to technological innovation and manufacturing precision. The industry for industrial automation components—encompassing sensors, controllers, actuators, drives, robotics, and human-machine interfaces—represents the backbone of modern manufacturing infrastructure.
The Australian brakes and clutches industry plays a vital role in ensuring vehicle performance, safety, and efficiency across both automotive and industrial segments. As the nation transitions toward electric mobility and smarter manufacturing systems, the demand for advanced braking and clutch mechanisms is rising significantly.
The Philippines automotive wiring harness industry stands at a transformative juncture, driven by technological innovations that are reshaping vehicle electrical architectures worldwide. As vehicles evolve into sophisticated mobile computing platforms, the wiring harness, the circulatory system transmitting electrical power and data throughout modern automobiles, has become increasingly complex and critical to vehicle performance.
Japan's hybrid vehicles market stands as a global benchmark for sustainable mobility innovation, demonstrating remarkable growth and technological leadership. The market achieved a valuation of USD 33.57 Billion in 2024. Japan's hybrid vehicle (HV) market is one of the most established globally, originating with pioneering models like the Toyota Prius. It currently represents a significant portion of the country's automotive sales.
The Japan warehouse robotics market is a highly dynamic and rapidly expanding segment of the global automation industry. The market, valued at USD 414.0 Million in 2024, is on a sharp growth trajectory. Its growth is fueled by critical domestic factors, including a severe labor shortage, the rapid expansion of e-commerce, and Japan's strategic position as a world-leading robotics manufacturer.
The UK is rapidly evolving into a dynamic hub for autonomous vehicle research, testing, and early-stage deployments. A strong ecosystem comprising academic institutions, technology start-ups, automakers, and mobility service providers fosters continuous innovation. Supported by a skilled workforce specializing in software, sensing, robotics, and transportation systems, the nation has become a fertile ground for experimentation.
Japan’s transportation landscape is on the brink of a major shift, with robo taxis, autonomous, driverless vehicles designed for passenger and goods transport, emerging as a practical mobility solution. The Japan robo taxi market reached USD 83.2 Million in 2024 . This remarkable expansion reflects Japan’s broader move toward smart mobility, sustainability, and automation.
The Japan electric truck market is experiencing transformative growth as the nation accelerates toward sustainable transportation and carbon neutrality. As a leading automotive manufacturing hub, Japan is witnessing unprecedented momentum in commercial vehicle electrification, driven by stringent environmental regulations, technological innovation, and strategic government support. The electric truck industry represents a critical component of Japan's commitment to achieving 100% electrified vehicle sales by 2035 and carbon neutrality by 2050.
An EV charging station represents the necessary main infrastructure that allows electrical energy to be transferred from the power grid into electric vehicles to enable their use for transportation. Unlike conventional fueling stations that offer liquid fuels, EV charging stations provide electric power through the use of standardized connectors and smart control systems. The core components include a power conversion unit, which transforms alternating current from the grid into direct current for the vehicle battery; a charging controller controlling communication between the charger and the EV; and a connector or plug matched to the vehicle's charging interface.
An electric scooter is a two-wheeled vehicle powered by an electric motor and rechargeable battery, aimed at offering the means for efficient, eco-friendly, and cost-effective urban mobility. Apart from the traditional scooters that are powered by internal combustion engines, the electric scooters make use of lithium-ion or lead-acid batteries that feed an electric supply to a BLDC motor, which drives the wheels either directly or via a belt or chain mechanism.
Electric bikes, commonly referred to as e-bikes, are one of the most transformational innovations in modern personal mobility, combining conventional bicycle mechanics with advanced electric propulsion technology. At the heart of e-bikes are an electric motor, a rechargeable battery, and a control system that add assistance to the rider while pedaling, making cycling easier, faster, and more accessible across varied terrains. Based on their design, they can be further categorized into pedal-assist, throttle-controlled, or hybrid models, each providing different levels of rider control and engagement of the motor.
The micro-mobility industry has emerged as a transformative force in urban transportation, revolutionizing how people navigate cities worldwide. According to IMARC, the global micro-mobility market size was valued at USD 63.10 Billion in 2024. Looking forward, IMARC Group estimates the market to reach USD 204.83 Billion by 2033, exhibiting a CAGR of 12.86% from 2025-2033.
India's electric vehicle (EV) revolution is accelerating at a breakneck speed, powered by a strategic combination of government incentives, infrastructure investments, and manufacturing policies that are transforming the automotive landscape. The IMARC Group forecasts that the Indian electric car market reached USD 963 Million in 2024.
The diesel engine industry is standing at a transformative crossroads. As global markets are pushing for sustainability, stricter emissions compliance, and cutting-edge innovations, diesel powertrains are facing both immense pressure and promising potential.
The global tire market is a multi-billion-dollar industry, driven by the growing demand for vehicles across emerging economies and the replacement tire segment in developed countries. The global tire market is expected to grow at a compound annual growth rate (CAGR) of 4.70% between 2025 and 2033. The industry is heavily influenced by factors such as technological advancements, raw material prices, environmental regulations, and consumer preferences.
Australia's electric vehicle (EV) sector is experiencing swift expansion, fueled by increasing interest in eco-friendly transportation alternatives. In 2024, sales of battery electric and plug-in hybrid vehicles hit an all-time high, totaling around 114,000 units.
The electric bus industry is the part of the transportation sector that deals with the production and installation of buses that run completely or partially on electricity, employing battery packs or fuel cells in place of conventional diesel or gasoline engines. The buses deliver lower greenhouse gas emissions, lesser noise levels, and enhanced energy efficiency, and thus they are a prime solution for environmentally friendly public transport.
India's electric vehicle market is undergoing a profound transformation, impelled by green priorities, economic imperatives, and changing consumer trends. With rising concerns about air pollution and fossil fuel dependence, electric mobility has become a strategic option for India's transport industry. Policy clarity, technology development, and an emerging ecosystem of makers and suppliers are driving this market shift.
The global electric vehicle market size was valued at USD 755 Billion in 2024. The global EV market is rapidly expanding, driven by technological advancements, government incentives, stricter emission regulations, rising fuel costs, extended battery range, growing environmental consciousness, and significant investments in charging and production infrastructure.
Electric Vehicles, or EVs, are vehicles operated partially or wholly by electrical power, generally with rechargeable battery packs as their fuel. In contrast to conventional internal combustion engine cars, EVs emit no tailpipe emissions, making them a cleaner, environmentally friendly transportation choice. EVs comprise Battery Electric Vehicles (BEVs), Plug-in Hybrid Electric Vehicles (PHEVs), and Hybrid Electric Vehicles (HEVs), and are gaining ground in passenger, commercial, and two-wheeler segments owing to developments in battery technology, charging infrastructure, and policy support.
Aluminum alloy wheels are high-performance, lightweight, and durable components widely used in the automotive industry. Their superior strength-to-weight ratio enhances vehicle efficiency, fuel economy, and handling, making them a preferred choice for both passenger and commercial vehicles. Beyond their functional benefits, aluminum alloy wheels contribute to vehicle aesthetics, offering sleek designs and customization options that appeal to consumers. Their corrosion resistance and thermal conductivity further enhance braking performance and longevity. With increasing demand for fuel-efficient and stylish vehicles, aluminum alloy wheels play a crucial role in the global automotive sector, catering to OEMs, aftermarket suppliers, and performance vehicle manufacturers.
A tyre is a crucial component of a vehicle, serving as the outer covering of a wheel. Its main purposes are to support the vehicle's weight, provide traction for movement, and act as a flexible cushion that absorbs shocks from the road. Usually composed of rubber, tires are strengthened with steel and cloth. Tires for cars, trucks, motorbikes, bicycles, and other vehicles have different designs and compositions depending on the vehicle type and its intended usage. To improve stability and grip, they have a tread pattern on the outside.
Electric kick scooters are small, battery-operated personal transportation vehicles intended for short-distance and urban movement. They offer an economical and environmentally responsible substitute for conventional modes of mobility thanks to their electric engine, rechargeable battery, and lightweight frame. The need for sustainable transportation options, traffic congestion, and growing urbanisation have all contributed to their rise in popularity. Electric kick scooters are now the go-to option for last-mile connectivity and personal commuting because to developments in battery technology, connectivity features, and government programs encouraging micro-mobility.
An automotive wiring harness is an organized assembly of electrical wires, connectors, and terminals that transmit power and signals across a vehicle’s electrical system. It guarantees effective communication between several parts, including the engine control unit, lighting, and sensors. Wiring harnesses are intended to increase vehicle performance and safety by lowering the possibility of short circuits. By maximising electrical connectivity and lowering wire complexity, they are utilised in both conventional and electric automobiles and are essential to contemporary automotive technology.
In an automotive braking system, brake pads are the most important parts since they are engineered to contact the brake rotor to produce friction, thus stopping or slowing down a vehicle in virtually any driving condition safely and efficiently. The key way of classifying these pads is according to their material types: low metallic, ceramic, organic, and semi-metallic.
Tires are essential components of vehicles designed to provide traction, support, and absorb road shocks. Primarily made of rubber, tires consist of treads, belts, and sidewalls that work together to offer grip, stability, and durability. Modern tires come in various types – such as all-season, winter, and performance tires – each engineered for specific driving conditions. The two major tire categories are radial and bias tires, and they are available in different sizes to suit various vehicle types, including passenger cars, light commercial vehicles, medium and heavy commercial vehicles, two-wheelers, and off-road vehicles.
Electric Vehicles (EVs) are powered by electric motors instead of traditional internal combustion engines (ICEs). Electric motors propel EVs by utilizing electricity stored in rechargeable batteries or other energy storage systems. They produce lower or zero tailpipe emissions, reduce air pollution and greenhouse gas (GHG) emissions, and help in mitigating climate change. Electric vehicles consist of various components, such as battery cells and packs, reducers, fuel stacks, power control units, power conditioners, air compressors, humidifiers, motors, on-board chargers, battery management systems, and others. EVs are classified into four types based on propulsion, outlined below.
Saudi Arabia is the second-largest producer and exporter of crude oil and holds the second-largest proven oil reserves in the world, with around 267 billion barrels. The country's oil sector is a significant part of its economy, accounting for 75% of government revenue and approximately 90% of exports. However, due to the volatility of oil prices and the potential for economic instability, Saudi Arabia is increasingly focusing on non-oil activities to reduce its dependency on the oil sector. Non-oil commodities tend to have more stable prices, providing protection against these fluctuations and strengthening the country's social, economic, and financial sectors.