Who Leads the Orthopedic Prosthetics Industry? Competitive Landscape and Market Share Breakdown
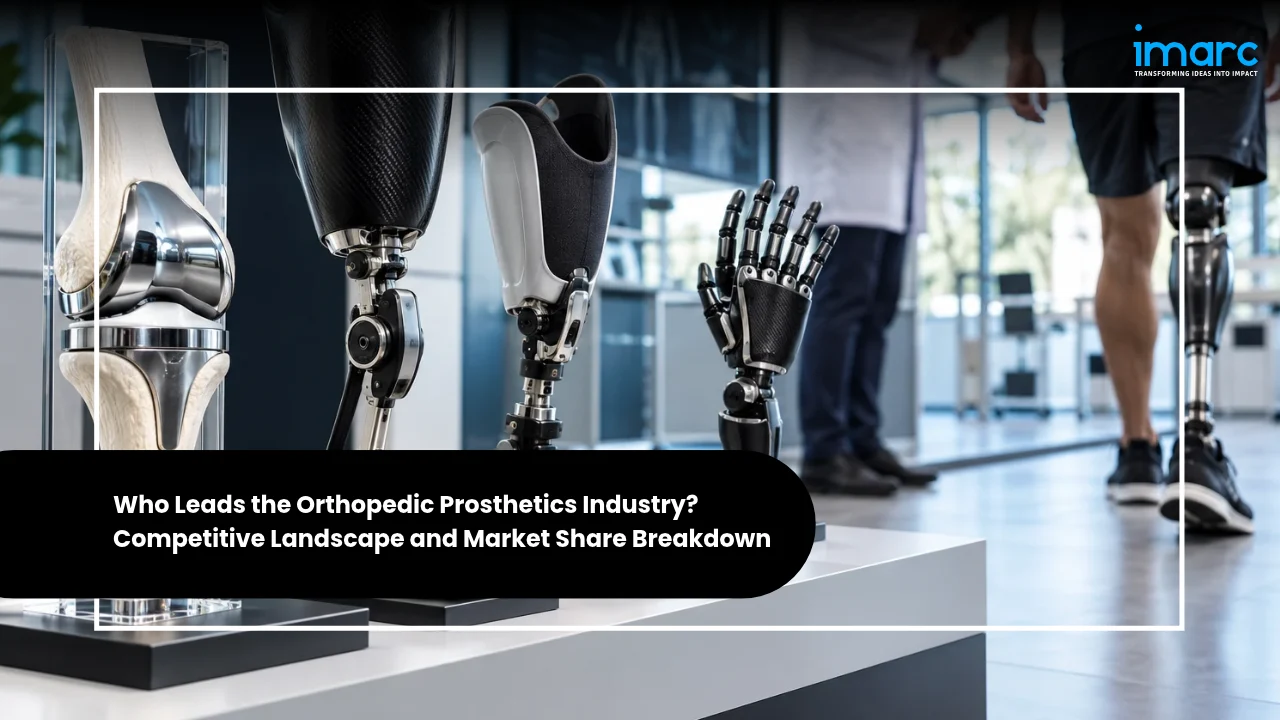
Introduction: Orthopedic Prosthetics Market Outlook
The global orthopedic prosthetics market is moving away from a replacement-device business model and toward a capability-driven care model, in which fit, function and follow-up data determine whether a device delivers value. According to IMARC Group, the market was valued at USD 2.5 Billion in 2025 and is projected to reach USD 3.5 Billion by 2034, expanding at a CAGR of 3.61% between 2026 and 2034. A mid-single-digit growth rate may look modest, but it is applied to a large installed patient base, and every additional percentage point of orthopedic prosthetics market size carries years of fitting, servicing and rehabilitation spending rather than a single transaction.
The demand base is structural rather than cyclical. Ageing populations, a rising incidence of diabetes and vascular disease, road traffic trauma and conflict-related injuries all feed the same clinical pipeline: limb loss that requires prosthetic restoration and long-term rehabilitation. Because these causes are chronic and expanding in middle-income economies, the orthopedic prosthetics market growth outlook is less exposed to consumer spending cycles than most medical device categories, and far more exposed to health system capacity, reimbursement design and the availability of trained prosthetists.
The defining theme of the current cycle is customisation at scale. In July 2024, the Orthopaedic Research Lab at Radboudumc, working with ATRO Medical, began developing a 3D-printed PCU meniscus prosthesis that uses AI to scan the healthy meniscus in one leg and generate a matching implant design for the affected leg. In March 2024, NIPPON EXPRESS HOLDINGS, INC. invested in Instalimb, Inc. through the NX Global Innovation Fund to support 3D-printed prosthetics operations in the Philippines and India. These projects show where the orthopedic prosthetics market trends are heading: from standardised component kits toward patient-specific geometry produced close to the point of care.
This blog sets out the orthopedic prosthetics market size, segment shares and forecast, then examines the technology shifts, regional hotspots, competitive strategies and policy frameworks that will shape the sector through 2034.
Key Takeaways
- The global orthopedic prosthetics market was valued at USD 2.5 Billion in 2025 and is forecast to reach USD 3.5 Billion by 2034, equivalent to a CAGR of 3.61% across 2026-2034.
- Upper extremity prosthetics is the leading product category with a 38.6% share of 2025 revenue, ahead of lower extremity prosthetics, liners, sockets and modular components.
- North America dominates the orthopedic prosthetics market with a 39.3% share in 2025, and the United States alone generates 88.20% of that regional revenue.
- In May 2024, Ottobock SE & Co. KGaA introduced the Evanto foot, a mechanical prosthetic ankle-foot system built around dynamic, flexible and stable performance.
- The dominant trend is customisation at scale, with AI-assisted design and 3D printing moving from research projects such as the Radboudumc meniscus prosthesis to commercial operations backed by investors including NIPPON EXPRESS HOLDINGS.
Market Size, Share & Growth Outlook
According to IMARC Group, the global orthopedic prosthetics market size reached USD 2.5 Billion in 2025 and is expected to reach USD 3.5 Billion by 2034, reflecting a CAGR of 3.61% during 2026-2034. The leading segments are:
- Product: Upper extremity prosthetics leads with a 38.6% share in 2025, ahead of lower extremity prosthetics, liners, sockets and modular components. Advances in myoelectric control systems and lighter materials have widened clinical use, and the segment carries both functional and psychological value because it restores hand and arm function in daily activity.
- Technology: Electric powered devices account for 37.2% of 2025 revenue, followed by conventional and hybrid orthopedic prosthetics. Myoelectric sensors and microprocessors that interpret muscle signals explain why the highest-value technology tier keeps gaining share against purely mechanical alternatives.
- End User: Hospitals hold 33.7% of demand, ahead of prosthetics clinics, rehabilitation centres and other settings, because initial fitting, post-operative care and physical therapy are concentrated in hospital departments that also manage reimbursement and device evaluation.
- Region: North America leads with 39.3% of global revenue in 2025, and the United States accounts for 88.20% of that regional total, which makes US reimbursement policy the single most important demand variable in the orthopedic prosthetics market analysis.
Because the three leading categories (upper extremity devices, electric power and hospitals) all sit in the higher-value tier of the market, revenue concentration exceeds unit concentration, and pricing pressure in any one of them moves the global total more than volume shifts elsewhere.
Recent News & Mega Announcements
Product, investment and clinical announcements between 2023 and 2024 show where companies expect differentiation to come from: mechanical performance, sensing integration, workforce capacity and cheaper production routes.
- Ottobock launches the Evanto foot (May 2024): Ottobock SE & Co. KGaA unveiled the Evanto foot, a mechanical prosthetic that targets dynamic, flexible and stable performance. The launch matters because mechanical devices remain the volume backbone of the market in cost-sensitive regions, so performance gains at that tier widen the addressable patient pool.
- NIPPON EXPRESS backs 3D-printed prosthetics (March 2024): NIPPON EXPRESS HOLDINGS, INC. invested in Instalimb, Inc. through the NX Global Innovation Fund, following a February 2024 commitment, to sustain the company's expansion in the Philippines and India. The capital signals that logistics and industrial groups now see distributed, print-on-site prosthetic production as a viable commercial model in emerging markets.
- OrthoPediatrics acquires Boston Orthotics & Prosthetics (January 2024): OrthoPediatrics Corp. acquired a paediatric orthotic management company with more than 50 years of operating history, expanding its Specialty Bracing Division into non-surgical treatment for scoliosis and neuromuscular disorders. Paediatric orthotic and prosthetic care is a relatively under-served niche, and consolidation there builds referral control ahead of demand growth.
- AI-designed meniscus prosthesis begins development (July 2024): The Orthopaedic Research Lab at Radboudumc, with ATRO Medical, started work on a 3D-printed PCU meniscus prosthesis that scans the healthy meniscus in one leg to design an implant for the affected leg. The project is an early template for scan-to-implant workflows that could later be transferred to external prosthetic components.
- Advanced prosthetic leg developed in the UK (October 2024): The University of the West of England (UWE) Bristol developed a technologically advanced prosthetic leg for people with above-knee amputations, reinforcing Europe's role in publicly funded prosthetic research.
- Workforce pipeline expands in the United States (June 2024): East Tennessee State University launched an orthotics and prosthetics programme to address national shortages of certified prosthetists and orthotists. Clinical labour supply, not device availability, is often the binding constraint on market growth.
- Sensing moves into liners and electrodes (May and June 2023): WillowWood Global LLC launched the Alpha Control Liner System with Coapt, embedding electronics in the prosthetic liner to stabilise electrode contact, while Fillauer LLC released the Myo/One Electrode system, a compact waterproof design supporting two EMG channels without extra sealing rings or cables.
Industry Trends Shaping 2026
Three developments explain most of the change in orthopedic prosthetics market trends expected through 2026 and beyond.
1. AI-Assisted Design and 3D-Printed Customisation
The economics of prosthetic fitting are being reshaped by digital capture and additive manufacturing. Scanning a residual limb, designing a socket in software and printing it on site compresses a process that traditionally required multiple plaster casts, manual rectification and repeated clinic visits. The Radboudumc and ATRO Medical meniscus project illustrates the logic: AI uses the healthy side of the body as a reference to generate a patient-specific design, reducing the artisan dependency that limits throughput in many clinics.
The commercial signal is equally important. The Instalimb investment by NIPPON EXPRESS HOLDINGS shows that distributed printing is being treated as an operating business rather than a research curiosity, particularly where conventional supply chains are thin and where imported components carry high landed costs. For manufacturers, the strategic implication is that value migrates from moulded hardware toward design libraries, scanning workflows and print-ready material systems.
2. Sensor-Driven and Microprocessor-Controlled Devices
Electronic control has become the premium tier of the orthopedic prosthetics market. Microprocessor knees, myoelectric hands and powered ankles use sensors and algorithms to read gait, adjust resistance and adapt cadence in real time, which improves stability on uneven ground and reduces compensatory strain on the intact limb. Össur hf. set an early benchmark with the Power Knee, a motorised system that tracks movement patterns and adjusts pace and cadence continuously.
The supporting ecosystem is maturing just as quickly. WillowWood and Fillauer, working with Coapt, have pushed sensing into the liner and electrode layer, stabilising the signal that drives control. Signal quality, battery life and weight, rather than raw processing power, are now the practical constraints on adoption, and they explain why electric powered technology holds 37.2% of 2025 revenue despite higher unit prices.
3. Diabetes-Led Amputation Burden and Post-Trauma Rehabilitation
Diabetes is the most predictable driver of prosthetic demand. Neuropathy and poor peripheral circulation lead to chronic ulcers that frequently progress to lower limb amputation, and people with diabetes face a materially higher amputation risk than the general population. Reported figures indicate that around 154,000 people with diabetes undergo amputation each year in the United States, and that the large majority of non-traumatic lower limb amputations are diabetes-related.
The same pattern is visible in the trauma pipeline. Road traffic crashes cause an estimated 1.19 million deaths and leave tens of millions injured or disabled each year. For the orthopedic prosthetics market, the consequence is a demand base that is rising in absolute terms even where per-capita spending is flat, and a shift in clinical priorities toward preventive foot care, faster post-amputation fitting and rehabilitation pathways that shorten time to first prosthesis.

Geographic Hotspots
North America remains the anchor region of the orthopedic prosthetics market, holding 39.3% of global revenue in 2025. Within that total, the United States accounts for 88.20% of regional demand, supported by a dense network of specialised prosthetic clinics, established reimbursement rules and rapid uptake of microprocessor-controlled and electric powered devices. The regional advantage is less about device availability than about funding pathways: insurance coverage and government healthcare programmes determine whether a patient receives a mechanical device or a powered one, and that single decision sets the revenue per case.
Europe is a research-led market with a strong public health component. Road traffic injuries in Germany, where roughly 21,600 people were injured in February 2023 alone according to the federal statistics office, sustain demand for orthotic and prosthetic care, while academic programmes continue to push device capability. The University of the West of England's advanced prosthetic leg for above-knee amputees, developed in October 2024, is a case in which public research funding feeds directly into the regional device pipeline.
Asia Pacific carries the strongest structural upside. Diabetes-related amputations are rising, road trauma remains elevated and governments are intervening in pricing. Australia allocated AUD 22 Million (USD 13.8 Million) in the 2021-2022 Federal Budget to reform the Prostheses List, aligning benefits with public device prices while preserving patient access and clinician choice. In India, the Ministry of Road Transport and Highways recorded 461,312 road accidents in 2022, a trauma base that generates long-term rehabilitation demand, and the country is also a testing ground for lower-cost 3D-printed devices.
Latin America combines a large diabetes cohort with rapid demographic ageing. More than 32 million adults in the region had diabetes in 2023, and people aged over 60 represented 13.4% of the population in 2022, around 88.6 million people, a share projected to reach 16.5% by 2030. Because diabetic foot complications drive most non-traumatic amputations, this combination moves prosthetic demand from a niche clinical need to a mainstream chronic care requirement.
The Middle East and Africa show the highest diabetes prevalence of any region at 16.2%, alongside a projected 86% increase in the diabetic population, reaching 136 million by 2045. Regional spending on diabetes care of USD 32.6 Billion represents only 3.4% of global expenditure, which explains why prosthetic access remains uneven despite clear clinical need. Saudi Arabia's Vision 2030 healthcare transformation is the most visible policy response, expanding infrastructure, workforce capability and technology adoption across the kingdom.
Competitive Landscape & Key Players' Strategies
The orthopedic prosthetics market is highly competitive and fragmented across device tiers. Leading companies concentrate research and development spending on lightweight materials, structural strength and patient-specific geometry, because comfort and mobility outcomes now drive clinician preference as much as price. Competition also runs along affordability and service access, since a device that cannot be fitted, repaired or reimbursed has little commercial value in most markets. Regulatory compliance and documented clinical outcomes have become purchasing criteria rather than background requirements.
- Ottobock SE & Co. KGaA: Combines powered and mechanical prosthetics with a broad clinical education footprint, and used the May 2024 Evanto foot launch to defend the mechanical tier where volume and affordability matter.
- Össur hf.: Positions itself in bionic and microprocessor-controlled knees and feet, using sensor-driven gait adaptation to justify premium pricing in reimbursed markets.
- Blatchford Limited: Focuses on lower limb prosthetics with an emphasis on hydraulic and microprocessor-controlled components for active users.
- Fillauer LLC: Builds component and interface depth, including the Myo/One Electrode system developed with Coapt to simplify myoelectric control hardware.
- WillowWood Global LLC: Pushes sensing into the liner layer, with the Alpha Control Liner System designed to deliver consistent electrode contact for myoelectric users.
- Hanger Inc.: Operates as a clinical services network, giving it direct patient flow and fitting data that device-only manufacturers cannot easily replicate.
- Steeper Inc.: Addresses the cosmetic and confidence dimension of limb loss, having launched the LIMB-art prosthetic leg cover range in January 2023 with sub-250 gram nylon covers.
- Johnson & Johnson: Brings orthopaedic reconstruction and trauma scale into adjacent amputation care pathways.
- Smith & Nephew Plc: Combines orthopaedic reconstruction with advanced wound management, a relevant adjacency given that diabetic foot ulcers precede many amputations.
- Stryker Corporation: Leverages trauma and joint reconstruction portfolios to compete for hospital-level procurement and surgeon relationships.
- Zimmer Biomet: Anchors its position in orthopaedic reconstruction, with hospital access that supports bundled prosthetic and implant procurement.
- Protunix: Competes in custom and specialised prosthetic manufacturing, where patient-specific design capability matters more than catalogue breadth.
The strategic pattern is convergence: device makers are buying or partnering into sensing, software and clinical services, while service networks invest in manufacturing partnerships to control cost of goods. Consolidation, such as the OrthoPediatrics acquisition of Boston Orthotics & Prosthetics in January 2024, reflects a search for referral control and portfolio breadth rather than pure manufacturing scale.
Policy & Regulatory Landscape, Challenges & Risks
Government policy has become a primary market force, shaping both device prices and patient access. Key frameworks include:
- Australia's Prostheses List reforms (2021-2022 Federal Budget): AUD 22 Million (USD 13.8 Million) was committed to align benefits with public prosthetic device prices while preserving patient access and clinician choice. The reform increases price transparency and puts pressure on premium device margins, but it also secures a funded pathway for advanced prosthetics that would otherwise be self-funded.
- Saudi Vision 2030 Health Sector Transformation Program: The programme upgrades infrastructure, workforce capability and technology adoption across the healthcare system, which matters because the Middle East and Africa region carries a 16.2% diabetes prevalence and a projected 86% rise in diabetic patients to 136 million by 2045.
- United States insurance and reimbursement coverage: Medicare and commercial coverage reduce the out-of-pocket burden that otherwise pushes patients toward mechanical devices, and the resulting access supports the country's 88.20% share of North American revenue. Any tightening of coverage criteria for microprocessor-controlled devices would be felt across the global total.
- Road safety and trauma reporting frameworks: National reporting systems, such as India's Ministry of Road Transport and Highways count of 461,312 accidents in 2022, and global road safety advocacy by the World Health Organization, indirectly expand the trauma rehabilitation caseload that prosthetic providers serve.
Weak reimbursement coordination between these frameworks remains the gap. A device funded in one jurisdiction is frequently excluded in another, so multinational manufacturers must maintain separate pricing and evidence strategies for each market.
On the constraining side, several structural risks persist:
- Reimbursement variability and out-of-pocket burden: Where coverage is partial or slow to approve powered devices, patients default to lower-cost mechanical options, capping revenue per case and slowing the shift toward electric powered technology.
- Shortage of certified prosthetists and clinical capacity: Fitting capacity, not device supply, limits throughput in many regions, which is why new academic programmes such as the East Tennessee State University initiative in June 2024 matter commercially as well as clinically.
- Fragmented access in lower-income markets: High diabetes prevalence in the Middle East and Africa coexists with regional diabetes spending of USD 32.6 Billion, only 3.4% of the global total, so clinical need outruns funded demand.
- Regulatory and software validation complexity: Microprocessor-controlled and app-connected prosthetics require ongoing software verification, cybersecurity oversight and post-market surveillance, which lengthens approval cycles and raises lifecycle cost for smaller manufacturers.
Forecast 2026-2034
The forecast period implies roughly USD 1.0 Billion of additional annual revenue between 2025 and 2034, growing from USD 2.5 Billion to USD 3.5 Billion, at a CAGR of 3.61%. That figure should be read as a base case built on current reimbursement rules, current clinical capacity and steady epidemiological pressure rather than on a technology step change. Compounding at this rate requires consistent volume growth in emerging markets and stable pricing in developed ones.
The upside case rests on three levers. Faster adoption of electric powered devices would raise revenue per case; expanded reimbursement for microprocessor technology would accelerate that shift; and 3D-printed, locally produced sockets could lower the cost floor enough to convert currently untreated patients in Asia Pacific and Africa into paying demand.
The downside case is equally identifiable. Prosthetist shortages delay fitting even when devices are funded, price reforms compress margins without expanding volumes quickly, and macroeconomic pressure on health budgets can defer elective prosthetic upgrades. Because the market is driven by chronic conditions rather than discretionary procedures, the downside is likely to appear as slower conversion of diagnosed patients into fitted patients rather than as outright contraction.
Opportunities for Stakeholders
- Device manufacturers: The clearest opportunity sits in the mid-tier gap between mechanical and fully powered prosthetics, where performance improvements such as the Evanto foot can capture price-sensitive patients without the reimbursement burden of microprocessor systems.
- Hospitals and prosthetics clinics: Hospitals already hold 33.7% of demand, so investing in digital scanning, in-house printing and structured rehabilitation pathways allows them to shorten fitting cycles and raise throughput without adding clinical staff.
- Component and materials suppliers: Sensing liners, waterproof electrodes and lightweight structural materials are becoming the differentiators inside finished devices, which gives component specialists leverage in co-development agreements.
- Payers and governments: Funding preventive diabetic foot care alongside prosthetic provision reduces long-term cost, since the amputation burden driving demand is largely preventable at the ulcer stage.
- Technology and software partners: Design libraries, scan-to-fit algorithms and remote adjustment platforms create recurring revenue in a market that has historically earned once per device.
- Investors: Distributed 3D-printed production in the Philippines and India, supported by the Instalimb investment, indicates that capital is available for models that reduce cost per fitting rather than increase device sophistication.
Mobility Outcomes as the New Benchmark
The orthopedic prosthetics market is no longer measured primarily by how many devices are shipped. It is increasingly measured by time to first fitting, functional outcome and device service life, because those variables determine both patient value and payer willingness to fund advanced technology. A CAGR of 3.61% through 2034 is achievable on epidemiology alone, but the more interesting growth will come from converting untreated patients into fitted ones and from shifting them toward electric powered and sensor-driven systems.
The constraints are human and institutional rather than technical. Prosthetist shortages, uneven reimbursement and fragmented access in high-prevalence regions will decide how quickly innovations such as AI-designed, 3D-printed prostheses reach mainstream clinical practice. Companies that pair device performance with fitting capacity, training and financing support are therefore better positioned than those competing on hardware specifications alone. On that basis, the next decade of orthopedic prosthetics market growth will reward operational reach as much as engineering ambition.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Health supplements and functional nutrition products are made by blending vitamins, minerals, proteins, probiotics, and botanical extracts and turning them into tablets, capsules, softgels, powders, gummies, and drinks under food-grade good manufacturing practices.
Generic medicines are copies of off-patent brands that contain the same active ingredient, strength, dosage form, and effect, and are approved on the basis of bioequivalence rather than new clinical trials, so they reach patients at a fraction of the original price.
The UK Health Insurance Market is at an inflection point, shaped by the mounting strain on the National Health Service and a structural shift in how employers and individuals seek to protect their health. According to IMARC Group, the market was valued at USD 67.2 Billion in 2025 to USD 70.9 Billion in 2026 and is projected to reach USD 98.6 Billion by 2034, growing at a CAGR of 4.21% (2026–2034).
Single-use syringes are sterile medical devices made from a moulded plastic barrel and plunger, a rubber gasket, and usually a fine stainless steel needle, and they are used once and discarded to prevent infection.
Absorbent cotton wool is raw cotton that has been cleaned, scoured, and bleached to remove natural waxes, oils, and impurities, then carded into soft, pure white layers that absorb many times their own weight in liquid.
Generic formulations are finished medicines, such as tablets and capsules, that contain the same active ingredient, strength, and effect as an original brand once its patent expires.
IV solutions, also called intravenous fluids or large volume parenterals, are sterile solutions given directly into a patient's vein to restore fluids and electrolytes, provide nutrition, or deliver medicines.
Paracetamol, also called acetaminophen, is one of the world's most widely used medicines for pain and fever, sold in tablets, syrups, suspensions, injections, and combination products.
Ayurveda is India's traditional system of medicine, and Ayurvedic medicines are made from herbs, minerals, and natural bases such as ghee, oils, honey, and jaggery, following classical texts and modern quality standards.
The Europe Medical Cannabis Industry has moved decisively from a patchwork of national pilot programmes into a credentialed pharmaceutical market with prescriptions, import quotas, reimbursement pathways and EU-GMP supply chains. According to IMARC Group, the market reached USD 3,060.0 Million in 2025 and is projected to reach USD 13,161.29 Million by 2034, expanding at a CAGR of 17.60% (2026–2034).
Workplace wellbeing in Asia-Pacific has shifted from a discretionary benefit to something employers are measured on, by regulators, insurers, and the talent market alike. According to IMARC Group, the Corporate Wellness Market was valued at USD 75.0 Billion in 2025 and is projected to reach USD 129.5 Billion by 2034, growing at a CAGR of 6.07% (2026–2034).
The Europe Digital Health Industry has become the continent's principal answer to a demographic and fiscal problem that hospitals alone cannot solve: ageing populations, rising chronic-disease burdens and persistent clinical staff shortages, set against public health budgets that cannot expand at the same pace as demand.
For two decades India bought most of its medical technology from abroad. The government's own assessment put import dependence at more than 85% of the market in 2020, and the country's role was that of a large consumer rather than a producer. That position is now changing, as incentive schemes, multinational localization, and domestic innovation turn the Indian medical devices sector into a manufacturing and export base.
Rapid diagnostic tests deliver results in minutes, without laboratory equipment, at a clinic, pharmacy, field camp, or at home. Lateral flow tests for malaria, dengue, typhoid, HIV, hepatitis, syphilis, pregnancy, fertility, drugs of abuse, and cardiac markers have become an essential part of India's healthcare system, especially in primary care and rural areas where laboratories are scarce.
Setting up a Generic Injectables Manufacturing Plant in India is a high-value, highly regulated venture, powered by the country's position as the pharmacy of the world, growing global demand for affordable injectables, and a wave of patent expiries opening new products to generic competition.
Setting up a Pharmaceutical Manufacturing Plant in India is a high-potential, strategically strong venture, powered by the country's position as the pharmacy of the world and one of the largest generic drug producers globally. India's deep formulation expertise, cost competitiveness, and vast domestic and export demand make a pharmaceutical manufacturing unit setup in India one of the most attractive opportunities in the healthcare sector.
The Dental 3D Printing Market is attracting renewed investor attention because the technology has moved from a promising adjunct to a default production method inside dental laboratories and clinics.
Vitamin water is a functional, non-carbonated beverage that is created by the fortification of purified water with a combination of vitamins, minerals, and sometimes electrolytes, along with natural or artificial flavors and sweeteners. It is placed in a category between bottled water and carbonated soft drinks, providing hydration with a functional twist.
Vitamin B12, or cobalamin, is a water-soluble vitamin that contains the metal cobalt and is a micronutrient required by the human body. It acts as a coenzyme in the synthesis of DNA, the production of red blood cells, and the functioning of the nervous system.
Japan's dietary supplements industry has become one of the most advanced and innovation-led industries in the world. It is at the nexus of science, culture, and consumer health awareness.
A syringe is a medical instrument that is used to inject fluids into the body or to withdraw fluids from the body. A syringe usually has a cylindrical body, a plunger that moves inside the body to generate pressure or suction, and a nozzle to which a needle can be attached.
Cosmetic surgery in Australia today has evolved into a significant element of the greater beauty and wellness economy. Changing cultural attitudes, advances in medical aesthetics, and the rise of social media over the last ten years have reconstituted the ways in which cosmetic surgery is perceived and undertaken by Australians.
The contact lenses market represents a dynamic segment of the global vision care industry, characterized by continuous innovation and expanding demographic demand.
Brazil's diagnostic imaging equipment market stands at a pivotal moment as Latin America's largest and most dynamic healthcare arena. With substantial investments in hospital modernization, regulatory reforms, and artificial intelligence adoption, the market is transforming rapidly. As providers transition from analog to AI-ready platforms, Brazil emerges as a critical destination for medical device manufacturers seeking growth through the next decade.
The Indian healthcare space has indeed been changing. Telemedicine has emerged as one of the most important drivers of this change. Driving this transformation is the increased adoption of digital tools, growing patient awareness, and the pressing need to make healthcare more accessible across diverse geographies.
The Australia medical aesthetics industry size reached USD 396.4 Million in 2025. Looking forward, the market is expected to reach USD 784.8 Million by 2034, exhibiting a growth rate (CAGR) of 7.89% during 2026-2034. Over the last ten years, the medical aesthetic industry in Australia has transformed from a niche beauty service into a mainstream part of healthcare and wellness.
A rapid diagnostic test (RDT) kit is a medical device designed to quickly detect specific biomarkers, antigens, antibodies, or nucleic acids linked to diseases—typically within minutes and without the need for sophisticated laboratory equipment. These kits often use lateral flow assays, immunochromatographic strips, or rapid molecular testing methods to deliver fast and reliable results.
The Philippines pharmaceutical industry stands as one of Southeast Asia's most dynamic and rapidly expanding healthcare markets in the ASEAN region. With a market valuation reaching USD 3.36 Billion in 2025, the sector demonstrates resilience and tremendous growth potential.
Pharmaceuticals are medical products, substances, or formulations involved in the development, manufacture, and regulation for the prevention, diagnosis, treatment, and management of diseases in humans as well as animals.
The Australia aged care industry stands at a pivotal juncture as the nation grapples with demographic shifts that are reshaping the landscape of elderly care services. With an aging population that continues to expand, Australia faces both unprecedented challenges and remarkable opportunities in delivering quality care to its senior citizens.
The Indian vaccines industry holds an unparalleled position globally, often celebrated as the pharmacy of the world due and its massive production scale and capabilities. It reached INR 113.7 Billion in 2024 according to IMARC Group and it is projected to grow at a CAGR of 8.8% from 2025-2033.
The medical imaging market has reached a transformational phase, driven both by rapid technological advancements and growing demands for precision-driven diagnostics. As health systems worldwide come under increasing pressure to improve patient outcomes while minimizing procedural risks and optimizing clinical workflows, medical imaging has become one of the most important cornerstones of modern medicine.
India’s medical devices industry is on a sustained growth trajectory driven by expanding hospital infrastructure, rising chronic disease burden, stronger local manufacturing supported by government incentives, and a rapidly growing shift toward portable and home care devices.
Pectin represents a naturally occurring polysaccharide mainly extracted from cell walls of fruits (mainly from citrus peel and apple pomace). It is a soluble dietary fiber and a hydrocolloid with gelling, thickening, and stabilizing properties. It is mostly composed of galacturonic acid units.
Paracetamol, also referred to as acetaminophen, is an analgesic and antipyretic compound that is commonly used worldwide for the treatment of mild to moderate pain and the management of fever. The mechanism of action occurs mainly in the central nervous system, where it inhibits the mechanisms that regulate pain and body temperature, but lacks anti-inflammatory properties.
The Australia wellness tourism industry has emerged as a critical segment of the country’s broader travel and hospitality sector. It reflects a growing global emphasis on health, self-care, and holistic well-being, capturing the attention of travelers seeking experiences that combine relaxation, rejuvenation, and personal growth.
The Brazil cardiovascular devices market represents a crucial segment in the country’s healthcare ecosystem, addressing one of the leading causes of morbidity and mortality: cardiovascular diseases. Conditions such as heart attacks, stroke, arrhythmias, and heart failure require ongoing medical intervention and advanced heart disease treatment solutions. With the rising prevalence of cardiovascular disorders, demand for comprehensive cardiac care equipment and innovative treatment modalities is increasing.
India's Ayurvedic products market is experiencing remarkable transformation as consumers increasingly prioritize holistic wellness and natural remedies over conventional alternatives. The convergence of traditional healing wisdom with modern consumer preferences has created a dynamic landscape where herbal medicines, chemical-free personal care products, and immunity-boosting supplements are becoming household staples.
Nicotine pouches are small, smokeless oral delivery products of nicotine, free from tobacco, designed to allow for controlled release of the active principle without burning, vaporizing, or use of traditional tobacco leaves. It consists of a small pouch that contains a matrix made basically from plant fibers, flavorings, pH adjusters, and stabilizers impregnated with nicotine, encased in a permeable material permitting the gradual absorption of the product via the oral mucosa.
The pharmaceutical industry in Japan is among the most advanced globally, recognized for combining innovation, high-quality standards, and patient-centered care. Its extensive value chain includes drug discovery, clinical trials, manufacturing, distribution, marketing, and post-market surveillance. Serving both domestic and international markets, Japanese pharmaceutical companies are respected for regulatory compliance, safety, and reliability, establishing them as trusted global collaborators in drug development.
The pharmaceutical industry in Japan is among the most advanced globally, recognized for combining innovation, high-quality standards, and patient-centered care. Its extensive value chain includes drug discovery, clinical trials, manufacturing, distribution, marketing, and post-market surveillance. Serving both domestic and international markets, Japanese pharmaceutical companies are respected for regulatory compliance, safety, and reliability, establishing them as trusted global collaborators in drug development.
The global healthcare IT industry is on a remarkable upswing, fueled by the surge in preventive care, digital health platforms, and smarter patient management systems. According to IMARC Group, the market hit USD 363.15 Billion in 2024, a clear sign of worldwide adoption. An aging population, the growing comfort with remote care, and the push toward personalized medicine are all speeding this momentum.
The global endoscopy devices market is on a sharp growth path, fueled by the shift toward minimally invasive procedures, the need for early diagnosis, and cutting-edge imaging technologies. IMARC Group reported the market hit USD 50.01 Billion in 2024, underscoring its worldwide acceptance.
The global business-to-business (B2B) payments landscape is experiencing a fundamental transformation that is reshaping how enterprises conduct financial transactions across borders and industries. The market, valued at approximately 1,189.6 Billion in 2024, is projecting remarkable growth with expectations to reach USD 2,189.0 Billion by 2033, exhibiting a CAGR of 7% from 2025-2033. This exponential expansion is signaling a paradigm shift in commercial finance, driven by technological innovation, changing business expectations, and the urgent need for more efficient payment infrastructures.
The smart medical devices market is entering a decade defined by connected care, real-time diagnostics, and patient empowerment. Valued at USD 45.9 Billion in 2024, the market is projected to reach USD 82 Billion by 2033, expanding at a compound annual growth rate (CAGR) of 6.33% between 2025 and 2033 by IMARC Group. This steady rise reflects growing confidence in data-driven healthcare systems, integration of IoT in medical environments, and the increasing role of artificial intelligence in clinical decision-making.
Active Pharmaceutical Ingredients (APIs) are the bioactive molecules of any drug used in pharmaceuticals, which cause the desired therapeutic action in the body of a human being. APIs are the central core of all drugs, chemical or biological and are responsible for the efficacy, strength, and safety of the drug. APIs are synthesized by various complex chemical synthesis, fermentation, biotechnological, or extraction processes based on the type of drug.
A bio medical incinerator is a high-temperature combustion system specialized for biomedical waste disposal by hospitals, clinics, laboratories, and research institutions. Biomedical waste usually consists of infectious waste, pathological waste, sharps, pharmaceuticals, and contaminated disposables that are very hazardous to human health and the environment if not treated.
Obesity, once viewed primarily as a lifestyle choice, is now widely recognized as a complex and chronic disease characterized by excessive body fat accumulation. Its global prevalence is escalating at an alarming rate posing a significant and growing challenge to public health systems worldwide.
Gonorrhea, a sexually transmitted infection caused by the bacterium Neisseria gonorrhoeae, is a major public health issue globally. Reports show that over one million new cases of curable STIs are contracted every day by individuals aged 15 to 49 years, with the majority being asymptomatic.
The 7 major allergic conjunctivitis markets reached a value of USD 2.1 Billion in 2024. Looking forward, IMARC Group expects the 7MM to reach USD 2.9 Billion by 2035, exhibiting a growth rate (CAGR) of 3.00% during 2025-2035.
The healthcare sector is changing rapidly because of the growing demand for better ways to manage chronic diseases. As we move toward 2025 and beyond, digital tools are playing an important role in dealing with conditions like diabetes, heart disease, cancer, and respiratory problems.
The global multivitamin gummies market consists of chewable dietary supplements that are charged with key vitamins and minerals aimed at maintaining general health and wellness. The gummies present a handy, enjoyable, and easy-to-swallow option to classic pills or tablets, hence are predominantly preferred by children and adults who do not like taking pills.
India's pharmaceutical sector is evolving rapidly, supported by the integration of artificial intelligence (AI) across the value chain. As of 2023, India ranked as the third-largest pharmaceutical producer by volume, accounting for 20% of global generic drug exports.
As Lung Cancer Awareness continues to build global momentum in 2025, Artificial Intelligence (AI) is proving to be a transformative force—not only in clinical diagnostics but also in public education and preventive health efforts. Given that lung cancer remains one of the world’s deadliest cancers, accounting for over 1.8 million deaths each year and a five-year survival rate of just 28.4%, the integration of AI marks a critical turning point.
Observed on May 19, Hepatitis Testing Day 2025 emphasizes the need to "Test. Treat. Eliminate," highlighting the gap in diagnosing hepatitis B and C, which cause over 1.3 million deaths annually. Hepatitis remains a major global health threat, on par with HIV, tuberculosis, and malaria. The growing viral hepatitis market <Viral Hepatitis Market Size | Share, Trends - 2034 > reflects rising demand for better diagnostics, treatments, and integrated care. The WHO warns that without faster testing and treatment, the goal of eliminating hepatitis by 2030 may not be achieved, with disparities in diagnostics, particularly in low- and middle-income countries, hindering progress.
Observed on May 8, World Ovarian Cancer Day 2025 carries the theme “No Woman Left Behind,” reinforcing the urgent need to close the gaps in access, diagnosis, treatment, and care across all regions and socioeconomic groups. Ovarian cancer remains one of the deadliest gynecological cancers, often detected too late due to vague symptoms and limited screening tools. The World Ovarian Cancer Coalition projects a 55% rise in annual cases and nearly 70% more deaths by 2050, with the heaviest burden falling on low- and middle-income countries. Equitable access to early diagnostics, genetic testing, and targeted therapies is critical.
In clinics around the world, a concerning pattern is becoming increasingly evident: a growing number of patients are experiencing wheezing, breathlessness, and persistent coughing. This surge reflects a broader global trend. According to the World Health Organization (WHO), more than 260 million people are currently living with asthma, making it one of the most widespread and persistent chronic respiratory conditions globally.
Observed on April 25, World Malaria Day 2025 carries the theme “Accelerating Equity in Malaria Prevention and Cure,” underscoring the urgent need to reach communities still lacking access to life-saving vaccines and diagnostics. While global malaria death rates have seen modest declines, the disease continues to claim the life of one child every minute, highlighting the critical need for swift, equity-driven action
Sulfamethoxazole is a common synthetic antibacterial that is a member of the sulfonamide class of antibiotics. This substance plays a very significant role in modern medicine due to the amazing capabilities offered by the substance for curing infections and bacterial diseases. Trimethoprim and sulfamethoxazole are frequently used together to create the well-known antibiotic co-trimoxazole, which is well-known for its potency against a variety of bacterial infections. It works by preventing the manufacture of folic acid, which is necessary for the growth of bacteria. Sulfamethoxazole is an essential part of modern antibiotic therapy since it has been used to treat lung infections, urinary tract infections, and other common bacterial illnesses.
Healthcare consumables are necessary medical supplies used for patient treatment, diagnostics, and cleanliness in clinics, hospitals, and home care settings. These consist of supplies such as surgical masks, bandages, gloves, syringes, catheters, and disinfectants. Usually, they are disposable or single use to preserve sterility and stop infections. Healthcare consumables are an essential component of the global healthcare ecosystem and are in high demand due to expanding healthcare needs, an increase in operations, infection control measures, and technological improvements.
Catheters are flexible, tubular medical devices designed to access various body cavities, organs, or blood vessels for diagnostic or therapeutic purposes. They can be broadly classified into types based on their application, including urinary catheters, cardiac catheters, and intravenous (IV) catheters. Catheters are commonly used in diverse healthcare settings for managing chronic conditions, enabling fluid drainage, delivering medications, or facilitating minimally invasive surgeries.
Bioinformatics involves applying computational techniques and tools to study and understand biological systems at the molecular level. It is a field of study that combines mathematics, biology, computer science, and statistics to research genomic data and biological networks. The goal is to interpret information from large biological data sets, such as DNA sequences, protein structures, gene expressions, and other high-throughput experimental data. This field provides various products and services, such as knowledge management tools, bioinformatics platforms, and services.
A non-animal model refers to an experimental system or method used in scientific research or testing that does not involve the use of animals. These models are developed to simulate biological processes, test hypotheses, or study diseases without the need for live animals. The aim is often to reduce the reliance on animal testing, which has ethical implications and raises concerns about animal welfare.
Cell therapy involves the transplantation and manipulation of living cells to replace and repair damaged tissue. Its primary branches include stem cell therapy and non-stem cell therapy. Stem cell therapy utilizes stem cells to repair, replace, or rejuvenate damaged or diseased cells and tissues as they possess the ability to differentiate into various specialized cell types, making them valuable for regenerative medicine. Non-stem cell-based therapies typically involve somatic cells isolated from the human body. These cells are propagated, expanded, selected, and then administered to patients for curative, preventive, or diagnostic purposes. On the other hand, gene therapy seeks to treat diseases by introducing, replacing, or inactivating genes within cells.