Gypsum Plasterboard Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
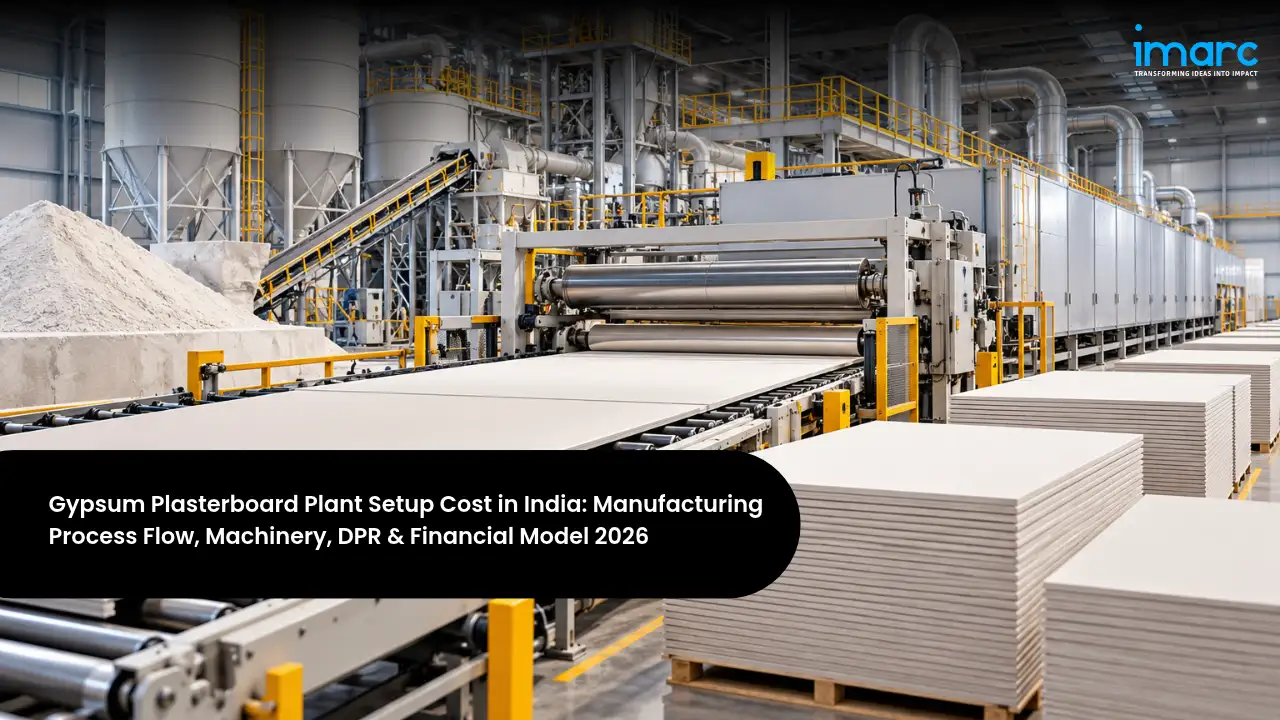
Gypsum plasterboard is a flat building panel with a core of set gypsum bonded between a face paper and a back paper. Fixed to light steel frames, it creates ceilings, partitions, and wall linings that go up far faster than brick and wet plaster, weigh much less, and resist fire because gypsum holds chemically bound water. It is now the default interior material for offices, malls, hotels, hospitals, airports, and a growing share of apartments. IMARC estimates India's gypsum board market at about USD 1.09 billion in 2025, rising to about USD 1.62 billion by 2034. Rapid urban construction, stricter fire codes, the push for faster building methods, and new sources of by-product gypsum make Gypsum Plasterboard Manufacturing Plant Setup in India a compelling opportunity for building material companies and industrial investors.
Investment is shaped by line capacity, whether the plant calcines its own gypsum or buys stucco, the gypsum source, and how many specialty board types it makes. The Gypsum Plasterboard Manufacturing Plant Cost ranges from about INR 40–80 crore for a compact line of 5 to 10 million square metres a year, to INR 150–300 crore for a full line of 20 to 30 million square metres a year with in-house calcination, and INR 400–700 crore for a high-speed, multi-product plant of 50 million square metres a year or more. Raw materials account for 50 to 60% of operating cost and fuel and power for another 20 to 25%, so gypsum, liner paper, and energy prices largely decide returns. A well-run line typically earns a gross margin of 30 to 40% and a net margin of 12 to 18%.
This guide is written for investors exploring how to start a Gypsum Plasterboard manufacturing plant in India. It uses a reference line of about 20 million square metres a year producing standard, moisture-resistant, and fire-resistant boards for interior contractors, developers, and building material dealers, and it also covers compact lines and large integrated plants. It explains products and markets, demand drivers, the production process, machinery and raw materials, site selection and infrastructure, capital and operating costs, profitability, approvals, and how a DPR and financial model bring these together into a plan lenders can back.
India Market Snapshot
| Key Facts | Details |
|---|---|
| India Gypsum Board Market (2025) | About USD 1.09 Billion |
| India Market Forecast (2034) | USD 1.62 Billion, 4.42% CAGR |
| Global Gypsum Board Market (2025) | USD 31.72 Billion |
| India Gypsum Imports (FY2022-23) | 5.76 Million Tonnes, mostly Oman |
| Typical Plant Capacity | 20 – 40 Million m² a Year |
| Indicative Total Investment | INR 40 Crore to 700 Crore |
The numbers point to a market that is growing steadily on the back of commercial interiors, housing, and public buildings. India imports much of its high-purity gypsum, mainly from Oman, but phosphogypsum from fertiliser plants and FGD gypsum from coal power stations are becoming practical alternatives. The investment range reflects three distinct entry routes: a compact line, a full-scale line with its own calcination, and a large plant with several product lines. The sections below compare them.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Product Range | Standard, moisture, fire, acoustic, tiles |
| Plant Capacity | 5 – 50+ Million m² Per Year |
| Total Project Investment | INR 40–80 Crore (compact line) to 400–700 Crore (large plant) |
| Payback Period | 4 – 6 Years |
| Net Profit Margin | 12 – 18% |
| IRR | 16 – 24% |
| Preferred States | Rajasthan, Gujarat, Tamil Nadu, Andhra Pradesh, Maharashtra, Uttar Pradesh |
| Key Requirement | Gypsum source, liner paper, dealer reach |
Treat these figures as a planning range. Actual results depend on gypsum purity and landed cost, liner paper prices, gas or fuel costs, freight to key cities, the share of value-added boards, and how strongly established brands defend their markets. A site-specific Gypsum Plasterboard Feasibility Report tests each of these assumptions against your chosen gypsum source, line size, product mix, location, and sales channels.
Table of Contents
- What is Gypsum Plasterboard Manufacturing?
- Why is Gypsum Plasterboard Manufacturing Growing in India?
- Gypsum Plasterboard Manufacturing Process Flow
- Raw Materials for Gypsum Plasterboard Manufacturing
- Location, Land & Infrastructure
- Gypsum Plasterboard Manufacturing Machinery and Equipment
- Gypsum Plasterboard Manufacturing Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for Gypsum Plasterboard Manufacturing in India
- Recent Developments in the India Gypsum Plasterboard Manufacturing Industry
- How a Gypsum Plasterboard Manufacturing Project Report and DPR Helps Investors
- Frequently Asked Questions
What is Gypsum Plasterboard Manufacturing?
Plasterboard is made from stucco, which is gypsum heated to drive off part of its water. When stucco is mixed back with water, it rehydrates and sets into a hard, interlocking crystal mass. On a board line, this slurry is foamed to reduce weight, blended with starch and additives, spread between two paper liners, and allowed to set before it is cut and dried. Boards are commonly 9.5, 12.5, or 15 mm thick and 1.2 metres wide. Water repellents produce moisture-resistant boards, glass fibre and vermiculite produce fire-rated boards, and denser cores give impact-resistant grades for hospitals and schools.
Plasterboard is rarely sold on its own. Producers usually offer complete drywall systems with steel framing, screws, joint tape, and jointing compounds, backed by installer training and technical support. A Gypsum Plasterboard Manufacturing Plant typically sells through building material dealers and distributors, drywall and interior fit-out contractors, real estate developers, government and institutional projects, and export markets in nearby countries. Specifiers and contractors look for flat boards with sharp edges, consistent weight and strength, proven fire and moisture performance, BIS certification, and reliable delivery.
- False Ceilings: Suspended and framed ceilings in homes and offices.
- Drywall Partitions: Fast, light internal walls on steel studs.
- Wall Linings: Smooth finishes over brick or block walls.
- Specialty Zones: Fire shafts, wet areas, and acoustic rooms.
Board Types and Where They Are Used
The product range decides additive systems, line configuration, and which customers a plant can serve:
| Board Type | Description | Key Property | Primary Demand |
|---|---|---|---|
| Standard Board | 12.5 mm paper-faced | Low cost | Ceilings, partitions |
| Moisture-Resistant | Water-repellent core | Damp tolerance | Wet areas |
| Fire-Rated Board | Glass fibre core | Longer fire rating | Shafts, corridors |
| Acoustic Board | Perforated face | Noise control | Offices, halls |
| Ceiling Tiles | Laminated, small size | Quick fixing | Grid ceilings |
| Impact Board | Dense core | Durability | Hospitals, schools |
A basic line can make standard boards, but moisture- and fire-rated grades need additional dosing for repellents and glass fibre, while acoustic boards and ceiling tiles need perforating, laminating, and cutting sections. Impact boards call for denser slurries and tighter control. New entrants usually begin with standard and moisture-resistant boards, which carry the largest volumes, and add fire-rated, acoustic, and tile products as their distribution and technical teams mature.
Why is Gypsum Plasterboard Manufacturing Growing in India?
Key Growth Drivers in India and Export Markets
Several structural trends are pushing more construction toward dry interior systems:
- Commercial fit-outs: Offices, retail, hotels, and data centres rely heavily on plasterboard ceilings and walls.
- Urban housing: Apartment buyers increasingly expect false ceilings and drywall finishes.
- Speed of construction: Dry systems cut construction time, labour, and site waste.
- Fire safety rules: Building codes require fire-rated partitions in many building types.
- Green buildings: By-product gypsum and recyclable boards help projects earn green ratings.
India-Specific Market Opportunity
| Segment | Market Context | Manufacturing Role |
|---|---|---|
| Commercial Interiors | Offices, retail, hotels | Ceilings, partitions |
| Residential Projects | Urban apartments | Standard, moisture boards |
| Public Buildings | Hospitals, airports | Fire, impact boards |
| Data Centres | Fire-rated spaces | Fire-rated boards |
| Modular Construction | Prefab buildings | Drywall systems |
Because boards are bulky, freight protects regional producers, so the clearest opening for a new plant is supplying standard and moisture-resistant boards to dealers and contractors within a few hundred kilometres. Fire-rated boards for commercial and institutional projects and low-carbon boards made from by-product gypsum offer further room to differentiate. Plants that pair consistent quality with dealer support and installer training will win share fastest.
Gypsum Plasterboard Manufacturing Process Flow
Knowing the process helps plan equipment, layout, and the points where cost and quality are set. Gypsum is received, crushed, dried, and ground, then calcined into stucco and cooled. The stucco is mixed with water, foam, and additives, formed between paper liners, allowed to set on a long belt, cut to length, dried in a multi-deck kiln, and finally trimmed, inspected, and bundled. Calcination and slurry control set board strength and weight, and the dryer uses the most energy.
The Gypsum Plasterboard Manufacturing Process Flow
The table follows a continuous line with its own calcination. Lines that buy stucco begin at the slurry mixing stage.
| Unit Operation | Key Activity |
|---|---|
| Gypsum Intake | Rock or by-product received |
| Crushing & Grinding | Sized and dried |
| Calcination | Gypsum turned to stucco |
| Stucco Conditioning | Cooled, stored in silos |
| Slurry Preparation | Water, foam, additives |
| Forming | Slurry between papers |
| Setting | Core hardens on belt |
| Cutting | Boards cut to length |
| Drying | Multi-deck kiln |
| Finishing & Bundling | Trimmed, checked, packed |
Profitability turns on two levers. The first is stucco quality, since clean, evenly calcined gypsum needs less water and additive and yields strong, light boards, whereas impurities and uneven calcination raise board weight and rejects. The second is line efficiency, because cost per square metre falls sharply when the line runs near rated speed with little waste, foam keeps board weight down, and dryer heat is recovered.
Raw Materials for Gypsum Plasterboard Manufacturing
The core input is gypsum, sourced as mined rock, FGD gypsum from power plants, or phosphogypsum from fertiliser plants. Other inputs include face and back liner papers, starch, foaming agents, setting accelerators and retarders, glass fibre and water repellents for specialty grades, and edge tape and packaging. Natural gypsum is mined mainly in Rajasthan, large quantities are imported from Oman, and by-product supplies are growing.
| Raw Material | Role in Product | India Sourcing | % of OpEx |
|---|---|---|---|
| Gypsum | Core material | Mines, imports | 20–28% |
| Liner Paper | Board faces | Domestic, imported | 18–22% |
| Starch & Additives | Bond, set control | Domestic suppliers | 4–6% |
| Foam & Glass Fibre | Weight, fire rating | Domestic suppliers | 2–4% |
| Edge Tape & Packing | Bundling | Domestic suppliers | 1–2% |
Gypsum and paper dominate material costs. Mined gypsum varies in purity, imported gypsum moves with ocean freight, and by-product gypsum may need washing and drying before use. Long-term offtake agreements with mines, power stations, or fertiliser plants, at least two qualified paper suppliers, and careful blending of gypsum sources keep costs and quality under control.
Location, Land & Infrastructure
Plasterboard is heavy and bulky relative to its value, so freight shapes site selection more than for most building materials. The best sites sit either next to a reliable gypsum source or within a few hundred kilometres of large construction markets, with access to natural gas or other fuel for calcining and drying, reliable power, and good roads. A long, flat plot is needed for the continuous line, and a site near a port helps plants that depend on imported gypsum or liner paper.
Choosing the Best Location for Gypsum Plasterboard Manufacturing Plant Setup
| State / Region | Why It Works | Key Advantage |
|---|---|---|
| Rajasthan | Bikaner, Nagaur gypsum | Natural gypsum |
| Gujarat | Ports, gas network | Imports, fuel |
| Tamil Nadu | Chennai industrial belt | Southern demand |
| Andhra Pradesh | Fertiliser and ports | Phosphogypsum |
| Maharashtra | Mumbai, Pune markets | Large demand |
| Uttar Pradesh | NCR and north | Demand, by-products |
Rajasthan has natural gypsum within reach of northern and western cities, and Gujarat offers ports and a gas network for imported gypsum. Tamil Nadu and Andhra Pradesh serve fast-growing southern markets, with Andhra Pradesh also offering phosphogypsum, while Maharashtra and Uttar Pradesh place plants close to the large Mumbai, Pune, and NCR markets. The final choice should balance gypsum supply, freight to customers, energy cost, incentives, and land price.
Quality, Safety and Environmental Systems
Boards are tested against the Indian standard for gypsum plasterboards, and specifiers check flexural strength, nail pull, weight, edge hardness, water absorption, fire performance, and dimensions. A credible plant runs a laboratory for stucco and board testing, online thickness and width control, and lot traceability, and has access to fire testing for rated systems. Safety programmes cover dust, hot gases from calciners and dryers, moving machinery, and fire risk in paper stores. Environmental controls include bag filters, kiln emission monitoring, and recycling of broken boards into the process. An experienced Gypsum Plasterboard Manufacturing Consultant in India can help set the gypsum strategy, line design, product mix, and certification plan so the plant meets regulatory and customer expectations from the first day.
Infrastructure Requirements (20 Million m² Line)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Total Land Area | 15 – 25 acres | Long, flat plot |
| Production Hall | Forming to packing | Continuous line |
| Gypsum Sheds | Covered storage | Weeks of stock |
| Calcination Block | Calciner, silos | Dust control |
| Utilities | Gas, power, water | 3 – 5 MW load |
| Finished Goods Store | Dry, flat floors | Pallet storage |
| Laboratory | Stucco, board tests | BIS testing |
The production hall and covered storage for gypsum, paper, and boards matter most, because boards must stay dry and flat until delivery. A dependable fuel supply for calcining and drying, effective dust control, a well-equipped laboratory, and road access for heavy trucks complete the essentials.
Gypsum Plasterboard Manufacturing Machinery and Equipment
Equipment spans gypsum preparation, calcination, stucco handling, mixing, forming, setting, cutting, drying, finishing, packing, dust control, and testing. The calciner, forming section, multi-deck dryer, and control systems take most of the machinery budget.
| Equipment | Function | Key Specification |
|---|---|---|
| Crusher & Mill | Prepare gypsum | With drying |
| Calciner | Produce stucco | Kettle or flash |
| Stucco Silos | Store and dose | Weigh feeders |
| Pin Mixer | Make slurry | Continuous |
| Foam Unit | Lower density | Automatic |
| Forming Station | Shape board | Paper unwinders |
| Setting Belt | Harden core | Long conveyor |
| Rotary Cutter | Cut boards | Synchronised knife |
| Multi-Deck Dryer | Dry boards | Gas or thermal oil |
| Trimmer & Stacker | Finish, bundle | Automatic |
| Test Instruments | Check quality | Flexural, density |
Line design should match the product plan. A compact line can buy stucco and use smaller mixing, forming, and drying units, while a full line adds its own crushing, drying, and calcination, faster forming, and long multi-deck dryers with heat recovery. Large plants add specialty dosing, perforation and lamination lines for acoustic boards and tiles, and full automation, and strong dust collection and heat recovery pay back in both working conditions and cost.
Gypsum Plasterboard Manufacturing Plant Setup Cost in India (CapEx & OpEx)
The tables below show how capital and operating costs typically split for a line of about 20 million square metres a year. The final Gypsum Plasterboard Investment Cost for your project will vary with line size, in-house calcination, gypsum source, specialty equipment, land price, and location.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Plant & Machinery | 50–60% | Calciner, line, dryer |
| Civil Works | 15–20% | Hall, sheds, stores |
| Land & Site Development | 5–8% | Land and approvals |
| Utilities & Gas Connection | 4–6% | Power, gas, water |
| Pre-operative & Certification | 3–5% | BIS, trials, training |
| Working Capital | 8–12% | Gypsum, paper, stock |
Machinery and buildings take the largest share because a continuous line is long and needs a big, well-built hall. Working capital funds gypsum and paper inventories, finished boards in many sizes, and credit to dealers and contractors. Since winning share from established brands takes time and freight limits reach, a detailed Gypsum Plasterboard Business Plan should model sales by product, region, and channel, gypsum, paper, and fuel costs, line speed and yield, freight, pricing, and working capital together, so that funding carries the business through its ramp-up years.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Raw Materials & Packaging | 50–60% | Gypsum, paper, additives |
| Utilities (fuel, power) | 20–25% | Calcining, drying |
| Labour | 5–8% | Operators, technicians |
| Maintenance | 2–4% | Line and dryer |
| Freight & Distribution | 6–10% | Bulky product |
| Overheads & Marketing | 3–5% | Dealer support |
Because materials and energy dominate costs, margins depend on gypsum and paper prices, fuel efficiency, line speed, board weight, and the mix of specialty boards. A sound operating model tracks material and fuel cost per square metre, line uptime, rejects, freight per square metre by region, and realised prices by product and channel, and tests margins against higher fuel or paper costs and price competition.
Financial Analysis and Profitability
For a reference line of 20 million square metres a year, the financial profile is attractive, backed by steady construction demand and healthy gross margins, though returns are sensitive to material and fuel costs, freight, and market access. The profitability of Gypsum Plasterboard manufacturing business in India rises with low-cost gypsum, efficient drying, high line speed and uptime, a strong dealer and contractor network, more specialty boards in the mix, and a plant located close to major cities.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 30–40% | Material, fuel driven |
| Net Profit Margin | 12–18% | After freight, taxes |
| Payback Period | 4–6 Years | Capital-intensive line |
| IRR (Internal Rate of Return) | 16–24% | Higher with specialty |
| Capacity Utilization (stable ops) | 65–85% | Market-driven |
| Break-even Capacity Utilization | 45–55% | High fixed costs |
Cost position and market reach decide where a plant falls in these ranges. Lines with cheap gypsum, efficient drying, and strong distribution near big cities earn healthy margins, while plants far from markets or reliant on costly imported gypsum earn much less. Fire-rated, moisture-resistant, and acoustic boards generally carry better margins than standard boards.
Returns improve by locking in by-product or local gypsum, recovering heat from calciners and dryers, lowering board weight with foam, building dealer and installer networks, selling complete drywall systems, and adding specialty boards and ceiling tiles over time.
Key Risks and Mitigation
Key risks include gypsum supply and purity, swings in paper and fuel prices, strong competition from multinational brands, high freight costs, slow acceptance of drywall in some regions, and construction cycles. Long-term supply contracts and blending reduce supply risk; efficient operations and pricing discipline reduce cost risk; regional focus, service, and installer training help against competition; good site selection limits freight risk; and a balanced mix of residential, commercial, and institutional sales reduces demand risk. Promoters often engage a Gypsum Plasterboard Business Plan Consultant in India to stress-test these scenarios before committing capital.
Licenses and Approvals for Gypsum Plasterboard Manufacturing in India
Approvals for a board line cover environmental consent, product certification, raw material supply, fuel, and factory safety. Promoters setting up a Gypsum Plasterboard Manufacturing Plant in India generally need the following:
- Pollution Control: Consent to Establish and Operate from the state pollution control board, with dust and emission conditions.
- BIS Certification: Certification to the Indian standard for gypsum plasterboards, often required in tenders.
- Gypsum Supply: Mining leases or supply agreements with mines, power plants, or fertiliser companies.
- Fuel & Boilers: Gas connection and approvals for thermal oil heaters or boilers.
- Factory & Fire: Factory license, building plan approval, and fire NOC for paper and board stores.
- Green Credentials: Product certifications and environmental declarations for green building projects.
- Business & Trade Registrations: Business registration, GST, Udyam, trademark, and Import Export Code.
Pollution control consent, the fuel connection, and BIS certification usually sit on the critical path, since the line cannot run or sell into large projects without them. Filing these early and starting dealer and contractor trials during construction shortens the path to regular sales.
Note: The exact approvals, registrations, licenses, and certification requirements may vary depending on factors such as plant location, capacity, products, state pollution control categories, customer specifications, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India Gypsum Plasterboard Manufacturing Industry
Recent announcements show where the industry is heading:
- New board capacity: In August 2026, Sakarni Plaster announced an investment of about INR 450 crore, including about INR 150 crore for a gypsum board plant in Andhra Pradesh in a joint venture with Coromandel.
- By-product gypsum: In April 2026, Balrampur Chini Mills announced a wallboard plant at Kumbhi, Uttar Pradesh, of about 7.6 million boards a year, using gypsum from its PLA plant.
- Low-carbon tiles: In December 2025, Saint-Gobain India commissioned a near net zero gypsum ceiling tile plant of 5 million square metres a year in Visakhapatnam.
- Large integrated site: In August 2025, Saint-Gobain began building an Oragadam, Tamil Nadu site that will include gypsum wallboard, described as its largest Asia-Pacific investment.
Together these point to rising domestic capacity, wider use of by-product gypsum, and a move toward low-carbon products. New entrants that secure gypsum, locate near demand, and build strong distribution will be best placed to compete.
How a Gypsum Plasterboard Manufacturing Project Report and DPR Helps Investors
A detailed DPR lays out the venture from end to end, covering market demand and product choice, gypsum sourcing, line design, approvals, distribution, and economics. It helps investors fix capacity, product mix, and location, estimate capital and operating costs, judge profitability, and identify risks before money is committed.
Its centrepiece is a detailed Gypsum Plasterboard Financial Model that covers revenue by product, region, and channel, gypsum, paper, additive, and fuel costs, line speed and yield, labour, freight, working capital, debt service, cash flows, break-even, return on investment, and payback across price and demand scenarios. Lenders and investors rely on this model to judge long-term viability, which is why many promoters appoint a Gypsum Plasterboard Plant Project Report Consultant in India to build the report and check its assumptions against current market data.
For a plasterboard project, a strong DPR also settles the gypsum strategy, the line and energy design, the product and distribution plan, and freight economics, the factors most likely to decide success. By testing margins against gypsum, paper, and fuel prices and competitive pricing, it turns a steadily growing opportunity into a plan that banks and partners can support.
Frequently Asked Questions
What are the first steps to set up a gypsum plasterboard manufacturing plant in India?
Define your products, line size, and target markets, then commission a feasibility study and DPR. Secure gypsum and liner paper supply, choose a site near gypsum or major markets, apply for pollution control consent, a fuel connection, and BIS certification, install the line, and build a network of dealers, contractors, and trained installers.
How much does a gypsum plasterboard manufacturing plant cost in India?
Investment ranges from about INR 40–80 crore for a compact line of 5 to 10 million square metres a year to INR 150–300 crore for a line of 20 to 30 million square metres a year, and INR 400–700 crore for a large plant of 50 million square metres a year or more.
What are the main steps in making gypsum plasterboards?
Gypsum is crushed, dried, ground, and calcined into stucco, which is cooled, mixed into a foamed slurry, formed between paper liners, set on a belt, cut, dried in a multi-deck kiln, and then trimmed, checked, and bundled.
Which machinery does a gypsum plasterboard manufacturing plant need?
Core equipment includes crushers and mills, calciners, stucco silos and dosing, pin mixers, foam units, forming stations, setting belts, rotary cutters, multi-deck dryers, trimmers and stackers, and testing instruments.
What raw materials go into gypsum plasterboard manufacturing?
The main inputs are natural, FGD, or phospho gypsum, face and back liner papers, starch, foaming agents, setting accelerators, glass fibre and water repellents for specialty grades, and edge tape and packaging.
How profitable is gypsum plasterboard manufacturing in India?
A well-run line usually earns a 30 to 40% gross margin and a 12 to 18% net margin, with payback in about 4 to 6 years. Results depend on gypsum, paper, and fuel costs, freight, line efficiency, and product mix.
Which approvals does a gypsum plasterboard manufacturing plant need in India?
Typical approvals include pollution control consents, BIS certification, gypsum supply agreements or mining leases, fuel and boiler approvals, a factory license, building approval, and fire NOC, plus GST, Udyam, trademark, and Import Export Code registrations.
How do I get a feasibility study or DPR for a gypsum plasterboard manufacturing project?
A detailed feasibility study and DPR covers demand, products, gypsum sourcing, line design, approvals, distribution, and full financials. Investors usually engage a Gypsum Plasterboard Manufacturing Feasibility Study Consultant with building materials experience to prepare the report and validate it for lenders.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

MIG welding wire is a continuous solid wire, usually 0.8 to 1.6 mm in diameter, that is fed through a welding gun and melted by an electric arc under a shielding gas to join metals.
Gypsum board, also called plasterboard or drywall, is a panel made of a set gypsum core sandwiched between two sheets of heavy paper.
Steel forgings are strong, reliable metal parts made by shaping heated steel under the force of presses and hammers, which refines the grain structure and gives far better strength and fatigue resistance than casting or machining from bar.
PVC boards, mainly PVC foam boards and WPC boards, are lightweight, waterproof, termite-proof sheets used as an alternative to plywood and MDF in kitchens, bathrooms, wardrobes, furniture, partitions, signage, and interiors.
Laminated veneer lumber, or LVL, is an engineered wood product made by bonding thin wood veneers with their grain running in the same direction, producing straight, strong, and dimensionally stable members from fast-growing plantation timber.
Fly ash bricks turn a waste product from coal-fired power plants into strong, uniform building blocks that need no firing in a kiln. India's thermal power plants generated about 340 million tonnes of fly ash in 2024-25, and government rules require building projects within 300 km of these plants to use ash-based bricks and blocks where they are priced competitively.
Nuts and bolts hold together almost everything that is built or manufactured, from cars, tractors, and two-wheelers to bridges, towers, railways, machinery, and household appliances.
Precast elements are cast in a factory under controlled conditions and then transported to site, where they are lifted into place like the parts of a kit. India's construction sector is turning to this method to build faster, with better quality and less dependence on site labour.
Rice husk ash (RHA) is the residue left when rice husk is burned, and when the burning is properly controlled it is one of the richest natural sources of amorphous silica, typically 85 to 95% silica by weight.
Concrete poles carry most of India's low-tension and 11 kV distribution lines, as well as street lights, rural feeders, and telecom cables. They are strong, durable, resistant to rust, rot, and termites, need almost no maintenance, and cost less than steel poles, which makes them the default choice for state power distribution companies.
Crushed stone aggregates and manufactured sand are the most widely used construction materials after water. They form the bulk of concrete, the base layers of roads and runways, railway ballast, and the fill under buildings, factories, and ports.
Almost every industrial process generates heat that has to be removed. Power plants, steel mills, refineries, chemical and pharmaceutical units, food processors, plastics moulders, and now data centers all rely on cooling towers, chillers, and heat rejection equipment running around the clock.
Steel is the backbone of India's economic growth. Buildings, bridges, railways, highways, ports, power plants, automobiles, machinery, and household appliances all depend on it. India is the world's second-largest steel producer, and crude steel output reached about 170 million tonnes in 2025-26.
Ready mix concrete (RMC) is concrete batched in a central plant to a precise, engineered mix design and delivered to construction sites in transit mixers, ready to pour.
Open a modular kitchen cabinet, a wardrobe shutter, or an office workstation in India today and there is a good chance it is made from medium density fibreboard.
India is the world's second-largest producer of ceramic tiles, and walking through any new apartment, mall, hospital, or metro station shows why. Tiles have replaced mosaic, stone, and plain cement floors in homes across the country, while large-format glazed vitrified slabs are now standard in premium projects.
Setting up a TMT Bar Manufacturing Plant in India is a high-demand, infrastructure-driven venture, powered by the country's massive construction and housing boom, government infrastructure spending, and steady urbanisation.
Setting up a Cement Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's massive infrastructure programme, housing boom, and status as the world's second-largest cement producer.
Setting up a PVC Panel Manufacturing Plant in India is a high-demand, construction-driven venture, powered by the country's building boom, fast-growing interior and renovation market, and the shift away from plywood and plaster toward affordable, waterproof panels.
Setting up an Electric Motor Manufacturing Plant in India is a high-value, engineering-driven venture, powered by the country's industrial expansion, energy-efficiency push, and the rise of electric vehicles and automation.
Setting up an Iron Ore Pellets Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's ambitious steel-capacity expansion, the shift toward value-added iron ore, and rising demand from blast furnaces and sponge iron units.
The Saudi Arabia construction market has emerged as one of the most closely watched construction economies in the world. The market reached USD 101.4 Billion in 2025 and is projected to reach USD 140.4 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 3.6% between 2026 and 2034.
A WPC (Wood Plastic Composite) door is a type of composite door made from a combination of wood fibers or wood flour and thermoplastic resins like PVC, polyethylene, or polypropylene, with additives to improve durability and processability. The resulting composite material is then extruded or molded into door panels and frames, providing the attractive look of wood and the strength and water-resistance of plastic.
UPVC windows refer to window frames and window assemblies manufactured from ‘unplasticized polyvinyl chloride,’ which is a relatively rigid and strong thermoplastic substance. While PVC is a flexible material that requires the addition of a softening substance called a plasticizer to be formed into a durable performance material, PVC window frames and UPVC window assemblies, for instance, do not display such requirements due to the presence of unplasticizers, a component of the material that provides enhanced strength, stability, and resistance to the elements such as UV radiation, moisture, and temperature changes.
The Saudi Arabia factoring market represents a critical component of the Kingdom's evolving financial services landscape, offering businesses an increasingly popular alternative to traditional bank lending. Factoring, which involves the sale of accounts receivable to a third-party financial institution at a discount, has emerged as a vital mechanism for improving liquidity, managing cash flow, and mitigating credit risk across diverse industry sectors.
The GCC bridge construction market represents a vital component of the region's ambitious infrastructure transformation agenda, serving as a cornerstone for enhanced mobility, economic integration, and sustainable urban development across the Gulf states.
The Australia industrial couplings industry stands at a transformative juncture in 2025, propelled by technological advancement and surging demand across critical sectors. As mechanical devices connecting two shafts to transmit power and torque, industrial couplings form the backbone of machinery operations in manufacturing, mining, automotive, and energy sectors.
The Saudi Arabia real estate market stands at a pivotal juncture in its evolution, representing one of the most dynamic and transformative sectors within the Kingdom's economy. With this country having a very ambitious agenda of economic diversification and modernization, the real estate business has come out as one of the pillars of this transformation.
Steel is an alloy that consists of iron and carbon in addition to trace amounts of other elements like manganese, silicon, chromium, and nickel. The amount of carbon in steel is usually less than two percent and is an important factor in determining the strength, hardness, and ductility of steel.
Saudi Arabia’s precast concrete market reached USD 1.2 Billion in 2024 as per the IMARC Group, clear proof that off-site construction is rapidly becoming the Kingdom’s go-to building solution. With residential, commercial, and major infrastructure projects multiplying, developers are increasingly turning to precast building solutions to keep pace.
The GCC cold storage construction market represents critical infrastructure underpinning regional food security, pharmaceutical distribution, and temperature-sensitive logistics across the Arabian Peninsula. As Gulf Cooperation Council nations diversify their economies and reduce hydrocarbon dependence, robust cold chain infrastructure has emerged as a cornerstone of sustainable development planning.
PVC panels are lightweight, durable building materials made from polyvinyl chloride using extrusion or molding processes. They are available as rigid or semi-rigid sheets designed primarily for wall and ceiling cladding, partitions, and decorative finishes. Known for their excellent resistance to moisture, chemicals, termites, and corrosion, PVC panels offer a smooth surface and a clean, polished look that’s easy to maintain. Available in an extensive range of colors, textures, and patterns, these panels serve as a practical alternative to traditional materials like wood, plaster, or tiles.
Ready mix concrete (RMC) is a precisely engineered construction material produced in a controlled environment within a batching plant and delivered to construction sites in a freshly mixed, plastic state. It is formulated by combining cement, aggregates, water, and chemical or mineral admixtures in carefully proportioned quantities to achieve specific performance characteristics. Unlike site-mixed concrete, RMC ensures consistent quality, uniformity, and superior workability through automated production and quality control processes.
The construction industry across the Gulf Cooperation Council (GCC) member states is at the core of a monumental economic transformation. Far exceeding traditional building activities, the sector now serves as the principal vehicle for national economic diversification strategies, moving these nations beyond reliance on oil revenues.
Paver blocks are precast construction material made basically from cement, aggregates, sand, and pigments for constructing surfacing. They are produced in standardized shape and thickness, allowing each unit to interlock to form a strong, load-bearing surface with no need for continuous concrete pouring. Paver blocks possess high compressive strength, abrasion resistance, and are easy to lay and maintain.
The Brazil ceramic tiles market has witnessed stable growth, reflecting broader trends in the construction and building materials industries of the country. The Brazil ceramic tiles market size was valued at USD 1.6 Billion in 2025. The market is expected to reach USD 2.2 Billion by 2034, exhibiting a CAGR of 3.91% during 2026-2034.
MDF is an engineered wood product produced by breaking down hardwood or softwood residuals into wood fibers, which are then combined with resin binders under heat and pressure. MDF exhibits a homogeneous density, a smooth surface, and fine texture, ensuring a much more workable material compared to natural wood.
Float glass is a type of flat glass that is manufactured by floating molten glass on a bed of molten tin. This produces a smooth, uniform surface and consistent thickness. The float process was developed by Pilkington in the 1950s and revolutionized glassmaking because it enabled the production of large, flawless sheets of glass without needing polishing or grinding. The basic raw materials used-silica sand, soda ash, limestone, and dolomite-are heated in the furnace to a very high temperature, then continuously poured onto the tin bath, where the molten glass spreads out into an even layer. It cools and solidifies into a perfectly flat and perfectly transparent sheet. As it provides optical clarity and strength and is easily processed into coated, laminated, or toughened forms, float glass is used as a basic product for various applications, ranging from architectural and automotive to industrial applications.
ERW steel pipes can be identified as one of the most important categories of welded pipes and find wide applications in infrastructure, construction, and other industries because of their precision, cost-effectiveness, and reliability. The raw material to produce these pipes is either hot-rolled or cold-rolled steel coils that are longitudinally formed and welded by the application of high-frequency electric resistance welding.
Drill bits are specifically designed cutting instruments intended to produce cylindrical holes in various materials, ranging from soft woods and plastics to hardened steels, stone, and rock. Although they seem straightforward, drill bits consist of various specialized shapes, coatings, and materials that are designed to suit the cutting characteristics of the intended material and the requirements of the drilling task.
Concrete is among the most widely used construction materials in the world due to its strength, versatility, and durability. It is a composite material largely made of cement, water, aggregates-sand, gravel, or crushed stone-and in some cases, admixtures which give special properties to the concrete.
Clay bricks are one of the oldest and most extensively used construction materials in the globe, appreciated for their strength, durability, insulation against heat, and beauty. They are produced mainly from natural clay and shale, which are fashioned, dried, and subjected to high-temperature firing to produce a hard, dense material that can resist multiple environmental and structural stresses. The mix generally consists of alumina, silica, lime, iron oxide, and magnesia that collectively decide the color, texture, and performance properties of the brick.
Metal beam crash barriers and high mast light poles are essential infrastructural features providing security and visibility on highways, city roads, and industrial sites. Metal beam crash barriers or guardrails are made of galvanized steel beams, typically W-beam or Thrie-beam, that are designed to dissipate the impact energy on impact with a vehicle and minimize death and damage to vehicles.
Laminated plywood is an engineered wood material that is produced by laminating several layers of thin veneers of wood together with powerful adhesives and covering them with a protective or decorative laminate sheet. This amalgamation not only increases the strength of the plywood but also its beauty, which is why it is extremely versatile for use in furniture, cabinetry, floors, paneling, and interior design.
Ductile iron pipes (DIP) are a key part of new water and wastewater infrastructure, providing enhanced performance capabilities over older piping materials. Cast from ductile cast iron, a material that has the strength of steel combined with the resistance to corrosion of cast iron, these pipes are designed to endure high-pressure use while still being flexible enough to absorb stress without cracking.
The real estate sector plays a critical role in driving economic growth and shaping communities. It significantly contributes to national economies by generating jobs, influencing investment flows, and boosting government revenues through taxes. Beyond these economic benefits, real estate development directly affects the quality of life by creating homes, enhancing infrastructure, and revitalizing urban areas.
Gypsum boards, also referred to as drywall or plasterboard, are lightweight, strong and fireproof building materials that are frequently used for partitions, walls and ceilings. Constructed from a gypsum core encased in paper liners, they provide improved acoustics, cost effectiveness, and speedy installation. Gypsum boards are favoured in industrial, commercial, and residential construction because of its environmentally beneficial qualities, ability to withstand moisture, and ability to insulate against heat. They are an essential part of efficient and sustainable construction methods because of their adaptability to contemporary building processes.
A frameless shower door is a modern and aesthetically appealing bathroom fixture that has gained popularity for its sleek and minimalist design. They are constructed without the bulky metal framing that surrounds the glass panels and are typically made from thick, tempered glass that is securely attached to the wall and floor using hinges or brackets.