Which Automotive Actuator Industry Segments Offer Investors the Highest Growth?
Introduction
Every function in a modern vehicle that moves, from a brake caliper to an air-conditioning flap, depends on an actuator that turns an electronic command into physical motion. The global automotive actuators market size was valued at USD 31.1 Billion in 2025 and is forecast to reach USD 47.3 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 4.62% during 2026–2034, according to IMARC Group.
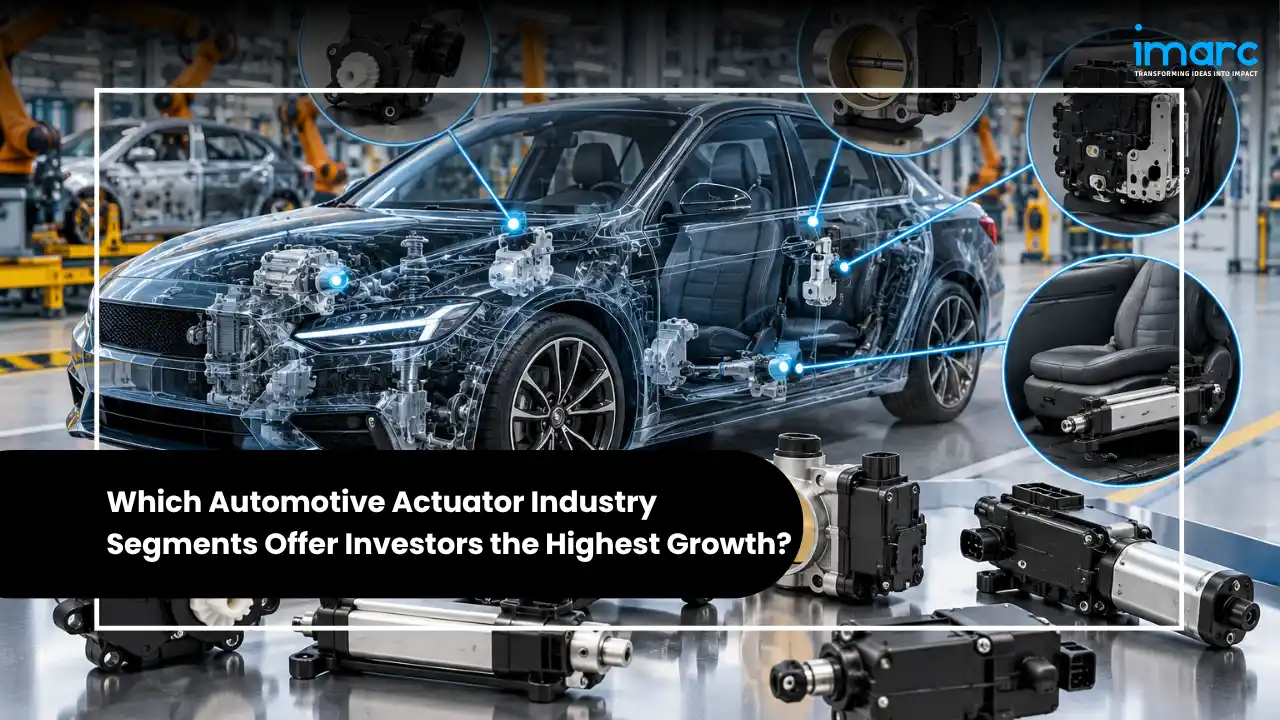
As IMARC Group describes them, automotive actuators are integrated components of electronic control systems that convert electrical or hydraulic energy into motion. They activate control valves, regulate throttles that direct airflow in climate management systems, operate power liftgates, and adjust engine flywheel speed and torque. They are commercially available in hydraulic, electric, and pneumatic variants.
By product, brake actuators currently hold the largest share of the automotive actuators market, linear motion dominates by motion type, and Asia-Pacific leads regionally, per IMARC Group. The demand mix, however, is shifting toward three engines: by-wire braking and steering, electric vehicle (EV) thermal management, and sensor-integrated smart actuation. Electrification is the common thread. According to the International Energy Agency (IEA), global electric car sales grew 20% in 2025 to exceed 20 million units, meaning roughly one in four new cars sold worldwide was electric.
This blog delivers a focused automotive actuators market analysis covering market size and segmentation, recent announcements, sector-level demand trends, regional hotspots, competitive positioning, policy tailwinds and risks, and the long-range forecast.
Key Takeaways
- The global automotive actuators market reached USD 31.1 Billion in 2025 and is forecast to hit USD 47.3 Billion by 2034, at a CAGR of 4.62% (2026–2034), per IMARC Group.
- Brake actuators hold the largest product share, linear actuators lead by motion type, and Asia-Pacific dominates regionally, according to IMARC Group.
- Electric car sales exceeded 20 million units in 2025 and are projected to reach 23 million in 2026, per the IEA, lifting demand for thermal management valves, HVAC actuators, and electrified chassis systems.
- Brake-by-wire is entering series production: Bosch said its by-wire brake actuator was expected in production vehicles for an Asian automaker from early 2026.
- Rare-earth magnet supply, tariffs, and shifting EV subsidies are the main risks, while the U.S. FMVSS 127 automatic emergency braking rule (September 2029 deadline) and the EU's proposed 2035 CO2 target revision shape the policy backdrop.
Market Size, Share & Growth Outlook
According to IMARC Group, the automotive actuators market generated revenue of USD 31.1 Billion in 2025 and is set to reach USD 47.3 Billion by 2034, at a CAGR of 4.62%. The report covers historical data for 2020–2025 and forecasts for 2026–2034. Segment-level analysis reveals where value concentrates:
- Product: IMARC Group segments the market into brake actuators, HVAC actuators, headlamp actuators, grill shutter actuators, seat actuators, coolant and refrigerant valve actuators, and others. Brake actuators currently hold the largest market share. Braking is the most safety-critical actuated function in a vehicle, and it is where the industry's by-wire shift is concentrated.
- Motion: The market is divided into linear and rotatory actuators. Linear actuators currently exhibit a clear dominance, according to IMARC Group.
- Vehicle Type: Passenger vehicles, commercial vehicles, and others. Commercial vehicles are gaining electrified content: the IEA reports that global electric truck sales more than doubled in 2025.
- Sales Channel: Original equipment manufacturer (OEM) and aftermarket channels, with OEM supply tied to new vehicle programs and aftermarket demand tied to the installed base of actuator-equipped vehicles.
- Region: North America, Asia-Pacific, Europe, Latin America, and the Middle East and Africa. Asia-Pacific currently dominates the global market, per IMARC Group, which also publishes dedicated country reports for China, Japan, Mexico, and Brazil.
Recent News & Mega Announcements
Suppliers are reorganizing portfolios and commissioning capacity around electrified, software-defined vehicles. Recent developments include:
- In September 2025, Continental completed the spin-off of its Automotive group sector as Aumovio SE, which began trading on the Frankfurt Stock Exchange on September 18, 2025, leaving Continental AG focused on tires.
- In October 2025, Bosch unveiled its by-wire brake actuator in Japan at the Japan Mobility Show 2025. According to the company, the hydraulic brake-by-wire system removes the mechanical link between pedal and brakes, and series production for an Asian automaker was expected to start in early 2026. Bosch also completed installation of its 10th-generation ESP production line at its Tochigi plant in October 2025.
- In December 2025, the European Commission presented its Automotive Package, proposing to lower the 2035 fleet-wide CO2 reduction target for new cars from 100% to 90% versus 2021 levels. The proposal still requires approval from the European Parliament and member states.
- In May 2026, Johnson Electric reported fiscal 2025/26 Automotive Products Group sales of USD 3,054 million, or 84% of group sales, noting that global vehicle production growth remains lackluster amid affordability concerns, tariff pressure, and shifting battery electric vehicle economics.
- In July 2026, CTS Corporation reported securing about USD 163 million in new transportation business awards in the second quarter, including a roughly USD 100 million sensor award from a major North American OEM.
- By September 2026, Nidec India's third plant in Neemrana, Rajasthan was slated to begin operations, producing electric power steering motors, park lock actuators, electric water pumps, electric oil pumps, and BLDC engine cooling fan motors.
Collectively, these announcements show capacity and R&D shifting toward by-wire safety systems, electrified thermal and powertrain components, and localized production in high-growth markets.
Industry Trends Shaping 2026
Three demand engines are redefining the automotive actuators market through the forecast period.
1. By-Wire Braking and Steering
Brake actuators already lead the market by product, and by-wire architectures are widening their role. In a by-wire system, driver input travels electronically to the actuator rather than through a mechanical linkage. Bosch states its hydraulic brake-by-wire system pairs a by-wire brake actuator with an ESP unit, either of which can build brake pressure on all four wheels if a fault occurs, and that combining brake-by-wire with steer-by-wire reduces variants between left-hand and right-hand drive vehicles. Industry reporting also notes that two Asian customers were due to begin series production with Bosch's electromechanical brake and steering systems in 2026, and that ZF has equipped the Nio ET9 with steer-by-wire. Safety regulation reinforces the shift: the U.S. NHTSA estimated its FMVSS 127 automatic emergency braking rule would save at least 360 lives and prevent more than 24,000 injuries annually.
2. EV Thermal Management and HVAC Actuation
Electrification multiplies the valves and flaps that manage battery, cabin, and powertrain temperature, which maps directly to IMARC Group's HVAC actuator and coolant and refrigerant valve actuator segments. IMARC Group also cites growing installation of actuators in HVAC systems and refrigerants as a positive demand factor. The volume backdrop is strong: the IEA reports electric car sales exceeded 20 million in 2025, with 23 million projected for 2026, and nearly 22 million electric cars were produced in 2025. Suppliers are responding. At IAA Mobility 2025, MAHLE showed an EV thermal management module with an integrated heat pump that it says can increase range by up to 20% even at low temperatures. MAHLE also states it develops and produces electric actuators alongside its thermal management systems.
3. Smart, Sensor-Integrated Actuation
IMARC Group identifies the introduction of intelligent actuators with smart sensors, control units, and Internet of Things (IoT) solutions as a primary growth driver, citing their ability to sense vehicle speed and movement and calculate the distance between the vehicle and surrounding objects. The growing sales of autonomous cars add to this outlook. Supplier order books reflect the sensing layer: CTS, which manufactures sensors and actuators, booked its roughly USD 100 million North American OEM sensor award in the second quarter of 2026. The IEA's 2026 Global EV Outlook also adds a new section on automotive software and AI trends, signaling how central software has become to vehicle systems.

Geographic Hotspots
Asia-Pacific remains the center of gravity and currently dominates the global automotive actuators market, per IMARC Group. China produced 34.531 million vehicles and sold 34.40 million in 2025, with exports of 7.098 million units, according to the China Association of Automobile Manufacturers (CAAM). New energy vehicles accounted for 47.9% of new vehicle sales. Johnson Electric reported 4% sales growth in the Asia-Pacific region for the quarter ended June 30, 2026, driven by program ramp-ups and share gains with Chinese domestic OEMs.
India is scaling as both a market and a manufacturing base. The Society of Indian Automobile Manufacturers (SIAM) reported record FY2025-26 domestic wholesales of 28,265,519 units, up 10.4%, with vehicle exports of 6,647,685 units, up 24%. Europe is supported by CO2 standards: IEA data shows electric car sales reached 4.2 million in 2025, or 28% of new cars sold. In North America, U.S. EV sales stayed just under 10% of car sales and dropped at the end of 2025 after tax credits ended, per the IEA. Latin America is covered by IMARC Group's dedicated Mexico and Brazil reports.
Competitive Landscape & Key Players' Strategies
IMARC Group's competitive landscape profiles ten companies spanning global Tier-1 suppliers, motion-control specialists, and electronics firms. Key players include:
- Continental AG: Its former Automotive group sector, covering vehicle electronics, sensors, and braking systems, now operates as Aumovio SE following the September 2025 spin-off; Continental AG is a tire-focused company.
- CTS Corporation: Manufactures sensors, actuators, and electronic components; booked about USD 163 million of new transportation awards in Q2 2026.
- DENSO Corporation: Powertrain, thermal, and electronics supplier; has outlined a ¥10 trillion decade-long R&D investment plan aimed at electrification and safety.
- EFI Automotive: Profiled by IMARC Group among the participants in the global automotive actuators market.
- Johnson Electric Holdings Limited: Motors, actuators, and motion subsystems specialist; automotive generated 84% of FY2025/26 group sales.
- MAHLE GmbH: Pairing electric actuators with thermal management modules and heat pump technology for EVs.
- Mitsubishi Electric Mobility Corporation: Began operations on April 1, 2024 as the spin-off of Mitsubishi Electric's automotive-equipment business.
- Nidec Corporation: Localizing production of park lock actuators, electric power steering motors, and electric pumps at its third India plant.
- Robert Bosch GmbH: Commercializing by-wire brake actuators and 10th-generation ESP, alongside steer-by-wire development.
- Stoneridge: Vehicle electronics supplier with a commercial vehicle focus; second quarter 2026 sales grew 15.1% year over year to USD 181.4 million.
Across the board, players are competing on electrification readiness, by-wire safety capability, sensor integration, and localized manufacturing close to OEM customers.
Policy & Regulatory Landscape, Challenges & Risks
Regulation increasingly dictates actuator content and powertrain mix. Key frameworks include:
- U.S. FMVSS 127: NHTSA's final rule requires automatic emergency braking, including pedestrian AEB, on light vehicles up to 10,000 lbs by September 1, 2029. A legal challenge remains in abeyance, and the deadline stands unless a proposed revision is adopted, per an April 2026 legal analysis.
- EU Automotive Package: The December 2025 proposal would lower the 2035 target to a 90% CO2 reduction, with the remainder offset through low-carbon steel or e-fuels and biofuels. It awaits approval from EU co-legislators.
- India demand-side measures: SIAM attributes record FY2025-26 sales to GST reforms, repo rate cuts, and income tax relief.
- China export controls on rare earths: Introduced in April 2025, these now shape magnet sourcing for motor-driven components worldwide.
On the constraining side, several structural risks persist:
- Rare-earth magnet dependence: China controls up to 70% of rare-earth mining and about 90% of magnet production, per AlixPartners. The European Association of Automotive Suppliers said some European suppliers suspended production lines after the April 2025 controls.
- Subsidy-driven EV volatility: IEA data show global electric car sales fell 8% in Q1 2026 versus Q1 2025 after policy changes in China and the United States.
- Tariffs and affordability: Johnson Electric cites affordability concerns, geopolitical uncertainty, and tariff pressure, while CTS flags tariff and consumer uncertainty in light vehicles.
- Regulatory uncertainty: The unresolved status of FMVSS 127 and the pending EU proposal complicate multi-year platform and sourcing decisions.
Forecast 2026–2034
IMARC Group projects the automotive actuators market to grow from USD 31.1 Billion in 2025 to USD 47.3 Billion by 2034, at a CAGR of 4.62%. IMARC Group attributes growth to engine downsizing for fuel efficiency, rising safety concerns and road accident incidence, government promotion of electric and hydraulic actuators that avoid combustion emissions, the arrival of intelligent actuators with smart sensors and IoT, growing autonomous car sales, and wider installation in HVAC systems and refrigerants.
Third-party outlooks point the same direction over the long term. The IEA projects the global EV fleet, excluding two- and three-wheelers, could grow from nearly 80 million today to as many as 510 million by 2035 even without new policy announcements. Near-term momentum is likely to be uneven, given the early 2026 EV dip, but the structural mix shift toward electrified thermal, braking, and steering actuators supports sustained expansion across brake, HVAC, and valve segments.
Opportunities for Stakeholders
This growth trajectory creates differentiated opportunities across the value chain:
- Tier-1 Suppliers & Manufacturers: By-wire brake and steering actuators carry redundancy and software content; Bosch's early-2026 series production start signals commercial readiness.
- Thermal & HVAC Component Makers: Heat pump modules, coolant and refrigerant valves, and HVAC actuators scale with electric car production of nearly 22 million units in 2025, per the IEA.
- Investors: India's record FY2025-26 sales and 24% export growth, together with localization such as Nidec's Neemrana plant, support regional capacity theses.
- Materials & Motor Technology Providers: Supply disruption in 2025 raises the value of low-rare-earth motor designs; MAHLE showed a second-generation contactless transmitter that it says removes rare-earth dependence.
- Aftermarket & Service Players: A growing installed base of EVs, forecast by the IEA to reach up to 510 million by 2035, expands the long-term replacement pool for actuators.
- OEMs & Governments: Safety mandates such as FMVSS 127 and EU CO2 rules create clear compliance-driven demand for braking and thermal actuation.
Three Demand Engines, One Essential Component
The global automotive actuators market is no longer a story about mechanical convenience features. By-wire safety systems, EV thermal management, and sensor-integrated smart actuation are each rewriting the demand curve on their own timelines, and together they help explain why the market is set to reach USD 47.3 Billion by 2034, according to IMARC Group. Segmentation by product, motion, vehicle type, sales channel, and region has become the essential lens for reading the industry.
For suppliers, the imperative is to secure rare-earth and semiconductor-adjacent inputs while building by-wire and thermal capabilities. For investors, the opportunity concentrates in regions combining vehicle volume growth with localization, notably Asia-Pacific. For policymakers, the lesson of this cycle is that safety rules and emissions targets directly determine actuator content, and the regions that give clear, stable direction will shape the next decade of the automotive actuators market.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

India is the world's largest two-wheeler market, and it is steadily going electric. Electric scooters, motorcycles, and mopeds offer running costs far below petrol models, suit short urban commutes and delivery work, and are central to the country's clean mobility goals.
Electric bicycles, or e-bikes, combine a conventional bicycle with a small electric motor, a lithium-ion battery, and a controller that assists the rider's pedalling. In India, models limited to 250 watts and 25 km/h do not need registration or a driving license, cost a few paise per kilometre to run, and suit short commutes, fitness riding, students, and last-mile delivery.
Walk into a modern Indian car parts plant, pharmaceutical packing line, or electronics factory and you will see robots welding and palletising, conveyors moving parts between stations, vision cameras checking quality, and control panels coordinating it all.
Tyres are essential to every vehicle on India's roads, from two-wheelers and three-wheelers to cars, buses, trucks, tractors, and off-highway machines.
If the battery is the heart of an electric vehicle, the wiring harness is its nervous system. Every EV needs low-voltage harnesses for lights, sensors, and controls, plus high-voltage harnesses that carry hundreds of volts and high currents between the battery, inverter, motor, and charging port, and dedicated harnesses inside the battery pack that monitor every cell.
Every electric vehicle needs a brain between the battery and the motor. The motor controller, often called the traction inverter in larger vehicles, converts DC power from the battery into precisely controlled AC power for the motor, manages acceleration, regenerative braking, and efficiency, and protects the whole powertrain from faults.
Every vehicle on the road depends on forged parts. Crankshafts, connecting rods, steering knuckles, axle beams, gears, and hubs are forged because the process gives steel a continuous grain flow and the strength to survive millions of load cycles.
Setting up an Automotive Components Manufacturing Plant in India is a high-potential, export-capable venture, powered by the country's large automobile industry, deep supplier base, and growing role as a global sourcing hub for auto parts.
The global automotive lead-acid battery market reached USD 13.89 Billion in 2025 and is projected to reach USD 16.60 Billion by 2034, growing at a CAGR of 1.94% (2026–2034).
Setting up an Electric Scooter Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's rapid shift to electric mobility, supportive EV policies, and surging demand for affordable, clean urban transport. As two-wheelers dominate Indian roads and buyers move from petrol to battery-powered scooter manufacturing, an EV Scooter Manufacturing Plant is one of the most accessible and strategically timed entry points into the electric vehicle economy.
Capital is flowing into the united states used car market because structural affordability pressure, digital retail maturity, and a record-old national vehicle fleet have converged into a genuinely investable thesis.
The Europe Tire Market reached a volume of 458.89 Million Units in 2025 and is projected to reach 565.69 Million Units by 2034, growing at a CAGR of 2.35% (2026–2034).
A strategic analysis of how PLI policies and localization drive global OEM investments. India’s EV battery market hits USD 15,898.31 Million by 2034 (21.7% CAGR).
A tyre is circular in shape and made of a combination of rubber materials that fit perfectly over a circular rim on a wheel, providing traction, load-carrying capabilities, shock absorption, and directional stability. As such, tyres are engineered materials composed of a combination of natural or synthetic materials. They are composed of a combination of materials such as rubber, a combination of materials such as steel or textile, and various chemical materials, among others.
A tractor is a self-propelled, torque-requiring vehicle intended primarily for pulling power at low speeds for agricultural, industrial, and utility purposes. It functions as a mobile power source that can be used for towing, pushing, lifting, or driving a variety of agricultural implements through mechanical, hydraulic, or power take-off systems. Tractors are designed with powerful propulsion systems, sturdy frames, and versatile coupling systems for use on different terrains and under heavy loads.
The electric boat and ship market size is experiencing unparalleled growth as the marine industry embraces electrification on a large scale across different geographies. As sustainability is becoming a strategic priority, with each passing day, more and more marine operators look to electric propulsion technologies as alternatives aimed at cutting down emissions, improving operational efficiencies, and enabling greener ports.
The GCC car rental market has emerged as a critical component of the region's transportation ecosystem, driven by robust tourism activity, expanding business travel, and a substantial expatriate population. Countries across the Gulf Cooperation Council are witnessing unprecedented demand for flexible mobility solutions that cater to diverse customer segments. The GCC car rental market size was valued at USD 1.65 Billion in 2024 as governments prioritize infrastructure development and sustainable tourism initiatives.
The Indian automotive sector has formed a vital part of the country's industrial and economic development for a long period. Over the years, the industry has transformed significantly, influenced by changes in technology, global trends, and consumer preference. Among the various factors shaping its trajectory, government policies have emerged as a decisive force driving growth, innovation, and competitiveness in the India auto parts manufacturing industry.
The India motorcycle tires market continues to evolve in response to changing mobility preferences, rising urbanization, and the growing significance of two-wheelers as essential transportation assets for millions of riders. As per sources, the India motorcycle tires market size reached USD 933.66 Million in 2024. The market is projected to reach USD 2,419.36 Million by 2033, exhibiting a growth rate (CAGR) of 10.3% during 2025-2033.
The Saudi Arabia tire market is undergoing a significant transformation driven by the nation’s economic diversification, rapid urbanization, and growing vehicle ownership. As one of the largest automotive hubs in the Middle East, Saudi Arabia is witnessing increasing demand for both passenger and commercial vehicle tires across urban and industrial regions.
One of the world's most dynamic and quickly changing markets, India's automotive industry is undergoing revolutionary changes in both the new and used car markets. Despite general economic uncertainty, the used car industry has shown remarkable resilience and growth potential, making it a particularly vibrant part of this ecosystem.
One of the world's most vibrant and quickly growing automobile markets is India's passenger car sector. From technological innovation to economic development, a number of interrelated factors have contributed to the sector's remarkable transformation. For stakeholders looking to take advantage of the enormous opportunities in this dynamic market, it is imperative that they comprehend these growth drivers.
India's truck industry is at a turning point in its development, driven by extensive government policies that are changing the commercial vehicle market. The industry, which is the foundation of the country's logistics ecosystem, is gaining previously unheard-of momentum thanks to smart regulatory frameworks and forward-thinking legislative initiatives. A fundamental change in truck operations on Indian highways is being sparked by government initiatives ranging from infrastructure development to emission standards, digitalization, and financial incentives.
The electric rickshaw sector in India has experienced a significant upheaval in recent years and is now a vital part of the country's sustainable transportation network. Strategic government policies aimed at hastening the adoption of clean mobility solutions have played a major role in orchestrating this evolution. India's larger vision of sustainable urbanization is in line with the electric rickshaw industry, which combines social development objectives, economic opportunities, and environmental imperatives.
Transportation in India is undergoing a spectacular change with the advent of electric two-wheelers that are quite an enticing alternative to traditional fuel-powered ones. This change is not merely an act of technological transformation, but an indication of how millions of Indians will think about city mobility, eco-awareness, and economic effectiveness.
As one of the world's leading industrial powerhouses, Japan has long been recognized for its commitment to technological innovation and manufacturing precision. The industry for industrial automation components—encompassing sensors, controllers, actuators, drives, robotics, and human-machine interfaces—represents the backbone of modern manufacturing infrastructure.
The Australian brakes and clutches industry plays a vital role in ensuring vehicle performance, safety, and efficiency across both automotive and industrial segments. As the nation transitions toward electric mobility and smarter manufacturing systems, the demand for advanced braking and clutch mechanisms is rising significantly.
The Philippines automotive wiring harness industry stands at a transformative juncture, driven by technological innovations that are reshaping vehicle electrical architectures worldwide. As vehicles evolve into sophisticated mobile computing platforms, the wiring harness, the circulatory system transmitting electrical power and data throughout modern automobiles, has become increasingly complex and critical to vehicle performance.
Japan's hybrid vehicles market stands as a global benchmark for sustainable mobility innovation, demonstrating remarkable growth and technological leadership. The market achieved a valuation of USD 33.57 Billion in 2024. Japan's hybrid vehicle (HV) market is one of the most established globally, originating with pioneering models like the Toyota Prius. It currently represents a significant portion of the country's automotive sales.
The Japan warehouse robotics market is a highly dynamic and rapidly expanding segment of the global automation industry. The market, valued at USD 414.0 Million in 2024, is on a sharp growth trajectory. Its growth is fueled by critical domestic factors, including a severe labor shortage, the rapid expansion of e-commerce, and Japan's strategic position as a world-leading robotics manufacturer.
The UK is rapidly evolving into a dynamic hub for autonomous vehicle research, testing, and early-stage deployments. A strong ecosystem comprising academic institutions, technology start-ups, automakers, and mobility service providers fosters continuous innovation. Supported by a skilled workforce specializing in software, sensing, robotics, and transportation systems, the nation has become a fertile ground for experimentation.
Japan’s transportation landscape is on the brink of a major shift, with robo taxis, autonomous, driverless vehicles designed for passenger and goods transport, emerging as a practical mobility solution. The Japan robo taxi market reached USD 83.2 Million in 2024 . This remarkable expansion reflects Japan’s broader move toward smart mobility, sustainability, and automation.
The Japan electric truck market is experiencing transformative growth as the nation accelerates toward sustainable transportation and carbon neutrality. As a leading automotive manufacturing hub, Japan is witnessing unprecedented momentum in commercial vehicle electrification, driven by stringent environmental regulations, technological innovation, and strategic government support. The electric truck industry represents a critical component of Japan's commitment to achieving 100% electrified vehicle sales by 2035 and carbon neutrality by 2050.
An EV charging station represents the necessary main infrastructure that allows electrical energy to be transferred from the power grid into electric vehicles to enable their use for transportation. Unlike conventional fueling stations that offer liquid fuels, EV charging stations provide electric power through the use of standardized connectors and smart control systems. The core components include a power conversion unit, which transforms alternating current from the grid into direct current for the vehicle battery; a charging controller controlling communication between the charger and the EV; and a connector or plug matched to the vehicle's charging interface.
An electric scooter is a two-wheeled vehicle powered by an electric motor and rechargeable battery, aimed at offering the means for efficient, eco-friendly, and cost-effective urban mobility. Apart from the traditional scooters that are powered by internal combustion engines, the electric scooters make use of lithium-ion or lead-acid batteries that feed an electric supply to a BLDC motor, which drives the wheels either directly or via a belt or chain mechanism.
Electric bikes, commonly referred to as e-bikes, are one of the most transformational innovations in modern personal mobility, combining conventional bicycle mechanics with advanced electric propulsion technology. At the heart of e-bikes are an electric motor, a rechargeable battery, and a control system that add assistance to the rider while pedaling, making cycling easier, faster, and more accessible across varied terrains. Based on their design, they can be further categorized into pedal-assist, throttle-controlled, or hybrid models, each providing different levels of rider control and engagement of the motor.
The micro-mobility industry has emerged as a transformative force in urban transportation, revolutionizing how people navigate cities worldwide. According to IMARC, the global micro-mobility market size was valued at USD 63.10 Billion in 2024. Looking forward, IMARC Group estimates the market to reach USD 204.83 Billion by 2033, exhibiting a CAGR of 12.86% from 2025-2033.
India's electric vehicle (EV) revolution is accelerating at a breakneck speed, powered by a strategic combination of government incentives, infrastructure investments, and manufacturing policies that are transforming the automotive landscape. The IMARC Group forecasts that the Indian electric car market reached USD 963 Million in 2024.
The diesel engine industry is standing at a transformative crossroads. As global markets are pushing for sustainability, stricter emissions compliance, and cutting-edge innovations, diesel powertrains are facing both immense pressure and promising potential.
The global tire market is a multi-billion-dollar industry, driven by the growing demand for vehicles across emerging economies and the replacement tire segment in developed countries. The global tire market is expected to grow at a compound annual growth rate (CAGR) of 4.70% between 2025 and 2033. The industry is heavily influenced by factors such as technological advancements, raw material prices, environmental regulations, and consumer preferences.
Australia's electric vehicle (EV) sector is experiencing swift expansion, fueled by increasing interest in eco-friendly transportation alternatives. In 2024, sales of battery electric and plug-in hybrid vehicles hit an all-time high, totaling around 114,000 units.
The electric bus industry is the part of the transportation sector that deals with the production and installation of buses that run completely or partially on electricity, employing battery packs or fuel cells in place of conventional diesel or gasoline engines. The buses deliver lower greenhouse gas emissions, lesser noise levels, and enhanced energy efficiency, and thus they are a prime solution for environmentally friendly public transport.
India's electric vehicle market is undergoing a profound transformation, impelled by green priorities, economic imperatives, and changing consumer trends. With rising concerns about air pollution and fossil fuel dependence, electric mobility has become a strategic option for India's transport industry. Policy clarity, technology development, and an emerging ecosystem of makers and suppliers are driving this market shift.
The global electric vehicle market size was valued at USD 755 Billion in 2024. The global EV market is rapidly expanding, driven by technological advancements, government incentives, stricter emission regulations, rising fuel costs, extended battery range, growing environmental consciousness, and significant investments in charging and production infrastructure.
Electric Vehicles, or EVs, are vehicles operated partially or wholly by electrical power, generally with rechargeable battery packs as their fuel. In contrast to conventional internal combustion engine cars, EVs emit no tailpipe emissions, making them a cleaner, environmentally friendly transportation choice. EVs comprise Battery Electric Vehicles (BEVs), Plug-in Hybrid Electric Vehicles (PHEVs), and Hybrid Electric Vehicles (HEVs), and are gaining ground in passenger, commercial, and two-wheeler segments owing to developments in battery technology, charging infrastructure, and policy support.
Aluminum alloy wheels are high-performance, lightweight, and durable components widely used in the automotive industry. Their superior strength-to-weight ratio enhances vehicle efficiency, fuel economy, and handling, making them a preferred choice for both passenger and commercial vehicles. Beyond their functional benefits, aluminum alloy wheels contribute to vehicle aesthetics, offering sleek designs and customization options that appeal to consumers. Their corrosion resistance and thermal conductivity further enhance braking performance and longevity. With increasing demand for fuel-efficient and stylish vehicles, aluminum alloy wheels play a crucial role in the global automotive sector, catering to OEMs, aftermarket suppliers, and performance vehicle manufacturers.
A tyre is a crucial component of a vehicle, serving as the outer covering of a wheel. Its main purposes are to support the vehicle's weight, provide traction for movement, and act as a flexible cushion that absorbs shocks from the road. Usually composed of rubber, tires are strengthened with steel and cloth. Tires for cars, trucks, motorbikes, bicycles, and other vehicles have different designs and compositions depending on the vehicle type and its intended usage. To improve stability and grip, they have a tread pattern on the outside.
Electric kick scooters are small, battery-operated personal transportation vehicles intended for short-distance and urban movement. They offer an economical and environmentally responsible substitute for conventional modes of mobility thanks to their electric engine, rechargeable battery, and lightweight frame. The need for sustainable transportation options, traffic congestion, and growing urbanisation have all contributed to their rise in popularity. Electric kick scooters are now the go-to option for last-mile connectivity and personal commuting because to developments in battery technology, connectivity features, and government programs encouraging micro-mobility.
An automotive wiring harness is an organized assembly of electrical wires, connectors, and terminals that transmit power and signals across a vehicle’s electrical system. It guarantees effective communication between several parts, including the engine control unit, lighting, and sensors. Wiring harnesses are intended to increase vehicle performance and safety by lowering the possibility of short circuits. By maximising electrical connectivity and lowering wire complexity, they are utilised in both conventional and electric automobiles and are essential to contemporary automotive technology.
In an automotive braking system, brake pads are the most important parts since they are engineered to contact the brake rotor to produce friction, thus stopping or slowing down a vehicle in virtually any driving condition safely and efficiently. The key way of classifying these pads is according to their material types: low metallic, ceramic, organic, and semi-metallic.
Tires are essential components of vehicles designed to provide traction, support, and absorb road shocks. Primarily made of rubber, tires consist of treads, belts, and sidewalls that work together to offer grip, stability, and durability. Modern tires come in various types – such as all-season, winter, and performance tires – each engineered for specific driving conditions. The two major tire categories are radial and bias tires, and they are available in different sizes to suit various vehicle types, including passenger cars, light commercial vehicles, medium and heavy commercial vehicles, two-wheelers, and off-road vehicles.
Electric Vehicles (EVs) are powered by electric motors instead of traditional internal combustion engines (ICEs). Electric motors propel EVs by utilizing electricity stored in rechargeable batteries or other energy storage systems. They produce lower or zero tailpipe emissions, reduce air pollution and greenhouse gas (GHG) emissions, and help in mitigating climate change. Electric vehicles consist of various components, such as battery cells and packs, reducers, fuel stacks, power control units, power conditioners, air compressors, humidifiers, motors, on-board chargers, battery management systems, and others. EVs are classified into four types based on propulsion, outlined below.
Saudi Arabia is the second-largest producer and exporter of crude oil and holds the second-largest proven oil reserves in the world, with around 267 billion barrels. The country's oil sector is a significant part of its economy, accounting for 75% of government revenue and approximately 90% of exports. However, due to the volatility of oil prices and the potential for economic instability, Saudi Arabia is increasingly focusing on non-oil activities to reduce its dependency on the oil sector. Non-oil commodities tend to have more stable prices, providing protection against these fluctuations and strengthening the country's social, economic, and financial sectors.