Germany Battery Recycling Industry: Regulation, Government Schemes, Demand and Investment Area
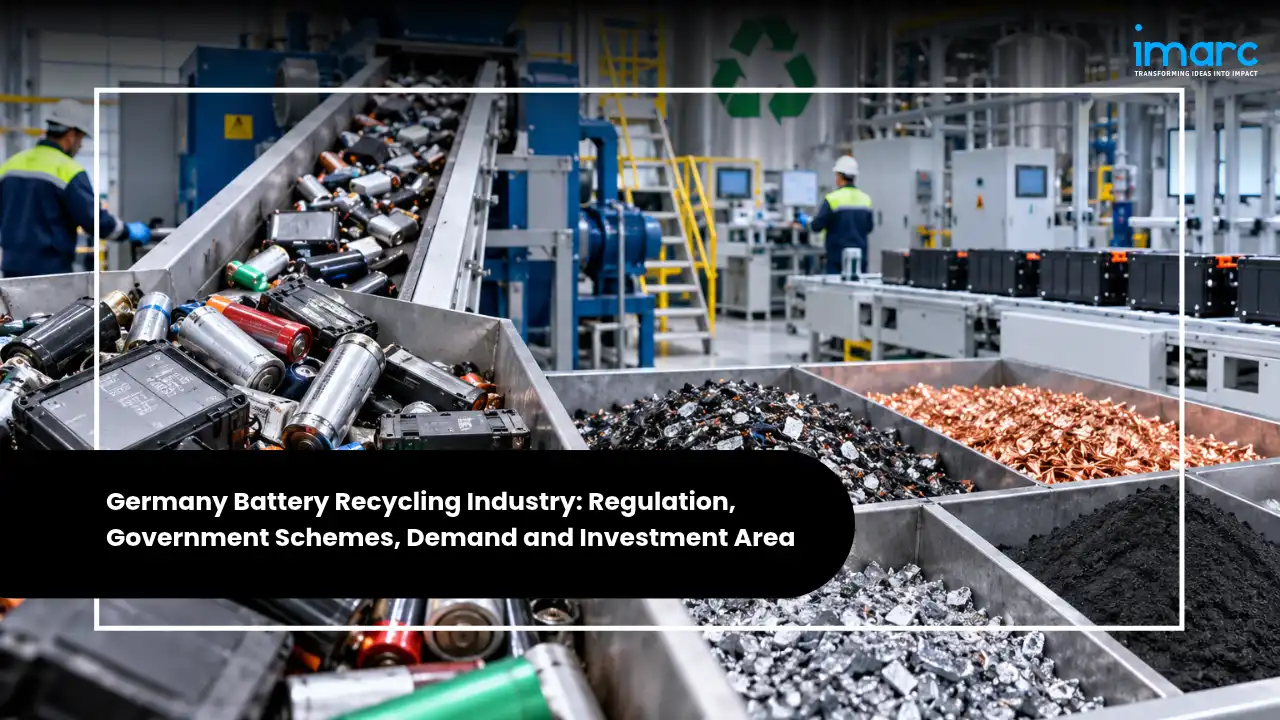
Introduction: Germany's Battery Recycling Industry Moves From Compliance to Closed-Loop Supply
The Germany Battery Recycling Industry sits where Europe's largest automotive manufacturing base meets its most demanding battery regulation. According to IMARC Group, the market reached USD 814.3 Million in 2025 and is projected to reach USD 1,617.0 Million by 2034, expanding at a CAGR of 7.68% during 2026–2034. The legal anchor is Regulation (EU) 2023/1542, the EU Battery Regulation. It has applied since 18 February 2024 and sets collection targets, minimum recycling efficiencies, material recovery rates and recycled-content thresholds. Germany implements it through the Batterierecht-Durchführungsgesetz (BattDG), which replaced the long-standing Battery Act (BattG). The reason investors and regulators are paying attention is feedstock: the country combines large vehicle output, a dense base of cell and component makers, and growing stationary storage, so it generates both end-of-life batteries and production scrap.
The drivers on the demand side are structural. Electric vehicle batteries put on the road in recent years will return for recycling over the coming decade, while scrap from cell and module production and from industrial storage already provides steady volumes. Automotive manufacturers want recycled lithium, cobalt and nickel to meet future recycled-content obligations and to reduce import dependence. On the supply side, the EU Critical Raw Materials Act (Regulation (EU) 2024/1252) sets a 2030 benchmark of 25% of annual EU consumption of strategic raw materials coming from recycling. It also caps dependence on any single third country at 65%. At national level, the federal government has backed a Raw Materials Fund of up to EUR 1 billion, managed by KfW, to de-risk raw material projects.
The main market insights concern segmentation and geography. Lead-acid recycling is a mature, closed-loop business, while lithium-ion is the segment where new capacity, new processes and new capital are concentrated. Automotive sources dominate the growth narrative, and activity clusters in Lower Saxony, Brandenburg, Baden-Württemberg and North Rhine-Westphalia. The defining theme for 2026 is the move from collecting, dismantling and exporting black mass towards domestic refining that returns battery-grade materials to German cell and vehicle makers.
This blog examines the Germany Battery Recycling Industry's size and segments, recent announcements, trends shaping 2026, geographic hotspots, competitive landscape, policy and regulatory environment, forecast through 2034, and the opportunities available to recyclers, investors, technology providers and automotive and battery manufacturers.
Key Takeaways
- The Germany Battery Recycling Industry reached USD 814.3 Million in 2025 and is forecast to reach USD 1,617.0 Million by 2034, nearly doubling at a CAGR of 7.68% (2026–2034).
- Activity is concentrated in industrial and automotive regions, notably Lower Saxony, Brandenburg, Baden-Württemberg and North Rhine-Westphalia, where recyclers sit close to vehicle plants, cell producers and chemical sites.
- The EU Battery Regulation (EU) 2023/1542 requires minimum recycled content in new batteries from 18 August 2031, including 16% cobalt, 6% lithium and 6% nickel, and mandates a digital battery passport from 18 February 2027 for EV and larger industrial batteries.
- In October 2024, Mercedes-Benz opened its in-house battery recycling plant in Kuppenheim, targeting a material recovery rate above 96%, a sign that closed-loop recycling is moving inside OEM supply chains.
Germany Battery Recycling Industry Size, Share & Growth Outlook
Growth is driven by a change in what is being recycled. Mature lead-acid streams provide a stable base, while lithium-ion volumes, production scrap and storage batteries lift the value of the market. The market is best read through these dimensions:
- By Battery Material Type: Lithium-ion batteries form the long-established base, supported by a mature collection and smelting chain. Lithium-ion batteries are the fastest-growing segment, and nickel-based batteries and other chemistries complete the mix.
- By Source: Automotive batteries, covering starter batteries and increasingly traction batteries, are the main volume and growth source. Industrial batteries and consumer electronics batteries make up the other streams, with portable batteries collected through retail and municipal take-back.
- By Region: Battery recycling by region in Western Germany, Southern Germany, Eastern Germany, Northern Germany, close to feedstock, chemical infrastructure and export logistics.
Recent News & Mega Announcements
Recent developments in the Germany Battery Recycling Industry include significant regulatory milestones, investments and industrial openings:
- In July 2025, the European Union adopted a one-year postponement of the battery due diligence obligations under the Battery Regulation to 18 August 2027, leaving the collection, recycling efficiency, material recovery and recycled-content rules unchanged.
- In March 2025, the European Commission selected its first 47 strategic projects under the Critical Raw Materials Act across 13 Member States, covering extraction, processing, recycling and substitution and giving selected projects faster permitting and easier access to finance.
- In January 2025, Germany's Batterierecht-Durchführungsgesetz (BattDG) took effect as the national implementing law for the EU Battery Regulation, replacing the earlier Battery Act and setting out producer registration, take-back and enforcement duties.
- In October 2024, Mercedes-Benz opened its in-house battery recycling plant in Kuppenheim, Baden-Württemberg, using a mechanical and hydrometallurgical process designed for a material recovery rate of more than 96%, with recovered materials intended for new cells.
- In May 2024, the EU Critical Raw Materials Act (Regulation (EU) 2024/1252) entered into force, setting a 2030 benchmark of 25% of annual EU consumption of strategic raw materials from recycling.
Together, these developments show a market moving from regulatory preparation to physical capacity. Binding rules are now fixed through the early 2030s, and OEMs are building their own recycling loops.
Industry Trends Shaping 2026
Three trends are shaping the Germany Battery Recycling Industry in 2026:
1. Closed-Loop Recycling Moves Inside OEMs
Automakers are bringing recycling in-house. Mercedes-Benz opened its Kuppenheim plant in October 2024 with a recovery target above 96%. Volkswagen has run a pilot recycling plant at Salzgitter since January 2021, targeting recovery of more than 90% of raw materials. Both aim to feed recovered metals back into new cells, a model that anticipates the EU's recycled-content thresholds from 18 August 2031.
2. Hydrometallurgy and Mechanical-First Processes Scale Up
Germany's technology base is shifting towards low-temperature processing. Duesenfeld uses a vacuum-based mechanical process, Cylib is developing hydrometallurgical recycling for an industrial plant at Dormagen, and BASF has built a black mass plant at Schwarzheide. Lithium recovery is the commercial focus, since the Battery Regulation requires 50% lithium recovery by 2027, rising to 80% by 2031, alongside 90% for cobalt and nickel by 2027.
3. Battery Passport and Recycled-Content Rules Take Hold
Traceability is becoming a market feature. The EU Battery Regulation requires a digital battery passport for EV and larger industrial batteries from 18 February 2027, giving recyclers chemistry and composition data. Minimum recycled content then applies from 18 August 2031: 16% cobalt, 85% lead, 6% lithium and 6% nickel, rising in the 2036 step to 26% cobalt, 12% lithium and 15% nickel. Recyclers that can certify origin and purity will earn contracts.
Geographic Hotspots
Lower Saxony is the traditional centre of metals and battery recycling. Salzgitter hosts Volkswagen's recycling pilot and the group's cell-manufacturing ambitions, while the Harz region around Goslar and Wendeburg has long metallurgical and mechanical processing experience. The state offers feedstock from automotive supply chainsand a dense network of dismantlers, scrap processors and metallurgical sites, and it is close to export ports.
Brandenburg is rising as a cell-production and processing corridor. BASF's black mass plant at Schwarzheide serves nearby cathode-materials and cell activity, and the region's industrial land and energy availability attract new refining projects.
Baden-Württemberg combines OEM and tier-one demand with in-house recycling. Mercedes-Benz's Kuppenheim plant and the Primobius process partnership around Hilchenbach show how vehicle makers and technology developers work together to secure recovered materials.
North Rhine-Westphalia has chemical-industry infrastructure, specialist metallurgical recyclers such as Accurec in Krefeld, and new hydrometallurgical projects such as Cylib's planned plant at Dormagen. Bremen and Hamburg act as logistics gateways for imported scrap, exported black mass and shipped metals, and Bremerhaven is home to Redux Recycling.
Competitive Landscape
The competitive landscape is shaped by a combination of established industry participants, emerging businesses, and specialized providers, with competition influenced by product quality, innovation, pricing strategies, distribution capabilities, and customer service. Market participants focus on strengthening their market presence by enhancing product offerings, improving operational efficiency, expanding distribution networks, and adapting to evolving consumer preferences. Technological advancements, changing purchasing behaviour, regulatory developments, and shifting industry requirements also influence competitive strategies. As market conditions evolve, businesses increasingly emphasize differentiation, value creation, and customer-centric approaches to sustain competitiveness and capitalize on emerging growth opportunities.
Policy & Regulatory Environment
The policy framework is among the most detailed in the world and is largely fixed through the early 2030s.
- EU Battery Regulation (EU) 2023/1542: Applies since 18 February 2024. It sets collection targets for portable batteries of 63% by end-2027 and 73% by end-2030, and for light means of transport batteries of 51% by end-2028 and 61% by end-2031. Minimum recycling efficiencies are 65% (2025) and 70% (2030) for lithium-based batteries and 80% (2025) and 85% (2030) for lead-acid batteries.
- Material recovery targets: 90% for cobalt, copper, lead and nickel by 2027, rising to 95% by 2031, and 50% for lithium by 2027, rising to 80% by 2031.
- Batterierecht-Durchführungsgesetz (BattDG): Germany's national implementing law, which replaced the Battery Act, assigns producer registration, take-back and enforcement duties and keeps extended producer responsibility at the centre of the system.
- Critical Raw Materials Act (Regulation (EU) 2024/1252): Sets a 2030 benchmark of 25% of EU consumption of strategic raw materials from recycling and offers faster permitting for strategic projects.
- National financing: The federal Raw Materials Fund, managed by KfW with up to EUR 1 billion, is intended to reduce risk for raw material projects, including recycling.
The main compliance risk lies in timing: due diligence obligations are postponed to 18 August 2027, but recovery, passport and recycled-content rules remain on schedule.
Forecast 2026–2034
IMARC Group projects the Germany Battery Recycling Industry to grow from USD 814.3 Million in 2025 to USD 1,617.0 Million by 2034, a CAGR of 7.68% during 2026–2034. Growth is expected to build gradually. Early years are supported by production scrap, storage batteries and lead-acid volumes, while the second half of the period benefits from rising volumes of end-of-life EV traction batteries and the enforcement of recycled-content thresholds from 2031.
Key variables include EV adoption pace, metal prices (particularly lithium, cobalt and nickel), the success of domestic refining projects, energy costs and the share of black mass that continues to be exported. Policy clarity is a tailwind, while competition from Asian refiners and OEM in-house plants may shape the addressable market for independent recyclers.
Investment Opportunities
Opportunities in the Germany Battery Recycling Industry span the value chain:
- Domestic hydrometallurgical refining: Capacity that turns black mass into battery-grade lithium, nickel, cobalt and manganese salts is the most strategic gap, supported by recovery targets and the Critical Raw Materials Act.
- Pre-treatment and logistics: Safe collection, storage, transport and discharge of damaged lithium-ion batteries is a specialist service with growing demand.
- Technology licensing and process equipment: Mechanical, low-energy and direct-recycling technologies can be licensed to recyclers and OEMs.
- Data and traceability services: Battery passport compliance, state-of-health diagnostics and material certification create software and service revenue.
- Second-life and repurposing: Stationary storage using retired EV packs extends value before recycling.
- Partnerships with OEMs and cell makers: Offtake and feedstock agreements reduce risk for new plants and secure recycled-content supply.
Conclusion
The Germany Battery Recycling Industry is entering a phase in which regulation, feedstock and industrial strategy align. With a market of USD 814.3 Million in 2025 heading towards USD 1,617.0 Million by 2034, at a 7.68% CAGR, the sector offers steady growth anchored in binding EU rules and Germany's automotive and battery manufacturing base. Success will depend on securing feedstock, reaching battery-grade output, and certifying recycled content for customers. Companies that invest in domestic refining, partnerships and traceability are best placed to capture value as the first large wave of end-of-life EV batteries arrives.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Electric cars are the fastest-growing part of India's passenger vehicle market. Sales roughly doubled in 2025-26, about 6% of new cars sold in the first seven months of 2026 were electric, and more than a dozen models from Indian and global brands now compete across hatchbacks, sedans, and SUVs.
Every electric vehicle needs a charger, and as India's EV fleet grows, so does demand for the equipment that powers it. India registered more than 2.3 million EVs in 2025, public charging stations grew from about 5,000 in 2022 to more than 27,000 by March 2026, and the PM E-DRIVE scheme is funding 72,300 more public chargers by 2028.
Electric vehicles are moving from early adoption to the mainstream in India. Nearly 19 lakh EVs were registered in the first seven months of 2026, and in some segments the shift is already well advanced: more than four in ten new passenger three-wheelers sold in 2026 were electric, while electric two-wheelers, cars, buses, and light commercial vehicles are all gaining share.
Every function in a modern vehicle that moves, from a brake caliper to an air-conditioning flap, depends on an actuator that turns an electronic command into physical motion. The global automotive actuators market size was valued at USD 31.1 Billion in 2025 and is forecast to reach USD 47.3 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 4.62% during 2026–2034, according to IMARC Group.
India is the world's largest two-wheeler market, and it is steadily going electric. Electric scooters, motorcycles, and mopeds offer running costs far below petrol models, suit short urban commutes and delivery work, and are central to the country's clean mobility goals.
Electric bicycles, or e-bikes, combine a conventional bicycle with a small electric motor, a lithium-ion battery, and a controller that assists the rider's pedalling. In India, models limited to 250 watts and 25 km/h do not need registration or a driving license, cost a few paise per kilometre to run, and suit short commutes, fitness riding, students, and last-mile delivery.
Walk into a modern Indian car parts plant, pharmaceutical packing line, or electronics factory and you will see robots welding and palletising, conveyors moving parts between stations, vision cameras checking quality, and control panels coordinating it all.
Tyres are essential to every vehicle on India's roads, from two-wheelers and three-wheelers to cars, buses, trucks, tractors, and off-highway machines.
If the battery is the heart of an electric vehicle, the wiring harness is its nervous system. Every EV needs low-voltage harnesses for lights, sensors, and controls, plus high-voltage harnesses that carry hundreds of volts and high currents between the battery, inverter, motor, and charging port, and dedicated harnesses inside the battery pack that monitor every cell.
Every electric vehicle needs a brain between the battery and the motor. The motor controller, often called the traction inverter in larger vehicles, converts DC power from the battery into precisely controlled AC power for the motor, manages acceleration, regenerative braking, and efficiency, and protects the whole powertrain from faults.
Every vehicle on the road depends on forged parts. Crankshafts, connecting rods, steering knuckles, axle beams, gears, and hubs are forged because the process gives steel a continuous grain flow and the strength to survive millions of load cycles.
Setting up an Automotive Components Manufacturing Plant in India is a high-potential, export-capable venture, powered by the country's large automobile industry, deep supplier base, and growing role as a global sourcing hub for auto parts.
The global automotive lead-acid battery market reached USD 13.89 Billion in 2025 and is projected to reach USD 16.60 Billion by 2034, growing at a CAGR of 1.94% (2026–2034).
Setting up an Electric Scooter Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's rapid shift to electric mobility, supportive EV policies, and surging demand for affordable, clean urban transport. As two-wheelers dominate Indian roads and buyers move from petrol to battery-powered scooter manufacturing, an EV Scooter Manufacturing Plant is one of the most accessible and strategically timed entry points into the electric vehicle economy.
Capital is flowing into the united states used car market because structural affordability pressure, digital retail maturity, and a record-old national vehicle fleet have converged into a genuinely investable thesis.
The Europe Tire Market reached a volume of 458.89 Million Units in 2025 and is projected to reach 565.69 Million Units by 2034, growing at a CAGR of 2.35% (2026–2034).
A strategic analysis of how PLI policies and localization drive global OEM investments. India’s EV battery market hits USD 15,898.31 Million by 2034 (21.7% CAGR).
A tyre is circular in shape and made of a combination of rubber materials that fit perfectly over a circular rim on a wheel, providing traction, load-carrying capabilities, shock absorption, and directional stability. As such, tyres are engineered materials composed of a combination of natural or synthetic materials. They are composed of a combination of materials such as rubber, a combination of materials such as steel or textile, and various chemical materials, among others.
A tractor is a self-propelled, torque-requiring vehicle intended primarily for pulling power at low speeds for agricultural, industrial, and utility purposes. It functions as a mobile power source that can be used for towing, pushing, lifting, or driving a variety of agricultural implements through mechanical, hydraulic, or power take-off systems. Tractors are designed with powerful propulsion systems, sturdy frames, and versatile coupling systems for use on different terrains and under heavy loads.
The electric boat and ship market size is experiencing unparalleled growth as the marine industry embraces electrification on a large scale across different geographies. As sustainability is becoming a strategic priority, with each passing day, more and more marine operators look to electric propulsion technologies as alternatives aimed at cutting down emissions, improving operational efficiencies, and enabling greener ports.
The GCC car rental market has emerged as a critical component of the region's transportation ecosystem, driven by robust tourism activity, expanding business travel, and a substantial expatriate population. Countries across the Gulf Cooperation Council are witnessing unprecedented demand for flexible mobility solutions that cater to diverse customer segments. The GCC car rental market size was valued at USD 1.65 Billion in 2024 as governments prioritize infrastructure development and sustainable tourism initiatives.
The Indian automotive sector has formed a vital part of the country's industrial and economic development for a long period. Over the years, the industry has transformed significantly, influenced by changes in technology, global trends, and consumer preference. Among the various factors shaping its trajectory, government policies have emerged as a decisive force driving growth, innovation, and competitiveness in the India auto parts manufacturing industry.
The India motorcycle tires market continues to evolve in response to changing mobility preferences, rising urbanization, and the growing significance of two-wheelers as essential transportation assets for millions of riders. As per sources, the India motorcycle tires market size reached USD 933.66 Million in 2024. The market is projected to reach USD 2,419.36 Million by 2033, exhibiting a growth rate (CAGR) of 10.3% during 2025-2033.
The Saudi Arabia tire market is undergoing a significant transformation driven by the nation’s economic diversification, rapid urbanization, and growing vehicle ownership. As one of the largest automotive hubs in the Middle East, Saudi Arabia is witnessing increasing demand for both passenger and commercial vehicle tires across urban and industrial regions.
One of the world's most dynamic and quickly changing markets, India's automotive industry is undergoing revolutionary changes in both the new and used car markets. Despite general economic uncertainty, the used car industry has shown remarkable resilience and growth potential, making it a particularly vibrant part of this ecosystem.
One of the world's most vibrant and quickly growing automobile markets is India's passenger car sector. From technological innovation to economic development, a number of interrelated factors have contributed to the sector's remarkable transformation. For stakeholders looking to take advantage of the enormous opportunities in this dynamic market, it is imperative that they comprehend these growth drivers.
India's truck industry is at a turning point in its development, driven by extensive government policies that are changing the commercial vehicle market. The industry, which is the foundation of the country's logistics ecosystem, is gaining previously unheard-of momentum thanks to smart regulatory frameworks and forward-thinking legislative initiatives. A fundamental change in truck operations on Indian highways is being sparked by government initiatives ranging from infrastructure development to emission standards, digitalization, and financial incentives.
The electric rickshaw sector in India has experienced a significant upheaval in recent years and is now a vital part of the country's sustainable transportation network. Strategic government policies aimed at hastening the adoption of clean mobility solutions have played a major role in orchestrating this evolution. India's larger vision of sustainable urbanization is in line with the electric rickshaw industry, which combines social development objectives, economic opportunities, and environmental imperatives.
Transportation in India is undergoing a spectacular change with the advent of electric two-wheelers that are quite an enticing alternative to traditional fuel-powered ones. This change is not merely an act of technological transformation, but an indication of how millions of Indians will think about city mobility, eco-awareness, and economic effectiveness.
As one of the world's leading industrial powerhouses, Japan has long been recognized for its commitment to technological innovation and manufacturing precision. The industry for industrial automation components—encompassing sensors, controllers, actuators, drives, robotics, and human-machine interfaces—represents the backbone of modern manufacturing infrastructure.
The Australian brakes and clutches industry plays a vital role in ensuring vehicle performance, safety, and efficiency across both automotive and industrial segments. As the nation transitions toward electric mobility and smarter manufacturing systems, the demand for advanced braking and clutch mechanisms is rising significantly.
The Philippines automotive wiring harness industry stands at a transformative juncture, driven by technological innovations that are reshaping vehicle electrical architectures worldwide. As vehicles evolve into sophisticated mobile computing platforms, the wiring harness, the circulatory system transmitting electrical power and data throughout modern automobiles, has become increasingly complex and critical to vehicle performance.
Japan's hybrid vehicles market stands as a global benchmark for sustainable mobility innovation, demonstrating remarkable growth and technological leadership. The market achieved a valuation of USD 33.57 Billion in 2024. Japan's hybrid vehicle (HV) market is one of the most established globally, originating with pioneering models like the Toyota Prius. It currently represents a significant portion of the country's automotive sales.
The Japan warehouse robotics market is a highly dynamic and rapidly expanding segment of the global automation industry. The market, valued at USD 414.0 Million in 2024, is on a sharp growth trajectory. Its growth is fueled by critical domestic factors, including a severe labor shortage, the rapid expansion of e-commerce, and Japan's strategic position as a world-leading robotics manufacturer.
The UK is rapidly evolving into a dynamic hub for autonomous vehicle research, testing, and early-stage deployments. A strong ecosystem comprising academic institutions, technology start-ups, automakers, and mobility service providers fosters continuous innovation. Supported by a skilled workforce specializing in software, sensing, robotics, and transportation systems, the nation has become a fertile ground for experimentation.
Japan’s transportation landscape is on the brink of a major shift, with robo taxis, autonomous, driverless vehicles designed for passenger and goods transport, emerging as a practical mobility solution. The Japan robo taxi market reached USD 83.2 Million in 2024 . This remarkable expansion reflects Japan’s broader move toward smart mobility, sustainability, and automation.
The Japan electric truck market is experiencing transformative growth as the nation accelerates toward sustainable transportation and carbon neutrality. As a leading automotive manufacturing hub, Japan is witnessing unprecedented momentum in commercial vehicle electrification, driven by stringent environmental regulations, technological innovation, and strategic government support. The electric truck industry represents a critical component of Japan's commitment to achieving 100% electrified vehicle sales by 2035 and carbon neutrality by 2050.
An EV charging station represents the necessary main infrastructure that allows electrical energy to be transferred from the power grid into electric vehicles to enable their use for transportation. Unlike conventional fueling stations that offer liquid fuels, EV charging stations provide electric power through the use of standardized connectors and smart control systems. The core components include a power conversion unit, which transforms alternating current from the grid into direct current for the vehicle battery; a charging controller controlling communication between the charger and the EV; and a connector or plug matched to the vehicle's charging interface.
An electric scooter is a two-wheeled vehicle powered by an electric motor and rechargeable battery, aimed at offering the means for efficient, eco-friendly, and cost-effective urban mobility. Apart from the traditional scooters that are powered by internal combustion engines, the electric scooters make use of lithium-ion or lead-acid batteries that feed an electric supply to a BLDC motor, which drives the wheels either directly or via a belt or chain mechanism.
Electric bikes, commonly referred to as e-bikes, are one of the most transformational innovations in modern personal mobility, combining conventional bicycle mechanics with advanced electric propulsion technology. At the heart of e-bikes are an electric motor, a rechargeable battery, and a control system that add assistance to the rider while pedaling, making cycling easier, faster, and more accessible across varied terrains. Based on their design, they can be further categorized into pedal-assist, throttle-controlled, or hybrid models, each providing different levels of rider control and engagement of the motor.
The micro-mobility industry has emerged as a transformative force in urban transportation, revolutionizing how people navigate cities worldwide. According to IMARC, the global micro-mobility market size was valued at USD 63.10 Billion in 2024. Looking forward, IMARC Group estimates the market to reach USD 204.83 Billion by 2033, exhibiting a CAGR of 12.86% from 2025-2033.
India's electric vehicle (EV) revolution is accelerating at a breakneck speed, powered by a strategic combination of government incentives, infrastructure investments, and manufacturing policies that are transforming the automotive landscape. The IMARC Group forecasts that the Indian electric car market reached USD 963 Million in 2024.
The diesel engine industry is standing at a transformative crossroads. As global markets are pushing for sustainability, stricter emissions compliance, and cutting-edge innovations, diesel powertrains are facing both immense pressure and promising potential.
The global tire market is a multi-billion-dollar industry, driven by the growing demand for vehicles across emerging economies and the replacement tire segment in developed countries. The global tire market is expected to grow at a compound annual growth rate (CAGR) of 4.70% between 2025 and 2033. The industry is heavily influenced by factors such as technological advancements, raw material prices, environmental regulations, and consumer preferences.
Australia's electric vehicle (EV) sector is experiencing swift expansion, fueled by increasing interest in eco-friendly transportation alternatives. In 2024, sales of battery electric and plug-in hybrid vehicles hit an all-time high, totaling around 114,000 units.
The electric bus industry is the part of the transportation sector that deals with the production and installation of buses that run completely or partially on electricity, employing battery packs or fuel cells in place of conventional diesel or gasoline engines. The buses deliver lower greenhouse gas emissions, lesser noise levels, and enhanced energy efficiency, and thus they are a prime solution for environmentally friendly public transport.
India's electric vehicle market is undergoing a profound transformation, impelled by green priorities, economic imperatives, and changing consumer trends. With rising concerns about air pollution and fossil fuel dependence, electric mobility has become a strategic option for India's transport industry. Policy clarity, technology development, and an emerging ecosystem of makers and suppliers are driving this market shift.
The global electric vehicle market size was valued at USD 755 Billion in 2024. The global EV market is rapidly expanding, driven by technological advancements, government incentives, stricter emission regulations, rising fuel costs, extended battery range, growing environmental consciousness, and significant investments in charging and production infrastructure.
Electric Vehicles, or EVs, are vehicles operated partially or wholly by electrical power, generally with rechargeable battery packs as their fuel. In contrast to conventional internal combustion engine cars, EVs emit no tailpipe emissions, making them a cleaner, environmentally friendly transportation choice. EVs comprise Battery Electric Vehicles (BEVs), Plug-in Hybrid Electric Vehicles (PHEVs), and Hybrid Electric Vehicles (HEVs), and are gaining ground in passenger, commercial, and two-wheeler segments owing to developments in battery technology, charging infrastructure, and policy support.
Aluminum alloy wheels are high-performance, lightweight, and durable components widely used in the automotive industry. Their superior strength-to-weight ratio enhances vehicle efficiency, fuel economy, and handling, making them a preferred choice for both passenger and commercial vehicles. Beyond their functional benefits, aluminum alloy wheels contribute to vehicle aesthetics, offering sleek designs and customization options that appeal to consumers. Their corrosion resistance and thermal conductivity further enhance braking performance and longevity. With increasing demand for fuel-efficient and stylish vehicles, aluminum alloy wheels play a crucial role in the global automotive sector, catering to OEMs, aftermarket suppliers, and performance vehicle manufacturers.
A tyre is a crucial component of a vehicle, serving as the outer covering of a wheel. Its main purposes are to support the vehicle's weight, provide traction for movement, and act as a flexible cushion that absorbs shocks from the road. Usually composed of rubber, tires are strengthened with steel and cloth. Tires for cars, trucks, motorbikes, bicycles, and other vehicles have different designs and compositions depending on the vehicle type and its intended usage. To improve stability and grip, they have a tread pattern on the outside.
Electric kick scooters are small, battery-operated personal transportation vehicles intended for short-distance and urban movement. They offer an economical and environmentally responsible substitute for conventional modes of mobility thanks to their electric engine, rechargeable battery, and lightweight frame. The need for sustainable transportation options, traffic congestion, and growing urbanisation have all contributed to their rise in popularity. Electric kick scooters are now the go-to option for last-mile connectivity and personal commuting because to developments in battery technology, connectivity features, and government programs encouraging micro-mobility.
An automotive wiring harness is an organized assembly of electrical wires, connectors, and terminals that transmit power and signals across a vehicle’s electrical system. It guarantees effective communication between several parts, including the engine control unit, lighting, and sensors. Wiring harnesses are intended to increase vehicle performance and safety by lowering the possibility of short circuits. By maximising electrical connectivity and lowering wire complexity, they are utilised in both conventional and electric automobiles and are essential to contemporary automotive technology.
In an automotive braking system, brake pads are the most important parts since they are engineered to contact the brake rotor to produce friction, thus stopping or slowing down a vehicle in virtually any driving condition safely and efficiently. The key way of classifying these pads is according to their material types: low metallic, ceramic, organic, and semi-metallic.
Tires are essential components of vehicles designed to provide traction, support, and absorb road shocks. Primarily made of rubber, tires consist of treads, belts, and sidewalls that work together to offer grip, stability, and durability. Modern tires come in various types – such as all-season, winter, and performance tires – each engineered for specific driving conditions. The two major tire categories are radial and bias tires, and they are available in different sizes to suit various vehicle types, including passenger cars, light commercial vehicles, medium and heavy commercial vehicles, two-wheelers, and off-road vehicles.
Electric Vehicles (EVs) are powered by electric motors instead of traditional internal combustion engines (ICEs). Electric motors propel EVs by utilizing electricity stored in rechargeable batteries or other energy storage systems. They produce lower or zero tailpipe emissions, reduce air pollution and greenhouse gas (GHG) emissions, and help in mitigating climate change. Electric vehicles consist of various components, such as battery cells and packs, reducers, fuel stacks, power control units, power conditioners, air compressors, humidifiers, motors, on-board chargers, battery management systems, and others. EVs are classified into four types based on propulsion, outlined below.
Saudi Arabia is the second-largest producer and exporter of crude oil and holds the second-largest proven oil reserves in the world, with around 267 billion barrels. The country's oil sector is a significant part of its economy, accounting for 75% of government revenue and approximately 90% of exports. However, due to the volatility of oil prices and the potential for economic instability, Saudi Arabia is increasingly focusing on non-oil activities to reduce its dependency on the oil sector. Non-oil commodities tend to have more stable prices, providing protection against these fluctuations and strengthening the country's social, economic, and financial sectors.