Why Modular Construction Could Become a Key Solution for Japan's Future Building Needs
Introduction: Japan's Off-Site Building Shift
Japan's construction industry is at an inflection point, and the Japan modular construction market sits at the centre of the response. According to IMARC Group, the Japan modular construction market size increased from USD 18.11 Billion in 2025 to USD 18.85 Billion in 2026 and is projected to reach USD 29.27 Billion by 2034, growing at a compound annual growth rate of 5.65% from 2026 to 2034.
The expansion is being driven by structural pressures rather than a temporary surge in demand. Japan's construction workforce is shrinking as experienced tradespeople retire and fewer young workers enter site-based occupations, which raises the cost, schedule risk and safety exposure of conventional building. Urbanisation continues to concentrate population in metropolitan areas where land is scarce and delivery windows are tight. At the same time, the country's exposure to earthquakes and extreme weather sustains demand for structures that can be engineered to precise seismic specifications in a factory and then erected quickly on site.
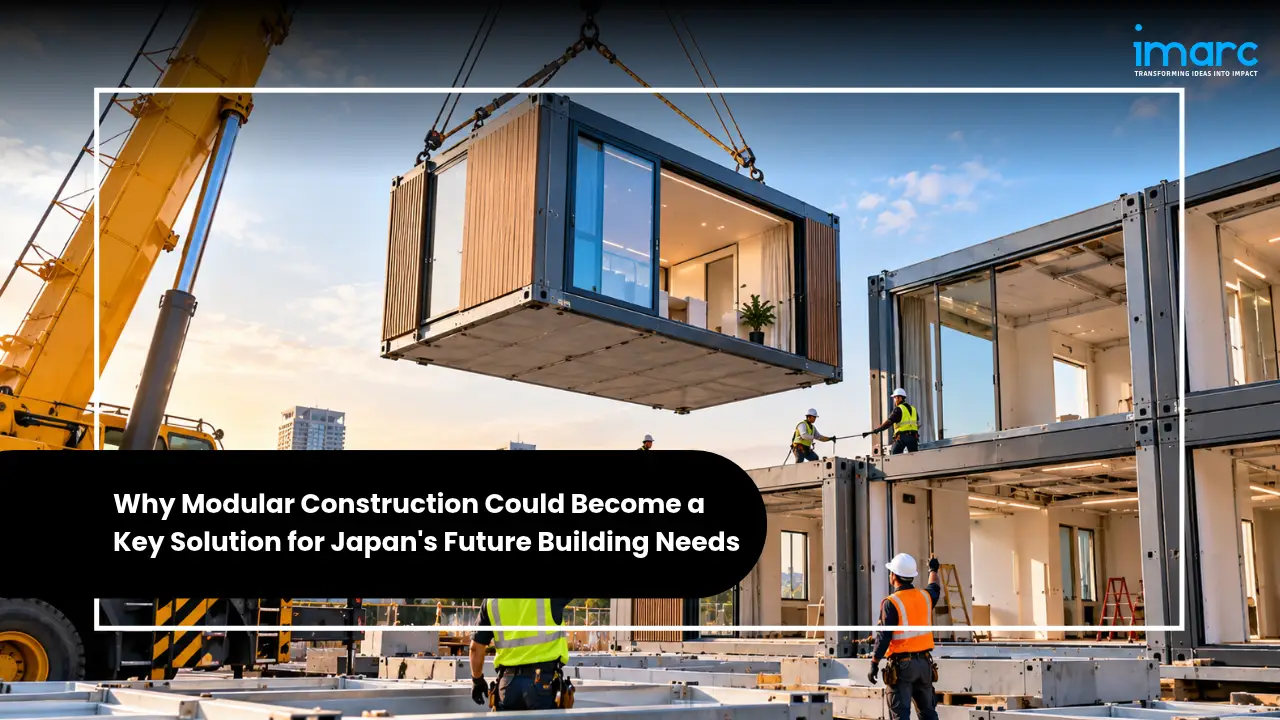
The defining trend is the integration of building information modelling and digital twin technology into off-site manufacturing. The Ministry of Land, Infrastructure, Transport and Tourism has pushed BIM into mainstream public works delivery, giving modular producers a shared digital language for design, simulation and quality control before production begins. Daiwa House, Japan's largest homebuilder, operates industrialised lines in which individual components are fabricated to specification and then assembled on site, a model it has carried into Europe through Daiwa House Modular Europe.
This blog examines the market size and segmentation of the Japan modular construction market, the developments that shaped 2025 and 2026, the industry trends behind the shift to off-site delivery, the regional hotspots, the competitive and policy landscape, and the opportunities open to developers, manufacturers, material suppliers and investors.
Key Takeaways
- Market size and growth: The Japan modular construction market stood at USD 18.11 Billion in 2025, is expected to reach USD 18.85 Billion in 2026, and is forecast to touch USD 29.27 Billion by 2034, growing at a CAGR of 5.65% over 2026 to 2034.
- Leading type segment: Permanent modular construction accounts for a 58.4% share of the market in 2025, reflecting demand for long-life, fixed-location residential and commercial structures that satisfy Japan's seismic and energy performance rules.
- Leading region: The Kanto Region holds a 38.5% share in 2025, supported by Tokyo's population density, large-scale development activity and early adoption of BIM and net-zero construction standards.
- Notable recent development: The rebuilding programme that followed the January 2024 Noto Peninsula earthquake relied heavily on prefabricated housing, with 6,882 temporary housing units scheduled for completion by the end of 2024, demonstrating modular delivery at emergency scale.
- Key trend: The integration of building information modelling and digital twin workflows into factory production is compressing delivery timelines, cutting rework and reducing material waste across the Japan modular construction industry.
Market Size, Share & Growth Outlook
According to IMARC Group, the Japan modular construction market size increased from USD 18.11 Billion in 2025 to USD 18.85 Billion in 2026 and is projected to reach USD 29.27 Billion by 2034, growing at a compound annual growth rate of 5.65% during 2026-2034. That trajectory matters because Japan's overall construction sector is mature and labour constrained; growth of this scale therefore points to a shift in delivery method rather than simple volume growth. The leading segments are:
- Type: Permanent modular construction leads with a 58.4% share in 2025. These are factory-built structures designed for long-term, fixed-location use. They dominate because Japanese building regulations demand high seismic resistance, energy efficiency and structural durability, all of which are easier to guarantee inside a controlled manufacturing environment than on a variable construction site. Permanent systems also allow seismic isolation, barrier-free layouts and integrated mechanical services to be built into modules before they leave the factory. Re-locatable units account for the balance of the type split, serving construction camps, temporary offices, disaster response and short-cycle commercial needs.
- Material: Wood is the leading material with a 42.3% share in 2025, ahead of steel, concrete and others. Wood's position rests on Japan's long timber-building tradition, an established prefabricated wood housing industry, and the rising use of cross-laminated timber and glulam panels, which combine a high strength-to-weight ratio and strong seismic performance with much lower embodied carbon than concrete or steel.
- End User: Residential is the largest end-user segment with a 45.6% share in 2025. Demand is anchored in affordable, space-efficient housing for an ageing population, densification pressure in metropolitan areas and the difficulty of recruiting on-site trades. Commercial and industrial applications make up the remainder and are gaining ground as mid-rise mass timber systems prove their fire resistance and acoustic performance.
- Region: The Kanto Region accounts for 38.5% of the market in 2025, the largest regional share. Tokyo's density, the scale of infrastructure and residential development across the metropolitan corridor, and earlier adoption of BIM and net-zero building standards explain the lead. Other regions hold smaller shares and are covered in the Geographic Hotspots section below.
Taken together, these shares describe a market anchored in permanent, wood-based residential construction, with the Kanto metropolitan corridor as its commercial centre of gravity.
Recent News & Mega Announcements
The 2023 to 2025 period produced several developments that clarify how quickly off-site delivery is moving from a niche method to a mainstream one in Japan.
- BIM becomes standard practice in public works (2023 onward): The Ministry of Land, Infrastructure, Transport and Tourism has applied BIM/CIM to public works projects as a general principle from fiscal year 2023, with small-scale projects exempted. Public procurement is where design standards are effectively set, so standardised digital models lower the cost of producing factory-built components to a common specification and make modular tendering more predictable for contractors.
- Noto Peninsula earthquake reconstruction (January 2024 to December 2025): The earthquake that struck Ishikawa Prefecture on 1 January 2024 triggered one of the largest rapid housing deployments in recent Japanese history. The Ishikawa Prefectural Government built around 6,800 new housing units for displaced residents, and all 6,882 temporary housing units planned for victims were scheduled for completion by the end of 2024. Two years after the event, more than 18,000 people were still living in temporary housing, which underlines both the scale of the need and the case for faster, factory-based rebuilding.
- Overtime cap extended to construction (April 2024): Japan's work style reform rules extended binding upper limits on overtime to the construction industry from April 2024, following occupational drivers and physicians. Construction workers now face an annual overtime ceiling of 720 hours, which reduces the hours available on site and strengthens the economic case for moving fabrication into factories.
- Daiwa House expands modular capacity abroad (2023 onward): Daiwa House opened a modular production plant in Fürstenwalde, Germany, in 2023 to serve European demand for efficient and affordable housing. The investment signals that the industrialised construction model refined in Japan is being exported, and it validates the factory economics that underpin the domestic market as well.
- Net zero energy housing reaches a new high (2025): Sekisui House reported that 96% of the new detached houses it sold in Japan in 2025 were net zero energy houses, which the company described as a new record. For the modular supply chain this indicates that energy performance has become a mainstream customer expectation rather than a premium upgrade, and that factory production is the practical route to delivering it consistently across volume housing.
Industry Trends Shaping 2026
Three trends dominate the outlook for the Japan modular construction industry as it moves through 2026.
1. BIM and Digital Twin Integration in Off-Site Manufacturing
Japanese construction firms are accelerating the use of building information modelling and digital twin technology within modular and prefabricated production workflows. The Ministry of Land, Infrastructure, Transport and Tourism has issued guidelines encouraging BIM adoption across public infrastructure and large-scale developments, and its i-Construction programme, launched in 2016, set a target of a 20% increase in construction productivity through the adoption of 3D technology. The relevance for modular manufacturing is direct. A digital model allows a producer to simulate module geometry, service routing and assembly sequencing before steel or timber is cut, which reduces rework rates, trims material waste and shortens the interval between order and handover. Because modular output depends on repeatable factory processes, the return on digital investment is easier to capture than in conventional site-based construction, where variability in ground conditions and trade availability is harder to control.
2. Rising Demand for Disaster-Resilient and Seismically Safe Structures
Japan's exposure to seismic activity and extreme weather continues to drive demand for modular structures engineered to advanced earthquake-resistance specifications. The 2024 Noto Peninsula earthquake demonstrated the value of rapid deployment: temporary housing was built at scale in Ishikawa Prefecture within a compressed timeframe, and prefabricated units were assembled in Wajima and Suzu from mid-January 2024 onward. The experience has two implications for the market. First, municipal and prefectural authorities now have operational evidence that factory-built housing can be procured and installed faster than conventional construction in a disrupted supply environment. Second, permanent modular systems that embed seismic isolation and enhanced structural frames are increasingly specified as the default for reconstruction, not only for emergency shelter. That combination of repeat disaster exposure and a maturing permanent modular product set reinforces long-term demand rather than a one-off spike.
3. Expansion of Wood-Based Modular Construction Aligned with Sustainability Goals
Growing adoption of engineered timber, particularly cross-laminated timber and glulam panels, is reshaping Japan's modular landscape. The country has extensive domestic forest resources and deep woodworking expertise, which positions timber as both a sustainable and a structurally effective modular material. The government actively promotes wood construction through pro-timber initiatives, housing quality programmes and carbon reduction mandates, which in turn catalyses investment in wood-based prefabricated systems. University and industry collaborations on timber innovation are progressively improving fire resistance, acoustic separation and panel performance, widening the range of applications from low-rise housing into mid-rise residential and commercial projects. Because wood also offers substantially lower embodied carbon than concrete or steel, it aligns modular delivery with corporate and national decarbonisation targets, giving developers a compliance-friendly route that supports the market's largest material segment.
Geographic Hotspots
The Kanto Region is the centre of gravity for the Japan modular construction market, holding a 38.5% share in 2025. The concentration reflects Tokyo's population density, the scale of infrastructure and residential development across the metropolitan corridor, and the region's earlier adoption of building information modelling and net-zero construction standards. Large-scale redevelopment, infill housing on constrained urban plots and the concentration of corporate construction budgets in and around the capital all favour factory-built systems, because off-site production shifts labour and assembly time away from congested sites.
Kansai, centred on Osaka, Kyoto and Kobe, represents the second tier of demand. Urban redevelopment, hospitality and mixed-use construction have supported steady requirements for panelised and volumetric modular systems, and the region's industrial base includes established prefabricated housing capacity. Hokuriku is a distinct case, because reconstruction after the Noto Peninsula earthquake has generated concentrated demand for both temporary and permanent housing in Ishikawa and neighbouring prefectures. That activity is finite, but it has left local authorities and contractors with practical familiarity in modular procurement that is likely to persist.
Beyond these, Chubu, Kyushu and Hokkaido contribute through a mix of industrial facilities, logistics buildings and timber housing. Hokkaido's cold climate makes the thermal performance that factory assembly delivers reliably particularly valuable, while Kyushu's semiconductor and automotive investment has generated demand for fast delivery of plant-adjacent facilities and worker accommodation. Regional shares will continue to trail Kanto, but infrastructure investment and tourism-linked construction are gradually broadening the geographic base of the market.
Competitive Landscape
The competitive landscape is shaped by a combination of established industry participants, emerging businesses, and specialized providers, with competition influenced by product quality, innovation, pricing strategies, distribution capabilities, and customer service. Market participants focus on strengthening their market presence by enhancing product offerings, improving operational efficiency, expanding distribution networks, and adapting to evolving consumer preferences. Technological advancements, changing purchasing behaviour, regulatory developments, and shifting industry requirements also influence competitive strategies. As market conditions evolve, businesses increasingly emphasize differentiation, value creation, and customer-centric approaches to sustain competitiveness and capitalize on emerging growth opportunities.
Policy & Regulatory Landscape, Challenges & Risks
Government policy sits directly behind the market's growth trajectory, but it also imposes constraints and cost that shape who can compete.
- Regulatory driver, seismic codes: Japan's Building Standards Act sets some of the world's most demanding seismic performance requirements. Factory production helps manufacturers integrate seismic isolation and reinforced frames into modules under controlled conditions, which is a competitive advantage for permanent modular suppliers but also a specification burden for smaller entrants.
- Regulatory driver, BIM and digital public works: The BIM/CIM mandate for public works from fiscal year 2023 and the MLIT i-Construction programme have made digital delivery a de facto requirement in public procurement, effectively raising the technical threshold for suppliers.
- Regulatory driver, working hours: The binding overtime ceiling of 720 hours per year for construction workers, applied from April 2024, reduces site labour availability and makes off-site fabrication economically more attractive, while also raising the cost of any work that must still be done on site.
- Regulatory driver, carbon and energy mandates: National carbon neutrality targets and energy efficiency requirements push developers toward low-embodied-carbon materials and high-performance building envelopes, which advantages cross-laminated timber and factory-sealed assemblies. This is the main policy channel through which wood sustains its 42.3% material share.
Challenges & Risks
- Challenge, capital intensity: Modular production requires plant, automation and tooling investment alongside a fixed cost base. Manufacturers must therefore secure order pipelines to keep utilisation high, which makes earnings sensitive to demand cycles and to the timing of reconstruction programmes.
- Challenge, transport and site constraints: Modules must travel through Japanese road networks, and width, height and weight limits restrict module dimensions. Urban sites frequently lack the laydown and crane access that volumetric installation requires, which can push projects back toward panelised solutions.
- Challenge, standardisation versus customisation: Japanese homeowners expect a high degree of design choice, which conflicts with the repeatability that drives factory cost efficiency. Balancing configurable product platforms against true customisation remains a central commercial difficulty.
- Risk, dependence on disaster and reconstruction cycles: A meaningful share of demand is linked to post-disaster rebuilding. A quieter seismic period would not eliminate the market, but it would slow the segments most exposed to emergency and reconstruction procurement.
Forecast 2026-2034
The Japan modular construction market is positioned for sustained expansion through the forecast period. Revenue rose from USD 18.11 Billion in 2025 to USD 18.85 Billion in 2026, and the market is expected to reach USD 29.27 Billion by 2034, equivalent to a compound annual growth rate of 5.65% from 2026 to 2034. In a construction market that is mature and labour constrained, a rate of this order indicates method substitution: modular delivery taking share from conventional site-based building rather than the sector simply growing with the economy.
The composition of that growth is likely to remain stable. Permanent modular systems should continue to hold the majority of value, since long-life residential and commercial projects carry the largest contract values and demand the seismic and energy performance that factories deliver reliably. Wood should retain its lead among materials, supported by engineered timber supply chains and carbon mandates, with steel and concrete serving specific structural and high-rise applications. Residential demand will remain the single largest end-user category, driven by ageing households, urban densification and the difficulty of staffing conventional sites.
Digitally, the next phase of growth depends on how quickly building information modelling, robotic assembly and digital twin based quality management spread from the leading manufacturers into the mid-tier. Geographically, the Kanto Region will remain the dominant engine, while Hokuriku reconstruction demand, Kansai redevelopment and industrial investment in Chubu and Kyushu gradually broaden the base. The principal risks to the forecast are input cost volatility in engineered timber, transport limits on module size and the pace at which municipal approval processes adapt to factory-built delivery.
Opportunities for Stakeholders
- Developers and general contractors: Off-site delivery reduces on-site labour hours at a time when the 720-hour annual overtime ceiling limits scheduling flexibility. Contractors that build modular capability into their tender models can protect programme certainty on dense urban sites and on reconstruction contracts where speed carries a premium.
- Off-site manufacturers: The gap between the 2025 base of USD 18.11 Billion and the USD 29.27 Billion forecast for 2034 represents capacity that must be built. Manufacturers that invest in automation and flexible production lines, rather than single-product plants, are best placed to serve both permanent residential demand and re-locatable project work.
- Engineered timber and material suppliers: Wood's 42.3% share in 2025 makes cross-laminated timber, glulam and panelised systems a priority supply chain. Suppliers that can certify fire, acoustic and structural performance for mid-rise applications open a larger addressable market than low-rise housing alone.
- Technology and software providers: BIM and digital twin adoption is now embedded in public procurement practice. Vendors offering model-based production planning, clash detection and factory scheduling tailored to modular tolerances have a defined and growing customer base across builders of all sizes.
- Investors and financial institutions: The market's structural drivers, labour scarcity, code-driven resilience and decarbonisation mandates, are policy-supported rather than sentiment-driven. Industrialised construction assets therefore offer long-duration exposure to Japanese construction demand with less sensitivity to single-project cycles.
- Municipalities and public agencies: Disaster preparedness planning depends on being able to deploy housing quickly. Framework agreements with modular suppliers, combined with pre-approved standard designs, would shorten response times and reduce the administrative load during emergencies.
- Workforce and training bodies: As fabrication shifts indoors, the skills profile changes toward factory operations, digital modelling and quality assurance. Training programmes aligned to these roles address the labour constraint at its source rather than simply working around it.
Building Japan's Future Off-Site
Modular construction is not a novelty in Japan; it is an established industrial capability that is now being asked to carry a much larger share of the country's building needs. The convergence of a shrinking site workforce, a binding overtime ceiling, one of the world's strictest seismic codes, carbon reduction mandates and repeated disaster exposure has turned off-site delivery from an efficiency option into a practical necessity. That is why the market moves from USD 18.11 Billion in 2025 to USD 18.85 Billion in 2026 and is forecast to reach USD 29.27 Billion by 2034, at a CAGR of 5.65%.
The shape of the market reinforces the same conclusion. Permanent systems hold 58.4%, wood holds 42.3% and residential end use holds 45.6%, which describes a product set built for long-life, sustainable, code-compliant housing rather than temporary expedients. Concentrated in the Kanto Region at 38.5%, the industry still has room to broaden into Kansai, Hokuriku, Chubu and Kyushu as reconstruction, redevelopment and industrial investment create new demand centres.
The constraint is not demand but execution. Factory capacity, transport limits on module dimensions, approval pathways and the balance between standardisation and customer choice will determine how much of the forecast is realised and by whom. For manufacturers, material suppliers, technology vendors and public agencies alike, the opportunity lies in treating modular construction as core infrastructure for Japanese building delivery, not as a fallback method for emergencies.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

DI pipes are made by treating molten iron with magnesium so that its graphite forms tiny spheres instead of flakes, casting it in spinning water-cooled moulds, and then annealing, zinc coating, cement lining, and testing each pipe.
Gypsum plasterboard is a flat building panel with a core of set gypsum bonded between a face paper and a back paper. Fixed to light steel frames, it creates ceilings, partitions, and wall linings that go up far faster than brick and wet plaster, weigh much less, and resist fire because gypsum holds chemically bound water.
MIG welding wire is a continuous solid wire, usually 0.8 to 1.6 mm in diameter, that is fed through a welding gun and melted by an electric arc under a shielding gas to join metals.
Gypsum board, also called plasterboard or drywall, is a panel made of a set gypsum core sandwiched between two sheets of heavy paper.
Steel forgings are strong, reliable metal parts made by shaping heated steel under the force of presses and hammers, which refines the grain structure and gives far better strength and fatigue resistance than casting or machining from bar.
PVC boards, mainly PVC foam boards and WPC boards, are lightweight, waterproof, termite-proof sheets used as an alternative to plywood and MDF in kitchens, bathrooms, wardrobes, furniture, partitions, signage, and interiors.
Laminated veneer lumber, or LVL, is an engineered wood product made by bonding thin wood veneers with their grain running in the same direction, producing straight, strong, and dimensionally stable members from fast-growing plantation timber.
Fly ash bricks turn a waste product from coal-fired power plants into strong, uniform building blocks that need no firing in a kiln. India's thermal power plants generated about 340 million tonnes of fly ash in 2024-25, and government rules require building projects within 300 km of these plants to use ash-based bricks and blocks where they are priced competitively.
Nuts and bolts hold together almost everything that is built or manufactured, from cars, tractors, and two-wheelers to bridges, towers, railways, machinery, and household appliances.
Precast elements are cast in a factory under controlled conditions and then transported to site, where they are lifted into place like the parts of a kit. India's construction sector is turning to this method to build faster, with better quality and less dependence on site labour.
Rice husk ash (RHA) is the residue left when rice husk is burned, and when the burning is properly controlled it is one of the richest natural sources of amorphous silica, typically 85 to 95% silica by weight.
Concrete poles carry most of India's low-tension and 11 kV distribution lines, as well as street lights, rural feeders, and telecom cables. They are strong, durable, resistant to rust, rot, and termites, need almost no maintenance, and cost less than steel poles, which makes them the default choice for state power distribution companies.
Crushed stone aggregates and manufactured sand are the most widely used construction materials after water. They form the bulk of concrete, the base layers of roads and runways, railway ballast, and the fill under buildings, factories, and ports.
Almost every industrial process generates heat that has to be removed. Power plants, steel mills, refineries, chemical and pharmaceutical units, food processors, plastics moulders, and now data centers all rely on cooling towers, chillers, and heat rejection equipment running around the clock.
Steel is the backbone of India's economic growth. Buildings, bridges, railways, highways, ports, power plants, automobiles, machinery, and household appliances all depend on it. India is the world's second-largest steel producer, and crude steel output reached about 170 million tonnes in 2025-26.
Ready mix concrete (RMC) is concrete batched in a central plant to a precise, engineered mix design and delivered to construction sites in transit mixers, ready to pour.
Open a modular kitchen cabinet, a wardrobe shutter, or an office workstation in India today and there is a good chance it is made from medium density fibreboard.
India is the world's second-largest producer of ceramic tiles, and walking through any new apartment, mall, hospital, or metro station shows why. Tiles have replaced mosaic, stone, and plain cement floors in homes across the country, while large-format glazed vitrified slabs are now standard in premium projects.
Setting up a TMT Bar Manufacturing Plant in India is a high-demand, infrastructure-driven venture, powered by the country's massive construction and housing boom, government infrastructure spending, and steady urbanisation.
Setting up a Cement Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's massive infrastructure programme, housing boom, and status as the world's second-largest cement producer.
Setting up a PVC Panel Manufacturing Plant in India is a high-demand, construction-driven venture, powered by the country's building boom, fast-growing interior and renovation market, and the shift away from plywood and plaster toward affordable, waterproof panels.
Setting up an Electric Motor Manufacturing Plant in India is a high-value, engineering-driven venture, powered by the country's industrial expansion, energy-efficiency push, and the rise of electric vehicles and automation.
Setting up an Iron Ore Pellets Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's ambitious steel-capacity expansion, the shift toward value-added iron ore, and rising demand from blast furnaces and sponge iron units.
The Saudi Arabia construction market has emerged as one of the most closely watched construction economies in the world. The market reached USD 101.4 Billion in 2025 and is projected to reach USD 140.4 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 3.6% between 2026 and 2034.
A WPC (Wood Plastic Composite) door is a type of composite door made from a combination of wood fibers or wood flour and thermoplastic resins like PVC, polyethylene, or polypropylene, with additives to improve durability and processability. The resulting composite material is then extruded or molded into door panels and frames, providing the attractive look of wood and the strength and water-resistance of plastic.
UPVC windows refer to window frames and window assemblies manufactured from ‘unplasticized polyvinyl chloride,’ which is a relatively rigid and strong thermoplastic substance. While PVC is a flexible material that requires the addition of a softening substance called a plasticizer to be formed into a durable performance material, PVC window frames and UPVC window assemblies, for instance, do not display such requirements due to the presence of unplasticizers, a component of the material that provides enhanced strength, stability, and resistance to the elements such as UV radiation, moisture, and temperature changes.
The Saudi Arabia factoring market represents a critical component of the Kingdom's evolving financial services landscape, offering businesses an increasingly popular alternative to traditional bank lending. Factoring, which involves the sale of accounts receivable to a third-party financial institution at a discount, has emerged as a vital mechanism for improving liquidity, managing cash flow, and mitigating credit risk across diverse industry sectors.
The GCC bridge construction market represents a vital component of the region's ambitious infrastructure transformation agenda, serving as a cornerstone for enhanced mobility, economic integration, and sustainable urban development across the Gulf states.
The Australia industrial couplings industry stands at a transformative juncture in 2025, propelled by technological advancement and surging demand across critical sectors. As mechanical devices connecting two shafts to transmit power and torque, industrial couplings form the backbone of machinery operations in manufacturing, mining, automotive, and energy sectors.
The Saudi Arabia real estate market stands at a pivotal juncture in its evolution, representing one of the most dynamic and transformative sectors within the Kingdom's economy. With this country having a very ambitious agenda of economic diversification and modernization, the real estate business has come out as one of the pillars of this transformation.
Steel is an alloy that consists of iron and carbon in addition to trace amounts of other elements like manganese, silicon, chromium, and nickel. The amount of carbon in steel is usually less than two percent and is an important factor in determining the strength, hardness, and ductility of steel.
Saudi Arabia’s precast concrete market reached USD 1.2 Billion in 2024 as per the IMARC Group, clear proof that off-site construction is rapidly becoming the Kingdom’s go-to building solution. With residential, commercial, and major infrastructure projects multiplying, developers are increasingly turning to precast building solutions to keep pace.
The GCC cold storage construction market represents critical infrastructure underpinning regional food security, pharmaceutical distribution, and temperature-sensitive logistics across the Arabian Peninsula. As Gulf Cooperation Council nations diversify their economies and reduce hydrocarbon dependence, robust cold chain infrastructure has emerged as a cornerstone of sustainable development planning.
PVC panels are lightweight, durable building materials made from polyvinyl chloride using extrusion or molding processes. They are available as rigid or semi-rigid sheets designed primarily for wall and ceiling cladding, partitions, and decorative finishes. Known for their excellent resistance to moisture, chemicals, termites, and corrosion, PVC panels offer a smooth surface and a clean, polished look that’s easy to maintain. Available in an extensive range of colors, textures, and patterns, these panels serve as a practical alternative to traditional materials like wood, plaster, or tiles.
Ready mix concrete (RMC) is a precisely engineered construction material produced in a controlled environment within a batching plant and delivered to construction sites in a freshly mixed, plastic state. It is formulated by combining cement, aggregates, water, and chemical or mineral admixtures in carefully proportioned quantities to achieve specific performance characteristics. Unlike site-mixed concrete, RMC ensures consistent quality, uniformity, and superior workability through automated production and quality control processes.
The construction industry across the Gulf Cooperation Council (GCC) member states is at the core of a monumental economic transformation. Far exceeding traditional building activities, the sector now serves as the principal vehicle for national economic diversification strategies, moving these nations beyond reliance on oil revenues.
Paver blocks are precast construction material made basically from cement, aggregates, sand, and pigments for constructing surfacing. They are produced in standardized shape and thickness, allowing each unit to interlock to form a strong, load-bearing surface with no need for continuous concrete pouring. Paver blocks possess high compressive strength, abrasion resistance, and are easy to lay and maintain.
The Brazil ceramic tiles market has witnessed stable growth, reflecting broader trends in the construction and building materials industries of the country. The Brazil ceramic tiles market size was valued at USD 1.6 Billion in 2025. The market is expected to reach USD 2.2 Billion by 2034, exhibiting a CAGR of 3.91% during 2026-2034.
MDF is an engineered wood product produced by breaking down hardwood or softwood residuals into wood fibers, which are then combined with resin binders under heat and pressure. MDF exhibits a homogeneous density, a smooth surface, and fine texture, ensuring a much more workable material compared to natural wood.
Float glass is a type of flat glass that is manufactured by floating molten glass on a bed of molten tin. This produces a smooth, uniform surface and consistent thickness. The float process was developed by Pilkington in the 1950s and revolutionized glassmaking because it enabled the production of large, flawless sheets of glass without needing polishing or grinding. The basic raw materials used-silica sand, soda ash, limestone, and dolomite-are heated in the furnace to a very high temperature, then continuously poured onto the tin bath, where the molten glass spreads out into an even layer. It cools and solidifies into a perfectly flat and perfectly transparent sheet. As it provides optical clarity and strength and is easily processed into coated, laminated, or toughened forms, float glass is used as a basic product for various applications, ranging from architectural and automotive to industrial applications.
ERW steel pipes can be identified as one of the most important categories of welded pipes and find wide applications in infrastructure, construction, and other industries because of their precision, cost-effectiveness, and reliability. The raw material to produce these pipes is either hot-rolled or cold-rolled steel coils that are longitudinally formed and welded by the application of high-frequency electric resistance welding.
Drill bits are specifically designed cutting instruments intended to produce cylindrical holes in various materials, ranging from soft woods and plastics to hardened steels, stone, and rock. Although they seem straightforward, drill bits consist of various specialized shapes, coatings, and materials that are designed to suit the cutting characteristics of the intended material and the requirements of the drilling task.
Concrete is among the most widely used construction materials in the world due to its strength, versatility, and durability. It is a composite material largely made of cement, water, aggregates-sand, gravel, or crushed stone-and in some cases, admixtures which give special properties to the concrete.
Clay bricks are one of the oldest and most extensively used construction materials in the globe, appreciated for their strength, durability, insulation against heat, and beauty. They are produced mainly from natural clay and shale, which are fashioned, dried, and subjected to high-temperature firing to produce a hard, dense material that can resist multiple environmental and structural stresses. The mix generally consists of alumina, silica, lime, iron oxide, and magnesia that collectively decide the color, texture, and performance properties of the brick.
Metal beam crash barriers and high mast light poles are essential infrastructural features providing security and visibility on highways, city roads, and industrial sites. Metal beam crash barriers or guardrails are made of galvanized steel beams, typically W-beam or Thrie-beam, that are designed to dissipate the impact energy on impact with a vehicle and minimize death and damage to vehicles.
Laminated plywood is an engineered wood material that is produced by laminating several layers of thin veneers of wood together with powerful adhesives and covering them with a protective or decorative laminate sheet. This amalgamation not only increases the strength of the plywood but also its beauty, which is why it is extremely versatile for use in furniture, cabinetry, floors, paneling, and interior design.
Ductile iron pipes (DIP) are a key part of new water and wastewater infrastructure, providing enhanced performance capabilities over older piping materials. Cast from ductile cast iron, a material that has the strength of steel combined with the resistance to corrosion of cast iron, these pipes are designed to endure high-pressure use while still being flexible enough to absorb stress without cracking.
The real estate sector plays a critical role in driving economic growth and shaping communities. It significantly contributes to national economies by generating jobs, influencing investment flows, and boosting government revenues through taxes. Beyond these economic benefits, real estate development directly affects the quality of life by creating homes, enhancing infrastructure, and revitalizing urban areas.
Gypsum boards, also referred to as drywall or plasterboard, are lightweight, strong and fireproof building materials that are frequently used for partitions, walls and ceilings. Constructed from a gypsum core encased in paper liners, they provide improved acoustics, cost effectiveness, and speedy installation. Gypsum boards are favoured in industrial, commercial, and residential construction because of its environmentally beneficial qualities, ability to withstand moisture, and ability to insulate against heat. They are an essential part of efficient and sustainable construction methods because of their adaptability to contemporary building processes.
A frameless shower door is a modern and aesthetically appealing bathroom fixture that has gained popularity for its sleek and minimalist design. They are constructed without the bulky metal framing that surrounds the glass panels and are typically made from thick, tempered glass that is securely attached to the wall and floor using hinges or brackets.