How Large Is the Global Industrial Robotics Market and Which Segments Carry the Most Weight?
Introduction: Mapping the Automation Backbone
The industrial robotics market is no longer a peripheral capital-goods category; it is the mechanical layer underneath global manufacturing capacity, and its size is now measured in tens of billions of dollars of annual revenue. According to IMARC Group, the global industrial robotics market stood at USD 22.1 Billion in 2025, is estimated at USD 25.1 Billion in 2026, and is projected to reach USD 56.1 Billion by 2034, expanding at a CAGR of 10.57% during 2026-2034. That implies an industry roughly 2.2 times its present size within eight years, a rate that sits well above underlying growth in global industrial output and signals that robots are gaining share inside the factory budget rather than simply riding a rising tide.
The demand base is broadening. Automotive assembly remains the anchor customer, but electronics, food and beverage, metals and machinery, plastics and pharmaceuticals are all adding capacity. Three forces reinforce each other: rising labour costs and demographic shrinkage in high-wage economies, the integration of artificial intelligence and industrial data into machine control, and the spread of smart factory architectures in which robots are networked nodes rather than isolated cells. Each of these shifts the economics of automation from a narrow large-enterprise calculation to a mainstream productivity decision for mid-sized manufacturers.
The defining theme of the current cycle is that intelligence is moving into the machine. In July 2025, ABB introduced three robot families designed specifically for Chinese mid-market buyers, the Lite+, PoWa and IRB1200, priced from about USD 20,000 to over USD 100,000 including controllers, with one model operational within 60 minutes of being unpacked and programmable by voice or by demonstration rather than through code. That combination of lower price points and easier programming is what turns a mature hardware category into a fast-growing one.
This blog examines how large the industrial robotics market is, which segments carry the most weight, where the growth is geographically concentrated, how leading vendors are repositioning, and what policy and structural risks could slow the trajectory.
Key Takeaways
- The global industrial robotics market is valued at USD 22.1 Billion in 2025 and USD 25.1 Billion in 2026, and is forecast to reach USD 56.1 Billion by 2034, at a CAGR of 10.57% during 2026-2034.
- Articulated robots form the largest product type, materials handling is the largest function, and electrical and electronics is the largest end use industry, making the high-precision pick-and-place cell the commercial centre of gravity of the market.
- Asia Pacific dominates the industrial robotics market, and the International Federation of Robotics recorded that Asia accounted for 74% of new robot deployments in 2024, against 16% in Europe and 9% in the Americas.
- The most consequential recent commercial move was ABB's July 2025 launch of three China-specific robot families, the Lite+, PoWa and IRB1200, priced from roughly USD 20,000 to over USD 100,000 to capture mid-market buyers.
- The key trend is the fusion of AI with robotics hardware, where vision, voice-based programming and self-optimising controllers reduce deployment time and open automation to manufacturers that previously could not justify it.
Industrial Robotics Market Size, Share & Growth Outlook
According to IMARC Group, the global industrial robotics market was valued at USD 22.1 Billion in 2025, is projected to reach USD 25.1 Billion in 2026, and is forecast to touch USD 56.1 Billion by 2034, registering a CAGR of 10.57% during 2026-2034. The step from 2025 to 2026 alone implies growth of roughly 13.6%, an unusually steep rate for capital equipment and one that points to both unit volume expansion and a richer revenue mix per installation, since controllers, vision systems, safety hardware and software are increasingly sold with the arm. The leading segments are:
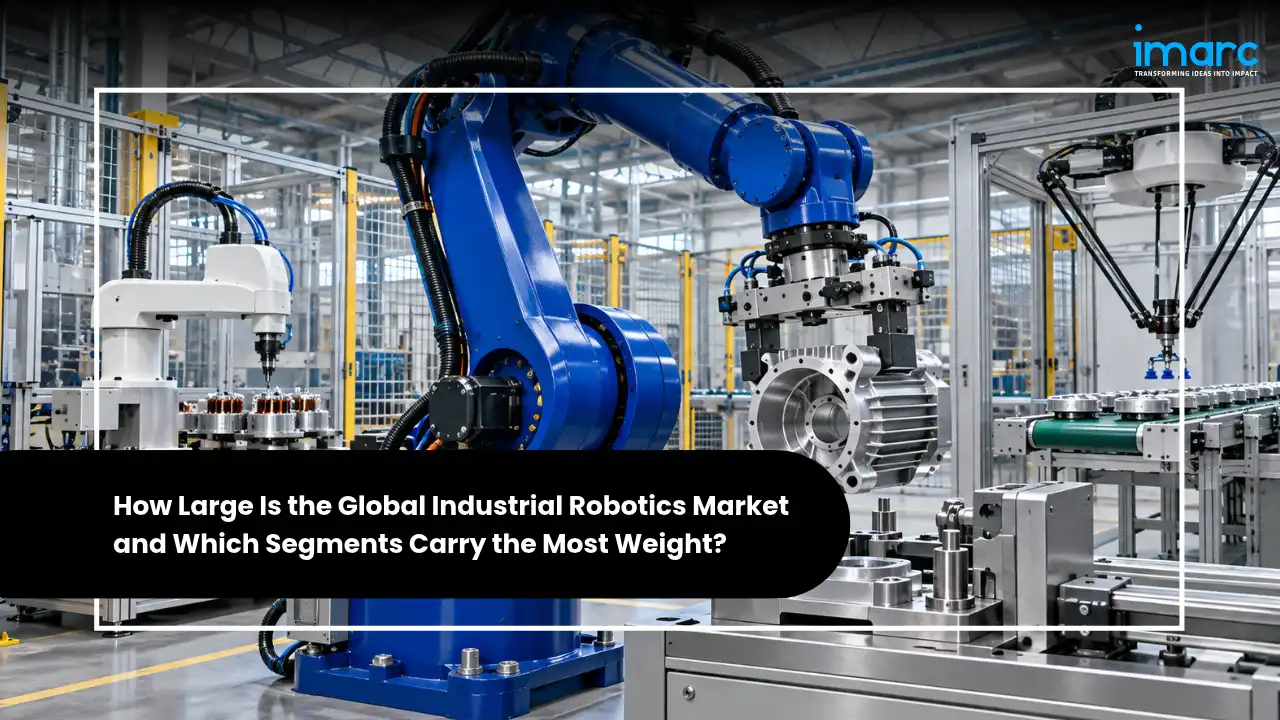
- Type: Articulated robots represent the largest segment of the industrial robotics market. Their multi-axis architecture, typically offering three to six or more degrees of freedom, makes them the default choice for welding, handling and assembly tasks that require reach and repeatability, which is why they anchor the majority of automotive and heavy-industry cells.
- Function: Materials handling holds the largest share by function. Pick-and-place, machine tending, palletising and conveyor transfer are the most common forms of robot deployment across industries because they are repetitive, physically demanding and straightforward to justify on payback grounds.
- End Use Industry: Electrical and electronics accounts for the majority of demand. High-speed placement of components on printed circuit boards, connector assembly and vision-based defect inspection make electronics the most robot-intensive general industry, and it has also been the largest customer segment in China for several years.
- Region: Asia Pacific exhibits clear dominance, supported by rapid industrialisation in China, Japan, India, South Korea and Taiwan, rising labour costs that push manufacturers toward automation, and government programmes that subsidise industrial upgrading.
These four dimensions reinforce one another rather than competing for attention: the articulated arm is the platform, materials handling is the task, electronics is the customer, and Asia Pacific is the location. Together they explain why the market's growth is not evenly distributed across the segmentation map, and why a large share of new product development is aimed at the intersection of those four characteristics.
The 2025 base figure also matters as a scale marker. At USD 22.1 Billion, the industrial robotics market is roughly the size of a mid-tier global industrial equipment category, yet it sits upstream of trillions of dollars of manufactured output, which is why modest swings in robot uptake have disproportionate effects on productivity statistics and on component supply chains.
Recent News & Mega Announcements
The 2025 news flow shows vendors shifting from incremental payload upgrades to software, localisation and factory-floor integration. The most significant announcements of the past eighteen months include:
- December 2025: FANUC overhauls its heavy-payload platform. At iREX 2025 in Tokyo, FANUC announced a full model change of its R-2000 large robot series with maintenance-free operation, alongside the CRX-3iA collaborative robot that can be carried with one hand and the long-reach P-55/15-21A painting robot, extending coverage from general industry to automotive painting lines.
- November 2025: China's MIIT accelerates robot deployment in factories. At a State Council Information Office briefing on 10 November 2025, the Ministry of Industry and Information Technology confirmed it will deepen the "Robot+" application action, pushing industrial and humanoid robots into plants with priority on welding, assembly, painting and handling, and extending robot use into mining, explosives handling and emergency response.
- September 2025: IFR reports the second-highest installation year on record. World Robotics 2025 recorded 542,000 industrial robots installed in 2024, more than double the number a decade earlier and the fourth consecutive year above 500,000 units, with the operational global stock rising 9% to 4,664,000 units.
- August 2025: ABB expands its large robot portfolio. ABB Robotics added the IRB 6730S, IRB 6750S and IRB 6760, taking its next-generation range to 11 robot families and 60 variants, with shelf-mounted units handling payloads up to 350 kg and OmniCore controllers cutting energy consumption by 20% relative to earlier platforms.
- July 2025: ABB builds a robot family for China's mid-market. ABB launched the Lite+, PoWa and IRB1200 for electronics, food and beverage, and metals customers, arguing that Chinese mid-market robot sales should grow about 8% a year in value over three years, with production at its Shanghai factory.
Industry Trends Shaping 2026
Three structural shifts are redefining competition in the industrial robotics market as the forecast period opens.
1. AI Moves from Add-On to Operating Layer
Artificial intelligence is migrating from separate quality-inspection boxes into the robot controller itself. At China's 25th International Industry Fair in September 2025, KUKA released five AI industrial agents spanning vision, autonomous mobile robot navigation and engineering software, claiming coverage across more than ten industry sub-scenarios, while FANUC introduced its R-50iA controller with stronger on-board computing, more capable vision and a safety-oriented remote maintenance architecture.
The commercial consequence is shorter commissioning. When a robot can be programmed by demonstration or voice, and when vision calibration is automated, the engineering hours that once dominated total project cost fall sharply. ABB's July 2025 launch illustrates the direction of travel: a robot that can be operational within an hour of unpacking, with a price band starting near USD 20,000, competes on ease of use rather than on payload alone.
For buyers, this reframes the investment case. The constraint on automation in small and mid-sized plants has never been the availability of arms; it has been the cost and scarcity of people who can integrate them. AI-assisted programming attacks that constraint directly, which is why the technology is likely to expand the addressable market rather than simply improve existing installations.
2. Localisation and the Mid-Market Price Ladder
The supply side is fragmenting along national lines. Chinese manufacturers sold more robots at home than foreign suppliers for the first time in 2024, lifting their domestic market share to 57% from 47% a year earlier, according to the International Federation of Robotics, while China's operational stock passed two million units. That is a structural change in pricing power, not a cyclical fluctuation.
Incumbent vendors are responding by designing for price tiers rather than exporting global platforms unchanged. ABB's China-specific families, produced locally in Shanghai, target pick-and-place, packaging and basic inspection work that large automotive-grade cells were never priced for. ABB also disclosed that China represents around 30% of its robotics business, which explains the willingness to localise both design and manufacturing.
The effect on the industrial robotics market is to widen the entry point. When a capable six-axis or SCARA-class system sits at USD 20,000 instead of USD 80,000, the number of factories that can justify automation multiplies, and growth becomes less dependent on the capital cycles of the automotive industry.
3. Easier Deployment through Modular and Collaborative Design
Hardware architecture is converging on modularity. ABB's next-generation range shares spare parts and service tools across 11 families, and its shelf-mounted IRB 6730S and IRB 6750S can be installed at height to work alongside floor-mounted units, raising the number of spot welds applied to a car body from 70 to 80 joints in 15 seconds. Modularity lowers total cost of ownership through shared inventory and faster service, which matters more to fleet operators than any single specification.
Collaboration is the second half of the story. FANUC's one-handed CRX-3iA and the wider adoption of cobots have made it practical to place robots next to people without full guarding, while revised safety standardisation now assesses application risk rather than product category, so a nominally collaborative arm moving sharp sheet metal at speed is treated on its merits rather than its label.
Deployment speed has become a competitive metric in its own right. Vendors that can demonstrate commissioning in hours, remote diagnostics and upgradeable software are displacing suppliers that sell on payload and repeatability alone, and this shift is visible in the way 2025 product launches were presented, with energy savings, controller platforms and software ecosystems taking equal billing with mechanical specifications.

Geographic Hotspots in the Industrial Robotics Market
Asia Pacific is not merely the largest region; it is the region that sets the pace of global installations. The International Federation of Robotics recorded 542,000 units installed worldwide in 2024, of which Asia accounted for 74%, Europe 16% and the Americas 9%. Within Asia, China alone represented 54% of global deployments at a record 295,000 units, with an operational stock of 2,027,000 robots, the largest of any country. Domestic Chinese suppliers captured 57% of their home market, a shift with direct implications for the pricing strategies of Japanese, European and Korean vendors.
The rest of Asia is uneven. Japan remained the second-largest market with 44,500 units installed in 2024, a 4% decline, and an operational stock of 450,500 units, reflecting a mature replacement market rather than rapid expansion. South Korea installed 30,600 units, down 3% and broadly flat since 2019, while India set a record of 9,100 units, up 7%, with the automotive industry accounting for 45% of demand. India's trajectory is the most important long-term variable in the region because its manufacturing base is expanding from a low automation base rather than replacing existing capacity.
Europe remains the second-largest regional market by value but is contracting at the margin. Installations fell 8% to 85,000 units in 2024, still the second-highest total on record, with 80% of European demand concentrated in the European Union. Germany, the largest European market and the fifth-largest globally, installed 26,982 units, down 5%, equal to 32% of the European total. Italy fell 16% to 8,783 units, Spain reached 5,100 units on automotive demand, France declined 24% to 4,900 units, and the United Kingdom dropped 35% to 2,500 units after the 2023 peak created by the super-deduction tax credit expired. Nearshoring has provided partial support, with average annual growth in European installations of 3% between 2019 and 2024.
The Americas are smaller in volume but strategically important. The United States is the largest market in the region and one of the three largest globally, and the region's 9% share of global deployments understates its importance in defence, pharmaceuticals, food processing and logistics automation, where specification standards and safety expectations are high and average selling prices are correspondingly elevated.
Industrial Robotics Market Competitive Landscape & Key Players Strategies
The industrial robotics market is oligopolistic at the platform level and fragmented at the integration level. A small group of Japanese, European and Korean manufacturers controls the majority of global arm production, while thousands of system integrators, gripper makers, vision suppliers and software firms compete for the project revenue that surrounds each installation. IMARC Group identifies the following as leading participants, among many others:
- ABB Ltd.: Focuses on advanced industrial robots, collaborative robotics, and automation solutions, serving industries such as automotive, electronics, logistics, and manufacturing. The company emphasizes AI-powered automation, precision, and energy-efficient robotic systems.
- DAIHEN Corporation: Specializes in industrial robots, welding automation, and power supply equipment, catering to manufacturing industries that require high-precision welding, material handling, and automated production processes.
- DENSO Corporation: Offers compact industrial robots, including SCARA and articulated robots, with applications across automotive, electronics, and precision manufacturing. The company focuses on high-speed automation, accuracy, and production efficiency.
- FANUC: Competes through a comprehensive portfolio of industrial robots, CNC systems, and factory automation solutions, supporting applications such as welding, painting, assembly, and material handling across manufacturing facilities.
- Kawasaki Heavy Industries Ltd.: Provides industrial robotic systems for automotive manufacturing, welding, painting, assembly, and material handling, emphasizing high-payload capabilities and automated production solutions.
- KUKA AG: Focuses on industrial robots, autonomous mobile robots, and integrated automation systems, serving automotive, electronics, healthcare, and logistics industries. The company emphasizes flexible manufacturing and intelligent automation technologies.
- Mitsubishi Electric Corporation: Offers industrial robots, including articulated and SCARA systems, alongside factory automation equipment and control technologies, helping manufacturers improve production accuracy and operational efficiency.
- Nachi-Fujikoshi Corp.: Specializes in industrial robots, robotic arms, and automation technologies, with applications in welding, assembly, machining, and material handling across automotive and industrial manufacturing.
- OMRON Corporation: Focuses on industrial automation, collaborative robots, autonomous mobile robots, and intelligent control systems, helping manufacturers streamline production workflows and improve workplace safety.
- Panasonic Corporation: Offers industrial automation and robotic solutions for manufacturing applications, particularly in electronics production, assembly, welding, and precision processing, emphasizing productivity and advanced manufacturing technologies.
- Seiko Epson Corporation: Competes through SCARA and six-axis industrial robots designed for high-speed assembly, precision handling, and electronics manufacturing, emphasizing compact designs, accuracy, and operational efficiency.
- Universal Robots A/S (Teradyne Inc.): Specializes in collaborative robots (cobots) designed to work alongside human operators, supporting applications such as machine tending, assembly, packaging, and quality inspection.
- Yamaha Motor Co. Ltd.: Provides industrial robots, including SCARA robots, Cartesian robots, and linear transfer systems, serving electronics, automotive, and precision manufacturing industries through high-speed and flexible automation solutions.
- Yaskawa Electric Corporation: Offers industrial robotic systems under its MOTOMAN brand, covering welding, painting, assembly, and material handling applications. The company focuses on motion control, intelligent automation, and integrated manufacturing solutions.
Three strategic themes cut across this group. The first is software monetisation, as vendors try to convert one-off hardware sales into recurring revenue from fleet management, analytics and remote service. The second is localisation of both manufacturing and design to defend share in China, where domestic suppliers now hold the majority of their home market. The third is portfolio breadth, since buyers increasingly want one supplier for large arms, cobots, mobile robots and controllers, and vendors without a complete line are being pushed into partnerships or acquisition strategies.
Policy & Regulatory Landscape, Challenges & Risks
Government policy has become a primary market force, shaping both the pace of deployment and the compliance cost of every installation. Key frameworks include:
- EU Machinery Regulation (EU) 2023/1230: Replacing the Machinery Directive 2006/42/EC, most provisions apply from 20 January 2027 and bring autonomous machinery, cybersecurity and safety-related software within scope. Safety components with fully or partly self-evolving behaviour using machine learning are listed as high-risk, requiring notified body involvement, which raises certification cost and lead time for AI-driven robot cells.
- EU Artificial Intelligence Act (Regulation (EU) 2024/1689): Applies in parallel with the machinery regime, classifying an AI system as high-risk where it is a safety component of machinery listed in the AI Act's Annex I and requires third-party conformity assessment. For robot builders this means a single product can trigger two conformity processes, with the most relevant penalty provisions applying from 20 January 2027.
- China's "Robot+" Application Action and MIIT deployment push: The action plan set a target of doubling manufacturing robot density by 2025 relative to 2020, and in November 2025 the Ministry of Industry and Information Technology confirmed further measures to place industrial and humanoid robots in welding, assembly, painting and handling roles, with subsidies and pilot programmes at provincial level supporting adoption.
- National industrial upgrading programmes across Asia: China's 14th Five-Year Plan for the robotics industry targets global leadership in robot technology and high-end manufacturing by 2035, and comparable incentive structures in Japan, South Korea and India are directed at robot density, domestic component supply and small and medium enterprise automation.
On the constraining side, several structural risks persist:
- Capital intensity and payback uncertainty: A single large articulated cell, with controller, safeguarding, end-of-arm tooling and integration, can cost several times the price of the arm itself, and at interest rates above those of the past decade, manufacturers with thin margins defer projects even when the operational case is sound.
- Skills and integration capacity: IMARC Group identifies a shortage of skilled workers as a direct constraint, and the bottleneck is acute at the integrator layer, where programming, safety validation and process knowledge determine whether a project finishes on schedule.
- Integration complexity and multi-vendor interoperability: Fleets assembled from different generations and brands of controller create data and safety inconsistencies, and every substantial modification to a cell can trigger fresh risk assessment obligations under the incoming European regime.
- Regulatory and compliance burden: Notified body involvement for AI-based safety functions, lifetime cybersecurity obligations for networked robots and documentation duties extending at least ten years after placement on the market add fixed costs that fall hardest on smaller builders and on custom, low-volume machines.
Forecast 2026-2034
On IMARC Group's projections, the industrial robotics market moves from USD 25.1 Billion in 2026 to USD 56.1 Billion by 2034, a CAGR of 10.57% that implies roughly USD 31 Billion of additional annual revenue being created over eight years. Because this is a capital-goods market, that revenue growth cannot come from price alone; it requires unit volumes to keep climbing while average selling prices stay under pressure from Chinese competition.
Unit economics support the arithmetic. The International Federation of Robotics expected global installations to rise about 6% to 575,000 units in 2025 and to exceed 700,000 units by 2028, with average annual growth near 10% through that period, and China remaining the largest market beyond it. If value grows slightly faster than units, the gap will be closed by richer content per robot: more sensors, more vision, more software licences and more service contracts attached to each machine.
Segment mix should shift gradually rather than abruptly. Articulated robots will remain the largest type because automotive body-in-white and heavy handling cannot be served by smaller formats, but growth rates should be higher in collaborative and compact platforms as food and beverage, electronics assembly and logistics absorb automation. Food and beverage is already the fastest-moving customer group in several markets, with Chinese installations in the sector rising 86% year on year to 8,900 units in 2024, and general industry demand outside automotive and electronics has been compounding from a small base.
The main risk to the forecast is not technological but cyclical. A prolonged downturn in automotive investment, a sharper contraction in European manufacturing or a policy shock in trade would each flatten a year or two of the curve, yet none of them alters the underlying substitution of labour by machines in economies where the working-age population is shrinking.
Opportunities for Stakeholders
- System integrators and engineering firms: The mid-market tier opened by robots priced from about USD 20,000 upward needs integration, safety validation and process design that first-time buyers cannot supply internally, making regional integrators the main channel for volume growth.
- Component and subsystem suppliers: Demand for vision systems, force-torque sensors, grippers, safety controllers and energy-efficient drives scales with every unit shipped, and content per robot is rising faster than unit volumes, which favours suppliers over platform builders in margin terms.
- Software and service providers: Remote monitoring, predictive maintenance, fleet management and controller-level AI applications create recurring revenue on an installed base of more than 4.6 million industrial robots, and the compliance requirements taking effect in 2027 create a parallel market for documentation and cybersecurity services.
- Manufacturers in emerging automation markets: India, with a record 9,100 units installed in 2024 and automotive accounting for 45% of demand, and Southeast Asian economies undergoing industrial relocation offer growth from a low base where the productivity gain per dollar invested is highest.
- Food, beverage and pharmaceutical producers: These sectors combine labour shortages, hygiene requirements and high product-mix variability, the exact profile where collaborative and compact robots now deliver acceptable payback, and where installed volumes are still far below those of automotive and electronics.
Where the Weight Will Shift
The answer to the question of scale is unambiguous: the industrial robotics market is a USD 22.1 Billion business in 2025 moving to USD 25.1 Billion in 2026 and USD 56.1 Billion by 2034, at a 10.57% CAGR, which places it among the faster-growing categories of global industrial capital spending. The answer to the question of weight is equally clear. Articulated robots dominate the product mix, materials handling dominates the application mix, electrical and electronics dominates the customer mix, and Asia Pacific dominates the map, with 74% of 2024 installations and a Chinese market that alone accounted for 54% of global deployments.
What is changing is not the identity of the leading segments but the width of the market beneath them. Chinese suppliers now hold the majority of their home market, ABB is designing robots specifically for mid-market Chinese buyers, FANUC has rebuilt its heavy-payload platform around maintenance-free operation, and AI-assisted programming is cutting the engineering hours that once kept small factories out of automation entirely. Each of these moves pushes the entry price down and pushes the number of viable buyers up.
For stakeholders, the practical implication is that growth will be earned at the edges of the segmentation map rather than at its centre. The largest segments will keep their share, but the incremental revenue between 2026 and 2034 will come disproportionately from mid-market buyers, from general industry applications outside automotive, from emerging manufacturing geographies and from the software and service layers attached to every robot shipped.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

A Drone Manufacturing Plant Setup in India sits at the centre of one of the country's most actively promoted new industries. Drones, or unmanned aircraft systems, are now used to spray crops, map land, inspect power lines and pipelines, monitor construction, deliver medicines, film events, and support police and defence forces.
The Philippines Data Center Industry has moved from a supporting role on Southeast Asia's digital map to a market with its own investment thesis, its own power constraints and its own policy agenda. According to IMARC Group, the Philippines data center market size reached USD 3,030.7 Million in 2025 and is forecast to reach USD 6,193.5 Million by 2034, expanding at a CAGR of 8.02% during 2026-2034.
The Japan fintech market is undergoing a structural transformation driven by the convergence of regulatory innovation, consumer digital adoption, and advanced technology deployment. According to IMARC Group, the market grew from USD 10.52 Billion in 2025 to USD 12.28 Billion in 2026 and is projected to reach USD 32.63 Billion by 2034, expanding at a CAGR of 13.0% during 2026-2034.
The cloud backup market has shifted from a peripheral IT line item to a core component of enterprise resilience, and the revenue trajectory reflects that change. IMARC Group estimates the market at USD 6.0 Billion in 2025, rising to USD 7.2 Billion in 2026 and reaching USD 22.7 Billion by 2034, a CAGR of 15.50% between 2026 and 2034.
The Mexico HVAC market is experiencing a structural shift that goes well beyond cyclical demand. According to IMARC Group, the market was valued at USD 6,162.3 Million in 2025 and is projected to reach USD 22,299.2 Million by 2034, expanding at a CAGR of 14.90% during 2026–2034.
The Japan 3D Printing Market is no longer a niche prototyping story. It is a precision-manufacturing market moving toward industrial-scale production, and the segment mix is shifting faster than the headline number suggests. The market grew from USD 2.02 Billion in 2025 to an estimated USD 2.48 Billion in 2026 and is projected to reach USD 9.08 Billion by 2034, expanding at a CAGR of 17.60% during 2026-2034.
Battery chargers are essential devices used to recharge batteries in a variety of applications ranging from consumer electronics to electric vehicles (EVs). India, with its growing demand for consumer electronics and the electrification of transportation, still relies heavily on imports for battery chargers.
Solid state drives store data on NAND flash memory chips instead of spinning disks, making them faster, quieter, tougher, and more energy-efficient than hard drives. They are now standard in laptops, desktops, gaming consoles, and servers, and they are the backbone of storage in data centres and AI computing.
The retail automation market sits at the centre of a structural shift in how goods are sold, priced, moved and paid for. According to IMARC Group, The global retail automation market grew from USD 21.2 Billion in 2025 to USD 23.2 Billion in 2026. Looking forward, IMARC Group expects the market to reach USD 40.9 Billion by 2034, exhibiting a growth rate (CAGR) of 7.34% during 2026-2034.
CCTV cameras now watch over homes, shops, offices, factories, highways, railway stations, and entire cities, and India has become one of the fastest-growing surveillance markets in the world.
The Wireless Charging Market is rapidly transitioning from a convenience feature to a foundational technology layer across consumer electronics, electric vehicles, healthcare devices, and industrial automation.
Artificial intelligence has changed what a data center needs. GPU clusters draw several times more power per rack than traditional servers and produce far more heat, so operators need heavier racks, higher-capacity power distribution, larger UPS systems, and liquid cooling that was rare only a few years ago.
Mexico has become one of Latin America's most active data center destinations, as hyperscalers build cloud regions, manufacturers relocate supply chains, and enterprises move workloads off their own premises.
Japan built the world's deepest robotics ecosystem, and it is now rebuilding that ecosystem around artificial intelligence. According to IMARC Group, the Japan Industrial Robotics Market was valued at USD 1,285.76 Million in 2025 and is projected to reach USD 2,864.83 Million by 2034, growing at a CAGR of 9.31% (2026–2034).
The Japan HR Tech Market grew from USD 2.16 Billion in 2025 to USD 2.31 Billion in 2026 and is projected to reach USD 3.93 Billion by 2034, at a CAGR of 6.87% (2026–2034). Rapid AI and machine learning integration across HR processes, stringent labor compliance requirements, and accelerating digital transformation of enterprise HR operations are the key growth catalysts driving Japan Human Resource Technology adoption.
The Japan Digital Printing Market reached USD 1.46 Billion in 2025 and is projected to reach USD 2.51 Billion by 2034, growing at a CAGR of 6.24% (2026–2034). Digital printing transfers digital files directly onto substrates such as paper, fabric, plastic, glass, and ceramic without traditional printing plates, and Japan Digital Printing Industry is undergoing a genuine technology transformation as AI, cloud workflows, and sustainable ink chemistry converge.
Europe's data center sector is drawing renewed investor attention because AI compute demand, digital sovereignty regulation, and renewable-energy siting economics have converged into a single, unusually large capital cycle.
The Japan Supply Chain Management Software Market reached USD 1,194.5 Million in 2025 and is projected to reach USD 1,616.7 Million by 2034, growing at a CAGR of 3.42% (2026–2034), as manufacturers and logistics operators across the country replace manual, spreadsheet-driven planning with connected digital platforms.
The Japan In-App Advertising Market is evolving rapidly as brand budgets shift decisively toward mobile-first channels. The market reached USD 9.21 Billion in 2025 and is projected to reach USD 30.30 Billion by 2034, growing at a CAGR of 14.16% (2026–2034), making this one of the fastest-growing segments within the broader Japan Mobile Advertising Market.
India’s data center sector is entering a defining growth phase. From a handful of facilities concentrated in Mumbai and Bengaluru a decade ago, the India data center industry has evolved into a continental-scale infrastructure ecosystem attracting billions of dollars in global investment.
As the Kingdom advances its economic diversification and technological development agenda, smart city development has emerged as a cornerstone of national strategy. This analysis explores the multifaceted dimensions of smart city initiatives, examining how digital innovation reshapes urban landscapes across Saudi Arabia.
The network security industry stands at the forefront of modern enterprise defense strategies, as organizations worldwide are confronting an increasingly hostile digital landscape. With cyber threats evolving in sophistication and frequency, businesses across every sector recognize that robust network protection is no longer optional but essential for operational continuity and stakeholder trust.
India has emerged as a global powerhouse in technology services, transforming from a back-office support destination to a strategic innovation hub. The nation's technology sector represents a cornerstone of economic development, driving substantial contributions to GDP while creating millions of employment opportunities across urban and rural landscapes.
The process of digital transformation in India has become an extremely fast one in the last several years, and cloud computing has become a foundation of the revolution. The India cloud computing market is experiencing an unprecedented growth as organizations in various sectors come to the realization of the strategic value of cloud infrastructure.
The Kingdom of Saudi Arabia stands at the forefront of a remarkable digital transformation that is fundamentally reshaping its economic landscape and technological capabilities. The data center market research in the country reveals a sector experiencing unprecedented momentum, driven by the nation's ambitious modernization agenda and its strategic positioning as a regional technology hub.
The global sports management software market represents a dynamic and promptly evolving industry that rests at the intersection of technology innovation and the multibillion-dollar sports industry. As organizations across amateur leagues, professional clubs, sports associations, and entertainment venues seek competitive advantages in an increasingly digital landscape, sophisticated software platforms have emerged as essential infrastructure.
Saudi Arabia's corporate training market is experiencing a profound transformation, driven by an ambitious national agenda focused on economic diversification, digital innovation, and workforce empowerment.
The Gulf Cooperation Council (GCC) region continues to position itself as one of the fastest-evolving markets for packaged beverages, with bottled water standing at the forefront of this transformation. The GCC bottled water market size has expanded steadily in recent years, supported by a strong shift toward health-driven consumption, improved hydration awareness, and evolving lifestyle patterns across the member countries.
The digital health market in Saudi Arabia has been undergoing a phenomenal transformation through convergence, where healthcare providers, government agencies, and technology innovators join forces to create more accessible, efficient, and patient-centered ecosystems in healthcare.
The market represents one of the most dynamic segments within the region's rapidly evolving entertainment landscape. The GCC anime market size reached USD 644 Million in 2024 as per IMARC Group and is projected to grow to USD 1,265 Million by 2033 at a CAGR of 7.8% during 2025-2033.
The UK quantum computing industry has emerged as a critical frontier in the global race toward next-generation computing capabilities. Britain's ecosystem brings together world-class universities, pioneering research institutions, and ambitious commercial ventures working to harness quantum mechanics for computational advantage.
The Australia smart homes Industry has emerged as one of the most dynamic sectors within the global connected living ecosystem. Valued at USD 4.29 Billion in 2025, the market is projected to reach USD 11.54 Billion by 2034, according to IMARC Group.
India is undergoing an accelerated digital transformation, a systemic shift that is dependent on robust, high-performance digital infrastructure. At the very core of this paradigm is the surge in demand for facilities that can reliably store, process, and manage the nation’s exploding data volumes.
Over the last decade, digital payment systems in India have undergone a significant transformation, and credit cards have emerged as one of the major components of this financial revolution. Driven by increasing financial literacy, deeper penetration of digital banking, and a gradual shift towards cashless transactions, the Indian credit card market is growing at a rapid pace.
The Saudi Arabia industrial safety equipment market size reached USD 38.70 Million in 2024, experiencing a transformative phase as the Kingdom intensifies its focus on workplace protection and regulatory compliance across diverse industrial sectors. Industrial safety equipment is playing an increasingly vital role in safeguarding workers and assets throughout the oil and gas, construction, manufacturing, mining, and chemical processing industries that form the backbone of Saudi Arabia's economy.
The Germany smart cities market stands as one of Europe’s most advanced models of urban innovation, driven by sustainability, digitalization, and citizen-focused design. Germany’s smart city vision emphasizes balancing efficiency with inclusivity, integrating technology seamlessly into everyday urban life.
The IoT market of Saudi Arabia is seeing unprecedented growth as the Kingdom speeds up its journey toward comprehensive digital transformation. This is a growth trajectory that reflects commitment to modern infrastructure, increasing operational efficiency, and positioning Saudi Arabia as the regional technology hub.
The Brazil C4ISR market forms a vital part of the modernization agenda for the nation's defense, entailing sophisticated systems for command, control, communications, computers, intelligence, surveillance, and reconnaissance. As South America's largest economy and military force, Brazil has always taken the lead in developing advanced defense IT infrastructure to address regional security challenges and emphasize its strategic autonomy.
The data center market in Brazil has emerged as a vital cog in Latin America's wheel of digital transformation. With the increasing adoption of digital technologies, the need for reliable, secure, and scalable data storage and processing infrastructures is rapidly rising among enterprises, governments, and consumers.
The Saudi Arabia e-commerce market is undergoing a major transformation, becoming one of the fastest-growing digital economies in the Middle East. It reached a value of USD 222.9 Billion in 2024 on account of the rapidly expanding digital landscape, government initiatives like Vision 2030, and the increasing adoption of mobile commerce (m-commerce) and digital payment solutions.
The Saudi Arabia telecom market is undergoing rapid transformation mainly driven by accelerated digitalization, robust policy support, and growing consumer connectivity needs. The industry serves as a critical pillar of the Kingdom’s Vision 2030 strategy which aims to diversify the economy and establish Saudi Arabia as a digital hub in the Middle East.
The Australia legal services industry is undergoing rapid change driven by growing demand, technological advancement, and evolving regulation. Firms that are innovating while upholding quality, ethics, and client trust are succeeding. Regulatory complexity is fueling advisory work, technology is reshaping service delivery, and Australia’s position is enabling regional growth.
The Latin America carbon footprint management market represents a critical frontier in the global transition toward sustainable business practices and environmental accountability. As organizations across the region confront mounting pressure from stakeholders, investors, and regulatory bodies, the demand for sophisticated carbon emission tracking systems has intensified dramatically.
The UK's ATM market, therefore, stands as an important pillar in its financial ecosystem for the benefit of millions of consumers and businesses who rely on timely, convenient, and secure ways of accessing cash. However, despite the rapid acceleration of contactless payments and digital banking, ATMs remain indispensable across the urban and rural areas.
The India smartphone industry has cemented its position as one of the world's most critical and dynamic technology markets, undergoing a profound transformation driven by consumer aspiration and technological advancement. Far from merely being a volume-driven segment, the market is experiencing a significant value premiumisation trend, where consumers are increasingly upgrading to feature-rich and higher-priced devices.
India is now undergoing a transformative phase of the Internet of Things (IoT) industry, as it solidifies its role as a key facilitator of the ambitions of the Indian economy to become digital. IoT, which was initially viewed as a futuristic idea, has quickly become a baseline technology in the consumer, enterprise, and public infrastructure domains.
As banks and startups embrace modernization, secure and efficient digital platforms are attracting strong local and global investment. Artificial intelligence (AI), automation, and predictive analytics are redefining how finance works in Australia. These tools make transactions faster, decisions sharper, and client experiences more intuitive. From fraud detection to personalized banking, technology is transforming every corner of the market.
The Europe artificial intelligence market stands at a pivotal juncture, balancing unprecedented technological advancement with complex regulatory frameworks and strategic imperatives. As businesses across the continent accelerate their AI adoption Europe initiatives, the region emerges as a distinctive force in global artificial intelligence development, characterized by its commitment to ethical innovation and human-centric technologies.
India’s rapid digitalization has transformed the way organizations operate, connect, and deliver services. However, this digital shift has also exposed enterprises to a surge in cyber threats, ranging from ransomware and phishing to sophisticated data breaches and identity theft. As companies across sectors increase their reliance on digital platforms, the frequency and complexity of cyberattacks have intensified, forcing both public and private institutions to prioritize cybersecurity investments.
The Europe drones market has evolved into an indispensable aspect of the continent's operational and technological environment. Drones are now sequentially incorporated into sectors that rely on precision, real-time monitoring, and safe performance of field operations. Their capacity for aerial monitoring, environmental condition evaluation, and real-time observation allows companies to achieve greater accuracy in decision-making while reducing reliance on human intervention in hazardous areas.
The 3D printing industry is currently experiencing a revolutionary growth that has had a radical change on the manufacturing operations within the industries of the world. The technology is also referred to as additive manufacturing (AM), and it is the way to create three-dimensional objects by adding layers to the digital model, thereby providing unprecedented flexibility in both design and production. The 3D printing sector of the world has become a pivotal source of innovation enabler, efficiency, supply chain resilience, and competitive edges to organizations as small-and-medium-sized as small businesses to Fortune 500 organizations.
The education sector in India is witnessing a sea change with digital learning becoming integral to both formal and informal education. The rapid rise of online education platforms has reshaped the way schools, coaching institutes, and higher education centers impart learning experiences, accelerated by pandemic-driven digital acceleration. And today, technology-enabled education is no longer confined to urban centers; it is reaching Tier-2 and Tier-3 cities, democratizing access to quality learning resources for millions of students.
India’s healthcare sector is undergoing a technological transformation, with artificial intelligence positioned as a central driver of change. With a population exceeding 146.39 crore and a system challenged by issues of accessibility, affordability, and quality, AI is no longer optional but essential for building sustainable healthcare solutions.
India health and wellness market is on a fast track, with more people paying attention to preventive care and overall well-being. IMARC Group stated that the market hit USD 156.01 Billion in 2024, owing to the boom in nutraceuticals, fitness, and digital health platforms. Artificial intelligence (AI) is bringing a fresh wave of innovation to health and wellness, enhancing personalized fitness routines, predictive health insights, and more efficient wellness tracking.
Japan's ecotourism industry is experiencing a remarkable transformation, positioning the country as Asia's leading destination for sustainable travel experiences. The market, which is reaching unprecedented valuations of USD 12,999.78 Million in 2024, is demonstrating exceptional growth momentum with projections indicating an expansion to USD 34,542.85 Million by 2033, representing a robust compound annual growth rate (CAGR) of 11.47% during the 2025-2033 period.
The United Kingdom is currently establishing itself as one of Europe's most dynamic blockchain innovation hubs, demonstrating remarkable resilience and growth despite global economic uncertainties. The UK blockchain market reached a valuation of USD 0.66 Billion in 2024 and is projecting explosive growth toward USD 54.63 Billion by 2033, exhibiting a compound annual growth rate (CAGR) of 63.26% during the forecast period. This extraordinary trajectory is placing the nation at the forefront of distributed ledger technology adoption and development.
Japan has been a world leader in robotics, especially industrial, for decades. The nation's unflinching faith in technology development, precision manufacturing, and automation has made it a world leader in industrial robotics. Industrial robots have transformed the manufacturing process to become necessary equipment in today's manufacturing, helping companies increase productivity, retain quality, decrease errors in operations, and enhance efficiency in processes.
The Europe 3D printing market stands at the forefront of a manufacturing revolution that is reshaping industries across the continent. As additive manufacturing technologies mature and expand beyond prototyping into full-scale production, European manufacturers, healthcare providers, and aerospace companies are increasingly embracing these transformative solutions. With substantial government backing, strategic industry collaborations, and breakthrough material innovations, the European 3D printing landscape is positioned for remarkable expansion through 2033.
The Philippines gaming industry has emerged as Southeast Asia's fastest-rising digital entertainment powerhouse, achieving USD 4,822.00 Million in gross gaming revenue for 2024. This explosive growth signals a fundamental transformation in how Filipinos engage with interactive entertainment, driven by the rapid adoption of augmented reality (AR) and virtual reality (VR) technologies.
The data monetization market has emerged as a critical pillar of the modern digital economy, transforming how organizations create value from their information assets. As businesses recognize data as a strategic asset, the ability to extract financial value has become a competitive imperative. The global data monetization industry encompasses diverse approaches, ranging from direct data sales to indirect monetization through enhanced decision-making. According to IMARC Group, the industry reached USD 4.1 Billion in 2024. It is projected to reach USD 16.1 Billion by 2033, at a CAGR of 15.76% during 2025-2033.
The global access control market is entering a phase of serious expansion and transformation. In 2024, IMARC placed its value at USD 10.6 Billion, with a forecast of USD 18.8 Billion by 2033 (CAGR of 6.5 %). This reflects how rapidly the underlying technologies, threat landscape, and regulatory regimes are shifting. Across enterprises, campuses, infrastructure sites, and smart buildings, access control is evolving from door-level locks to identity, context, behavior, and integration. In many markets, access control is becoming an essential bridge between physical security and cybersecurity.
The media consumption landscape in Japan is in the midst of a revolutionary change with over-the-top (OTT) services as a leading force behind the way viewers are consuming entertainment content. OTT services, which provide video content directly on the internet and not via conventional cable or satellite television, are fast becoming a standard in Japanese homes. The growth of the Japanese OTT industry has been shaped by various factors, from technological innovations to changing consumer tastes.
The e-commerce market in Mexico is thriving, driven by increased internet access, mobile shopping, and smooth digital payment options. IMARC Group estimated that the market reached an impressive USD 47.52 Billion in 2024, signifying a distinct transition towards online shopping.
The global Industry 4.0 market is experiencing strong momentum, propelled by the integration of smart technologies across manufacturing, logistics, and energy sectors. With automation, connectivity, and data intelligence at its core, Industry 4.0 is reshaping how enterprises design, produce, and deliver products.
The global soft skills training market size was valued at USD 33.39 Billion in 2024. Looking forward, IMARC Group estimates the market to reach USD 92.59 Billion by 2033, exhibiting a CAGR of 11.40% during 2025-2033. This substantial growth reflects a fundamental shift in how organizations approach workforce development, as the recognition of soft skills as strategic assets rather than supplementary competencies becomes universal across industries.
The global Wi-Fi infrastructure market is experiencing unprecedented expansion, fundamentally reshaping how organizations operate and consumers interact with technology. According to Wi-Fi Alliance, the official industry certification body, 4.1 Billion Wi-Fi devices are forecast to ship in 2024, contributing to 45.9 Billion cumulative Wi-Fi shipments over the technology's 25-year lifetime.
Australia's mobile money industry is experiencing unprecedented transformation as artificial intelligence reshapes the landscape of digital payments, mobile wallets, and financial services. The integration of sophisticated AI technologies has revolutionized how Australians conduct transactions, manage their finances, and interact with digital payment platforms. From smartphone-based payment solutions to advanced fraud detection systems, AI is driving innovation across every facet of the mobile money ecosystem.
India vehicle tracking market is undergoing a significant transformation, with artificial intelligence emerging as a central driver of innovation. According to the IMARC Group’s report, the market size reached USD 0.90 Billion in 2024.
India stands at a decisive stage where economic growth must advance in parallel with environmental sustainability. According to an IMARC Group report, the Indian green technology and sustainability market reached USD 837.2 Million in 2024, reflecting the nation’s growing commitment to sustainable development.
Closed-Circuit Television (CCTV) cameras are electronic monitoring systems that are used to watch, record, and send video images for security and observational reasons. Unlike television broadcasting, CCTV signals are sent to selected monitors or recording devices, and hence they are the backbone of contemporary security infrastructure.
India's educational technology sector stands at the precipice of a transformative revolution, with artificial intelligence (AI) emerging as the primary catalyst driving unprecedented growth and innovation. The convergence of AI technologies with educational platforms is fundamentally reshaping how millions of Indian students access, consume, and engage with learning content, creating an ecosystem that democratizes access to quality education across the country’s diverse linguistic and socioeconomic groups.
Japan’s higher education sector is at a major turning point as demographic and economic pressures converge with technological disruption. One of the major trends in the Japan higher education market include the number of students entering universities has been shrinking for decades due to the country’s aging population, creating structural challenges for institutions that once relied on a stable or growing pool of applicants.
Japan, a global leader in technological innovation, is at the forefront of a new digital revolution in its satellite communication sector. As the nation pushes toward a more connected and resilient future, the integration of Artificial Intelligence (AI) is proving to be a critical catalyst. From enhancing network performance to automating complex operations AI is not just an add-on it is a foundational technology reshaping the very fabric of satellite communication.
Generative artificial intelligence (AI) is rapidly becoming one of the most influential technologies of the decade, and its global footprint is continuously expanding. Nations across the world are exploring its transformative potential, with Japan emerging as a unique hub where technological innovation, traditional industries, and forward-looking government policies are converging.
A battery charger is a piece of electrical equipment that is used to recharge a rechargeable battery by imposing an electric current upon it. The main purpose of a charger is to transfer alternating current (AC) from the power source into an appropriate direct current (DC) that has the required voltage and current for the particular type of battery. Battery chargers play a vital role in a broad variety of applications, from consumer devices and electric vehicles (EVs) to industrial equipment and renewable energy systems.
Indian manufacturing continues to grapple with significant losses caused by defects, rework, and product returns, which weaken profitability and competitiveness. As per an industry report, in FY22, the total return order volume in India stood at 14.86%. Furthermore, high-volume industries such as automotive, FMCG packaging, textiles, and electronics are particularly exposed, where even a small defect rate can translate into substantial financial setbacks. Industry research states that in mature operations, the Cost of Poor Quality (COPQ) can account for as much as 15–20% of total sales. Moreover, Return Prime’s recent report shows that returns remain a major challenge in e-commerce sales, with 17.6% of all orders being sent back.
Industry 4.0 has been a defining milestone in the advancement of manufacturing. It is responsible for introducing automation, digitization, and data-driven processes that significantly enhanced productivity and precision. Presently, India is moving into the next phase of manufacturing, that is, autonomous factories. Here, artificial intelligence (AI) goes beyond simple automation, enabling systems to render decisions, learn from changing conditions, and continuously improve operations. This shift has the potential to reshape industrial growth in the country and establish new standards for smart manufacturing.
Indian manufacturers are facing difficulties due to rising input costs, shortages of skilled labour, unplanned machine downtime, and inconsistent product quality. According to an industry report, during the July–September quarter of FY25, raw material expenses for 1,679 listed non-financial manufacturing companies increased by 5.1%, outpacing sales growth, which rose by only 3.3%. Similarly, the Global Talent Shortage Survey 2025 reported that 80% of Indian employers report difficulty finding skilled talent, compared to the global average of 74%, highlighting a severe talent crunch.
According to the International Energy Agency (IEA), global energy-related CO2 emissions grew by 0.8% in 2024 to a record 37.8 gigatonnes, driving atmospheric concentrations to an unprecedented 422.5 ppm. This has led to an increased urgency in addressing climate change. Similarly, the industries are facing unprecedented pressure to rethink their operations due to the energy demand rising by 2.2% in 2024, which is faster than the annual average of 1.3% witnessed between 2013 and 2023.
India is among the fastest-growing economies globally. The nation is currently the fourth-largest economy in the world and is on its way to becoming the third-largest, with an estimated GDP of USD 7.3 Trillion by 2030. This momentum is not only strengthening India’s economic resilience but also opening lucrative opportunities for businesses, investors, and technology providers aligned with the country’s growth vision.
The role of artificial intelligence (AI) in modern project management has transitioned from a theoretical concept to a strategic imperative. As businesses navigate increasingly complex projects in a data-driven world, AI is emerging as a powerful force for efficiency, accuracy, and innovation.
The artificial intelligence market is no longer niche. Current projections value the market at a significant level today, with strong growth expected as generative AI matures, computing costs decline, and enterprise pilots scale into full production.
The data center sector in Japan is at the epicenter of a tech revolution, wherein artificial intelligence (AI) is fundamentally redefining how digital infrastructure manages, scales, and adapts. With the country progressing toward digital transformation in various industries, AI has been the force behind unprecedented innovation in the design, management, and optimization of data centers.
In the modern era, the global video streaming market is fundamentally reshaping the entertainment landscape, driven by the dual forces of digitalization and the escalating demand for on-demand content. Artificial intelligence (AI) also serves as a pivotal catalyst for this growth, enabling the personalization of user experiences through tailored recommendations, improved content discovery, and enhanced audience engagement.
The global gaming console market is undergoing a significant transformation, fueled by the adoption of artificial intelligence (AI) and an increasing demand for interactive entertainment.
For decades, call centers have played a central role in customer service. Traditionally staffed with large teams of agents, they operated as cost-heavy units designed to handle inquiries, complaints, and service requests. While essential, this model was often associated with inefficiencies, long wait times, and high employee turnover.
According to IMARC Group, the global identity verification market was valued at USD 13.8 Billion in 2024 and is projected to reach USD 46.4 Billion by 2030, expanding at a CAGR of 14.4% during 2023–2030. This strong growth is being fueled by the increasing adoption of artificial intelligence (AI) and machine learning (ML), which are enabling higher levels of automation, fraud detection, and real-time authentication.
Japan is a leader in digital transformation, known for being one of the most advanced nations in technology globally. Artificial Intelligence (AI) is becoming an integral force across various sectors, and the telecom industry is no exception.
Generative AI is revolutionizing industries by bringing fresh, game-changing solutions that boost creativity and streamline workflows. Whether it’s automating content creation or optimizing complex processes in fields like healthcare and finance, AI is opening doors to exciting new possibilities.
The e-commerce market has undergone a seismic shift in the past twenty years. What started as simple, text-based product pages has grown into a complex web of intelligent platforms capable of customizing experiences for every individual user. At the core of this evolution is Artificial Intelligence (AI).
The global laptop and tablet market includes portable computing devices for both personal and commercial use, providing mobility, flexibility, and connectivity. Laptops extend desktop computers' power and functionality in a portable package, while tablets provide light-touch screen interfaces for consumption of media, creative work, and on-the-go productivity.
The global cloud gaming industry is experiencing an unprecedented surge, driven by technological advancements and evolving consumer preferences. As the market expands, Artificial Intelligence (AI) stands out as a pivotal force, reshaping every facet of the cloud gaming landscape, from infrastructure to player experience. It enables smarter resource allocation, real-time content personalization, latency reduction, and advanced game logic.
The global power bank market is experiencing steady growth as digital lifestyles become more integrated into everyday routines. With rising dependence on smartphones, tablets, laptops, and wearables, power banks have shifted from being simple backup batteries to versatile, feature-rich accessories that fulfill the needs of a wide range of users. Consumers now prefer power banks with fast-charging capabilities, higher battery capacity, and environmentally responsible designs.
The hybrid cloud market across the world has been changing at a very fast rate, with companies globally adopting the mix of on-premises and cloud-based infrastructures to fuel innovation and operational effectiveness.
Japan’s artificial intelligence (AI)-driven three-dimensional (3D) printing startups are redefining manufacturing by merging speed, sustainability, and precision. Japan’s additive manufacturing scene is moving beyond prototypes—it's rewriting how industries build, design, and innovate.
As a global leader in technology and innovation, Japan has increasingly recognized the critical importance of cybersecurity to protect its digital infrastructure.
Electric cables or power cables are the fundamental parts employed for the transfer of electrical power or signals over short and long distances. They generally comprise one or more conductors, typically composed of copper or aluminum, covered with insulating materials and protective sheaths. Electric cables, based on their use, differ in structure, including low-voltage, medium-voltage, and high-voltage power cables, control cables, instrumentation cables, or data transfer cables like fiber optics.
Smart Factory and Industry 4.0 Integration is a comprehensive set of services that helps firms overhaul their manufacturing processes by embracing new technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), robotics, big data analytics, and cloud computing.
Digitalization is reshaping the very essence of travel, transforming it into a more personalized, convenient, and efficient experience than ever before. With the growing popularity of travel platforms, travelers now have the power to plan and book their entire journey with just a few taps on their smartphones.
Product and facility certification support offers professional assistance to companies in resolving complicated processes of product certification and facility certification. Our services facilitate adherence to global standards and regulatory guidelines to ensure hassle-free market entry and operational continuity across global markets.
The global e-commerce landscape is rapidly transforming, propelled by several evolving e-commerce industry trends. These fundamental shifts encompass changes in consumer behavior, rapid technological advancements, and increasing internet accessibility worldwide. As a direct result, brands are now prioritizing quick delivery, mobile-centric platforms, and deeply customized digital experiences.
Setting up a drone manufacturing plant with a step-by-step business plan covering setup, costs, equipment, compliance, and market strategy.
India’s textile industry is undergoing a transformative shift led by the government’s visionary PM MITRA (Mega Integrated Textile Region and Apparel) Parks initiative. With a mission to establish India as a worldwide leader in textiles, this program is creating world-class integrated manufacturing zones that drive innovation, reduce production costs, and boost sustainability.
India’s sports technology sector is gaining extraordinary momentum, driven by the digitalization of sports leagues, enhanced fan engagement, and increasing investments in athletic performance solutions. With the Indian Premier League (IPL) 2025 poised to become the most tech-driven tournament to date, the market is no longer restricted to wearables and broadcasting; it now powers every aspect of sports, from grassroots training to AI-based strategic decision-making.
India is becoming a popular location for foreign manufacturers because of its quickly expanding economy, affordable labour costs, and consistent government support. For businesses looking to establish manufacturing facilities in the nation, the Government's "Make in India" incentive program offers an alluring alternative. This guide will assist in comprehending the crucial requirements for setting up a manufacturing facility in India.
Factory audits are important for companies that intend to ensure compliance and quality in operations as well as supply chain efficiency. India is experiencing unparalleled growth in manufacturing. The skills to perform factory audits effectively can be used to counter most risks related to Indian supplier relationships. This blog gives a complete step-by-step guide on how to perform factory audits in India, including a complete checklist.
Establishing a manufacturing plant is a major investment that requires meticulous planning and a thorough understanding of the associated costs. Whether a seasoned entrepreneur or an industrial novice, understanding the "cost equation" is vital for making informed financial decisions and ensuring the long-term profitability of the operations. This blog will break down the various expenses associated with establishing a manufacturing facility in India.
Setting up a manufacturing plant is a significant milestone for any business, but it comes with complexities that require careful planning, research, and execution. From selecting the right location to ensuring regulatory compliance and operational efficiency, every aspect needs expert attention to guarantee success. This is where IMARC Group steps in, offering comprehensive pre-feasibility studies and consultation services to help businesses establish manufacturing plants seamlessly.
The manufacturing sector is a cornerstone of India's economy. It accounted for about 14% of the overall GDP of the nation in 2024 and has employed millions of people across the country. India has been a rising manufacturing powerhouse globally and 2025 is expected to be a turning point. Given the better government focus and strong labor force, along with the increasingly effective infrastructure, India is likely to be sealed as a prime destination for global manufacturers.
Many have encountered this scenario: visiting a website with enthusiasm to purchase a product seen in an advertisement, only to face challenges such as navigating a complex interface, unresponsive customer service, and a cumbersome checkout process.
The OTT industry is experiencing a pivotal transformation, signaling the advent of a new digital entertainment era. Consumers are increasingly demanding convenience and personalized experiences on OTT platforms. As a result, platforms are investing massively in technologies such as AI to enhance the recommendations of content and improve user experience.
From established giants in the United States and Europe to fast-paced markets in Asia, the e-commerce revolution is creating a competitive marketplace that transcends geographical boundaries. Vietnam stands out as a key force in this global trend, showcasing the potential of e-commerce to drive national economic transformation. The country’s e-commerce industry is witnessing tremendous growth, driven by new markets and growth opportunities in established markets.
Head-mounted displays consist of small displays with in-built sensors and optics that project images directly onto the user's eyes. They provide a virtual reality (VR) or augmented reality (AR) experience that allows users to interact with digital objects or environments. They resemble glasses or goggles and are designed to be worn on the head. They comprise many components, such as a controller, sensor, camera, lens, goggles, head tracker, case, connector, display, battery, processor, memory, pico projector, and accessories. Tracking systems and sensors detect the user's head movements and adjust the displayed content accordingly, offering the user a more realistic, immersive, and interactive experience.
5G technology or fifth-generation wireless technology is the latest advancement in mobile communication systems that provides enhanced data transfer speeds, reduces latency rates, improves reliability, and increases network capacity. This technology operates in the mm-wave spectrum, the spectrum band ranging from 30 to 300 gigahertz (GHz), which facilitates high-speed networks and faster data delivery. 5G technology supports the growth of emerging technologies like artificial intelligence (AI), machine learning (ML), and edge computing, enabling new business models and unlocking economic potential. It enhances the performance of business applications and digital experiences, such as video conferencing, online gaming, live streaming media, and self-driving cars. The components included in 5G technology are hardware, software, and services, and it is utilized in a wide range of applications, such as automation, video services, connected vehicles, smart homes, virtual & augmented reality, and monitoring & tracking. For better connectivity of networks, various industries, such as manufacturing, automotive, transportation & logistics, media & entertainment, energy & utilities, healthcare, government, and others, have deployed 5G technology extensively.
Robotics is the branch of engineering that deals with designing, constructing, and operating robots. Robots are programmable machines capable of carrying out tasks autonomously or semi-autonomously. Major types of robotics include industrial and service robots, combining elements of mechanical engineering, electrical engineering, computer science, and artificial intelligence (AI). Industrial robots encompass articulated, Cartesian, SCARA, and cylindrical robots. Service robots serve personal, domestic, and professional purposes, used in various applications, such as household tasks, entertainment, defense, fieldwork, logistics, healthcare, infrastructure, mobile platforms, and cleaning, and more. Robotics can efficiently and accurately perform tasks in environments that may be hazardous or challenging for humans. Robots reduce human labor, enhance production efficiency, lower costs, and improve product quality in various industries. Robotics is further categorized into types such as industrial robotics, food robotics, warehouse robotics, smart robotics, automotive robotics, agriculture robotics, logistics robotics, construction robotics, space robotics, and others. Nowadays, robotics has become an important part of many industries, even being used to explore deep oceans and space. Additionally, it is employed in creating autonomous vehicles, performing surgery, and conducting medical diagnoses.
Artificial Intelligence (AI) chips are designed to accelerate and optimize AI and Machine Learning (ML) workloads. The field of AI involves tasks such as pattern recognition, data analysis, and decision-making, which often require massive parallel processing. AI chips perform various tasks like deep learning, neural network processing, and other computationally intensive operations. These chips are tailored to support the parallel computing needs of AI workloads, making them well-suited for these tasks.
Oman is situated on the southeastern coast of the Arabian Peninsula. It boasts a rich cultural heritage, stunning landscapes, and a diverse range of attractions, making it an emerging destination in the tourism market. The country offers a wide array of tourist activities, including sunbathing, swimming, kitesurfing, diving, snorkeling, boating, among many others. Beach activities and kite surfing are popular in Muscat, Al Sawadi Beach, Alzaiba Beach, and Masirah Island, while desert safaris are a highlight in Wahiba Sands. Oman's rich historical heritage includes numerous UNESCO World Heritage Sites, ancient temples, forts, and palaces, such as Bahla Fort and the Archaeological Sites of Bat, Al-Khutm, and Al-Ayn.
Virtual reality (VR) gaming represents a new generation of computer games that leverage VR technology to provide high-definition visuals, spatial audio, and precise motion tracking, creating a sense of presence and immersion. VR gaming offers a 360-degree view of the virtual environment, keeping players engaged for longer periods compared to traditional gaming. Additionally, VR gaming is used in rehabilitation and the treatment of phobias, anxiety disorders, and other psychological conditions. It is also employed to train soldiers in combat scenarios, strategy, and decision-making.
Cloud computing delivers computing services over the internet, including servers, storage, databases, networking, software, analytics, and intelligence. It promotes faster innovation, flexible resource allocation, and economies of scale. Moreover, it offers numerous advantages, such as cost efficiency, mobility, scalability, reliability, and automatic software updates, among others.