Why Industrial Robotics Is Becoming Essential to Japan's Manufacturing Future
Introduction: Japan's Robotics Ecosystem Enters an AI-Driven Era
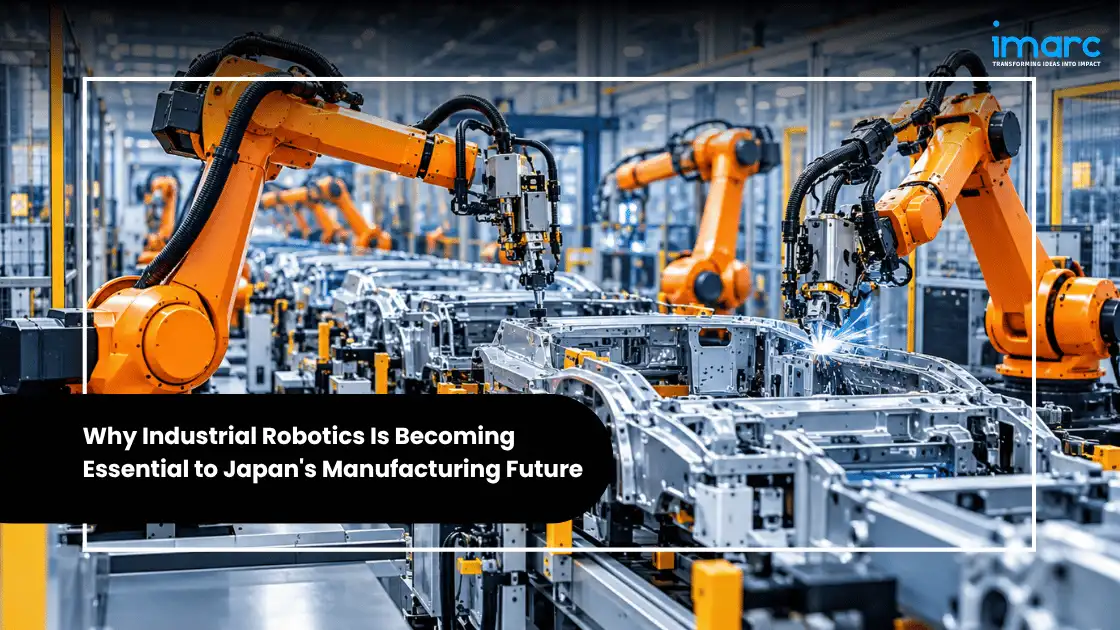
Japan built the world's deepest robotics ecosystem, and it is now rebuilding that ecosystem around artificial intelligence. According to IMARC Group, the Japan Industrial Robotics Market was valued at USD 1,285.76 Million in 2025 and is projected to reach USD 2,864.83 Million by 2034, growing at a CAGR of 9.31% (2026–2034). Domestic manufacturers still anchor global supply, and Japan remains the world's second-largest industrial robot market, with an operational stock of 450,500 units in 2024.
Demographics make automation a necessity rather than an efficiency project. Japan's working-age population is projected to decline to 45 million by 2065, and roughly 600,000 industrial jobs already sit unfilled. Robots are increasingly deployed not to displace workers but to staff roles that employers cannot fill, from warehouse picking to welding cells.
The shift underway is qualitative as much as quantitative. AI robotics in Japan is moving from pre-programmed repetition toward systems that perceive, plan, and adapt on the line, backed by national physical AI programmes and partnerships with global chip and model providers. That transition is what will decide productivity gains over the next decade.
This blog covers the Japan industrial robotics market's size and segments, recent announcements, the trends shaping 2026, regional hotspots, competitive strategies, policy support and risks, and the long-range forecast, helping manufacturers, integrators, and investors plan their automation roadmaps.
Key Takeaways
- The Japan Industrial Robotics Market was valued at USD 1,285.76 Million in 2025 and is forecast to reach USD 2,864.83 Million by 2034, at a CAGR of 9.31% (2026–2034).
- Articulated robots lead by type with a 48.6% share, while automotive is the largest end-user industry at 36.9%, followed by electrical and electronics at 27.4%.
- The Kanto region holds the largest regional share at 37.5%, ahead of Kansai/Kinki at 22.8%, while Kyushu-Okinawa is the fastest-growing region.
- Domestic manufacturers control an estimated 60% to 70% of Japan's installed robot base, led by FANUC, Yaskawa Electric, Kawasaki Heavy Industries, Mitsubishi Electric, and DENSO.
- The key industry trend is physical AI: in 2026, Japan launched a national multimodal foundation model programme for robots and its largest robot makers began building AI-driven autonomous systems.
Market Size, Share & Growth Outlook
According to IMARC Group, demand is concentrated in a few robot types and a handful of heavy manufacturing sectors, with regional activity following Japan's industrial corridors. Order momentum has also turned sharply positive: industrial robot orders reached JPY 294.8 billion in the first quarter of 2026, up 41.0% year on year and an all-time high for the second consecutive quarter. The leading segments are:
- Robot Type: Articulated robots hold a 48.6% share, ahead of SCARA at 21.7% and Cartesian at 13.4%, reflecting their reach and flexibility in welding, assembly, and materials handling cells.
- End-User Industry: Automotive leads with 36.9%, followed by electrical and electronics at 27.4% and general manufacturing at 14.6%, as electric vehicle and component lines drive new installations.
- Application: Deployments span soldering and welding, materials handling, assembling and disassembling, painting and dispensing, and milling, cutting, and processing, with handling and welding anchoring most automotive and electronics lines.
- Region: The Kanto region commands 37.5%, ahead of Kansai/Kinki at 22.8% and Central/Chubu at 15.9%.
Growth is not uniform, however. Exports rose 35.4% year on year in the first quarter of 2026 while domestic shipments fell 4.0%, showing that demand for robotics technology in Japan's own plants is lagging the pull from overseas buyers.
Recent News & Mega Announcements
The last two years have turned Japan's robotics agenda into an AI agenda:
- In July 2026, Fujitsu began exploring physical AI development with FANUC, Yaskawa Electric, and Kawasaki Heavy Industries, using NVIDIA Cosmos, Isaac, and Omniverse alongside its own Takane large language model, targeting factories, retail and logistics, and healthcare.
- In July 2026, Yaskawa Electric unveiled an agentic robot system pairing its MOTOMAN NEXT robot with Google DeepMind's Gemini Robotics ER 1.6 model, enabling robots to assess a scene, plan a path, and recover from errors without detailed programming.
- In June 2026, METI and NEDO launched a multimodal foundation model project for AI robots and physical AI, selecting Noetra Corp. and AIST as lead developers for fiscal 2026 through fiscal 2030.
- In April 2026, reporting on Japan's automation push put METI's robotics commitment at about USD 6.3 billion, with a stated ambition to hold 30% of the global robotics market by 2040.
Together, these moves signal that Japan is competing on robot intelligence and software platforms, not only on precision hardware.
Industry Trends Shaping 2026
Three trends are reshaping industrial robotics in Japan through 2026:
1. AI, IoT, and Predictive Analytics in Smart Factories
Sensor data, vision systems, and analytics are being fused into the control layer so cells can adjust to variation instead of halting. Yaskawa's agentic system combines machine vision, path planning, and force sensing with automatic error recovery and links to production management systems, a template for how smart manufacturing in Japan will handle mixed, high-variety production. In Japan smart factory projects, the practical payoff is fewer line stoppages, tighter quality control, and maintenance scheduled before failure rather than after it.
2. National Physical AI Platforms
Robot intelligence is becoming national infrastructure. The METI-NEDO project aims to build a domestic multimodal foundation model while reducing AI power consumption and accelerating competitive physical AI across industries, and reporting on the programme describes funding of up to JPY 1 trillion over five years and a target of 10 million AI-powered robots across 18 industries by 2040. Fujitsu's stated aim is a sovereign, open collaborative control platform that standardizes robot integration, which would lower the cost of deploying multi-vendor fleets.
3. Robots Filling Jobs Employers Cannot Staff
Industrial automation in Japan is increasingly demand-led by labor scarcity. With about 600,000 unfilled industrial jobs and the working-age population set to shrink by nearly 15 million over the next two decades, automation is moving into warehouses, construction sites, and care settings where recruitment has failed. Fujitsu's physical AI work explicitly targets retail and logistics materials handling and healthcare transport, both sectors outside the traditional factory base.

Geographic Hotspots
The Kanto region leads the Japan Industrial Robotics Market with a 37.5% share, followed by Kansai/Kinki at 22.8%, Central/Chubu at 15.9%, and Kyushu-Okinawa at 9.4%. Kanto combines corporate headquarters, electronics production, and dense logistics networks around Tokyo, while Chubu remains the heart of automotive assembly and Kansai supports machinery and precision components.
Kyushu-Okinawa is the fastest-growing region, expanding at roughly 11% annually, driven by semiconductor investment. Government support for TSMC's Kumamoto project, reported at about JPY 2.6 trillion, and JPY 920 billion committed to Rapidus is pulling cleanroom handling, inspection, and wafer-transfer robots into the southwest, extending demand beyond the traditional automotive belt.
Competitive Landscape & Key Players' Strategies
The Japan industrial robotics market is highly concentrated, with domestic manufacturers controlling approximately 60% to 70% of the domestic installed base. Competition is shifting from payload and cycle time toward AI software, autonomy, and integration platforms. Key players include:
- DENSO: Extends precision assembly expertise into new domains, introducing a fully automated robotic harvesting system for agriculture in May 2024.
- FANUC Corporation: Works with Fujitsu and NVIDIA on physical AI deployment, adding intelligence to a large installed base of articulated and collaborative robots.
- Kawasaki Heavy Industries: Announced an initiative to advance its robotics and automation capabilities in December 2024, and joined the Fujitsu-NVIDIA physical AI collaboration.
- Mitsubishi Electric: Ranked among the market's leading players, it pairs robots with controllers, drives, and plant-level automation systems.
- Nachi-Fujikoshi: Ranked among the market's leading players, it supplies articulated robots to automotive and metalworking customers.
- Seiko Epson: Ranked among the market's leading players, it focuses on SCARA and compact precision robots for electronics and small-parts assembly.
- Yaskawa Electric: Commercializes agentic robotics with Google DeepMind's Gemini Robotics models, positioning software autonomy as its differentiator.
The common strategy is to keep hardware leadership while capturing the software layer, since foundation models and integration platforms will determine switching costs in the next cycle.
Policy & Regulatory Landscape, Challenges & Risks
Government programmes underpin much of the innovation agenda:
- Society 5.0 and Connected Industries: National frameworks promoting the integration of cyber-physical systems and data-driven manufacturing.
- METI Factory Automation Programmes: Support automation adoption across industrial sectors, extended in 2026 by the multimodal foundation model project for AI robots run with NEDO.
- Semiconductor Investment Support: Large-scale funding for TSMC's Kumamoto fabs and Rapidus creates direct demand for cleanroom-grade robotics.
Key challenges and risks include:
- Soft domestic demand: Domestic shipments fell 4.0% year on year in the first quarter of 2026, with both electrical machinery and automotive declining, even as exports surged.
- Export dependence: Exports accounted for JPY 199.8 billion of JPY 251.9 billion in first-quarter 2026 shipments, leaving makers exposed to demand cycles and trade policy in China, Southeast Asia, and North America.
- Installed base renewal: Annual installations in Japan were 44,500 units in 2024, down 4%, while the operational stock grew 3% to 450,500 units, pointing to an ageing fleet that will need retrofit or replacement.
- Funding continuity: Only the first two years of the national physical AI programme are guaranteed, with later funding subject to annual stage-gate reviews.
Forecast 2026–2034
IMARC Group projects the Japan Industrial Robotics Market to grow from USD 1,285.76 Million in 2025 to USD 2,864.83 Million by 2034, a CAGR of 9.31% (2026–2034). Growth will be carried by three demand streams: replacement and upgrade of an ageing installed base, semiconductor and electronics capacity additions, and the spread of robots into logistics, healthcare, and services.
The composition of that growth will change. Autonomous, AI-guided robots should take a rising share of new installations as foundation models mature, with articulated robots retaining leadership and Kyushu-Okinawa growing fastest at around 11% annually. If the national target of 10 million AI-powered robots across 18 industries by 2040 advances on schedule, the addressable base widens well beyond traditional factory floors.
Opportunities for Stakeholders
- Automotive & EV Manufacturers: Use robots to absorb model complexity in battery, motor, and assembly lines, where automotive already accounts for the largest share of installations.
- Semiconductor & Electronics Firms: Equip new fabs in Kyushu and electronics plants with cleanroom handling and inspection robots as capacity comes online.
- Logistics & Warehousing Operators: Deploy picking, sorting, and transport robots to cover shifts that cannot be staffed, cutting dependence on scarce labor.
- System Integrators & Software Vendors: Build the calibration, simulation, and fleet-management layers that multi-vendor AI robot deployments require.
- Investors: Back suppliers of vision systems, force sensors, and control software, the components that turn conventional arms into adaptive machines.
Conclusion: Securing Japan's Manufacturing Future Through Intelligent Automation
Industrial robotics in Japan has moved from a productivity lever to a structural requirement. With a shrinking workforce, record export orders, and a national push into physical AI, the country is betting that intelligent machines can hold its manufacturing base together while sustaining a CAGR of 9.31% (2026–2034).
For manufacturers, the priority is to pair automation investment with data and skills so that AI-enabled cells deliver the promised precision and uptime. For technology vendors, the opening lies in software and integration rather than hardware alone. For policymakers, sustained funding and clear standards will decide whether Japan converts its robotics lead into an enduring advantage in intelligent manufacturing.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

The Japan HR Tech Market grew from USD 2.16 Billion in 2025 to USD 2.31 Billion in 2026 and is projected to reach USD 3.93 Billion by 2034, at a CAGR of 6.87% (2026–2034). Rapid AI and machine learning integration across HR processes, stringent labor compliance requirements, and accelerating digital transformation of enterprise HR operations are the key growth catalysts driving Japan Human Resource Technology adoption.
The Japan Digital Printing Market reached USD 1.46 Billion in 2025 and is projected to reach USD 2.51 Billion by 2034, growing at a CAGR of 6.24% (2026–2034). Digital printing transfers digital files directly onto substrates such as paper, fabric, plastic, glass, and ceramic without traditional printing plates, and Japan Digital Printing Industry is undergoing a genuine technology transformation as AI, cloud workflows, and sustainable ink chemistry converge.
Europe's data center sector is drawing renewed investor attention because AI compute demand, digital sovereignty regulation, and renewable-energy siting economics have converged into a single, unusually large capital cycle.
The Japan Supply Chain Management Software Market reached USD 1,194.5 Million in 2025 and is projected to reach USD 1,616.7 Million by 2034, growing at a CAGR of 3.42% (2026–2034), as manufacturers and logistics operators across the country replace manual, spreadsheet-driven planning with connected digital platforms.
The Japan In-App Advertising Market is evolving rapidly as brand budgets shift decisively toward mobile-first channels. The market reached USD 9.21 Billion in 2025 and is projected to reach USD 30.30 Billion by 2034, growing at a CAGR of 14.16% (2026–2034), making this one of the fastest-growing segments within the broader Japan Mobile Advertising Market.
India’s data center sector is entering a defining growth phase. From a handful of facilities concentrated in Mumbai and Bengaluru a decade ago, the India data center industry has evolved into a continental-scale infrastructure ecosystem attracting billions of dollars in global investment.
As the Kingdom advances its economic diversification and technological development agenda, smart city development has emerged as a cornerstone of national strategy. This analysis explores the multifaceted dimensions of smart city initiatives, examining how digital innovation reshapes urban landscapes across Saudi Arabia.
The network security industry stands at the forefront of modern enterprise defense strategies, as organizations worldwide are confronting an increasingly hostile digital landscape. With cyber threats evolving in sophistication and frequency, businesses across every sector recognize that robust network protection is no longer optional but essential for operational continuity and stakeholder trust.
India has emerged as a global powerhouse in technology services, transforming from a back-office support destination to a strategic innovation hub. The nation's technology sector represents a cornerstone of economic development, driving substantial contributions to GDP while creating millions of employment opportunities across urban and rural landscapes.
The process of digital transformation in India has become an extremely fast one in the last several years, and cloud computing has become a foundation of the revolution. The India cloud computing market is experiencing an unprecedented growth as organizations in various sectors come to the realization of the strategic value of cloud infrastructure.
The Kingdom of Saudi Arabia stands at the forefront of a remarkable digital transformation that is fundamentally reshaping its economic landscape and technological capabilities. The data center market research in the country reveals a sector experiencing unprecedented momentum, driven by the nation's ambitious modernization agenda and its strategic positioning as a regional technology hub.
The global sports management software market represents a dynamic and promptly evolving industry that rests at the intersection of technology innovation and the multibillion-dollar sports industry. As organizations across amateur leagues, professional clubs, sports associations, and entertainment venues seek competitive advantages in an increasingly digital landscape, sophisticated software platforms have emerged as essential infrastructure.
Saudi Arabia's corporate training market is experiencing a profound transformation, driven by an ambitious national agenda focused on economic diversification, digital innovation, and workforce empowerment.
The Gulf Cooperation Council (GCC) region continues to position itself as one of the fastest-evolving markets for packaged beverages, with bottled water standing at the forefront of this transformation. The GCC bottled water market size has expanded steadily in recent years, supported by a strong shift toward health-driven consumption, improved hydration awareness, and evolving lifestyle patterns across the member countries.
The digital health market in Saudi Arabia has been undergoing a phenomenal transformation through convergence, where healthcare providers, government agencies, and technology innovators join forces to create more accessible, efficient, and patient-centered ecosystems in healthcare.
The market represents one of the most dynamic segments within the region's rapidly evolving entertainment landscape. The GCC anime market size reached USD 644 Million in 2024 as per IMARC Group and is projected to grow to USD 1,265 Million by 2033 at a CAGR of 7.8% during 2025-2033.
The UK quantum computing industry has emerged as a critical frontier in the global race toward next-generation computing capabilities. Britain's ecosystem brings together world-class universities, pioneering research institutions, and ambitious commercial ventures working to harness quantum mechanics for computational advantage.
The Australia smart homes Industry has emerged as one of the most dynamic sectors within the global connected living ecosystem. Valued at USD 4.29 Billion in 2025, the market is projected to reach USD 11.54 Billion by 2034, according to IMARC Group.
India is undergoing an accelerated digital transformation, a systemic shift that is dependent on robust, high-performance digital infrastructure. At the very core of this paradigm is the surge in demand for facilities that can reliably store, process, and manage the nation’s exploding data volumes.
Over the last decade, digital payment systems in India have undergone a significant transformation, and credit cards have emerged as one of the major components of this financial revolution. Driven by increasing financial literacy, deeper penetration of digital banking, and a gradual shift towards cashless transactions, the Indian credit card market is growing at a rapid pace.
The Saudi Arabia industrial safety equipment market size reached USD 38.70 Million in 2024, experiencing a transformative phase as the Kingdom intensifies its focus on workplace protection and regulatory compliance across diverse industrial sectors. Industrial safety equipment is playing an increasingly vital role in safeguarding workers and assets throughout the oil and gas, construction, manufacturing, mining, and chemical processing industries that form the backbone of Saudi Arabia's economy.
The Germany smart cities market stands as one of Europe’s most advanced models of urban innovation, driven by sustainability, digitalization, and citizen-focused design. Germany’s smart city vision emphasizes balancing efficiency with inclusivity, integrating technology seamlessly into everyday urban life.
The IoT market of Saudi Arabia is seeing unprecedented growth as the Kingdom speeds up its journey toward comprehensive digital transformation. This is a growth trajectory that reflects commitment to modern infrastructure, increasing operational efficiency, and positioning Saudi Arabia as the regional technology hub.
The Brazil C4ISR market forms a vital part of the modernization agenda for the nation's defense, entailing sophisticated systems for command, control, communications, computers, intelligence, surveillance, and reconnaissance. As South America's largest economy and military force, Brazil has always taken the lead in developing advanced defense IT infrastructure to address regional security challenges and emphasize its strategic autonomy.
The data center market in Brazil has emerged as a vital cog in Latin America's wheel of digital transformation. With the increasing adoption of digital technologies, the need for reliable, secure, and scalable data storage and processing infrastructures is rapidly rising among enterprises, governments, and consumers.
The Saudi Arabia e-commerce market is undergoing a major transformation, becoming one of the fastest-growing digital economies in the Middle East. It reached a value of USD 222.9 Billion in 2024 on account of the rapidly expanding digital landscape, government initiatives like Vision 2030, and the increasing adoption of mobile commerce (m-commerce) and digital payment solutions.
The Saudi Arabia telecom market is undergoing rapid transformation mainly driven by accelerated digitalization, robust policy support, and growing consumer connectivity needs. The industry serves as a critical pillar of the Kingdom’s Vision 2030 strategy which aims to diversify the economy and establish Saudi Arabia as a digital hub in the Middle East.
The Australia legal services industry is undergoing rapid change driven by growing demand, technological advancement, and evolving regulation. Firms that are innovating while upholding quality, ethics, and client trust are succeeding. Regulatory complexity is fueling advisory work, technology is reshaping service delivery, and Australia’s position is enabling regional growth.
The Latin America carbon footprint management market represents a critical frontier in the global transition toward sustainable business practices and environmental accountability. As organizations across the region confront mounting pressure from stakeholders, investors, and regulatory bodies, the demand for sophisticated carbon emission tracking systems has intensified dramatically.
The UK's ATM market, therefore, stands as an important pillar in its financial ecosystem for the benefit of millions of consumers and businesses who rely on timely, convenient, and secure ways of accessing cash. However, despite the rapid acceleration of contactless payments and digital banking, ATMs remain indispensable across the urban and rural areas.
The India smartphone industry has cemented its position as one of the world's most critical and dynamic technology markets, undergoing a profound transformation driven by consumer aspiration and technological advancement. Far from merely being a volume-driven segment, the market is experiencing a significant value premiumisation trend, where consumers are increasingly upgrading to feature-rich and higher-priced devices.
India is now undergoing a transformative phase of the Internet of Things (IoT) industry, as it solidifies its role as a key facilitator of the ambitions of the Indian economy to become digital. IoT, which was initially viewed as a futuristic idea, has quickly become a baseline technology in the consumer, enterprise, and public infrastructure domains.
As banks and startups embrace modernization, secure and efficient digital platforms are attracting strong local and global investment. Artificial intelligence (AI), automation, and predictive analytics are redefining how finance works in Australia. These tools make transactions faster, decisions sharper, and client experiences more intuitive. From fraud detection to personalized banking, technology is transforming every corner of the market.
The Europe artificial intelligence market stands at a pivotal juncture, balancing unprecedented technological advancement with complex regulatory frameworks and strategic imperatives. As businesses across the continent accelerate their AI adoption Europe initiatives, the region emerges as a distinctive force in global artificial intelligence development, characterized by its commitment to ethical innovation and human-centric technologies.
India’s rapid digitalization has transformed the way organizations operate, connect, and deliver services. However, this digital shift has also exposed enterprises to a surge in cyber threats, ranging from ransomware and phishing to sophisticated data breaches and identity theft. As companies across sectors increase their reliance on digital platforms, the frequency and complexity of cyberattacks have intensified, forcing both public and private institutions to prioritize cybersecurity investments.
The Europe drones market has evolved into an indispensable aspect of the continent's operational and technological environment. Drones are now sequentially incorporated into sectors that rely on precision, real-time monitoring, and safe performance of field operations. Their capacity for aerial monitoring, environmental condition evaluation, and real-time observation allows companies to achieve greater accuracy in decision-making while reducing reliance on human intervention in hazardous areas.
The 3D printing industry is currently experiencing a revolutionary growth that has had a radical change on the manufacturing operations within the industries of the world. The technology is also referred to as additive manufacturing (AM), and it is the way to create three-dimensional objects by adding layers to the digital model, thereby providing unprecedented flexibility in both design and production. The 3D printing sector of the world has become a pivotal source of innovation enabler, efficiency, supply chain resilience, and competitive edges to organizations as small-and-medium-sized as small businesses to Fortune 500 organizations.
The education sector in India is witnessing a sea change with digital learning becoming integral to both formal and informal education. The rapid rise of online education platforms has reshaped the way schools, coaching institutes, and higher education centers impart learning experiences, accelerated by pandemic-driven digital acceleration. And today, technology-enabled education is no longer confined to urban centers; it is reaching Tier-2 and Tier-3 cities, democratizing access to quality learning resources for millions of students.
India’s healthcare sector is undergoing a technological transformation, with artificial intelligence positioned as a central driver of change. With a population exceeding 146.39 crore and a system challenged by issues of accessibility, affordability, and quality, AI is no longer optional but essential for building sustainable healthcare solutions.
India health and wellness market is on a fast track, with more people paying attention to preventive care and overall well-being. IMARC Group stated that the market hit USD 156.01 Billion in 2024, owing to the boom in nutraceuticals, fitness, and digital health platforms. Artificial intelligence (AI) is bringing a fresh wave of innovation to health and wellness, enhancing personalized fitness routines, predictive health insights, and more efficient wellness tracking.
Japan's ecotourism industry is experiencing a remarkable transformation, positioning the country as Asia's leading destination for sustainable travel experiences. The market, which is reaching unprecedented valuations of USD 12,999.78 Million in 2024, is demonstrating exceptional growth momentum with projections indicating an expansion to USD 34,542.85 Million by 2033, representing a robust compound annual growth rate (CAGR) of 11.47% during the 2025-2033 period.
The United Kingdom is currently establishing itself as one of Europe's most dynamic blockchain innovation hubs, demonstrating remarkable resilience and growth despite global economic uncertainties. The UK blockchain market reached a valuation of USD 0.66 Billion in 2024 and is projecting explosive growth toward USD 54.63 Billion by 2033, exhibiting a compound annual growth rate (CAGR) of 63.26% during the forecast period. This extraordinary trajectory is placing the nation at the forefront of distributed ledger technology adoption and development.
Japan has been a world leader in robotics, especially industrial, for decades. The nation's unflinching faith in technology development, precision manufacturing, and automation has made it a world leader in industrial robotics. Industrial robots have transformed the manufacturing process to become necessary equipment in today's manufacturing, helping companies increase productivity, retain quality, decrease errors in operations, and enhance efficiency in processes.
The Europe 3D printing market stands at the forefront of a manufacturing revolution that is reshaping industries across the continent. As additive manufacturing technologies mature and expand beyond prototyping into full-scale production, European manufacturers, healthcare providers, and aerospace companies are increasingly embracing these transformative solutions. With substantial government backing, strategic industry collaborations, and breakthrough material innovations, the European 3D printing landscape is positioned for remarkable expansion through 2033.
The Philippines gaming industry has emerged as Southeast Asia's fastest-rising digital entertainment powerhouse, achieving USD 4,822.00 Million in gross gaming revenue for 2024. This explosive growth signals a fundamental transformation in how Filipinos engage with interactive entertainment, driven by the rapid adoption of augmented reality (AR) and virtual reality (VR) technologies.
The data monetization market has emerged as a critical pillar of the modern digital economy, transforming how organizations create value from their information assets. As businesses recognize data as a strategic asset, the ability to extract financial value has become a competitive imperative. The global data monetization industry encompasses diverse approaches, ranging from direct data sales to indirect monetization through enhanced decision-making. According to IMARC Group, the industry reached USD 4.1 Billion in 2024. It is projected to reach USD 16.1 Billion by 2033, at a CAGR of 15.76% during 2025-2033.
The global access control market is entering a phase of serious expansion and transformation. In 2024, IMARC placed its value at USD 10.6 Billion, with a forecast of USD 18.8 Billion by 2033 (CAGR of 6.5 %). This reflects how rapidly the underlying technologies, threat landscape, and regulatory regimes are shifting. Across enterprises, campuses, infrastructure sites, and smart buildings, access control is evolving from door-level locks to identity, context, behavior, and integration. In many markets, access control is becoming an essential bridge between physical security and cybersecurity.
The media consumption landscape in Japan is in the midst of a revolutionary change with over-the-top (OTT) services as a leading force behind the way viewers are consuming entertainment content. OTT services, which provide video content directly on the internet and not via conventional cable or satellite television, are fast becoming a standard in Japanese homes. The growth of the Japanese OTT industry has been shaped by various factors, from technological innovations to changing consumer tastes.
The e-commerce market in Mexico is thriving, driven by increased internet access, mobile shopping, and smooth digital payment options. IMARC Group estimated that the market reached an impressive USD 47.52 Billion in 2024, signifying a distinct transition towards online shopping.
The global Industry 4.0 market is experiencing strong momentum, propelled by the integration of smart technologies across manufacturing, logistics, and energy sectors. With automation, connectivity, and data intelligence at its core, Industry 4.0 is reshaping how enterprises design, produce, and deliver products.
The global soft skills training market size was valued at USD 33.39 Billion in 2024. Looking forward, IMARC Group estimates the market to reach USD 92.59 Billion by 2033, exhibiting a CAGR of 11.40% during 2025-2033. This substantial growth reflects a fundamental shift in how organizations approach workforce development, as the recognition of soft skills as strategic assets rather than supplementary competencies becomes universal across industries.
The global Wi-Fi infrastructure market is experiencing unprecedented expansion, fundamentally reshaping how organizations operate and consumers interact with technology. According to Wi-Fi Alliance, the official industry certification body, 4.1 Billion Wi-Fi devices are forecast to ship in 2024, contributing to 45.9 Billion cumulative Wi-Fi shipments over the technology's 25-year lifetime.
Australia's mobile money industry is experiencing unprecedented transformation as artificial intelligence reshapes the landscape of digital payments, mobile wallets, and financial services. The integration of sophisticated AI technologies has revolutionized how Australians conduct transactions, manage their finances, and interact with digital payment platforms. From smartphone-based payment solutions to advanced fraud detection systems, AI is driving innovation across every facet of the mobile money ecosystem.
India vehicle tracking market is undergoing a significant transformation, with artificial intelligence emerging as a central driver of innovation. According to the IMARC Group’s report, the market size reached USD 0.90 Billion in 2024.
India stands at a decisive stage where economic growth must advance in parallel with environmental sustainability. According to an IMARC Group report, the Indian green technology and sustainability market reached USD 837.2 Million in 2024, reflecting the nation’s growing commitment to sustainable development.
Closed-Circuit Television (CCTV) cameras are electronic monitoring systems that are used to watch, record, and send video images for security and observational reasons. Unlike television broadcasting, CCTV signals are sent to selected monitors or recording devices, and hence they are the backbone of contemporary security infrastructure.
India's educational technology sector stands at the precipice of a transformative revolution, with artificial intelligence (AI) emerging as the primary catalyst driving unprecedented growth and innovation. The convergence of AI technologies with educational platforms is fundamentally reshaping how millions of Indian students access, consume, and engage with learning content, creating an ecosystem that democratizes access to quality education across the country’s diverse linguistic and socioeconomic groups.
Japan’s higher education sector is at a major turning point as demographic and economic pressures converge with technological disruption. One of the major trends in the Japan higher education market include the number of students entering universities has been shrinking for decades due to the country’s aging population, creating structural challenges for institutions that once relied on a stable or growing pool of applicants.
Japan, a global leader in technological innovation, is at the forefront of a new digital revolution in its satellite communication sector. As the nation pushes toward a more connected and resilient future, the integration of Artificial Intelligence (AI) is proving to be a critical catalyst. From enhancing network performance to automating complex operations AI is not just an add-on it is a foundational technology reshaping the very fabric of satellite communication.
Generative artificial intelligence (AI) is rapidly becoming one of the most influential technologies of the decade, and its global footprint is continuously expanding. Nations across the world are exploring its transformative potential, with Japan emerging as a unique hub where technological innovation, traditional industries, and forward-looking government policies are converging.
A battery charger is a piece of electrical equipment that is used to recharge a rechargeable battery by imposing an electric current upon it. The main purpose of a charger is to transfer alternating current (AC) from the power source into an appropriate direct current (DC) that has the required voltage and current for the particular type of battery. Battery chargers play a vital role in a broad variety of applications, from consumer devices and electric vehicles (EVs) to industrial equipment and renewable energy systems.
Indian manufacturing continues to grapple with significant losses caused by defects, rework, and product returns, which weaken profitability and competitiveness. As per an industry report, in FY22, the total return order volume in India stood at 14.86%. Furthermore, high-volume industries such as automotive, FMCG packaging, textiles, and electronics are particularly exposed, where even a small defect rate can translate into substantial financial setbacks. Industry research states that in mature operations, the Cost of Poor Quality (COPQ) can account for as much as 15–20% of total sales. Moreover, Return Prime’s recent report shows that returns remain a major challenge in e-commerce sales, with 17.6% of all orders being sent back.
Industry 4.0 has been a defining milestone in the advancement of manufacturing. It is responsible for introducing automation, digitization, and data-driven processes that significantly enhanced productivity and precision. Presently, India is moving into the next phase of manufacturing, that is, autonomous factories. Here, artificial intelligence (AI) goes beyond simple automation, enabling systems to render decisions, learn from changing conditions, and continuously improve operations. This shift has the potential to reshape industrial growth in the country and establish new standards for smart manufacturing.
Indian manufacturers are facing difficulties due to rising input costs, shortages of skilled labour, unplanned machine downtime, and inconsistent product quality. According to an industry report, during the July–September quarter of FY25, raw material expenses for 1,679 listed non-financial manufacturing companies increased by 5.1%, outpacing sales growth, which rose by only 3.3%. Similarly, the Global Talent Shortage Survey 2025 reported that 80% of Indian employers report difficulty finding skilled talent, compared to the global average of 74%, highlighting a severe talent crunch.
According to the International Energy Agency (IEA), global energy-related CO2 emissions grew by 0.8% in 2024 to a record 37.8 gigatonnes, driving atmospheric concentrations to an unprecedented 422.5 ppm. This has led to an increased urgency in addressing climate change. Similarly, the industries are facing unprecedented pressure to rethink their operations due to the energy demand rising by 2.2% in 2024, which is faster than the annual average of 1.3% witnessed between 2013 and 2023.
India is among the fastest-growing economies globally. The nation is currently the fourth-largest economy in the world and is on its way to becoming the third-largest, with an estimated GDP of USD 7.3 Trillion by 2030. This momentum is not only strengthening India’s economic resilience but also opening lucrative opportunities for businesses, investors, and technology providers aligned with the country’s growth vision.
The role of artificial intelligence (AI) in modern project management has transitioned from a theoretical concept to a strategic imperative. As businesses navigate increasingly complex projects in a data-driven world, AI is emerging as a powerful force for efficiency, accuracy, and innovation.
The artificial intelligence market is no longer niche. Current projections value the market at a significant level today, with strong growth expected as generative AI matures, computing costs decline, and enterprise pilots scale into full production.
The data center sector in Japan is at the epicenter of a tech revolution, wherein artificial intelligence (AI) is fundamentally redefining how digital infrastructure manages, scales, and adapts. With the country progressing toward digital transformation in various industries, AI has been the force behind unprecedented innovation in the design, management, and optimization of data centers.
In the modern era, the global video streaming market is fundamentally reshaping the entertainment landscape, driven by the dual forces of digitalization and the escalating demand for on-demand content. Artificial intelligence (AI) also serves as a pivotal catalyst for this growth, enabling the personalization of user experiences through tailored recommendations, improved content discovery, and enhanced audience engagement.
The global gaming console market is undergoing a significant transformation, fueled by the adoption of artificial intelligence (AI) and an increasing demand for interactive entertainment.
For decades, call centers have played a central role in customer service. Traditionally staffed with large teams of agents, they operated as cost-heavy units designed to handle inquiries, complaints, and service requests. While essential, this model was often associated with inefficiencies, long wait times, and high employee turnover.
According to IMARC Group, the global identity verification market was valued at USD 13.8 Billion in 2024 and is projected to reach USD 46.4 Billion by 2030, expanding at a CAGR of 14.4% during 2023–2030. This strong growth is being fueled by the increasing adoption of artificial intelligence (AI) and machine learning (ML), which are enabling higher levels of automation, fraud detection, and real-time authentication.
Japan is a leader in digital transformation, known for being one of the most advanced nations in technology globally. Artificial Intelligence (AI) is becoming an integral force across various sectors, and the telecom industry is no exception.
Generative AI is revolutionizing industries by bringing fresh, game-changing solutions that boost creativity and streamline workflows. Whether it’s automating content creation or optimizing complex processes in fields like healthcare and finance, AI is opening doors to exciting new possibilities.
The e-commerce market has undergone a seismic shift in the past twenty years. What started as simple, text-based product pages has grown into a complex web of intelligent platforms capable of customizing experiences for every individual user. At the core of this evolution is Artificial Intelligence (AI).
The global laptop and tablet market includes portable computing devices for both personal and commercial use, providing mobility, flexibility, and connectivity. Laptops extend desktop computers' power and functionality in a portable package, while tablets provide light-touch screen interfaces for consumption of media, creative work, and on-the-go productivity.
The global cloud gaming industry is experiencing an unprecedented surge, driven by technological advancements and evolving consumer preferences. As the market expands, Artificial Intelligence (AI) stands out as a pivotal force, reshaping every facet of the cloud gaming landscape, from infrastructure to player experience. It enables smarter resource allocation, real-time content personalization, latency reduction, and advanced game logic.
The global power bank market is experiencing steady growth as digital lifestyles become more integrated into everyday routines. With rising dependence on smartphones, tablets, laptops, and wearables, power banks have shifted from being simple backup batteries to versatile, feature-rich accessories that fulfill the needs of a wide range of users. Consumers now prefer power banks with fast-charging capabilities, higher battery capacity, and environmentally responsible designs.
The hybrid cloud market across the world has been changing at a very fast rate, with companies globally adopting the mix of on-premises and cloud-based infrastructures to fuel innovation and operational effectiveness.
Japan’s artificial intelligence (AI)-driven three-dimensional (3D) printing startups are redefining manufacturing by merging speed, sustainability, and precision. Japan’s additive manufacturing scene is moving beyond prototypes—it's rewriting how industries build, design, and innovate.
As a global leader in technology and innovation, Japan has increasingly recognized the critical importance of cybersecurity to protect its digital infrastructure.
Electric cables or power cables are the fundamental parts employed for the transfer of electrical power or signals over short and long distances. They generally comprise one or more conductors, typically composed of copper or aluminum, covered with insulating materials and protective sheaths. Electric cables, based on their use, differ in structure, including low-voltage, medium-voltage, and high-voltage power cables, control cables, instrumentation cables, or data transfer cables like fiber optics.
Smart Factory and Industry 4.0 Integration is a comprehensive set of services that helps firms overhaul their manufacturing processes by embracing new technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), robotics, big data analytics, and cloud computing.
Digitalization is reshaping the very essence of travel, transforming it into a more personalized, convenient, and efficient experience than ever before. With the growing popularity of travel platforms, travelers now have the power to plan and book their entire journey with just a few taps on their smartphones.
Product and facility certification support offers professional assistance to companies in resolving complicated processes of product certification and facility certification. Our services facilitate adherence to global standards and regulatory guidelines to ensure hassle-free market entry and operational continuity across global markets.
The global e-commerce landscape is rapidly transforming, propelled by several evolving e-commerce industry trends. These fundamental shifts encompass changes in consumer behavior, rapid technological advancements, and increasing internet accessibility worldwide. As a direct result, brands are now prioritizing quick delivery, mobile-centric platforms, and deeply customized digital experiences.
Setting up a drone manufacturing plant with a step-by-step business plan covering setup, costs, equipment, compliance, and market strategy.
India’s textile industry is undergoing a transformative shift led by the government’s visionary PM MITRA (Mega Integrated Textile Region and Apparel) Parks initiative. With a mission to establish India as a worldwide leader in textiles, this program is creating world-class integrated manufacturing zones that drive innovation, reduce production costs, and boost sustainability.
India’s sports technology sector is gaining extraordinary momentum, driven by the digitalization of sports leagues, enhanced fan engagement, and increasing investments in athletic performance solutions. With the Indian Premier League (IPL) 2025 poised to become the most tech-driven tournament to date, the market is no longer restricted to wearables and broadcasting; it now powers every aspect of sports, from grassroots training to AI-based strategic decision-making.
India is becoming a popular location for foreign manufacturers because of its quickly expanding economy, affordable labour costs, and consistent government support. For businesses looking to establish manufacturing facilities in the nation, the Government's "Make in India" incentive program offers an alluring alternative. This guide will assist in comprehending the crucial requirements for setting up a manufacturing facility in India.
Factory audits are important for companies that intend to ensure compliance and quality in operations as well as supply chain efficiency. India is experiencing unparalleled growth in manufacturing. The skills to perform factory audits effectively can be used to counter most risks related to Indian supplier relationships. This blog gives a complete step-by-step guide on how to perform factory audits in India, including a complete checklist.
Establishing a manufacturing plant is a major investment that requires meticulous planning and a thorough understanding of the associated costs. Whether a seasoned entrepreneur or an industrial novice, understanding the "cost equation" is vital for making informed financial decisions and ensuring the long-term profitability of the operations. This blog will break down the various expenses associated with establishing a manufacturing facility in India.
Setting up a manufacturing plant is a significant milestone for any business, but it comes with complexities that require careful planning, research, and execution. From selecting the right location to ensuring regulatory compliance and operational efficiency, every aspect needs expert attention to guarantee success. This is where IMARC Group steps in, offering comprehensive pre-feasibility studies and consultation services to help businesses establish manufacturing plants seamlessly.
The manufacturing sector is a cornerstone of India's economy. It accounted for about 14% of the overall GDP of the nation in 2024 and has employed millions of people across the country. India has been a rising manufacturing powerhouse globally and 2025 is expected to be a turning point. Given the better government focus and strong labor force, along with the increasingly effective infrastructure, India is likely to be sealed as a prime destination for global manufacturers.
Many have encountered this scenario: visiting a website with enthusiasm to purchase a product seen in an advertisement, only to face challenges such as navigating a complex interface, unresponsive customer service, and a cumbersome checkout process.
The OTT industry is experiencing a pivotal transformation, signaling the advent of a new digital entertainment era. Consumers are increasingly demanding convenience and personalized experiences on OTT platforms. As a result, platforms are investing massively in technologies such as AI to enhance the recommendations of content and improve user experience.
From established giants in the United States and Europe to fast-paced markets in Asia, the e-commerce revolution is creating a competitive marketplace that transcends geographical boundaries. Vietnam stands out as a key force in this global trend, showcasing the potential of e-commerce to drive national economic transformation. The country’s e-commerce industry is witnessing tremendous growth, driven by new markets and growth opportunities in established markets.
Head-mounted displays consist of small displays with in-built sensors and optics that project images directly onto the user's eyes. They provide a virtual reality (VR) or augmented reality (AR) experience that allows users to interact with digital objects or environments. They resemble glasses or goggles and are designed to be worn on the head. They comprise many components, such as a controller, sensor, camera, lens, goggles, head tracker, case, connector, display, battery, processor, memory, pico projector, and accessories. Tracking systems and sensors detect the user's head movements and adjust the displayed content accordingly, offering the user a more realistic, immersive, and interactive experience.
5G technology or fifth-generation wireless technology is the latest advancement in mobile communication systems that provides enhanced data transfer speeds, reduces latency rates, improves reliability, and increases network capacity. This technology operates in the mm-wave spectrum, the spectrum band ranging from 30 to 300 gigahertz (GHz), which facilitates high-speed networks and faster data delivery. 5G technology supports the growth of emerging technologies like artificial intelligence (AI), machine learning (ML), and edge computing, enabling new business models and unlocking economic potential. It enhances the performance of business applications and digital experiences, such as video conferencing, online gaming, live streaming media, and self-driving cars. The components included in 5G technology are hardware, software, and services, and it is utilized in a wide range of applications, such as automation, video services, connected vehicles, smart homes, virtual & augmented reality, and monitoring & tracking. For better connectivity of networks, various industries, such as manufacturing, automotive, transportation & logistics, media & entertainment, energy & utilities, healthcare, government, and others, have deployed 5G technology extensively.
Robotics is the branch of engineering that deals with designing, constructing, and operating robots. Robots are programmable machines capable of carrying out tasks autonomously or semi-autonomously. Major types of robotics include industrial and service robots, combining elements of mechanical engineering, electrical engineering, computer science, and artificial intelligence (AI). Industrial robots encompass articulated, Cartesian, SCARA, and cylindrical robots. Service robots serve personal, domestic, and professional purposes, used in various applications, such as household tasks, entertainment, defense, fieldwork, logistics, healthcare, infrastructure, mobile platforms, and cleaning, and more. Robotics can efficiently and accurately perform tasks in environments that may be hazardous or challenging for humans. Robots reduce human labor, enhance production efficiency, lower costs, and improve product quality in various industries. Robotics is further categorized into types such as industrial robotics, food robotics, warehouse robotics, smart robotics, automotive robotics, agriculture robotics, logistics robotics, construction robotics, space robotics, and others. Nowadays, robotics has become an important part of many industries, even being used to explore deep oceans and space. Additionally, it is employed in creating autonomous vehicles, performing surgery, and conducting medical diagnoses.
Artificial Intelligence (AI) chips are designed to accelerate and optimize AI and Machine Learning (ML) workloads. The field of AI involves tasks such as pattern recognition, data analysis, and decision-making, which often require massive parallel processing. AI chips perform various tasks like deep learning, neural network processing, and other computationally intensive operations. These chips are tailored to support the parallel computing needs of AI workloads, making them well-suited for these tasks.
Oman is situated on the southeastern coast of the Arabian Peninsula. It boasts a rich cultural heritage, stunning landscapes, and a diverse range of attractions, making it an emerging destination in the tourism market. The country offers a wide array of tourist activities, including sunbathing, swimming, kitesurfing, diving, snorkeling, boating, among many others. Beach activities and kite surfing are popular in Muscat, Al Sawadi Beach, Alzaiba Beach, and Masirah Island, while desert safaris are a highlight in Wahiba Sands. Oman's rich historical heritage includes numerous UNESCO World Heritage Sites, ancient temples, forts, and palaces, such as Bahla Fort and the Archaeological Sites of Bat, Al-Khutm, and Al-Ayn.
Virtual reality (VR) gaming represents a new generation of computer games that leverage VR technology to provide high-definition visuals, spatial audio, and precise motion tracking, creating a sense of presence and immersion. VR gaming offers a 360-degree view of the virtual environment, keeping players engaged for longer periods compared to traditional gaming. Additionally, VR gaming is used in rehabilitation and the treatment of phobias, anxiety disorders, and other psychological conditions. It is also employed to train soldiers in combat scenarios, strategy, and decision-making.
Cloud computing delivers computing services over the internet, including servers, storage, databases, networking, software, analytics, and intelligence. It promotes faster innovation, flexible resource allocation, and economies of scale. Moreover, it offers numerous advantages, such as cost efficiency, mobility, scalability, reliability, and automatic software updates, among others.