Which Japan 3D Printing Segments Lead Growth: Metal, Polymer, Printers, Materials, or Services?
Introduction: Which Segments Power Japan's 3D Printing Market
The Japan 3D Printing Market is no longer a niche prototyping story. It is a precision-manufacturing market moving toward industrial-scale production, and the segment mix is shifting faster than the headline number suggests. The market grew from USD 2.02 Billion in 2025 to an estimated USD 2.48 Billion in 2026 and is projected to reach USD 9.08 Billion by 2034, expanding at a CAGR of 17.60% during 2026-2034.
Three forces sit behind that trajectory. Government-backed reshoring and automation programmes are pushing small and mid-sized manufacturers toward digital fabrication, automotive and aerospace buyers are qualifying additively manufactured parts for functional use, and Japan's shrinking pool of skilled production workers is making automation an economic necessity rather than an option. Each of these drivers favours different segments, which is why growth is uneven across metal, polymer, printers, materials and services.
One development captures the direction of travel. In February 2026, Japan approved its first two-storey, 3D-printed reinforced concrete residence, a 50-square-metre home developed by Kizuki that meets the country's seismic standards. The approval moved additive manufacturing from prototype validation into building-code compliance, a threshold that matters far more than any single equipment launch.
This blog breaks down which segments lead the Japan 3D Printing Market by size and by growth rate, examines the regional hotspots and competitive strategies, and sets out the policy frameworks, structural risks and opportunities that will define the market through 2034.
Key Takeaways
- The Japan 3D Printing Market stood at USD 2.02 Billion in 2025, an estimated USD 2.48 Billion in 2026, and is forecast to reach USD 9.08 Billion by 2034, expanding at a CAGR of 17.60% during 2026-2034.
- Fused deposition modeling remains the largest technology segment with a 26.8% share in 2025, but electron beam melting is growing fastest at roughly 21.2% CAGR, which is where the metal opportunity concentrates.
- The Kanto region accounts for a 34.1% share in 2025, anchored by Tokyo's concentration of manufacturers, research institutions and precision-engineering demand.
- The most notable recent development is the February 2026 approval of Japan's first two-storey, 3D-printed reinforced concrete home, developed by Kizuki, which brought additive construction inside the national seismic compliance framework.
- The defining trend is metal additive manufacturing consolidation, as equipment makers, material suppliers and service providers combine to offer integrated design-to-post-processing solutions for automotive, aerospace and medical buyers.
Market Size, Share & Growth Outlook
According to IMARC Group, the Japan 3D Printing Market was valued at USD 2.02 Billion in 2025, is estimated at USD 2.48 Billion in 2026, and is projected to reach USD 9.08 Billion by 2034, expanding at a CAGR of 17.60% during 2026-2034. For context, the market stood at USD 0.90 Billion in 2020 and is anchored at USD 4.55 Billion in 2030, which means roughly four-fifths of the forecast expansion from 2026 is still ahead of the market, not behind it. The leading segments are:
- Technology: Fused deposition modeling accounts for a 26.8% share in 2025, reflecting its low material cost and fast iteration cycles for functional part production in consumer electronics and machinery. Electron beam melting is the fastest-growing technology at approximately 21.2% CAGR (2026-2034), followed by digital light processing at roughly 19.5% CAGR, while fused deposition modeling grows at a steadier 16.8% through 2034.
- Offering: Printers command the largest revenue pool at a 37.4% share in 2025, as manufacturers keep investing in industrial-grade hardware and metal-printer production lines. Services follow at 28.1%, supported by growing outsourcing to managed 3D-printing bureaus. Material accounts for 21.5%, while software, at 13.0%, is the fastest-growing offering as AI-integrated design tools gain traction across aerospace and healthcare workflows.
- Material: Polymer filaments and powders lead on volume, given their lower cost per part and wide availability, while metal feedstock is the faster-growing category as aerospace, medical-implant and tooling applications scale. Sustainable and recycled filaments and powders are an emerging sub-segment rather than a leading one.
- Application and End User: Prototyping and tooling remain the largest application blocks, with automotive, consumer electronics, machinery and healthcare the dominant end-user groups. Healthcare demand skews toward patient-specific devices, while automotive demand is concentrated in jigs, fixtures and lightweight structural parts.
- Region: The Kanto region holds a 34.1% share in 2025, the single largest regional pool, reflecting Tokyo's manufacturing and R&D concentration.
The practical reading is that Japan's market is a hardware-led market with a services undercurrent. Printers generate the most revenue today, but the growth rate belongs to metal technologies and to the service bureaus that let manufacturers access metal capability without owning the equipment.
Recent News & Mega Announcements
Developments between 2025 and 2026 show the market moving from equipment acquisition toward application qualification:
- Kizuki's 3D-printed concrete home cleared Japanese standards (February 2026): Japan approved its first two-storey, 3D-printed reinforced concrete residence, a 50-square-metre unit that meets strict seismic requirements. The significance is regulatory rather than technical: once a printed structure clears national seismic criteria, construction-grade printing becomes bankable for developers and insurers, not just a demonstration project.
- Skylrk's 3D-printed sneaker debuted in Tokyo (December 2025): Justin Bieber's brand Skylrk ran a four-day pop-up in Harajuku and introduced its first 3D-printed sneaker, the "Earth Bender." Consumer lifestyle footwear is a low-certification, high-visibility application, and its arrival in a Tokyo retail format signals that additive manufacturing is now a commercial product decision in Japan's consumer segment.
- Metal additive manufacturing consolidation accelerated: Equipment manufacturers, material suppliers, software developers and service providers continued forming partnerships and pursuing acquisitions to offer integrated design, printing, materials and post-processing. For Japanese buyers this shortens the qualification cycle, because a single vendor now carries responsibility for the full process chain.
- Managed 3D-printing services gained ground: Japanese manufacturers increasingly route specialised production to service bureaus such as Ricoh's managed 3D-printing offering, which supports the service segment's 28.1% share of the offering mix.
- Material innovation refocused on plastics and metals (February 2025): Industry analysis highlighted plastics as the leading material family on versatility and cost-effectiveness, with metals the faster-growing category, a split that mirrors Japan's own segment structure.
- Japan's metal printing ambition has deep roots (August 2013): Long-running industry coverage documented a national push aimed specifically at metal 3D printing, with the domestic programme framed around building an industrial metal-printing capability rather than consumer machines. That policy direction is now visible in the metal segment's growth premium.
Industry Trends Shaping 2026
Three trends explain why the segment mix is changing faster than overall market growth would imply. Each one redistributes value between printers, materials and services.
1. Metal Additive Manufacturing Consolidation
The metal additive manufacturing chain is consolidating. Equipment manufacturers, powder suppliers, software developers and post-processing specialists are forming partnerships or pursuing acquisitions so that they can offer integrated solutions covering design, printing, materials and finishing in one contract. In Japan, this matters because the buyer is typically a tier-one automotive or aerospace supplier that cannot absorb the qualification risk of stitching together four separate vendors. Consolidation improves technology standardisation, reduces production cost per qualified part, and strengthens domestic supply chains. It also gives established industrial firms a lower-friction route into metal AM adoption across automotive, aerospace, medical and precision-engineering applications, which is precisely the demand base that supports electron beam melting's roughly 21.2% CAGR through 2034.
2. Construction-Grade 3D Printing
Construction-grade 3D printing is moving from pilot to permitted. Builders are exploring automated methods for producing houses, structural components and customised architectural elements, cutting material waste, construction time and dependence on manual labour. The February 2026 approval of Kizuki's two-storey, 3D-printed reinforced concrete residence is the pivotal marker: a 50-square-metre home that satisfies Japan's seismic standards demonstrates that automated construction can deliver safe, precise housing rather than only design-led prototypes. With a construction sector facing chronic labour shortages and a continuing need for rapid rebuilding in disaster-prone regions, printed construction addresses two national problems at once. It also pulls demand toward large-format printers, specialised concrete mixes and certification services, none of which sit in the traditional polymer prototyping stack.
3. Sustainable and Recycled Print Materials
Material sustainability is becoming a procurement criterion rather than a marketing claim. Manufacturers are developing filaments and powders from recycled plastics, bio-based polymers and reusable metal feedstock, reducing production waste, carbon emissions and dependence on virgin resources. Adoption is rising across automotive, consumer goods, construction and education, and the appeal is commercial as much as environmental: recycled feedstock lowers input cost for the small and mid-sized enterprises that dominate Japan's manufacturing base, while reusable metal powder improves the economics of metal printing, where material can account for a large share of per-part cost. In a market where high material and equipment costs are the primary restraint on adoption, circular feedstock is one of the few levers that improves both cost and environmental performance simultaneously.
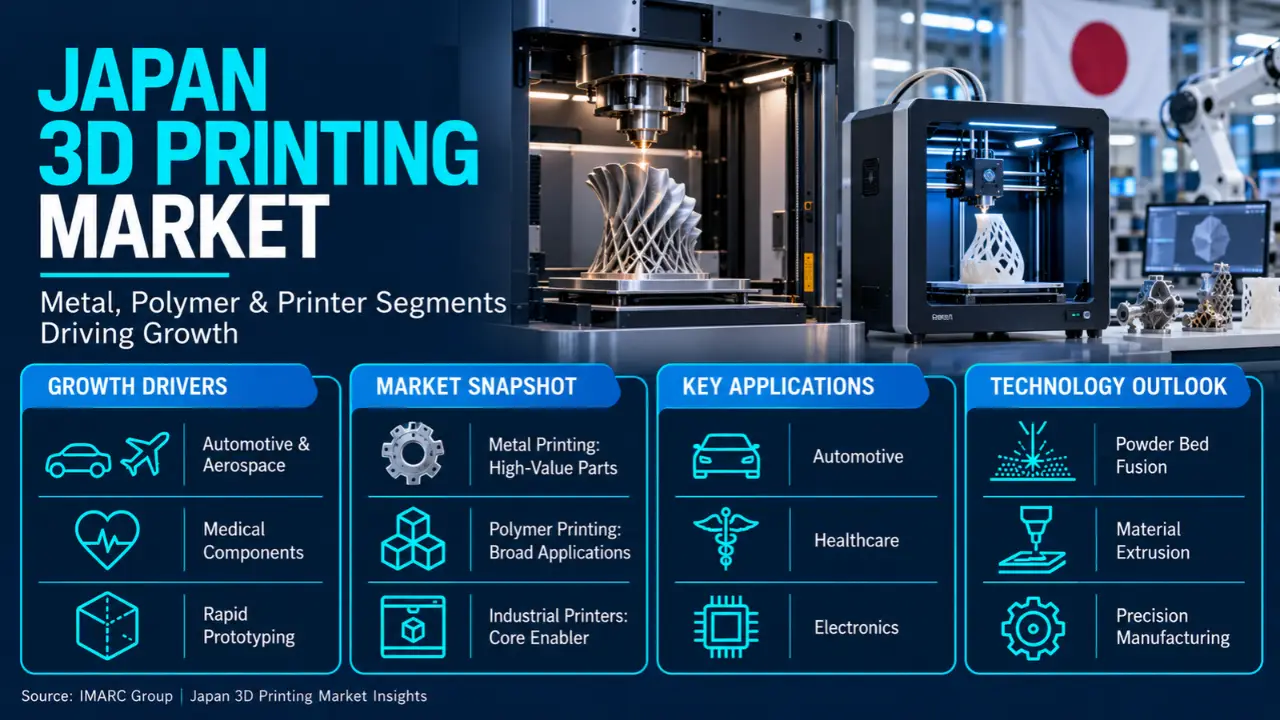
Geographic Hotspots
Japanese additive manufacturing demand is heavily concentrated. The Kanto region accounts for a 34.1% share in 2025, the largest regional pool in the country, anchored by Tokyo's dense concentration of manufacturers, research institutions and precision-engineering demand. The region hosts leading pharmaceutical, automotive and electronics manufacturers alongside top-tier universities that drive additive-manufacturing research collaboration, which is why Kanto leads on both hardware investment and service-bureau revenue. Buyers here tend to be early qualifiers, and the presence of research partners shortens validation cycles for new materials and processes.
The remainder of the market follows Japan's industrial geography. The Chubu region around Aichi carries the automotive supply chain, where metal AM demand is concentrated in tooling, conformal cooling inserts and lightweight structural components, and where gigacasting integration is the most credible near-term opportunity. Kansai contributes through machinery, electronics and a dense small and mid-sized manufacturer base that favours fused deposition modeling on cost grounds. Kyushu has become a semiconductor and electronics manufacturing cluster, creating demand for precision jigs, fixtures and thermal-management parts. Northern and western regions contribute smaller volumes, but construction-grade printing has a disproportionately large potential there, given labour shortages and rebuilding requirements in disaster-affected areas.
The pattern to note is that regional share is not the same as regional growth. Kanto leads on absolute revenue because of industrial density, while the fastest technology growth (metal and digital light processing) is dispersed across Chubu, Kansai and Kyushu manufacturing clusters where the application demand actually sits.
Competitive Landscape & Key Players' Strategies
Competition in the Japan 3D Printing Industry runs along three visible strategies: metal-hardware innovation, managed services and construction-grade application. The market is led by domestic machine-tool and technology majors, with Sodick, Ricoh and Obayashi Corporation identified as the key players. Very few participants compete on price alone, because qualification and process reliability decide most industrial contracts.
- Sodick: A Japanese precision-machinery manufacturer and key innovator in metal 3D printing, pioneering One Process Milling (OPM) technology that integrates laser powder-bed fusion with high-speed milling for improved accuracy and surface finish. Key products include the OPM250L, OPM350L and PM325S, serving automotive, electronics, medical-device, aerospace and precision-engineering buyers. Its strategic focus is on high-precision metal additive manufacturing, with ongoing work on printing speed, operating rates, material compatibility, automation and large-part production.
- Ricoh: Tokyo-headquartered Ricoh has moved from traditional 2D office equipment into industrial 3D printing, offering equipment, consultancy, design optimisation, prototyping, production and post-processing services under its RICOH All-In 3D Print offering. It positions managed services as an outsourced production route for manufacturers that need additive capability without owning industrial equipment, supporting the service segment's 28.1% share of the offering mix. It is also advancing aluminium binder-jetting technology for lightweight, thermal-management parts used in electric vehicles and electronics.
- Obayashi Corporation: A pioneer in Japan's construction 3D printing market, Obayashi leads the development of on-site additive manufacturing and created Japan's first 3D-printed, earthquake-proof cement building, the 3dpod. This gives it a strong position in construction-grade printing, a segment where regulatory clearance is the main barrier to entry.
The competitive lesson is that hardware leadership alone no longer secures share, whether the strength is metal precision, managed services or on-site construction. The vendors gaining ground are those that can carry a part from design through qualification to finished component, because that is what Japanese industrial buyers are actually purchasing.
Policy & Regulatory Landscape, Challenges & Risks
Government policy has become a primary market force in Japanese additive manufacturing. Key frameworks include:
- METI-backed manufacturing and reshoring programmes: Ministry of Economy, Trade and Industry incentives subsidise additive-manufacturing adoption among small and mid-sized enterprises, with the stated aim of producing complex components domestically via metal 3D printing by 2030. The effect is to pull forward capital investment that would otherwise wait for payback evidence, which is why the printer segment retains a 37.4% revenue share.
- National metal additive manufacturing push: Japan's long-running programme has been directed specifically at metal printing rather than consumer machines, with the objective of building domestic industrial capability. That sustained policy focus, documented as far back as 2013, explains why metal technologies now carry the fastest growth rates in the market.
- Building certification and seismic compliance standards: The approval of Kizuki's two-storey 3D-printed reinforced concrete residence in February 2026 established a compliance pathway for printed structures under Japanese seismic requirements. Certification, not capability, was the binding constraint, so the approval effectively opens the construction segment to mainstream developers.
- Materials and process standards development: Work on uniform standards for materials, process validation, quality assurance and part certification is underway across the ecosystem, supported by industry funding and consolidation among vendors. Standardisation is the precondition for additive parts entering regulated aerospace and medical supply chains at volume.
On the constraining side, several structural risks persist:
- High equipment and material costs: Industrial printers, specialised software, post-processing systems and advanced materials carry high upfront and maintenance costs, with uncertain returns on investment. This delays purchasing decisions, particularly among small and mid-sized enterprises, and keeps a large share of the addressable base dependent on service bureaus rather than direct ownership.
- Limited large-scale production standardisation: The absence of uniform standards across materials, process validation and part certification makes high-volume production difficult. Variation between equipment and production runs reduces consistency, which slows adoption in regulated and high-volume industries where reproducibility is non-negotiable.
- Skilled operator shortage: Japan faces a shortage of professionals skilled in 3D modelling, printer operation, material selection and post-processing. This limits how effectively companies can implement additive manufacturing internally and increases dependence on specialised external service providers, concentrating capability in a small number of bureaus.
- Slow adoption among legacy manufacturers: Many traditional manufacturers remain cautious about replacing established production methods because of high initial costs, certification concerns and uncertain returns. This conservatism slows integration into large-scale industrial operations and means adoption often arrives through a single qualified application rather than a plant-wide transition.
Forecast 2026-2034
The forecast period assumes steady industrial demand rather than a step change. From USD 2.48 Billion in 2026, the market is anchored at USD 4.55 Billion in 2030 and projected to reach USD 9.08 Billion by 2034, a 17.60% CAGR that implies the market grows more than three-and-a-half times over eight years. The compounding profile is back-loaded: growth accelerates as metal qualification cycles complete and as construction-grade printing moves from first approvals to repeatable projects.
At segment level, the divergence matters more than the aggregate. Electron beam melting grows at roughly 21.2% CAGR (2026-2034), driven by aerospace and medical-implant demand for high-strength metal parts, where the willingness to pay for certified performance is highest. Digital light processing follows at approximately 19.5% CAGR, supported by jewellery and dental prototyping, applications with short design cycles and low certification burden. Fused deposition modeling, the largest technology segment at 26.8% share, grows at a steadier 16.8% through 2034, still expanding but ceding relative share as metal scales.
On the offering side, printers should retain revenue leadership because industrial hardware purchases are large and lumpy, but services are the segment to watch. As metal adoption rises and in-house skills remain scarce, the share of production routed to managed bureaus increases, which is why the service category already holds 28.1% of the offering mix. The plausible outcome by 2034 is a market where hardware still generates the most revenue, metal generates the most incremental growth, and services capture the margin that comes from qualification expertise.
Opportunities for Stakeholders
The growth segments point to specific, actionable openings:
- Metal AM suppliers and integrators: Automotive gigacasting offers the clearest volume opportunity, using metal printing to produce complex mould inserts, conformal cooling channels, lightweight components and customised tooling. Japan's automotive base can accelerate adoption by cutting tooling lead times and improving casting efficiency, and electron beam melting's roughly 21.2% CAGR indicates where capacity should be built.
- Construction and building-material players: Construction 3D printing enables faster, automated and material-efficient production of homes, structural components and customised architectural designs, while addressing labour shortages, reducing waste and supporting rapid rebuilding in disaster-prone regions. The February 2026 Kizuki approval provides the compliance template.
- Healthcare and dental specialists: Patient-specific devices, implants and dental prosthetics are among the highest-value applications, and digital light processing's roughly 19.5% CAGR reflects that demand. Providers that combine printing with scanning and design workflow capture more of the value than pure printing services.
- Service bureaus and managed-service providers: The skilled-operator shortage is a structural advantage for outsourced production. Bureaus that offer qualification support, not just printing capacity, are positioned to absorb demand from small and mid-sized enterprises that cannot justify in-house metal systems.
- Material producers and recyclers: Recycled plastics, bio-based polymers and reusable metal feedstock improve both cost and sustainability performance, which matters in a market where high material cost is the primary adoption restraint. Material suppliers that document feedstock traceability also gain an advantage as certification requirements tighten.
- Software and automation vendors: Integration with CAD, simulation and smart factory systems is the mechanism through which additive manufacturing enters mainstream production planning, and Japan's estimated USD 12.9 billion in domestic software spending indicates the digital readiness base is already in place.
Metal, Materials and Machines in Motion
The answer to the question in the title is not a single segment. Printers lead the Japan 3D Printing Market on revenue with a 37.4% share, fused deposition modeling leads on technology adoption with 26.8%, and Kanto leads geographically with 34.1%. These are the segments that define the market today. But the segments that lead growth are different: metal technologies, led by electron beam melting at roughly 21.2% CAGR, are expanding fastest, and services at 28.1% of the offering mix are absorbing the demand that manufacturers cannot meet in-house.
That split between size and growth is the central insight for anyone allocating capital in this market. A supplier that optimises only for the largest current revenue pool will underweight the qualification-heavy metal chain and the service capability that surrounds it. A supplier that chases growth without the standardisation and certification work that metal and construction applications demand will stall at the prototype stage.
The trajectory from USD 2.48 Billion in 2026 to USD 9.08 Billion by 2034, at a 17.60% CAGR is achievable on current policy support, automotive and aerospace qualification progress, and the compliance pathway now established for printed construction. The constraint is not demand. It is the cost of entry, the shortage of skilled operators and the slow pace of standardisation, which together determine how quickly Japanese manufacturers convert interest into qualified production.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Battery chargers are essential devices used to recharge batteries in a variety of applications ranging from consumer electronics to electric vehicles (EVs). India, with its growing demand for consumer electronics and the electrification of transportation, still relies heavily on imports for battery chargers.
Solid state drives store data on NAND flash memory chips instead of spinning disks, making them faster, quieter, tougher, and more energy-efficient than hard drives. They are now standard in laptops, desktops, gaming consoles, and servers, and they are the backbone of storage in data centres and AI computing.
The retail automation market sits at the centre of a structural shift in how goods are sold, priced, moved and paid for. According to IMARC Group, The global retail automation market grew from USD 21.2 Billion in 2025 to USD 23.2 Billion in 2026. Looking forward, IMARC Group expects the market to reach USD 40.9 Billion by 2034, exhibiting a growth rate (CAGR) of 7.34% during 2026-2034.
CCTV cameras now watch over homes, shops, offices, factories, highways, railway stations, and entire cities, and India has become one of the fastest-growing surveillance markets in the world.
The Wireless Charging Market is rapidly transitioning from a convenience feature to a foundational technology layer across consumer electronics, electric vehicles, healthcare devices, and industrial automation.
Artificial intelligence has changed what a data center needs. GPU clusters draw several times more power per rack than traditional servers and produce far more heat, so operators need heavier racks, higher-capacity power distribution, larger UPS systems, and liquid cooling that was rare only a few years ago.
Mexico has become one of Latin America's most active data center destinations, as hyperscalers build cloud regions, manufacturers relocate supply chains, and enterprises move workloads off their own premises.
Japan built the world's deepest robotics ecosystem, and it is now rebuilding that ecosystem around artificial intelligence. According to IMARC Group, the Japan Industrial Robotics Market was valued at USD 1,285.76 Million in 2025 and is projected to reach USD 2,864.83 Million by 2034, growing at a CAGR of 9.31% (2026–2034).
The Japan HR Tech Market grew from USD 2.16 Billion in 2025 to USD 2.31 Billion in 2026 and is projected to reach USD 3.93 Billion by 2034, at a CAGR of 6.87% (2026–2034). Rapid AI and machine learning integration across HR processes, stringent labor compliance requirements, and accelerating digital transformation of enterprise HR operations are the key growth catalysts driving Japan Human Resource Technology adoption.
The Japan Digital Printing Market reached USD 1.46 Billion in 2025 and is projected to reach USD 2.51 Billion by 2034, growing at a CAGR of 6.24% (2026–2034). Digital printing transfers digital files directly onto substrates such as paper, fabric, plastic, glass, and ceramic without traditional printing plates, and Japan Digital Printing Industry is undergoing a genuine technology transformation as AI, cloud workflows, and sustainable ink chemistry converge.
Europe's data center sector is drawing renewed investor attention because AI compute demand, digital sovereignty regulation, and renewable-energy siting economics have converged into a single, unusually large capital cycle.
The Japan Supply Chain Management Software Market reached USD 1,194.5 Million in 2025 and is projected to reach USD 1,616.7 Million by 2034, growing at a CAGR of 3.42% (2026–2034), as manufacturers and logistics operators across the country replace manual, spreadsheet-driven planning with connected digital platforms.
The Japan In-App Advertising Market is evolving rapidly as brand budgets shift decisively toward mobile-first channels. The market reached USD 9.21 Billion in 2025 and is projected to reach USD 30.30 Billion by 2034, growing at a CAGR of 14.16% (2026–2034), making this one of the fastest-growing segments within the broader Japan Mobile Advertising Market.
India’s data center sector is entering a defining growth phase. From a handful of facilities concentrated in Mumbai and Bengaluru a decade ago, the India data center industry has evolved into a continental-scale infrastructure ecosystem attracting billions of dollars in global investment.
As the Kingdom advances its economic diversification and technological development agenda, smart city development has emerged as a cornerstone of national strategy. This analysis explores the multifaceted dimensions of smart city initiatives, examining how digital innovation reshapes urban landscapes across Saudi Arabia.
The network security industry stands at the forefront of modern enterprise defense strategies, as organizations worldwide are confronting an increasingly hostile digital landscape. With cyber threats evolving in sophistication and frequency, businesses across every sector recognize that robust network protection is no longer optional but essential for operational continuity and stakeholder trust.
India has emerged as a global powerhouse in technology services, transforming from a back-office support destination to a strategic innovation hub. The nation's technology sector represents a cornerstone of economic development, driving substantial contributions to GDP while creating millions of employment opportunities across urban and rural landscapes.
The process of digital transformation in India has become an extremely fast one in the last several years, and cloud computing has become a foundation of the revolution. The India cloud computing market is experiencing an unprecedented growth as organizations in various sectors come to the realization of the strategic value of cloud infrastructure.
The Kingdom of Saudi Arabia stands at the forefront of a remarkable digital transformation that is fundamentally reshaping its economic landscape and technological capabilities. The data center market research in the country reveals a sector experiencing unprecedented momentum, driven by the nation's ambitious modernization agenda and its strategic positioning as a regional technology hub.
The global sports management software market represents a dynamic and promptly evolving industry that rests at the intersection of technology innovation and the multibillion-dollar sports industry. As organizations across amateur leagues, professional clubs, sports associations, and entertainment venues seek competitive advantages in an increasingly digital landscape, sophisticated software platforms have emerged as essential infrastructure.
Saudi Arabia's corporate training market is experiencing a profound transformation, driven by an ambitious national agenda focused on economic diversification, digital innovation, and workforce empowerment.
The Gulf Cooperation Council (GCC) region continues to position itself as one of the fastest-evolving markets for packaged beverages, with bottled water standing at the forefront of this transformation. The GCC bottled water market size has expanded steadily in recent years, supported by a strong shift toward health-driven consumption, improved hydration awareness, and evolving lifestyle patterns across the member countries.
The digital health market in Saudi Arabia has been undergoing a phenomenal transformation through convergence, where healthcare providers, government agencies, and technology innovators join forces to create more accessible, efficient, and patient-centered ecosystems in healthcare.
The market represents one of the most dynamic segments within the region's rapidly evolving entertainment landscape. The GCC anime market size reached USD 644 Million in 2024 as per IMARC Group and is projected to grow to USD 1,265 Million by 2033 at a CAGR of 7.8% during 2025-2033.
The UK quantum computing industry has emerged as a critical frontier in the global race toward next-generation computing capabilities. Britain's ecosystem brings together world-class universities, pioneering research institutions, and ambitious commercial ventures working to harness quantum mechanics for computational advantage.
The Australia smart homes Industry has emerged as one of the most dynamic sectors within the global connected living ecosystem. Valued at USD 4.29 Billion in 2025, the market is projected to reach USD 11.54 Billion by 2034, according to IMARC Group.
India is undergoing an accelerated digital transformation, a systemic shift that is dependent on robust, high-performance digital infrastructure. At the very core of this paradigm is the surge in demand for facilities that can reliably store, process, and manage the nation’s exploding data volumes.
Over the last decade, digital payment systems in India have undergone a significant transformation, and credit cards have emerged as one of the major components of this financial revolution. Driven by increasing financial literacy, deeper penetration of digital banking, and a gradual shift towards cashless transactions, the Indian credit card market is growing at a rapid pace.
The Saudi Arabia industrial safety equipment market size reached USD 38.70 Million in 2024, experiencing a transformative phase as the Kingdom intensifies its focus on workplace protection and regulatory compliance across diverse industrial sectors. Industrial safety equipment is playing an increasingly vital role in safeguarding workers and assets throughout the oil and gas, construction, manufacturing, mining, and chemical processing industries that form the backbone of Saudi Arabia's economy.
The Germany smart cities market stands as one of Europe’s most advanced models of urban innovation, driven by sustainability, digitalization, and citizen-focused design. Germany’s smart city vision emphasizes balancing efficiency with inclusivity, integrating technology seamlessly into everyday urban life.
The IoT market of Saudi Arabia is seeing unprecedented growth as the Kingdom speeds up its journey toward comprehensive digital transformation. This is a growth trajectory that reflects commitment to modern infrastructure, increasing operational efficiency, and positioning Saudi Arabia as the regional technology hub.
The Brazil C4ISR market forms a vital part of the modernization agenda for the nation's defense, entailing sophisticated systems for command, control, communications, computers, intelligence, surveillance, and reconnaissance. As South America's largest economy and military force, Brazil has always taken the lead in developing advanced defense IT infrastructure to address regional security challenges and emphasize its strategic autonomy.
The data center market in Brazil has emerged as a vital cog in Latin America's wheel of digital transformation. With the increasing adoption of digital technologies, the need for reliable, secure, and scalable data storage and processing infrastructures is rapidly rising among enterprises, governments, and consumers.
The Saudi Arabia e-commerce market is undergoing a major transformation, becoming one of the fastest-growing digital economies in the Middle East. It reached a value of USD 222.9 Billion in 2024 on account of the rapidly expanding digital landscape, government initiatives like Vision 2030, and the increasing adoption of mobile commerce (m-commerce) and digital payment solutions.
The Saudi Arabia telecom market is undergoing rapid transformation mainly driven by accelerated digitalization, robust policy support, and growing consumer connectivity needs. The industry serves as a critical pillar of the Kingdom’s Vision 2030 strategy which aims to diversify the economy and establish Saudi Arabia as a digital hub in the Middle East.
The Australia legal services industry is undergoing rapid change driven by growing demand, technological advancement, and evolving regulation. Firms that are innovating while upholding quality, ethics, and client trust are succeeding. Regulatory complexity is fueling advisory work, technology is reshaping service delivery, and Australia’s position is enabling regional growth.
The Latin America carbon footprint management market represents a critical frontier in the global transition toward sustainable business practices and environmental accountability. As organizations across the region confront mounting pressure from stakeholders, investors, and regulatory bodies, the demand for sophisticated carbon emission tracking systems has intensified dramatically.
The UK's ATM market, therefore, stands as an important pillar in its financial ecosystem for the benefit of millions of consumers and businesses who rely on timely, convenient, and secure ways of accessing cash. However, despite the rapid acceleration of contactless payments and digital banking, ATMs remain indispensable across the urban and rural areas.
The India smartphone industry has cemented its position as one of the world's most critical and dynamic technology markets, undergoing a profound transformation driven by consumer aspiration and technological advancement. Far from merely being a volume-driven segment, the market is experiencing a significant value premiumisation trend, where consumers are increasingly upgrading to feature-rich and higher-priced devices.
India is now undergoing a transformative phase of the Internet of Things (IoT) industry, as it solidifies its role as a key facilitator of the ambitions of the Indian economy to become digital. IoT, which was initially viewed as a futuristic idea, has quickly become a baseline technology in the consumer, enterprise, and public infrastructure domains.
As banks and startups embrace modernization, secure and efficient digital platforms are attracting strong local and global investment. Artificial intelligence (AI), automation, and predictive analytics are redefining how finance works in Australia. These tools make transactions faster, decisions sharper, and client experiences more intuitive. From fraud detection to personalized banking, technology is transforming every corner of the market.
The Europe artificial intelligence market stands at a pivotal juncture, balancing unprecedented technological advancement with complex regulatory frameworks and strategic imperatives. As businesses across the continent accelerate their AI adoption Europe initiatives, the region emerges as a distinctive force in global artificial intelligence development, characterized by its commitment to ethical innovation and human-centric technologies.
India’s rapid digitalization has transformed the way organizations operate, connect, and deliver services. However, this digital shift has also exposed enterprises to a surge in cyber threats, ranging from ransomware and phishing to sophisticated data breaches and identity theft. As companies across sectors increase their reliance on digital platforms, the frequency and complexity of cyberattacks have intensified, forcing both public and private institutions to prioritize cybersecurity investments.
The Europe drones market has evolved into an indispensable aspect of the continent's operational and technological environment. Drones are now sequentially incorporated into sectors that rely on precision, real-time monitoring, and safe performance of field operations. Their capacity for aerial monitoring, environmental condition evaluation, and real-time observation allows companies to achieve greater accuracy in decision-making while reducing reliance on human intervention in hazardous areas.
The 3D printing industry is currently experiencing a revolutionary growth that has had a radical change on the manufacturing operations within the industries of the world. The technology is also referred to as additive manufacturing (AM), and it is the way to create three-dimensional objects by adding layers to the digital model, thereby providing unprecedented flexibility in both design and production. The 3D printing sector of the world has become a pivotal source of innovation enabler, efficiency, supply chain resilience, and competitive edges to organizations as small-and-medium-sized as small businesses to Fortune 500 organizations.
The education sector in India is witnessing a sea change with digital learning becoming integral to both formal and informal education. The rapid rise of online education platforms has reshaped the way schools, coaching institutes, and higher education centers impart learning experiences, accelerated by pandemic-driven digital acceleration. And today, technology-enabled education is no longer confined to urban centers; it is reaching Tier-2 and Tier-3 cities, democratizing access to quality learning resources for millions of students.
India’s healthcare sector is undergoing a technological transformation, with artificial intelligence positioned as a central driver of change. With a population exceeding 146.39 crore and a system challenged by issues of accessibility, affordability, and quality, AI is no longer optional but essential for building sustainable healthcare solutions.
India health and wellness market is on a fast track, with more people paying attention to preventive care and overall well-being. IMARC Group stated that the market hit USD 156.01 Billion in 2024, owing to the boom in nutraceuticals, fitness, and digital health platforms. Artificial intelligence (AI) is bringing a fresh wave of innovation to health and wellness, enhancing personalized fitness routines, predictive health insights, and more efficient wellness tracking.
Japan's ecotourism industry is experiencing a remarkable transformation, positioning the country as Asia's leading destination for sustainable travel experiences. The market, which is reaching unprecedented valuations of USD 12,999.78 Million in 2024, is demonstrating exceptional growth momentum with projections indicating an expansion to USD 34,542.85 Million by 2033, representing a robust compound annual growth rate (CAGR) of 11.47% during the 2025-2033 period.
The United Kingdom is currently establishing itself as one of Europe's most dynamic blockchain innovation hubs, demonstrating remarkable resilience and growth despite global economic uncertainties. The UK blockchain market reached a valuation of USD 0.66 Billion in 2024 and is projecting explosive growth toward USD 54.63 Billion by 2033, exhibiting a compound annual growth rate (CAGR) of 63.26% during the forecast period. This extraordinary trajectory is placing the nation at the forefront of distributed ledger technology adoption and development.
Japan has been a world leader in robotics, especially industrial, for decades. The nation's unflinching faith in technology development, precision manufacturing, and automation has made it a world leader in industrial robotics. Industrial robots have transformed the manufacturing process to become necessary equipment in today's manufacturing, helping companies increase productivity, retain quality, decrease errors in operations, and enhance efficiency in processes.
The Europe 3D printing market stands at the forefront of a manufacturing revolution that is reshaping industries across the continent. As additive manufacturing technologies mature and expand beyond prototyping into full-scale production, European manufacturers, healthcare providers, and aerospace companies are increasingly embracing these transformative solutions. With substantial government backing, strategic industry collaborations, and breakthrough material innovations, the European 3D printing landscape is positioned for remarkable expansion through 2033.
The Philippines gaming industry has emerged as Southeast Asia's fastest-rising digital entertainment powerhouse, achieving USD 4,822.00 Million in gross gaming revenue for 2024. This explosive growth signals a fundamental transformation in how Filipinos engage with interactive entertainment, driven by the rapid adoption of augmented reality (AR) and virtual reality (VR) technologies.
The data monetization market has emerged as a critical pillar of the modern digital economy, transforming how organizations create value from their information assets. As businesses recognize data as a strategic asset, the ability to extract financial value has become a competitive imperative. The global data monetization industry encompasses diverse approaches, ranging from direct data sales to indirect monetization through enhanced decision-making. According to IMARC Group, the industry reached USD 4.1 Billion in 2024. It is projected to reach USD 16.1 Billion by 2033, at a CAGR of 15.76% during 2025-2033.
The global access control market is entering a phase of serious expansion and transformation. In 2024, IMARC placed its value at USD 10.6 Billion, with a forecast of USD 18.8 Billion by 2033 (CAGR of 6.5 %). This reflects how rapidly the underlying technologies, threat landscape, and regulatory regimes are shifting. Across enterprises, campuses, infrastructure sites, and smart buildings, access control is evolving from door-level locks to identity, context, behavior, and integration. In many markets, access control is becoming an essential bridge between physical security and cybersecurity.
The media consumption landscape in Japan is in the midst of a revolutionary change with over-the-top (OTT) services as a leading force behind the way viewers are consuming entertainment content. OTT services, which provide video content directly on the internet and not via conventional cable or satellite television, are fast becoming a standard in Japanese homes. The growth of the Japanese OTT industry has been shaped by various factors, from technological innovations to changing consumer tastes.
The e-commerce market in Mexico is thriving, driven by increased internet access, mobile shopping, and smooth digital payment options. IMARC Group estimated that the market reached an impressive USD 47.52 Billion in 2024, signifying a distinct transition towards online shopping.
The global Industry 4.0 market is experiencing strong momentum, propelled by the integration of smart technologies across manufacturing, logistics, and energy sectors. With automation, connectivity, and data intelligence at its core, Industry 4.0 is reshaping how enterprises design, produce, and deliver products.
The global soft skills training market size was valued at USD 33.39 Billion in 2024. Looking forward, IMARC Group estimates the market to reach USD 92.59 Billion by 2033, exhibiting a CAGR of 11.40% during 2025-2033. This substantial growth reflects a fundamental shift in how organizations approach workforce development, as the recognition of soft skills as strategic assets rather than supplementary competencies becomes universal across industries.
The global Wi-Fi infrastructure market is experiencing unprecedented expansion, fundamentally reshaping how organizations operate and consumers interact with technology. According to Wi-Fi Alliance, the official industry certification body, 4.1 Billion Wi-Fi devices are forecast to ship in 2024, contributing to 45.9 Billion cumulative Wi-Fi shipments over the technology's 25-year lifetime.
Australia's mobile money industry is experiencing unprecedented transformation as artificial intelligence reshapes the landscape of digital payments, mobile wallets, and financial services. The integration of sophisticated AI technologies has revolutionized how Australians conduct transactions, manage their finances, and interact with digital payment platforms. From smartphone-based payment solutions to advanced fraud detection systems, AI is driving innovation across every facet of the mobile money ecosystem.
India vehicle tracking market is undergoing a significant transformation, with artificial intelligence emerging as a central driver of innovation. According to the IMARC Group’s report, the market size reached USD 0.90 Billion in 2024.
India stands at a decisive stage where economic growth must advance in parallel with environmental sustainability. According to an IMARC Group report, the Indian green technology and sustainability market reached USD 837.2 Million in 2024, reflecting the nation’s growing commitment to sustainable development.
Closed-Circuit Television (CCTV) cameras are electronic monitoring systems that are used to watch, record, and send video images for security and observational reasons. Unlike television broadcasting, CCTV signals are sent to selected monitors or recording devices, and hence they are the backbone of contemporary security infrastructure.
India's educational technology sector stands at the precipice of a transformative revolution, with artificial intelligence (AI) emerging as the primary catalyst driving unprecedented growth and innovation. The convergence of AI technologies with educational platforms is fundamentally reshaping how millions of Indian students access, consume, and engage with learning content, creating an ecosystem that democratizes access to quality education across the country’s diverse linguistic and socioeconomic groups.
Japan’s higher education sector is at a major turning point as demographic and economic pressures converge with technological disruption. One of the major trends in the Japan higher education market include the number of students entering universities has been shrinking for decades due to the country’s aging population, creating structural challenges for institutions that once relied on a stable or growing pool of applicants.
Japan, a global leader in technological innovation, is at the forefront of a new digital revolution in its satellite communication sector. As the nation pushes toward a more connected and resilient future, the integration of Artificial Intelligence (AI) is proving to be a critical catalyst. From enhancing network performance to automating complex operations AI is not just an add-on it is a foundational technology reshaping the very fabric of satellite communication.
Generative artificial intelligence (AI) is rapidly becoming one of the most influential technologies of the decade, and its global footprint is continuously expanding. Nations across the world are exploring its transformative potential, with Japan emerging as a unique hub where technological innovation, traditional industries, and forward-looking government policies are converging.
A battery charger is a piece of electrical equipment that is used to recharge a rechargeable battery by imposing an electric current upon it. The main purpose of a charger is to transfer alternating current (AC) from the power source into an appropriate direct current (DC) that has the required voltage and current for the particular type of battery. Battery chargers play a vital role in a broad variety of applications, from consumer devices and electric vehicles (EVs) to industrial equipment and renewable energy systems.
Indian manufacturing continues to grapple with significant losses caused by defects, rework, and product returns, which weaken profitability and competitiveness. As per an industry report, in FY22, the total return order volume in India stood at 14.86%. Furthermore, high-volume industries such as automotive, FMCG packaging, textiles, and electronics are particularly exposed, where even a small defect rate can translate into substantial financial setbacks. Industry research states that in mature operations, the Cost of Poor Quality (COPQ) can account for as much as 15–20% of total sales. Moreover, Return Prime’s recent report shows that returns remain a major challenge in e-commerce sales, with 17.6% of all orders being sent back.
Industry 4.0 has been a defining milestone in the advancement of manufacturing. It is responsible for introducing automation, digitization, and data-driven processes that significantly enhanced productivity and precision. Presently, India is moving into the next phase of manufacturing, that is, autonomous factories. Here, artificial intelligence (AI) goes beyond simple automation, enabling systems to render decisions, learn from changing conditions, and continuously improve operations. This shift has the potential to reshape industrial growth in the country and establish new standards for smart manufacturing.
Indian manufacturers are facing difficulties due to rising input costs, shortages of skilled labour, unplanned machine downtime, and inconsistent product quality. According to an industry report, during the July–September quarter of FY25, raw material expenses for 1,679 listed non-financial manufacturing companies increased by 5.1%, outpacing sales growth, which rose by only 3.3%. Similarly, the Global Talent Shortage Survey 2025 reported that 80% of Indian employers report difficulty finding skilled talent, compared to the global average of 74%, highlighting a severe talent crunch.
According to the International Energy Agency (IEA), global energy-related CO2 emissions grew by 0.8% in 2024 to a record 37.8 gigatonnes, driving atmospheric concentrations to an unprecedented 422.5 ppm. This has led to an increased urgency in addressing climate change. Similarly, the industries are facing unprecedented pressure to rethink their operations due to the energy demand rising by 2.2% in 2024, which is faster than the annual average of 1.3% witnessed between 2013 and 2023.
India is among the fastest-growing economies globally. The nation is currently the fourth-largest economy in the world and is on its way to becoming the third-largest, with an estimated GDP of USD 7.3 Trillion by 2030. This momentum is not only strengthening India’s economic resilience but also opening lucrative opportunities for businesses, investors, and technology providers aligned with the country’s growth vision.
The role of artificial intelligence (AI) in modern project management has transitioned from a theoretical concept to a strategic imperative. As businesses navigate increasingly complex projects in a data-driven world, AI is emerging as a powerful force for efficiency, accuracy, and innovation.
The artificial intelligence market is no longer niche. Current projections value the market at a significant level today, with strong growth expected as generative AI matures, computing costs decline, and enterprise pilots scale into full production.
The data center sector in Japan is at the epicenter of a tech revolution, wherein artificial intelligence (AI) is fundamentally redefining how digital infrastructure manages, scales, and adapts. With the country progressing toward digital transformation in various industries, AI has been the force behind unprecedented innovation in the design, management, and optimization of data centers.
In the modern era, the global video streaming market is fundamentally reshaping the entertainment landscape, driven by the dual forces of digitalization and the escalating demand for on-demand content. Artificial intelligence (AI) also serves as a pivotal catalyst for this growth, enabling the personalization of user experiences through tailored recommendations, improved content discovery, and enhanced audience engagement.
The global gaming console market is undergoing a significant transformation, fueled by the adoption of artificial intelligence (AI) and an increasing demand for interactive entertainment.
For decades, call centers have played a central role in customer service. Traditionally staffed with large teams of agents, they operated as cost-heavy units designed to handle inquiries, complaints, and service requests. While essential, this model was often associated with inefficiencies, long wait times, and high employee turnover.
According to IMARC Group, the global identity verification market was valued at USD 13.8 Billion in 2024 and is projected to reach USD 46.4 Billion by 2030, expanding at a CAGR of 14.4% during 2023–2030. This strong growth is being fueled by the increasing adoption of artificial intelligence (AI) and machine learning (ML), which are enabling higher levels of automation, fraud detection, and real-time authentication.
Japan is a leader in digital transformation, known for being one of the most advanced nations in technology globally. Artificial Intelligence (AI) is becoming an integral force across various sectors, and the telecom industry is no exception.
Generative AI is revolutionizing industries by bringing fresh, game-changing solutions that boost creativity and streamline workflows. Whether it’s automating content creation or optimizing complex processes in fields like healthcare and finance, AI is opening doors to exciting new possibilities.
The e-commerce market has undergone a seismic shift in the past twenty years. What started as simple, text-based product pages has grown into a complex web of intelligent platforms capable of customizing experiences for every individual user. At the core of this evolution is Artificial Intelligence (AI).
The global laptop and tablet market includes portable computing devices for both personal and commercial use, providing mobility, flexibility, and connectivity. Laptops extend desktop computers' power and functionality in a portable package, while tablets provide light-touch screen interfaces for consumption of media, creative work, and on-the-go productivity.
The global cloud gaming industry is experiencing an unprecedented surge, driven by technological advancements and evolving consumer preferences. As the market expands, Artificial Intelligence (AI) stands out as a pivotal force, reshaping every facet of the cloud gaming landscape, from infrastructure to player experience. It enables smarter resource allocation, real-time content personalization, latency reduction, and advanced game logic.
The global power bank market is experiencing steady growth as digital lifestyles become more integrated into everyday routines. With rising dependence on smartphones, tablets, laptops, and wearables, power banks have shifted from being simple backup batteries to versatile, feature-rich accessories that fulfill the needs of a wide range of users. Consumers now prefer power banks with fast-charging capabilities, higher battery capacity, and environmentally responsible designs.
The hybrid cloud market across the world has been changing at a very fast rate, with companies globally adopting the mix of on-premises and cloud-based infrastructures to fuel innovation and operational effectiveness.
Japan’s artificial intelligence (AI)-driven three-dimensional (3D) printing startups are redefining manufacturing by merging speed, sustainability, and precision. Japan’s additive manufacturing scene is moving beyond prototypes—it's rewriting how industries build, design, and innovate.
As a global leader in technology and innovation, Japan has increasingly recognized the critical importance of cybersecurity to protect its digital infrastructure.
Electric cables or power cables are the fundamental parts employed for the transfer of electrical power or signals over short and long distances. They generally comprise one or more conductors, typically composed of copper or aluminum, covered with insulating materials and protective sheaths. Electric cables, based on their use, differ in structure, including low-voltage, medium-voltage, and high-voltage power cables, control cables, instrumentation cables, or data transfer cables like fiber optics.
Smart Factory and Industry 4.0 Integration is a comprehensive set of services that helps firms overhaul their manufacturing processes by embracing new technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), robotics, big data analytics, and cloud computing.
Digitalization is reshaping the very essence of travel, transforming it into a more personalized, convenient, and efficient experience than ever before. With the growing popularity of travel platforms, travelers now have the power to plan and book their entire journey with just a few taps on their smartphones.
Product and facility certification support offers professional assistance to companies in resolving complicated processes of product certification and facility certification. Our services facilitate adherence to global standards and regulatory guidelines to ensure hassle-free market entry and operational continuity across global markets.
The global e-commerce landscape is rapidly transforming, propelled by several evolving e-commerce industry trends. These fundamental shifts encompass changes in consumer behavior, rapid technological advancements, and increasing internet accessibility worldwide. As a direct result, brands are now prioritizing quick delivery, mobile-centric platforms, and deeply customized digital experiences.
Setting up a drone manufacturing plant with a step-by-step business plan covering setup, costs, equipment, compliance, and market strategy.
India’s textile industry is undergoing a transformative shift led by the government’s visionary PM MITRA (Mega Integrated Textile Region and Apparel) Parks initiative. With a mission to establish India as a worldwide leader in textiles, this program is creating world-class integrated manufacturing zones that drive innovation, reduce production costs, and boost sustainability.
India’s sports technology sector is gaining extraordinary momentum, driven by the digitalization of sports leagues, enhanced fan engagement, and increasing investments in athletic performance solutions. With the Indian Premier League (IPL) 2025 poised to become the most tech-driven tournament to date, the market is no longer restricted to wearables and broadcasting; it now powers every aspect of sports, from grassroots training to AI-based strategic decision-making.
India is becoming a popular location for foreign manufacturers because of its quickly expanding economy, affordable labour costs, and consistent government support. For businesses looking to establish manufacturing facilities in the nation, the Government's "Make in India" incentive program offers an alluring alternative. This guide will assist in comprehending the crucial requirements for setting up a manufacturing facility in India.
Factory audits are important for companies that intend to ensure compliance and quality in operations as well as supply chain efficiency. India is experiencing unparalleled growth in manufacturing. The skills to perform factory audits effectively can be used to counter most risks related to Indian supplier relationships. This blog gives a complete step-by-step guide on how to perform factory audits in India, including a complete checklist.
Establishing a manufacturing plant is a major investment that requires meticulous planning and a thorough understanding of the associated costs. Whether a seasoned entrepreneur or an industrial novice, understanding the "cost equation" is vital for making informed financial decisions and ensuring the long-term profitability of the operations. This blog will break down the various expenses associated with establishing a manufacturing facility in India.
Setting up a manufacturing plant is a significant milestone for any business, but it comes with complexities that require careful planning, research, and execution. From selecting the right location to ensuring regulatory compliance and operational efficiency, every aspect needs expert attention to guarantee success. This is where IMARC Group steps in, offering comprehensive pre-feasibility studies and consultation services to help businesses establish manufacturing plants seamlessly.
The manufacturing sector is a cornerstone of India's economy. It accounted for about 14% of the overall GDP of the nation in 2024 and has employed millions of people across the country. India has been a rising manufacturing powerhouse globally and 2025 is expected to be a turning point. Given the better government focus and strong labor force, along with the increasingly effective infrastructure, India is likely to be sealed as a prime destination for global manufacturers.
Many have encountered this scenario: visiting a website with enthusiasm to purchase a product seen in an advertisement, only to face challenges such as navigating a complex interface, unresponsive customer service, and a cumbersome checkout process.
The OTT industry is experiencing a pivotal transformation, signaling the advent of a new digital entertainment era. Consumers are increasingly demanding convenience and personalized experiences on OTT platforms. As a result, platforms are investing massively in technologies such as AI to enhance the recommendations of content and improve user experience.
From established giants in the United States and Europe to fast-paced markets in Asia, the e-commerce revolution is creating a competitive marketplace that transcends geographical boundaries. Vietnam stands out as a key force in this global trend, showcasing the potential of e-commerce to drive national economic transformation. The country’s e-commerce industry is witnessing tremendous growth, driven by new markets and growth opportunities in established markets.
Head-mounted displays consist of small displays with in-built sensors and optics that project images directly onto the user's eyes. They provide a virtual reality (VR) or augmented reality (AR) experience that allows users to interact with digital objects or environments. They resemble glasses or goggles and are designed to be worn on the head. They comprise many components, such as a controller, sensor, camera, lens, goggles, head tracker, case, connector, display, battery, processor, memory, pico projector, and accessories. Tracking systems and sensors detect the user's head movements and adjust the displayed content accordingly, offering the user a more realistic, immersive, and interactive experience.
5G technology or fifth-generation wireless technology is the latest advancement in mobile communication systems that provides enhanced data transfer speeds, reduces latency rates, improves reliability, and increases network capacity. This technology operates in the mm-wave spectrum, the spectrum band ranging from 30 to 300 gigahertz (GHz), which facilitates high-speed networks and faster data delivery. 5G technology supports the growth of emerging technologies like artificial intelligence (AI), machine learning (ML), and edge computing, enabling new business models and unlocking economic potential. It enhances the performance of business applications and digital experiences, such as video conferencing, online gaming, live streaming media, and self-driving cars. The components included in 5G technology are hardware, software, and services, and it is utilized in a wide range of applications, such as automation, video services, connected vehicles, smart homes, virtual & augmented reality, and monitoring & tracking. For better connectivity of networks, various industries, such as manufacturing, automotive, transportation & logistics, media & entertainment, energy & utilities, healthcare, government, and others, have deployed 5G technology extensively.
Robotics is the branch of engineering that deals with designing, constructing, and operating robots. Robots are programmable machines capable of carrying out tasks autonomously or semi-autonomously. Major types of robotics include industrial and service robots, combining elements of mechanical engineering, electrical engineering, computer science, and artificial intelligence (AI). Industrial robots encompass articulated, Cartesian, SCARA, and cylindrical robots. Service robots serve personal, domestic, and professional purposes, used in various applications, such as household tasks, entertainment, defense, fieldwork, logistics, healthcare, infrastructure, mobile platforms, and cleaning, and more. Robotics can efficiently and accurately perform tasks in environments that may be hazardous or challenging for humans. Robots reduce human labor, enhance production efficiency, lower costs, and improve product quality in various industries. Robotics is further categorized into types such as industrial robotics, food robotics, warehouse robotics, smart robotics, automotive robotics, agriculture robotics, logistics robotics, construction robotics, space robotics, and others. Nowadays, robotics has become an important part of many industries, even being used to explore deep oceans and space. Additionally, it is employed in creating autonomous vehicles, performing surgery, and conducting medical diagnoses.
Artificial Intelligence (AI) chips are designed to accelerate and optimize AI and Machine Learning (ML) workloads. The field of AI involves tasks such as pattern recognition, data analysis, and decision-making, which often require massive parallel processing. AI chips perform various tasks like deep learning, neural network processing, and other computationally intensive operations. These chips are tailored to support the parallel computing needs of AI workloads, making them well-suited for these tasks.
Oman is situated on the southeastern coast of the Arabian Peninsula. It boasts a rich cultural heritage, stunning landscapes, and a diverse range of attractions, making it an emerging destination in the tourism market. The country offers a wide array of tourist activities, including sunbathing, swimming, kitesurfing, diving, snorkeling, boating, among many others. Beach activities and kite surfing are popular in Muscat, Al Sawadi Beach, Alzaiba Beach, and Masirah Island, while desert safaris are a highlight in Wahiba Sands. Oman's rich historical heritage includes numerous UNESCO World Heritage Sites, ancient temples, forts, and palaces, such as Bahla Fort and the Archaeological Sites of Bat, Al-Khutm, and Al-Ayn.
Virtual reality (VR) gaming represents a new generation of computer games that leverage VR technology to provide high-definition visuals, spatial audio, and precise motion tracking, creating a sense of presence and immersion. VR gaming offers a 360-degree view of the virtual environment, keeping players engaged for longer periods compared to traditional gaming. Additionally, VR gaming is used in rehabilitation and the treatment of phobias, anxiety disorders, and other psychological conditions. It is also employed to train soldiers in combat scenarios, strategy, and decision-making.
Cloud computing delivers computing services over the internet, including servers, storage, databases, networking, software, analytics, and intelligence. It promotes faster innovation, flexible resource allocation, and economies of scale. Moreover, it offers numerous advantages, such as cost efficiency, mobility, scalability, reliability, and automatic software updates, among others.