Why Is the Online Car Buying Market Expanding Faster Than Traditional Franchise Dealer Retail Across Regions?
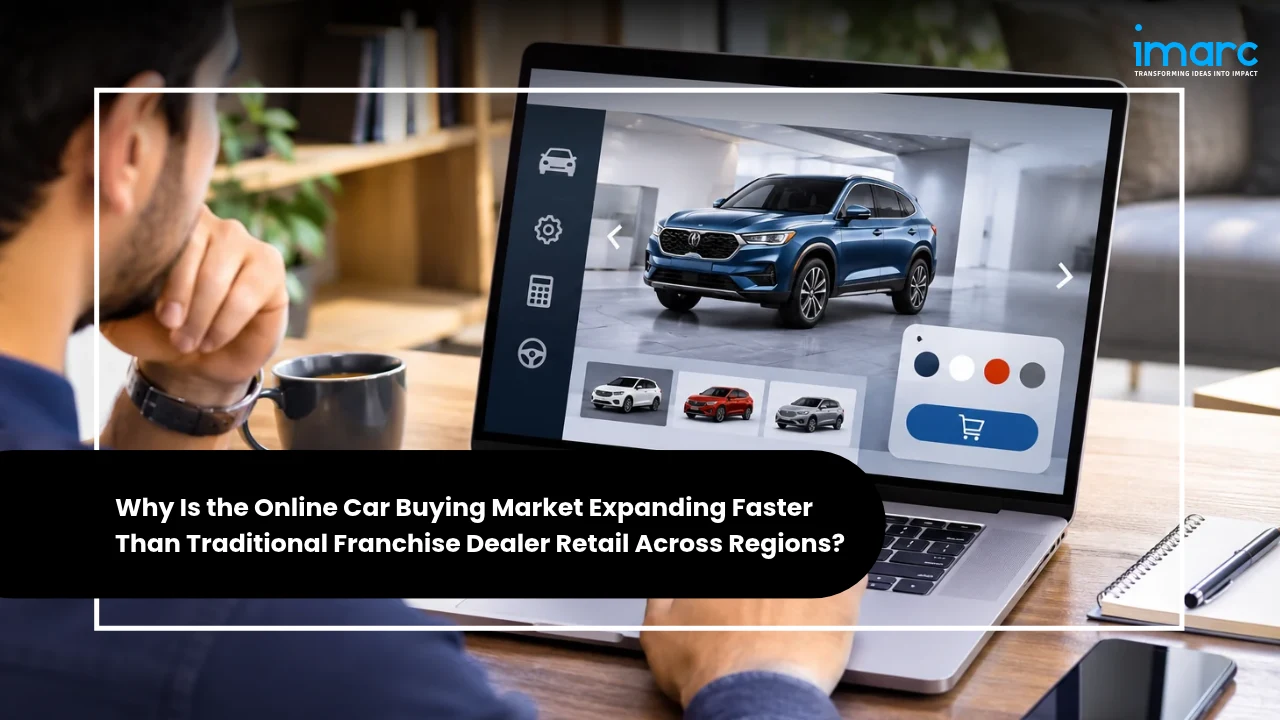
Introduction: Why Online Car Buying Outpaces Dealers
The increasing adoption of digital platforms is transforming vehicle purchasing behaviour, with consumers increasingly relying on online channels to explore models, compare prices, and evaluate buying options. According to IMARC Group, the global market grew from USD 390.4 Billion in 2025 to USD 424.9 Billion in 2026, and it is projected to reach USD 836.4 Billion by 2034, registering a CAGR of 8.80% during 2026-2034. This growth reflects changing consumer preferences, greater digital accessibility, and the expanding role of online platforms in simplifying vehicle research and purchase decisions.
Four advantages explain the divergence. Online channels strip out showroom overhead and compress customer acquisition costs, so platforms can pass part of the saving into price and financing terms. They also dissolve geography: a buyer in a district with no franchised outlet can compare inventory held by dealers hundreds of kilometres away. Transparency tools, including vehicle history reports, independent ratings and total-cost calculators, reduce the information asymmetry that once protected dealer margins. And demand-side behaviour has shifted, with younger buyers treating a vehicle as one more digital transaction rather than a visit-based ritual.
The defining theme is convergence rather than displacement. Franchise groups are building their own digital storefronts instead of ceding the channel to pure-play marketplaces. Several established dealership groups are also investing in digital retailing capabilities to make online vehicle discovery, buying, and selling more accessible to customers, while CarGurus moved to acquire CarOffer in full to own the wholesale and instant-offer layer sitting behind retail listings. The result is a hybrid model in which the platform owns the transaction journey while the franchise network supplies reconditioning, delivery and service capacity.
This blog examines the current state of online car buying industry, the segments and regions carrying the 8.80% growth path, the announcements and policies reshaping competitive positions, and where stakeholders can act on the USD 836.4 Billion opportunity projected for 2034.
Key Takeaways
- The global online car buying market is valued at USD 424.9 Billion in 2026, up from USD 390.4 Billion in 2025, and is forecast to reach USD 836.4 Billion by 2034, at a CAGR of 8.80%, meaning the channel nearly doubles in eight years.
- Pre-owned vehicles represent the leading category and SUVs the leading vehicle type, with petrol retaining the largest propulsion share, a mix that confirms online demand is concentrated in high-volume, price-sensitive segments rather than premium niches.
- North America accounts for the largest regional share of the market, supported by established automotive e-commerce platforms, home delivery options and a consumer base already comfortable with large-ticket digital purchases.
- Hertz Global launched a fully online used-car marketplace in September 2025, expanding its digital vehicle sales strategy alongside its collaboration with Amazon Autos. The platform also allows customers to receive trade-in offers, highlighting how established automotive retailers are combining online vehicle discovery, purchasing and trade-in services to create more integrated digital buying experiences.
- The key trend is the growing integration of online and offline automotive retail channels. Franchise dealer groups are strengthening their digital retail capabilities, while marketplaces are expanding their offerings through financing, trade-in valuation, and delivery services. This integrated approach is making the vehicle buying process more convenient and creating a connected retail experience across digital and physical channels.
Market Size, Share & Growth Outlook
According to IMARC Group, the global online car buying market stood at USD 390.4 Billion in 2025, rose to USD 424.9 Billion in 2026, and is forecast to reach USD 836.4 Billion by 2034, expanding at a CAGR of 8.80% during 2026-2034. The leading segments are:
- Vehicle Type: SUVs represent the largest segment of the market. Their dominance reflects buyer preference for interior space, ground clearance and all-wheel-drive capability, and it matters commercially because SUVs carry higher average transaction values, which lifts the revenue base on which platforms earn commission and financing margin.
- Propulsion Type: Petrol accounts for the largest share of the market. Petrol vehicles carry lower upfront purchase costs than most electrified alternatives and rely on fuel infrastructure that is already universal, so the segment continues to anchor online volume even as hybrid and electric listings grow within the platform catalogues.
- Category: Pre-owned vehicles represent the leading segment. Pre-owned listings benefit most from the transparency tools that platforms provide, including accident records, service history and ownership data, and the cost saving relative to new vehicles makes the category the entry point for first-time online buyers.
- Region: North America leads the market, followed by Europe and Asia Pacific. The region's advantage rests on well-established automotive e-commerce platforms, mature home delivery logistics and a large base of repeat digital buyers who moved online during pandemic-era dealership restrictions and did not return fully to visit-led purchasing.
The segmentation carries a clear strategic message: growth is being driven by the volume end of the market, where standardised inspection, transparent history and finance pre-approval can be industrialised across hundreds of listings. Platforms that build repeatable processes around pre-owned SUVs and petrol vehicles achieve scale economics, while the new-vehicle and electrified segments extend the same infrastructure upward as average selling prices rise.
Recent News & Mega Announcements
Platform consolidation and dealer-backed digital tooling have defined the competitive news flow of the past three years. Each development below shifts volume from a single physical forecourt to a national or cross-border digital channel:
- July 2026: Carvana reported record second-quarter results, with 197,325 retail units sold (up 38% year over year) and total revenue of USD 7.376 billion (up 52%), along with net income of USD 513 million. The company guided to full-year 2026 adjusted EBITDA of USD 2.7 to USD 3.0 billion, up from USD 2.24 billion in 2025. Management indicated it holds roughly 2% of the used car market, which shows how much room remains for online-first retailers to gain share.
- April 2026: Amazon expanded its Amazon Autos program by adding Kia, Mazda, Subaru, Chevrolet and Jeep to its existing Hyundai and Ford lineup, with hundreds of dealers listing inventory across more than 130 cities. The program works through participating local dealers and does not bypass them, in a U.S. retail market where dealerships sold about USD 1.3 trillion worth of cars last year. The expansion extends large-scale online purchasing from used vehicles into new-vehicle retail.
- February 2026: India’s Spinny closed a funding round of USD 170 million led by Fidelity Investments and Accel Leaders Fund, valuing the company at about USD 1.5 billion. The transaction included USD 90 million of primary capital, with the remainder sold by early investors Blume Ventures and Fundamentum. The round signals continued investor interest in online-to-offline used car retail in India despite a lower valuation than the 2025 round.
- January 2026: Cox Automotive released its 16th annual Car Buyer Journey Study, based on responses from 2,300 consumers who bought a new or used vehicle in the previous 12 months. The study found that 7% of buyers purchased entirely online, while 28% said they want to buy entirely online and 37% want to finalize the purchase price online, though only 19% do. It also reported that 83% of consumers expect AI to affect car buying in the future, which points to a gap between online purchase intent and actual completion that digital retailing tools are trying to close.
Read together, these announcements describe a market where the transaction layer is being consolidated by platforms while the physical layer is being retained by dealer groups. Neither side is winning outright, and the competitive contest has moved to who controls the data, the finance offer and the delivery promise.
Industry Trends Shaping 2026
Three forces define the online car buying automotive industry trends that will shape 2026 and the remainder of the forecast window. Each one lowers the friction that previously kept large-ticket vehicle purchases tied to physical visits.
1. AI, AR and Virtual Showrooms Shorten the Consideration Window
Artificial intelligence and augmented reality have moved from demonstration features to core conversion infrastructure. AI-driven chatbots and virtual assistants now handle specification queries, eligibility checks and financing walkthroughs, while augmented reality lets a buyer rotate a vehicle, inspect trim details and test colour combinations in a virtual setting. The commercial effect is a shorter consideration window: research that once required three dealership visits can be completed in a single session, and the buyer arrives at the transaction stage already pre-qualified. Virtual showrooms also extend the catalogue beyond physical stock, allowing a regional dealer to present inventory it holds elsewhere without transporting vehicles speculatively.
The relevance to market growth is direct. Every reduction in the number of touchpoints needed to close a sale raises the conversion rate on the same marketing spend, which is precisely the mechanism that allows digital channels to compound faster than fixed-cost showroom networks.
2. Omnichannel Retailing Blends Marketplace Scale with Franchise Dealer Reach
The current state of online car buying automotive industry is best described as hybrid. Pure-play marketplaces brought scale, price comparison and nationwide inventory, but franchise groups still control reconditioning facilities, service bays, trade-in appraisal and, in many jurisdictions, the legal right to retail new vehicles. The two sides are therefore merging capabilities rather than competing for the same function. Dealer groups build or license digital storefronts, and marketplaces add dealer-facing tools for inventory management and lead routing.
This convergence explains why the channel is growing faster than franchise retail without replacing it. The platform supplies demand generation, transparency and financing pre-approval; the dealer supplies physical infrastructure and after-sales obligations. Buyers receive an end-to-end digital journey with a local pickup or delivery point, which removes the last objection that historically pushed large purchases back to the forecourt.
3. Transparent Pricing and Embedded Finance Become the Conversion Engine
Cost efficiency is the most durable driver in the market. Online platforms avoid the overhead of a physical showroom and can pass part of that saving into list prices or financing terms, and they expose those terms side by side so buyers can compare monthly payments, interest rates and total cost of ownership before committing. Finance calculators and pre-approval flows have become standard rather than premium features.
The consequence is a shift in where margin is earned. Platforms increasingly monetise through financing referral, insurance attachment, extended warranties and trade-in spread rather than listing fees alone. This diversifies revenue away from advertising cycles and makes the economics of an online transaction more resilient than a dealership model dependent on metal margin. It also raises the competitive bar: any operator that cannot show a transparent, finance-ready price now looks expensive next to one that can.

Geographic Hotspots
North America leads the market and remains the reference model for digital vehicle retail. The United States and Canada combine a large base of technology-comfortable consumers, extensive new and used vehicle selections on established platforms, and home delivery options that reach most metropolitan postcodes. Pandemic-era restrictions accelerated adoption when buyers sought safer alternatives to dealership visits, and much of that behaviour persisted once restrictions lifted. The region's share is reinforced by the presence of scaled marketplaces and listed dealer groups that have integrated digital retail into their core operations rather than treating it as a pilot.
Europe is the second major concentration and is distinguished by two characteristics. First, consumers show strong interest in low-emission vehicles, and online platforms have responded by widening electric and hybrid catalogues, which lifts average transaction value per listing. Second, the European Union's digitalisation agenda and e-commerce rulebook have created a comparatively consistent environment for cross-border selling, supported by a deep certified pre-owned market in Germany, the United Kingdom and France. The competitive landscape is consequently fragmented, with established manufacturers and startups pursuing the same digital experience mandate.
Asia Pacific is the fastest-moving region in behavioural terms. China combines a vast population, rising disposable income and a consumer base that already buys vehicles, including electric and luxury models, through digital platforms. India shows momentum among urban buyers seeking convenience, while Japan and South Korea are shifting toward digital purchase as automakers and platforms expand local presence. The diversity of income levels and regulatory regimes within the region means the addressable opportunity is uneven, but the direction of travel is consistent.
Latin America is adopting online car buying more slowly, with Brazil and Mexico showing the clearest interest as internet access improves and e-commerce culture matures. Price and feature comparison tools have appealed to buyers in these markets, though concerns over security and listing authenticity still restrain full conversion. As connectivity improves and platforms invest in verified inspection, the region's growth runway lengthens.
The Middle East and Africa presents the widest internal spread. The United Arab Emirates and Saudi Arabia show genuine appetite for digital purchase, supported by high income levels and tech-savvy populations, while adoption across much of Africa remains nascent because of infrastructure constraints and lower internet penetration. Urban e-commerce growth provides the realistic entry point, and platforms that design for local payment and delivery realities can build early positions.
Competitive Landscape & Key Players Strategies
Competition in the online car buying market is split between franchised dealer groups that have industrialised their digital operations and marketplaces that aggregate inventory and monetise traffic. Established automakers have entered by building platforms or partnering with existing e-commerce channels, leveraging brand recognition, vehicle range and dealer networks. Specialised marketplaces compete on listing depth, price transparency and interface quality, and many have added virtual showrooms, augmented reality tools and AI assistants to hold buyer attention through the full journey.
- Asbury Automotive Group: Focuses on digital automotive retailing through its dealership network and online purchasing platform, Clicklane, offering customers vehicle selection, financing, trade-in evaluations, and streamlined purchasing experiences.
- AutoNation: Competes through its extensive dealership network and digital automotive retail solutions, providing online vehicle searches, financing options, trade-in services, and integrated purchasing experiences for new and pre-owned vehicles.
- CarGurus, Inc.: Operates an automotive marketplace that connects buyers with dealerships and private sellers, emphasizing transparent pricing, vehicle comparisons, dealer ratings, and data-driven recommendations to simplify purchasing decisions.
- CarMax Enterprise Services, LLC: Specializes in online used-car retailing through digital vehicle discovery, financing prequalification, vehicle appraisals, and flexible delivery and store-pickup options, focusing on convenience and customer confidence.
- Cars and Bids LLC: Operates an online automotive auction platform specializing in enthusiast and collectible vehicles, connecting buyers and sellers through curated listings, vehicle descriptions, bidding functionality, and community engagement.
- Cars.com: Provides an online automotive marketplace that enables consumers to research, compare, and purchase vehicles through dealer listings, consumer reviews, pricing information, and digital retailing solutions.
- CarsDirect.com: Focuses on online vehicle discovery and purchasing assistance, helping consumers compare vehicle prices, explore financing options, and connect with dealerships through its digital automotive platform.
- Carvana: Competes through its digital-first used-car retailing model, offering online vehicle selection, financing, trade-in services, vehicle history information, and home delivery, supported by its vehicle inspection and reconditioning infrastructure.
- Group 1 Automotive, Inc.: Leverages its international dealership network and digital retailing capabilities to facilitate online vehicle searches, financing, trade-ins, and purchasing processes for new and pre-owned automobiles.
- Hendrick Automotive Group: Combines its established dealership presence with digital automotive retail solutions, enabling customers to explore vehicle inventories, compare models, access financing, and complete various purchasing activities online.
- Lithia Motors: Strengthens its digital automotive retail presence through its Driveway platform, offering online vehicle discovery, financing, trade-in evaluations, and vehicle delivery services across its dealership network.
- Miami Lakes Automall: Competes through its multi-brand dealership operations and online vehicle retailing services, providing digital inventory browsing, price comparisons, financing assistance, and customer support throughout the purchasing journey.
- TrueCar, Inc.: Operates a digital automotive marketplace connecting consumers with certified dealers, emphasizing transparent vehicle pricing, purchase incentives, dealer comparisons, and online tools that simplify the car-buying process.
Strategy is converging on three battlegrounds: ownership of the trade-in valuation, control of the finance offer, and reliability of the delivery promise. Platforms that own all three can price aggressively; dealer groups that own the physical layer can guarantee execution. The competitive advantage in 2026 accrues to whichever side builds partnerships that deliver both.
Policy & Regulatory Landscape, Challenges & Risks
Government policy and regulation have become primary determinants of how quickly online channels can convert demand into registered sales. Key frameworks include:
- European Union e-commerce and consumer protection rules: Harmonised pre-contractual information duties and withdrawal rights provide a predictable basis for cross-border online vehicle sales, which supports platform expansion across member states while raising compliance costs for smaller operators.
- United States state franchise and dealer licensing laws: Statutes in most states restrict manufacturer direct-to-consumer sales and define who may retail new vehicles, shaping platform strategy toward partnership and marketplace models rather than pure direct selling.
- China's new energy vehicle purchase tax treatment: The exemption was extended through 2025 with a phased reduction from 2026, a design that supported electrified volume on digital platforms and now creates a timing effect as buyers and platforms adjust to the higher effective cost.
- UK automotive policy support, 2024: Research cited by the industry body indicates that targeted policies could lift the annual value of the new car market from just over GBP 70 billion, illustrating how fiscal and regulatory design can shift showroom and online volumes within a single planning cycle.
On the constraining side, several structural risks persist:
- Trust and listing authenticity: Buyers still worry about the legitimacy of remote listings and hidden condition issues, so platforms that cannot verify inspection and history face higher abandonment at the final step, which raises acquisition costs and slows conversion.
- Logistics and delivery economics: Home delivery and multi-point vehicle movement carry thin margins that deteriorate with distance and low-density geography, limiting profitability outside metropolitan catchments and slowing expansion into rural demand.
- Financing exposure and rate sensitivity: Because online transactions lean heavily on monthly payment framing, higher borrowing costs compress affordability and can defer purchases, transferring interest-rate risk directly into platform conversion rates.
- Regulatory fragmentation and franchise resistance: Divergent state, national and regional rules on who may sell vehicles and how they must be disclosed create compliance overhead and give incumbent dealer associations grounds to contest direct-sales models, which can delay market entry.
- Operational handover risk: The transition from a completed digital transaction to physical handover, registration and after-sales support remains the weakest link, and failures at that stage generate the disputes that most damage repeat purchase intent.
Forecast 2026-2034
The forecast path runs from USD 424.9 Billion in 2026 to USD 836.4 Billion by 2034, a CAGR of 8.80% that implies roughly a doubling of market value across the period. That rate is notable because it is being achieved on a large existing base rather than from a small experimental segment; adding more than USD 400 billion of annual transaction value in eight years requires the channel to absorb mainstream volume, not just early adopters.
Growth is unlikely to be distributed evenly. Pre-owned vehicles should continue to anchor absolute volume because the transparency and financing tools available online matter most where vehicle history is uncertain. New vehicle sales through digital channels should grow faster in percentage terms as manufacturers standardise configuration and reservation tools, and as franchised groups extend their own storefronts. Electrified powertrains represent the clearest upside variable: their share inside online catalogues is rising, and each incremental electric listing carries a higher average transaction value than the petrol equivalents it displaces.
Regionally, North America is expected to defend its leading position on the strength of platform maturity and delivery infrastructure, while Asia Pacific contributes the largest increment of new demand as connectivity and middle-class purchasing power expand. Europe should grow steadily on the back of certified pre-owned volume and low-emission catalogue depth, and Latin America and the Middle East and Africa are expected to grow from smaller bases as verification and payment infrastructure improve. The overall shape of the forecast is therefore one of broadening rather than deepening: the same model that works in mature markets is being localised, not reinvented, across regions.
Opportunities for Stakeholders
- Franchised dealer groups: Integrate a digital storefront with existing service and reconditioning capacity to capture online demand without surrendering the after-sales relationship, and use the platform data to price trade-ins more accurately.
- Automakers: Standardise configuration, reservation and delivery interfaces so that dealers and marketplaces present consistent pricing, which reduces the discounting spiral that erodes brand value in digital channels.
- Online marketplaces: Move revenue from listing fees toward financing referral, insurance attachment and trade-in spread, reducing exposure to advertising cycles and improving revenue quality per transaction.
- Lenders and fintech providers: Build pre-approval products designed for a single-session purchase, since the ability to show a firm monthly payment at the point of comparison is now a primary conversion lever.
- Logistics and inspection providers: Offer standardised multi-point inspection and staged delivery as a bundled service, addressing the two operational weak points that most often break an online transaction.
- Technology vendors: Supply AI assistants, augmented reality configurators and vehicle history verification as modular components, allowing smaller regional dealers to compete on experience without building proprietary systems.
- Investors and acquirers: Focus on assets that own either the valuation layer or the physical execution layer, because businesses positioned between the two face margin compression as platforms and dealer groups integrate vertically.
Why Digital Retail Keeps Pulling Ahead
The online car buying market is outpacing traditional franchise dealer retail because it removes cost, distance and information asymmetry at the same time, and no physical network can remove all three. The figures bear this out: USD 390.4 Billion in 2025, USD 424.9 Billion in 2026, and USD 836.4 Billion by 2034, at a CAGR of 8.80%, a trajectory that no showroom expansion programme could match on capital efficiency.
The more important conclusion is that the contest is no longer between online and offline channels. It is between operators that control the full transaction journey and those that control only a fragment of it. Dealer groups that built platforms such as Clicklane, marketplaces that acquired the trade-in and wholesale layer such as CarGurus with CarOffer, and retailers that invested in marketplace traffic such as AutoNation with TrueCar are all pursuing the same objective from different starting points. The winners will be those that combine transparent pricing, verified inventory and dependable delivery, and that treat regulation and financing costs as design inputs rather than external shocks. On current evidence, that combination favours the digital channel, which is why its share of global vehicle transactions should keep rising through 2034.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

An Automotive Filter Manufacturing Plant Setup in India serves one of the most dependable segments of the auto component industry. Every vehicle uses several filters, including engine air filters, oil filters, fuel and diesel filters, and cabin air filters, and most must be replaced at regular service intervals, so demand comes both from new vehicle production and from a very large replacement market.
In a radial, the cords of the body ply run straight across the tyre from bead to bead, at right angles to the direction of travel, and a strong belt of steel cords sits under the tread. This design keeps the tread flat on the road, so the tyre runs cooler, grips better, lasts longer, and saves fuel compared with older bias designs.
Tyre pyrolysis oil, or TPO, is a dark fuel oil made by heating shredded end-of-life tyres to about 400 to 500°C without oxygen, so that the rubber breaks down into oil vapours, gas, carbon char, and steel wire.
A farm tractor is built around a frameless chassis in which the engine, clutch housing, gearbox, and rear axle are bolted together to carry the load, with a hydraulic lift and three-point linkage at the back, a power take-off shaft to drive implements, and large rear tyres for traction.
A traction battery is built from lithium-ion cells, each made by coating metal foils with cathode and anode materials, assembling them with a separator and electrolyte inside a sealed case, and charging them for the first time in a controlled formation process.
A goods carrier is built on a ladder-frame chassis of heavy steel side members, onto which the engine, gearbox, axles, suspension, brakes, fuel or battery system, and a pressed and welded cab are fitted, before the vehicle is painted, tested, and sent to body builders or customers.
E-buses run on large lithium-ion battery packs that drive electric traction motors, producing no tailpipe emissions, little noise, and far lower energy and maintenance costs per kilometre than diesel buses.
The Germany Battery Recycling Industry sits where Europe's largest automotive manufacturing base meets its most demanding battery regulation. According to IMARC Group, the market reached USD 814.3 Million in 2025 and is projected to reach USD 1,617.0 Million by 2034, expanding at a CAGR of 7.68% during 2026–2034.
Electric cars are the fastest-growing part of India's passenger vehicle market. Sales roughly doubled in 2025-26, about 6% of new cars sold in the first seven months of 2026 were electric, and more than a dozen models from Indian and global brands now compete across hatchbacks, sedans, and SUVs.
Every electric vehicle needs a charger, and as India's EV fleet grows, so does demand for the equipment that powers it. India registered more than 2.3 million EVs in 2025, public charging stations grew from about 5,000 in 2022 to more than 27,000 by March 2026, and the PM E-DRIVE scheme is funding 72,300 more public chargers by 2028.
Electric vehicles are moving from early adoption to the mainstream in India. Nearly 19 lakh EVs were registered in the first seven months of 2026, and in some segments the shift is already well advanced: more than four in ten new passenger three-wheelers sold in 2026 were electric, while electric two-wheelers, cars, buses, and light commercial vehicles are all gaining share.
Every function in a modern vehicle that moves, from a brake caliper to an air-conditioning flap, depends on an actuator that turns an electronic command into physical motion. The global automotive actuators market size was valued at USD 31.1 Billion in 2025 and is forecast to reach USD 47.3 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 4.62% during 2026–2034, according to IMARC Group.
India is the world's largest two-wheeler market, and it is steadily going electric. Electric scooters, motorcycles, and mopeds offer running costs far below petrol models, suit short urban commutes and delivery work, and are central to the country's clean mobility goals.
Electric bicycles, or e-bikes, combine a conventional bicycle with a small electric motor, a lithium-ion battery, and a controller that assists the rider's pedalling. In India, models limited to 250 watts and 25 km/h do not need registration or a driving license, cost a few paise per kilometre to run, and suit short commutes, fitness riding, students, and last-mile delivery.
Walk into a modern Indian car parts plant, pharmaceutical packing line, or electronics factory and you will see robots welding and palletising, conveyors moving parts between stations, vision cameras checking quality, and control panels coordinating it all.
Tyres are essential to every vehicle on India's roads, from two-wheelers and three-wheelers to cars, buses, trucks, tractors, and off-highway machines.
If the battery is the heart of an electric vehicle, the wiring harness is its nervous system. Every EV needs low-voltage harnesses for lights, sensors, and controls, plus high-voltage harnesses that carry hundreds of volts and high currents between the battery, inverter, motor, and charging port, and dedicated harnesses inside the battery pack that monitor every cell.
Every electric vehicle needs a brain between the battery and the motor. The motor controller, often called the traction inverter in larger vehicles, converts DC power from the battery into precisely controlled AC power for the motor, manages acceleration, regenerative braking, and efficiency, and protects the whole powertrain from faults.
Every vehicle on the road depends on forged parts. Crankshafts, connecting rods, steering knuckles, axle beams, gears, and hubs are forged because the process gives steel a continuous grain flow and the strength to survive millions of load cycles.
Setting up an Automotive Components Manufacturing Plant in India is a high-potential, export-capable venture, powered by the country's large automobile industry, deep supplier base, and growing role as a global sourcing hub for auto parts.
The global automotive lead-acid battery market reached USD 13.89 Billion in 2025 and is projected to reach USD 16.60 Billion by 2034, growing at a CAGR of 1.94% (2026–2034).
Setting up an Electric Scooter Manufacturing Plant in India is a capital-efficient, high-growth venture, driven by the country's rapid shift to electric mobility, supportive EV policies, and surging demand for affordable, clean urban transport. As two-wheelers dominate Indian roads and buyers move from petrol to battery-powered scooter manufacturing, an EV Scooter Manufacturing Plant is one of the most accessible and strategically timed entry points into the electric vehicle economy.
Capital is flowing into the united states used car market because structural affordability pressure, digital retail maturity, and a record-old national vehicle fleet have converged into a genuinely investable thesis.
The Europe Tire Market reached a volume of 458.89 Million Units in 2025 and is projected to reach 565.69 Million Units by 2034, growing at a CAGR of 2.35% (2026–2034).
A strategic analysis of how PLI policies and localization drive global OEM investments. India’s EV battery market hits USD 15,898.31 Million by 2034 (21.7% CAGR).
A tyre is circular in shape and made of a combination of rubber materials that fit perfectly over a circular rim on a wheel, providing traction, load-carrying capabilities, shock absorption, and directional stability. As such, tyres are engineered materials composed of a combination of natural or synthetic materials. They are composed of a combination of materials such as rubber, a combination of materials such as steel or textile, and various chemical materials, among others.
A tractor is a self-propelled, torque-requiring vehicle intended primarily for pulling power at low speeds for agricultural, industrial, and utility purposes. It functions as a mobile power source that can be used for towing, pushing, lifting, or driving a variety of agricultural implements through mechanical, hydraulic, or power take-off systems. Tractors are designed with powerful propulsion systems, sturdy frames, and versatile coupling systems for use on different terrains and under heavy loads.
The electric boat and ship market size is experiencing unparalleled growth as the marine industry embraces electrification on a large scale across different geographies. As sustainability is becoming a strategic priority, with each passing day, more and more marine operators look to electric propulsion technologies as alternatives aimed at cutting down emissions, improving operational efficiencies, and enabling greener ports.
The GCC car rental market has emerged as a critical component of the region's transportation ecosystem, driven by robust tourism activity, expanding business travel, and a substantial expatriate population. Countries across the Gulf Cooperation Council are witnessing unprecedented demand for flexible mobility solutions that cater to diverse customer segments. The GCC car rental market size was valued at USD 1.65 Billion in 2024 as governments prioritize infrastructure development and sustainable tourism initiatives.
The Indian automotive sector has formed a vital part of the country's industrial and economic development for a long period. Over the years, the industry has transformed significantly, influenced by changes in technology, global trends, and consumer preference. Among the various factors shaping its trajectory, government policies have emerged as a decisive force driving growth, innovation, and competitiveness in the India auto parts manufacturing industry.
The India motorcycle tires market continues to evolve in response to changing mobility preferences, rising urbanization, and the growing significance of two-wheelers as essential transportation assets for millions of riders. As per sources, the India motorcycle tires market size reached USD 933.66 Million in 2024. The market is projected to reach USD 2,419.36 Million by 2033, exhibiting a growth rate (CAGR) of 10.3% during 2025-2033.
The Saudi Arabia tire market is undergoing a significant transformation driven by the nation’s economic diversification, rapid urbanization, and growing vehicle ownership. As one of the largest automotive hubs in the Middle East, Saudi Arabia is witnessing increasing demand for both passenger and commercial vehicle tires across urban and industrial regions.
One of the world's most dynamic and quickly changing markets, India's automotive industry is undergoing revolutionary changes in both the new and used car markets. Despite general economic uncertainty, the used car industry has shown remarkable resilience and growth potential, making it a particularly vibrant part of this ecosystem.
One of the world's most vibrant and quickly growing automobile markets is India's passenger car sector. From technological innovation to economic development, a number of interrelated factors have contributed to the sector's remarkable transformation. For stakeholders looking to take advantage of the enormous opportunities in this dynamic market, it is imperative that they comprehend these growth drivers.
India's truck industry is at a turning point in its development, driven by extensive government policies that are changing the commercial vehicle market. The industry, which is the foundation of the country's logistics ecosystem, is gaining previously unheard-of momentum thanks to smart regulatory frameworks and forward-thinking legislative initiatives. A fundamental change in truck operations on Indian highways is being sparked by government initiatives ranging from infrastructure development to emission standards, digitalization, and financial incentives.
The electric rickshaw sector in India has experienced a significant upheaval in recent years and is now a vital part of the country's sustainable transportation network. Strategic government policies aimed at hastening the adoption of clean mobility solutions have played a major role in orchestrating this evolution. India's larger vision of sustainable urbanization is in line with the electric rickshaw industry, which combines social development objectives, economic opportunities, and environmental imperatives.
Transportation in India is undergoing a spectacular change with the advent of electric two-wheelers that are quite an enticing alternative to traditional fuel-powered ones. This change is not merely an act of technological transformation, but an indication of how millions of Indians will think about city mobility, eco-awareness, and economic effectiveness.
As one of the world's leading industrial powerhouses, Japan has long been recognized for its commitment to technological innovation and manufacturing precision. The industry for industrial automation components—encompassing sensors, controllers, actuators, drives, robotics, and human-machine interfaces—represents the backbone of modern manufacturing infrastructure.
The Australian brakes and clutches industry plays a vital role in ensuring vehicle performance, safety, and efficiency across both automotive and industrial segments. As the nation transitions toward electric mobility and smarter manufacturing systems, the demand for advanced braking and clutch mechanisms is rising significantly.
The Philippines automotive wiring harness industry stands at a transformative juncture, driven by technological innovations that are reshaping vehicle electrical architectures worldwide. As vehicles evolve into sophisticated mobile computing platforms, the wiring harness, the circulatory system transmitting electrical power and data throughout modern automobiles, has become increasingly complex and critical to vehicle performance.
Japan's hybrid vehicles market stands as a global benchmark for sustainable mobility innovation, demonstrating remarkable growth and technological leadership. The market achieved a valuation of USD 33.57 Billion in 2024. Japan's hybrid vehicle (HV) market is one of the most established globally, originating with pioneering models like the Toyota Prius. It currently represents a significant portion of the country's automotive sales.
The Japan warehouse robotics market is a highly dynamic and rapidly expanding segment of the global automation industry. The market, valued at USD 414.0 Million in 2024, is on a sharp growth trajectory. Its growth is fueled by critical domestic factors, including a severe labor shortage, the rapid expansion of e-commerce, and Japan's strategic position as a world-leading robotics manufacturer.
The UK is rapidly evolving into a dynamic hub for autonomous vehicle research, testing, and early-stage deployments. A strong ecosystem comprising academic institutions, technology start-ups, automakers, and mobility service providers fosters continuous innovation. Supported by a skilled workforce specializing in software, sensing, robotics, and transportation systems, the nation has become a fertile ground for experimentation.
Japan’s transportation landscape is on the brink of a major shift, with robo taxis, autonomous, driverless vehicles designed for passenger and goods transport, emerging as a practical mobility solution. The Japan robo taxi market reached USD 83.2 Million in 2024 . This remarkable expansion reflects Japan’s broader move toward smart mobility, sustainability, and automation.
The Japan electric truck market is experiencing transformative growth as the nation accelerates toward sustainable transportation and carbon neutrality. As a leading automotive manufacturing hub, Japan is witnessing unprecedented momentum in commercial vehicle electrification, driven by stringent environmental regulations, technological innovation, and strategic government support. The electric truck industry represents a critical component of Japan's commitment to achieving 100% electrified vehicle sales by 2035 and carbon neutrality by 2050.
An EV charging station represents the necessary main infrastructure that allows electrical energy to be transferred from the power grid into electric vehicles to enable their use for transportation. Unlike conventional fueling stations that offer liquid fuels, EV charging stations provide electric power through the use of standardized connectors and smart control systems. The core components include a power conversion unit, which transforms alternating current from the grid into direct current for the vehicle battery; a charging controller controlling communication between the charger and the EV; and a connector or plug matched to the vehicle's charging interface.
An electric scooter is a two-wheeled vehicle powered by an electric motor and rechargeable battery, aimed at offering the means for efficient, eco-friendly, and cost-effective urban mobility. Apart from the traditional scooters that are powered by internal combustion engines, the electric scooters make use of lithium-ion or lead-acid batteries that feed an electric supply to a BLDC motor, which drives the wheels either directly or via a belt or chain mechanism.
Electric bikes, commonly referred to as e-bikes, are one of the most transformational innovations in modern personal mobility, combining conventional bicycle mechanics with advanced electric propulsion technology. At the heart of e-bikes are an electric motor, a rechargeable battery, and a control system that add assistance to the rider while pedaling, making cycling easier, faster, and more accessible across varied terrains. Based on their design, they can be further categorized into pedal-assist, throttle-controlled, or hybrid models, each providing different levels of rider control and engagement of the motor.
The micro-mobility industry has emerged as a transformative force in urban transportation, revolutionizing how people navigate cities worldwide. According to IMARC, the global micro-mobility market size was valued at USD 63.10 Billion in 2024. Looking forward, IMARC Group estimates the market to reach USD 204.83 Billion by 2033, exhibiting a CAGR of 12.86% from 2025-2033.
India's electric vehicle (EV) revolution is accelerating at a breakneck speed, powered by a strategic combination of government incentives, infrastructure investments, and manufacturing policies that are transforming the automotive landscape. The IMARC Group forecasts that the Indian electric car market reached USD 963 Million in 2024.
The diesel engine industry is standing at a transformative crossroads. As global markets are pushing for sustainability, stricter emissions compliance, and cutting-edge innovations, diesel powertrains are facing both immense pressure and promising potential.
The global tire market is a multi-billion-dollar industry, driven by the growing demand for vehicles across emerging economies and the replacement tire segment in developed countries. The global tire market is expected to grow at a compound annual growth rate (CAGR) of 4.70% between 2025 and 2033. The industry is heavily influenced by factors such as technological advancements, raw material prices, environmental regulations, and consumer preferences.
Australia's electric vehicle (EV) sector is experiencing swift expansion, fueled by increasing interest in eco-friendly transportation alternatives. In 2024, sales of battery electric and plug-in hybrid vehicles hit an all-time high, totaling around 114,000 units.
The electric bus industry is the part of the transportation sector that deals with the production and installation of buses that run completely or partially on electricity, employing battery packs or fuel cells in place of conventional diesel or gasoline engines. The buses deliver lower greenhouse gas emissions, lesser noise levels, and enhanced energy efficiency, and thus they are a prime solution for environmentally friendly public transport.
India's electric vehicle market is undergoing a profound transformation, impelled by green priorities, economic imperatives, and changing consumer trends. With rising concerns about air pollution and fossil fuel dependence, electric mobility has become a strategic option for India's transport industry. Policy clarity, technology development, and an emerging ecosystem of makers and suppliers are driving this market shift.
The global electric vehicle market size was valued at USD 755 Billion in 2024. The global EV market is rapidly expanding, driven by technological advancements, government incentives, stricter emission regulations, rising fuel costs, extended battery range, growing environmental consciousness, and significant investments in charging and production infrastructure.
Electric Vehicles, or EVs, are vehicles operated partially or wholly by electrical power, generally with rechargeable battery packs as their fuel. In contrast to conventional internal combustion engine cars, EVs emit no tailpipe emissions, making them a cleaner, environmentally friendly transportation choice. EVs comprise Battery Electric Vehicles (BEVs), Plug-in Hybrid Electric Vehicles (PHEVs), and Hybrid Electric Vehicles (HEVs), and are gaining ground in passenger, commercial, and two-wheeler segments owing to developments in battery technology, charging infrastructure, and policy support.
Aluminum alloy wheels are high-performance, lightweight, and durable components widely used in the automotive industry. Their superior strength-to-weight ratio enhances vehicle efficiency, fuel economy, and handling, making them a preferred choice for both passenger and commercial vehicles. Beyond their functional benefits, aluminum alloy wheels contribute to vehicle aesthetics, offering sleek designs and customization options that appeal to consumers. Their corrosion resistance and thermal conductivity further enhance braking performance and longevity. With increasing demand for fuel-efficient and stylish vehicles, aluminum alloy wheels play a crucial role in the global automotive sector, catering to OEMs, aftermarket suppliers, and performance vehicle manufacturers.
A tyre is a crucial component of a vehicle, serving as the outer covering of a wheel. Its main purposes are to support the vehicle's weight, provide traction for movement, and act as a flexible cushion that absorbs shocks from the road. Usually composed of rubber, tires are strengthened with steel and cloth. Tires for cars, trucks, motorbikes, bicycles, and other vehicles have different designs and compositions depending on the vehicle type and its intended usage. To improve stability and grip, they have a tread pattern on the outside.
Electric kick scooters are small, battery-operated personal transportation vehicles intended for short-distance and urban movement. They offer an economical and environmentally responsible substitute for conventional modes of mobility thanks to their electric engine, rechargeable battery, and lightweight frame. The need for sustainable transportation options, traffic congestion, and growing urbanisation have all contributed to their rise in popularity. Electric kick scooters are now the go-to option for last-mile connectivity and personal commuting because to developments in battery technology, connectivity features, and government programs encouraging micro-mobility.
An automotive wiring harness is an organized assembly of electrical wires, connectors, and terminals that transmit power and signals across a vehicle’s electrical system. It guarantees effective communication between several parts, including the engine control unit, lighting, and sensors. Wiring harnesses are intended to increase vehicle performance and safety by lowering the possibility of short circuits. By maximising electrical connectivity and lowering wire complexity, they are utilised in both conventional and electric automobiles and are essential to contemporary automotive technology.
In an automotive braking system, brake pads are the most important parts since they are engineered to contact the brake rotor to produce friction, thus stopping or slowing down a vehicle in virtually any driving condition safely and efficiently. The key way of classifying these pads is according to their material types: low metallic, ceramic, organic, and semi-metallic.
Tires are essential components of vehicles designed to provide traction, support, and absorb road shocks. Primarily made of rubber, tires consist of treads, belts, and sidewalls that work together to offer grip, stability, and durability. Modern tires come in various types – such as all-season, winter, and performance tires – each engineered for specific driving conditions. The two major tire categories are radial and bias tires, and they are available in different sizes to suit various vehicle types, including passenger cars, light commercial vehicles, medium and heavy commercial vehicles, two-wheelers, and off-road vehicles.
Electric Vehicles (EVs) are powered by electric motors instead of traditional internal combustion engines (ICEs). Electric motors propel EVs by utilizing electricity stored in rechargeable batteries or other energy storage systems. They produce lower or zero tailpipe emissions, reduce air pollution and greenhouse gas (GHG) emissions, and help in mitigating climate change. Electric vehicles consist of various components, such as battery cells and packs, reducers, fuel stacks, power control units, power conditioners, air compressors, humidifiers, motors, on-board chargers, battery management systems, and others. EVs are classified into four types based on propulsion, outlined below.
Saudi Arabia is the second-largest producer and exporter of crude oil and holds the second-largest proven oil reserves in the world, with around 267 billion barrels. The country's oil sector is a significant part of its economy, accounting for 75% of government revenue and approximately 90% of exports. However, due to the volatility of oil prices and the potential for economic instability, Saudi Arabia is increasingly focusing on non-oil activities to reduce its dependency on the oil sector. Non-oil commodities tend to have more stable prices, providing protection against these fluctuations and strengthening the country's social, economic, and financial sectors.