How Early Education Is Driving Growth in the Indian Pre-School/Childcare Market
Introduction: Early Learning Reshapes Childcare
The Indian pre-school/childcare market has moved from a support service for working parents into a mainstream household education decision, and the numbers reflect that shift. According to IMARC Group, the market grew from USD 5.1 Billion in 2025 to USD 5.9 Billion in 2026 and is projected to reach USD 12.0 Billion by 2034, expanding at a CAGR of 9.16% between 2026 and 2034. A market that roughly doubles in eight years is not being carried by demographics alone; it is being carried by a change in what parents expect the first six years of a child's life to deliver.
The demand-side drivers are well established. Rising female labour force participation has converted preschool enrollment from an aspirational choice into a practical household requirement, while urbanisation and the erosion of joint family childcare have left nuclear households dependent on professional supervision. Layered on top is a policy signal: national frameworks now treat foundational literacy and numeracy as a developmental priority, which has raised parental confidence in organised providers.
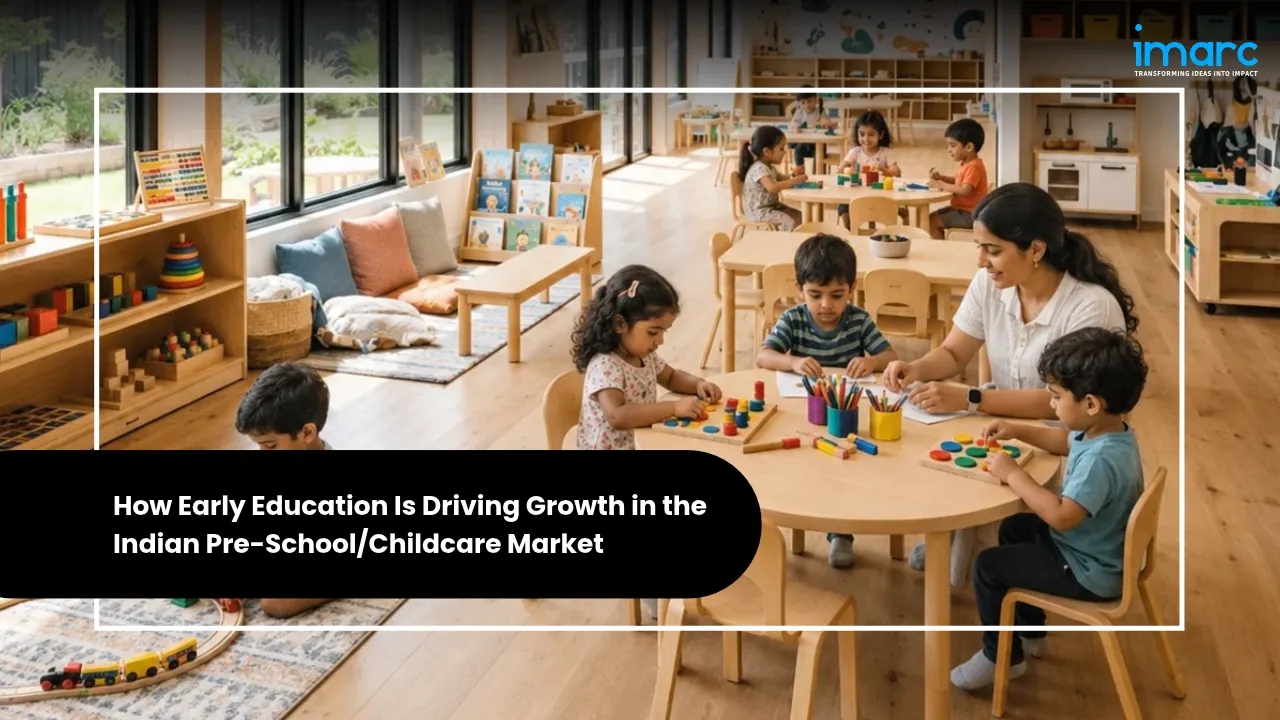
The clearest structural change is in curriculum. Operators are moving away from rote recitation toward activity and play-based learning. In November 2024, Bachpan Play School launched SPROUT, a preschool curriculum aligned with the National Education Policy 2020 and the National Curriculum Framework for Foundational Stage, rolled out across more than 1,200 branches nationwide. Curriculum has become a competitive asset rather than an afterthought.
This blog examines how early education is reshaping the Indian Pre-School/Childcare Market, covering market size and segmentation, recent investments, three structural trends, regional hotspots, competitive strategy, the policy and risk environment, and the outlook to 2034.
Key Takeaways
- The Indian Pre-School/Childcare Market stood at USD 5.1 Billion in 2025, is estimated at USD 5.9 Billion in 2026, and is forecast to reach USD 12.0 Billion by 2034, at a CAGR of 9.16% over 2026 to 2034.
- Full day care is the leading facility segment with a 64.5% share in 2025, as dual-income households buy an integrated day of supervision, meals and learning.
- North India is the leading region with a 32.8% share in 2025, anchored by Delhi-NCR, which alone accounts for 24.5% of the major city segment.
- The most notable recent development is the strategic funding secured by HMI Learning, operator of the Happy Minds International brand, from Germany's Klett Group in December 2025, which signals cross-border investor interest in Indian early education.
- The defining trend is the shift to NEP-aligned, play-based curricula and extended-hour daycare models, which is turning preschools into full early childhood development providers rather than standalone playgroups.
Market Size, Share & Growth Outlook
According to IMARC Group, the Indian Pre-School/Childcare Market was valued at USD 5.1 Billion in 2025, rose to USD 5.9 Billion in 2026, and is projected to reach USD 12.0 Billion by 2034, growing at a CAGR of 9.16% from 2026 to 2034. The single-year step from 2025 to 2026 adds close to USD 0.8 Billion of revenue, which matters because it indicates that demand is outpacing the supply of organised, quality-compliant capacity rather than simply tracking enrollment growth. In a sector where the majority of supply is still informal, that gap is where branded operators are concentrating investment. The leading segments are:
- Facility: Full day care accounts for a 64.5% share in 2025, well ahead of after school care, because working households want supervision, meals, rest and structured learning inside one managed day rather than a short session.
- Ownership: Private operators hold an 89.2% share in 2025, reflecting the limited reach of government-run early education infrastructure and the franchise-led structure through which the sector has scaled.
- Age Group: The 2 to 4 years cohort represents a 48.5% share in 2025, the band parents treat as the formative window for language acquisition, social adaptation and early cognitive development.
- Location: Standalone facilities lead with a 48.5% share in 2025, sustained by neighbourhood trust, independent pricing power and lighter franchise obligations compared with school or office premises.
- Region: North India leads with a 32.8% share in 2025, supported by population scale, dense urban agglomerations and a strong base of organised chains.
Read together, these shares describe a market that is private-led, urban, full-day and northern-weighted. That profile determines where capital, franchise expansion and curriculum investment are most likely to concentrate over the forecast period, and it explains why organised chains prioritise metropolitan clusters before moving into Tier-II corridors.
Recent News & Mega Announcements
Capital and capacity announcements between late 2024 and early 2026 show how quickly the sector is professionalising, with both strategic investors and franchise networks committing to expansion:
- HMI Learning (December 2025): The operator of the Happy Minds International preschool and daycare brand secured strategic funding from Germany's Klett Group to accelerate its India expansion, an early sign of foreign strategic capital entering Indian early education rather than only domestic venture funding.
- Hello Kids (March 2025): The preschool chain marked the opening of its 1,000th centre across India and Bangladesh, demonstrating how franchising can scale a preschool brand to national coverage within a relatively short operating history.
- Footprints Childcare (May 2025): The preschool and daycare chain raised USD 7.5 Million in Series A funding to expand a network of 175 centres across more than 25 cities, with site selection driven by proximity to workplaces and residential hubs.
- Alphabetz International Preschool (January 2026): The brand inaugurated 60 new centres across 11 states, including Telangana, Karnataka and Andhra Pradesh, positioning itself in the affordable international-standard tier rather than the premium segment.
- Bachpan Play School (November 2024): The launch of the SPROUT curriculum, aligned with NEP 2020 and the National Curriculum Framework for Foundational Stage, was extended across more than 1,200 branches, showing that curriculum IP is now a scalable franchise asset.
- KLAY (January 2026): The KLAY Harsha Icon centre in Hyderabad began offering extended daycare and full-day preschool services with structured routines, meals and enrichment activities, a model built explicitly around working parents' schedules.
The pattern across these announcements is consistent: funding is going into multi-city networks, and product design is moving toward longer hours and documented pedagogy. Both raise the capital intensity of the sector, which tends to favour organised chains over individual operators in metropolitan markets.
Industry Trends Shaping 2026
Three trends are restructuring how preschool education in India is designed, delivered and priced in 2026, and each has a direct bearing on where revenue growth will come from.
1. NEP-Aligned, Play-Based Curricula Replace Rote Learning
The National Education Policy 2020 and the National Curriculum Framework for Foundational Stage, released in October 2022, reframed the early years as a structured learning stage built on play, activity and observation rather than recitation. Private operators have responded by treating curriculum alignment as a marketing and quality credential. Bachpan's SPROUT rollout in November 2024 is the clearest commercial example, with the brand positioning a NEP-aligned framework across more than 1,200 branches.
The operational consequences are tangible. Curriculum redesign requires teacher retraining, redesigned classrooms with activity zones rather than rows of desks, and learning materials that support experiential tasks. That raises per-centre investment and creates a quality gap between organised chains that can absorb the cost and standalone operators that cannot, which is one reason regulatory maturity tends to consolidate share toward branded networks in metropolitan areas.
2. Digital Parent Engagement Becomes a Retention Tool
Parents now expect real-time visibility into a child's day, and preschools are using digital platforms to deliver it. Progress dashboards, photo and activity feeds, digital portfolios and app-based fee collection have shifted from differentiators to baseline expectations among urban, smartphone-fluent families. The operational payoff is measurable: preschools using childcare communication applications such as Kiglee reported that parents save between 30 and 90 minutes daily through real-time updates and streamlined communication.
For operators, the value runs in both directions. Transparency builds trust and reduces the daily information friction that drives parent churn, while digitised attendance, billing and event management cut administrative overhead per centre. This matters commercially because preschool retention is a multi-year revenue decision: a family that stays from age two to age six is worth materially more than a single-year enrollment, so tools that reduce early exit have a direct effect on lifetime value.
3. Extended-Hour Daycare Blurs the Line Between Care and School
Full day care already holds a 64.5% share of the Indian Pre-School/Childcare Market, and the service model is expanding further into extended hours. Operators are adding nap routines, nutrition programmes, transport and afternoon enrichment to accommodate professional schedules, effectively merging the daycare and preschool propositions into a single offering. KLAY's January 2026 launch of extended daycare and full-day preschool services at its Hyderabad centre illustrates the direction, with structured routines and meals built around working parents' days.
This shift changes facility economics. Longer operating hours require higher staffing ratios across shifts, larger kitchens, dedicated rest areas and stronger safety protocols, all of which raise fixed costs per centre and push operators toward premium pricing in high-income catchments. It also widens the addressable market, because families that would not pay for a four-hour playgroup will pay for a full working day of supervised care and learning.

Geographic Hotspots in the Indian Pre-School/Childcare Market
North India leads the Indian Pre-School/Childcare Market with a 32.8% share in 2025, and the concentration is structural rather than incidental. The region contains some of the country's largest urban agglomerations, a comparatively young population profile and rapidly rising female workforce participation, all of which convert directly into enrollment demand. It also hosts the deepest base of organised chains and franchise networks, reflecting better access to investment capital and a consumer base that treats early education as academic preparation rather than supervised care.
Within the major city segment, Delhi-NCR accounts for a 24.5% share in 2025. The explanation lies in three overlapping factors: high population density, a high proportion of nuclear and dual-income households, and a concentration of working professionals in sectors with demanding schedules. NCR also spans established metropolitan zones and fast-growing satellite corridors, which allows operators to run premium formats in core areas and mid-market formats in peripheral towns. Proximity to national early childhood policy institutions has reinforced an early-adopter culture among parents, which in turn supports above-average investment in facility quality and educator training.
The secondary hotspots follow employment geography. Bengaluru, Hyderabad, Chennai, Mumbai and Kolkata together form the next tier of demand, each anchored by an IT, manufacturing or financial services base that sustains dual-income households. Hyderabad in particular has seen new full-day and extended-care formats launched in 2026, reflecting its technology workforce profile. Mumbai and Pune reflect the western cluster, where Pune district alone recorded nearly 1,850 registered private pre-primary centres in 2025, a mix of branded chains and small neighbourhood preschools.
The forward geography is Tier-II. As residential development spreads into peripheral corridors and satellite towns, standalone preschools typically arrive first and establish community trust before branded chains enter. For franchisors, these markets offer lower real estate costs and less competitive intensity, but the constraint is teacher availability rather than demand, which is why expansion into smaller cities tends to lag the underlying household demand by several years.
Competitive Landscape & Key Players Strategies
The Indian Pre-School/Childcare Market is heterogeneous. Organised branded chains, regional multi-city operators and a large base of independent standalone facilities compete side by side, and the private sector's 89.2% share means competitive intensity is essentially a private-to-private contest. Chains compete on curriculum IP, brand recognition, facility standards and technology integration. Standalone operators compete on proximity, personal familiarity with families and pricing flexibility. Differentiation through internationally aligned pedagogy, digital parent platforms and extended service offerings has become the main battleground in metropolitan catchments.
Strategy is diverging along three lines. First, franchising remains the dominant scaling mechanism, because it transfers capital expenditure to franchise partners while the brand owner monetises curriculum, training and supply. Second, curriculum and teacher training are being formalised into proprietary assets, which builds switching costs for franchise partners and supports premium fee positioning. Third, location strategy is shifting toward workplace and residential cluster proximity, since travel time is a decisive factor for parents managing two careers.
- Kidzee: Operates one of the largest preschool networks in the country, with scale built on standardised curriculum, franchise support systems and broad geographic coverage across metro and non-metro markets.
- Bachpan Global: Positioned around an indigenously developed, NEP-aligned curriculum, with SPROUT rolled out across more than 1,200 branches to differentiate on pedagogy rather than price.
- EuroKids: Competes on structured early learning programmes and brand consistency across a multi-city footprint, with a strong emphasis on parent communication and child development tracking.
- Tree House Education & Accessories Ltd.: A listed participant that combines preschool operations with educational materials and accessories, giving it exposure across both service and content revenue streams.
- Shemrock Play School: Built around a franchise-led model with a long operating history, and a curriculum orientation toward school readiness for the 2 to 5 year cohort.
- Kangaroo Kids: Positions itself in the premium, internationally influenced segment, targeting parents who prioritise pedagogy depth and facility quality over affordability.
- Hello Kids: Reached its 1,000th centre across India and Bangladesh in March 2025, illustrating franchise-led scale as a route to national and cross-border presence.
- Little Millennium: Targets the foundational learning segment with structured curriculum progression, leaning on parent education and school readiness outcomes as its core proposition.
- Podar Jumbo Kids: Part of a wider education group, which allows it to leverage institutional brand equity and, in some cases, shared infrastructure and teacher pipelines.
- T.I.M.E. Kids: Extends a broader education and test-preparation brand into the early years, using existing brand recall to enter preschool catchments.
The competitive gap that matters over the forecast period is not brand awareness but execution capability: trained teacher supply, curriculum fidelity across franchise outlets, and the ability to operate profitably at longer service hours.
Policy & Regulatory Landscape, Challenges & Risks
Government policy has become a primary market force, because it simultaneously validates early education as a national priority and shapes the quality benchmarks that organised operators must meet. Key frameworks include:
- National Education Policy 2020: Restructures school education into a 5+3+3+4 design with a foundational stage covering ages three to eight, and commits the state to universal provisioning of quality early childhood care and education. For the market, this legitimises preschool enrollment as part of the education pathway rather than a private childcare arrangement.
- National Curriculum Framework for Foundational Stage (2022): Sets out play-based, activity-led pedagogy and defines learning outcomes for children aged three to eight, giving private operators a reference standard to align curriculum and teacher training against, as Bachpan did with its SPROUT rollout.
- Palna (National Creche Scheme) under Mission Shakti: Provides crèche and daycare support for children of working mothers, institutionalising the idea of regulated out-of-home care and normalising daycare as a service category, which supports demand creation even where public supply remains limited.
- Maternity Benefit (Amendment) Act, 2017: Extends paid maternity leave to 26 weeks and mandates crèche facilities in establishments with 50 or more employees, which formalises employer-adjacent childcare demand and supports office-premises daycare formats.
On the constraining side, several structural risks persist:
- Affordability constraints: Private providers dominate with an 89.2% share, and the cumulative cost of tuition, transport, meals and uniforms places organised preschool beyond the reach of lower-income households, capping addressable penetration and leaving large unmet demand in informal-economy segments.
- Shortage of qualified early childhood educators: Expansion of the organised sector has outpaced the supply of formally trained teachers, which constrains curriculum fidelity, delays entry into smaller cities and drives up personnel costs through competitive wage pressure.
- Fragmented regulatory framework: The Right to Education Act does not extend to pre-primary education, leaving licensing, safety and quality standards split across state governments, local bodies and education departments, which raises compliance costs for multi-state operators and slows formalisation.
- Demand concentration and demographic transition: Revenue is heavily weighted toward urban dual-income households and toward the north, so a slower urban job market or continued fertility decline in high-income catchments would directly affect enrollment volumes in the premium tier.
Indian Pre-School/Childcare Market Forecast 2026-2034
The forecast path runs from USD 5.9 Billion in 2026 to USD 12.0 Billion by 2034, a CAGR of 9.16% that implies close to USD 6.1 Billion of incremental revenue being added over eight years. The rate is notable less for its pace than for its durability: it is underpinned by recurring household expenditure tied to a fixed developmental window, which makes revenue less cyclical than discretionary consumer categories.
The composition of that growth is likely to shift. Volume expansion will continue in Tier-II and peripheral metropolitan corridors, where organised penetration is still thin and franchise economics are favourable. Value growth, however, will come from premiumisation: longer service hours, nutrition and transport add-ons, technology-enabled parent platforms and documented learning outcomes. Since full day care already represents 64.5% of the market, incremental revenue is more likely to come from higher realisation per child than from a shift in service mix.
Two conditions govern whether the trajectory holds. The first is teacher supply; without a meaningful expansion of early childhood training capacity, operators will be able to open centres faster than they can staff them. The second is regulatory clarity; a more unified national standard for licensing and quality would reduce compliance friction and accelerate formalisation, while continued fragmentation will keep a large share of the market informal and slow the shift of demand toward organised providers.
Opportunities for Stakeholders in the Indian Pre-School/Childcare Market
The gap between household demand and organised supply is the central commercial opportunity in this sector, and it opens different entry points for different participants:
- Organised chains and franchisors: The strongest lever is curriculum and training standardisation, which allows rapid outlet additions without proportional quality loss, and supports premium fee positioning in catchments where parents are already comparing pedagogy rather than price.
- Standalone operators: Positioned closest to families, they can defend share through service reliability and community reputation, and can adopt NEP-aligned practices to close the quality gap with branded networks at relatively low cost.
- Technology and platform providers: Parent communication, attendance, billing and progress-tracking tools address a measurable operational pain point and carry recurring subscription economics across thousands of centres.
- Investors and strategic acquirers: Fragmentation across a market with an 89.2% private share creates roll-up potential, and the December 2025 entry of a European strategic investor indicates that institutional capital sees long-term rather than cyclical value.
- Teacher training institutions: The shortage of formally qualified early childhood educators is the sector's binding constraint, which makes accredited training programmes a parallel commercial opportunity rather than a support function.
- Real estate and workplace developers: With extended-hour daycare gaining ground, co-located childcare near office and residential clusters offers developers a service differentiator and gives operators access to captive demand.
From Daycare to Foundational Learning
The Indian Pre-School/Childcare Market has crossed a threshold. Parents are no longer buying supervision, they are buying a documented learning pathway for children aged two to six, and providers have reorganised their curriculum, staffing and facility design around that expectation. The shift from USD 5.1 Billion in 2025 to a projected USD 12.0 Billion by 2034 reflects that repricing of the category as much as it reflects rising enrollment.
The constraints are real and are unlikely to disappear quickly. Teacher supply, affordability and state-level regulatory fragmentation will keep a substantial share of the market informal and will slow expansion into smaller cities. But the direction of travel is clear: NEP-aligned pedagogy, longer service hours and digital parent engagement are becoming standard rather than premium features, and operators that can deliver them consistently and at scale will capture a disproportionate share of the next phase of growth.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Setting up a Toilet Paper Manufacturing Plant in India is a bet on one of the country's most under-penetrated hygiene categories. Per capita tissue consumption in India is estimated at under 0.2 kg a year, against a global average of more than 5 kg, yet demand is rising quickly as hotels, offices, hospitals, malls, airports, and urban households adopt Western-style hygiene habits.
The global Bluetooth speaker market is expanding at a rate that most consumer electronics categories no longer achieve, but the growth is being earned under unusually tight margins. According to IMARC Group, the market reached USD 19.5 Billion in 2025 and is projected to reach USD 66.1 Billion by 2034, a CAGR of 14.10% during 2026-2034.
A Glass Bottle Manufacturing Plant Setup in India serves some of the country's steadiest consumer industries. Glass bottles and jars package liquor, beer, soft drinks, sauces, pickles, pharmaceuticals, cosmetics, and perfumes, and brand owners value glass for being inert, impermeable, premium in appearance, and endlessly recyclable.
A Razor Manufacturing Plant Setup in India targets a product that hundreds of millions of people buy again and again. Razors range from traditional double-edge safety blades used by barbers and in rural markets to disposable twin- and triple-blade razors and premium multi-blade cartridge systems.
Setting up a Ceiling Fan Manufacturing Plant in India is a practical, demand-backed venture in one of the world's largest fan markets. Long summers across most of the country, steady housing construction, near-universal household electrification, and a regulatory push toward energy-efficient BLDC models keep demand both large and upgrading.
Adult incontinence products, such as pant-style and tape-style diapers, underpads, and insert pads, are absorbent hygiene products made from fluff pulp and super absorbent polymer wrapped between soft nonwoven fabrics and a leak-proof backsheet, with elastics and fasteners for a secure fit.
The product is a dry, ready-to-chew blend of cut and processed areca nut with catechu, slaked lime, cardamom, flavours, and sweeteners, sold in small pouches, tins, and jars as an after-meal mouth freshener across India.
Male latex contraceptives are thin sheaths made by dipping glass formers into compounded natural rubber latex, curing the film in ovens, stripping and washing the pieces, and then testing every single one electronically for holes before lubricating and sealing it in foil.
Disposable paperboard plates are pressed from food-grade board, often laminated with silver foil paper or coated for grease and moisture resistance, and are used at weddings, festivals, religious gatherings, street food stalls, canteens, caterers, quick-service restaurants, and homes.
The US handicrafts market has moved from the margins of the hobby and gift economy into one of the more resilient corners of American consumer spending. According to IMARC Group, the market stood at USD 345.24 Billion in 2025, rose to USD 372.05 Billion in 2026, and is projected to reach USD 676.82 Billion by 2034, expanding at a CAGR of 7.77% during 2026-2034.
A pocket lighter is a small plastic or metal reservoir of liquefied butane fitted with a valve, a flame adjuster, and an ignition system, either a steel wheel striking a flint or a piezoelectric spark, that releases and lights a controlled flame at the press of a button.
The Saudi Arabia luxury apparel market has moved beyond the volume-led phase of its expansion. IMARC Group values the market at USD 752.2 Million in 2025, with a forecast of USD 1,102.8 Million by 2034, implying a CAGR of 4.34% during 2026-2034.
Cigarettes are composed of finely cut tobacco leaf rolled into a paper cylinder, often with a filter at one end. In India, the demand for domestic cigarette production has grown due to rising consumer markets and diminishing reliance on imports.
The Saudi Arabia kitchen chimney market is moving decisively upmarket, as households stop treating ventilation as a hidden utility and start specifying it as part of kitchen design, indoor air quality and resale value.
Faucets, also called taps or CP fittings, control the flow of water in kitchens, bathrooms, and commercial washrooms. Most quality faucets in India are made from brass that is forged or cast, precision machined, polished, and chrome plated, then fitted with ceramic disc cartridges, aerators, and handles, while lower-priced ranges use stainless steel, zinc, or plastic.
Toys range from moulded plastic figures, vehicles, and building blocks to ride-on cars, soft plush toys, educational and STEM kits, electronic and remote-controlled toys, board games, and puzzles.
The UK Furniture Market is experiencing a period of selective growth, where headline expansion masks significant divergence at the segment level. According to IMARC Group, the market was valued at USD 22.78 Billion in 2025 and is projected to reach USD 32.40 Billion by 2034, growing at a CAGR of 3.87% (2026–2034).
Fast moving consumer goods are everyday products that sell quickly at relatively low prices, such as detergents, dishwash products, surface cleaners, soaps, shampoos, toothpaste, packaged foods, and beverages.
Footwear covers sports shoes, sneakers, leather shoes, sandals, slippers, safety boots, and school shoes. India is the world's second-largest footwear producer, making about 2.9 billion pairs a year, or roughly 12.5% of global output, and its domestic market was valued at about USD 20.67 billion in 2025.
Washing powder is one of the most widely used household products in India, bought by almost every family for hand washing and, increasingly, for washing machines.
Energy meters measure the electricity used by every home, shop, factory, and farm connection, and they sit at the centre of India's effort to cut distribution losses and modernise its power sector.
Sanitary napkins are an essential hygiene product for hundreds of millions of women and girls in India, and one of the fastest-growing categories in personal care.
The Healthy Snacks Market has moved decisively from a niche wellness category to a mainstream pillar of the global food and beverage industry, driven by a fundamental and durable shift in how consumers around the world think about what they eat between meals.
India is one of the world's largest producers and consumers of textiles, and it generates around 7 million tonnes of textile waste every year, from cutting scraps and yarn waste in factories to old clothes and household textiles.
India has more than a billion mobile connections, creating a large and recurring market for chargers, cables, protective cases, screen guards, earbuds and other mobile accessories.
The television has quietly become the most connected screen in many Indian homes. Streaming apps, cricket in 4K, YouTube, and voice-controlled content have turned the TV into a smart device, and falling prices, a lower GST rate, and easy online buying have brought smart TVs within reach of millions of first-time buyers.
India is sleeping better, or at least spending more to try. Rising incomes, smaller urban homes, a booming hotel sector, and growing awareness of back health have pushed households away from cotton gaddas toward engineered foam, spring, and hybrid mattresses.
Setting up a Diaper Manufacturing Plant in India is a high-speed converting venture powered by rising hygiene awareness, growing disposable incomes, low current penetration, and expanding demand across baby and adult categories.
Setting up a Liquid Detergent Manufacturing Plant in India is a formulation-and-blending venture with relatively accessible entry capital, powered by rising hygiene awareness, a steady shift from powders to liquids, expanding modern retail, and growing demand across laundry, dishwash, and household cleaning categories.
Setting up a Kraft Paper Manufacturing Plant in India is a high-demand, sustainability-driven venture, powered by the country's booming e-commerce, packaging, and corrugated-box industries. Kraft paper is the base material for corrugated boxes and packaging, and demand is rising as businesses shift from plastic to recyclable paper-based packaging.
Setting up a Garment Manufacturing Plant in India is a high-demand, employment-generating venture, powered by the country's vast textile base, skilled workforce, and growing role as a global apparel sourcing hub.
The Luxury Fashion Market reached USD 261.0 Billion in 2025 and is projected to reach USD 341.0 Billion by 2034, growing at a CAGR of 3.02% (2026–2034).
Setting up a Container Manufacturing Plant in India is a capital-efficient, high-demand venture powered by the country's fast-growing food, pharmaceutical, FMCG, and industrial packaging sectors.
Bath soap is a body wash product developed primarily to provide personal care. It is made by the alkali saponification, a method that generates soap salts and glycerin in the soap via a reaction between fats or oils and an alkali, such as sodium hydroxide. Bath soaps are made by separating out dirt, sweat, excess oil and microorganisms while helping to remove dirt, sweat, excess oil and water soap from the skin to avoid dirt, extra oil and bacteria and viruses while preserving the balance of both cleansing the skin and compatibility between the application.
Waste tyre recycling can be defined as the organized collection, treatment, and recovery of end-of-life tyres (ELTs) to produce new materials, energy sources, or secondary raw materials. Tyres are made up of vulcanized rubber, steel reinforcement, textiles, and chemical compounds, making them non-biodegradable materials that cannot be easily decomposed.
Wallpaper is a decorative and practical wall covering material used to cover interior surfaces for aesthetic purposes, protection, and ambiance. It is usually made from paper, vinyl, non-woven fibers, textile backing, or a combination of materials, printed or embossed with designs, textures, or solid colors.
The Australian footwear industry is experiencing a remarkable transformation as it navigates a confluence of shifting consumer preferences, technological advancements, and sustainability imperatives.
Tennis ball production is the process of making standardized balls for the game of tennis. The process involves making balls with specific performance and bounce features. A tennis ball is made up of a hollow rubber core that is filled with pressurized air. The core is then covered with a woven felt material.
Soap is a type of cleaning agent made by the chemical reaction of fats or oils and an alkali in a process known as saponification. The chemical reaction transforms triglycerides into soap, also known as fatty acid salts, giving these substances the properties of a surfactant, allowing the substance to be used for the removal of dirt, oil, and bacteria from surfaces.
The size of the global hair oil market has undergone significant transformation with increasing consciousness among consumers to adopt hair care as part of their personal wellness, beyond the realm of mere beauty. Hair oils, being long considered one of the traditional grooming essentials, have transformed into complex formulations to suit various hair types and scalp conditions. Over the past years, lifestyle change, growing awareness related to scalp health, and the rising demand for natural beauty have significantly impacted the consumption pattern in the hair oil segment.
The global online grocery market research landscape has undergone unprecedented changes in recent years, with an upward trend marking the way consumers engage with food retail. There has been a significant expansion in the size of the online grocery market, fuelled by changing consumer preferences, technological advances, and increased convenience associated with digital shopping. Households are showing a growing reliance on online platforms for regular essentials more than ever, making the sector a cornerstone of modern retail.
The UAE’s pet food sector has emerged as one of the most dynamic and lifestyle-influenced consumer categories. While historically smaller and more niche compared to mainstream food and beverage markets, the industry has grown in relevance due to changing demographics, international influences, and shifting consumer priorities. Residents across major cities are embracing pets as companions for emotional well-being and as part of a balanced lifestyle.
The Saudi Arabia road freight transport market represents one of the key building blocks of the economic infrastructure in the Kingdom, providing for cargo movement across various domestic supply chains. It also involves road freight operations, which allow for the distribution of goods-from manufactured goods, consumer goods, and industrial supplies to agricultural produce-across its large and wide geography.
The Saudi Arabia luxury market represents one of the most dynamic and rapidly evolving segments within the Middle Eastern premium retail landscape. As the Kingdom undergoes comprehensive economic diversification and social transformation, luxury consumption patterns are experiencing unprecedented shifts that reflect changing demographics, evolving consumer preferences, and ambitious national development goals.
The Philippines retail sector has become a pluralistic and dynamic environment where old-fashioned stores coexist with high-tech contemporary formats enabled by digital strength. The Philippines retail sector market size reached USD 648.2 Billion in 2025. The market is projected to reach USD 1,223.1 Billion by 2034, exhibiting a growth rate (CAGR) of 7.31% during 2026-2034.
Polyester fabric is a type of synthetic fabric made from polyester fibers. The main source of polyester fibers is petrochemical polymers like polyethylene terephthalate. Polyester fabric is made from processing chips of polymers to produce continuous filaments and staple fibers. The processing of polymers involves heating and melting chips of polymers made from petrochemical materials to produce continuous filaments and staple fibers.
India's gaming industry is rapidly evolving into one of the largest and most dynamic markets in the world. Driven by the increasing adoption of smartphones, affordable internet, and a tech-savvy youth population, gaming is becoming a mainstream form of entertainment.
The beauty landscape in India is undergoing a major transformation propelled by creativity, research, and technology. The India cosmetics market size was valued at USD 15.46 Billion in 2025. Looking forward, the market is expected to reach USD 25.39 Billion by 2034, exhibiting a CAGR of 5.7% from 2026-2034.
The drivers for changing India's textile sector include sustainability, modernization of production, and the introduction of advanced chemical solutions. The India textile market size was valued at USD 152.40 Billion in 2025. The market is projected to reach USD 213.75 Billion by 2034, exhibiting a CAGR of 3.83% from 2026-2034. It places the India textile chemicals market at an important position in this evolution, enabling everything from fiber processing to finishing.
India's consumer landscape is experiencing a profound transformation, driven by rapid digital adoption, evolving consumer preferences, and robust infrastructure development. The shift from traditional brick-and-mortar shopping to digital platforms represents more than a mere change in purchasing channels—it signifies a fundamental restructuring of how businesses engage with consumers and how millions of Indians access goods and services.
The Saudi Arabia deodorants market size continues to evolve as consumers embrace modern grooming habits, premium personal care products, and innovative hygiene solutions. With rising awareness of body care, fragrance layering, and daily freshness, deodorants have become an essential part of both men’s and women’s personal grooming rituals.
Pet foods consist of commercially processed foods that contain nutritional requirements tailored according to their consumption by domesticated pets like dogs, cats, birds, fish, and small animals. The foods contain planned nutritional compositions, such as ingredients like protein, carbohydrate, fat, vitamins, and minerals.
Perfume is a scented liquid composition that contains a mixture of fragrance chemicals, essential oils, aroma chemicals, fixatives, and solvents that are formulated for a pleasing and distinct fragrance emission upon application on human skin or on objects.
Technological advancements and shifting consumer expectations have caused the worldwide washing machine industry to drastically change. Washing machines are becoming indispensable parts of contemporary homes, smoothly integrating into smart home ecosystems from conventional semi-automatic models to fully linked, smart appliances.
Paper plates are disposable food containers, also referred to as tableware, and are made mostly from paperboard, pulp, and materials that are derived from fibers. These plates are designed to be convenient, hygienic, and easy to handle while being moisture and grease-proof, making them ideal for packing different food varieties, ranging from dry foods to moist and greasy food items.
The GCC cigarette lighter market is undergoing a steady phase of expansion due to evolving consumer habits, sustained product demand, and widening distribution channels across the region. In 2024, the GCC cigarette lighter market was valued at USD 197 Million. A key factor shaping industry performance is the rise in convenience-led purchases, driven by widespread retail penetration, duty-free availability, and the continued popularity of smoking-related accessories.
Paint brushes are hand-operated applicator tools, designed and manufactured with great precision, utilizing the capabilities of these tools to apply, spread, and manage liquid paint, along with other forms of paint such as varnishes, stains, lacquers, and surface finishes, onto a desired surface. Paint brushes are commonly manufactured using a series of components, including a handle, a ferrule, and natural or man-made hairs, or a combination of these two. They are also manufactured and designed with different shapes and sizes, according to the viscosity and texture of the paint.
Pan masala is a ready-to-use chewing mixture that is traditionally used as a mouth freshener as well as a digestive aid and is of South Asian origin. It is prepared by mixing different components such as areca nut, catechu, slaked lime, spices, flavoring agents, sweet agents, and aroma agents in specific proportions. It is usually packed ready for use and is different from the betel quid variant that is prepared by using fresh betel leaves. Contemporary formulations of pan masala aim to achieve consistency, shelf life, and standardized flavor so that it can be mass-produced and marketed.
Paper bags can be defined as the final product made from paper-based material such as kraft paper, recycled paper, or specialty paper, used for packing or storing products. Paper bags come in different shapes and sizes with varying strength, ranging from flat-bottom paper bags, gusseted paper bags, and handled paper bags. Paper bags can be biodegradable, can be recycled, and can be made from renewable resources.
The Brazil cosmetics products market represents one of the most vibrant and diverse beauty sectors in Latin America, reflecting a deep-seated cultural emphasis on personal appearance, wellness, and self-care. The Brazilian consumer has long been known for a keen taste for grooming, fashion, and aesthetics, which logically applies to the cosmetics industry. Driven by an expanding middle-class population, an increase in urbanization, and increasing awareness about wellness-oriented lifestyles, the market continues to evolve.
The commercial landscape across the globe is undergoing a seismic shift, driven by technology, changing consumer expectations, and macroeconomic volatility. This transformation is particularly pronounced in high-density, globally connected urban centres like Singapore. Historically a powerhouse of trade and luxury commerce, the nation is now navigating an intricate matrix of digital disruption and soaring operational pressures.
The India confectionery industry has emerged as one of the most dynamic segments within the country's food and beverage sector. Driven by changing consumer preferences, rising disposable incomes, and evolving lifestyles, the market continues to witness remarkable transformation across urban and rural landscapes.
As disposable incomes rise, households are diversifying across investment-grade gold, diamond-studded jewellery, and designer ornaments. Gold, in particular, holds unmatched cultural and economic importance, sustaining demand even through economic fluctuations. Recent indicators show how this cultural attachment continues to translate into measurable investment momentum. Gold demand stood at 135 tonnes in Q2 2025, with a full-year forecast between 600 and 700 tonnes. By mid-2025, India’s total gold holdings reached 66.7 tonnes, with two tonnes added in June and nine tonnes in the first half of the year.
Mobile accessories encompass a wide range of auxiliary products that are intended to complement, protect, enhance, or extend the functional capabilities of smartphones and other portable communication devices. Examples of these accessories include protective cases, screen guards, chargers, power banks, earphones, wireless earbuds, smart wearables, mounts, portable speakers, and connectivity adapters. They enable better usability, device safety, personalization, convenience, and integration with digital ecosystems. Mobile accessories are made from a variety of materials and technologies to meet various performance, durability, and design requirements for different groups of users.
Japan boasts a long and rich culture of traditional board games such as Go and Shogi, which have long been a fundamental component of its culture. The current board game market in Japan, though, is a vibrant mix of these indigenous games and an incredibly diverse range of modern games based on both Western and domestic design schools.
The tobacco industry has long been a cornerstone in world trade and consumer culture, shaping the courses of economies, employment landscapes, and industrial practices for centuries. Even in today's world, with growing awareness regarding health and sustainability, tobacco remains an imposing force in global commerce.
The Australia sportswear industry is experiencing unprecedented momentum, transforming into a multi-billion-dollar powerhouse where fashion, fitness, and lifestyle converge. As health consciousness sweeps the continent and athleisure becomes a wardrobe staple, the Australian market leads a global revolution in performance apparel.
Japan's luxury apparel industry has traditionally been characterized by its profound respect for craftsmanship, quality, and cultural refinement. Japanese consumers have a reverence for art and nuance, preferring items that reflect precision and enduring design over short-lived trends. Over the past decade, Japanese luxury fashion has transcended conventional retailing experiences and assumed a contemporary identity that coalesces international influences with domestic sentiments.
A mattress is a cushioned structure intended to support the human body, either while sleeping, resting, or for therapeutic purposes. It is typically made up of comfort layers, including foam, latex, fiber, or gel, combined with a supportive core, like innerspring coils, high-density foam, or hybrid constructions. Mattresses are designed to evenly distribute body weight to relieve pressure points and ensure proper spinal alignment.
Liquid detergent is a formulated cleaning solution comprising surfactants, solvents, builders, enzymes, pH stabilizers, perfumes, and other additives, which are collectively used for removing dirt, stains, and oils from fabrics, dishes, and different surfaces. Unlike powdered detergents, liquid detergents dissolve immediately in water, allowing even distribution during washing and effective performance in both hot and cold water.
The Japan personal luxury goods industry stands as one of the world’s most crucial and dynamic markets, consistently ranking among the top three globally, alongside the United States and China. In 2024, Japan personal luxury goods market size reached USD 32,060.65 Million in 2024.
The luxury watch industry represents one of the most enduring segments of the global fashion and lifestyle market. Combining precision engineering with timeless craftsmanship, luxury watches continue to hold strong appeal among high-net-worth individuals, collectors, and aspirational consumers. The global luxury watch market size reached USD 29.12 Billion in 2024, reflecting steady growth driven by premiumization, rising consumer demand in emerging economies, and the enduring value of heritage timepieces.
The Vietnam athleisure market stands at a pivotal juncture, experiencing remarkable transformation driven by evolving lifestyles, rising health consciousness, and rapid urbanization. As Vietnamese people are increasingly prioritizing wellness and seeking versatile clothing that seamlessly transitions from gym workouts to casual social settings, the demand for activewear trends has surged dramatically. With lifestyle apparel Vietnam witnessing unprecedented growth and fitness clothing demand reaching new heights, both international brands and homegrown labels are competing vigorously to capture market share in this dynamic sector.
The Philippines conveyor belt market is picking up speed, powered by the country’s industrial growth and focus on automation. According to the IMARC Group, the market reached USD 31.23 Million in 2024, reflecting notable growth across manufacturing, mining, logistics, and food processing. As industries modernize, the need for efficient material handling systems is creating strong momentum for both domestic and imported conveyor solutions.
The US retail market is undergoing a profound transformation, fueled by the integration of artificial intelligence (AI) across multiple business operations. From personalized consumer engagement to predictive inventory management and dynamic pricing strategies, AI is redefining how retailers operate, compete, and deliver value. Increasing consumer expectations for seamless, personalized, and efficient shopping experiences are prompting businesses to embrace AI-driven solutions to optimize performance, reduce costs, and enhance decision-making.
The global beauty and personal care products market is undergoing a profound transformation, driven by technological innovation, evolving consumer expectations, and sustainability-focused practices. Increasing consumer awareness of health, wellness, and ethical sourcing is compelling companies to rethink traditional formulations and adopt advanced manufacturing techniques. Businesses are now integrating biotechnology, artificial intelligence, and data-driven insights into product development, distribution, and marketing strategies.
The Philippines board game market is on a winning streak, fueled by a growing passion for social play, learning, and creative pastimes. According to IMARC Group, the market reached USD 83.39 Million in 2024, reflecting how board gaming is becoming a favorite form of entertainment across generations. Family games, strategy and role-playing titles, and educational options for kids are gaining steady traction, alongside collectible and pop culture–inspired editions.
The Australian fantasy sports industry is entering a phase of heightened momentum, with market size for 2024 reaching approximately USD 810.6 Million, as detailed in a recent report. This market is forecast to grow to USD 2,180.2 Million by 2033, representing a compound annual growth rate (CAGR) of around 10.4 % from 2025 through 2033 .
Australia's textile recycling sector is experiencing a technological renaissance, with 40% of SMEs currently adopting artificial intelligence (AI), marking a 5% increase compared to the previous quarter (July-Sept 2024). The percentage of businesses unaware of how to utilize AI has decreased by 2% to 21%.
Containers are standardized, tough, watertight containers for efficient storage and transportation of goods by ship, rail, and truck without the need for handling the cargo itself. They are the lifeblood of global trade and logistics, allowing for effective intermodal transport. Constructed from high-strength steel, aluminum, or composite materials, they are designed to withstand rigorous marine and environmental elements. The most common types are dry storage containers for general cargo; however, there are also refrigerated (reefers) for perishables, tank containers for liquids and gases, open-top and flat-rack for oversized equipment, and high-cube for voluminous cargo. Standardization, mainly through ISO specifications, allows for seamless compatibility and efficiency throughout global logistics systems.
Carpet is a textile floor covering made of a pile, tufts of yarn or fiber, sewn to a backing for dimensional stability. Carpets are manufactured in various construction forms: tufted (universal across the world, yarn punched through a primary backing and treated with secondary backing), woven (Wilton and Axminster, highly valued for durability and pattern intricacy), needle-felt (bonded fibers for industrial applications), and knotted (hand-made rugs).
Aloe vera gel is a natural concentrate obtained from the parenchyma of the inner leaf of Aloe barbadensis miller, which is valued for its therapeutic, nutritional, and cosmetic uses. The gel mostly comprises water (more than 95%) and polysaccharides, vitamins, minerals, amino acids, enzymes, and antioxidants responsible for its soothing, moisturizing, and healing actions. Renowned for its anti-inflammatory, antimicrobial, and skin-rejuvenating properties, the aloe vera gel finds broad application in personal care cosmetics, pharmaceuticals, food supplements, and beverages.
Aloe vera is a perennial fleshy succulent plant of the species Aloe barbadensis miller, grown worldwide for its nutritional, medicinal, and cosmetic benefits. It has two primary constituents: the transparent inner gel consisting mainly of polysaccharides, vitamins, enzymes, and amino acids; and the yellowish latex, consisting of anthraquinones with powerful laxative properties. Aloe vera gel is highly prized for its emollient, moisturizing, and healing properties and is a common ingredient in skincare, personal care, and pharmaceutical products.
Air purifiers are appliances that enhance indoor air quality by eliminating pollutants like dust, allergens, smoke, volatile organic compounds (VOCs), and microbial particles. They work on various technologies such as HEPA (High-Efficiency Particulate Air) filters, activated carbon filters, UV-C light, ionizers, and photocatalytic oxidation. Their major components are usually fans or blowers, filter media, sensors, electronic controls, and metal or durable plastic housings. Some of the crucial characteristics of air purifiers include efficiency of filtration, airflow, noise levels, power consumption, and filter material durability.
Air coolers are evaporative coolers based on the principle of water evaporation, utilizing a fan or blower to blow cooled air, as opposed to air conditioners, which function based on refrigerant and compressor principles. Air coolers are designed to deliver low-cost and energy-efficient temperature management, mainly applicable to dry and hot climates. They generally consist of a pump, motor, cooling pads, water tank, blower/fan, and electronic control units. Main characteristics are low energy usage, environmental friendliness, portability, and low cost. Production of air coolers typically consists of combining sheet metal or plastic enclosures with motor-driven fans, water distribution networks, and cellulose or aspen cooling pads.
A4 paper, which is one of the most commonly used paper formats around the world, is 210 mm × 297 mm and forms the part of the ISO 216 system. It mainly consists of cellulose fibers obtained from wood pulp, recycled papers, or other fibrous raw materials like bagasse or bamboo. A4 paper contains crucial characteristics like smoothness, even thickness, high opacity, brightness, tensile strength, and durability, which enable it for printing, copying, and writing. The production process includes pulping raw fibers, bleaching for whiteness, refining for increasing fiber bonding, and sheet formation under regulated drying and calendaring.
The manufacturing sector is constantly changing with continuously rising demands for sustainability, innovation, and efficiency. The time comes when companies want to expand their business or venture into new markets.
India's manufacturing industry is experiencing a remarkable transformation and growth in 2025, aiming to establish the nation as a key player in global manufacturing. Supported by governmental initiatives such as the Make in India program and the Production Linked Incentive (PLI) schemes, the sector has drawn significant foreign direct investment (FDI) and encouraged innovation across multiple industries.
India's manufacturing industry is undergoing a turning point in 2025 based on strong government initiatives, a highly skilled and youthful population, and a worldwide trend towards diverse supply chains.
The global tobacco sector remains one of the most mature yet closely scrutinized industries in the world. With demand persisting across both developing and developed markets, cigarette production continues to be a high-volume, technically refined activity governed by extensive regulation and economic influence.
The global vegan cosmetics market is experiencing unprecedented growth, driven by a new wave of conscious consumers who demand beauty products that are not only effective, but also ethical, sustainable, and cruelty-free. This movement is more than just a passing trend; it's a fundamental shift in values that is reshaping the industry.
The global online grocery market has rapidly evolved from a convenience service to a mainstream retail segment, reshaping how consumers shop for everyday essentials. According to the IMARC group report, the market reached a value of USD 710.10 Billion in 2024 and is projected to witness consistent expansion.
The India textile market is picking up serious momentum, supported by smarter tech and changing user preferences. As more buyers look for eco-friendly, premium-quality products, manufacturers are stepping up with automation, digital tools, and flexible production systems.
The global toys market plays a crucial role as toys fundamentally support child development by fostering creativity, cognitive skills, and social interaction. In 2024, the global toys market was valued at USD 113.94 Billion.
The worldwide luxury watch market is poised for sustained growth, driven by rising affluence, aspirational lifestyle, and digital evolution. As consumers place greater importance on exclusivity and craftsmanship, demand for luxury watches is growing in developed as well as emerging markets.
Baby wipes are wet disposable wipes used to clean the tender skin of an infant, mostly when changing diapers. Composed of non-woven materials and embedded with delicate cleansing products, commonly made from water, mild surfactants, moisturizers such as aloe vera, and preservatives baby wipes are made to be delicate, hypoallergenic, and safe for daily use.
A tennis ball is a type of high-performance sporting ball used in both competitive and recreational tennis. On various court surfaces, its rubber core and felt covering provide the best bounce, speed, and durability. Both pressurised and non-pressurized tennis balls are available to accommodate different playing situations and ability levels. Under international regulations, they are crucial for competitions and training, and business expansion is being driven by sustainability and material innovation.
Caramel colour or E150d, is a common food and beverage colouring ingredient that is made by carefully heating food-grade carbohydrates with alkali or acid catalysts. Known as sulfite ammonia caramel, it gives baked items, sauces, soft drinks, and alcoholic beverages a rich brown colour. In food business, it is a preferred option because to its stability, solubility, and capacity to improve aesthetic appeal. Major food regulators across the world have authorised E150d and regulated it for safe consumption.
Kitchen appliances are a diverse category of electrical and mechanical devices that are essential in modern kitchens for various cooking and food preparation tasks. These appliances have revolutionized the way we prepare and cook food, making the process more efficient and convenient. For instance, refrigerators are crucial for storing perishable foods and keeping them fresh. Ovens and stoves are fundamental for baking, roasting, and cooking on open flames or electric coils. Microwaves provide quick heating, cooking, and defrosting, saving time in the kitchen. Dishwashers automate the often-tedious task of cleaning dishes, while blenders and food processors simplify chopping, pureeing, and blending ingredients.
A plastic cigarette lighter is a small portable hand-held device that gives a flame generally used for lighting cigarettes, cigars, candles, and other small things. They are mostly butane-gas fueled, which makes them easily disposable after all the fuel has been depleted. It's manufactured using polycarbonate or polypropylene plastic, so it's very lightweight and affordable.
Tissue paper, made from both virgin and recycled pulp, has become an essential part of daily life for cleaning, dusting, wrapping, and personal use. The industry's expansion is driven by luxurious tissue products, ultra-absorbent paper towels, and rising prices. Favorable factors such as growth in the IT sector, tourism, and MNCs, along with shifts in lifestyle and attitudes towards hygiene, cleanliness, and freshness, have boosted tissue consumption. Institutions like hospitals, malls, office complexes, and F&B chains are major consumers. Government support for sustainable practices has further spurred growth. West and South India are projected to be the largest consumers of tissues due to high foreign tourist influx, growing urbanization, and a hot climate that increases demand for disposable tissues.
While secondary research acts as the base of decision-making for businesses, primary research fills in the gaps that only a nuanced and personalized perspective can deliver. With enormous volumes of data being added daily on search engines, relying on obsolete and unauthentic data could cost businesses heavily. To stay ahead of the curve and make informed decisions, tapping directly into the information gathered through your customers is essential. This helps reveal the drivers of the decision-making process, unveiling unmet needs, and highlighting nascent trends before they take shape.
Consumer behavior mainly includes consumers’ mental, emotional, and behavioral responses toward the buying pattern of products. There are several factors that influence consumer behavior, such as personal, social, cultural, and psychological. Personal factors include the age, gender, and income of the consumer. Social factors like friends and family and cultural factors such as religion and tradition also play an important role in consumer buying patterns. Motivation, perception, and learning about goods and services change consumer preferences and fall under psychological factors.