Textile Chemicals Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
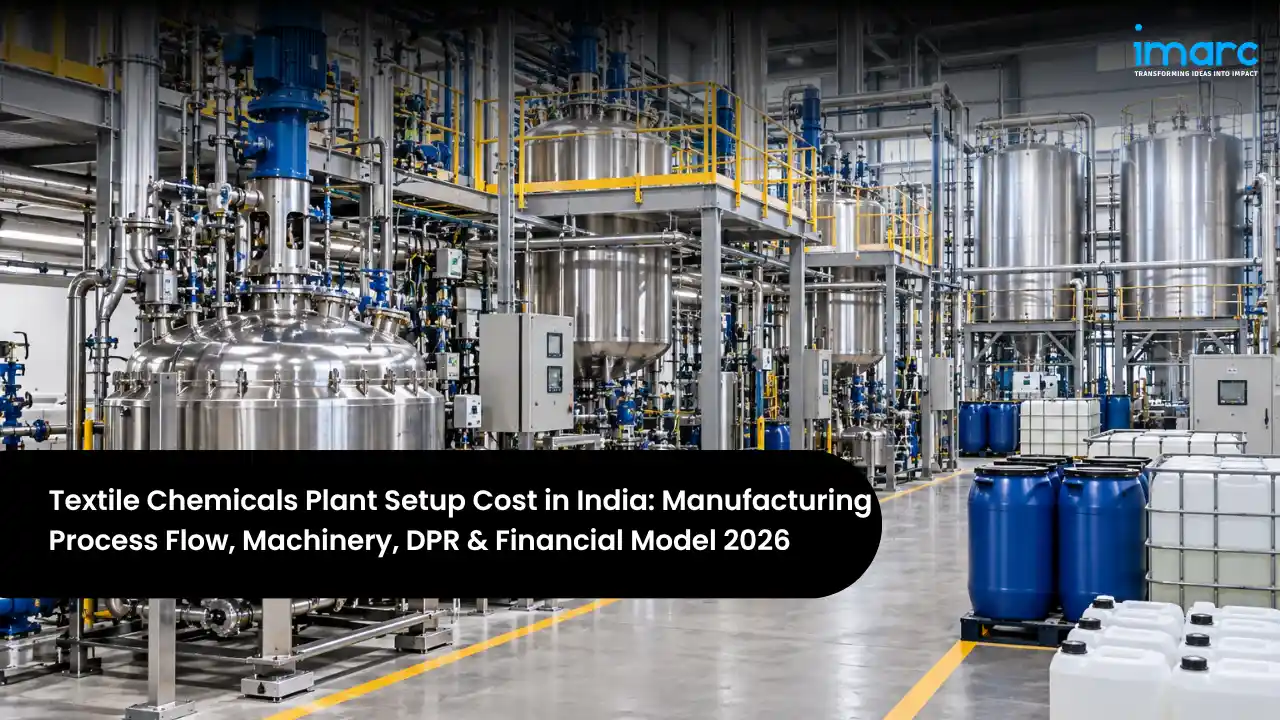
Setting up a Textile Chemicals Manufacturing Plant in India is a high-value, demand-driven venture, powered by the country's vast textile industry, its rise as a global apparel and fabric sourcing hub, and a strong push toward import substitution in specialty chemicals. Textile chemicals are the auxiliaries and formulations used at every stage of fabric processing, from pretreatment and dyeing to finishing, and demand rises with every metre of fabric produced. With a deep domestic textile base, growing technical-textile demand, and a chemical-manufacturing ecosystem centred in states like Gujarat, a Textile Chemicals Manufacturing Plant is one of the more attractive value-added opportunities in the specialty chemicals economy.
The Textile Chemicals Manufacturing Plant Cost depends on capacity, product portfolio, and whether the unit synthesises actives or formulates them, with total project investment typically ranging from INR 5 crore to INR 50 crore. Raw material, chiefly surfactants, polymers, silicones, and specialty actives, is the largest operating input, so sourcing and formulation efficiency are the most important financial decisions in the project, and together they shape the overall Textile Chemicals Investment Cost. At healthy capacity utilization, a well-run unit in India delivers a net profit margin of 10 to 18% and an IRR of 20 to 30%, with payback typically achieved within 3 to 5 years.
This guide is written for investors and entrepreneurs asking how to start a Textile Chemicals manufacturing plant in India. It covers what the business involves, why demand is rising, the process flow, the machinery and raw materials required, location and infrastructure planning, a detailed cost and financial breakdown, the licenses you must secure, and how a project report and DPR turns all of this into a bankable plan.
India Market Snapshot
| Key Facts | Details |
|---|---|
| India Specialty Chemicals Market | Large, multi-billion dollar (indicative) |
| Primary Products | Pretreatment, dyeing, and finishing chemicals |
| Projected Market CAGR (2026–2034) | 9–13% (indicative) |
| Typical Plant Capacity | Few thousand to 20,000+ TPA |
| Indicative Total Investment | INR 5–50 Crore |
| Typical Payback Period | 3–5 Years |
The snapshot captures why a Textile Chemicals Manufacturing Plant in India attracts strong investor interest: an essential input to a huge textile industry, broad and growing demand, and a maturing specialty-chemicals base. The wide investment range reflects a genuine choice of scope and scale, from a formulation unit blending purchased actives to a larger integrated plant that synthesises its own chemistry. Because textile chemicals are a recurring, consumable input across dyeing and processing houses, the demand base is resilient, which is part of why lenders view the sector favourably. The rest of this guide unpacks that decision in detail.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Plant Capacity (Typical) | Few thousand to 20,000+ TPA |
| Total Project Investment | INR 5 – 50 Crore |
| Payback Period | 3 – 5 Years |
| Net Profit Margin | 10 – 18% |
| IRR | 20 – 30% |
| Best Locations | Gujarat, Maharashtra, Tamil Nadu, Punjab, Rajasthan |
| Mandatory Approvals | CPCB/SPCB, Factory Licence, PESO, Fire NOC, GST |
| Primary Revenue | Textile processing auxiliaries and finishes |
These indicative parameters give a realistic frame for early feasibility work. The returns are attractive, but they depend on securing competitively priced raw material, developing reliable formulations, and building steady buyers among dyeing houses, processing mills, and textile brands. A well-prepared Textile Chemicals Feasibility Report tightens each of these numbers to your specific location, capacity, and product portfolio.
Table of Contents
- What are Textile Chemicals?
- Why is Textile Chemicals Growing in India?
- Textile Chemicals Process Flow
- Raw Materials Required for Textile Chemicals
- Location, Land & Infrastructure
- Textile Chemicals Machinery and Equipment
- Textile Chemicals Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for Textile Chemicals Plant in India
- Recent Developments in the India Textile Chemicals Industry
- How a Textile Chemicals Project Report and DPR Helps Investors
- Frequently Asked Questions
What are Textile Chemicals?
Textile chemicals manufacturing is the production of the auxiliaries, agents, and formulations used to process fabric, from preparing and dyeing it to giving it functional finishes. Most Indian units either synthesise active chemistry through reactions or, more commonly, formulate finished products by blending purchased actives with additives, and many do both. The output spans pretreatment agents, dyeing and printing auxiliaries, and finishing chemicals, all consumed in large volumes by dyeing houses and processing mills.
From a business perspective, what makes this sector attractive in India is the combination of a massive captive customer base and steady, recurring demand. Every dyeing house, processing mill, and finishing unit is a repeat buyer, and a growing chemical-supplier ecosystem provides the surfactants, polymers, and actives needed. A manufacturer that develops reliable, consistent products and supports customers technically is positioned to serve a large, essential, and steadily growing market driven by textile output and rising quality standards.
- Pretreatment Chemicals: Desizing, scouring, and bleaching agents that prepare fabric for dyeing, a high-volume category.
- Dyeing & Printing Auxiliaries: Levelling, dispersing, fixing, and thickening agents that improve dye uptake and print quality.
- Finishing Chemicals: Softeners, binders, and functional finishes that add feel, durability, and performance.
- Functional & Eco Finishes: Water repellents, flame retardants, and eco-compliant chemistry that command better prices.
The Main Segments in Textile Chemicals
Understanding which segment your unit will serve is the foundational decision, because it drives chemistry, machinery, and value:
| Segment | Typical Products | Key Property | Primary Demand |
|---|---|---|---|
| Pretreatment | Scouring, bleaching agents | High volume | Processing mills |
| Dyeing Auxiliaries | Levelling, fixing agents | Quality-driven | Dyeing houses |
| Finishing | Softeners, binders | Higher margin | Finishing units |
| Functional / Eco | Repellents, eco finishes | Specialty, premium | Brands and exporters |
This choice shapes the entire unit, because pretreatment agents are high-volume commodity chemistry while finishing and functional formulations command better margins but need stronger R&D and process control. Many Indian entrants begin with pretreatment and standard auxiliaries, the largest and most accessible segment, and move toward finishing and eco-compliant specialty chemistry as they build formulation capability and buyers. The segment decision drives everything from machinery to the level of investment required.
Why is Textile Chemicals Growing in India?
Key Growth Drivers in the Indian Market
India's textile chemicals sector is being propelled by several structural factors that combine a huge domestic textile base with import substitution and rising standards. Few products ride as many favourable trends at once:
- Large, growing textile industry: India's vast and expanding fabric-processing base creates enormous, recurring demand for processing auxiliaries.
- Import substitution push: A drive to replace imported specialty chemistry with domestic production favours local manufacturers.
- Rising quality and eco standards: Buyer and regulatory demand for compliant, sustainable chemistry expands the higher-value segment.
- Technical and functional textiles: Growth in performance fabrics increases demand for functional finishes and specialty agents.
- China-plus-one sourcing: Global supply-chain diversification is drawing textile and chemical value into India.
India-Specific Market Opportunity
| Segment | India Market Context | Chemical Role |
|---|---|---|
| Fabric Processing | Large dyeing and processing base | Core auxiliaries |
| Apparel Exports | Rising global sourcing share | Compliant chemistry |
| Technical Textiles | Fast-growing segment | Functional finishes |
| Home Textiles | Strong export category | Finishing agents |
| Sustainable Textiles | Eco-compliance demand | Green chemistry |
The strongest opportunity lies in supplying dyeing houses, processing mills, and exporters with consistent, competitively priced, and increasingly eco-compliant chemistry, ideally near both raw-material supply and textile clusters. A manufacturer that delivers reliable products with technical support can lock in steady, repeat orders. Moving into finishing, functional, and green formulations, where margins are better and relationships stickier, further strengthens a unit's position in a large, growing market.
Textile Chemicals Process Flow
Understanding how these products are actually made helps you plan equipment, raw-material handling, and the main cost drivers. Production is a batch operation that turns raw chemistry into a reacted or blended, quality-checked, and packed product, with quality control throughout, and it is both utility- and effluent-sensitive. The typical flow moves raw material through reaction or blending to a tested, filtered, and filled product:
The Textile Chemicals Manufacturing Process
In this flow, raw materials are charged into reactors or blending vessels, reacted or mixed under controlled temperature and agitation, adjusted for pH and viscosity, then quality-tested, filtered, and filled. Consistent batch control and reliable quality testing are essential to products that perform the same way every time on a customer's fabric.
| Unit Operation | Key Activity |
|---|---|
| Raw Material Intake | Raw materials received and tested |
| Charging | Materials charged into the vessel |
| Reaction / Blending | Reacted or mixed under control |
| Heating / Cooling | Temperature controlled for the batch |
| Adjustment | pH and viscosity adjusted to spec |
| Quality Testing | Batch tested in the laboratory |
| Filtration | Product filtered for clarity |
| Storage | Held in bulk storage tanks |
| Filling & Packing | Filled into drums or carboys |
| Dispatch | Labelled and dispatched to buyers |
Two points determine profitability across this flow. First, formulation quality and batch consistency drive both performance and cost, so reaction or blending control and quality testing directly govern outcomes. Second, the process uses utilities and generates effluent, so energy efficiency and proper treatment are decisive for both margin and compliance. Rigorous quality control, batch by batch, is what allows a manufacturer to certify products to specification and win repeat orders. Because dyeing houses and mills run their own tight processes, consistent product performance and reliable supply matter as much to them as headline price.
Raw Materials Required for Textile Chemicals
The main inputs are surfactants, polymers, silicones, solvents, and specialty actives, and securing them at competitive prices and consistent quality is the single biggest determinant of a unit's viability. Because raw material dominates cost and its price varies with petrochemical and specialty cycles, procurement strategy and a reliable supplier network materially affect margin, alongside the additives and packaging the process needs.
| Raw Material | Role in Process | India Sourcing | % of OpEx |
|---|---|---|---|
| Surfactants & Actives | Core functional chemistry | Domestic and imports | 45–55% |
| Polymers & Silicones | Finishing and binders | Domestic and imports | 10–15% |
| Solvents & Additives | Carriers and adjusters | Domestic suppliers | 5–10% |
| Packaging & Consumables | Drums, carboys, filters | Domestic suppliers | 3–6% |
Because raw material is such a large and variable share of cost, sourcing strategy is the biggest lever on profitability. India has a growing domestic base of surfactants, polymers, and intermediates supplemented by imports, so supply is available, but prices can swing with petrochemical cycles, making reliable supplier relationships and sensible inventory important. Utilities are the other meaningful cost, so efficient steam, power, and cooling protect margins, since reactions and blending run on continuous heat and agitation. Packaging and consumables are smaller but critical, and consistent active quality from suppliers is essential, since a variable input directly shows up as inconsistent product on a customer's fabric.
Location, Land & Infrastructure
Choosing the best location for Textile Chemicals manufacturing plant setup significantly affects raw-material access, effluent-treatment capacity, and proximity to textile clusters. Being in a designated chemical zone, near supply and dyeing hubs, and with reliable utilities shapes site selection, alongside adequate land and the effluent and safety infrastructure a chemical process demands.
Best States for Textile Chemicals Plant Setup in India
| State | Why It Works | Key Advantage |
|---|---|---|
| Gujarat | India's chemical hub | Raw material and zones |
| Maharashtra | Chemical and textile base | Supply and demand |
| Tamil Nadu | Major textile cluster | Dyeing-house demand |
| Punjab | Textile processing base | Proximity to mills |
| Rajasthan | Growing chemical and textile | Land and demand |
| Telangana | Chemical industry base | Ecosystem and access |
The strongest locations combine reliable raw-material supply and utilities with proximity to textile clusters and effluent-treatment infrastructure. Gujarat and Maharashtra offer deep chemical ecosystems and industrial zones, while Tamil Nadu, Punjab, and Rajasthan add large dyeing and processing demand. Because chemical manufacturing is effluent- and safety-sensitive, being in a notified industrial or chemical zone with common effluent treatment, hazardous-waste handling, and emergency infrastructure should weigh heavily in the final choice, alongside land for reactors, storage, and utilities.
Infrastructure Requirements (Mid-Sized Plant)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Total Land Area | 3,000 – 15,000 sq. meters | Space for plant and storage |
| Reaction & Blending Block | Reactor and vessel layout | For batch processing |
| Raw Material Storage | Tank farm and warehouse | Safe chemical storage |
| Utilities Block | Boiler, chiller, and power | For heating and cooling |
| Effluent Treatment Plant | ETP with treatment capacity | Mandatory; effluent-sensitive |
| Quality Laboratory | QC and R&D lab | For batch and product testing |
| Safety & Fire Systems | Fire and emergency setup | For hazardous handling |
Infrastructure for a chemical unit centres on the reaction and blending block, utilities, effluent treatment, and a well-equipped laboratory, because output, cost, safety, and compliance depend on all of them. Effluent treatment and safety systems are especially important given how closely regulators scrutinize chemical plants, and a proper tank farm keeps raw materials safely stored and traceable. Planning the layout with room to add reactors or a second line later makes future expansion far cheaper than reconfiguring a constrained site, so scalable design pays off early.
Textile Chemicals Machinery and Equipment
The equipment set spans reaction, blending, and filling, and the line-up scales with capacity and whether the unit synthesises or formulates. Because product quality and safety depend on well-controlled processing, machinery must be corrosion-resistant and well instrumented. The core machinery, from raw-material charging through finished-product filling, is summarized below.
| Equipment | Function | Key Specification |
|---|---|---|
| Reactors (SS / Glass-lined) | Synthesise active chemistry | Corrosion-resistant, jacketed |
| Blending Vessels | Formulate finished products | With agitators and heating |
| Agitators & Mixers | Ensure uniform mixing | Speed and torque control |
| Boiler / Thermic Heater | Supply process heat | For reaction temperature |
| Chiller / Cooling | Control cooling | For temperature control |
| Storage Tanks | Hold raw material and product | Bulk storage capacity |
| Filtration System | Clarify products | Filter presses or cartridges |
| Filling Machine | Pack into drums | Semi or fully automatic |
| ETP Equipment | Treat effluent | For environmental compliance |
| Laboratory & QC Instruments | Test and develop products | Viscometer, pH, spectrophotometer |
Equipment selection should follow your product scope and capacity rather than the other way around. A formulation unit centres on blending vessels, storage, and filling, while a unit that synthesises actives needs reactors, better temperature control, and stronger safety and effluent systems. Utilities, effluent, and laboratory capability are central and easy to under-budget, because chemical manufacturing depends on reliable heating and cooling, compliant treatment, and rigorous testing to hold quality and stay within environmental norms.
Textile Chemicals Plant Setup Cost in India (CapEx & OpEx)
The tables below give you a breakdown of both the upfront capital investment and the ongoing operating costs, based on industry analysis of a mid-sized facility in India. The actual Textile Chemicals Manufacturing Plant Cost for your specific project will depend on your chosen location, capacity, product portfolio, and level of automation.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Reactors & Process Equipment | 30–40% | Reactors, vessels, and mixing |
| Building & Civil Works | 12–18% | Plant block and storage |
| Utilities & Power | 10–15% | Boiler, chiller, and power |
| Effluent & Safety Systems | 8–12% | ETP, safety, and fire systems |
| Laboratory & R&D Setup | 4–7% | QC and product development |
| Pre-operative & Misc. Costs | 4–7% | Engineering fees, DPR, and approvals |
| Working Capital | 12–18% | Raw material stock and receivables |
The CapEx profile is dominated by reactors and process equipment, with utilities, effluent, and safety systems significant because chemical manufacturing needs reliable heat, cooling, and compliant treatment. Working capital matters because raw material and actives must be bought and stocked ahead of production and sales. Under-provisioning effluent, safety, or working capital is a common and costly mistake, so all are modelled carefully in the Textile Chemicals Business Plan and Financial Model.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Raw Material & Actives | 50–60% | Largest cost; price varies with cycles |
| Utilities (Power & Steam) | 8–12% | Heating, cooling, and agitation |
| Labour & Manpower | 8–12% | Operators, chemists, and QC staff |
| Packaging & Consumables | 5–8% | Drums, carboys, and filters |
| Effluent & Compliance | 4–7% | Treatment and environmental norms |
| Maintenance & Overheads | 3–6% | Plant upkeep and factory costs |
With raw material and actives dominating operating cost, this is fundamentally a chemistry-and-formulation business, and margin depends on cheap, consistent inputs, efficient utilities, and high yield. Raw-material prices move with petrochemical and specialty cycles, so a financial model should track them closely and stress-test margins against input-cost swings, which are the biggest variable, while accounting for the steady demand that textile processing provides. Higher-value finishing and functional products, where formulation adds more value, are what lift the blended margin above commodity levels.
Financial Analysis and Profitability
Based on analysis of a mid-sized textile chemicals facility in India, the financial profile is attractive, supported by essential, growing demand and a maturing supplier base. Because raw material and formulation drive economics, the profitability of Textile Chemicals manufacturing business in India improves markedly with efficient sourcing, strong product development, high utilization, and a move toward higher-value chemistry.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 22–35% | Driven by raw material and product mix |
| Net Profit Margin | 10–18% | After depreciation and Indian corporate taxes |
| Payback Period | 3–5 Years | Faster with a specialty mix |
| IRR (Internal Rate of Return) | 20–30% | Higher for finishing and functional chemistry |
| Capacity Utilization (stable ops) | 70–85% | Batch flexibility suits varied demand |
| Break-even Capacity Utilization | 50–65% | Steady processing demand supports throughput |
Raw-material cost, product mix, and utilization are the factors that most determine outcomes, because a plant must run its reactors and vessels at good utilization to spread fixed costs, and its margin depends heavily on how much value the formulation adds. An operator with reliable inputs, strong formulations, and steady buyer demand can run comfortably above break-even, while one exposed to input-price swings or stuck in commodity chemistry will see thinner margins. This is why sourcing and product development are as central to the financial model as the machinery itself.
There are several ways to strengthen returns in the Indian context: securing competitively priced actives through strong supplier relationships, investing in R&D to develop differentiated and eco-compliant products, moving into finishing and functional chemistry, keeping plant utilization high, and controlling effluent and utilities efficiently. Reliable customer relationships and technical service further stabilize demand and pricing. Delivering consistent, compliant products with strong technical support also helps a unit build long-term supply arrangements with large processing houses, which smooths out the demand swings that hurt smaller, order-to-order suppliers.
Key Risks and Mitigation
The principal risks are raw-material price volatility, environmental compliance, and product-quality consistency. Input risk is mitigated by diversified suppliers and inventory planning; compliance risk is mitigated by robust effluent treatment, safety systems, and adherence to norms; and quality risk is mitigated by strong R&D, batch control, and testing. A manufacturer that treats sourcing, compliance, and quality as core priorities is far better placed to sustain the returns the model promises.
Licenses and Approvals for Textile Chemicals Plant in India
The approvals for this business are important, because chemical manufacturing is effluent-generating, involves hazardous materials, and is closely regulated for safety and environment. Manufacturers planning to establish a Textile Chemicals Manufacturing Plant generally need to obtain the following before commencing operations, and pollution-control and safety approvals are especially central:
- Pollution Control Consents: Consent to Establish and Consent to Operate from the State Pollution Control Board (CTE and CTO), central for a chemical process.
- Business & Tax Registration: Company or firm incorporation, GST registration, and Udyam (MSME) registration.
- Factory Licence: Factory establishment and operation approval under the Occupational Safety, Health and Working Conditions Code, 2020.
- Hazardous Chemical Approvals: Hazardous-waste authorization and compliance with chemical-handling and storage rules.
- PESO / Explosives Licence: Approvals for solvent and flammable-material storage where applicable.
- Fire Safety NOC: Fire safety and emergency-preparedness compliance for the facility.
- Labour & Export Registrations: EPF and ESI registrations, and IEC for units planning to export.
For a chemical unit, pollution-control consents, hazardous-material approvals, and safety compliance are the critical items and should be pursued early, in parallel with construction, because a chemical plant cannot operate without them. Engaging a consultant familiar with environmental, safety, and chemical regulations is usually worth the cost, since a delayed consent can idle a completed plant. Sequencing approvals well, alongside raw-material and customer development, can shave months off the project timeline.
Note: The exact approvals, registrations, licences, and compliance requirements may vary depending on factors such as plant location, capacity, product chemistry, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India Textile Chemicals Industry
A few structural trends give useful context for investors considering entry into this industry:
- Sustainable and eco chemistry: Buyer and regulatory demand for ZDHC-compliant, eco-friendly chemistry is reshaping the product mix toward green formulations.
- Import substitution and China-plus-one: A push to localize specialty chemistry and diversify supply chains is drawing production into India.
- Technical-textile growth: Rising demand for functional and performance fabrics is expanding the market for specialty finishes.
The common thread is a market growing with textile output and shifting toward sustainable, higher-value chemistry, with compliance and R&D increasingly important. For a new entrant, the implication is clear: the window to establish compliant, capable capacity and build processing-house relationships is open, and those who build sourcing security, product development, and compliance into their model from the start will be best placed as demand grows through the decade.
How a Textile Chemicals Project Report and DPR Helps Investors
A comprehensive Textile Chemicals Project Report, prepared as a Detailed Project Report (DPR), provides a structured roadmap for establishing the facility by evaluating every aspect of the venture, from market demand and product mix to machinery selection, plant layout, and economics. It helps investors determine the optimal capacity and portfolio, estimate capital expenditure (CapEx) and operating expenditure (OpEx), assess profitability, and identify potential risks before implementation.
The report also brings together a Textile Chemicals Business Plan with revenue forecasts, production costs, cash flow analysis, break-even assessment, return on investment (ROI), and payback period calculations, supported by a detailed Textile Chemicals Financial Model. These insights enable investors, lenders, and stakeholders to make informed decisions and evaluate the long-term viability of the project. Many investors engage a Textile Chemicals Business Plan Consultant in India or a Textile Chemicals Manufacturing Consultant in India to prepare and validate these documents.
For a chemical project specifically, a strong DPR also clarifies the sourcing strategy, the product and R&D focus, and the environmental and safety pathway, which are the factors most likely to determine success. By modelling utilization against realistic demand and testing margins against input-cost swings, the report turns a competitive but essential-input opportunity into an executable plan that lenders and partners can trust. It also maps the phased scale-up, from an initial set of reactors and vessels to full capacity, so investors can see how the unit grows and when each tranche of funding is needed.
Frequently Asked Questions
How to start a Textile Chemicals plant in India?
Begin by choosing your product portfolio and capacity, then prepare a feasibility report and DPR, secure land in a chemical zone near supply and textile clusters, arrange reactors or blending equipment, tie up raw-material suppliers and buyers, and obtain pollution-control, safety, and factory approvals. A detailed project report maps each step for your target setup.
What is the Textile Chemicals Plant Cost in India?
It typically ranges from INR 5 crore to INR 50 crore depending on capacity, product scope, and whether you synthesise or formulate, and the wider Textile Chemicals Investment Cost is driven by process equipment and working capital. Reactors, utilities, and raw-material stock are the largest components.
What is the Textile Chemicals Process?
The process runs from raw-material intake and charging, through reaction or blending under controlled temperature and agitation, pH and viscosity adjustment, and quality testing, to filtration, storage, filling, and dispatch, with batch-by-batch quality control throughout.
What machinery is required for a textile chemicals plant?
Key equipment includes reactors or blending vessels with agitators, heating and cooling systems, storage tanks, a filtration system, filling machines, effluent-treatment equipment, and a well-equipped laboratory with instruments such as a viscometer, pH meter, and spectrophotometer.
What is the best location for Textile Chemicals plant setup?
The ideal site is a notified chemical zone combining reliable raw-material supply, utilities, and effluent infrastructure with proximity to textile clusters. Gujarat, Maharashtra, Tamil Nadu, Punjab, and Rajasthan are leading choices.
What is the ROI of Textile Chemicals business in India?
It is attractive, with a typical 10 to 18% net profit margin and a 20 to 30% IRR, and a 3 to 5 year payback at healthy utilization. Returns improve with efficient sourcing, strong product development, higher-value finishing chemistry, and high utilization, though margins track raw-material prices.
How do I get a project report or feasibility report for a textile chemicals plant?
A Textile Chemicals Project Report and Textile Chemicals Feasibility Report cover the full plant setup and financials. Many investors engage a Textile Chemicals Plant Project Report Consultant in India or a Textile Chemicals Manufacturing Feasibility Study Consultant to prepare and validate them.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Setting up a Metal Fabrication Plant in India is a high-demand, infrastructure-driven venture, powered by the country's construction boom, expanding capital-goods sector, and the Make in India push toward domestic engineering.
Setting up an HDPE Pipe Manufacturing Plant in India is a high-demand, infrastructure-linked venture, powered by the country's massive investment in water supply, irrigation, gas distribution, and sanitation.
India's ethanol industry has moved from a sugar by-product business to a pillar of national energy security. According to IMARC Group, the industry was valued at USD 3.43 Billion in 2025, rose to USD 4.14 Billion in 2026, and is projected to reach USD 11.78 Billion by 2034, growing at a CAGR of 13.95% (2026–2034).
Setting up a Tyre Pyrolysis Plant in India is a profitable, environmentally valuable venture, driven by the country's mounting waste-tyre problem, circular-economy policy, and demand for alternative fuels and recovered carbon black. Tyre pyrolysis converts end-of-life tyres into pyrolysis oil, carbon black, steel wire, and combustible gas, turning a difficult waste stream into marketable products.
The lithium ion battery market in India reached USD 3.59 Billion in 2025 and is projected to reach USD 9.79 Billion by 2034, growing at a CAGR of 11.78% (2026–2034).
Setting up a Bio-CNG Production Plant in India is a capital-intensive but high-potential venture, driven by the country's push for clean fuel, waste-to-energy policy, and energy security. Bio-CNG, also known as compressed biogas, is produced by purifying biogas generated from organic and agricultural waste into a high-methane fuel equivalent to conventional CNG.
Setting up a dicalcium phosphate manufacturing plant in India is a capital-intensive but high-potential venture. India’s combined strength as the world’s third-largest poultry producer, largest milk producer, and largest generic drug manufacturer creates one of the deepest and most diversified DCP demand bases globally. With domestic raw material availability and supportive government policies, the country offers a uniquely favourable environment for new and expanding DCP manufacturers.
The Australia Steel Industry is drawing renewed investor attention as government-backed decarbonization funding, sovereign manufacturing policy, and structural demand from construction and mining converge in a single market cycle.
Xanthan gum is a high molecular weight extracellular polysaccharide, which is produced by the fermentation of carbohydrates by the bacterium Xanthomonas campestris. It is a complex polysaccharide, chemically consisting of a cellulose backbone with trisaccharide chains, which impart it with remarkable rheological properties. It is highly soluble in water and has the ability to create high viscosity even at low concentrations.
A ball bearing is a type of mechanical rolling-element bearing that helps to support radial loads, as well as end loads, while reducing the friction between two surfaces that move. It consists of two rings, one outer and one inner, with balls that are made of steel or other materials, which lie between the two rings. In between the balls, there is also a cage that helps to space the balls evenly.
Urea is an organic chemical substance that contains a large proportion of nitrogen and thus ranks as one of the most crucial compounds containing the element. Urea is a white, crystalline solid with a very high solubility in water and a stable structure under confined storage conditions. Urea is produced through the reaction of ammonia and carbon dioxide. It is a very rich source of the element and is also portable. Since the element is an essential component for the development and growth of plants, it is greatly used in the agricultural sector as well as in a number of industrial processes.
Tyre pyrolysis refers to a thermal recycling process whereby waste tyres are transformed into recyclable materials using a process of pyrolysis. Pyrolysis refers to a process whereby tyres are heated in the absence of oxygen to produce various useful resources. When tyres are subjected to elevated temperatures in the absence of oxygen, the various polymers found in tyres are reduced to simpler components without undergoing the process of combustion.
The global packaging industry is undergoing a profound transformation, with barrier films emerging as one of the most crucial components enabling product integrity, extended shelf life, and improved sustainability. As consumer expectations shift toward freshness, safety, and environmental responsibility, the importance of advanced barrier solutions continues to rise. In this evolving scenario, the barrier films market size is gaining increased attention, driven by innovations that enhance material performance while supporting ecofriendly packaging strategies.
The Saudi Arabia ethanol market represents a critical segment within the Kingdom's evolving industrial landscape. As one of the world's leading energy producers, Saudi Arabia strategically diversifies its economic portfolio beyond traditional hydrocarbon dependence. Ethanol, a versatile alcohol compound with applications spanning pharmaceuticals, personal care, chemicals, and fuel blending, has emerged as an essential component in this transformation.
Tile adhesive manufacturing is the industrial process of producing a specialized adhesive for fixing tiles to a substrate of concrete, cement screed, plaster, drywall, or existing tiles. Tile adhesives are normally made from a combination of cement, polymers, fillers, and performance additives that improve bonding power, flexibility, water resistance, and setting times.
Toughened glass production is the industrial process of making safety glass that is much stronger and more resistant to impact than regular annealed glass. The production process involves heating flat glass to high temperatures and then rapidly cooling it, which causes compressive stresses on the surface and tensile stresses in the core.
As the nation pursues ambitious infrastructure goals and accelerates urban development initiatives, prefabricated construction and structural steel solutions have emerged as indispensable components of modern building practices.
Sulfuric acid is a highly corrosive, colorless to slightly viscous inorganic acid that consists of sulfur, oxygen, and hydrogen. It is one of the most widely used industrial chemicals in the world because of its strong acidic properties and high reactivity.
Sponge iron, also called direct reduced iron (DRI), is a metallic material produced through the solid-state reduction of iron ore without melting it. The oxygen in iron ore is removed through the action of reducing gases or solid carbon at a temperature below the melting point of iron. The product has a porous, sponge-like appearance, and this is why it is called sponge iron.
Sodium ferrocyanide is a chemical that is classified as an inorganic coordination compound, comprising sodium ions and the ferrocyanide complex. This chemical is typically denoted by the chemical formula Na4[Fe(CN)6]·10H2O. Although the chemical contains cyanide ions, it is stable and less toxic, as the cyanide ions are strongly bound to the iron ion.
SLES is an anionic surfactant that finds wide application due to its outstanding performance on cleansing, foaming, and emulsifying properties. It is prepared by the ethoxylation of lauryl alcohol, usually sourced from natural fats or oils, followed by sulphonation and neutralization. The process of ethoxylation differentiates SLES from SLS in that SLES shows better mildness and lower irritation while retaining strong detergency.
Sodium chloride is an inorganic chemical compound that consists of sodium and chlorine ions, known as common salt. Its chemical formula is NaCl, which often tends towards crystalline form. It can be easily taken out from seawater, rock salt deposits, or salt lakes. The chemical properties of this compound make it completely water-soluble, with a stable nature.
The Gulf Cooperation Council cement market stands at a critical juncture as regional economies accelerate infrastructure development and pursue ambitious economic diversification strategies. Cement consumption across the GCC nations continues to expand, driven by transformative megaprojects, rapid urbanization, and substantial government investment in construction infrastructure.
The Kingdom of Saudi Arabia is undergoing an unprecedented economic transformation, shifting its traditional reliance on hydrocarbon revenues toward a diverse, knowledge-based economy. Central to this monumental shift is the steel industry in Saudi Arabia, a sector that serves as a foundational pillar for virtually every national development project.
A silk reeling unit is a type of manufacturing plant where raw silk threads are obtained from the cocoons of silkworm moths and processed into raw silk yarn by weaving them into a continuous strand of raw silk.
PVC solvent cement is a specialized adhesive formulation used to create permanent joints between polyvinyl chloride (PVC) pipes, fittings, and components. Unlike standard adhesives that rely on surface bonding, solvent cement chemically fuses PVC materials together. It works by using a blend of solvents and resins that temporarily soften and dissolve the surfaces of the PVC components.
PVC (Polyvinyl Chloride) pipes are durable and versatile piping products made from a synthetic thermoplastic polymer known for its strength, chemical resistance, and longevity. These pipes are produced primarily through the extrusion process, which ensures consistent wall thickness and uniform mechanical properties. Available in both rigid and flexible forms, PVC pipes are designed to transport fluids, gases, or solids safely under controlled pressure and temperature conditions.
Plastic pyrolysis is a form of recycling plastic waste via a process referred to as thermochemical recycling. This process produces liquid fuels, gases, and solid wastes through thermal degradation under low or no oxygen. Unlike traditional recycling, plastic pyrolysis involves the breakdown of long polymer chains into smaller hydrocarbon molecules using heat, in most cases in the presence of catalysts.
Insulation tapes made of PVC are adhesive tapes produced through a process involving a polyvinyl chloride (PVC) carrier coated with an adhesive made of rubber or acrylic materials. These insulation tapes have applications in electrical installations to serve their intended purpose of insulation and protection against environmental damage for electrical components and cables.
Precipitated silica is a synthetic and amorphous silicon dioxide, which is prepared through a process of controlled chemical reaction between soluble silicates and mineral acids. Unlike regular silica, precipitated silica is manufactured to have desired particle sizes, surface area, and porosity in terms of its structure, determining its final end-use performance. Precipitated silica is a fine, white, and free-flowing powdered substance.
Plywood is an engineered wood product made by bonding multiple thin layers of wood veneer together with strong adhesives under heat and pressure. The veneers are oriented so that their grain directions are at right angles to each other in successive layers, a manufacturing technique that improves strength, stability in dimensions, and resistance to cracking or warping.
Plastic crates are a rigid and reusable construction with a production material that includes a thermoplastic such as high-density polyethylene (HDPE) and Polypropylene (PP). These crates have design features that ensure the efficient storage, transport, and handling of goods while having a strong load-bearing capacity and a longer life span.
The cement industry remains one of the most critical foundations of global development, shaping the built environment and enabling progress across residential, commercial, and industrial landscapes. As construction activity expands and infrastructure investment intensifies, the cement market size continues to evolve, supported by new material innovations, sustainability priorities, and smart manufacturing technologies.
The GCC ceramic tiles market has emerged as one of the most dynamic segments in the region's construction and building materials sector. Spanning countries including United Arab Emirates, Saudi Arabia, Kuwait, Oman, Qatar, and Bahrain, the market reflects the Gulf region's ambitious transformation from oil-dependent economies to diversified, modern nations.
Paints are liquids, semi-liquids, or powdered materials, usually having a high content of pigments, binders or resins, solvents or vehicles, or additives, intended for application onto substrates to create a continuous film after drying or curing. Paints work as materials after their application, possessing several functionalities, such as protecting the surface, adding color, or modifying functionalities. Paints contain several components, such as binders or resins, pigments, solvents or vehicles, or additives, each differing based on their functionalities. The binder or resin is mainly involved in providing strength or adhesive characteristics, while pigments are used to create colors or opaqueness.
Organic fertilizers refer to nutrient-value-adding materials that come from ecologically degradable sources like plant debris, animal manure, composted materials, bio-wastes, bone meal, and microbe organisms. Another key point of distinction between organic and synthetic fertilizers is that whereas synthetic fertilizers give quicker nutrient release through chemical reactions, nutrient release occurs via bacterial decomposition in the case of organic fertilizers.
Oleochemicals are chemicals obtained from natural fats and oils derived mainly from renewable plant-based feedstocks like palm oil, palm kernel oil, coconut oil, soybean oil, and other materials high in triglyceride content. These raw materials are transformed into fatty acids, fatty alcohols, glycerin, methyl esters, and other derivatives by means of hydrolysis, transesterification, hydrogenation, fractionation, and other techniques. They represent renewable, biodegradable, and environmentally friendly alternatives to chemicals made from petrochemical raw materials.
NdFeB magnets are a family of high-performance permanent magnets primarily made of an alloy of neodymium, iron, and boron. They are fabricated by the sintering or bonding processes, which create extremely high magnetic energy density and make them the most powerful commercial magnets. NdFeB magnets have the best coercivity, remanence, and effectiveness in compact forms that can generate strong magnetic fields in the smallest volume.
Mineral wool ceiling tiles consist of acoustic and thermal insulation panels fabricated from inorganic fibers, which originate mainly from molten basalt, slag, or other mineral-based raw materials. The fibers are spun and bonded together with resins, then compressed into rigid tiles that perform well in terms of sound absorption, fire resistance, and moisture tolerance. They are usually available in standard sizes for application in suspended ceiling systems in commercial, industrial, and institutional buildings.
Methanol, also known as methyl alcohol or wood alcohol, is a colorless liquid that is volatile and flammable with the chemical formula CH3OH. The simplest of the alcohols, it is produced mainly by the catalytic conversion process of natural gas, coal, or biomass into synthesis gas-a mixture of carbon monoxide and hydrogen-further followed by methanol synthesis under high pressure.
Lubricating oil is a specially formulated liquid substance that reduces friction, wear, and generation of heat between moving mechanical surfaces. It is usually made from refined mineral base oils, synthetic oils, or a mixture of both, supplemented with performance-improving additives such as anti-wear agents, detergents, dispersants, antioxidants, corrosion inhibitors, and viscosity improvers.
The Philippines passenger vehicles lubricants industry stands at a transformative juncture, driven by robust automotive sector expansion, technological innovation, and evolving consumer preferences toward high-performance products. As the Philippine economy demonstrates resilient growth and vehicle ownership continues to rise, the demand for premium automotive lubricants has accelerated significantly across the archipelago.
Hydrogen is the lightest and most abundant element in the universe, being a colorless, odorless, highly combustible gas. It does not usually occur free in nature but is produced from hydrogen-rich compounds like water, natural gas, biomass, or other hydrocarbons. Owing to its high energy content per unit mass and clean combustion (with the production of water vapor only), hydrogen is widely recognized as a versatile energy carrier. Depending on how hydrogen is produced, it is classified as grey, blue, or green and increasingly plays a significant role in clean energy systems, industrial processing, and developing low-carbon technologies.
HDPE pipes are thermoplastic piping systems made from high-strength polyethylene resin, which features excellent flexibility, high impact resistance, and strong chemical and corrosion resistance. HDPE pipes are produced by extruding molten polyethylene into a variety of diameters and pressure ratings. Their seamless structure, along with their low friction and resistance to internal pressure and external load, makes them ideal for the transport of fluids. HDPE pipes boast superior endurance, long service life, and leak-free performance, since it is possible to join them through heat fusion, thus creating monolithic, continuous pipelines that are suitable for buried, aboveground, or underwater installations.
Graphite is a crystalline form of pure carbon, where atoms are organized in layered hexagonal structures, reflecting exceptional lubricity, electrical conductivity, heat resistance, and a high degree of chemical stability. It comes in many forms: flake, amorphous, vein, and synthetic graphite-derived from petroleum coke or coal tar pitch. Because of this layered structure, the sheets slip easily, which gives graphite its characteristic softness and lubricity, while strong covalent bonding within the layers makes it thermally stable and conductive. The unique characteristics make graphite indispensable in uses such as steelmaking, refractories, batteries, electronics, and in high-performance industrial components.
The Japan urea industry stands as a critical pillar supporting multiple sectors of the nation's economy, from agricultural productivity to automotive emissions control. As a nitrogen-rich compound essential for modern farming practices, urea plays an indispensable role in ensuring food security for Japan's population while simultaneously addressing stringent environmental standards through its industrial applications.
The Japan industrial gases industry stands as a critical enabler of the nation's economic infrastructure, supporting diverse sectors including manufacturing, healthcare, electronics, semiconductors, steel production, and energy generation. Industrial gases such as oxygen, hydrogen, nitrogen, carbon dioxide, argon, and specialty gases serve as essential inputs across these industries, facilitating everything from metal fabrication and medical treatments to advanced semiconductor manufacturing.
A fire extinguisher is either a portable or fixed device that is designed to combat and suppress small fires by discharging a controlled substance, which cools the burning material, cuts off oxygen supply, or interrupts the chemical chain reaction sustaining combustion. It is among the most important items that comprise fire protection systems, finding wide applications in residential, commercial, industrial, and transport environments.
Fiberglass, also known as glass fiber, is a composite material manufactured by weaving, chopping, or layering minute strands of glass into strong yet lightweight and durable products. It is made by melting silica sand, limestone, soda ash, and other raw materials together at very high temperatures-around 1,700°C-through which molten glass is obtained. It is extruded through fine nozzles to create continuous filaments, then combined into mats, fabrics, or roving later on, according to use.
Engine oil is a specific lubricant that serves to reduce friction, wear, and heat in an internal combustion engine's moving parts, allowing the smooth operation of such engines. Besides lubrication, it accomplishes other very important tasks: cooling, cleaning, sealing, and protection against corrosion. The two major components of engine oil formulation are the base oil and additives. The base oils, mineral or petroleum-based, synthetic, and semi-synthetic, constitute approximately 70-90% of the formulation and provide the fluidity and viscosity for the best performance.
The Australia bioplastics industry is experiencing unprecedented growth, driven by intensifying consumer demand for sustainable alternatives and robust government sustainability initiatives.
Ferrous sulphate is an inorganic salt, composed of iron, sulfur, and oxygen, and is mainly known for its pale green or blue-green crystalline appearance. It exists in various hydrated forms, the most common being ferrous sulphate heptahydrate (FeSO4·7H2O), although it is also produced largely as a monohydrate and anhydrous variant, depending on the industrial needs. It is usually manufactured as a by-product of the pickling of steel using sulfuric acid, or it could be produced as a co-product from titanium dioxide pigment manufacture.
Bamboo plywood is an engineered wood product that is made by laminating thin strips or veneers of bamboo into multi-layered panels to create a stable, uniform sheet material combining the natural aesthetics of bamboo with the structural versatility of plywood. Unlike conventional plywood made from hardwood or softwood veneers, bamboo plywood most often uses strand-woven, horizontal, or vertical lamination patterns of bamboo culm that are bonded under heat and pressure with formaldehyde-free or low-emission adhesives.
Biomass pellets are a sustainable, carbon-neutral, and renewable source of energy made from organic materials such as forestry waste, agricultural residues, sawdust, wood chips, and other biomass feedstocks. Biomass pellets are small, cylindrical in shape, and usually between 6 and 12 millimeters in diameter and are utilized as a clean energy alternative to fossil fuels in power production, heating, and for industrial purposes.
Bioethanol is a biodegradable, renewable alcohol that is made by fermenting sugars from biomass resources like corn, sugarcane, wheat, cassava, and cellulosic materials like agricultural waste and forest residues. It is cleaner than gasoline from fossil fuels and provides valuable decreases in greenhouse gases and helps to move us toward sustainable energy systems. The process of production of bioethanol is mainly about the conversion of biomass carbohydrate to simple sugars by hydrolysis and subsequent fermentation by yeast or bacteria into ethanol.
Blue ammonia is one type of ammonia production that is meant to reduce carbon dioxide emissions. Traditional methods of ammonia production include sourcing hydrogen from natural gas, usually through steam methane reforming (SMR) or auto-thermal reforming (ATR) and then reacting this hydrogen with nitrogen (from air) through the Haber-Bosch process. The "blue" suffix indicates that the carbon dioxide waste product produced in the course of hydrogen synthesis is captured (through Carbon Capture, Utilization, and Storage / CCUS) and not released into the environment.
Biodiesel is a renewable and biodegradable fuel source mainly from vegetable oils, animal fats, or waste cooking oils, and can serve as a direct replacement or blend with traditional petroleum diesel. It is chemically constituted by fatty acid methyl esters (FAMEs), which are formed when triglycerides react with methanol or ethanol in the presence of a catalyst under transesterification.
Anhydrous Ferric Chloride, FeCl3, is a corrosive dark brown crystalline chemical that finds extensive application as a major industrial chemical in water treatment, metallurgy, electronic manufacturing, and chemical synthesis industries. It is produced by reacting chlorine gas with iron or ferrous chloride at elevated temperatures to form a high-purity, moisture-free product. In contrast to its hydrate, anhydrous ferric chloride is not aqueous and is mostly used in processes involving controlled levels of moisture, for example, etching circuits in electronics and as a catalyst in the synthesis of organics.
Ammonium Bicarbonate (NH4HCO3) is a white crystalline inorganic chemical used extensively in the fertilizer, food processing, pharmaceutical, and chemical industries. It is a salt that is produced by the combination of ammonia, carbon dioxide, and water and is renowned for decomposing at relatively low temperatures into ammonia, carbon dioxide, and water vapor. This characteristic makes it useful as a leavening agent for the food industry, especially in baked foods, cookies, and crackers, which produce a light and porous texture due to its presence.
Biodegradable plastic granules are eco-friendly polymer materials designed to decompose naturally through the action of microorganisms such as bacteria, fungi, and algae, reducing the environmental burden associated with conventional plastics. These granules are the fundamental raw materials used in the production of biodegradable products such as packaging films, agricultural mulch, carry bags, cutlery, and medical components.
Bioplastics are a category of materials that come entirely or partly from renewable biological resources like corn starch, sugarcane, vegetable oils, or cellulose, to be used as sustainable substitutes for traditional petroleum-based plastics. Bioplastics may be biodegradable, non-biodegradable, or compostable, depending on their chemical composition and manufacturing process.
Battery recycling is the collection, dismantling, and processing of used or end-of-life batteries to recover valuable materials and limit environmental threats. With the burgeoning exponential increase in electric vehicles (EV), renewable energy storage, and consumer electronics, the number of spent batteries has skyrocketed, necessitating recycling as a key component of the energy transition worldwide.
Binding wire is a low-cost, flexible steel wire, mainly utilized for tying, fastening, and bundling in applications of construction, industry, agriculture, and packaging. Usually produced from mild steel wire rod by successive cold-drawing, annealing and surface-finishing processes, binding wire comes in an assortment of gauges (typically 18–24 AWG / 1.0–1.6 mm) and in a few forms: soft/annealed plain wire, galvanized (zinc-coated) wire for corrosion-proofing, and polymer/PVC-coated wire for better handling and durability.
Aluminum anodizing is an electrochemical process that improves the surface characteristics of aluminum by creating a long-lasting, corrosion-resistant oxide coating on its surface. In contrast to coatings or paint applied to the outside surface, anodizing makes the outer surface of aluminum into a protective aluminum oxide coating that is bonded integrally to the metal and will last long and stay adherent.
Aluminum powder is a finely divided metallic aluminum with a wide range of applications in various industries because of its specific physical and chemical properties. It is manufactured by atomization, mechanical grinding, or flake milling of pure aluminium. The powder has high reactivity, low density, high thermal conductivity, and high reflectivity. Depending on the manufacturing technique, it can exhibit spherical, irregular, or flake-like morphologies, making it suitable for diverse applications.
Aluminum bottles are lightweight, strong, and recyclable packages manufactured mostly from high-purity aluminum that provides a sustainable and premium alternative to conventional plastic and glass packaging. Aluminum bottles integrate functionality with style and, therefore, are gaining popularity in industries like beverages, cosmetics, personal care, pharmaceuticals, and household products.
Aluminum ingots are standardized raw forms of aluminum that are produced by smelting and refining processes, which act as a basic raw material for downstream industries. The ingots are commonly prepared by refining bauxite ore to alumina through the Bayer process, followed by electrolytic reduction in smelters through the Hall-Héroult process. The molten aluminum thus produced is cast into ingot shape for transportation convenience, handling, and further processing.
Aluminum extrusion is a versatile metal forming process whereby aluminum billets are pushed through a shaped die to create long profiles with the same cross-section. Through this process, manufacturers can create intricate shapes that balance strength, lightweight characteristics, and beauty, making it a cornerstone of several industries.
Activated alumina balls are porous, granular, and spherical materials consisting of aluminum oxide (Al2O3). They possess a large surface area, high adsorbing capacity, and excellent resistance to thermal shock and abrasion. Manufactured by the controlled dehydroxylation of aluminum hydroxide, activated alumina balls are chemically inert, non-toxic, and possess excellent water and polar molecule affinity. Due to such features, they find extensive applications as desiccants, adsorbents, and catalysts. In industrial operations, they are useful for drying gases and liquids in processes, eliminating fluoride, arsenic, and selenium ions from water, and as a catalyst carrier in petrochemical refining applications.
Activated carbon or activated charcoal is a very porous form of carbon with an incredibly large surface area, usually anywhere from 500 to 1,500 m²/g. Manufactured by activating carbon-rich materials such as coconut shells, wood, coal, or peat, it is subjected to physical or chemical treatment to create its distinctive pore structure. The microporous structure enables activated carbon to efficiently absorb gases, vapors, and dissolved materials, which makes it a vital adsorbent in all industries.
Glass Fiber Reinforced Polymer (GFRP) rebar and mesh are composite materials developed to be used in place of the conventional steel reinforcement in concrete structures. They consist of continuous glass fibers dispersed within a polymeric resin matrix, most commonly epoxy, vinyl ester, or polyester. The synergy between the tensile strength of glass fiber and the corrosion inhibition properties of polymers produces reinforcement products that are light weight, corrosion-free, and extremely durable.
Phosphorus Pentasulfide (P2S5) is a yellow-green crystalline compound primarily produced through the controlled reaction of elemental phosphorus and sulfur. As a key phosphorus-based intermediate, it plays a critical role in the chemical industry, particularly in the manufacture of lubricant additives such as zinc dialkyldithiophosphate (ZDDP), agrochemicals, and battery electrolytes. Structurally, P2S5 consists of phosphorus and sulfur atoms bonded in a cage-like configuration, imparting high reactivity and compatibility with organic synthesis pathways. It is valued for its sulfur-donating properties, thermal stability, and role as a bridging compound in synthesizing more complex phosphorus-sulfur compounds.
Steel bolts and fasteners are integral mechanical components that provide secure connections across industrial, commercial, and household applications. Comprising primarily of carbon steel, alloy steel, or stainless steel, these fasteners are engineered to withstand significant mechanical loads, torque, and environmental exposure. Their key properties include high tensile strength, corrosion resistance, dimensional precision, and durability under cyclic stress. Manufacturing typically involves processes such as forging, machining, threading, and surface finishing to meet exacting industry standards.
Copper sulphate is an inorganic chemical made up of copper, sulfur, and oxygen that is best known for its crystalline blue color and varied uses. Most often found as copper sulphate pentahydrate (CuSO4·5H2O), it is prized for its water solubility, stability, and fungicidal activity. Primary characteristics are that it is a fungicide, herbicide, algicide, and electrolyte used in industrial applications. It also serves as a precursor for the manufacture of other compounds of copper and as a laboratory reagent.
Sebacic acid is a naturally occurring dicarboxylic acid, a long-chain organic compound with two carboxyl functional groups. It is mainly produced from castor oil through cracking and purification in a significant industrial process, as it is a valuable bio-based chemical with major industrial relevance. The white flaky or crystalline powder is cherished for its superior properties, such as high thermal stability, corrosion resistance, and the ability to form long-lasting polymers.
Aluminium conductors are electrical wires or cables whose current-carrying core is primarily made of aluminium (or its alloys), used for overhead transmission lines, distribution, AAC (All Aluminium Conductor), AAAC (All Aluminium Alloy Conductor), ACSR (Aluminium Conductor Steel Reinforced), etc. The material is lightweight, has relatively good electrical conductivity (lower than copper but acceptable for many applications), and is cost-effective per unit weight.
Steel rolling products, encompassing hot-rolled, cold-rolled, and coated steel sheets and coils, form the backbone of numerous industrial applications, from automotive manufacturing to construction and infrastructure. The cost of these products is influenced by a complex interplay of raw material prices, energy costs, labor, technological advancements, and logistical considerations.
Treatment of sewage is the procedure of eliminating contaminants from domestic or industrial wastewater to yield treated effluent that can be safely released into the environment or recycled for different purposes. Sewage contains organic matter, nutrients, suspended solids, microorganisms, and chemical pollutants and hence physical, chemical, and biological processes must be utilized for purification.
Green methanol is a renewable and sustainable form of methanol produced from non-fossil-based feedstocks such as biomass, municipal solid waste, biogas, or captured carbon dioxide combined with green hydrogen generated via electrolysis powered by renewable energy. Chemically, it is identical to conventional methanol (CH3OH), a simple alcohol with high energy density and versatile chemical properties.
Sodium hydrosulfide (NaHS) is an inorganic chemical mainly known for its good reducing nature and adaptability in uses in industry. It exists as pale yellow solid or liquid in aqueous solution with the smell of sulfur. It is chemically obtained by the partial neutralization of hydrogen sulfide (H2S) by sodium hydroxide (NaOH) to form a stable and water-soluble salt.
Recycled Polyethylene Terephthalate (rPET) is a thermoplastic polymer obtained from post-consumer and post-industrial PET waste, mainly plastic bottles and packaging materials. It is chemically the same as virgin PET, composed of polymerized units of terephthalic acid and ethylene glycol, but is made from a recycling process that minimizes dependence on fossil-based feedstocks. Major characteristics of rPET are high strength-to-weight ratio, chemical resistance, dimensional stability, and high recyclability.
Animal feed grade Di-calcium Phosphate (DCP) is a mineral feed supplement commonly applied in animal and poultry nutrition to fortify dietary calcium and phosphorus—two of the most important nutrients in maintaining animal health and production levels. Manufactured predominantly through the reaction of phosphate rock-based phosphoric acid with calcium carbonate or lime, feed-grade DCP is generally found as a white or off-white granular or powdered material.
Copper tubes are cylindrical hollow goods consisting mainly of purified copper, which are highly prized for their high thermal conductivity, corrosion resistance, ductility, and antimicrobial qualities. They are produced by processes like casting, extrusion, and drawing, which provide accurate dimensions and clean internal surfaces.
Automotive fabrics are specialized textile materials engineered for use in vehicle interiors, combining aesthetics, functionality, and durability. Unlike ordinary textiles, automotive fabrics must withstand prolonged wear, UV exposure, temperature variations, and continuous contact, while also contributing to passenger comfort and vehicle safety.
Aluminum sheets, cans, and foils are among the most common types of processed aluminum, serving industries from packaging and construction to transport and consumer products. Aluminum sheets are flat-rolled material manufactured in a range of thicknesses and grades, prized for light weight, corrosion resistance, and ability to be recycled, ideal for use in car body panels, building cladding, roofs, and kitchen appliances.
Synthetic graphite is a state-of-the-art carbon material developed through petroleum coke and coal tar pitch treatment at high temperatures, providing highly crystalline carbon materials of higher purity and uniformity than natural graphite. Synthetic graphite is produced in controlled industrial conditions unlike natural graphite, which is excavated.
Diammonium Phosphate (DAP) is among the most popular phosphorus fertilizers in the world due to its high concentration of nutrients and multiple uses in agriculture. It is manufactured by reacting ammonia with phosphoric acid, forming a compound that has about 18% nitrogen and 46% phosphorus pentoxide (P2O5). Such levels of nutrients make DAP an effective supply of critical macronutrients for plants, especially for root development, seed germination, and plant growth early on.
Australia's battery recycling market is charging ahead, with a value of USD 336 Million in 2024 and no signs of slowing down. Driven by the booming demand for cleaner, greener solutions—especially in the Australia battery energy market and electric vehicle (EV) sectors—the industry is expected to reach USD 612.55 Million by 2033. That’s a steady growth rate of 6.90% annually from 2025-2033.
Green ammonia is used to describe ammonia made from renewable energy systems like wind, solar, or hydropower through water electrolysis to obtain green hydrogen, then blended with nitrogen in the air through the Haber-Bosch process. Unlike traditional ammonia, which is derived from natural gas and produces enormous amounts of CO2, green ammonia is a carbon-free and sustainable alternative.
Hydrogen Peroxide (H2O2) is an all-purpose, eco-friendly chemical used extensively as an oxidizing, bleaching, and disinfectant agent in various industries. Hydrogen Peroxide is a clear, colorless liquid with high oxidizing power, breaking down into oxygen and water, and thus a clean alternative to several hazardous chemicals.
Biofertilizers are microbial products that contain living microbes, and they enhance plant growth through the improvement of nutrient availability in the soil microcosm. They may consist of useful microorganisms like Rhizobium, Azotobacter, Azospirillum, phosphate-solubilizing bacteria (PSB), and mycorrhizal fungi. These microorganisms form symbiotic or associative relations with plants and enhance nitrogen fixation, phosphorus solubilization, and the uptake of required nutrients.
Steel stands as one of the world’s most essential industrial materials, forming the backbone of modern infrastructure, manufacturing, and economic progress. As a critical material, its production and consumption directly influence global economic dynamics. The steel market has seen significant evolution, driven by innovations, demand from diverse sectors, and increasingly sustainable practices.
The global petrochemicals market is witnessing steady growth, supported by rising end-user consumption, industrial diversification, and infrastructure development across both developed and emerging economies.
Ethyl acetate is a volatile, colorless, flammable liquid having a characteristic sweet smell. It is primarily used as a solvent in various industrial and commercial applications. It finds primary production through esterification from ethanol and acetic acid.
Ammonium nitrate (NH4NO3) is a white solid that is widely used as a high-nitrogen fertilizer and as a component of industrial explosives. It is made by neutralization of ammonia with nitric acid and is very soluble in water, making it useful for its efficiency in providing nitrogen to plants.
Ceramic tiles are durable, versatile, and cost-effective building materials made from natural clay, sand, and water, which are shaped, glazed, and kiln-fired at high temperatures. Known for their aesthetic appeal, resistance to moisture, and ease of maintenance, ceramic tiles are widely used in flooring, walls, kitchen backsplashes, and bathrooms across residential, commercial, and industrial spaces.
Diethylenetriamine (DETA) is a colorless, hygroscopic organic chemical compound of the ethyleneamine group having the chemical formula HN(CH2CH2NH2)2. It is a triamine that contains two primary amine groups and one secondary amine group, thus imparting to it a highly reactive molecular structure to be used in a number of industrial processes.
Calcium Chloride Anhydrous (CaCl2) is an off-white, hygroscopic inorganic substance commonly utilized due to its high desiccating and exothermic properties. The anhydrous form, as opposed to its hydrated counterparts, has no water molecules within it, thus making it very effective to use in moisture control processes.
Explore a step-by-step guide to setting up a unsaturated polyester resin production plant including planning, machinery, raw materials, costs & demand drivers.
Explore the growth, trends, and innovations driving the global bio-lubricant market toward a sustainable future.
Medium Density Fibreboard (MDF) is an engineered wood product created by dissolving hardwood or softwood residues into wood fibers, blending them with wax and resin binders, and molding them into panels under the pressure of high temperature. MDF is renowned for its even density, smooth surface, and easy machinability and is used extensively in cabinetry, flooring, furniture, and interior decoration because of its relative cheapness and adaptability as compared to plywood and solid wood.
Lanthanum oxide (La2O3) is a white, odorless, and extremely stable rare earth compound obtained mainly from monazite and bastnäsite ores. It is essential for a vast array of industrial uses such as the manufacture of optical lenses, ceramics, phosphors, and battery electrodes. Lanthanum oxide is also used extensively as a catalyst in petroleum refining processes, particularly in fluid catalytic cracking (FCC) operations. Due to its exceptional electrical, optical, and catalytic properties, La2O3 is an important material for advanced technologies like electric vehicles (EVs), smart electronics, and renewable energy devices.
Silica sand is a pure quartz-based material used extensively by many industries. It is known for its durability, chemical inertness, and resistance to heat, and it is an important raw material in glass production, construction, foundries, electronics, and hydraulic fracturing (fracking). Increasing demand for high-purity silica in semiconductors, solar panels, and filters is fueling market growth. With more infrastructure development and development in silica processing, the applications keep expanding, and it is becoming an essential industrial commodity worldwide.
Stone paper is an innovative, eco-friendly material gaining traction across various industries due to its durability, sustainability, and water resistance. Made primarily from calcium carbonate and resin, it offers a tree-free alternative to traditional paper, reducing deforestation and water consumption. Its tear-resistant and smooth texture makes it ideal for printing, packaging, and stationery applications. Additionally, stone paper is recyclable, photodegradable, and highly resistant to moisture, making it suitable for outdoor and high-humidity environments. With growing environmental concerns and demand for sustainable packaging and printing solutions, stone paper is emerging as a key player in the global paper industry, attracting interest from publishers, packaging manufacturers, and eco-conscious brands.
Nitrile gloves are synthetic rubber gloves that are extensively used in the medical, industrial, and food industries because of their strength, resistance to chemicals, and hypoallergenic nature. They are ideal for people with allergies since they are latex-free, as opposed to latex gloves. They are more flexible, puncture-resistant, and resistant to infection and chemicals. The demand for nitrile gloves in manufacturing, healthcare, and laboratory environments is increasing because of stringent safety regulations and increasing hygiene consciousness, which is driving the worldwide market growth.
Acetic acid (CH3COOH) is a clear, colorless liquid organic compound with a sour taste and a pungent odor. It is produced by the carbonylation of methanol and is also manufactured via bacterial fermentation. Acetic acid is extensively employed in the manufacturing of vinyl acetate monomer (VAM), purified terephthalic acid (PTA), acetic anhydride, and ester solvents, among others. It provides solvent effectiveness, chemically useful to use in syntheses, as well as utilization in the fabrication of polymers and resins.
Calcium bromide (CaBr2) is an inorganic compound commonly used in drilling fluids for oil and gas exploration, as well as in pharmaceutical and photographic applications. It is a white, crystalline solid or solution that dissolves very easily and is used as a clear, dense brine in well drilling operations. Calcium bromide is prized for its capacity to manage pressure and avoid well blowouts due to its exceptional thermal and chemical stability. The growing energy industry and improvements in drilling technology are the main drivers of its demand.
Laminated veneer lumber (LVL) is one of the most popular engineered wood products, which is manufactured from sliced and peeled thin wood veneers. LVL is a light material used for construction, which is utilized in public structures, industrial warehouses, product parts, large, prefabricated buildings, as well as designed wooden homes. This can be attributed to its strength, uniformity, high strength, and dimensional accuracy. Apart from this, it is utilized for structural framing in residential and commercial building work, including lintels, joists, beams, purlins, scaffold boards, concrete formwork, and truss chords.
Cross-laminated timber (CLT), an engineered wood product, is renowned for its durability, strength, and adaptability in contemporary building. CLT provides a lightweight yet strong substitute for steel and concrete in structures with sustainable engineering. Its layered structure adds to its integrity and makes it suitable for building anything from residential to commercial to high-rise buildings. Besides being aesthetically pleasing for eco-friendly building projects, CLT has very good fire resistance, thermal performance, and ease of installation. CLT changes the architectural sphere and instigates the development of new concepts for urban environments and shaping the future of sustainable construction.
Copper wire is a versatile, flexible, and highly conductive electrical wire used extensively in power transmission, telecommunications, and electronics. Fabricated from pure copper, copper wire has good thermal and electrical conductivity, resistance to corrosion, and ease of processing. Copper wire plays a critical role in construction, automotive, and consumer electronics industries. With the increased demand for effective power distribution and advancing technology, the copper wire market keeps growing because of urbanization, electrification, and growth in infrastructure development globally.
Aluminum wire rods are critical industrial products renowned for their high conductivity, strength, and versatility. They are cylindrical metal rods that are the backbone of electrical transmission and distribution systems and play a fundamental role in power infrastructure, building construction, and manufacturing. Due to their good conductivity and low weight, they are a top choice for cable production, overhead power lines, and electrical wires. Outside of electrical uses, aluminum wire rods find extensive application in the automotive, aerospace, and industrial industries, where their corrosion resistance and recyclability play important roles in sustainability initiatives.
N-Methyl Aniline (NMA) is an organic chemical compound widely used as an intermediate in various industrial applications. It plays a crucial role in the production of dyes, agrochemicals, pharmaceuticals and fuel additives. As a key component in high-octane fuel formulations NMA enhances combustion efficiency and reduces engine knocking making it valuable in the automotive and petroleum industries. Its use in the synthesis of specialty chemicals and pigments further expands its industrial significance.
Ammonium perchlorate is a crystalline, white inorganic substance that finds principal application as an energetic oxidizer in solid rocket propellants, explosives, and pyrotechnics. Its release of oxygen when subjected to heat gives it a fundamental role in different industrial and technological processes. Aside from its primary application in propulsion systems, it is also used in pyrotechnic devices to generate controlled, vibrant flames and brilliant effects, especially in aerospace displays and enormous entertainment productions.
Potassium sulfate (K2SO4) is an inorganic compound widely used as a specialty fertilizer, providing essential potassium and sulfur nutrients to crops. Its low salt index makes it the preferred crop for crops that are sensitive to chloride, like fruits, vegetables, and tobacco. Potassium sulphate is also used in pharmaceutical and glass manufacturing processes, among other industrial processes. It is the perfect choice for contemporary agricultural methods because of its high solubility and compatibility with irrigation systems, which promote plant development, yield enhancement, and soil health maintenance.
Battery electrolyte is a key element of energy storage, facilitating the flow of ions between electrodes to drive devices effectively. It is an important factor in lithium-ion, solid-state, and future batteries, influencing performance, safety, and durability. In electric vehicles, renewable energy storage systems, and consumer devices, development in electrolyte technology targets sustainability, improved conductivity, and heat resistance for unlocking the future of clean energy technologies.
Cobalt acetate is an inorganic substance that is frequently utilised in chemical synthesis as a precursor, dye mordant, and catalyst. This crystalline solid has a reddish-purple appearance and is very soluble in organic solvents and water. In addition to being widely used in the manufacture of paints, inks, and adhesives, it is also an essential component of polyester and a catalyst in oxidation processes. It is a crucial component in many industries, with industrial uses driving its demand, especially in petrochemicals, textiles, and battery technology.
Transformer oil, sometimes referred to as insulating oil, is essential to electrical transformer operation. Its main functions are to cool and insulate the internal parts. By acting as a dielectric medium, the oil prolongs the transformer's lifespan and improves overall performance by preventing electrical discharges between various components. It moves around inside the transformer, assisting in the dissipation of heat produced during the conversion of energy. Although there are synthetic and bio-based substitutes, refined mineral oil is usually the source of it. Moisture, impurities, or the disintegration of the oil's chemical structure can all cause its quality to decline over time. It must be tested and maintained on a regular basis to stay effective.
Silica gel is obtained from silica dioxide a naturally occurring compound in sand and comprises fine particles that can soak quantity of water. It is a drying agent that is frequently packaged in tiny paper or cloth packets as tiny, transparent beads or crystals of clear rock. These packets are frequently included with business goods to guard against moisture-related damage. Food, clothing, and electronics are just a few of the many things that include silica gel packets. Although silica gel is typically non-toxic, it poses a choking hazard, particularly to young children.
Amorphous silicon dioxide (silica) particles dispersed in water are known as colloidal silica. In order to produce these amorphous silica particles, silica nuclei from silicate solutions are polymerised in an alkaline environment to create silica sols with a high surface area and a nanometre size. The surface of the silica nanoparticles is then charged, which causes the particles to reject one another and create a stable colloid, or dispersion. Although colloidal silica comes in a variety of grades, all of them are made up of silica particles that range in size from roughly 2 nm to 150 nm. The particles might exist as discrete particles or as slightly organised aggregates, and they can have a spherical or slightly irregular shape.
In a time characterized by environmental awareness and limited resources, sustainable manufacturing has become an essential priority for companies all over the world. Sustainable manufacturing is a model beyond conventional manufacturing practices, focusing on the production of goods in a manner that reduces harm to the environment, uses less energy and natural resources, and prioritizes the health and safety of workers, communities, and consumers.
Intravenous (IV) solutions represent a critical and ubiquitous component of modern healthcare, playing a fundamental role in patient care and treatment. These sterile, liquid formulations consist of a carefully balanced blend of fluids and electrolytes, administered directly into a patient's bloodstream. They are tailored to address a wide range of medical needs, from rehydration and medication delivery to nutritional support and blood transfusions.
Titanium dioxide (TiO 2) is a white, naturally being mineral extensively used as a pigment, UV blocker, and opacifier. A vital element of paints, coatings, plastics, cosmetics, and sunscreens, it's well- known for its exceptional opacity, high illumination, and superior light- scattering capabilities. Also, TiO 2 is essential for advanced operations like photocatalysis, food, and pharmaceuticals. Because of its non-toxic and chemical- resistant rates, it's a necessary element of numerous different sectors, performing in steady demand worldwide.
Yellow phosphorus, a chemical element with the symbol P and atomic number 15, is a fascinating and essential element in the periodic table. This highly reactive nonmetal is widely known for its distinctive yellow appearance and its crucial role in various industrial applications. Found in nature primarily as phosphates, yellow phosphorus is isolated through a complex process to ensure its purity and effectiveness. Its versatility allows it to be employed in the production of fertilizers, detergents, and even in the synthesis of organophosphorus compounds used in medicine and pesticides.
Xanthan gum is a food additive that is produced by fermenting simple sugar using bacteria. It quickly disperses and creates a viscous and stable solution when added to a liquid for providing a thickness or stabilizing effect to a product. It assists in improving the texture, flavour, consistency, appearance, and shelf life of a product. It aids in preventing food products from separating and allowing them to flow smoothly and can lower blood sugar levels among individuals. It also reduces cholesterol levels, slows digestion, supports weight loss management, and treats dry mouth problems.
Titanium sponge is a highly porous, lightweight form of titanium metal produced through the Kroll process. It is the major raw material in the production of titanium alloys in industrial, automotive, medical implant, and aerospace applications. For high-performance industries, titanium sponge is an indispensable component as it has a very high strength-to-weight ratio, is resistant to corrosion, and is biocompatible. It is prepared by reducing titanium tetrachloride (TiCl4) with magnesium, followed by purification and processing to produce titanium compounds that can be used.
Urea is a nitrogenous compound produced in living organisms as a byproduct of the metabolism of protein degradation. In industrial and agricultural use, urea is a synthetic compound produced on a large scale for use as a fertilizer. Urea is a critical source of nitrogen that helps to enhance plant growth and development. Its high content of nitrogen makes it popular in the agricultural sector and serves as a concentrated, readily available source of nitrogen for crops. Besides being a fertilizer, urea also has several industrial uses, such as the manufacture of adhesives and some resins, as well as plastics.
Active dry yeast is a dehydrated form of yeast commonly used in baking and fermentation. Its dormant yeast cells spring to life when they are rehydrated with warm water. In bread-making, brewing, and other fermentation operations, active dry yeast is frequently employed due to its extended shelf life and convenience of storing. It aids in flavour development and raises dough by generating carbon dioxide. It is a necessary component of both commercial and home baking due to its dependability and convenience.
Ethylene-vinyl alcohol, commonly referred to as EVOH, is an extraordinary polymer with outstanding properties that have revolutionized applications in packaging, industrial, and medical fields. The copolymer consists of alternating ethylene and vinyl alcohol monomer units, which result in the unique gas barrier property that makes EVOH a strong contender for food packaging applications.
Ethylene propylene diene monomer (EPDM) is an adaptable synthetic rubber with unique performance properties. It is a copolymer of ethylene, propylene, and diene monomers and is manufactured through suspension, solution polymerization, or gas-phase polymerization processes. It is commonly used in belts, window and door seals, tubing, roofing membrane, non-slip coatings, radiator, drain tubes, and trunk seals.
Ferrosilicon, an iron alloy made of silicon and iron, is a very versatile alloy that is used in many different industries, especially the steel and casting industries. Its composition can vary, with silicon content ranging from 15% to 90%, depending on the application and desired properties.
Polytetrafluoroethylene (PTFE) refers to a tough, waxy and non-flammable synthetic resin that consists of carbon and fluorine atoms. It is manufactured through the free-radical polymerization process of chloroform, fluorspar and hydrochloric acid. PTFE is usually used to give a non-stick coating to surfaces, especially cookware, such as pans and baking trays and industrial products.
Collagen in the connective tissues, bone, and skin of cows and pigs contains gelatin. A common method for creating this colourless, odourless animal protein is to boil ligaments, tendons, and skin in water. Its outstanding physical characteristics include low viscosity, dispersion stability, high affinity, and dispersibility.
Electrolytic manganese dioxide (EMD) is made by dissolving manganese dioxide in sulfuric acid and placing between two electrodes. Manganese dioxide, also referred to as Manganese (IV) oxide, is an inorganic compound that is commonly found in blackish or brown solid and is insoluble in water. EMD is a highly refined form of MnO2 designed to meet the specific electrical requirements of battery manufacturers.
Electrolytic manganese metal is a pure form of the metallic element manganese, Mn concentration ranges from 99.7% to 99.9%. It is termed "electrolytic" because the refining process involves electrolysis. In other words, a chemical reaction powered by an electric current. Heating the ore and applying chemical processes to remove most impurities is the first steps in the processing of manganese.
Ethanol is a renewable biofuel produced primarily from crops such as corn, sugarcane, and biomass. It is often added to fuel to lower carbon emissions and improve energy security. Additionally, ethanol is used in the beverage, chemical, and pharmaceutical sectors. Ethanol is becoming more popular as a cleaner substitute for fossil fuels due to the rising need for sustainable energy solutions, which is propelling improvements in biofuel technology and production efficiency.
Widely recognized for its superior mechanical, chemical, and thermal properties, unsaturated polyester resin (UPR) is a highly versatile thermosetting polymer utilized across multiple industries. UPR is created when unsaturated acids and glycols react mostly used in composites, coatings, and adhesives.
Sodium cyanide (NaCN) is a highly toxic, colorless crystalline compound with a faint almond-like odor. It is a water-soluble salt composed of sodium (Na+) and cyanide (CN-) ions, known for its versatile applications across various industrial sectors. Despite its hazardous nature, sodium cyanide is extensively used due to its unique properties and efficacy in specific processes.
Caustic soda is the common term for sodium hydroxide (NaOH), a versatile alkali widely used in industries such as chemicals, textiles, pulp and paper, detergents, and water treatment. Sodium hydroxide is known to have strong alkaline properties. It is employed in manufacturing processes such as saponification, pH regulation, and chemical synthesis, making it essential for diversified industrial applications.
Citric acid is a naturally occurring weak organic acid found in citrus fruits, widely used for its sour taste, preservative properties, and acidity regulation. Industrially, it is produced through the fermentation of sugars and is a key ingredient in the food and beverage industry, where it enhances flavor and preserves freshness. Additionally, it has applications in pharmaceuticals, cosmetics, and cleaning products due to its ability to stabilize ingredients and chelate metals.
Calcium stearate, a key chemical compound, holds significant importance across various industries due to its multifunctional properties. Comprising calcium and stearic acid, it serves as a versatile additive and processing aid. As a widely utilized stabilizer and lubricant in the manufacturing of plastics, rubber, and pharmaceuticals, calcium stearate plays a pivotal role in enhancing material properties and processing efficiency.
Calcium hypochlorite is a powerful chemical compound, widely used in many different applications and industries. This white solid, made up of calcium, oxygen, and chlorine, contains excellent chlorine content with a strong oxidation capability. Being an oxidizing agent that gives out chlorine when dissolved in water, it is in huge demand for the treatment, sanitation, and disinfection of water.
Nitrocellulose, also known as cellulose nitrate or guncotton, is a chemically modified form of cellulose known for its exceptional film-forming capabilities, strong adhesion, and biodegradability. It is widely used in applications such as wood coatings, printing inks, leather finishes, automotive paints, nail varnishes, and more.
The growth of the copper wire market is primarily driven by increased electricity demand, heightened investments in construction, expansion of electrical infrastructure, the rise of renewable energy, a shift toward electric vehicles in the automotive industry, and the growing adoption of electric appliances. The development of smart grids and investments in upgrading power transmission systems further boost global copper wire demand. Additionally, the telecom industry's use of copper in optic fiber cables and infrastructure development in emerging markets, especially in Asia Pacific and Latin America, are expected to sustain high demand for copper wire in the coming years.
Urea, also known as carbamide, is an organic compound with the formula CO(NH2)2. It is a highly versatile and widely used chemical, primarily known for its role in agriculture as a nitrogen fertilizer. Urea is available in various grades, including fertilizer grade, feed grade, and technical grade, and is used in a wide range of applications, such as nitrogenous fertilizers, stabilizing agents, keratolytic, and resins, among others. Key industries that utilize urea include agriculture, chemicals, automotive, and medical sectors.
Lithium-ion batteries are rechargeable power sources widely used in devices such as cell phones, laptops, and electric vehicles. These batteries store energy by transferring lithium ions between the anode and cathode electrodes, with the electrolyte facilitating this movement and generating free electrons at the anode. Key types of lithium-ion batteries include those with lithium cobalt oxide, lithium iron phosphate, lithium nickel manganese cobalt, and lithium manganese oxide. Lithium-ion batteries come in a range of capacities from 0 mAh to 6000 mAh. They offer several advantages, including a high energy-to-weight ratio, excellent charge retention, and generally longer lifespans with more charge/discharge cycles compared to other rechargeable batteries.
Brazil is renowned across the world for its enormous rainforests and agricultural resources. Over the recent years, the country has emerged as a major player in the global cellulose industry. As per IMARC estimates, the cellulose fiber market in Brazil was valued at US$ 740.4 Million in 2023. By 2032, the market is projected to reach US$ 1,379.9 Million, growing at a CAGR of 7.0% from 2024 till 2032. Strategic investments in the industry, along with favorable environmental conditions, are guiding a cellulose revolution in Brazil, which is likely to have profound implications for both regional and international markets.
Green chemistry refers to the practice of creating new chemicals, materials, and processes that are less toxic to human health and the environment. It comprises the utilization of renewable resources and reducing waste and energy consumption. Green chemicals are used in various applications such as industrial and chemical, food and beverages, automotive, packaging, construction, agriculture, personal care, and many others. Nowadays, different types of green chemicals are available in the market, including bio-alcohol (bioethanol, bio-butanol, bio-methanol, and many others), bio-organic acids (bio-lactic acid, bio-acetic acid, bio-citric acid, bio-adipic acid, bio-acrylic acid, bio-succinic acid, and others), biopolymers (poly-lactic acid, bio-polyethylene, and others), bio-ketones, bio-solvents, and many other organic acids.
Vanadium has been discovered in sediment samples collected from the Gulf of Khambhat, which opens into the Arabian Sea off Alang in Gujarat. This discovery is expected to enhance the production of steel and titanium in India and boost redox battery manufacturing. Vanadium is one of the most abundant transition metals and is typically found in various minerals, including vanadinite, patronite, and carnotite. It is a hard, ductile, and rare grey metal, often extracted as a byproduct while processing other metals such as iron and uranium.
Steel is a versatile and widely used alloy composed primarily of iron and carbon, with small amounts of other elements such as manganese, chromium, nickel, and others. It is a widely utilized material in construction, manufacturing, and various industries. Steel exhibits a range of desirable properties, including high tensile strength, durability, hardness, corrosion resistance, heat resistance, and the ability to be formed into different shapes. Carbon steel, alloy steel, stainless steel, and tool steel are the main types of steel. Steel is utilized in the manufacturing of various products, including ingots, semi-finished materials, hot-rolled sheets and coils, galvanized sheets, steel tubes and fittings, plates, wire rods, and many others. Its applications span various industries such as building and construction, electrical appliances, metal products, automotive, transportation, and mechanical equipment. The top five exporters of steel are China, Japan, South Korea, and Germany. Similarly, the major importers of steel include the United States, Germany, Italy, and Turkey.
Copper is an essential material in electrical wiring, electronics, and heating systems. It is also highly ductile and malleable, allowing it to be easily shaped and drawn into thin wires. Additionally, copper possesses antimicrobial properties, making it useful in medical and architectural applications. Its resistance to corrosion and its ability to form alloys with other metals further enhance its versatility across various industries.