Polylactic Acid Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
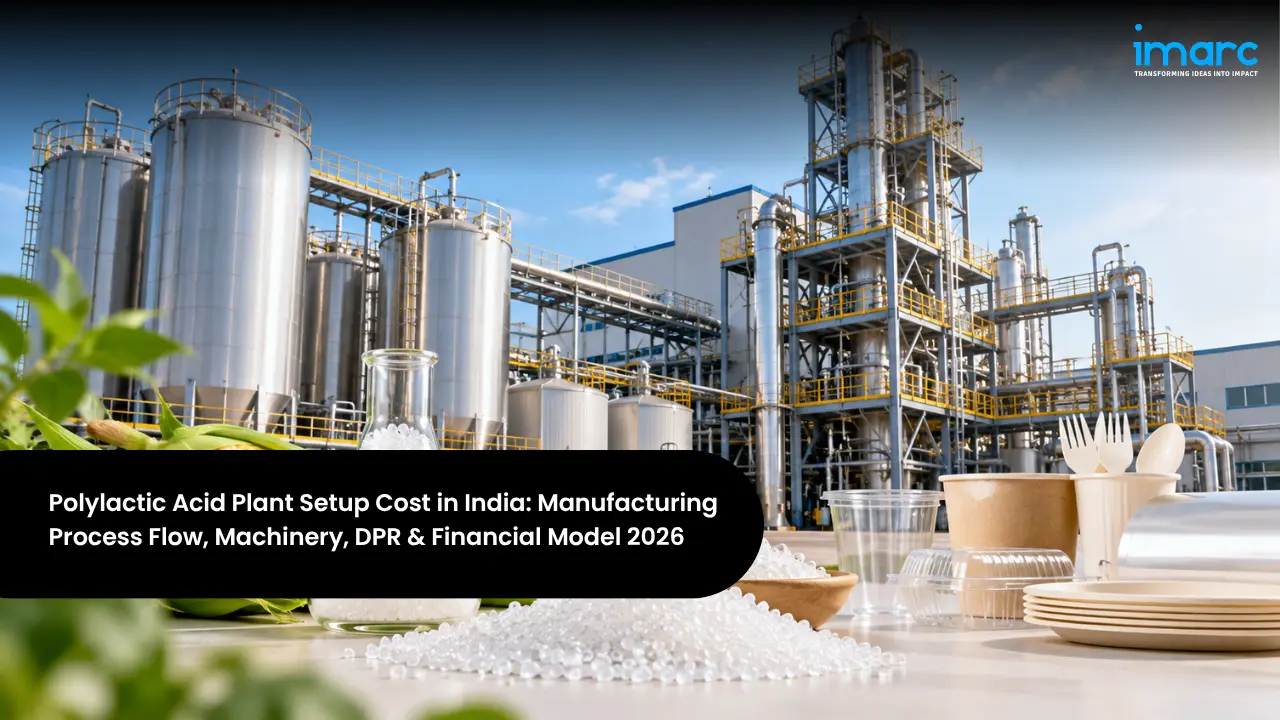
Polylactic acid (PLA) is the most widely produced bio-based and compostable plastic. It is made from sugars in crops such as sugarcane and maize, and it can replace conventional plastics in food containers, cups, cutlery, films, fibres, 3D printing filament, and medical devices. India's ban on many single-use plastics, rising demand for compostable packaging from food delivery and quick-commerce platforms, and the country's vast sugarcane base have turned PLA from an imported niche into a domestic manufacturing opportunity. India's first integrated sugarcane-to-PLA plant is nearing completion in Uttar Pradesh, and with the domestic bioplastics market projected to grow at close to 19% a year, Polylactic Acid Manufacturing Plant Setup in India is attracting serious attention from sugar companies, chemical groups, and packaging investors.
Investment depends above all on how far back into the value chain the plant goes and on its scale. A plant that buys lactic acid and converts it to lactide and PLA is less complex than an integrated facility that also ferments sugar into lactic acid, and both are capital-intensive because PLA economics improve sharply with size. The Polylactic Acid Manufacturing Plant Cost ranges from about INR 150–400 crore for a demonstration-scale plant of 1,000 to 5,000 tonnes a year to INR 1,000–2,000 crore for a lactic acid-based plant of 25,000 to 50,000 tonnes a year, and INR 2,800–3,500 crore for an integrated sugar-to-PLA plant of 75,000 to 1,00,000 tonnes a year. Raw materials make up 60 to 70% of operating cost and utilities 20 to 25%, so feedstock cost, conversion yield, and energy efficiency shape profitability. A well-run plant at scale typically earns a gross margin of 30 to 40% and a net margin of 15 to 25%.
This guide is written for investors exploring how to start a Polylactic Acid manufacturing plant in India. It focuses on the lactide and ring-opening polymerisation route used for commercial PLA, covering both integrated plants that ferment their own lactic acid and plants that buy it. It covers products and markets, the demand outlook, the production process flow, machinery and raw materials, location and infrastructure, a detailed cost and financial breakdown, approvals, and how a DPR and financial model turn all of this into a bankable plan.
India Market Snapshot
| Key Facts | Details |
|---|---|
| Global PLA Market (2025) | USD 1,298.0 Million |
| Projected Global Market (2034) | USD 4,155.4 Million, 13.39% CAGR |
| India Bioplastics Market (2025) | USD 546.6 Million |
| Projected India Bioplastics Market (2034) | USD 2,672.5 Million, 18.71% CAGR |
| Biodegradable Share of India Bioplastics (2025) | 56.8% |
| Indicative Total Investment | INR 150 Crore to 3,500 Crore |
The snapshot shows a global PLA market growing at double-digit rates and an Indian bioplastics market growing even faster from a smaller base, with biodegradable materials such as PLA already holding the larger share. Until now India has imported almost all of its PLA, so domestic plants can compete on logistics, supply reliability, and local feedstock. The wide investment range reflects a real choice between a demonstration plant, a mid-sized plant buying lactic acid, and a large integrated sugar-to-PLA complex. The sections below work through that choice.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Product Range | Packaging, film, fibre, injection moulding, and specialty PLA grades |
| Plant Capacity | 50,000 – 2,00,000 Tonnes per year (commercial scale) |
| Total Project Investment | INR 150 Crore (demonstration) to 2,800–3,500 Crore (integrated plant) |
| Payback Period | 5 – 8 Years |
| Net Profit Margin | 15 – 25% at scale |
| IRR | 14 – 20% |
| Preferred States | Uttar Pradesh, Maharashtra, Karnataka, Tamil Nadu, Gujarat, Bihar |
| Key Requirement | Low-cost sugar feedstock, proven technology, and offtake partners |
These ranges provide a realistic frame for early planning, but actual returns depend on sugar or lactic acid prices, technology performance and licensing terms, plant scale and utilisation, the premium customers pay over conventional plastics, enforcement of plastic regulations, and competition from imports. A site-specific Polylactic Acid Feasibility Report narrows each of these assumptions to your chosen route, grades, capacity, location, and customers.
Table of Contents
- What is Polylactic Acid Manufacturing?
- Why is Polylactic Acid Manufacturing Growing in India?
- Polylactic Acid Manufacturing Process Flow
- Raw Materials Required for Polylactic Acid Manufacturing
- Location, Land & Infrastructure
- Polylactic Acid Manufacturing Machinery and Equipment
- Polylactic Acid Manufacturing Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for Polylactic Acid Manufacturing in India
- Recent Developments in the India Polylactic Acid Manufacturing Industry
- How a Polylactic Acid Manufacturing Project Report and DPR Helps Investors
- Frequently Asked Questions
What is Polylactic Acid Manufacturing?
Polylactic acid is a thermoplastic polyester made from lactic acid, which is produced by fermenting sugars from sugarcane, maize, cassava, or other starch crops. In commercial production, lactic acid is first converted into a cyclic molecule called lactide, which is purified and then polymerised into long PLA chains. By controlling the mix of L- and D-forms of lactide and the molecular weight, producers make grades ranging from rigid, clear packaging plastics to fibres and heat-resistant moulding resins. PLA is industrially compostable, is processed on conventional plastic machinery, and has a much lower carbon footprint than many fossil-based plastics.
Commercially, PLA resin is sold to converters who turn it into finished products. A Polylactic Acid Manufacturing Plant can supply packaging and food-service converters, film and bag makers, textile and nonwoven producers, injection moulders of cutlery and consumer goods, 3D printing filament makers, medical device companies, agricultural film producers, and export markets. Buyers value consistent melt properties, purity, certifications for compostability and food contact, reliable supply, and technical support.
- Packaging & Food Service: Cups, containers, trays, clamshells, cutlery, and straws.
- Films & Bags: Compostable carry bags, liners, and mulch films, often blended with PBAT.
- Fibres & Nonwovens: Textiles, wipes, hygiene products, and tea bags.
- Specialty Uses: 3D printing filament and bioresorbable medical devices.
The Main PLA Grades and Applications
Choosing the grade mix is the most important commercial decision, because it determines lactide purity, polymerisation conditions, finishing, and customers:
| Grade | Description | Key Property | Primary Demand |
|---|---|---|---|
| Thermoforming & Sheet Grade | Rigid, clear PLA | Clarity and stiffness | Cups, trays, containers |
| Film & Bag Grade | PLA for blown and cast films | Flexibility in blends | Carry bags and liners |
| Fibre & Nonwoven Grade | Spinnable PLA | Fine, strong fibres | Textiles, wipes, hygiene |
| Injection Moulding Grade | High-flow or heat-resistant PLA | Mouldability | Cutlery and consumer goods |
| 3D Printing Grade | Filament-ready PLA | Easy printing | Filament makers |
| Medical Grade | High-purity PLLA and copolymers | Bioresorbable | Sutures and implants |
These choices shape the whole plant. Packaging, film, and moulding grades are the volume markets and can be served from a single polymerisation line with grade changes, while fibre grades need tighter control and medical grades require separate high-purity production and regulatory approvals. Most new entrants therefore begin with packaging and injection moulding grades for domestic converters, develop film and fibre grades with partners, and consider specialty grades once the core plant is running well.
Why is Polylactic Acid Manufacturing Growing in India?
Key Growth Drivers in the Indian Market
Demand is supported by plastic regulations, packaging growth, corporate sustainability goals, and India's agricultural feedstock base:
- Single-use plastic ban: Since July 2022, many single-use plastic items have been banned, pushing brands and converters towards compostable alternatives.
- Food delivery and quick commerce: Rapid growth in packaged and delivered food is raising demand for compostable containers, cutlery, and bags.
- Brand sustainability commitments: FMCG, food-service, and retail companies are setting targets for compostable and bio-based packaging.
- Tax and policy support: GST on biodegradable bags was cut from 18% to 5% in September 2025, and state policies support bio-based manufacturing.
- Local feedstock and import substitution: India imports most of its PLA today, while its sugarcane and maize output can support domestic production.
India-Specific Market Opportunity
| Segment | India Market Context | PLA Role |
|---|---|---|
| Food Service & Delivery | Fast-growing delivery platforms | Containers, cups, and cutlery |
| Carry Bags & Films | Plastic regulation enforcement | Film grades and PBAT blends |
| FMCG & Retail Packaging | Brand sustainability targets | Rigid and flexible packaging |
| Textiles & Hygiene | Large textile industry | Fibre and nonwoven grades |
The strongest opportunity for new entrants lies in supplying domestic converters who currently import PLA, especially in food service, carry bags, and packaging, where local supply, shorter lead times, and technical support are valuable. Producers that secure low-cost feedstock, partner with converters and brands on product development, and obtain recognised compostability and food-contact certifications will be best placed as demand scales.
Polylactic Acid Manufacturing Process Flow
Understanding the process helps you plan equipment, utilities, and where cost and quality are decided. Integrated production runs from feedstock preparation and fermentation through lactic acid purification, oligomerisation, lactide formation and purification, ring-opening polymerisation, devolatilisation, and pelletising to testing and dispatch. Lactide purity and polymerisation control determine product quality, while lactic acid yield and energy use are the largest controllable costs.
The Polylactic Acid Manufacturing Process Flow
The sequence below reflects an integrated sugar-to-PLA plant. A plant that buys lactic acid begins at the concentration and oligomerisation step, which reduces capital cost but adds dependence on lactic acid suppliers.
| Unit Operation | Key Activity |
|---|---|
| Feedstock Preparation | Sugar, cane juice, or starch converted to fermentable sugars |
| Fermentation | Bacteria convert sugars to lactic acid |
| Lactic Acid Recovery & Purification | Filtration, acidification, and purification |
| Concentration & Oligomerisation | Water removed, short-chain prepolymer formed |
| Lactide Formation | Prepolymer cracked to lactide under vacuum |
| Lactide Purification | Distillation or crystallisation to high purity |
| Ring-Opening Polymerisation | Lactide polymerised with a catalyst |
| Devolatilisation | Residual lactide removed and recycled |
| Pelletising, Crystallisation & Drying | Polymer cut, crystallised, and dried |
| Testing, Packing & Dispatch | Grade checks, bagging, and shipment |
Two factors decide profitability across this flow. The first is yield: sugar-to-lactic acid conversion, lactic acid recovery, and lactide yield compound through the process, so losses at each stage raise cost per tonne of PLA, and recycling of off-spec lactide and oligomers is essential. The second is energy, because purification, vacuum distillation, and evaporation consume large amounts of steam and power, so heat integration, efficient vacuum systems, and cogeneration with bagasse or biomass improve margins.
Raw Materials Required for Polylactic Acid Manufacturing
The main input for an integrated plant is fermentable sugar from sugarcane juice, raw sugar, or dextrose from maize or cassava starch, while non-integrated plants buy lactic acid. Other inputs are neutralising agents and acids used in fermentation and recovery, nutrients and enzymes, polymerisation catalysts such as tin octoate, stabilisers and additives, and packaging. Because sugar or lactic acid is by far the largest cost and its price follows agricultural markets and government sugar policy, secure feedstock supply is central to project planning.
| Raw Material | Role in Process | India Sourcing | % of OpEx |
|---|---|---|---|
| Sugar, Cane Juice, or Dextrose (or Lactic Acid) | Main feedstock | Sugar mills, starch makers, or imports | 50–58% |
| Neutralising Agents & Acids | Fermentation and recovery | Domestic chemical producers | 3–5% |
| Nutrients & Enzymes | Support fermentation | Domestic and imported | 1–2% |
| Catalysts & Stabilisers | Polymerisation and stability | Largely imported | 1–2% |
| Additives & Packaging | Grade modification and bagging | Domestic suppliers | 1–2% |
India is one of the world's largest producers of sugarcane and a major producer of maize, giving integrated plants strong feedstock options, especially when located within or beside sugar mills that can also supply steam and power from bagasse. Non-integrated plants depend on a small number of lactic acid suppliers, so long-term contracts or partnerships are important.
Location, Land & Infrastructure
Site selection for a PLA plant is shaped by access to low-cost sugar or starch feedstock, availability of steam and power, ideally from bagasse cogeneration, water for fermentation and cooling, proximity to packaging and textile converters, road and port connectivity, and state incentives for bio-based manufacturing.
Choosing the Best Location for Polylactic Acid Manufacturing Plant Setup
| State / Region | Why It Works | Key Advantage |
|---|---|---|
| Uttar Pradesh | India's largest sugarcane producer | Feedstock and policy support |
| Maharashtra | Large sugar industry and converters | Feedstock, technology, and markets |
| Karnataka | Sugarcane and maize production | Feedstock and southern markets |
| Tamil Nadu | Sugar mills and packaging hubs | Converters and ports |
| Gujarat | Chemical and packaging industries | Customers, ports, and utilities |
| Bihar & Punjab | Maize and starch processing | Starch-based feedstock |
Uttar Pradesh, Maharashtra, and Karnataka suit integrated plants beside sugar mills, combining feedstock, bagasse-based steam and power, and established agricultural supply chains. Tamil Nadu and Gujarat place plants close to packaging converters and ports, while Bihar and Punjab offer starch-based feedstock. The final choice should weigh feedstock cost, utility integration, water, customer proximity, and incentives.
Quality, Safety and Environmental Systems
Customers specify molecular weight, optical purity, melt flow, residual lactide, moisture, and colour, so a credible plant needs a laboratory with chromatography, rheology, and thermal analysis, batch traceability, and ISO 9001 quality systems. PLA sold for compostable products should be certified to standards such as IS/ISO 17088, EN 13432, or ASTM D6400, and food-contact grades must meet applicable food safety requirements, while converters of compostable plastics need CPCB certification under the Plastic Waste Management Rules. Fermentation needs strict hygiene, and the plant must manage steam, vacuum, and chemical handling safely, with zero liquid discharge and by-product management for gypsum or salts. An experienced Polylactic Acid Manufacturing Consultant in India can help plan technology selection, feedstock strategy, certifications, and plant design so the facility meets customer and regulatory requirements from the start.
Infrastructure Requirements (Integrated PLA Plant)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Total Land Area | 40 – 100 acres | Ideally beside a sugar mill |
| Fermentation Section | Fermenters, media prep, seed train | Hygienic design and cleaning systems |
| Purification & Lactide Section | Evaporators, distillation, crystallisers | Vacuum and heat integration |
| Polymerisation & Pelletising | Reactors, devolatilisers, pelletisers | Clean, dry handling |
| Steam & Power | Boiler or bagasse cogeneration | Large steam demand |
| Water & ZLD | Process water, cooling, ZLD plant | Recycling of process water |
| Warehousing | Dry storage for PLA pellets | Moisture-controlled storage |
Reliable, low-cost steam and power and a well-designed water and zero liquid discharge system are the most important infrastructure requirements, since purification and polymerisation are energy-intensive and fermentation uses large volumes of water.
Polylactic Acid Manufacturing Machinery and Equipment
The equipment set covers feedstock preparation, fermentation, lactic acid recovery, concentration, lactide production and purification, polymerisation, finishing, utilities, and testing. Fermentation and purification equipment, lactide reactors and columns, and polymerisation lines account for most of the machinery budget. The main items are summarised below.
| Equipment | Function | Key Specification |
|---|---|---|
| Feedstock Preparation System | Prepare fermentable sugars | Dissolution or starch hydrolysis |
| Fermenters & Seed Train | Produce lactic acid | Sterile, temperature-controlled |
| Filtration & Separation Units | Recover lactic acid | Membranes, filters, centrifuges |
| Evaporators & Purification Columns | Concentrate and purify | Multi-effect, energy-efficient |
| Oligomerisation Reactors | Form prepolymer | Vacuum and temperature control |
| Lactide Reactor & Distillation | Make and purify lactide | High-vacuum operation |
| Polymerisation Reactors | Ring-opening polymerisation | Continuous or batch reactors |
| Devolatiliser | Remove residual lactide | Recycles lactide to process |
| Pelletiser, Crystalliser & Dryer | Finish PLA pellets | Uniform, dry pellets |
| Utilities & ZLD Plant | Steam, cooling, vacuum, water recovery | Integrated energy design |
| Quality Laboratory | Test grades | GPC, rheometer, DSC |
Machinery should follow the route, capacity, and grade plan. Proven lactide and polymerisation technology from experienced licensors reduces start-up and quality risk, while integrated plants add fermentation and lactic acid purification that demand specialised bioprocess expertise.
Polylactic Acid Manufacturing Plant Setup Cost in India (CapEx & OpEx)
The tables below break down capital and operating costs for an integrated sugar-to-PLA plant in India. The final Polylactic Acid Investment Cost for your project will depend on the route, capacity, technology licensing terms, integration with sugar mill utilities, grade range, the level of automation, and location.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Plant & Machinery | 50–60% | Fermentation, purification, lactide, polymerisation |
| Utilities & ZLD Systems | 10–14% | Boiler, cooling, chillers, vacuum, ZLD |
| Civil Works & Buildings | 10–14% | Process buildings, warehouses, foundations |
| Technology Licensing & Engineering | 6–8% | Process license, basic and detailed engineering |
| Land & Site Development | 2–4% | Land, roads, and drainage |
| Pre-operative & Contingency | 4–6% | Commissioning, trials, buffer |
| Working Capital | 6–10% | Feedstock, PLA inventory, receivables |
Process equipment dominates the capital budget, and utilities, zero liquid discharge, and technology licensing are larger than in most polymer plants because of fermentation and purification. Working capital is moderate, though seasonal cane supply may require sugar stocks. Because PLA prices carry a premium over conventional plastics that depends on regulation and brand demand, a detailed Polylactic Acid Business Plan should model feedstock prices, yields, utility costs, grade mix, selling prices, and ramp-up together, so that funding can carry the plant through market development.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Raw Materials (sugar or lactic acid, chemicals) | 60–70% | Feedstock follows sugar markets |
| Utilities (steam, power, water) | 20–25% | Purification and vacuum distillation |
| Labour | 3–5% | Bioprocess and polymer specialists |
| Maintenance & Catalysts | 2–4% | Reactors, columns, and catalysts |
| Logistics & Selling | 2–3% | Technical sales and distribution |
| Certification & Overheads | 1–2% | Compostability and food-contact certification |
With feedstock and utilities making up most of the cost, margins depend on sugar or lactic acid prices, conversion yields, energy efficiency, and the price premium PLA commands. A good operating model tracks feedstock cost per tonne of PLA, yield at each stage, steam and power per tonne, grade mix, and realised prices, and tests how margins respond when sugar prices rise, when imports undercut prices, or when regulatory enforcement changes.
Financial Analysis and Profitability
Based on analysis of an integrated sugar-to-PLA plant, the financial profile is attractive at scale, supported by fast-growing demand and low-cost local feedstock, but projects are capital-intensive and returns depend on reaching high utilisation and building converter demand. The profitability of Polylactic Acid manufacturing business in India improves markedly with low-cost sugar feedstock, integration with sugar mill utilities, high conversion yields, proven technology, a balanced grade mix, and long-term supply agreements with converters and brands.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 30–40% | At scale with low-cost feedstock |
| Net Profit Margin | 15–25% | After depreciation and Indian corporate taxes |
| Payback Period | 5–8 Years | Capital-intensive projects |
| IRR (Internal Rate of Return) | 14–20% | Higher with utility integration |
| Capacity Utilization (stable ops) | 65–85% | Depends on market development |
| Break-even Capacity Utilization | 45–55% | High fixed costs |
Scale, feedstock, and market development decide where a plant lands within these ranges. Integrated plants beside sugar mills with low-cost feedstock and utilities can compete with imports and earn healthy margins, while smaller plants buying lactic acid face higher costs. Specialty grades for fibres, heat-resistant moulding, and medical uses command premiums over standard packaging grades.
Returns can be strengthened by integrating with sugar mills for feedstock, steam, and power, licensing proven technology, recycling lactide and off-spec material, developing grades with converters and brands, obtaining international certifications for exports, and expanding capacity in phases as demand grows.
Key Risks and Mitigation
The main risks are slower adoption if plastic rules are weakly enforced, competition from imported PLA and other bioplastics, sugar price and policy volatility, technology scale-up challenges, and the premium customers will pay. Demand risk is reduced through converter partnerships and offtake agreements; competition risk by scale and local service; feedstock risk by integration and diversification; technology risk by proven licensors and performance guarantees; and pricing risk by specialty grades. Promoters often work with a Polylactic Acid Business Plan Consultant in India to test these scenarios before committing capital.
Licenses and Approvals for Polylactic Acid Manufacturing in India
Approvals for a PLA plant combine chemical manufacturing clearances with bioprocess, utility, and product certification requirements. Promoters setting up a Polylactic Acid Manufacturing Plant in India generally need the following:
- Environmental Clearance: Environmental clearance under the EIA Notification as applicable for chemical and fermentation-based manufacturing.
- Pollution Control Consents: Consent to Establish and Consent to Operate from the State Pollution Control Board, with zero liquid discharge where required.
- Hazardous Waste Authorisation: Authorisation for spent catalysts, chemical residues, and other wastes.
- Boiler & Utility Approvals: Boiler registration under the Boilers Act, power connection, and water permissions.
- Product Certifications: Compostability certification to IS/ISO 17088 or equivalent, food-contact compliance, and support for converters obtaining CPCB certificates.
- Factory & Fire Approvals: Factory license under the Occupational Safety, Health and Working Conditions Code, 2020, building approval, and Fire NOC.
- Business & Trade Registrations: Company incorporation, GST, Udyam where applicable, IEC for imports and exports, and EPF and ESI registrations.
Environmental clearance and pollution consents are usually on the critical path, while product certifications and customer trials determine how quickly sales ramp up. Planning approvals, technology licensing, and converter partnerships in parallel with engineering shortens the time from investment decision to commercial production.
Note: The exact approvals, registrations, licenses, and certification requirements may vary depending on factors such as plant location, capacity, production route, product grades, export markets, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India Polylactic Acid Manufacturing Industry
Several recent developments give useful context for investors considering this market:
- First integrated plant: Balrampur Chini Mills is building an 80,000 tonne-a-year sugarcane-to-PLA plant at Kumbhi, Uttar Pradesh, with capex revised to INR 3,080 crore and commissioning targeted in the second half of FY2026-27.
- Market development: By April 2026, Balrampur reported engagement with over 100 customers and more than 30 ongoing trials, and it secured its first institutional PLA product order from the Lucknow Cantonment Board.
- Domestic technology: Praj Industries inaugurated a lactic acid and lactide demonstration plant at Jejuri in October 2024 and partnered with thyssenkrupp Uhde in April 2025 to offer end-to-end PLA technology.
- Tax relief: In September 2025, GST on biodegradable bags was cut from 18% to 5%, improving the competitiveness of compostable products.
The common thread is a domestic PLA industry moving from imports to local production, backed by sugar companies, technology providers, and supportive policy.
How a Polylactic Acid Manufacturing Project Report and DPR Helps Investors
A detailed DPR provides a structured roadmap for the venture, from market demand and route selection to plant design, machinery, feedstock and utility strategy, certifications, approvals, and economics. It helps investors decide the right route, capacity, and grade mix, estimate capital and operating expenditure, assess profitability, and identify risks before committing funds.
At its core is a detailed Polylactic Acid Financial Model covering revenue by grade and customer segment, feedstock and chemical costs, yields at each stage, steam and power costs, licensing fees, working capital, debt servicing, cash flows, break-even, return on investment, and payback under different price and demand scenarios. Banks and investors rely on this model to judge long-term viability, which is why many promoters appoint a Polylactic Acid Plant Project Report Consultant in India to prepare the report and validate its assumptions against current market data.
For a PLA project, a strong DPR also clarifies the feedstock and utility integration plan, the technology choice, the certification roadmap, and the market development and offtake strategy, which together are the factors most likely to decide success. By testing margins against feedstock price swings, slower adoption, and import competition, the report turns an emerging-material opportunity into a plan that lenders and partners can trust.
Frequently Asked Questions
What are the first steps to set up a polylactic acid manufacturing plant in India?
Start by choosing the route, capacity, and target grades, and secure feedstock and utility arrangements, ideally with a sugar mill. Then commission a feasibility study and DPR, select a technology licensor, sign converter and offtake partnerships, obtain environmental clearance and pollution consents, build the fermentation, lactide, and polymerisation sections, run trials, and obtain compostability and food-contact certifications before commercial sales.
How much does it cost to set up a polylactic acid manufacturing plant in India?
Investment ranges from about INR 150–400 crore for a demonstration-scale plant of 1,000 to 5,000 tonnes a year to INR 1,000–2,000 crore for a lactic acid-based plant of 25,000 to 50,000 tonnes a year, and INR 2,800–3,500 crore for an integrated sugar-to-PLA plant of 75,000 to 1,00,000 tonnes a year.
What are the main steps in polylactic acid manufacturing?
The flow runs from feedstock preparation through fermentation, lactic acid recovery and purification, concentration and oligomerisation, lactide formation and purification, ring-opening polymerisation, devolatilisation, pelletising, crystallisation and drying, and testing, packing, and dispatch.
Which machinery does a polylactic acid manufacturing plant need?
Key equipment includes feedstock preparation systems, fermenters and seed trains, filtration and separation units, evaporators and purification columns, oligomerisation reactors, lactide reactors and distillation, polymerisation reactors, devolatilisers, pelletisers, crystallisers and dryers, utilities and zero liquid discharge systems, and a quality laboratory.
What raw materials are used to make polylactic acid?
Integrated plants use sugar, cane juice, or starch-based dextrose, along with neutralising agents, acids, nutrients, and enzymes for fermentation. Non-integrated plants buy lactic acid. Both use polymerisation catalysts, stabilisers, additives, and packaging.
How profitable is polylactic acid manufacturing in India?
At scale, a well-run plant typically earns a 30 to 40% gross margin and a 15 to 25% net margin, with payback in about 5 to 8 years. Profitability depends on feedstock cost, yields, energy efficiency, utilisation, and the price premium for PLA.
Which approvals does a polylactic acid manufacturing plant need in India?
Typical approvals include environmental clearance as applicable, State Pollution Control Board consents, hazardous waste authorisation, boiler registration, power and water approvals, a factory license, Fire NOC, compostability and food-contact certifications, and GST, IEC, and labour registrations.
How do I get a feasibility study or DPR for a polylactic acid manufacturing project?
A detailed feasibility study and DPR covers market demand, route and technology selection, feedstock and utility strategy, plant design, certifications, approvals, and full financials. Investors usually engage a Polylactic Acid Manufacturing Feasibility Study Consultant with experience in bioprocess and polymer projects to prepare the report and validate it for lenders.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Construction and demolition (C&D) waste, the concrete, bricks, mortar, stone, tiles, and soil left behind when buildings, roads, and bridges are built, repaired, or pulled down, is one of the largest waste streams in India. Estimates range from 150 to more than 500 million tonnes a year, yet only a small share is recycled, while the rest is dumped on vacant land, riverbanks, and roadsides.
Cold-rolled coil is the precision end of the flat steel business. Car bodies, two-wheeler parts, refrigerators, washing machines, steel furniture, electrical panels, precision tubes, drums, and barrels all rely on its smooth surface, tight thickness tolerances, and excellent formability, and it is also the base for galvanised and colour-coated sheet used in roofing and appliances.
Biofuels are fuels made from crops, residues, and waste, and they have become a central part of India's plan to cut crude oil imports, support farmers, and reduce emissions.
Natural gas is the cleanest-burning fossil fuel and a vital feedstock for India's fertiliser, refining, petrochemical, power, ceramics, and glass industries, as well as the fuel behind city gas networks that supply CNG to vehicles and piped gas to homes.
Green methanol is methanol made from renewable sources rather than coal or natural gas, either by combining green hydrogen with captured carbon dioxide (e-methanol) or by converting biomass and biogas (bio-methanol).
Glass can be recycled endlessly without losing quality, and every tonne of clean cullet fed back into a furnace saves raw materials, energy, and carbon emissions.
GFRP composites combine strong glass fibres with a tough polymer resin to create products that are light, rust-proof, electrically non-conductive, and very strong for their weight.
India generated about 4.1 million tonnes of plastic waste in 2022-23, and the volume has been growing steadily with packaging, retail, and consumer goods. Plastic that is not recycled clogs drains, pollutes rivers and land, and is often burned in the open.
India's towns and cities generate around 1.6 lakh tonnes of municipal solid waste every day, and that figure is rising with urbanisation and consumption. For decades much of this waste was dumped on open land, creating more than 2,400 dumpsites holding an estimated 25 crore tonnes of legacy waste.
Hot-rolled coils are the workhorse of the flat steel industry. Pipes and tubes, LPG cylinders, boilers, truck chassis, wheels, railway wagons, ship plates, pre-engineered buildings, and cold-rolled and coated steel all start life as HR coil. India is the world's second-largest steel producer, with crude steel output of about 170 million tonnes in 2025-26, and flat products now make up more than half of domestic steel demand.
Copper is essential to electrification. It carries power through cables, transformers, motors, electric vehicles, solar and wind installations, data centres, and electronics, and it can be recycled again and again without losing its properties.
Charcoal is one of the oldest fuels and carbon materials, yet demand for it is expanding in new directions. Beyond its traditional use as a cooking fuel, charcoal is now an export product in the form of barbecue and shisha briquettes, a feedstock for activated carbon used in water and air purification, a renewable reductant for metallurgy, and, as biochar, a soil enhancer and carbon removal product.
Lithium hydroxide is one of the two key lithium chemicals that feed the battery industry. Battery-grade lithium hydroxide monohydrate is the preferred lithium source for high-nickel NMC and NCA cathodes used in long-range electric vehicles, while technical grades go into lubricating greases, ceramics, and specialty chemicals.
Sebacic acid is a bio-based, ten-carbon dicarboxylic acid made from castor oil. It is a key building block for high-performance nylons such as nylon 6,10 and 10,10, plasticizers such as dibutyl and dioctyl sebacate, synthetic lubricants and greases, corrosion inhibitors in engine coolants, polyurethanes, alkyd resins, adhesives, cosmetics, and pharmaceutical intermediates.
PET bottles are the most widely used rigid packaging format for beverages and many consumer products. They are light, clear, shatter-resistant, and fully recyclable.
Amino acids are the building blocks of protein and among the most important biochemicals in the modern economy. Lysine, methionine, threonine, and tryptophan are added to poultry, pig, and aquaculture feed to improve growth and reduce feed costs.
Aluminum extrusions are everywhere in modern life. They form windows, doors, facades, and partitions in buildings, solar panel frames and mounting structures, electric vehicle battery enclosures and body parts, rail coaches, electronics housings, furniture, and industrial machinery.
Lithium-ion cells are the energy building block of the electric and digital economy. Electric two-wheelers, cars, buses, grid-scale energy storage, telecom towers, inverters, power tools, laptops, and smartphones all depend on them.
Walk into almost any Indian home painted in the last decade and the walls are likely coated in emulsion paint. Water-based, low in odour, washable, and available in thousands of shades from a dealer's tinting machine, emulsions have steadily replaced distempers and solvent-based finishes as households upgrade and repaint.
Almost everything electrical in India runs on copper wire, from the house wiring hidden inside walls to the windings of fans, motors, and transformers, the harnesses in cars and electric vehicles, and the cables that connect solar parks to the grid.
Activated carbon is the quiet workhorse of purification. A single gram can hold hundreds of square metres of internal surface area, which is why it is used to clean drinking water, remove odours and pollutants from air, decolourise sugar, purify medicines, and recover gold from ore.
Setting up a Paint Manufacturing Plant in India is a formulation-and-dispersion venture with relatively accessible entry capital, powered by a booming housing and construction market, rising incomes, rapid urbanisation, and a steady shift from unorganised to branded products.
Setting up a NdFeB Magnet Manufacturing Plant in India is a strategically critical, technology-intensive venture positioned at the heart of the clean-energy and electric-mobility transition.
Setting up an algae based biofuel manufacturing plant in India is a next-generation bioenergy venture positioned at the intersection of the country's clean-energy transition, its biofuel-blending ambitions, and rising demand for sustainable aviation fuel.
Setting up an ethanol manufacturing plant in India is a fermentation-and-distillation venture riding one of the country's strongest policy tailwinds: the Ethanol Blending Programme and the drive toward higher petrol blending.
Look around any modern Indian building, car showroom, or kitchen and toughened glass is everywhere: glazed facades, shower cubicles, railings, office partitions, refrigerator shelves, gas stove tops, and car windows.
Setting up a Di-Ammonium Phosphate (DAP) Manufacturing Plant in India is a capital-intensive, strategically important venture tied to the country's food security and its push to reduce fertilizer import dependence.
Setting up a Biofertilizer Manufacturing Plant in India is a microbiology-and-blending venture with relatively accessible entry capital, powered by a strong national push toward natural and organic farming, rising soil-health awareness, growing demand for organically produced food and sustainable agricultural practices, and supportive government schemes.
Setting up a Citric Acid Manufacturing Plant in India is a fermentation-and-purification venture with strong import-substitution appeal, powered by heavy domestic demand across food and beverages, pharmaceuticals, detergents, and industrial cleaning.
Setting up a PVC Pipes Manufacturing Plant in India is an extrusion-and-conversion venture with relatively accessible entry capital, powered by a vast agriculture and irrigation base, a booming construction and plumbing market, and large government water-supply and sanitation programmes.
Nitrocellulose is one of those quiet workhorse materials that most people never see but use every day. It gives printing inks their fast drying, wood lacquers their gloss, and nail varnish its hard, bright finish.
Setting up a Precipitated Silica Manufacturing Plant in India is a specialty-chemical venture powered by a fast-growing tyre and rubber industry, rising demand for fuel-efficient green tyres, and steady use across oral care, food, agrochemicals, and coatings.
Setting up a Plywood Manufacturing Plant in India is a wood-panel venture with relatively accessible entry capital, powered by a booming housing and real-estate market, rising furniture and interior demand, growing incomes, and a structural shift from the unorganised to the organised, branded sector.
Setting up a Fiber Glass Manufacturing Plant in India is a capital-intensive, technology-led venture powered by booming construction, a fast-growing wind-energy sector, vehicle lightweighting, and rising demand for corrosion-resistant composites across pipes, tanks, and electrical applications.
Setting up a Copper Tube Manufacturing Plant in India is a metal-conversion venture powered by a booming air-conditioning and refrigeration market, expanding plumbing and construction, and steady demand from electrical, industrial, and medical-gas applications.
Setting up a Caustic Soda Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's large chemical, alumina, textile, and soap industries and the essential role of caustic soda as a basic building-block chemical.
Setting up a Sulfuric Acid Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's large fertilizer sector, expanding chemical industry, and the essential role of sulfuric acid as the world's most produced industrial chemical.
Setting up an Engine Oil Manufacturing Plant in India is a blending-driven, working-capital-intensive venture, powered by a vast and growing vehicle parc, expanding industrial machinery, and steady replacement demand for lubricants across automotive, industrial, and marine applications.
Setting up a Graphite Manufacturing Plant in India is a minerals-and-materials venture with strong strategic appeal, powered by the electric-vehicle and battery boom, steady demand from refractories, foundries, and lubricants, and a national push to build critical-mineral capacity.
Setting up a Titanium Dioxide Manufacturing Plant in India is a capital-intensive, high-value venture, powered by the country's booming paints and coatings industry, growing plastics and paper demand, and a strong opportunity to substitute large imports of this critical white pigment.
Setting up a Glass Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's construction boom, growing packaging needs, and rising demand from automotive, solar, and consumer sectors.
Setting up a Sponge Iron Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's steel-capacity expansion, its position as the world's largest sponge iron producer, and strong demand from induction furnaces and electric arc furnaces.
Setting up an Aluminium Recycling Manufacturing Plant in India is a high-demand, sustainability-driven venture, powered by the country's booming automotive and construction sectors, the circular-economy push, and the huge energy advantage of recycled over primary metal.
Setting up a Textile Chemicals Manufacturing Plant in India is a high-value, demand-driven venture, powered by the country's vast textile industry, its rise as a global apparel and fabric sourcing hub, and a strong push toward import substitution in specialty chemicals.
Setting up a Metal Fabrication Plant in India is a high-demand, infrastructure-driven venture, powered by the country's construction boom, expanding capital-goods sector, and the Make in India push toward domestic engineering.
Setting up an HDPE Pipe Manufacturing Plant in India is a high-demand, infrastructure-linked venture, powered by the country's massive investment in water supply, irrigation, gas distribution, and sanitation.
India's ethanol industry has moved from a sugar by-product business to a pillar of national energy security. According to IMARC Group, the industry was valued at USD 3.43 Billion in 2025, rose to USD 4.14 Billion in 2026, and is projected to reach USD 11.78 Billion by 2034, growing at a CAGR of 13.95% (2026–2034).
Setting up a Tyre Pyrolysis Plant in India is a profitable, environmentally valuable venture, driven by the country's mounting waste-tyre problem, circular-economy policy, and demand for alternative fuels and recovered carbon black. Tyre pyrolysis converts end-of-life tyres into pyrolysis oil, carbon black, steel wire, and combustible gas, turning a difficult waste stream into marketable products.
The lithium ion battery market in India reached USD 3.59 Billion in 2025 and is projected to reach USD 9.79 Billion by 2034, growing at a CAGR of 11.78% (2026–2034).
Setting up a Bio-CNG Production Plant in India is a capital-intensive but high-potential venture, driven by the country's push for clean fuel, waste-to-energy policy, and energy security. Bio-CNG, also known as compressed biogas, is produced by purifying biogas generated from organic and agricultural waste into a high-methane fuel equivalent to conventional CNG.
Setting up a dicalcium phosphate manufacturing plant in India is a capital-intensive but high-potential venture. India’s combined strength as the world’s third-largest poultry producer, largest milk producer, and largest generic drug manufacturer creates one of the deepest and most diversified DCP demand bases globally. With domestic raw material availability and supportive government policies, the country offers a uniquely favourable environment for new and expanding DCP manufacturers.
The Australia Steel Industry is drawing renewed investor attention as government-backed decarbonization funding, sovereign manufacturing policy, and structural demand from construction and mining converge in a single market cycle.
Xanthan gum is a high molecular weight extracellular polysaccharide, which is produced by the fermentation of carbohydrates by the bacterium Xanthomonas campestris. It is a complex polysaccharide, chemically consisting of a cellulose backbone with trisaccharide chains, which impart it with remarkable rheological properties. It is highly soluble in water and has the ability to create high viscosity even at low concentrations.
A ball bearing is a type of mechanical rolling-element bearing that helps to support radial loads, as well as end loads, while reducing the friction between two surfaces that move. It consists of two rings, one outer and one inner, with balls that are made of steel or other materials, which lie between the two rings. In between the balls, there is also a cage that helps to space the balls evenly.
Urea is an organic chemical substance that contains a large proportion of nitrogen and thus ranks as one of the most crucial compounds containing the element. Urea is a white, crystalline solid with a very high solubility in water and a stable structure under confined storage conditions. Urea is produced through the reaction of ammonia and carbon dioxide. It is a very rich source of the element and is also portable. Since the element is an essential component for the development and growth of plants, it is greatly used in the agricultural sector as well as in a number of industrial processes.
Tyre pyrolysis refers to a thermal recycling process whereby waste tyres are transformed into recyclable materials using a process of pyrolysis. Pyrolysis refers to a process whereby tyres are heated in the absence of oxygen to produce various useful resources. When tyres are subjected to elevated temperatures in the absence of oxygen, the various polymers found in tyres are reduced to simpler components without undergoing the process of combustion.
The global packaging industry is undergoing a profound transformation, with barrier films emerging as one of the most crucial components enabling product integrity, extended shelf life, and improved sustainability. As consumer expectations shift toward freshness, safety, and environmental responsibility, the importance of advanced barrier solutions continues to rise. In this evolving scenario, the barrier films market size is gaining increased attention, driven by innovations that enhance material performance while supporting ecofriendly packaging strategies.
The Saudi Arabia ethanol market represents a critical segment within the Kingdom's evolving industrial landscape. As one of the world's leading energy producers, Saudi Arabia strategically diversifies its economic portfolio beyond traditional hydrocarbon dependence. Ethanol, a versatile alcohol compound with applications spanning pharmaceuticals, personal care, chemicals, and fuel blending, has emerged as an essential component in this transformation.
Tile adhesive manufacturing is the industrial process of producing a specialized adhesive for fixing tiles to a substrate of concrete, cement screed, plaster, drywall, or existing tiles. Tile adhesives are normally made from a combination of cement, polymers, fillers, and performance additives that improve bonding power, flexibility, water resistance, and setting times.
Toughened glass production is the industrial process of making safety glass that is much stronger and more resistant to impact than regular annealed glass. The production process involves heating flat glass to high temperatures and then rapidly cooling it, which causes compressive stresses on the surface and tensile stresses in the core.
As the nation pursues ambitious infrastructure goals and accelerates urban development initiatives, prefabricated construction and structural steel solutions have emerged as indispensable components of modern building practices.
Sulfuric acid is a highly corrosive, colorless to slightly viscous inorganic acid that consists of sulfur, oxygen, and hydrogen. It is one of the most widely used industrial chemicals in the world because of its strong acidic properties and high reactivity.
Sponge iron, also called direct reduced iron (DRI), is a metallic material produced through the solid-state reduction of iron ore without melting it. The oxygen in iron ore is removed through the action of reducing gases or solid carbon at a temperature below the melting point of iron. The product has a porous, sponge-like appearance, and this is why it is called sponge iron.
Sodium ferrocyanide is a chemical that is classified as an inorganic coordination compound, comprising sodium ions and the ferrocyanide complex. This chemical is typically denoted by the chemical formula Na4[Fe(CN)6]·10H2O. Although the chemical contains cyanide ions, it is stable and less toxic, as the cyanide ions are strongly bound to the iron ion.
SLES is an anionic surfactant that finds wide application due to its outstanding performance on cleansing, foaming, and emulsifying properties. It is prepared by the ethoxylation of lauryl alcohol, usually sourced from natural fats or oils, followed by sulphonation and neutralization. The process of ethoxylation differentiates SLES from SLS in that SLES shows better mildness and lower irritation while retaining strong detergency.
Sodium chloride is an inorganic chemical compound that consists of sodium and chlorine ions, known as common salt. Its chemical formula is NaCl, which often tends towards crystalline form. It can be easily taken out from seawater, rock salt deposits, or salt lakes. The chemical properties of this compound make it completely water-soluble, with a stable nature.
The Gulf Cooperation Council cement market stands at a critical juncture as regional economies accelerate infrastructure development and pursue ambitious economic diversification strategies. Cement consumption across the GCC nations continues to expand, driven by transformative megaprojects, rapid urbanization, and substantial government investment in construction infrastructure.
The Kingdom of Saudi Arabia is undergoing an unprecedented economic transformation, shifting its traditional reliance on hydrocarbon revenues toward a diverse, knowledge-based economy. Central to this monumental shift is the steel industry in Saudi Arabia, a sector that serves as a foundational pillar for virtually every national development project.
A silk reeling unit is a type of manufacturing plant where raw silk threads are obtained from the cocoons of silkworm moths and processed into raw silk yarn by weaving them into a continuous strand of raw silk.
PVC solvent cement is a specialized adhesive formulation used to create permanent joints between polyvinyl chloride (PVC) pipes, fittings, and components. Unlike standard adhesives that rely on surface bonding, solvent cement chemically fuses PVC materials together. It works by using a blend of solvents and resins that temporarily soften and dissolve the surfaces of the PVC components.
PVC (Polyvinyl Chloride) pipes are durable and versatile piping products made from a synthetic thermoplastic polymer known for its strength, chemical resistance, and longevity. These pipes are produced primarily through the extrusion process, which ensures consistent wall thickness and uniform mechanical properties. Available in both rigid and flexible forms, PVC pipes are designed to transport fluids, gases, or solids safely under controlled pressure and temperature conditions.
Plastic pyrolysis is a form of recycling plastic waste via a process referred to as thermochemical recycling. This process produces liquid fuels, gases, and solid wastes through thermal degradation under low or no oxygen. Unlike traditional recycling, plastic pyrolysis involves the breakdown of long polymer chains into smaller hydrocarbon molecules using heat, in most cases in the presence of catalysts.
Insulation tapes made of PVC are adhesive tapes produced through a process involving a polyvinyl chloride (PVC) carrier coated with an adhesive made of rubber or acrylic materials. These insulation tapes have applications in electrical installations to serve their intended purpose of insulation and protection against environmental damage for electrical components and cables.
Precipitated silica is a synthetic and amorphous silicon dioxide, which is prepared through a process of controlled chemical reaction between soluble silicates and mineral acids. Unlike regular silica, precipitated silica is manufactured to have desired particle sizes, surface area, and porosity in terms of its structure, determining its final end-use performance. Precipitated silica is a fine, white, and free-flowing powdered substance.
Plywood is an engineered wood product made by bonding multiple thin layers of wood veneer together with strong adhesives under heat and pressure. The veneers are oriented so that their grain directions are at right angles to each other in successive layers, a manufacturing technique that improves strength, stability in dimensions, and resistance to cracking or warping.
Plastic crates are a rigid and reusable construction with a production material that includes a thermoplastic such as high-density polyethylene (HDPE) and Polypropylene (PP). These crates have design features that ensure the efficient storage, transport, and handling of goods while having a strong load-bearing capacity and a longer life span.
The cement industry remains one of the most critical foundations of global development, shaping the built environment and enabling progress across residential, commercial, and industrial landscapes. As construction activity expands and infrastructure investment intensifies, the cement market size continues to evolve, supported by new material innovations, sustainability priorities, and smart manufacturing technologies.
The GCC ceramic tiles market has emerged as one of the most dynamic segments in the region's construction and building materials sector. Spanning countries including United Arab Emirates, Saudi Arabia, Kuwait, Oman, Qatar, and Bahrain, the market reflects the Gulf region's ambitious transformation from oil-dependent economies to diversified, modern nations.
Paints are liquids, semi-liquids, or powdered materials, usually having a high content of pigments, binders or resins, solvents or vehicles, or additives, intended for application onto substrates to create a continuous film after drying or curing. Paints work as materials after their application, possessing several functionalities, such as protecting the surface, adding color, or modifying functionalities. Paints contain several components, such as binders or resins, pigments, solvents or vehicles, or additives, each differing based on their functionalities. The binder or resin is mainly involved in providing strength or adhesive characteristics, while pigments are used to create colors or opaqueness.
Organic fertilizers refer to nutrient-value-adding materials that come from ecologically degradable sources like plant debris, animal manure, composted materials, bio-wastes, bone meal, and microbe organisms. Another key point of distinction between organic and synthetic fertilizers is that whereas synthetic fertilizers give quicker nutrient release through chemical reactions, nutrient release occurs via bacterial decomposition in the case of organic fertilizers.
Oleochemicals are chemicals obtained from natural fats and oils derived mainly from renewable plant-based feedstocks like palm oil, palm kernel oil, coconut oil, soybean oil, and other materials high in triglyceride content. These raw materials are transformed into fatty acids, fatty alcohols, glycerin, methyl esters, and other derivatives by means of hydrolysis, transesterification, hydrogenation, fractionation, and other techniques. They represent renewable, biodegradable, and environmentally friendly alternatives to chemicals made from petrochemical raw materials.
NdFeB magnets are a family of high-performance permanent magnets primarily made of an alloy of neodymium, iron, and boron. They are fabricated by the sintering or bonding processes, which create extremely high magnetic energy density and make them the most powerful commercial magnets. NdFeB magnets have the best coercivity, remanence, and effectiveness in compact forms that can generate strong magnetic fields in the smallest volume.
Mineral wool ceiling tiles consist of acoustic and thermal insulation panels fabricated from inorganic fibers, which originate mainly from molten basalt, slag, or other mineral-based raw materials. The fibers are spun and bonded together with resins, then compressed into rigid tiles that perform well in terms of sound absorption, fire resistance, and moisture tolerance. They are usually available in standard sizes for application in suspended ceiling systems in commercial, industrial, and institutional buildings.
Methanol, also known as methyl alcohol or wood alcohol, is a colorless liquid that is volatile and flammable with the chemical formula CH3OH. The simplest of the alcohols, it is produced mainly by the catalytic conversion process of natural gas, coal, or biomass into synthesis gas-a mixture of carbon monoxide and hydrogen-further followed by methanol synthesis under high pressure.
Lubricating oil is a specially formulated liquid substance that reduces friction, wear, and generation of heat between moving mechanical surfaces. It is usually made from refined mineral base oils, synthetic oils, or a mixture of both, supplemented with performance-improving additives such as anti-wear agents, detergents, dispersants, antioxidants, corrosion inhibitors, and viscosity improvers.
The Philippines passenger vehicles lubricants industry stands at a transformative juncture, driven by robust automotive sector expansion, technological innovation, and evolving consumer preferences toward high-performance products. As the Philippine economy demonstrates resilient growth and vehicle ownership continues to rise, the demand for premium automotive lubricants has accelerated significantly across the archipelago.
Hydrogen is the lightest and most abundant element in the universe, being a colorless, odorless, highly combustible gas. It does not usually occur free in nature but is produced from hydrogen-rich compounds like water, natural gas, biomass, or other hydrocarbons. Owing to its high energy content per unit mass and clean combustion (with the production of water vapor only), hydrogen is widely recognized as a versatile energy carrier. Depending on how hydrogen is produced, it is classified as grey, blue, or green and increasingly plays a significant role in clean energy systems, industrial processing, and developing low-carbon technologies.
HDPE pipes are thermoplastic piping systems made from high-strength polyethylene resin, which features excellent flexibility, high impact resistance, and strong chemical and corrosion resistance. HDPE pipes are produced by extruding molten polyethylene into a variety of diameters and pressure ratings. Their seamless structure, along with their low friction and resistance to internal pressure and external load, makes them ideal for the transport of fluids. HDPE pipes boast superior endurance, long service life, and leak-free performance, since it is possible to join them through heat fusion, thus creating monolithic, continuous pipelines that are suitable for buried, aboveground, or underwater installations.
Graphite is a crystalline form of pure carbon, where atoms are organized in layered hexagonal structures, reflecting exceptional lubricity, electrical conductivity, heat resistance, and a high degree of chemical stability. It comes in many forms: flake, amorphous, vein, and synthetic graphite-derived from petroleum coke or coal tar pitch. Because of this layered structure, the sheets slip easily, which gives graphite its characteristic softness and lubricity, while strong covalent bonding within the layers makes it thermally stable and conductive. The unique characteristics make graphite indispensable in uses such as steelmaking, refractories, batteries, electronics, and in high-performance industrial components.
The Japan urea industry stands as a critical pillar supporting multiple sectors of the nation's economy, from agricultural productivity to automotive emissions control. As a nitrogen-rich compound essential for modern farming practices, urea plays an indispensable role in ensuring food security for Japan's population while simultaneously addressing stringent environmental standards through its industrial applications.
The Japan industrial gases industry stands as a critical enabler of the nation's economic infrastructure, supporting diverse sectors including manufacturing, healthcare, electronics, semiconductors, steel production, and energy generation. Industrial gases such as oxygen, hydrogen, nitrogen, carbon dioxide, argon, and specialty gases serve as essential inputs across these industries, facilitating everything from metal fabrication and medical treatments to advanced semiconductor manufacturing.
A fire extinguisher is either a portable or fixed device that is designed to combat and suppress small fires by discharging a controlled substance, which cools the burning material, cuts off oxygen supply, or interrupts the chemical chain reaction sustaining combustion. It is among the most important items that comprise fire protection systems, finding wide applications in residential, commercial, industrial, and transport environments.
Fiberglass, also known as glass fiber, is a composite material manufactured by weaving, chopping, or layering minute strands of glass into strong yet lightweight and durable products. It is made by melting silica sand, limestone, soda ash, and other raw materials together at very high temperatures-around 1,700°C-through which molten glass is obtained. It is extruded through fine nozzles to create continuous filaments, then combined into mats, fabrics, or roving later on, according to use.
Engine oil is a specific lubricant that serves to reduce friction, wear, and heat in an internal combustion engine's moving parts, allowing the smooth operation of such engines. Besides lubrication, it accomplishes other very important tasks: cooling, cleaning, sealing, and protection against corrosion. The two major components of engine oil formulation are the base oil and additives. The base oils, mineral or petroleum-based, synthetic, and semi-synthetic, constitute approximately 70-90% of the formulation and provide the fluidity and viscosity for the best performance.
The Australia bioplastics industry is experiencing unprecedented growth, driven by intensifying consumer demand for sustainable alternatives and robust government sustainability initiatives.
Ferrous sulphate is an inorganic salt, composed of iron, sulfur, and oxygen, and is mainly known for its pale green or blue-green crystalline appearance. It exists in various hydrated forms, the most common being ferrous sulphate heptahydrate (FeSO4·7H2O), although it is also produced largely as a monohydrate and anhydrous variant, depending on the industrial needs. It is usually manufactured as a by-product of the pickling of steel using sulfuric acid, or it could be produced as a co-product from titanium dioxide pigment manufacture.
Bamboo plywood is an engineered wood product that is made by laminating thin strips or veneers of bamboo into multi-layered panels to create a stable, uniform sheet material combining the natural aesthetics of bamboo with the structural versatility of plywood. Unlike conventional plywood made from hardwood or softwood veneers, bamboo plywood most often uses strand-woven, horizontal, or vertical lamination patterns of bamboo culm that are bonded under heat and pressure with formaldehyde-free or low-emission adhesives.
Biomass pellets are a sustainable, carbon-neutral, and renewable source of energy made from organic materials such as forestry waste, agricultural residues, sawdust, wood chips, and other biomass feedstocks. Biomass pellets are small, cylindrical in shape, and usually between 6 and 12 millimeters in diameter and are utilized as a clean energy alternative to fossil fuels in power production, heating, and for industrial purposes.
Bioethanol is a biodegradable, renewable alcohol that is made by fermenting sugars from biomass resources like corn, sugarcane, wheat, cassava, and cellulosic materials like agricultural waste and forest residues. It is cleaner than gasoline from fossil fuels and provides valuable decreases in greenhouse gases and helps to move us toward sustainable energy systems. The process of production of bioethanol is mainly about the conversion of biomass carbohydrate to simple sugars by hydrolysis and subsequent fermentation by yeast or bacteria into ethanol.
Blue ammonia is one type of ammonia production that is meant to reduce carbon dioxide emissions. Traditional methods of ammonia production include sourcing hydrogen from natural gas, usually through steam methane reforming (SMR) or auto-thermal reforming (ATR) and then reacting this hydrogen with nitrogen (from air) through the Haber-Bosch process. The "blue" suffix indicates that the carbon dioxide waste product produced in the course of hydrogen synthesis is captured (through Carbon Capture, Utilization, and Storage / CCUS) and not released into the environment.
Biodiesel is a renewable and biodegradable fuel source mainly from vegetable oils, animal fats, or waste cooking oils, and can serve as a direct replacement or blend with traditional petroleum diesel. It is chemically constituted by fatty acid methyl esters (FAMEs), which are formed when triglycerides react with methanol or ethanol in the presence of a catalyst under transesterification.
Anhydrous Ferric Chloride, FeCl3, is a corrosive dark brown crystalline chemical that finds extensive application as a major industrial chemical in water treatment, metallurgy, electronic manufacturing, and chemical synthesis industries. It is produced by reacting chlorine gas with iron or ferrous chloride at elevated temperatures to form a high-purity, moisture-free product. In contrast to its hydrate, anhydrous ferric chloride is not aqueous and is mostly used in processes involving controlled levels of moisture, for example, etching circuits in electronics and as a catalyst in the synthesis of organics.
Ammonium Bicarbonate (NH4HCO3) is a white crystalline inorganic chemical used extensively in the fertilizer, food processing, pharmaceutical, and chemical industries. It is a salt that is produced by the combination of ammonia, carbon dioxide, and water and is renowned for decomposing at relatively low temperatures into ammonia, carbon dioxide, and water vapor. This characteristic makes it useful as a leavening agent for the food industry, especially in baked foods, cookies, and crackers, which produce a light and porous texture due to its presence.
Biodegradable plastic granules are eco-friendly polymer materials designed to decompose naturally through the action of microorganisms such as bacteria, fungi, and algae, reducing the environmental burden associated with conventional plastics. These granules are the fundamental raw materials used in the production of biodegradable products such as packaging films, agricultural mulch, carry bags, cutlery, and medical components.
Bioplastics are a category of materials that come entirely or partly from renewable biological resources like corn starch, sugarcane, vegetable oils, or cellulose, to be used as sustainable substitutes for traditional petroleum-based plastics. Bioplastics may be biodegradable, non-biodegradable, or compostable, depending on their chemical composition and manufacturing process.
Battery recycling is the collection, dismantling, and processing of used or end-of-life batteries to recover valuable materials and limit environmental threats. With the burgeoning exponential increase in electric vehicles (EV), renewable energy storage, and consumer electronics, the number of spent batteries has skyrocketed, necessitating recycling as a key component of the energy transition worldwide.
Binding wire is a low-cost, flexible steel wire, mainly utilized for tying, fastening, and bundling in applications of construction, industry, agriculture, and packaging. Usually produced from mild steel wire rod by successive cold-drawing, annealing and surface-finishing processes, binding wire comes in an assortment of gauges (typically 18–24 AWG / 1.0–1.6 mm) and in a few forms: soft/annealed plain wire, galvanized (zinc-coated) wire for corrosion-proofing, and polymer/PVC-coated wire for better handling and durability.
Aluminum anodizing is an electrochemical process that improves the surface characteristics of aluminum by creating a long-lasting, corrosion-resistant oxide coating on its surface. In contrast to coatings or paint applied to the outside surface, anodizing makes the outer surface of aluminum into a protective aluminum oxide coating that is bonded integrally to the metal and will last long and stay adherent.
Aluminum powder is a finely divided metallic aluminum with a wide range of applications in various industries because of its specific physical and chemical properties. It is manufactured by atomization, mechanical grinding, or flake milling of pure aluminium. The powder has high reactivity, low density, high thermal conductivity, and high reflectivity. Depending on the manufacturing technique, it can exhibit spherical, irregular, or flake-like morphologies, making it suitable for diverse applications.
Aluminum bottles are lightweight, strong, and recyclable packages manufactured mostly from high-purity aluminum that provides a sustainable and premium alternative to conventional plastic and glass packaging. Aluminum bottles integrate functionality with style and, therefore, are gaining popularity in industries like beverages, cosmetics, personal care, pharmaceuticals, and household products.
Aluminum ingots are standardized raw forms of aluminum that are produced by smelting and refining processes, which act as a basic raw material for downstream industries. The ingots are commonly prepared by refining bauxite ore to alumina through the Bayer process, followed by electrolytic reduction in smelters through the Hall-Héroult process. The molten aluminum thus produced is cast into ingot shape for transportation convenience, handling, and further processing.
Aluminum extrusion is a versatile metal forming process whereby aluminum billets are pushed through a shaped die to create long profiles with the same cross-section. Through this process, manufacturers can create intricate shapes that balance strength, lightweight characteristics, and beauty, making it a cornerstone of several industries.
Activated alumina balls are porous, granular, and spherical materials consisting of aluminum oxide (Al2O3). They possess a large surface area, high adsorbing capacity, and excellent resistance to thermal shock and abrasion. Manufactured by the controlled dehydroxylation of aluminum hydroxide, activated alumina balls are chemically inert, non-toxic, and possess excellent water and polar molecule affinity. Due to such features, they find extensive applications as desiccants, adsorbents, and catalysts. In industrial operations, they are useful for drying gases and liquids in processes, eliminating fluoride, arsenic, and selenium ions from water, and as a catalyst carrier in petrochemical refining applications.
Activated carbon or activated charcoal is a very porous form of carbon with an incredibly large surface area, usually anywhere from 500 to 1,500 m²/g. Manufactured by activating carbon-rich materials such as coconut shells, wood, coal, or peat, it is subjected to physical or chemical treatment to create its distinctive pore structure. The microporous structure enables activated carbon to efficiently absorb gases, vapors, and dissolved materials, which makes it a vital adsorbent in all industries.
Glass Fiber Reinforced Polymer (GFRP) rebar and mesh are composite materials developed to be used in place of the conventional steel reinforcement in concrete structures. They consist of continuous glass fibers dispersed within a polymeric resin matrix, most commonly epoxy, vinyl ester, or polyester. The synergy between the tensile strength of glass fiber and the corrosion inhibition properties of polymers produces reinforcement products that are light weight, corrosion-free, and extremely durable.
Phosphorus Pentasulfide (P2S5) is a yellow-green crystalline compound primarily produced through the controlled reaction of elemental phosphorus and sulfur. As a key phosphorus-based intermediate, it plays a critical role in the chemical industry, particularly in the manufacture of lubricant additives such as zinc dialkyldithiophosphate (ZDDP), agrochemicals, and battery electrolytes. Structurally, P2S5 consists of phosphorus and sulfur atoms bonded in a cage-like configuration, imparting high reactivity and compatibility with organic synthesis pathways. It is valued for its sulfur-donating properties, thermal stability, and role as a bridging compound in synthesizing more complex phosphorus-sulfur compounds.
Steel bolts and fasteners are integral mechanical components that provide secure connections across industrial, commercial, and household applications. Comprising primarily of carbon steel, alloy steel, or stainless steel, these fasteners are engineered to withstand significant mechanical loads, torque, and environmental exposure. Their key properties include high tensile strength, corrosion resistance, dimensional precision, and durability under cyclic stress. Manufacturing typically involves processes such as forging, machining, threading, and surface finishing to meet exacting industry standards.
Copper sulphate is an inorganic chemical made up of copper, sulfur, and oxygen that is best known for its crystalline blue color and varied uses. Most often found as copper sulphate pentahydrate (CuSO4·5H2O), it is prized for its water solubility, stability, and fungicidal activity. Primary characteristics are that it is a fungicide, herbicide, algicide, and electrolyte used in industrial applications. It also serves as a precursor for the manufacture of other compounds of copper and as a laboratory reagent.
Sebacic acid is a naturally occurring dicarboxylic acid, a long-chain organic compound with two carboxyl functional groups. It is mainly produced from castor oil through cracking and purification in a significant industrial process, as it is a valuable bio-based chemical with major industrial relevance. The white flaky or crystalline powder is cherished for its superior properties, such as high thermal stability, corrosion resistance, and the ability to form long-lasting polymers.
Aluminium conductors are electrical wires or cables whose current-carrying core is primarily made of aluminium (or its alloys), used for overhead transmission lines, distribution, AAC (All Aluminium Conductor), AAAC (All Aluminium Alloy Conductor), ACSR (Aluminium Conductor Steel Reinforced), etc. The material is lightweight, has relatively good electrical conductivity (lower than copper but acceptable for many applications), and is cost-effective per unit weight.
Steel rolling products, encompassing hot-rolled, cold-rolled, and coated steel sheets and coils, form the backbone of numerous industrial applications, from automotive manufacturing to construction and infrastructure. The cost of these products is influenced by a complex interplay of raw material prices, energy costs, labor, technological advancements, and logistical considerations.
Treatment of sewage is the procedure of eliminating contaminants from domestic or industrial wastewater to yield treated effluent that can be safely released into the environment or recycled for different purposes. Sewage contains organic matter, nutrients, suspended solids, microorganisms, and chemical pollutants and hence physical, chemical, and biological processes must be utilized for purification.
Green methanol is a renewable and sustainable form of methanol produced from non-fossil-based feedstocks such as biomass, municipal solid waste, biogas, or captured carbon dioxide combined with green hydrogen generated via electrolysis powered by renewable energy. Chemically, it is identical to conventional methanol (CH3OH), a simple alcohol with high energy density and versatile chemical properties.
Sodium hydrosulfide (NaHS) is an inorganic chemical mainly known for its good reducing nature and adaptability in uses in industry. It exists as pale yellow solid or liquid in aqueous solution with the smell of sulfur. It is chemically obtained by the partial neutralization of hydrogen sulfide (H2S) by sodium hydroxide (NaOH) to form a stable and water-soluble salt.
Recycled Polyethylene Terephthalate (rPET) is a thermoplastic polymer obtained from post-consumer and post-industrial PET waste, mainly plastic bottles and packaging materials. It is chemically the same as virgin PET, composed of polymerized units of terephthalic acid and ethylene glycol, but is made from a recycling process that minimizes dependence on fossil-based feedstocks. Major characteristics of rPET are high strength-to-weight ratio, chemical resistance, dimensional stability, and high recyclability.
Animal feed grade Di-calcium Phosphate (DCP) is a mineral feed supplement commonly applied in animal and poultry nutrition to fortify dietary calcium and phosphorus—two of the most important nutrients in maintaining animal health and production levels. Manufactured predominantly through the reaction of phosphate rock-based phosphoric acid with calcium carbonate or lime, feed-grade DCP is generally found as a white or off-white granular or powdered material.
Copper tubes are cylindrical hollow goods consisting mainly of purified copper, which are highly prized for their high thermal conductivity, corrosion resistance, ductility, and antimicrobial qualities. They are produced by processes like casting, extrusion, and drawing, which provide accurate dimensions and clean internal surfaces.
Automotive fabrics are specialized textile materials engineered for use in vehicle interiors, combining aesthetics, functionality, and durability. Unlike ordinary textiles, automotive fabrics must withstand prolonged wear, UV exposure, temperature variations, and continuous contact, while also contributing to passenger comfort and vehicle safety.
Aluminum sheets, cans, and foils are among the most common types of processed aluminum, serving industries from packaging and construction to transport and consumer products. Aluminum sheets are flat-rolled material manufactured in a range of thicknesses and grades, prized for light weight, corrosion resistance, and ability to be recycled, ideal for use in car body panels, building cladding, roofs, and kitchen appliances.
Synthetic graphite is a state-of-the-art carbon material developed through petroleum coke and coal tar pitch treatment at high temperatures, providing highly crystalline carbon materials of higher purity and uniformity than natural graphite. Synthetic graphite is produced in controlled industrial conditions unlike natural graphite, which is excavated.
Diammonium Phosphate (DAP) is among the most popular phosphorus fertilizers in the world due to its high concentration of nutrients and multiple uses in agriculture. It is manufactured by reacting ammonia with phosphoric acid, forming a compound that has about 18% nitrogen and 46% phosphorus pentoxide (P2O5). Such levels of nutrients make DAP an effective supply of critical macronutrients for plants, especially for root development, seed germination, and plant growth early on.
Australia's battery recycling market is charging ahead, with a value of USD 336 Million in 2024 and no signs of slowing down. Driven by the booming demand for cleaner, greener solutions—especially in the Australia battery energy market and electric vehicle (EV) sectors—the industry is expected to reach USD 612.55 Million by 2033. That’s a steady growth rate of 6.90% annually from 2025-2033.
Green ammonia is used to describe ammonia made from renewable energy systems like wind, solar, or hydropower through water electrolysis to obtain green hydrogen, then blended with nitrogen in the air through the Haber-Bosch process. Unlike traditional ammonia, which is derived from natural gas and produces enormous amounts of CO2, green ammonia is a carbon-free and sustainable alternative.
Hydrogen Peroxide (H2O2) is an all-purpose, eco-friendly chemical used extensively as an oxidizing, bleaching, and disinfectant agent in various industries. Hydrogen Peroxide is a clear, colorless liquid with high oxidizing power, breaking down into oxygen and water, and thus a clean alternative to several hazardous chemicals.
Biofertilizers are microbial products that contain living microbes, and they enhance plant growth through the improvement of nutrient availability in the soil microcosm. They may consist of useful microorganisms like Rhizobium, Azotobacter, Azospirillum, phosphate-solubilizing bacteria (PSB), and mycorrhizal fungi. These microorganisms form symbiotic or associative relations with plants and enhance nitrogen fixation, phosphorus solubilization, and the uptake of required nutrients.
Steel stands as one of the world’s most essential industrial materials, forming the backbone of modern infrastructure, manufacturing, and economic progress. As a critical material, its production and consumption directly influence global economic dynamics. The steel market has seen significant evolution, driven by innovations, demand from diverse sectors, and increasingly sustainable practices.
The global petrochemicals market is witnessing steady growth, supported by rising end-user consumption, industrial diversification, and infrastructure development across both developed and emerging economies.
Ethyl acetate is a volatile, colorless, flammable liquid having a characteristic sweet smell. It is primarily used as a solvent in various industrial and commercial applications. It finds primary production through esterification from ethanol and acetic acid.
Ammonium nitrate (NH4NO3) is a white solid that is widely used as a high-nitrogen fertilizer and as a component of industrial explosives. It is made by neutralization of ammonia with nitric acid and is very soluble in water, making it useful for its efficiency in providing nitrogen to plants.
Ceramic tiles are durable, versatile, and cost-effective building materials made from natural clay, sand, and water, which are shaped, glazed, and kiln-fired at high temperatures. Known for their aesthetic appeal, resistance to moisture, and ease of maintenance, ceramic tiles are widely used in flooring, walls, kitchen backsplashes, and bathrooms across residential, commercial, and industrial spaces.
Diethylenetriamine (DETA) is a colorless, hygroscopic organic chemical compound of the ethyleneamine group having the chemical formula HN(CH2CH2NH2)2. It is a triamine that contains two primary amine groups and one secondary amine group, thus imparting to it a highly reactive molecular structure to be used in a number of industrial processes.
Calcium Chloride Anhydrous (CaCl2) is an off-white, hygroscopic inorganic substance commonly utilized due to its high desiccating and exothermic properties. The anhydrous form, as opposed to its hydrated counterparts, has no water molecules within it, thus making it very effective to use in moisture control processes.
Explore a step-by-step guide to setting up a unsaturated polyester resin production plant including planning, machinery, raw materials, costs & demand drivers.
Explore the growth, trends, and innovations driving the global bio-lubricant market toward a sustainable future.
Medium Density Fibreboard (MDF) is an engineered wood product created by dissolving hardwood or softwood residues into wood fibers, blending them with wax and resin binders, and molding them into panels under the pressure of high temperature. MDF is renowned for its even density, smooth surface, and easy machinability and is used extensively in cabinetry, flooring, furniture, and interior decoration because of its relative cheapness and adaptability as compared to plywood and solid wood.
Lanthanum oxide (La2O3) is a white, odorless, and extremely stable rare earth compound obtained mainly from monazite and bastnäsite ores. It is essential for a vast array of industrial uses such as the manufacture of optical lenses, ceramics, phosphors, and battery electrodes. Lanthanum oxide is also used extensively as a catalyst in petroleum refining processes, particularly in fluid catalytic cracking (FCC) operations. Due to its exceptional electrical, optical, and catalytic properties, La2O3 is an important material for advanced technologies like electric vehicles (EVs), smart electronics, and renewable energy devices.
Silica sand is a pure quartz-based material used extensively by many industries. It is known for its durability, chemical inertness, and resistance to heat, and it is an important raw material in glass production, construction, foundries, electronics, and hydraulic fracturing (fracking). Increasing demand for high-purity silica in semiconductors, solar panels, and filters is fueling market growth. With more infrastructure development and development in silica processing, the applications keep expanding, and it is becoming an essential industrial commodity worldwide.
Stone paper is an innovative, eco-friendly material gaining traction across various industries due to its durability, sustainability, and water resistance. Made primarily from calcium carbonate and resin, it offers a tree-free alternative to traditional paper, reducing deforestation and water consumption. Its tear-resistant and smooth texture makes it ideal for printing, packaging, and stationery applications. Additionally, stone paper is recyclable, photodegradable, and highly resistant to moisture, making it suitable for outdoor and high-humidity environments. With growing environmental concerns and demand for sustainable packaging and printing solutions, stone paper is emerging as a key player in the global paper industry, attracting interest from publishers, packaging manufacturers, and eco-conscious brands.
Nitrile gloves are synthetic rubber gloves that are extensively used in the medical, industrial, and food industries because of their strength, resistance to chemicals, and hypoallergenic nature. They are ideal for people with allergies since they are latex-free, as opposed to latex gloves. They are more flexible, puncture-resistant, and resistant to infection and chemicals. The demand for nitrile gloves in manufacturing, healthcare, and laboratory environments is increasing because of stringent safety regulations and increasing hygiene consciousness, which is driving the worldwide market growth.
Acetic acid (CH3COOH) is a clear, colorless liquid organic compound with a sour taste and a pungent odor. It is produced by the carbonylation of methanol and is also manufactured via bacterial fermentation. Acetic acid is extensively employed in the manufacturing of vinyl acetate monomer (VAM), purified terephthalic acid (PTA), acetic anhydride, and ester solvents, among others. It provides solvent effectiveness, chemically useful to use in syntheses, as well as utilization in the fabrication of polymers and resins.
Calcium bromide (CaBr2) is an inorganic compound commonly used in drilling fluids for oil and gas exploration, as well as in pharmaceutical and photographic applications. It is a white, crystalline solid or solution that dissolves very easily and is used as a clear, dense brine in well drilling operations. Calcium bromide is prized for its capacity to manage pressure and avoid well blowouts due to its exceptional thermal and chemical stability. The growing energy industry and improvements in drilling technology are the main drivers of its demand.
Laminated veneer lumber (LVL) is one of the most popular engineered wood products, which is manufactured from sliced and peeled thin wood veneers. LVL is a light material used for construction, which is utilized in public structures, industrial warehouses, product parts, large, prefabricated buildings, as well as designed wooden homes. This can be attributed to its strength, uniformity, high strength, and dimensional accuracy. Apart from this, it is utilized for structural framing in residential and commercial building work, including lintels, joists, beams, purlins, scaffold boards, concrete formwork, and truss chords.
Cross-laminated timber (CLT), an engineered wood product, is renowned for its durability, strength, and adaptability in contemporary building. CLT provides a lightweight yet strong substitute for steel and concrete in structures with sustainable engineering. Its layered structure adds to its integrity and makes it suitable for building anything from residential to commercial to high-rise buildings. Besides being aesthetically pleasing for eco-friendly building projects, CLT has very good fire resistance, thermal performance, and ease of installation. CLT changes the architectural sphere and instigates the development of new concepts for urban environments and shaping the future of sustainable construction.
Copper wire is a versatile, flexible, and highly conductive electrical wire used extensively in power transmission, telecommunications, and electronics. Fabricated from pure copper, copper wire has good thermal and electrical conductivity, resistance to corrosion, and ease of processing. Copper wire plays a critical role in construction, automotive, and consumer electronics industries. With the increased demand for effective power distribution and advancing technology, the copper wire market keeps growing because of urbanization, electrification, and growth in infrastructure development globally.
Aluminum wire rods are critical industrial products renowned for their high conductivity, strength, and versatility. They are cylindrical metal rods that are the backbone of electrical transmission and distribution systems and play a fundamental role in power infrastructure, building construction, and manufacturing. Due to their good conductivity and low weight, they are a top choice for cable production, overhead power lines, and electrical wires. Outside of electrical uses, aluminum wire rods find extensive application in the automotive, aerospace, and industrial industries, where their corrosion resistance and recyclability play important roles in sustainability initiatives.
N-Methyl Aniline (NMA) is an organic chemical compound widely used as an intermediate in various industrial applications. It plays a crucial role in the production of dyes, agrochemicals, pharmaceuticals and fuel additives. As a key component in high-octane fuel formulations NMA enhances combustion efficiency and reduces engine knocking making it valuable in the automotive and petroleum industries. Its use in the synthesis of specialty chemicals and pigments further expands its industrial significance.
Ammonium perchlorate is a crystalline, white inorganic substance that finds principal application as an energetic oxidizer in solid rocket propellants, explosives, and pyrotechnics. Its release of oxygen when subjected to heat gives it a fundamental role in different industrial and technological processes. Aside from its primary application in propulsion systems, it is also used in pyrotechnic devices to generate controlled, vibrant flames and brilliant effects, especially in aerospace displays and enormous entertainment productions.
Potassium sulfate (K2SO4) is an inorganic compound widely used as a specialty fertilizer, providing essential potassium and sulfur nutrients to crops. Its low salt index makes it the preferred crop for crops that are sensitive to chloride, like fruits, vegetables, and tobacco. Potassium sulphate is also used in pharmaceutical and glass manufacturing processes, among other industrial processes. It is the perfect choice for contemporary agricultural methods because of its high solubility and compatibility with irrigation systems, which promote plant development, yield enhancement, and soil health maintenance.
Battery electrolyte is a key element of energy storage, facilitating the flow of ions between electrodes to drive devices effectively. It is an important factor in lithium-ion, solid-state, and future batteries, influencing performance, safety, and durability. In electric vehicles, renewable energy storage systems, and consumer devices, development in electrolyte technology targets sustainability, improved conductivity, and heat resistance for unlocking the future of clean energy technologies.
Cobalt acetate is an inorganic substance that is frequently utilised in chemical synthesis as a precursor, dye mordant, and catalyst. This crystalline solid has a reddish-purple appearance and is very soluble in organic solvents and water. In addition to being widely used in the manufacture of paints, inks, and adhesives, it is also an essential component of polyester and a catalyst in oxidation processes. It is a crucial component in many industries, with industrial uses driving its demand, especially in petrochemicals, textiles, and battery technology.
Transformer oil, sometimes referred to as insulating oil, is essential to electrical transformer operation. Its main functions are to cool and insulate the internal parts. By acting as a dielectric medium, the oil prolongs the transformer's lifespan and improves overall performance by preventing electrical discharges between various components. It moves around inside the transformer, assisting in the dissipation of heat produced during the conversion of energy. Although there are synthetic and bio-based substitutes, refined mineral oil is usually the source of it. Moisture, impurities, or the disintegration of the oil's chemical structure can all cause its quality to decline over time. It must be tested and maintained on a regular basis to stay effective.
Silica gel is obtained from silica dioxide a naturally occurring compound in sand and comprises fine particles that can soak quantity of water. It is a drying agent that is frequently packaged in tiny paper or cloth packets as tiny, transparent beads or crystals of clear rock. These packets are frequently included with business goods to guard against moisture-related damage. Food, clothing, and electronics are just a few of the many things that include silica gel packets. Although silica gel is typically non-toxic, it poses a choking hazard, particularly to young children.
Amorphous silicon dioxide (silica) particles dispersed in water are known as colloidal silica. In order to produce these amorphous silica particles, silica nuclei from silicate solutions are polymerised in an alkaline environment to create silica sols with a high surface area and a nanometre size. The surface of the silica nanoparticles is then charged, which causes the particles to reject one another and create a stable colloid, or dispersion. Although colloidal silica comes in a variety of grades, all of them are made up of silica particles that range in size from roughly 2 nm to 150 nm. The particles might exist as discrete particles or as slightly organised aggregates, and they can have a spherical or slightly irregular shape.
In a time characterized by environmental awareness and limited resources, sustainable manufacturing has become an essential priority for companies all over the world. Sustainable manufacturing is a model beyond conventional manufacturing practices, focusing on the production of goods in a manner that reduces harm to the environment, uses less energy and natural resources, and prioritizes the health and safety of workers, communities, and consumers.
Intravenous (IV) solutions represent a critical and ubiquitous component of modern healthcare, playing a fundamental role in patient care and treatment. These sterile, liquid formulations consist of a carefully balanced blend of fluids and electrolytes, administered directly into a patient's bloodstream. They are tailored to address a wide range of medical needs, from rehydration and medication delivery to nutritional support and blood transfusions.
Titanium dioxide (TiO 2) is a white, naturally being mineral extensively used as a pigment, UV blocker, and opacifier. A vital element of paints, coatings, plastics, cosmetics, and sunscreens, it's well- known for its exceptional opacity, high illumination, and superior light- scattering capabilities. Also, TiO 2 is essential for advanced operations like photocatalysis, food, and pharmaceuticals. Because of its non-toxic and chemical- resistant rates, it's a necessary element of numerous different sectors, performing in steady demand worldwide.
Yellow phosphorus, a chemical element with the symbol P and atomic number 15, is a fascinating and essential element in the periodic table. This highly reactive nonmetal is widely known for its distinctive yellow appearance and its crucial role in various industrial applications. Found in nature primarily as phosphates, yellow phosphorus is isolated through a complex process to ensure its purity and effectiveness. Its versatility allows it to be employed in the production of fertilizers, detergents, and even in the synthesis of organophosphorus compounds used in medicine and pesticides.
Xanthan gum is a food additive that is produced by fermenting simple sugar using bacteria. It quickly disperses and creates a viscous and stable solution when added to a liquid for providing a thickness or stabilizing effect to a product. It assists in improving the texture, flavour, consistency, appearance, and shelf life of a product. It aids in preventing food products from separating and allowing them to flow smoothly and can lower blood sugar levels among individuals. It also reduces cholesterol levels, slows digestion, supports weight loss management, and treats dry mouth problems.
Titanium sponge is a highly porous, lightweight form of titanium metal produced through the Kroll process. It is the major raw material in the production of titanium alloys in industrial, automotive, medical implant, and aerospace applications. For high-performance industries, titanium sponge is an indispensable component as it has a very high strength-to-weight ratio, is resistant to corrosion, and is biocompatible. It is prepared by reducing titanium tetrachloride (TiCl4) with magnesium, followed by purification and processing to produce titanium compounds that can be used.
Urea is a nitrogenous compound produced in living organisms as a byproduct of the metabolism of protein degradation. In industrial and agricultural use, urea is a synthetic compound produced on a large scale for use as a fertilizer. Urea is a critical source of nitrogen that helps to enhance plant growth and development. Its high content of nitrogen makes it popular in the agricultural sector and serves as a concentrated, readily available source of nitrogen for crops. Besides being a fertilizer, urea also has several industrial uses, such as the manufacture of adhesives and some resins, as well as plastics.
Active dry yeast is a dehydrated form of yeast commonly used in baking and fermentation. Its dormant yeast cells spring to life when they are rehydrated with warm water. In bread-making, brewing, and other fermentation operations, active dry yeast is frequently employed due to its extended shelf life and convenience of storing. It aids in flavour development and raises dough by generating carbon dioxide. It is a necessary component of both commercial and home baking due to its dependability and convenience.
Ethylene-vinyl alcohol, commonly referred to as EVOH, is an extraordinary polymer with outstanding properties that have revolutionized applications in packaging, industrial, and medical fields. The copolymer consists of alternating ethylene and vinyl alcohol monomer units, which result in the unique gas barrier property that makes EVOH a strong contender for food packaging applications.
Ethylene propylene diene monomer (EPDM) is an adaptable synthetic rubber with unique performance properties. It is a copolymer of ethylene, propylene, and diene monomers and is manufactured through suspension, solution polymerization, or gas-phase polymerization processes. It is commonly used in belts, window and door seals, tubing, roofing membrane, non-slip coatings, radiator, drain tubes, and trunk seals.
Ferrosilicon, an iron alloy made of silicon and iron, is a very versatile alloy that is used in many different industries, especially the steel and casting industries. Its composition can vary, with silicon content ranging from 15% to 90%, depending on the application and desired properties.
Polytetrafluoroethylene (PTFE) refers to a tough, waxy and non-flammable synthetic resin that consists of carbon and fluorine atoms. It is manufactured through the free-radical polymerization process of chloroform, fluorspar and hydrochloric acid. PTFE is usually used to give a non-stick coating to surfaces, especially cookware, such as pans and baking trays and industrial products.
Collagen in the connective tissues, bone, and skin of cows and pigs contains gelatin. A common method for creating this colourless, odourless animal protein is to boil ligaments, tendons, and skin in water. Its outstanding physical characteristics include low viscosity, dispersion stability, high affinity, and dispersibility.
Electrolytic manganese dioxide (EMD) is made by dissolving manganese dioxide in sulfuric acid and placing between two electrodes. Manganese dioxide, also referred to as Manganese (IV) oxide, is an inorganic compound that is commonly found in blackish or brown solid and is insoluble in water. EMD is a highly refined form of MnO2 designed to meet the specific electrical requirements of battery manufacturers.
Electrolytic manganese metal is a pure form of the metallic element manganese, Mn concentration ranges from 99.7% to 99.9%. It is termed "electrolytic" because the refining process involves electrolysis. In other words, a chemical reaction powered by an electric current. Heating the ore and applying chemical processes to remove most impurities is the first steps in the processing of manganese.
Ethanol is a renewable biofuel produced primarily from crops such as corn, sugarcane, and biomass. It is often added to fuel to lower carbon emissions and improve energy security. Additionally, ethanol is used in the beverage, chemical, and pharmaceutical sectors. Ethanol is becoming more popular as a cleaner substitute for fossil fuels due to the rising need for sustainable energy solutions, which is propelling improvements in biofuel technology and production efficiency.
Widely recognized for its superior mechanical, chemical, and thermal properties, unsaturated polyester resin (UPR) is a highly versatile thermosetting polymer utilized across multiple industries. UPR is created when unsaturated acids and glycols react mostly used in composites, coatings, and adhesives.
Sodium cyanide (NaCN) is a highly toxic, colorless crystalline compound with a faint almond-like odor. It is a water-soluble salt composed of sodium (Na+) and cyanide (CN-) ions, known for its versatile applications across various industrial sectors. Despite its hazardous nature, sodium cyanide is extensively used due to its unique properties and efficacy in specific processes.
Caustic soda is the common term for sodium hydroxide (NaOH), a versatile alkali widely used in industries such as chemicals, textiles, pulp and paper, detergents, and water treatment. Sodium hydroxide is known to have strong alkaline properties. It is employed in manufacturing processes such as saponification, pH regulation, and chemical synthesis, making it essential for diversified industrial applications.
Citric acid is a naturally occurring weak organic acid found in citrus fruits, widely used for its sour taste, preservative properties, and acidity regulation. Industrially, it is produced through the fermentation of sugars and is a key ingredient in the food and beverage industry, where it enhances flavor and preserves freshness. Additionally, it has applications in pharmaceuticals, cosmetics, and cleaning products due to its ability to stabilize ingredients and chelate metals.
Calcium stearate, a key chemical compound, holds significant importance across various industries due to its multifunctional properties. Comprising calcium and stearic acid, it serves as a versatile additive and processing aid. As a widely utilized stabilizer and lubricant in the manufacturing of plastics, rubber, and pharmaceuticals, calcium stearate plays a pivotal role in enhancing material properties and processing efficiency.
Calcium hypochlorite is a powerful chemical compound, widely used in many different applications and industries. This white solid, made up of calcium, oxygen, and chlorine, contains excellent chlorine content with a strong oxidation capability. Being an oxidizing agent that gives out chlorine when dissolved in water, it is in huge demand for the treatment, sanitation, and disinfection of water.
Nitrocellulose, also known as cellulose nitrate or guncotton, is a chemically modified form of cellulose known for its exceptional film-forming capabilities, strong adhesion, and biodegradability. It is widely used in applications such as wood coatings, printing inks, leather finishes, automotive paints, nail varnishes, and more.
The growth of the copper wire market is primarily driven by increased electricity demand, heightened investments in construction, expansion of electrical infrastructure, the rise of renewable energy, a shift toward electric vehicles in the automotive industry, and the growing adoption of electric appliances. The development of smart grids and investments in upgrading power transmission systems further boost global copper wire demand. Additionally, the telecom industry's use of copper in optic fiber cables and infrastructure development in emerging markets, especially in Asia Pacific and Latin America, are expected to sustain high demand for copper wire in the coming years.
Urea, also known as carbamide, is an organic compound with the formula CO(NH2)2. It is a highly versatile and widely used chemical, primarily known for its role in agriculture as a nitrogen fertilizer. Urea is available in various grades, including fertilizer grade, feed grade, and technical grade, and is used in a wide range of applications, such as nitrogenous fertilizers, stabilizing agents, keratolytic, and resins, among others. Key industries that utilize urea include agriculture, chemicals, automotive, and medical sectors.
Lithium-ion batteries are rechargeable power sources widely used in devices such as cell phones, laptops, and electric vehicles. These batteries store energy by transferring lithium ions between the anode and cathode electrodes, with the electrolyte facilitating this movement and generating free electrons at the anode. Key types of lithium-ion batteries include those with lithium cobalt oxide, lithium iron phosphate, lithium nickel manganese cobalt, and lithium manganese oxide. Lithium-ion batteries come in a range of capacities from 0 mAh to 6000 mAh. They offer several advantages, including a high energy-to-weight ratio, excellent charge retention, and generally longer lifespans with more charge/discharge cycles compared to other rechargeable batteries.
Brazil is renowned across the world for its enormous rainforests and agricultural resources. Over the recent years, the country has emerged as a major player in the global cellulose industry. As per IMARC estimates, the cellulose fiber market in Brazil was valued at US$ 740.4 Million in 2023. By 2032, the market is projected to reach US$ 1,379.9 Million, growing at a CAGR of 7.0% from 2024 till 2032. Strategic investments in the industry, along with favorable environmental conditions, are guiding a cellulose revolution in Brazil, which is likely to have profound implications for both regional and international markets.
Green chemistry refers to the practice of creating new chemicals, materials, and processes that are less toxic to human health and the environment. It comprises the utilization of renewable resources and reducing waste and energy consumption. Green chemicals are used in various applications such as industrial and chemical, food and beverages, automotive, packaging, construction, agriculture, personal care, and many others. Nowadays, different types of green chemicals are available in the market, including bio-alcohol (bioethanol, bio-butanol, bio-methanol, and many others), bio-organic acids (bio-lactic acid, bio-acetic acid, bio-citric acid, bio-adipic acid, bio-acrylic acid, bio-succinic acid, and others), biopolymers (poly-lactic acid, bio-polyethylene, and others), bio-ketones, bio-solvents, and many other organic acids.
Vanadium has been discovered in sediment samples collected from the Gulf of Khambhat, which opens into the Arabian Sea off Alang in Gujarat. This discovery is expected to enhance the production of steel and titanium in India and boost redox battery manufacturing. Vanadium is one of the most abundant transition metals and is typically found in various minerals, including vanadinite, patronite, and carnotite. It is a hard, ductile, and rare grey metal, often extracted as a byproduct while processing other metals such as iron and uranium.
Steel is a versatile and widely used alloy composed primarily of iron and carbon, with small amounts of other elements such as manganese, chromium, nickel, and others. It is a widely utilized material in construction, manufacturing, and various industries. Steel exhibits a range of desirable properties, including high tensile strength, durability, hardness, corrosion resistance, heat resistance, and the ability to be formed into different shapes. Carbon steel, alloy steel, stainless steel, and tool steel are the main types of steel. Steel is utilized in the manufacturing of various products, including ingots, semi-finished materials, hot-rolled sheets and coils, galvanized sheets, steel tubes and fittings, plates, wire rods, and many others. Its applications span various industries such as building and construction, electrical appliances, metal products, automotive, transportation, and mechanical equipment. The top five exporters of steel are China, Japan, South Korea, and Germany. Similarly, the major importers of steel include the United States, Germany, Italy, and Turkey.
Copper is an essential material in electrical wiring, electronics, and heating systems. It is also highly ductile and malleable, allowing it to be easily shaped and drawn into thin wires. Additionally, copper possesses antimicrobial properties, making it useful in medical and architectural applications. Its resistance to corrosion and its ability to form alloys with other metals further enhance its versatility across various industries.