Coffee Packaging Market: Trends Reshaping Growth, From Compostable Pods to Resealable Pouches
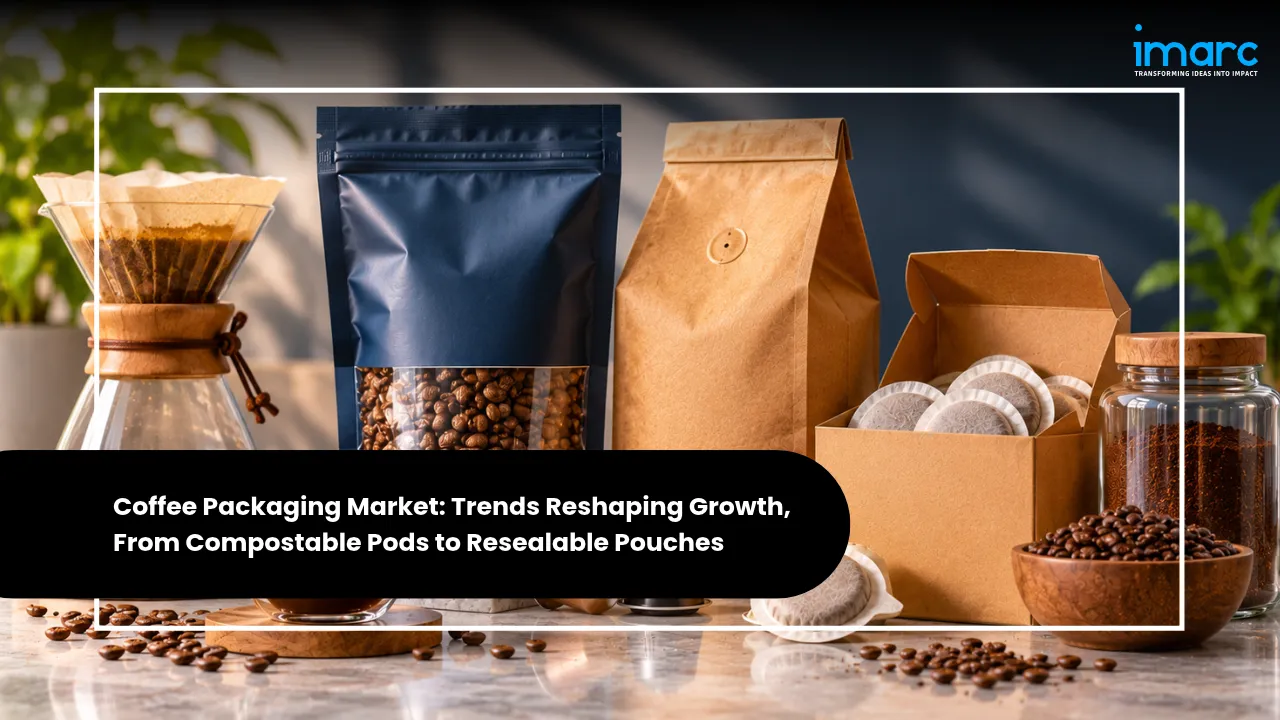
Introduction: Trends Reshaping the Coffee Packaging Market
The global coffee packaging market size reached USD 910.9 Million in 2025 and is projected to climb to USD 1,388.1 Million by 2034, registering a CAGR of 4.65% during 2026-2034. That trajectory is moderate by consumer-packaging standards, but it understates how much structural change is compressed into it. Volume growth is incremental; the mix of formats, materials and compliance features inside that volume is changing considerably faster.
Demand is being pulled by four forces: the need to protect aroma and freshness in a product that degrades quickly on exposure to oxygen, moisture and light; convenience formats suited to single-serve brewing and smaller households; premiumisation, which turns packaging into a carrier of origin, roast and provenance information; and the expansion of online coffee sales, where a pack must survive shipping and still present well on arrival. Each of these raises the technical content of a pack, and therefore its value per unit.
The most consequential shift, however, is regulatory. Single-serve coffee pods have moved to the centre of packaging law. Under the EU Packaging and Packaging Waste Regulation, permeable tea and coffee bags and single-serve units must be compostable from 12 February 2028, and Member States may extend that requirement to non-permeable formats. Industry has already begun moving early. In late 2025, coffee brands and retailers representing more than 90% of pods sold in Belgium committed to sell only industrially compostable pods from 12 August 2026, eighteen months ahead of the legal deadline, a step expected to divert roughly 4,600 tonnes of pod waste a year into organic collection.
At the same time, the resealable pouch has consolidated its position as the workhorse retail format, absorbing one-way degassing valves, mono-material recyclable structures and high-quality print. This blog works through the coffee packaging market trends behind that reconfiguration, covering market size and shares, recent announcements, regional hotspots, competitive strategy and the regulatory pressures that will shape 2026 and beyond.
Key Takeaways
- The coffee packaging market was valued at USD 910.9 Million in 2025 and is forecast to reach USD 1,388.1 Million by 2034, growing at 4.65% CAGR between 2026 and 2034.
- Metal holds the largest share of the market by packaging material, sitting inside a market that adds roughly USD 477.2 Million in absolute value over the forecast window.
- Europe is the largest regional market, and it is also where compliance deadlines arrive first, with the EU packaging regulation applying from 12 August 2026.
- The most notable recent development was Sonoco's completion of the Eviosys acquisition on 4 December 2024 for approximately USD 3.9 billion, lifting EMEA to more than 40% of company sales and creating the world's largest metal packaging manufacturer.
- The defining trend is the shift from voluntary sustainability claims to legally enforced format rules, as compostable pods move from pilot programmes to a 12 February 2028 compliance deadline in the EU.
Market Size, Share & Growth Outlook
According to IMARC Group, the global coffee packaging market stood at USD 910.9 Million in 2025 and is forecast to reach USD 1,388.1 Million by 2034, growing at a CAGR of 4.65% over 2026-2034, which implies an absolute addition of about USD 477.2 Million in market value across the forecast window. A rate of this order describes a mature, replacement-driven market in which growth comes from format upgrades, material substitution and packaging intensity per unit of coffee sold, rather than from a sudden surge in consumption. The leading segments are:
- Packaging Type: Pouches anchor the format mix and are identified in the report as the preferred choice on account of convenience, versatility and airtight sealing, with side gusseted bags and block bottom bags holding the premium and shelf-ready tiers where barrier performance and print area matter most.
- Packaging Material: Metal holds the largest share of the market by material, valued for exceptional barrier properties against oxygen and light, durability through the distribution chain, and the high recyclability of aluminium.
- Application: Retail sales represent the largest application segment, supported by at-home consumption, branding requirements and the growth of direct-to-consumer and e-commerce channels; institutional sales form the smaller, contract-driven counterpart.
- Region: Europe is the largest regional market, reflecting deep-rooted coffee culture, an emphasis on premium and single-origin products, and the most advanced sustainability regulation anywhere in the world.
These four dimensions together define the coffee packaging market share structure, and they are increasingly read as one decision rather than four. A roaster choosing a pouch format is simultaneously choosing a material, a recyclability class and a fee band under producer responsibility rules, so format and material strategy can no longer be separated.
Recent News & Mega Announcements
The 2024 to 2026 period produced a cluster of regulatory and corporate events that reset the supply side of the market. The most consequential were:
- EU packaging regulation enters into force (February 2025): Regulation (EU) 2025/40 was adopted on 19 December 2024, entered into force on 11 February 2025 and applies from 12 August 2026, with permeable coffee bags and single-serve units required to be compostable from 12 February 2028 and all packaging required to be recyclable by 2030. For pod and pouch converters, this converts a design preference into a market-access condition.
- Belgian suppliers advance compostability by 18 months (late 2025): Coffee brands and supermarket chains representing more than 90% of pods sold in Belgium committed to commercialise only industrially compostable pods from 12 August 2026 instead of waiting for the 12 February 2028 statutory deadline, a move expected to divert approximately 4,600 tonnes of pod waste annually from residual to organic streams. The applicants noted that around 80% of pods sold were already compostable, which shows how quickly a voluntary standard can become a de facto requirement.
- Amcor completes the Berry Global merger (April 2025): Amcor closed its all-stock combination with Berry Global on 30 April 2025, a transaction valued at approximately USD 10.4 billion, with management targeting about USD 650 million in annual pre-tax synergies by fiscal 2028. Consolidation at this scale changes the bargaining position of converters relative to roasters, particularly in flexible film supply.
- Sonoco completes Eviosys and rebrands the business (December 2024 to April 2025): Sonoco closed its acquisition of Eviosys on 4 December 2024 for approximately USD 3.9 billion and relaunched the unit as Sonoco Metal Packaging EMEA on 2 April 2025, expanding EMEA from 14% to more than 40% of company sales across 45 metal packaging plants in 17 countries. The deal strengthens the metal can and tin tier that premium and institutional coffee brands rely on.
- UK Plastic Packaging Tax rate rises (April 2025): The tax rose to £223.69 per tonne from 1 April 2025 and applies to plastic packaging components containing less than 30% recycled content. For coffee films, where barrier layers complicate recycled content, the tax functions as a recurring cost signal in favour of mono-material and recycle-ready structures.
Industry Trends Shaping 2026
Three structural trends define the 2026 outlook, and each of them changes capital allocation decisions rather than merely product design.
1. Compostable Pods Move From Pilot to Compliance Deadline
Compostable capsules have existed commercially for years, but until recently they competed against aluminium and polypropylene pods on convenience and cost rather than on legality. The EU packaging regulation changes the terms of that contest: permeable coffee bags and single-serve units must be compostable from 12 February 2028, with Member States able to extend the requirement to non-permeable formats. Because the deadline is fixed and the format is standardised, the decision is no longer whether to convert but how fast to do so without losing brew quality.
The engineering constraint is the pack itself. A pod must hold pressure during extraction, resist moisture ingress during storage and degrade in an industrial composting environment within the window defined by EN 13432. That combination pushes converters toward polylactic acid blends, starch-based compounds and fibre-based bodies with compostable filter layers, and it raises the importance of oxygen transmission rate testing at the design stage rather than at the end of the line.
The Belgian commitment illustrates the commercial logic. Suppliers covering over 90% of the national pod market moved the date forward to 12 August 2026, and the Flemish waste agency linked revised household sorting instructions to industry-wide compostability. That sequencing matters: compostable packaging delivers no environmental benefit unless the collection system separates it, so brands that move first also shape the sorting rules that follow.
2. Resealable Pouches and Degassing Technology Set the Retail Standard
The resealable pouch has become the default retail format because it solves three problems at once. A reseal closure preserves freshness between uses and reduces household waste; a one-way degassing valve releases carbon dioxide from freshly roasted beans while blocking oxygen ingress; and the flat or block bottom profile gives brands shelf presence and a printable surface large enough for origin, roast and brewing information. IMARC identifies pouches as the leading format on convenience and versatility, with side gusseted bags and block bottom bags serving the premium end of the same demand.
The technical frontier has shifted to combining that functionality with recyclability. Multi-material laminates deliver excellent barrier performance but are difficult to recycle, and they now attract higher producer responsibility fees and, in some markets, tax exposure. The response is mono-material polyethylene and polypropylene structures, barrier coatings and paper-based laminates with thin functional layers, all of which must still meet shelf-life targets measured in months.
Resealability is also becoming an e-commerce requirement rather than a retail nicety. As roasted coffee moves through subscription and direct-to-consumer channels, packs must resist compression and handling damage while remaining easy to open and reclose, which is pushing converters toward higher puncture resistance and more robust zipper profiles on the same film structure.
3. Recycled Content, Lightweighting and Cost-Signal Design
The third trend is the quietest and probably the most pervasive: packaging design is being optimised against fee schedules, not just against material cost. Extended producer responsibility systems under the EU packaging regulation modulate fees by weight and recyclability, and national taxes such as the UK Plastic Packaging Tax apply directly to plastic components with less than 30% recycled content. Each of these converts a gram of material and a percentage point of recycled content into a recurring line item.
The practical effect is lightweighting with a purpose. Converters are reducing film thickness where barrier performance allows, eliminating unnecessary secondary packaging, and substituting paper or fibre where the product does not need an absolute oxygen barrier. Metal retains an advantage in this environment because aluminium is recyclable at scale and carries a well-established secondary market, which is one reason it continues to hold the largest share by material despite competition from flexible formats.
There is a limit to how far this optimisation can go without performance loss. Coffee is unusually sensitive to oxygen, and a film that is 20% lighter but lets through marginally more oxygen can shorten shelf life enough to increase retail waste. The credible position for converters is therefore evidence-based: barrier data, recyclability certification and compostability testing presented alongside the commercial proposal, because brand owners increasingly need that documentation to register packaging and declare conformity.

Geographic Hotspots
Europe is the largest regional market for coffee packaging, and it is also the most demanding. Deep-rooted coffee culture across Italy, Germany, France, Spain and the United Kingdom sustains high consumption of roasted and ground, whole bean and single-serve formats, while premiumisation has pushed specialty roasters to differentiate on print quality, origin labelling and valve performance. Regulation compounds the effect: the EU packaging regulation applies directly from 12 August 2026, sets a 2030 recyclability obligation and permits national compostability requirements for single-serve units. No other region combines consumption depth, premiumisation and regulatory stringency to the same degree, which is why Europe anchors the coffee packaging market.
North America is the second major arena and the most pod-dependent. Single-serve formats are embedded in household routines, large-format club packs dominate grocery, and a fast-growing specialty segment buys on roast date and origin. The regulatory direction differs from Europe: rather than compostability mandates, the pressure comes from state-level recycling and packaging producer responsibility rules, which favour recyclable polypropylene and mono-material designs over compostable ones. That divergence means a pod structure approved in one market is not automatically deployable in the other, and dual-tooling is now a normal cost of doing business for multinational brands.
Asia Pacific is the fastest-changing region in the global coffee packaging industry. Japan and South Korea maintain strong canned and bottled coffee cultures that support metal and glass formats, while China, India, Indonesia and Australia are seeing café culture, instant coffee premiumisation and e-commerce expansion simultaneously. The result is a market where sachets, stick packs and small-format pouches coexist with premium whole-bean bags, and where local converting capacity rather than imported stock increasingly determines pack economics.
Latin America, led by Brazil and Mexico, combines producing-country dynamics with rising domestic consumption, which supports bulk sacks and institutional formats alongside retail pouches. The Middle East and Africa remains the smallest region but shows steady demand growth through institutional channels, hospitality and traditional cardamom-accented coffee formats, where metal tins and rigid containers retain cultural and functional relevance. Across all regions, the common thread is that packaging decisions are becoming local compliance decisions as much as consumer decisions.
Competitive Landscape & Key Players Strategies
The competitive landscape is moderately concentrated at the top and fragmented below it. A small group of global converters controls film, laminate and metal capacity, while hundreds of regional printers and pouch specialists serve local roasters. IMARC reports that leading players have converged on a similar strategic agenda: compostable and biodegradable material development, one-way degassing valves and high-barrier structures, resealable and portion-control convenience features, premium print and design collaboration, customisation across sizes and formats, and shipping-robust packaging for online sales. The coffee packaging market analysis below summarises how the largest suppliers are positioned.
- Amcor Limited: Completed its merger with Berry Global on 30 April 2025, creating a combined group with about USD 24 billion in revenue, and is targeting roughly USD 650 million in annual pre-tax synergies by fiscal 2028; the combined portfolio spans flexible films and rigid containers, which allows cross-selling across pod lids, pouch laminates and closures.
- Constantia Flexibles Group GmbH: Concentrates on high-barrier flexible laminates and mono-material, recycle-ready structures for coffee and other dry goods, positioning itself on the compliance documentation that brand owners now require for registration.
- Goglio S.p.A.: A specialist in one-way degassing valves and integrated valve-plus-film systems, a component niche that grows more valuable as roasters extend shelf life and as recyclable films require redesigned valve interfaces.
- Graham Packaging Company: Focuses on rigid and container formats, relevant to ready-to-drink coffee and to brands seeking reusable or refillable packaging systems.
- Huhtamaki Oyj: Leans on fibre and paper-based formats, a portfolio that benefits directly from substitution away from multi-material laminates in markets with weight-based fees.
- ProAmpac: Positions around recyclable flexible packaging and short-run print capability, serving both private label and specialty roasters.
- Roastar Inc.: Built around digital printing and low minimum order quantities, which suits the specialty segment where roast-date freshness and frequent label changes matter more than unit cost.
- Sonoco Products Company: Became the world's largest metal packaging manufacturer after closing the Eviosys acquisition on 4 December 2024 for approximately USD 3.9 Billion, with 45 metal plants in 17 countries, strengthening its position in coffee tins, cans and closures.
- Swiss Pack: A pouch-focused converter serving specialty coffee with stand-up and flat-bottom formats, where print quality and reseal performance drive the purchase decision.
- WestRock Company: Strings fibre-based cartons, paperboard and protective packaging, now within the Smurfit Westrock group after the 2024 combination, and is relevant to gift packs, multipacks and e-commerce shipper design.
The strategic pattern is consolidation at the material and platform level combined with specialisation at the format level. Large converters are buying scale to absorb compliance costs and resin volatility; smaller players are competing on speed, print and service to roasters who cannot place container-scale orders.
Policy & Regulatory Landscape, Challenges & Risks
Government policy has become a primary market force in coffee packaging, and it now determines which structures can be sold in which market. Key frameworks include:
- EU Packaging and Packaging Waste Regulation (EU) 2025/40: Adopted on 19 December 2024, in force from 11 February 2025 and directly applicable from 12 August 2026, it requires all packaging to be recyclable by 2030, mandates compostability for permeable coffee bags and single-serve units from 12 February 2028, introduces harmonised material labelling and a declaration of conformity, and restricts certain single-use formats from 2030. For coffee packers, the practical consequence is that every pouch and pod structure must be requalified against recyclability or compostability criteria within the current investment cycle.
- Extended producer responsibility and national packaging registers: The regulation obliges producers to register in each Member State where packaging is first placed on the market and to report volumes by material and format, with fees funding collection, sorting and recycling. Because fees are modulated by weight and recyclability, they create a continuous financial incentive to lightweight and to move to mono-material structures, and they make packaging data management a compliance function in its own right.
- UK Plastic Packaging Tax: Applied at £223.69 per tonne from 1 April 2025 to plastic packaging components containing less than 30% recycled content, with a de minimis threshold for small producers. For coffee films, where barrier layers have historically limited recycled content, the tax effectively subsidises the shift to mono-material and recycle-ready designs.
- National compostability mandates and early industry adoption: Member States may require compostable single-serve units and non-permeable coffee bags, and Belgium shows how quickly that discretion can become a market standard, with brands and retailers covering more than 90% of national pod sales committing to exclusively compostable pods from 12 August 2026, ahead of the 12 February 2028 deadline, diverting approximately 4,600 tonnes of waste annually.
On the constraining side, several structural risks persist:
- Resin and aluminium price volatility: Coffee packaging is a thin-margin conversion business in which polymer and aluminium costs pass through with a lag, so a sustained input spike compresses converter margins and forces brand owners into reformulation at short notice, which in turn risks re-testing already approved structures.
- Performance and cost limits of compostable materials: Compostable substrates typically offer narrower processing windows and weaker moisture barriers than conventional laminates, and they cost more per unit at current volumes; a pod that fails to hold pressure during extraction or shortens shelf life undermines the very freshness promise the packaging exists to deliver.
- Collection and composting infrastructure gaps: Compostability only delivers environmental value where industrial composting capacity and separate collection exist, and coverage varies widely across and within countries; without sorting instructions aligned to industry-wide adoption, compostable pods simply enter residual waste and the regulatory rationale weakens.
- Compliance cost concentration and regulatory fragmentation: Conformity assessment, testing, registration and labelling impose fixed costs that weigh most heavily on small and mid-sized specialty roasters, while differing national interpretations of compostability and labelling rules force separate stock-keeping units for what is functionally the same pack, raising inventory and tooling costs.
Forecast 2026-2034
The coffee packaging market forecast points to USD 1,388.1 Million by 2034, up from USD 910.9 Million in 2025, a 4.65% CAGR across the intervening years. Expressed in absolute terms, the market adds roughly USD 477.2 Million in value over the period, which is a meaningful increment for a category where unit volumes grow only in line with coffee consumption and household formation. Most of that value therefore has to come from price and mix: higher-specification barrier films, compostable pod components, decorated premium pouches and metal formats that carry a higher value per kilogram than commodity alternatives.
Segment composition is likely to shift faster than the headline rate. Compostable pod components should see the steepest expansion between 2026 and 2028 as the EU deadline approaches and as early adopters such as the Belgian market normalise industrial compostability. Mono-material and recycle-ready pouch structures should take share within the flexible segment as producer responsibility fees and recycled-content rules bite. Metal is expected to defend its leading share by material, supported by aluminium's recyclability, its barrier performance and the consolidation of capacity following recent acquisitions.
Regional growth should remain uneven. Europe will continue to set the compliance agenda and to generate the highest value per pack, while Asia Pacific offers the strongest volume upside as coffee consumption rises across China, India, Indonesia and Southeast Asia. North America will grow steadily on the strength of single-serve and club formats, with recyclability rather than compostability as the organising principle. The principal downside risks to this forecast are a delay or dilution in national implementation of the packaging rules and a sustained polymer cost shock, both of which would push conversion investment into later years rather than cancel it.
Opportunities for Stakeholders
- Converters with proven mono-material platforms: brand owners need recycle-ready films that meet existing shelf-life targets, and suppliers able to supply barrier data and recyclability certification alongside the film can win multi-year qualification contracts as registration deadlines approach.
- Compostable pod capacity built ahead of 2028: With the EU deadline fixed and the Belgian market moving to exclusively compostable pods from 12 August 2026, converters that commission capacity early can lock in supply agreements before demand peaks and before tooling lead times lengthen.
- Valve and closure specialists: As recyclable and compostable films behave differently from conventional laminates, degassing valve interfaces need redesign, which creates a component-level opportunity for specialists such as Goglio and for closure suppliers serving rigid formats.
- Digital print providers serving specialty roasters: Short runs, frequent label changes and roast-date freshness favour digital printing, and small roasters facing rising compliance fixed costs will increasingly outsource decoration rather than invest in plates.
- Metal packaging suppliers targeting premium and institutional channels: Aluminium's recyclability and barrier performance align well with fee structures that reward recyclable materials, opening share gains in gift packs, foodservice and hospitality formats.
- Material innovators in fibre and coated paper: Substitution away from multi-material laminates in markets with weight-based fees creates room for paper-based structures where an absolute oxygen barrier is not essential, particularly in instant coffee and single-serve sachets.
- Compliance and data service providers: Registration, volume reporting, conformity documentation and compostability testing are becoming recurring operational needs for roasters of every size, and few mid-sized brands have the capability in house.
Coffee Packaging Market at a Compliance Turning Point
The coffee packaging market is not growing quickly, and it does not need to. At USD 910.9 Million in 2025 rising to USD 1,388.1 Million by 2034, at a 4.65% CAGR, the value of the category will be determined less by how much coffee is packed and more by what the pack is made of, how it is certified and how easily it can be collected and reprocessed. The two formats that define this phase, the compostable pod and the resealable high-barrier pouch, are both responses to the same pressure: packaging must now perform as infrastructure as well as marketing.
The regulatory calendar is unusually clear. The EU packaging regulation applies from 12 August 2026, compostability for coffee pods and permeable bags follows on 12 February 2028, and recyclability for all packaging is required by 2030. Industry has begun to move ahead of those dates, as the Belgian pod commitment shows, and the supply side has consolidated to fund the transition, with Amcor's combination with Berry Global and Sonoco's acquisition of Eviosys reshaping capacity in flexible films and metal respectively. For roasters, converters and material suppliers, the decisive question over the next three years is not whether to convert formats, but how to do so without losing the freshness performance on which the entire category's premium rests.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

A Potato Starch Manufacturing Plant Setup in India builds on the country's position as the world's second-largest potato producer. Potato starch is a fine, white, neutral-tasting powder extracted from potatoes, valued for its high viscosity, clear gels, binding strength, and clean flavour.
A Mineral Water Processing Plant Setup in India serves one of the most essential and fastest-growing consumer categories in the country.
Setting up a Sugar Manufacturing Plant in India means entering one of the country's largest and most policy-shaped agro-industries.
A Ghee Manufacturing Plant Setup in India builds on one of the country's most trusted and widely consumed dairy products. Ghee, or clarified butter, is made by heating butter or cream until the water evaporates and the milk solids separate, leaving a golden, aromatic fat with a long shelf life.
A Cashew Nut Manufacturing Plant Setup in India builds on one of the country's oldest and most export-oriented agro-processing industries.
Setting up a Whey Protein Powder Manufacturing Plant in India addresses a striking gap in the world's largest milk-producing nation. India produces close to 250 million tonnes of milk a year, yet it imports an estimated 80 to 90% of the supplement-grade whey used by its fast-growing sports nutrition and protein brands.
The Indian animal feed market is being reshaped less by what happens inside a feed mill than by what appears on Indian dinner plates. According to IMARC Group, the market was valued at INR 1,186.30 Billion in 2025 and is projected to reach INR 2,112.96 Billion by 2034, expanding at a CAGR of 6.6% over 2026-2034.
Setting up a Pectin Manufacturing Plant in India is a timely, import-substitution opportunity in a fast-growing food ingredients segment.
Peanut spread is a smooth or crunchy paste made by roasting, skinning, and grinding groundnuts, often with a little salt, sugar, and a stabiliser. It is rich in protein and healthy fats, and in India it has moved from a niche import to an everyday breakfast and fitness food sold through supermarkets, pharmacies, gyms, and online stores.
The organic and natural pet food market has moved from a specialist shelf in independent pet stores to a structural growth engine inside global pet care. According to IMARC Group, the global natural pet food market reached USD 33.6 Billion in 2025 and is projected to reach USD 59.4 Billion by 2034, expanding at a CAGR of 6.33% during 2026-2034.
Edible oils are produced by pressing and solvent-extracting oilseeds such as soybean, mustard, groundnut, and sunflower, or by importing crude palm, soybean, and sunflower oil, and then refining them through degumming, bleaching, and deodorisation to remove impurities, colour, and odour before packing them for homes, restaurants, and food processors.
Club soda is purified water chilled and charged with food-grade carbon dioxide under pressure, then filled into PET bottles, glass bottles, or cans and sealed so that it keeps its fizz until opened.
Ice cream is a frozen dairy dessert made by pasteurising and homogenising a mix of milk, cream, sugar, stabilisers, and flavours, then freezing it while whipping in air and hardening it at very low temperatures.
CNSL, the dark, viscous liquid held in the honeycomb of the cashew shell, is recovered by pressing shells left over from kernel processing and then heating the crude liquid so that its anacardic acid turns into cardanol.
Ground spices and blended masalas turn whole chilli, turmeric, coriander, cumin, pepper, and other spices into clean, safe, ready-to-use powders and mixes for homes, restaurants, food processors, and export buyers.
Fishmeal is a brown, protein-rich powder made by cooking, pressing, drying, and grinding small oily fish and fish processing waste, with fish oil recovered as a valuable co-product.
Dried banana ingredients are made by washing, peeling, and slicing fresh fruit, treating it to prevent browning, drying it in belt, tray, or spray dryers, and milling it into a fine, shelf-stable product.
Dried egg is made by breaking fresh eggs, pasteurising the liquid whole egg, yolk, or white, and spray drying it into a fine powder that keeps for a year or more without refrigeration.
Whey is the liquid left after milk is made into cheese or paneer, and it contains high-quality proteins that can be separated by membrane filtration and spray dried into concentrates and isolates.
The pectin market has moved from the back of the ingredient label to the centre of product development strategy. As food manufacturers strip out synthetic gelling agents, stabilisers and thickeners, pectin has become one of the few hydrocolloids that can deliver texture and shelf stability while still reading as a familiar, fruit-derived ingredient.
Poultry processing turns live broilers into hygienically slaughtered, chilled, cut, and packed meat, ready for retail shelves, restaurants, quick-service chains, caterers, and export. India produced about 10.5 million tonnes of meat in 2024-25, and poultry made up roughly half of it at 5.18 million tonnes, yet around 85% of birds are still sold live or slaughtered in small wet-market shops.
The global tomato ketchup market reached USD 20.8 Billion in 2025 and is projected to reach USD 26.3 Billion by 2034, growing at a CAGR of 2.68% during 2026-2034, according to IMARC Group. Those numbers describe a mature, high-volume condiment category rather than a fast-growing one.
Coconut shell powder is made by cleaning, drying, crushing, and finely grinding the hard inner shell of the coconut into a uniform powder. Because the shell is dense, rich in lignin, low in ash, and slightly oily, the powder is an excellent natural filler.
Dextrins are modified starches made by heating dry starch, usually with a small amount of acid, so that its long molecules break into shorter ones. The result is a powder that dissolves easily in water and forms strong, quick-drying adhesive films.
Fruit powders are made by drying fruit pulp or juice into a fine, free-flowing powder that keeps the flavour, colour, and much of the nutrition of fresh fruit while lasting months without refrigeration.
Yeast is a living microorganism that makes bread rise, ferments beer, wine, and spirits, turns sugar into fuel ethanol, and supplies protein, vitamins, and flavour to food, feed, and nutrition products.
The global champagne market is entering a phase where value growth matters more than volume growth. IMARC Group values the market at USD 6.6 Billion in 2025 and projects it to reach USD 8.1 Billion by 2034, expanding at a CAGR of 2.25% during 2026-2034.
India is one of the world's leading coffee producers and exporters, growing shade-grown arabica and robusta in the hills of Karnataka, Kerala, and Tamil Nadu and supplying green, roasted, and instant coffee to more than 100 countries.
The Australia Online Grocery Industry has crossed the point where volume growth is the scarce commodity. What is scarce now is profitable volume. According to IMARC Group, the market reached USD 17.22 Billion in 2025 and USD 21.91 Billion in 2026, and is projected to reach USD 96.59 Billion by 2034, expanding at a CAGR of 20.37% (2026–2034), a more than five-fold expansion in under a decade. That growth is unfolding inside one of the most closely regulated grocery markets in the developed world.
Baby formula, also known as infant formula, is a manufactured food product designed to serve as a substitute for or supplement to human breast milk for infants and young children up to three years of age.
Palm oil is the world's most widely used vegetable oil, extracted from the fruit of the oil palm and used in cooking oils, vanaspati, bakery fats, snacks, soaps, cosmetics, and oleochemicals, while the kernel yields palm kernel oil and cake.
Beer is one of the world's most widely consumed drinks, brewed from malted barley, water, hops, and yeast, often with rice or maize as adjuncts. In India, beer accounts for only a small share of alcohol consumption compared with most countries, but that is changing as a young, urban, and increasingly female consumer base embraces lighter drinks, premium lagers, wheat beers, and craft styles.
Bread, buns, rusk, cakes, cookies, and biscuits are part of daily meals and snacking in almost every Indian household, from metro cities to small towns.
Makhana has moved from a pond crop traded through village aggregators into a branded snack with its own export code and a national board behind it. According to IMARC Group, the India makhana market was valued at INR 9.29 Billion in 2025 and is projected to reach INR 19.95 Billion by 2034, growing at a CAGR of 8.85% (2026–2034).
Packaged drinking water has become an everyday essential in India, sold at railway stations, highway dhabas, offices, weddings, hotels, and homes. Concerns about groundwater contamination, rising incomes, travel and tourism, and hot summers keep demand growing year after year, and the market is worth more than USD 8 billion.
Every year, India's vehicles, machinery, and industries consume around 3 million tonnes of lubricants, making the country one of the world's largest lubricant markets.
Indian wine has come a long way from a niche curiosity to a genuine lifestyle category. Young urban consumers, growing interest in food pairing, wine tourism in regions such as Nashik and Nandi Valley, and supportive state grape policies have given domestic wineries room to grow, while producers have steadily improved quality and won international recognition.
Setting up an Extra Neutral Alcohol Manufacturing Plant in India is a fermentation-and-distillation venture anchored to the large and growing alcoholic-beverage industry, along with pharmaceutical, cosmetic, and industrial demand.
Setting up a Shrimp Processing Plant in India is a high-potential, export-oriented venture, powered by the country's position as one of the world's largest shrimp producers and exporters. India's vast coastline, expanding vannamei aquaculture, and strong demand from the United States, China, the European Union, and Japan make a frozen shrimp processing Plant Setup in India one of the most attractive opportunities in the seafood sector.
India's post-pandemic food delivery boom, followed by the new quick-commerce disruption from Zepto Cafe and Swiggy Bolt, has turned the Cloud Kitchen Market in India into a genuine focus of global investor curiosity.
The total addressable market for India's functional beverages is expanding from USD 6.9 Billion in 2025 to a projected USD 18.8 Billion by 2034, growing at a CAGR of 10.74% (2026–2034).
The halal food market has moved well beyond a religious-compliance niche into one of the largest, fastest-growing consumer food categories in the world. The global market was valued at USD 2,956.4 billion in 2025 and is projected to reach USD 6,329.3 billion by 2034, expanding at a compound annual growth rate (CAGR) of 8.56% between 2026 and 2034.
India’s dairy industry is undergoing a structural transformation, driven by rising incomes, urbanization, changing consumption patterns, and strong policy support. Traditionally dominated by an unorganized and cooperative-led system, the sector is now evolving into a more competitive, branded, and technology-enabled ecosystem.
Cheese is a dairy food made by coagulating the proteins in milk, mainly casein, using enzymes, acids, or microorganisms, followed by separating the curds from the whey. Cheese can be made from the milk of cows, buffaloes, goats, sheep, or a combination of these. The coagulated curd is then processed by cutting, cooking, pressing, salting, and aging to achieve desired texture, moisture, and flavor characteristics.
Avocado oil is a vegetable oil that is extracted from the pulp of ripe avocados (Persea americana), unlike other vegetable oils that are extracted from seeds. Avocado oil contains high amounts of monounsaturated fatty acids, specifically oleic acid, as well as phytosterols, tocopherols, and carotenoids. Avocado oil can be classified as extra virgin, virgin, or refined, depending on the extraction and refining process.
Wine is a type of alcoholic drink that is made by the controlled fermentation of grape juice, where the natural or added yeast ferments the sugars in the juice to produce ethanol, carbon dioxide, and other compounds. Wine is made up of water, ethanol, organic acids, phenolic compounds, aromatic esters, and trace minerals.
Whey protein is a high-quality, complete protein obtained from whey, which is the liquid by-product of cheese production. Milk coagulated with enzymes or acids separates into curds (casein) and whey. Whey is a liquid that contains soluble proteins like beta-lactoglobulin, alpha-lactalbumin, serum albumin, and immunoglobulins. Whey is filtered and dried to produce commercial products like whey protein concentrate (WPC), whey protein isolate (WPI), and whey protein hydrolysate (WPH).
Whole egg powder is a dehydrated egg ingredient made by spray drying homogenized liquid whole eggs, which include a mixture of egg yolk and egg white in their natural ratio. Fresh whole shell eggs are broken, filtered, pasteurized, and then processed into a stable powder form using controlled drying methods. The final product preserves the functional and nutritional qualities of fresh eggs, such as high-quality protein, essential amino acids, lipids, vitamins, and emulsifying fractions.
Tea is a drink made from the processed leaves and flower buds of the plant Camellia sinensis. The essential properties of tea, namely flavor, aroma, color, and strength, depend on the level of oxidation, drying, and fermentation of the processed leaves. Tea can be categorized based on the processing techniques into black tea, green tea, oolong tea, white tea, and specialty teas.
Soy milk is a plant-based beverage made from whole soybeans that have been soaked, ground, and their liquid extracted, then cooked and filtered. It is completely devoid of elements originating from animals and is intended to operate and look like dairy milk. In addition to naturally existing proteins, carbs, and healthy fats from soybeans, soy milk is frequently supplemented with vitamins and minerals to improve its nutritional value.
Soya chunks are a protein-rich food item that is prepared using defatted soy flour, which is a by-product of soybean oil extraction. Soya chunks are prepared using the process of extrusion cooking, which converts the soy flour into porous, sponge-like granules with a fibrous structure that resembles meat when rehydrated.
Soya chunks are a protein-rich food item that is prepared using defatted soy flour, which is a by-product of soybean oil extraction. Soya chunks are prepared using the process of extrusion cooking, which converts the soy flour into porous, sponge-like granules with a fibrous structure that resembles meat when rehydrated. Soya chunks have a neutral flavor, which helps them absorb the flavors of spices and seasonings while cooking.
Saudi Arabia’s precast concrete market reached USD 1.2 Billion in 2024 as per the IMARC Group, clear proof that off-site construction is rapidly becoming the Kingdom’s go-to building solution. With residential, commercial, and major infrastructure projects multiplying, developers are increasingly turning to precast building solutions to keep pace.
The global emergency food market has emerged as a critical component of household preparedness infrastructure, disaster response frameworks, and government stockpiling programs worldwide. In March 2025, the National Disaster Response Force (NDRF), established in India, conducted a National Capacity Building Competition for State Disaster Response Forces (SDRFs) to improve their readiness and effectiveness in managing collapsed structure emergencies.
The Saudi Arabia sauces and seasonings market size is expanding steadily as consumers embrace more diverse flavors, convenient food formats, and global culinary influences. Evolving lifestyles, greater exposure to international cuisines, and a strong shift toward home cooking have collectively shaped the contemporary marketplace.
The GCC chocolate market has experienced robust expansion in recent years, driven by evolving consumer preferences, rising disposable incomes, and the proliferation of international brands. In 2024, the GCC chocolate market size reached USD 3,200.77 Million, reflecting sustained growth across premium, artisanal, and mass-market segments.
The Gulf Cooperation Council (GCC) region continues to position itself as one of the fastest-evolving markets for packaged beverages, with bottled water standing at the forefront of this transformation. The GCC bottled water market size has expanded steadily in recent years, supported by a strong shift toward health-driven consumption, improved hydration awareness, and evolving lifestyle patterns across the member countries.
India’s pet sector has experienced a remarkable transformation, driven by urbanization, evolving lifestyles, and a stronger emotional bond between people and their companion animals. What was once a niche trend among a few urban families has now become a widespread practice across Indian households, where pets are regarded as integral members of the family.
Shrimp is one of the world’s most precious natural spices, derived from the dried red stigmas of the Crocus sativus flower. Each bloom yields only a few delicate stigmas, which must be carefully hand-harvested, dried, and processed to preserve their vibrant color, distinctive aroma, and rich flavor. The spice’s deep golden-yellow hue, bitter-sweet taste, and unique fragrance are primarily attributed to its key bioactive compounds like crocin, picrocrocin, and safranal.
The Australian craft beer industry has emerged as a significant segment of the broader alcoholic beverages market driven by evolving consumer preferences, rising disposable incomes, and a growing appreciation for artisanal and premium products. Over the past decade, the market has witnessed substantial expansion with craft breweries increasingly occupying a distinct niche in the highly competitive beer sector.
India is witnessing a profound transformation in how its citizens approach health and wellness. The nutritional supplements market of the country has evolved from a niche segment into a mainstream industry serving millions of health-conscious consumers.
Sea salt is a natural mineral product obtained through the solar evaporation of seawater, followed by harvesting, washing, drying, grading, and packaging. Unlike refined table salt, which undergoes heavy chemical processing, sea salt production relies primarily on solar energy and natural crystallization, allowing it to retain trace minerals such as magnesium, calcium, and potassium that contribute to its distinct taste and nutritional value.
Saffron is one of the world’s most precious natural spices, derived from the dried red stigmas of the Crocus sativus flower. Each bloom yields only a few delicate stigmas, which must be carefully hand-harvested, dried, and processed to preserve their vibrant color, distinctive aroma, and rich flavor.
The India edible oil market stands as one of the most dynamic sectors within the country's consumer goods landscape. As households increasingly prioritize quality, health, and convenience, demand for diverse oil varieties continues to surge. The transformation from traditional purchasing habits to modern retail experiences reflects broader shifts in consumer awareness and lifestyle choices.
India's organic food industry stands at the intersection of health consciousness, agricultural innovation, and sustainable practices. As consumers increasingly prioritize chemical-free nutrition and environmental sustainability, the sector faces transformative opportunities alongside significant operational challenges shaped by evolving dietary preferences, technology adoption in agriculture, and regulatory frameworks that collectively define market dynamics.
Japan’s gluten-free foods and drinks market has evolved into a vibrant segment of the country’s growing health and wellness culture. Once catering mainly to individuals with celiac disease or gluten intolerance, gluten-free products now appeal to a broader demographic pursuing balanced, wellness-oriented lifestyles.
The GCC coconut water market is experiencing remarkable momentum as consumer preferences shift decisively toward natural hydration solutions and functional beverages. This transformation is propelled by heightened health consciousness, expanding fitness culture, and growing awareness of the nutritional benefits associated with coconut-based drinks.
The Saudi Arabia online grocery market is experiencing transformative growth, driven by widespread digital adoption, evolving consumer preferences, and strategic government initiatives aligned with Vision 2030. As one of the fastest-growing e-commerce segments in the Middle East, the online grocery sector is reshaping how Saudi consumers shop for everyday essentials.
Onion powder is a dehydrated and ground seasoning that results from the drying of fresh onions into a concentrated powdered form. The process of dehydration removes moisture from the product, while maintaining the flavor, aroma, and pungency characteristics of the onion, thereby making it a stable and ready-to-use ingredient with a longer shelf life. Onion powder can be prepared through various controlled drying, grinding, and screening processes from white, red, or yellow onion varieties.
Japan's animal feed industry stands as a cornerstone of the nation's agricultural infrastructure, supporting domestic livestock production and ensuring food security. The sector encompasses diverse feed products for cattle, swine, poultry, and aquaculture operations that sustain Japan's protein supply chain.
Nutraceuticals are bioactive, health-enhancing products derived from food sources, botanical ingredients, or purified nutrients that provide physiological benefits beyond basic nutrition. They include dietary supplements, functional foods, fortified beverages, herbal extracts, probiotics, omega-fatty-acid formulations, vitamins, minerals, and specialized nutritional compounds. Nutraceuticals are designed to support wellness, prevent nutrient deficiencies, and promote specific health outcomes, including the improvement of immunity, digestive balance, cognitive function, metabolic health, or cardiovascular support.
India's spice industry stands as a vibrant cornerstone of the nation's agricultural economy and cultural identity. As global consumers increasingly seek authentic flavors and natural ingredients, India's position as the world's leading spice producer continues to strengthen.
According to IMARC Group, India's ice cream consumption has grown nearly fourfold over the past decade. Despite this, India's per-capita consumption stands at just ~400 ml per year — far below the global average of ~2.5 litres. That gap is not a weakness. It is the single most compelling argument for the industry's long-term runway.
Millet represents a group of small-seeded cereals, primarily from the Poaceae family, which are grown as staple foods for thousands of years in Asia and Africa and, increasingly, in other parts of the world. These cereals include pearl millet, foxtail millet, finger millet, proso millet, barnyard millet, and little millet.
Milk powder is a type of dehydrated dairy product, which is manufactured by removing almost all moisture from liquid milk by means of various evaporation and drying techniques. The resultant product is a stable, shelf-friendly powder containing most of the nutritional components of milk, including proteins, lactose, minerals, and fats. Milk powder may be prepared from whole, skimmed, or partially skimmed milk, depending on its intended use. The very low moisture content inhibits microbial growth and spoilage; hence, it becomes more feasible regarding transport, storage, and usage in different formulations.
Meat generally denotes the animal tissues that are consumed and mainly include muscle fibers, though the content of fat, connective tissue, and moisture may vary. There are a number of sources, although they are mainly livestock such as cattle, pigs, sheep, poultry, and, in some regions, game animals.
Australia's tea market is at a crossroads, undergoing extraordinary change inspired by changing consumption habits, health awareness, and the explosion of functional drinks.
The Australia dairy industry stands as a vital pillar of the nation's agricultural economy, representing the third-largest rural sector and contributing significantly to both domestic food security and export earnings.
India has emerged as one of the fastest-growing fisheries producers in the world, backed by rising health awareness, export diversification, and evolving aquaculture technology.
Ice cream is a frozen dairy dessert made by blending milk, cream, sugar, and flavorings, then freezing the mixture while incorporating air to give a smooth, creamy texture. The mixture is pasteurized, homogenized, then churned under controlled conditions to prevent the formation of large ice crystals. Depending on the recipe and product category, it may contain stabilizers, emulsifiers, fruits, nuts, chocolate, or other inclusions. It comes in hardpacked ice cream, softserve, gelato, sorbets, and frozen yogurt. The texture, flavor, and quality of this frozen dessert will depend on the ratios of ingredients used and the techniques followed in processing.
The Philippines mushroom industry is undergoing a transformative phase, driven by a growing consumer shift toward functional and nutrient-dense foods. As health awareness rises across both urban and rural populations, mushrooms are increasingly recognized for their high protein, fiber, and antioxidant content. This change is not merely dietary it reflects a broader movement toward wellness-oriented lifestyles that prioritize natural, sustainable, and locally sourced food options. For agribusiness investors and food manufacturers, this evolution signals significant growth potential in both production and value-added segments of the market.
The Vietnam aquaculture market has transformed from traditional fishing practices into one of the world's most dynamic seafood production sectors. Vietnam now ranks as the fourth-largest aquaculture producer globally, supplying markets across Asia, Europe, and the Americas. Understanding what drives this growth is essential for investors, businesses, and policymakers looking to engage with this evolving industry.
French fries are thin strips of baked or deep-fried potatoes with a fluffy inside and a crispy outside. They originated in Europe and are now a common fast-food staple that is consumed as a snack or side dish in many countries. French fries are made mostly from high-starch potatoes and are produced in large quantities by chopping, blanching, frying, and occasionally freezing. They are among the most well-liked and extensively consumed potato-based food products in the world because of their ability to be seasoned, flavored, or combined with condiments like cheese, mayonnaise, or ketchup.
Glucose powder is a crystalline or powdered form of a simple sugar, glucose, derived mainly from sources of starch: corn, wheat, or rice. Glucose powder is obtained by the hydrolysis of starch into glucose by enzymes, followed by purification and concentration of the solution and its drying to yield a readily water-soluble, easily digested carbohydrate powder. Glucose powder is an instant source of energy as it is quickly absorbed in the body, which makes the product valuable in food, beverage, nutraceutical, and pharmaceutical applications. It has a neutral taste, a very high sweetness index compared to regular sugar, and excellent dissolving properties, making it useful in various industrial formulations and household consumption.
Ghee is a class of clarified butter that, conventionally, is prepared by simmering butter until the milk solids separate and caramelize, leaving a golden, fragrant fat. Presently, it is widely used in South Asian, Middle Eastern, and increasingly global cuisines. Ghee has a high smoke point, long shelf life, and rich flavor, which makes it suitable for cooking, frying, and flavor enhancement. During its production, water and milk proteins are removed, making the product a lactose-free fat that contains fat-soluble vitamins and bioactive compounds. Its stability, purity, and distinctive taste make ghee an important culinary and functional ingredient in both traditional and modern food applications.
Fruit powder is made by removing the moisture content of whole fruits through various methods, such as spray drying, freeze-drying, drum drying, or vacuum drying, to get a finely ground, dehydrated powder form. After drying, the fruit is then milled into a stable, lightweight, and shelf-friendly powder that retains much of the fruit's natural flavor, aroma, nutrients, and color. Fruit powders have the essence of fresh fruit in concentrated, easy-to-handle form and are thus highly versatile in food, beverage, nutraceutical, and cosmetic applications. They offer an alternative to fresh fruits in a more convenient manner with longer shelf life and consistent quality for industrial use.
Garlic powder is the dried form of garlic, made by drying fresh garlic cloves and then grinding them to a uniform powder. Garlic dehydration removes moisture while preserving much of the flavor, aroma, and pungency of garlic. This concentrated form offers longer shelf life, easy storage, and consistent taste compared to fresh garlic. Garlic powder is widely used as a seasoning, marinade ingredient, and flavor enhancer in culinary, industrial, and packaged-food applications. Garlic powder imparts the taste of garlic without peeling or chopping into the dishes; therefore, it is very convenient and versatile for both homes and large-scale food manufacturers.
The Frozen food market is highly diversified, encompassing categories like frozen ready meals, fruits and vegetables, meat, seafood, desserts, and bakery items. This robust growth is fueled by fundamental shifts, including urbanization, the rise of dual-income households, and a consumer demand for convenience without compromising nutritional value. Modern freezing technologies ensure high quality and extended shelf life, addressing the critical issue of food waste.
The United States shrimp market stands as one of the most dynamic segments within the global seafood industry. It reached 983,000 Tons in 2024 as per IMARC Group and is projected to reach 1,280,000 Tons by 2033 at a growth rate of 3% from 2025 to 2033. As consumer preferences shift toward healthier protein sources and sustainable options, shrimp has emerged as a cornerstone of American dietary habits. The market reflects transformations in consumer behavior, international trade dynamics, and technological innovation within aquaculture and seafood processing.
The Australia gluten-free food industry is flourishing, powered by a surge in health-conscious consumers, a rise in gluten intolerance cases, and a growing appetite for clean-label, nutritious products. In 2024, the industry reached a notable milestone, hitting USD 361.20 Million, according to IMARC Group. Popular categories like gluten-free bakery items, snacks, dairy, and ready-to-eat (RTE) meals are leading the charge.
The global frozen food industry has undergone a remarkable transformation over the past decade, evolving from a convenience-focused sector into a sophisticated, technology-driven marketplace that prioritizes quality, nutrition, and sustainability. Innovation serves as the primary catalyst for this evolution, fundamentally reshaping consumer perceptions and market dynamics across all geographic regions.
Egg powder is a type of dehydrated product prepared from whole eggs, egg whites, or egg yolks, using a controlled drying process that removes moisture content while preserving the natural nutrients, flavor, and functional properties in fresh eggs. Originally developed to extend the shelf life of eggs, it was also meant to be convenient and easily transportable for food manufacturing, catering, and military or outdoor purposes.
The global ginger market is currently experiencing a remarkable phase of expansion, positioning itself as one of the most dynamic segments within the spice and functional ingredient industries. As consumers worldwide are increasingly gravitating toward natural, health-promoting ingredients, ginger is emerging as a star performer that is capturing attention across multiple sectors, from culinary applications to pharmaceuticals and nutraceuticals. The market is demonstrating robust momentum that industry analysts are tracking with considerable interest.
Coconut is an important tropical crop with a wide array of uses, and hence it is considered the "Tree of Life." The fruit, leaves, trunk, and roots of coconuts yield a wide range of products. Each part has economic value and, therefore, provides a means of livelihood in many rural communities and agro-industrial development in tropical regions such as Southeast Asia, South Asia, and the Pacific Islands.
Coconut yogurt is a plant-based alternative to traditional dairy, made from the rich milk of mature coconuts. This yogurt boasts the same feel and taste as traditional dairy yogurt, all the while catering to vegans, lactose-intolerant, or allergenic consumers. Manufactured like traditional yogurt, this variety is fermented with live bacterial cultures such as Lactobacillus bulgaricus and Streptococcus thermophilus. These same cultures ferment the natural sugars of the coconut milk into lactic acid during processing, creating a thick consistency and giving it that tangy taste typical of yogurt.
The Australian dog food market is undergoing an important transformation, motivated mainly by advancements in AI technology. As more people own pets, they increasingly demand more tailored and nutritious options for dogs. Both technology and artificial intelligence (AI) are important to facilitate this, and reshaping the industry overall.
Coconut sugar, also known as coconut palm sugar, is a natural sweetener derived from the sap of flower buds from the coconut palm tree, Cocos nucifera. It has traditionally been produced in various tropical countries like Indonesia, the Philippines, India, and Thailand, where coconut cultivation is plentiful. This type of sugar is produced by tapping the flower buds of the coconut palm to collect the sap. The sap collected is then heated gently to boil off the water content, concentrate the sugars, and form a thick syrup.
The cashew nut is the kidney-shaped seed of the cashew apple, which is the fruit of the tropical evergreen tree Anacardium occidentale. In trade, the "cashew nut" is the edible kernel extracted from the drupe that lies under the cashew apple; the apple itself is consumed for juices and value-added products in certain markets. Cashew trees are adapted to tropical and subtropical regions with good drainage soils, and leading producers are Vietnam, India, Côte d'Ivoire, Brazil, and some West African states.
Carbonated soft drinks (CSDs) are soft drinks that contain carbon dioxide gas dissolved under pressure, providing the characteristic fizz and invigorating mouth feel that consumers like. They generally consist of carbonated water, sweeteners (sugar, high-fructose corn syrup, or low-calorie alternatives), flavoring ingredients, colorants, and preservatives. The products that fall under the category are colas, lemon-lime beverages, fruit-flavored sodas, tonic water, and sparkling mineral water.
Beer is one of the oldest and most popular alcoholic drinks in the world, made by the fermentation of cereal grains, usually barley, but also wheat, maize, or rice using yeast, hops, and water. The process of brewing turns these natural products into a drink that has intricate flavors, fizz, and a range of alcohol levels, usually 3% to 8% ABV. Hops add bitterness and flavor, with malted barley adding fermentable sugars and color. Beer has developed in centuries from small-scale, craft brewing to an international industrialized market with identifiable styles including lagers, ales, stouts, and pilsners.
The areca nut, or betel nut, is the seed of the areca palm (Areca catechu), a tropical palm mainly grown in South and Southeast Asia. It is one of the oldest described masticatories, chewing historically with betel leaf and lime for its mild stimulant effect. The nut is oval, fibrous, and high in alkaloids like arecoline, which is responsible for the typical flavor and psychoactive effects. Top producers are India, Bangladesh, Sri Lanka, Indonesia, Myanmar, Thailand, and China, with India dominating in both output and consumption.
Apple juice is among the most popular fruit drinks in the world, appreciated for its crisp flavor, inherent sweetness, and health advantages. Apple juice is made by pressing fresh apples and filtering the resulting liquid, containing vital nutrients like vitamin C, potassium, antioxidants, and polyphenols that support immune function, cardiovascular health, and hydration. Based on manufacturing techniques, apple juice can be clear, murky, or concentrated, with each type presenting unique taste profiles and longevity attributes.
Banana powder is a dry, fine, nutrient-dense substance created by dehydrating ripe or unripe bananas using methods like spray drying, freeze drying, or drum drying. It acts as an easy and shelf-stable substitute for fresh bananas, preserving most of their essential nutrients such as potassium, magnesium, vitamin B6, and dietary fiber. The production process includes choosing premium bananas, removing their peels, cutting them into slices, and drying them to an optimal moisture content before milling into a fine powder.
Almonds are nutrient-dense seeds obtained from the fruit of the Prunus dulcis tree, highly prized as a food item and source of industrial raw materials. Botanically drupes, almonds have a hard shell covering the edible kernel, which is rich in proteins, monounsaturated fat, fiber, vitamins, and minerals. The two main varieties are sweet almonds, eaten raw or processed into food items, and bitter almonds, used conventionally to extract oil and flavor after purging. The distinguishing features are mild nutty taste, excellent shelf life if kept properly, and very good compatibility with food as well as non-food uses. Almonds are processed in several steps like cleaning, shelling, blanching, roasting, or oil extraction, depending on the final purpose.
In today's fast-paced world, ready-to-eat food has become a staple for anyone juggling work, family, or travel. These foods offer the comfort of a home-cooked dish, without the time and effort, making them a go-to solution for people who crave convenience. With over 4 billion people living in cities globally and the number of dual-income households rising, the time available for traditional cooking has significantly decreased, creating consistent demand for quick meal options.
Cocoa powder is one of the main derivatives of the cocoa bean, which is derived after cocoa butter has been extracted from it during the chocolate production process. It consists mainly of non-fat cocoa solids, which contain a high content of polyphenols, flavonoids, and alkaloids like theobromine. Famous for its intense color, bitter-sweet taste, and antioxidant activity, cocoa powder comes in natural and alkalized (Dutch-processed) grades, each with distinctive taste profiles and functional characteristics.
Cassava starch or tapioca starch is a white, odorless, fine powder extracted from the cassava plant's roots (Manihot esculenta). Cassava starch has diverse applications in food, pharmaceutical, textile, paper, and adhesives industries because of its unbeatable thickening, gelling, binding, and stabilizing properties. In the food industry, cassava starch finds its applications in bakery, confectionery, dairy, beverages, and gluten-free foods as a substitute for wheat and corn-based starches.
The global vegan yogurt market was valued at USD 3.40 Billion in 2024 and is projected to reach USD 12.21 Billion by 2033, growing at a CAGR of 14.51% from 2025 to 2033. This expansion is marked by ongoing innovation, enhanced consumer personalization, and a deeper commitment to sustainability.
The guacamole market is experiencing a notable change, primarily fueled by an increasing consumer preference for healthy, convenient, and natural food choices. In 2024, the market was valued at USD 1379.9 Million. Guacamole is a creamy avocado-based dip originating from Mexican cuisine has grown into a globally popular food product recognized for its nutritional value and versatility.
Corn starch tableware is a new and ecofriendly solution to traditional plastic disposable items, which aims at solving the increasing environmental issues linked to plastic waste. Comprising mostly of corn starch, a plant-based and renewable resource, the products range from plates, bowls, cups, cutlery, and food containers, all of which are completely biodegradable and compostable.
Artificial Intelligence (AI) is transforming India's beer market at a rapid pace by balancing art with advanced technology. Right from brewing to branding, AI makes fermentation precise, temperature adjustment accurate, and ingredient control efficient, guaranteeing consistent quality and innovation in taste.
Soybean oil is a major vegetable oil used as food obtained from the seeds of the soybean crop. It ranks among the world's most significant edible oils, widely utilized in the preparation of foods, processed food items, industrial purposes, and increasingly in biofuels. High in polyunsaturated fats, especially omega-6 fatty acids, soybean oil has applications in non-food industries such as the production of biodiesel, cosmetics, naphthas, and lubricants.
A bun is a small, round or oval-shaped, soft-textured bread product that can be slightly sweet or savory in taste. Made chiefly of wheat flour, yeast, sugar, salt, water, and fat, buns are found in most cuisines around the globe.
The global dairy market is presently experiencing a profound transformation. This is largely accredited to the strategic integration of artificial intelligence (AI), a technology poised to redefine established paradigms of efficiency and innovation within the industry.
People’s relationship with food is undergoing a profound transformation. No longer just a source of fuel, what individuals eat is now seen as a cornerstone of the overall well-being—a tool to boost immunity, sharpen focus, support digestion, and build long-term resilience. This evolution in consumer consciousness is creating a powerful demand for foods that are functional, organic, and transparently made with real ingredients.
Tequila, once confined to regional consumption in Mexico, has now become a popular spirit worldwide, known for its rich heritage, skilled craftsmanship, and premium quality. Made from blue agave, tequila has attracted international consumers for its distinct flavor, artisanal qualities, and cocktail versatility.
Avocado oil is a nutritious oil pressed from the pulp of avocados (Persea americana), in contrast with most oils, which are seed derived. Avocado oil is valued for its rich content of monounsaturated fats, especially oleic acid, in addition to necessary vitamins like E, A, and D. Avocado oil has a mild, buttery taste and very high smoke point and is used both in food preparation and cosmetics.
Biscuits are dry, baked foods made from flour and usually crisp in texture and flat in shape, eaten frequently as a snack or with a meal. They consist mostly of wheat flour, sugar, fat (butter or vegetable oil), and leavening agents such as baking powder. Flavors and variety may be added using ingredients like milk solids, chocolate, spices, or dried fruits. Biscuits come in sweet and savory forms, varying from cookies and cream-filled to salted crackers. Their shelf life, which is lengthy, convenient packaging, and broad taste appeal have made them a household staple, school staple, and workplace staple worldwide.
Nutritional powders have become essential nutritional supplements created to address the specific health needs of vulnerable demographics, including diabetic patients, the aged, and the sick. When regular food intake is inadequate or compromised, these powders, which are made with specially designed compositions and are high in vital vitamins, minerals, protein, and carbs, offer balanced nourishment. Specialized baby formulas guarantee the best possible growth and development in the early years of life.
Vegetable oils remain among the world’s most widely used agricultural products, essential to food manufacturing, biofuels, cosmetics, and industrial goods.
Learn key financial strategies, operational and capital cost planning essentials for starting a profitable livestock feed production business in 2025.
World Tea Day, celebrated every year on May 21st, is an opportunity to appreciate the rich history, cultural significance, and economic impact of tea. From its origins in ancient China to its status as a global commodity, tea continues to connect people, cultures, and economies.
Mango pulp is the thick, smooth, and semi-liquid product yielded by crushing or pulping ripened mangoes. It is the inner flesh of the mango fruit extracted, without the skin and seeds. Mango pulp is widely utilized as a base for many food items, including mango juice, nectar, drinks, smoothies, ice creams, desserts, and as a topping for pancakes or yogurt. Mango juice is a cool drink prepared from ripe mangoes' juice. To make mango juice, the ripe mangoes are normally peeled, pitted, and the flesh of the mango is squeezed to get the pulp. The pulp is further treated to remove the juice from any remaining fibers or solids.
Soy sauce is a liquid condiment used extensively in cooking and seasoning food. Produced from fermented soybeans, wheat, salt, and water, it provides a deep umami taste that can be used to enhance different foods. It is a common ingredient in Asian cooking and has become popular worldwide in marinades, stir-fries, dips, and processed foods. Come in various forms including light, dark, and low-sodium, soy sauce meets the different consumer tastes and nutritional requirements, rendering it a vital ingredient in the food industry.
Instant coffee is a quick and easy-to-brew coffee beverage that is produced by brewing coffee beans into a liquid that concentrates and evaporates into powder or grain form. It rapidly dissolves in hot water, so it's highly sought after by customers demanding fast and easy coffee brewing. It has a long storage life and is inexpensive, making it popular in homes, offices, and food service establishments. It is fueled by urbanization, hectic lifestyles, and growing demand for convenience drinks.
Glucose syrup and sorbitol syrup are versatile sweeteners widely used across the food and beverage industry. Their ability to enhance texture, retain moisture, and extend shelf life makes them essential ingredients in confectionery, bakery, dairy, and beverage products. Beyond their functional benefits, these syrups contribute to taste enhancement and product stability, catering to consumer preferences for smooth, consistent formulations.
Potato flakes are a highly adaptable food ingredient created by processing cooked potatoes into thin, dehydrated slices. They are often used in soups, snacks, baked goods, and fast meals and are well-known for their usefulness, taste, and simplicity of usage. These flakes provide a reliable and effective option for home cooking, foodservice, and commercial food production while preserving the natural flavour, texture, and nutritional value of fresh potatoes. They are indispensable in a variety of culinary applications due to their lengthy shelf life, lightweight design, and easy rehydration method. Their ability to be used in a variety of recipes, from thickened stews to crispy coatings, further solidifies their position as a basic component of the world's food industry.
Industrial enzymes are biological catalysts that fast-track the chemical process that is involved during the industrial processes. Their use is mainly seen in the food and beverage, pharmaceutical, textile, biofuel, and detergent industries. This enzyme is very effective as it is energy efficient and has cleaner and greener production. Its stability and specificity make it a wonderful tool for breaking complex molecules while improving product quality and yield. Industrial enzymes can enhance the texture of bread, benefit dairy processing, assist in the production of biofuels, and clean wastewater. All these phenomena illustrate that industrial enzymes are a mandatory requirement to manufacture many more products with sustainability and cost effectiveness for multiple industries.
Sorbitol is a sugar alcohol widely used as a sweetener, humectant, and stabilizer in food, pharmaceuticals, and cosmetics. It is made commercially by hydrogenating glucose and is naturally present in fruits like apples and pears. Because of its mild sweetness, low glycaemic index, and ability to retain moisture, sorbitol is a popular ingredient in skincare, dental care, and sugar-free goods. It is also an essential component of industrial processes and a laxative in medical applications.
Inedible beef tallow, a byproduct of the meat processing industry, is derived from beef suet and serves various industrial and commercial purposes. This versatile substance undergoes rendering, a process that separates the fat from solid components. Inedible beef tallow's primary application is in animal feed, as it provides essential fats and energy for livestock, particularly in pet food and livestock supplements. Additionally, it finds use in the cosmetics and personal care industry, contributing to the production of candles, soaps, and skin-care products.
Vitamin C supplements are typically made by extracting ascorbic acid from various sources, such as citrus fruits, or synthesizing it in a laboratory setting. The extracted or synthesized ascorbic acid is then processed and formulated into different types of supplements, including tablets, capsules, chewable, and powdered forms. One of the primary advantages of Vitamin C supplements is their ability to support a healthy immune system.
Over the recent decade, the online food and grocery delivery business in India has witnessed exponential growth. This expansion is attributed to the increasing penetration of smartphones, the affordability and convenience offered by food delivery app services, and the growing availability of low-cost internet services. The industry has become progressively competitive, with numerous local and international players competing for a significant market share. Nonetheless, despite the extreme competition, global players are continuing to make significant investments in India on account of its significant market share in the global online food delivery market.
‘World Food Day’ is celebrated on October 16th as a global responsibility to abolish hunger. 2024’s theme for the day is ‘Right to foods for a better life and a better future’. This theme highlights the significance of enabling access to nutritious food for all, particularly in the face of global challenges, including poverty, climate change, and conflict. In line with this theme, in October 2024, India and the United Arab Emirates (UAE) announced plans for developing a food corridor between the two nations, with an initial investment of over USD 2 Billion (INR 17,000 Crore) in food processing and logistics for food parks. This project significantly reinforces the UAE's food security while providing support to Indian farmers. The initiative is part of a bigger investment strategy targeting over USD100 Billion across key sectors, including manufacturing, infrastructure, and logistics.
A vegan, or a plant-based diet, focuses mainly on consuming fruits, vegetables, grains, legumes, nuts, and seeds. It excludes all animal-derived products and ingredients, including meat, poultry, fish, dairy, eggs, and honey. Nowadays, people are shifting toward vegan diets for a variety of reasons, such as ethical concerns for animal welfare, environmental sustainability, health benefits, and personal preferences.
Functional foods promote overall well-being and offer specific health benefits beyond daily nutrient intake. These benefits encompass enhanced bone health, effective cholesterol management, improved heart health, and eye health. Functional foods include probiotic yoghurt, omega-3 enriched eggs, fortified milk, antioxidant-rich berries, and functional beverages.
Fusion cuisine and beverages blend different ingredients, flavors, or techniques from various culinary or cultural backgrounds to create unique and innovative flavor profiles in dishes and drinks. Fusion beverages encompass both alcoholic and non-alcoholic options, including cocktails, mocktails, smoothies, teas, and more. These beverages span a spectrum from simple combinations to complex and inventive concoctions. Changing taste preferences and global connectivity are the main reasons for the increasing adoption of fusion beverages. They are available in various product types, such as carbonated drinks, fused teas and coffees, fruit juices, fusion alcoholic beverages, energy drinks, sports drinks, and more. These beverages are accessible through off-trade outlets (hypermarkets, supermarkets, discounters, grocery stores, off-license stores, alcohol and confectionery stores, highly specialized retailers, and online stores), as well as on-trade establishments (pubs, bars, cafés, restaurants, clubs, discos, hotels, mass events, and others). Examples of fusion beverages include fruit-infused tea, Asian-inspired cocktails, spicy margaritas, bubble tea creations, mojito variations, and infused waters. Furthermore, fusion cuisine merges elements from diverse culinary traditions, such as Asian, European, African, or Latin American, to craft new and exciting dishes. Examples of fusion cuisine include sushi burritos, Thai basil pizza, kimchi tacos, and more.