Indian Animal Feed Market: How Rising Protein Consumption Fuels Growth
Introduction: Why Protein Demand Is Reshaping Feed
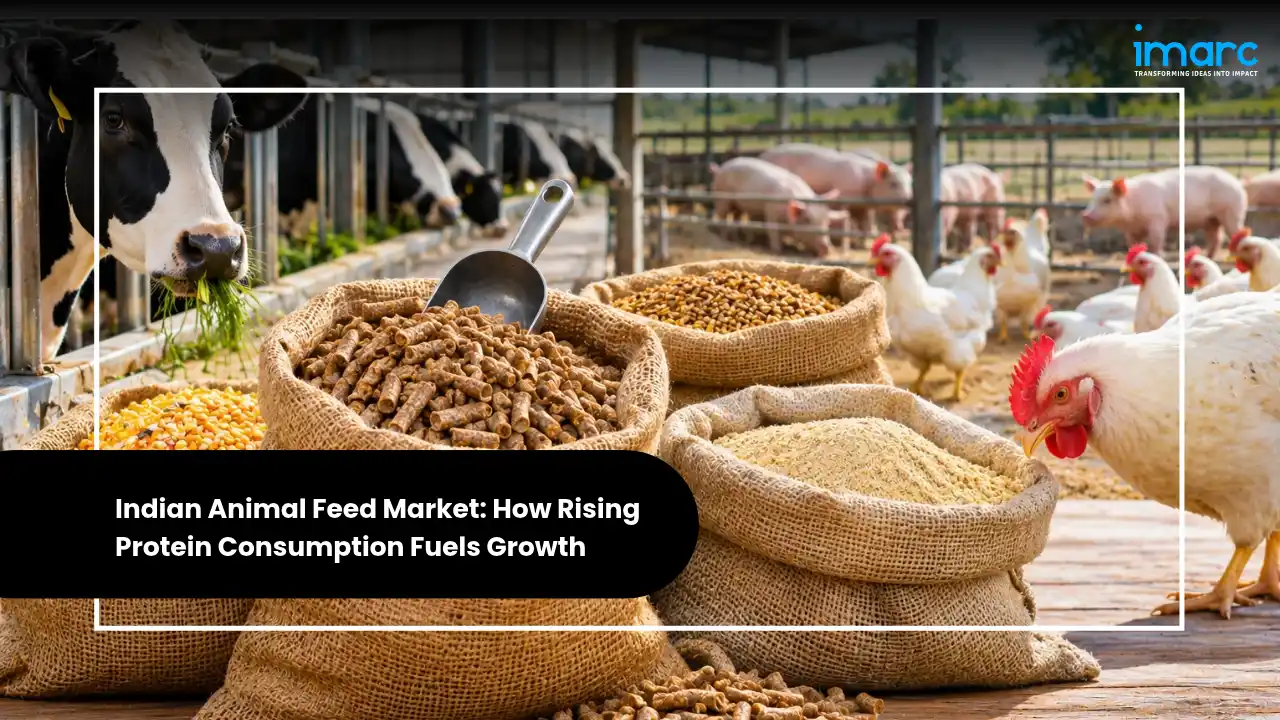
The Indian animal feed market is being reshaped less by what happens inside a feed mill than by what appears on Indian dinner plates. According to IMARC Group, the market was valued at INR 1,186.30 Billion in 2025 and is projected to reach INR 2,112.96 Billion by 2034, expanding at a CAGR of 6.6% over 2026-2034. Compounded across nine years, that rate leaves the market roughly 78% larger at the end of the forecast window than at the start, and the single largest reason is protein.
Three forces converge behind that number. Households in metropolitan and second-tier cities are adding meat, eggs, dairy and seafood to daily diets as disposable incomes rise, a pattern that reviewers of India's livestock economy trace directly to urban income growth and changing food habits. Livestock numbers are expanding at the same time, and herds and flocks are moving away from grazing and crop residue toward commercial systems that cannot reach productivity targets without manufactured feed. Federal and state programmes now fund feed plants, distribution chains and quality infrastructure, lowering the cost of that transition for producers.
The defining trend is precision. Feed is becoming a formulated, species-specific and stage-specific product rather than a commodity blend of grain and oilcake. De Heus India made the point in 2025 by commissioning a plant at Rajpura in Punjab with an investment of nearly USD 17 million, an installed capacity of 180 kMT that can be raised to 240 kMT, and dedicated production lines for cattle, buffalo, poultry and pig feed. A facility built around four species lines is a statement that manufacturers expect demand to be segmented rather than aggregated.
This blog sets out the market's size and segmentation, the developments of 2024 and 2025, the trends shaping 2026, the regional geography of demand, the strategies of the top animal feed companies in India, and the policy and risk factors that will determine how much of the protein opportunity the industry actually captures.
Key Takeaways
- The Indian animal feed market was valued at INR 1,186.30 Billion in 2025 and is forecast to reach INR 2,112.96 Billion by 2034, growing at a CAGR of 6.6% between 2026 and 2034.
- Poultry feed is the leading product type with a 56% share in 2025, reflecting the expansion of organised broiler and layer farming and sustained growth in chicken and egg consumption.
- North India is the leading region with a 31% share in 2025, supported by the dairy belts of Punjab, Haryana and Uttar Pradesh and by proximity to grain surplus that lowers raw material costs.
- The most notable recent development was De Heus India's Rajpura plant, built with nearly USD 17 million of investment and an installed capacity of 180 kMT expandable to 240 kMT, with separate lines for cattle, buffalo, poultry and pig feed.
- The key trend is the move toward precision feeding, digital formulation and alternative proteins, illustrated by Elmentoz Research's plan for a black soldier fly protein facility capable of processing 2,000 MT of industrial by-products each month.
Indian Animal Feed Market Size, Share & Growth Outlook
According to IMARC Group, the Indian animal feed market size stood at INR 1,186.30 Billion in 2025 and is projected to reach INR 2,112.96 Billion by 2034, registering a CAGR of 6.6% between 2026 and 2034. A 6.6% annual growth rate looks unremarkable in isolation, but it is a volume story rather than a price story: reaching that endpoint requires manufacturers to physically produce and distribute substantially more feed, which explains why the industry's strategic agenda is dominated by capacity additions and distribution reach rather than by price realisation. It also explains why the growth is not evenly distributed across product categories or states. The leading segments are:
- Product Type: Poultry feed accounts for a 56% share in 2025, making it the largest product category by a wide margin. The share reflects two structural facts: chicken and eggs are the cheapest and most widely consumed animal proteins in India, and broiler and layer farming has consolidated into integrated and contract systems in Andhra Pradesh, Telangana and Karnataka that specify feed formulations as a condition of participation. Poultry feed therefore converts rising protein demand into commercial feed demand faster than any other category.
- Cattle Feed: This is the second major product line and the one most closely tied to rural incomes. Any assessment of cattle feed market size in India begins in the dairy belts of the north and west, where cooperative networks procure milk daily and where wheat bran, rice bran and oilseed meal are available within short haulage distances. Demand here is steadier than in poultry but more sensitive to milk procurement prices and monsoon-driven fodder availability.
- Region: North India leads with a 31% share in 2025, driven by extensive dairy farming in Punjab, Haryana and Uttar Pradesh, established agricultural infrastructure, and proximity to major grain-producing belts that keeps raw material procurement cost-effective. The region's dealer and retailer networks reach remote villages in a way that distribution systems elsewhere are still building.
The segmentation points to a market where one product type and one region set the tempo, while cattle feed, aquafeed and the southern and western belts determine how quickly the base of demand broadens beyond that core.
Recent News & Mega Announcements
Capital is moving into Indian feed manufacturing and feed-adjacent technology at a pace that was rare a decade ago. The developments below, concentrated in 2024 and 2025, show where investors expect feed volume to come from and which parts of the value chain they consider underbuilt:
- De Heus India, Rajpura, Punjab (2025): The Indian arm of De Heus Animal Nutrition commissioned one of the largest and most sophisticated feed plants in the country, built with an investment of nearly USD 17 million, with an installed capacity of 180 kMT and headroom to reach 240 kMT. Dedicated cattle, buffalo, poultry and pig lines and European automation position the plant to compete on formulation consistency rather than on price alone.
- Dsm-firmenich Animal Nutrition & Health, Jadcherla, Hyderabad (2025): The company opened a feed additive facility spanning 11,200 square metres, including a production line for mycotoxin risk management solutions and new storage capacity, built to global standards for quality, safety and environmental protection. Additive capacity matters because premium formulations depend on a reliable local supply of vitamins, enzymes and toxin binders.
- Elmentoz Research, seed funding (2025): The deep-tech biotech firm completed an initial seed round from angel investors in India and Norway and is building what it describes as India's largest black soldier fly oriented smart protein facility, designed to process 2,000 MT of industrial by-products every month using proprietary automation.
- NDDB Dairy Services, Nagpur (November 2025): The foundation stone for a 250 metric tonnes per day cattle feed plant was laid virtually at the Agrovision event in Nagpur, with the Union Minister for Road Transport and Highways and the Union Minister of Agriculture and Farmers' Welfare in attendance. Cooperative-owned capacity of this scale signals that dairy institutions intend to supply their own feed rather than cede the segment to private brands.
- Karnataka maize procurement at MSP (December 2025): The state government allowed poultry feed producers to buy maize directly from farmers at Minimum Support Price rates for the 2025-26 kharif season, reducing dependence on middlemen and improving price realisation for growers. For feed mills, direct procurement is a margin and predictability measure as much as a farmer welfare measure.
- Sabarkantha Dairy, Gujarat (2024): A state-of-the-art animal feed plant with a production capacity of 800 metric tons was inaugurated, representing an investment of INR 210 Crore (USD 25.2 million) and demonstrating public sector commitment to modernising livestock nutrition infrastructure.
- Loopworm, silkworm-derived protein (2024): The agritech startup introduced animal feed protein derived from silkworms as an eco-friendly alternative to conventional protein sources, addressing resource efficiency alongside nutrition.
- USDA Economic Research Service, India outlook (March 2025): Analysis published by the agency notes that India's population and income are expected to grow steadily through 2050, which could lead to increased domestic demand for animal food products. That long-horizon demand signal underpins the capacity decisions being taken today.
Industry Trends Shaping 2026 in the Indian Animal Feed Market
Three shifts define how the Indian animal feed market is likely to evolve through 2026 and beyond. Each is already visible in commercial decisions rather than in forecasts alone.
1. Precision Feeding and Digital Integration
Automation and digital tools are being adopted quickly by feed manufacturers seeking to improve nutritional delivery, cut waste and raise production consistency. Real-time batching systems, ingredient tracking platforms and automated mixing technologies allow tighter quality control while reducing the human error that creeps into manual formulation. The commercial logic is straightforward: feed is the largest recurring cost in livestock production, so small improvements in conversion efficiency translate into meaningful gains for the farmer and into brand loyalty for the manufacturer.
The benefits extend past the factory gate. Mobile applications and digital platforms for inventory management, distribution tracking and farmer engagement are reaching rural and semi-urban customers who historically had no access to advanced supply chain tools. Farmers can monitor feed intake patterns, animal health indicators and performance metrics, which supports earlier intervention and better productivity outcomes. The Elmentoz facility announced in 2025, with its monthly processing target of 2,000 MT of industrial by-products under proprietary automation, illustrates how far the technology layer now reaches into what was once a low-tech blending business.
2. Alternative Proteins and Circular Ingredient Sourcing
Environmental considerations are reshaping ingredient sourcing across the industry. Manufacturers are incorporating agro-industrial by-products and alternative protein sources to reduce dependence on conventional grains while lowering costs and environmental footprints. For a country that imports substantial quantities of oilseeds and pulses, diversifying protein inputs is an economic necessity as much as a sustainability goal. Loopworm's silkworm-derived feed protein, introduced in 2024, is one example of a domestic input stream that does not compete with food-grade grain.
Policy attention to protein supply is rising globally as well. Public investment in protein diversification is being tracked across governments as a route to feeding a growing population, and the European Commission's Protein Action Plan frames protein production as a question of farmer opportunity and rural value creation. Indian guidelines on emission reduction and waste management are pushing in the same direction, encouraging research into insect meals, algae-based proteins and fermented agricultural residues that offer comparable nutritional profiles with a smaller ecological footprint.
3. Premium Formulations and Additive Innovation
Consumer awareness of food safety and nutritional quality is pushing demand toward premium feed enriched with specialised additives and micronutrients. Livestock producers are adopting fortified formulations containing vitamins, minerals, amino acids and probiotics to improve animal health, reproductive efficiency and end-product quality. Species-specific feeds tailored to different growth stages are becoming standard practice, particularly in commercial poultry and dairy operations where productivity correlates directly with feed quality. The commercial poultry and dairy segments are where the willingness to pay for formulation quality is highest, because a marginal gain in feed conversion or milk yield is measurable within a single production cycle.
The quality shift is most pronounced in organised farming that serves urban markets demanding traceable, safe animal products, which in turn forces manufacturers to invest in research and development. The dsm-firmenich additive plant at Jadcherla, with its mycotoxin risk management line, speaks to a specific concern: contaminated feed undermines both animal performance and brand credibility, and buyers increasingly treat toxin-binding capability as a baseline requirement rather than an optional extra.

Geographic Hotspots
North India's 31% share in 2025 rests on dairy rather than poultry. Haryana, Punjab and Uttar Pradesh together hold extensive buffalo and cattle populations that support India's position as the world's largest milk producer, and the region generates abundant wheat bran, rice bran and oilseed meal from Punjab's agricultural activity, giving cattle feed manufacturers cost-effective raw material within short distances. Cooperative dairy networks across Uttar Pradesh procure millions of litres of milk daily, creating consistent demand for nutritionally balanced cattle feed. The concentration of feed plants near grain mandis and processing facilities reduces transport costs, and dealer and retailer channels reach remote villages alongside agricultural extension services that promote scientific feeding. Haryana's more progressive farmers are adopting total mixed ration systems and silage-based regimens, which pulls demand toward specialised cattle feed that complements roughage and optimises rumen fermentation for milk fat and protein yields.
South India is where the poultry and aquafeed story concentrates. Broiler and layer operations in Andhra Pradesh and Telangana have moved into integrated and contract farming arrangements that standardise feed specifications and quality parameters, ensuring consistent flock performance and disease resistance. Karnataka's poultry clusters show how locally produced maize and soybean meal directly determines feed pricing competitiveness, while proximity to metropolitan consumption centres supports rapid inventory turnover and freshness. Coastal aquaculture across Andhra Pradesh and Tamil Nadu sustains demand for specialised aquafeed, a category that requires different extrusion and nutrient expertise from poultry feed and where the industry's export orientation raises quality expectations to international standards.
East India remains the least saturated belt, with a more fragmented base of smallholders and a shorter history of commercial feed adoption. It is also where the marginal growth from converting home-mixed rations to manufactured feed is largest, which makes it strategically important even though its current share is modest. West India combines strong dairy institutions with growing poultry capacity: the Sabarkantha dairy feed plant in Gujarat and the 250 MTPD NDDB Dairy Services plant announced at Nagpur in November 2025 both sit in this belt, and Gujarat's cooperative model offers a template for how institutional demand can anchor feed plant utilisation. Maharashtra and Rajasthan add cattle and poultry volume that broadens the western base beyond dairy alone.
Competitive Landscape & Key Players Strategies
The Indian animal feed market has a consolidated-yet-competitive structure. Multinational corporations bring technological capability, extensive distribution and integrated value chains; diversified domestic conglomerates bring agricultural sector presence and balance sheet depth; and regional specialists serve niche species and geographies with tighter service relationships. Competition centres on three levers: product innovation through functional additives, cost optimisation through backward integration into ingredient sourcing, and market penetration through tailored portfolios for different farmer segments.
Identifying the largest animal feed manufacturers in India requires looking past revenue alone, because the market rewards those who combine formulation expertise with procurement reach and last-mile distribution. Strategic collaboration with livestock producers, investment in research and development, and capacity expansion in high-growth regions are the defining competitive behaviours. The top animal feed companies in India are also converging on service models, bundling feed with veterinary advice, farm management support and digital tracking, because a farmer who receives performance data alongside a nutrition programme is far harder to switch than one who buys on price. The most prominent participants include:
- Anmol Feed: A regional manufacturer competing on cattle and poultry formulations with a strong dealer network.
- Avanti Feeds Limited: A listed player with a substantial aquaculture and shrimp feed franchise and an export-oriented customer base.
- Charoen Pokphand Foods PCL: A multinational with integrated poultry and aquafeed operations and a vertically coordinated supply model.
- Godrej Agrovet Limited: A diversified agribusiness conglomerate combining animal feed with crop protection and dairy operations.
- Grobest Feeds Corporation India Pvt Limited: An aquaculture-focused supplier with technical specialisation in shrimp and fish nutrition.
- Growel Feeds Private Limited: An aquafeed specialist with a broad product portfolio across species and life stages.
- JAPFA India: Part of an integrated protein group with poultry operations that anchor captive and commercial feed demand.
- Kapila Group: A dairy and cattle feed player with cooperative and private channel reach.
- KSE Limited: A Kerala-based manufacturer with a cattle feed franchise tied to southern dairy networks.
- SKM Animal Feeds & Foods (India) Private Limited: A poultry feed producer serving the southern broiler belt.
- Suguna Foods Private Limited: A poultry integrator whose contract farming model generates captive feed requirements.
- The Waterbase Limited: An aquaculture feed and shrimp farming business with technical service capabilities.
- Uno Feeds: A poultry feed manufacturer competing on formulation quality and regional distribution.
Alongside these established names, newer entrants such as Elmentoz Research and Loopworm are positioning themselves in ingredient innovation rather than finished feed, which suggests the next phase of competition may run through the supply chain rather than only through the brand on the bag.
Policy & Regulatory Landscape, Challenges & Risks
Government policy has become a primary market force. Key frameworks include:
- National Livestock Mission: The scheme supports feed manufacturing facilities and distribution systems serving rural agricultural communities, effectively lowering the capital cost of capacity creation in underserved districts and extending commercial feed into geographies where private investment alone would not have gone.
- Rashtriya Gokul Mission: Focused on dairy productivity and breed improvement, the mission raises the returns from balanced feeding, because genetic gains only translate into milk yield when nutrition keeps pace. For feed manufacturers it expands the addressable market among dairy farmers who are already investing in animals.
- Karnataka's direct maize procurement at MSP (December 2025): Allowing poultry feed producers to buy maize directly from farmers at Minimum Support Price for the 2025-26 kharif season removes intermediaries from the chain, improving farmer realisation and giving mills a more predictable input base during a period of commodity volatility.
- Feed quality standards and safety certification: Regulatory frameworks establishing feed quality standards and safety certifications professionalise the industry and protect farmers from adulterated or substandard products, building confidence in commercial feed adoption and raising the compliance bar for small, under-equipped manufacturers.
On the constraining side, several structural risks persist:
- Raw material price volatility and import dependence: Feed economics remain vulnerable to swings in maize, soybean meal and fishmeal prices, and India imports substantial quantities of oilseeds and pulses to bridge domestic gaps. Currency movements and trade policy changes create input cost uncertainty that compresses manufacturer margins and can price feed out of reach for smallholders.
- Fragmented farmer base and limited awareness: The livestock sector is dominated by smallholders with limited resources, traditional practices and constrained access to technical information. Many continue with home-mixed formulations or agricultural by-products despite suboptimal nutritional outcomes, and extension gaps, language barriers and conservative mindsets slow penetration.
- Quality control and regulatory compliance: Raw material authentication, contamination prevention and nutrient verification are demanding, and incidents involving adulteration, antibiotic residues or aflatoxin contamination can damage brand reputations quickly. Smaller manufacturers with limited testing infrastructure struggle to meet specifications, and enforcement is unevenly applied across states.
- Disease outbreaks and biosecurity shocks: Periodic outbreaks affecting poultry and other livestock populations can disrupt demand for feed and destabilise farm incomes within weeks, and the risk is amplified where biosecurity practices and veterinary surveillance remain uneven across production clusters.
Forecast 2026-2034
The forecast period opens with the market at INR 1,186.30 Billion and closes at INR 2,112.96 Billion by 2034, a CAGR of 6.6% that compounds into roughly INR 926.66 Billion of incremental revenue. For anyone tracking the animal feed market size in India for 2026 as a planning baseline, the implication is that growth will be generated by volume expansion and portfolio mix rather than by a rising price per tonne, which places the burden of delivery on manufacturing capacity, procurement and distribution.
Poultry feed's 56% share makes it the swing factor. If organised broiler and layer production continues to consolidate around integrated and contract models in the south and west, poultry feed will keep pace with the headline rate and may exceed it in years when maize and soybean meal prices are favourable. Cattle feed, anchored in the dairy belts, offers slower but steadier growth tied to milk procurement prices and cooperative investment, and the NDDB Dairy Services plant announced at Nagpur shows that institutional capacity is being built to serve it. Aquafeed remains the smallest category but carries disproportionate value because export-oriented shrimp farming requires specialised formulations meeting international quality standards.
Regionally, North India's 31% share is not seriously threatened within the forecast window, though its relative weight may soften as the east converts smallholder feeding to commercial products and as southern poultry and aquafeed clusters expand. The risk to the trajectory is concentrated on the cost side. A sustained spike in maize or soybean meal prices, or a prolonged currency depreciation that raises imported ingredient costs, would slow adoption among the marginal farmers who represent most of the remaining addressable market. The base case therefore assumes reasonably stable commodity conditions, continued policy support for feed infrastructure, and steady progress in farmer awareness.
Opportunities for Stakeholders
- Feed manufacturers: Capacity close to grain belts and consumption centres captures both procurement and logistics savings. The Rajpura model of multi-species lines under one roof allows a single plant to serve dairy, poultry and pig demand, improving utilisation across seasons.
- Dairy cooperatives and institutions: Owning feed capacity, as NDDB Dairy Services and Sabarkantha Dairy are doing, converts milk procurement networks into a captive feed channel and captures value that currently accrues to third-party suppliers.
- Aquafeed and specialty producers: Export-oriented shrimp and fish farming demands formulations meeting international standards, a segment where technical service capability commands a premium and where domestic competition remains thinner than in poultry feed.
- Ingredient and biotech innovators: Insect protein, fermented residues and additive manufacturing address the industry's two persistent weaknesses, import dependence and formulation quality. Elmentoz, Loopworm and the dsm-firmenich facility each target a different point on that chain.
- Farmers and producer organisations: Bulk procurement through farmer producer organisations and dairy societies lowers unit costs and improves access to scientifically formulated feed, particularly in eastern states where commercial penetration is lowest.
- Investors and strategic acquirers: Market consolidation through acquisitions and capacity expansion indicates maturation, and established players with economies of scale and integrated supply chains are the natural consolidators as compliance costs rise for smaller mills.
Protein Demand Will Keep Driving Feed
The direction of the Indian animal feed market is set by a demand shift that is difficult to reverse. As incomes rise and urban food habits broaden, consumption of meat, eggs, dairy and seafood keeps climbing, and each additional unit of animal protein requires feed that is formulated, tested and delivered on schedule. The market's expansion from INR 1,186.30 Billion in 2025 to a projected INR 2,112.96 Billion by 2034, at a CAGR of 6.6% is the financial expression of that shift, and it explains why almost every major announcement of the past two years has been a capacity announcement.
The composition of that growth matters as much as its size. Poultry feed's 56% share in 2025 and North India's 31% share describe a market with a clear centre of gravity, but the strategic openings sit at the edges: cattle feed in the dairy belts, aquafeed in the coastal clusters, alternative proteins that reduce import exposure, and the eastern states where home-mixed rations still dominate. Manufacturers that invest in formulation quality, procurement depth and farmer-level service will capture more of the value than those competing purely on price per bag.
The constraints are real but familiar. Commodity volatility, fragmented farm structures, quality assurance gaps and disease risk have shaped this industry for decades, and the policy environment is now actively working against them through feed plant support, dairy productivity programmes and direct procurement mechanisms. Demand for protein is doing the rest.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Setting up a Pectin Manufacturing Plant in India is a timely, import-substitution opportunity in a fast-growing food ingredients segment.
Peanut spread is a smooth or crunchy paste made by roasting, skinning, and grinding groundnuts, often with a little salt, sugar, and a stabiliser. It is rich in protein and healthy fats, and in India it has moved from a niche import to an everyday breakfast and fitness food sold through supermarkets, pharmacies, gyms, and online stores.
The organic and natural pet food market has moved from a specialist shelf in independent pet stores to a structural growth engine inside global pet care. According to IMARC Group, the global natural pet food market reached USD 33.6 Billion in 2025 and is projected to reach USD 59.4 Billion by 2034, expanding at a CAGR of 6.33% during 2026-2034.
Edible oils are produced by pressing and solvent-extracting oilseeds such as soybean, mustard, groundnut, and sunflower, or by importing crude palm, soybean, and sunflower oil, and then refining them through degumming, bleaching, and deodorisation to remove impurities, colour, and odour before packing them for homes, restaurants, and food processors.
Club soda is purified water chilled and charged with food-grade carbon dioxide under pressure, then filled into PET bottles, glass bottles, or cans and sealed so that it keeps its fizz until opened.
Ice cream is a frozen dairy dessert made by pasteurising and homogenising a mix of milk, cream, sugar, stabilisers, and flavours, then freezing it while whipping in air and hardening it at very low temperatures.
CNSL, the dark, viscous liquid held in the honeycomb of the cashew shell, is recovered by pressing shells left over from kernel processing and then heating the crude liquid so that its anacardic acid turns into cardanol.
Ground spices and blended masalas turn whole chilli, turmeric, coriander, cumin, pepper, and other spices into clean, safe, ready-to-use powders and mixes for homes, restaurants, food processors, and export buyers.
Fishmeal is a brown, protein-rich powder made by cooking, pressing, drying, and grinding small oily fish and fish processing waste, with fish oil recovered as a valuable co-product.
Dried banana ingredients are made by washing, peeling, and slicing fresh fruit, treating it to prevent browning, drying it in belt, tray, or spray dryers, and milling it into a fine, shelf-stable product.
Dried egg is made by breaking fresh eggs, pasteurising the liquid whole egg, yolk, or white, and spray drying it into a fine powder that keeps for a year or more without refrigeration.
Whey is the liquid left after milk is made into cheese or paneer, and it contains high-quality proteins that can be separated by membrane filtration and spray dried into concentrates and isolates.
The pectin market has moved from the back of the ingredient label to the centre of product development strategy. As food manufacturers strip out synthetic gelling agents, stabilisers and thickeners, pectin has become one of the few hydrocolloids that can deliver texture and shelf stability while still reading as a familiar, fruit-derived ingredient.
Poultry processing turns live broilers into hygienically slaughtered, chilled, cut, and packed meat, ready for retail shelves, restaurants, quick-service chains, caterers, and export. India produced about 10.5 million tonnes of meat in 2024-25, and poultry made up roughly half of it at 5.18 million tonnes, yet around 85% of birds are still sold live or slaughtered in small wet-market shops.
The global tomato ketchup market reached USD 20.8 Billion in 2025 and is projected to reach USD 26.3 Billion by 2034, growing at a CAGR of 2.68% during 2026-2034, according to IMARC Group. Those numbers describe a mature, high-volume condiment category rather than a fast-growing one.
Coconut shell powder is made by cleaning, drying, crushing, and finely grinding the hard inner shell of the coconut into a uniform powder. Because the shell is dense, rich in lignin, low in ash, and slightly oily, the powder is an excellent natural filler.
Dextrins are modified starches made by heating dry starch, usually with a small amount of acid, so that its long molecules break into shorter ones. The result is a powder that dissolves easily in water and forms strong, quick-drying adhesive films.
Fruit powders are made by drying fruit pulp or juice into a fine, free-flowing powder that keeps the flavour, colour, and much of the nutrition of fresh fruit while lasting months without refrigeration.
Yeast is a living microorganism that makes bread rise, ferments beer, wine, and spirits, turns sugar into fuel ethanol, and supplies protein, vitamins, and flavour to food, feed, and nutrition products.
The global champagne market is entering a phase where value growth matters more than volume growth. IMARC Group values the market at USD 6.6 Billion in 2025 and projects it to reach USD 8.1 Billion by 2034, expanding at a CAGR of 2.25% during 2026-2034.
India is one of the world's leading coffee producers and exporters, growing shade-grown arabica and robusta in the hills of Karnataka, Kerala, and Tamil Nadu and supplying green, roasted, and instant coffee to more than 100 countries.
The Australia Online Grocery Industry has crossed the point where volume growth is the scarce commodity. What is scarce now is profitable volume. According to IMARC Group, the market reached USD 17.22 Billion in 2025 and USD 21.91 Billion in 2026, and is projected to reach USD 96.59 Billion by 2034, expanding at a CAGR of 20.37% (2026–2034), a more than five-fold expansion in under a decade. That growth is unfolding inside one of the most closely regulated grocery markets in the developed world.
Baby formula, also known as infant formula, is a manufactured food product designed to serve as a substitute for or supplement to human breast milk for infants and young children up to three years of age.
Palm oil is the world's most widely used vegetable oil, extracted from the fruit of the oil palm and used in cooking oils, vanaspati, bakery fats, snacks, soaps, cosmetics, and oleochemicals, while the kernel yields palm kernel oil and cake.
Beer is one of the world's most widely consumed drinks, brewed from malted barley, water, hops, and yeast, often with rice or maize as adjuncts. In India, beer accounts for only a small share of alcohol consumption compared with most countries, but that is changing as a young, urban, and increasingly female consumer base embraces lighter drinks, premium lagers, wheat beers, and craft styles.
Bread, buns, rusk, cakes, cookies, and biscuits are part of daily meals and snacking in almost every Indian household, from metro cities to small towns.
Makhana has moved from a pond crop traded through village aggregators into a branded snack with its own export code and a national board behind it. According to IMARC Group, the India makhana market was valued at INR 9.29 Billion in 2025 and is projected to reach INR 19.95 Billion by 2034, growing at a CAGR of 8.85% (2026–2034).
Packaged drinking water has become an everyday essential in India, sold at railway stations, highway dhabas, offices, weddings, hotels, and homes. Concerns about groundwater contamination, rising incomes, travel and tourism, and hot summers keep demand growing year after year, and the market is worth more than USD 8 billion.
Every year, India's vehicles, machinery, and industries consume around 3 million tonnes of lubricants, making the country one of the world's largest lubricant markets.
Indian wine has come a long way from a niche curiosity to a genuine lifestyle category. Young urban consumers, growing interest in food pairing, wine tourism in regions such as Nashik and Nandi Valley, and supportive state grape policies have given domestic wineries room to grow, while producers have steadily improved quality and won international recognition.
Setting up an Extra Neutral Alcohol Manufacturing Plant in India is a fermentation-and-distillation venture anchored to the large and growing alcoholic-beverage industry, along with pharmaceutical, cosmetic, and industrial demand.
Setting up a Shrimp Processing Plant in India is a high-potential, export-oriented venture, powered by the country's position as one of the world's largest shrimp producers and exporters. India's vast coastline, expanding vannamei aquaculture, and strong demand from the United States, China, the European Union, and Japan make a frozen shrimp processing Plant Setup in India one of the most attractive opportunities in the seafood sector.
India's post-pandemic food delivery boom, followed by the new quick-commerce disruption from Zepto Cafe and Swiggy Bolt, has turned the Cloud Kitchen Market in India into a genuine focus of global investor curiosity.
The total addressable market for India's functional beverages is expanding from USD 6.9 Billion in 2025 to a projected USD 18.8 Billion by 2034, growing at a CAGR of 10.74% (2026–2034).
The halal food market has moved well beyond a religious-compliance niche into one of the largest, fastest-growing consumer food categories in the world. The global market was valued at USD 2,956.4 billion in 2025 and is projected to reach USD 6,329.3 billion by 2034, expanding at a compound annual growth rate (CAGR) of 8.56% between 2026 and 2034.
India’s dairy industry is undergoing a structural transformation, driven by rising incomes, urbanization, changing consumption patterns, and strong policy support. Traditionally dominated by an unorganized and cooperative-led system, the sector is now evolving into a more competitive, branded, and technology-enabled ecosystem.
Cheese is a dairy food made by coagulating the proteins in milk, mainly casein, using enzymes, acids, or microorganisms, followed by separating the curds from the whey. Cheese can be made from the milk of cows, buffaloes, goats, sheep, or a combination of these. The coagulated curd is then processed by cutting, cooking, pressing, salting, and aging to achieve desired texture, moisture, and flavor characteristics.
Avocado oil is a vegetable oil that is extracted from the pulp of ripe avocados (Persea americana), unlike other vegetable oils that are extracted from seeds. Avocado oil contains high amounts of monounsaturated fatty acids, specifically oleic acid, as well as phytosterols, tocopherols, and carotenoids. Avocado oil can be classified as extra virgin, virgin, or refined, depending on the extraction and refining process.
Wine is a type of alcoholic drink that is made by the controlled fermentation of grape juice, where the natural or added yeast ferments the sugars in the juice to produce ethanol, carbon dioxide, and other compounds. Wine is made up of water, ethanol, organic acids, phenolic compounds, aromatic esters, and trace minerals.
Whey protein is a high-quality, complete protein obtained from whey, which is the liquid by-product of cheese production. Milk coagulated with enzymes or acids separates into curds (casein) and whey. Whey is a liquid that contains soluble proteins like beta-lactoglobulin, alpha-lactalbumin, serum albumin, and immunoglobulins. Whey is filtered and dried to produce commercial products like whey protein concentrate (WPC), whey protein isolate (WPI), and whey protein hydrolysate (WPH).
Whole egg powder is a dehydrated egg ingredient made by spray drying homogenized liquid whole eggs, which include a mixture of egg yolk and egg white in their natural ratio. Fresh whole shell eggs are broken, filtered, pasteurized, and then processed into a stable powder form using controlled drying methods. The final product preserves the functional and nutritional qualities of fresh eggs, such as high-quality protein, essential amino acids, lipids, vitamins, and emulsifying fractions.
Tea is a drink made from the processed leaves and flower buds of the plant Camellia sinensis. The essential properties of tea, namely flavor, aroma, color, and strength, depend on the level of oxidation, drying, and fermentation of the processed leaves. Tea can be categorized based on the processing techniques into black tea, green tea, oolong tea, white tea, and specialty teas.
Soy milk is a plant-based beverage made from whole soybeans that have been soaked, ground, and their liquid extracted, then cooked and filtered. It is completely devoid of elements originating from animals and is intended to operate and look like dairy milk. In addition to naturally existing proteins, carbs, and healthy fats from soybeans, soy milk is frequently supplemented with vitamins and minerals to improve its nutritional value.
Soya chunks are a protein-rich food item that is prepared using defatted soy flour, which is a by-product of soybean oil extraction. Soya chunks are prepared using the process of extrusion cooking, which converts the soy flour into porous, sponge-like granules with a fibrous structure that resembles meat when rehydrated.
Soya chunks are a protein-rich food item that is prepared using defatted soy flour, which is a by-product of soybean oil extraction. Soya chunks are prepared using the process of extrusion cooking, which converts the soy flour into porous, sponge-like granules with a fibrous structure that resembles meat when rehydrated. Soya chunks have a neutral flavor, which helps them absorb the flavors of spices and seasonings while cooking.
Saudi Arabia’s precast concrete market reached USD 1.2 Billion in 2024 as per the IMARC Group, clear proof that off-site construction is rapidly becoming the Kingdom’s go-to building solution. With residential, commercial, and major infrastructure projects multiplying, developers are increasingly turning to precast building solutions to keep pace.
The global emergency food market has emerged as a critical component of household preparedness infrastructure, disaster response frameworks, and government stockpiling programs worldwide. In March 2025, the National Disaster Response Force (NDRF), established in India, conducted a National Capacity Building Competition for State Disaster Response Forces (SDRFs) to improve their readiness and effectiveness in managing collapsed structure emergencies.
The Saudi Arabia sauces and seasonings market size is expanding steadily as consumers embrace more diverse flavors, convenient food formats, and global culinary influences. Evolving lifestyles, greater exposure to international cuisines, and a strong shift toward home cooking have collectively shaped the contemporary marketplace.
The GCC chocolate market has experienced robust expansion in recent years, driven by evolving consumer preferences, rising disposable incomes, and the proliferation of international brands. In 2024, the GCC chocolate market size reached USD 3,200.77 Million, reflecting sustained growth across premium, artisanal, and mass-market segments.
The Gulf Cooperation Council (GCC) region continues to position itself as one of the fastest-evolving markets for packaged beverages, with bottled water standing at the forefront of this transformation. The GCC bottled water market size has expanded steadily in recent years, supported by a strong shift toward health-driven consumption, improved hydration awareness, and evolving lifestyle patterns across the member countries.
India’s pet sector has experienced a remarkable transformation, driven by urbanization, evolving lifestyles, and a stronger emotional bond between people and their companion animals. What was once a niche trend among a few urban families has now become a widespread practice across Indian households, where pets are regarded as integral members of the family.
Shrimp is one of the world’s most precious natural spices, derived from the dried red stigmas of the Crocus sativus flower. Each bloom yields only a few delicate stigmas, which must be carefully hand-harvested, dried, and processed to preserve their vibrant color, distinctive aroma, and rich flavor. The spice’s deep golden-yellow hue, bitter-sweet taste, and unique fragrance are primarily attributed to its key bioactive compounds like crocin, picrocrocin, and safranal.
The Australian craft beer industry has emerged as a significant segment of the broader alcoholic beverages market driven by evolving consumer preferences, rising disposable incomes, and a growing appreciation for artisanal and premium products. Over the past decade, the market has witnessed substantial expansion with craft breweries increasingly occupying a distinct niche in the highly competitive beer sector.
India is witnessing a profound transformation in how its citizens approach health and wellness. The nutritional supplements market of the country has evolved from a niche segment into a mainstream industry serving millions of health-conscious consumers.
Sea salt is a natural mineral product obtained through the solar evaporation of seawater, followed by harvesting, washing, drying, grading, and packaging. Unlike refined table salt, which undergoes heavy chemical processing, sea salt production relies primarily on solar energy and natural crystallization, allowing it to retain trace minerals such as magnesium, calcium, and potassium that contribute to its distinct taste and nutritional value.
Saffron is one of the world’s most precious natural spices, derived from the dried red stigmas of the Crocus sativus flower. Each bloom yields only a few delicate stigmas, which must be carefully hand-harvested, dried, and processed to preserve their vibrant color, distinctive aroma, and rich flavor.
The India edible oil market stands as one of the most dynamic sectors within the country's consumer goods landscape. As households increasingly prioritize quality, health, and convenience, demand for diverse oil varieties continues to surge. The transformation from traditional purchasing habits to modern retail experiences reflects broader shifts in consumer awareness and lifestyle choices.
India's organic food industry stands at the intersection of health consciousness, agricultural innovation, and sustainable practices. As consumers increasingly prioritize chemical-free nutrition and environmental sustainability, the sector faces transformative opportunities alongside significant operational challenges shaped by evolving dietary preferences, technology adoption in agriculture, and regulatory frameworks that collectively define market dynamics.
Japan’s gluten-free foods and drinks market has evolved into a vibrant segment of the country’s growing health and wellness culture. Once catering mainly to individuals with celiac disease or gluten intolerance, gluten-free products now appeal to a broader demographic pursuing balanced, wellness-oriented lifestyles.
The GCC coconut water market is experiencing remarkable momentum as consumer preferences shift decisively toward natural hydration solutions and functional beverages. This transformation is propelled by heightened health consciousness, expanding fitness culture, and growing awareness of the nutritional benefits associated with coconut-based drinks.
The Saudi Arabia online grocery market is experiencing transformative growth, driven by widespread digital adoption, evolving consumer preferences, and strategic government initiatives aligned with Vision 2030. As one of the fastest-growing e-commerce segments in the Middle East, the online grocery sector is reshaping how Saudi consumers shop for everyday essentials.
Onion powder is a dehydrated and ground seasoning that results from the drying of fresh onions into a concentrated powdered form. The process of dehydration removes moisture from the product, while maintaining the flavor, aroma, and pungency characteristics of the onion, thereby making it a stable and ready-to-use ingredient with a longer shelf life. Onion powder can be prepared through various controlled drying, grinding, and screening processes from white, red, or yellow onion varieties.
Japan's animal feed industry stands as a cornerstone of the nation's agricultural infrastructure, supporting domestic livestock production and ensuring food security. The sector encompasses diverse feed products for cattle, swine, poultry, and aquaculture operations that sustain Japan's protein supply chain.
Nutraceuticals are bioactive, health-enhancing products derived from food sources, botanical ingredients, or purified nutrients that provide physiological benefits beyond basic nutrition. They include dietary supplements, functional foods, fortified beverages, herbal extracts, probiotics, omega-fatty-acid formulations, vitamins, minerals, and specialized nutritional compounds. Nutraceuticals are designed to support wellness, prevent nutrient deficiencies, and promote specific health outcomes, including the improvement of immunity, digestive balance, cognitive function, metabolic health, or cardiovascular support.
India's spice industry stands as a vibrant cornerstone of the nation's agricultural economy and cultural identity. As global consumers increasingly seek authentic flavors and natural ingredients, India's position as the world's leading spice producer continues to strengthen.
According to IMARC Group, India's ice cream consumption has grown nearly fourfold over the past decade. Despite this, India's per-capita consumption stands at just ~400 ml per year — far below the global average of ~2.5 litres. That gap is not a weakness. It is the single most compelling argument for the industry's long-term runway.
Millet represents a group of small-seeded cereals, primarily from the Poaceae family, which are grown as staple foods for thousands of years in Asia and Africa and, increasingly, in other parts of the world. These cereals include pearl millet, foxtail millet, finger millet, proso millet, barnyard millet, and little millet.
Milk powder is a type of dehydrated dairy product, which is manufactured by removing almost all moisture from liquid milk by means of various evaporation and drying techniques. The resultant product is a stable, shelf-friendly powder containing most of the nutritional components of milk, including proteins, lactose, minerals, and fats. Milk powder may be prepared from whole, skimmed, or partially skimmed milk, depending on its intended use. The very low moisture content inhibits microbial growth and spoilage; hence, it becomes more feasible regarding transport, storage, and usage in different formulations.
Meat generally denotes the animal tissues that are consumed and mainly include muscle fibers, though the content of fat, connective tissue, and moisture may vary. There are a number of sources, although they are mainly livestock such as cattle, pigs, sheep, poultry, and, in some regions, game animals.
Australia's tea market is at a crossroads, undergoing extraordinary change inspired by changing consumption habits, health awareness, and the explosion of functional drinks.
The Australia dairy industry stands as a vital pillar of the nation's agricultural economy, representing the third-largest rural sector and contributing significantly to both domestic food security and export earnings.
India has emerged as one of the fastest-growing fisheries producers in the world, backed by rising health awareness, export diversification, and evolving aquaculture technology.
Ice cream is a frozen dairy dessert made by blending milk, cream, sugar, and flavorings, then freezing the mixture while incorporating air to give a smooth, creamy texture. The mixture is pasteurized, homogenized, then churned under controlled conditions to prevent the formation of large ice crystals. Depending on the recipe and product category, it may contain stabilizers, emulsifiers, fruits, nuts, chocolate, or other inclusions. It comes in hardpacked ice cream, softserve, gelato, sorbets, and frozen yogurt. The texture, flavor, and quality of this frozen dessert will depend on the ratios of ingredients used and the techniques followed in processing.
The Philippines mushroom industry is undergoing a transformative phase, driven by a growing consumer shift toward functional and nutrient-dense foods. As health awareness rises across both urban and rural populations, mushrooms are increasingly recognized for their high protein, fiber, and antioxidant content. This change is not merely dietary it reflects a broader movement toward wellness-oriented lifestyles that prioritize natural, sustainable, and locally sourced food options. For agribusiness investors and food manufacturers, this evolution signals significant growth potential in both production and value-added segments of the market.
The Vietnam aquaculture market has transformed from traditional fishing practices into one of the world's most dynamic seafood production sectors. Vietnam now ranks as the fourth-largest aquaculture producer globally, supplying markets across Asia, Europe, and the Americas. Understanding what drives this growth is essential for investors, businesses, and policymakers looking to engage with this evolving industry.
French fries are thin strips of baked or deep-fried potatoes with a fluffy inside and a crispy outside. They originated in Europe and are now a common fast-food staple that is consumed as a snack or side dish in many countries. French fries are made mostly from high-starch potatoes and are produced in large quantities by chopping, blanching, frying, and occasionally freezing. They are among the most well-liked and extensively consumed potato-based food products in the world because of their ability to be seasoned, flavored, or combined with condiments like cheese, mayonnaise, or ketchup.
Glucose powder is a crystalline or powdered form of a simple sugar, glucose, derived mainly from sources of starch: corn, wheat, or rice. Glucose powder is obtained by the hydrolysis of starch into glucose by enzymes, followed by purification and concentration of the solution and its drying to yield a readily water-soluble, easily digested carbohydrate powder. Glucose powder is an instant source of energy as it is quickly absorbed in the body, which makes the product valuable in food, beverage, nutraceutical, and pharmaceutical applications. It has a neutral taste, a very high sweetness index compared to regular sugar, and excellent dissolving properties, making it useful in various industrial formulations and household consumption.
Ghee is a class of clarified butter that, conventionally, is prepared by simmering butter until the milk solids separate and caramelize, leaving a golden, fragrant fat. Presently, it is widely used in South Asian, Middle Eastern, and increasingly global cuisines. Ghee has a high smoke point, long shelf life, and rich flavor, which makes it suitable for cooking, frying, and flavor enhancement. During its production, water and milk proteins are removed, making the product a lactose-free fat that contains fat-soluble vitamins and bioactive compounds. Its stability, purity, and distinctive taste make ghee an important culinary and functional ingredient in both traditional and modern food applications.
Fruit powder is made by removing the moisture content of whole fruits through various methods, such as spray drying, freeze-drying, drum drying, or vacuum drying, to get a finely ground, dehydrated powder form. After drying, the fruit is then milled into a stable, lightweight, and shelf-friendly powder that retains much of the fruit's natural flavor, aroma, nutrients, and color. Fruit powders have the essence of fresh fruit in concentrated, easy-to-handle form and are thus highly versatile in food, beverage, nutraceutical, and cosmetic applications. They offer an alternative to fresh fruits in a more convenient manner with longer shelf life and consistent quality for industrial use.
Garlic powder is the dried form of garlic, made by drying fresh garlic cloves and then grinding them to a uniform powder. Garlic dehydration removes moisture while preserving much of the flavor, aroma, and pungency of garlic. This concentrated form offers longer shelf life, easy storage, and consistent taste compared to fresh garlic. Garlic powder is widely used as a seasoning, marinade ingredient, and flavor enhancer in culinary, industrial, and packaged-food applications. Garlic powder imparts the taste of garlic without peeling or chopping into the dishes; therefore, it is very convenient and versatile for both homes and large-scale food manufacturers.
The Frozen food market is highly diversified, encompassing categories like frozen ready meals, fruits and vegetables, meat, seafood, desserts, and bakery items. This robust growth is fueled by fundamental shifts, including urbanization, the rise of dual-income households, and a consumer demand for convenience without compromising nutritional value. Modern freezing technologies ensure high quality and extended shelf life, addressing the critical issue of food waste.
The United States shrimp market stands as one of the most dynamic segments within the global seafood industry. It reached 983,000 Tons in 2024 as per IMARC Group and is projected to reach 1,280,000 Tons by 2033 at a growth rate of 3% from 2025 to 2033. As consumer preferences shift toward healthier protein sources and sustainable options, shrimp has emerged as a cornerstone of American dietary habits. The market reflects transformations in consumer behavior, international trade dynamics, and technological innovation within aquaculture and seafood processing.
The Australia gluten-free food industry is flourishing, powered by a surge in health-conscious consumers, a rise in gluten intolerance cases, and a growing appetite for clean-label, nutritious products. In 2024, the industry reached a notable milestone, hitting USD 361.20 Million, according to IMARC Group. Popular categories like gluten-free bakery items, snacks, dairy, and ready-to-eat (RTE) meals are leading the charge.
The global frozen food industry has undergone a remarkable transformation over the past decade, evolving from a convenience-focused sector into a sophisticated, technology-driven marketplace that prioritizes quality, nutrition, and sustainability. Innovation serves as the primary catalyst for this evolution, fundamentally reshaping consumer perceptions and market dynamics across all geographic regions.
Egg powder is a type of dehydrated product prepared from whole eggs, egg whites, or egg yolks, using a controlled drying process that removes moisture content while preserving the natural nutrients, flavor, and functional properties in fresh eggs. Originally developed to extend the shelf life of eggs, it was also meant to be convenient and easily transportable for food manufacturing, catering, and military or outdoor purposes.
The global ginger market is currently experiencing a remarkable phase of expansion, positioning itself as one of the most dynamic segments within the spice and functional ingredient industries. As consumers worldwide are increasingly gravitating toward natural, health-promoting ingredients, ginger is emerging as a star performer that is capturing attention across multiple sectors, from culinary applications to pharmaceuticals and nutraceuticals. The market is demonstrating robust momentum that industry analysts are tracking with considerable interest.
Coconut is an important tropical crop with a wide array of uses, and hence it is considered the "Tree of Life." The fruit, leaves, trunk, and roots of coconuts yield a wide range of products. Each part has economic value and, therefore, provides a means of livelihood in many rural communities and agro-industrial development in tropical regions such as Southeast Asia, South Asia, and the Pacific Islands.
Coconut yogurt is a plant-based alternative to traditional dairy, made from the rich milk of mature coconuts. This yogurt boasts the same feel and taste as traditional dairy yogurt, all the while catering to vegans, lactose-intolerant, or allergenic consumers. Manufactured like traditional yogurt, this variety is fermented with live bacterial cultures such as Lactobacillus bulgaricus and Streptococcus thermophilus. These same cultures ferment the natural sugars of the coconut milk into lactic acid during processing, creating a thick consistency and giving it that tangy taste typical of yogurt.
The Australian dog food market is undergoing an important transformation, motivated mainly by advancements in AI technology. As more people own pets, they increasingly demand more tailored and nutritious options for dogs. Both technology and artificial intelligence (AI) are important to facilitate this, and reshaping the industry overall.
Coconut sugar, also known as coconut palm sugar, is a natural sweetener derived from the sap of flower buds from the coconut palm tree, Cocos nucifera. It has traditionally been produced in various tropical countries like Indonesia, the Philippines, India, and Thailand, where coconut cultivation is plentiful. This type of sugar is produced by tapping the flower buds of the coconut palm to collect the sap. The sap collected is then heated gently to boil off the water content, concentrate the sugars, and form a thick syrup.
The cashew nut is the kidney-shaped seed of the cashew apple, which is the fruit of the tropical evergreen tree Anacardium occidentale. In trade, the "cashew nut" is the edible kernel extracted from the drupe that lies under the cashew apple; the apple itself is consumed for juices and value-added products in certain markets. Cashew trees are adapted to tropical and subtropical regions with good drainage soils, and leading producers are Vietnam, India, Côte d'Ivoire, Brazil, and some West African states.
Carbonated soft drinks (CSDs) are soft drinks that contain carbon dioxide gas dissolved under pressure, providing the characteristic fizz and invigorating mouth feel that consumers like. They generally consist of carbonated water, sweeteners (sugar, high-fructose corn syrup, or low-calorie alternatives), flavoring ingredients, colorants, and preservatives. The products that fall under the category are colas, lemon-lime beverages, fruit-flavored sodas, tonic water, and sparkling mineral water.
Beer is one of the oldest and most popular alcoholic drinks in the world, made by the fermentation of cereal grains, usually barley, but also wheat, maize, or rice using yeast, hops, and water. The process of brewing turns these natural products into a drink that has intricate flavors, fizz, and a range of alcohol levels, usually 3% to 8% ABV. Hops add bitterness and flavor, with malted barley adding fermentable sugars and color. Beer has developed in centuries from small-scale, craft brewing to an international industrialized market with identifiable styles including lagers, ales, stouts, and pilsners.
The areca nut, or betel nut, is the seed of the areca palm (Areca catechu), a tropical palm mainly grown in South and Southeast Asia. It is one of the oldest described masticatories, chewing historically with betel leaf and lime for its mild stimulant effect. The nut is oval, fibrous, and high in alkaloids like arecoline, which is responsible for the typical flavor and psychoactive effects. Top producers are India, Bangladesh, Sri Lanka, Indonesia, Myanmar, Thailand, and China, with India dominating in both output and consumption.
Apple juice is among the most popular fruit drinks in the world, appreciated for its crisp flavor, inherent sweetness, and health advantages. Apple juice is made by pressing fresh apples and filtering the resulting liquid, containing vital nutrients like vitamin C, potassium, antioxidants, and polyphenols that support immune function, cardiovascular health, and hydration. Based on manufacturing techniques, apple juice can be clear, murky, or concentrated, with each type presenting unique taste profiles and longevity attributes.
Banana powder is a dry, fine, nutrient-dense substance created by dehydrating ripe or unripe bananas using methods like spray drying, freeze drying, or drum drying. It acts as an easy and shelf-stable substitute for fresh bananas, preserving most of their essential nutrients such as potassium, magnesium, vitamin B6, and dietary fiber. The production process includes choosing premium bananas, removing their peels, cutting them into slices, and drying them to an optimal moisture content before milling into a fine powder.
Almonds are nutrient-dense seeds obtained from the fruit of the Prunus dulcis tree, highly prized as a food item and source of industrial raw materials. Botanically drupes, almonds have a hard shell covering the edible kernel, which is rich in proteins, monounsaturated fat, fiber, vitamins, and minerals. The two main varieties are sweet almonds, eaten raw or processed into food items, and bitter almonds, used conventionally to extract oil and flavor after purging. The distinguishing features are mild nutty taste, excellent shelf life if kept properly, and very good compatibility with food as well as non-food uses. Almonds are processed in several steps like cleaning, shelling, blanching, roasting, or oil extraction, depending on the final purpose.
In today's fast-paced world, ready-to-eat food has become a staple for anyone juggling work, family, or travel. These foods offer the comfort of a home-cooked dish, without the time and effort, making them a go-to solution for people who crave convenience. With over 4 billion people living in cities globally and the number of dual-income households rising, the time available for traditional cooking has significantly decreased, creating consistent demand for quick meal options.
Cocoa powder is one of the main derivatives of the cocoa bean, which is derived after cocoa butter has been extracted from it during the chocolate production process. It consists mainly of non-fat cocoa solids, which contain a high content of polyphenols, flavonoids, and alkaloids like theobromine. Famous for its intense color, bitter-sweet taste, and antioxidant activity, cocoa powder comes in natural and alkalized (Dutch-processed) grades, each with distinctive taste profiles and functional characteristics.
Cassava starch or tapioca starch is a white, odorless, fine powder extracted from the cassava plant's roots (Manihot esculenta). Cassava starch has diverse applications in food, pharmaceutical, textile, paper, and adhesives industries because of its unbeatable thickening, gelling, binding, and stabilizing properties. In the food industry, cassava starch finds its applications in bakery, confectionery, dairy, beverages, and gluten-free foods as a substitute for wheat and corn-based starches.
The global vegan yogurt market was valued at USD 3.40 Billion in 2024 and is projected to reach USD 12.21 Billion by 2033, growing at a CAGR of 14.51% from 2025 to 2033. This expansion is marked by ongoing innovation, enhanced consumer personalization, and a deeper commitment to sustainability.
The guacamole market is experiencing a notable change, primarily fueled by an increasing consumer preference for healthy, convenient, and natural food choices. In 2024, the market was valued at USD 1379.9 Million. Guacamole is a creamy avocado-based dip originating from Mexican cuisine has grown into a globally popular food product recognized for its nutritional value and versatility.
Corn starch tableware is a new and ecofriendly solution to traditional plastic disposable items, which aims at solving the increasing environmental issues linked to plastic waste. Comprising mostly of corn starch, a plant-based and renewable resource, the products range from plates, bowls, cups, cutlery, and food containers, all of which are completely biodegradable and compostable.
Artificial Intelligence (AI) is transforming India's beer market at a rapid pace by balancing art with advanced technology. Right from brewing to branding, AI makes fermentation precise, temperature adjustment accurate, and ingredient control efficient, guaranteeing consistent quality and innovation in taste.
Soybean oil is a major vegetable oil used as food obtained from the seeds of the soybean crop. It ranks among the world's most significant edible oils, widely utilized in the preparation of foods, processed food items, industrial purposes, and increasingly in biofuels. High in polyunsaturated fats, especially omega-6 fatty acids, soybean oil has applications in non-food industries such as the production of biodiesel, cosmetics, naphthas, and lubricants.
A bun is a small, round or oval-shaped, soft-textured bread product that can be slightly sweet or savory in taste. Made chiefly of wheat flour, yeast, sugar, salt, water, and fat, buns are found in most cuisines around the globe.
The global dairy market is presently experiencing a profound transformation. This is largely accredited to the strategic integration of artificial intelligence (AI), a technology poised to redefine established paradigms of efficiency and innovation within the industry.
People’s relationship with food is undergoing a profound transformation. No longer just a source of fuel, what individuals eat is now seen as a cornerstone of the overall well-being—a tool to boost immunity, sharpen focus, support digestion, and build long-term resilience. This evolution in consumer consciousness is creating a powerful demand for foods that are functional, organic, and transparently made with real ingredients.
Tequila, once confined to regional consumption in Mexico, has now become a popular spirit worldwide, known for its rich heritage, skilled craftsmanship, and premium quality. Made from blue agave, tequila has attracted international consumers for its distinct flavor, artisanal qualities, and cocktail versatility.
Avocado oil is a nutritious oil pressed from the pulp of avocados (Persea americana), in contrast with most oils, which are seed derived. Avocado oil is valued for its rich content of monounsaturated fats, especially oleic acid, in addition to necessary vitamins like E, A, and D. Avocado oil has a mild, buttery taste and very high smoke point and is used both in food preparation and cosmetics.
Biscuits are dry, baked foods made from flour and usually crisp in texture and flat in shape, eaten frequently as a snack or with a meal. They consist mostly of wheat flour, sugar, fat (butter or vegetable oil), and leavening agents such as baking powder. Flavors and variety may be added using ingredients like milk solids, chocolate, spices, or dried fruits. Biscuits come in sweet and savory forms, varying from cookies and cream-filled to salted crackers. Their shelf life, which is lengthy, convenient packaging, and broad taste appeal have made them a household staple, school staple, and workplace staple worldwide.
Nutritional powders have become essential nutritional supplements created to address the specific health needs of vulnerable demographics, including diabetic patients, the aged, and the sick. When regular food intake is inadequate or compromised, these powders, which are made with specially designed compositions and are high in vital vitamins, minerals, protein, and carbs, offer balanced nourishment. Specialized baby formulas guarantee the best possible growth and development in the early years of life.
Vegetable oils remain among the world’s most widely used agricultural products, essential to food manufacturing, biofuels, cosmetics, and industrial goods.
Learn key financial strategies, operational and capital cost planning essentials for starting a profitable livestock feed production business in 2025.
World Tea Day, celebrated every year on May 21st, is an opportunity to appreciate the rich history, cultural significance, and economic impact of tea. From its origins in ancient China to its status as a global commodity, tea continues to connect people, cultures, and economies.
Mango pulp is the thick, smooth, and semi-liquid product yielded by crushing or pulping ripened mangoes. It is the inner flesh of the mango fruit extracted, without the skin and seeds. Mango pulp is widely utilized as a base for many food items, including mango juice, nectar, drinks, smoothies, ice creams, desserts, and as a topping for pancakes or yogurt. Mango juice is a cool drink prepared from ripe mangoes' juice. To make mango juice, the ripe mangoes are normally peeled, pitted, and the flesh of the mango is squeezed to get the pulp. The pulp is further treated to remove the juice from any remaining fibers or solids.
Soy sauce is a liquid condiment used extensively in cooking and seasoning food. Produced from fermented soybeans, wheat, salt, and water, it provides a deep umami taste that can be used to enhance different foods. It is a common ingredient in Asian cooking and has become popular worldwide in marinades, stir-fries, dips, and processed foods. Come in various forms including light, dark, and low-sodium, soy sauce meets the different consumer tastes and nutritional requirements, rendering it a vital ingredient in the food industry.
Instant coffee is a quick and easy-to-brew coffee beverage that is produced by brewing coffee beans into a liquid that concentrates and evaporates into powder or grain form. It rapidly dissolves in hot water, so it's highly sought after by customers demanding fast and easy coffee brewing. It has a long storage life and is inexpensive, making it popular in homes, offices, and food service establishments. It is fueled by urbanization, hectic lifestyles, and growing demand for convenience drinks.
Glucose syrup and sorbitol syrup are versatile sweeteners widely used across the food and beverage industry. Their ability to enhance texture, retain moisture, and extend shelf life makes them essential ingredients in confectionery, bakery, dairy, and beverage products. Beyond their functional benefits, these syrups contribute to taste enhancement and product stability, catering to consumer preferences for smooth, consistent formulations.
Potato flakes are a highly adaptable food ingredient created by processing cooked potatoes into thin, dehydrated slices. They are often used in soups, snacks, baked goods, and fast meals and are well-known for their usefulness, taste, and simplicity of usage. These flakes provide a reliable and effective option for home cooking, foodservice, and commercial food production while preserving the natural flavour, texture, and nutritional value of fresh potatoes. They are indispensable in a variety of culinary applications due to their lengthy shelf life, lightweight design, and easy rehydration method. Their ability to be used in a variety of recipes, from thickened stews to crispy coatings, further solidifies their position as a basic component of the world's food industry.
Industrial enzymes are biological catalysts that fast-track the chemical process that is involved during the industrial processes. Their use is mainly seen in the food and beverage, pharmaceutical, textile, biofuel, and detergent industries. This enzyme is very effective as it is energy efficient and has cleaner and greener production. Its stability and specificity make it a wonderful tool for breaking complex molecules while improving product quality and yield. Industrial enzymes can enhance the texture of bread, benefit dairy processing, assist in the production of biofuels, and clean wastewater. All these phenomena illustrate that industrial enzymes are a mandatory requirement to manufacture many more products with sustainability and cost effectiveness for multiple industries.
Sorbitol is a sugar alcohol widely used as a sweetener, humectant, and stabilizer in food, pharmaceuticals, and cosmetics. It is made commercially by hydrogenating glucose and is naturally present in fruits like apples and pears. Because of its mild sweetness, low glycaemic index, and ability to retain moisture, sorbitol is a popular ingredient in skincare, dental care, and sugar-free goods. It is also an essential component of industrial processes and a laxative in medical applications.
Inedible beef tallow, a byproduct of the meat processing industry, is derived from beef suet and serves various industrial and commercial purposes. This versatile substance undergoes rendering, a process that separates the fat from solid components. Inedible beef tallow's primary application is in animal feed, as it provides essential fats and energy for livestock, particularly in pet food and livestock supplements. Additionally, it finds use in the cosmetics and personal care industry, contributing to the production of candles, soaps, and skin-care products.
Vitamin C supplements are typically made by extracting ascorbic acid from various sources, such as citrus fruits, or synthesizing it in a laboratory setting. The extracted or synthesized ascorbic acid is then processed and formulated into different types of supplements, including tablets, capsules, chewable, and powdered forms. One of the primary advantages of Vitamin C supplements is their ability to support a healthy immune system.
Over the recent decade, the online food and grocery delivery business in India has witnessed exponential growth. This expansion is attributed to the increasing penetration of smartphones, the affordability and convenience offered by food delivery app services, and the growing availability of low-cost internet services. The industry has become progressively competitive, with numerous local and international players competing for a significant market share. Nonetheless, despite the extreme competition, global players are continuing to make significant investments in India on account of its significant market share in the global online food delivery market.
‘World Food Day’ is celebrated on October 16th as a global responsibility to abolish hunger. 2024’s theme for the day is ‘Right to foods for a better life and a better future’. This theme highlights the significance of enabling access to nutritious food for all, particularly in the face of global challenges, including poverty, climate change, and conflict. In line with this theme, in October 2024, India and the United Arab Emirates (UAE) announced plans for developing a food corridor between the two nations, with an initial investment of over USD 2 Billion (INR 17,000 Crore) in food processing and logistics for food parks. This project significantly reinforces the UAE's food security while providing support to Indian farmers. The initiative is part of a bigger investment strategy targeting over USD100 Billion across key sectors, including manufacturing, infrastructure, and logistics.
A vegan, or a plant-based diet, focuses mainly on consuming fruits, vegetables, grains, legumes, nuts, and seeds. It excludes all animal-derived products and ingredients, including meat, poultry, fish, dairy, eggs, and honey. Nowadays, people are shifting toward vegan diets for a variety of reasons, such as ethical concerns for animal welfare, environmental sustainability, health benefits, and personal preferences.
Functional foods promote overall well-being and offer specific health benefits beyond daily nutrient intake. These benefits encompass enhanced bone health, effective cholesterol management, improved heart health, and eye health. Functional foods include probiotic yoghurt, omega-3 enriched eggs, fortified milk, antioxidant-rich berries, and functional beverages.
Fusion cuisine and beverages blend different ingredients, flavors, or techniques from various culinary or cultural backgrounds to create unique and innovative flavor profiles in dishes and drinks. Fusion beverages encompass both alcoholic and non-alcoholic options, including cocktails, mocktails, smoothies, teas, and more. These beverages span a spectrum from simple combinations to complex and inventive concoctions. Changing taste preferences and global connectivity are the main reasons for the increasing adoption of fusion beverages. They are available in various product types, such as carbonated drinks, fused teas and coffees, fruit juices, fusion alcoholic beverages, energy drinks, sports drinks, and more. These beverages are accessible through off-trade outlets (hypermarkets, supermarkets, discounters, grocery stores, off-license stores, alcohol and confectionery stores, highly specialized retailers, and online stores), as well as on-trade establishments (pubs, bars, cafés, restaurants, clubs, discos, hotels, mass events, and others). Examples of fusion beverages include fruit-infused tea, Asian-inspired cocktails, spicy margaritas, bubble tea creations, mojito variations, and infused waters. Furthermore, fusion cuisine merges elements from diverse culinary traditions, such as Asian, European, African, or Latin American, to craft new and exciting dishes. Examples of fusion cuisine include sushi burritos, Thai basil pizza, kimchi tacos, and more.