Single Super Phosphate Plant Setup Cost in India: Manufacturing Process Flow, Machinery, DPR & Financial Model 2026
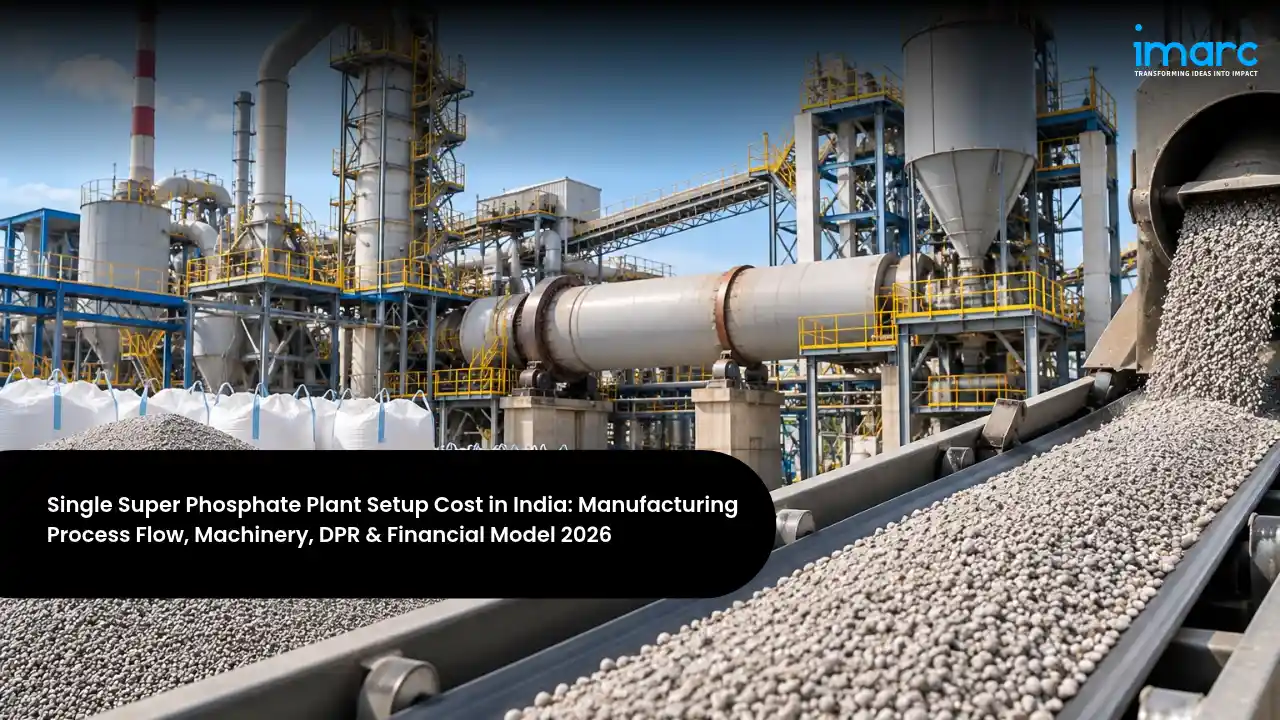
SSP is a phosphatic fertiliser made by reacting finely ground rock phosphate with sulphuric acid, giving a product with about 16% water-soluble phosphate, 11% sulphur, and around 19 to 21% calcium. Because it supplies sulphur and calcium as well as phosphorus, it suits oilseeds, pulses, sugarcane, and vegetables, and it is often the cheapest source of phosphorus for Indian farmers. SSP is covered under the government's Nutrient Based Subsidy scheme, with a subsidy of INR 7,408 per tonne for Rabi 2025-26 and extra support for zinc and boron fortified grades. With India relying heavily on imported DAP, the push for domestic phosphate fertilisers, and simple, proven technology, Single Super Phosphate Manufacturing Plant Setup in India remains a viable opportunity for fertiliser and chemical investors.
Investment depends mainly on annual capacity, whether the plant makes powdered or granulated product, whether it has its own sulphuric acid plant, curing space, fume scrubbing, fortification, and warehousing. The Single Super Phosphate Manufacturing Plant Cost ranges from about INR 25–40 crore for a powdered plant of 50,000 to 60,000 tonnes a year buying sulphuric acid to INR 90–140 crore for a plant of about 120,000 tonnes a year with granulation and a captive acid plant, and INR 200–300 crore for a large unit of 200,000 tonnes a year or more with fortified grades and captive power. Raw materials make up 70 to 80% of operating cost and utilities 10 to 15%, so rock phosphate and sulphur prices shape profitability. A well-run plant typically earns a gross margin of 20 to 30% and a net margin of 8 to 15%.
This guide is written for investors exploring how to start a Single Super Phosphate manufacturing plant in India. It focuses on a plant of about 120,000 tonnes a year producing powdered, granulated, and zincated grades, with a 150 tonne per day sulphur-burning acid plant, sold through dealers and cooperatives, and also explains small units and large plants. It covers products and markets, the demand outlook, the production process flow, machinery and raw materials, location and infrastructure, a detailed cost and financial breakdown, fertiliser control and subsidy approvals, and how a DPR and financial model turn all of this into a bankable plan.
India Market Snapshot
| Key Facts | Details |
|---|---|
| Global Market (2025) | About USD 19.5 Billion |
| Global Market Forecast (2034) | USD 24.35 Billion, 2.5% CAGR |
| NBS Subsidy (Rabi 2025-26) | INR 7,408 per Tonne |
| Fortification Add-On | INR 500 Zinc, INR 300 Boron |
| Typical Plant Capacity | 50,000 – 200,000 Tonnes a Year |
| Indicative Total Investment | INR 25 Crore to 300 Crore |
The snapshot shows a mature product supported by a predictable subsidy and steady demand from Indian agriculture. Rock phosphate and sulphur dominate the cost structure and are largely imported, so raw material sourcing and the subsidy level matter more than technology. Many existing plants run well below capacity, so dealer reach, product quality, and working capital decide who succeeds. The wide investment range reflects a real choice between a small powdered unit and a larger integrated plant.
Investment Highlights
Indicative Project Cost in India (2026)
| Parameter | Value |
|---|---|
| Product Range | Powdered, granulated, zincated, boronated |
| Plant Capacity | 50,000 – 200,000+ Tonnes per Year |
| Total Project Investment | INR 25–40 Crore (small unit) to 200–300 Crore (large plant) |
| Payback Period | 4 – 6 Years |
| Net Profit Margin | 8 – 15% |
| IRR | 15 – 20% |
| Preferred States | Madhya Pradesh, Rajasthan, Gujarat, Maharashtra, Uttar Pradesh, Andhra Pradesh |
| Key Requirement | Rock phosphate, FCO approval, dealers |
These ranges provide a realistic frame for early planning, but actual returns depend on imported rock phosphate and sulphur prices, the subsidy rate announced each season, the timing of subsidy payments, freight to retail points, monsoon conditions, competition from DAP and NPK fertilisers, and tightening rules on fluoride emissions. A site-specific Single Super Phosphate Feasibility Report narrows each of these assumptions to your chosen grades, capacity, location, and markets.
Table of Contents
- What is Single Super Phosphate Manufacturing?
- Why is Single Super Phosphate Manufacturing Growing in India?
- Single Super Phosphate Manufacturing Process Flow
- Raw Materials Required for Single Super Phosphate Manufacturing
- Location, Land & Infrastructure
- Single Super Phosphate Manufacturing Machinery and Equipment
- Single Super Phosphate Manufacturing Plant Setup Cost in India (CapEx & OpEx)
- Financial Analysis and Profitability
- Licenses and Approvals for Single Super Phosphate Manufacturing in India
- Recent Developments in the India Single Super Phosphate Manufacturing Industry
- How a Single Super Phosphate Manufacturing Project Report and DPR Helps Investors
- Frequently Asked Questions
What is Single Super Phosphate Manufacturing?
Superphosphate forms when sulphuric acid converts insoluble tricalcium phosphate in rock phosphate into water-soluble monocalcium phosphate and gypsum. The reaction mass sets in a den, then cures for two to three weeks while the reaction completes, before being broken up, screened, and either sold as powder or granulated for easier handling. Roughly 0.6 tonnes of rock phosphate and 0.37 tonnes of sulphuric acid make one tonne of product. Water-soluble and total phosphate, free acid, moisture, sulphur content, particle size, and granule strength decide quality, and all are set by the Fertiliser Control Order.
Commercially, the fertiliser is sold through private dealers, cooperatives, and state marketing federations to farmers growing oilseeds, pulses, sugarcane, cotton, vegetables, and cereals, and to companies that blend it into mixed fertilisers. A Single Super Phosphate Manufacturing Plant can serve all these channels by offering powder, granules, and fortified grades in 50 kg bags. Buyers value consistent quality, granule strength, timely supply before sowing, attractive dealer margins, and prices fixed within the subsidy framework.
- Oilseeds & Pulses: Sulphur boosts oil and protein content.
- Sugarcane & Cotton: Phosphorus and calcium for cash crops.
- Vegetables & Fruits: Balanced nutrition for horticulture.
- Mixed Fertilisers: Base for blends and granulated NPKs.
The Main Grades and Products
Choosing the product mix is the most important commercial decision, because it determines equipment, subsidy, and customers:
| Product | Description | Key Property | Primary Demand |
|---|---|---|---|
| Powdered Grade | Cured, screened | Lowest cost | Dealers, blenders |
| Granulated Grade | Rotary drum granules | Easy application | Farmers |
| Zincated Grade | Zinc fortified | Extra subsidy | Zinc-deficient soils |
| Boronated Grade | Boron fortified | Extra subsidy | Oilseeds, fruits |
| Sulphuric Acid | Captive surplus | Merchant sales | Chemical users |
| Steam & Power | Acid plant heat | Energy credit | Captive use |
These choices shape the whole plant. Powdered product is cheapest to make but harder to sell to farmers who prefer granules, while granulation adds dryers, granulators, and fuel cost, but improves acceptance and prices. Fortified grades earn extra subsidy, and a captive acid plant lowers raw material cost and generates steam and power. Most new entrants start with powder and granules, then add fortified grades and an acid plant as volumes grow.
Why is Single Super Phosphate Manufacturing Growing in India?
Key Growth Drivers in India and Export Markets
Demand is supported by government policy and by the agronomic value of sulphur and phosphorus:
- Subsidy support: The NBS scheme keeps prices affordable for farmers.
- Sulphur deficiency: Many Indian soils lack sulphur, which this product supplies.
- Import substitution: Domestic phosphate fertiliser reduces reliance on imported DAP.
- Oilseed and pulse missions: Government programmes promote crops that respond well to sulphur.
- Neighbouring markets: Nepal, Bhutan, and Bangladesh offer small export outlets.
India-Specific Market Opportunity
| Segment | Market Context | Manufacturing Role |
|---|---|---|
| Private Dealers | Rural networks | Branded bags |
| Cooperatives | State federations | Bulk supply |
| Fertiliser Majors | Marketing tie-ups | Contract supply |
| Mixture Makers | Blended products | Powdered grade |
The strongest opportunity for new entrants lies in regions with strong oilseed, pulse, and sugarcane demand, in marketing tie-ups with large fertiliser companies that sell under their brands, and in fortified grades that earn extra subsidy. Producers that combine reliable rock phosphate supply, a captive acid plant, consistent quality, and a strong dealer network will be best placed to grow.
Single Super Phosphate Manufacturing Process Flow
Understanding the process helps you plan equipment, layout, and where cost and quality are decided. The flow runs from rock phosphate receipt and grinding through acid dilution, mixing and reaction, den setting, pile curing, disintegration and screening, granulation, drying and cooling, and fortification and bagging, with fume scrubbing throughout. Grinding fineness and acid ratio decide how completely the rock reacts, while curing decides the final soluble phosphate.
The Single Super Phosphate Manufacturing Process Flow
The sequence below reflects a plant with granulation and a captive acid plant. Powder-only units stop after curing and screening.
| Unit Operation | Key Activity |
|---|---|
| Rock Receipt | Grade tested |
| Grinding | Ball mill, fine powder |
| Acid Dilution | To reaction strength |
| Mixing & Reaction | Rock and acid |
| Den Setting | Continuous den |
| Pile Curing | Two to three weeks |
| Disintegration | Lumps broken |
| Granulation | Rotary drum |
| Drying & Screening | Rotary dryer, screens |
| Fortification & Bagging | Zinc, boron, 50 kg bags |
Two factors decide profitability across this flow. The first is conversion efficiency, because rock phosphate is the largest cost, so fine grinding, the right acid ratio, and proper curing turn more of the phosphate into the water-soluble form that the subsidy and buyers pay for. The second is acid cost, since a captive sulphur-burning acid plant usually makes acid far cheaper than buying it and supplies steam and power that cut utility bills.
Raw Materials Required for Single Super Phosphate Manufacturing
The main raw materials are rock phosphate of about 30 to 32% phosphate content, mostly imported from Jordan, Morocco, Egypt, and Togo, with some domestic rock from Rajasthan and Madhya Pradesh, and sulphuric acid, either bought or made from sulphur in a captive plant, along with zinc and boron compounds for fortified grades, and HDPE bags.
| Raw Material | Role in Product | India Sourcing | % of OpEx |
|---|---|---|---|
| Rock Phosphate | Phosphate source | Mostly imported | 45–55% |
| Sulphur or Acid | Reacts with rock | Refineries, imports | 15–20% |
| Micronutrients | Fortification | Domestic suppliers | 1–2% |
| Packaging Bags | HDPE bags | Domestic suppliers | 4–6% |
| Process Chemicals | Scrubbing, other | Domestic suppliers | 0.5–1% |
Rock phosphate is by far the largest cost, and its price and availability depend on global markets, freight, and supplier countries, which have been disrupted by conflicts in recent years. Long-term contracts with overseas suppliers, using domestic rock where its quality allows, buying sulphur from Indian refineries, and holding enough stock for the cropping seasons help manage cost and supply risk.
Location, Land & Infrastructure
Site selection for a superphosphate plant is driven by access to rock phosphate from ports or domestic mines, sulphur or acid supply, and proximity to major consuming regions. Other factors include road and rail links for bulky inputs and bags, reliable power, space for curing and warehousing, and approval for chemical units. Because the product is low in value per tonne and must be delivered to retail points across the state, locating near the main farming markets with good access to ports or mines is usually the best option.
Choosing the Best Location for Single Super Phosphate Manufacturing Plant Setup
| State / Region | Why It Works | Key Advantage |
|---|---|---|
| Madhya Pradesh | Soybean belt, rock | Demand, raw material |
| Rajasthan | Udaipur rock mines | Domestic rock |
| Gujarat | Kandla, Mundra ports | Imported rock |
| Maharashtra | Cane, cotton, pulses | Large demand |
| Uttar Pradesh | Largest farm state | Volume demand |
| Andhra Pradesh | Ports, oilseeds | Southern market |
Madhya Pradesh combines a large soybean belt with domestic rock and a cluster of existing units, while Rajasthan offers domestic rock phosphate and Gujarat provides port access for imports. Maharashtra and Uttar Pradesh are among the largest fertiliser markets, and Andhra Pradesh offers ports and oilseed demand. The final choice should weigh rock and acid access, freight to markets, and land cost.
Quality, Safety and Environmental Systems
Every grade must meet the specifications in the Fertiliser Control Order for water-soluble and total phosphate, free acid, moisture, and sulphur, and state inspectors regularly sample product at plants and dealers. A credible plant needs a laboratory for these tests, batch records, and bag marking as required by law. Safety focuses on handling sulphuric acid and molten sulphur, dust from grinding, and fumes from the reaction. Environmental systems cover scrubbing of fluorine compounds released during reaction, sulphur dioxide control in the acid plant, dust collection, and effluent treatment. An experienced Single Super Phosphate Manufacturing Consultant in India can help plan capacity, grades, equipment, and approvals so the plant meets regulatory and customer requirements from the start.
Infrastructure Requirements (120,000 TPA Plant)
| Infrastructure Element | Specification | India-Specific Note |
|---|---|---|
| Total Land Area | 15 – 25 acres | Industrial area |
| Rock Storage | Covered shed | Season stock |
| Acid Plant Area | 150 TPD unit | Sulphur storage |
| Curing Shed | Large covered area | Two to three weeks |
| Granulation Plant | Drum, dryer | Fuel supply |
| Warehouse | Bagged product | Seasonal stocks |
| Scrubbers & Lab | Fume control, QC | FCO testing |
Large covered sheds for rock storage, curing, and finished goods are the most important infrastructure requirements, since curing takes weeks and sales follow the cropping seasons. An acid plant with sulphur storage, a granulation plant, effective fume scrubbing, and good road access complete the core needs.
Single Super Phosphate Manufacturing Machinery and Equipment
The equipment set covers rock crushing and grinding, acid preparation, reaction, curing, granulation, drying, pollution control, acid making, and bagging. The acid plant, granulation and drying line, and reaction section account for most of the machinery budget.
| Equipment | Function | Key Specification |
|---|---|---|
| Rock Crusher | Break rock | Jaw or hammer |
| Ball Mill | Grind rock | With classifier |
| Acid Dilution & Mixer | React rock and acid | Cone or pug mill |
| Continuous Den | Set product | Slat conveyor |
| Disintegrator | Break lumps | Cage mill |
| Rotary Granulator | Form granules | Drum type |
| Rotary Dryer & Cooler | Dry granules | Hot air |
| Screening Unit | Size product | Vibrating screens |
| Fume Scrubbers | Capture fluorine | Water scrubbing |
| Sulphuric Acid Plant | Make acid | Sulphur burning, DCDA |
| Bagging Machine | Fill bags | Automatic weighing |
Machinery should follow the product plan. A small unit needs a crusher, ball mill, mixer, den, disintegrator, scrubbers, and bagging, buying acid from outside, while a mid-sized plant adds granulation, drying, screening, and a captive acid plant. Large plants add bigger lines, power generation from acid plant steam, and fortification systems, and a good stock of mill liners, conveyor parts, and acid plant spares is essential at every scale.
Single Super Phosphate Manufacturing Plant Setup Cost in India (CapEx & OpEx)
The tables below break down capital and operating costs for a plant of about 120,000 tonnes a year in India. The final Single Super Phosphate Investment Cost for your project will depend on capacity, granulation, acid plant integration, fortification, warehousing, land cost, and location.
Capital Expenditure (CapEx) Cost Structure
| CapEx Component | % of Total CapEx | What It Covers |
|---|---|---|
| Reaction & Curing Section | 20–26% | Mills, mixer, den |
| Granulation & Drying | 15–20% | Granulator, dryer |
| Sulphuric Acid Plant | 20–26% | Burner, converter |
| Pollution Control & Utilities | 8–12% | Scrubbers, power |
| Civil Works, Land & Site | 12–16% | Sheds, warehouse |
| Working Capital | 10–15% | Rock, subsidy dues |
The reaction section, granulation line, and acid plant make up most of the fixed capital, while working capital is significant because rock is imported in bulk, stocks build before each season, and subsidy is paid only after sales are recorded. Because of this, a detailed Single Super Phosphate Business Plan should model sales by grade and region, rock and sulphur prices, subsidy rates and payment timing, freight to retail points, dealer margins, seasonal demand, and working capital together, so that funding supports the business through cycles in raw material prices and subsidy.
Operating Expenditure (OpEx) Cost Structure
| OpEx Component | % of Total OpEx | India-Specific Note |
|---|---|---|
| Raw Materials & Packaging | 70–80% | Rock, sulphur, bags |
| Utilities | 10–15% | Power, dryer fuel |
| Labour | 3–5% | Operators, loaders |
| Maintenance | 2–3% | Mills, conveyors |
| Logistics | 3–5% | Delivery to retail |
| Overheads & Testing | 1–2% | FCO testing, admin |
With raw materials making up most of the cost, margins depend on rock and sulphur prices, conversion efficiency, the subsidy rate, utilisation, and freight. A good operating model tracks rock and acid per tonne, water-soluble phosphate achieved, power and fuel per tonne, freight per tonne, and realised prices including subsidy, and tests results against higher rock prices, lower subsidy rates, or weaker seasonal demand.
Financial Analysis and Profitability
Based on analysis of a 120,000 TPA plant, the financial profile is moderate and policy driven, supported by a stable subsidy and steady farm demand, but returns depend heavily on raw material costs, subsidy levels, and utilisation, which is low at many existing plants. The profitability of Single Super Phosphate manufacturing business in India improves markedly with a captive acid plant, reliable rock supply, granulated and fortified grades, a strong dealer network or a marketing tie-up with a larger company, and tight control of working capital.
| Financial Metric | Indicative Value | India Context |
|---|---|---|
| Gross Profit Margin | 20–30% | Subsidy linked |
| Net Profit Margin | 8–15% | After depreciation, taxes |
| Payback Period | 4–6 Years | Moderate capital |
| IRR (Internal Rate of Return) | 15–20% | Higher with acid plant |
| Capacity Utilization (stable ops) | 50–75% | Seasonal demand |
| Break-even Capacity Utilization | 40–50% | Moderate fixed costs |
Utilisation and integration decide where a plant lands within these ranges. Many Indian plants run at well under two-thirds of capacity because of seasonal demand and limited marketing reach, so the ability to sell steadily matters greatly. Plants with captive acid, granulation, and fortified grades earn noticeably better margins than powder-only units buying acid.
Returns can be strengthened by building a captive acid plant, using acid plant steam for power, adding granulated and fortified grades, tying up with established fertiliser marketers, supplying mixture makers, and developing domestic rock sources where quality permits.
Key Risks and Mitigation
The main risks are rock phosphate and sulphur price swings, changes in subsidy rates, delayed subsidy payments, low utilisation, quality failures in state sampling, and fluoride emission compliance. Price risk is reduced by long-term contracts and captive acid; subsidy risk by careful planning around seasonal rates; payment risk by adequate working capital; utilisation risk by marketing tie-ups; quality risk by strict testing; and compliance risk by effective scrubbers. Promoters often work with a Single Super Phosphate Business Plan Consultant in India to test these scenarios before committing capital.
Licenses and Approvals for Single Super Phosphate Manufacturing in India
Approvals for a superphosphate plant centre on the Fertiliser Control Order, subsidy registration, and environmental and safety requirements, along with standard business registrations. Promoters setting up a Single Super Phosphate Manufacturing Plant in India generally need the following:
- FCO Certificate: Certificate of manufacture from the state agriculture department under the Fertiliser Control Order.
- Subsidy Registration: Registration with the Department of Fertilizers to claim NBS subsidy, with quality and sales reporting.
- Environmental Approvals: Environmental clearance where applicable, and consent to establish and operate.
- Hazardous Chemicals: Compliance for sulphuric acid and sulphur storage, with on-site emergency plans.
- Boiler Registration: Registration of the acid plant waste heat boiler under boiler regulations.
- Factory & Fire: Factory license, building plan approval, and fire NOC.
- Business & Trade Registrations: Business registration, GST, Udyam, trademark, and Import Export Code.
The FCO certificate and subsidy registration are usually on the critical path, since product cannot be sold under the subsidy scheme without them. Preparing quality systems and documentation early shortens the time from investment decision to regular subsidised sales.
Note: The exact approvals, registrations, licenses, and certification requirements may vary depending on factors such as plant location, capacity, products, state pollution control categories, customer specifications, and applicable regulations. Businesses are advised to undertake a detailed regulatory assessment during the project planning stage to ensure full compliance and timely implementation.
Recent Developments in the India Single Super Phosphate Manufacturing Industry
Several recent developments give useful context for investors considering this market:
- Subsidy rates: In January 2026, the government set the Rabi 2025-26 subsidy for this grade at INR 7,408 per tonne, with a total NBS budget of about INR 37,952 crore.
- Regional exports: In August 2025, BVFCL signed a five-year deal to supply this fertiliser and others to Bhutan's National Seed Centre.
- Rock supply: In March 2025, industry reports said a deal for about 250,000 tonnes a year of rock phosphate from Togo was in advanced talks.
- Marketing tie-ups: In June 2024, HURL signed agreements with manufacturers to market 5 lakh tonnes across 13 states in FY2024-25.
The common thread is steady policy support, efforts to secure rock phosphate supply, and new marketing arrangements that help smaller plants sell more. New entrants who secure raw materials, integrate acid production, and partner with strong marketers will be best placed to grow.
How a Single Super Phosphate Manufacturing Project Report and DPR Helps Investors
A detailed DPR provides a structured roadmap for the venture, from market demand and grade selection to rock and sulphur sourcing, process and equipment selection, plant design, approvals, and economics. It helps investors decide the right grades, capacity, and location, estimate capital and operating expenditure, assess profitability, and identify risks before committing funds.
At its core is a detailed Single Super Phosphate Financial Model covering sales by grade, region, and season, rock phosphate and sulphur prices, acid plant economics, subsidy rates and payment timing, freight to retail points, dealer margins, labour, utilities, working capital, debt servicing, cash flows, break-even, return on investment, and payback under different price and subsidy scenarios. Banks and investors rely on this model to judge long-term viability, which is why many promoters appoint a Single Super Phosphate Plant Project Report Consultant in India to prepare the report and validate its assumptions against current market data.
For a project of this kind, a strong DPR also clarifies the raw material sourcing plan, the case for a captive acid plant, the grade mix, and the marketing strategy, which together are the factors most likely to decide success.
Frequently Asked Questions
What are the first steps to set up a single super phosphate manufacturing plant in India?
Start by securing rock phosphate and acid or sulphur supply, and decide whether to sell through your own dealers or a marketing tie-up. Then commission a feasibility study and DPR, choose a site near demand and raw materials, obtain environmental approvals, the FCO certificate, and subsidy registration, install the plant, and build distribution.
How much does it cost to set up a single super phosphate manufacturing plant in India?
Investment ranges from about INR 25–40 crore for a powdered plant of 50,000 to 60,000 tonnes a year to INR 90–140 crore for a plant of about 120,000 tonnes a year with granulation and an acid plant, and INR 200–300 crore for a plant of 200,000 tonnes a year or more.
What are the main steps in making single super phosphate?
The flow runs from rock receipt and grinding through acid dilution, mixing and reaction, den setting, pile curing, disintegration, granulation, drying and screening, and fortification and bagging.
Which machinery does the single super phosphate manufacturing plant need?
Key equipment includes rock crushers, ball mills, acid dilution and mixing units, continuous dens, disintegrators, rotary granulators, dryers and coolers, screening units, fume scrubbers, a sulphuric acid plant, and bagging machines.
What raw materials are used for single super phosphate manufacturing?
The main raw materials are rock phosphate and sulphuric acid, or sulphur for a captive acid plant, along with zinc and boron compounds for fortified grades, process chemicals, and HDPE bags.
How profitable is single super phosphate manufacturing in India?
A well-run plant typically earns a 20 to 30% gross margin and an 8 to 15% net margin, with payback in about 4 to 6 years. Profitability depends on raw material prices, subsidy rates, utilisation, and integration.
Which approvals does the single super phosphate manufacturing plant need in India?
Typical approvals include an FCO certificate of manufacture, subsidy registration with the Department of Fertilizers, environmental approvals, hazardous chemical compliance, boiler registration, factory and fire approvals, and GST, Udyam, trademark, and Import Export Code registrations.
How do I get a feasibility study or DPR for the single super phosphate manufacturing project?
A detailed feasibility study and DPR covers market demand, grades, raw material sourcing, technology, plant design, approvals, and full financials. Investors usually engage a Single Super Phosphate Manufacturing Feasibility Study Consultant with experience in fertiliser and chemical projects to prepare the report and validate it for lenders.
Our Clients
Contact Us
Have a question or need assistance?
Please complete the form with your inquiry or reach out to us at
Phone Number
+91-120-433-0800+1-201-971-6302
+44-113-547-7077
Previous Post

Tying wire is soft, annealed mild steel wire, usually 18 or 20 gauge, that site workers twist around the crossing points of reinforcement bars to hold them in place while concrete is poured. It is also used for fencing, bundling, packaging, and supporting crops in orchards and vineyards.
Carbon fiber is a strong, stiff, and very light material made of thin filaments of almost pure carbon, produced mainly by heating polyacrylonitrile (PAN) fibers in carefully controlled stages.
Xanthan is a natural polysaccharide made by fermenting sugars with the bacterium Xanthomonas campestris. Even at very low doses it thickens, stabilises, and suspends, and it holds its viscosity across wide ranges of temperature, pH, and salt, which makes it one of the most widely used hydrocolloids in sauces, dressings, bakery, gluten-free foods, beverages, pharmaceuticals, toothpaste, cosmetics, and oilfield drilling fluids.
Crop protection products such as insecticides, herbicides, fungicides, and plant growth regulators help farmers control pests, weeds, and diseases that would otherwise destroy a large share of the harvest.
CMC, also called cellulose gum, is a water-soluble polymer made by reacting cellulose from cotton linters or wood pulp with caustic soda and monochloroacetic acid.
Insulating oil is the highly refined liquid that fills power and distribution transformers, reactors, switchgear, and instrument transformers, where it insulates live parts, carries heat away from windings, and protects paper insulation from moisture and oxygen.
Aluminium pipes and tubes are light, strong, corrosion-resistant, and easy to bend, cut, and join, which makes them widely used in farm sprinkler systems, air conditioners and refrigeration, vehicles, scaffolding and construction, solar mounting structures, furniture, and electrical installations.
Commercial ammonium carbonate, long known as baker's ammonia or salt of hartshorn, is a white crystalline solid made from ammonia, carbon dioxide, and water.
Magnesium is the lightest structural metal, about a third lighter than aluminium, and is essential as an alloying element in aluminium cans, sheets, and castings, as a desulphurising agent in steel making, as a reducing agent for titanium and other metals, and increasingly in lightweight die-cast parts for vehicles and electronics.
Biodegradable plastics are polymers that microorganisms can break down into water, carbon dioxide, and biomass under composting or natural conditions, offering an alternative to conventional plastics for carry bags, garbage bags, mulch films, food packaging, and disposable items.
Ammonium bicarbonate is a white crystalline salt made by reacting ammonia, carbon dioxide, and water. Known in bakeries as baking ammonia, it is a leavening agent that leaves no residue on heating, which makes it ideal for biscuits, crackers, and cookies, and it is also used as a blowing agent in rubber and plastics, in dyes, pharmaceuticals, and ceramics, as a nitrogen fertilizer in parts of Asia, and to dissolve plaster of Paris idols after festivals.
Aluminum is light, strong, corrosion-resistant, and endlessly recyclable, which makes it essential for vehicles, buildings, power cables, packaging, and consumer goods.
AAC block adhesive, also called block jointing mortar or thin-bed mortar, is a ready-mixed dry powder of cement, fine graded sand, and polymer additives that is mixed with water on site to bond autoclaved aerated concrete (AAC) blocks with joints of only 2 to 4 mm.
Ethyl acetate is a colourless, fast-evaporating solvent with a mild fruity odour, made mainly by esterifying ethanol with acetic acid. It is one of the most widely used industrial solvents, found in flexible packaging inks, paints and coatings, adhesives, pharmaceutical processing, food flavours and decaffeination, and nail polish removers.
Acetylene is a colourless, highly flammable gas that burns with oxygen at around 3,100°C, the hottest flame of any common fuel gas. This makes it the standard gas for oxy-acetylene welding, cutting, brazing, and flame hardening, and it is also used in laboratories, glass working, and as a feedstock for chemicals such as acetylene black.
Titanium nitride (TiN) is an extremely hard, gold-coloured ceramic with a melting point near 2,950°C, good electrical conductivity, and excellent wear and corrosion resistance.
Iron powder is finely divided iron, usually 98 to 99.5% pure, made by atomising molten iron with high-pressure water, by reducing iron ore or mill scale, or, for special grades, by electrolysis and carbonyl processes.
High-purity quartz is silica (SiO2) refined to 99.95% purity or higher, with total impurities measured in parts per million. It is the raw material for the quartz crucibles used to grow silicon ingots for solar cells and semiconductors, for fused quartz tubes, rods, and glassware used in chip fabs, lighting, and optical fibre, and for specialty fillers in electronics.
Black sulphur, known in the trade as Sulphur Black 1 (C.I. 53185), is the most widely used sulphur dye. It is the low-cost, deep black that gives denim, workwear, socks, and cotton fabrics their fast black and grey shades.
Aluminium granules are small, free-flowing particles of aluminium or aluminium alloy, usually between 0.05 mm and 10 mm in size, made by melting aluminium and breaking the molten stream into droplets that solidify into discrete particles.
Methanol is one of the world's most important basic chemicals, used to make formaldehyde, acetic acid, MTBE, chloromethanes, solvents, pharmaceuticals, and pesticides, and increasingly as a clean fuel for blending, marine use, and hydrogen carriage.
Lubricating oils reduce friction, wear, and heat in engines, gearboxes, hydraulic systems, turbines, and industrial machinery, and they are essential to every vehicle, factory, and power plant. They are made by blending base oils with additive packages that give each grade its performance.
Fertilizers supply the nitrogen, phosphorus, potassium, and secondary and micronutrients that crops need, and they are central to India's food security. India consumed about 32.9 million tonnes of nutrients in 2024-25, making it one of the world's largest fertilizer markets, yet domestic production meets only about two-thirds of demand, with heavy reliance on imported DAP, urea, potash, and raw materials.
Plastic products are everywhere in modern life, from packaging, pipes, and household goods to automotive parts, appliances, electrical fittings, medical devices, and agricultural films. India's plastics market was valued at about USD 46.8 billion in 2025 and is expected to grow by more than 6% a year, driven by packaging, infrastructure, automobiles, consumer goods, and agriculture.
Oleochemicals are chemicals made from vegetable oils and animal fats instead of petroleum, and they include fatty acids, fatty alcohols, glycerine, esters, and amines.
Hydrogen peroxide is one of the cleanest oxidising and bleaching chemicals in industrial use, because it breaks down into only water and oxygen. It bleaches pulp, paper, and cotton, treats effluents, disinfects, sterilises food packaging, and serves as a reagent in chemical and pharmaceutical synthesis, while ultra-pure grades are used to clean silicon wafers in semiconductor and solar cell fabs.
Sorbitol is a sugar alcohol made from glucose that keeps toothpaste moist, sweetens sugar-free sweets and syrups, binds tablets, and serves as a building block for vitamin C, surfactants, and polyols.
Silica in its manufactured, amorphous forms is a hidden ingredient in everyday products: it reinforces tyres and rubber goods, cleans teeth in toothpaste, keeps food and feed powders free-flowing, carries agrochemicals and vitamins, and adds matting to paints and coatings.
Lithium iron phosphate (LFP) batteries have become the chemistry of choice for grid storage, electric two- and three-wheelers, buses, telecom towers, and home inverters, because they are safe, long-lasting, and free of cobalt and nickel.
Argon is an inert gas that makes up about 0.93% of the air we breathe, and it plays a quiet but essential role in modern industry. It shields welds in fabrication shops, refines stainless steel, protects silicon crystals in solar ingot furnaces, fills insulated windows, and supports semiconductor and electronics production.
Zinc is the metal that protects steel from rust. Most of it is used to galvanise steel for construction, power transmission towers, highway crash barriers, solar mounting structures, automobiles, and appliances, while the rest goes into die-cast components, brass, zinc oxide, chemicals, and batteries.
Epoxy resins are high-performance thermosetting polymers that cure into hard, chemically resistant, and strongly adhesive materials. They are the backbone of protective and industrial coatings, floor coatings, structural adhesives, wind turbine blades and other composites, electrical insulation, printed circuit boards, and construction chemicals.
Particleboard is an engineered wood panel made by pressing wood particles with resin under heat. It is flat, uniform, easy to machine, and far cheaper than solid wood or plywood, which makes it the core material for modular kitchens, wardrobes, office furniture, shelving, and ready-to-assemble furniture.
Polylactic acid (PLA) is the most widely produced bio-based and compostable plastic. It is made from sugars in crops such as sugarcane and maize, and it can replace conventional plastics in food containers, cups, cutlery, films, fibres, 3D printing filament, and medical devices.
Construction and demolition (C&D) waste, the concrete, bricks, mortar, stone, tiles, and soil left behind when buildings, roads, and bridges are built, repaired, or pulled down, is one of the largest waste streams in India. Estimates range from 150 to more than 500 million tonnes a year, yet only a small share is recycled, while the rest is dumped on vacant land, riverbanks, and roadsides.
Cold-rolled coil is the precision end of the flat steel business. Car bodies, two-wheeler parts, refrigerators, washing machines, steel furniture, electrical panels, precision tubes, drums, and barrels all rely on its smooth surface, tight thickness tolerances, and excellent formability, and it is also the base for galvanised and colour-coated sheet used in roofing and appliances.
Biofuels are fuels made from crops, residues, and waste, and they have become a central part of India's plan to cut crude oil imports, support farmers, and reduce emissions.
Natural gas is the cleanest-burning fossil fuel and a vital feedstock for India's fertiliser, refining, petrochemical, power, ceramics, and glass industries, as well as the fuel behind city gas networks that supply CNG to vehicles and piped gas to homes.
Green methanol is methanol made from renewable sources rather than coal or natural gas, either by combining green hydrogen with captured carbon dioxide (e-methanol) or by converting biomass and biogas (bio-methanol).
Glass can be recycled endlessly without losing quality, and every tonne of clean cullet fed back into a furnace saves raw materials, energy, and carbon emissions.
GFRP composites combine strong glass fibres with a tough polymer resin to create products that are light, rust-proof, electrically non-conductive, and very strong for their weight.
India generated about 4.1 million tonnes of plastic waste in 2022-23, and the volume has been growing steadily with packaging, retail, and consumer goods. Plastic that is not recycled clogs drains, pollutes rivers and land, and is often burned in the open.
India's towns and cities generate around 1.6 lakh tonnes of municipal solid waste every day, and that figure is rising with urbanisation and consumption. For decades much of this waste was dumped on open land, creating more than 2,400 dumpsites holding an estimated 25 crore tonnes of legacy waste.
Hot-rolled coils are the workhorse of the flat steel industry. Pipes and tubes, LPG cylinders, boilers, truck chassis, wheels, railway wagons, ship plates, pre-engineered buildings, and cold-rolled and coated steel all start life as HR coil. India is the world's second-largest steel producer, with crude steel output of about 170 million tonnes in 2025-26, and flat products now make up more than half of domestic steel demand.
Copper is essential to electrification. It carries power through cables, transformers, motors, electric vehicles, solar and wind installations, data centres, and electronics, and it can be recycled again and again without losing its properties.
Charcoal is one of the oldest fuels and carbon materials, yet demand for it is expanding in new directions. Beyond its traditional use as a cooking fuel, charcoal is now an export product in the form of barbecue and shisha briquettes, a feedstock for activated carbon used in water and air purification, a renewable reductant for metallurgy, and, as biochar, a soil enhancer and carbon removal product.
Lithium hydroxide is one of the two key lithium chemicals that feed the battery industry. Battery-grade lithium hydroxide monohydrate is the preferred lithium source for high-nickel NMC and NCA cathodes used in long-range electric vehicles, while technical grades go into lubricating greases, ceramics, and specialty chemicals.
Sebacic acid is a bio-based, ten-carbon dicarboxylic acid made from castor oil. It is a key building block for high-performance nylons such as nylon 6,10 and 10,10, plasticizers such as dibutyl and dioctyl sebacate, synthetic lubricants and greases, corrosion inhibitors in engine coolants, polyurethanes, alkyd resins, adhesives, cosmetics, and pharmaceutical intermediates.
PET bottles are the most widely used rigid packaging format for beverages and many consumer products. They are light, clear, shatter-resistant, and fully recyclable.
Amino acids are the building blocks of protein and among the most important biochemicals in the modern economy. Lysine, methionine, threonine, and tryptophan are added to poultry, pig, and aquaculture feed to improve growth and reduce feed costs.
Aluminum extrusions are everywhere in modern life. They form windows, doors, facades, and partitions in buildings, solar panel frames and mounting structures, electric vehicle battery enclosures and body parts, rail coaches, electronics housings, furniture, and industrial machinery.
Lithium-ion cells are the energy building block of the electric and digital economy. Electric two-wheelers, cars, buses, grid-scale energy storage, telecom towers, inverters, power tools, laptops, and smartphones all depend on them.
Walk into almost any Indian home painted in the last decade and the walls are likely coated in emulsion paint. Water-based, low in odour, washable, and available in thousands of shades from a dealer's tinting machine, emulsions have steadily replaced distempers and solvent-based finishes as households upgrade and repaint.
Almost everything electrical in India runs on copper wire, from the house wiring hidden inside walls to the windings of fans, motors, and transformers, the harnesses in cars and electric vehicles, and the cables that connect solar parks to the grid.
Activated carbon is the quiet workhorse of purification. A single gram can hold hundreds of square metres of internal surface area, which is why it is used to clean drinking water, remove odours and pollutants from air, decolourise sugar, purify medicines, and recover gold from ore.
Setting up a Paint Manufacturing Plant in India is a formulation-and-dispersion venture with relatively accessible entry capital, powered by a booming housing and construction market, rising incomes, rapid urbanisation, and a steady shift from unorganised to branded products.
Setting up a NdFeB Magnet Manufacturing Plant in India is a strategically critical, technology-intensive venture positioned at the heart of the clean-energy and electric-mobility transition.
Setting up an algae based biofuel manufacturing plant in India is a next-generation bioenergy venture positioned at the intersection of the country's clean-energy transition, its biofuel-blending ambitions, and rising demand for sustainable aviation fuel.
Setting up an ethanol manufacturing plant in India is a fermentation-and-distillation venture riding one of the country's strongest policy tailwinds: the Ethanol Blending Programme and the drive toward higher petrol blending.
Look around any modern Indian building, car showroom, or kitchen and toughened glass is everywhere: glazed facades, shower cubicles, railings, office partitions, refrigerator shelves, gas stove tops, and car windows.
Setting up a Di-Ammonium Phosphate (DAP) Manufacturing Plant in India is a capital-intensive, strategically important venture tied to the country's food security and its push to reduce fertilizer import dependence.
Setting up a Biofertilizer Manufacturing Plant in India is a microbiology-and-blending venture with relatively accessible entry capital, powered by a strong national push toward natural and organic farming, rising soil-health awareness, growing demand for organically produced food and sustainable agricultural practices, and supportive government schemes.
Setting up a Citric Acid Manufacturing Plant in India is a fermentation-and-purification venture with strong import-substitution appeal, powered by heavy domestic demand across food and beverages, pharmaceuticals, detergents, and industrial cleaning.
Setting up a PVC Pipes Manufacturing Plant in India is an extrusion-and-conversion venture with relatively accessible entry capital, powered by a vast agriculture and irrigation base, a booming construction and plumbing market, and large government water-supply and sanitation programmes.
Nitrocellulose is one of those quiet workhorse materials that most people never see but use every day. It gives printing inks their fast drying, wood lacquers their gloss, and nail varnish its hard, bright finish.
Setting up a Precipitated Silica Manufacturing Plant in India is a specialty-chemical venture powered by a fast-growing tyre and rubber industry, rising demand for fuel-efficient green tyres, and steady use across oral care, food, agrochemicals, and coatings.
Setting up a Plywood Manufacturing Plant in India is a wood-panel venture with relatively accessible entry capital, powered by a booming housing and real-estate market, rising furniture and interior demand, growing incomes, and a structural shift from the unorganised to the organised, branded sector.
Setting up a Fiber Glass Manufacturing Plant in India is a capital-intensive, technology-led venture powered by booming construction, a fast-growing wind-energy sector, vehicle lightweighting, and rising demand for corrosion-resistant composites across pipes, tanks, and electrical applications.
Setting up a Copper Tube Manufacturing Plant in India is a metal-conversion venture powered by a booming air-conditioning and refrigeration market, expanding plumbing and construction, and steady demand from electrical, industrial, and medical-gas applications.
Setting up a Caustic Soda Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's large chemical, alumina, textile, and soap industries and the essential role of caustic soda as a basic building-block chemical.
Setting up a Sulfuric Acid Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's large fertilizer sector, expanding chemical industry, and the essential role of sulfuric acid as the world's most produced industrial chemical.
Setting up an Engine Oil Manufacturing Plant in India is a blending-driven, working-capital-intensive venture, powered by a vast and growing vehicle parc, expanding industrial machinery, and steady replacement demand for lubricants across automotive, industrial, and marine applications.
Setting up a Graphite Manufacturing Plant in India is a minerals-and-materials venture with strong strategic appeal, powered by the electric-vehicle and battery boom, steady demand from refractories, foundries, and lubricants, and a national push to build critical-mineral capacity.
Setting up a Titanium Dioxide Manufacturing Plant in India is a capital-intensive, high-value venture, powered by the country's booming paints and coatings industry, growing plastics and paper demand, and a strong opportunity to substitute large imports of this critical white pigment.
Setting up a Glass Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's construction boom, growing packaging needs, and rising demand from automotive, solar, and consumer sectors.
Setting up a Sponge Iron Manufacturing Plant in India is a capital-intensive, high-demand venture, powered by the country's steel-capacity expansion, its position as the world's largest sponge iron producer, and strong demand from induction furnaces and electric arc furnaces.
Setting up an Aluminium Recycling Manufacturing Plant in India is a high-demand, sustainability-driven venture, powered by the country's booming automotive and construction sectors, the circular-economy push, and the huge energy advantage of recycled over primary metal.
Setting up a Textile Chemicals Manufacturing Plant in India is a high-value, demand-driven venture, powered by the country's vast textile industry, its rise as a global apparel and fabric sourcing hub, and a strong push toward import substitution in specialty chemicals.
Setting up a Metal Fabrication Plant in India is a high-demand, infrastructure-driven venture, powered by the country's construction boom, expanding capital-goods sector, and the Make in India push toward domestic engineering.
Setting up an HDPE Pipe Manufacturing Plant in India is a high-demand, infrastructure-linked venture, powered by the country's massive investment in water supply, irrigation, gas distribution, and sanitation.
India's ethanol industry has moved from a sugar by-product business to a pillar of national energy security. According to IMARC Group, the industry was valued at USD 3.43 Billion in 2025, rose to USD 4.14 Billion in 2026, and is projected to reach USD 11.78 Billion by 2034, growing at a CAGR of 13.95% (2026–2034).
Setting up a Tyre Pyrolysis Plant in India is a profitable, environmentally valuable venture, driven by the country's mounting waste-tyre problem, circular-economy policy, and demand for alternative fuels and recovered carbon black. Tyre pyrolysis converts end-of-life tyres into pyrolysis oil, carbon black, steel wire, and combustible gas, turning a difficult waste stream into marketable products.
The lithium ion battery market in India reached USD 3.59 Billion in 2025 and is projected to reach USD 9.79 Billion by 2034, growing at a CAGR of 11.78% (2026–2034).
Setting up a Bio-CNG Production Plant in India is a capital-intensive but high-potential venture, driven by the country's push for clean fuel, waste-to-energy policy, and energy security. Bio-CNG, also known as compressed biogas, is produced by purifying biogas generated from organic and agricultural waste into a high-methane fuel equivalent to conventional CNG.
Setting up a dicalcium phosphate manufacturing plant in India is a capital-intensive but high-potential venture. India’s combined strength as the world’s third-largest poultry producer, largest milk producer, and largest generic drug manufacturer creates one of the deepest and most diversified DCP demand bases globally. With domestic raw material availability and supportive government policies, the country offers a uniquely favourable environment for new and expanding DCP manufacturers.
The Australia Steel Industry is drawing renewed investor attention as government-backed decarbonization funding, sovereign manufacturing policy, and structural demand from construction and mining converge in a single market cycle.
Xanthan gum is a high molecular weight extracellular polysaccharide, which is produced by the fermentation of carbohydrates by the bacterium Xanthomonas campestris. It is a complex polysaccharide, chemically consisting of a cellulose backbone with trisaccharide chains, which impart it with remarkable rheological properties. It is highly soluble in water and has the ability to create high viscosity even at low concentrations.
A ball bearing is a type of mechanical rolling-element bearing that helps to support radial loads, as well as end loads, while reducing the friction between two surfaces that move. It consists of two rings, one outer and one inner, with balls that are made of steel or other materials, which lie between the two rings. In between the balls, there is also a cage that helps to space the balls evenly.
Urea is an organic chemical substance that contains a large proportion of nitrogen and thus ranks as one of the most crucial compounds containing the element. Urea is a white, crystalline solid with a very high solubility in water and a stable structure under confined storage conditions. Urea is produced through the reaction of ammonia and carbon dioxide. It is a very rich source of the element and is also portable. Since the element is an essential component for the development and growth of plants, it is greatly used in the agricultural sector as well as in a number of industrial processes.
Tyre pyrolysis refers to a thermal recycling process whereby waste tyres are transformed into recyclable materials using a process of pyrolysis. Pyrolysis refers to a process whereby tyres are heated in the absence of oxygen to produce various useful resources. When tyres are subjected to elevated temperatures in the absence of oxygen, the various polymers found in tyres are reduced to simpler components without undergoing the process of combustion.
The global packaging industry is undergoing a profound transformation, with barrier films emerging as one of the most crucial components enabling product integrity, extended shelf life, and improved sustainability. As consumer expectations shift toward freshness, safety, and environmental responsibility, the importance of advanced barrier solutions continues to rise. In this evolving scenario, the barrier films market size is gaining increased attention, driven by innovations that enhance material performance while supporting ecofriendly packaging strategies.
The Saudi Arabia ethanol market represents a critical segment within the Kingdom's evolving industrial landscape. As one of the world's leading energy producers, Saudi Arabia strategically diversifies its economic portfolio beyond traditional hydrocarbon dependence. Ethanol, a versatile alcohol compound with applications spanning pharmaceuticals, personal care, chemicals, and fuel blending, has emerged as an essential component in this transformation.
Tile adhesive manufacturing is the industrial process of producing a specialized adhesive for fixing tiles to a substrate of concrete, cement screed, plaster, drywall, or existing tiles. Tile adhesives are normally made from a combination of cement, polymers, fillers, and performance additives that improve bonding power, flexibility, water resistance, and setting times.
Toughened glass production is the industrial process of making safety glass that is much stronger and more resistant to impact than regular annealed glass. The production process involves heating flat glass to high temperatures and then rapidly cooling it, which causes compressive stresses on the surface and tensile stresses in the core.
As the nation pursues ambitious infrastructure goals and accelerates urban development initiatives, prefabricated construction and structural steel solutions have emerged as indispensable components of modern building practices.
Sulfuric acid is a highly corrosive, colorless to slightly viscous inorganic acid that consists of sulfur, oxygen, and hydrogen. It is one of the most widely used industrial chemicals in the world because of its strong acidic properties and high reactivity.
Sponge iron, also called direct reduced iron (DRI), is a metallic material produced through the solid-state reduction of iron ore without melting it. The oxygen in iron ore is removed through the action of reducing gases or solid carbon at a temperature below the melting point of iron. The product has a porous, sponge-like appearance, and this is why it is called sponge iron.
Sodium ferrocyanide is a chemical that is classified as an inorganic coordination compound, comprising sodium ions and the ferrocyanide complex. This chemical is typically denoted by the chemical formula Na4[Fe(CN)6]·10H2O. Although the chemical contains cyanide ions, it is stable and less toxic, as the cyanide ions are strongly bound to the iron ion.
SLES is an anionic surfactant that finds wide application due to its outstanding performance on cleansing, foaming, and emulsifying properties. It is prepared by the ethoxylation of lauryl alcohol, usually sourced from natural fats or oils, followed by sulphonation and neutralization. The process of ethoxylation differentiates SLES from SLS in that SLES shows better mildness and lower irritation while retaining strong detergency.
Sodium chloride is an inorganic chemical compound that consists of sodium and chlorine ions, known as common salt. Its chemical formula is NaCl, which often tends towards crystalline form. It can be easily taken out from seawater, rock salt deposits, or salt lakes. The chemical properties of this compound make it completely water-soluble, with a stable nature.
The Gulf Cooperation Council cement market stands at a critical juncture as regional economies accelerate infrastructure development and pursue ambitious economic diversification strategies. Cement consumption across the GCC nations continues to expand, driven by transformative megaprojects, rapid urbanization, and substantial government investment in construction infrastructure.
The Kingdom of Saudi Arabia is undergoing an unprecedented economic transformation, shifting its traditional reliance on hydrocarbon revenues toward a diverse, knowledge-based economy. Central to this monumental shift is the steel industry in Saudi Arabia, a sector that serves as a foundational pillar for virtually every national development project.
A silk reeling unit is a type of manufacturing plant where raw silk threads are obtained from the cocoons of silkworm moths and processed into raw silk yarn by weaving them into a continuous strand of raw silk.
PVC solvent cement is a specialized adhesive formulation used to create permanent joints between polyvinyl chloride (PVC) pipes, fittings, and components. Unlike standard adhesives that rely on surface bonding, solvent cement chemically fuses PVC materials together. It works by using a blend of solvents and resins that temporarily soften and dissolve the surfaces of the PVC components.
PVC (Polyvinyl Chloride) pipes are durable and versatile piping products made from a synthetic thermoplastic polymer known for its strength, chemical resistance, and longevity. These pipes are produced primarily through the extrusion process, which ensures consistent wall thickness and uniform mechanical properties. Available in both rigid and flexible forms, PVC pipes are designed to transport fluids, gases, or solids safely under controlled pressure and temperature conditions.
Plastic pyrolysis is a form of recycling plastic waste via a process referred to as thermochemical recycling. This process produces liquid fuels, gases, and solid wastes through thermal degradation under low or no oxygen. Unlike traditional recycling, plastic pyrolysis involves the breakdown of long polymer chains into smaller hydrocarbon molecules using heat, in most cases in the presence of catalysts.
Insulation tapes made of PVC are adhesive tapes produced through a process involving a polyvinyl chloride (PVC) carrier coated with an adhesive made of rubber or acrylic materials. These insulation tapes have applications in electrical installations to serve their intended purpose of insulation and protection against environmental damage for electrical components and cables.
Precipitated silica is a synthetic and amorphous silicon dioxide, which is prepared through a process of controlled chemical reaction between soluble silicates and mineral acids. Unlike regular silica, precipitated silica is manufactured to have desired particle sizes, surface area, and porosity in terms of its structure, determining its final end-use performance. Precipitated silica is a fine, white, and free-flowing powdered substance.
Plywood is an engineered wood product made by bonding multiple thin layers of wood veneer together with strong adhesives under heat and pressure. The veneers are oriented so that their grain directions are at right angles to each other in successive layers, a manufacturing technique that improves strength, stability in dimensions, and resistance to cracking or warping.
Plastic crates are a rigid and reusable construction with a production material that includes a thermoplastic such as high-density polyethylene (HDPE) and Polypropylene (PP). These crates have design features that ensure the efficient storage, transport, and handling of goods while having a strong load-bearing capacity and a longer life span.
The cement industry remains one of the most critical foundations of global development, shaping the built environment and enabling progress across residential, commercial, and industrial landscapes. As construction activity expands and infrastructure investment intensifies, the cement market size continues to evolve, supported by new material innovations, sustainability priorities, and smart manufacturing technologies.
The GCC ceramic tiles market has emerged as one of the most dynamic segments in the region's construction and building materials sector. Spanning countries including United Arab Emirates, Saudi Arabia, Kuwait, Oman, Qatar, and Bahrain, the market reflects the Gulf region's ambitious transformation from oil-dependent economies to diversified, modern nations.
Paints are liquids, semi-liquids, or powdered materials, usually having a high content of pigments, binders or resins, solvents or vehicles, or additives, intended for application onto substrates to create a continuous film after drying or curing. Paints work as materials after their application, possessing several functionalities, such as protecting the surface, adding color, or modifying functionalities. Paints contain several components, such as binders or resins, pigments, solvents or vehicles, or additives, each differing based on their functionalities. The binder or resin is mainly involved in providing strength or adhesive characteristics, while pigments are used to create colors or opaqueness.
Organic fertilizers refer to nutrient-value-adding materials that come from ecologically degradable sources like plant debris, animal manure, composted materials, bio-wastes, bone meal, and microbe organisms. Another key point of distinction between organic and synthetic fertilizers is that whereas synthetic fertilizers give quicker nutrient release through chemical reactions, nutrient release occurs via bacterial decomposition in the case of organic fertilizers.
Oleochemicals are chemicals obtained from natural fats and oils derived mainly from renewable plant-based feedstocks like palm oil, palm kernel oil, coconut oil, soybean oil, and other materials high in triglyceride content. These raw materials are transformed into fatty acids, fatty alcohols, glycerin, methyl esters, and other derivatives by means of hydrolysis, transesterification, hydrogenation, fractionation, and other techniques. They represent renewable, biodegradable, and environmentally friendly alternatives to chemicals made from petrochemical raw materials.
NdFeB magnets are a family of high-performance permanent magnets primarily made of an alloy of neodymium, iron, and boron. They are fabricated by the sintering or bonding processes, which create extremely high magnetic energy density and make them the most powerful commercial magnets. NdFeB magnets have the best coercivity, remanence, and effectiveness in compact forms that can generate strong magnetic fields in the smallest volume.
Mineral wool ceiling tiles consist of acoustic and thermal insulation panels fabricated from inorganic fibers, which originate mainly from molten basalt, slag, or other mineral-based raw materials. The fibers are spun and bonded together with resins, then compressed into rigid tiles that perform well in terms of sound absorption, fire resistance, and moisture tolerance. They are usually available in standard sizes for application in suspended ceiling systems in commercial, industrial, and institutional buildings.
Methanol, also known as methyl alcohol or wood alcohol, is a colorless liquid that is volatile and flammable with the chemical formula CH3OH. The simplest of the alcohols, it is produced mainly by the catalytic conversion process of natural gas, coal, or biomass into synthesis gas-a mixture of carbon monoxide and hydrogen-further followed by methanol synthesis under high pressure.
Lubricating oil is a specially formulated liquid substance that reduces friction, wear, and generation of heat between moving mechanical surfaces. It is usually made from refined mineral base oils, synthetic oils, or a mixture of both, supplemented with performance-improving additives such as anti-wear agents, detergents, dispersants, antioxidants, corrosion inhibitors, and viscosity improvers.
The Philippines passenger vehicles lubricants industry stands at a transformative juncture, driven by robust automotive sector expansion, technological innovation, and evolving consumer preferences toward high-performance products. As the Philippine economy demonstrates resilient growth and vehicle ownership continues to rise, the demand for premium automotive lubricants has accelerated significantly across the archipelago.
Hydrogen is the lightest and most abundant element in the universe, being a colorless, odorless, highly combustible gas. It does not usually occur free in nature but is produced from hydrogen-rich compounds like water, natural gas, biomass, or other hydrocarbons. Owing to its high energy content per unit mass and clean combustion (with the production of water vapor only), hydrogen is widely recognized as a versatile energy carrier. Depending on how hydrogen is produced, it is classified as grey, blue, or green and increasingly plays a significant role in clean energy systems, industrial processing, and developing low-carbon technologies.
HDPE pipes are thermoplastic piping systems made from high-strength polyethylene resin, which features excellent flexibility, high impact resistance, and strong chemical and corrosion resistance. HDPE pipes are produced by extruding molten polyethylene into a variety of diameters and pressure ratings. Their seamless structure, along with their low friction and resistance to internal pressure and external load, makes them ideal for the transport of fluids. HDPE pipes boast superior endurance, long service life, and leak-free performance, since it is possible to join them through heat fusion, thus creating monolithic, continuous pipelines that are suitable for buried, aboveground, or underwater installations.
Graphite is a crystalline form of pure carbon, where atoms are organized in layered hexagonal structures, reflecting exceptional lubricity, electrical conductivity, heat resistance, and a high degree of chemical stability. It comes in many forms: flake, amorphous, vein, and synthetic graphite-derived from petroleum coke or coal tar pitch. Because of this layered structure, the sheets slip easily, which gives graphite its characteristic softness and lubricity, while strong covalent bonding within the layers makes it thermally stable and conductive. The unique characteristics make graphite indispensable in uses such as steelmaking, refractories, batteries, electronics, and in high-performance industrial components.
The Japan urea industry stands as a critical pillar supporting multiple sectors of the nation's economy, from agricultural productivity to automotive emissions control. As a nitrogen-rich compound essential for modern farming practices, urea plays an indispensable role in ensuring food security for Japan's population while simultaneously addressing stringent environmental standards through its industrial applications.
The Japan industrial gases industry stands as a critical enabler of the nation's economic infrastructure, supporting diverse sectors including manufacturing, healthcare, electronics, semiconductors, steel production, and energy generation. Industrial gases such as oxygen, hydrogen, nitrogen, carbon dioxide, argon, and specialty gases serve as essential inputs across these industries, facilitating everything from metal fabrication and medical treatments to advanced semiconductor manufacturing.
A fire extinguisher is either a portable or fixed device that is designed to combat and suppress small fires by discharging a controlled substance, which cools the burning material, cuts off oxygen supply, or interrupts the chemical chain reaction sustaining combustion. It is among the most important items that comprise fire protection systems, finding wide applications in residential, commercial, industrial, and transport environments.
Fiberglass, also known as glass fiber, is a composite material manufactured by weaving, chopping, or layering minute strands of glass into strong yet lightweight and durable products. It is made by melting silica sand, limestone, soda ash, and other raw materials together at very high temperatures-around 1,700°C-through which molten glass is obtained. It is extruded through fine nozzles to create continuous filaments, then combined into mats, fabrics, or roving later on, according to use.
Engine oil is a specific lubricant that serves to reduce friction, wear, and heat in an internal combustion engine's moving parts, allowing the smooth operation of such engines. Besides lubrication, it accomplishes other very important tasks: cooling, cleaning, sealing, and protection against corrosion. The two major components of engine oil formulation are the base oil and additives. The base oils, mineral or petroleum-based, synthetic, and semi-synthetic, constitute approximately 70-90% of the formulation and provide the fluidity and viscosity for the best performance.
The Australia bioplastics industry is experiencing unprecedented growth, driven by intensifying consumer demand for sustainable alternatives and robust government sustainability initiatives.
Ferrous sulphate is an inorganic salt, composed of iron, sulfur, and oxygen, and is mainly known for its pale green or blue-green crystalline appearance. It exists in various hydrated forms, the most common being ferrous sulphate heptahydrate (FeSO4·7H2O), although it is also produced largely as a monohydrate and anhydrous variant, depending on the industrial needs. It is usually manufactured as a by-product of the pickling of steel using sulfuric acid, or it could be produced as a co-product from titanium dioxide pigment manufacture.
Bamboo plywood is an engineered wood product that is made by laminating thin strips or veneers of bamboo into multi-layered panels to create a stable, uniform sheet material combining the natural aesthetics of bamboo with the structural versatility of plywood. Unlike conventional plywood made from hardwood or softwood veneers, bamboo plywood most often uses strand-woven, horizontal, or vertical lamination patterns of bamboo culm that are bonded under heat and pressure with formaldehyde-free or low-emission adhesives.
Biomass pellets are a sustainable, carbon-neutral, and renewable source of energy made from organic materials such as forestry waste, agricultural residues, sawdust, wood chips, and other biomass feedstocks. Biomass pellets are small, cylindrical in shape, and usually between 6 and 12 millimeters in diameter and are utilized as a clean energy alternative to fossil fuels in power production, heating, and for industrial purposes.
Bioethanol is a biodegradable, renewable alcohol that is made by fermenting sugars from biomass resources like corn, sugarcane, wheat, cassava, and cellulosic materials like agricultural waste and forest residues. It is cleaner than gasoline from fossil fuels and provides valuable decreases in greenhouse gases and helps to move us toward sustainable energy systems. The process of production of bioethanol is mainly about the conversion of biomass carbohydrate to simple sugars by hydrolysis and subsequent fermentation by yeast or bacteria into ethanol.
Blue ammonia is one type of ammonia production that is meant to reduce carbon dioxide emissions. Traditional methods of ammonia production include sourcing hydrogen from natural gas, usually through steam methane reforming (SMR) or auto-thermal reforming (ATR) and then reacting this hydrogen with nitrogen (from air) through the Haber-Bosch process. The "blue" suffix indicates that the carbon dioxide waste product produced in the course of hydrogen synthesis is captured (through Carbon Capture, Utilization, and Storage / CCUS) and not released into the environment.
Biodiesel is a renewable and biodegradable fuel source mainly from vegetable oils, animal fats, or waste cooking oils, and can serve as a direct replacement or blend with traditional petroleum diesel. It is chemically constituted by fatty acid methyl esters (FAMEs), which are formed when triglycerides react with methanol or ethanol in the presence of a catalyst under transesterification.
Anhydrous Ferric Chloride, FeCl3, is a corrosive dark brown crystalline chemical that finds extensive application as a major industrial chemical in water treatment, metallurgy, electronic manufacturing, and chemical synthesis industries. It is produced by reacting chlorine gas with iron or ferrous chloride at elevated temperatures to form a high-purity, moisture-free product. In contrast to its hydrate, anhydrous ferric chloride is not aqueous and is mostly used in processes involving controlled levels of moisture, for example, etching circuits in electronics and as a catalyst in the synthesis of organics.
Ammonium Bicarbonate (NH4HCO3) is a white crystalline inorganic chemical used extensively in the fertilizer, food processing, pharmaceutical, and chemical industries. It is a salt that is produced by the combination of ammonia, carbon dioxide, and water and is renowned for decomposing at relatively low temperatures into ammonia, carbon dioxide, and water vapor. This characteristic makes it useful as a leavening agent for the food industry, especially in baked foods, cookies, and crackers, which produce a light and porous texture due to its presence.
Biodegradable plastic granules are eco-friendly polymer materials designed to decompose naturally through the action of microorganisms such as bacteria, fungi, and algae, reducing the environmental burden associated with conventional plastics. These granules are the fundamental raw materials used in the production of biodegradable products such as packaging films, agricultural mulch, carry bags, cutlery, and medical components.
Bioplastics are a category of materials that come entirely or partly from renewable biological resources like corn starch, sugarcane, vegetable oils, or cellulose, to be used as sustainable substitutes for traditional petroleum-based plastics. Bioplastics may be biodegradable, non-biodegradable, or compostable, depending on their chemical composition and manufacturing process.
Battery recycling is the collection, dismantling, and processing of used or end-of-life batteries to recover valuable materials and limit environmental threats. With the burgeoning exponential increase in electric vehicles (EV), renewable energy storage, and consumer electronics, the number of spent batteries has skyrocketed, necessitating recycling as a key component of the energy transition worldwide.
Binding wire is a low-cost, flexible steel wire, mainly utilized for tying, fastening, and bundling in applications of construction, industry, agriculture, and packaging. Usually produced from mild steel wire rod by successive cold-drawing, annealing and surface-finishing processes, binding wire comes in an assortment of gauges (typically 18–24 AWG / 1.0–1.6 mm) and in a few forms: soft/annealed plain wire, galvanized (zinc-coated) wire for corrosion-proofing, and polymer/PVC-coated wire for better handling and durability.
Aluminum anodizing is an electrochemical process that improves the surface characteristics of aluminum by creating a long-lasting, corrosion-resistant oxide coating on its surface. In contrast to coatings or paint applied to the outside surface, anodizing makes the outer surface of aluminum into a protective aluminum oxide coating that is bonded integrally to the metal and will last long and stay adherent.
Aluminum powder is a finely divided metallic aluminum with a wide range of applications in various industries because of its specific physical and chemical properties. It is manufactured by atomization, mechanical grinding, or flake milling of pure aluminium. The powder has high reactivity, low density, high thermal conductivity, and high reflectivity. Depending on the manufacturing technique, it can exhibit spherical, irregular, or flake-like morphologies, making it suitable for diverse applications.
Aluminum bottles are lightweight, strong, and recyclable packages manufactured mostly from high-purity aluminum that provides a sustainable and premium alternative to conventional plastic and glass packaging. Aluminum bottles integrate functionality with style and, therefore, are gaining popularity in industries like beverages, cosmetics, personal care, pharmaceuticals, and household products.
Aluminum ingots are standardized raw forms of aluminum that are produced by smelting and refining processes, which act as a basic raw material for downstream industries. The ingots are commonly prepared by refining bauxite ore to alumina through the Bayer process, followed by electrolytic reduction in smelters through the Hall-Héroult process. The molten aluminum thus produced is cast into ingot shape for transportation convenience, handling, and further processing.
Aluminum extrusion is a versatile metal forming process whereby aluminum billets are pushed through a shaped die to create long profiles with the same cross-section. Through this process, manufacturers can create intricate shapes that balance strength, lightweight characteristics, and beauty, making it a cornerstone of several industries.
Activated alumina balls are porous, granular, and spherical materials consisting of aluminum oxide (Al2O3). They possess a large surface area, high adsorbing capacity, and excellent resistance to thermal shock and abrasion. Manufactured by the controlled dehydroxylation of aluminum hydroxide, activated alumina balls are chemically inert, non-toxic, and possess excellent water and polar molecule affinity. Due to such features, they find extensive applications as desiccants, adsorbents, and catalysts. In industrial operations, they are useful for drying gases and liquids in processes, eliminating fluoride, arsenic, and selenium ions from water, and as a catalyst carrier in petrochemical refining applications.
Activated carbon or activated charcoal is a very porous form of carbon with an incredibly large surface area, usually anywhere from 500 to 1,500 m²/g. Manufactured by activating carbon-rich materials such as coconut shells, wood, coal, or peat, it is subjected to physical or chemical treatment to create its distinctive pore structure. The microporous structure enables activated carbon to efficiently absorb gases, vapors, and dissolved materials, which makes it a vital adsorbent in all industries.
Glass Fiber Reinforced Polymer (GFRP) rebar and mesh are composite materials developed to be used in place of the conventional steel reinforcement in concrete structures. They consist of continuous glass fibers dispersed within a polymeric resin matrix, most commonly epoxy, vinyl ester, or polyester. The synergy between the tensile strength of glass fiber and the corrosion inhibition properties of polymers produces reinforcement products that are light weight, corrosion-free, and extremely durable.
Phosphorus Pentasulfide (P2S5) is a yellow-green crystalline compound primarily produced through the controlled reaction of elemental phosphorus and sulfur. As a key phosphorus-based intermediate, it plays a critical role in the chemical industry, particularly in the manufacture of lubricant additives such as zinc dialkyldithiophosphate (ZDDP), agrochemicals, and battery electrolytes. Structurally, P2S5 consists of phosphorus and sulfur atoms bonded in a cage-like configuration, imparting high reactivity and compatibility with organic synthesis pathways. It is valued for its sulfur-donating properties, thermal stability, and role as a bridging compound in synthesizing more complex phosphorus-sulfur compounds.
Steel bolts and fasteners are integral mechanical components that provide secure connections across industrial, commercial, and household applications. Comprising primarily of carbon steel, alloy steel, or stainless steel, these fasteners are engineered to withstand significant mechanical loads, torque, and environmental exposure. Their key properties include high tensile strength, corrosion resistance, dimensional precision, and durability under cyclic stress. Manufacturing typically involves processes such as forging, machining, threading, and surface finishing to meet exacting industry standards.
Copper sulphate is an inorganic chemical made up of copper, sulfur, and oxygen that is best known for its crystalline blue color and varied uses. Most often found as copper sulphate pentahydrate (CuSO4·5H2O), it is prized for its water solubility, stability, and fungicidal activity. Primary characteristics are that it is a fungicide, herbicide, algicide, and electrolyte used in industrial applications. It also serves as a precursor for the manufacture of other compounds of copper and as a laboratory reagent.
Sebacic acid is a naturally occurring dicarboxylic acid, a long-chain organic compound with two carboxyl functional groups. It is mainly produced from castor oil through cracking and purification in a significant industrial process, as it is a valuable bio-based chemical with major industrial relevance. The white flaky or crystalline powder is cherished for its superior properties, such as high thermal stability, corrosion resistance, and the ability to form long-lasting polymers.
Aluminium conductors are electrical wires or cables whose current-carrying core is primarily made of aluminium (or its alloys), used for overhead transmission lines, distribution, AAC (All Aluminium Conductor), AAAC (All Aluminium Alloy Conductor), ACSR (Aluminium Conductor Steel Reinforced), etc. The material is lightweight, has relatively good electrical conductivity (lower than copper but acceptable for many applications), and is cost-effective per unit weight.
Steel rolling products, encompassing hot-rolled, cold-rolled, and coated steel sheets and coils, form the backbone of numerous industrial applications, from automotive manufacturing to construction and infrastructure. The cost of these products is influenced by a complex interplay of raw material prices, energy costs, labor, technological advancements, and logistical considerations.
Treatment of sewage is the procedure of eliminating contaminants from domestic or industrial wastewater to yield treated effluent that can be safely released into the environment or recycled for different purposes. Sewage contains organic matter, nutrients, suspended solids, microorganisms, and chemical pollutants and hence physical, chemical, and biological processes must be utilized for purification.
Green methanol is a renewable and sustainable form of methanol produced from non-fossil-based feedstocks such as biomass, municipal solid waste, biogas, or captured carbon dioxide combined with green hydrogen generated via electrolysis powered by renewable energy. Chemically, it is identical to conventional methanol (CH3OH), a simple alcohol with high energy density and versatile chemical properties.
Sodium hydrosulfide (NaHS) is an inorganic chemical mainly known for its good reducing nature and adaptability in uses in industry. It exists as pale yellow solid or liquid in aqueous solution with the smell of sulfur. It is chemically obtained by the partial neutralization of hydrogen sulfide (H2S) by sodium hydroxide (NaOH) to form a stable and water-soluble salt.
Recycled Polyethylene Terephthalate (rPET) is a thermoplastic polymer obtained from post-consumer and post-industrial PET waste, mainly plastic bottles and packaging materials. It is chemically the same as virgin PET, composed of polymerized units of terephthalic acid and ethylene glycol, but is made from a recycling process that minimizes dependence on fossil-based feedstocks. Major characteristics of rPET are high strength-to-weight ratio, chemical resistance, dimensional stability, and high recyclability.
Animal feed grade Di-calcium Phosphate (DCP) is a mineral feed supplement commonly applied in animal and poultry nutrition to fortify dietary calcium and phosphorus—two of the most important nutrients in maintaining animal health and production levels. Manufactured predominantly through the reaction of phosphate rock-based phosphoric acid with calcium carbonate or lime, feed-grade DCP is generally found as a white or off-white granular or powdered material.
Copper tubes are cylindrical hollow goods consisting mainly of purified copper, which are highly prized for their high thermal conductivity, corrosion resistance, ductility, and antimicrobial qualities. They are produced by processes like casting, extrusion, and drawing, which provide accurate dimensions and clean internal surfaces.
Automotive fabrics are specialized textile materials engineered for use in vehicle interiors, combining aesthetics, functionality, and durability. Unlike ordinary textiles, automotive fabrics must withstand prolonged wear, UV exposure, temperature variations, and continuous contact, while also contributing to passenger comfort and vehicle safety.
Aluminum sheets, cans, and foils are among the most common types of processed aluminum, serving industries from packaging and construction to transport and consumer products. Aluminum sheets are flat-rolled material manufactured in a range of thicknesses and grades, prized for light weight, corrosion resistance, and ability to be recycled, ideal for use in car body panels, building cladding, roofs, and kitchen appliances.
Synthetic graphite is a state-of-the-art carbon material developed through petroleum coke and coal tar pitch treatment at high temperatures, providing highly crystalline carbon materials of higher purity and uniformity than natural graphite. Synthetic graphite is produced in controlled industrial conditions unlike natural graphite, which is excavated.
Diammonium Phosphate (DAP) is among the most popular phosphorus fertilizers in the world due to its high concentration of nutrients and multiple uses in agriculture. It is manufactured by reacting ammonia with phosphoric acid, forming a compound that has about 18% nitrogen and 46% phosphorus pentoxide (P2O5). Such levels of nutrients make DAP an effective supply of critical macronutrients for plants, especially for root development, seed germination, and plant growth early on.
Australia's battery recycling market is charging ahead, with a value of USD 336 Million in 2024 and no signs of slowing down. Driven by the booming demand for cleaner, greener solutions—especially in the Australia battery energy market and electric vehicle (EV) sectors—the industry is expected to reach USD 612.55 Million by 2033. That’s a steady growth rate of 6.90% annually from 2025-2033.
Green ammonia is used to describe ammonia made from renewable energy systems like wind, solar, or hydropower through water electrolysis to obtain green hydrogen, then blended with nitrogen in the air through the Haber-Bosch process. Unlike traditional ammonia, which is derived from natural gas and produces enormous amounts of CO2, green ammonia is a carbon-free and sustainable alternative.
Hydrogen Peroxide (H2O2) is an all-purpose, eco-friendly chemical used extensively as an oxidizing, bleaching, and disinfectant agent in various industries. Hydrogen Peroxide is a clear, colorless liquid with high oxidizing power, breaking down into oxygen and water, and thus a clean alternative to several hazardous chemicals.
Biofertilizers are microbial products that contain living microbes, and they enhance plant growth through the improvement of nutrient availability in the soil microcosm. They may consist of useful microorganisms like Rhizobium, Azotobacter, Azospirillum, phosphate-solubilizing bacteria (PSB), and mycorrhizal fungi. These microorganisms form symbiotic or associative relations with plants and enhance nitrogen fixation, phosphorus solubilization, and the uptake of required nutrients.
Steel stands as one of the world’s most essential industrial materials, forming the backbone of modern infrastructure, manufacturing, and economic progress. As a critical material, its production and consumption directly influence global economic dynamics. The steel market has seen significant evolution, driven by innovations, demand from diverse sectors, and increasingly sustainable practices.
The global petrochemicals market is witnessing steady growth, supported by rising end-user consumption, industrial diversification, and infrastructure development across both developed and emerging economies.
Ethyl acetate is a volatile, colorless, flammable liquid having a characteristic sweet smell. It is primarily used as a solvent in various industrial and commercial applications. It finds primary production through esterification from ethanol and acetic acid.
Ammonium nitrate (NH4NO3) is a white solid that is widely used as a high-nitrogen fertilizer and as a component of industrial explosives. It is made by neutralization of ammonia with nitric acid and is very soluble in water, making it useful for its efficiency in providing nitrogen to plants.
Ceramic tiles are durable, versatile, and cost-effective building materials made from natural clay, sand, and water, which are shaped, glazed, and kiln-fired at high temperatures. Known for their aesthetic appeal, resistance to moisture, and ease of maintenance, ceramic tiles are widely used in flooring, walls, kitchen backsplashes, and bathrooms across residential, commercial, and industrial spaces.
Diethylenetriamine (DETA) is a colorless, hygroscopic organic chemical compound of the ethyleneamine group having the chemical formula HN(CH2CH2NH2)2. It is a triamine that contains two primary amine groups and one secondary amine group, thus imparting to it a highly reactive molecular structure to be used in a number of industrial processes.
Calcium Chloride Anhydrous (CaCl2) is an off-white, hygroscopic inorganic substance commonly utilized due to its high desiccating and exothermic properties. The anhydrous form, as opposed to its hydrated counterparts, has no water molecules within it, thus making it very effective to use in moisture control processes.
Explore a step-by-step guide to setting up a unsaturated polyester resin production plant including planning, machinery, raw materials, costs & demand drivers.
Explore the growth, trends, and innovations driving the global bio-lubricant market toward a sustainable future.
Medium Density Fibreboard (MDF) is an engineered wood product created by dissolving hardwood or softwood residues into wood fibers, blending them with wax and resin binders, and molding them into panels under the pressure of high temperature. MDF is renowned for its even density, smooth surface, and easy machinability and is used extensively in cabinetry, flooring, furniture, and interior decoration because of its relative cheapness and adaptability as compared to plywood and solid wood.
Lanthanum oxide (La2O3) is a white, odorless, and extremely stable rare earth compound obtained mainly from monazite and bastnäsite ores. It is essential for a vast array of industrial uses such as the manufacture of optical lenses, ceramics, phosphors, and battery electrodes. Lanthanum oxide is also used extensively as a catalyst in petroleum refining processes, particularly in fluid catalytic cracking (FCC) operations. Due to its exceptional electrical, optical, and catalytic properties, La2O3 is an important material for advanced technologies like electric vehicles (EVs), smart electronics, and renewable energy devices.
Silica sand is a pure quartz-based material used extensively by many industries. It is known for its durability, chemical inertness, and resistance to heat, and it is an important raw material in glass production, construction, foundries, electronics, and hydraulic fracturing (fracking). Increasing demand for high-purity silica in semiconductors, solar panels, and filters is fueling market growth. With more infrastructure development and development in silica processing, the applications keep expanding, and it is becoming an essential industrial commodity worldwide.
Stone paper is an innovative, eco-friendly material gaining traction across various industries due to its durability, sustainability, and water resistance. Made primarily from calcium carbonate and resin, it offers a tree-free alternative to traditional paper, reducing deforestation and water consumption. Its tear-resistant and smooth texture makes it ideal for printing, packaging, and stationery applications. Additionally, stone paper is recyclable, photodegradable, and highly resistant to moisture, making it suitable for outdoor and high-humidity environments. With growing environmental concerns and demand for sustainable packaging and printing solutions, stone paper is emerging as a key player in the global paper industry, attracting interest from publishers, packaging manufacturers, and eco-conscious brands.
Nitrile gloves are synthetic rubber gloves that are extensively used in the medical, industrial, and food industries because of their strength, resistance to chemicals, and hypoallergenic nature. They are ideal for people with allergies since they are latex-free, as opposed to latex gloves. They are more flexible, puncture-resistant, and resistant to infection and chemicals. The demand for nitrile gloves in manufacturing, healthcare, and laboratory environments is increasing because of stringent safety regulations and increasing hygiene consciousness, which is driving the worldwide market growth.
Acetic acid (CH3COOH) is a clear, colorless liquid organic compound with a sour taste and a pungent odor. It is produced by the carbonylation of methanol and is also manufactured via bacterial fermentation. Acetic acid is extensively employed in the manufacturing of vinyl acetate monomer (VAM), purified terephthalic acid (PTA), acetic anhydride, and ester solvents, among others. It provides solvent effectiveness, chemically useful to use in syntheses, as well as utilization in the fabrication of polymers and resins.
Calcium bromide (CaBr2) is an inorganic compound commonly used in drilling fluids for oil and gas exploration, as well as in pharmaceutical and photographic applications. It is a white, crystalline solid or solution that dissolves very easily and is used as a clear, dense brine in well drilling operations. Calcium bromide is prized for its capacity to manage pressure and avoid well blowouts due to its exceptional thermal and chemical stability. The growing energy industry and improvements in drilling technology are the main drivers of its demand.
Laminated veneer lumber (LVL) is one of the most popular engineered wood products, which is manufactured from sliced and peeled thin wood veneers. LVL is a light material used for construction, which is utilized in public structures, industrial warehouses, product parts, large, prefabricated buildings, as well as designed wooden homes. This can be attributed to its strength, uniformity, high strength, and dimensional accuracy. Apart from this, it is utilized for structural framing in residential and commercial building work, including lintels, joists, beams, purlins, scaffold boards, concrete formwork, and truss chords.
Cross-laminated timber (CLT), an engineered wood product, is renowned for its durability, strength, and adaptability in contemporary building. CLT provides a lightweight yet strong substitute for steel and concrete in structures with sustainable engineering. Its layered structure adds to its integrity and makes it suitable for building anything from residential to commercial to high-rise buildings. Besides being aesthetically pleasing for eco-friendly building projects, CLT has very good fire resistance, thermal performance, and ease of installation. CLT changes the architectural sphere and instigates the development of new concepts for urban environments and shaping the future of sustainable construction.
Copper wire is a versatile, flexible, and highly conductive electrical wire used extensively in power transmission, telecommunications, and electronics. Fabricated from pure copper, copper wire has good thermal and electrical conductivity, resistance to corrosion, and ease of processing. Copper wire plays a critical role in construction, automotive, and consumer electronics industries. With the increased demand for effective power distribution and advancing technology, the copper wire market keeps growing because of urbanization, electrification, and growth in infrastructure development globally.
Aluminum wire rods are critical industrial products renowned for their high conductivity, strength, and versatility. They are cylindrical metal rods that are the backbone of electrical transmission and distribution systems and play a fundamental role in power infrastructure, building construction, and manufacturing. Due to their good conductivity and low weight, they are a top choice for cable production, overhead power lines, and electrical wires. Outside of electrical uses, aluminum wire rods find extensive application in the automotive, aerospace, and industrial industries, where their corrosion resistance and recyclability play important roles in sustainability initiatives.
N-Methyl Aniline (NMA) is an organic chemical compound widely used as an intermediate in various industrial applications. It plays a crucial role in the production of dyes, agrochemicals, pharmaceuticals and fuel additives. As a key component in high-octane fuel formulations NMA enhances combustion efficiency and reduces engine knocking making it valuable in the automotive and petroleum industries. Its use in the synthesis of specialty chemicals and pigments further expands its industrial significance.
Ammonium perchlorate is a crystalline, white inorganic substance that finds principal application as an energetic oxidizer in solid rocket propellants, explosives, and pyrotechnics. Its release of oxygen when subjected to heat gives it a fundamental role in different industrial and technological processes. Aside from its primary application in propulsion systems, it is also used in pyrotechnic devices to generate controlled, vibrant flames and brilliant effects, especially in aerospace displays and enormous entertainment productions.
Potassium sulfate (K2SO4) is an inorganic compound widely used as a specialty fertilizer, providing essential potassium and sulfur nutrients to crops. Its low salt index makes it the preferred crop for crops that are sensitive to chloride, like fruits, vegetables, and tobacco. Potassium sulphate is also used in pharmaceutical and glass manufacturing processes, among other industrial processes. It is the perfect choice for contemporary agricultural methods because of its high solubility and compatibility with irrigation systems, which promote plant development, yield enhancement, and soil health maintenance.
Battery electrolyte is a key element of energy storage, facilitating the flow of ions between electrodes to drive devices effectively. It is an important factor in lithium-ion, solid-state, and future batteries, influencing performance, safety, and durability. In electric vehicles, renewable energy storage systems, and consumer devices, development in electrolyte technology targets sustainability, improved conductivity, and heat resistance for unlocking the future of clean energy technologies.
Cobalt acetate is an inorganic substance that is frequently utilised in chemical synthesis as a precursor, dye mordant, and catalyst. This crystalline solid has a reddish-purple appearance and is very soluble in organic solvents and water. In addition to being widely used in the manufacture of paints, inks, and adhesives, it is also an essential component of polyester and a catalyst in oxidation processes. It is a crucial component in many industries, with industrial uses driving its demand, especially in petrochemicals, textiles, and battery technology.
Transformer oil, sometimes referred to as insulating oil, is essential to electrical transformer operation. Its main functions are to cool and insulate the internal parts. By acting as a dielectric medium, the oil prolongs the transformer's lifespan and improves overall performance by preventing electrical discharges between various components. It moves around inside the transformer, assisting in the dissipation of heat produced during the conversion of energy. Although there are synthetic and bio-based substitutes, refined mineral oil is usually the source of it. Moisture, impurities, or the disintegration of the oil's chemical structure can all cause its quality to decline over time. It must be tested and maintained on a regular basis to stay effective.
Silica gel is obtained from silica dioxide a naturally occurring compound in sand and comprises fine particles that can soak quantity of water. It is a drying agent that is frequently packaged in tiny paper or cloth packets as tiny, transparent beads or crystals of clear rock. These packets are frequently included with business goods to guard against moisture-related damage. Food, clothing, and electronics are just a few of the many things that include silica gel packets. Although silica gel is typically non-toxic, it poses a choking hazard, particularly to young children.
Amorphous silicon dioxide (silica) particles dispersed in water are known as colloidal silica. In order to produce these amorphous silica particles, silica nuclei from silicate solutions are polymerised in an alkaline environment to create silica sols with a high surface area and a nanometre size. The surface of the silica nanoparticles is then charged, which causes the particles to reject one another and create a stable colloid, or dispersion. Although colloidal silica comes in a variety of grades, all of them are made up of silica particles that range in size from roughly 2 nm to 150 nm. The particles might exist as discrete particles or as slightly organised aggregates, and they can have a spherical or slightly irregular shape.
In a time characterized by environmental awareness and limited resources, sustainable manufacturing has become an essential priority for companies all over the world. Sustainable manufacturing is a model beyond conventional manufacturing practices, focusing on the production of goods in a manner that reduces harm to the environment, uses less energy and natural resources, and prioritizes the health and safety of workers, communities, and consumers.
Intravenous (IV) solutions represent a critical and ubiquitous component of modern healthcare, playing a fundamental role in patient care and treatment. These sterile, liquid formulations consist of a carefully balanced blend of fluids and electrolytes, administered directly into a patient's bloodstream. They are tailored to address a wide range of medical needs, from rehydration and medication delivery to nutritional support and blood transfusions.
Titanium dioxide (TiO 2) is a white, naturally being mineral extensively used as a pigment, UV blocker, and opacifier. A vital element of paints, coatings, plastics, cosmetics, and sunscreens, it's well- known for its exceptional opacity, high illumination, and superior light- scattering capabilities. Also, TiO 2 is essential for advanced operations like photocatalysis, food, and pharmaceuticals. Because of its non-toxic and chemical- resistant rates, it's a necessary element of numerous different sectors, performing in steady demand worldwide.
Yellow phosphorus, a chemical element with the symbol P and atomic number 15, is a fascinating and essential element in the periodic table. This highly reactive nonmetal is widely known for its distinctive yellow appearance and its crucial role in various industrial applications. Found in nature primarily as phosphates, yellow phosphorus is isolated through a complex process to ensure its purity and effectiveness. Its versatility allows it to be employed in the production of fertilizers, detergents, and even in the synthesis of organophosphorus compounds used in medicine and pesticides.
Xanthan gum is a food additive that is produced by fermenting simple sugar using bacteria. It quickly disperses and creates a viscous and stable solution when added to a liquid for providing a thickness or stabilizing effect to a product. It assists in improving the texture, flavour, consistency, appearance, and shelf life of a product. It aids in preventing food products from separating and allowing them to flow smoothly and can lower blood sugar levels among individuals. It also reduces cholesterol levels, slows digestion, supports weight loss management, and treats dry mouth problems.
Titanium sponge is a highly porous, lightweight form of titanium metal produced through the Kroll process. It is the major raw material in the production of titanium alloys in industrial, automotive, medical implant, and aerospace applications. For high-performance industries, titanium sponge is an indispensable component as it has a very high strength-to-weight ratio, is resistant to corrosion, and is biocompatible. It is prepared by reducing titanium tetrachloride (TiCl4) with magnesium, followed by purification and processing to produce titanium compounds that can be used.
Urea is a nitrogenous compound produced in living organisms as a byproduct of the metabolism of protein degradation. In industrial and agricultural use, urea is a synthetic compound produced on a large scale for use as a fertilizer. Urea is a critical source of nitrogen that helps to enhance plant growth and development. Its high content of nitrogen makes it popular in the agricultural sector and serves as a concentrated, readily available source of nitrogen for crops. Besides being a fertilizer, urea also has several industrial uses, such as the manufacture of adhesives and some resins, as well as plastics.
Active dry yeast is a dehydrated form of yeast commonly used in baking and fermentation. Its dormant yeast cells spring to life when they are rehydrated with warm water. In bread-making, brewing, and other fermentation operations, active dry yeast is frequently employed due to its extended shelf life and convenience of storing. It aids in flavour development and raises dough by generating carbon dioxide. It is a necessary component of both commercial and home baking due to its dependability and convenience.
Ethylene-vinyl alcohol, commonly referred to as EVOH, is an extraordinary polymer with outstanding properties that have revolutionized applications in packaging, industrial, and medical fields. The copolymer consists of alternating ethylene and vinyl alcohol monomer units, which result in the unique gas barrier property that makes EVOH a strong contender for food packaging applications.
Ethylene propylene diene monomer (EPDM) is an adaptable synthetic rubber with unique performance properties. It is a copolymer of ethylene, propylene, and diene monomers and is manufactured through suspension, solution polymerization, or gas-phase polymerization processes. It is commonly used in belts, window and door seals, tubing, roofing membrane, non-slip coatings, radiator, drain tubes, and trunk seals.
Ferrosilicon, an iron alloy made of silicon and iron, is a very versatile alloy that is used in many different industries, especially the steel and casting industries. Its composition can vary, with silicon content ranging from 15% to 90%, depending on the application and desired properties.
Polytetrafluoroethylene (PTFE) refers to a tough, waxy and non-flammable synthetic resin that consists of carbon and fluorine atoms. It is manufactured through the free-radical polymerization process of chloroform, fluorspar and hydrochloric acid. PTFE is usually used to give a non-stick coating to surfaces, especially cookware, such as pans and baking trays and industrial products.
Collagen in the connective tissues, bone, and skin of cows and pigs contains gelatin. A common method for creating this colourless, odourless animal protein is to boil ligaments, tendons, and skin in water. Its outstanding physical characteristics include low viscosity, dispersion stability, high affinity, and dispersibility.
Electrolytic manganese dioxide (EMD) is made by dissolving manganese dioxide in sulfuric acid and placing between two electrodes. Manganese dioxide, also referred to as Manganese (IV) oxide, is an inorganic compound that is commonly found in blackish or brown solid and is insoluble in water. EMD is a highly refined form of MnO2 designed to meet the specific electrical requirements of battery manufacturers.
Electrolytic manganese metal is a pure form of the metallic element manganese, Mn concentration ranges from 99.7% to 99.9%. It is termed "electrolytic" because the refining process involves electrolysis. In other words, a chemical reaction powered by an electric current. Heating the ore and applying chemical processes to remove most impurities is the first steps in the processing of manganese.
Ethanol is a renewable biofuel produced primarily from crops such as corn, sugarcane, and biomass. It is often added to fuel to lower carbon emissions and improve energy security. Additionally, ethanol is used in the beverage, chemical, and pharmaceutical sectors. Ethanol is becoming more popular as a cleaner substitute for fossil fuels due to the rising need for sustainable energy solutions, which is propelling improvements in biofuel technology and production efficiency.
Widely recognized for its superior mechanical, chemical, and thermal properties, unsaturated polyester resin (UPR) is a highly versatile thermosetting polymer utilized across multiple industries. UPR is created when unsaturated acids and glycols react mostly used in composites, coatings, and adhesives.
Sodium cyanide (NaCN) is a highly toxic, colorless crystalline compound with a faint almond-like odor. It is a water-soluble salt composed of sodium (Na+) and cyanide (CN-) ions, known for its versatile applications across various industrial sectors. Despite its hazardous nature, sodium cyanide is extensively used due to its unique properties and efficacy in specific processes.
Caustic soda is the common term for sodium hydroxide (NaOH), a versatile alkali widely used in industries such as chemicals, textiles, pulp and paper, detergents, and water treatment. Sodium hydroxide is known to have strong alkaline properties. It is employed in manufacturing processes such as saponification, pH regulation, and chemical synthesis, making it essential for diversified industrial applications.
Citric acid is a naturally occurring weak organic acid found in citrus fruits, widely used for its sour taste, preservative properties, and acidity regulation. Industrially, it is produced through the fermentation of sugars and is a key ingredient in the food and beverage industry, where it enhances flavor and preserves freshness. Additionally, it has applications in pharmaceuticals, cosmetics, and cleaning products due to its ability to stabilize ingredients and chelate metals.
Calcium stearate, a key chemical compound, holds significant importance across various industries due to its multifunctional properties. Comprising calcium and stearic acid, it serves as a versatile additive and processing aid. As a widely utilized stabilizer and lubricant in the manufacturing of plastics, rubber, and pharmaceuticals, calcium stearate plays a pivotal role in enhancing material properties and processing efficiency.
Calcium hypochlorite is a powerful chemical compound, widely used in many different applications and industries. This white solid, made up of calcium, oxygen, and chlorine, contains excellent chlorine content with a strong oxidation capability. Being an oxidizing agent that gives out chlorine when dissolved in water, it is in huge demand for the treatment, sanitation, and disinfection of water.
Nitrocellulose, also known as cellulose nitrate or guncotton, is a chemically modified form of cellulose known for its exceptional film-forming capabilities, strong adhesion, and biodegradability. It is widely used in applications such as wood coatings, printing inks, leather finishes, automotive paints, nail varnishes, and more.
The growth of the copper wire market is primarily driven by increased electricity demand, heightened investments in construction, expansion of electrical infrastructure, the rise of renewable energy, a shift toward electric vehicles in the automotive industry, and the growing adoption of electric appliances. The development of smart grids and investments in upgrading power transmission systems further boost global copper wire demand. Additionally, the telecom industry's use of copper in optic fiber cables and infrastructure development in emerging markets, especially in Asia Pacific and Latin America, are expected to sustain high demand for copper wire in the coming years.
Urea, also known as carbamide, is an organic compound with the formula CO(NH2)2. It is a highly versatile and widely used chemical, primarily known for its role in agriculture as a nitrogen fertilizer. Urea is available in various grades, including fertilizer grade, feed grade, and technical grade, and is used in a wide range of applications, such as nitrogenous fertilizers, stabilizing agents, keratolytic, and resins, among others. Key industries that utilize urea include agriculture, chemicals, automotive, and medical sectors.
Lithium-ion batteries are rechargeable power sources widely used in devices such as cell phones, laptops, and electric vehicles. These batteries store energy by transferring lithium ions between the anode and cathode electrodes, with the electrolyte facilitating this movement and generating free electrons at the anode. Key types of lithium-ion batteries include those with lithium cobalt oxide, lithium iron phosphate, lithium nickel manganese cobalt, and lithium manganese oxide. Lithium-ion batteries come in a range of capacities from 0 mAh to 6000 mAh. They offer several advantages, including a high energy-to-weight ratio, excellent charge retention, and generally longer lifespans with more charge/discharge cycles compared to other rechargeable batteries.
Brazil is renowned across the world for its enormous rainforests and agricultural resources. Over the recent years, the country has emerged as a major player in the global cellulose industry. As per IMARC estimates, the cellulose fiber market in Brazil was valued at US$ 740.4 Million in 2023. By 2032, the market is projected to reach US$ 1,379.9 Million, growing at a CAGR of 7.0% from 2024 till 2032. Strategic investments in the industry, along with favorable environmental conditions, are guiding a cellulose revolution in Brazil, which is likely to have profound implications for both regional and international markets.
Green chemistry refers to the practice of creating new chemicals, materials, and processes that are less toxic to human health and the environment. It comprises the utilization of renewable resources and reducing waste and energy consumption. Green chemicals are used in various applications such as industrial and chemical, food and beverages, automotive, packaging, construction, agriculture, personal care, and many others. Nowadays, different types of green chemicals are available in the market, including bio-alcohol (bioethanol, bio-butanol, bio-methanol, and many others), bio-organic acids (bio-lactic acid, bio-acetic acid, bio-citric acid, bio-adipic acid, bio-acrylic acid, bio-succinic acid, and others), biopolymers (poly-lactic acid, bio-polyethylene, and others), bio-ketones, bio-solvents, and many other organic acids.
Vanadium has been discovered in sediment samples collected from the Gulf of Khambhat, which opens into the Arabian Sea off Alang in Gujarat. This discovery is expected to enhance the production of steel and titanium in India and boost redox battery manufacturing. Vanadium is one of the most abundant transition metals and is typically found in various minerals, including vanadinite, patronite, and carnotite. It is a hard, ductile, and rare grey metal, often extracted as a byproduct while processing other metals such as iron and uranium.
Steel is a versatile and widely used alloy composed primarily of iron and carbon, with small amounts of other elements such as manganese, chromium, nickel, and others. It is a widely utilized material in construction, manufacturing, and various industries. Steel exhibits a range of desirable properties, including high tensile strength, durability, hardness, corrosion resistance, heat resistance, and the ability to be formed into different shapes. Carbon steel, alloy steel, stainless steel, and tool steel are the main types of steel. Steel is utilized in the manufacturing of various products, including ingots, semi-finished materials, hot-rolled sheets and coils, galvanized sheets, steel tubes and fittings, plates, wire rods, and many others. Its applications span various industries such as building and construction, electrical appliances, metal products, automotive, transportation, and mechanical equipment. The top five exporters of steel are China, Japan, South Korea, and Germany. Similarly, the major importers of steel include the United States, Germany, Italy, and Turkey.
Copper is an essential material in electrical wiring, electronics, and heating systems. It is also highly ductile and malleable, allowing it to be easily shaped and drawn into thin wires. Additionally, copper possesses antimicrobial properties, making it useful in medical and architectural applications. Its resistance to corrosion and its ability to form alloys with other metals further enhance its versatility across various industries.